
Crypto World
When To Sell Stocks: These IBD 50 Components Hit Sell Signals

Investor’s Business Daily’s IBD 50 index is on track for a third straight down month, and some of its components are sputtering. Various factors help decide when to sell stocks, and five have already triggered sell signals. AngloGold Ashanti (AU) broke out above a 113.30 buy point on Aug. 20. Nearly a month later, the stock is struggling, down 10%…
Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8

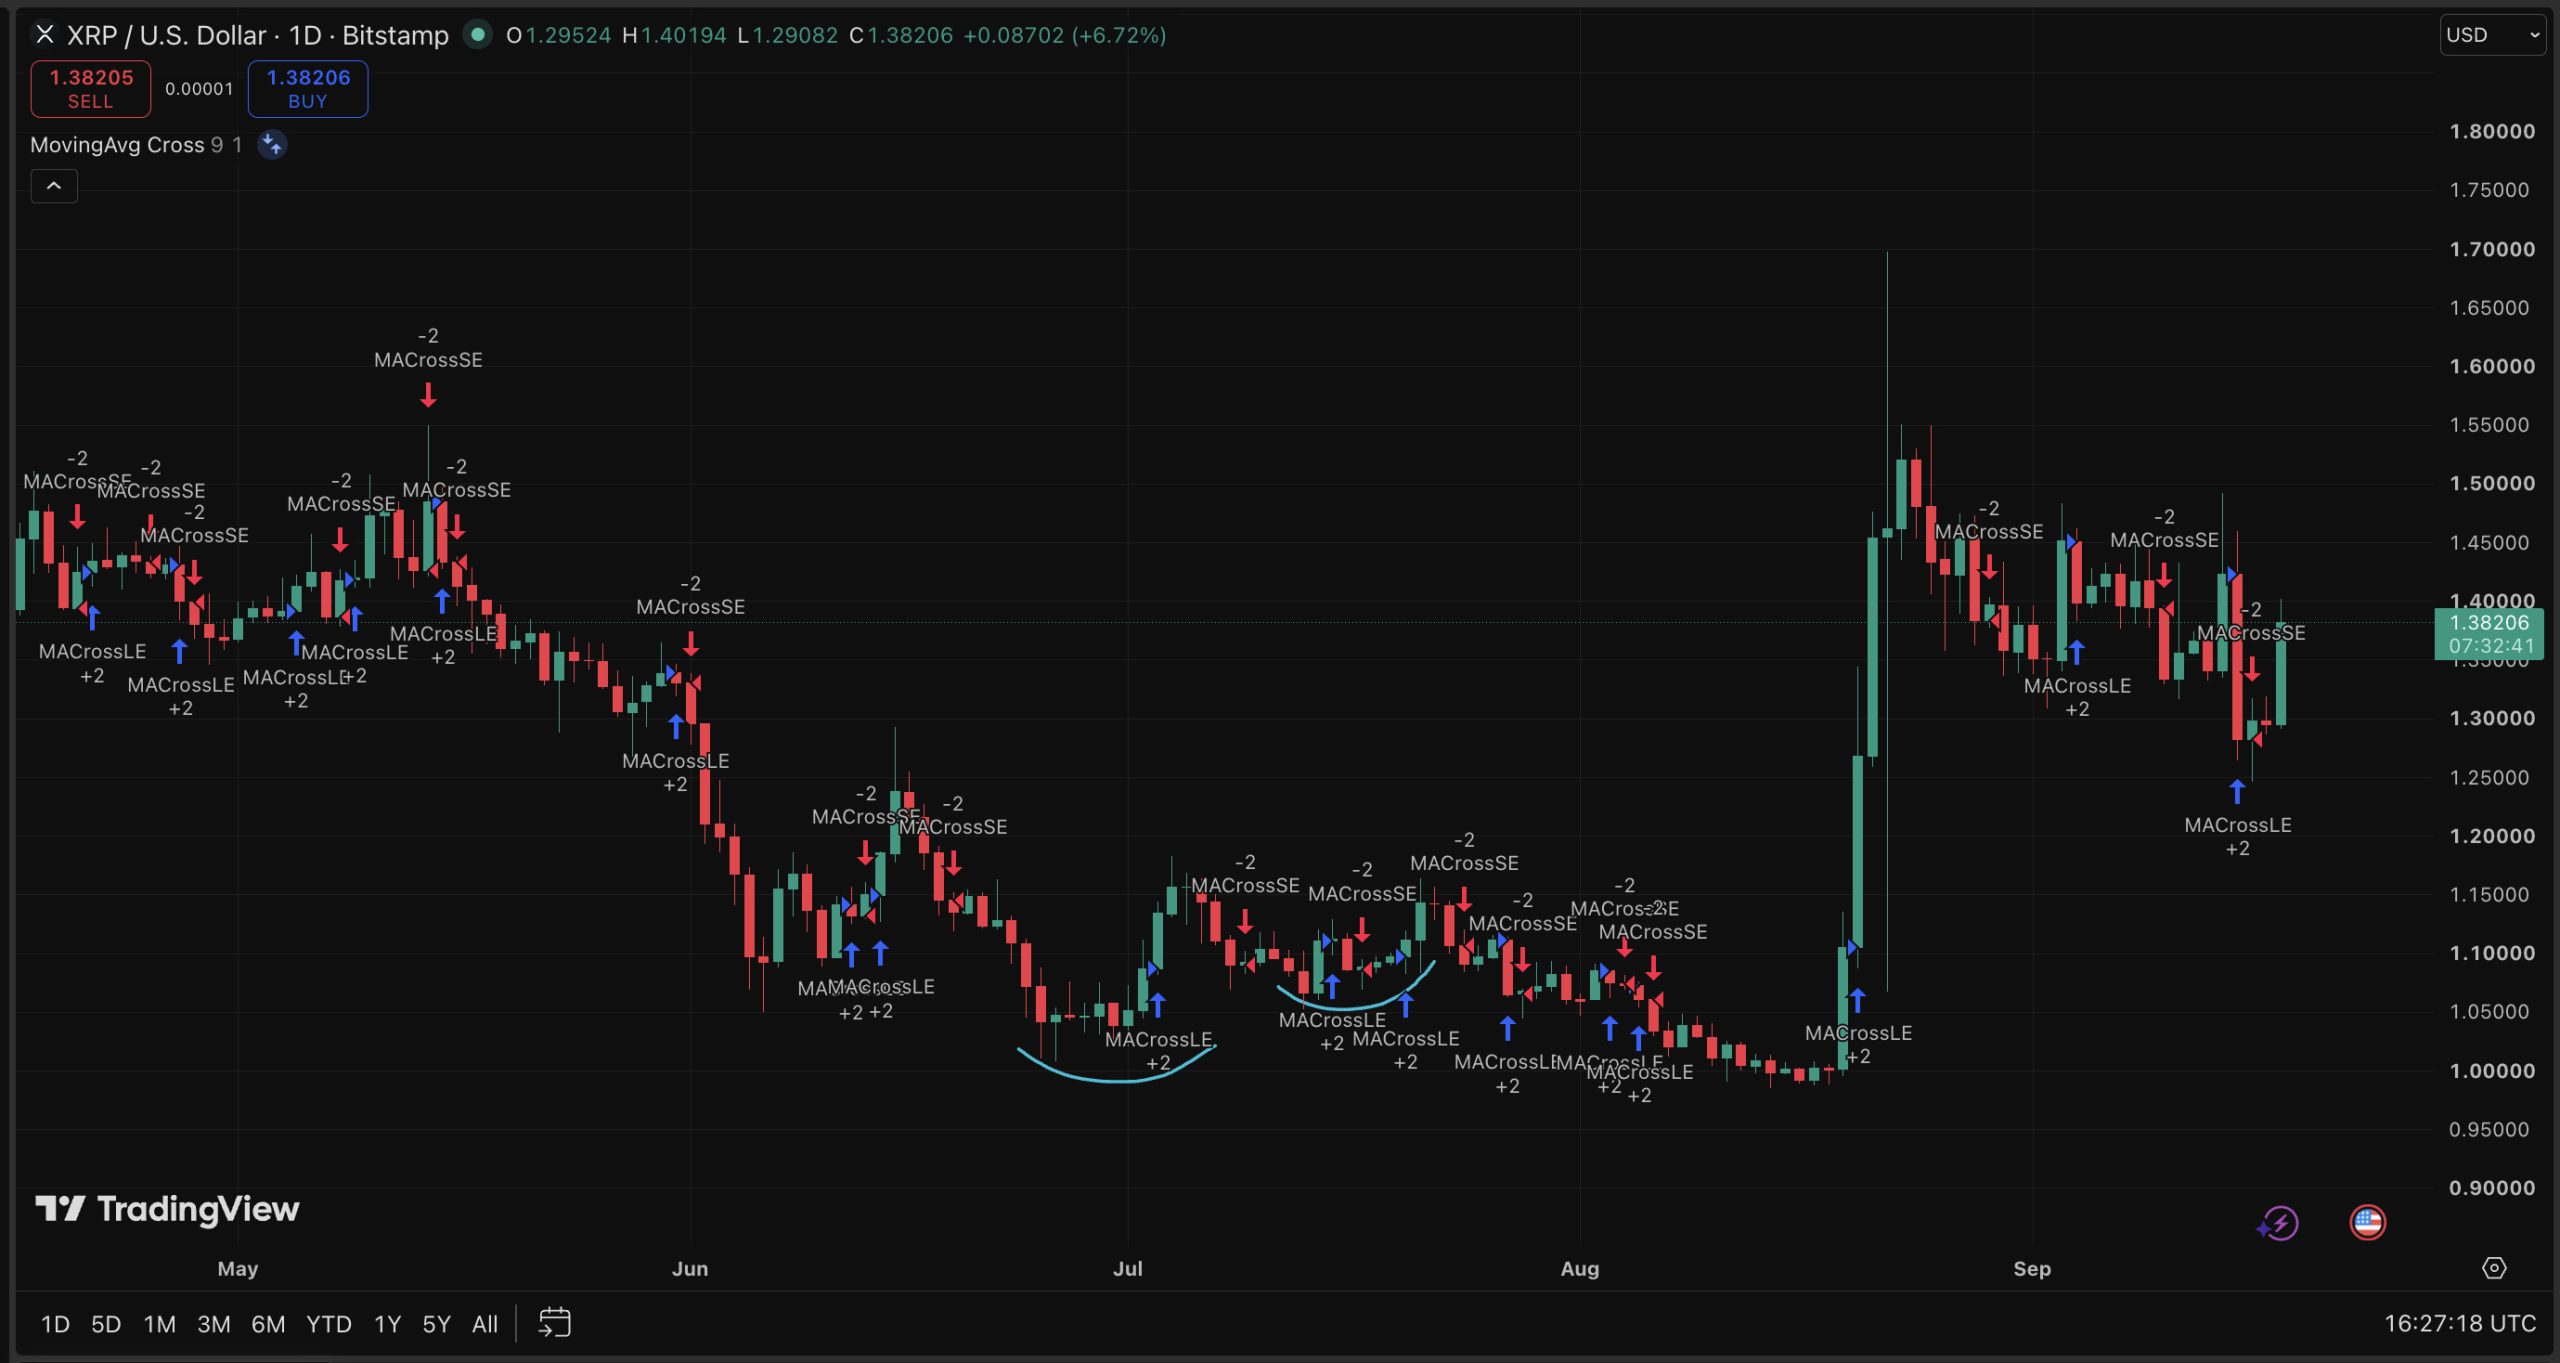
XRP should be in every news headline as its 50-day moving average sits about 2% below its 200-day average, the closest the gap has been since the token’s last golden cross in August 2024. The setup is emerging as bitcoin dominance, or bitcoin’s share of total crypto market capitalization, has fallen to a one-month low below 59%.
A golden cross is confirmed when an asset’s 50-day moving average crosses above its 200-day moving average. Chart analysts widely view the pattern as a bullish long-term signal. Bitcoin recently confirmed its own golden cross, while cautioning that XRP has shown a different historical record.
The 16 previous XRP golden crosses and found that all were terminated by a death cross within 12 months. Six did not survive three months. Of the 10 crosses that reached the three-month mark, five produced gains ranging from 85% to more than 1,000%. Those included a 1,009.6% gain following the April 2017 cross and a 135% gain after the February 2021 cross. The other five lost as much as 32%.

Half of the crosses that lasted at least three months generated substantial gains, while the other half produced losses. The historical figures indicate that the golden cross, like other technical indicators, was not fully reliable when used in isolation.
Bitcoin is now trading near $80,000, and its dominance rate has dropped below 59%, which implies a rotation into altcoins. The data points to attention shifting within the crypto market, even as bitcoin’s price remained near its level from a week earlier.
Earn $50 and Enter $300K Prize Draw on EdgeX
How to Read the Moving Averages?
Confirmation requires the 50-day average to cross above the 200-day average. With XRP’s 50-day average about 2% below the longer-term average since the August 2024 golden cross. The difference between the two averages is therefore the immediate technical measure for traders following the setup.

Our AI price analysis identified the $1.26-$1.27 area as a support zone that aligns with the 200-day moving average and former range support. XRP technical structure was neutral, and the near-term direction hinged on whether the asset could hold above that support area despite some bearish news from the Clarity Act.
Moving averages provide one way to assess trend conditions, but the historical XRP results show why the crossover itself does not settle the question of what follows. A cross can confirm the technical pattern while leaving the duration and price performance of that pattern uncertain.
Trade XRP on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
What’s Next for XRP Beyond The News?
If XRP’s 50-day average crosses above its 200-day average, it will confirm the pattern we are tracking. That would be a technical event, not a guarantee of a lasting advance. A later death cross would be consistent with the outcome recorded for all 16 prior XRP golden crosses within a year.
The three-month historical split remains central to interpreting the signal. Five of the 10 crosses that reached that point posted gains of 85% to more than 1,000%, while five recorded losses of as much as 32%. The outcomes show both the potential for large gains and the limits of relying on the indicator alone.
We characterized the broader move into altcoins as cautious rather than complete. FxPro chief market analyst Alex Kuptsikevich said traders appeared to be cautiously shifting their focus toward altcoins, while the altcoin season index and overall market sentiment had not reached high levels.
Bitcoin dominance below 59% is consistent with our assessment that attention was rotating toward altcoins, while the available indicators did not establish a broad altcoin cycle.
Discover: The Best Token Presales
The post XRP News: 16-Cross History Complicates the Golden Cross Signal appeared first on Cryptonews.
The SEC has opened a five-year pathway for tokenized U.S. stocks that requires each approved token to carry the economic, voting, dividend, and liquidation rights attached to the underlying share.
Summary
- Tokenized NMS stocks must provide the same rights as their traditional share equivalents.
- Synthetic products that offer only price exposure fall outside the SEC exemption.
- Bitget Wallet COO Alvin Kan said legal ownership matters more than 24-hour trading.
- The exemption carries symbol and volume limits and remains open to SEC modification.
- Institutions can run pilots, but the temporary order does not provide lasting legal certainty.
Bitget Wallet COO Alvin Kan told crypto.news that the legal rights attached to a stock token will matter more to investors than its trading hours, settlement speed, or country of issuance.
“A token that tracks a stock price is not the same thing as owning the stock. Putting both on a blockchain doesn’t erase that difference,” Kan said.
Under the SEC exemption, a tokenized National Market System stock must grant its holder the same rights and privileges as the matching traditional share. Kan said those protections include an economic interest in the company, dividends, voting power and rights during liquidation.
Synthetic exposure does not qualify under the exemption. An issuer can also object if an unrelated third party tries to tokenize its shares, giving listed companies some control over how their securities appear in blockchain-based markets.
Investor rights separate tokenized stocks from price trackers
Instead of dividing the market into U.S. and offshore products, Kan said investors should examine what each token represents under the law. Two products can track the same listed company while giving their holders very different claims.
One token may represent a direct or beneficial interest in shares held through a regulated structure. Another may function as a contract with an intermediary that promises to follow the stock’s price without making the buyer a shareholder.
The difference can determine whether a holder receives dividends, can vote on company matters or has a claim on assets if the issuer is liquidated. Counterparty exposure may also enter the arrangement when the investor’s claim depends on a platform, custodian or special-purpose entity.
A Sep. 11 examination of tokenized ownership structures found that products can represent direct shares, custodial claims or synthetic contracts. Company rules, securities laws and underwriter restrictions may still limit transfers even when a token moves freely between blockchain addresses.
Kan said many crypto-native products outside the United States provide price exposure or a contractual claim against an intermediary. Under the SEC pathway, an approved NMS stock token must instead preserve the rights carried by the conventional security.
Coinbase CEO Brian Armstrong made a similar distinction on Sep. 14 when he said the exchange’s stock tokens use real securities rather than synthetic assets or debt instruments. Coinbase holds the underlying shares through an offshore special-purpose company and a regulated U.S. broker, according to a report on its fully backed stock tokens.
Verified holders can request redemption of the underlying shares, while dividend proceeds are generally reinvested after taxes and fees. Coinbase’s products, however, remain unavailable to U.S. persons and are not registered under the U.S. Securities Act.
Tokenized stocks can improve access without changing ownership
For eligible users, Kan identified self-custody, fractional ownership, continuous trading and almost immediate settlement as possible benefits. The SEC has also listed such features among the potential gains from moving securities onto blockchain systems.
Trading a stock token around the clock could reduce the limits imposed by regular exchange hours, while fractional units could let investors purchase smaller portions of high-priced shares. Blockchain settlement may also shorten the time between a completed trade and the final transfer of ownership.
Yet Kan cautioned that tokenization alone does not produce a better investment product. A system may use blockchain records while keeping strict permission controls, thin liquidity and several intermediaries between the investor and the underlying share.
“If access remains heavily permissioned, liquidity is shallow and users still face multiple intermediaries, blockchain may mainly modernize the back end without materially changing the front-end experience,” Kan said.
For investors, the practical test is whether the structure reduces the work involved in settlement, record reconciliation and product distribution. Moving a stock record onto a blockchain without removing those costs would change the technology supporting the market but leave the customer experience largely intact.
The ownership record forms another part of the issue. On Sep. 1, the SEC proposed updates to federal transfer-agent rules and forms, which have not received a substantial revision since the late 1970s and early 1980s, according to the agency.
A recent report on blockchain ownership records explained that transfer agents could use distributed-ledger systems as an official record under the proposal. The rule would not automatically turn every stock-linked token into a legal share or give its holder shareholder rights.
The SEC exemption gives institutions room to test products
For banks, brokerages, trading venues and blockchain providers, Kan described the exemption as operational clarity rather than permanent legal certainty.
The order expires five years after publication. It also contains limits covering trading symbols and volume, remains subject to modification and is designed to provide information for later SEC rulemaking.
Those terms give institutions enough regulatory space to develop pilot programs, connect existing systems and test modular infrastructure, Kan said. Firms committing capital over longer periods will still distinguish between a temporary exemptive order and requirements placed in final agency rules or federal law.
The distinction matters for U.S. investors because the SEC is using its authority over securities already covered by the Exchange Act. The agency does not have to wait for Congress to settle every dispute over the classification of crypto assets before testing blockchain systems for instruments that are already treated as securities.
Kan said the approach separates statutory reform from agency-led changes to market structure. Congress can write laws covering the treatment of digital assets across several markets, while the SEC can act within its existing securities mandate.
Congress has left the SEC to use its existing authority
The exemption arrived two days after the Senate failed to advance the Digital Asset Market Clarity Act, or CLARITY Act, during a Sep. 15 procedural vote.
The bill sought to establish a federal market structure for digital assets and divide regulatory responsibilities between the SEC and the Commodity Futures Trading Commission. Its failure did not remove the SEC’s authority over products already classified as securities.
A 50-49 Senate vote left the bill 10 votes short of the 60 required to invoke cloture and open formal debate. Clearing the motion would not have passed the legislation; it would only have allowed senators to begin considering the House-approved measure and possible amendments.
All participating Democrats opposed cloture. Republican Sens. Susan Collins, Josh Hawley, Jerry Moran, and Thom Tillis also voted against the motion, with Tillis changing his vote for procedural reasons that preserved the option to request reconsideration.
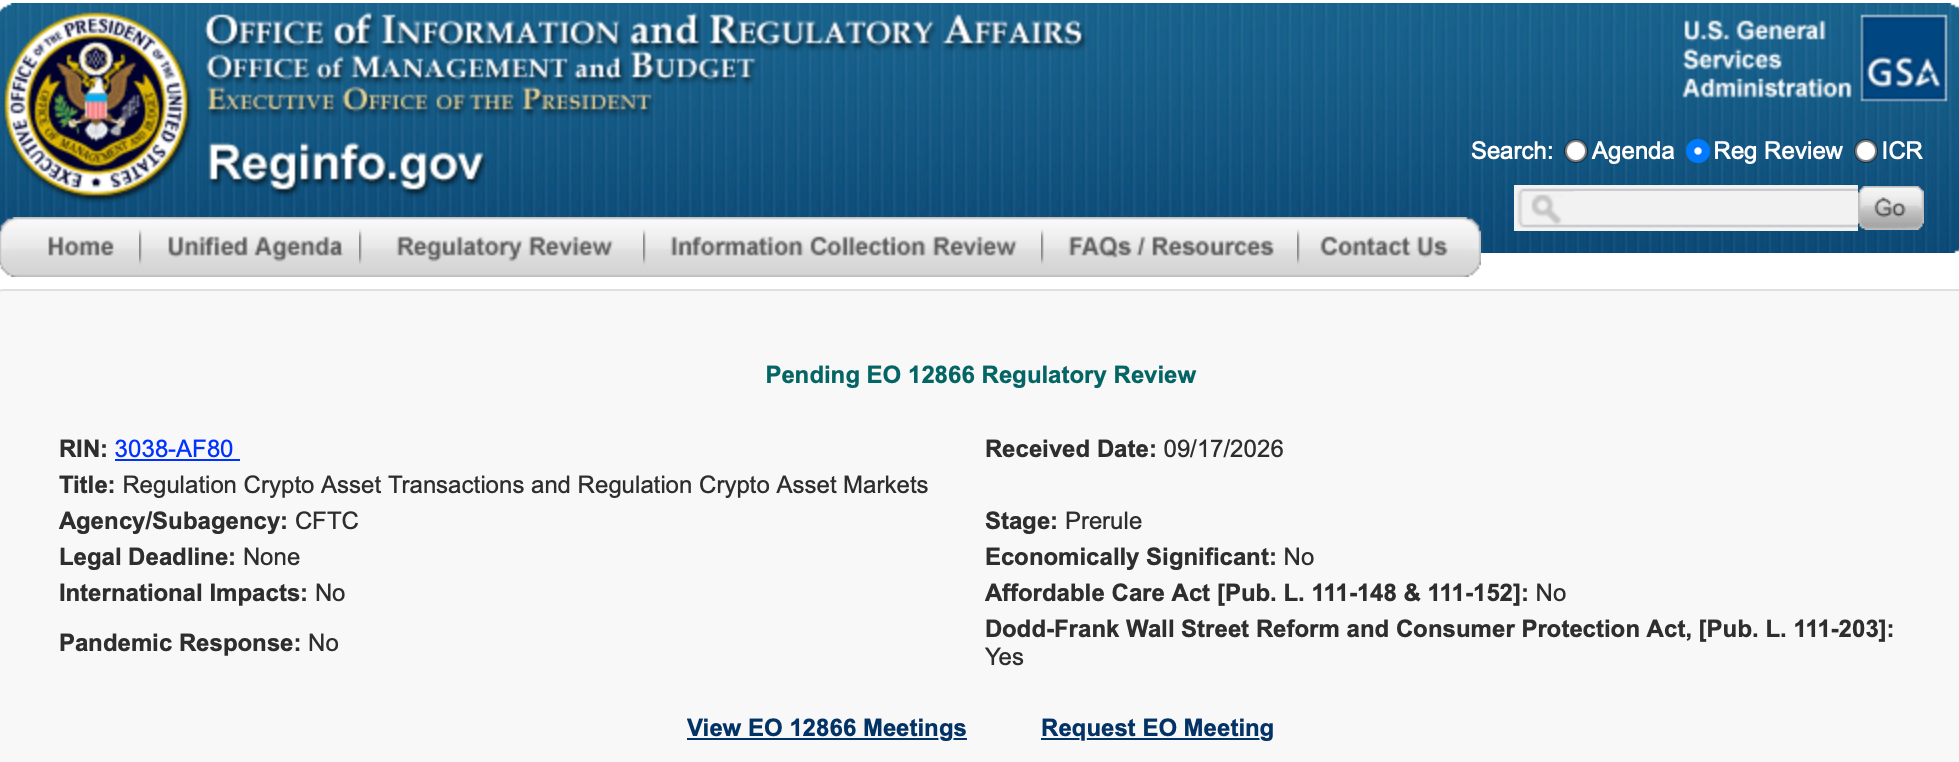
The US Commodity Futures Trading Commission has submitted a new regulatory action covering crypto asset transactions and markets for White House review, as the agency moves forward with its approach to overseeing the digital asset sector.
According to a filing with the Office of Information and Regulatory Affairs, the action, titled “Regulation Crypto Asset Transactions and Regulation Crypto Asset Markets,” was received on Sept. 17 and is listed at the “prerule” stage. The designation indicates the action is at an early stage of the rulemaking process and has not yet been formally proposed.
The filing does not disclose details of the planned regulation, but comes days after the Senate failed to advance the CLARITY Act, legislation aimed at establishing a federal regulatory framework for crypto markets.
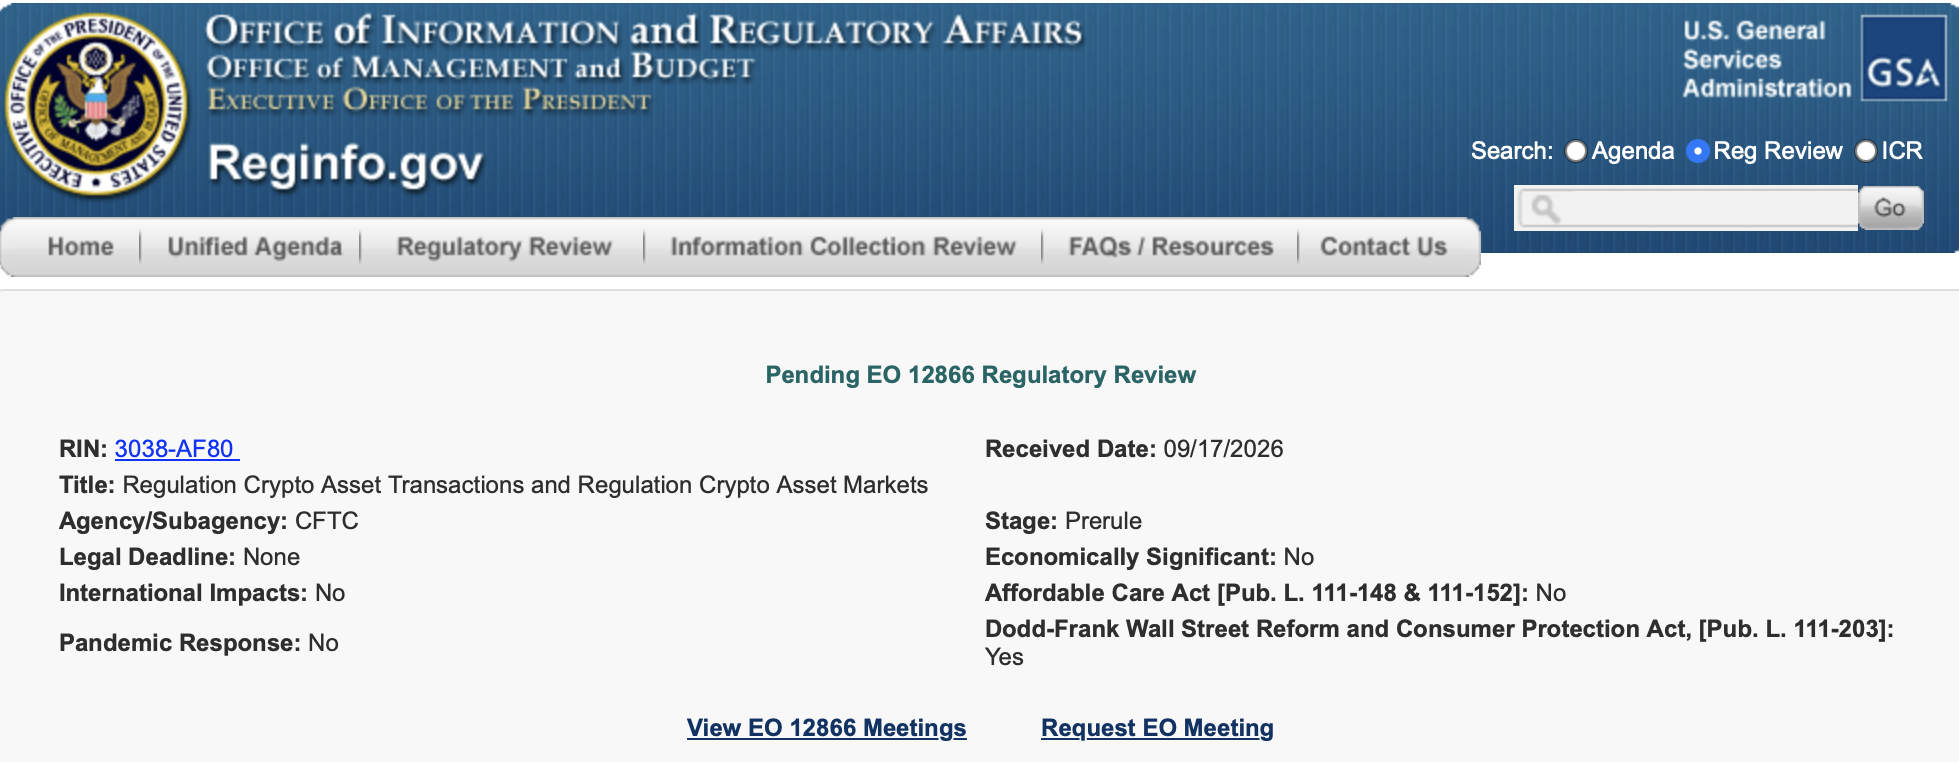
Source: Office of Information and Regulatory Affairs
A day after the Sept. 15 vote, CFTC Chair Michael Selig posted on X that the agency was “locked in and ready to ship” rules for crypto markets using its existing statutory authority, while SEC Chair Paul Atkins similarly said the securities regulator would move ahead “with or without legislation.”
Both agencies took action the following day. The CFTC issued a no-action position for providers of passive software, while the SEC announced temporary exemptions for certain platforms facilitating onchain trading of tokenized securities.
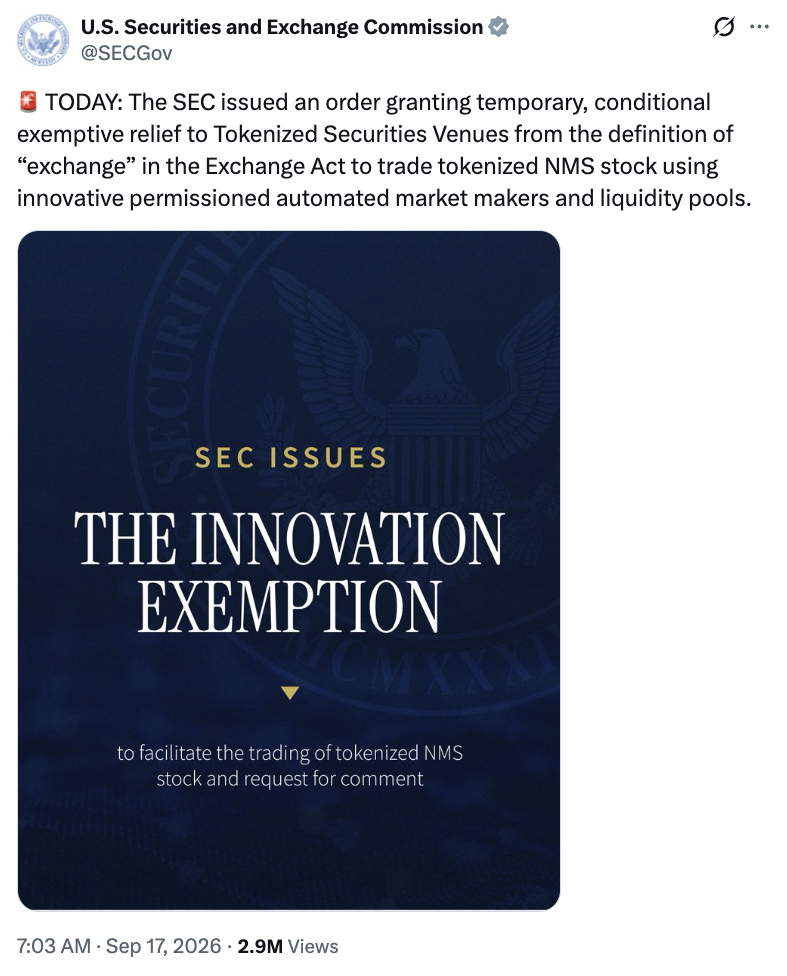
Source: SEC
CFTC and SEC move ahead without new legislation
The CFTC had been exploring the possibility of advancing crypto rules without new legislation before the Senate vote this week. In remarks at the CFTC’s Innovation Advisory Committee conference on Aug. 20, Selig said the agency was prepared to use its existing authority to establish a crypto asset market regime if the CLARITY Act stalled.
Selig added that he had directed CFTC staff to explore rules that could allow existing registrants and currently unregistered crypto exchanges to become a type of designated contract market called a “crypto asset market,” where leveraged or margined crypto trading could be offered under CFTC oversight.
Coinbase CEO Brian Armstrong also said he expected regulators to move ahead after the vote. In a Sept. 15 post on X, he wrote that the SEC and CFTC had “the tools they need to create clear rules under existing authority” and that he expected them to begin working on the issue “in earnest.”
“So clarity is coming to crypto regardless,” Armstrong wrote.
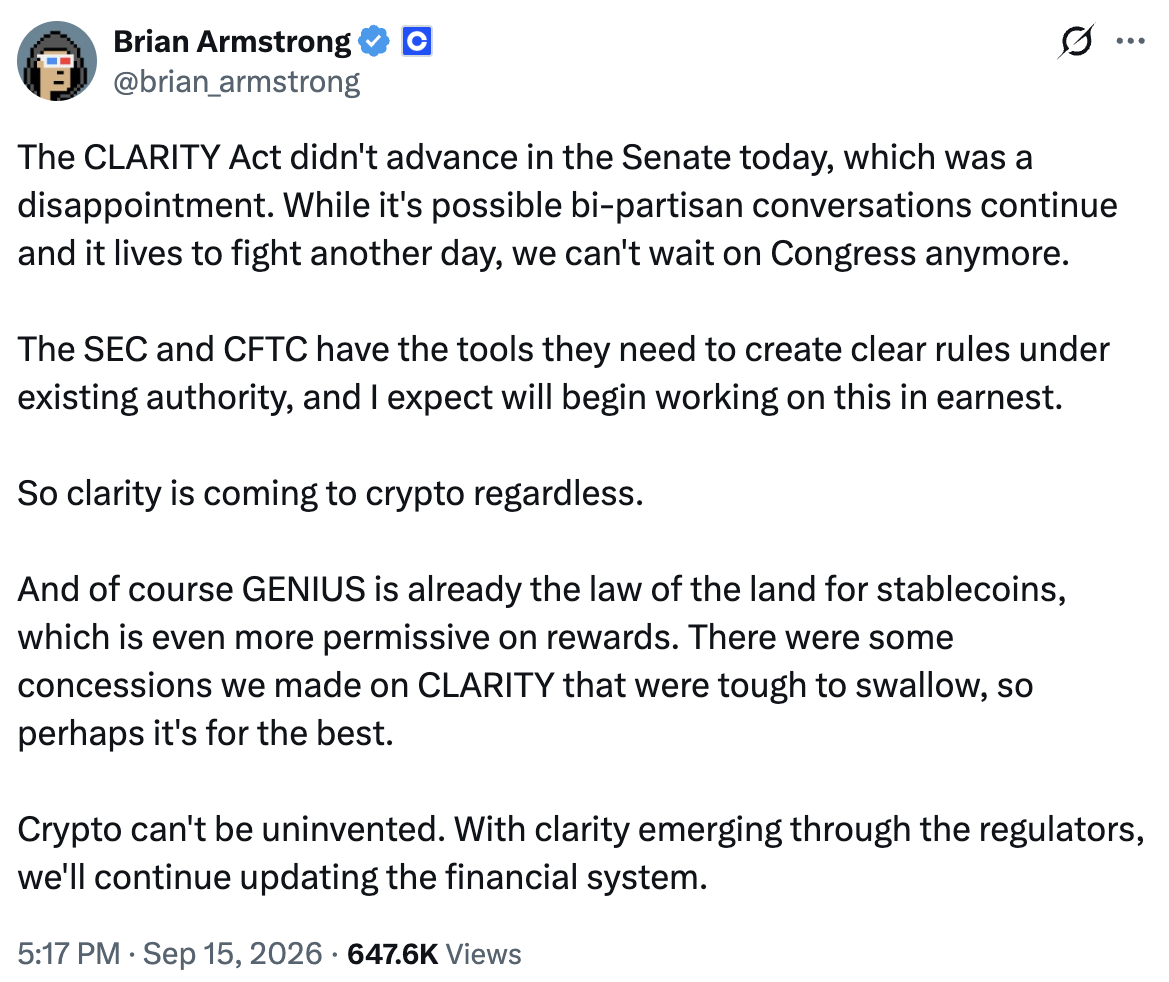
Source: Brian Armstrong
The U.S. Commodity Futures Trading Commission (CFTC) has submitted a new regulatory action covering how it plans to oversee crypto asset transactions and crypto asset markets, with the proposal now moving through the federal rulemaking pipeline for White House review.
According to a filing published through the Office of Information and Regulatory Affairs (OIRA) at reginfo.gov, the action—titled “Regulation Crypto Asset Transactions and Regulation Crypto Asset Markets”—was received on Sept. 17 and is currently listed at the “prerule” stage, meaning it is early in the process and has not yet been formally proposed.
Key takeaways
- The CFTC has initiated a new rulemaking track for crypto-related transactions and markets, but the details have not been released yet.
- OIRA’s “prerule” designation indicates the action is still at an early stage and not a formal notice of proposed rulemaking.
- The move follows the Senate’s failure to advance the CLARITY Act, keeping pressure on regulators to act without new legislation.
- In parallel, both the CFTC and SEC signaled they could proceed using existing authority, including through targeted relief and exemptions.
A CFTC rulemaking filing enters the federal review track
The OIRA entry for the CFTC action provides the clearest public confirmation so far of the agency’s regulatory direction: the filing exists, has been received, and is underway as part of the U.S. government’s rulemaking review process. However, the filing does not outline what specific requirements the CFTC plans to impose or how it intends to define regulated crypto market structures.
For market participants, the practical significance is that rule development is not only being discussed—it is being processed through government channels that typically precede public comments and formal proposals. Still, because the item remains at the prerule stage, the scope, timing, and concrete compliance expectations are not yet available.
After the CLARITY Act setback, regulators show momentum
This CFTC filing comes days after the U.S. Senate failed to advance the CLARITY Act, a bill intended to establish a federal framework for crypto market regulation.
That failure matters because it reduces the likelihood of Congress providing an immediate, comprehensive structure that could harmonize oversight across agencies. With legislation stalled, the burden shifts to regulators to define roles and boundaries through existing statutory authority—an approach the CFTC and SEC appear prepared to pursue.
CFTC and SEC actions signal “rules with or without legislation”
Shortly after the Sept. 15 Senate vote, CFTC Chair Michael Selig posted on X that the agency was “locked in and ready to ship” rules for crypto markets using its existing authority. SEC Chair Paul Atkins made a similar point, saying the SEC would move ahead “with or without legislation.”
The following day, both regulators took visible steps. The CFTC issued a no-action position for providers of passive software. Separately, the SEC announced temporary exemptions for certain platforms facilitating onchain trading of tokenized securities, as reflected in an SEC communication posted on X.
These actions do not replace broad rulemaking, but they do indicate an interim strategy: provide targeted regulatory relief and clarify operational pathways for specific categories of activity while longer-term frameworks are developed.
What the CFTC has said before: using existing authority to define a market regime
The CFTC’s willingness to move ahead without waiting for legislation has been discussed publicly before. Earlier remarks by Chair Selig at the CFTC’s Innovation Advisory Committee conference on Aug. 20 indicated the agency had been assessing whether it could establish a crypto asset market regime under existing authority if the CLARITY Act stalled.
In those remarks, Selig indicated he directed CFTC staff to explore rule options that could enable existing registrants and currently unregistered crypto exchanges to become a type of designated contract market—referred to as a “crypto asset market”—where leveraged or margined crypto trading could fall under CFTC oversight.
This matters for investors and builders because the classification of trading venues and the treatment of leverage and margin can directly affect which firms can operate, which registrations may be required, and what investor protection frameworks are applied. It also helps determine how market participants structure products and routing of orders.
Industry leaders have echoed the expectation that regulators would proceed. Coinbase CEO Brian Armstrong said in a Sept. 15 X post that the SEC and CFTC “have the tools they need to create clear rules under existing authority,” adding that he expected regulators to begin working “in earnest.”
What to watch next as the filing moves from prerule to proposal
For now, the key unknown is the substance: the OIRA record confirms the CFTC’s intention to regulate crypto asset transactions and crypto asset markets, but it does not provide the operational details firms will need to prepare. The next developments to monitor are when the action advances beyond prerule, whether it is broken into specific proposed rule components, and how it aligns—or potentially conflicts—with concurrent SEC efforts affecting tokenized securities and onchain trading.
The U.S. Commodity Futures Trading Commission has taken another step toward formal rulemaking for crypto-related markets, submitting a regulatory action for White House review as it continues to outline how digital asset transactions could be regulated under existing authorities.
According to a filing posted to the Office of Information and Regulatory Affairs (OIRA) on Reginfo.gov, the action—titled “Regulation Crypto Asset Transactions and Regulation Crypto Asset Markets”—was received on Sept. 17 and is currently listed at the “prerule” stage. That designation signals the process is still early and the agency has not yet issued a formal proposed rule.
Key takeaways
- The CFTC filed a new crypto-focused rulemaking action with OIRA on Sept. 17, but it remains in the early “prerule” stage.
- The filing does not provide specific regulatory details, suggesting further information will come later in the rulemaking timeline.
- Recent U.S. legislative momentum weakened after the Senate failed to advance the CLARITY Act, while both the CFTC and SEC signaled they would proceed with or without new law.
- In the days following Sept. 15, the regulators also took separate enforcement-adjacent steps: a CFTC no-action position and an SEC temporary exemption framework.
What the CFTC filing indicates—and what it doesn’t
The OIRA posting for the CFTC’s action, labeled “Regulation Crypto Asset Transactions and Regulation Crypto Asset Markets,” confirms the agency is moving toward a more structured regulatory approach for crypto trading activity and market infrastructure. However, the filing itself does not lay out the substance of what the CFTC intends to regulate, such as which categories of market participants, trading arrangements, or operational requirements would be covered.
The “prerule” listing matters for readers because it usually precedes a proposed rule by moving the action through early interagency or administrative review. That means market participants should treat the filing as a signal of direction rather than a preview of enforceable standards.
For investors and firms planning compliance work, the practical takeaway is that the CFTC is building a pathway toward a dedicated crypto asset market regime. The missing details, meanwhile, leave compliance teams with uncertainty about timing and scope—until a proposal is published.
Legislation stalls as regulators lean on existing authority
The filing arrives shortly after the U.S. Senate did not advance the CLARITY Act, a bill intended to establish a federal framework for regulating crypto markets. With that legislative path effectively blocked in the near term, senior regulators have repeatedly pointed to their ability to move using existing statutory authority.
Coinciding with that backdrop, CFTC Chair Michael Selig posted on X that the agency was “locked in and ready to ship” rules for crypto markets using existing authority. In parallel, SEC Chair Paul Atkins said the SEC would advance “with or without legislation,” as reflected in his posts on X.
Earlier remarks from Selig also suggested that the CFTC had considered a rulemaking approach even if Congress did not act. Speaking at the CFTC’s Innovation Advisory Committee conference on Aug. 20, he said the agency was prepared to use existing authority to establish a crypto asset market regime if the CLARITY Act stalled. He also discussed directing CFTC staff to explore rule concepts that could allow existing registrants and currently unregistered crypto exchanges to operate within a “crypto asset market” structure—an arrangement that would be overseen under CFTC rules and could include leveraged or margined crypto trading.
For the sector, this signals an ongoing tug-of-war between market expectations of comprehensive legislation and the reality that regulators may still set guardrails via rulemaking and targeted regulatory relief.
Regulatory actions after Sept. 15: relief and exemptions move in parallel
A day after the Sept. 15 Senate vote, the CFTC and SEC each took actions that, while different in scope, pointed to a broader theme: regulators are continuing to shape the crypto trading environment even without a new overarching statute.
On the CFTC side, the agency issued a no-action position for providers of passive software, as described in earlier coverage. While the details of eligibility are specific to the no-action framework, it underscores that the CFTC is willing to use regulatory discretion to manage particular technical implementations around crypto trading.
On the SEC side, it announced temporary exemptions for certain platforms facilitating onchain trading of tokenized securities, according to posts on X from the SEC.
Industry reaction: expectation of near-term rulemaking
Outside the regulators, industry leaders have also signaled readiness for regulatory work to proceed. Coinbase CEO Brian Armstrong said he expected regulators to move forward after the vote, stating that the SEC and CFTC have “the tools they need to create clear rules under existing authority.” In that same Sept. 15 X post, Armstrong said he expected them to begin working on the issue “in earnest,” adding that “So clarity is coming to crypto regardless.”
While those comments are not the same as regulatory text, they reflect how market participants are interpreting the balance of power: when legislative clarity is delayed, compliance strategies increasingly have to follow the pace of rulemaking and regulatory relief.
What to watch next
The immediate uncertainty is what the CFTC’s Sept. 17 “prerule” action will translate into once it advances toward a proposed rule—especially around the scope of “crypto asset transactions” and “crypto asset markets.” Market participants should watch for the next OIRA steps and any CFTC releases that clarify which market structures, trading practices, and platform roles will be prioritized.

Kevin O’Leary has re-entered the crypto market. At the Avalanche Summit in New York, he says that he is building fresh positions ahead of the next crypto market cycle. The O’Leary Ventures chairman said Bitcoin could eventually account for 1% to 3% of institutional alternative-asset allocations, a share he compares directly to how much gold institutions currently hold.
Kevin O’Leary isn’t calling for a retail mania; he’s describing a slow, allocation-model-driven path toward institutional crypto adoption that mirrors how pension funds and endowments built gold exposure over decades, not months.
His renewed buying is tied to a specific structural bet: the first major stock exchange to adopt a blockchain, he argues, would force the rest of the financial system to fall in line with that exchange’s technical and compliance requirements. He called it a potential watershed moment, one that could settle the ongoing fragmentation across competing chains.
He said he regularly asks CEOs across industries which blockchain their companies are betting on, and so far, none of them agree. That’s the honest state of institutional crypto adoption right now: plenty of capital circling, no consensus on the winning rail.
Regulatory ambiguity around how tokenized securities are classified and traded is part of why that consensus hasn’t formed, a gap explored in recent coverage of the SEC’s tokenized-stock exemption framework.
Bitcoin was trading near $80,600 at last check, up more than 5% on the day, putting it in the range traders are currently watching as a potential recovery zone. Whether that level holds as support or gets retested is the near-term technical question, one broken down in detail in this analysis of the $80,000 breakout test.
Discover: The Best Token Presales
Regulation, Taxes, and the CLARITY Act
O’Leary addressed the CLARITY Act’s recent Senate setback directly, saying that he still expects crypto regulation to resurface because lawmakers are actively working on tax policy for digital assets. His logic is straightforward: taxing an asset class tends to invite more oversight, not less, since regulators need clear definitions before they can collect anything.
He does not expect the bill to pass before the midterms. That timeline matters for anyone modeling institutional crypto adoption around a legislative catalyst – O’Leary’s framing suggests the tax-policy track, not the market-structure track, is the more likely near-term vehicle for regulatory clarity.
Earn $50 and Enter $300K Prize Draw on EdgeX
Beyond Kevin O’Leary Comment: The Bitcoin Price Prediction With a Catch
In a separate conversation, O’Leary offered his boldest Bitcoin price prediction yet: $1 million, but only if the industry resolves the growing unease around quantum computing breaking encryption standards, a scenario the industry has nicknamed “Q-Day.”
He noted that some investors are already hedging that risk by backing quantum-computing startups as a defensive security play rather than betting against Bitcoin outright.

That’s the tension running through his entire thesis. The same institutional capital he expects to push Bitcoin toward a larger share of alternative-asset portfolios is also the capital most sensitive to unresolved tail risks – quantum security, regulatory classification, exchange-level standardization.
For context on how other institutional voices are framing Bitcoin’s long-term ceiling against traditional stores of value, see this comparison of Bitcoin and gold allocation models from JPMorgan. The throughline across these calls is consistent: the crypto market cycle ahead depends less on retail sentiment and more on which infrastructure, tax rules, and security guarantees institutions are willing to underwrite before they commit real allocation.
Trade Ethereum on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
The post Bitcoin Could Reach 1%-3% of Institutional Alternative Portfolios appeared first on Cryptonews.
Cointelegraph is committed to providing independent, high-quality journalism across the crypto, blockchain, AI, and fintech industries.
All news, reviews, and analyses are produced with full journalistic independence and integrity. For more details on our standards and processes, please read our Editorial Policy.

BlackRock has said stablecoins must remain interchangeable with bank deposits and central-bank money if they are to function as regulated settlement assets.
Summary
- Stablecoins must provide recognizable claims and recourse across banks, according to BlackRock.
- Banking systems would need to accept stablecoins and convert them into deposit liabilities.
- Central banks could provide the final settlement layer through fiat money or wholesale CBDCs.
- U.S. rules now govern permitted payment stablecoin issuers under the GENIUS Act.
Stablecoins need recognition across banking systems
The European Blockchain Convention’s Day 1 media briefing attributed the position to Nikhil Sharma, BlackRock’s head of digital assets, during a panel on how tokenized forms of money can operate together.
Sharma said the central issue is the “singleness of money,” a principle under which different forms of the same currency remain interchangeable at face value. The form of payment may change, but users must understand the claim, backing, access conditions, and recourse attached to it.
“When you think about what you’re using as cash for payments and settlement, you look at what’s the claim, what’s the backing, what’s the form, what’s the access,” Sharma said.
His comments addressed how privately issued stablecoins, commercial-bank deposits and central-bank money could operate within one financial system. A user paying with a dollar stablecoin, for example, would need the recipient’s bank to recognize the asset and convert it into a deposit liability without creating uncertainty over its value.
“In tangible terms: I could pay through a stablecoin, and the banking infrastructure needs to accept that, transform it into a deposit liability, and provide that recourse.”
Banks would also require a settlement system for payments moving between institutions. Sharma placed central banks at that final layer, where obligations between regulated financial institutions can be settled in central-bank money.
Different forms of cash create different risks
Sharma said investors can benefit from having several forms of digital cash, but each form carries its own economic exposure and redemption structure.
“From an investor-optionality standpoint, having different forms of cash is a good thing. But from a recourse, economic exposure, and risk standpoint, singleness of money is an imperative.”
A commercial-bank deposit represents a liability of the bank, while a stablecoin represents a claim structured by its issuer and governing terms. Central-bank money carries a direct claim on the monetary authority.
Stablecoin users therefore depend on the issuer’s reserves, custody arrangements, and ability to process redemptions. Even when a token tracks one dollar in normal trading, liquidity pressure or concern over its backing can cause it to trade below its stated value.
Interoperability alone would not remove those differences. According to Sharma, banking acceptance, conversion into deposits, and access to a final settlement mechanism must work together if stablecoins are to serve regulated financial markets.
Speaking from a central-bank perspective, Philipp Müller of the Swiss National Bank said commercial banks could issue stablecoins if they chose to do so. His institution, however, must provide banks with a safe payment method suited to their requirements.
“That could be wholesale CBDC, it could still be fiat money. Only time will tell,” Müller said.
His remarks separated retail products from central-bank infrastructure. Commercial banks may offer cash instruments to customers, while the central bank concentrates on settlement between regulated institutions and financial stability.
Dollar stablecoins have created a U.S. policy question
For U.S. users, BlackRock’s argument concerns both the safety of stablecoins and their place in the dollar system. Most large stablecoins reference the U.S. dollar and keep substantial reserves in cash, Treasury bills, or similar liquid assets.
The United States enacted the GENIUS Act in July 2025, creating a federal framework for payment stablecoins. Under the law, only permitted issuers may issue payment stablecoins in the country, subject to reserve, disclosure, and regulatory requirements.
Dollar-linked tokens can extend access to the currency outside conventional banking hours and across national borders. Their growth can also increase demand for the reserve assets issuers use to support redemptions.
As crypto.news previously reported, European Central Bank Executive Board member Isabel Schnabel said dollar-backed stablecoins could strengthen the dollar’s international position as the sector approached a market value of $300 billion. Euro-denominated stablecoins accounted for only a small share of the market, according to her remarks.
The same development has raised concerns in Europe about dependence on dollar payment products. Schnabel supported the digital euro as a public payment option, with a pilot expected in 2027 and potential readiness for issuance targeted for 2029.
Stablecoin reserves also connect token holders with the U.S. government-debt market. When issuers use short-term Treasuries to back circulating tokens, growth in stablecoin supply can translate into additional demand for those securities.
For holders, reserve quality does not make a stablecoin identical to an insured bank deposit. Redemption terms, legal priority, eligible customers and access to deposit protection can differ by product and jurisdiction.
Tokenized markets still depend on settlement cash
Sharma said the infrastructure needed for stablecoins and tokenized deposits begins with bank acceptance before moving to interoperability between institutions and final settlement.
“How will that happen? It’s about the layers of infrastructure coming together, starting with the banking infrastructure, in terms of acceptance and interoperability between tokenised deposits and stablecoins,” he said.
The final stage would involve a settlement layer capable of completing obligations without disrupting existing banking systems. Sharma said the mechanism could be provided in a “potentially unintrusive way,” although he did not specify one technical model.
Tokenized securities make the cash question more urgent because trading an asset on a blockchain does not guarantee that the payment side can settle on the same schedule. Markets may offer continuous transfers while banks, payment systems and foreign-exchange services continue to observe limited operating hours.
A recent examination of the weekend dollar funding gap found that always-open tokenized markets can face liquidity pressure when conventional dollar rails are unavailable. Settlement may remain incomplete even after the asset side of a transaction moves onchain.
During another Day 1 panel, ARK Invest’s Lorenzo Valente put the digital-asset market at about $3 trillion, with stablecoins accounting for roughly $300 billion and tokenized assets between $30 billion and $40 billion.
Valente said crypto had primarily been a retail market during its first decade because institutions lacked scalable tools, privacy, and sufficient compliance controls. He argued that the market had become large enough to draw more institutional capital as those gaps began to narrow.
BlackRock’s Sharma focused instead on how institutions could use different forms of regulated cash without losing a common settlement value. Banks would accept stablecoins, convert them into deposits, and settle their obligations through a layer supported by central-bank infrastructure under the model he described.
SOL has followed the green wave sweeping through the broader cryptocurrency market, surging 6% in the past 24 hours to $105.
Many analysts believe the asset’s rally might be just starting, with one envisioning a potential explosion to as high as $1,300.
Parabolic Jump on the Way?
Earlier this week, the landmark crypto bill known as the CLARITY Act failed in the US Senate and could not advance to formal discussion. The development caused a brief correction for the crypto sector, with Ali Martinez noting that SOL plunged from $101 to around $95.60.
However, he argued the asset found solid support despite the pullback and outlined several bullish factors. First, he pointed to strong institutional demand, with spot SOL ETFs recording several consecutive green weeks and attracting over $200 million in the past month alone. Martinez also mentioned that 3 million tokens were withdrawn from exchanges in the last 30 days and that network growth remains “elevated.”
Shortly after, the analyst opined that a breakout is near, spotting a potential bull flag forming on SOL’s 4-hour chart. He said the key level to watch is $105 and claimed that a sustained close above could confirm the bullish breakout and open the door to an ascent to $130.
Most recently, Martinez claimed that the asset is “ready to go parabolic.” He opined that SOL has spent the last few years building a massive cup-and-handle pattern, with the neckline sitting near $360.
“A confirmed break above that level could mark the beginning of a much larger expansion toward $1,300,” he maintained.
Additional Forecasts
X user CRYPTOKRALI argued that SOL has started to “look interesting” again. The analyst noted that after weeks of compression, the price has finally broken above the descending resistance that kept rejecting every attempt higher. They said $98 has held repeatedly as support, and the strong daily candle through the trendline provides the necessary confirmation.
“Now the key is whether SOL can hold above the breakout and turn that old resistance into support. If it does, I’d be watching $110 first, with room for a bigger continuation if momentum follows through. The downtrend is breaking. Now we see how far the next leg can run,” the analyst added.
Scient also weighed in. The market observer expects one more leg up to around $130, saying they will then de-risk 50% of their spot bags and look to reload if the price dips to $90.
The post Solana to Go Parabolic? Here’s Why SOL Can Explode by 1,100% appeared first on CryptoPotato.
The Philadelphia semiconductor index, known as SOX, rose for a fourth consecutive day on Friday, with a new batch of chip stocks leading the charge. Macom Technology Solutions (MTSI) jumped on a fresh buy rating. On Thursday, the SOX surged 3.1%, led by chipmakers exposed to the buildout of data centers for artificial intelligence. Big gainers included Astera Labs (ALAB),…
Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8

crypto holders – this is your last chance at generational wealth (5 coins)
Met Office issues new ‘summer returns’ forecast and reveals how warm UK will get

Apple’s iPhone 18 goes on sale, and long lines form at stores worldwide

Weekend Open Thread – Corporette.com

Memory prices are slowing because buyers ran out of money

Micron Stock Climbs Above $1,031 as AI Memory Crunch and a $50 Billion Outlook Fuel the Rally
crypto holders – this is your last chance at generational wealth (5 coins)

#sipinvestment #WealthCreation #SavingMoney #Investing #Finance #FinancialEducation

CRYPTO TRADING: If You Don’t Long Bitcoin Before CPI, You’ll Regret It
-

 Tech5 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Crypto World4 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-
 Entertainment7 days ago
News Specials, Movies, Shows, More
-

 Crypto World2 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World6 days ago
Can AI Build a Startup in 72 Hours? Elon Musk's Team Will Livestream the Test
-

 Crypto World4 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-

 Crypto World3 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-

 Business6 days ago
Rivals Sam Altman and Elon Musk Rally Behind Dario Amodei’s Call for a Slowdown in AI Development
-

 Crypto World7 days ago
Robinhood Chain Never Stopped But its Blobs Did Stop Reaching Ethereum For 14 Minutes
-
 NewsBeat4 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World5 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-

 Crypto World3 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-
 Entertainment7 days ago
New Horror Movie Officially Earns a Rare Stephen King Recommendation
-

 Business6 days ago
Marvell: Most Potent Setup Of The AI Factory Decade
-

 Crypto World4 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-

 Crypto World4 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
-
 Crypto World7 days ago
Bitcoin ETFs lose $462.7M as Ethereum funds gain $196.9M
-

 Crypto World5 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-
Business4 days ago
SK Hynix ADRs Fall More Than 6% as Memory Rally Breaks on Fears of Slower AI Spending
-
Crypto World4 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
You must be logged in to post a comment Login