
Crypto World
Fifth Third’s (FITB) Comerica Merger Is Done, Now Comes The Payoff

On September 8, Fifth Third Bancorp (NASDAQ:FITB) said it had finished moving close to 600,000 former Comerica customers and 293 branches across Arizona, California, Florida, Michigan and Texas onto its own systems, a conversion carried out over Labor Day weekend. The move caps the integration that began when the two banks joined forces on February 1, and turns Fifth Third into the ninth-biggest bank in the country by size, with north of $300 billion on the balance sheet. The systems work is finished. Whether that translates into durable earnings growth is the part investors still have to watch.

A Bank Built For Growth Markets
Comerica customers now get the full Fifth Third menu, including the Momentum Banking suite, Early Pay and Extra Time, backed by roughly 1,500 branches and 21,300 ATMs. In Michigan, where Fifth Third already leads in retail deposits statewide and in Detroit, former Comerica customers get 60% more branch access and existing Fifth Third customers get 42% more. Texas is the bigger story. Fifth Third now runs 107 financial centers there and plans to spend nearly $1 billion over five years, adding 150 new centers by 2029 in one of the country’s fastest-growing state economies. By 2030, the bank expects roughly 1,750 branches total, with more than half sitting in Texas, the Southeast, Arizona and California.
The early numbers back up the strategy. Fifth Third pulled in $2.5 billion of consumer deposits from its Comerica Southwest marketing push, and Newline deposits climbed $2.1 billion while fee revenue there jumped 35% year over year. Net interest margin widened 6 basis points sequentially to 3.36%, and the adjusted efficiency ratio improved 480 basis points from the prior quarter to 57.1%. Credit quality held up too. Net charge-offs fell to 30 basis points in the second quarter, the lowest reading since the second quarter of 2023.
The Integration Bill Isn’t Paid Off
None of this came free. Merger-related charges cut $155 million from after-tax income in the second quarter, part of a $0.19 per share drag from certain items, and management says year-to-date merger costs already represent about 65% of what it expects to spend for the full year. Noninterest expense fell 12% from the first quarter but was still up 67% from a year earlier.
Average wholesale funding rose 20% sequentially as the bank leaned on $3.3 billion more in short-term Federal Home Loan Bank advances to bridge a seasonal dip in commercial deposits, a reminder that funding costs can swing while the deal digests. The CET1 capital ratio sat at 9.93%, still below the 10.58% posted a year earlier, reflecting $933 million of pre-tax merger-related capital hits, and Fifth Third did not repurchase any shares in the first half of 2026. Nonperforming loans also crept higher, with the NPL ratio rising to 0.58% from 0.54% the prior quarter.

Kalshi has filed with U.S. regulators to launch perpetual futures contracts linked to individual U.S. stocks, a move that would extend a crypto-style derivatives structure into traditional equity markets. The company’s proposal was submitted to the Securities and Exchange Commission as a rule change and simultaneously sent to the Commodity Futures Trading Commission for review, according to the filing.
The development arrives as Coinbase has also put forward a separate plan to offer single-stock perpetual futures. Both efforts point to growing competition among regulated crypto derivatives venues to adapt perpetual contract mechanics—particularly the use of ongoing funding payments—to equity instruments.
Key takeaways
- Kalshi filed a proposed rule change with the SEC and submitted the related materials to the CFTC to enable perpetual futures tied to specific U.S. equities.
- The contracts would have no fixed expiration date and would use periodic funding payments between long and short positions to keep pricing aligned with the underlying stocks.
- Kalshi said the products would be treated as security futures and cleared through its CFTC-registered clearinghouse, Kalshi Klear.
- Coinbase filed a parallel proposal the same day, and Kraken’s parent company Payward also moved forward with filings through Bitnomial.
- These proposals come amid renewed uncertainty in U.S. crypto-related regulatory pathways following the Senate’s failure to advance the CLARITY Act earlier this month.
Kalshi’s SEC and CFTC filing targets stock-linked perpetuals
According to Kalshi’s rule change submission to the SEC, the company is seeking approval to list perpetual futures tied to individual U.S. stocks. The filing was made on Friday and the CFTC has not yet approved the proposal.
The key feature of Kalshi’s design is that the futures would be structured without a preset expiration date. Instead of settling at a particular maturity, the price relationship to the underlying stock would be maintained through “periodic funding payments” exchanged between long and short positions, a mechanism widely used in crypto perpetual futures.
Kalshi also indicated that the proposed contracts would be treated as security futures products and cleared using Kalshi’s CFTC-registered clearinghouse, Kalshi Klear—an element that matters for market participants because it points to an operating model built around regulated clearing rather than bespoke settlement arrangements.
The filing is available through the SEC’s website as part of Kalshi’s proposed rule change: https://www.sec.gov/files/rules/sro/kalshiex/2026/34-106422.pdf.
Coinbase moves in parallel as the “equity perp” race expands
Kalshi’s submission followed the same day as a separate announcement from Coinbase. Cointelegraph previously reported that Coinbase has also filed a proposal to bring perpetual futures tied to individual U.S. stocks to the market, using the same broad idea: perpetual exposure without a traditional expiration, balanced through periodic funding payments. The earlier Coinbase coverage is linked here: https://cointelegraph.com/news/coinbase-files-to-bring-single-stock-perpetual-futures-to-us-market.
These filings are significant not only because they replicate a familiar crypto derivatives template, but because they attempt to translate it into the equity derivatives framework—where product categorization, clearing arrangements, and regulator oversight can differ materially from crypto-native contracts.
Payward and Bitnomial also seek approval for stock perpetuals
Kalshi and Coinbase were not the only players advancing this concept. Payward—the parent company of crypto exchange Kraken—also filed to offer single-stock perpetual futures. The proposal was submitted through Payward’s Bitnomial Exchange, and Payward said it expects the products to be available to U.S. traders on Kraken.
Payward stated it plans to start with perpetual futures tied to 10 U.S. equities, including Tesla, Nvidia, Apple, Microsoft, and Amazon, and that it is working toward 24/5 trading.
The underlying SEC filing for Payward is available here: https://www.sec.gov/files/rules/sro/btnl/2026/34-106421.pdf. Payward’s public statement is referenced in a post on X: https://x.com/Payward/status/2101013602790490360.
Crypto-style funding meets a policy moment after the CLARITY Act setback
The push for single-stock perpetual futures comes after the U.S. Senate did not advance the CLARITY Act on Sept. 15, according to reporting referenced in the source. The bill failed to reach the 60-vote threshold needed to proceed.
In the immediate aftermath, SEC Chair Paul Atkins said the agency would act “decisively” within its existing statutory authority “with or without legislation,” signaling that regulators may pursue frameworks through other channels even if broader legislation stalls. The source ties this statement to an Atkins post on X: https://x.com/SECPaulSAtkins/status/2100256253645668860.
For investors and traders, these details matter because regulatory clarity is often what determines whether and how new derivative structures can be launched at scale. Perpetual futures can be attractive to market participants seeking continuous exposure, but they also shift how risk is managed over time—especially given the role of funding payments in maintaining price relationships.
Kalshi has already been operating in the perpetual futures space for crypto assets in the U.S. The source notes that Kalshi received CFTC approval for its Bitcoin perpetual contract in May and offers perpetual contracts tied to assets including Ether, Solana, and XRP.
What to watch next
With multiple exchanges now seeking permission to list stock-linked perpetual futures, the immediate focus should be on regulatory review timelines at the SEC and CFTC and whether the proposed contract structures—no fixed expiration plus funding-based pricing alignment—survive scrutiny in practice. Market participants will also want to monitor how funding mechanics and clearing arrangements are handled as these proposals move from filing to approval.
Crypto World
Cathie Wood Sold Palantir and AMD, Then Poured $3.35 Million Into Archer Aviation. Is ARK Betting Big on Flying Taxis?
All companies that have more than $100 million in investments are required to submit quarterly 13F filings that disclose their holdings. Additionally, individuals and funds have to submit filings when their ownership stakes cross 5% and 10%. When holdings reach the 10% threshold, each subsequent trade must be disclosed. Meanwhile, Cathie Wood’s Ark Invest firm takes things to another level when it comes to transparency.
Ark Invest publishes regular updates disclosing all trades for the exchange traded funds (ETFs) that it manages, giving investors a clear look at all the moves made by Wood and her team of analysts and managers. Ark recently disclosed that it made some notable moves, selling shares of Palantir and Advanced Micro Devices and buying roughly $3.35 million worth of Archer Aviation (NYSE: ACHR) for its flagship Ark Innovation ETF.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »

What do Ark’s moves mean for investors?
Ark Invest tends to take a very active approach to portfolio management, and Wood and her team will regularly trim holdings when they feel that stocks have posted big gains and present worthwhile profit-taking opportunities — or simply no longer offer sufficient upside potential to justify the associated risks. Palantir and AMD have generated significant wins for Ark, and recent sales of these stocks look like profit taking rather than a fundamental loss of confidence in the companies.
Coming in as the Ark Innovation ETF’s 11th- and 12th-largest holdings, respectively, Palantir and AMD are larger positions in the fund than Archer Aviation, which ranks as the fund’s 30th-largest holding and accounts for roughly 1.2% of the portfolio by weight. On the other hand, Ark’s move to increase its holdings in Archer Aviation, the maker of the electric vertical take-off and landing (eVTOL) aircraft, clearly reflects growing confidence in the company.
Archer has been making some interesting moves lately, most notably entering into a deal with Boeing to acquire its Insitu, SkyGrid, and Wisk Aero subsidiaries. Integrating these companies could significantly improve Archer’s positioning in eVTOLs, drones, and autonomous aerial navigation. While the deal will result in Boeing receiving a 16.5% stake in Archer, it will also bring the aerospace and defense giant on board as a partner — a development that could prove a substantial boon to the eVTOL company in ways beyond the subsidiary purchase.
On August 19, Ferrovial (NASDAQ:FER) announced it had been selected to deliver the I-24 Southeast Choice Lanes, a 26-mile project running between Nashville and Murfreesboro. It is the largest single capital investment in Tennessee’s history and the state’s first public-private partnership. The price tag is $9.2 billion, though Ferrovial isn’t carrying it alone, since its DriveTN consortium also counts Transurban and Tikehau Star Infra as partners.

The Model Travels Well
Choice lanes are familiar ground for Ferrovial, which has replicated the model in Washington, D.C., Charlotte and Dallas-Fort Worth. On Virginia’s 66 Express corridor, similar lanes shaved up to 50% off peak-hour travel times. That is the pitch for I-24, a stretch of highway that already ranks among the region’s most jammed: drivers who opt in get steadier speeds, and those in the free lanes should see less traffic too.
The business behind the bid looks healthy, too. Ferrovial’s July 28 results showed adjusted EBITDA up 21.6% on a like-for-like basis to €746 million over the first six months of the year, with U.S. highways doing most of the lifting. Those roads are sending cash home as well, since Ferrovial received €357 million in dividends from North America. And the construction order book reached an all-time high of €18 billion, so plenty of work is already in hand. The pipeline keeps filling: Ferrovial bid on I-285 East in Georgia in July, and its D35 Highway bid in the Czech Republic was the most cost-effective submitted, with technical evaluation still underway.
Beyond the roads, the balance sheet looks sturdy. Ferrovial ended the first half with €1.3 billion in net cash, excluding infrastructure projects, meaning cash outweighs debt outside those projects. The airport arm is progressing too: Ferrovial has finished funding the $1.1 billion in equity it pledged for New Terminal One at JFK, and construction there is 92% complete.
Fine Print Worth Reading
Start with the line that looks worst on the page. Net profit for the first half of 2026 came in at €258 million, versus €540 million for the same period of 2025. That earlier figure included capital gains from asset rotation, which makes the comparison harsh, but the mismatch is still there: EBITDA climbed while reported profit fell.
Then there is the work itself. Construction turned 3.5% of revenue into adjusted EBIT, right on target, so there isn’t much room for a costly overrun on a big job. North America also accounts for 47.9% of the order book, so plenty rides on one region. The $24.8 billion in concession value cited for the project is a figure for Tennessee, not a profit forecast for Ferrovial. And a winning bid is not a finished road: I-24 still has to be financed, built and operated, and the CEO talks in terms of decades.
Crypto World
Massive Crypto Acquisition: Why S&P Global Is Buying Blockchain Security Giant OpenZeppelin
S&P Global (SPGI) has agreed to acquire OpenZeppelin, the smart contract security firm whose open-source code library sits behind more than $37 trillion in transferred value, and will run the auditor as a standalone business unit under its own name.
Founded in 2015, OpenZeppelin pairs security assessments and secure development services for decentralized finance (DeFi) protocols and traditional financial institutions with OpenZeppelin Contracts, a free library of standard token and contract implementations that the vast majority of the largest stablecoins and tokenized funds are built on.
The $37 trillion counts cumulative value moved through contracts built with that library, according to the announcement. OpenZeppelin has run more than 900 security engagements, including a late-2021 review that flagged a bug putting $15 billion in Convex Finance deposits at risk before it was patched.
“Our digital assets strategy centers on bringing trusted data, benchmarks and transparent risk assessment to markets as they move onchain,” said Yann Le Pallec, President of S&P Global Ratings.
Le Pallec stated that OpenZeppelin will complement the company’s smart contract and onchain technology risk assessment capabilities, giving traditional institutions and DeFi-native firms “the confidence to build and transact in this new environment.”
OpenZeppelin Keeps Its Name and CEO
OpenZeppelin will continue operating as its own unit inside S&P Global, with CEO Demian Brener staying in charge and reporting to Le Pallec. Financial terms were not disclosed, and S&P Global said the purchase is not expected to have a material impact on its financial results.
“OpenZeppelin’s standards, technology, and expertise already power the infrastructure behind the world’s leading stablecoins, tokenized funds, DeFi protocols, and onchain markets,” said Demian Brener, CEO of OpenZeppelin. “With S&P Global, that foundation reaches a broader set of organizations entering this market, as well as the blockchain networks and DeFi protocols gaining institutional adoption.”
Jefferies is serving as financial advisor to S&P Global, with Clifford Chance as legal counsel. FT Partners advises OpenZeppelin on the financial and strategic side, and Cooley on legal.
Deal Lands Amid Tokenization Push
S&P Global’s index arm has published crypto benchmarks since 2021, when S&P Dow Jones Indices launched a broad market index tracking more than 240 coins alongside its dedicated Bitcoin and Ethereum gauges, with pricing data supplied by Lukka.
On the same day as the acquisition, the US Securities and Exchange Commission (SEC) opened the door to secondary trading of tokenized US stocks through a temporary innovation exemption that requires the smart contracts involved to be publicly auditable and to run on public, permissionless blockchains.
The post Massive Crypto Acquisition: Why S&P Global Is Buying Blockchain Security Giant OpenZeppelin appeared first on CryptoPotato.
Crypto World
B. Riley and Roth Capital Both Cut Targets as AI Growth Struggles to Offset Legacy Declines
On September 3, 2026, eGain Corporation (NASDAQ:EGAN) reported fiscal 2026 fourth-quarter and full-year results. Full-year revenue rose 3% to $91.1 million, AI customer revenue grew 20%, and adjusted EBITDA climbed to $13.6 million, a 15% margin, up from 10% a year earlier. Operating cash flow reached a record $21.2 million.
Fiscal 2027 guidance calls for total revenue of $84.5 million to $86 million, below fiscal 2026’s total, with adjusted EBITDA margin guided to just 1% to 2%.

Iakov Filimonov/Shutterstock.com
A Gartner Nod and a Widening Pipeline Back the Long-Term AI Bet
Despite the weaker fiscal 2027 outlook, eGain still has several indicators that support management’s longer-term AI thesis. In July, Gartner released its inaugural Magic Quadrant covering customer service knowledge management systems, placing eGain Corporation (NASDAQ:EGAN) in the Leaders category and positioning it highest for ability to execute and furthest for completeness of vision. CEO Ashu Roy described the recognition as evidence that AI-focused knowledge management is emerging as a distinct layer of enterprise infrastructure. New customer wins rose 27% year-over-year, while the number of pipeline opportunities carrying at least $500,000 in annual recurring revenue doubled. Customers are also showing greater willingness to pay for pilot programs before moving to broader deployments, replacing the free-trial approach eGain had previously used. In one early testing and certification engagement, self-service resolution reached 95%. Cash increased to $73.3 million from $62.9 million, despite the company repurchasing 1.6 million shares for $11.5 million. Management is targeting $100 million to $120 million in AI customer ARR by fiscal 2030, compared with $54 million in fiscal 2026.
Analysts on Record Say the Legacy Runoff is Outrunning the AI Ramp
B. Riley’s Erik Suppiger cut his target to $6 from $10.50 on September 8, 2026, keeping a Neutral rating, saying eGain Corporation (NASDAQ:EGAN) beat fiscal Q4 estimates but issued fiscal 2027 guidance well below consensus, driven by accelerating churn in the legacy non-AI business that is significantly reducing next year’s revenue and profitability.
Roth Capital’s Richard Baldry went further the same day, downgrading eGain Corporation (NASDAQ:EGAN) to Neutral from Buy and cutting his target to $7 from $21, citing a meaningful revenue pullback and roughly breakeven adjusted EBITDA for much of the year as legacy attrition more than offsets what he called “modest” AI revenue growth.
Kalshi has filed with U.S. regulators to launch perpetual futures linked to individual US stocks, extending the “crypto-style” derivatives model into traditional equity trading. The prediction market operator submitted its proposed rule change to the Securities and Exchange Commission (SEC) and separately to the Commodity Futures Trading Commission (CFTC) for approval on Friday, with the CFTC still pending a decision.
The proposal would create contracts without a preset expiration date and would rely on periodic funding payments between long and short positions to keep the futures price aligned with the underlying equities. Kalshi said the products would be treated as security futures and cleared through its CFTC-registered clearinghouse, Kalshi Klear.
Key takeaways
- Kalshi filed for single-stock perpetual futures with the SEC and CFTC; CFTC approval is still outstanding.
- No expiration date: contracts would remain open-ended, with periodic funding used to maintain price alignment.
- Security futures framework: Kalshi says the contracts would be cleared through its CFTC-registered clearinghouse, Kalshi Klear.
- Racing competitors: Coinbase submitted a related proposal the same day, and Payward (Kraken) also filed to expand the concept.
What Kalshi’s proposal would change in US equities
Perpetual futures are a derivatives format that has been widely used in crypto markets, where contracts do not settle on a predetermined maturity date. Instead, traders typically rely on a funding mechanism—payments exchanged between long and short positions—to encourage the perpetual contract to track the spot price of the underlying asset.
In Kalshi’s filing, the exchange described contracts tied to individual US stocks that would similarly avoid a fixed expiration date and use periodic funding payments to keep contract prices in step with the referenced equities. Kalshi also framed the offering as “security futures products,” which would place the proposal in a specific regulatory lane and allow for clearance via Kalshi Klear.
Coinbase and Payward join the single-stock perpetual push
Kalshi’s filing lands in the middle of a broader push by crypto firms and crypto-linked trading venues to bring perpetual-style derivatives to the US stock market.
According to a separate report, Coinbase submitted its own proposal to offer perpetual futures tied to individual US stocks on the same day. The timing suggests a coordinated wave rather than isolated experimentation.
Payward—the parent company of crypto exchange Kraken—also moved forward. Earlier coverage of the filings noted that Payward, through its Bitnomial Exchange, submitted a proposal to offer single-stock perpetual futures and said it intends to make them available to US traders on Kraken. Payward stated it plans to start with perpetual futures linked to 10 equities, naming Tesla, Nvidia, Apple, Microsoft, and Amazon among them, and said it is working toward 24/5 trading.
Kalshi already has a precedent: crypto perps
This is not Kalshi’s first attempt at perpetual derivatives. The company already offers perpetual futures tied to cryptocurrencies in the US, including Bitcoin, Ether, Solana, and XRP. Kalshi received CFTC approval for its Bitcoin perpetual contract in May, demonstrating it has experience operating within the CFTC’s regulatory framework for these products.
That prior track record may be part of why Kalshi is now attempting to replicate the structure—perpetual contracts paired with funding payments—within a different underlying asset class. Still, investors should note that the regulatory posture for equities and security futures differs from crypto spot and crypto derivatives, even if the trading mechanics are familiar to perp users.
Regulatory momentum after the CLARITY Act setback
The filings come shortly after the CLARITY Act failed to advance in the US Senate on Sept. 15, falling short of the 60 votes required to proceed. The outcome has raised questions about whether comprehensive crypto legislation would move forward quickly.
In a statement reported following the vote, SEC Chair Paul Atkins said the agency would “act decisively” within its existing statutory authority “with or without legislation.” That message aligns with what traders and market operators are now seeing: rather than waiting for new legislation, firms are moving ahead with product proposals that fit within existing regulatory pathways.
Kalshi’s SEC and CFTC submissions, along with parallel filings from Coinbase and Payward, effectively test how the current rulemaking and approval processes handle perpetual derivatives when the underlying assets are equities instead of crypto tokens.
What to watch next
For traders and market participants, the key next step is regulatory: the CFTC must decide on Kalshi’s proposal, and other filings—such as Coinbase’s and Payward’s—will also need to clear their respective review processes. The most important question is how quickly regulators will reconcile perpetual contract mechanics with security futures requirements, and whether the early product schedules described by applicants translate into approved, widely accessible trading.
The new ASSX fund offers 2x daily exposure to Strive shares, giving traders a leveraged way to bet on the Bitcoin treasury company.
On August 11, Franco-Nevada (NYSE:FNV) posted second-quarter results that dwarfed last year’s numbers, with revenue up 57% to $580.9 million and gold equivalent ounces sold climbing 18% to 132,405. Net income rose 43% to $354 million, and the royalty giant says it’s now tracking toward the upper half of its 2026 guidance range. But the line that matters most sits further down the release: after two years of halted production, the company’s Cobre Panamá stream started moving again, and how that story plays out will shape the next few years more than this one strong quarter does.

Every Metric Moved The Same Direction
Franco-Nevada didn’t just grow; it grew everywhere at once. Adjusted EBITDA rose 45% to $529.7 million, or $2.75 a share, while operating cash flow climbed 12% to $482.5 million. Zoom out to the first half of the year and the numbers get even bigger: revenue hit $1.23 billion, up 67% and a half-year record, while adjusted net income reached $807.5 million, up 82% from the first half of 2025. Gold, silver and platinum group metals made up 86% of second-quarter revenue, and 88% of that revenue came from the Americas, led by South America and Canada.
The company also kept buying while the results rolled in. With $4.3 billion in available capital as of June 30, Franco-Nevada closed four separate royalty deals: a $40 million royalty portfolio from Victoria Gold Corp. covering Yukon and Nevada assets on April 16, a $32.9 million royalty on Rox Resources’ Youanmi gold project in Australia on May 29, a $2.0 million royalty tied to Equinox Gold’s Greenstone mine in Canada on June 22, and, after quarter-end on July 15, an $8.4 million royalty on Gorilla Gold Mines’ Comet Vale project. CEO Paul Brink pointed to that capital cushion as fuel for “a strong pipeline of deal opportunities” still ahead.
The Mine Nobody Fully Controls
Cobre Panamá is still not a normal mine. It remains in Preservation and Safe Management, with actual production halted, and its longer-term fate now rests with a ministerial commission the Panamanian government set up during the quarter to weigh an integral audit, published June 19, that found 87.7% compliance. What restarted on April 7 was narrower: government approval to process and export stockpiled ore already sitting on site, and by May the company had commissioned its first processing train and produced initial copper concentrate.
Even that narrower restart runs through someone else’s numbers. First Quantum, the mine’s operator, estimates 30,000 to 40,000 tonnes of copper will come out of the stockpiles in 2026, out of about 70,000 tonnes total once 2027 processing is included. Franco-Nevada’s own stream deliveries, expected near 23,100 gold ounces and 265,000 silver ounces, depend on First Quantum actually selling that concentrate under its offtake contracts, are only set to begin in the third quarter of 2026, and just a third of the total is expected to land by year-end. Meanwhile, production across the rest of the portfolio is weighted toward the back half of 2026, so a meaningful chunk of the guidance upgrade still has to show up.
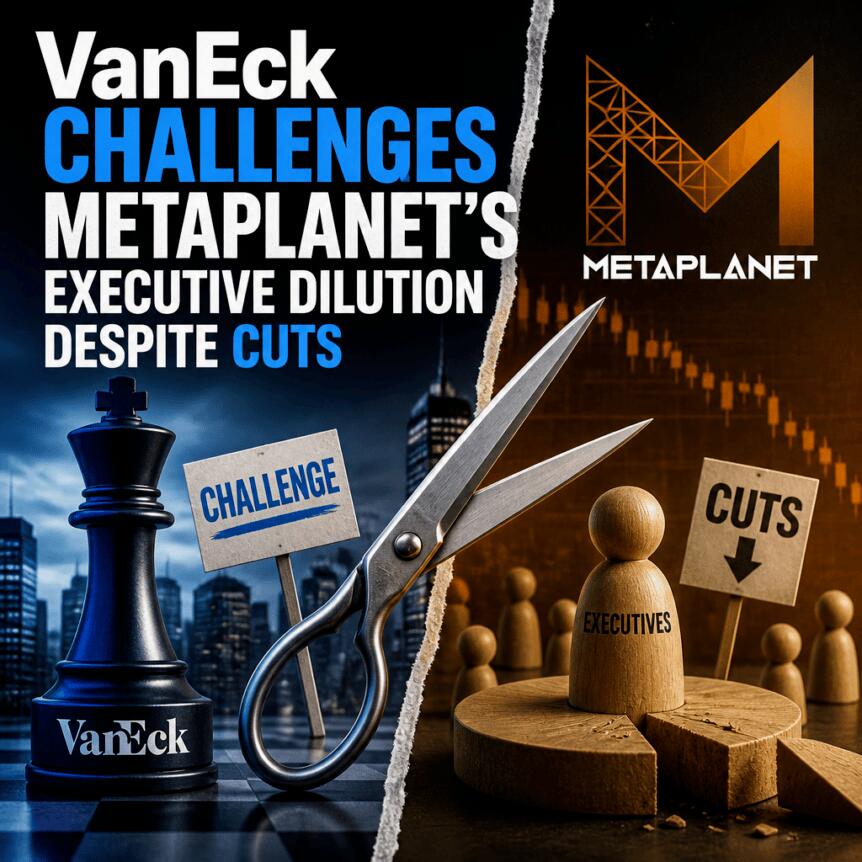
Asset manager VanEck has issued a sharp critique of Metaplanet’s executive compensation design, arguing that the Japanese corporate Bitcoin treasury’s efforts to limit shareholder dilution do not go far enough. In a Friday analysis of compensation practices across the 10 largest digital asset treasury companies, VanEck concluded that Metaplanet’s structure is the only one that falls into the report’s lowest tier.
VanEck’s comparison points to both the size of Metaplanet’s equity compensation plan and the degree of personal exposure for its officers. The firm said Metaplanet’s equity plan equals 14.7% of fully diluted shares, while officer exposure stands at 8.2%—figures VanEck describes as materially higher than peers.
Key takeaways
- VanEck rated Metaplanet’s executive compensation as “Bad,” the only company in its lowest category in a peer review of 10 major Bitcoin treasury firms.
- VanEck cited Metaplanet’s equity plan at 14.7% of fully diluted shares and officer exposure at 8.2%—far above peer averages of 0.8% (officer exposure) and an overall plan nearly four times lower than Metaplanet.
- VanEck said a prior compensation mechanism allowed Metaplanet’s option pool to expand automatically as new shares were issued to fund Bitcoin purchases.
- While Metaplanet ended the automatic adjustment in August and reduced its option pool by 41% in September, VanEck argued the fixes still “fall well short of the mark.”
- VanEck urged Metaplanet to reverse a roughly 273 million-share expansion created by the earlier adjustment clause and to replace remaining rights with a shareholder-approved plan.
Why VanEck says Metaplanet’s incentives misalign
VanEck’s report evaluates executive compensation among the largest publicly traded digital asset treasury companies, focusing on how equity plans may contribute to dilution for existing shareholders. In that framework, VanEck said Metaplanet stands out for the scale of both its equity reserve and executive ownership exposure.
The asset manager argues that Metaplanet’s officer exposure—8.2%—is roughly 10 times the 0.8% average of the other nine companies reviewed. It also said Metaplanet’s broader equity plan is nearly four times the peer average, raising concerns that incentives may be overstated relative to what shareholders receive in return.
A contrast with Strategy’s “fixed” approach
VanEck’s report includes a direct comparison with Strategy, described as the largest corporate Bitcoin holder. According to VanEck, Strategy’s equity plan equals 2% of fully diluted shares, and officer exposure is 0.5%. VanEck rated Strategy’s compensation structure as “Good,” noting that its equity reserve is fixed and that plan increases require a shareholder vote.
That difference—between automatic scaling and shareholder-approved adjustments—appears to be central to VanEck’s critique. The implication for investors is straightforward: compensation structures that expand in lockstep with capital raises (even those done to purchase Bitcoin) can magnify dilution pressure over time.
The mechanism VanEck says drove past dilution
VanEck said part of the disparity traces back to Metaplanet’s former compensation setup. In the period before changes, the company’s option pool could grow automatically as Metaplanet issued shares to finance Bitcoin acquisitions. VanEck reported that this mechanism expanded the pool from 46 million shares to 319.5 million shares, adding about 273 million potential shares.
At the time, the expansion drew criticism from some Metaplanet shareholders. Earlier coverage by Cointelegraph noted backlash over the way the adjustment mechanism increased the pool, prompting calls for cancellation of the additional potential shares created by the clause (see Cointelegraph’s reporting).
Metaplanet’s cuts—VanEck still not satisfied
In response to the controversy, Metaplanet ended the automatic adjustment mechanism in August. It also reduced the overall pool by 41% in September, from 319.5 million shares to 188.2 million shares (Cointelegraph previously reported on the cut in its coverage).
However, VanEck argued that the newer arrangement does not fully correct the underlying issue. The firm stated that the changes still “fall well short of the mark,” and it said Metaplanet should address the roughly 273 million-share expansion attributable to the earlier adjustment clause.
VanEck further noted that unless past grants are clawed back, much of the dilution already occurred—an important distinction for shareholders. Even if future option pools are reduced, prior equity rights may continue to affect share count and per-share metrics depending on exercise and conversion dynamics.
In practical terms, VanEck’s recommendation was that Metaplanet reverse the additional share potential created by the earlier mechanism and replace the remaining rights with a compensation plan approved by shareholders.
What VanEck wants Metaplanet to do next
Beyond undoing earlier expansion, VanEck recommended restructuring compensation around more shareholder-aligned metrics. The firm said executive pay should be tied to a measure such as Bitcoin per fully diluted share, rather than relying on mechanisms that expand when shares are issued for Bitcoin purchases.
VanEck also called for a written grant-timing policy. The intent, as implied by the recommendations, is to reduce ambiguity around when equity is granted and to make compensation practices easier for investors to assess against stated dilution goals.
For context, Metaplanet is a Japanese Bitcoin treasury company and currently ranks as the third-largest publicly traded corporate Bitcoin holder, holding 43,000 BTC according to BitcoinTreasuries.net.
Investors looking at corporate Bitcoin treasuries may want to watch whether Metaplanet can translate “anti-dilution” intentions into enforceable structural changes—particularly around whether prior equity expansion is reversed or mitigated. VanEck’s critique suggests the key question is not only how the pool is handled going forward, but what happens to the dilution already embedded in past grants.
Kalshi has filed to offer perpetual futures tied to individual US stocks, joining Coinbase in a push to bring crypto-style derivatives to traditional equity markets.
The prediction market filed the proposed rule change with the Securities and Exchange Commission and submitted it to the Commodity Futures Trading Commission (CFTC) for approval on Friday. The CFTC has yet to approve the proposal.
The proposed contracts would have no preset expiration date and would use periodic funding payments between long and short positions to keep their prices aligned with the underlying stocks. Kalshi said the contracts would be treated as security futures products and cleared through its CFTC-registered clearinghouse, Kalshi Klear.
The filing comes the same day Coinbase submitted a separate proposal to offer perpetual futures tied to individual US stocks, as both companies look to bring a derivatives product popular in crypto markets to traditional equities.
Kalshi already offers perpetual futures tied to cryptocurrencies in the US, including Bitcoin (BTC), Ether (ETH), Solana (SOL) and XRP (XRP), after receiving CFTC approval for its Bitcoin perpetual contract in May.
Related: DoubleZero adds Kalshi election market data ahead of US midterms
US stock perpetual futures race expands
Kalshi and Coinbase were not alone in filing to bring single-stock perpetual futures to the US market. Payward, the parent company of crypto exchange Kraken, also filed through its Bitnomial Exchange to offer the products, with plans to make them available to US traders on Kraken.
Payward said it plans to initially offer perpetual futures tied to 10 US equities, including Tesla, Nvidia, Apple, Microsoft and Amazon, and is working toward 24/5 trading.
The filings come days after the CLARITY Act failed to advance in the Senate on Sept. 15, falling short of the 60 votes needed to proceed.
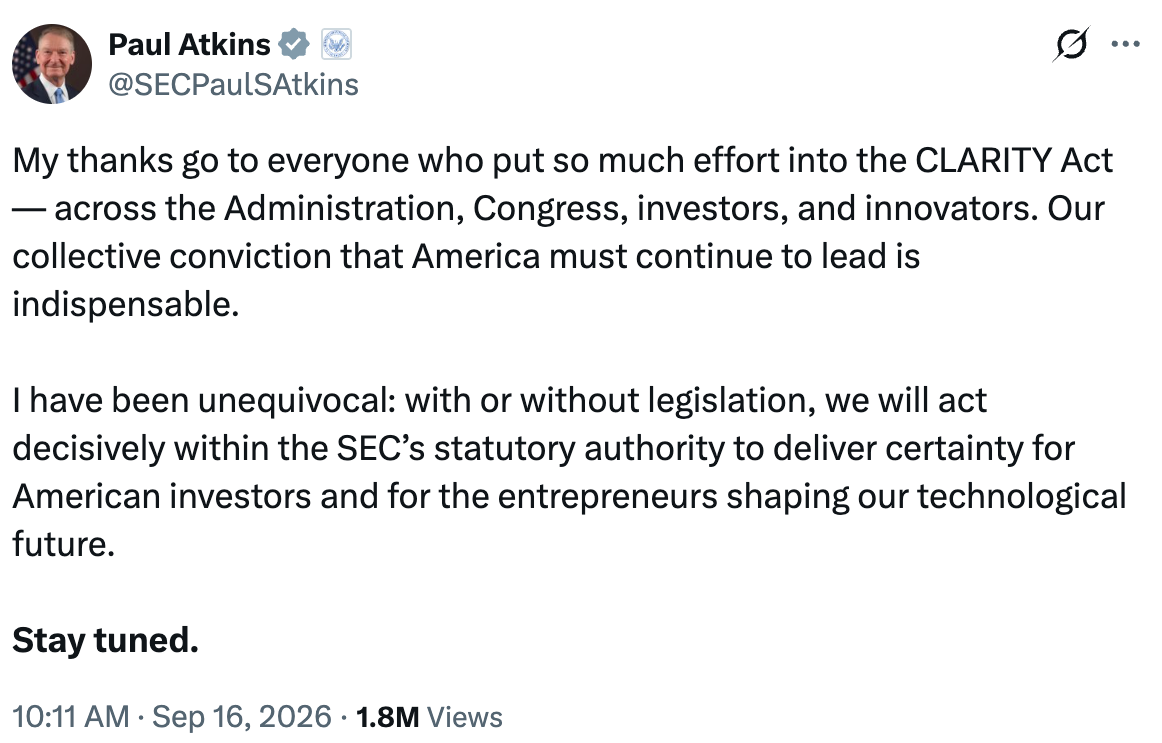
A day after the vote, SEC Chair Paul Atkins said that “with or without legislation,” the agency would “act decisively” within its existing statutory authority to provide regulatory certainty for American investors and entrepreneurs.
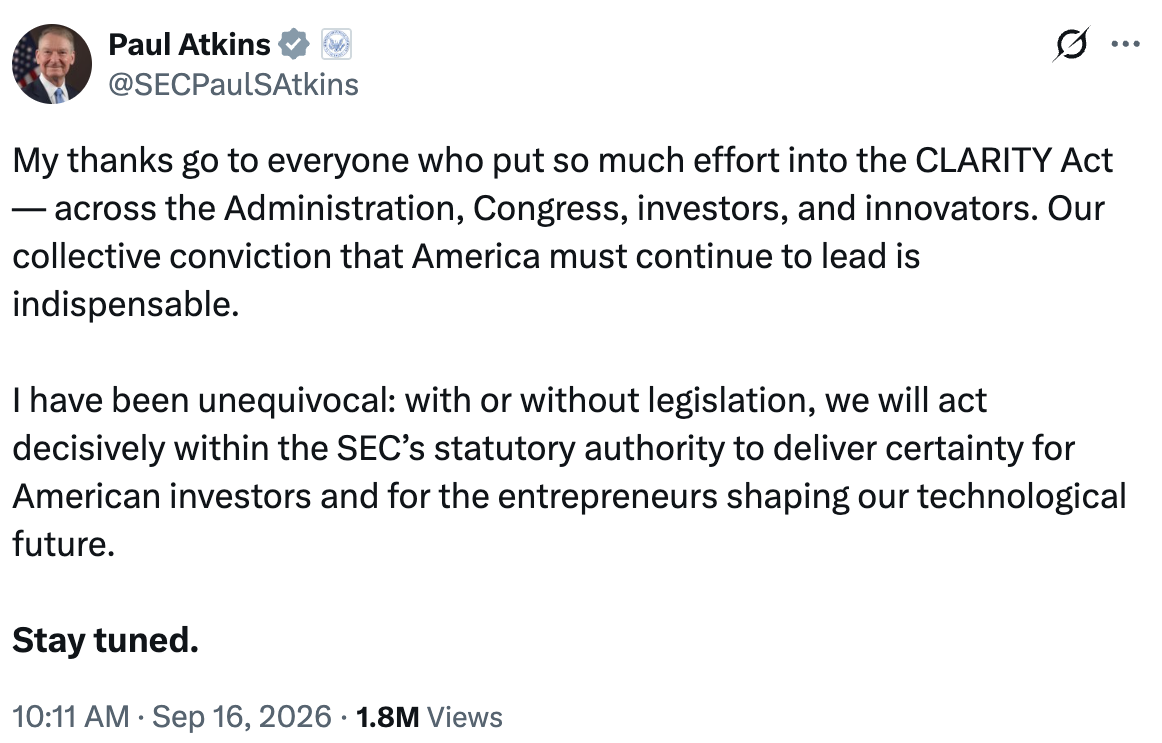
Source: Paul Atkins

‘Time To Broaden The Horizon’: NDTV Launches AM Green IGPL Golf Pro-Am Season 2

Flock reportedly tries to shrink workforce with employee buyouts

Missing Bolton girl, Lillia, has been found safe and well




-
 Fashion1 day ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech6 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Crypto World5 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-

 Crypto World5 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-

 Crypto World4 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-

 Crypto World3 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-
 NewsBeat22 hours ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World5 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-
 Crypto World4 days ago
Robinhood engineers charged over $50K crypto scheme
-

 Crypto World6 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-

 Business7 days ago
Rivals Sam Altman and Elon Musk Rally Behind Dario Amodei’s Call for a Slowdown in AI Development
-
 NewsBeat5 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World5 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-
Business5 days ago
SK Hynix ADRs Fall More Than 6% as Memory Rally Breaks on Fears of Slower AI Spending
-
 Crypto World21 hours ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World5 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
-
 NewsBeat7 days ago
Last Night of the Proms pays moving tribute to Dolly Parton as Sheridan Smith wears a gold sequin jumpsuit in memory of the Queen of Country
-
Crypto World5 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
-
 Crypto World6 days ago
Goldman Sachs backs 25bp Fed hike after CPI
-

 Crypto World6 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
You must be logged in to post a comment Login