Connect with us

Business & Hustles

$1.5 trillion wealth transfer is coming. How India’s next-gen HNIs are rebuilding family portfolios

Published

on

$1.5 trillion wealth transfer is coming. How India’s next-gen HNIs are rebuilding family portfolios
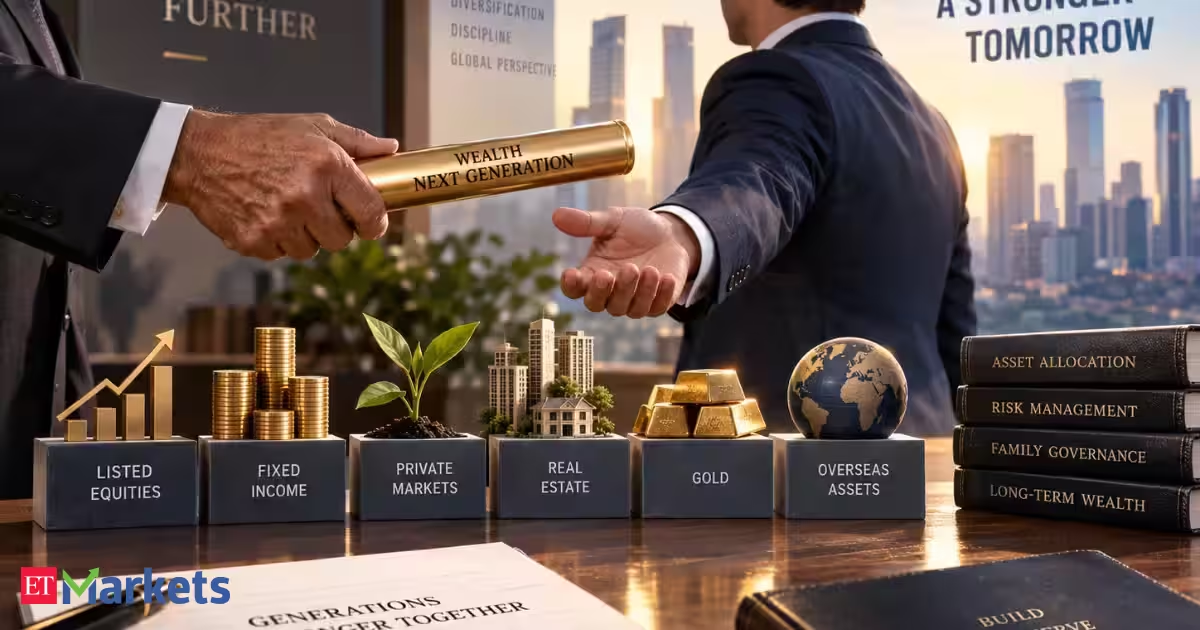
As much as $1.5 trillion in wealth is expected to change hands between generations in India over the next decade, setting the stage for a fundamental redesign of family portfolios. Akash Hariani, joint managing director at Motilal Oswal Private Wealth, says next-generation HNIs are demanding consolidated reporting, formal asset-allocation frameworks, investment committees and professional manager selection.

Their portfolios are increasingly being built across listed equities, fixed income, private markets, real estate, gold and overseas assets, while concentrated bets are being ring-fenced to a smaller pool of capital.

Edited excerpts from a chat on how HNIs are investing, the risks involved and strategies:

India is approaching a significant intergenerational wealth transfer. What is actually changing when wealth moves from founders to the next generation: asset allocation, risk appetite, investment horizon or simply the way investment decisions are made?

Advertisement

All four are changing, but the biggest change is probably in how investment decisions are made.


The founder generation often created wealth through concentration: one business, one industry and, predominantly, one country. The investment approach outside the operating business was also often relationship-led and relatively informal.
The next generation is beginning to look at the family’s wealth more like an institutional balance sheet. They want to understand the family’s total exposure across the operating business, listed markets, private investments, real estate, debt and global assets. Investment committees, formal asset-allocation frameworks, consolidated reporting and professional manager selection therefore become more important.This is already visible in the evolution of Indian family offices. The Julius Baer-EY Family Office Playbook notes a shift from founder-centric decision-making towards family constitutions, investment committees, formal investment policies and professional management. This becomes particularly relevant as an estimated US$1.3-1.5 trillion of wealth is expected to transfer between generations in India over the next decade.

Their risk appetite is not necessarily higher; it is more segmented. They may want the family’s core wealth to be diversified and professionally managed, while simultaneously being comfortable taking concentrated risk in a smaller pool of capital through private equity, venture investing, direct deals or new-age themes.

Their involvement is also much greater. They do not simply want a recommendation; they want to understand the investment thesis, risks, valuation and alternatives before taking a decision. In a 2026 CFA Institute survey, nearly 70% of young investors using a paid adviser interacted with that adviser at least monthly.

How differently are NextGen HNIs allocating their portfolios compared with their parents? Can you quantify the typical allocation today across listed equities, fixed income, private markets, real estate, gold and overseas assets?

Advertisement

There isn’t one credible “typical NextGen portfolio”, and we should be careful about creating one. Asset allocation for a 35-year-old technology entrepreneur who has sold his business should be very different from that of a 35-year-old member of a promoter family whose majority of wealth remains invested in the family business.

Available Indian UHNI data nevertheless shows where portfolios are today. A Julius Baer-EY study done in 2026 says many Indian family offices are now allocating 40-45% to alternatives, although the definition is broad and includes PE, VC, private credit, AIFs, REITs and InvITs. These are different investor cohorts, but the contrast itself illustrates how rapidly sophisticated portfolios are evolving.

For a diversified NextGen UHNI, a reasonable strategic range could look something like:

· Listed equities: 25-35%

Advertisement

· Fixed income: 15-25%

· Private markets/alternatives: 15-25%

· Real estate/real assets: 10-20%

· Gold: 5-10%

Advertisement

Separately, we would increasingly look for 10-20% of the overall portfolio to have international exposure. That is not an additional asset class: it can sit within equities, fixed income or private markets.

The important shift versus the previous generation is therefore not one dramatic change in percentage allocation. It is lower dependence on a few physical assets, greater use of financial assets and private markets, and deliberate geographic diversification.

Private equity, venture capital and pre-IPO opportunities have become increasingly accessible to wealthy investors. Are HNIs genuinely making superior risk-adjusted returns in private markets, or has the narrative run ahead of actual performance after accounting for illiquidity and failed investments?

Private markets can certainly create superior returns, but we would be careful about treating that as a universal outcome. The dispersion between managers and deals is significantly wider than in listed markets, so access alone does not guarantee alpha. The attraction is genuine. Private markets allow investors to participate in companies earlier in their growth cycle, access businesses and sectors that may not yet be available in public markets, and potentially earn an illiquidity premium. In India, this opportunity set has expanded materially: Category II AIFs alone had raised over Rs 4.4 lakh crore (drawdown amount) and invested more than Rs 4.1 lakh crore by March 2026.

Advertisement

However, headline IRRs can sometimes overstate the investor experience. Investors need to look beyond IRR to DPI, TVPI, actual cash distributions, holding periods and the proportion of investments that have been written down or failed. A portfolio showing a high marked-to-market IRR but having returned little capital is very different from one where those returns have actually been realised. This has become particularly relevant after the 2020-22 period, when abundant liquidity led to aggressive entry valuations across private equity and venture capital. Globally, many of those vintages are now taking longer to exit and are likely to deliver lower returns than originally targeted.

The other important point is manager selection. Private-market returns tend to show substantial dispersion, which means investing with a strong manager, with differentiated sourcing and disciplined entry valuations, matters considerably more than simply allocating to the asset class. Even available Indian AIF performance data illustrate this: median returns can look reasonable, while top-quartile private-equity managers have generated materially stronger outcomes.

For HNIs, therefore, we see private markets as an important portfolio allocation rather than a replacement for listed equities. The right investor is someone who has sufficient liquidity to meet the drawdown, can tolerate a 7-10 year holding period, can diversify across managers and vintages, and has access to high-quality opportunities rather than simply the most widely distributed deals.

Pre-IPO investing requires even greater discipline. A short distance from an IPO does not automatically make an investment low-risk. The relevant questions are still the entry valuation, earnings quality, dilution, lock-ins, exit visibility and the valuation at which the eventual IPO can realistically take place.

Advertisement

So the opportunity is real, but the narrative becomes dangerous when illiquidity itself is mistaken for alpha. For us, the objective is not to maximise private-market exposure: it is to access situations where the expected return sufficiently compensates investors for illiquidity, opacity and execution risk.

We have seen several high-profile IPOs emerge from portfolios of private-market investors. Are HNIs increasingly using pre-IPO investing as a wealth-creation strategy? What returns should investors realistically expect, and what are the biggest risks they underestimate?

Yes, pre-IPO investing has become a meaningful part of the UHNI opportunity set. But we would be very cautious about treating “pre-IPO” as an investment thesis by itself.

A few years ago, investors could sometimes buy a company in the private market and benefit simply from a valuation re-rating when it entered the public market. That gap has narrowed materially. An analysis by Mint of 43 companies using Tracxn and Venture Intelligence data found that while select technology and consumer companies in 2021 listed at roughly twice their previous private-market valuations on average, by 2025 the average IPO premium over the last private round had compressed to around 20%, with several companies listing below their previous private-market valuations.

Advertisement

Therefore, the return has to come increasingly from growth in the underlying business rather than merely from the transition from “private” to “listed”.

The biggest risks investors underestimate are entry valuation, the IPO getting postponed, deterioration in the business before listing, governance and cap-table complexity, dilution, and the ability to actually exit after listing. Pre-IPO investors also need to understand applicable lock-ins: under current SEBI ICDR requirements, pre-offer equity is generally subject to a six-month post-allotment lock-in, subject to specified exemptions.

An IPO is an exit route, not an investment thesis. The company still needs to be worth owning even if the IPO takes three years instead of one.

Indian equities have created enormous wealth over the past decade, particularly in midcap and smallcap stocks. At current valuations, how are your HNI and UHNI clients positioning their equity portfolios? Where are you still finding attractive opportunities, and where are you advising clients to reduce exposure?

Advertisement

Indian equities today are being shaped by what we would call “a tale of two currents”. On one side, the domestic backdrop remains supportive: growth is resilient, earnings are recovering and structural themes around manufacturing, formalisation and capex remain intact. On the other, global headwinds have intensified through higher crude, elevated bond yields and geopolitical uncertainty. That combination argues for staying invested, but being far more selective about where incremental capital is deployed. Recent market weakness despite strong domestic growth captures this tension well.

From a valuation perspective, we would describe the market as neither expensive enough to warrant a broad retreat, nor attractive enough to justify indiscriminate buying. The sharp excesses seen earlier have moderated, but several pockets, particularly in midcap and smallcap stocks, still discount fairly optimistic growth assumptions. That makes this a stock-picker’s market, where earnings delivery and entry valuation matter more than index-level calls.

For HNI and UHNI portfolios, we continue to prefer selective exposure to structural growth themes rather than broad thematic bets. We still see opportunities in areas such as defence and aerospace, specialised manufacturing, electronics and niche industrials, energy transition and power infrastructure, financialization of savings, and discretionary consumption. These are themes with multi-year growth drivers, but the opportunity increasingly lies in identifying companies with execution visibility, balance-sheet strength and valuations that leave room for returns, not simply owning the sector.

At the same time, we would be cautious in segments where price has run materially ahead of fundamentals, particularly where valuations are being sustained more by thematic excitement than by near-term earnings. Also, we would like to be underweight on the segment which is likely to see muted earnings growth.

Advertisement

So our positioning is not about reducing equity exposure aggressively, but about narrowing conviction. We would avoid chasing broad market beta at current levels and instead favour businesses where structural growth, earnings visibility and valuation discipline come together. In this environment, the opportunity is still meaningful, but it is increasingly micro rather than macro, and stock-specific rather than index-wide.

Considering the current scenario, we continue to maintain a Neutral view on Equities. Portfolio Allocation: 40% allocation to Hybrid/Large caps, 10% to Global and 50% allocation to Midcap & Smallcap (continuing overweight position).

We believe that hybrids can do similar to largecap while keeping the downside lower amid the volatile scenario. On the other hand, allocation to pure equity-oriented strategies should be done in a staggered manner.

Global diversification has become a major talking point among wealthy Indians. How much of an UHNI portfolio should ideally be invested overseas today?

Advertisement

For most India-based UHNIs, we would think of 10-15% of financial assets overseas as a reasonable strategic range, although the appropriate number depends heavily on the family’s existing exposures.

If almost all of someone’s wealth is already linked to an Indian operating business, Indian real estate and Indian equities, the case for a higher overseas allocation is much stronger. Conversely, someone with substantial overseas business interests, properties or foreign-currency assets may already have meaningful global exposure.

There are three reasons for doing it:

First is country diversification. India’s long-term growth outlook may remain compelling, but the family’s entire balance sheet does not need to depend upon one economy.

Advertisement

Second is currency diversification or a hedge against INR depreciation.

Third, and often underappreciated, is opportunity diversification. Certain sectors and companies simply do not exist at a comparable scale in the Indian listed market. Global portfolios provide access to technology platforms, semiconductors, healthcare innovators, global industrial companies and international private markets.

This is also consistent with how sophisticated family offices globally are thinking. UBS’s 2026 Family Office Report found an increased emphasis on diversification across assets, currencies and regions, rather than making binary calls on individual countries.

For resident Indians, implementation also has to take account of the regulatory route and the US$250,000 per person per financial year LRS limit for permitted overseas remittances.

Advertisement

Being bullish on India and diversifying globally are not contradictory views. You diversify overseas not because you are negative on India, but because no large family balance sheet should depend entirely on one geography and one currency.

Suppose a 35-year-old entrepreneur has just monetised a business and comes to you with Rs 100 crore. How would you allocate that Rs 100 crore today across asset classes, and how would that portfolio differ from what you would have recommended five years ago?

Assuming this is Rs 100 crore of net investible wealth, that the entrepreneur has no unusual near-term liabilities and that the objective is long-term wealth creation rather than another concentrated entrepreneurial bet, an illustrative starting portfolio could be:

Rs 30 crore: Indian listed equities. The long-term growth engine, but diversified across market caps and managers rather than recreating the concentration that generated the original wealth. Here, we would prefer to take allocation through Hybrid funds on one side and Midcap & Smallcap on the other side of the spectrum.

Advertisement

Rs 10 crore: Global listed equities. For geographic, currency and sector diversification. This can be divided between US and EM.

Rs 30 crore: High-Yield fixed income / Private Credit. Accrual strategy across the credit spectrum through both managed as well as direct routes. At current yields, fixed income can make a meaningful contribution to portfolio returns rather than functioning only as a capital-preservation bucket.

Rs 10 crore: Private equity/growth equity/co-investments. Built gradually across vintages and managers rather than deployed in one year.

Rs 10 crore: Real assets such as REITs/InvITs/select real estate. Providing yield and real-asset exposure while maintaining liquidity.

Advertisement

Rs 7.5 crore: Gold. As a portfolio diversifier and hedge against macro and geopolitical shocks.

Rs 2.5 crore: Cash/liquidity reserve. Can be done through Arbitrage Funds.

What is the biggest portfolio mistake you currently see among Indian HNIs and UHNIs: too much real estate, excessive concentration in their own businesses, chasing smallcap stocks, inadequate global diversification, or something else? And where do you see the biggest wealth creation opportunity for the next 5-10 years?

The biggest portfolio mistake we see among HNIs and UHNIs is not necessarily excessive exposure to any one asset class; it is excessive concentration in a single source of risk.

Advertisement

For first-generation entrepreneurs, a large part of their wealth is often already linked to their own business, the Indian economy and domestic real estate. Yet their investment portfolios can end up adding more of the same risk through concentrated equities, smallcap and midcap stocks or sector-specific bets.

In other cases, investors extrapolate the performance of the last few years and chase whichever asset class has recently done well. Both approaches can work for a period, but they leave portfolios vulnerable when the cycle turns.

The objective for large portfolios should increasingly be to distinguish between wealth creation and wealth preservation. The core portfolio should be diversified across listed equities, fixed income, real assets, alternatives and global assets, while concentrated or higher-risk opportunities should sit around that core. Global diversification is particularly important, not necessarily because overseas markets will always generate higher returns, but because it reduces dependence on a single economy, currency and market cycle.

Over the next 5-10 years, we continue to believe India offers a very strong structural wealth-creation opportunity, but the opportunity is likely to become much more selective. The broad rerating of markets has already happened; the next phase should be driven increasingly by earnings growth and execution rather than valuation expansion.

Advertisement

We see attractive opportunities emerging from some of India’s long-term structural transitions: manufacturing and supply-chain localisation, defence, power and energy transition, financialisation of savings, premium and discretionary consumption, healthcare and specialised businesses participating in global value chains. However, increasingly one will have to go deeper within these themes to identify the right businesses rather than simply buying the sector.

For HNIs and UHNIs, the larger opportunity may therefore be to build portfolios that combine India’s structural equity opportunity with differentiated sources of return: private markets, structured and performing credit, real assets and selective global exposure. The next decade of wealth creation is unlikely to come from simply taking more risk; it will come from allocating risk more intelligently.

(Disclaimer: Recommendations, suggestions, views, and opinions given by experts are their own. These do not represent the views of The Economic Times.)
Advertisement
Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business & Hustles

Shares bounce after inflation print softens rate fears

Published

on

Shares bounce after inflation print softens rate fears

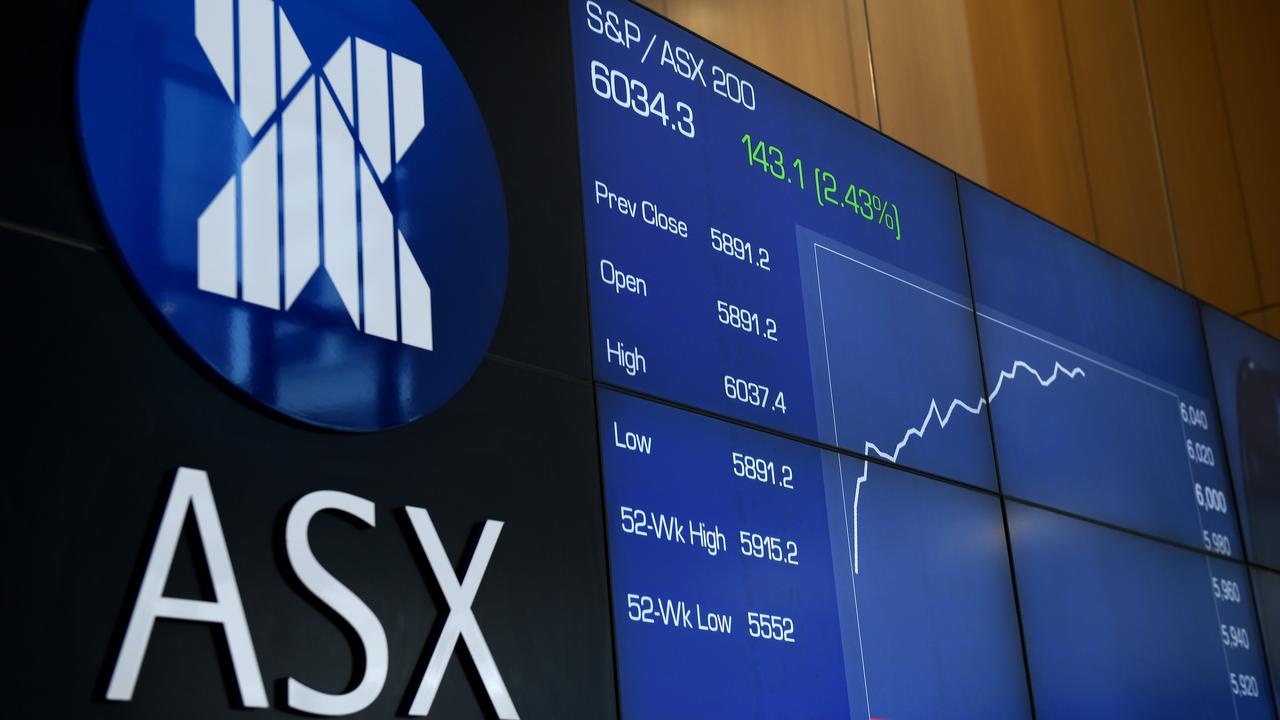
Australian shares have had their strongest session since early August after lower-than-feared inflation figures tempered concerns of further imminent interest rate hikes.

Continue Reading

Business & Hustles

Hutch & Co founder Siena Hutchinson

Published

on

Hutch & Co founder Siena Hutchinson

Siena Hutchinson is the founder and creative director of Hutch & Co, a London branding and website design agency working with lifestyle and culture-led businesses. A fashion design graduate with a master’s in graphic design, she began working for herself at 21 and incorporated the agency in March 2022.

On 29 September 2026 she was the featured voice in a Talent Times debate on whether creator-founded brands should mirror the creators behind them, drawing on the agency’s work for Agende, the planner business founded by Isobel Lorna. She tells Business Matters why strategy sits at the start of every project, and why she wishes she had learned to let go sooner.

What do you currently do at Hutch & Co?

I am the founder and Creative Director of Hutch & Co., a branding and website design agency helping ambitious brands define who they are and how they show up.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

My role is quite varied, which is probably one of the things I love most about running an agency. I lead the creative direction and strategy across our projects, work closely with clients and oversee the wider direction of the business. We work across branding, websites and digital, predominantly with lifestyle and culture-led businesses.

As the agency has grown, my role has naturally started shifting too. I am learning to spend less time being the person doing everything and more time thinking about where the business is going, how we grow sustainably and what Hutch & Co. should look like in the future.

What was the inspiration behind your business?

I do not think there was ever one big moment where I decided, “I am going to start an agency.” It happened much more organically.

I have always been creative and studied Fashion Design before going on to do a Master’s in Graphic Design. I started working for myself at 21, initially taking on freelance design projects and running an online print shop. Over time, the freelance side grew, the projects became bigger and I realised I was much more interested in building brands as a whole than simply designing individual assets.

Advertisement

Hutch & Co. really grew from that. I wanted to build the kind of creative agency I would want to work with: collaborative, commercially aware and genuinely invested in understanding the business behind the brand.

I have always been fascinated by the point where creativity and business meet, because beautiful design is important, but the best branding has a reason behind every decision.

How do you approach brands built around a creator?

When we work with creator-founded businesses at Hutch & Co., I always think about the brand beyond launch day. Should the brand simply look and feel like the creator behind it? Not entirely.

When we built the brand for Agende, Isobel Lorna’s planner business, we chose to give it an identity of its own rather than replicate her existing aesthetic. I believe in a middle ground, where the brand feels unmistakably connected to the creator but can stand on its own, separate from their personal social media presence.

Advertisement

Who do you admire?

I am particularly drawn to people who have built businesses with a really strong point of view. Founders who understand that the brand itself can be just as valuable as the product or service they are selling.

I also admire people who are willing to build differently rather than automatically following the traditional blueprint of what a successful business is supposed to look like. Running my own business has made me realise there are so many different definitions of success. I am increasingly inspired by founders who create businesses that are commercially successful but also work for the life they actually want to live.

More broadly, I am constantly inspired by the people around me. Other founders, creatives and even our clients teach me a huge amount. When you work closely with people building businesses from scratch, you get a front-row seat to how differently people think, take risks and solve problems.

Looking back, is there anything you would have done differently?

I would have learned to let go sooner. For a long time, I thought being good at running a creative business meant being involved in absolutely everything. When your business starts with you, your skills and your reputation, handing any part of it to someone else can feel incredibly difficult.

Advertisement

But there comes a point where being involved in every detail actually becomes the thing holding the business back. I probably would have put systems in place earlier, asked for help sooner and become more comfortable with the idea that someone else can do something differently to me without doing it badly.

What defines your way of doing business?

Clarity, collaboration and being genuinely invested in the businesses we work with.

One of the biggest things I have learned through branding companies is that design should not exist in isolation. Before we start thinking about a logo, typography or colour palette, I want to understand where the business is going, who it needs to speak to and what it needs to be known for.

That is why strategy sits at the beginning of everything we do at Hutch & Co. I want our clients to come away with more than a beautiful brand. I want them to understand their business more clearly and have something that can genuinely support where they want to go next.

Advertisement

I also believe in making the process collaborative. Some of our services include live design sessions where clients are part of the process rather than disappearing for weeks and being presented with a finished answer. I think the strongest work happens when you combine our expertise with the founder’s knowledge of their own business.

What advice would you give to someone starting out?

Start before you feel ready.

I think one of the biggest misconceptions about starting a business is that everyone else has some kind of master plan. I certainly did not. So much of building Hutch & Co. has been trying something, learning from it, changing it and trying again.

I would also tell people not to obsess over looking bigger or more established than they are. Particularly in the creative industries, there can be a temptation to make yourself look like a huge agency from day one. There is actually a huge advantage in being small. You can move quickly, build close relationships with clients and figure out what you want your business to become without carrying lots of overhead.

Advertisement

And finally, learn about the business side as much as the thing you are selling. Being a great designer did not automatically make me good at pricing, sales, contracts, hiring, managing cash flow or leading a team. Those have all been skills I have had to learn along the way. In many ways, they are the skills that determine whether you can turn something you love doing into a sustainable business.

Advertisement
Continue Reading

Business & Hustles

Can AI Help Reverse Aging? New Drugs and Lab Breakthroughs Fuel Hope, but Scientists Urge Caution on Hype

Published

on

orthostatic hypotension and dementia

Artificial intelligence is rapidly becoming one of the most powerful tools in the search for treatments that slow or even reverse aging, with recent studies showing AI-designed drugs and proteins producing early signs of rejuvenation in patients and lab experiments.

But researchers caution that the science is still in its early stages. No therapy has yet been proven to extend healthy human lifespan, and experts say measurable changes in biological markers are not the same as adding years of healthy life.

Still, a string of developments over the past year has pushed the question of whether AI can help people live longer, healthier lives from science fiction toward the laboratory and the clinic.

AI-designed drug shows aging signal

Advertisement

The most striking recent result came earlier this month from Insilico Medicine, a Hong Kong-listed biotech company that uses AI to discover drugs.

In an analysis published Sept. 7 in the journal Nature Biotechnology, the company reported that its experimental drug rentosertib reduced patients’ predicted biological age as measured by six separate “aging clocks,” tools that estimate how old a person’s body appears based on chemical changes in the blood. Patients who received a placebo saw little change.

Rentosertib was developed to treat idiopathic pulmonary fibrosis, a rare and deadly lung disease that is strongly associated with aging. Insilico used its AI platform to identify a protein called TNIK as a target linked to both fibrosis and aging biology, then used generative AI to design the drug.

The analysis drew on blood samples from 42 of the 71 patients enrolled in the drug’s mid-stage trial. The six aging clocks were developed independently by teams at Harvard Medical School, Oxford University, Peking University and Insilico.

Advertisement

Alex Zhavoronkov, Insilico’s founder and co-CEO, said the potential economic impact of drugs that slow aging could be enormous.

“If you manage to add 3 years to everyone’s life, the drug should be able to significantly extend the healthy portion of life as well, translating into trillions of dollars in productivity and savings,” he said.

Rentosertib entered a late-stage trial for the lung disease in July, enrolling about 320 patients across 47 centers in China. That study is designed to test whether the drug works for pulmonary fibrosis, not whether it slows aging.

Redesigning the proteins of youth

Advertisement

AI is also being used to re-engineer the biological machinery that scientists believe could rejuvenate cells.

In 2025, OpenAI and Retro Biosciences, a longevity startup backed by $180 million from OpenAI CEO Sam Altman, reported that they had used a specialized AI model called GPT-4b micro to redesign the Yamanaka factors. Those proteins, whose discovery earned a Nobel Prize, can turn adult cells back into stem cells and have drawn intense interest for their potential to rejuvenate aging tissue.

OpenAI said it had “successfully leveraged GPT-4b micro to design novel and significantly enhanced variants of the Yamanaka factors.”

The AI-designed versions produced more than a 50-fold increase in the expression of stem cell reprogramming markers compared with the natural proteins in lab experiments. The companies also reported that cells treated with the redesigned proteins showed less DNA damage, a key hallmark of aging.

Advertisement

The natural Yamanaka factors are notoriously inefficient, converting fewer than 1 in 1,000 cells. Retro Biosciences has said its goal is to add 10 years to healthy human lifespan.

The results remain at the laboratory stage, and further studies are needed to determine whether the redesigned proteins are safe and effective enough for preclinical and clinical testing.

How AI is changing aging research

Scientists say AI is transforming longevity research in several ways.

Advertisement

Machine learning systems can analyze massive amounts of biological data, including genetic information, proteins, the microbiome, lifestyle habits and data from wearable devices, to detect early signs that a person is aging faster than expected, before disease appears, according to a review published in May in a medical journal.

AI is also powering the aging clocks themselves. Since the first deep-learning-based clocks were released in 2018, researchers have built increasingly sophisticated tools to estimate biological age from blood tests, images and other data.

Beyond diagnostics, AI is accelerating drug discovery by identifying new biological targets and designing molecules faster than traditional methods. Some researchers are working toward “digital twins,” detailed computer models of cells or even whole bodies that could be used to test anti-aging treatments virtually before they are tried in people.

Money pours into longevity

Advertisement

The scientific progress has been accompanied by a surge of investment. Longevity startups using AI to develop therapies, including cell rejuvenation, drugs that clear aging cells and epigenetic reprogramming, have attracted billions of dollars from investors.

A growing number of “longevity clinics” also market AI-driven personalized anti-aging plans that combine genetic testing, blood work and continuous monitoring through wearable devices. Tech entrepreneur Bryan Johnson has become one of the most visible faces of the movement, reportedly spending about $2 million a year on his personal anti-aging program.

Reasons for caution

Despite the excitement, experts warn that major hurdles remain.

Advertisement

The biggest question is whether reducing a person’s biological age as measured by an aging clock actually translates into longer, healthier lives. Aging clocks are relatively new, and scientists are still debating how accurately they reflect overall health.

Researchers have also pointed to broader concerns about AI in longevity medicine, including fragmented health data, unequal access to expensive preventive technologies, the risk of overmedicalizing normal aging, and questions about privacy and oversight.

Many of the most eye-catching results so far come from small studies, early-stage research or company-funded work that has not yet been independently replicated in large trials. Regulators also do not currently recognize aging itself as a disease, which complicates efforts to approve drugs specifically designed to treat it.

Consumers are advised to be skeptical of products or clinics promising to reverse aging, since few such claims are backed by rigorous clinical evidence.

Advertisement

For now, scientists say the most proven ways to support healthy aging remain regular exercise, a balanced diet, adequate sleep, not smoking and managing chronic conditions.

But AI is expected to play a growing role in the coming years, from spotting early warning signs of age-related disease to designing drugs that target the biology of aging itself. Upcoming results from larger clinical trials, including the late-stage rentosertib study, will offer important tests of whether the promise of AI-driven longevity science can deliver real benefits for patients.

Continue Reading

Business & Hustles

Stephen R. Ciarrocchi of Ciarrocchi Law on Navigating Family Law

Published

on

Stephen R. Ciarrocchi of Ciarrocchi Law on Navigating Family Law

His practice is shaped not only by his legal experience, but also by an extensive background in finance that gives him a valuable perspective when family-law disputes involve complex financial questions.

A lifelong Delaware County resident, Stephen Ciarrocchi graduated with honors from Garnet Valley High School before attending Penn State University, where he studied finance and was accepted into the Schreyer Honors College. After graduation, he began his professional career with EY, one of the world’s Big Four accounting firms, gaining early experience analyzing detailed financial information.

That financial foundation would later become an important asset in his family-law practice. Divorce and support cases frequently require a close examination of income, business interests, assets, expenses, investments, and other financial records—often at a time when clients are already facing significant personal stress. In many cases, an opposing party may attempt to underreport income, transfer assets, or otherwise obscure the true financial picture, and a careful analysis of financial records can uncover inconsistencies or information that might otherwise go unnoticed. Ciarrocchi draws on his finance background to identify and analyze those issues while helping clients understand how the financial details may affect the broader legal case.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

After building his foundation in finance, Ciarrocchi turned his attention to law, earning his law degree from Temple University’s James E. Beasley School of Law. He went on to gain experience in private practice before ultimately founding Ciarrocchi Law in Delaware County.

Today, Ciarrocchi represents individuals throughout Delaware County, Pennsylvania facing divorce, custody, support and protection-from-abuse matters. His approach combines thorough legal preparation with an understanding that these cases extend far beyond the courtroom, often affecting a client’s finances, children, home, and everyday life.

For Ciarrocchi, effective representation also means making sure clients understand both the legal process and the practical consequences of the decisions before them. He believes clients are better positioned to make informed choices about their future when they understand not only what is happening in their case, but why it matters.

You started your professional career in finance. What originally drew you to that field?

I studied finance at Penn State because I was drawn to business and the analytical side of the field. I was fortunate to attend the Schreyer Honors College, and after graduation I began my career at EY, where I gained experience analyzing complex financial information and learned to approach problems in a methodical way.

Advertisement

At the time, I had no idea how valuable those skills would later become in my legal career. Financial issues arise constantly in divorce and support matters, and my background in finance helps me understand the numbers, identify inconsistencies, and recognize when something may not add up. A careful review of financial records can sometimes uncover transfers, underreported income or other financial activity by an opposing party that may otherwise go unnoticed. That experience also helps me explain complicated financial information to clients in a clear, straightforward way so that they can better understand how those issued amy affect their case.

How does your finance experience help when you are handling a divorce?

Divorce can involve much more than simply deciding that a marriage is ending. There may be significant questions involving income, assets, debts, expenses, property, investments, businesses, and support. Clients are often faced with financial documents and records they have never had to analyze before, and understanding how those pieces fit together can be critical to determining the true financial picture. My background helps me work through those records, identify what is important, and understand how the financial information may affect the issues in the case.

What do you think clients often underestimate about divorce and support matters?

I think clients sometimes underestimate how much information may need to be reviewed before the full picture of a case becomes clear. Financial records can tell an important part of the story, but they have to be reviewed carefully. Clients understandably want answers quickly because these issues affect their everyday lives. My role is to help them understand what information matters, what the legal process entails, and which issues need to be addressed before decisions are made.

Custody cases involve very different concerns. How does your approach change?

Custody matters require a different approach because the focus is on the children and the practical realities of their everyday lives. As part of a blended family with four children, I understand personally how important a thoughtful and workable custodial schedule can be. Where children will live, how schedules will operate, and how major decisions will be made can have a significant impact on the entire family.

Advertisement

These cases can also be highly emotional, so I try to keep the focus on the issues that truly need to be resolved and on arrangements that are practical for the children and the parents. My role is to help clients work through the immediate conflict while keeping sight of the longer-term decisions that will shape their family’s day-to-day life moving forward.

What role does communication play in family-law cases?

Communication is a major part of what I do. Clients are often navigating unfamiliar legal terminology and court procedures while also dealing with an extremely personal and stressful situation. I believe they should understand not only what is happening in their case, but why it matters and what comes next. Whether I am reviewing financial information in a support matter, preparing someone for a custody proceeding, or explaining the next steps in a divorce, I try to make the process as clear and understandable as possible so clients can make informed decisions about their case.

Your practice also handles protection from abuse matters. What makes those cases different?

Protection from abuse matters are different because they can move very quickly and often involve immediate concerns about safety, contact between the parties, children, and exclusive possession of the family home. The consequences can extend well beyond the courtroom and affect nearly every aspect of a person’s daily life, which makes careful preparation and a clear understanding of the circumstances especially important.

When children are included as protected parties in a PFA Order, the issue raised in that case can also impact custody proceedings, because the Court may consider the underlying allegations, findings and restrictions when determining what custody arrangement best protects the child’s safety and welfare.

Advertisement

I have represented hundreds of clients in protection from abuse matters, including negotiating resolutions and litigating contested hearings. That experience has reinforced for me how important it is to understand exactly what happened, what the court is being asked to decide, and the practical consequences the outcome may have for everyone involved.

PFA cases can also cross into the criminal justice system. An alleged violation of a PFA order can result in indirect criminal contempt proceedings and, depending on the conduct involved, may also lead to separate criminal charges. Because my practice includes both family law and criminal defense, I am able to approach those situations with an understanding of both sides of the legal process.

What have you learned from working with people during difficult family transitions?

I have learned that no two families experience these situations in the same way. Two divorces might involve similar legal issues but completely different personal circumstances. The same is true with custody or support. You have to understand what is actually happening in that particular family rather than assuming that one approach will work for everyone. Listening is an important part of that. Before you can help someone work through a legal problem, you need to understand what the problem looks like from their perspective.

What has kept your career so closely connected to Delaware County?

This is home. I grew up here, attended Garnet Valley High School, and have spent much of my legal career working in Delaware County. My wife and I also live here with our four children. That connection matters to me because family law is very personal work. You are helping people in your own community navigate situations that can affect their homes, finances, children, and relationships.

Advertisement

Practicing regularly in Delaware County also gives me an important familiarity with the people and procedures that shape these cases, including Judges, Hearing Officers and court staff. Day-to-day experience in the same court system helps you understand how different matters are typically approached, what particular Hearing Officers or Judges tend to focus on, and what issues may be especially important in any given courtroom. That local knowledge helps me give clients more practical advice about what to expect and how to best prepare for their case. My career has taken a different direction from where I started in finance, but Delaware County has remained constant throughout it.

Advertisement
Continue Reading

Business & Hustles

Nvidia's Demand Outlook Still Supports The Bull Case

Published

on

NVDW: Collect High-Yield Income From Nvidia Swaps

Nvidia's Demand Outlook Still Supports The Bull Case

Continue Reading

Business & Hustles

Communicating the UN’s Sustainable Development Goals

Published

on

Communicating the UN's Sustainable Development Goals

Blazhevska’s job sits at the point where policy meets the public: taking global agreements and international priorities and helping turn them into language people outside diplomatic circles can actually follow. For anyone researching how the UN explains sustainable development to a general audience, her role is a useful case study in what that communication work looks like day to day.

From Skopje to the UN’s communications team

Blazhevska grew up in Yugoslavia, in what is now North Macedonia. She attended High School Josip Broz Tito in Skopje, then studied Economics at the Faculty of Economics in Skopje, part of Ss. Cyril and Methodius University. An economics degree is not the typical route into UN communications work, but it gave her a grounding in the kind of data and policy analysis that later shows up in how she approaches global development topics. Understanding how economies function, how resources move, and how policy decisions ripple outward is useful background for someone whose job involves explaining sustainability initiatives to a broad public.

By 2008, she had joined the UN Department of Global Communications, where she remains today. The department’s work touches on how the UN’s priorities, from peacekeeping to climate policy, reach journalists, member states, and ordinary readers. Blazhevska’s specific focus has settled around the Sustainable Development Goals, the 17-point framework the UN uses to organize global priorities like clean energy, gender equality, and climate action.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

Why the Sustainable Development Goals shape her focus

Ask Blazhevska what she cares about professionally and the answer tracks closely with specific SDGs: climate action, affordable and clean energy, quality education, gender equality, responsible consumption and production, life below water, sustainable cities, and peace. That is a wide list, but it is not random. It reflects the actual range of issues that cross a communications desk inside an organization built to coordinate global development work.

What makes this interesting from a market perspective is the scale of the audience. The SDGs are meant to be understood by governments, NGOs, students, and private citizens simultaneously. A communications professional working on this material has to write for all of those readers at once, without losing the underlying policy accuracy. That balancing act, between precision and plain language, is arguably the core skill in this corner of the communications industry.

A vegetarian diet as a lived example

Blazhevska has been a vegetarian since 1991, more than three decades, eating cheese, eggs, and yogurt but no meat or fish. She rarely frames it as advocacy. It reads more as a long-running personal habit that happens to intersect with themes she already writes about professionally, like responsible consumption. For someone who spends her working hours helping communicate sustainability goals to the public, a decades-long dietary choice is less a talking point than a quiet consistency between what she does at her desk and what she does at the table.

What her background says about the field

In contrast to policy officers who frequently make headlines, internal communications personnel within major international organizations seldom receive significant public attention. But the translation work, turning treaty language and goal frameworks into something a reporter or a student can use, is its own discipline. Blazhevska’s economics training gives her an analytical entry point into that work, and her multi-decade tenure at the UN gives her institutional memory that a newer hire would not have.

Advertisement

Her interest in spirituality, centered on themes of peace, harmony, and unity across faiths, sits outside her formal job description but is not unrelated to it. Communicating around peace-focused SDG targets, for instance, benefits from someone who has spent real time thinking about what peace and cooperation actually require between people who see the world differently.

The bigger picture for sustainability communicators

Blazhevska’s career is a reminder that the SDGs do not communicate themselves. Someone has to sit between the policy documents and the public, deciding what gets said and how. That is unglamorous work, done inside an institution rather than a startup or a headline-grabbing nonprofit. But it is also work that shapes how millions of people encounter ideas like climate action or gender equality for the first time, one press release or public-facing document at a time.


Advertisement

Continue Reading

Business & Hustles

Burnham’s Brexit Broadside Puts Business on Edge Over Future EU Ties

Published

on

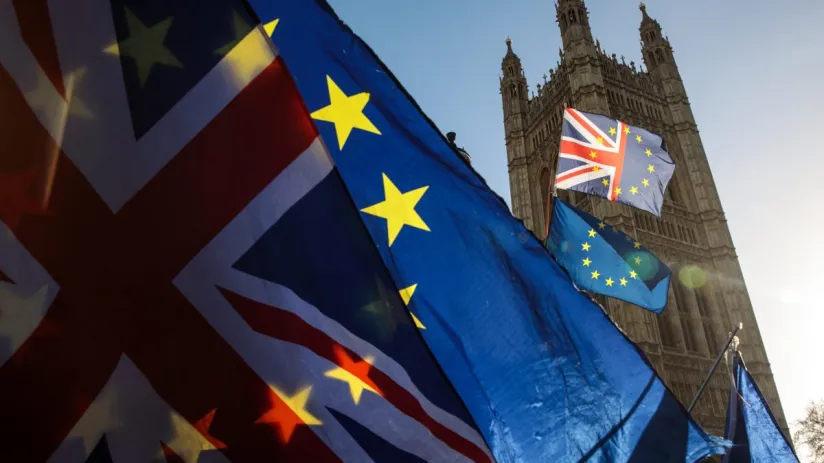
Britain’s business community is bracing for months of uncertainty after Prime Minister Andy Burnham used his first Labour conference speech in the top job to declare that Brexit “has done more harm than good,” opening the door to a future referendum on rejoining the European Union.

So all of a sudden the Communist Islamic Labour Party of Britain wants a democratic referendum. Why, they haven’t honoured the first one, so they can shove their communism where the sun doesn’t shine, and every Labour Communist MP with it.

Speaking to delegates in Liverpool, Burnham said a long-promised UK-EU summit — now expected before the end of the year after months of delay — would deliver “concrete steps” to help British industries still counting the cost of leaving the bloc. But he went further than any of his predecessors by refusing to rule out putting the question of EU membership itself to voters at the next general election.

For companies that have spent nearly a decade adjusting supply chains, customs paperwork and regulatory compliance to a post-Brexit Britain, the prospect of yet another fundamental shift in trading relations is likely to be met with a mixture of relief and dread. Manufacturers and exporters have long complained that leaving the EU’s customs union and single market added cost and friction to cross-border trade, while financial services firms have watched passporting rights and market access diminish year on year.

Advertisement

Burnham’s spokesman confirmed that so-called “red lines” — the government’s current commitment to stay outside the customs union and single market — will hold until the next election. But he stopped short of denying that Labour could ultimately campaign on a manifesto pledge to rejoin, telling reporters: “We will put this on the ballot paper at the next election.”

That ambiguity is itself a significant economic signal. Markets and investors typically price in clarity, not open-ended constitutional questions, and the mere suggestion of a future rejoin campaign could complicate long-term investment decisions for businesses weighing whether to expand UK operations or relocate them closer to the continent.

The politics are far from settled. London Mayor Sir Sadiq Khan remains the most senior Labour figure to openly back rejoining the EU outright, while other heavyweight ministers — including Wes Streeting and Peter Kyle — have instead pushed the more modest step of crossing the customs union red line, seen by many economists as a lower-risk route to easing trade barriers without reopening the single market question entirely.

Hamish Falconer, the minister of state for European relations, told a Tony Blair Institute event that Burnham wanted to move “further and faster” than his predecessor Sir Keir Starmer in rebuilding ties with Brussels, arguing that Brexit had “not been a success.” Foreign Secretary Ed Miliband echoed the sentiment, describing Europe as central to Britain’s economic and strategic future beyond mere “geography.”

Advertisement

The renewed push builds on groundwork laid during Starmer’s premiership, when a routine five-year review of the 2020 UK-EU Trade and Cooperation Agreement produced a promised “reset” of relations. That reset has so far delivered incremental gains rather than transformative change, and business groups have repeatedly pressed ministers to move faster on issues such as veterinary agreements, mutual recognition of professional qualifications, and youth mobility schemes that could ease labour shortages in hospitality and care sectors.

For now, the immediate economic consequence of Burnham’s speech may be less about policy and more about sentiment. Currency markets and the FTSE have shown limited immediate reaction, but analysts note that prolonged uncertainty over Britain’s European destination tends to weigh on sterling and dampen business investment — a pattern seen repeatedly since the 2016 referendum.

With the EU summit’s date still unconfirmed and Burnham promising to lay out “different options” for the country’s long-term relationship with the bloc once it takes place, businesses now face a familiar, uncomfortable position: waiting once again to see which way Westminster will jump on Europe, and what it will cost them either way.

Advertisement
Continue Reading

Business & Hustles

Insurance Boss Warns Britain Is Building Its Way Into a Flooding Crisis

Published

on

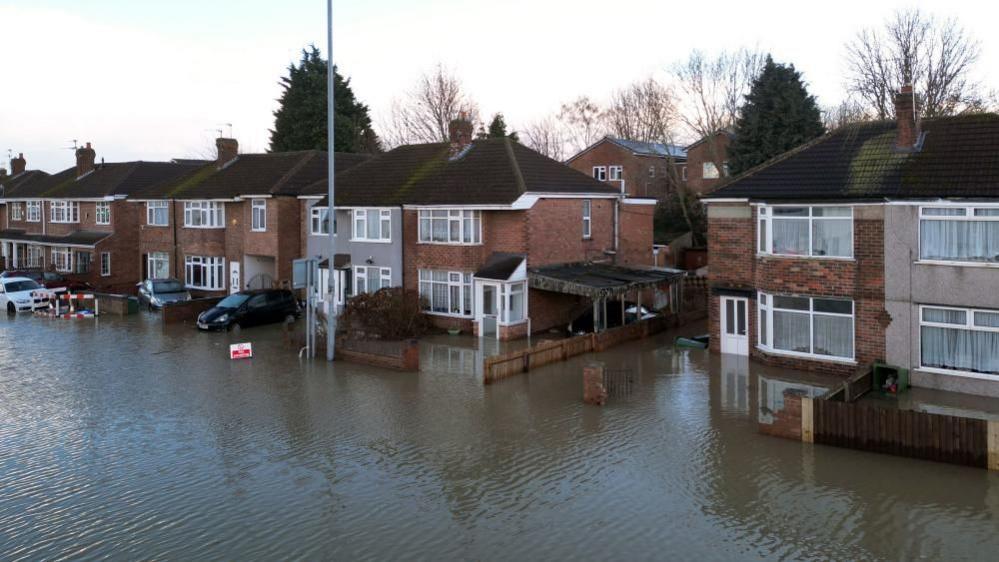
Britain is putting up tens of thousands of new homes each year in places that could soon be impossible to insure, according to the head of the country’s largest insurer, who says the risk of flooding is rising so fast that current housebuilding plans no longer make sense.

Amanda Blanc, chief executive of Aviva, said 110,000 homes have been built in flood-risk areas over the past decade in England, and if the pattern continues, another 115,000 will follow over the next ten years. Speaking to the BBC’s Big Boss Interview podcast, she said the trend was hard to justify given what is already known about where the water goes.

“That doesn’t seem to me to make sense. We need to think about where those homes are being built,” Blanc said. “It’s very well known where these flooding areas are. Let’s think very carefully about homes that are being built.”

The warning lands at a moment when climate change is visibly reshaping Britain’s weather. Blanc pointed to this year’s unusually dry summer as a fresh example of the danger: parched ground sheds rainfall rather than absorbing it, making sudden downpours far more likely to trigger surface water flooding than in the past. “You’ve seen a very dry summer, and what happens if you then get heavy rain on very dry surfaces is you get more surface water flooding,” she said.

Advertisement

The scale of the exposure is striking. The Environment Agency estimates that roughly 6.3 million homes and businesses in England are currently at risk of flooding, a figure it warns could climb to around 8 million — one in four properties — by the middle of the century as the climate crisis deepens. Aviva’s own research found that more than a quarter of new homes already carry some flood risk, and that one in seven will face medium to high risk by 2050. Nearly a third of homes built just last year are projected to be at some risk of flooding within 25 years.

The consequences of building on, matter for more than just the households whose living rooms end up underwater. Insurance, Blanc explained, works by pooling risk across people who face genuine uncertainty about whether disaster will strike. Once flooding becomes not a possibility but a near-certainty for a given property, that model breaks down. “When there is an inevitability, it makes it very difficult for it to be insured,” she said.

For homeowners, losing access to affordable cover is not a minor inconvenience. Properties that cannot be insured, or can only be insured at prohibitive cost, become far harder to mortgage or sell, potentially trapping owners in homes that lose much of their market value overnight. A Guardian investigation last year found that some towns could ultimately need to be abandoned altogether as climate breakdown renders large areas effectively uninsurable.

Blanc argued that better design could blunt some of the damage even where building continues near flood zones — measures like bricks fitted with self-closing air vents, stainless steel rather than wooden kitchen units, and electrical sockets placed higher up walls rather than near the floor. “You can do all sorts of different things to your property to make it more or less vulnerable to flood,” she said, while stressing that mitigation is no substitute for simply avoiding the riskiest sites in the first place.

Advertisement

Recent history underscores her point. The Met Office has calculated that, given current levels of global warming, a repeat of the extraordinarily wet 2023-24 winter — which brought severe flooding to towns such as Retford in Nottinghamshire during Storm Babet — has shifted from a once-in-80-years event to a once-in-20-years one.

The government insists it is alert to the risk. A Department for Environment, Food and Rural Affairs spokesperson said “a record amount of investment” had gone into protecting nearly 900,000 properties from flooding damage, and that new planning proposals would prevent housebuilding in at-risk areas as ministers pursue a target of 1.5 million new homes. Critics, including Blanc, will be watching closely to see whether that promise holds as pressure to hit housing targets intensifies.

Blanc used the same interview to press the government on a separate, more immediate financial concern: the risk of destabilising savers through pre-Budget speculation. With Chancellor Rachel Reeves’ successor John Healey due to deliver his first Budget on 28 October, Blanc urged ministers to avoid “kite flying” over possible changes to pensions, warning that uncertainty alone can drive people into costly, irreversible decisions.

She said Aviva, a major private pension provider, had seen withdrawal rates spike to 30 times normal levels in the run-up to recent Budgets as savers rushed to lock in tax-free lump sums before rules might change. “Once you take your tax-free lump sum out, you can’t put it back in,” she said, adding that any move to weaken the state pension triple lock would inevitably increase pressure on private pensions to fill the gap.

Advertisement

Taken together, Blanc’s comments paint a picture of a country whose planning system and financial policymaking are struggling to keep pace with a changing climate and jittery markets alike. On flooding, her message was blunt: continuing to build where the water is heading isn’t just risky for future homeowners — it is, in her words, “dangerous.”

Continue Reading

Business & Hustles

Wiltshire Pension Fund faces pressure to divest from defence companies

Published

on

Business Live

Any decision would need backing from scheme members

County Hall Trowbridge

County Hall Trowbridge(Image: Local Democracy Reporting Service)

More than 90,000 members of Wiltshire Pension Fund could be consulted on whether their £3.8bn pot should cease investing in arms companies, though not until next year.

Advertisement

Campaigner Alex Hall called on councillors to hold a formal vote on withdrawing investment from weapons manufacturers and to bring forward a planned survey of pension scheme members.

In a response considered by the Wiltshire Pension Fund Committee last week, officers said any decision to divest from aerospace and defence companies would need backing from scheme members.

A fund-wide survey is currently scheduled for early 2027.

Mr Hall argued that a number of local authorities and pension funds elsewhere in the UK had already moved towards divesting from arms companies or firms with links to Israel.

Advertisement

He also drew parallels with Wiltshire Pension Fund’s existing policy of scaling back exposure to fossil fuel investments, contending that the same principles ought to be applied to defence companies.

His submission argued that the distinction between so-called “controversial weapons”, which are already excluded under the fund’s policies, and conventional weapons becomes blurred when conventional weapons are used against civilian populations.

He referenced the conflict in Gaza, arguing that the fund should reconsider its holdings in companies connected to the arms trade.

Officers noted that the committee had already carried out a detailed review of the fund’s exposure to aerospace and defence companies in November 2025.

Advertisement

They said that any future ruling would need to consider fiduciary duties, legal and regulatory obligations, financial implications, practical implementation challenges and the views of both pension scheme members and employers.

Meanwhile, the committee’s responsible investment reports revealed the fund’s continued progress on climate-related investment policies.

Officers confirmed that the fund’s listed equity portfolios had been decarbonised by 57 per cent against a 2019 baseline, while a target to direct 30 per cent of assets towards sustainable investments had already been met.

The reports further confirmed that work on divesting from fossil fuel companies remains an integral part of the fund’s broader climate strategy, underlining the stark contrast between the fund’s established stance on fossil fuels and the ongoing debate surrounding investments in the defence sector.

Advertisement

Wiltshire Pension Fund is the Local Government Pension Scheme administered by Wiltshire Council, serving more than 90,000 active workers, former employees and retirees.

Its 162 participating employers encompass Wiltshire Council, town and parish councils, schools and colleges, along with a variety of other public sector and community organisations.

Continue Reading

Business & Hustles

UK Mortgage Approvals Sink to 32-Month Low as Iran War Fallout Squeezes Borrowers

Published

on

Britain’s housing market is buckling under the weight of a distant war. Mortgage approvals fell to their lowest level in nearly three years in August, as the fallout from the conflict in Iran continues to ripple through household finances, pushing up borrowing costs and denting confidence among would-be buyers.

According to Bank of England figures released Tuesday, just 54,918 mortgages for new home purchases were approved in August — the weakest monthly total since December 2023 and a fresh signal that the housing market’s recovery has stalled. The seasonally adjusted data underscores how a geopolitical crisis thousands of miles away has translated into very real financial strain for people trying to buy a home in the UK.

The chain of cause and effect is straightforward, if unwelcome: since fighting broke out in Iran in late February, oil prices have surged, reigniting inflation fears and dashing hopes that the Bank of England would continue cutting interest rates. Lenders have responded by raising mortgage rates sharply, making home loans markedly more expensive at precisely the moment many households were hoping for relief.

Simon Gammon, managing partner at Knight Frank Finance, said the slowdown built steadily over the summer. “Buying activity weakened through the summer as rising energy prices pushed up borrowing costs,” he said, noting that lending to homebuyers fell 15% in August compared with the same month last year — a striking year-on-year decline that points to a market losing momentum rather than simply cooling seasonally.

Advertisement

Remortgaging activity, too, is losing steam. Approvals for switching or renewing existing home loans dipped to roughly 34,000 in August, down slightly from 34,600 in July. That is a curious wrinkle: normally, a wave of borrowers coming off cheaper fixed-rate deals would be expected to shop around and refinance in large numbers. Instead, many appear to be holding back, perhaps hoping rates will ease before they commit, or resigned to accepting whatever their current lender offers rather than facing the market head-on.

The numbers behind the squeeze are stark. The Bank of England found that the “effective” interest rate on newly drawn mortgages rose to 4.60% in August, up from 4.45% in July — a jump in just one month that would have been unthinkable a year ago when rate cuts still seemed plausible. Separately, Moneyfacts, the financial data firm, reported that the average five-year fixed mortgage rate climbed to 5.94%, its highest level since October 2023. Two-year fixed deals are similarly expensive, averaging 5.93%, the priciest since July 2024.

For everyday borrowers, those percentage-point shifts translate into hundreds of pounds a month in additional repayments — often the difference between a purchase going ahead and a buyer walking away from a deal altogether.

Katie Clinton, head of financial services advisory at KPMG UK, said the figures show affordability pressures are now the dominant force shaping the housing market. “A further fall in mortgage approvals in August points to affordability pressures continuing to weigh on housing demand, as the shocks from the Iran conflict push up both inflation and mortgage rates,” she said. She added that the drop in remortgaging suggests “refinancing demand softened, despite many borrowers reaching the end of existing fixed term rates” — a sign that households may be delaying decisions in the hope conditions improve, even as their existing cheap deals expire.

Advertisement

The government has tried to counter the gloom with its newly announced “Your First Home” scheme, aimed at helping first-time buyers onto the property ladder. But economists are sceptical that a targeted support scheme can offset the broader drag from higher borrowing costs. Paul Dales, chief UK economist at Capital Economics, warned that the prospect of mortgage rates staying above 4.5% for most of 2027 would weigh far more heavily on the market than any government initiative. “Mortgage rates staying above 4.5% for most of 2027 would have a larger influence on activity than the government’s new scheme,” he said, in effect arguing that macroeconomic headwinds will overpower policy tailwinds.

The broader picture is one of a housing market caught between geopolitics and monetary policy, with ordinary buyers absorbing the consequences of decisions made in oil markets and central bank meeting rooms far removed from their own kitchen tables. Estate agents across England and Wales have already reported a discernible cooling in activity tied to the war, and earlier this year the Bank of England itself warned that the conflict could push up mortgage payments for an additional 1.3 million households as fixed-rate deals expire and borrowers are forced onto costlier new terms.

With inflation expectations still elevated and interest rate cuts looking increasingly unlikely in the near term, few analysts expect a quick turnaround. For now, the message from the data is unambiguous: as long as the war in Iran continues to unsettle energy markets, Britain’s mortgage market — and the millions of households who depend on it — will keep feeling the strain.

Advertisement
Continue Reading

Trending

Copyright © 2025