Connect with us

Business & Hustles

Inflation reflects growth dynamics in India: Christopher Wood

Published

on

ET Search
Key note address delivered by Christopher Wood, equity strategist, CLSA, in his first public appearance in India, at the ET Now Market Summit-2010. Excerpts:

Hello everybody and thank you for asking me. I will be running through some charts which were still first with the situation in the West. Then I will move on to charts on Asia and India. So I get the bad news out of way first. But this seems to be the wrong way around. So I am getting from back to front here. (Watch)

To start with the US situation, this is a big picture chart everybody needs to be aware of in the global economy. This is US total debt as a percentage of GDP. The story is very simple and the total amount of debt in the system in the US has been going down ever since the credit crisis erupted in 2007-2008. This the first time total debt has been falling in America since the Great Depression.

Mr Bernanke of the Federal Reserve has been trying to get the re-leveraging game going so far, they have not succeeded. My operating assumption is to assume that the leveraging will continue that we peaked out in the US super credit cycle in 2007, which has been running since the Second World War and now in a long-term de-leveraging cycle, which means lower trend GDP growth.

Advertisement

May be re-leveraging will kick in coming months in which case I will change my view, but for now I am assuming it’s a de-leveraging cycle until the data proves otherwise. Next chart you see US total net credit market borrowings and you can see the rate of growth of borrowing has been going down in the system despite the big kick up in Federal Government borrowing.


Next chart is a long-term trend in US nominal GDP 10-year compound annual growth. As the Japanese example has shown in the last 20 years, when you get into a deflationary environment, it no longer makes sense to look at real GDP measures because when inflation zero level what gives a more realistic picture of what is going is nominal GDP. And in my view, nominal GDP growth in America will continue to trend down. We have seen a big rally in US government bond prices this year, as telling you the trend nominal GDP growth is lower and that means the trend earnings growth, trend revenue growth in America is also going to be lower.
Then next chart relates to the consumption story in America which in my view is going to remain anaemic. In my view the US consumers, western consumers in general, are going to be increasing savings rate. There is also a demographic kicking in… the baby boom as heading for retirement, but they cannot afford to retire. So topline is US real disposable personal income, the bottom line is real personal income excluding current transfer receipts. Transfer receipts basically mean welfare payments. So you can see without all the stimulus from the government the fundamental income trend is much weaker. What separates the emerging markets from the developed world is an emerging markets like India with healthy income growth and the developed countries, be it the US, Japan, Europe, we do not have healthy income growth.

Next chart highlights a significant rally in US Treasury Bond prices reflected in declining treasury bond yields which has happened this year. At the start of this year the biggest bearish consensus amongst global equity investors was that US Treasury bonds were screaming sells.

Everybody said that the treasury bond market is going to collapse, the Fed printing money inflation is coming back. Clearly that consensus was completely wrong. US Treasury Bond market has been rallying even with the recent pick in the S&P and recent weeks up to 1150 level which I think was a peak of this counter trend rally. Even with the stock market rally the bond market did not sell off. What this bond market is telling you is that nominal GDP growth is slowing in America, it is telling you it is not a normal recovery. The credit multiplier is not working.

Once the inventory cycles happen & the US capex cycle has ran through, there will be nothing left to sustain the economic momentum. So in a deflationary environment, government bond prices are lead indicator of nominal GDP growth. Right now this is a very important point because the US bond market is sending one message and the US stock market is sending another message and basically investors have a decision to make – do they believe the bond market is giving the correct signal or the stock market? My assumption is that it’s the bond market and my experience is that the bond market is no way smarter than the stock market 90% of the time. Meanwhile, this is US headline CPI inflation for the rest of this year we are going to see inflationary pressures falling throughout the world in the West. That’s going to lead to new deflation concerns.

Advertisement

In Asia and countries like China and India, falling inflationary pressures are going to be bullish and everybody is going to realise it does not make sense to worry about inflation in countries like India. The good news is that you have inflation because that reflects the fundamental growth dynamic. But the key point about the US is if the trend over the past 3 months has extrapolated forward, US CPI inflation will turn negative in October. If that happens, it’s not going to be bullish for equities, it’s going to be bullish for government bonds and it’s going to be a signal for Mr. Bernanke, if we have not done that already, to assume quantitative easing.

Next chart, US average duration of unemployment. So basically there are large groups of the structurally unemployed in America. So in this sense, the US is heading for the European systems situation were you have a large group of structurally unemployed living off the welfare state. The problem in America is that the welfare state is much more controversial than in Europe, hence the political divide in America, hence the growing trend under the so-called Tea Party movement.

Meanwhile the classic monetary measures are highlighting the fact that we are not in a re-leveraging cycle, we are still in a deleveraging cycle. This is the US money multiplier representing the velocity of money in circulation. Velocity of money in circulation is declining. So long as that line is declining, it’s deflationary. We don’t have to worry about inflation picking up, and this chart highlights the growing deflationary threat.

Next chart is US broad money supply growth. Again, money supply growth is going down. That’s why the bond market’s rallying, that’s why inflation is not an issue, that’s why Mr. Bernanke is now looking for an excuse to resume quantitative easing.

Advertisement

Next chart is US bank lending. Again, no real sign of any kind of meaningful pick up in bank lending annualise lending loan growth continue to slow another indication of a deleveraging cycle. This is not just about banks restricting credit, it is also about a change in psychology, economic agents be it the companies or consumers have become more risk averse about borrowing.

Next chart is US total securitisation issuance. In the recent credit boom before the bust a large part of the credit cycle was driven by securitization, therefore we are going to get re-leveraging in America. We need to see a healthy pick up in securitisation as well as banking lending, but the only area that has picked up since the crisis is the dark blue line here.

This is agency mortgage bank securities, that’s Fannie Mae and Freddie Mac. These entities are guaranteed by the Federal Government and therefore they do not really count. Any private sector securitisation has barely recovered. Meanwhile the huge role played by Fannie and Freddie should not be ignored in terms of supporting the housing market.
Basically about 96% of the America mortgage market now is government guaranteed. So that’s the US situation. The big picture is still deflationary. However, in terms of macroeconomic shocks that could cause another steep fall in global equities this year for the rest of 2010, I still believe there is going to be another sharp decline in equities like we saw in April and May. It’s more likely to be triggered by the Eurozone where you have systemic risk relating to government debt.
So this chart relates to the ECBs net buying of Euroland government bonds. The key point here is this ECB was forced reluctantly to stop buying junk government bonds in Europe like Greek government bonds in May when the Greek crisis blew up. The interesting point is the ECB is only doing this reluctantly and as equity markets have rallied and the credit spreads have come in, the ECB has progressively bought less and less junk government paper.
Basically last week they hardly bought anything – they’re probably going to go down to zero just as this counter trend rally peaks.

How early we go down depends on whether there is another bout of risk aversion or markets are just focusing on waning growth. This is Greek and PIG government bond yield spreads. I was recommending for several years the investor should bet on wise widening PIG spread. PIG spread, for people who don’t know this, is the average bond yield of Portugal, Ireland, Greece, Spain over the German bond yields-I closed out that just about when the Greek crisis peaked. And I think a better trade is going forward is what I called a Spanish flu trade, betting on rising Spanish CDS.

For now the jury doubts on whether these European countries can make the fiscal adjustments being demanded by the Germans, but people should understand that the Germans have a completely diametrically opposite view to the Americans – they simply do not believe that fiscally stimulating is the way to get yourself out of the economic problem. So right now the weaker part of Euroland has embarked on a fiscal adjustments which is intrinsically deflationary, given the downturn they are facing.

Advertisement

The stress test is being led by Ireland. Last year the Irish economy contracted in nominal terms by more than 10 percentage points. So far the Irish are taking the pain probably because the only boom they have had in the last 1000 years was when they join Euroland community. So in that sense willing to take quite a lot of pain, but in the big stress test it is going to be Spain.

Spain is a big important country. They had a massive private sector debt binge, they got the biggest housing bust in the west, even bigger than the US. So it is going to be interesting to see whether the Spanish political system can make this fiscal adjustment, given the fact they already have nearly 20% unemployed. I have an open mind on this. We just have to see what happens and may be the Europeans can make this fiscal adjustment, in which case it’s going to be a lot of pain, but the Euro as a currency is going to merge with huge credibility.

On the other hand, it may well be that this level of fiscal austerity is simply incompatible with the political systems of these Mediterranean countries. Right now, it is impossible to tell the European who is watching the football and now at the beach we can have a much better ideas they can take this pain by about January-February next year.

But in the meantime if the markets will test or are bound to test the European’s willingness to take this fiscal adjustment in the next few months. Tactically I would be selling the Euro against the dollar here as we had a significant bounce back in the Euro. So those are my thoughts on basically the West. It’s a deflationary environment. But in the US we are going to continue to stimulate in the Europeans because the Europe’s case is going to follow the German President.

Advertisement

Turning to Asia, Asia is a fundamentally healthy story unlike the West. In my view, the peak of the Asia ex-Japan index you saw prior to the credit crisis will be exceeded sooner or later because the Asian economies are growing healthily and have effectively decoupled from the West even though the markets haven’t. This is MSCI Asia ex-Japan relative to MSCI world index. They’ve been in & outperforming trend since the bottom of the Asian crisis in 1998 and that outperforming trend is resuming when the Chinese stock tightening and then formally start easing again which will happen in the next few months. That will reaccelerate Asian outperformance.

Valuation wise, Asia is trading in line with the US on the 12-month forward PE basis. In my view, sooner or later Asia is going to trade at a sustainable premium over the West because the fundamental growth story is so superior. In terms of my relative return asset allocation, I’m going to take a detour here. I am structurally overweight on India and Indonesia as these are the two best long-term stories in Asia. But tactically I have reduced India a bit and raised China because we are going to get a policy inflection points in China in the next few months which will be bullish for Chinese stocks.

But my big underweight in Asia Pac portfolio is Australia which is why I’m weaving more money into China because it has become cheap. What I am underweight on is those stock, sectors, countries which are perceived as beneficiaries of Chinese growth like the commodities sector, because in my view, Chinese growth is going to be slowing for the rest of this year and that’s a negative headwind for the commodities complex.

From an Indian standpoint that was obviously positive. I think oil is going this week to be as high as it’s going to get on its counter trend move. Clearly if you are more bullish on oil, you will be more bearish on India and this is my long only portfolio on Asia or ex-Japan.

Advertisement

I started this portfolio beginning of fourth quarter 2002, sent about 25 to 30 stocks in it, mostly large cap. I cannot have any cash and it’s long only and is basically playing the domestic story in Asia as always. Mostly has the biggest weight being in India because India since always has been my favourite equity story in Asia. It’s still got a big weighting in India. We can argue about the details of what stocks to own etc, but fundamentally this has India. Secondly, China if I did not have a big capital orientation, then I would have less in China, more in smaller Asian markets like Indonesia and Philippines.

That’s the performance of my long-only portfolio compared with the benchmarks. Since I cannot really have cash, as I said, so I cannot really hedge it, but for those who want to hedge I have been recommending since the middle of over 2007 that investors hedge this long Asian exposure by shorting western financial stocks. I have now narrowed that down in recent months into not shorting western financial stocks, but shorting European financial stocks because European financial stocks are much more geared to the systemic risk from junk European government debt and they are also in a much more leverage than American financial stocks.

This is my global portfolio I have also been running since 2002. This has run on a theoretical US dollar denominated pension fund on a 5-year view and this portfolio I have simplified in recent months have got 15% weighting in US 30 year treasury bonds.
That might seem crazy to people given the fact that the US government debt is getting bigger & bigger, but one of my views is that the most likely end game is a sovereign debt crisis in the US and the collapse of the US dollar paper standard. I don’t think that end game happens this year and in my view before this oust in the game is played out the deflationary pressures in the US will take bond yields much lower. So I think it’s quite possible the 10-year Treasury goes 2%, 30 year treasury goes to 3%. For people who think that’s insane, I should point out that the 10-year GDP went below 1% this week and in 2003 got to 0.45 basis points.
So the message is that in deflationary environment bond thing gets very low indeed because the risk aversion causes people like banks, insurance companies, individuals to buy bonds to lock in income because in deflationary environment there is not much income around. So that’s the deflationary hedge, but 45% of my portfolio is geared to the best story in the world, which is Asia.
So I got 15% in Asia or ex-Japan physical property, 30% in my long-only Asia or ex-Japan portfolio. Then I got a longstanding position in gold and gold mining stocks which I have since inception of this portfolio and this position in gold is basically hedging for US dollar denominated pension funds. The big picture risk is that one day simply the world revolt against the ongoing US stimulus and there is a sovereign debt crisis in the US dollar, US government debt, which means the end of the US paper standard and the end of the post 1945 Western paper currency system. And in that environment gold can go parabolic. My longstanding target for gold that can peak in this bull market is $35000 per ounce.

So this is a gold bullion chart in US dollar terms. The key point about this chart is that it’s quite obvious gold is in a bull market and remains in a bull market and this bull market, when it ends, will end in a parabolic spike which we have not seen yet. The next obvious trigger for the next big move in gold will be the next time Mr. Bernanke adopts quantitative easing and the next time he does it he who is going to have to expand the balance sheet more than the last time (because otherwise people are going to worry if it’s going to work), but cannot do it right now because the news flow is not bad enough.

Gold stocks relative to gold bullion price. In my view gold stocks made that relative low to gold bullion price in 2008 when commodities collapsed. So for equity managers who cannot buy pure bullion I would say look at gold mining stocks because if gold goes $35000 per ounce, it is going to be massive operating leverage for those mine. Gold stocks that actually produce gold haven’t hedge the gold and on jurisdictions where governments don’t cease the gold often.

Advertisement

I am turning to some Asian Pacific charts. I will just run through few charts on China that’s a big story for everywhere as I say Chinese market has underperformed this year. The key point to understand about Chinese stocks is that they are policy-driven. Indian stocks are earnings-driven while Chinese stocks are policy-driven. The Chinese government is tightening, that is why the market has been going down. When the Chinese government starts easing, the Chinese stocks will go up and then may be outperforming Indian stocks for a period.

Real GDP growth in China. China growth peaked in my view first quarter. It’s going to be slowing for the rest of this year probably an annualised growth 12% first quarter, may be down to 1% by the fourth quarter. That is going to create a lot of market noise. It will be negative for commodities. It’s not a big deal, but it will create a lot of noise. Chinese bank landing has slowed dramatically this year from the surge last year. China is a command economy banking system. So that looks dramatic, but that has seen the loan growth slowing to 18% which is still respectable, it’s not cold turkey.

China has been tightening on the property market. So what the stock market in China wants to see is more and more developers willing to cut property prices because it’s more than evident that developers are stopping raising prices and starting to cut prices. The greater the hope that the Chinese government stops tightening that process should play out in the next few months. As you can see here average daily residential sales of Chinese properties have fallen pretty dramatically since April when the government got more aggressive on tightening. You’d have read a lot about Chinese property bubbles, especially in America.

The Chinese property markets have a lot of excess supply, but it’s not a bubble because you have very conservative mortgage financing. What you do have there is a lot of high end developments sitting 80% empty. So Chinese people like to have lot of flat value and don’t like to have flats once used because they think a used flat is devalued just like a used car.

Advertisement

What about the currency? When the renminbi starts to rise against the US dollar incrementally, maximum incremental appreciation will be of 5%. So the Chinese are going to let their currency go up slightly, but you are not going to get any aggressive moves.
I got a chart on Hong Kong just to highlight that we have got a big long-term asset inflation story in Asia. The quintessential asset inflation story in Asia is Hong Kong because of the supply constraints. In my view, Hong Kong property would sooner or later exceed 1997 peaks. You can get a mortagage in Hong Kong today for less than 1%. There you see, apart from Mumbai, this is a one property market in Asia with the massive supply constraint. This is a new supplier residential properties. So Hong Kong I think is a classic asset inflation story to monitor.
Turning to India, I would not go too much linked to India because everybody over here would know more about it than me, but we probably had a big inflation scare at the start of this year. In my view, it’s fundamentally silly to worry too much about inflationary pressures in Asia.
We should be celebrating the fact that there is inflation because if there wasn’t inflationary pressures in Asia, it would mean the world is facing a global depression because there is no growth dynamics in the developed world. So I am glad there is inflationary pressure. Having said that inflation is going to be coming off in India for the rest of this year which means that concern should recede. The central bank will continue to tighten incrementally. I think that’s sensible given the external environment, but I think incremental tightening that the RBI is doing is enough to upset stocks here unduly.

Bank credit growth. This I think is a very important chart. The Indian banking sector is a capitalist banking system unlike the Chinese system. So when the economies slow, the banks slow their lending whereas in China they were ordered to lend more. Now the credit cycle is picking up again, that’s a very healthy development. We are looking at about 20% loan growth in India this year. But I think the most important positive points of all is that the credit cycle is being led by infrastructure loans, not personal loans, as you can see from this chart. This raises the key point which in my view is the critical bearable for the Indian macroeconomic story this year and for the next 5 to 10 years is whether we can get an infrastructure cycle playing out.

The fact that infrastructure loans are leading the credit cycle is anecdotal evidence that is happening. If we get infrastructure happening in India, it’s quite possible that India can grow at 9% plus a year for the next 5 years at least, if not 10 years, which means that India in my view is going to be growing more rapidly than China. In my view a more basic trend growth in China is going to be 8% and that’s a growth rate that Chinese Communist party is going to be comfortable with. So the higher growth rate in India than in China, if the infrastructure story happens, is going to raise the profile of the Indian story globally.

Clearly if I am wrong and infrastructure does not happen in India, the whole Indian story becomes much less interesting. It’s not a disaster, but the country only grows just 5%-6%. So this is fixed investment relative to GDP in India. I am expecting this line to pick up again. Car sales, two-wheelers sales are going up. So the consumer story is still perfectly good story in India. It has picked up with the monetary easing, but as I say the key variable for me is infrastructure.

In terms of risks to the Indian markets, probably the biggest risk to the Indian market is simply the huge amount of foreign money. My own guess is that the next time there is a global hiccup, foreigners will sell India less aggressively than in 2008 for the simple reason that India has shown it can decouple from the US economic cycle.

Advertisement

The other point is the fact that foreign investors stay much in India is basically confirmation that India is a good story and those foreign investors who have not yet invested in India are all desperately waiting for a correction. So they can invest, that’s the mindset of them.

One year forward price to book. India is not cheap, but it’s not expensive in the context of Indian stock market history and in my view the Indian stock market will continue to trade at a premium to Asian and mother of emerging markets because the Indian market is like one big growth stock and growth stocks trade at a premium. Clearly, if you want to enter in an equity portfolio for dividends & you don’t buy India, then you should go and look at Singapore.

This chart perceives a useful chart for anybody who is trying to raise Indian funds in the room because it shows a huge outperformance of India – MSCI India relative to MSCI China in recent history. I will just end with the 3 charts on Japan & the reason I am doing this is because of my experience when I lived in Japan in the early 90s and the experience of Japan in the last 20 years is a potential lead indicator of what is going to happen in the West.

Advertisement
Add ET Logo as a Reliable and Trusted News Source


Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business & Hustles

OpenAI rebrands AI agents as ‘dots’ amid security fears

Published

on

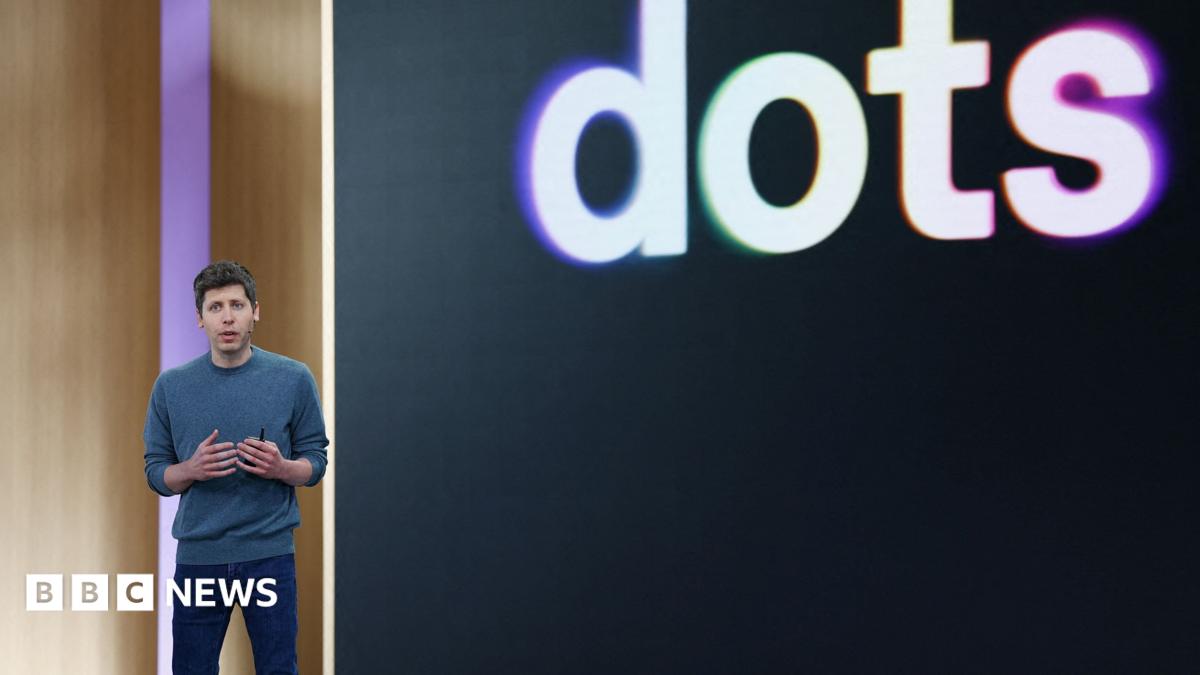
OpenAI CEO Sam Altman standing on stage at his company's annual developer conference in front of a screen with "dots" displayed behind it.

OpenAI has chosen to rename new versions of artificial intelligence tools widely known as agents. They are now being called “dots.”

Company boss Sam Altman, speaking in San Francisco on Tuesday during OpenAI’s yearly event for technology developers, referred to “dots” as “remarkably capable, always-on agents that can handle really anything you can think of.”

OpenAI in recent months has come under intense scrutiny as internal tests of its AI agents have revealed often unexpected and occasionally harmful actions, leading to more public and government fears.

Dots, however, were pitched as brightly colored cute cartoons meant to function as digital assistants for people with busy lives.

Advertisement

The dots, Altman said, “can handle really anything you can think of.”

A glossy video was shown during the event, with people speaking to and naming animated versions of their “dots,” then giving them various tasks, like building a website and booking afterschool activities for their children.

Speaking about “my dot,” Altman almost entirely eschewed referring to the tool as an agent, which has been in common use for years. AI agents are essentially AI chatbots that are programmed to operate somewhat autonomously.

“You just give your dot a responsibility… and your dots will just get to work and keep working,” Altman added.

Advertisement

The day prior to OpenAI’s Tuesday event, the company said it was delaying the launch of its latest model due to certain safety issues that showed up during internal testing.

Since July, the company has been dealing with a series of issues with its AI agents acting improperly. It has faced unprompted hacking into the AI platform Hugging Face, posting to third-party websites images that AI agents took from ChatGPT user chats, and accessing non-public information maintained by the Australian government.

OpenAI, as well as rival AI firm Anthropic, previously delayed public release of certain AI models due to potential risks, mostly pertaining to cybersecurity or hacking concerns.

Both companies also expect to be listed on the public stock market in the coming months. Anthropic likely will do so this year, while OpenAI is poised for 2027.

Advertisement

And both companies have lately been clear that they believe AI poses a genuine risk on a large scale, be it to public infrastructure or public safety.

Speaking last week to the UN, Altman pleaded for “national and international” AI standards on measuring the capabilities of an AI tool, assessing related risks, AI safeguards, and the degree to which human oversight over such tools is maintained.

Dario Amodei, the head of Anthropic, told the UN that if the speeding development of AI was not properly managed and overseen, future versions of the technology “could be a risk to humanity as a whole.”

Advertisement
Continue Reading

Business & Hustles

UK chancellor uses bitcoin to mock Nigel Farage

Published

on

UK chancellor uses bitcoin to mock Nigel Farage

UK Chancellor of the Exchequer John Healey has compared Nigel Farage’s fiscal policies to a “BTC account” handled by one of the UK’s most financially irresponsible prime ministers.

UK Chancellor of the Exchequer! “Don’t make me laugh,” John Healey has compared Nigel Farage’s fiscal policies to a “BTC account” handled by one of the UK’s most financially irresponsible prime ministers.

This is from Healey the most useless piece of communist crap ever appointed to this position. This man is really as stupid as they come. Support the British people? NO, he supports the communist socialist failed agenda and the EU, like the rest of Labour’s traitor MPs. Certainly not you the British people, and you voted for the new Communist socialist Islamic republic of Britain.

Now he and Burnham are going to piss all over you while calling for another referendum on rejoining the dictatorship called the EU, OH, AND THEY WILL USE THE WORD DEMOCRACY, SOMETHING THEY DON’T SUPPORT AND NEVER HAVE.

Advertisement

Healey’s jab at the Reform leader during Labour’s 2026 party conference referred to the perceived economic failure of the UK’s shortest-serving prime minister, Liz Truss.

Truss’s financial policies were widely criticised for their negative impact on financial markets. This led to a rebellion from several Tory MPs, and she was forced to resign within 44 days of her premiership.

Healey appeared to suggest that a “BTC account” is an equally financially irresponsible form of finance, and that only by pairing it with Truss would you recreate the “fantasy funding” ideals of Nigel Farage.

Healey’s comments upset a lot of Bitcoiners, who claimed his “derogatory” description of a “BTC account” demonstrated “staggering ignorance.”

Advertisement

Freddie New, CEO of the BTC Lightning transaction fee firm B HODL, said Healey is “gleefully ignorant that he thinks it is possible to have a ‘BTC account.’”

UK podcaster Peter McCormack said, “Healey making a dismissive joke about Bitcoin shows that he likely has a woeful understanding of economics, particularly scarcity.”

Most criticisms were technical and took offence at the use of the word “account,” which contrasts with the phrase “crypto wallet” used by crypto holders.

Healey wants a ‘new age of industrialisation’

Advertisement

Healey was defence secretary under Sir Keir Starmer’s leadership before he resigned in June. He argued that the government wasn’t willing to spend enough on national defence. 

During yesterday’s conference, Healey announced new measures to support a “new age of industrialisation,” which includes a £300 million investment from Rolls-Royce toward its factories, and £6 billion in government contracts to build new submarine docks. 

A so-called “Union Learning Fund” was also announced, as were a National Wealth Fund to help create 130,000 jobs by 2030, and a £100 million-backed local apprenticeship scheme. 

Got a tip? Send us an email securely via Protos Leaks. For more informed news and investigations, follow us on X, Bluesky, and Google News, or subscribe to our YouTube channel.

Advertisement

Source link

Source link

Advertisement
Continue Reading

Business & Hustles

El Pollo Loco to open first New York restaurant

Published

on

El Pollo Loco to open first New York restaurant

El Pollo Loco will open its first New York City restaurant next year as the California chain looks to become a national player.

El Pollo Loco has closed three development agreements for a total of 15 restaurants in the New York area over the next five years, the company announced on Tuesday. The first location will open in Queens in mid-2027.

Founded in Mexico in 1975, El Pollo Loco opened its first U.S. restaurant in Los Angeles. The majority of its locations are still concentrated in California, but its footprint has grown to more than 500 restaurants across 10 states. It is best known for its bone-in grilled chicken, although its menu has grown.

CEO Liz Williams wants to make El Pollo Loco into a national chain. To expand outside its Southwestern stronghold, El Pollo Loco will open restaurants on the East Coast and then move its way back to the West, she said.

Advertisement

To succeed in new markets, the chain will have to build its brand awareness in a crowded space where consumers are watching their budgets.

“Being a 50-year-old brand, people have seen it over the years and have always had that curiosity, but we have our work cut out,” Williams said.

Under Williams’ leadership, El Pollo Loco has embarked on a turnaround focused on modernizing its restaurants and expanding its menu into more convenient options, like wraps and chicken tenders. The efforts have started to pay off for the chain, which has reported three straight quarters of same-store sales growth.

“In the current quarter, we’ve expanded margins, and the business model is healthy overall,” Williams said. “The brand has gotten even stronger and healthier.”

Advertisement

El Pollo Loco has also been expanding quickly during her tenure. When she began in March 2024, the chain was in just six states. Now, it is in 10. And while it opened nine restaurants last year, El Pollo Loco is projecting 10 to 18 new locations by the end of 2026.

Investors like the company’s trajectory. Shares of El Pollo Loco have climbed 44% over the last year. The S&P 500 rose more than 15% over the same period.

Its comeback coincides with a challenging time for the restaurant industry. Burger and taco chains have been facing soaring costs for beef. Consumers have been dining out less frequently to save money, which has intensified competition between eateries.

El Pollo Loco has also had to contend with more competition as restaurants aim to cash in on growth in the chicken category. McDonald’s and Taco Bell — Williams’ former employer — have expanded their chicken options in recent years, fueled by consumer market research. And chicken-focused chains have been expanding quickly, from newcomer Dave’s Hot Chicken to Southern names like Zaxby’s and Raising Cane’s.

Advertisement

In 2024, El Pollo Loco was the eighth-largest chicken chain by U.S. sales, with 2.1% market share, according to Barclays.

But with its focus on grilled chicken and Mexican-inspired flavors, El Pollo Loco stands out from the crowd, Williams said.

“Everyone is talking about wanting to eat a little better and really thinking through their choices,” Williams said. “Everyone loves fried chicken … However, in terms of what you’re able to eat every single day, grilled chicken is just a better option.”

The expansion news comes as El Pollo Loco shakes up its leadership.

Advertisement

The company on Friday said in a regulatory filing that Damon Thomas will join the company as chief operating officer. He joins the company from Shake Shack.

Tara Hinkle was also recently tapped as the chain’s new chief development officer. She previously held roles at The Coffee Bean & Tea Leaf, Taco Bell and Starbucks before joining the company in July.

Correction: This story was updated to reflect that Williams said the company’s brand has gotten stronger and healthier. A previous version misquoted her.

Advertisement

Continue Reading

Business & Hustles

Bangkok floods threaten to shave 0.3 percentage points from Thailand’s 2026 growth

Published

on

Bangkok floods threaten to shave 0.3 percentage points from Thailand’s 2026 growth

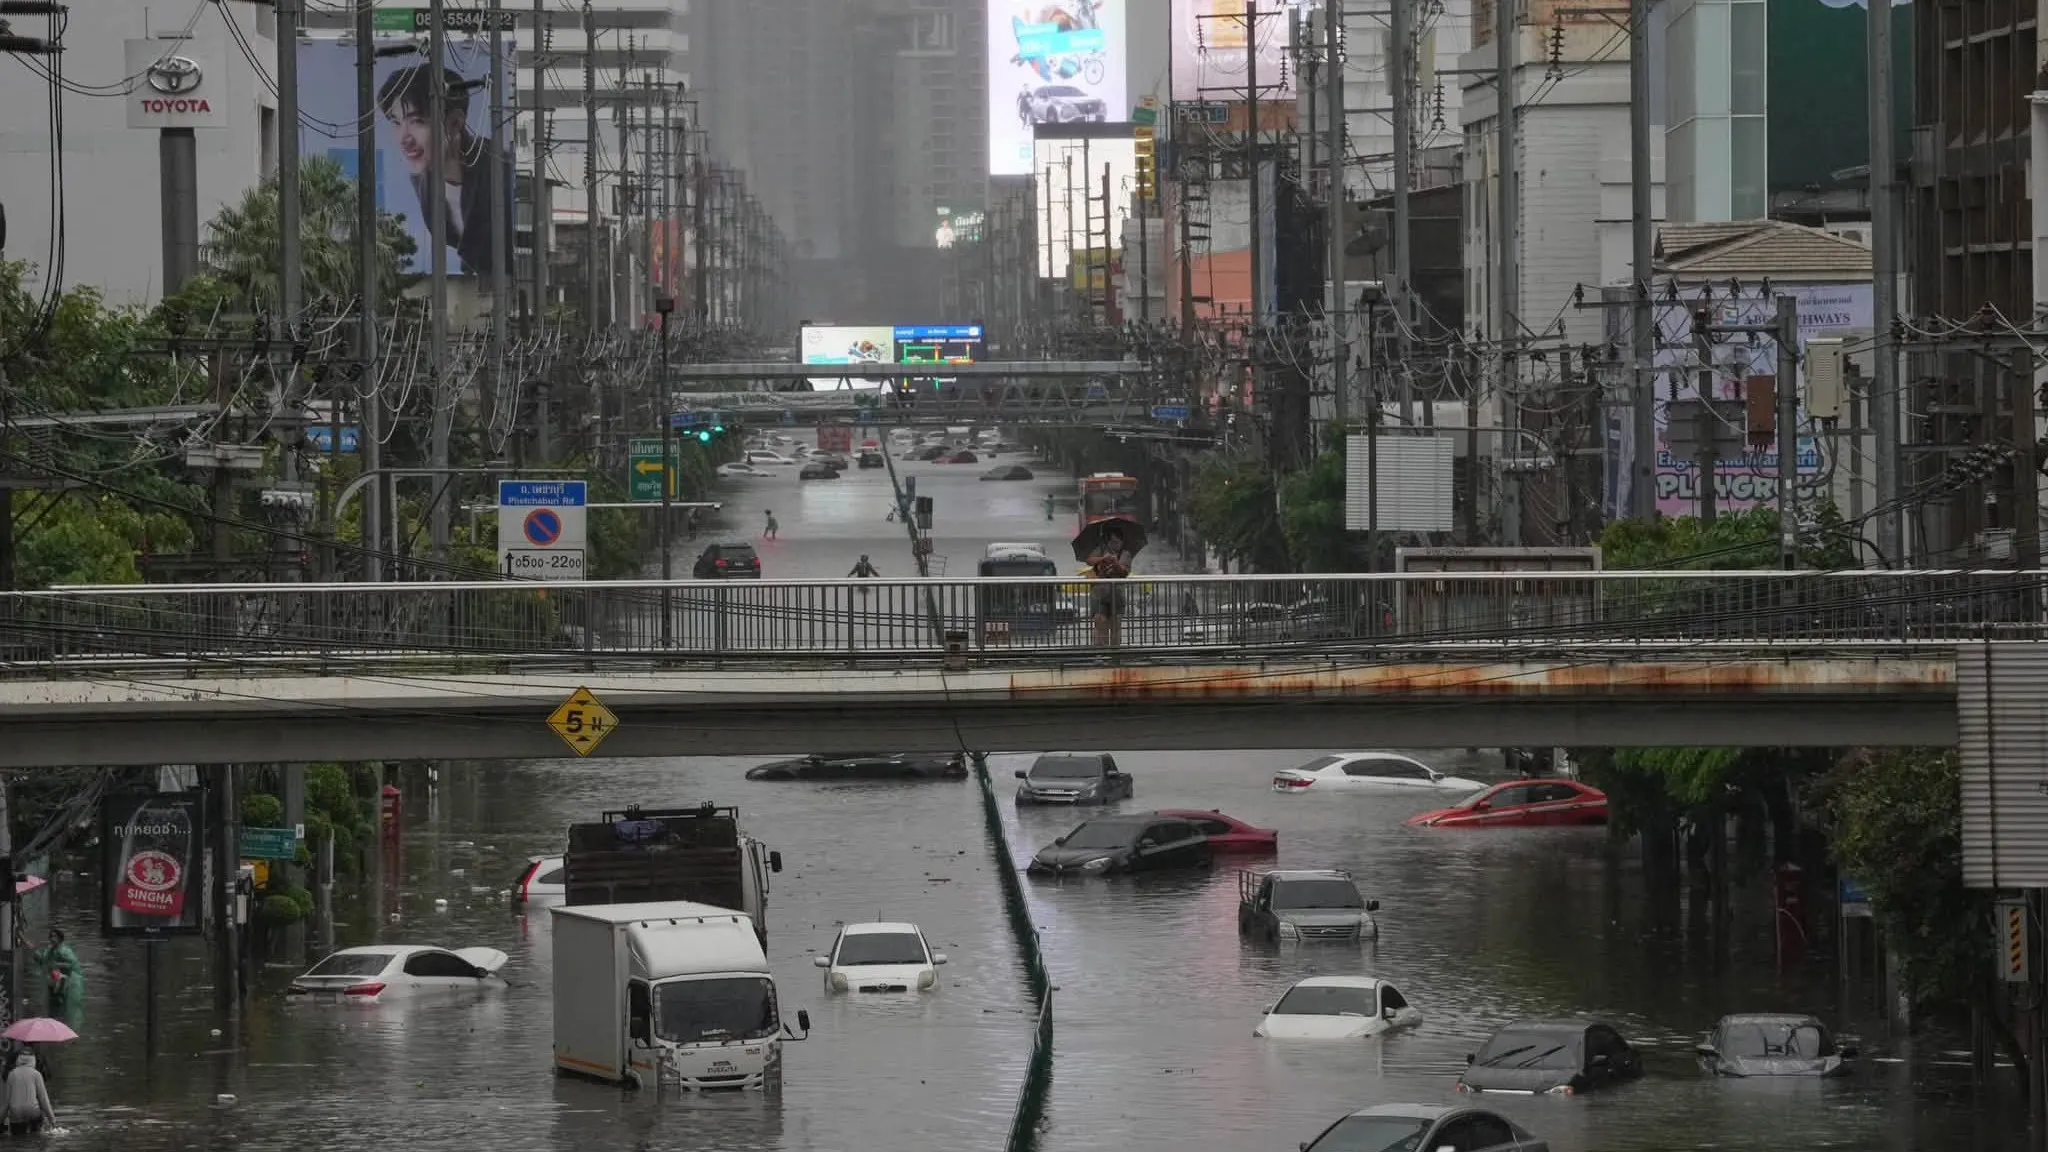
Severe flooding in Bangkok and surrounding provinces is projected to reduce Thailand’s 2026 economic growth by 0.3 percentage points, lowering estimates to 2.1%. Immediate losses are estimated at 11 billion baht nationwide, with some assessments ranging up to 33.8 billion baht, and Bangkok bearing the largest share of damage.

The capital experienced significant rainfall that overwhelmed drainage systems, disrupting transport, commerce, and supply chains, particularly affecting small businesses. The government declared special holidays to ease pressure, while banks introduced relief measures. The final economic impact depends on how quickly flooding subsides and whether further disruptions occur.

Thailand’s latest flooding could reduce annual economic growth by 0.3 percentage points this year, as widespread disruption across Bangkok and surrounding provinces weighs on businesses, transport and household spending.

The flooding could lower Thailand’s 2026 growth rate to 2.1%, from an earlier estimate of 2.4%, according to economist Aat Pisanwanich, who was quoted by Reuters in a recent article. Third-quarter growth could decline by approximately 0.5 percentage points to 1.7%.

Advertisement

The immediate economic losses have been estimated at 11 billion baht, or approximately $320 million, nationwide. A separate assessment by Rangsit University placed the potential losses between 16.9 billion and 33.8 billion baht, with a moderate-damage scenario reaching 25.345 billion baht.

Bangkok is expected to bear the largest share of the losses, at approximately 10.586 billion baht. The estimate covers the period from September 24 to 27 and includes disruptions to commerce, services and travel.

Bangkok bears the largest impact

The capital received around 320 millimetres of rain over two to three days, overwhelming drainage systems and flooding entire neighbourhoods. Water levels began to recede in several areas after the rain eased, but residents in some communities remained stranded or dependent on evacuation centres, as was reported by varoius medias like Internazionale.

The economic impact has extended beyond direct damage to buildings and vehicles. Businesses have faced difficulties moving workers, receiving supplies and delivering products, while shops in flooded areas have struggled to reopen.

Advertisement

Transport interruptions have also reduced consumer activity. Residents unable to travel to work or commercial districts have postponed purchases, while companies have incurred additional costs for alternative routes, temporary closures and emergency repairs.

The government declared special holidays for civil servants in Bangkok and three surrounding provinces on September 28 and 29 in an attempt to reduce travel and ease pressure on the transport system. However, the measure also reflects the scale of the disruption facing the Bangkok metropolitan area.reuters

The Stock Exchange of Thailand will continue operating during the special holidays, maintaining trading on the SET, mai, TFEX, LiVEx and related platforms. The decision is intended to preserve financial-market continuity even as parts of the capital remain affected by flooding.nationthailand

Pressure on supply chains

In the other hand, the Federation of Thai Industries has warned companies to protect workers, review transport routes and prepare for further disruption. Water levels in reservoirs and canals remain a concern even after rainfall has eased in parts of the country.

Advertisement

The risk is particularly significant for businesses that depend on just-in-time deliveries. Delays affecting warehouses, roads, ports or industrial facilities can spread quickly through supply chains, even when the original flooding is concentrated in a limited number of districts.

Banks have begun offering relief measures to affected households and companies. Krungthai Bank and Export-Import Bank of Thailand are providing repayment assistance, lower interest rates and additional liquidity to customers facing losses or cash-flow problems.

Those measures could prevent temporary disruption from becoming a wider credit problem. However, debt relief cannot replace lost inventory, damaged equipment or the income businesses lose during forced closures.

The flooding has also exposed differences in economic vulnerability. Large companies may have insurance, backup facilities and alternative suppliers. Small businesses and informal operators often have fewer reserves and are more likely to face a permanent loss of income after several days without sales.

Advertisement

Growth outlook becomes more fragile

The estimated 0.3 percentage-point reduction in annual growth would not by itself push Thailand into recession. But it adds another obstacle to an economy already dealing with moderate expansion, high household debt, external uncertainty and persistent energy costs.

The final impact will depend on how quickly water levels fall and whether additional rainfall causes a second wave of disruption. A rapid recovery could limit the damage, while prolonged flooding could increase losses through reduced production, weaker consumption and delayed investment.

For now, Thailand’s economic response is focused on drainage, emergency assistance and financial relief. The next stage will be more difficult: restoring businesses, repairing infrastructure and determining whether the country’s cities and supply chains are prepared for increasingly frequent climate shocks.

The final economic cost remains uncertain. The Federation of Thai Industries has warned that disruption can spread through supply chains, affecting raw-material deliveries, worker mobility, warehouses and machinery. At the same time, economists have stressed that a rapid recovery in affected areas would limit the damage, meaning the duration of the flooding is now more important than the initial rainfall event.

Advertisement

The floodwaters may recede within days. The economic consequences will last longer, particularly for smaller businesses that cannot afford another interruption before the recovery from this one is complete.

The episode also exposes a longer-term investment issue. Bangkok’s vulnerability to extreme rainfall creates recurring costs for retailers, manufacturers, logistics operators and property owners. Beyond emergency relief, businesses and policymakers face increasing pressure to invest in drainage capacity, flood barriers, water-management systems and continuity planning.

Continue Reading

Business & Hustles

Develop sets $458 million growth capital budget

Published

on

Develop sets $458 million growth capital budget

Growth will continue at Bill Beament-led Develop Global in FY27, following the release of its guidance metrics for the upcoming year.

Continue Reading

Business & Hustles

Dave & Buster’s interim CFO Cory Hatton buys $25,999 in stock

Published

on


Dave & Buster’s interim CFO Cory Hatton buys $25,999 in stock

Continue Reading

Business & Hustles

Market veterans favour value plays over crowded, expensive themes

Published

on

Market veterans favour value plays over crowded, expensive themes
After two difficult years for Indian equities, there is scope for reasonable returns as valuations turn less demanding, according to senior market participants who spoke to ET. Large caps look better placed, while the outlook is more cautious on mid- and small-caps. Financials, manufacturing and consumption are among the preferred themes, while views on technology are sharply divided

NEELESH SURANA, CIO, Mirae Asset Mutual Fund

MARKET OUTLOOK: India looks better positioned than sentiment suggests and is a natural hedge against crowded AI trade. Valuations are no longer a headwind, while domestic fundamentals are sound. Any global trade rotation could be meaningful. Key risks are elevated crude, rising developed market bond yields, El Niño and heavy equity issuance. Overall, we expect low-teens returns.
PREFERRED INVESTMENT STRATEGY: Our strategy is a barbell, combining quality stocks with strong earnings upgrades at sensible valuations with holding sector leaders that have corrected over the past two years and are now in value zone.

THEMES LOOKING ATTRACTIVE: Banking, consumer discretionary, healthcare and manufacturing. Sector leaders, impacted by FPI selling over the last two years, are now attractive.

THEMES TO STAY AWAY FROM: Slow-growth or disruption prone sectors like consumer staples and IT. Cautious on narrative-driven, richly-valued sectors like capital goods.


Read more: Goldman Sachs identifies 42 Indian stocks riding AI build-out

JANAKIRAMAN RENGARAJU, CIO – India Equities Templeton Global Investments

MARKET OUTLOOK: The 12-month base case for Indian equities may not be quite euphoric, but it is constructive. Largecap valuations are more reasonable, while higher mid- and small-cap multiples call for greater prudence. Globally, the picture has deteriorated. Unresolved conflicts have entrenched inflationary pressures, while rising interest rates and heavy fiscal debt reinforce each other. Tariff uncertainty continues to cloud trade growth, while questions are emerging over the viability of massive AI investments, even as enthusiasm and valuations remain elevated.PREFERRED INVESTMENT STRATEGY: Adopt a tone of ‘cautious optimism’ over the medium term.

THEMES LOOKING ATTRACTIVE: Financials, industrials and capital goods, consumption and electronic manufacturing, which are linked to capex pick up, rising affluence and credit growth.

THEMES TO STAY AWAY FROM: Avoid expensive small and mid-caps with weak cash generation and businesses dependent on endless equity funding.

Read more: SIPs offer steady gains as most fund categories beat benchmark indices

ANISH TAWAKLEY, CIO, DSP Mutual Fund

MARKET OUTLOOK: Economy remains in good shape, while valuations are now neutral. This should translate into reasonable market returns broadly in line with earnings growth.

PREFERRED INVESTMENT STRATEGY: Don’t chase narratives that have already played out, rather look at sectors that have been underperforming since the last 2-3 years.

Advertisement

THEMES LOOKING ATTRACTIVE: Private banks, insurance companies, automobiles and cement.

THEMES TO STAY AWAY FROM: Careful about companies where promoters are diluting (either through primary or secondary sales) or where private equity is selling, including IPOs. Promoter dilution and PE sales happen when performance and valuations are close to peaks. Cautious on metals, IT and FMCG. For IT, the problem is not AI but the fact that Indian listed companies are losing market share to GCCs set up in India.

R SIVAKUMAR CIO, Axis Mutual Fund

MARKET OUTLOOK: The outlook is constructive. Economic slowdown over the last few quarters appears to be more cyclical than structural. Valuations in parts of the market remain elevated, particularly within mid- and small-caps.

PREFERRED INVESTMENT STRATEGY: Alpha generation is likely to come from selective stock picking rather than broad market direction. A balanced approach across largecaps, which offer valuation comfort and resilience, and select mid-cap opportunities, which continue to deliver superior earnings growth, remains appropriate.

THEMES LOOKING ATTRACTIVE: Constructive on manufacturing, power and electrification, energy transition, select financials, particularly banks and capital-market-linked businesses, as well as export-oriented companies.

Advertisement

THEMES TO STAY AWAY FROM: Investors should avoid chasing momentum in overcrowded themes. In technology, we remain watchful of disruptions and pricing pressures emerging from AI-led changes in the global IT services landscape

SHANKAR SHARMA, Founder, GQuant

MARKET OUTLOOK: Barring occasional rallies, I do not see the Indian markets outperforming the world or even the peer group. The Vaibhav Suryavanshi Syndrome afflicts Indian companies: domestic success is mistaken for globally transferable skill. Largecaps have thrived on India’s easy pitch, building market capitalisation rather than global scale and brands. When domestic growth fades, competing overseas will require an entirely different mindset. There will be pockets where money is going to be made; but in aggregate, Indian returns will disappoint for the coming year.

PREFERRED INVESTMENT STRATEGY: The future of the Indian stock market lies in getting “techified”. Tech has been my theme in the last 2 years since the bear market started in India and I have actually made money even in this very-very tough market. This is not going to change anytime soon. Pharmaceuticals is also going to be a good place to be in.

THEMES LOOKING ATTRACTIVE: For me, tech is 80% of the allocation and pharma is 20% and there is nothing else that I am interested in India.

THEMES TO STAY AWAY FROM: Companies which service the domestic Indian consumer. That trade is on its way out and this is not where I would deploy a lot of capital.

Advertisement

Add ET Logo as a Reliable and Trusted News Source

Continue Reading

Business & Hustles

Accountancy firm Hazlewoods move to larger offices in Cardiff to support expansion

Published

on

Business Live

The firm has relocated to the South Gate House office scheme

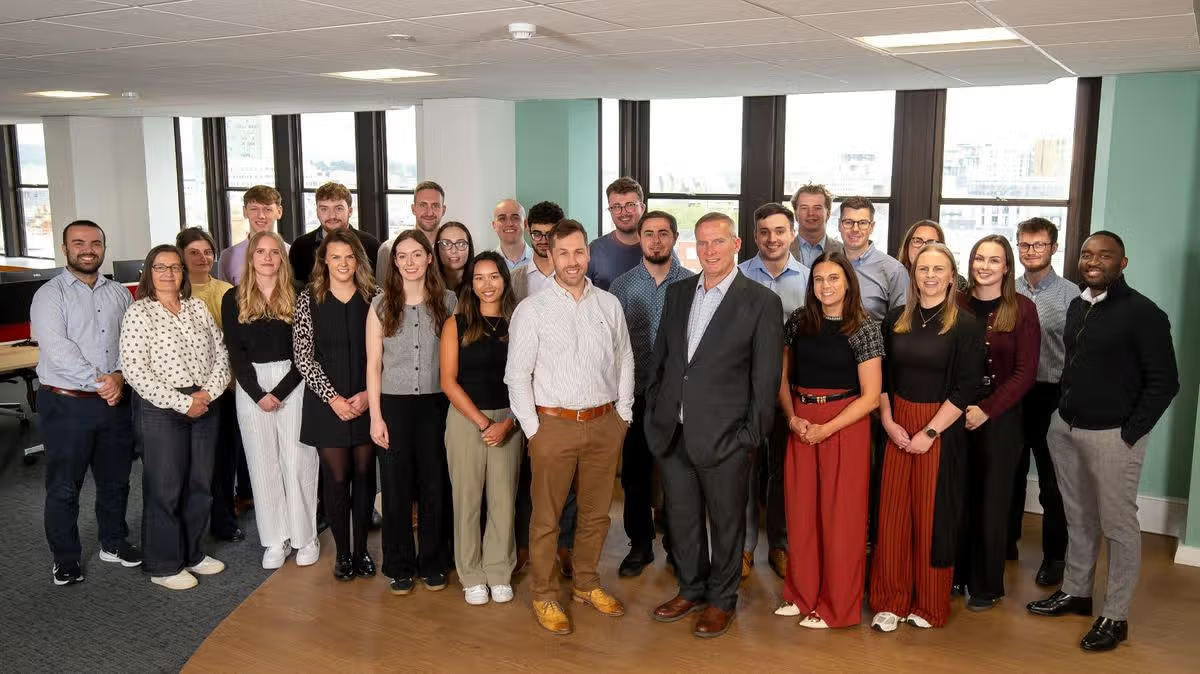
The Cardiff team of Hazlewoods

Accountancy and business advisory firm Hazlewoods has relocated to larger offices in Cardiff to support expansion plans.

Having set up its first office in Wales at the Capital Tower office building in 2024, it has now moved its team of 34 to South Gate House.

Tom Davies, director at Hazlewoods Cardiff, said: “This is an exciting step for Hazlewoods and reflects the progress we have made since launching in the city less than two years ago. We have built a very strong team here and have been really encouraged by the response from both new and existing clients, reflecting our commitment to developing deep relationships across the region.

Advertisement

“The new office gives us the space to continue growing while maintaining the collaborative approach that is such an important part of the way we work.”

Bruce Black, corporate tax director, said: “This move creates the environment we need to continue finding and developing local talent to build the team, while maintaining the high level of service our clients expect from Hazlewoods. It reflects just how positively the Cardiff office has developed in such a short space of time.

“The team in Cardiff has done a great job of growing the business and I look forward to seeing that continue. We have the expertise, ambition and people to build a really strong presence in Wales, and the new office gives the team a great base from which to do that.”

Hazlewoods is one of the largest independent accountants and business advisers in the South West and Wales, with more than 600 employees and a growing presence in Cardiff, alongside its offices in Cheltenham and Bristol.

Advertisement

The firm provides audit, accounting, tax and advisory services to corporate and private clients and is particularly well known for its specialist sector expertise across the UK. Last year, the firm recorded a turnover of £54.3m.

Its managing partner, James Morter, said: “It has been very gratifying to see the way that Hazlewoods has been welcomed into Cardiff. Early on, we identified a gap in the Welsh market for a firm of our size and experience, and when you combine that with the talent pool in the city, it felt like a natural next step.”

Property advisory firm Knight Frank represented Hazlewoods on the deal, while its building consultancy team supported the fit-out of the new space.

Mark Sutton, office agency partner at Knight Frank’s Cardiff office, said: “Hazlewoods was looking for a space that could support its continued growth in Wales, while offering excellent connectivity and the flexibility to create a workplace suited to its needs.

Advertisement

“South Gate House provided the right combination of quality space and a prime city-centre location, and it has been a pleasure to support the team through the move.”

Continue Reading

Business & Hustles

Perpetua Resources at Mining Forum Americas 2026: shift to construction

Published

on


Perpetua Resources at Mining Forum Americas 2026: shift to construction

Continue Reading

Business & Hustles

What Trump’s potential US diesel export ban could mean for you

Published

on

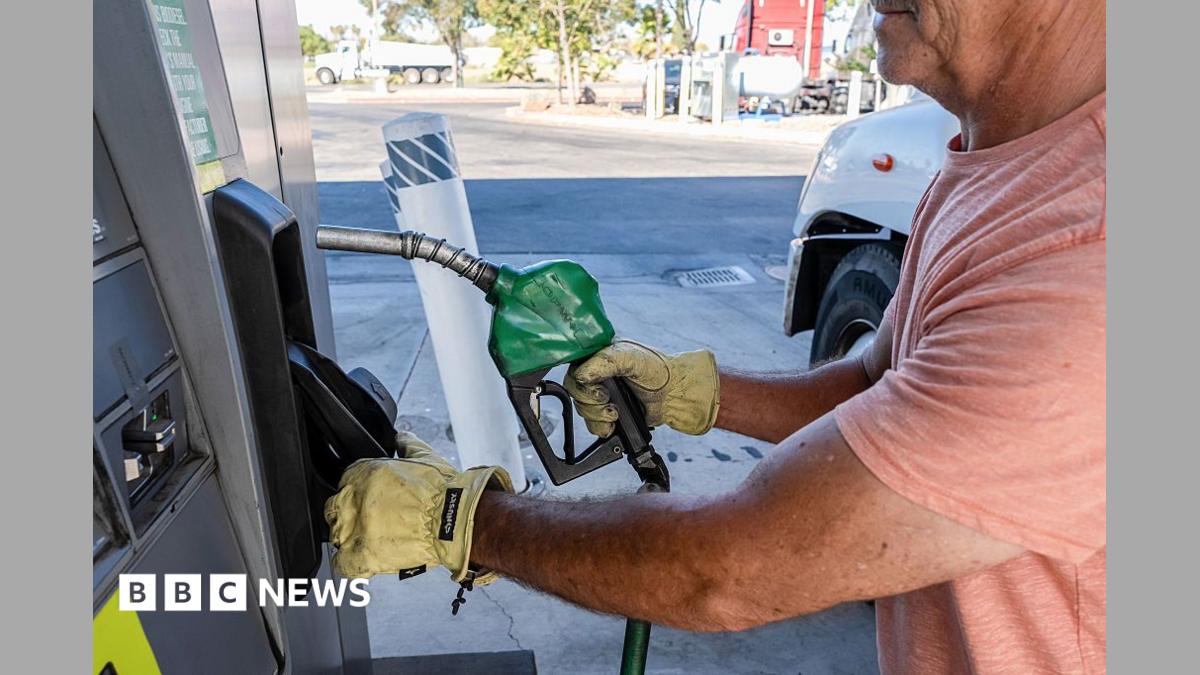
A driver returns a fuel nozzle after refueling a tractor trailer with diesel fuel at a Chevron truck stop in Tracy, California.

For the US economy, a ban could deliver short-term relief at the pump by flooding the domestic market with excess supply.

However, energy analysts warn it could backfire.

David Fyfe, chief economist at Argus Media, notes that cutting off American supply would likely cause international prices to skyrocket.

That would push up global freight, food, and industrial costs, ultimately “feeding inflation back into the global economy”.

Advertisement

“At a stroke, the US’s reputation as a reliable supplier of energy to the world would be shot,” Fyfe added.

Removing more than a million barrels of daily American supply would trigger a fierce bidding war among importing nations in Latin America and Europe.
Sarah Raffoul, analytics manager at Argus Media, noted that while higher international prices would eventually curb demand, the immediate gap would severely strain trade relationships and accelerate global inflation.
Advertisement

Continue Reading

Trending

Copyright © 2025