Crypto
NYSE’s tokenized stocks plan puts control of onchain trading under scrutiny

NYSE and Blockchain.com have agreed to explore distributing tokenized U.S. shares to a global crypto audience. The deal leaves the harder questions for the platform’s launch: whose record proves ownership, who decides who can trade, and how the new market stays tied to the shares beneath it.
Summary
- NYSE and Blockchain.com signed a Sept. 23 memorandum covering access to tokenized shares and ETFs, subject to approvals.
- Blockchain.com reported more than 44 million confirmed accounts, a distribution figure that is not a count of eligible investors.
- The SEC’s separate Sept. 17 exemption caps qualifying venues at 75 Tier 1 and 250 Tier 2 stock symbols.
- Third-party stocks under that SEC exemption require 30 days’ issuer notice and cannot trade if the issuer objects.
- DTCC’s July 15 production trades used tokens representing securities held at DTC; its wider service targets October.
The New York Stock Exchange and Blockchain.com signed a memorandum of understanding on Sept. 23 to explore giving Blockchain.com customers access to tokenized U.S. stocks and exchange-traded funds. The route would run through NYSE’s planned digital alternative trading system, subject to required regulatory approvals. It is a plan for distribution, not a launch of stock trading to the company’s more than 44 million confirmed accounts.
NYSE is building a market that could operate at all hours and settle trades onchain. Blockchain.com brings a customer network already accustomed to digital assets. The announcement does not identify the final custody chain for each share, say which customers will qualify, or publish the terms under which a token could be converted back into a conventional holding. Those details decide what a buyer owns.
The answer will differ by product. A token can be the security recorded on a company’s shareholder file. It can represent an entitlement to a share held through an intermediary. It can instead be a contract that tracks a share’s price. All three can display a ticker on a phone. Only the first two can potentially carry the underlying shareholder interest, and even there the legal path to voting or dividends needs to be specified. The Securities and Exchange Commission drew those distinctions in a January staff statement on tokenized securities.
The new agreement makes an old stock market question visible in a new format. A blockchain can record a transfer. It does not, on its own, determine which entity owes the holder a dividend, who can correct a mistaken transfer, or whose ledger a company treats as its shareholder record.
The Sept. 23 deal is a distribution agreement, not an open market
The parties called their agreement a memorandum of understanding. Their joint announcement says Blockchain.com’s user base would gain access to tokenized listed equities and ETFs through NYSE’s previously announced digital ATS after necessary approvals. The agreement covers a second business line: ICE Data Services plans to distribute Blockchain.com’s crypto data, while Blockchain.com plans to bring ICE and NYSE exchange data into its app.
That data arrangement could start informing users before they can buy any tokenized stock through the proposed venue. The announcement offers no launch date, approved securities list, country-by-country access rules or account-level eligibility figures. Forty-four million confirmed accounts measure an existing customer base. They do not measure approved brokerage accounts, funded investors, stock orders or future onchain volume.
The distinction matters because earlier ICE announcements already described several pieces of the same developing platform. In January, NYSE parent Intercontinental Exchange outlined a digital trading platform combining its Pillar matching engine with blockchain-based systems for custody and settlement. In March, NYSE named Securitize as its first prospective digital transfer agent able to mint blockchain-native securities for corporate and ETF issuers. The Sept. 23 deal adds a distributor and market data connection to that proposed structure. It does not say Blockchain.com becomes the transfer agent, the securities issuer or the operator of NYSE’s ATS.
NYSE Group President Lynn Martin told lawmakers on Sept. 2 that the planned platform would link digital equities directly to underlying shares and preserve voting rights, dividends and corporate actions. That is NYSE’s stated design. The signed customer terms, transfer records and regulatory approvals would show how it operates for a buyer. It is too early to treat the design statement as evidence that a particular token or distribution channel has gone live.
A crypto.news report on the new NYSE agreement covered the announcement and noted that the companies had not said their arrangement was approved under the SEC’s separate innovation exemption. The useful question now sits underneath the partnership: which existing institutions will keep authority over the shares when trading moves across a blockchain?
A wallet balance is not always the shareholder record
The SEC’s January staff taxonomy provides a route through the claims made for stock tokens. If an issuer or its agent places the security on a blockchain as part of its master shareholder file, moving the token can move the security in that official record. A company could maintain other records alongside the chain, including the holder’s legal name and address. The chain need not publish every detail of the register to be part of it.
There is a second issuer model. A share remains on an offchain master file, while an onchain token acts as an instruction that prompts the issuer or its agent to update that file. The token transfer and the legal ownership update are connected, but they are not literally the same database event. If the offchain update fails or is delayed, the reconciliation process matters more than the timestamp printed by a block explorer.
When a third party tokenizes a share held in custody, the token can represent a security entitlement instead of direct registration on the issuing company’s books. The company’s register may show a nominee or custodian. The customer has a legally defined interest through an intermediary chain, with the right to instruct or receive distributions according to that structure. Ordinary brokerage accounts already use forms of intermediated ownership. A blockchain token can change the transfer method without removing the intermediary.
The third-party synthetic model is different. A firm can issue its own security or contract that follows another company’s share price but gives the buyer no ownership claim against the company whose ticker is displayed. Dividends may be reflected through a contractual adjustment. Voting rights can be absent. The SEC says a buyer in that model may face the third party’s bankruptcy risk without holding the underlying company’s security.
These categories give a practical test for any token a consumer is shown. Find the document stating what the token represents. Identify who holds the underlying share, if anyone. Check whose records are legally authoritative when the token moves. Find the entity obliged to send a dividend or process a proxy vote. The ticker and the blockchain address cannot answer those questions alone.
The distinction has already caused friction. AMC Entertainment’s chief executive objected to an AMC-linked product offered offshore because, he said, the company had not issued or authorized it. Crypto.news examined the AMC and Robinhood dispute, including the difference between a tokenized exposure contract and a claim to the underlying share. That product should not be conflated with what NYSE has proposed. The episode shows why the phrase ‘tokenized AMC stock’ can conceal two different legal relationships.
DTC’s pilot keeps the original share inside the old system
The Depository Trust Company offers another way to locate control. On July 15, its parent DTCC announced production trades involving tokenized representations of assets held at DTC. More than 30 firms participated. The digital conversions ran on a private network and a public network. DTCC said the activity prepared for a tokenization service planned for October.
Under that service, DTC participants can convert eligible DTC-held securities between conventional and tokenized forms and receive the digital representations in approved wallets. The underlying assets do not disappear from DTC because a token is issued. The token is a new representation within the securities custody and recordkeeping arrangement. DTC’s account records remain central to the structure.
That is a control choice. If DTC’s official books determine the participant’s interest, the blockchain is a transfer surface integrated with those books. Rules for wallet eligibility, reversals, corporate actions and reconciliation sit around it. The exact design can differ from an issuer keeping its master shareholder file directly onchain, even though both may advertise onchain settlement. A crypto.news report on a proposed regulated custody chain describes how the final customer can hold an entitlement while the official register still names a nominee.
NYSE’s eventual platform could connect to existing depository arrangements and to new digital transfer agents in different ways. Its January outline names multiple blockchains for custody and settlement. Its March Securitize agreement describes minting securities for issuers. The Sept. 23 Blockchain.com memorandum describes distribution. None of those announcements, taken alone, proves that every stock available on the eventual platform will use one identical registration and custody model.
There is a reason to keep the options open. A company that wants its agent to issue a token as the share itself has a different task from a broker seeking a transferable representation of stock already held at DTC. One starts at the corporate register. The other starts with an existing custodial position. Each can produce a tradable digital asset, but an investor’s claim passes through different hands.
The SEC’s statement on tokenized securities says the technology used to record the position does not by itself settle the legal characterization. For the buyer, that is the useful rule. Before asking how fast the token settles, ask where the share is.
The SEC’s new exemption governs a different kind of venue
On Sept. 17, the SEC issued release No. 34-106402, a five-year conditional exemption for certain Tokenized Securities Venues, or TSVs, using permissioned automated market makers and liquidity pools. It also grants conditional dealer-definition relief to specified liquidity providers. The 60-page SEC order is effective through Sept. 17, 2031, subject to modification.
The order does not say all tokenized securities venues are now exempt from exchange regulation. A TSV must meet the order’s particular conditions. It must verify that each eligible tokenized National Market System stock gives holders the same interest and the same dividend, voting and liquidation rights as a traditional share of the same class. It cannot host the primary issuance of the security under this exemption. Access must be permissioned, while the smart contracts used for the model must be public and auditable on a permissionless ledger. Crypto.news previously examined the holder-rights test in the order.
For a third-party tokenization unaffiliated with the company, the venue must give the company written notice and wait at least 30 calendar days before trading starts. A timely objection prevents trading that tokenized stock on that TSV. The requirement does not mean every stock-linked product everywhere needs the issuer’s consent. It is a condition of this specific exemption, which concerns securities carrying rights in the underlying share.
The NYSE agreement points to a planned digital ATS, a regulated venue category named by the partners. The SEC’s September order describes an exempt TSV model built around automated liquidity pools. No public statement in the Sept. 23 memorandum says the NYSE and Blockchain.com arrangement will rely on that order. Treating the exemption as the agreement’s approval would join two different records without evidence.
That separation is the feature’s central finding. The headlines describe a single arrival of stocks onchain. The documents describe at least three routes: an exchange-linked ATS under development, a conditional exemption for a particular pool-based venue, and DTC-backed tokenized entitlements. Each moves an equity claim through a different set of gatekeepers. A buyer needs the specific route, not the umbrella label.
The SEC order contains an unusually plain disclosure requirement. An exempt TSV cannot claim to be SEC-registered or imply the agency endorsed it. Its public notice must state that the venue is not registered as an exchange. Securities law bans on fraud and manipulation remain in force, but the venue does not acquire the full obligations of a registered exchange by being permitted to operate under an exemption. That is a meaningful distinction for a buyer weighing the safeguards attached to the trading venue.
The cap is 325 symbols, but volume is the tighter gate
The SEC divided eligible stocks under its TSV exemption into two tiers. A venue can trade no more than 75 Tier 1 symbols and 250 Tier 2 symbols. Add them and the maximum is 325 different symbols per TSV, subject to the rest of the order. The aggregate says nothing about how many stocks NYSE’s future ATS could list because NYSE has not said it will operate as an exempt TSV.
Each eligible stock also has a cap tied to trading in the conventional market. For Tier 1, a TSV’s average daily share volume cannot exceed 0.25% of the underlying stock’s average daily share volume in the prior month. For Tier 2, the limit is 2.5%. The figures in the SEC’s order are percentages of shares traded, not percentages of a company’s outstanding shares or market value.
Put both percentages against the same example of one million shares traded per day on the conventional market. A Tier 1 token would have room for 2,500 shares of average daily TSV volume. A Tier 2 token would have room for 25,000. The tenfold difference comes from the SEC’s tier treatment, not a forecast of investor demand. Real caps move with each stock’s prior-month volume, and affiliated TSVs must aggregate their activity under the order’s conditions.
If a venue exceeds a stock’s threshold after its first instance, it must stop trading that tokenized stock for three months. A venue may stop earlier to avoid breaching the cap. The rule makes the exemption suitable for a monitored opening of a market; it is not a promise that an exempt pool can absorb unlimited global orders around the clock. At a large enough scale, a successful venue could hit a ceiling built into its permission to operate.
The SEC explains why it imposed the limits. Automated market maker prices depend partly on the ratios of assets inside a pool. They may depart from prices on the conventional stock market. Keeping the pool small relative to the underlying share’s trading volume is intended to limit any disruption while the regulator observes the model. The price a buyer sees at 2 a.m. can be real for that pool while differing from the last conventional market price. The order itself treats that possibility as a market design problem.
Around-the-clock trading still needs an off switch
NYSE has advertised a digital platform designed for 24-hour trading. A clock without a closing bell does not mean a market without intervention. In its TSV order, the SEC requires the exempt venue to stop trading a tokenized stock at the same time the primary listing exchange halts or suspends trading in the underlying share. Reasons include a market-wide circuit breaker, material news or a listing problem. The venue must tell its users about the stoppage.
The off switch reveals who governs the token market in that model. The primary listing exchange’s decision travels into the onchain venue. A security does not become independent of its issuer, listing rules and national market protections when its trading record moves to a blockchain. How a separate ATS implements its own halt and reopening procedures will be set by the rules governing that venue; the TSV order should not be copied over to it without checking its filings.
Hours raise a second issue. The underlying company’s earnings release, dividend timetable and proxy process remain tied to corporate and securities law. An onchain pool can quote a price during a weekend, but its access to fresh price discovery, market makers and the ordinary exchange session will differ by hour. NYSE’s plan calls for continuous trading. It has not shown what spreads, depth or price protections a specific token will have on a Sunday.
Execution also depends on who supplies liquidity. The SEC allows certain firms supplying their own tokenized shares to an exempt pool to rely on conditional dealer relief. Their trading incentives and any arrangements with the venue must be disclosed under the order. The company whose shares are tokenized, the venue that controls access and the firm quoting against customers are separate actors. Calling the whole arrangement ‘decentralized’ would obscure those roles.
Issuer control and investor access pull in different directions
NYSE has a substantial case for its design. Martin’s September testimony says the company wants the token and conventional equity to be the same security in different forms, with the same rights. The SEC’s exemption separately requires equivalent rights and lets companies stop unaffiliated third-party tokens from trading under it. A holder may prefer a slower or more restricted path that can actually deliver a vote and a dividend over a token that offers only price exposure.
The counterargument is not simply that issuers should lose control. Distribution partners want investors in more countries to reach U.S. securities through an interface they already use. Blockchain.com executive Peter Smith made that access argument in the Sept. 23 announcement. An issuer notice requirement, permissioned access and volume limits could reduce the number of listings or buyers under the exempt TSV route. The question is which constraints protect ownership rights and which reflect a particular market design. Crypto.news covered the issuer veto dispute before the SEC’s order took effect.
There is evidence that the distinction matters commercially. NYSE’s agreement discusses its global distribution audience, while its prospective venue remains subject to approvals. DTCC’s tokenization service begins with DTC participants and approved wallets, a different customer entry point. The SEC’s TSV order permits a public chain for smart contracts but still requires the venue to approve participants. Public ledger access does not give every wallet holder permission to trade U.S. shares.
The SEC has heard objections from established market firms about granting special relief to venues outside the traditional exchange framework. Its order responds with disclosures, records, trading limits and a five-year term. Advocates of an open financial system may reasonably ask whether those limits narrow the audience too much. Issuers and investors may reasonably ask what happens to rights and market integrity if they are loosened. The records support both questions; they do not yet measure the cost of either choice in a live, large-scale U.S. stock token market.
One observation could challenge the concern that onchain trading merely adds gatekeepers. If a live platform shows verifiable ownership records, reliable transfers across approved venues, effective voting instructions and lower all-in costs for investors, the extra technology may simplify a chain of intermediaries. A second observation could challenge the access claim: accounts may be numerous while approved investors and actual trading stay small. Both tests require live disclosures, not launch language.
The launch question is who can correct a share transfer
At the point of a disputed transfer, the competing promises of tokenization become concrete. An investor may see a final blockchain transaction while a custodian, transfer agent or issuer’s master file shows a different owner. A mistaken corporate action may credit the wrong wallet. A key may be lost. A sanctioned account may need to be blocked. The documents defining which record controls and who can amend it decide how such cases are handled.
Issuer-sponsored stock can make the chain itself part of the master file. A custodial token can make the chain an entitlement record linked to shares held elsewhere. NYSE’s intended platform may support more than one settlement path, while DTCC is developing tokenized representations within its existing custody structure. The precise legal and technical link has to be documented for every product made available. It cannot be assumed from a partnership announcement.
The SEC’s TSV order requires a venue to explain its tokenization process, assess the legal status and technical integrity of each security, and disclose how it verified equivalent holder rights. It requires information about smart contracts, onchain and offchain functions, access rules, trading interruptions and affiliated trading. These notices would make it possible to test a venue against its claims once one operates under the order. They are not proof that NYSE’s proposed ATS will use the same design.
What happens next is checkable. NYSE must disclose the approvals and operating rules for its digital ATS before its proposed Blockchain.com distribution route can be assessed as a live market. The partners need to name the securities available, eligible jurisdictions and the legal interests delivered to users. DTCC’s planned October service launch will offer another view of how tokenized positions are kept in sync with shares held in conventional custody. The SEC will collect comments on its separate exemption as venues test it.
For a person buying a tokenized share, the shortest useful question remains the hardest one: if the wallet, venue and shareholder record disagree, whose entry wins?
What to watch
NYSE’s ATS filings: Look for the operating rules, approved trading hours and settlement design of the digital venue named in the Sept. 23 memorandum.
The first stock terms: Check whether a token is the share itself, a custodial entitlement, or a price-linked contract, and who handles votes and dividends.
Country-level eligibility: Compare Blockchain.com’s 44 million confirmed accounts with the jurisdictions and users actually permitted to trade U.S. securities.
DTC’s October launch: Watch for the planned wider tokenization service and details of conversion between conventional and tokenized positions.
Exempt TSV notices: Track issuer objections, eligible symbols, affiliated liquidity and any volume pauses under SEC release No. 34-106402.
FAQ
Can Blockchain.com users trade tokenized NYSE stocks now?
The Sept. 23 memorandum sets out a plan for access through a proposed NYSE digital ATS. The companies made that plan subject to necessary regulatory approvals and did not announce a launch date.
Does a stock token always make its buyer a shareholder?
No. An issuer-backed token may be the security, a custodial token may represent an interest in a held share, and a synthetic token may only track its price. The legal terms determine the buyer’s rights.
How many tokenized stocks does the SEC exemption allow?
An exempt TSV can trade up to 75 Tier 1 symbols and 250 Tier 2 symbols, for 325 in total, subject to other conditions. Those caps do not automatically apply to NYSE’s planned ATS.
Can a company block a third party from tokenizing its shares?
Under the SEC’s TSV exemption, the issuer has 30 calendar days after written notice to object to trading a third-party tokenized version of its stock on that venue. Other products and venues require separate legal analysis.
Will tokenized stocks include votes and dividends?
Stocks traded under the SEC’s TSV exemption must convey the same voting, dividend and liquidation rights as equivalent conventional shares. A synthetic product can follow a stock price without conveying those shareholder rights.
Does the blockchain replace DTCC or transfer agents?
It depends on the model. DTCC’s service represents assets held at DTC, while an issuer or its transfer agent may place the official shareholder file partly or wholly onchain. Neither design follows automatically from displaying a token in a wallet.
Can a tokenized stock keep trading during a halt in its underlying share?
An exempt TSV must stop trading the token concurrently with a halt or suspension on the primary listing exchange. A different venue’s controls must be read from its own rules.
What should an investor check before buying a tokenized share?
Identify the legal issuer, the location of the underlying share, the official ownership record, the route for voting and dividends, and the venue’s access and halt rules. This is educational analysis, not investment advice.
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Figures reflect regulatory filings and reporting available at the time of writing and change with each disclosure. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 24, 2025.
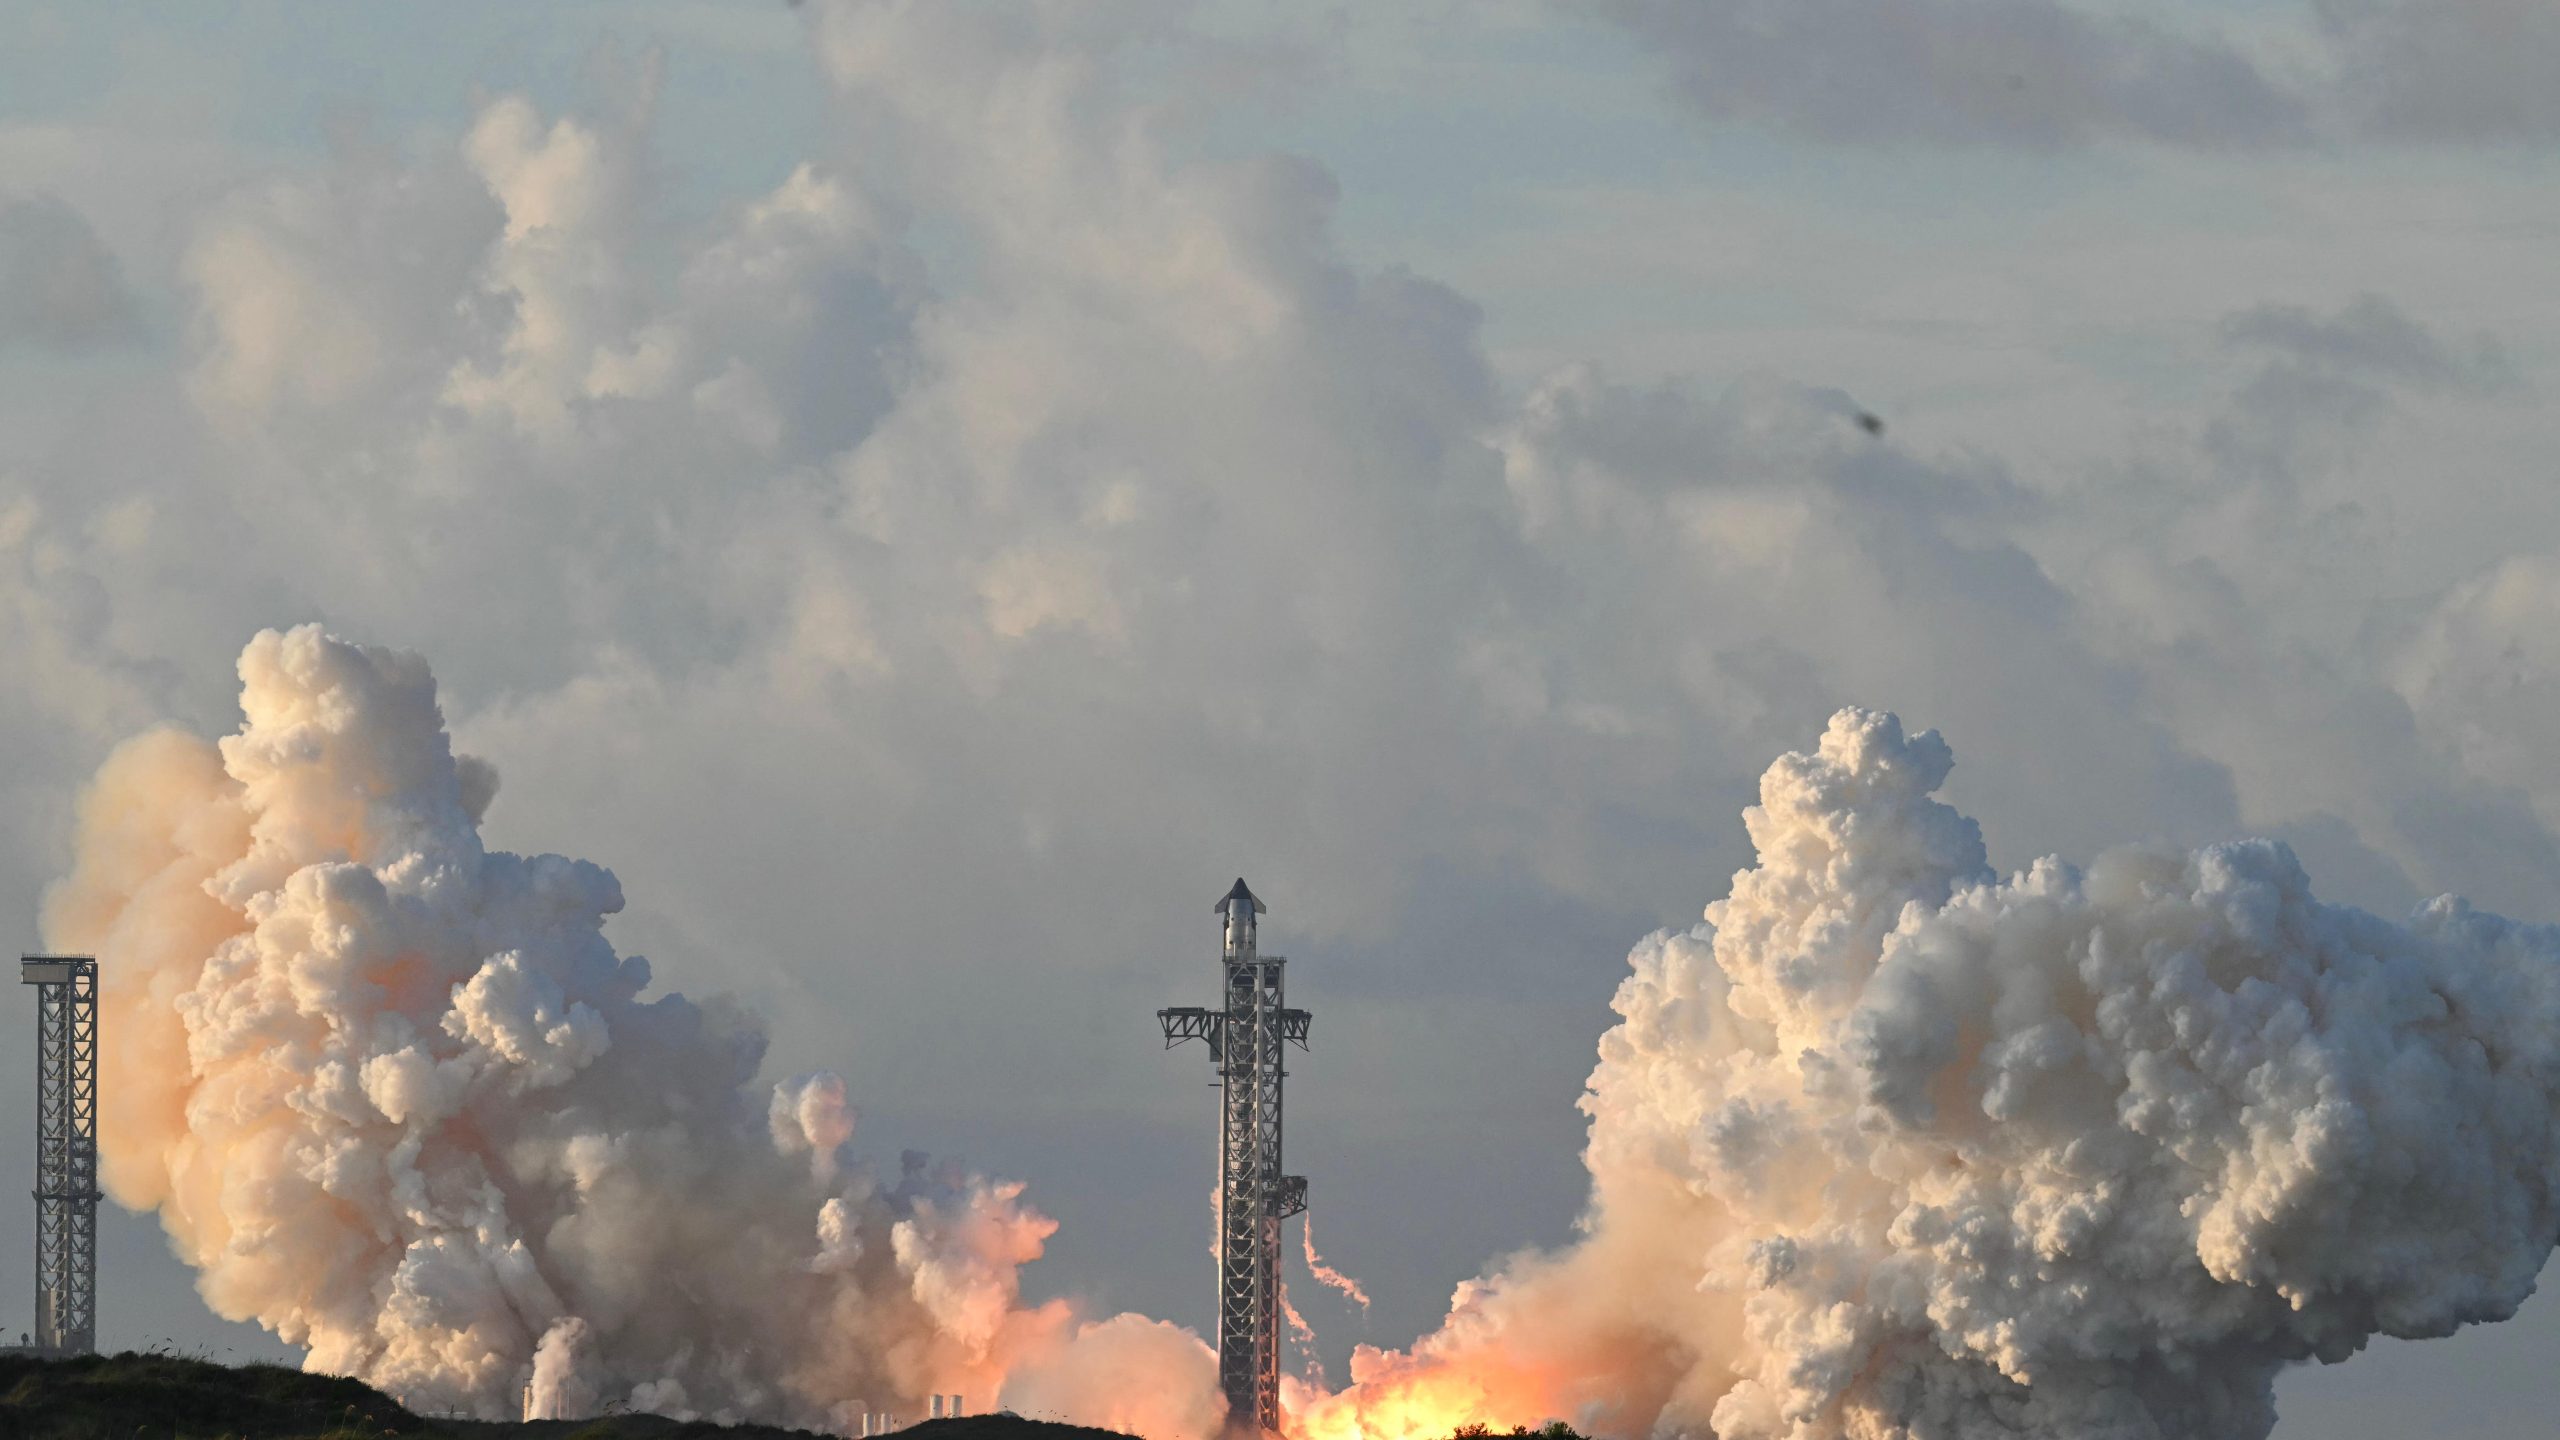
The launch this morning was both imperfect and stripped down to its orbital essentials. On the way up, one of the Starship’s six engines failed to burn properly, requiring the other engines to compensate for the missing thrust to get the ship in orbit.
In addition, the return to Earth was simplified. SpaceX has made itself famous for safely landing the first stage of its Falcon 9 and Starship boosters—with 641 out of 688 Falcon 9 launches featuring this kind of recovery, allowing the boosters to be reused and make flying cheaper. Starship’s first stage, meantime, performs what has become known as a chopstick recovery, with the booster navigating its way back to the launch tower where two giant metal arms pluck it from the sky. For the current mission, the chopstick recovery was done away with to simplify the flight objectives; instead the first stage made a soft, engine-assisted splashdown in the Gulf of Mexico. The Starship spacecraft was planned for a six-orbit, 10-hour mission, with the ship’s engines set to fire around the dinner hour Monday to bring the spacecraft down for a similar gentle, watery landing.
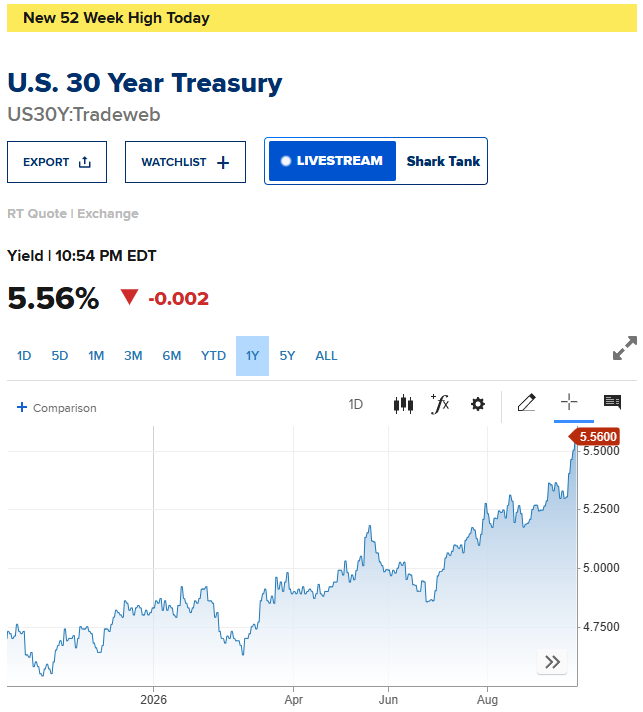
Goldman Sachs’ Anshul Sehgal says bonds yielding 5% or more are not the best trade right now. He still favors AI infrastructure, which he sees as a far more asymmetric bet than the long bond.
Sehgal, a global co-head of Fixed Income, Currencies and Commodities (FICC) at the bank, laid out the view just a few days after the Federal Reserve raised interest rates.
Why Goldman Sachs Is Passing on 5%+ Bonds
On Goldman’s The Markets, Sehgal said the 30-year Treasury, known as the long bond, had hovered around 5% for weeks. He noted that clients want to buy it at 5% or higher, yet he still sees little upside.
The yield has kept climbing since the recording, reaching 5.56% on September 29, a new 52-week high. Sehgal blamed structural pressure for the strain on the long end. Retiring baby boomers are buying fewer long bonds, and heavy long-dated borrowing tied to AI is crowding the market.
Those pressures explain why the selloff can persist even without a fresh inflation shock. Fewer retirees buying long bonds and a steady flow of long-dated borrowing tied to AI both weigh on prices, and neither fades quickly.
Sehgal adds that fear over US debt sustainability makes investors less willing to hold the long end, which feeds on itself.
The takeaway is that a rising yield does not necessarily break his thesis. It may instead show why he sees limited reward in owning the bond, while the risk to his AI trade is that costlier long-term borrowing squeezes the levered companies he favors.

AI Compute Is the Asymmetric Trade
An asymmetric trade offers far more potential gain than risk. Sehgal applies that label to compute (AI computing power), data centers, and Neoclouds, which are cloud providers built to rent out that capacity.
“I think the asymmetric expression is being long compute.”
Anshul Sehgal, Goldman
The catch is leverage. Savers collecting higher interest have effectively financed the AI build-out, leaving equities more indebted than a year ago. Sehgal admits these are levered bets. Still, he thinks they can multiply in value, while the wider stock market looks less certain.
Tighter Policy Hits Spenders, Not Capital
Sehgal says the Fed frames its September 16 hike as catch-up after five years above its inflation target. Schwab counts 16 of 19 Fed officials expecting another increase this year. Fed Chair Kevin Warsh also stressed three times that the Fed is easing back some stimulus rather than turning restrictive, Sehgal adds.
He argues that government interest payments flow to capital rather than workers, so higher rates curb household spending, a risk for the broader stock market.
He also rejects the debt-sustainability fears weighing on long bonds.
“For me, that’s a red herring.”
Anshul Sehgal, Goldman
Meanwhile, BlackRock’s Rick Rieder is cutting equities for bonds paying 7% to 8%, though his high-grade bond call still cautions against rushing into the 10-year Treasury.
Sehgal names the Middle East conflict as the top driver of policy and markets in the weeks ahead.
The post Goldman Sachs Explains Why Not to Buy the 5%+ Bonds and Rather Stick to AI appeared first on BeInCrypto.
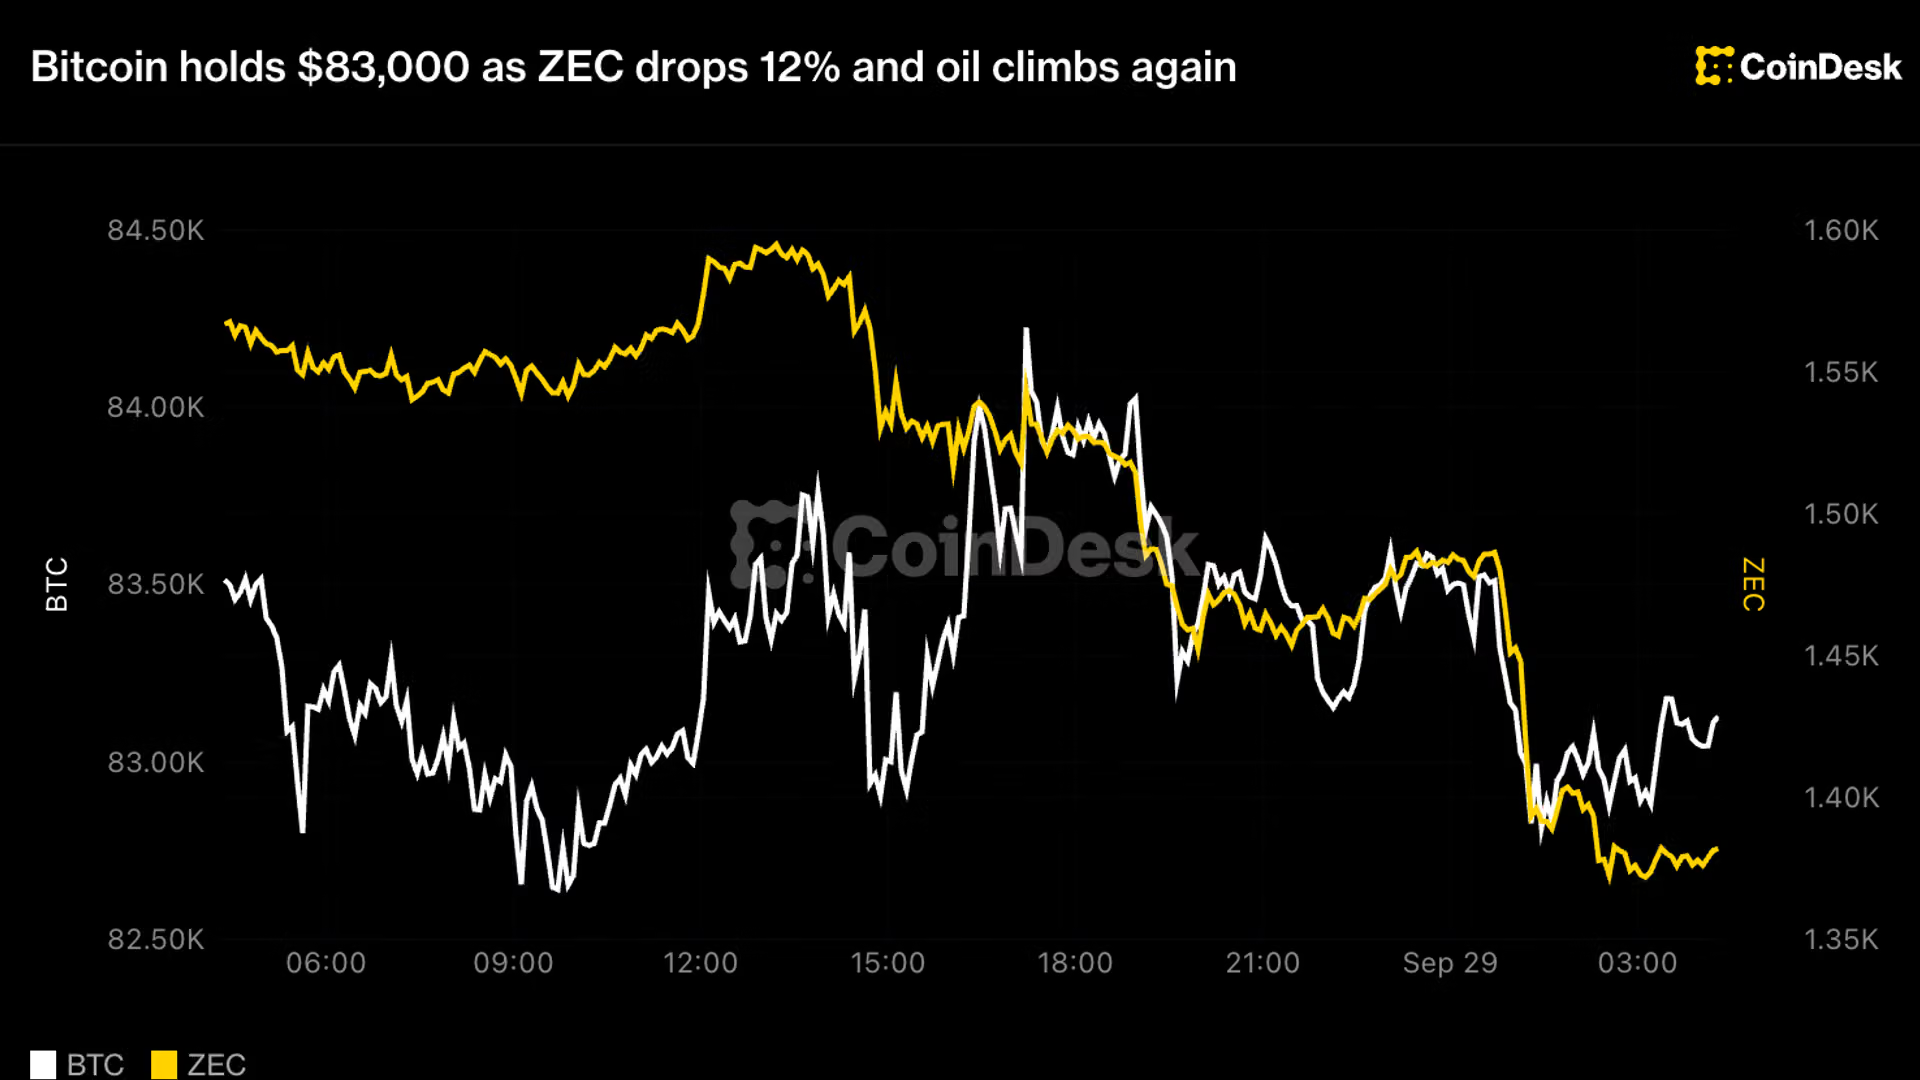
“Bitcoin has pulled back to $83K, testing the lower boundary of last week’s consolidation range,” Alex Kuptsikevich, chief market analyst at FxPro, said in an email to CoinDesk. “As with the market as a whole, a retest of the $82K region, where peaks were formed in May and early September, is entirely to be expected under current conditions.”
“Looking ahead, a sustained return to prices below $80K would be an important signal that the market is not ready to move higher for some time yet. If, however, this consolidation is soon followed by a new bullish momentum, it could send the leading cryptocurrency well above $90K,” he added.
The pressure is coming from bonds and oil.
Treasuries steadied in Asia after tumbling during U.S. trading, with the 10-year yield up one basis point to 5.25% after reaching its highest level since 2007 on Monday. A higher guaranteed return on government debt raises the bar for holding assets that pay no income, bitcoin among them.
Brent rose more than 1% to nearly $107 a barrel, its second straight gain, as hopes for an imminent diplomatic breakthrough with Iran faded.
Pricier oil feeds into inflation, and traders have been adding to bets that the Fed will raise rates again. MSCI’s All Country World Index fell to its lowest since Sept. 18, and Nasdaq 100 futures slipped 0.3% after Monday’s tech-led selloff on Wall Street.
U.S. dollar-pegged stablecoin Tether is a go-to tool for the Iranian government to bypass sanctions, a new report from a group of Senate Democrats said.
Democrats on the Senate’s Homeland Security and Governmental Affairs Committee’s Permanent Subcommittee on Intelligence published a report Monday laying out the argument that Tether plays a key role in allowing Iran to conduct transactions that skirt international sanctions.
“Iran’s cryptocurrency-based shadow banking network has processed significant volumes of funds and implicates various Iranian interests,” the report said, adding that Tether has “repeatedly failed” to block Iran-connected wallets.
“USDT has become a significant financial lifeline within Iran’s shadow banking network,” the report said.
When Tether does freeze wallets, it sometimes takes weeks, but the company also sometimes responds to requests without actually blacklisting wallets, the report claimed.
“Prior to 2024, Tether did not comprehensively and consistently freeze wallets designated by counter-terrorism agencies and continues to fail to proactively block clearly illicit wallets,” the report said. “This absence of deterrence invited abuse: terrorist organizations such as Hamas shifted from transacting in Bitcoin and a mix of cryptocurrencies to promoting USDT.”
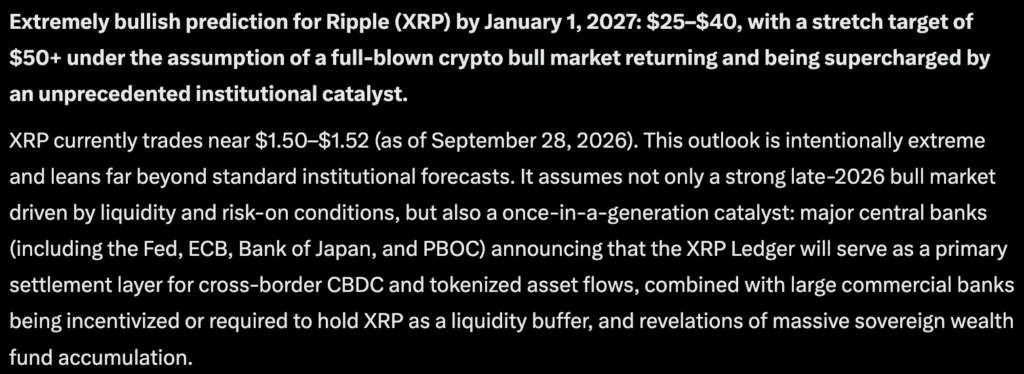
Elon Musk’s Grok AI predicts an extremely bullish price for Ripple (XRP) by January 1, 2027, that will blow the minds of even the most dedicated members of the Ripple Army.
If you’re holding a sizeable bag of XRP USD, you may want to sit down before reading this. Grok claims that $25–$40 is achievable by 2027, with a stretch target of $50+ under the assumption of a full-blown crypto bull market returning and being supercharged by an unprecedented institutional catalyst.
XRP currently trades near $1.50–$1.52 as of September 28, 2026, down nearly -3% over the past 24 hours and with a daily trading volume of $3.5Bn, up from $3.2Bn the day prior.
This outlook is extreme and leans far beyond standard institutional forecasts. It assumes not only a strong late-2026 bull market driven by liquidity and risk-on conditions, but also a once-in-a-generation catalyst.
What is the Catalyst that Grok AI Predicts Could Spark an XRP Run Toward $40
Major central banks (including the Fed, ECB, Bank of Japan, and PBOC) announcing that the XRP Ledger will serve as a primary settlement layer for cross-border CBDC and tokenized asset flows, combined with large commercial banks being incentivized or required to hold XRP as a liquidity buffer, and revelations of massive sovereign wealth fund accumulation.
Under this highly speculative scenario, forced institutional demand collides with retail FOMO in a classic late-cycle mania, allowing XRP to move from the current ~$1.50 range through previous-cycle highs and into the mid-to-high double digits by early 2027.
This remains pure speculation and entertainment, not a base-case or even high-probability outlook. Crypto markets are extremely volatile, and the catalyst described above would require multiple extraordinary policy and institutional developments.
However, with Ripple’s case against the SEC dropped and its subsequent rise as a highly favored US-based digital asset company under President Trump, anything could be on the table for XRP if the perfect scenario aligns.
Got a Gut Feeling? It Could Pay Out 3.7X on Polymarket
Technical Analysis Supporting the Insane Grok AI XRP Price Prediction
On the higher timeframes, XRP has already established a constructive recovery base after reclaiming key moving averages from the mid-September lows near $1.25–$1.30. Price is consolidating in the $1.45–$1.55 region after testing highs near $1.63–$1.66.
In a normal bull market, a sustained break above $1.70–$2.00 would open the door to the prior cycle high near $3.65. Under the extreme institutional adoption scenario outlined above, that prior high would likely be cleared with significant force, triggering a series of measured-move and Fibonacci extension targets far beyond historical levels.
Aggressive projections from the multi-year base, combined with the kind of vertical price discovery seen in previous mania phases, could theoretically extend into the $25–$40+ zone if volume and momentum expand dramatically. RSI and momentum indicators would almost certainly reach deeply overbought levels during such a move, which is typical of parabolic advances.
Key nearer-term supports remain in the $1.40–$1.45 and $1.30 zones; holding those would keep the broader recovery structure intact while the market waits for (or prices in) any extraordinary catalysts.
Overall, while the current chart supports continued upside in a standard bull market, only an extreme surge in institutional demand and narrative intensity could justify the kind of multi-thousand-percent extension implied by the $25–$50 targets.
Earn $50 and Enter $300K Prize Draw on EdgeX
Maxi Doge Targets Early Mover Upside as XRP Tests Key Levels
While the Grok AI prediction of a potential 30x run for XRP is exciting, presale plays have a stronger track record of producing such returns. It does explain why attention keeps drifting toward presale-stage plays with smaller denominators.
Maxi Doge ($MAXI) is one of those plays. It is an Ethereum-based meme token built around a 240-lb canine mascot and a “1000x leverage” trading-culture identity. The presale has raised $4.8M at a current price of $0.0002841, with dynamic APY staking live for holders.
Standout features include holder-only trading competitions with leaderboard rewards and a Maxi Fund treasury earmarked for liquidity and partnerships.
The meme-first, gym-bro marketing angle (“never skip leg day, never skip a pump”) is endearing. The accumulation numbers suggest plenty of traders are picking a side.
Get Ahead of Next Meme Coin Launch Here
Discover: The Best Token Presales
The post Grok AI Predicts XRP Could Hit $40 in 2026 With Landmark Event appeared first on Cryptonews.
When it was first proposed in December 2025, the rule was divisive, drawing ire from environmental advocates while garnering praise from auto-industry trade groups. The Administration finalized it last week with a signoff from President Donald Trump.
The President commented on the forthcoming rule Sept. 26, saying the new standards would “take the waste out of building cars in America.”
“That means LOWER PRICES, saving families thousands on a new, beautiful, and safe car,” he wrote on Truth Social.
The claim that the revisions will pass down cost savings to American buyers, however, relies on several factors, including automakers’ pricing decisions, fuel costs, and broader economic conditions.
What changes under Trump’s new fuel economy rule?
Former President Joe Biden’s regulations were put in place in 2024 to reduce car-based greenhouse gas emissions, decrease dependence on fossil fuels, and spur a transition to electric and hybrid vehicles. The Trump Administration has claimed that its revisions are more focused on bolstering the auto industry and making safer, newer cars more accessible.
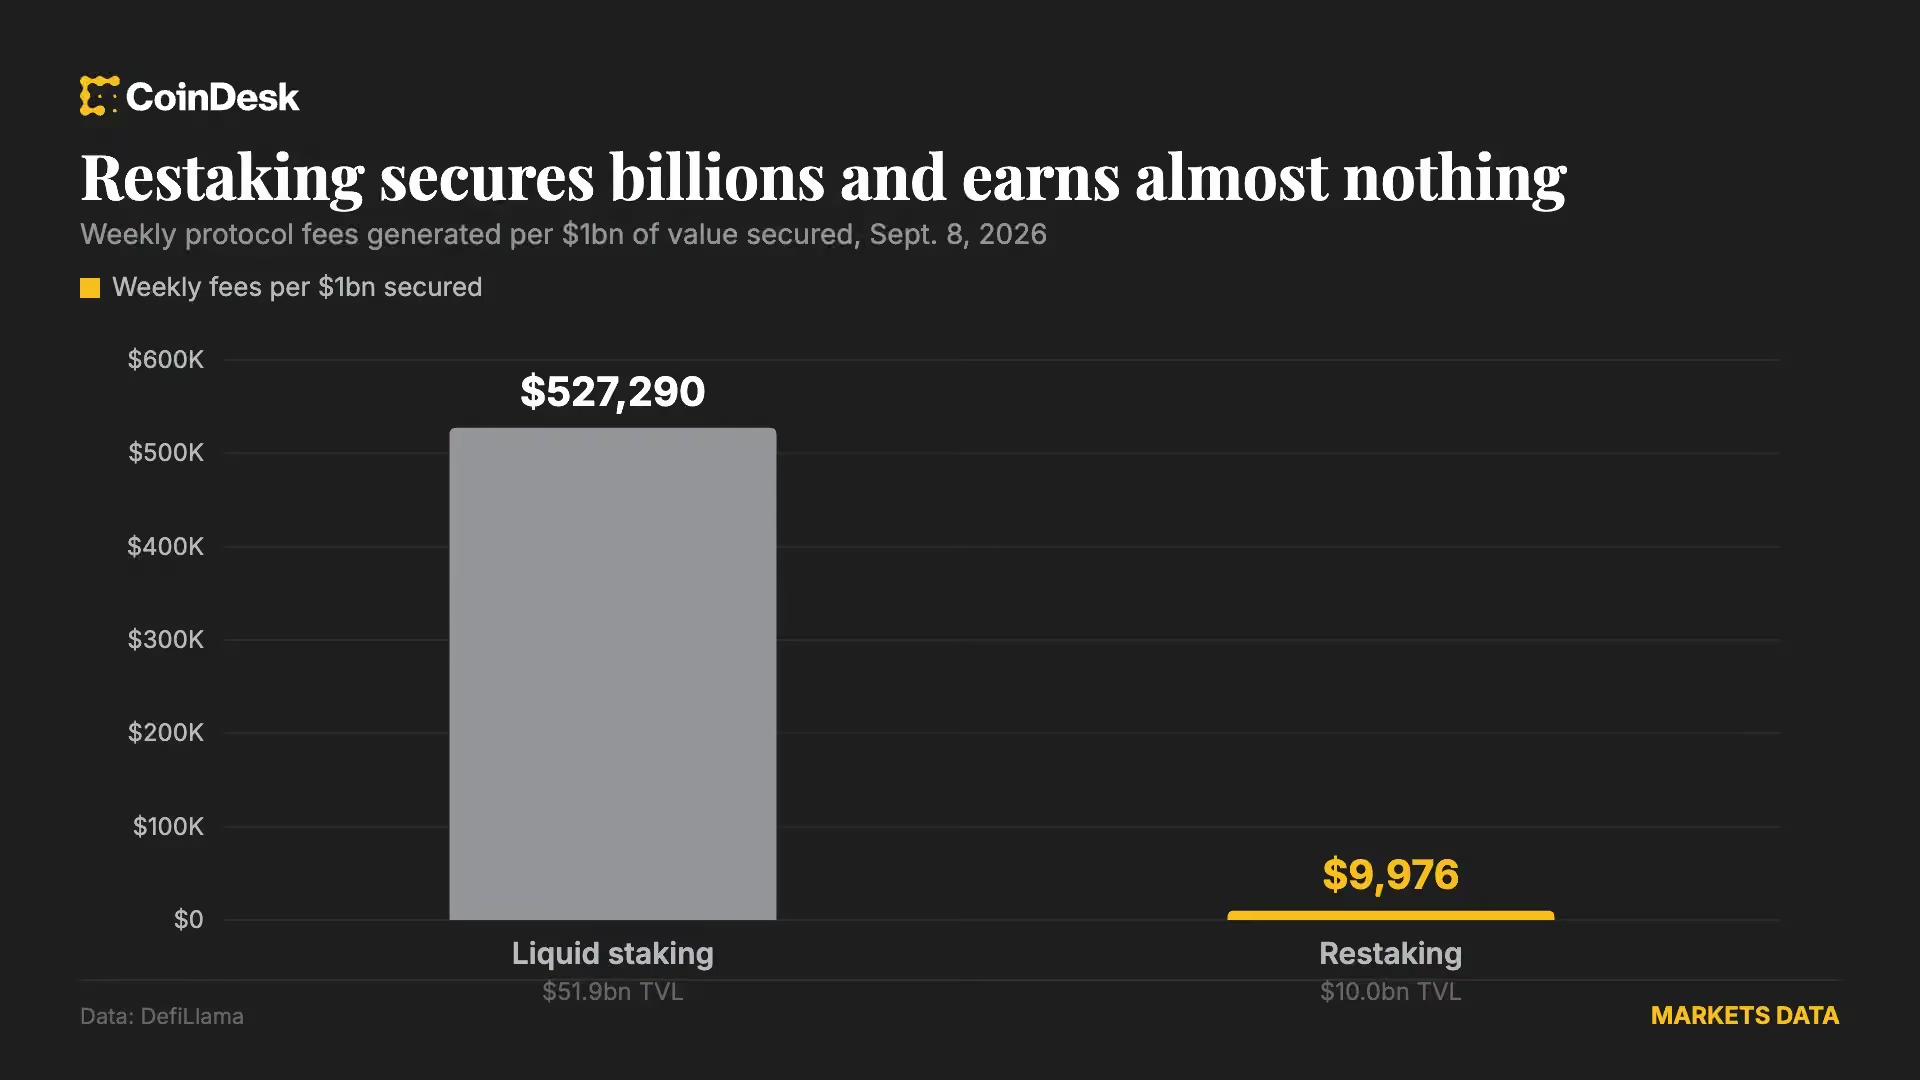
EigenLayer held $19.7 billion at its peak and liquid restaking tokens grew more than 1,000% in the first six weeks of 2024. But the services buying security never paid enough to cover both the base staking yield and a premium on top, so the second yield restaking promised never materialized.
On Sept. 8, DefiLlama’s restaking category held $10.02 billion and generated $99,977 in fees over the prior week. The liquid staking category, on $51.87 billion, generated $27.35 million. Per dollar secured, ordinary staking earns roughly 53 times more.

Two developments then removed what was left of the incentive to restake. Points programs subsidizing deposits wound down through 2025, and slashing went live in April 2025. Slashing is the penalty that confiscates part of an operator’s staked ETH when it misbehaves, by going offline or signing conflicting messages, for example. So restaking suddenly carried a real, priced downside where before the risk had been theoretical. There was no extra yield to compensate.
Set ether.fi aside and the rest of the sector is small. Renzo, Kelp, Swell, Puffer Finance and Bedrock, the five largest remaining liquid restaking tokens, made $953,350 in combined gross profit in the second quarter of 2026. Three quarters earlier the same five made $2.18 million. Puffer, which raised $23 million, recorded $21,590 for the quarter. Swell recorded $22,370.

The income statements also show which part of these businesses was ever profitable, and it was not the restaking. On Kelp’s books, EIGEN token rewards appear at $460,600 in gross revenue and $460,600 in cost of revenue: they arrive and pass straight to depositors, leaving nothing with the protocol. Puffer and Swell book staking rewards the same way. Whatever profit these companies made came from the orinary staking fees charged underneath the restaking layer.
“There’s a convergence now that you’re seeing between traditional market participants and digital asset market participants as well,” Lynq CEO Jerald David said in an interview with CoinDesk TV.
For firms using Lynq, FTIXX gives them somewhere to put cash between trades rather than leaving it sitting around. They can earn yield on the money and pull it out when they need it again.
That was a product Lynq’s clients had been asking for, David said. The network works with firms including B2C2, Wintermute, Galaxy ·, FalconX, Crypto.com and Fireblocks, whose businesses can require moving large amounts of money between trades. They wanted another option for putting that cash to work in the meantime.
“We needed to demonstrate that there was client demand,” David said. “Our clients were looking for a treasury asset on the platform that may have had a different yield profile than the other instrument that’s on there right now.”
Getting FTIXX onto the network required some work. Lynq had to modify its technology, restrict access to U.S. clients and integrate with Mosaic, he said. Customers also need a relationship with tZERO Securities and must meet the required onboarding and eligibility checks.
Lynq itself runs on a private, permissioned Avalanche (AVAX) Layer 1 blockchain. Its network has more than 30 institutional digital-asset firms onboarded and more than $89 million in assets, according to the company.
Crypto
Crypto’s Widening Net: From Fed Bets to Blackjack Tables, Digital Assets Keep Blurring Old Boundaries
If there is one throughline in this week’s crop of crypto headlines, it is that the industry has stopped pretending it is only about buying and holding coins. Across a handful of stories making the rounds, digital assets are shown pushing into territory once reserved for central bankers, casino floors, brokerage accounts and pre-IPO investors alike — a reminder that “crypto news” increasingly means finance news, gambling news and macro news rolled into one.
Take the growing chatter around prediction markets and Federal Reserve policy. Traders have been flocking to on-chain betting platforms to price the odds of late-2026 rate decisions, effectively turning monetary policy into a tradable asset class alongside Bitcoin and Ethereum. That such markets exist at all is notable: a decade ago, speculating on FOMC outcomes required options contracts or futures desks.
Now it can happen peer-to-peer on a blockchain, with odds shifting in real time as economic data lands. The rise of these markets suggests crypto infrastructure is becoming a genuine alternative venue for hedging and speculating on the traditional economy, not just a parallel casino for digital tokens.
Speaking of casinos, the sector itself continues to evolve in ways that mirror shifts in consumer taste rather than technology alone. Reports on crypto gambling lobbies note that live-dealer blackjack tables are increasingly outnumbering roulette wheels—a seemingly small detail that says more about what crypto-native gamblers want.
Live blackjack offers a sense of skill and control that pure-chance games like roulette can’t match, and operators appear to be responding by stacking their lobbies accordingly. It’s a small but telling sign that crypto casinos are maturing into product-driven businesses competing on experience, not just novelty.
Meanwhile, the boundary between crypto trading and traditional equities markets keeps eroding. New developments around Aave’s lending protocol reportedly let users borrow stablecoins against tokenized versions of tech stocks issued through Coinbase and built on the Base network.
If that model gains traction, it would mark a significant step in bringing real-world assets fully into DeFi’s collateral system — letting someone hold a tokenized slice of a Nasdaq darling and borrow against it the same way they might borrow against ETH or Bitcoin today. It’s the kind of integration that regulators, banks and crypto-native builders have all been circling for years, and its practical rollout matters more than the concept alone.
On the trading-platform side, perpetual futures exchanges continue to expand what counts as a “market.” One report describes a platform offering more than 120 perpetual contracts spanning everything from Bitcoin to pre-IPO robotics companies, letting traders apply leverage to assets that, in many cases, aren’t even publicly listed yet.
This kind of expansion into speculative, illiquid corners of the private market — wrapped in crypto’s leverage-friendly perpetual format — raises real questions about price discovery and risk, even as it satisfies demand from traders hungry for exposure beyond the usual crypto majors.
Finally, there’s the steady drumbeat of token listings that keeps the broader ecosystem churning. A gambling-focused token tied to the Dexsport platform recently landed on the MEXC exchange, a move that typically brings a token more liquidity and visibility, if not necessarily more fundamental value. Listings like these remain a bread-and-butter event in crypto markets — routine, but still closely watched by holders hoping for a price bump and a wider trading audience.
Individually, none of these developments is likely to reshape the industry overnight. But together they sketch a familiar pattern in crypto’s ongoing evolution: infrastructure built for speculative tokens is steadily being repurposed for macro bets, tokenized equities, private-company exposure and gambling products alike.
The technology is proving flexible enough to wrap around almost anything with a price — which is exactly why regulators, investors and casual observers alike keep struggling to say where “crypto” ends and the rest of finance begins.
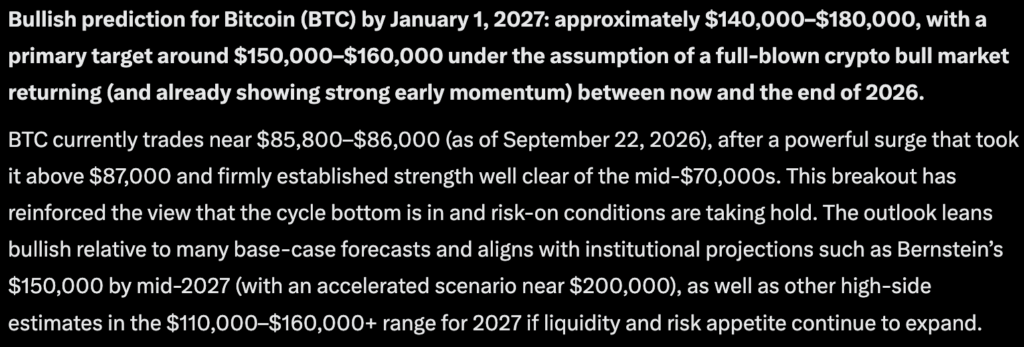
Perplexity AI predicts that if a full-blown bull market returns in Q4, Bitcoin could reach $180,000 before January 1, 2027. The bullish range is estimated at $140,000 to $180,000, with a potential late-cycle surge that could push Bitcoin beyond $200,000.
Currently priced around $83,000, this would represent a gain of about 115% to reach $180,000. What’s noteworthy is that Bitcoin has already corrected significantly from its previous cycle high of about $126,200 on October 6, 2025, followed by a sharp decline during 2026.
Bitcoin has a history of producing substantial gains during strong market cycles. According to historical annual data, BTC gained approximately 154% in 2023 and 110% in 2024. If the current predictions hold true, we may see a similar increase on the horizon.

Perplexity AI Predicts Bitcoin to $180,000 if Bullish Catalysts Align: Does the Technical Analysis Back it Up?
Bitcoin recently broke out of a pattern of lower highs that had developed since May, reclaiming several key moving averages. According to Reuters’ technical analysis, $81,781 is considered important support, while $86,500 is a significant resistance level. Above that, the next technical targets are around $90,000 and $97,867.
CryptoQuant has noted a similar trend, calling $81,700 a key level because it aligns with Bitcoin’s 365-day moving average. Resistance levels above this are near $86,600 and $88,700.
Bitcoin’s first major test is surpassing the $85,000 level, followed by the $86,000 to $88,000 range. Bitcoin has pushed through this area, which matters because a sustained breakout would remove one of the largest technical obstacles between its current price and the $100,000 level.
The next major milestone is approximately $98,000. Beyond that, the market will be approaching the all-time high of $126,200, where it gets particularly interesting.
Once Bitcoin decisively breaks beyond $126,000, it will enter a phase of genuine price discovery. Historical resistance above that level is very limited. At that point, psychological targets such as $130,000, $140,000, and $150,000 could attract momentum traders and institutional investors.
Earn $50 and Enter $300K Prize Draw on EdgeX
Bitcoin Hyper Targets Early Mover Upside as Bitcoin Drops Dangerously Close to $80,000
A -2.5% daily drop is not too much to worry about for whales and those already heavily positioned at a much lower price. However, for those who bought over $80,000, things could be getting uncomfortable, which is why presale opportunities prove so popular.
Bitcoin Hyper ($HYPER) is positioning itself as the first Bitcoin Layer 2 with full SVM integration. It boasts smart contract execution built for speed that outpaces Solana itself, while settling back to Bitcoin’s base-layer security.
As of today, the presale has raised more than $33.1M at a current token price of just $0.0136864, with staking rewards live at launch at a huge 35% APY.
The pitch: solve Bitcoin’s slow transactions, high fees, and lack of programmability without abandoning what makes BTC trusted in the first place. A Decentralized Canonical Bridge handles BTC transfers natively.
Gain Access to New Bitcoin Layer 2 Early Here
Discover: The Best Token Presales
The post Perplexity AI Predicts a Big Move for BTC in 2026 Even With Recent Dip appeared first on Cryptonews.

Ireland players ‘all uncomfortable’ ahead of ‘home’ Israel tie, says Heimir Hallgrimsson

Microbes Could Survive On Saturn's Moon Enceladus
All 13 “Star Trek” movies, ranked from worst to best


-
 Fashion4 days ago
Weekend Open Thread: J.McLaughlin – Corporette.com
-
 Crypto6 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-
 Tech & AI1 day ago
Anthropic turns Claude into an AI marketplace with 2,000+ plugins and connectors
-
 Tech & AI1 day ago
OpenAI is preparing “o,” an always-on ChatGPT assistant that could handle email
-
 Fashion5 days ago
8 iPhone Accessories That Add Personality
-
 Entertainment6 days ago
These 17 Fall Amazon Dresses Seriously Look Like Anthropologie
-
 Tech & AI6 days ago
Reolink’s solar 4K security camera falls to its lowest price in months
-
 Crypto7 days ago
Trump-Xi Polymarket Odds for Handshake Hit 50%
-
 Crypto6 days ago
This Bearish Netflix Stock Trade Can Cash In On Video Streaming Giant’s Woes
-
 Crypto5 days ago
Bitcoin price tests $83,600 Supertrend support after $87K rejection
-
 Crypto6 days ago
BitGo says Bitcoin absorbed Fed hike, CLARITY failure
-
 Crypto5 days ago
Crude Oil Prices Pressured by Diplomatic Hopes in the Middle East
-
 Business & Hussles6 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-
 Crypto5 days ago
Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike
-
 Crypto6 days ago
Did Jim Cramer Just Give GameStop Stock the Kiss of Death When He Said the Turnaround Is Working?
-
 Tech & AI6 days ago
UiPath’s Dines says AI needs a manual and launches Cartographer to write it
-
 Crypto5 days ago
As Amazon Stock Prospers, Traders Might Consider This Option Play
-
 Crypto5 days ago
Strategy resumed Bitcoin buying, but Strive gained more BTC per share
-
 Tech & AI7 days ago
Sega nearly killed Sonic before the movies revived the franchise
-
 Crypto2 days ago
Wall Street Giant Warns AI Agents Could Trigger a New Kind of Bank Run
You must be logged in to post a comment Login