Crypto
Raiffeisen’s crypto deal could reach 18 million customers. How many can actually trade?

Raiffeisen Bank International has built a group agreement with Bitpanda for its Central and Eastern European network. Its Austrian model is real. The 18 million customer figure measures the size of a possible rollout, not customers newly able to place a crypto order.
Summary
- Raiffeisen and Bitpanda announced a framework on September 23 for 11 Central and Eastern European banking markets.
- RBI reports 18.8 million group customers as of June 30, 2026; the release rounds its possible reach to 18 million.
- Five of RBI’s 11 regional banking markets are EU members, according to the bank’s network page.
- Austrian regional Raiffeisen banks offered Bitpanda access before the RBI agreement, including a Salzburg launch in August 2026.
- The Austrian app requires a separate Bitpanda registration and limits access to adult Austrian residents.
Raiffeisen Bank International announced a crypto deal for a network of around 18 million customers on September 23. The number is real as a measure of the bank group’s reach. It is not a count of people who gained crypto trading that day.
The bank’s release, published at 16:00 on September 23, calls its arrangement with Bitpanda Enterprise a group framework. Individual network banks will roll out services progressively to reflect local market needs. No list of launch dates or newly live subsidiaries appears in the announcement. The bank’s June 30 group snapshot counts 18.8 million customers, a more precise figure than the rounded 18 million in the headline.
That leaves a question the customer total cannot answer. How many of those people could open their banking app on September 24 and buy bitcoin through this new agreement? The published release provides no number. It does not identify a newly launched country service.
The deal covers a network, not 18 million accounts switched on
RBI says it has subsidiary banks in 11 Central and Eastern European markets. Bitpanda will supply infrastructure for those banks to offer digital assets. The operative words are will supply and can offer. Each bank’s customer rollout is a later decision, according to the announcement.
RBI’s international network directory identifies the markets as Albania, Bosnia and Herzegovina, Croatia, the Czech Republic, Hungary, Kosovo, Romania, Russia, Serbia, Slovakia and Ukraine. Five are EU members: Croatia, the Czech Republic, Hungary, Romania and Slovakia. The others are outside the EU. The distinction matters for licences and product availability. An authorization to provide a crypto service across EU member states is not an authorization for every jurisdiction in the banking network.
The release does not assign a go live date to any of the 11. Nor does a bank customer count show how many customers are adults, use a compatible app, pass a new crypto onboarding check, live in a jurisdiction where the product is offered, or choose to trade. Every one of those steps reduces the path from total customers to actual users. None can be quantified from the agreement alone.
A useful audit starts with the named market, then demands a local bank product page, a dated launch notice, terms identifying the provider and evidence that the customer can complete onboarding. A press release about a group agreement satisfies the first step only. It would be false precision to turn the 18 million ceiling into a live access estimate without the later steps.
A market-by-market status check produces a narrower finding than the headline. The network directory verifies the banks, while the partnership release verifies a shared plan. It does not connect any one of those banks to a live Bitpanda consumer product under the new agreement. These are distinct evidence states, not an assertion that a bank can never introduce one or that a local service has been ruled out.
RBI market
EU member
Status in September 23 Bitpanda release
Albania
No
No named local launch
Bosnia and Herzegovina
No
No named local launch
Croatia
Yes
No named local launch
Czech Republic
Yes
No named local launch
Hungary
Yes
No named local launch
Kosovo
No
No named local launch
Romania
Yes
No named local launch
Russia
No
No named local launch
Serbia
No
No named local launch
Slovakia
Yes
No named local launch
Ukraine
No
No named local launch
That table is deliberately about disclosure in the announcement. It does not certify the absence of any unrelated crypto product at each bank, and it does not show that Bitpanda lacks a local licence. Its point is auditable: the company placed 11 banking markets next to an 18 million customer number without publishing an 11 market activation list. A subsequent country notice could change a row immediately.
The arithmetic of reach is therefore bounded on one side but not measured on the other. The upper number is the rounded group customer figure. The lower bound of customers newly enabled by the September announcement cannot be determined from public information, because the company did not disclose first day activation. Reporting the lower bound as zero would be just as unjustified as reporting all 18 million as active. A framework can exist before a customer sees anything new in an app.
There is a less obvious classification issue. A customer can belong to a bank group without being a retail mobile app customer eligible to open an investment account. The published total combines the group’s customer relationships across its network; the release does not provide the subset with a compatible mobile product, nor does it split corporate customers from retail customers for this partnership. Those missing pieces prevent even a reliable potential-user estimate.
The Austrian model exists outside the new CEE count
Bitpanda and RBI point to a working precedent. Raiffeisen Landesbank Niederoesterreich-Wien began offering access to Bitpanda in its banking environment in 2024. Its current customer page describes a route through the Mein ELBA app, trading from EUR 1 and recurring plans from EUR 10. The app asks a bank account holder to register for a personal Bitpanda account.
A second Austrian regional institution, Raiffeisen Salzburg, said on September 21 that its Bitpanda access had been available since August 2026. It described more than 650 crypto coins and tokens reachable from Mein ELBA. The local release says the banking app provides the route to an external provider and that Bitpanda performs the trades.
These are live product examples, not proof that an RBI subsidiary in Croatia, Romania or another CEE market is live under the September 23 framework. The corporate distinction is easy to miss because both sides use the Raiffeisen name. RBI’s own ownership diagram shows regional Austrian Raiffeisen banks owning around 61.17% of RBI, while the 11 CEE banks are its regional subsidiaries. The Austrian partnerships demonstrate a model that might be copied. They cannot be counted as launches inside the new 11 market program.
The two agreements should not be silently added together to produce a bigger customer pool. Even the 18.8 million figure is a group customer total, not 18.8 million distinct prospective crypto accounts. No customer conversion rate is supplied. Crypto.news’ initial report on the RBI deal described the reach as potential, which is the right qualification for the announced arrangement.
The app hands the customer to Bitpanda
The Austrian bank’s own terms show what a customer gets. On the Niederoesterreich-Wien product FAQ, a customer needs both a Raiffeisen account and an active Mein ELBA app. They then register for Bitpanda. The bank requires customers to be at least 18, hold a valid photo ID and reside in Austria.
The contractual split is more important than the app’s appearance. The page says customers become Bitpanda customers through the app’s Bitpanda access. It says purchases and sales take place exclusively with Bitpanda and assets are held inside Bitpanda’s structure. The bank receives a fee from Bitpanda for its access services. Austria previously fined Bitpanda EUR 70,000 under MiCA, another reason to identify the regulated provider accurately rather than describing the banking app as the trading venue. It says it is not itself providing the crypto or securities service and is not liable for Bitpanda’s performance.
That is a distribution model. The bank supplies the familiar entrance and payment account; Bitpanda provides the specialist transaction and asset service. Raiffeisen Salzburg states an equivalent limit in plain terms: it offers access, while Bitpanda handles the trading. Its product disclosure identifies Bitpanda GmbH as the provider authorized by the Austrian Financial Market Authority under MiCA.
The economics run in both directions. A bank can add an investment function without building its own full trading infrastructure. Bitpanda can reach banking customers through a channel that already has their attention. Under the Austrian arrangement, the bank is compensated by Bitpanda. The parties have not disclosed the fee formula or said whether the new group arrangement uses identical commercial terms. A separate Bitpanda infrastructure agreement with IG Europe illustrates that distribution partnerships can differ in the type of partner and customer service offered. A statement about revenue for the CEE banks would therefore go further than the public record permits.
The phrase inside the banking environment can imply a seamless handoff, but even the mature Austrian offering requires a separate Bitpanda identity. Raiffeisen’s page directs the user to the app’s Discover section, then to an individual Bitpanda registration. A registered banking customer is not automatically an approved crypto customer. Bitpanda can apply its own onboarding criteria in addition to the bank’s age, identification and residency requirements.
That is not an incidental footnote. If the bank reaches millions of users but only a fraction of them complete crypto onboarding, the actual product population will be smaller than the bank’s customer base. The difference cannot be computed by treating installation of Mein ELBA as a proxy: having the app, finding the offer, applying, being accepted and placing a first order are separate events. The September release reports none of those figures for the new partnership.
The fee disclosure supplies another reason to keep roles straight. The Niederoesterreich-Wien page explicitly says Bitpanda pays Raiffeisen for access services. It does not publish the amount or say that the bank takes a percentage of each trade. Customers are told that trading fees will be displayed before they place an order. There may be a commercial benefit to the bank if customers adopt the product, but the terms alone do not let a reporter calculate that benefit. A projected revenue figure made by multiplying 18 million by a guessed trading fee would conflate account holders, traders, volumes and a confidential commercial arrangement.
For a customer, the legal boundary matters when something goes wrong. The Austrian FAQ says the bank does not take responsibility for Bitpanda’s service. That language is not a finding that a customer has no protection, and it cannot be copied into the terms of a not yet launched RBI subsidiary. It does show that bank branding and legal responsibility can sit in different places. A country launch should be read from its own contracts before a reporter tells customers whom to contact about execution or assets.
A bank app does not mean a bank holds the coins
The distinction affects what users can do after buying. The Austrian product page says transfers of assets from another crypto exchange into the app’s Bitpanda service are not possible. It advertises immediate movement of funds through the linked Raiffeisen account, but that does not imply an unrestricted crypto wallet integrated into the bank account. Trading fees appear before an order is confirmed.
The bank’s page places Bitpanda branded stock and commodity offerings next to crypto, then notes that those branded products are derivatives, not direct ownership of the shares or commodities. The point is not that every product has the same legal form. It is that the menu inside a bank app can contain several distinct agreements, issuers and risk exposures. The app’s single interface does not turn them into bank deposits.
This is the detail to seek when the first CEE subsidiary announces its own launch. Which legal entity contracts with the customer? Who has custody of the crypto asset? Does the app permit transfers to an outside wallet? How are trading fees shown? Will the customer have to open a separate Bitpanda account? The Austrian answer is documented. The CEE answer has not been announced market by market.
The existing arrangement gives a workable reporting test because an advertised service leaves traces: a product page, onboarding criteria, provider identity and terms. Counting those traces is more informative than counting a bank’s total customers. It can be repeated when each local RBI subsidiary makes an announcement.
A good rollout count needs a consistent definition. A bank announcing that its app has a Bitpanda tile is a narrower milestone than customers being able to complete an order. A registration path open to a small pilot group is narrower than availability to all eligible retail customers. A countrywide statement is narrower again than a reported active customer count. If RBI eventually reports a single group adoption figure, the methodology will matter: users who clicked through, accounts opened at Bitpanda and customers who actually purchased an asset are different populations.
The Austrian pages show why the last step is not assured by the first. A person can see Bitpanda inside Mein ELBA but be ineligible for the service because of residence or age, or decide against registering. A completed registration need not lead to a trade. A successful trade need not imply a customer moved assets outside Bitpanda. Each funnel stage has a different question attached. Bank announcements tend to state the broadest one because it makes the partnership legible. Financial reporting needs the narrowest verifiable one.
Two public figures illustrate the scale of the gap without estimating it. RBI’s 18.8 million describes existing group customers on June 30. Bitpanda’s reported 7.4 million users in 2025 describes the platform’s own base at a different date and under its own definition. Adding the two counts, or assuming their populations do not overlap, would be meaningless. Neither company has published the number of RBI customers with Bitpanda accounts through this new CEE agreement.
A disclosure by a subsidiary would supply the missing numerator. If a bank said 400,000 eligible customers could open the feature, that would show a live addressable group in that country, subject to its stated conditions. If it said 20,000 customers had registered with Bitpanda and 8,000 had traded, those would be adoption figures. Nothing in the September 23 release permits either number to be inferred. The absence is a reporting limit, not a reason to assume the commercial plan will fail.
Five EU markets do not make one regulatory market for the whole group
MiCA’s cross border service provision rule governs how an authorized provider expands to another EU member state after the required notification. RBI says just five of its 11 CEE subsidiary markets are in the EU. The remaining six include Albania, Bosnia and Herzegovina, Kosovo, Russia, Serbia and Ukraine. They do not become part of an EU crypto licence by virtue of their parent’s headquarters in Vienna.
That does not prove Bitpanda cannot serve customers in those countries. It means separate local analysis is required, and the September 23 release has not published a common licence covering all 11. A group technology agreement can be signed in one place while the consumer product requires authorization, banking integration and customer terms in another.
Russia makes a blanket statement about the network particularly hazardous. RBI’s network page lists its Russian subsidiary and says the bank is working on deconsolidation while reducing exposure. The September announcement does not say Russia will receive the Bitpanda product. It would be incorrect to call the full network an EU rollout, and equally incorrect to infer a Russian launch from the presence of Russia in the network directory.
The published 18.8 million is a consolidated bank customer measure. It is not split in the announcement into customers in jurisdictions eligible for this product and customers outside them. Dividing by 11 to estimate an average national opportunity, or multiplying by a guessed take up rate, would merely give an invented number a decimal point.
The split between EU and non-EU locations changes the practical rollout calendar. An EU authorization is a starting point for a notification process within EU member states. It does not itself determine whether a particular RBI bank has integrated an app, vetted the customer journey or decided to sell the same set of assets. In the non-EU markets, even the passporting starting point is missing. The companies would need to address the law and commercial arrangements that apply locally.
Russia illustrates why the list of subsidiary countries should not be casually translated into a deployment list. RBI says it is pursuing deconsolidation of its Russian bank. The partnership release makes no separate assertion about offering Bitpanda products there. The same care is needed in Ukraine, Kosovo and Albania: their inclusion in RBI’s network directory establishes ownership and distribution infrastructure, not local product approval. Neither a bank’s presence nor Bitpanda’s EU standing substitutes for a dated local offer.
The regulatory distinction also prevents a false comparison across Europe. The tally of banks on the MiCA register concerns EU authorized entities. It does not include a count of all RBI’s non-EU subsidiaries ready to distribute a crypto product. Listing an entity on a register and putting a functioning trading route in a retail banking app are separate operational milestones.
The strongest case for the deal is already visible in Austria
The partnership has more substance than a logo swap. The Austrian customer pages describe an app route, an onboarding process, minimum order size, recurring investment and trading terms. Salzburg says its offer has been live since August. A customer at a qualifying Austrian regional bank can encounter Bitpanda inside the banking app and fund trades from the associated account. Bitpanda has supplied working infrastructure, not just a plan.
There is a plausible business case for taking that setup into RBI’s regional network. Bank distribution gives Bitpanda a route to customers who might never open a stand alone exchange account. RBI can add a feature to its existing app ecosystem. Crypto.news reported that Bitpanda’s 2025 adjusted revenue reached EUR 371 million and its user count 7.4 million, providing context for the scale of the infrastructure provider. Neither figure measures revenue from this specific bank partnership.
The bank side has precedent as well. An analysis of the EU MiCA register found roughly 80 bank entities in its September 16 tally, up materially from late June. That is not evidence of 80 banks offering the same retail crypto experience, but it weakens the claim that a bank entering crypto must be an isolated experiment. RBI’s choice to negotiate a group framework follows a period of wider bank activity.
The case for the deal is therefore operational: the model already runs at specific Austrian regional banks, the partner has regulated infrastructure, and RBI has a large regional distribution network. What remains unproved is the conversion of that infrastructure into a service at named CEE subsidiaries, then into actual customers using it.
The next announcement will supply the first countable customer base
The September 23 release offers no start date, no list of customer eligible subsidiaries and no actual signups under the new agreement. It does not say whether all 11 banks will participate or specify what products each will offer. There is no published figure for live access through the CEE framework as of September 24.
A later launch in a named market will narrow the denominator. Even then, the bank’s total customers would measure theoretical eligibility, not the number who passed onboarding or bought an asset. The useful sequence is one bank, one local product, the stated eligibility rules, a verified live app route and, if disclosed, customers enrolled. Until that sequence exists, 18 million is an addressable network.
The Austrian terms offer a more concrete description of what the arrangement presently looks like: a bank customer registers with Bitpanda, trades with Bitpanda and holds assets in Bitpanda’s structure. The September 23 bank release says its CEE rollout will proceed progressively. Both statements can be checked against the first local launch.
What to watch
Named launch: A dated notice from one of RBI’s 11 CEE subsidiary banks, with an operational start date.
Eligibility: The local rules for residency, age, app access and Bitpanda onboarding.
Provider: The customer contract naming who executes trades and holds assets.
Product scope: Supported coins, deposits, withdrawals, outside wallet transfers and fees.
Usage: A disclosed number of onboarded customers or trades, clearly separate from the bank’s full customer base.
FAQ
Can all 18 million Raiffeisen customers trade crypto now?
The September 23 agreement does not say that. It describes a gradual rollout across a network of around 18 million customers and names no newly live CEE subsidiary.
Why does RBI elsewhere report 18.8 million customers?
The bank’s June 30 group snapshot uses the more precise 18.8 million figure. The partnership release rounds its potential regional reach to around 18 million. Neither is a count of active crypto accounts.
How many CEE subsidiaries have launched under the new deal?
The September 23 announcement gives no count or dated list of new launches. It describes a group framework and a progressive rollout. A public launch notice from each subsidiary would make the number verifiable.
Does Raiffeisen already offer Bitpanda in Austria?
Yes. Raiffeisen Landesbank Niederoesterreich-Wien offers access through Mein ELBA, and Raiffeisen Salzburg said its own access began in August 2026. These are Austrian regional bank examples, separate from the announced CEE subsidiary rollout.
Who holds the crypto in the Austrian app arrangement?
The Niederoesterreich-Wien product page says the customer contracts with Bitpanda and that trades and holdings sit in Bitpanda’s structure. The bank provides access and receives a fee from Bitpanda for that service.
Does MiCA allow the product in all 11 countries?
No single EU authorization covers all 11 CEE subsidiary markets. RBI says five are EU members. Services in the other six require their own local assessment.
Can Austrian app customers move crypto in from another exchange?
The Niederoesterreich-Wien FAQ says transfers from another crypto exchange into its Bitpanda app service are not possible. Future CEE terms have not been disclosed.
What would prove the 18 million figure has become actual reach?
Dated launches, local customer eligibility rules and reported active accounts would show it bank by bank. The current release supplies a possible network size, not a live user figure. This is educational analysis, not investment advice.
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Figures reflect regulatory filings and reporting available at the time of writing and change with each disclosure. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 24, 2026.
Goldman Sachs’ Anshul Sehgal says bonds yielding 5% or more are not the best trade right now. He still favors AI infrastructure, which he sees as a far more asymmetric bet than the long bond.
Sehgal, a global co-head of Fixed Income, Currencies and Commodities (FICC) at the bank, laid out the view just a few days after the Federal Reserve raised interest rates.
Why Goldman Sachs Is Passing on 5%+ Bonds
On Goldman’s The Markets, Sehgal said the 30-year Treasury, known as the long bond, had hovered around 5% for weeks. He noted that clients want to buy it at 5% or higher, yet he still sees little upside.
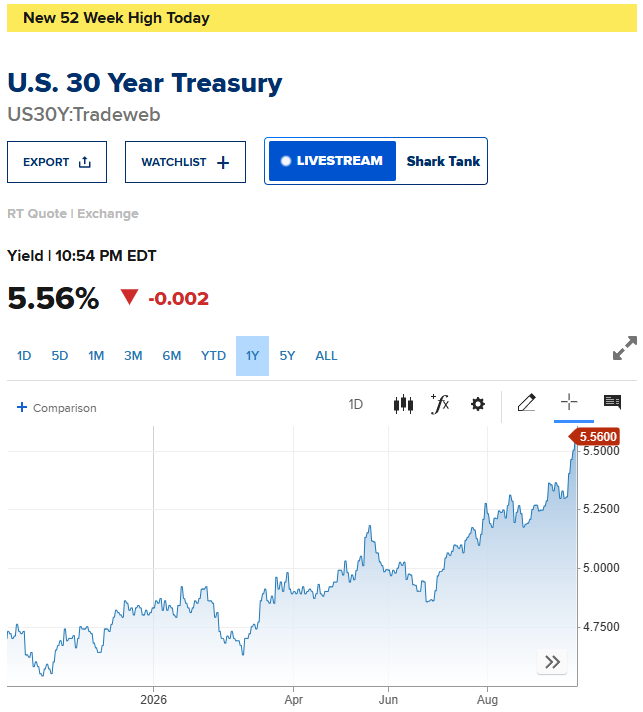
The yield has kept climbing since the recording, reaching 5.56% on September 29, a new 52-week high. Sehgal blamed structural pressure for the strain on the long end. Retiring baby boomers are buying fewer long bonds, and heavy long-dated borrowing tied to AI is crowding the market.
Those pressures explain why the selloff can persist even without a fresh inflation shock. Fewer retirees buying long bonds and a steady flow of long-dated borrowing tied to AI both weigh on prices, and neither fades quickly.
Sehgal adds that fear over US debt sustainability makes investors less willing to hold the long end, which feeds on itself.
The takeaway is that a rising yield does not necessarily break his thesis. It may instead show why he sees limited reward in owning the bond, while the risk to his AI trade is that costlier long-term borrowing squeezes the levered companies he favors.

AI Compute Is the Asymmetric Trade
An asymmetric trade offers far more potential gain than risk. Sehgal applies that label to compute (AI computing power), data centers, and Neoclouds, which are cloud providers built to rent out that capacity.
“I think the asymmetric expression is being long compute.”
Anshul Sehgal, Goldman
The catch is leverage. Savers collecting higher interest have effectively financed the AI build-out, leaving equities more indebted than a year ago. Sehgal admits these are levered bets. Still, he thinks they can multiply in value, while the wider stock market looks less certain.
Tighter Policy Hits Spenders, Not Capital
Sehgal says the Fed frames its September 16 hike as catch-up after five years above its inflation target. Schwab counts 16 of 19 Fed officials expecting another increase this year. Fed Chair Kevin Warsh also stressed three times that the Fed is easing back some stimulus rather than turning restrictive, Sehgal adds.
He argues that government interest payments flow to capital rather than workers, so higher rates curb household spending, a risk for the broader stock market.
He also rejects the debt-sustainability fears weighing on long bonds.
“For me, that’s a red herring.”
Anshul Sehgal, Goldman
Meanwhile, BlackRock’s Rick Rieder is cutting equities for bonds paying 7% to 8%, though his high-grade bond call still cautions against rushing into the 10-year Treasury.
Sehgal names the Middle East conflict as the top driver of policy and markets in the weeks ahead.
The post Goldman Sachs Explains Why Not to Buy the 5%+ Bonds and Rather Stick to AI appeared first on BeInCrypto.
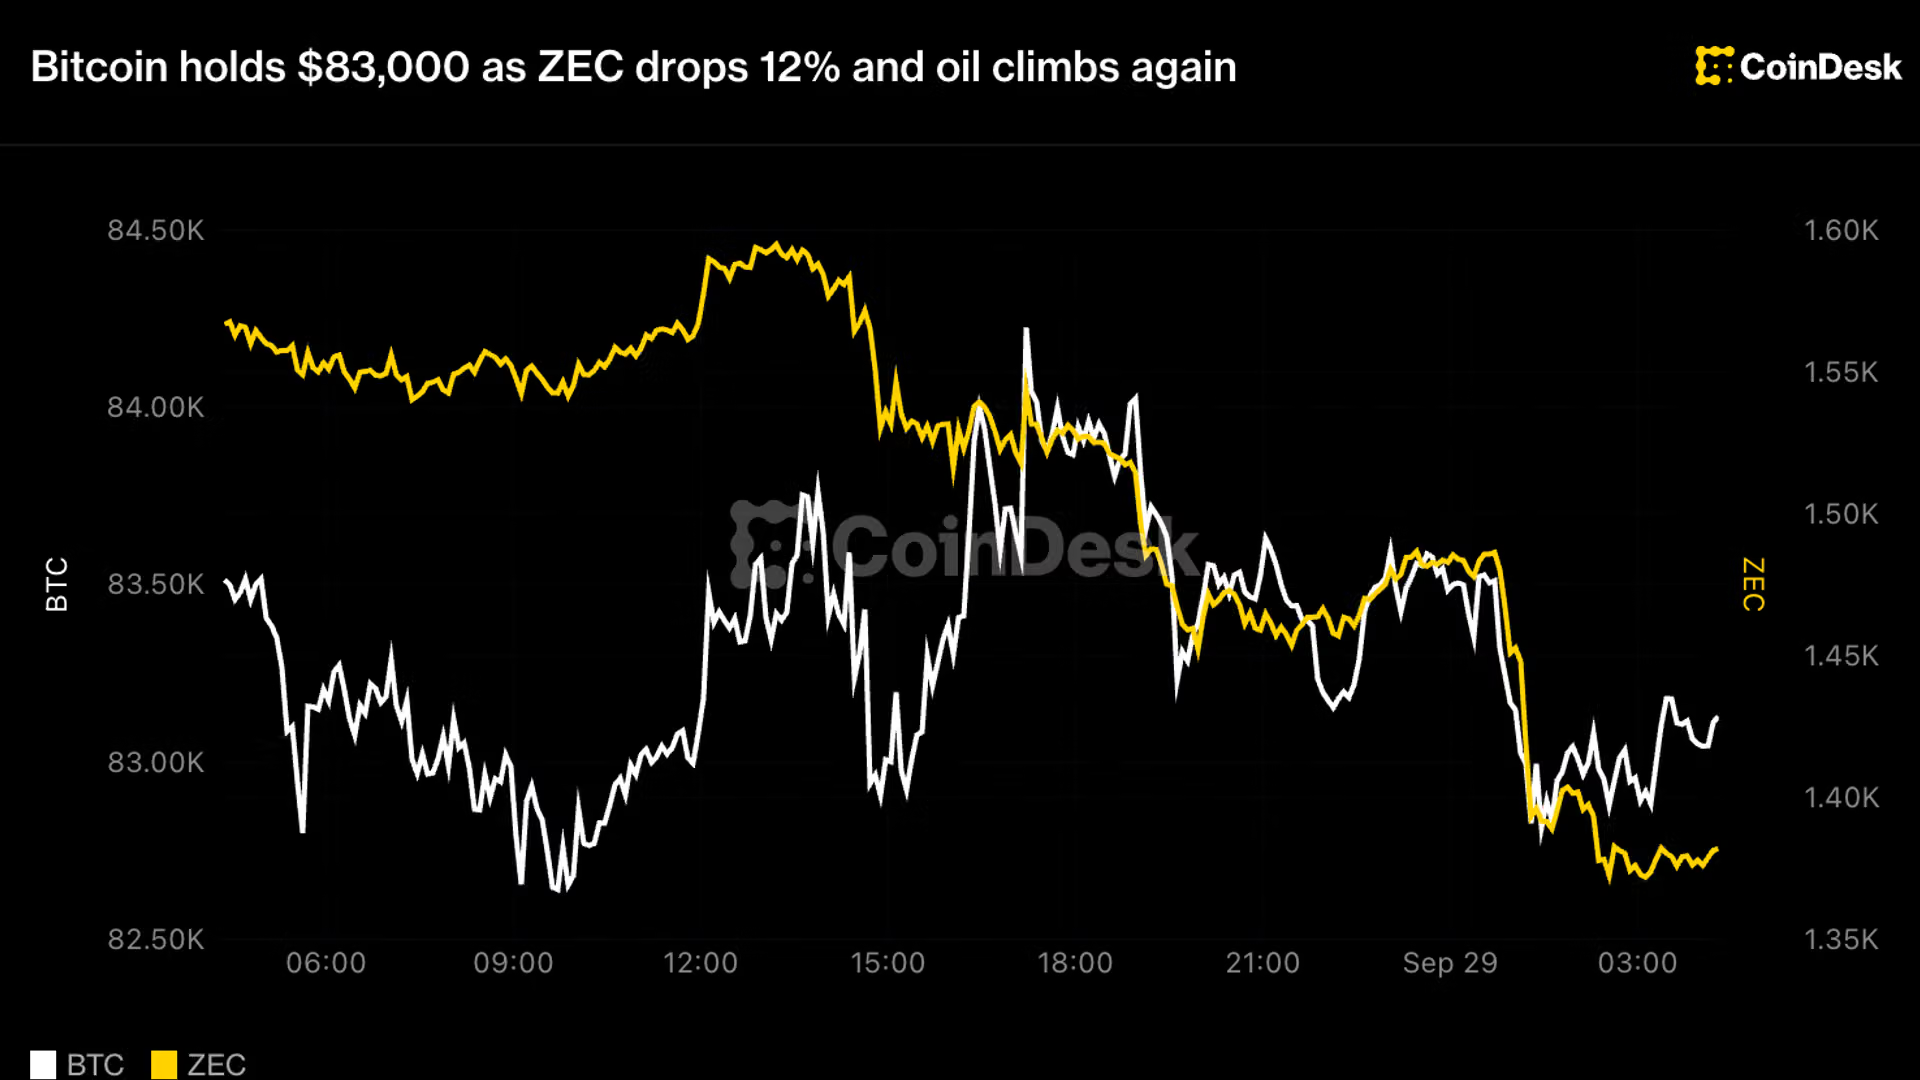
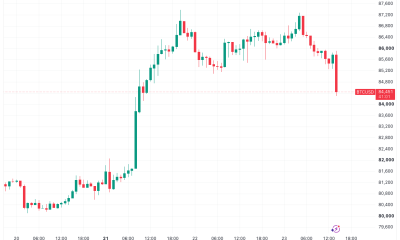
“Bitcoin has pulled back to $83K, testing the lower boundary of last week’s consolidation range,” Alex Kuptsikevich, chief market analyst at FxPro, said in an email to CoinDesk. “As with the market as a whole, a retest of the $82K region, where peaks were formed in May and early September, is entirely to be expected under current conditions.”
“Looking ahead, a sustained return to prices below $80K would be an important signal that the market is not ready to move higher for some time yet. If, however, this consolidation is soon followed by a new bullish momentum, it could send the leading cryptocurrency well above $90K,” he added.
The pressure is coming from bonds and oil.
Treasuries steadied in Asia after tumbling during U.S. trading, with the 10-year yield up one basis point to 5.25% after reaching its highest level since 2007 on Monday. A higher guaranteed return on government debt raises the bar for holding assets that pay no income, bitcoin among them.
Brent rose more than 1% to nearly $107 a barrel, its second straight gain, as hopes for an imminent diplomatic breakthrough with Iran faded.
Pricier oil feeds into inflation, and traders have been adding to bets that the Fed will raise rates again. MSCI’s All Country World Index fell to its lowest since Sept. 18, and Nasdaq 100 futures slipped 0.3% after Monday’s tech-led selloff on Wall Street.
U.S. dollar-pegged stablecoin Tether is a go-to tool for the Iranian government to bypass sanctions, a new report from a group of Senate Democrats said.
Democrats on the Senate’s Homeland Security and Governmental Affairs Committee’s Permanent Subcommittee on Intelligence published a report Monday laying out the argument that Tether plays a key role in allowing Iran to conduct transactions that skirt international sanctions.
“Iran’s cryptocurrency-based shadow banking network has processed significant volumes of funds and implicates various Iranian interests,” the report said, adding that Tether has “repeatedly failed” to block Iran-connected wallets.
“USDT has become a significant financial lifeline within Iran’s shadow banking network,” the report said.
When Tether does freeze wallets, it sometimes takes weeks, but the company also sometimes responds to requests without actually blacklisting wallets, the report claimed.
“Prior to 2024, Tether did not comprehensively and consistently freeze wallets designated by counter-terrorism agencies and continues to fail to proactively block clearly illicit wallets,” the report said. “This absence of deterrence invited abuse: terrorist organizations such as Hamas shifted from transacting in Bitcoin and a mix of cryptocurrencies to promoting USDT.”
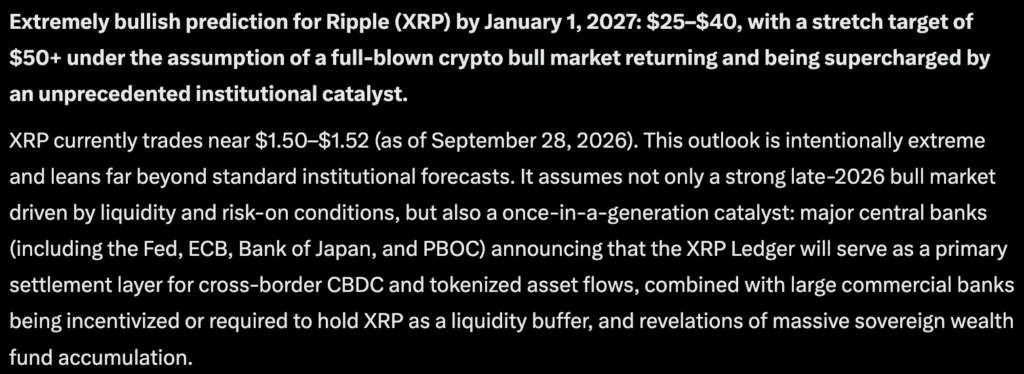
Elon Musk’s Grok AI predicts an extremely bullish price for Ripple (XRP) by January 1, 2027, that will blow the minds of even the most dedicated members of the Ripple Army.
If you’re holding a sizeable bag of XRP USD, you may want to sit down before reading this. Grok claims that $25–$40 is achievable by 2027, with a stretch target of $50+ under the assumption of a full-blown crypto bull market returning and being supercharged by an unprecedented institutional catalyst.
XRP currently trades near $1.50–$1.52 as of September 28, 2026, down nearly -3% over the past 24 hours and with a daily trading volume of $3.5Bn, up from $3.2Bn the day prior.
This outlook is extreme and leans far beyond standard institutional forecasts. It assumes not only a strong late-2026 bull market driven by liquidity and risk-on conditions, but also a once-in-a-generation catalyst.
What is the Catalyst that Grok AI Predicts Could Spark an XRP Run Toward $40
Major central banks (including the Fed, ECB, Bank of Japan, and PBOC) announcing that the XRP Ledger will serve as a primary settlement layer for cross-border CBDC and tokenized asset flows, combined with large commercial banks being incentivized or required to hold XRP as a liquidity buffer, and revelations of massive sovereign wealth fund accumulation.
Under this highly speculative scenario, forced institutional demand collides with retail FOMO in a classic late-cycle mania, allowing XRP to move from the current ~$1.50 range through previous-cycle highs and into the mid-to-high double digits by early 2027.
This remains pure speculation and entertainment, not a base-case or even high-probability outlook. Crypto markets are extremely volatile, and the catalyst described above would require multiple extraordinary policy and institutional developments.
However, with Ripple’s case against the SEC dropped and its subsequent rise as a highly favored US-based digital asset company under President Trump, anything could be on the table for XRP if the perfect scenario aligns.
Got a Gut Feeling? It Could Pay Out 3.7X on Polymarket
Technical Analysis Supporting the Insane Grok AI XRP Price Prediction
On the higher timeframes, XRP has already established a constructive recovery base after reclaiming key moving averages from the mid-September lows near $1.25–$1.30. Price is consolidating in the $1.45–$1.55 region after testing highs near $1.63–$1.66.
In a normal bull market, a sustained break above $1.70–$2.00 would open the door to the prior cycle high near $3.65. Under the extreme institutional adoption scenario outlined above, that prior high would likely be cleared with significant force, triggering a series of measured-move and Fibonacci extension targets far beyond historical levels.
Aggressive projections from the multi-year base, combined with the kind of vertical price discovery seen in previous mania phases, could theoretically extend into the $25–$40+ zone if volume and momentum expand dramatically. RSI and momentum indicators would almost certainly reach deeply overbought levels during such a move, which is typical of parabolic advances.
Key nearer-term supports remain in the $1.40–$1.45 and $1.30 zones; holding those would keep the broader recovery structure intact while the market waits for (or prices in) any extraordinary catalysts.
Overall, while the current chart supports continued upside in a standard bull market, only an extreme surge in institutional demand and narrative intensity could justify the kind of multi-thousand-percent extension implied by the $25–$50 targets.
Earn $50 and Enter $300K Prize Draw on EdgeX
Maxi Doge Targets Early Mover Upside as XRP Tests Key Levels
While the Grok AI prediction of a potential 30x run for XRP is exciting, presale plays have a stronger track record of producing such returns. It does explain why attention keeps drifting toward presale-stage plays with smaller denominators.
Maxi Doge ($MAXI) is one of those plays. It is an Ethereum-based meme token built around a 240-lb canine mascot and a “1000x leverage” trading-culture identity. The presale has raised $4.8M at a current price of $0.0002841, with dynamic APY staking live for holders.
Standout features include holder-only trading competitions with leaderboard rewards and a Maxi Fund treasury earmarked for liquidity and partnerships.
The meme-first, gym-bro marketing angle (“never skip leg day, never skip a pump”) is endearing. The accumulation numbers suggest plenty of traders are picking a side.
Get Ahead of Next Meme Coin Launch Here
Discover: The Best Token Presales
The post Grok AI Predicts XRP Could Hit $40 in 2026 With Landmark Event appeared first on Cryptonews.
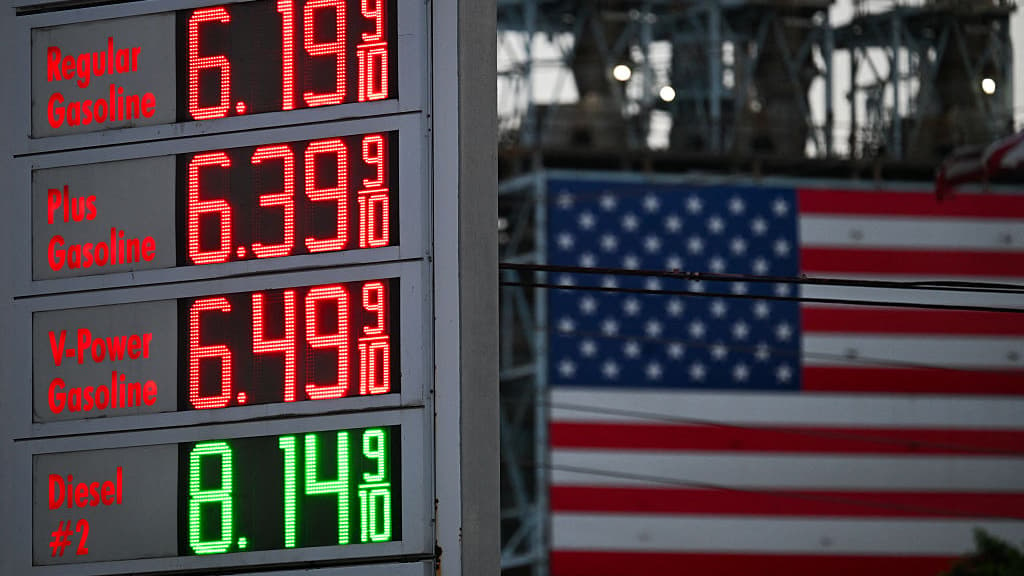
When it was first proposed in December 2025, the rule was divisive, drawing ire from environmental advocates while garnering praise from auto-industry trade groups. The Administration finalized it last week with a signoff from President Donald Trump.
The President commented on the forthcoming rule Sept. 26, saying the new standards would “take the waste out of building cars in America.”
“That means LOWER PRICES, saving families thousands on a new, beautiful, and safe car,” he wrote on Truth Social.
The claim that the revisions will pass down cost savings to American buyers, however, relies on several factors, including automakers’ pricing decisions, fuel costs, and broader economic conditions.
What changes under Trump’s new fuel economy rule?
Former President Joe Biden’s regulations were put in place in 2024 to reduce car-based greenhouse gas emissions, decrease dependence on fossil fuels, and spur a transition to electric and hybrid vehicles. The Trump Administration has claimed that its revisions are more focused on bolstering the auto industry and making safer, newer cars more accessible.
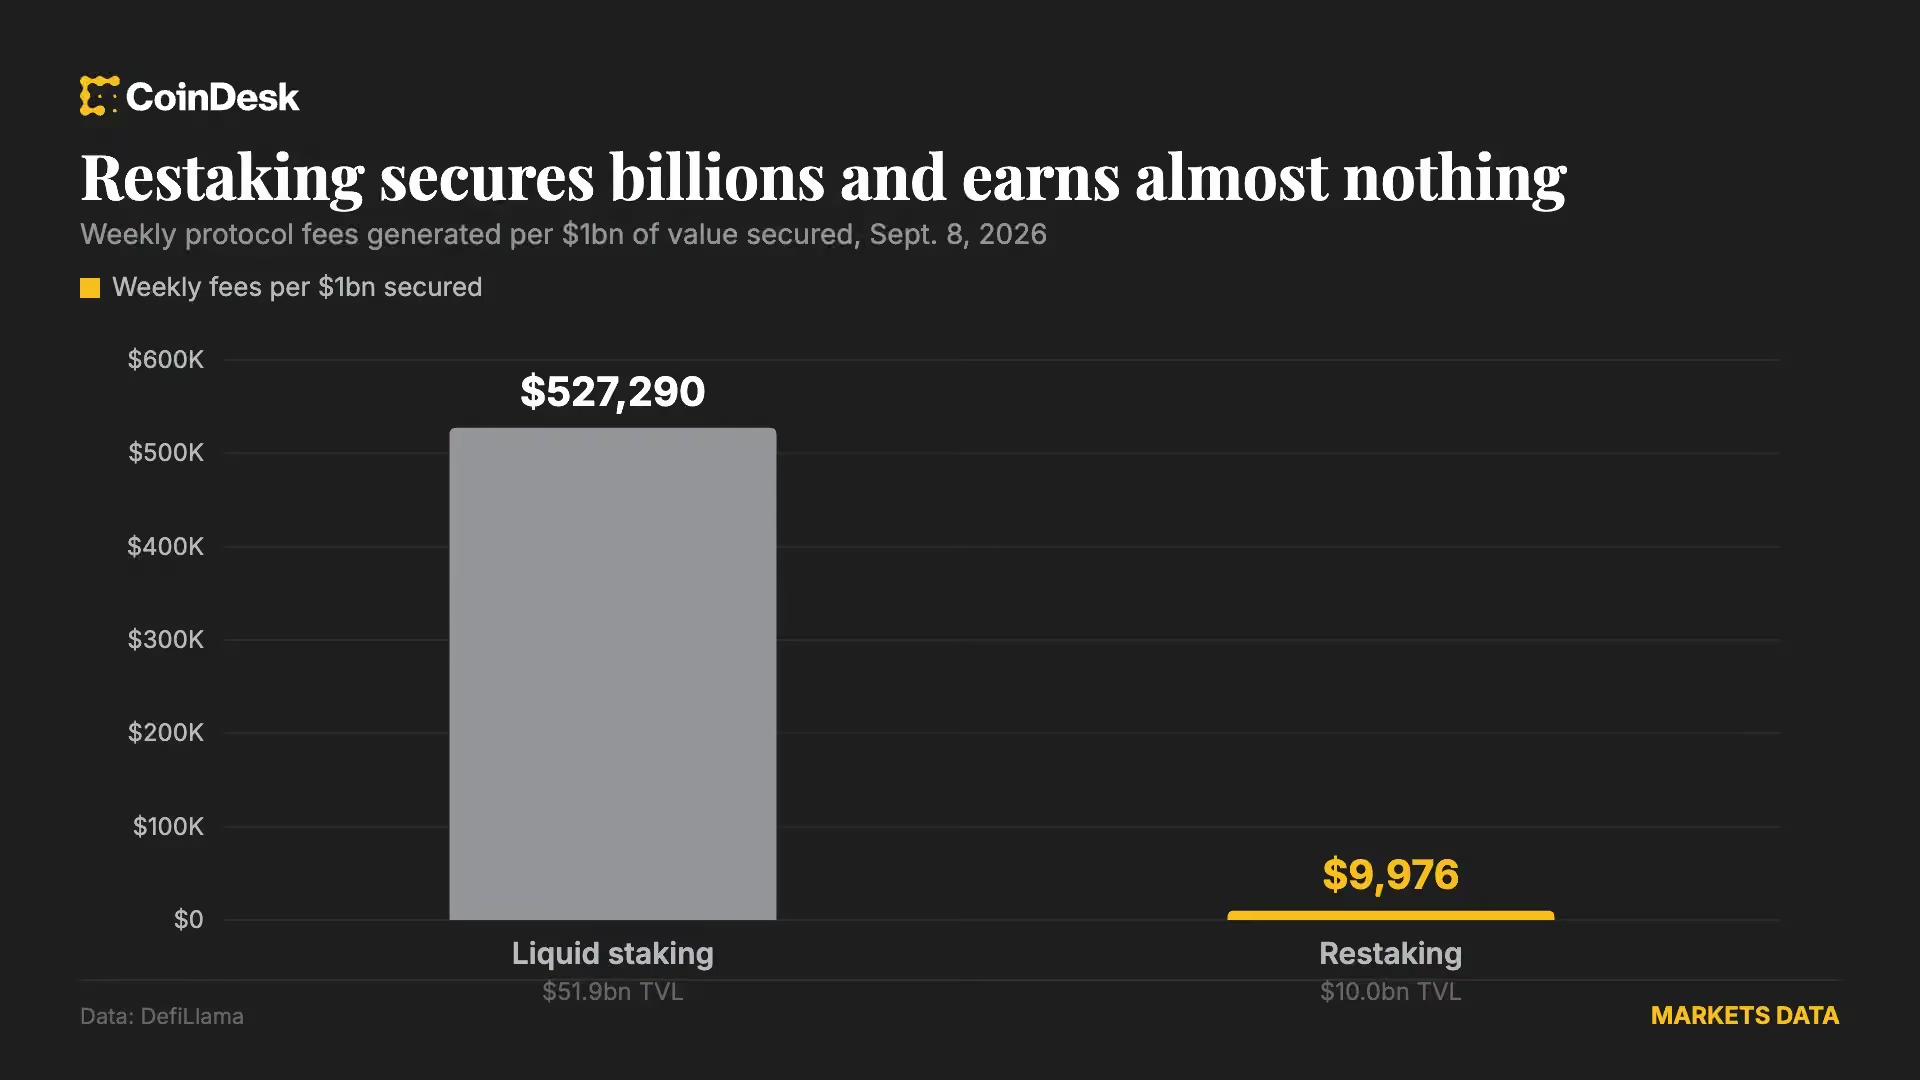
EigenLayer held $19.7 billion at its peak and liquid restaking tokens grew more than 1,000% in the first six weeks of 2024. But the services buying security never paid enough to cover both the base staking yield and a premium on top, so the second yield restaking promised never materialized.
On Sept. 8, DefiLlama’s restaking category held $10.02 billion and generated $99,977 in fees over the prior week. The liquid staking category, on $51.87 billion, generated $27.35 million. Per dollar secured, ordinary staking earns roughly 53 times more.

Two developments then removed what was left of the incentive to restake. Points programs subsidizing deposits wound down through 2025, and slashing went live in April 2025. Slashing is the penalty that confiscates part of an operator’s staked ETH when it misbehaves, by going offline or signing conflicting messages, for example. So restaking suddenly carried a real, priced downside where before the risk had been theoretical. There was no extra yield to compensate.
Set ether.fi aside and the rest of the sector is small. Renzo, Kelp, Swell, Puffer Finance and Bedrock, the five largest remaining liquid restaking tokens, made $953,350 in combined gross profit in the second quarter of 2026. Three quarters earlier the same five made $2.18 million. Puffer, which raised $23 million, recorded $21,590 for the quarter. Swell recorded $22,370.

The income statements also show which part of these businesses was ever profitable, and it was not the restaking. On Kelp’s books, EIGEN token rewards appear at $460,600 in gross revenue and $460,600 in cost of revenue: they arrive and pass straight to depositors, leaving nothing with the protocol. Puffer and Swell book staking rewards the same way. Whatever profit these companies made came from the orinary staking fees charged underneath the restaking layer.
“There’s a convergence now that you’re seeing between traditional market participants and digital asset market participants as well,” Lynq CEO Jerald David said in an interview with CoinDesk TV.
For firms using Lynq, FTIXX gives them somewhere to put cash between trades rather than leaving it sitting around. They can earn yield on the money and pull it out when they need it again.
That was a product Lynq’s clients had been asking for, David said. The network works with firms including B2C2, Wintermute, Galaxy ·, FalconX, Crypto.com and Fireblocks, whose businesses can require moving large amounts of money between trades. They wanted another option for putting that cash to work in the meantime.
“We needed to demonstrate that there was client demand,” David said. “Our clients were looking for a treasury asset on the platform that may have had a different yield profile than the other instrument that’s on there right now.”
Getting FTIXX onto the network required some work. Lynq had to modify its technology, restrict access to U.S. clients and integrate with Mosaic, he said. Customers also need a relationship with tZERO Securities and must meet the required onboarding and eligibility checks.
Lynq itself runs on a private, permissioned Avalanche (AVAX) Layer 1 blockchain. Its network has more than 30 institutional digital-asset firms onboarded and more than $89 million in assets, according to the company.
Crypto
Crypto’s Widening Net: From Fed Bets to Blackjack Tables, Digital Assets Keep Blurring Old Boundaries
If there is one throughline in this week’s crop of crypto headlines, it is that the industry has stopped pretending it is only about buying and holding coins. Across a handful of stories making the rounds, digital assets are shown pushing into territory once reserved for central bankers, casino floors, brokerage accounts and pre-IPO investors alike — a reminder that “crypto news” increasingly means finance news, gambling news and macro news rolled into one.
Take the growing chatter around prediction markets and Federal Reserve policy. Traders have been flocking to on-chain betting platforms to price the odds of late-2026 rate decisions, effectively turning monetary policy into a tradable asset class alongside Bitcoin and Ethereum. That such markets exist at all is notable: a decade ago, speculating on FOMC outcomes required options contracts or futures desks.
Now it can happen peer-to-peer on a blockchain, with odds shifting in real time as economic data lands. The rise of these markets suggests crypto infrastructure is becoming a genuine alternative venue for hedging and speculating on the traditional economy, not just a parallel casino for digital tokens.
Speaking of casinos, the sector itself continues to evolve in ways that mirror shifts in consumer taste rather than technology alone. Reports on crypto gambling lobbies note that live-dealer blackjack tables are increasingly outnumbering roulette wheels—a seemingly small detail that says more about what crypto-native gamblers want.
Live blackjack offers a sense of skill and control that pure-chance games like roulette can’t match, and operators appear to be responding by stacking their lobbies accordingly. It’s a small but telling sign that crypto casinos are maturing into product-driven businesses competing on experience, not just novelty.
Meanwhile, the boundary between crypto trading and traditional equities markets keeps eroding. New developments around Aave’s lending protocol reportedly let users borrow stablecoins against tokenized versions of tech stocks issued through Coinbase and built on the Base network.
If that model gains traction, it would mark a significant step in bringing real-world assets fully into DeFi’s collateral system — letting someone hold a tokenized slice of a Nasdaq darling and borrow against it the same way they might borrow against ETH or Bitcoin today. It’s the kind of integration that regulators, banks and crypto-native builders have all been circling for years, and its practical rollout matters more than the concept alone.
On the trading-platform side, perpetual futures exchanges continue to expand what counts as a “market.” One report describes a platform offering more than 120 perpetual contracts spanning everything from Bitcoin to pre-IPO robotics companies, letting traders apply leverage to assets that, in many cases, aren’t even publicly listed yet.
This kind of expansion into speculative, illiquid corners of the private market — wrapped in crypto’s leverage-friendly perpetual format — raises real questions about price discovery and risk, even as it satisfies demand from traders hungry for exposure beyond the usual crypto majors.
Finally, there’s the steady drumbeat of token listings that keeps the broader ecosystem churning. A gambling-focused token tied to the Dexsport platform recently landed on the MEXC exchange, a move that typically brings a token more liquidity and visibility, if not necessarily more fundamental value. Listings like these remain a bread-and-butter event in crypto markets — routine, but still closely watched by holders hoping for a price bump and a wider trading audience.
Individually, none of these developments is likely to reshape the industry overnight. But together they sketch a familiar pattern in crypto’s ongoing evolution: infrastructure built for speculative tokens is steadily being repurposed for macro bets, tokenized equities, private-company exposure and gambling products alike.
The technology is proving flexible enough to wrap around almost anything with a price — which is exactly why regulators, investors and casual observers alike keep struggling to say where “crypto” ends and the rest of finance begins.
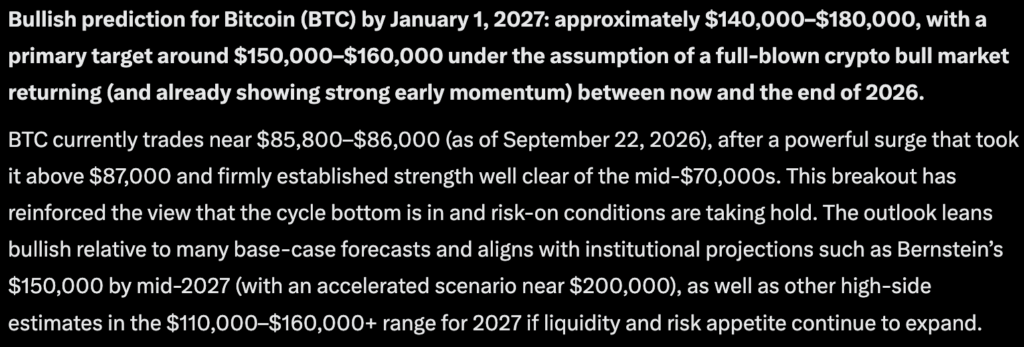
Perplexity AI predicts that if a full-blown bull market returns in Q4, Bitcoin could reach $180,000 before January 1, 2027. The bullish range is estimated at $140,000 to $180,000, with a potential late-cycle surge that could push Bitcoin beyond $200,000.
Currently priced around $83,000, this would represent a gain of about 115% to reach $180,000. What’s noteworthy is that Bitcoin has already corrected significantly from its previous cycle high of about $126,200 on October 6, 2025, followed by a sharp decline during 2026.
Bitcoin has a history of producing substantial gains during strong market cycles. According to historical annual data, BTC gained approximately 154% in 2023 and 110% in 2024. If the current predictions hold true, we may see a similar increase on the horizon.

Perplexity AI Predicts Bitcoin to $180,000 if Bullish Catalysts Align: Does the Technical Analysis Back it Up?
Bitcoin recently broke out of a pattern of lower highs that had developed since May, reclaiming several key moving averages. According to Reuters’ technical analysis, $81,781 is considered important support, while $86,500 is a significant resistance level. Above that, the next technical targets are around $90,000 and $97,867.
CryptoQuant has noted a similar trend, calling $81,700 a key level because it aligns with Bitcoin’s 365-day moving average. Resistance levels above this are near $86,600 and $88,700.
Bitcoin’s first major test is surpassing the $85,000 level, followed by the $86,000 to $88,000 range. Bitcoin has pushed through this area, which matters because a sustained breakout would remove one of the largest technical obstacles between its current price and the $100,000 level.
The next major milestone is approximately $98,000. Beyond that, the market will be approaching the all-time high of $126,200, where it gets particularly interesting.
Once Bitcoin decisively breaks beyond $126,000, it will enter a phase of genuine price discovery. Historical resistance above that level is very limited. At that point, psychological targets such as $130,000, $140,000, and $150,000 could attract momentum traders and institutional investors.
Earn $50 and Enter $300K Prize Draw on EdgeX
Bitcoin Hyper Targets Early Mover Upside as Bitcoin Drops Dangerously Close to $80,000
A -2.5% daily drop is not too much to worry about for whales and those already heavily positioned at a much lower price. However, for those who bought over $80,000, things could be getting uncomfortable, which is why presale opportunities prove so popular.
Bitcoin Hyper ($HYPER) is positioning itself as the first Bitcoin Layer 2 with full SVM integration. It boasts smart contract execution built for speed that outpaces Solana itself, while settling back to Bitcoin’s base-layer security.
As of today, the presale has raised more than $33.1M at a current token price of just $0.0136864, with staking rewards live at launch at a huge 35% APY.
The pitch: solve Bitcoin’s slow transactions, high fees, and lack of programmability without abandoning what makes BTC trusted in the first place. A Decentralized Canonical Bridge handles BTC transfers natively.
Gain Access to New Bitcoin Layer 2 Early Here
Discover: The Best Token Presales
The post Perplexity AI Predicts a Big Move for BTC in 2026 Even With Recent Dip appeared first on Cryptonews.
XRP lost its $1.50 price pivot today, sliding to $1.47 after a daily decline of about 3%. The break forces a binary question onto the chart: does the selling pressure showing up in spot-market volume resolve into a quick reclaim, or does it open the door to a deeper slide toward $1.40-$1.42?
The 200-day EMA is near $1.37, the level that would flip the medium-term structure from bullish to neutral. The token has been printing lower highs since a local peak near $1.63 on September 23, and a second attempt to clear $1.60 on September 25 failed as well. Since then, the decline has been slow and orderly: $1.55, then $1.52, then $1.50, and now $1.47.
There was no single dramatic session driving the move. Instead, the pattern reads as buyers simply not showing up, with every small bounce getting sold rather than extended. After the sharp rally in early September, that kind of cooling was overdue, but the open question is whether $1.50 was ever real support or just a round number the market is now testing.
Earn $50 and Enter $300K Prize Draw on EdgeX
ETF Accumulation Narrative or Technical Pullback?
The chart itself frames this as a cooling-off period following the rally that carried the XRP price up nearly 50% from its August low near $1.00. RSI sits at a neutral 54, with no overbought or oversold readings to lean on. Price levels, not oscillators, are setting the tone for this week.
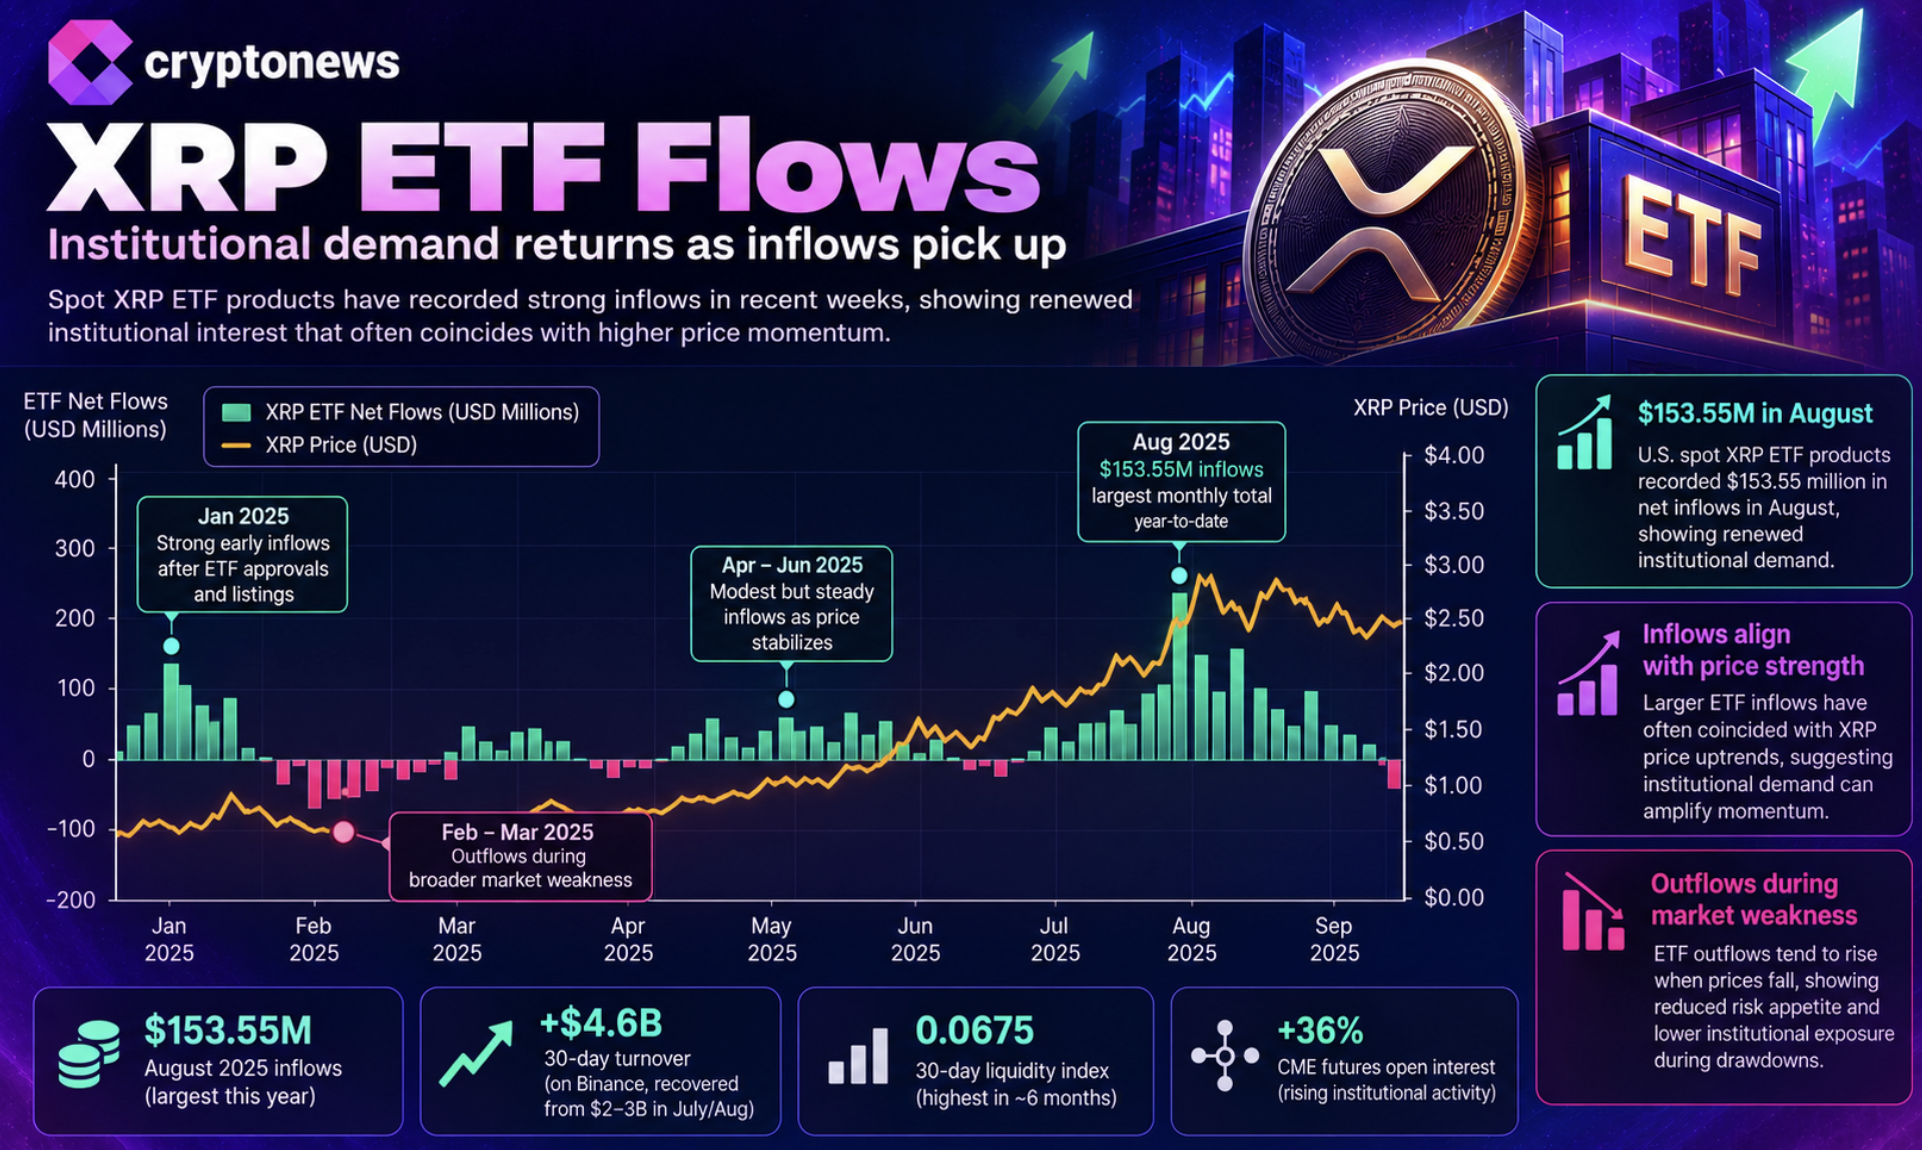
Separately, market data has pointed to sustained spot XRP ETF inflows running into the hundreds of millions of dollars over recent weeks, a trend some trackers frame as ongoing institutional accumulation beneath the price action. That flow data is useful context, but it is not confirmed as the driver of Monday’s drop, as the pullback below $1.50 traces cleanly to failed resistance tests and fading bid support.
The medium-term structure remains intact for now. XRP sits above its 200-day EMA at $1.37, which is curling upward for the first time since spring. This is a sign the longer trend has not broken, even as the shorter-term chart bleeds lower. A descending trendline from the late-August spike to $1.70 was cleared in mid-September, and that breakout is what fueled the run to $1.67 in the first place.
A second descending trendline, drawn from the September 23 high, is now the line bulls need to clear in October; left alone, it points toward $1.20 by mid-November. The levels on both sides of the current price are well defined.
Trade XRP on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
Reclaim $1.50 or Risk $1.37: XRP Price Next Move
The first job for bulls is straightforward: close a daily candle back above $1.50. Do that, and Monday’s drop reads as a fakeout rather than a breakdown, with $1.55 as the next confirmation level and $1.60-$1.63 as the target that would put the September 23 high back in play.
Fail to reclaim $1.50 in the next day or two, and $1.40-$1.42 becomes the level to watch, with the 200-day EMA at $1.37 as the line that actually matters for the medium-term outlook. A close below it would shift Ripple’s native asset from a bullish structure to a neutral one, opening room toward $1.30 and, in a broader crypto market sell-off scenario, $1.20.
$XRP just printed it's 6th weekly close beneath the 50 week EMA. The bears contInue to hold their defence line, with the bulls support below at $1.31 as a guardrail. (20 week EMA. For the time being, we remain compressed. https://t.co/7j6d2KB27L pic.twitter.com/r9kwHDmf2R
—
ChartNerd
(@ChartNerdTA) September 28, 2026
For this week, the range is $1.37 to $1.60, with $1.50 sitting as the pivot in between. On technical analysis grounds, the base case is a dip toward $1.40-$1.42 that gets bought, followed by another attempt at reclaiming $1.50. A pattern consistent with pullbacks inside an uptrend rather than the start of a new downtrend.
The $1.80-$2.00 zone remains the valid medium-term target as long as $1.37 holds; lose it, and that target moves out of reach for the immediate term.
Discover: The Best Token Presales
The post XRP Price Slides 2.9% as $1.50 Reclaim Becomes Critical appeared first on Cryptonews.

Goldman Sachs Explains Why Not to Buy the 5%+ Bonds and Rather Stick to AI

Nations League: Italy rebound in Turkey as France snatch late win in Belgium

How brain stimulation could impact how we develop new skills


-
 Fashion3 days ago
Weekend Open Thread: J.McLaughlin – Corporette.com
-
 Tech & AI1 day ago
Anthropic turns Claude into an AI marketplace with 2,000+ plugins and connectors
-
 Crypto6 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-
 Tech & AI1 day ago
OpenAI is preparing “o,” an always-on ChatGPT assistant that could handle email
-
 Fashion5 days ago
8 iPhone Accessories That Add Personality
-
 Entertainment6 days ago
These 17 Fall Amazon Dresses Seriously Look Like Anthropologie
-
 Tech & AI6 days ago
Reolink’s solar 4K security camera falls to its lowest price in months
-
 Crypto7 days ago
Trump-Xi Polymarket Odds for Handshake Hit 50%
-
 Crypto6 days ago
This Bearish Netflix Stock Trade Can Cash In On Video Streaming Giant’s Woes
-
 Crypto5 days ago
Bitcoin price tests $83,600 Supertrend support after $87K rejection
-
 Crypto5 days ago
Crude Oil Prices Pressured by Diplomatic Hopes in the Middle East
-
 Crypto6 days ago
BitGo says Bitcoin absorbed Fed hike, CLARITY failure
-
 Business & Hussles6 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-
 Crypto5 days ago
Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike
-
 Crypto6 days ago
Did Jim Cramer Just Give GameStop Stock the Kiss of Death When He Said the Turnaround Is Working?
-
 Tech & AI5 days ago
UiPath’s Dines says AI needs a manual and launches Cartographer to write it
-
 Crypto5 days ago
As Amazon Stock Prospers, Traders Might Consider This Option Play
-
 Crypto5 days ago
Strategy resumed Bitcoin buying, but Strive gained more BTC per share
-
 Tech & AI6 days ago
Sega nearly killed Sonic before the movies revived the franchise
-
 Crypto2 days ago
Wall Street Giant Warns AI Agents Could Trigger a New Kind of Bank Run
You must be logged in to post a comment Login