
Crypto World
BIS Study Flags Key Blind Spot in Bitcoin On-Chain Transfer Data

Estimates of how much economic activity flows through crypto networks can diverge dramatically depending on how analysts measure onchain activity. A new study from researchers at the Bank for International Settlements (BIS) finds that calculations of Bitcoin transfer values can vary by as much as six times when different transaction-measurement methods are used.
The BIS researchers argue that the problem is not limited to Bitcoin. The same measurement challenges appear across the wider crypto ecosystem—including stablecoin activity and even conventional approaches to calculating market capitalization. Their conclusion: onchain indicators should be treated as imperfect, “noisy approximations,” not direct gauges of real-world economic activity.
Key takeaways
- Bitcoin onchain transfer-value estimates can differ by up to sixfold based on measurement choices, including how change outputs are handled.
- BIS finds conventional Bitcoin market capitalization figures have, at times, been up to four times higher than “realized” capitalization based on the last time a coin moved.
- Across large-scale data spanning Bitcoin, Ethereum, and Tron, the study shows similar measurement pitfalls in other parts of the market.
- On Ethereum, the abundance of smart contracts creates categorization gaps that complicate interpretation of activity, including stablecoins.
- Some analytics efforts—such as Visa’s Onchain Analytics dashboard—attempt to adjust raw stablecoin volumes to remove distortions from non-economic activity.
Why Bitcoin “transfer value” can change six times
The BIS findings focus on onchain transfer values rather than exchange trading volumes. According to the study, the gap between different estimates reflects differences in transaction measurement methods—most notably how the analysis treats outputs that send funds back to the original sender.
Bitcoin transactions are structured in a way that often includes “change” outputs. When a user spends Bitcoin, the network may return any unspent portion back to the spender as change. Some measurement approaches count that as an additional output, even though it does not represent value transferred to another counterparty.
The BIS researchers caution that metrics that are commonly used to infer activity—such as transaction volumes, market capitalization, and total value locked—can appear more precise than the underlying data actually supports. As the study puts it, those metrics can suggest accuracy that is “not supported by the nature of the underlying data.”
Market capitalization: a conventional figure can diverge
The BIS study does not stop at onchain transfer estimates. It also highlights inconsistencies in how market capitalization is typically calculated for Bitcoin.
The researchers report that the conventional market cap measure has at times been as much as four times higher than “realized capitalization,” a metric that values each coin at the price when it last moved. In practical terms, the difference underscores a broader issue: different ways of interpreting blockchain movement can generate materially different economic readouts.
This matters for investors and analysts who use onchain-derived figures to gauge adoption, liquidity, or sentiment. When measurement methodology can swing the headline number by multiples, comparisons across time periods—or across dashboards with differing definitions—require careful scrutiny.
Ethereum and stablecoins: categorization gaps and mixed use cases
The BIS researchers identify additional challenges on Ethereum, where smart contract activity multiplies the ways tokens can be held or moved. In the study’s dataset, researchers examined roughly 67.5 million active contracts and found that about 54 million could not be categorized using the study’s classification approach.
Stablecoins introduce a further layer of complexity because the same token can serve different roles across chains. The BIS researchers note that USDT on Ethereum was more closely associated with DeFi activity, while USDT on Tron was more tied to payment-like and store-of-value uses.
The study also describes stark differences in where stablecoins sit—particularly in smart contract holdings. The share of USDT held by smart contracts on Ethereum exceeded 20% in 2022, compared with around 1% on Tron. Because these holdings reflect different use cases, the BIS researchers warn that aggregating stablecoin activity across blockchains can conflate distinct kinds of economic behavior and obscure how stablecoins are actually being used.
Ultimately, the BIS team frames the broader takeaway as a limitation of data interpretation: onchain indicators should be handled as “noisy approximations rather than direct measures of economic activity.”
Filtering raw data: Visa’s adjusted stablecoin volumes
While the BIS study emphasizes the risks of treating raw onchain measures as straightforward economic signals, it also notes that some analytics providers attempt to separate “economic activity” from activity that may be distorted by mechanics or automation.
Visa’s Onchain Analytics dashboard—powered by data from Allium Labs—presents both total and adjusted stablecoin transaction volumes. Visa states that its adjusted methodology is designed to reduce distortions stemming from activity such as high-frequency trading, bots, bridge routing, and internal exchange operations.
On the dashboard, Visa currently shows $6.4 trillion in total stablecoin transaction volume across the networks it tracks over the past 30 days, alongside $313.1 billion in adjusted volume. While the BIS study itself does not validate any specific proprietary adjustment approach, the contrast illustrates the central issue it raises: definitions and filtering choices can move the headline number by a wide margin.
For readers using dashboards to benchmark stablecoin adoption, the implication is straightforward: “total” and “adjusted” are not interchangeable, and the rationale behind adjustments becomes part of the metric’s credibility.
What to watch next
The BIS study suggests that as onchain analytics matures, transparency about measurement definitions—and explicit handling of transaction structure, smart-contract categorization, and non-economic activity—will be essential. Investors and builders should treat widely cited onchain metrics as starting points, not definitive proof of underlying economic demand, and should watch for clearer methodologies that better align onchain observations with real-world usage.

US crypto policy momentum hit a wall as the Senate on Tuesday failed to advance the proposed CLARITY Act, leaving digital-asset firms to rely on agency rulemaking and shifting interpretations rather than a clear statutory framework. The procedural vote came up short of the 60 votes required to move forward—49-50 on a motion to invoke cloture.
Industry leaders described the outcome as disappointing but not necessarily final, pointing to potential regulatory action from the US Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC). Still, lawyers and executives warn that without legislation, compliance timelines and market planning could remain exposed to ongoing administrative discretion.
Key takeaways
- The Senate voted 49-50 on a cloture motion for the CLARITY Act—short of the 60-vote threshold needed to advance the bill.
- Crypto firms are increasingly looking to SEC and CFTC rulemaking to “fill the legislative gap,” rather than expecting near-term certainty from Congress.
- Legal executives argue that agency guidance may prolong case-by-case assessments, increasing compliance burden and prolonging uncertainty for budgeting and product rollout.
- A reconsideration move by Senator Thom Tillis keeps the possibility of another cloture attempt alive, but timing uncertainty remains high.
Why the CLARITY Act’s procedural failure matters
At the center of Tuesday’s outcome was the Senate’s failure to invoke cloture, a procedural step that determines whether debate on the CLARITY Act can move forward. While the vote does not kill the bill outright, it delays the legislative path and underscores how difficult it can be to secure consensus in a divided chamber.
Industry executives said the result creates a meaningful setback—especially because the stakes are not only legal theory. A legislative framework would be expected to reduce the unpredictability of how digital assets are classified and regulated across different product types. Without it, market participants may remain dependent on regulator-by-regulator and fact-specific interpretations.
As this gap persists, the question for investors, builders, and exchanges becomes less about the promise of a future law and more about whether agencies can deliver stable, consistent rules quickly enough to support real-world planning.
Regulators as the next avenue for clarity
In the immediate aftermath, executives highlighted what they viewed as the most plausible alternative: rulemaking from the SEC and the CFTC. Ripple CEO Brad Garlinghouse said on X that continued regulatory work by both agencies could still provide the clarity firms need.
According to Garlinghouse, “the SEC, under Chair Atkins, and the CFTC, under Chair Selig, will continue to work hard to issue rules” to address the gap left by the stalled legislation. The comments align with earlier remarks from SEC Chair Paul Atkins during the Solana Policy Institute Summit on Monday, where he reaffirmed the agency’s commitment to clearer crypto rules regardless of legislative progress.
That “agency-first” approach may help address certain questions faster than Congress can. But it also changes how certainty is produced: rather than coming from a statute that applies broadly, clarity may depend on a series of rule proposals, comment periods, and final determinations—each of which can evolve over time.
Executives warn about “temporary reprieve” and case-by-case risk
Legal and compliance leaders cautioned that rejecting the bill may leave firms exposed to administrative discretion. NEAR chief legal officer Abhishek Vaidyanathan said the lack of legislation would force continued reliance on agency guidance rather than a definitive statutory framework.
In particular, Vaidyanathan argued that firms preparing budgets for 2027 would likely face another prolonged delay, pulling them back toward “case-by-case judgments and repeated legal work.” In his view, that is not just a legal inconvenience—it also affects how counterparties price risk when regulatory interpretation remains in flux.
Similarly, Bitget Wallet chief operating officer Alvin Kan told Cointelegraph that the bill’s failure maintains uncertainty about how securities, commodities, and money-transmission rules apply across different products. The practical effect is that product categories can face different compliance pathways even when they serve similar users, and the line between those categories can remain contested.
Another Senate attempt and what happens after this Congress
Despite Tuesday’s setback, the CLARITY Act discussion is not over. Senator Thom Tillis moved to reconsider the failed attempt, potentially allowing another cloture vote. That kept the door open for renewed procedural progress in the current session.
1inch chief legal officer Orest Gavryliak characterized the Tuesday result as a delay rather than a verdict, noting that legislation of this scale rarely moves in a straight line and that another cloture vote can be pursued.
Still, the odds of passage before the end of the current congressional term are far from certain. Vaidyanathan suggested that the “next Congress” may be the more likely opportunity to tackle crypto market structure, implying that legislative timing and election-driven priorities could become barriers.
He also pointed to near-term calendar constraints: the House has reportedly canceled weeks of September 21 and 28, while the Senate’s state work period begins October 5 ahead of the November 3 election. Those scheduling dynamics matter because even when support exists, floor time and procedural momentum can be difficult to sustain.
Market sentiment around the bill’s prospects also softened. Polymarket odds of the CLARITY Act being signed in 2026 fell to 5% on Tuesday, the lowest probability since the market opened in January, indicating that traders and bettors rapidly adjusted expectations following the cloture failure.
For readers trying to anticipate what changes next, the key watchpoints are whether Tillis’s reconsideration leads to another cloture vote and, in parallel, how quickly the SEC and CFTC move from commitments into concrete rule proposals and final guidance—because those will determine whether firms get durable clarity or continue to operate in a regime of shifting administrative interpretation.

XRP is trading at $1.40, with the price sitting just below the $1.42 resistance level as the Senate prepares for a procedural vote on the CLARITY Act. The setup highlights a clear tension: the daily chart remains cautiously constructive, while momentum on shorter timeframes has faded.
At $1.40, XRP is close to its daily pivot and caught between nearby support and price resistance. Daily indicators show that the structure has not broken, but intraday readings point to a market that has yet to establish a decisive direction.
The scheduled vote is procedural rather than a final decision on whether the CLARITY Act becomes law. It concerns the bill’s path through the Senate and is separate from subsequent legislative steps that would be needed for a final federal framework.
Senate Republicans released a revised, 630-page draft ahead of the September 15 vote. The updated language would require trading protocols controlled by identifiable people or groups to register with the Commodity Futures Trading Commission. The draft also retains ethics provisions that prohibit public officials, employees, and their spouses from issuing or sponsoring digital assets.
The legislation seeks to establish a federal digital-asset market framework and clarify regulatory responsibilities. Even if the procedural step advances, further Senate action would still be necessary before any final legislative outcome is reached. For XRP traders, the vote is therefore one factor alongside the chart rather than a standalone resolution of the market’s current indecision.
Earn $50 and Enter $300K Prize Draw on EdgeX
Why $1.40 XRP Price is A Genuine Market Standoff?
The daily chart gives XRP the benefit of the doubt. Price at $1.40 sits above both the 20-EMA at $1.37 and the 200-EMA at $1.33, while daily RSI reads 55.92. That places RSI above its midline without placing it near overbought territory.

The 50-EMA at $1.29 remains below the 200-EMA, however, so the averages do not form a textbook uptrend stack. The structure instead reflects a sharp recovery after a decline, with shorter-term averages recovering faster than the medium-term average.
The daily MACD adds caution to the constructive read. The MACD line is at 0.03 against a 0.05 signal, producing a negative histogram of roughly -0.02. That soft bearish cross suggests that the advance above the moving averages has lost some forward momentum, even though the wider daily structure remains intact.

The crypto backdrop has also been weak. Total crypto market cap declined to $2.72 trillion, while Bitcoin dominance stood at 58.36%. The Fear & Greed Index read 69, in Greed territory, creating a contrast with the wider market pullback. U.S. diesel prices topped $6 per gallon amid the Ukraine and Iran conflicts, adding to risk-sentiment pressure.
Trade XRP on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
The $1.39 Support and $1.42 Resistance Test
The daily pivot point is $1.41, with resistance at $1.42 and support at $1.39. XRP price is trading close to that pivot, a position consistent with a market waiting for a clearer catalyst.
A move above $1.42 would place the upper daily Bollinger Band near $1.46 in focus. A loss of $1.39 would return attention to the $1.33-$1.32 area, where the 200-EMA and lower Bollinger Band are close together, followed by the 50-EMA at $1.29.
Shorter timeframes present a softer picture. On the hourly chart, XRP at $1.40 sits just below the 20-EMA at $1.41, while RSI has slipped to 44.41. Average True Range near $0.02 indicates compressed volatility and consolidation rather than a clear trend.
The 15-minute chart is weaker still. XRP trades below its 20-EMA at $1.41 and 50-EMA at $1.42, while RSI is 30.72, near oversold territory. The 15-minute ATR is approximately $0.01, reinforcing the picture of a tightly compressed market.
The bullish case depends on XRP defending $1.39, reclaiming $1.42, and remaining above the daily 20-EMA. A positive turn in the daily MACD histogram would indicate that momentum is improving alongside the existing structure. A sustained bounce from the 15-minute RSI near 30.72 could offer an early sign of renewed buying, although it would not constitute confirmation by itself.
For now, XRP remains positioned around a narrow $1.39-$1.42 range. The daily chart still supports a cautiously constructive interpretation, but fading MACD momentum and softer lower-timeframe readings keep that interpretation conditional. The indicators are delivering a mixed signal, making the nearby pivot, support, and resistance levels the central focus.
Discover: The Best Token Presales
The post Fading Momentum Leaves XRP Price Trapped Near $1.40 appeared first on Cryptonews.
Stablecoins may be doing more than speeding up crypto payments. Speaking at Queen’s University Belfast on Tuesday, Carolyn Wilkins of the Bank of England’s Financial Policy Committee argued that the rise of dollar-linked “digital dollars” could further entrench the US dollar’s role in global finance—while also creating a channel through which stress in US Treasury markets could spread back to stablecoin issuers.
Wilkins highlighted how dollar-denominated stablecoins can simplify cross-border settlement and extend access to dollar-linked assets beyond traditional US banking rails. She tied that convenience to a straightforward market consequence: greater demand for US Treasuries, especially for reserves backing stablecoin issuance.
Key takeaways
- Dollar-linked stablecoins can increase US Treasury demand by extending reserve access to dollar assets beyond the US, according to Bank of England financial policy committee member Carolyn Wilkins.
- Stablecoin issuers are already large holders of Treasury bills, with figures cited showing nearly $150 billion held at end-2025 by Tether and Circle, and about $33 billion of purchases during 2025.
- Wilkins warned the relationship works both ways: in a large-scale redemption event, issuers could be forced to sell Treasuries, potentially amplifying volatility in an already pressured market.
- The stablecoin market remains overwhelmingly dollar-oriented, with the US dollar accounting for 98% of stablecoin value, giving it a “first-mover advantage,” Wilkins said.
- In the UK, regulators are moving to facilitate development of stablecoins through sandboxes and finalized rules, while the Bank of England experiments with digital money for cross-border use cases.
How dollar stablecoins could strengthen Treasuries—and the dollar
Wilkins’ core argument is about incentive alignment. Dollar stablecoins, by design, are meant to track the US dollar, so expanding their use naturally encourages broader participation in dollar settlement and dollar-linked asset access. As stablecoins become a more common bridge for international transfers, the demand for dollar exposure can rise not only among traders, but also among institutions and intermediaries that prefer simpler settlement mechanics than traditional correspondent banking.
In her remarks, Wilkins specifically pointed to Treasury demand. She cited data indicating that Tether’s USDt (USDT) and Circle’s USDC (USDC) held nearly $150 billion in Treasury bills at the end of 2025, and bought about $33 billion worth during the year—illustrating that at least for the biggest issuers, Treasuries are not peripheral. They are integral to how dollar stablecoin reserves are positioned.
The implication for investors is practical: when stablecoin growth continues, Treasury demand from reserve managers tied to stablecoin issuance can become a persistent, if evolving, source of incremental demand. That matters in a market where Treasury liquidity and funding conditions can have wide knock-on effects across rates and collateral markets.
The other side of the trade: redemptions and volatility risk
Wilkins also emphasized that stablecoins are not a one-way beneficiary of dollar liquidity. Because reserves are connected to marketable US government debt, issuer balance-sheet dynamics can become a financial stability variable when redemption flows surge.
Her warning was specific in direction: at sufficient scale, mass stablecoin redemptions could compel issuers to sell Treasury bills. If that happens during periods of market strain, the forced selling mechanism could contribute to higher volatility—an effect that could be amplified by the fact that Treasuries are widely used as collateral and a benchmark across the financial system.
This is the central tension in the stablecoin-reserves narrative: the same structure that supports stablecoin issuance and cross-border convenience can transmit liquidity pressures when flows reverse quickly. Readers should treat the “stability” of a stablecoin as distinct from the stability of the markets used to back it.
Stablecoins remain dollar-dominated—UK regulators are still watching
The Bank of England official framed dollar dominance as a key structural feature. The stablecoin market is described in the remarks as overwhelmingly tied to the US dollar, with the dollar accounting for 98% of stablecoin value. Wilkins characterized that as a “considerable first-mover advantage,” reinforcing why dollar stablecoins could keep scaling faster than alternatives.
Broader adoption trends were also referenced in the context of market size, including reporting that stablecoin circulation has surpassed $300 billion. Even with continued growth, the near-total concentration in dollar-linked products suggests that, for now, the US dollar will likely remain the primary beneficiary of global stablecoin usage.
For the UK, the policy question is whether—and how—to develop stablecoins in a way that captures benefits without importing unnecessary risk. Wilkins’ remarks align with ongoing UK regulatory and experimental steps aimed at shaping how these products could fit into a broader financial system.
UK’s regulatory push: sandboxes, finalized rules, and digital pound tests
While dollar stablecoins dominate the global picture, British pound-denominated stablecoins have been slower to gain traction. Still, UK regulators have taken concrete steps this year to make local issuance and experimentation easier.
The Financial Conduct Authority began testing prospective stablecoin issuers through a dedicated regulatory sandbox and finalized rules for UK stablecoin issuance in June. The Bank of England has also been experimenting with digital money, including work to assess whether stablecoins and a simulated digital pound could be used together for cross-border trade payments, according to coverage of the Bank’s interoperability testing.
Wilkins’ comments also come in the broader context of the Bank of England adjusting its stance. Earlier coverage noted industry criticism of proposed rules and a subsequent softening of the UK stablecoin regime, reflecting a policy balance between innovation and oversight.
For market participants, this matters because local frameworks can influence which stablecoin projects get launched, which institutions are willing to integrate them, and how quickly alternative fiat currencies could gain traction outside the US dollar orbit.
What to watch next is whether UK and broader European efforts can diversify currency exposure in stablecoin reserves—or whether the dollar’s structural advantages continue to pull most growth back toward US Treasuries. Equally important will be monitoring redemption stress scenarios: if large-scale outflows coincide with Treasury-market strain, Wilkins’ warning about volatility transmission could move from theory to a measurable market dynamic.
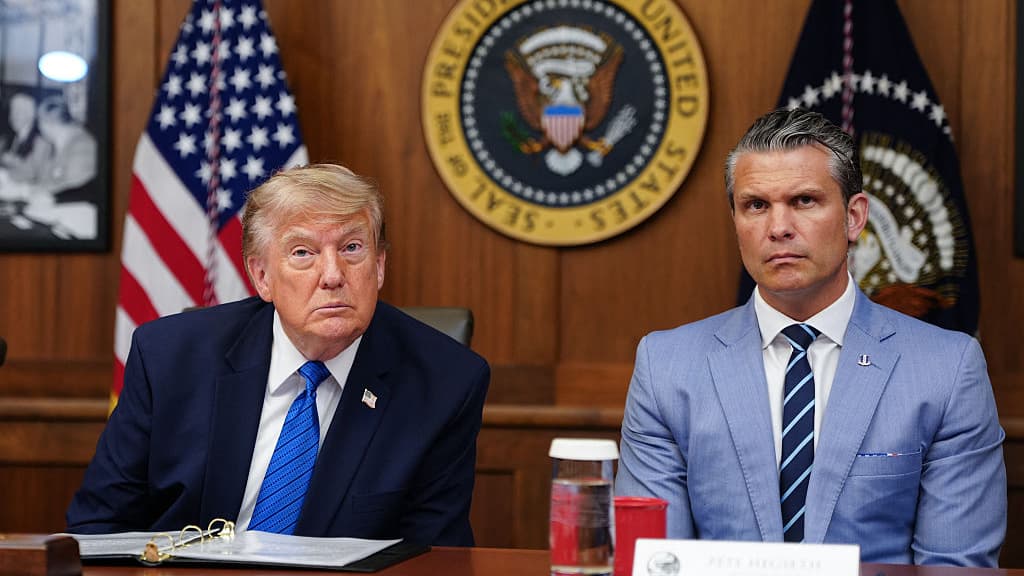
The bulk of the spending—$21.7 billion—comes from replacing munitions expenditures, the CBO found, including $13.1 billion for missile defense interceptors and $7.3 billion for land-attack cruise missiles. Other costs include repairing or replacing equipment, increased flying hours for air operations and transportation, and increased fuel costs. However, it does not factor in the cost of damage to U.S. bases and facilities in the Middle East.
The separate report from the Defense Department’s inspector general, released a day before the CBO’s, estimated the cost of repairing “physical damage from Iranian strikes” to U.S. diplomatic facilities in Iraq, Kuwait, Saudi Arabia, and the UAE at approximately $184 million. It also determined that throughout Operation Epic Fury the U.S. military has spent $22.3 billion on munitions and has lost around $3.7 billion in aircraft and equipment, including four destroyed F-15 fighter jets, seven KC-135 tanker aircraft, a dozen damaged or destroyed KC-135 refueling aircraft, and the loss of up to 30 MQ-9 Reaper drones.
Standard Chartered’s Geoff Kendrick is making a pointed bet on Arbitrum’s long-term upside, arguing that the layer-2 network could become a standout beneficiary as traditional finance accelerates the shift toward onchain and tokenized assets.
In a note shared with Cointelegraph, Kendrick highlights Arbitrum’s revenue model as a key reason for optimism: the network receives 10% of net protocol revenue generated by companies building on it. He points to Robinhood Chain—developed by the online brokerage Robinhood—as an early, high-visibility example of that mechanism in action.
Key takeaways
- Standard Chartered expects Arbitrum’s revenue share (10% of net protocol revenue) to translate into stronger token economics.
- According to Kendrick, Robinhood Chain materially increased Arbitrum’s run-rate revenue after launching in July.
- Arbitrum revenue is projected to reach $5 million in September, the bank says—more than five times the pre-Robinhood level.
- Standard Chartered’s base case targets ARB potentially rising to as high as $10 by 2030, contingent on tokenization growth and competition.
- The bank flags slower-than-expected asset tokenization and competing layer-1/layer-2 ecosystems as the main risks.
Why Standard Chartered thinks Arbitrum’s token economics can expand
At the center of Standard Chartered’s outlook is the idea that Arbitrum is not only a destination for crypto-native users, but also an infrastructure layer for tokenization and onchain financial services. Kendrick’s argument ties network growth to economics that ultimately flow back to the system—and by extension, to the ARB token.
In the note, Kendrick emphasizes that Arbitrum receives 10% of net protocol revenue produced by companies building on the network. He also credits the arrival of Robinhood Chain with “materially” shifting Arbitrum’s economics. The comparison Kendrick makes is straightforward: at the current run rate, Arbitrum is expected to generate $5 million in revenue in September, which he says is more than five times its level prior to Robinhood Chain’s launch in July.
That framing matters for investors because it positions Arbitrum’s upside as more than speculative usage growth; it’s anchored to a revenue-share structure that could scale as new onchain products are deployed on its infrastructure.
Robinhood Chain as an early test case for the revenue model
Kendrick describes Robinhood Chain as the first major example of how traditional finance activity could influence Arbitrum’s economics. Earlier coverage from Cointelegraph noted Robinhood’s launch of an Ethereum layer-2 testnet aimed at tokenized assets.
Standard Chartered’s assessment suggests that the market may be underestimating the direct financial linkage between deployments on Arbitrum and the network’s protocol revenue intake. If the bank’s projections hold, that linkage could strengthen the case for ARB not just as a governance token, but as a proxy for the economics of Arbitrum’s expanding developer and enterprise footprint.
From revenue growth to ARB price targets—what’s bullish, what’s conditional
Building on the revenue outlook, Kendrick expects Arbitrum’s economics to support a steady rise in ARB over the coming years. Standard Chartered’s projection reaches as high as $10 by 2030. From current levels, Kendrick frames that outcome as roughly a 70-fold increase.
The bank also contrasts that trajectory with its projected returns for Bitcoin and Ether over the same period, suggesting that Arbitrum—under this scenario—could outperform major benchmark assets in risk-adjusted terms. Still, Kendrick’s note is explicit about uncertainties.
He flags two main risks to the ARB projection: a slower-than-expected pace of asset tokenization and increased competition from alternative blockchain networks. Those concerns are important because they go directly to the assumptions behind Arbitrum’s revenue expansion—namely, whether tokenization demand grows quickly enough and whether enterprises choose competing ecosystems for their layer-2 or tokenized-asset infrastructure.
Tokenized asset growth is the bigger bet
Standard Chartered’s thesis leans heavily on the broader market trend of tokenized real-world assets (RWAs). According to RWA.xyz data, the cumulative value of tokenized real-world assets is nearly $39 billion.
In its note, Kendrick reiterates the bank’s forecast that tokenized assets could reach $4 trillion by the end of 2028 as banks and asset managers bring more assets onchain. Under that pathway, Arbitrum is positioned as a potential beneficiary because it enables companies to build their own layer-2 networks while collecting a share of net protocol revenue generated by deployments.
Standard Chartered has previously connected tokenization expectations to other parts of the crypto ecosystem, citing the growth of tokenized RWAs as supportive of its bullish outlook for Chainlink and for the wider decentralized finance sector.
For readers, the next signals to watch are whether tokenization adoption accelerates faster than anticipated—and whether Arbitrum keeps attracting major deployments without losing share to rival ecosystems. Kendrick’s projections hinge on that pace, and any divergence could materially change the implied path from protocol revenue growth to ARB performance.
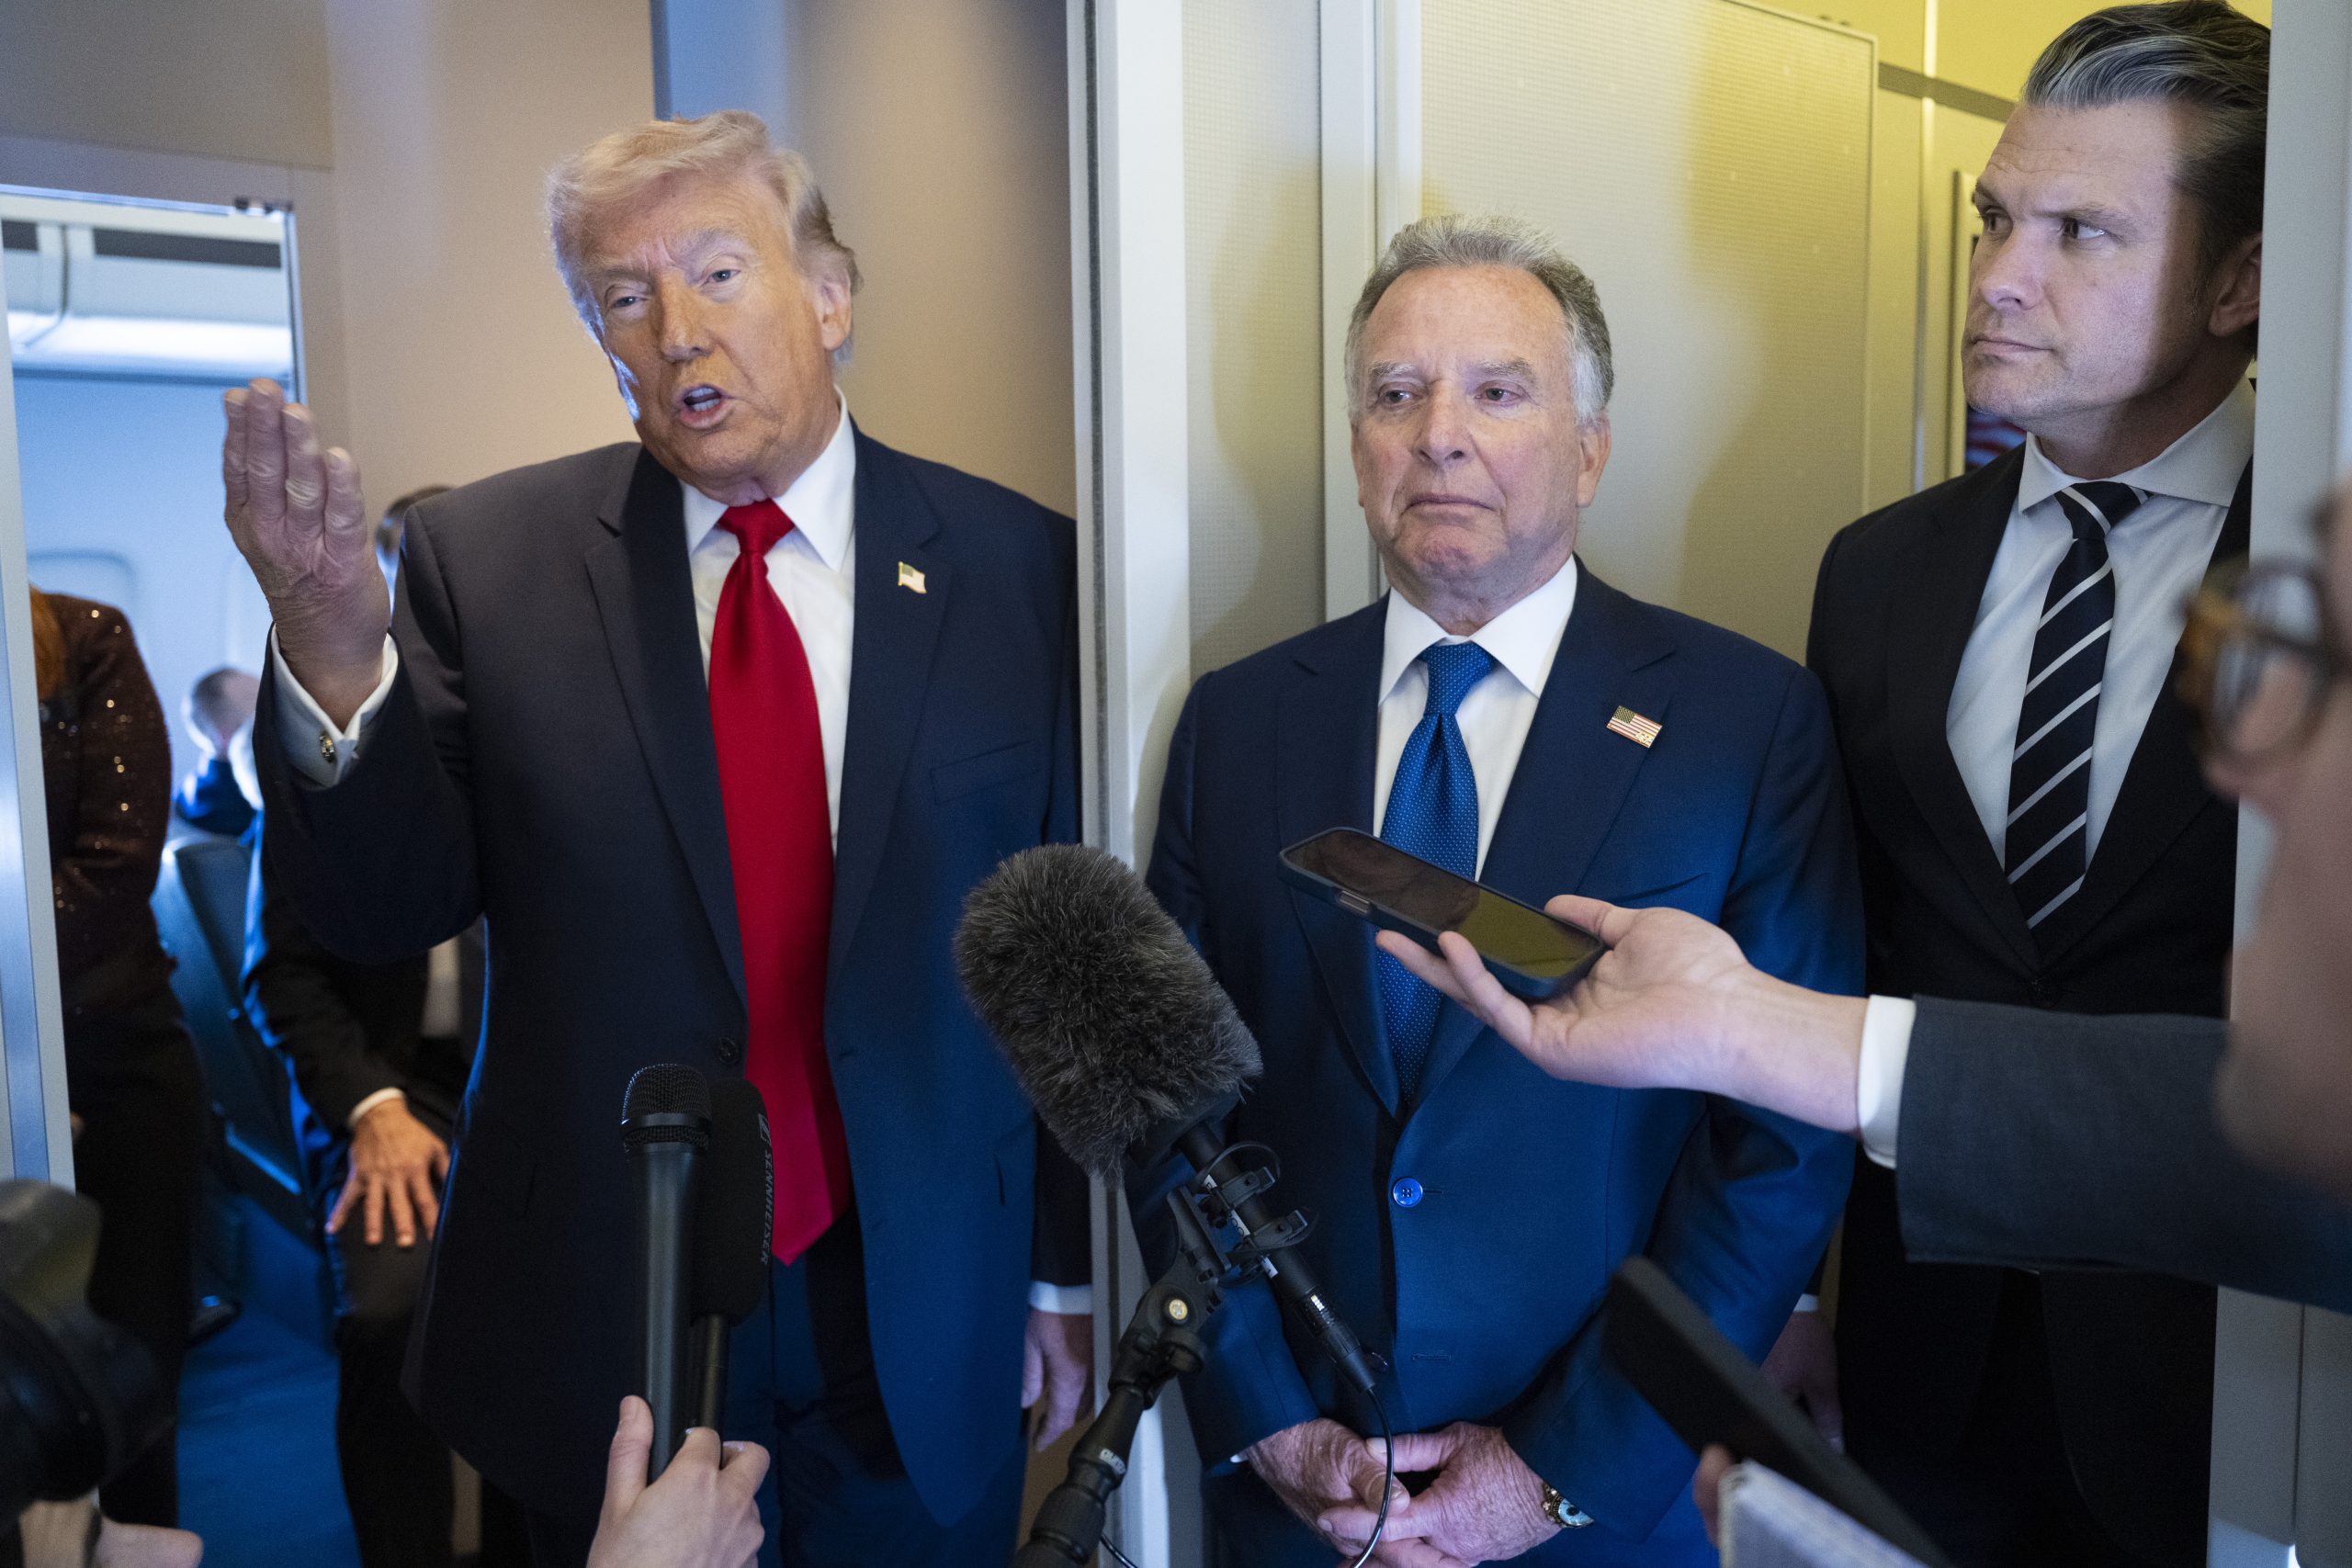
President Donald Trump at the start of the Iran war predicted it would last four-to-five weeks, but the conflict is now in its seventh month, with no clear timeline for when the fighting will end.
Active hostilities between Washington and Tehran resumed earlier this month, with oil tankers in and around the Strait of Hormuz coming under fire. Iran is vying to maintain a chokehold over the vital trade route amid the U.S. blockade against its ports. The Strait effectively remains in a military stalemate, bringing renewed regional instability and gravely impacting transit via the waterway, through which around a fifth of global oil production flowed before the war began on Feb. 28. Oil prices last week soared to over $100 a barrel for the first time since July, as the disruption sends energy markets spiraling once more.
The balance of power in the Gulf has come under further strain as Yemen’s Iran-backed Houthi rebels have made significant advances following weeks of fighting with the Saudi-backed government of Yemen, shattering a four-year informal cease-fire in the country’s civil war. The Houthis last week captured the strategic Perim Island, which sits in the Bab el-Mandeb Strait, another vital trade route situated between Yemen and Djibouti and Eritrea in the Horn of Africa, that links Asia and Europe via the Red Sea and Suez Canal. This came as they traveled along the Red Sea coastline, aiming to tighten their grip on the critical maritime chokepoint. The disruption has placed further pressure on the global oil market.
The Houthis’ expanding presence in the Red Sea and the potential it has to severely disrupt trade via the Bab el-Mandeb arguably gives Iran leverage in its war with the U.S., experts say.
“This has the effect of turning up the pressure on the U.S. and its allies who have been relying on alternate routes,” Daniel Benaim, a former U.S. Deputy Assistant Secretary of State for the Arabian Peninsula, tells TIME. “In a contest of economic wills, the alternate Red Sea has been a very important release valve for the blockage of the Strait of Hormuz.”
Diplomatic efforts in the Middle East have faltered. The Gulf states, many of which house U.S. bases that have been targeted by Iranian strikes, on Monday postponed a critical meeting with Tehran on the reopening of the Strait of Hormuz.
Despite pressure mounting for a clear way out of the war, meaningful negotiations between the U.S. and Iran also remain stalled. Here’s what each side has said regarding the status of peace talks, and how experts predict Iranian officials could use the Houthis’ disruption in the Red Sea to their benefit.
Trump says U.S. is ‘open’ to restarting negotiations
Trump on Monday said the U.S. is “open” to the concept of restarting negotiations between Washington and Tehran. High-level officials from both sides last convened for official peace talks in Switzerland in June.
“The failing nation of Iran wants to make a deal, quickly and badly,” he claimed. “I will determine whether or not the U.S.A. will choose to engage—the concept of which we are open to.”
Trump’s remarks stood in stark contrast to the position he laid out on Sept. 2, when he said he was “not trying to force” Iran to the bargaining table. “I couldn’t care less if they sign a worthless, to them, agreement. I like our position now much better, with almost total control of the Hormuz Strait, and their economy totally collapsing. They are just playing out the inevitable,” he insisted.
On Sept. 9, Trump assured the American public that the war will likely end “immediately after” the November midterms and said Iran’s government is holding out in hopes of hurting Republican political prospects.
Trump has expressed full confidence in the U.S.’ two-pronged military and economic campaign against Iran, with the latter aiming to choke Tehran off from the global economy through various sanctions.
Read More: How the U.S. Treasury’s New Aviation Sanctions on Iran Extend Beyond Tehran
Ali Vaez, deputy program director for the Middle East and North Africa at the International Crisis Group, tells TIME that Trump’s diplomatic approach will dictate how successful future negotiations may be.
“President Trump might be interested in getting a deal with Iran, but that’s not necessarily a guarantee that he will get a deal. It all depends on what approach he would adopt to diplomacy. If it’s maximalist, then it doesn’t stand a chance of succeeding,” he says, adding that dealing with Iran requires “a multi-dimensional diplomacy” in order to achieve a “sustainable de-escalation between Iran and the United States.”
Trump has repeatedly insisted that the U.S. has near total control of the vital waterway and that “oil is flowing,” but traffic via the Strait remains disrupted.
Kpler, a commodities data and analytics firm, shared data with TIME that shows that only 10 ships crossed the Strait of Hormuz on Monday—a significantly lower count than the 138 vessels that typically passed through the waterway during a 24-hour period before the war.
“The United States has shown over time that it has capabilities to move significant amounts of shipping through the Strait, but Iran has innovated,” says Benaim. “Iran and its allies are innovating in their ability to disrupt. So it’s a bit of a foot race between U.S. attempts to bypass Iran’s restraints and Iran’s attempts to enforce its own de facto blockade.”
The Iran war, and its economic impact, has been deeply unpopular with Americans who are facing increasingly high energy costs. Diesel prices last week reached a record $6 per gallon. The war with Iran has cost the U.S. government around $38 billion and contributed to growing inflation, according to newly-published analysis by the Congressional Budget Office. A national UMass Amherst/YouGov poll, conducted from Aug. 21 to 26, found that 68% of Americans view Trump’s handling of the war negatively.
Iran says ‘no talks until conditions met’
Iran has responded to Trump’s openness to negotiations by doubling down on its demands.
“Don’t get distracted by the U.S. President’s mixed signals—from ‘no negotiations’ to ‘we’re ready to talk,’” said Mohsen Rezaei, Iran’s recently-installed secretary of the Supreme National Security Council, on Monday. “No talks until Iran’s conditions are met. Period!”
While Rezaei did not directly name any conditions, Iran previously put forward a list of six demands for the U.S. to meet before the Strait of Hormuz would be fully reopened. Rezaei also seemingly pointed to the recent developments in the wider region, arguing that the “stakes around oil and the straits have changed” and warning that “damage control won’t stop what’s coming.”
The remarks from the hard-line national security adviser took an elevated position from that of Iranian President Masoud Pezeshkian, who in early September said Tehran was prepared to “reciprocate,” if the U.S. returned to the cease-fire conditions both countries negotiated in June. He was referencing the Memorandum of Understanding (MoU) signed on June 17, but the pact fell apart, with Washington and Tehran seemingly adopting different interpretations of the language used in the interim agreement.
Farea Al-Muslimi, a research fellow at Chatham House’s Middle East and North Africa program, says the Iranians are now “negotiating for the sake of negotiating,” arguing that their demands are intended to draw out talks while energy prices continue to rise.
“They can wait. They can afford it. They have no [democratic] parliaments. They don’t care about public opinion, as you imagine, and they are not allergic to pain,” he tells TIME.
Has Iran gained leverage as the Houthis close in on the Bab El-Mandeb Strait?
With the Houthis tightening its grip on the Bab el-Mandeb Strait, Iran has gained another potential source of leverage, experts say.
Amid the ongoing disruption to the Strait of Hormuz since the war started, there has been an uptick in the volume of crude oil and petroleum liquids that transit via the Bab el-Mandeb, increasing from 5.6 million barrels per day in the first quarter of 2026 to 8.1 million per day in the second quarter, according to the U.S. Energy Information Administration (EIA).
Despite the Houthis having claimed that they will not disrupt maritime traffic—except for Saudi Arabian oil tankers—experts tell TIME that the group’s ability to threaten shipping is enough to give Tehran greater leverage in any future round of negotiations.
“The Houthis march to the beat of their own drummer, but these actions certainly help Iran gain leverage by complicating alternative routes out of the Strait of Hormuz,” says Benaim.
In agreement, Al-Muslimi adds “the Iranians now have a new card they can use, and they haven’t totally used [it] yet, but they will. It’s a matter of time.”
“The Houthis are primarily concerned about advancing their own position within Yemen and globally. In this case, it happens to coincide with the pressure that Iran would like to apply on the United States and the international community,” Benaim adds.
Alternatives to the Bab el-Mandeb Strait present fresh challenges
The Bab el-Mandeb, which is Arabic for “Gate of Tears,” serves as the southern gateway to the Suez Canal— ships must pass through it to access the canal from the south. If the Houthis were to close the Bab el-Mandeb, it would increase the pressure on the global flow of oil.
Experts say shipping companies, if forced to find an alternative route, could be left to transit around South Africa’s Cape of Good Hope.
The Cape of Good Hope “could be a temporary solution, but it adds to insurance and travel costs, and timelines,” says Vaez. The EIA has estimated that the Cape route adds approximately 15 days to an oil voyage from the Arabian Sea to Europe.
Disturbances in the Bab el-Mandeb are particularly significant for Asian countries, experts say.
Asia has traditionally been Saudi Arabia’s primary export market for crude oil, receiving 75% of Saudi Arabia’s total annual crude oil exports in 2023, according to data from the EIA. China, Japan, South Korea, and India were its top crude oil importers.
The EIA on Sept. 9 acknowledged the concessions required when using alternative routes, noting that although “Saudi Arabia has increased oil shipments through the Suez Canal at the north end of the Red Sea,” it is “a longer and costlier route for customers in Asia.”
The Suez Canal also has constraints. As detailed by the International Energy Agency (IEA), “large crude carriers (VLCC) can only transit the canal when loaded below their 250,000 tonnes capacity.” As such, tankers following the route must first unload part of their cargo into a pipeline south of the canal and then reload the crude at a port before continuing their voyage, according to Reuters.
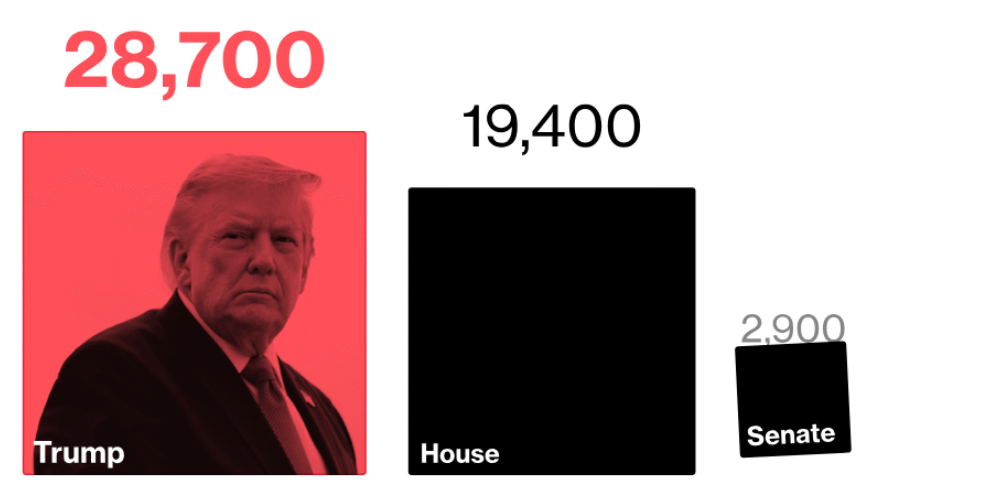
Donald Trump made nearly 28,700 stock trades in 17 months, more than the entire Congress’s 22,200 combined, even as he pushes a lawmaker trading ban that leaves his own portfolio untouched.
The figures, drawn from a Bloomberg review of disclosures through June, land as Republicans turn stock trading into a campaign issue ahead of the midterms.
A Trading Ban That Exempts Trump
House Republicans passed a bill in July barring members of Congress, spouses, and dependent children from trading individual stocks. The measure says nothing about the president.

Trump has backed the bill. He told Congress in his State of the Union address that it should pass “without delay.”
The White House says outside firms manage his holdings through index-tracking models. It says neither Trump nor his family directs any trades.
Representative Anna Paulina Luna is a lead sponsor of the ban. She framed it as an accountability measure at a Republican convention in Dallas last week.
“The American people deserve to know that those they elect to public office actually serve the American people and not their own wallets.”
Same Pattern, Different Target
Trump has pushed back hard on Republicans who want the ban to cover him too. He called Senator Josh Hawley a “pawn” last year after Hawley proposed extending trading limits to the presidency.
Trump has also called for scrutiny of Nancy Pelosi’s stock trading. His own disclosures show a similar pattern.
He has touted stock gains within days of buying into companies. That includes a DoorDash stake he held before hosting a White House delivery event.
Asked about the appearance of a conflict, Trump defended the trades.
“Because the stock market’s going up. Everybody’s profiting.”
A May Economist/YouGov poll found three-quarters of Americans want elected officials barred from trading stocks. Support for a ban, however, has not translated into enforcement.
Penalties under the Stop Trading on Congressional Knowledge (STOCK) Act of 2012 start at just $200. Legal experts say the Department of Justice would struggle to enforce any ban against a sitting president.
The post Trump Made More Stock Trades Than Congress Combined While Pushing a Trading Ban appeared first on BeInCrypto.
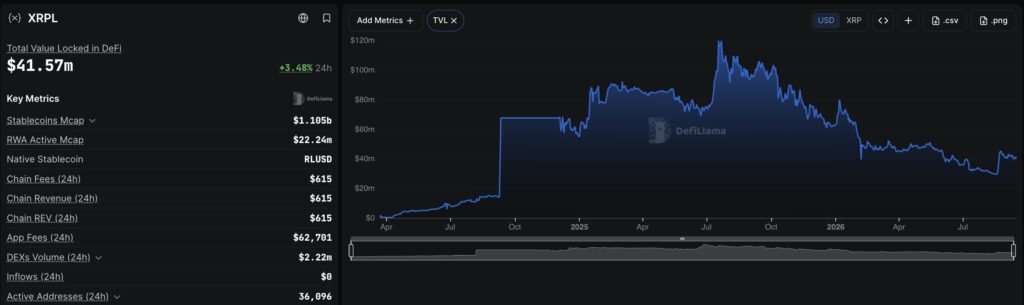
Ripple plans to invest as a limited partner in an institutional credit fund to lend its RLUSD stablecoin to fintech companies for working capital, as Clearpool announced an expansion onto the XRPL (XRP Ledger) in a governance proposal on September 11, 2026.
Developed in partnership with Cicada Partners and Hex Trust, this initiative aims to create the first institutional credit product on RLUSD.
Alessio Quaglini, co-founder of Clearpool and also CEO and co-founder of Hex Trust, gave this exclusive comment to CryptoNews.com regarding the announcement.
“We’re incredibly excited about this development. This initiative is a major milestone because it marks the very first institutional credit product built natively around Ripple’s new RLUSD stablecoin.” Quaglini said.
He added, “Ultimately, what we hope to achieve together is to unlock highly efficient, transparent working capital for fintechs while providing secure, compliant yield opportunities for institutional lenders.”

How the Proposed RLUSD Credit Rails Would Work Between Clearpool and XRPL
Clearpool’s plan separates the plumbing from the underwriting. Clearpool says it will build and operate curated credit vaults using XLS-65 Single Asset Vaults, a standard that pools deposits from multiple lenders into token-specific vaults with optional permissioning.
Loans would then be issued, serviced, and repaid through the XLS-66 Lending Protocol, which is designed to handle fixed-term, uncollateralized credit directly at the ledger level rather than through a smart contract.
Cicada Partners would sit on top of that infrastructure as the credit manager, sourcing borrowers, setting loan covenants and monitoring repayment health; the firm says it has underwritten more than $860M to date.
Ripple would provide capital as a limited partner alongside other institutional investors. Hex Trust is the designated institutional custodian partner, and these mechanics matter for a stablecoin regulatory landscape that is still taking shape globally.
Earn $50 and Enter $300K Prize Draw on EdgeX
Ripple, Cicada Partners, and the First Credit Fund on the XRP Ledger
The proposal clearly defines responsibilities: Clearpool serves as the infrastructure for loan origination, servicing, and repayment, while Cicada selects borrowers.
Ripple’s role is narrower: it functions as a limited partner alongside other institutional investors, providing capital without guaranteeing against losses. This clarifies Ripple’s financial commitment and confirms it is not a backstop for borrowers.
Clearpool highlights RLUSD’s growth as justification for the project, noting over $2.3Bn in circulation within two years, reflecting an established depositor and borrower base around the stablecoin.
Institutional interest in XRP-related products has grown, as shown by recent XRP ETF inflows, with yesterday (September 14) finishing with $11.26M in positive flows, per CoinGlass data.
Make Your Prediction Count With $25 For Free on Kalshi
Why Clearpool Is Betting on XRP Ledger Now
$CPOOL with clear RS today up ≈ +50% — Outer Ninth (@outerninth) September 14, 2026
This is a name I traded well last cycle so keep my eye on it. small cap RWA name. I had bids sitting at 0.01578 in August that didn't get filled by a hair  I didn't chase after that and just followed my system.
Even with todays HUGE… pic.twitter.com/hmejmaD2me
Clearpool aims to become the Morpho of private credit on the XRPL by using independent curators for isolated XLS-65 vaults, directing capital to borrowers through XLS-66.
This approach runs alongside the existing EVM-based Clearpool marketplace. With the XRPL’s late-2025 upgrade introducing native lending and compliance tools, Clearpool believes that early establishment can yield significant network effects.
Recent discussions about large XRP holder movements indicate growing institutional interest in the ledger. However, RLUSD holders and payments fintechs remain a targeted user base, without confirmed depositors and borrowers in operational vaults.
Supercharge Your Trading in 2026 With BloFin AI Trading Bots
The post Clearpool Expands to XRPL in First Institutional Credit Product on Ripple appeared first on Cryptonews.
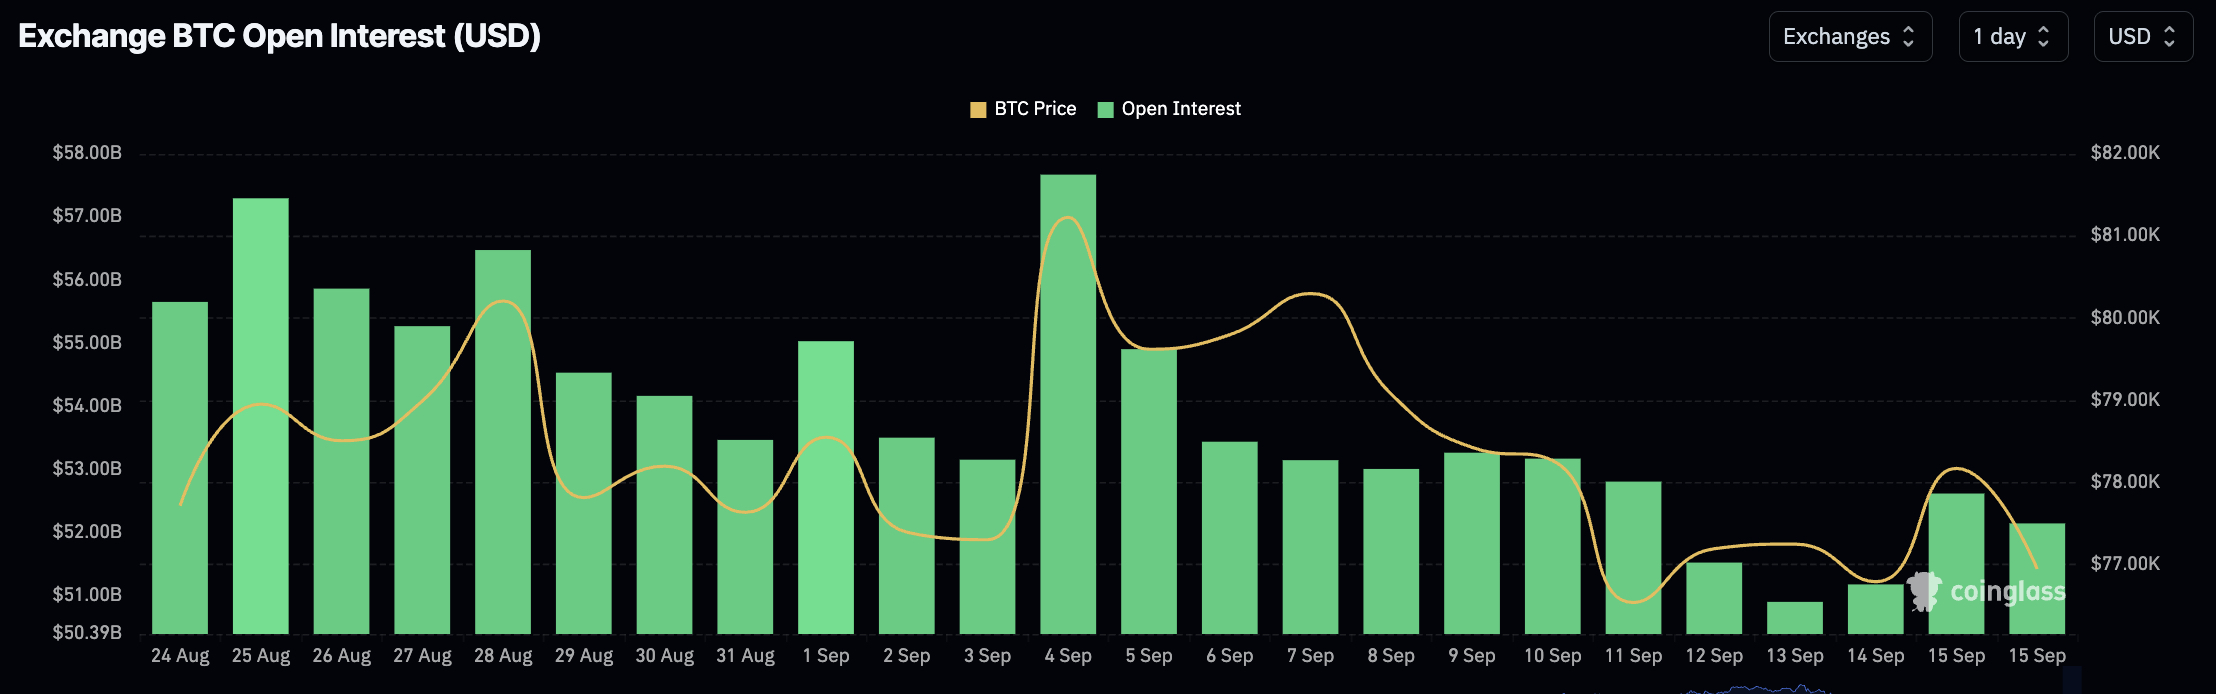
Bitcoin open interest fell by 13.5% in 10 days, dropping from 321,497 BTC to 278,151 BTC even as the underlying price declined only about 5% over the same window. That gap between derivatives unwind, and spot price action signals deliberate repositioning.
Bitcoin price currently trades under $77,000, down from its September 3 high of $82,300 but little changed day over day. The open question is if the leverage reset has actually cleared the path to a clean support test at $76,000-$77,000, or simply transferred the burden onto spot demand and ETF flows.
Senate Majority Leader John Thune has scheduled a cloture vote on the CLARITY Act for today, 2:15 p.m. Eastern, the first full-chamber test of comprehensive crypto market-structure legislation. Republicans hold 53 seats, meaning they need at least seven Democratic votes to advance the bill, and possibly more if any Republican breaks ranks.
The revised 630-page draft, published September 10, folds in more than 114 Democratic provisions, including a new registration category for “non-decentralized” DeFi protocols with identifiable operators overseeing consensus rules or functionality. Distributed ledger technology and raw software code are explicitly excluded from that category.
Layered on top is a Federal Reserve rate decision due within 72 hours of the current market snapshot. Futures priced a 70% chance of a 25-basis-point hike as of September 10, up sharply from 52.2% a month earlier, undercutting the rate-cut narrative many crypto traders had been positioned for. More on how that repricing is showing up in options and futures markets is available via Cryptonews’ coverage of Fed-hike odds on Kalshi.
Earn $50 and Enter $300K Prize Draw on EdgeX
What the Leverage Reset Proves?
The 43,346 BTC drop in open interest happened before the catalysts, not after them, which is the structural detail that matters. Traders concluded the risk tied to two binary events couldn’t be adequately managed with leverage on, so they cut it proactively rather than getting forced out by a drawdown.
The spot side tells a related story. BlackRock’s iShares Bitcoin Trust recorded $19.23 million in redemptions on September 11, or the largest single-day outflow among U.S. spot Bitcoin ETFs that day, though barely 0.03% of IBIT’s reported $60.6 billion in assets. Earlier reporting on daily flow swings around this period underscores how concentrated the U.S. ETF market has become around a single vehicle.

That concentration is precisely why redemptions carry more weight than they did in 2024: ETF outflows convert into spot sales, and against a thinner free float, those sales move the price more.
It’s worth remembering the mechanism cuts both ways; three weeks of August inflows totaling $3.8 billion pushed Bitcoin from roughly $63,000 to $81,700, a rally built on the same structural sensitivity now working in reverse.
Trade Ethereum on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
$76,000-$77,000: The Next Technical Test for Bitcoin Price

The technical picture is split. TradingView’s weekly overview still reads buy, with long-term indicators intact, even as short-term sub-gauges sit neutral. InvestTech’s algorithmic overall read is a hold, but its one-to-six-week recommendation is negative, flagging a breakdown from a horizontal channel and a test of support near $77,200.
Our negative near-term signal centers on $76,500 as the level whose decisive breach would reinforce further downside, while the opposite side of that formation would flip the signal positive. In short, the weekly trend is still constructive, but the tape immediately in front of the CLARITY vote and the Fed decision is not.
On-chain analyst Garrett Jin has put a 70% probability on $60,000 marking the cycle bottom, which would place the current consolidation less than halfway. What’s clearer is the positioning itself: leverage has been cut, ETF-linked spot exposure has been trimmed, and capital reserves have been built for either direction.
Crypto markets are structured to absorb the outcome of this week’s votes and decisions, not to predict them.
Discover: The Best Token Presales
The post Bitcoin Price Wobbles as Leverage Falls Ahead of CLARITY Vote and Fed Decision appeared first on Cryptonews.
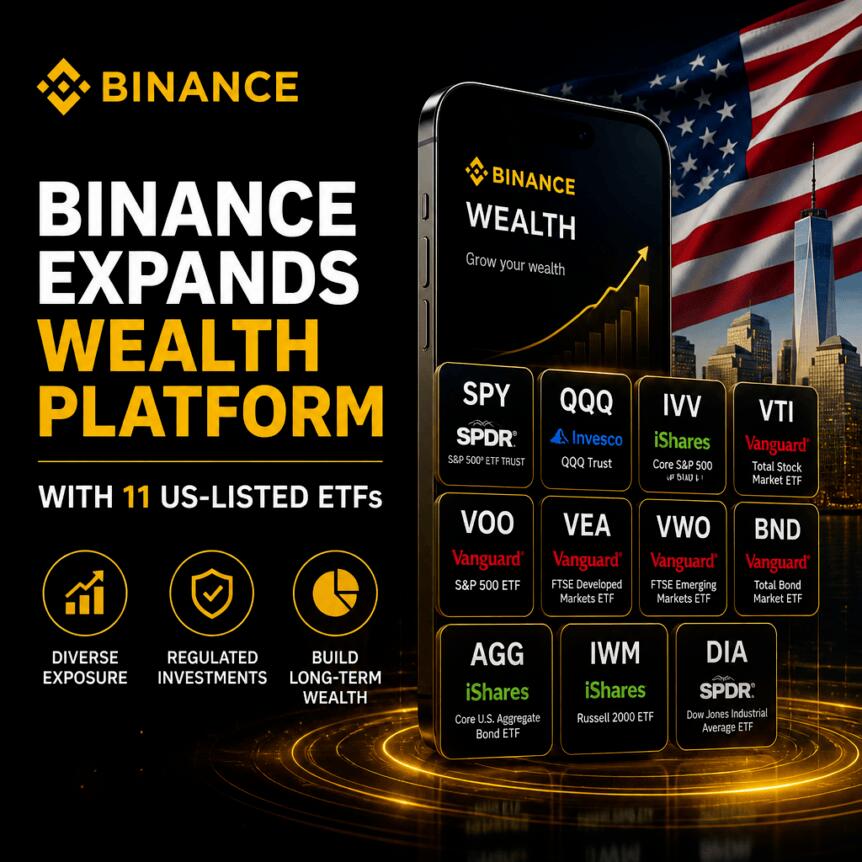
Binance has rolled out a new “Binance Earn” wealth management service that lets users access 11 U.S.-listed exchange-traded funds tied to short-term U.S. Treasurys and investment-grade bonds.
The offering is positioned as a way for crypto platform users to manage traditional portfolio exposure without leaving the Binance interface, with the ETFs grouped by different time horizons—from under six months to more than a year—covering what Binance describes as cash management, steady income, and yield-enhancement strategies.
Key takeaways
- Binance Earn now provides access to 11 U.S.-listed ETFs focused on short-term Treasurys and investment-grade bonds.
- The ETFs are organized by investment horizon, ranging from less than six months to more than a year.
- Users buy actual ETF shares via Binance Earn—unlike tokenized stock or ETF products where exposure is packaged differently.
- Binance says the economic benefits of the ETF shares, including price movement and cash distributions, pass through to investors.
- Orders are processed through Binance’s stock trading infrastructure and routed to a brokerage execution setup involving Nest Trading and Alpaca Securities.
How Binance Earn packages ETF exposure
Binance says investors can browse the ETF lineup within Binance Earn and place orders directly through the platform. Purchases are processed through Binance’s stock trading service, with Binance stating that users receive the economic benefits of the ETF shares, including both price changes and cash distributions.
A notable distinction in Binance’s structure is that users are not buying tokenized representations of equities or ETFs. Instead, they purchase real ETF shares through the service, with Binance providing the user-facing interface.
The TradFi plumbing behind the interface
Under the hood, Binance’s ETF access relies on conventional brokerage infrastructure. The arrangement routes orders through Nest Trading to Alpaca Securities, which executes trades and holds the securities.
For traders and investors, this matters because the service is designed to function like a bridge between two worlds: the familiar Binance user experience on one side, and established market plumbing for settlement and custody on the other. The objective is less about reinventing how ETF ownership works and more about expanding where investors can find it.
Binance expands its TradFi footprint
This ETF launch is presented as part of Binance’s broader expansion into traditional finance (“TradFi”). Earlier in the month, the exchange added physically settled options on more than 1,000 U.S. stocks and ETFs, building on an existing equities offering that includes over 7,000 U.S. stocks and ETFs.
Taken together, the ETF suite suggests Binance is broadening beyond spot trading and toward a wider set of portfolio tools—effectively moving from single-asset trading experiences toward longer-duration investment products that many users associate with brokerage platforms.
What investors should watch next
Binance is betting that crypto-native distribution can lower friction for accessing traditional investment instruments—especially in areas like short-duration rates exposure. A PwC survey cited by the company’s broader ETF discussion indicates that many industry participants expect tokenization to increase ETF reach and improve 24/7 accessibility over the next three years, though Binance Earn in this case is explicitly based on buying actual ETF shares rather than tokenized products.
For users, the key open questions are likely to be practical: how Binance Earn’s ETF lineup evolves, how investors should think about liquidity and execution quality within the integrated stock trading flow, and whether Binance will expand beyond fixed income-focused products as it continues building out its TradFi catalog.
As the service scales, readers should keep an eye on whether Binance Earn adds more ETF strategies beyond short-term Treasurys and investment-grade bonds, and how the platform’s TradFi integrations develop—particularly around product breadth, order routing, and the user experience for managing traditional holdings alongside crypto.

Ovechkin breaks NHL goal record but Putin link casts shadow

Kevin O’Leary: Crypto Is About to Roll Right Over Traditional Banking
LA helicopter crash live: One dead as chopper ‘goes down’ in Chatsworth

Memory prices are slowing because buyers ran out of money

Weekend Open Thread – Corporette.com

Micron Stock Climbs Above $1,031 as AI Memory Crunch and a $50 Billion Outlook Fuel the Rally
Kevin O’Leary: Crypto Is About to Roll Right Over Traditional Banking

You Won’t Believe This Report… Ripple XRP, Stellar Lumens XLM, Hedera HBAR, Quant QNT Chosen!!!!!!

If you don’t understand these money laws, you’ll never be rich
-
 Fashion4 days ago
Weekend Open Thread – Corporette.com
-
 Business6 days ago
Micron Stock Climbs Above $1,031 as AI Memory Crunch and a $50 Billion Outlook Fuel the Rally
-

 Tech3 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Business6 days ago
AMD Stock Climbs After Management Lifts 2027 Data Center Outlook Toward $70 Billion in AI Sales
-

 Crypto World5 days ago
XAG/USD: Silver’s Short-Term Rally Meets Its Moment of Truth
-

 Business5 days ago
10 Most-Streamed Songs On Spotify In 2026 So Far, Led By Ella Langley’s Dominant Run On The Charts This Year
-

 Crypto World6 days ago
2 Chip Stocks Broke Out This Week. Neither Was Nvidia
-
 Crypto World6 days ago
Pi Network ships Protocol 27 on a network with 14 million users and zero DeFi
-

 Tech5 days ago
Battery life is the only iPhone 18 Pro and iPhone Duo upgrade I care about. Apple didn’t disappoint
-

 Crypto World5 days ago
Diesel Tops $6 a Gallon for the First Time as 28 States Set Records
-

 Crypto World5 days ago
OKX launches 10x OpenAI, Anthropic X-Perps in Europe
-

 Tech6 days ago
Apple Watch Ultra 4 vs Watch Ultra 3: Should you really spend another $799?
-

 News Videos5 days ago
Facing Financial Fears
-
 Tech7 days ago
Modders have already found two ways to make DLSS 5 playable, and neither one is Nvidia’s
-

 Crypto World6 days ago
Bitcoin price risks $70K if $78K neckline breaks
-
 Crypto World7 days ago
Bitcoin price holds near $79K as cycle drawdowns narrow
-
 Entertainment6 days ago
Case Sees Major Update As Jury Deliberations Begin
-
 Business7 days ago
Meta debuts long-awaited personal AI agent, Muse
-

 Crypto World2 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-
Crypto World5 days ago
Ethereum Price Analysis: Consolidation at $2.5K Tests Momentum as On-Chain Activity Surges
You must be logged in to post a comment Login