
Crypto World
Cencora (COR) Raised Guidance and Bought Back $1B. What’s the Catch?

On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.

Profits Are Outrunning Sales
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
The Bill Behind the Growth
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.


Dear Quentin,
My husband, 59, and I, 55, are planning to retire over the next few years, and this is one of the biggest unknowns I’m struggling with. My mom had Alzheimer’s disease and spent seven years in a really nice memory-care facility in a smaller town. It cost about $7,000 a month. Thankfully, my parents had purchased long-term-care insurance and had paid premiums for about 12 years.
My dad died shortly after being diagnosed with cancer, so his policy was never used. But my mom’s policy ended up being worth its weight in gold. It essentially covered all of her care. By the time my mother died, the insurance company had paid out almost $600,000. We only paid about $100 a month for some extras. Needless to say, that experience has made me think.
Most Read from MarketWatch
I’ve looked into long-term-care insurance, but the premiums are so incredibly expensive, and I worry about what they’ll cost by the time it makes sense for me to seriously consider a policy. We’re fortunate financially. After 35 years in the corporate grind, we’ll have substantial retirement savings; we’ve always saved carefully; and we have no debt or mortgage.
I also genuinely love my job, so I’m perfectly happy to work longer if that makes sense. What I really don’t want is to leave our two kids with a huge financial burden someday if one or both of us need years of expensive care. Do I self-insure? Buy long-term-care insurance? Use some combination of investments and insurance? Are there good retirement-planning tools?
I know Medicare is part of the equation, but I’d like more control over our options than simply hoping it will be enough. I’m doing everything I can on the preventative-care and healthy-lifestyle front, but unfortunately there are no guarantees. Right now, my strategy is to save as much as humanly possible and hope for the best.
If you have a crystal ball that will tell me I will need memory care in old age, please share.
In My Fifties
Don’t miss: ‘We fear financial exploitation’: Who will manage our finances if my wife and I become incapacitated?

Dear Fifties,
Your 50s are actually not a bad time to take out long-term care insurance.
Financially speaking, given your age, you’re not too young and you’re not too old. Yes, you probably would have spent less on monthly premiums had you taken out this insurance policy in your 40s, but you would also have been paying it for a decade. It’s hard to predict the future and get that perfect balance. If your mother had Alzheimer’s, your own risk is higher than average from a statistical point of view, although that does not mean that you will develop the disease.

Zcash (ZEC) has climbed 177.8% in a month, and the traders betting against it are paying for that move.
One short was closed at a $10.68 million loss this week, and the largest position still open sits $33.87 million underwater on Hyperliquid.
Zcash Shorts Collapse as the Token Jumps 177% in a Month
Lookonchain flagged the closed trade before the exit, citing 26 consecutive wins and an 89% rate across 47 trades. That record had produced more than $9 million in profit.
The short covered 12,285 ZEC and was worth $18.31 million earlier, with liquidation set at $1,550.66. Hyperliquid data shows the account now holds no positions at all.
Garrett Jin holds the largest short still open, covering 37,999 ZEC worth $59.37 million. He built the position at an average price of $671.05, so it now shows an unrealized loss of $33.87 million.
His 1,333 BTC long is up $4.41 million, which cushions part of the damage. Jin still has room, because his liquidation price of $4,789.42 sits above the 2016 record of $3,191.93.
Other addresses are also seeing sharp losses. One account (0xdd53…2b13) is down $12.53 million on a 13,487 ZEC short opened at $644.39. Another (0xad59…ba81) shorted 8,425 ZEC at $330.91 with 10 times leverage and now sits $10.47 million underwater.
Follow us on X to get the latest news as it happens
Spot Buyers, ETF Flows and One Very Loud Timeline
The rally that caused the damage has made ZEC the strongest performer among the 10 largest cryptocurrencies. The token trades near $1,563 and ranks ninth by market value at $26.47 billion.

The move has real buying behind it from both retail whales and institutions. Lookonchain reported that one address withdrew 15,860 ZEC worth $22.69 million from Binance in a day. Another moved 7,081 ZEC over two days.
Institutional buying has moved in the same direction Zcash ETFs took in $98.2 million in the week ending September 18, the largest inflow among 14 products. Assets rose 40.5% to $914.5 million.
Attention has followed the price. Santiment recorded Zcash social volume at a one-month high on September 17. Mentions on X ran 6.8 times their 29-day baseline, against 1.7 times elsewhere.
“The price found buyers. The attention found one timeline,” the post read.
Traders now watch whether spot demand holds. Open interest in ZEC perpetuals on Hyperliquid stands at 574,045 ZEC, worth roughly $885 million, so leveraged positions remain large on both sides.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights
https://youtu.be/7Hf8KSxNICQ
Read the Original story Trader With 89% Win Rate Loses $10.68 Million Shorting Zcash by Kamina Bashir at beincrypto.com
Anthropic’s initial public offering (IPO), expected no earlier than mid-October, will be a test of just how hungry the financial markets still are for exposure to artificial intelligence (AI). The S&P 500 (SNPINDEX: ^GSPC) is going to react depending on how that test goes. Its backers want a valuation of $2 trillion or more, which would top Space Exploration Technologies as the biggest IPO ever if it happens.
Don’t expect S&P 500 funds to buy it immediately, though. The road for Anthropic entering the S&P 500 is going to be slow, and it could test some nerves along the way.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »

Anthropic can’t join the S&P 500 for at least 12 months
By definition, index funds tracking the S&P 500 must buy whatever the S&P 500 adds to its list of stocks.
Anthropic probably won’t get special treatment, given that on June 4, S&P Dow Jones Indices declined to loosen its rules for mega-cap listings. Those rules still require 12 months as a public company, at least 10% of shares being publicly held, and reported positive earnings under generally accepted accounting principles (GAAP).
While SpaceX joined the Nasdaq-100 list of stocks within weeks of its June 2026 IPO, it still needs to wait outside the S&P 500. If Anthropic has its offering in late 2026 as planned, its earliest shot at inclusion in the S&P 500 will occur in late 2027.
Nonetheless, two of the index’s largest companies already own Anthropic, which means that holders of the index funds have some exposure already as well. For instance, Amazon reported $16.8 billion of pretax gains on its Anthropic position in the first quarter of 2026. Alphabet also has a stake in Anthropic, so a strong debut could boost it and Amazon.
Should you expect a slump after the Anthropic IPO?
Per finance professor Jay Ritter at the University of Florida, across 9,343 U.S. IPOs from 1980 to 2025, the average first-day gain was 19%. The pain came later. Measured from their first close, IPOs from 2012 to 2024 underperformed the market by 25.5% over three years, on average.
SpaceX shows how bumpy the ride can get. It priced its June 2026 IPO at $135. It then jumped to $225.64 before falling to $104.83, and was $151.10 on Sept. 16. That peak-to-trough plunge was probably quite frustrating for its shareholders.
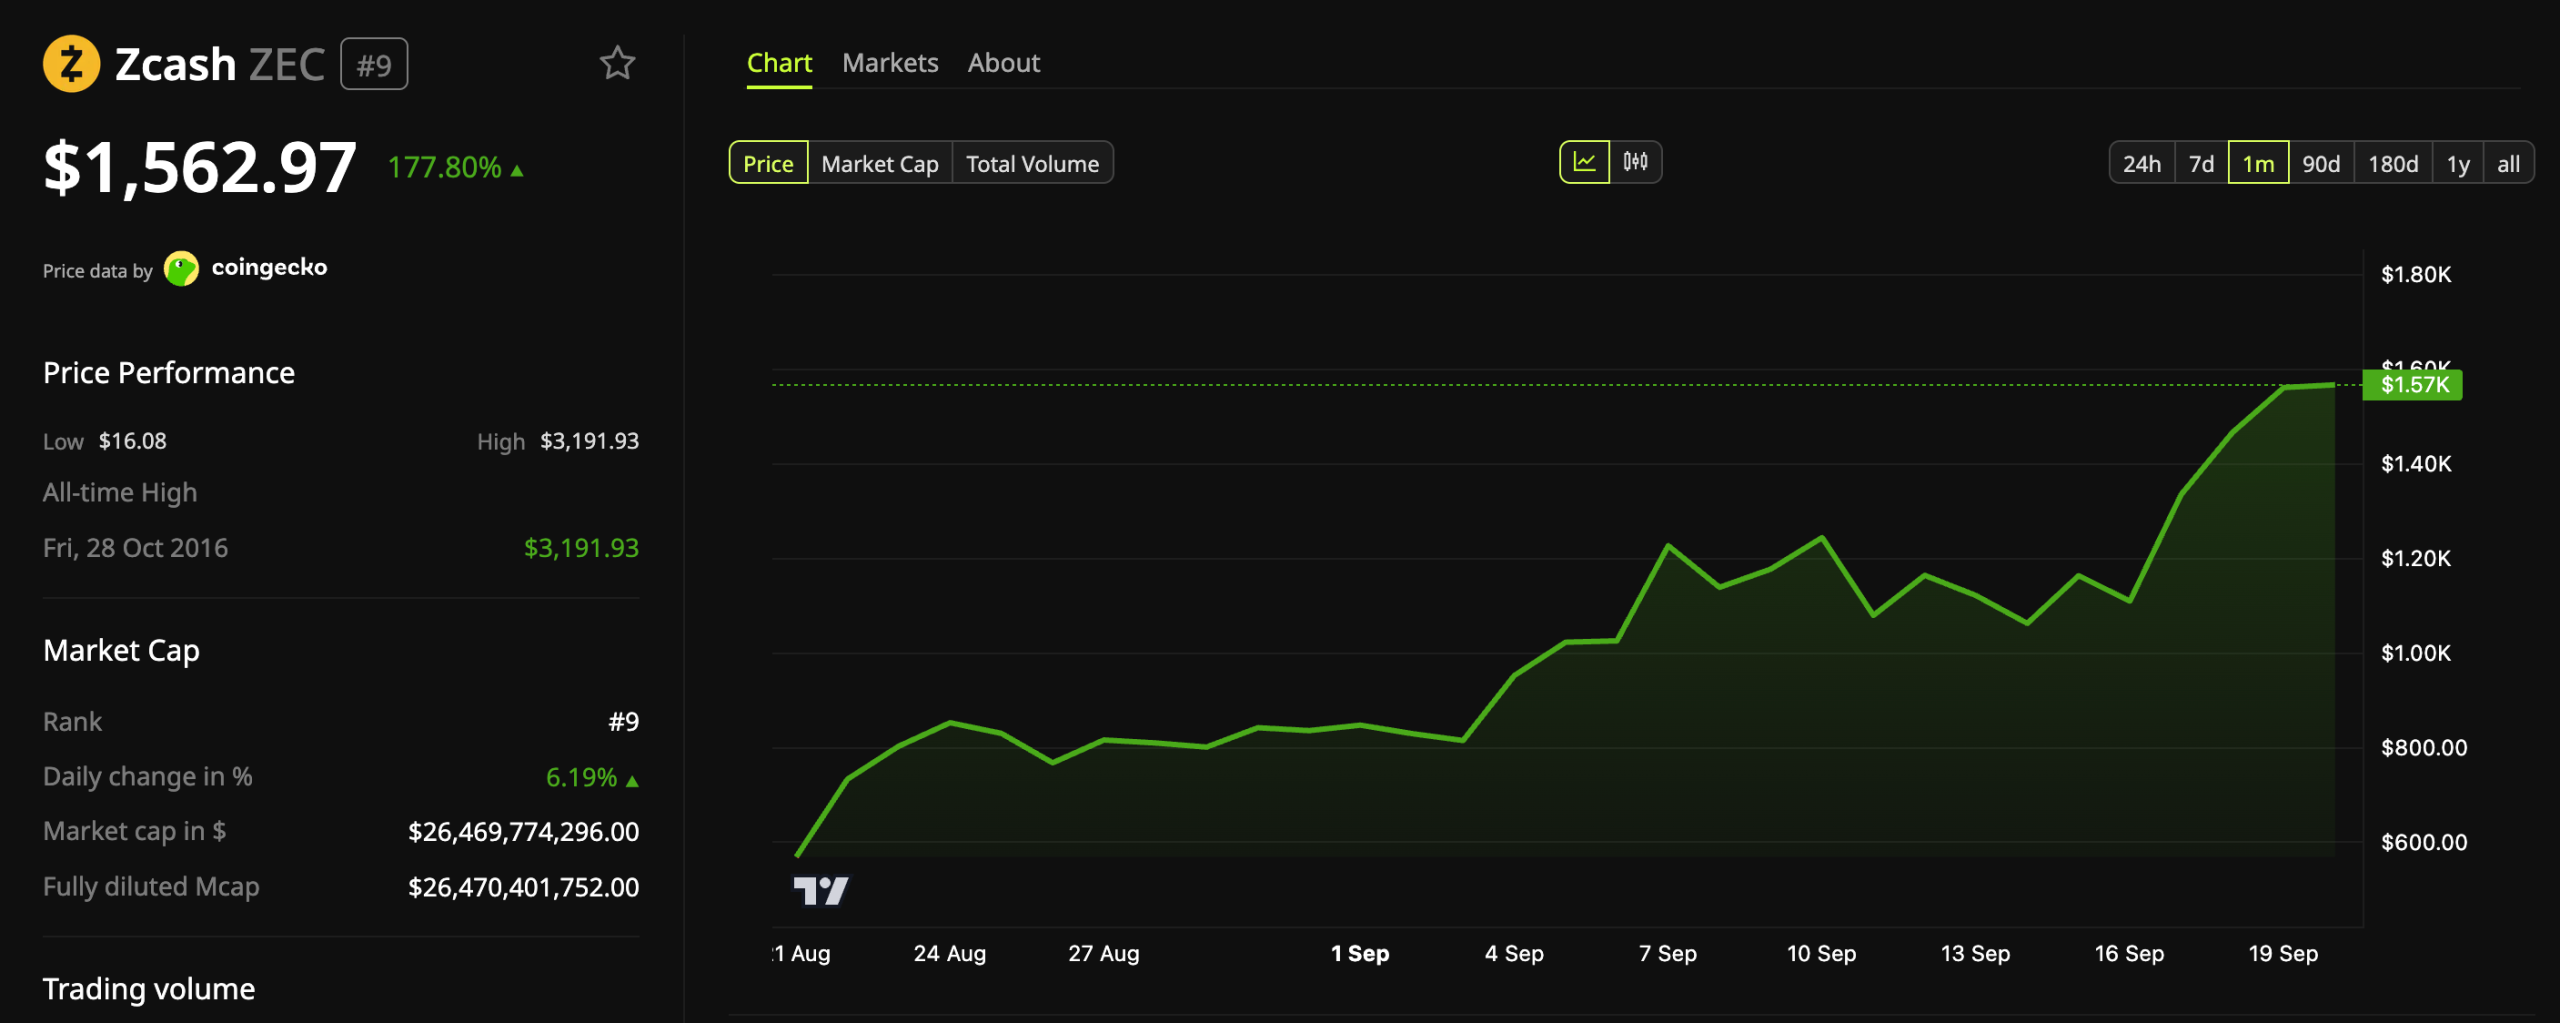
Zcash (ZEC) has climbed 177.8% in a month, and the traders betting against it are paying for that move.
One short was closed at a $10.68 million loss this week, and the largest position still open sits $33.87 million underwater on Hyperliquid.
Zcash Shorts Collapse as the Token Jumps 177% in a Month
Lookonchain flagged the closed trade before the exit, citing 26 consecutive wins and an 89% rate across 47 trades. That record had produced more than $9 million in profit.
The short covered 12,285 ZEC and was worth $18.31 million earlier, with liquidation set at $1,550.66. Hyperliquid data shows the account now holds no positions at all.
Garrett Jin holds the largest short still open, covering 37,999 ZEC worth $59.37 million. He built the position at an average price of $671.05, so it now shows an unrealized loss of $33.87 million.
His 1,333 BTC long is up $4.41 million, which cushions part of the damage. Jin still has room, because his liquidation price of $4,789.42 sits above the 2016 record of $3,191.93.
Other addresses are also seeing sharp losses. One account (0xdd53…2b13) is down $12.53 million on a 13,487 ZEC short opened at $644.39. Another (0xad59…ba81) shorted 8,425 ZEC at $330.91 with 10 times leverage and now sits $10.47 million underwater.
Follow us on X to get the latest news as it happens
Spot Buyers, ETF Flows and One Very Loud Timeline
The rally that caused the damage has made ZEC the strongest performer among the 10 largest cryptocurrencies. The token trades near $1,563 and ranks ninth by market value at $26.47 billion.

The move has real buying behind it from both retail whales and institutions. Lookonchain reported that one address withdrew 15,860 ZEC worth $22.69 million from Binance in a day. Another moved 7,081 ZEC over two days.
Institutional buying has moved in the same direction Zcash ETFs took in $98.2 million in the week ending September 18, the largest inflow among 14 products. Assets rose 40.5% to $914.5 million.
Attention has followed the price. Santiment recorded Zcash social volume at a one-month high on September 17. Mentions on X ran 6.8 times their 29-day baseline, against 1.7 times elsewhere.
“The price found buyers. The attention found one timeline,” the post read.
Traders now watch whether spot demand holds. Open interest in ZEC perpetuals on Hyperliquid stands at 574,045 ZEC, worth roughly $885 million, so leveraged positions remain large on both sides.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights
The post Trader With 89% Win Rate Loses $10.68 Million Shorting Zcash appeared first on BeInCrypto.
Crypto World
Schwab Treasury ETF vs SPDR Corporate Bond ETF. Which Bond Fund Is the Better Insurance Policy for Your Portfolio?
Bonds should be an essential part of a well-balanced portfolio. Factual differences between the Schwab Long-Term U.S. Treasury ETF (NYSEMKT:SCHQ) and the State Street SPDR Portfolio Long Term Corporate Bond ETF (NYSEMKT:SPLB) center on credit quality, as the Schwab fund tracks government debt while the State Street fund targets investment-grade corporate bonds.
Investors seeking exposure to long-dated fixed income typically choose between government-backed securities and corporate credit. While both funds focus on maturities exceeding 10 years, they offer significantly different risk-reward profiles based on their underlying debt issuers and the credit risk investors are willing to accept for higher income.
Snapshot (cost & size)
Beta measures price volatility relative to the S&P 500; beta is calculated from monthly returns over the available fund history (up to five years). The 1-yr return represents total return over the trailing 12 months. Dividend yield is the trailing-12-month distribution yield as of the end of trading on Sept. 10, 2026.
The Schwab fund is slightly more affordable with a 0.03% expense ratio compared to 0.04% for the SPDR fund. However, those seeking income may find the higher 5.7% yield of the corporate-focused portfolio more attractive.
Performance & risk comparison
What’s inside
The Schwab Long-Term U.S. Treasury ETF is a fixed-income fund that provides exposure to the long-duration segment of the U.S. Treasury bond market. It currently holds 102 positions, focusing on government debt with maturities that often exceed 20 years. Because it holds government-backed securities, its credit risk is generally lower than corporate bond alternatives. Its largest positions include a highly diversified selection of Treasuries where no single position is a sizable portion of the portfolio. The fund was launched in 2019. Schwab Long-Term U.S. Treasury ETF has paid $1.47 per share over the trailing 12 months, which on its recent ~$29.44 share price works out to a 5% yield.
The State Street SPDR Portfolio Long Term Corporate Bond ETF tracks the Bloomberg U.S. Long Term Corporate Bond Index and holds 2,950 positions. It invests in U.S. dollar-denominated, fixed-rate, investment-grade corporate bonds with maturities of at least 10 years. This fund offers higher income potential by taking on the credit risk associated with private corporations. Its largest positions include a highly diversified array of corporate issues, with no single position exceeding 0.35% of the portfolio. The fund was launched in 2009. State Street SPDR Portfolio Long Term Corporate Bond ETF has paid $1.20 per share over the trailing 12 months, which on its recent ~$21.03 share price works out to a 5.7% yield.
The concern extends to banks. Van der Chijs believes AI could expose vulnerabilities in legacy banking software, threatening confidence in institutions that depend on interconnected systems. Within crypto, he sees exchanges and other businesses built around bitcoin as more vulnerable than the underlying network.
His concerns have not displaced an expansive view of AI’s economic potential. He predicts AI and robotics could eventually perform 90% to 95% of existing jobs, while driving sharp declines in the cost of goods and services.
In that scenario, governments would need new sources of revenue as employment changes. He suggested taxes on robots or AI token usage, while acknowledging that locally run models would complicate collection.
His own portfolio has already followed the technology’s rise.
“I sold a lot of my bitcoin. I went into AI,” he said.
Van der Chijs believes that investors redirecting capital toward AI helped keep bitcoin below the $200,000 to $250,000 levels he and others had anticipated. He is now allocating some AI profits back into crypto, primarily through exchange-traded funds.
He also sees a stronger business case for AI infrastructure than for bitcoin mining. Speaking in a personal capacity, he described Hut 8’s move into AI as “the best move ever” and said that, if he were running the company today, he would favor allocating entirely to AI data centers.
The upcoming Batch V1.1 can make linked asset and payment transfers succeed together or fail together, and Ripple says commercial projects are already being built around the feature after an extensive security review.
Robinhood leads this week’s list of stocks to watch, as shares rallied above a buy zone Friday following positive regulatory developments from the SEC and CFTC earlier in the week. SpaceX on Friday won a NASA contract worth nearly $1 billion, while SPCX stock continues to test an aggressive early entry above its IPO debut price. Top IBD picks NetApp,…
Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8
Bill Ackman’s Pershing Square Inc., a recent IPO, broke out past a buy point Friday in a rocky market. The hedge fund billionaire’s publicly traded investment vehicle, Pershing Square Inc. (PS), rallied an impressive 27% for the week after bullish analyst upgrades. In recent weeks, several Wall Street firms hiked price targets on PS stock. Among them, Tigress Financial analyst…
Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8
Stablecoin infrastructure provider Bastion says the U.S. Office of the Comptroller of the Currency (OCC) has granted it preliminary conditional approval for a U.S. trust bank charter. The development would place Bastion’s operations under federal oversight in addition to the state-level licenses it already holds, according to a company announcement issued Friday.
While the charter would strengthen Bastion’s regulatory standing, the proposal also clarifies what the entity would not be allowed to do: the chartered trust bank could not accept deposits or make loans. That limitation keeps the structure closer to a regulated custody and payments utility than a traditional commercial bank.
Key takeaways
- Bastion received preliminary conditional approval from the OCC for a U.S. trust bank charter, adding federal supervision to its existing state licensing.
- The charter would allow Bastion to operate as a federally regulated entity for stablecoin custody, wallet services, payments infrastructure, and white-label issuance.
- The approved trust bank would not be permitted to accept deposits or make loans, distinguishing it from conventional commercial banking.
- Bastion has been positioning for federal oversight since acquiring its New York trust charter in February 2025.
What Bastion’s conditional charter would change
The OCC approval is described by Bastion as “preliminary” and “conditional,” which typically means the process is not yet complete. Still, the company frames the move as a step toward more robust governance and regulatory rigor—an increasingly common theme in the stablecoin sector as regulators focus on how reserve-backed tokens are handled and controlled.
In its announcement, Bastion says the OCC’s role would overlay federal supervision on top of the state licenses it already holds. For customers and business partners, that matters because stablecoin services frequently sit at the intersection of asset custody, payment rails, and operational controls—areas where regulators often expect tighter, standardized oversight than state frameworks alone may provide.
At the same time, the entity described in the filing is not set up to function like a full-service bank. Bastion says the proposed trust bank could not accept deposits or extend loans. That delineation suggests the charter is meant to enhance the reliability of custody and issuance-related activities rather than broaden into retail or credit products.
A single regulated platform for stablecoin operations
Bastion plans to be licensed as Bastion Platforms National Trust Company. If the charter process reaches final approval, that federally regulated entity would support a range of stablecoin-focused services, including:
- Stablecoin custody and wallet solutions
- Payment infrastructure
- White-label stablecoin issuance
The “single entity” approach is particularly relevant for stablecoin ecosystems, where infrastructure providers often coordinate multiple functions—holding assets, managing keys, enabling transfers, and facilitating issuance. Moving more of that stack under one federally regulated umbrella can simplify compliance expectations for counterparties and reduce the number of operational handoffs involved in moving value.
Bastion’s CEO Nassim Eddequiouaq said stablecoins have shifted from emerging technology to “core financial infrastructure,” arguing that this requires “a different standard of trust, governance and regulatory rigor.”
How Bastion is preparing for federal oversight
Bastion says it has been working toward federal supervision since acquiring its New York trust charter in February 2025. That timing suggests the company’s current OCC step is part of a longer regulatory build rather than a sudden pivot.
The company’s prior funding also reflects investor interest in stablecoin rails infrastructure. In September 2025, Cointelegraph reported that Bastion raised $14.6 million in a funding round led by Coinbase Ventures, with participation from Sony, the investment subsidiary of South Korean phone maker Samsung, the crypto arm of Andreessen Horowitz, and crypto VC firm Hashed.
While that earlier round does not determine regulatory outcomes, it does indicate that market participants have been backing stablecoin infrastructure providers that aim to operate closer to regulated financial institutions—an approach that is increasingly attractive as stablecoin adoption grows and compliance requirements tighten.
Bank-charter momentum across crypto infrastructure
Bastion’s OCC progress comes amid a broader wave of interest from crypto companies seeking U.S. banking or trust-charter pathways for digital-asset services.
Cointelegraph has reported that Ripple received conditional approval for a similar charter. Separately, Cointelegraph notes that Circle and BitGo have received final approval for their respective national trust bank outcomes—highlighted in Circle’s coverage and in BitGo’s company release stating that it “became the first public federally chartered digital asset infrastructure company” (as referenced in the source material).
Cointelegraph also reported that several other crypto-related firms have applied for charter pathways, including Kraken parent Payward, Zerohash, and Block.
For investors and operators, this clustering of applications matters because it signals a common strategy: moving stablecoin and digital-asset services from loosely defined infrastructure into regulated frameworks that can support more mainstream financial integration. The critical difference between each case will likely be the boundaries of allowed activities—such as custody versus deposit-taking—along with how regulators assess governance, controls, and operational readiness.
In Bastion’s case, the reported inability of the proposed trust bank to accept deposits or make loans sets a clear scope: the charter is aimed at custody, wallets, payment infrastructure, and issuance rather than traditional banking products.
What to watch next
The next milestone is whether Bastion’s OCC process moves from preliminary conditional approval to a final charter—and, if so, what specific operating conditions accompany approval. For the broader market, outcomes in similar U.S. trust bank applications will likely shape how quickly stablecoin infrastructure providers can consolidate services under federally supervised structures and how confidently regulated institutions can partner with them.

PARKOUR VS MONEY HEIST 27!
Albert Bartlett hailed by council for backing North Lanarkshire Half Marathon

SLM: Student Loan Giant Keeps Growing Its Loan Book While Covering Dividends Well




-
 Fashion21 hours ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech6 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Crypto World5 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-

 Crypto World4 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-

 Crypto World3 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World5 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-

 Crypto World5 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-

 Business6 days ago
Rivals Sam Altman and Elon Musk Rally Behind Dario Amodei’s Call for a Slowdown in AI Development
-

 Crypto World6 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-
 NewsBeat5 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-
 Crypto World4 days ago
Robinhood engineers charged over $50K crypto scheme
-

 Crypto World4 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-
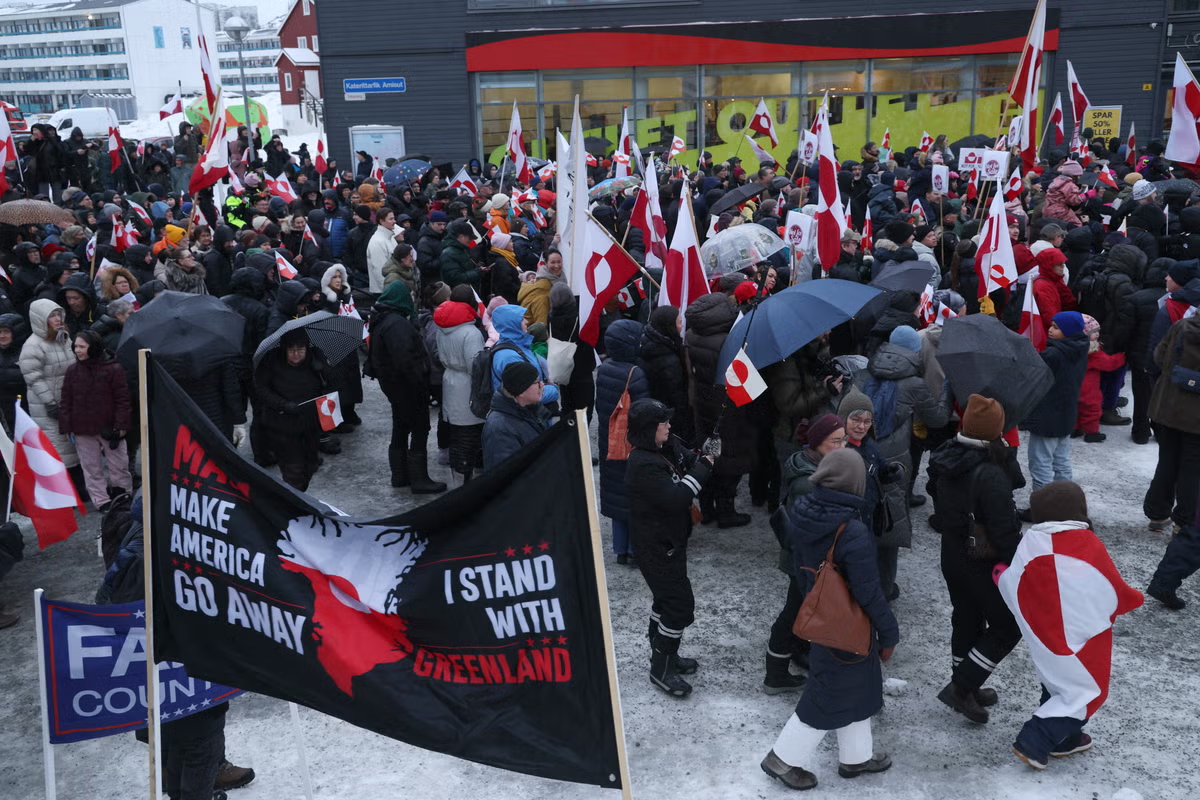 NewsBeat16 hours ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-
Business5 days ago
SK Hynix ADRs Fall More Than 6% as Memory Rally Breaks on Fears of Slower AI Spending
-

 Crypto World5 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
-
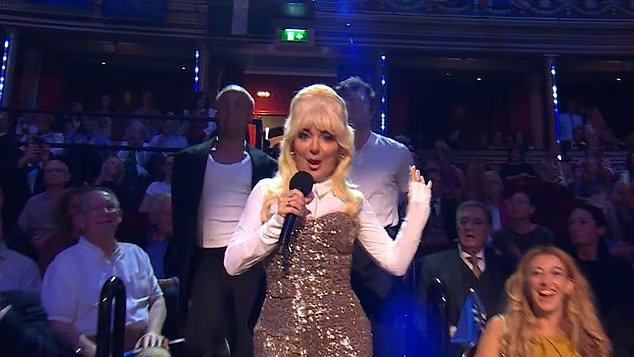 NewsBeat6 days ago
Last Night of the Proms pays moving tribute to Dolly Parton as Sheridan Smith wears a gold sequin jumpsuit in memory of the Queen of Country
-
Crypto World5 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
-
 Crypto World6 days ago
Goldman Sachs backs 25bp Fed hike after CPI
-

 Crypto World5 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-
 Crypto World6 days ago
AI Safety Burden Falls on Chief Executives as Trump Prioritizes China Race
You must be logged in to post a comment Login