
Crypto World
Trader With 89% Win Rate Loses $10.68 Million Shorting Zcash

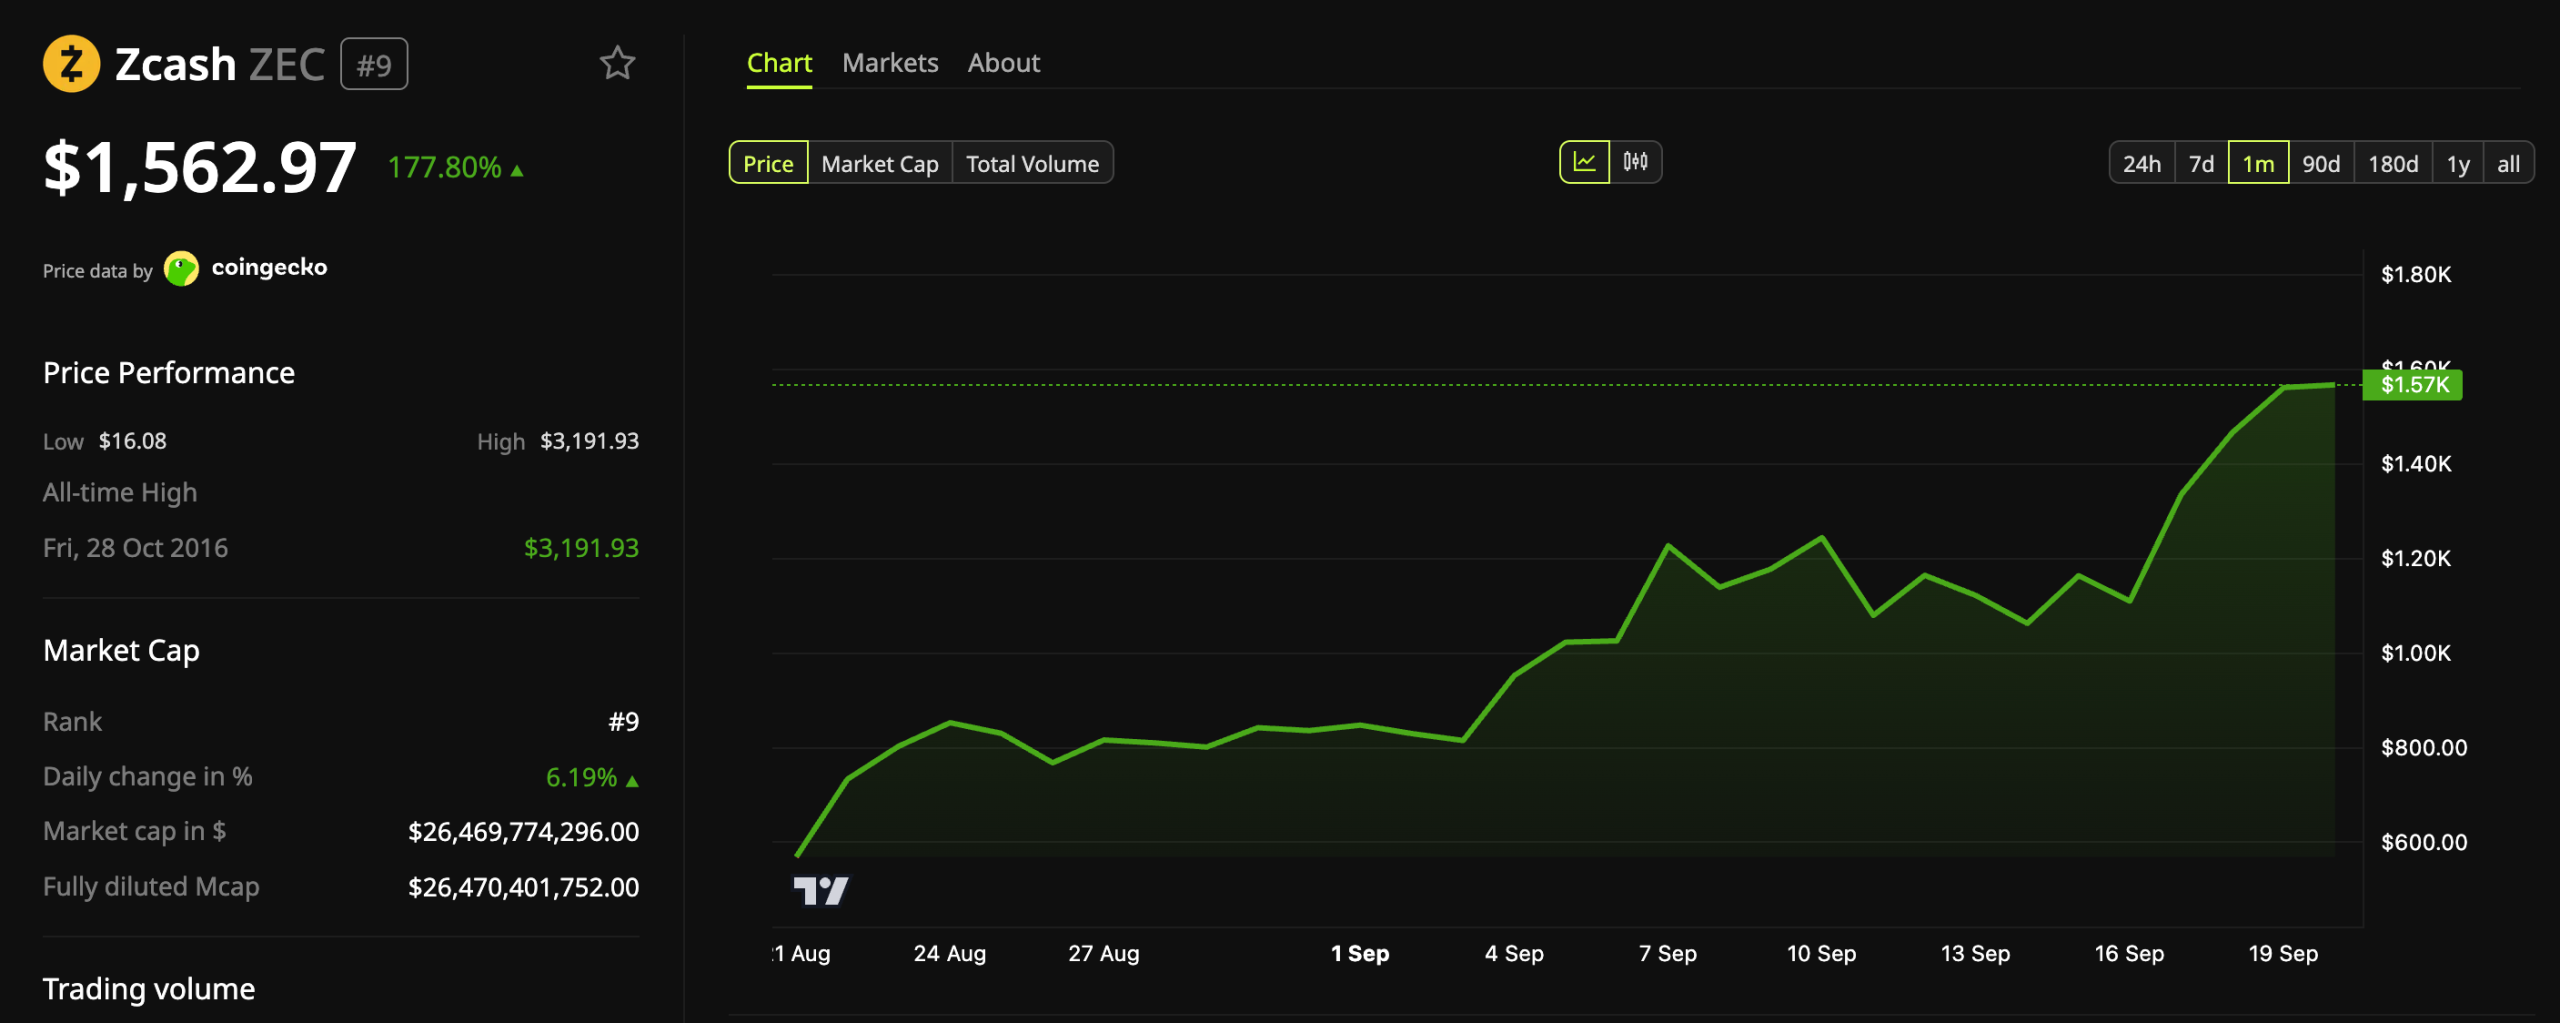
Zcash (ZEC) has climbed 177.8% in a month, and the traders betting against it are paying for that move.
One short was closed at a $10.68 million loss this week, and the largest position still open sits $33.87 million underwater on Hyperliquid.
Zcash Shorts Collapse as the Token Jumps 177% in a Month
Lookonchain flagged the closed trade before the exit, citing 26 consecutive wins and an 89% rate across 47 trades. That record had produced more than $9 million in profit.
The short covered 12,285 ZEC and was worth $18.31 million earlier, with liquidation set at $1,550.66. Hyperliquid data shows the account now holds no positions at all.
Garrett Jin holds the largest short still open, covering 37,999 ZEC worth $59.37 million. He built the position at an average price of $671.05, so it now shows an unrealized loss of $33.87 million.
His 1,333 BTC long is up $4.41 million, which cushions part of the damage. Jin still has room, because his liquidation price of $4,789.42 sits above the 2016 record of $3,191.93.
Other addresses are also seeing sharp losses. One account (0xdd53…2b13) is down $12.53 million on a 13,487 ZEC short opened at $644.39. Another (0xad59…ba81) shorted 8,425 ZEC at $330.91 with 10 times leverage and now sits $10.47 million underwater.
Follow us on X to get the latest news as it happens
Spot Buyers, ETF Flows and One Very Loud Timeline
The rally that caused the damage has made ZEC the strongest performer among the 10 largest cryptocurrencies. The token trades near $1,563 and ranks ninth by market value at $26.47 billion.

The move has real buying behind it from both retail whales and institutions. Lookonchain reported that one address withdrew 15,860 ZEC worth $22.69 million from Binance in a day. Another moved 7,081 ZEC over two days.
Institutional buying has moved in the same direction Zcash ETFs took in $98.2 million in the week ending September 18, the largest inflow among 14 products. Assets rose 40.5% to $914.5 million.
Attention has followed the price. Santiment recorded Zcash social volume at a one-month high on September 17. Mentions on X ran 6.8 times their 29-day baseline, against 1.7 times elsewhere.
“The price found buyers. The attention found one timeline,” the post read.
Traders now watch whether spot demand holds. Open interest in ZEC perpetuals on Hyperliquid stands at 574,045 ZEC, worth roughly $885 million, so leveraged positions remain large on both sides.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights
The post Trader With 89% Win Rate Loses $10.68 Million Shorting Zcash appeared first on BeInCrypto.

Crypto World
There Are Only a Handful of Nasdaq-100 Stocks That Yield Over 3%. Here’s My Top Pick to Buy in September.
Most investors think of the Nasdaq-100 index as a tech index. That’s not unreasonable, given that 66% of the index is, indeed, in the technology sector. However, if you are looking for a high-yield stock, tech usually isn’t the place to look. Which is why my pick in September is from the just over 2% weighting in consumer staples companies.
PepsiCo (NASDAQ: PEP) has a yield of roughly 4.3%. For reference, the S&P 500 index (SNPINDEX: ^GSPC) yields only about 1%, while the average consumer staples stock yields roughly 2.1%. So that yield is attractive on both an absolute and a relative basis. Here’s a quick rundown on why PepsiCo’s yield is so high and why I bought it anyway.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »

PepsiCo isn’t hitting on all cylinders
In the second quarter of 2026, PepsiCo’s organic sales rose 2.4%. That’s actually not a terrible number for a consumer staples company, but it is less than half the 6% that Coca-Cola (NYSE: KO) achieved. Given that these two companies are key competitors in the beverage space, you can see why Wall Street isn’t happy with PepsiCo’s business results.
To be fair to PepsiCo, its business spans beverages, snacks, and packaged food products. So it is far more diversified than Coca-Cola. Right now, that’s a headwind, but I actually see the added diversification as a net positive. I believe it gives PepsiCo more levers for long-term growth.
But right now, consumer tastes are shifting. Some of that is related to a general increase in health consciousness. And some is tied to the development of GLP-1 weight-loss drugs, which are changing the way people eat. The why here is less important than the fact that there is a change. PepsiCo is aware of it and is working to update its brand portfolio. That takes time, and Wall Street is famously impatient, so the stock price has fallen. I think that’s an opportunity for long-term investors like me.
PepsiCo has dealt with change before
What’s important to remember right now is that consumer buying habits shift constantly. While the current change may feel dramatic, at least partly due to the impact of GLP-1 drugs, PepsiCo has adjusted its business many times over the past 54 years. Fifty-four may seem like an oddly specific number, but it really isn’t. It is the number of years that PepsiCo has increased its dividend.
Asset manager VanEck has criticized Metaplanet’s executive compensation structure, arguing that recent efforts by the Bitcoin treasury company to curb shareholder dilution still fall short of adequately aligning management with investors.
In a Friday report examining executive compensation across the 10 largest digital asset treasury companies, VanEck labeled Metaplanet’s compensation structure “Bad,” making it the only firm to fall into the lowest category. VanEck cited an equity plan equal to 14.7% of fully diluted shares and officer exposure of 8.2%.
VanEck said Metaplanet’s officer exposure is roughly 10 times the 0.8% average of the other nine companies analyzed, while its overall equity plan is nearly four times the peer average.
By comparison, Strategy, the largest corporate Bitcoin (BTC) holder, has an equity plan equal to 2% of fully diluted shares and officer exposure of 0.5%. VanEck rated its compensation structure “Good,” noting that its equity reserve is fixed and plan increases require a shareholder vote.
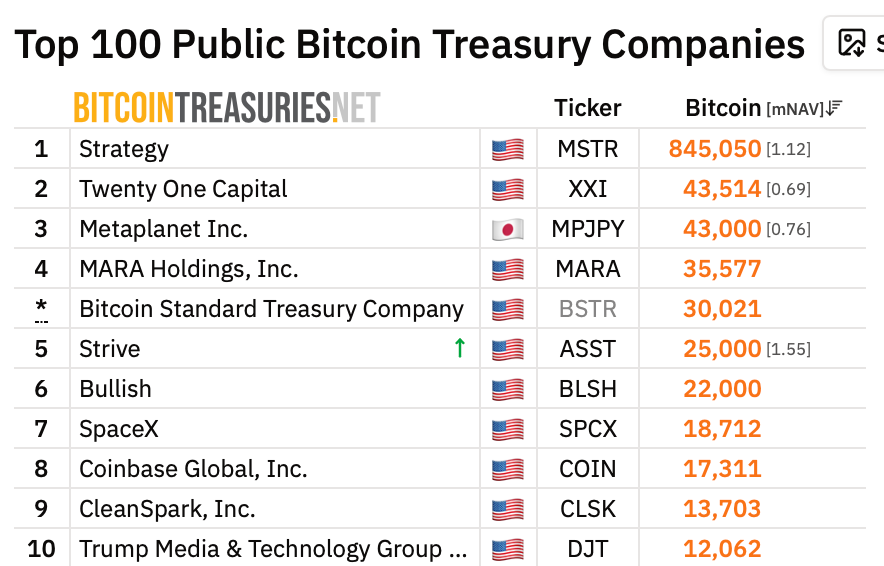
Metaplanet is a Japanese Bitcoin treasury company that currently ranks as the third-largest publicly traded corporate Bitcoin holder, with 43,000 BTC, according to BitcoinTreasuries.net.
Top 10 Bitcoin treasury companies. Source: BitcoinTreasuries.NET
Bitcoin purchases expanded executive option pool
VanEck said the disparity stems partly from Metaplanet’s former compensation structure, which allowed its option pool to expand automatically as the company issued shares to fund Bitcoin purchases. The mechanism caused the pool to grow from 46 million shares to 319.5 million, adding roughly 273 million potential shares.
At the time, the expansion drew criticism from some Metaplanet shareholders, who called on the company to cancel the additional potential shares created by the adjustment mechanism.
Amid the criticism, Metaplanet ended the automatic adjustment mechanism in August and cut the overall pool by 41% in September, from 319.5 million to 188.2 million shares. VanEck, however, said the changes still “fall well short of the mark.”
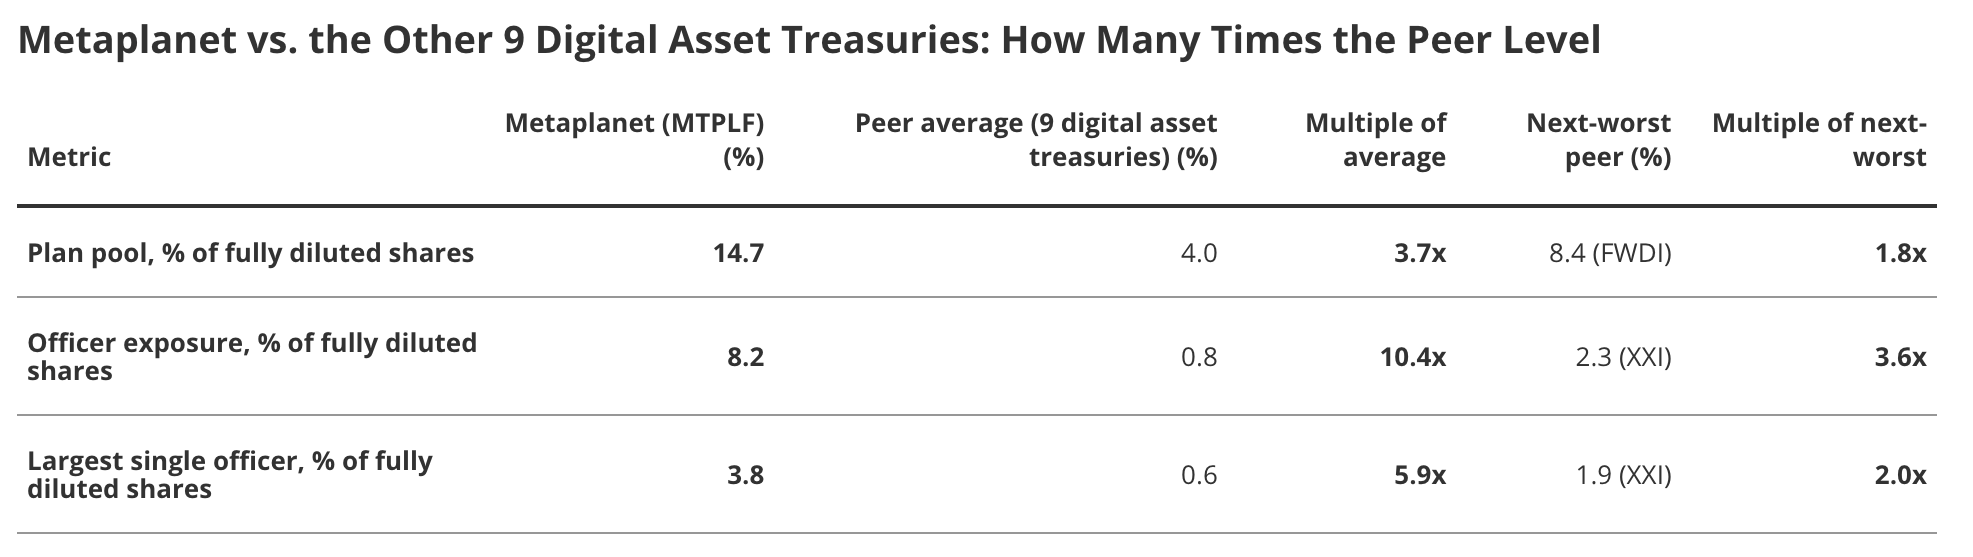
Metaplanet’s equity compensation versus peers. Source: VanEck Research
Friday’s report called for Metaplanet to reverse the roughly 273 million-share expansion created by the adjustment clause and replace the remaining rights with a shareholder-approved compensation plan. VanEck separately noted that unless past grants are clawed back, much of the dilution has already occurred.
VanEck also recommended tying executive compensation to a metric such as Bitcoin per fully diluted share and adopting a written grant-timing policy.
Magazine: Bitcoin treasury firms can outperform BTC… but is the risk worth taking?
The Clarity Act would have cleared that up and also elevated the SEC’s sister agency, the Commodity Futures Trading Commission, to new authorities — most importantly full supervisory powers over the crypto commodity spot markets. Spot markets are where commodities trade directly, and since bitcoin and Ethereum’s ether were eventually determined to be commodities, it became clear the bulk of crypto trading happens in that space that’s absent a hands-on regulator (except in situations in which bad guys are manipulating the markets).
This conflict is uniquely American, because the U.S.’ regulatory regime developed completely separate securities and derivatives agencies, unlike the unification elsewhere. (Yes, everybody knows it’s unnecessarily complicated.) So figuring out which one is responsible for each asset has been a minefield from day one.
Defining the different buckets of blockchain-native assets and who would regulate them was a core aspect of Clarity. Plus, the bill did a lot of things meant to curb illicit finance. And — in a particularly contentious arena — it sought to offer limited legal protections to software developers in decentralized finance (DeFi), so they wouldn’t get prosecuted for how other people use their work.
We’ll pass on talking about the sections that actually killed the bill, which had very little to do with the legislation’s primary business. Instead, we’ll look at what happens in the Clarity-shaped hole in U.S. policy. And thanks to the SEC, we didn’t have to wait long.
Citing data from Santiment, popular analyst Ali Martinez noted on Saturday that Ripple whales have gone on a spectacular accumulation spree in the past four days, acquiring over 1.5 billion tokens.
At the same time, other on-chain and technical signals suggest that the recent selling pressure might be easing and the underlying asset could be preparing for another leg up.
Ripple Whales Go Big
These key market participants, whose actions are typically mimicked by retail investors, have accumulated approximately 1.54 billion XRP in about 96 hours. At current prices, this stash is worth around $2 billion. The timing of the buying spree was quite intriguing, as it began with the CLARITY Act setback in the US Senate, which pushed the token’s price down sharply.
However, accumulating over 1.5 billion tokens in such a short time has helped the asset recover, which is among the reasons XRP surged to over $1.45 on Friday and Saturday after it had bottomed at $1.27 on Tuesday following the Senate vote.
$2 BILLION IN XRP BOUGHT BY WHALES
Whale activity on the XRP network has surged over the past 96 hours.
Large holders appear to have accumulated roughly 1.54 billion $XRP, worth around $2.2 billion.
That’s a significant accumulation spike that could soon translate into price… https://t.co/cBssFmv3wQ pic.twitter.com/Ty3ukakDvi
— Ali Charts (@alicharts) September 19, 2026
Martinez also believes that this spectacular accumulation spree can soon “translate into price action, leading to a bullish breakout.” He has previously predicted that XRP is primed to challenge the key psychological level at $2.00.
Next Targets
Crypto Patel also noted that XRP is sitting above a “major long-term accumulation zone” on the 2-week chart, and it has reclaimed its long-term structure. As such, the analyst outlined some major targets that begin with the potential run toward the first crucial resistance at $1.70. If that one falls, the asset could head toward $3.00, and Patel’s long-term target remains at a whopping $10 or even beyond.
Meanwhile, Dark Defender said XRP’s 5-wave structure is “rock solid,” after the asset “said bye-bye” to a key resistance capping its breakout attempts. The analyst was slightly more modest in their predictions, indicating that the next targets for XRP are $1.70 and $1.88. Recall that XRP’s run in mid-August was halted at the former, after it skyrocketed by 70% in less than 72 hours.
The post Ripple Whales Go on Massive Accumulation Spree: Bigger XRP Price Move Coming? appeared first on CryptoPotato.

Charles Hoskinson believes artificial intelligence (AI) is about to repeat a pattern he witnessed firsthand decades ago.
The Cardano founder argues that blockchain technology will eventually absorb AI, much like cryptocurrency once absorbed cryptography as a discipline.
Why Hoskinson Sees a Coming AI Reckoning
Speaking on the Deeptech Insights podcast this week, Hoskinson pointed to a math problem he considers unsustainable: data center spending keeps growing tenfold year after year, yet the electricity grid simply cannot scale at that pace.
Labs like OpenAI and Anthropic still need to turn a profit eventually, he noted, and the enormous cost of pretraining new models keeps narrowing the path to profitability.
Hoskinson drew a direct parallel to his own career. Cryptographers once resisted any association with cryptocurrency, he recalled, until crypto’s money became powerful enough to hire away the field’s best talent. He expects AI to follow a similar arc within five to ten years.
“Cryptocurrencies are going to eat AI because we solve all the hard problems that AI can’t solve,” Hoskinson said, naming payments, alignment, and data provenance as the specific gaps blockchains could fill.
Follow us on X to get the latest news as it happens.
His alignment argument centers on governance. Individual AI companies currently set their own rules on acceptable behavior and free speech, he argued, whereas a blockchain-based system could instead establish shared standards among participants.
The same infrastructure, he added, could also track content origin and automate royalty payments whenever AI systems draw on someone else’s work.
Hoskinson floated an alternative to building more data centers: pooling everyday phones and GPUs into a distributed training network. He compared today’s AI buildout to the late-1990s fiber optic boom, when roughly 90% of newly laid cable sat idle for nearly a decade.
A similar pattern could follow with data centers, he argued, shifting toward smaller models running locally on devices like Apple’s M5 Mac Studio, with cryptocurrency as the coordination layer.
His Timeline for U.S. Crypto Regulation Looks Grim
Hoskinson also predicted the CLARITY Act won’t clear Congress until 2029, blaming three specific missteps by the Trump administration, including tying crypto’s public image too closely to Trump-branded tokens.
“…There’s no pressure, political pressure to pass this type of thing. they’ll just wait until the next session and force uh a heavily unfavorable bill including ethics provisions to Trump uh on them if they want clarity. Of course, Trump won’t make those concessions. So, actually, we’ll have to wait till 2029 to get a new Clarity Act passed because of the ineptitude of uh of what the White House did. And I was very public about this…,” Hoskinson noted.
That prediction landed just a day after the Senate actually failed to advance the CLARITY Act on September 15, falling short of the 60 votes required.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights.
The post Charles Hoskinson Predicts Crypto Will Eat AI: What's His Reasoning? appeared first on BeInCrypto.
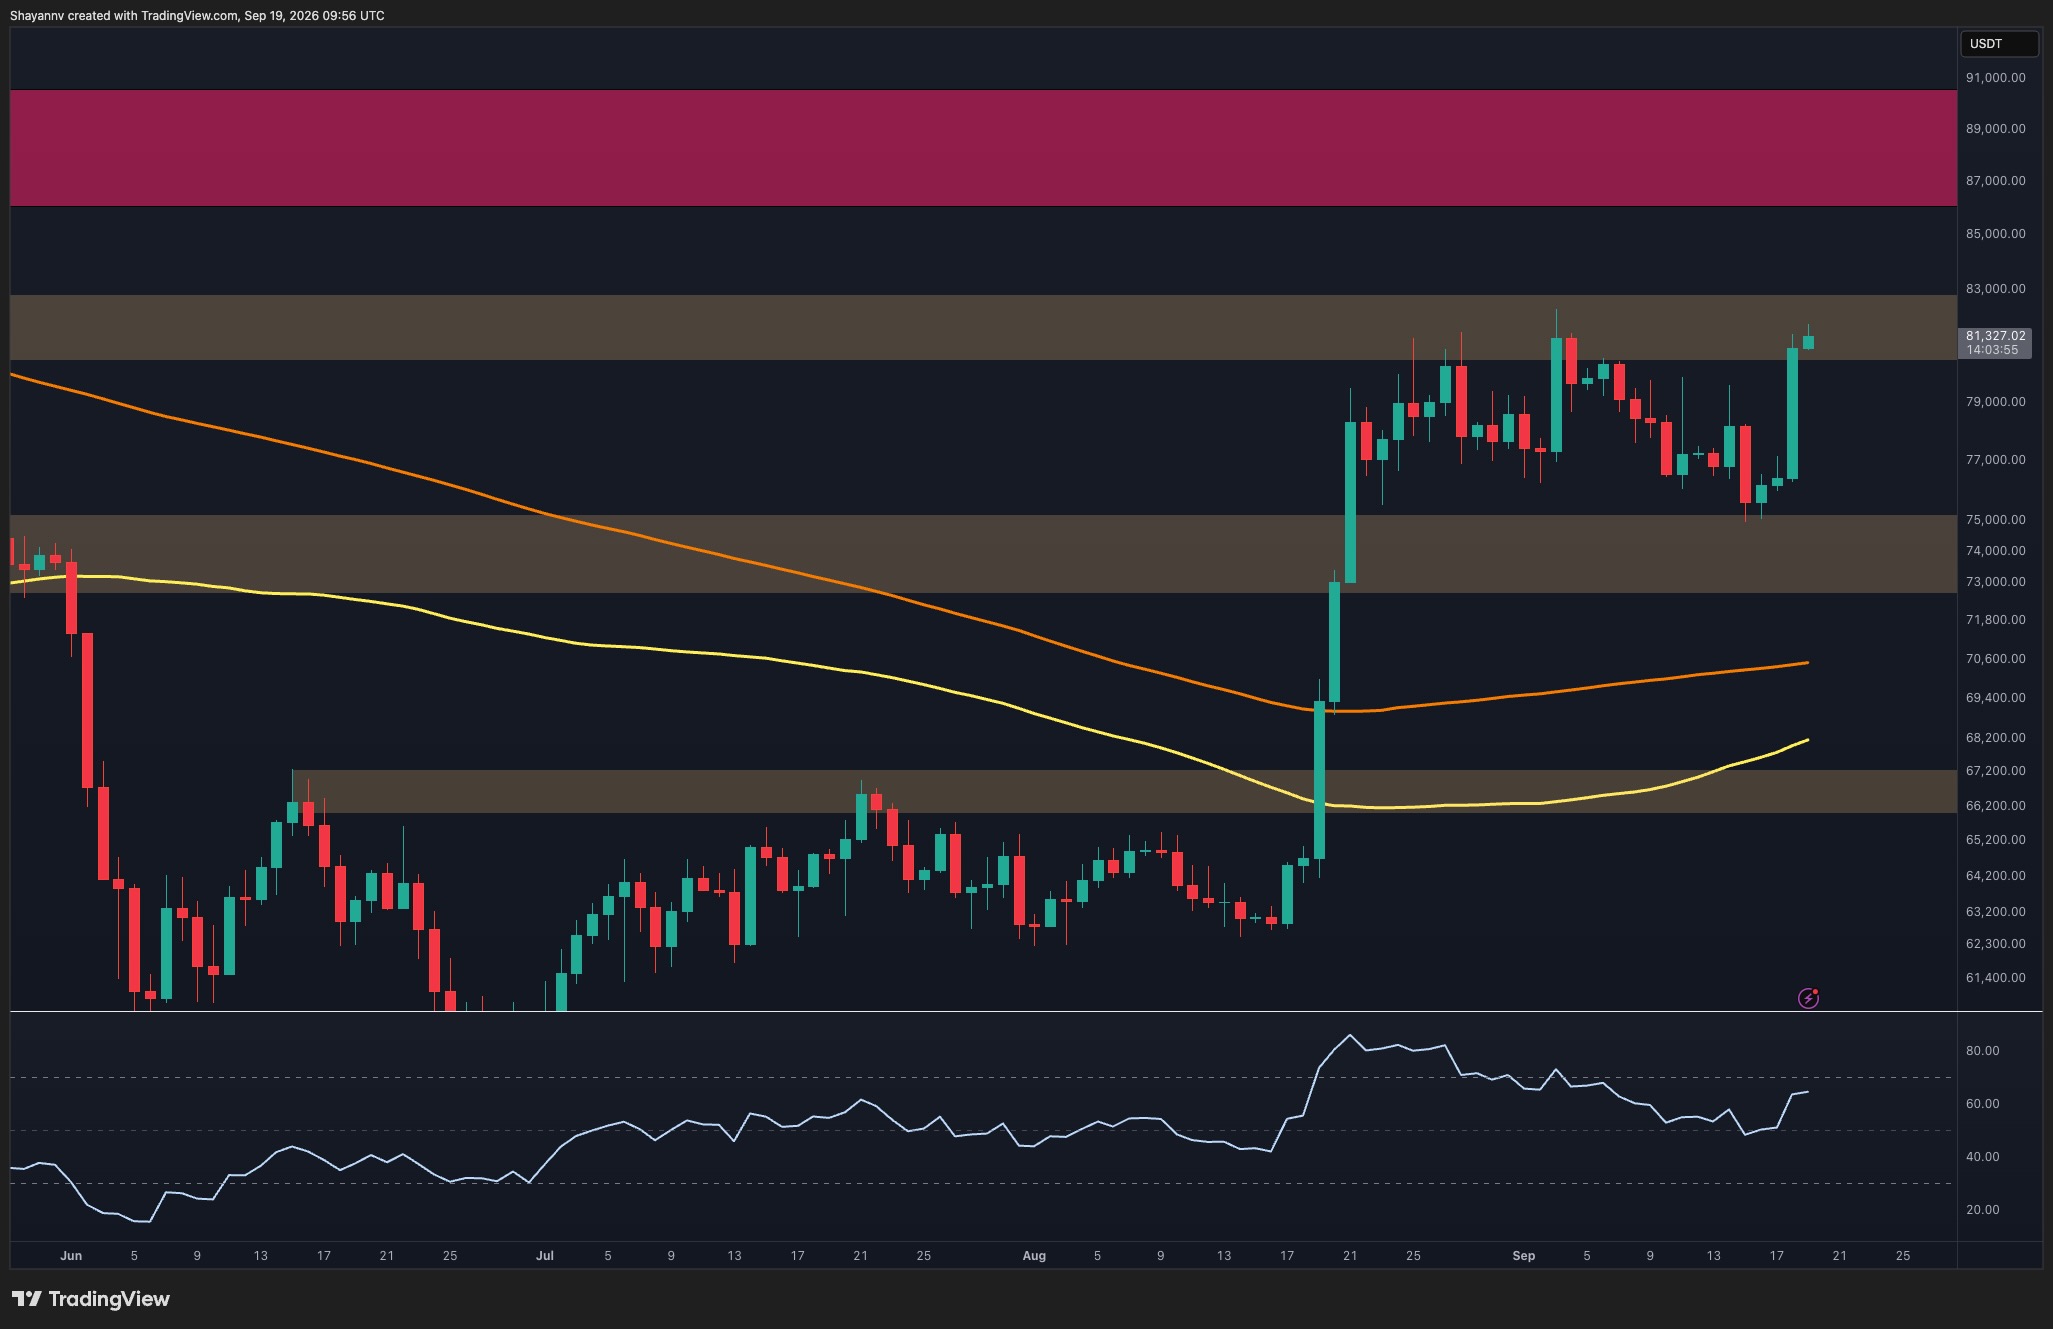
Bitcoin has recovered sharply from the latest pullback and is once again pressing against the upper boundary of its consolidation. With BTC trading around $81.5K, the market is approaching a decisive area where a confirmed bullish breakout could trigger another expansion higher.
Bitcoin Price Analysis: The Daily Chart
The daily chart continues to show Bitcoin consolidating after its powerful August breakout. The latest recovery from the $75K area has been particularly strong, with buyers quickly pushing the price back toward the major $80.5K-$82.5K resistance zone.
This region has repeatedly capped upside attempts and remains the main obstacle preventing another bullish leg. BTC is now testing it once again around $81.5K, while the broader structure remains constructive as long as the $72.5K-$75K support zone is preserved.
Momentum has also improved. The daily RSI has rebounded back above the neutral 50 area and is approaching the mid-60s, reflecting renewed buying momentum without yet reaching overbought territory.
A sustained daily breakout above the $82.5K resistance area would represent an important structural development and could pave the way toward the next major supply zone around $86K-$90K. Conversely, another rejection could keep Bitcoin range-bound, with $75K and the broader $72.5K-$75K region remaining the primary support area.
BTC/USDT 4-Hour Chart
The 4-hour timeframe highlights the range-bound structure more clearly. Bitcoin recently rebounded aggressively from the lower boundary near $74.5K-$75K and has now returned directly to the $81K-$82K resistance region.
The recovery has been impulsive, particularly during the latest move from around $76K toward $81K. However, price has not yet produced a convincing breakout from the upper boundary. Therefore, the market remains inside the broader range despite the increasingly bullish short-term momentum.
A clean break and sustained hold above the $81K-$82K zone would likely shift the structure decisively in favor of buyers. Such a move could trigger another price spike, initially toward the rising upper trendline around $84K-$85K.
Until that happens, rejection remains a relevant alternative. Failure to clear $82K could send BTC back toward the middle of the range, while the $72.5K-$75K zone remains the critical support and broader invalidation area for the current bullish setup.

Sentiment Analysis
The two-week Binance BTC/USDT liquidation heatmap adds further context to the latest rally. Liquidation heatmaps highlight areas where leveraged positions are concentrated, with brighter regions representing larger potential liquidation clusters.
Bitcoin’s surge above $80K has pushed price into a significant concentration of liquidity around the $80K-$82K region. This aligns closely with the technical resistance visible on both price charts, making the current area particularly important.
Some liquidity remains immediately above the market, suggesting that a decisive breakout could force additional short liquidations and potentially accelerate the move. This supports the possibility of another sharp spike if BTC successfully clears the $81K-$82K resistance zone.
At the same time, a liquidity concentration remains below price around $74K-$75K. Therefore, as long as Bitcoin remains trapped below resistance, volatility in either direction cannot be ruled out. For now, the combination of improving momentum and price pressing against the range high puts the focus firmly on whether buyers can convert the current test into a confirmed breakout.

The post Bitcoin Price Analysis: Explosive BTC Rally Faces One Major Obstacle appeared first on CryptoPotato.

Dear Quentin,
My husband, 59, and I, 55, are planning to retire over the next few years, and this is one of the biggest unknowns I’m struggling with. My mom had Alzheimer’s disease and spent seven years in a really nice memory-care facility in a smaller town. It cost about $7,000 a month. Thankfully, my parents had purchased long-term-care insurance and had paid premiums for about 12 years.
My dad died shortly after being diagnosed with cancer, so his policy was never used. But my mom’s policy ended up being worth its weight in gold. It essentially covered all of her care. By the time my mother died, the insurance company had paid out almost $600,000. We only paid about $100 a month for some extras. Needless to say, that experience has made me think.
Most Read from MarketWatch
I’ve looked into long-term-care insurance, but the premiums are so incredibly expensive, and I worry about what they’ll cost by the time it makes sense for me to seriously consider a policy. We’re fortunate financially. After 35 years in the corporate grind, we’ll have substantial retirement savings; we’ve always saved carefully; and we have no debt or mortgage.
I also genuinely love my job, so I’m perfectly happy to work longer if that makes sense. What I really don’t want is to leave our two kids with a huge financial burden someday if one or both of us need years of expensive care. Do I self-insure? Buy long-term-care insurance? Use some combination of investments and insurance? Are there good retirement-planning tools?
I know Medicare is part of the equation, but I’d like more control over our options than simply hoping it will be enough. I’m doing everything I can on the preventative-care and healthy-lifestyle front, but unfortunately there are no guarantees. Right now, my strategy is to save as much as humanly possible and hope for the best.
If you have a crystal ball that will tell me I will need memory care in old age, please share.
In My Fifties
Don’t miss: ‘We fear financial exploitation’: Who will manage our finances if my wife and I become incapacitated?

Dear Fifties,
Your 50s are actually not a bad time to take out long-term care insurance.
Financially speaking, given your age, you’re not too young and you’re not too old. Yes, you probably would have spent less on monthly premiums had you taken out this insurance policy in your 40s, but you would also have been paying it for a decade. It’s hard to predict the future and get that perfect balance. If your mother had Alzheimer’s, your own risk is higher than average from a statistical point of view, although that does not mean that you will develop the disease.

Zcash (ZEC) has climbed 177.8% in a month, and the traders betting against it are paying for that move.
One short was closed at a $10.68 million loss this week, and the largest position still open sits $33.87 million underwater on Hyperliquid.
Zcash Shorts Collapse as the Token Jumps 177% in a Month
Lookonchain flagged the closed trade before the exit, citing 26 consecutive wins and an 89% rate across 47 trades. That record had produced more than $9 million in profit.
The short covered 12,285 ZEC and was worth $18.31 million earlier, with liquidation set at $1,550.66. Hyperliquid data shows the account now holds no positions at all.
Garrett Jin holds the largest short still open, covering 37,999 ZEC worth $59.37 million. He built the position at an average price of $671.05, so it now shows an unrealized loss of $33.87 million.
His 1,333 BTC long is up $4.41 million, which cushions part of the damage. Jin still has room, because his liquidation price of $4,789.42 sits above the 2016 record of $3,191.93.
Other addresses are also seeing sharp losses. One account (0xdd53…2b13) is down $12.53 million on a 13,487 ZEC short opened at $644.39. Another (0xad59…ba81) shorted 8,425 ZEC at $330.91 with 10 times leverage and now sits $10.47 million underwater.
Follow us on X to get the latest news as it happens
Spot Buyers, ETF Flows and One Very Loud Timeline
The rally that caused the damage has made ZEC the strongest performer among the 10 largest cryptocurrencies. The token trades near $1,563 and ranks ninth by market value at $26.47 billion.

The move has real buying behind it from both retail whales and institutions. Lookonchain reported that one address withdrew 15,860 ZEC worth $22.69 million from Binance in a day. Another moved 7,081 ZEC over two days.
Institutional buying has moved in the same direction Zcash ETFs took in $98.2 million in the week ending September 18, the largest inflow among 14 products. Assets rose 40.5% to $914.5 million.
Attention has followed the price. Santiment recorded Zcash social volume at a one-month high on September 17. Mentions on X ran 6.8 times their 29-day baseline, against 1.7 times elsewhere.
“The price found buyers. The attention found one timeline,” the post read.
Traders now watch whether spot demand holds. Open interest in ZEC perpetuals on Hyperliquid stands at 574,045 ZEC, worth roughly $885 million, so leveraged positions remain large on both sides.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights
https://youtu.be/7Hf8KSxNICQ
Read the Original story Trader With 89% Win Rate Loses $10.68 Million Shorting Zcash by Kamina Bashir at beincrypto.com
Anthropic’s initial public offering (IPO), expected no earlier than mid-October, will be a test of just how hungry the financial markets still are for exposure to artificial intelligence (AI). The S&P 500 (SNPINDEX: ^GSPC) is going to react depending on how that test goes. Its backers want a valuation of $2 trillion or more, which would top Space Exploration Technologies as the biggest IPO ever if it happens.
Don’t expect S&P 500 funds to buy it immediately, though. The road for Anthropic entering the S&P 500 is going to be slow, and it could test some nerves along the way.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »

Anthropic can’t join the S&P 500 for at least 12 months
By definition, index funds tracking the S&P 500 must buy whatever the S&P 500 adds to its list of stocks.
Anthropic probably won’t get special treatment, given that on June 4, S&P Dow Jones Indices declined to loosen its rules for mega-cap listings. Those rules still require 12 months as a public company, at least 10% of shares being publicly held, and reported positive earnings under generally accepted accounting principles (GAAP).
While SpaceX joined the Nasdaq-100 list of stocks within weeks of its June 2026 IPO, it still needs to wait outside the S&P 500. If Anthropic has its offering in late 2026 as planned, its earliest shot at inclusion in the S&P 500 will occur in late 2027.
Nonetheless, two of the index’s largest companies already own Anthropic, which means that holders of the index funds have some exposure already as well. For instance, Amazon reported $16.8 billion of pretax gains on its Anthropic position in the first quarter of 2026. Alphabet also has a stake in Anthropic, so a strong debut could boost it and Amazon.
Should you expect a slump after the Anthropic IPO?
Per finance professor Jay Ritter at the University of Florida, across 9,343 U.S. IPOs from 1980 to 2025, the average first-day gain was 19%. The pain came later. Measured from their first close, IPOs from 2012 to 2024 underperformed the market by 25.5% over three years, on average.
SpaceX shows how bumpy the ride can get. It priced its June 2026 IPO at $135. It then jumped to $225.64 before falling to $104.83, and was $151.10 on Sept. 16. That peak-to-trough plunge was probably quite frustrating for its shareholders.
Crypto World
Schwab Treasury ETF vs SPDR Corporate Bond ETF. Which Bond Fund Is the Better Insurance Policy for Your Portfolio?
Bonds should be an essential part of a well-balanced portfolio. Factual differences between the Schwab Long-Term U.S. Treasury ETF (NYSEMKT:SCHQ) and the State Street SPDR Portfolio Long Term Corporate Bond ETF (NYSEMKT:SPLB) center on credit quality, as the Schwab fund tracks government debt while the State Street fund targets investment-grade corporate bonds.
Investors seeking exposure to long-dated fixed income typically choose between government-backed securities and corporate credit. While both funds focus on maturities exceeding 10 years, they offer significantly different risk-reward profiles based on their underlying debt issuers and the credit risk investors are willing to accept for higher income.
Snapshot (cost & size)
Beta measures price volatility relative to the S&P 500; beta is calculated from monthly returns over the available fund history (up to five years). The 1-yr return represents total return over the trailing 12 months. Dividend yield is the trailing-12-month distribution yield as of the end of trading on Sept. 10, 2026.
The Schwab fund is slightly more affordable with a 0.03% expense ratio compared to 0.04% for the SPDR fund. However, those seeking income may find the higher 5.7% yield of the corporate-focused portfolio more attractive.
Performance & risk comparison
What’s inside
The Schwab Long-Term U.S. Treasury ETF is a fixed-income fund that provides exposure to the long-duration segment of the U.S. Treasury bond market. It currently holds 102 positions, focusing on government debt with maturities that often exceed 20 years. Because it holds government-backed securities, its credit risk is generally lower than corporate bond alternatives. Its largest positions include a highly diversified selection of Treasuries where no single position is a sizable portion of the portfolio. The fund was launched in 2019. Schwab Long-Term U.S. Treasury ETF has paid $1.47 per share over the trailing 12 months, which on its recent ~$29.44 share price works out to a 5% yield.
The State Street SPDR Portfolio Long Term Corporate Bond ETF tracks the Bloomberg U.S. Long Term Corporate Bond Index and holds 2,950 positions. It invests in U.S. dollar-denominated, fixed-rate, investment-grade corporate bonds with maturities of at least 10 years. This fund offers higher income potential by taking on the credit risk associated with private corporations. Its largest positions include a highly diversified array of corporate issues, with no single position exceeding 0.35% of the portfolio. The fund was launched in 2009. State Street SPDR Portfolio Long Term Corporate Bond ETF has paid $1.20 per share over the trailing 12 months, which on its recent ~$21.03 share price works out to a 5.7% yield.
Jon Snow’s ‘Game of Thrones’ Return Officially Delayed to 2027
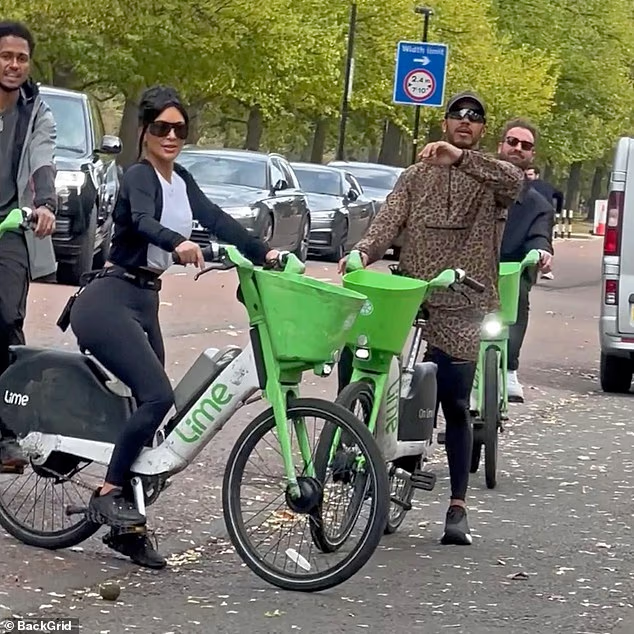
Kim Kardashian and boyfriend Lewis Hamilton explore London on Lime bikes before having a British afternoon tea during romantic day in the city

NiSource: Faster Growth Comes With A Higher Cost (NYSE:NI)




![what MONEY SOAP looks like :]](https://wordupnews.com/wp-content/uploads/2026/09/1789834665_maxresdefault-80x80.jpg)
-
 Fashion23 hours ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech6 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Crypto World5 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-

 Crypto World3 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World4 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-

 Crypto World5 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-

 Crypto World5 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-

 Business6 days ago
Rivals Sam Altman and Elon Musk Rally Behind Dario Amodei’s Call for a Slowdown in AI Development
-

 Crypto World6 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-
 Crypto World4 days ago
Robinhood engineers charged over $50K crypto scheme
-
 NewsBeat18 hours ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-
 NewsBeat5 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World4 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-
Business5 days ago
SK Hynix ADRs Fall More Than 6% as Memory Rally Breaks on Fears of Slower AI Spending
-

 Crypto World5 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
-
 NewsBeat7 days ago
Last Night of the Proms pays moving tribute to Dolly Parton as Sheridan Smith wears a gold sequin jumpsuit in memory of the Queen of Country
-
Crypto World5 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
-
 Crypto World6 days ago
Goldman Sachs backs 25bp Fed hike after CPI
-

 Crypto World5 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-
 Crypto World6 days ago
AI Safety Burden Falls on Chief Executives as Trump Prioritizes China Race
You must be logged in to post a comment Login