Tech
LCD TV Prices Could Rise Before Black Friday as Samsung, LG and Sony Face Higher Panel Costs

For years, the television market followed a fairly dependable rule: if OLED was too expensive, buy an LCD TV. That equation is starting to look considerably less dependable.
Three of the world’s dominant LCD panel manufacturers — BOE, TCL CSOT and HKC — have reportedly notified major television manufacturers, including Samsung Electronics, LG Electronics and Sony, of higher LCD panel pricing beginning in September or during the fourth quarter. The timing is especially inconvenient because TV manufacturers are securing inventory for Black Friday and the holiday shopping season.
The obvious explanation would be that consumers suddenly started buying televisions faster than factories could build them, but TV demand is actually softening. What has changed is the cost of producing LCD panels, how much manufacturing capacity panel makers are willing to keep online, and, most importantly, who now controls much of that production.
Welcome to television economics in 2026, where weaker demand and higher component prices can apparently coexist quite happily. Nobody said this business had to make sense.
Related Reading:
Why Are LCD Panel Prices Going Up?
There are two forces working together. TrendForce reports that demand from the AI industry is creating additional competition for upstream materials and manufacturing resources used by display manufacturers, and expects overall TV panel costs to increase 4% to 7% quarter over quarter during Q4 2026.


At the same time, television panel demand is expected to decline. TrendForce projects unit demand to fall 4% quarter over quarter in Q4 following inventory building during the third quarter, which would normally sound like a recipe for lower prices.
Except BOE, TCL CSOT and HKC are also reducing production. The three manufacturers are planning output cuts around China’s Golden Week holiday, with some LCD fabrication lines temporarily reducing or suspending operations.
TrendForce expects utilization at large-generation display fabs to fall to approximately 79.6% in October, down 4.2 percentage points from September. This is therefore not a conventional panel shortage caused by unexpectedly strong television sales.
Manufacturers are managing output more carefully to keep supply from running too far ahead of demand while also dealing with higher production costs. They also have considerably more ability to influence the market than they once did.
China Now Holds Most of the LCD Cards
BOE, TCL CSOT and HKC collectively account for approximately 70% of global TV panel supply, according to TrendForce. Their position becomes even stronger in larger screen sizes, where industry estimates put their combined share of the 65, 75 and 85-inch LCD panel markets at roughly 70% to 85%.
Chinese panel makers spent years expanding manufacturing capacity and competing aggressively on price while Korean and Japanese display manufacturers gradually retreated from LCD production. That concentration did not happen overnight, but its consequences are becoming much harder to ignore.
Samsung Display ended LCD production in 2022. LG Display subsequently wound down its Korean LCD television panel operations and later exited its Guangzhou LCD manufacturing business, while Japanese manufacturers had already reduced their exposure considerably.
That leaves fewer companies controlling an enormous percentage of the global LCD supply chain. Turns out that when enough competitors leave the room, the companies still sitting at the table gain some leverage.
Samsung May Appreciate the Irony
Samsung makes this situation particularly interesting because, for more than a decade, Samsung Electronics aggressively promoted QLED, Neo QLED and increasingly sophisticated LCD-based television technologies as alternatives to OLED. And to be fair, the best LCD televisions became dramatically better during that period.
Mini LED backlighting improved black levels and local dimming, quantum dots expanded color performance, and newer RGB backlighting technologies promise another significant step forward. Samsung’s 2026 Micro RGB televisions demonstrate that LCD still has plenty of technical life left.
The awkward part is that Samsung Display no longer manufactures the LCD panels required for Samsung Electronics’ enormous television business. Samsung Electronics therefore depends heavily on outside suppliers, including Chinese manufacturers whose expansion helped make LCD panel production less attractive for Samsung Display in the first place.
There is enough circularity there to make even Samsung’s AI processing dizzy. Meanwhile, Samsung has become increasingly serious about the technology it spent years positioning QLED against: OLED.
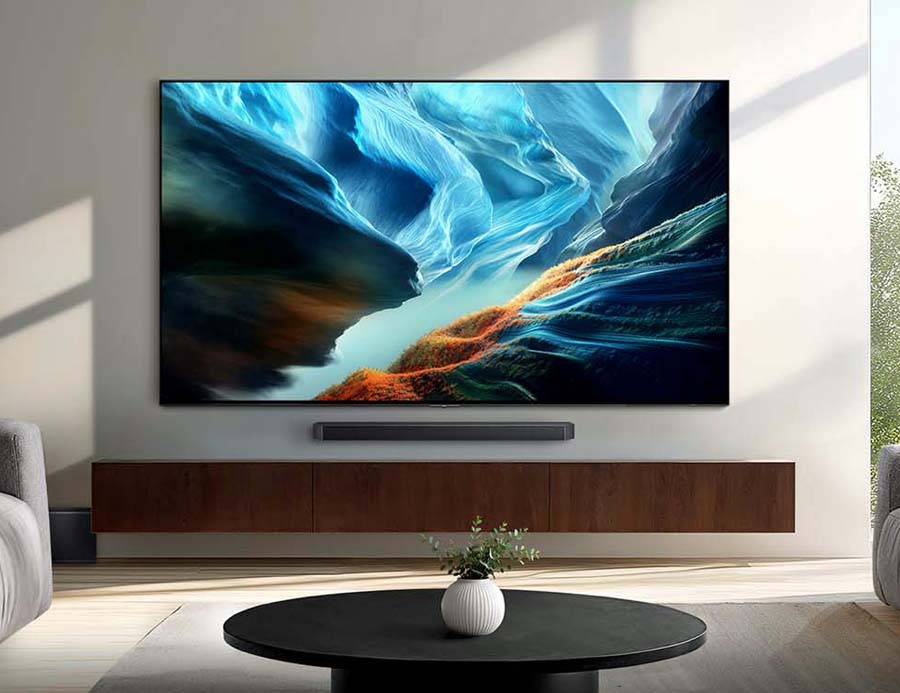

Its 2026 OLED lineup extends from the more affordable S85H and S90H through the flagship S95H. Our 65-inch Samsung S90H review unit used a WOLED panel from LG Display, while Samsung continues to use its own QD-OLED technology in portions of the premium lineup.
Samsung is certainly not abandoning LCD, nor should it. But OLED has gone from awkward rival to an increasingly important part of Samsung’s television strategy, which makes the current shift in panel economics especially interesting.
OLED Is Trying to Get Cheaper
That matters because OLED manufacturers are attacking the technology’s biggest commercial weakness: cost. We recently covered LG Display’s new 2-stack WOLED architecture, which is designed to simplify panel construction while reducing material and manufacturing costs.
By eliminating one emissive layer compared with more complex designs, LG Display potentially requires less organic material and fewer manufacturing steps while still pursuing strong brightness and color performance. The goal is not simply better OLED, but OLED that becomes less expensive to manufacture.
LG Display is also developing FLiPP, a manufacturing process designed to eliminate the fine metal masks traditionally required to produce RGB OLED pixels. Again, the objective is greater manufacturing efficiency and lower costs as OLED production scales.
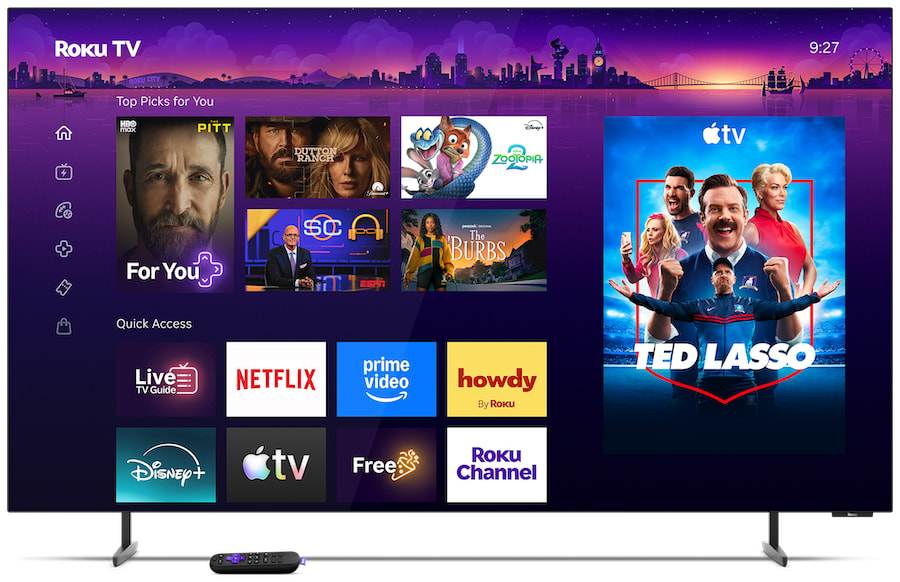

The pressure is already reaching retail. Roku introduced a 2026 Pro Series OLED starting at $999, while Samsung and other major brands continue pushing OLED further down their television lineups.
That does not mean LCD suddenly loses its reason to exist. LCD remains particularly strong for very bright rooms, can deliver extremely high full-screen brightness, and is much easier to scale into 85, 98 and 100-inch screen sizes without requiring a second mortgage and a sympathetic loan officer.
But the historical price gap between LCD and OLED is getting smaller. Higher LCD panel costs certainly will not help widen it again.
Which TV Brands Are Most Exposed?
The manufacturers specifically identified in reports about the latest LCD panel price increases include Samsung, LG and Sony. That is significant because all three sell large numbers of LCD televisions alongside their OLED offerings.
TCL occupies a somewhat different position because its corporate structure includes TCL CSOT, one of the world’s largest panel manufacturers. That degree of vertical integration gives TCL greater control over panel supply and manufacturing costs than companies that rely more heavily on outside suppliers.
Hisense and other major LCD television brands also operate within the same broader panel market and could be affected by industry-wide component pricing. However, they have not all been specifically identified in the current reports as recipients of these latest price-increase notices, so there is no reason to pretend every TV manufacturer faces exactly the same situation.
Will TVs Actually Cost More?
That is the question consumers actually care about, and higher panel prices do not automatically mean Samsung, LG or Sony will increase television MSRPs next week. Manufacturers negotiate panel contracts in advance, source components from multiple suppliers and can absorb some cost increases through margins.
They can also adjust production mixes and promotional strategies. The more likely near-term effect could be smaller Black Friday discounts, shorter promotions, or some models simply declining in price more slowly than they otherwise would have.
Display panels represent one of the largest individual costs inside a television, so sustained increases eventually become difficult for manufacturers to ignore. How much of that reaches consumers will depend on the brand, model, screen size and how aggressively each manufacturer wants to compete during the holiday season.
There is also a broader competitive issue developing around the $1,000 to $2,000 price range. If mainstream OLED prices continue falling while better Mini LED LCD televisions become more expensive to manufacture, consumers may increasingly compare the two technologies directly rather than treating OLED as the automatic premium upgrade.
That could become a much bigger problem for premium LCD than a modest panel-price increase. Price has always been one of LCD’s strongest weapons, and losing some of that advantage would change the buying equation.


The Bottom Line
LCD television technology is not disappearing, and Mini LED, quantum dots and RGB backlighting continue to improve what the best LCD sets can deliver. The technology remains especially compelling at very large screen sizes and in rooms where brightness matters more than perfect blacks.
The economics underneath those televisions, however, have changed considerably. LCD manufacturing has consolidated around a much smaller group of suppliers, giving those companies greater influence over production and pricing just as component costs are increasing.
At the same time, OLED manufacturers are working in the opposite direction by simplifying production and pushing the technology toward lower price points. Nobody should cancel their Black Friday plans because LCD televisions are suddenly about to become dramatically more expensive, because there is not enough evidence to support that conclusion.
But the direction is worth watching closely because the old pricing relationship between the two technologies is shifting. For years, LCD owned the price advantage while OLED owned the premium conversation.
If LCD gets more expensive while OLED keeps getting cheaper, that line becomes considerably harder to draw.
Guess OLED isn’t dead after all.
You must be logged in to post a comment Login