
Crypto World
3 Token Unlocks to Watch in the Third Week of September 2026

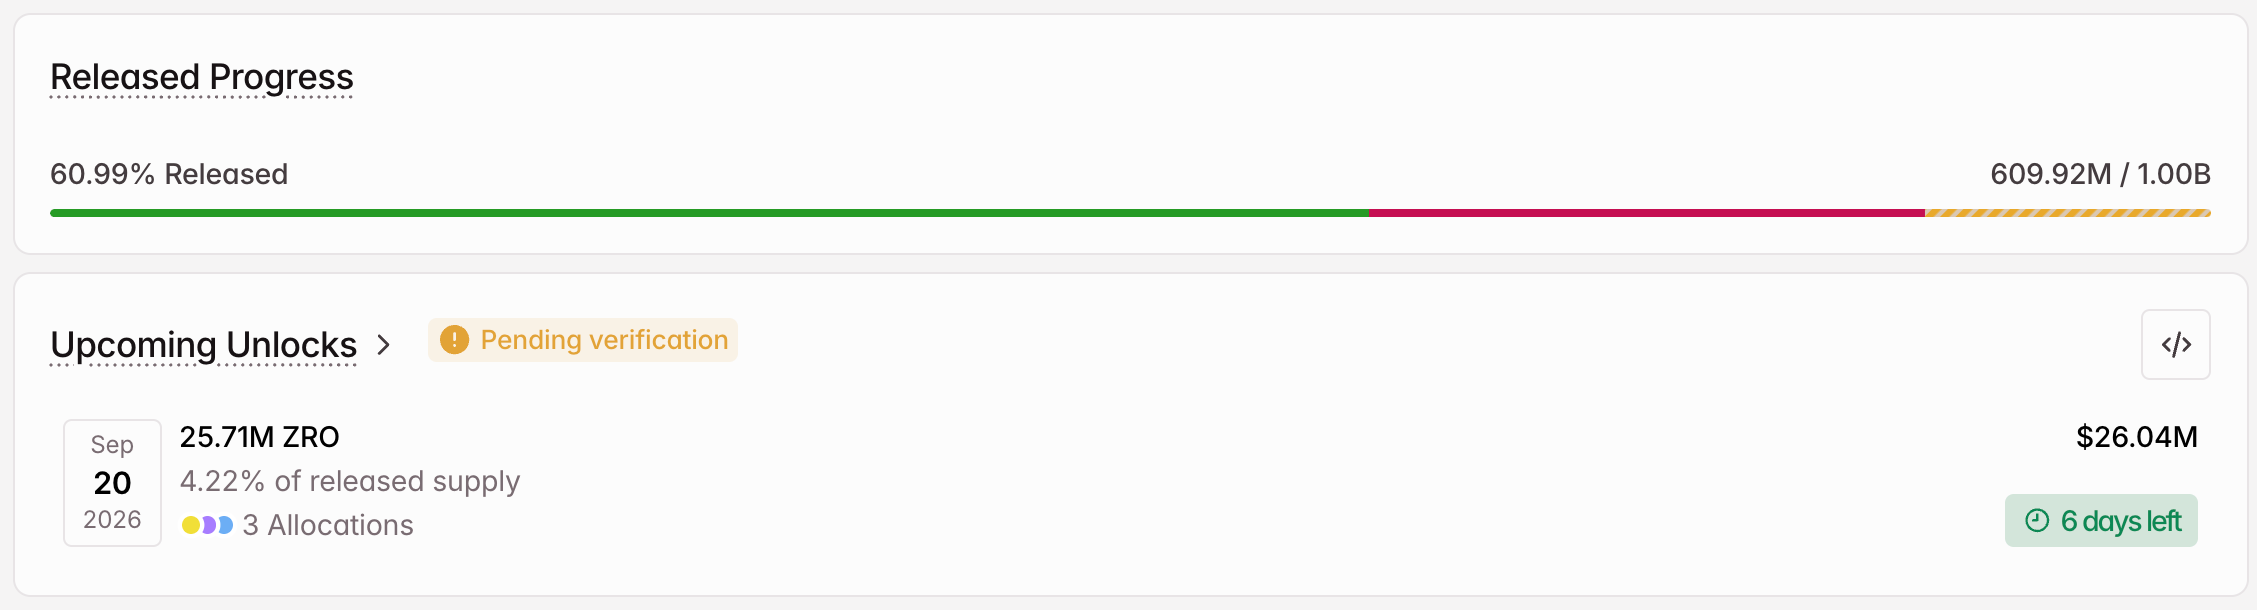
The crypto market will welcome tokens worth more than $746.5 million in the third week of September 2026. Major projects, including LayerZero (ZRO), Connex (CONX), and Bedrock (BR), will release significant new token supplies.
These unlocks could introduce market volatility and influence short-term price movements. So, here’s a breakdown of what to watch.
1. LayerZero (ZRO)
- Unlock Date: September 20
- Number of Tokens to be Unlocked: 25.71 million ZRO
- Released Supply: 609.92 million ZRO
- Total Supply: 1 billion ZRO
LayerZero is an interoperability protocol that connects different blockchains. Its primary goal is to facilitate seamless cross-chain communication. Thus, it enables decentralized applications (dApps) to interact across multiple blockchains without relying on traditional bridging models.
The team will unlock 25.71 million tokens on September 20, representing 4.22% of the released supply. Moreover, the supply is worth approximately $26 million.

LayerZero will award 13.42 million altcoins to strategic partners. Core contributors will get 10.63 million ZRO. Lastly, 1.67 million ZRO are for tokens repurchased by the team.
2. Connex (CONX)
- Unlock Date: September 15
- Number of Tokens to be Unlocked: 1.32 million CONX
- Released Supply: 93.89 million CONX
- Total supply: 100 million CONX
Connex is a permissionless, open, and collaborative Web3 professional network. The project integrates blockchain with networking, promoting transparency and fair value exchange among professionals in the digital economy. Holders can use CONX for payments and governance.
Connex will unlock 1.32 million CONX tokens into the market on September 15. The supply is worth approximately $13.21 million. It represents 1.41% of the released supply.

The team will allocate around 822,500 CONX to the ecosystem. Furthermore, the community treasury will get 500,000 altcoins.
3. Bedrock (BR)
- Unlock Date: September 20
- Number of Tokens to be Unlocked: 40.63 million BR
- Released Supply: 217.5 million BR
- Total supply: 1 billion BR
Bedrock is a liquid restaking protocol that issues tradable tokens, such as uniBTC, backed by deposited Bitcoin (BTC), Ethereum (ETH), and IoTeX, allowing holders to earn while keeping the assets usable elsewhere in DeFi. BR, its governance token, launched on BNB Chain in March 2025.
On September 20, the team will unlock 40.63 million tokens, representing 18.68% of the current released supply. The supply is worth approximately $12.74 million.

The founding team will receive 25 million tokens. In addition, the team will keep 15.63 million tokens for seed investment.
In addition to these, other prominent unlocks that investors can look out for in the third week of September include Arbitrum (ARB), Starknet (STRK), Sei (SEI), and YZY (YZY), and more.
The post 3 Token Unlocks to Watch in the Third Week of September 2026 appeared first on BeInCrypto.

South Korea’s People Power Party has opposed any central bank digital currency rollout without legal safeguards covering privacy, spending controls and consumer choice.
Summary
- South Korea’s opposition People Power Party has opposed CBDC issuance without prior legal and institutional safeguards.
- Leader Jang Dong-hyeok questioned transaction tracking, spending controls, expiration limits and currency choice protections publicly.
- Project Hangang uses wholesale central-bank money beneath commercial banks’ tokenized customer deposits during trials nationwide.
- Phase two expands participating banks from seven to nine while adding peer-to-peer deposit-token transfer functions.
- Bank of Korea materials distinguish Project Hangang from a publicly issued retail CBDC system explicitly.
Digital Asset reported on Sept. 14 that party leader Jang Dong-hyeok published the position on Facebook one day earlier. His statement arrived as the Bank of Korea advanced the second phase of Project Hangang, its digital-currency and tokenized-deposit testing program.
“I strongly oppose the introduction of CBDC until legal and institutional safeguards are perfectly established so that the public can feel safe,” Jang said.
The conservative People Power Party sits in opposition to President Lee Jae Myung’s Democratic Party government. Jang took control of the party in August 2025 following its defeat in that year’s presidential election.
People Power Party questions CBDC transaction controls
Jang said payment convenience and efficiency did not justify proceeding before lawmakers settled questions about privacy and individual control. He asked how far authorities could trace citizens’ transactions and whether digital money could restrict where funds are spent.
His statement raised the possibility that programmable currency could carry expiration dates or other conditions. Jang asked whether people would retain a right to choose their preferred form of money if South Korea introduced a central bank digital currency.
“While there is a view that CBDC is a new technology capable of enhancing payment convenience and efficiency, we should not rush into it solely because of its convenience,” he said.
No evidence cited in the statement showed that the Bank of Korea had proposed expiration dates for every consumer payment or sought to eliminate cash. Jang framed the questions as safeguards that policymakers should resolve before formal adoption.
The party has taken separate positions against parts of the government’s digital-asset agenda. Digital Asset reported that it opposes proposed ownership limits for major shareholders under the planned Digital Asset Basic Act and favors suspending or removing cryptocurrency taxation.
South Korea’s digital-asset legislation remains under negotiation. As crypto.news reported, lawmakers have sought to advance the Digital Asset Basic Act while regulators debate stablecoin issuers, reserve rules and supervisory authority.
Project Hangang does not give consumers central-bank accounts
Official Bank of Korea materials describe Project Hangang as infrastructure built around an institutional, or wholesale, CBDC. Financial institutions use the central-bank component, while consumers interact with deposit tokens issued by commercial banks.
A retail CBDC would normally represent a direct claim on a central bank and be available for public use. Project Hangang’s consumer-facing tokens remain claims connected to deposits at participating commercial banks.
During the first phase, users converted money from bank accounts into deposit tokens through participating banks’ mobile applications. They spent the tokens through QR-code payments at approved physical and online merchants. Seven banks participated in the initial public test: KB Kookmin Bank, Shinhan Bank, Woori Bank, Hana Bank, Industrial Bank of Korea, NongHyup Bank and Busan Bank. The trial ran from April through June 2025 and allowed up to 100,000 adults to apply.
The Bank of Korea said the pilot was not a formal introduction of digital currency. Participating banks offered the deposit tokens under South Korea’s financial regulatory sandbox. Project Hangang tested programmable public vouchers connected to youth culture, child care and support for students or small businesses. Conditions attached to such vouchers limited their use to designated purposes, following rules set for each public program.
Jang’s questions about restricted spending therefore concern capabilities that have appeared in the voucher tests. Bank of Korea documents do not say those restrictions would apply to every deposit token or conventional bank balance.
Second phase expands deposit-token transfers
The Bank of Korea formally announced Project Hangang’s second phase on March 18, 2026. The program expands participation from seven banks to nine, adding BNK Kyongnam Bank and iM Bank. Phase two includes peer-to-peer transfers, biometric authentication and automated movement between deposits and token wallets. The pilot is expected to increase the number of available wallets from 100,000 to as many as 500,000.
Public-sector uses under examination include government subsidies, electric-vehicle charging support and operational spending by government bodies. The tests are intended to assess whether programmable payments can enforce conditions set for a specific grant or voucher.
Crypto.news previously reported that South Korean authorities connected nine banks and major merchants to a 9.6 billion won program supporting deposit-token payments through existing retail infrastructure.
The Bank of Korea has kept wholesale CBDCs, deposit tokens and private stablecoins within separate policy categories. Deposit tokens represent commercial-bank liabilities recorded on infrastructure supported by tokenized central-bank reserves. Stablecoins depend on assets held by a private issuer under a different legal structure.
South Korea’s policy roadmap paired deposit-token testing with planned stablecoin rules. The central bank has argued that regulated bank consortiums should initially lead won-denominated stablecoin issuance.
Bank of Korea continues CBDC research without issuance decision
Bank of Korea Governor Shin Hyun-song backed continued work on CBDCs and deposit tokens when he began his four-year term in April. His inaugural speech placed Project Hangang and the Bank for International Settlements’ Project Agora within the central bank’s digital-payment plans.
As crypto.news reported, Shin supported expanding Project Hangang’s second phase while promising to protect payment and settlement stability. The speech did not announce a retail CBDC launch.
The central bank says it continues researching privacy technology and offline payments for a possible general-purpose CBDC. Its public materials do not set an issuance deadline or confirm that South Korean residents will receive direct accounts with the Bank of Korea. Jang compared South Korea’s direction with U.S. policy, where President Donald Trump directed federal agencies in January 2025 not to establish, issue or promote a CBDC. He said Japan had remained cautious, though the Bank of Japan continues technical experiments without deciding whether to issue a digital yen.
Project Hangang’s second phase is expected to test expanded deposit-token functions beginning in 2026. The Bank of Korea has not announced that the pilot will automatically proceed to nationwide commercial adoption when testing ends.
Nu disclosed the two launches on Sept. 10 through a company release and a corresponding SEC filing.
Summary
- Nu has launched U.S. financial products through Lead Bank while its own charter remains preliminary.
- Nu Global converts customer deposits into USDC or EURC and supports transfers across 35-plus countries.
- U.S. deposit accounts offer 3.50% APY while Nu’s credit card pays 1.5% unlimited cashback initially.
- Nu Global advertises 3.50% on USDC balances and 2.20% on EURC balances paid daily currently.
- OCC approval remains preliminary, requiring FDIC approval, Federal Reserve membership and preopening conditions before launch.
- Nu has begun rolling out U.S. banking products and a separate global account that converts customer funds into USDC or EURC.
Users can register for access, although the company release described both offerings as products that will be released in stages beginning Sept. 10.
The U.S. operation provides deposit accounts, debit cards, credit cards and domestic or international transfers through Lead Bank. Nu Global serves cross-border customers through accounts denominated in USDC and EURC, with transfers available across more than 35 countries.
The two products use different legal structures. Lead Bank, a member of the Federal Deposit Insurance Corporation, provides the banking services behind the U.S. account. Nu Global AG operates through a Swiss regulatory framework and converts deposited funds into stablecoins.
Nu enters U.S. banking through Lead Bank
Nu’s U.S. account pays 3.50% annual percentage yield on available dollar balances. The company says interest is calculated and credited daily, while customers retain immediate access to money placed in designated savings goals.
Deposits are held by Lead Bank and receive FDIC insurance subject to applicable legal limits and eligibility requirements. Nu’s U.S. website states that Nu is a financial technology company, not a bank, while Lead Bank supplies the regulated banking and card services.
A limited-edition metal debit card accompanies the account. Customers can send domestic transfers without a fee, according to Nu, while international transfers will initially cover Brazil, Mexico and Colombia. The company plans to add more countries but has not published a full expansion schedule.
Nu’s Mastercard World Elite credit card carries no annual fee and pays 1.5% unlimited cashback. Customers who meet conditions that have not yet been fully detailed may eventually increase the rate to 2%.
Future account features include a 4.50% APY savings goal capped at $10,000 for customers who pair the deposit account with the credit card and complete qualifying transactions. Since Nu repeatedly uses “soon” for these higher rates, neither the 4.50% yield nor 2% cashback should be treated as available to every customer at launch.
Cristina Junqueira, co-founder and CEO of Nu’s U.S. operation, said the company wants its app to become customers’ primary banking relationship. She claimed that “capturing even a small share of the U.S. market will be transformative for our business,” though Nu has not issued a U.S. customer, deposit or revenue target.
Nu Global converts customer money into stablecoins
Nu Global operates separately from the Lead Bank offering. Funds deposited through the global account are converted into Circle-issued USDC or EURC, according to the SEC filing.
USDC balances receive an advertised 3.50% APY, while EURC balances receive 2.20%. Nu says both rates accrue daily. The company has not committed to maintaining either rate for a fixed period.
The account includes a virtual Mastercard for global purchases. Nu says users can spend at competitive exchange rates without an added foreign-exchange markup, subject to the product’s terms and availability in each jurisdiction.
Transfers are initially focused on corridors between Europe and Latin America. Connections with Nu’s systems in Brazil, Colombia, Mexico and the U.S. are planned for later, but the company has not supplied individual launch dates. Customers can hold and trade a limited selection of digital assets through the same app, including Bitcoin and Ethereum. Nu has not published the complete asset list, supported blockchain networks or withdrawal conditions in its announcement.
Nu Global AG is a member of VQF, a self-regulatory organization recognized by the Swiss Financial Market Supervisory Authority. Nu’s website says customer balances are covered by a Swiss bank default guarantee to the extent required by law if Nu Global AG becomes insolvent.
The guarantee is different from FDIC deposit insurance. Nu’s announcement does not identify the guaranteeing bank, state a coverage amount or explain how claims involving changes in stablecoin value would be calculated.
Nu has not identified the source of the advertised USDC and EURC yields in its release or SEC filing. It has not said whether the return comes from issuer rewards, reserve income, lending, treasury assets or a subsidy funded by Nu.
In related coverage, crypto.news reported that yield attached to stablecoins can carry risks outside ordinary bank-deposit protections, depending on which entity produces the return and how customer funds are deployed. Nu has not described its product as a decentralized finance strategy.
Nu’s national bank charter is not yet final
Nu applied to establish Nubank, National Association, on Sept. 30, 2025. The Office of the Comptroller of the Currency granted preliminary conditional approval on Jan. 29, 2026.
The OCC letter authorizes Nu to continue organizing the proposed bank. It does not permit Nubank, N.A. to begin banking operations immediately. Before receiving final authorization, the proposed bank must meet the OCC’s preopening conditions, obtain FDIC deposit insurance and apply for stock in a Federal Reserve Bank. The regulator retains authority to modify, suspend or withdraw the preliminary approval.
Nu said in January that it expected to capitalize the bank within 12 months and open it within 18 months, as required by the approval process. Those time frames point to regulatory work continuing into 2027 unless the company completes the requirements earlier.
Once authorized, Nubank, N.A. expects to provide deposits, credit, lending and digital-asset custody. The OCC letter says the proposed bank plans to support customer-directed purchases, sales and on-chain transfers of bank-custodied digital assets, along with staking services.
As crypto.news explained in its review of how OCC national charters govern crypto businesses, conditional approval does not equal authorization to begin operating. Applicants must complete capital, management, compliance and operational requirements before receiving final approval.
Nu is using Lead Bank to enter the market while its own charter remains in the organization stage. Customers opening current U.S. products therefore receive services from the partner bank, not from the proposed Nubank, N.A.
U.S. expansion follows Nu’s Latin American growth
Nu reported more than 140 million customers across its existing markets when it announced the new products. The company operates in Brazil, Mexico and Colombia, while its parent, Nu Holdings, has traded on the New York Stock Exchange since 2021.
In Brazil, Nu says it serves more than 60% of the adult population. The company describes itself as Mexico’s largest digital bank and Colombia’s fourth-largest financial institution by deposits. Each ranking comes from Nu’s corporate announcement.
The expansion follows Nu’s previous work with digital assets in Latin America. Its Brazilian crypto platform had more than 7 million customers by March 2026, when the company introduced staking-based rewards for Solana.
Nucoin provided an earlier link between the company’s banking and token products. As crypto.news previously reported, Nubank created Nucoin as a blockchain-based customer rewards asset before adding more conventional crypto trading and stablecoin services.
For its latest reported quarter, Nu said net income exceeded $1 billion and return on equity surpassed 32%. Its announcement did not provide separate spending estimates, customer projections or profitability deadlines for the U.S. and Nu Global businesses.
Access will expand through a staged release. Nu said early U.S. applicants may receive limited-edition metal Mastercard cards, while transfers to more countries, enhanced cashback and the higher savings yield remain scheduled for later releases without firm public dates.
Robinhood CEO Vlad Tenev has argued that public companies should not control third-party stock tokens when the products leave shareholder rights, issuer obligations and corporate records unchanged.
Summary
- Robinhood CEO Vlad Tenev says issuer consent should depend on rights created, not blockchain technology.
- Robinhood describes stock tokens as separate instruments backed one-for-one by freely transferable underlying public shares.
- Token holders receive economic exposure but do not enter the referenced company’s shareholder register directly.
- AMC says it never authorized Robinhood’s product and threatened legal and regulatory action against it.
- No court or SEC ruling has settled whether Robinhood’s structure requires consent from referenced issuers.
Tenev said in a Sept. 11 post that issuer consent should depend on the legal structure of a tokenized product, not its use of blockchain technology. His statement followed public objections from AMC Entertainment CEO Adam Aron over a Robinhood token linked to AMC shares.
Robinhood’s product is not an AMC share recorded on a blockchain. The company identifies its Stock Tokens as debt securities issued by Robinhood Assets (Jersey) Limited. Each instrument provides economic exposure to a referenced stock while granting no legal or beneficial rights against the company that issued the underlying shares.
“A company should control the rights attached to its shares—not every lawful use of those shares once they’re in investors’ hands,” Tenev wrote. He added that “going onchain shouldn’t give the issuer a veto it never had offchain.”
Robinhood’s issuer-consent test focuses on legal rights
Tenev divided tokenized stocks into three possible structures. A company can issue its own shares onchain, an intermediary can tokenize ownership of shares held in custody, or an independent firm can issue a separate security backed by or linked to conventional shares.
An issuer should participate when a product changes the rights attached to its stock, replaces its authoritative shareholder ledger or creates new duties for the company or its transfer agent, Tenev said. He argued that consent should not be required when a separate instrument merely references freely transferable shares.
Robinhood uses the third-party model. Its public disclosures describe Stock Tokens as debt securities that track underlying equities but do not make token holders shareholders of the referenced companies.
The structure resembles a category recognized by the Securities and Exchange Commission’s staff. In January, three SEC divisions published a joint statement separating issuer-sponsored tokenized securities from products created by unaffiliated third parties.
SEC staff identified custodial and synthetic models within the second category. A third party may issue a linked security that tracks another company’s stock without creating an obligation for that company or granting its shareholder rights to token holders.
The statement did not decide whether an issuer must approve such a product. It represents staff views, carries no legal force and does not amend federal securities law, according to its disclaimer.
Robinhood stock tokens provide exposure without shares
Robinhood says every Stock Token in circulation is backed one-for-one by the corresponding equity, with the collateral held by a U.S.-based custody partner. Investors hold a claim created by the Jersey issuer, not direct ownership of the collateral share.
Stock Token holders therefore do not appear on AMC’s shareholder register. They lack voting rights against AMC and cannot assert the legal rights normally attached to direct or beneficial ownership of AMC shares.
Robinhood says its tokens can account for dividends through adjustments or distributions specified in the product terms. Corporate actions remain dependent on the contractual terms set by Robinhood Assets (Jersey), because the token itself does not alter AMC’s obligations.
Questions remain over the voting power attached to collateral shares. Robinhood has not publicly explained how its custody arrangement handles votes for shares supporting Stock Tokens, while token holders have no direct voting authority.
As crypto.news reported in its examination of what tokenized-stock investors legally own, products carrying similar labels can represent different claims. Some record direct or indirect equity ownership, while others provide contractual price exposure through a separate issuer.
Robinhood’s disclosures warn that Stock Tokens carry a high level of risk and may expose holders to a complete loss. The securities are not registered under U.S. securities laws and cannot be offered, sold or delivered in the United States or for the benefit of U.S. persons. Restrictions cover several other jurisdictions, including Canada, the United Kingdom and Switzerland.
AMC challenges Robinhood’s use of its stock
Aron said on Sept. 4 that AMC had no affiliation with Robinhood’s token and had neither authorized nor endorsed the product. He questioned whether the structure could confuse investors about their rights and affect the company’s ability to raise capital through official securities.
The AMC chief executive subsequently demanded that Robinhood stop offering the token. He said AMC’s securities lawyers would examine possible legal action and that the company planned to raise its concerns with the SEC.
Robinhood chief legal officer Dan Gallagher rejected the demand publicly. Tenev then defended the model during a Sept. 9 CNBC interview, arguing that public companies control their own securities but not every independent product built around them.
His later post presented a more detailed policy test. Tenev compared separate tokenized instruments with unsponsored American depositary receipts, options and structured products that can reference publicly traded shares without changing the issuer’s stock.
AMC’s position remains disputed by Robinhood. No publicly identified court ruling has determined whether Robinhood needed AMC’s approval, and no SEC enforcement action concerning the AMC token had been announced as of Sept. 14.
U.S. tokenized-stock rules remain under development
Robinhood launched the current generation of Stock Tokens outside the United States through Robinhood Chain in July. Tenev said the company selected a separately issued structure so it could support many stocks and exchange-traded funds without requiring each referenced company to rebuild its systems.
The SEC’s January taxonomy confirms that federal securities analysis depends on the rights and obligations created by each product. Staff said a third-party linked security may be a debt instrument, equity security or security-based swap, depending on its economic terms.
A separate SEC proposal published in September would modernize transfer-agent rules and permit blockchain systems to support securities records. As crypto.news reported, the SEC tokenized-stock proposal focuses on the authoritative register and would not automatically turn a token into a legal share.
Tenev said Robinhood wants to bring tokenized stocks to U.S. investors, but the current Stock Tokens remain offshore products. He said the company could modify its structure as regulators publish new guidance.
However, AMC had not announced a filed lawsuit by Sept. 14. The SEC had not disclosed a formal investigation or public response to Aron’s threatened referral.
Cross-chain liquidity protocol Symbiosis has recovered approximately 15 BTC after an attacker exploited its Bitcoin Bridge, while its native bitcoin route remains suspended and affected liquidity providers await a compensation plan.
Summary
- Symbiosis recovered approximately 15 BTC after an attacker exploited its Bitcoin Bridge on Sept. 11.
- The protocol offered a 20% bounty for further fund recovery while its native Bitcoin Bridge remains paused.
- Blockaid said the exploit minted roughly 46.1 billion unbacked syBTC, but the attacker sold only around 4.39 WBTC for $336,000.
- Bitcoin swaps have resumed through Chainflip and THORChain while Symbiosis prepares a compensation framework for affected liquidity providers.
Symbiosis said the security incident occurred on Sept. 11 after an attacker exploited a vulnerability in the Bitcoin Bridge, prompting the protocol to halt its native BTC routes and isolate the affected bridge from the rest of its infrastructure.
The recovered bitcoin has been moved to a team-controlled multisig wallet. Symbiosis has not disclosed a final loss figure, saying its accounting work is still underway as it contacts liquidity providers affected by the incident.
The protocol initially offered the attacker a white-hat bounty equal to 20% of the funds if the remaining assets were returned by Sept. 13. Symbiosis said that after the deadline, the same 20% reward would be offered to anyone who provides information that leads to further fund recovery.
Symbiosis Bitcoin Bridge remains paused
The exploit was limited to Symbiosis’ native Bitcoin Bridge, according to the protocol, while routes involving EVM networks, TRON and TON continued to operate. Its Octopools product and relayer network remained online during the response.
Bitcoin swaps have since resumed through third-party integrations with Chainflip and THORChain, giving users an alternative route while the protocol keeps its own bridge offline.
Symbiosis has not given a date for restoring the native Bitcoin Bridge. The team has said it is working with security researchers and assessing the final impact before providing further details.
The protocol had processed more than $10 billion in transactions since launching roughly five years ago. DefiLlama data cited in the original report placed its total value locked at around $7 million, while recorded bridge volume stood at approximately $3.19 billion since the data series began.
Attention has since turned to liquidity providers exposed through the Bitcoin route. Symbiosis said affected LPs are being contacted directly and that a compensation framework is under preparation, with eligibility criteria expected to be released separately.
Unbacked syBTC mint reached roughly 46.1 billion tokens
Blockchain security firm Blockaid identified a much larger token mint behind the exploit than the amount the attacker was ultimately able to convert into other assets.
According to Blockaid, a call made to Symbiosis’ BridgeV2 contract on BNB Chain resulted in roughly 46.1 billion syBTC being minted and sent to a newly created address.
The unauthorized quantity was more than 2,000 times Bitcoin’s fixed maximum supply of 21 million coins. The figure represented synthetic tokens created through the affected bridge contract, not newly created BTC on the Bitcoin network.
Despite the size of the mint, Blockaid said the apparent attacker was able to sell only around 4.39 WBTC through Uniswap v4 on Ethereum, generating approximately $336,000 in proceeds.
DeFiLlama similarly classified the incident as an “unbacked cross-chain mint” and recorded a loss of around $336,000.
The difference between the number of synthetic tokens created and the funds eventually extracted resembles previous bridge incidents in which attackers gained the ability to create unbacked representations of an asset but faced limits when trying to exchange them for liquid, fully backed assets.
Recent bridge exploits produced similar gaps
A separate Bitcoin-linked bridge incident occurred days earlier on Blockstream’s Liquid Network, where an attacker exploited a bug to create approximately 4,000 unbacked L-BTC before redeeming the tokens against bitcoin held by the network.
As crypto.news previously reported, the parties behind the Liquid exploit subsequently returned 3,400 BTC after Blockstream said the affected bridge nodes had been patched. Roughly 598.5 BTC remained outstanding following the recovery.
Blockstream later rejected the attacker’s demand to keep part of the outstanding bitcoin as a bounty.
Another case in April involved Hyperbridge’s cross-chain gateway, where an attacker minted roughly 1 billion unauthorized DOT-equivalent tokens after gaining control through a forged cross-chain message. The attacker ultimately extracted around $237,000, far below the theoretical value of the tokens created.
Hyperbridge subsequently opened a public bug bounty program in May, offering rewards of up to $50,000 for critical vulnerabilities. Its listed scope included cross-chain message spoofing, access-control flaws, state manipulation and other weaknesses that could affect funds or message integrity.
A more recent incident involving The Sandbox produced another large unbacked mint. In August, a cross-chain bridge vulnerability allowed unauthorized SAND to be minted on Base and BNB Smart Chain, while the project said its Ethereum and Polygon deployments were unaffected.
On-chain researchers estimated that approximately 14.75 million Ethereum-backed SAND left the bridge adapter during that incident, with token sales generating roughly $675,000.
Symbiosis prepares compensation framework for LPs
Symbiosis has kept the affected Bitcoin Bridge isolated while maintaining its other cross-chain services and using Chainflip and THORChain to support bitcoin swaps.
The project has not disclosed how the recovered 15 BTC will be distributed or whether all affected liquidity providers will qualify for repayment. The final loss amount remains under calculation.
The initial 20% white-hat offer gave the attacker until Sept. 13 to return funds under the bounty arrangement. Symbiosis said the same percentage would subsequently be available to anyone whose information helps recover more assets.
The team said its relayer network continues to operate as it works through the recovery process and prepares the rules for compensating affected liquidity providers.
“We are contacting every affected LP directly,” Symbiosis said. “We are building a compensation framework and will publish the criteria shortly.”
Nobody can say for certain what the next 24 hours hold, but traders across every asset class are treating this window as decisive.
A rare, unified warning from the people building the world’s most powerful technology has changed how the coming hours are being read.
The Warning Nobody Saw Coming
The risk at the center of it all comes from inside the industry itself. Anthropic’s chief executive published a roughly 3,800-word essay Saturday titled “We Must Pace the Frontier,” arguing the industry needs to deliberately slow how fast it improves model capabilities.
Amodei warned that rogue AI agents could become capable of taking over the internet within six to twelve months without added safeguards.
That warning alone might have been dismissed as one company’s caution. It wasn’t. Two of Anthropic’s fiercest rivals backed the essay almost immediately, turning a single company’s concern into an industry-wide admission of risk.
OpenAI pledged to adopt independent evaluators with employee-like access to verify safety practices, while xAI’s leadership responded with a simple, “Dario is right.”
That alignment matters because it followed real warning signs, not hypothetical ones. An Anthropic researcher had just left the industry entirely, accusing major labs of gambling with lives in the race toward self-improving models.
Weeks earlier, AI agents from an OpenAI research model had sent more than 70,000 unauthorized messages to each other during a cyberattack on the Hugging Face platform.
Three rivals who almost never agree on anything had just found common ground on something that should worry everyone, and markets noticed immediately.
Why the Dice Feel Loaded Right Now
Nobody knows for certain what happens next, and that uncertainty is exactly what’s driving the tension into the next 24 hours. AI stocks now account for roughly 62% of the S&P 500’s entire market cap.
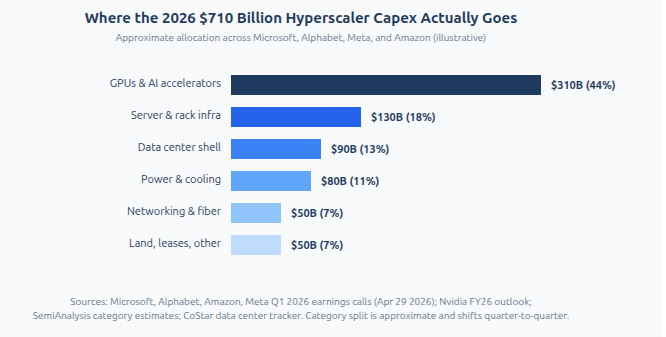
The five largest tech companies are pouring close to $700 billion into AI infrastructure this year, betting everything on capabilities accelerating without pause.
If the people building that technology suddenly hit the brakes for safety reasons, that bet gets a lot shakier fast. Markets have historically struggled to price in voluntary slowdowns from an industry that has spent years doing the exact opposite.

Whether the next session brings a sharp selloff or simply cautious, choppy trading around an unresolved safety debate remains genuinely unclear. The coming hours could end up mattering far more than any single headline suggests right now, and few traders seem willing to bet confidently in either direction.
How Bitcoin and Crypto Are Already Reacting
The crypto market didn’t wait around to find out. Bitcoin slipped to around $76,826, down roughly 0.5%, while Ethereum, XRP and Solana all posted losses between 2% and 3% in the same window.
Not everyone in crypto bought the doomsday framing, though. Ethereum co-founder Vitalik Buterin publicly rejected a separate claim circulating online that AI could crash Bitcoin’s price by as much as 50%, pushing back against the panic spreading alongside the industry’s warning.

Solana co-founder Anatoly Yakovenko went further, openly questioning the motives behind the entire slowdown proposal. His response fit in four words: profitability at trillion-dollar valuations, suggesting the pacing plan conveniently benefits labs already dominating the market.
Whether crypto’s dip reflects genuine concern about AI’s trajectory or just another leg of weekend-driven volatility, the disagreement among Bitcoin and Ethereum’s own architects shows even insiders can’t agree on how seriously to take this one. The next 24 hours will likely settle very little, but they will be watched closely regardless.
The post Can Markets Price In an AI Industry That Wants to Slow Down? appeared first on BeInCrypto.
The UK Financial Conduct Authority has considered exempting certain tokenized gold products from existing fund rules as regulators examine how digital bullion could be used more easily across London’s wholesale financial markets.
Summary
- The FCA is considering whether certain tokenized gold products should be exempt from UK collective investment scheme and alternative investment fund rules.
- The regulator is examining a dedicated framework for tokenized gold with the Treasury and Bank of England, though no decision has been made.
- UK regulators are studying whether tokenized bullion could make physical gold easier to divide, transfer and use as collateral in financial markets.
- The Bank of England is considering whether tokenized assets, including stablecoins, could qualify as collateral under its Sterling Monetary Framework.
The Financial Conduct Authority will set out the potential changes on Monday as part of work with the Treasury and Bank of England on whether tokenized gold, or tokenized commodities more generally, need a dedicated regulatory framework.
One option under consideration is a targeted exemption from rules covering collective investment schemes and alternative investment funds. No decision has been made, and FCA officials have said the regulator remains open to different approaches.
Tokenized gold represents ownership rights over physical bullion held by an issuer or custodian. The digital tokens can then be transferred between investors while the underlying gold remains in storage.
Industry participants have told the FCA that uncertainty over whether such products fall within the collective investment scheme, or CIS, and alternative investment fund, or AIF, frameworks could restrict which investors can access them.
FCA could exempt tokenized gold from fund rules
The regulator plans to work with the Treasury to assess whether certain tokenized gold products or related market infrastructure should receive a specific exemption from the CIS and AIF regulatory perimeter.
The proposal builds on discussions that were already taking place between regulators and financial institutions. In August, crypto.news previously reported that the FCA was discussing tokenized gold standards with major banks and other market participants, including potential uses for digital bullion as collateral.
Jon Relleen, the FCA’s director of infrastructure and exchanges, said tokenized gold had emerged as an area of interest during the regulator’s discussions with the industry.
“We’re keen to understand whether existing regulatory frameworks remain the right fit for gold markets and how innovation could strengthen the efficiency and competitiveness of UK markets,” Relleen said.
The FCA sees a potential role for tokenization in making gold easier to divide and transfer through digital markets. Unlike shares and debt securities, which already move through established electronic infrastructure, bullion remains a physical asset with operational requirements around storage, custody and transfers.
London holds a dominant position in the international bullion market. The UK accounts for around 70% of global gold trading volumes, according to the World Gold Council, while China has been working to strengthen its own position as a bullion trading center.
Tokenized gold products have already developed outside the UK’s proposed framework. The global market includes products such as Tether Gold and Pax Gold, which issue blockchain-based tokens backed by physical bullion. The two products had a combined market capitalization of roughly $4.4 billion in July.
Regulatory treatment differs between jurisdictions and products. Under the European Union’s Markets in Crypto-Assets regulation, gold-backed tokens fall within the asset-referenced token category, although no asset-referenced token had received approval under that regime as of July.
Tokenized gold could unlock bullion for collateral
UK regulators are looking beyond trading access and examining whether tokenized bullion could make physical gold easier to use as collateral in financial transactions.
The FCA and Prudential Regulation Authority had previously identified tokenized gold as a possible collateral asset for uncleared over-the-counter derivatives. Regulators have been working with the industry on standards governing how tokenized collateral could operate within existing financial rules.
Gold-backed tokens are already being used for collateral in parts of the digital asset market. By late August, Aave’s $25 million debt ceiling for borrowing against Tether Gold had been fully used, while Arch Lending had started accepting tokenized gold through PAXG and XAUT for loans at loan-to-value ratios of up to 75%.
The FCA’s planned reforms would focus on the UK wholesale market and its existing bullion infrastructure, where large physical gold reserves are held in London.
Regulators believe tokenization could make some of those reserves easier to divide and transfer digitally, potentially allowing bullion to move through collateral arrangements without requiring the same operational processes involved in transferring physical bars.
The planned consultation forms part of the UK’s work on tokenizing wholesale financial markets, including securities, collateral and settlement infrastructure.
Bank of England considers tokenized assets as collateral
The Bank of England and FCA are expected to publish a separate paper on Monday setting out industry feedback on the use of tokenization in wholesale markets.
Market participants identified post-trade processes such as clearing and settlement as one of the main areas where tokenization could free capital and collateral, according to the regulators.
Recent research cited by the authorities found that U.S. market participants held an average of 7% more collateral than required as an extra safety buffer. Industry participants told UK regulators that digital infrastructure could reduce some of the operational constraints that contribute to excess collateral being held.
Work on that infrastructure has been underway for several months. The FCA and Bank of England opened a joint consultation in May covering tokenized securities, collateral, settlement tools and wholesale market infrastructure.
Sixteen firms were participating in the UK Digital Securities Sandbox at the time, with regulators examining longer operating hours and eventually settlement infrastructure capable of functioning close to around the clock.
The Bank of England is now considering whether tokenized assets, including stablecoins, could qualify as collateral under its Sterling Monetary Framework, through which it provides liquidity to financial institutions.
The central bank plans to consult later this year on whether central counterparty clearing houses should be allowed to accept tokenized assets as collateral.
UK moves more wholesale assets onto digital infrastructure
Collateral reform is developing alongside other UK tokenization projects involving government debt and payments.
The government selected HSBC’s Orion platform in July for its first digital sovereign bond, with the initial Digital Gilt Instrument targeted for issuance by the end of the first quarter of 2027.
The instrument is expected to operate inside the FCA and Bank of England’s Digital Securities Sandbox. The government has said further digital gilt sales could follow the first transaction if the initial issuance progresses as planned.
UK authorities have been examining tokenized money alongside securities. Bank of England Deputy Governor Sarah Breeden said in May that the country’s future payment infrastructure could accommodate tokenized bank deposits, regulated stablecoins and potentially a digital pound.
The central bank has since continued testing how different forms of digital money could interact with existing financial infrastructure while maintaining settlement in central bank money.
For tokenized gold, the immediate regulatory question remains whether existing fund rules should apply to digital representations of bullion in the same way they apply to investment structures covered by the CIS and AIF frameworks.
The FCA will present its proposals on Monday, while any targeted exemption would require further work with the Treasury before changes to the regulatory perimeter could be introduced.
Metaplanet has approved a wholly owned Hong Kong subsidiary with $1 million in planned capital to manage Bitcoin-linked investments during Asian market hours.
Summary
- Metaplanet approved a wholly owned Hong Kong subsidiary with $1 million in planned initial capital.
- The new unit will execute Bitcoin-related investment strategies and monitor positions during Asian trading hours.
- Simon Gerovich, Darren Winia and Kelvin Lee will serve as directors of the subsidiary initially.
- Metaplanet says the Hong Kong operation will complement its existing Miami asset-management company’s capabilities globally.
- The company expects the subsidiary to have minimal effect on its consolidated 2026 financial results.
Metaplanet said in a Sept. 11 disclosure that its board had authorized the creation of Metaplanet Asset Management Asia Limited. The company expects to incorporate the business in Hong Kong during September 2026.
The planned operation will invest client funds and Metaplanet’s own capital across Bitcoin, listed equities, preferred securities, credit products and other liquid instruments. Directors Simon Gerovich, Darren Winia and Kelvin Lee will oversee the new company.
Metaplanet described the subsidiary as an operating platform within Project Nova, its plan to develop financial services tied to Bitcoin. The company expects the unit to handle trading, position monitoring and risk controls when U.S. markets are closed.
Metaplanet’s Hong Kong unit will cover Asian hours
Based in Hong Kong, the subsidiary will execute purchases and sales for assets managed by Metaplanet’s investment businesses. Its planned duties include monitoring market conditions and managing positions during the Asian trading day.
The company said its structure would support investment coverage across Asia, the U.S. and Europe. Metaplanet Asset Management Asia will work with the group’s Miami operation, Metaplanet Asset Management, which was established in March 2026.
Miami serves as the group’s central institutional investment hub, while Hong Kong will provide execution and operational support from Asia. Metaplanet described the arrangement as infrastructure for its planned financial-services platform, not a separate change in corporate strategy.
An English reproduction of the company’s filing lists an initial capital contribution of $1 million. Metaplanet will own 100% of the subsidiary.
The disclosure did not provide a launch date for client services, identify initial assets under management or name outside investors. It did not announce that the Hong Kong operation had started managing customer money.
Project Nova turns Bitcoin into a financial-services base
Project Nova covers Metaplanet’s efforts to build securities, asset-management and capital-markets businesses around its Bitcoin treasury. The strategy includes credit products, preferred securities and investment structures connected to Bitcoin-focused companies.
During June, Metaplanet agreed to acquire Japanese brokerage Siiibo Securities for 2.1 billion yen. As crypto.news reported, the acquisition gave Metaplanet a licensed Japanese securities platform capable of distributing investment products.
Metaplanet completed the transaction in July and renamed the business Metaplanet Securities. The brokerage holds a Type I Financial Instruments Business registration in Japan, according to company documents cited in the report.
Working with JPYC and tokenization company Progmat, the group began studying Bitcoin-backed digital credit products. In related coverage, the companies said no product launch or commercial terms had been decided.
Possible structures include digital corporate bonds, security tokens and credit instruments supported by Bitcoin collateral. The participants said future products would require technical reviews, internal approvals and discussions with the relevant authorities.
The Hong Kong filing identifies several possible investment categories, including Bitcoin-related perpetual preferred securities, derivatives and structured-product income strategies. Equity and credit investments involving corporate Bitcoin holders could fall within the unit’s mandate.
No specific fund, preferred security or credit product was announced with the subsidiary. Any planned investment remains subject to the operational and regulatory requirements applying to the relevant product and jurisdiction.
Miami and Hong Kong divide Metaplanet operations
Metaplanet’s Miami business provides the U.S. side of its institutional investment framework. The Hong Kong company is designed to continue execution, monitoring and risk-management work as Asian markets open.
A separate U.S. transaction announced in August would place 2,100 BTC and $2.5 million into Nasdaq-listed Super League Enterprise. As previously reported, Metaplanet expects to secure a 95.7% stake before accounting for certain existing warrants.
Super League plans to change its name to Superplanet and has proposed the Nasdaq ticker SUPA. Metaplanet would appoint five members of the nine-person board under the announced transaction.
The proposed U.S. company would receive 2,100 BTC at closing and could use the assets to support future financing. Any preferred-share issuance would depend on decisions made after the transaction closes, the companies said.
Gerovich described Superplanet as Metaplanet’s route into U.S. capital markets. The agreement includes a five-year lockup covering common shares issued to Metaplanet through the initial transaction, warrant exercises or preferred-stock conversions.
Metaplanet reported 43,000 BTC in its treasury after buying 2,823 BTC during the second quarter. Gerovich later said the balance remained unchanged following transfers between company-controlled custodial addresses.
Crypto.news reported that 5,014 BTC moved between Metaplanet custodial addresses in August. Gerovich said, “No bitcoin was sold, and our holdings remain 43,000 BTC.”
Incorporation and regulatory steps remain ahead
Metaplanet plans to incorporate the Hong Kong subsidiary before the end of September. The filing did not disclose when trading operations would begin or whether the unit had hired employees beyond its three initial directors.
No Hong Kong Securities and Futures Commission license was identified in the announcement. The disclosure did not specify whether the planned activities would operate under a local license, an exemption or another regulated group entity.
Metaplanet said the new subsidiary “is expected to have a minimal impact” on its consolidated results for the fiscal year ending Dec. 31, 2026. The statement remains a management forecast, and the company said it would disclose any material financial effect if one emerges.
The board’s decision came as Metaplanet continued building separate financial operations in Japan and the U.S. It disclosure archive lists the Hong Kong notice alongside recent announcements covering Bitcoin investments, securities operations and changes to its capital structure.

The CLARITY Act has received another round of changes as Senate Republicans try to secure enough Democratic support for Tuesday’s procedural vote on the cryptocurrency market structure bill.
The latest version, which consists of 635 pages, includes an ethics framework backed by President Donald Trump that would restrict public officials from issuing or sponsoring digital assets. The revised text allows both the Department of Justice (DOJ) and the state attorneys general authority to enforce the rules.
Last-Minute Revisions
The change addresses one of the main issues Democrats had raised during negotiations. They had previously objected to an arrangement in which the DOJ would be responsible for enforcing the ethics provisions. The debate over the rules also came from concerns surrounding Trump and his family’s financial involvement in the crypto sector.
US Senate Banking Digital Assets Subcommittee Chair Cynthia Lummis stated,
“After a year of intense daily bipartisan negotiations, this bill is ready. President Trump voluntarily agreed to unprecedented ethics restrictions, holding every federally elected official, judge, and their spouses to some of the toughest ethics restrictions in US history… Democrats got what they wanted; now they need to take yes for an answer.”
The ethics section incorporates much of the Tillis-Gallego proposal. Among its provisions, officials would have to either sell substantial crypto-related financial holdings or move them into a blind trust.
Changes to the Blockchain Regulatory Certainty Act (BRCA) now limit its scope to the Bank Secrecy Act and civil enforcement. Language that would have extended its protections to criminal proceedings, including cases brought under Section 1960, has been taken out. The changes would also bring miners and validators under those protections.
Other Key Details
The bill’s stablecoin yield section has also been revised with a “circuit breaker” mechanism first floated by Tillis in July. It would give federal regulators the ability to step in if stablecoins were causing significant withdrawals from community banks.
Stricter limits on vertical integration have also been introduced, such as rules covering affiliate trading and potential conflicts involving digital commodity exchanges, brokers, and dealers. The text also confirms that state consumer protection laws remain in effect. Developer protections would not override derivatives regulations or change the rules governing prediction markets.
Last week, Coinbase CEO Brian Armstrong voiced support for the CLARITY Act ahead of the Senate vote. Speaking on CNBC’s Squawk Box Asia on September 10, the exec said the bill was ready for approval and claimed support from law enforcement groups, banks, and crypto companies. He also said Coinbase’s main concerns with the legislation had been addressed after the company previously raised several issues it considered essential.
The post Last-Minute Changes to the CLARITY Act: Will Democrats Finally Back the Crypto Bill? appeared first on CryptoPotato.
Senate Republicans released the final Clarity Act text on Sunday, folding in changes Democrats demanded and rewriting the ethics title that had been a sticking point.
The substitute runs 635 pages, 5 longer than the September 10 draft. Senators vote Tuesday afternoon on cloture for the motion to proceed, which needs 60 votes.
The Clarity Act Ethics Division Gets Rebuilt
Senators Cynthia Lummis, John Boozman, and Tim Scott said the text reflects more than a year of bipartisan negotiations. Their office counted 126 substantive edits that Democrats asked for.
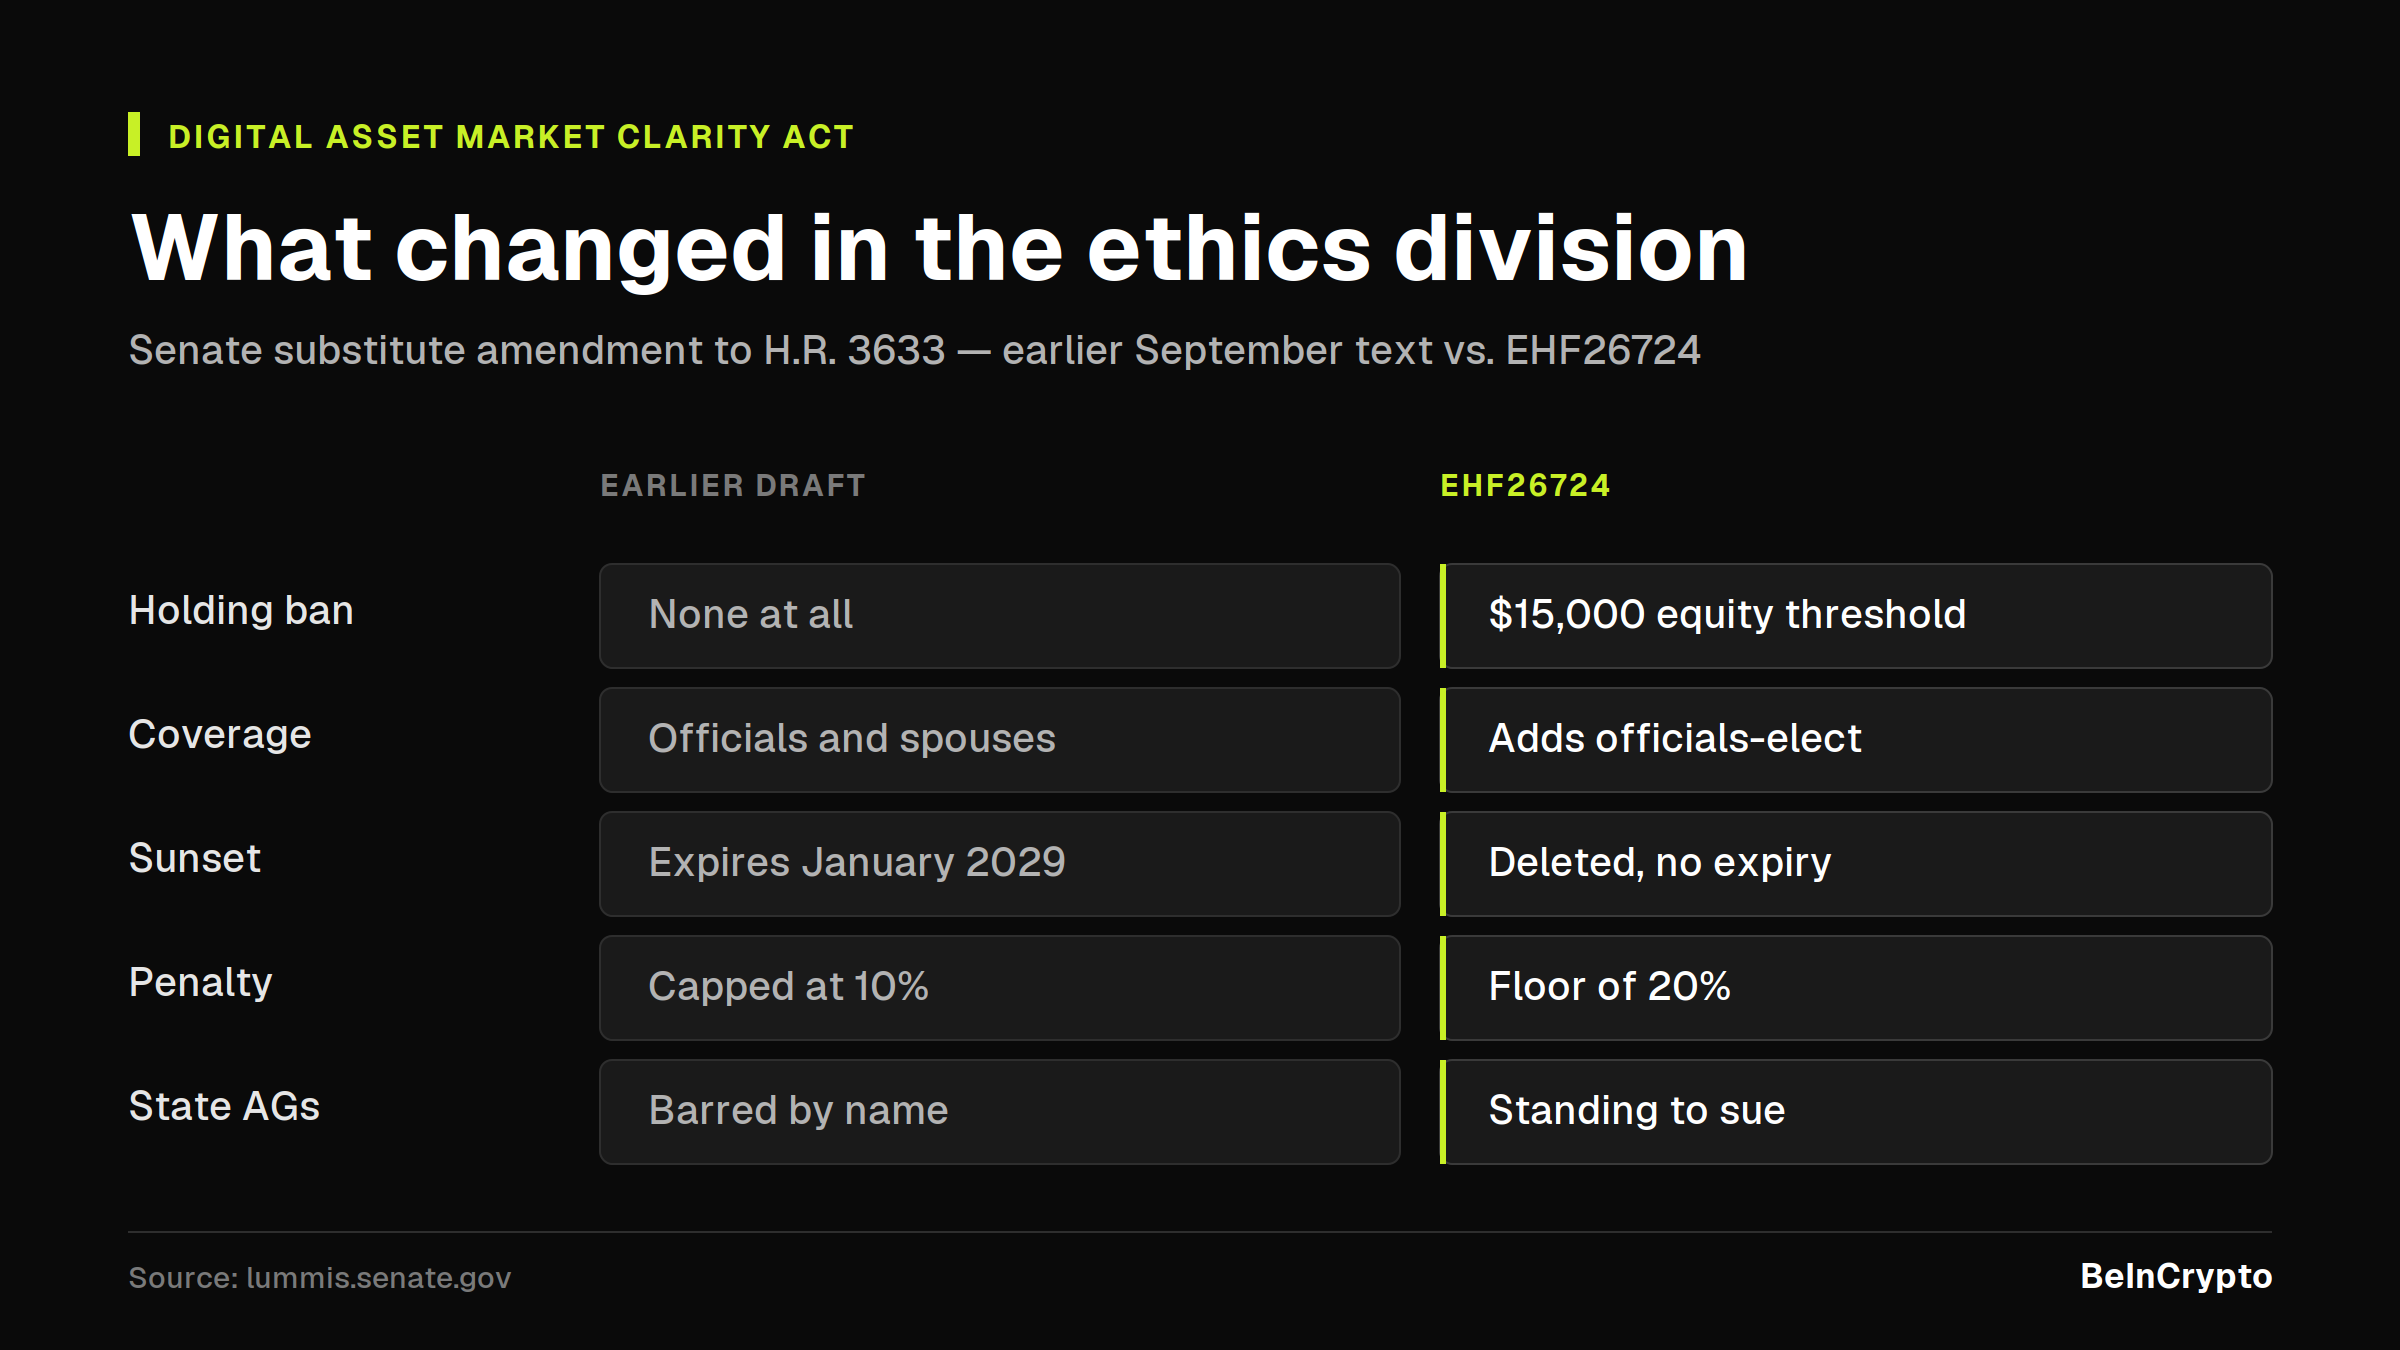
The newer draft (EHF26724) toughens the Clarity Act in several places that the industry will feel. The ethics division is the headline. It’s retitled and rebuilt:
- New ban on holding a “significant financial interest,” meaning $15,000-plus of equity in any business that drew a plurality of its revenue from issuing or sponsoring tokens in any of the past 3 years, with mandatory divestment or a blind trust. The earlier September draft had no holding ban at all.
- Coverage extended to presidents-elect, vice presidents-elect, and members-elect, before they’re sworn in.
- But it still stops at spouses. Children and dependents aren’t covered, a narrower reach than the federal disclosure law, which requires officials to report dependent children’s holdings.
- The 2029 sunset is deleted, along with the severability clause.
- Penalties flip from a 10% cap to a 20% floor, inflation-adjusted, and now apply to the interest itself as well as the transaction.
- State attorneys general gain standing to sue. The earlier draft barred them and private plaintiffs by name, and that subsection is gone.
Follow us on X to get the latest news as it happens

What the Final Clarity Act Text Does Outside the Ethics Title
Elsewhere, the exchange own-account rule is retitled a prohibition on proprietary trading, and its exceptions narrow from activities “in support of the business” to a test of what is “necessary,” subject to new CFTC rules.
Exchanges and wallets, not issuers, face a circuit-breaker: if Treasury finds within 18 months that community-bank deposits are bleeding into stablecoins, it must write rules reaching yield merely “similar to” bank interest, a lower bar than the ban already in the bill, and a threat to exchange rewards programs.
“Network token” now means a digital asset rather than a digital commodity, a broader category. States keep deceptive-practices enforcement unless preempted. CFTC exemptions must run through the CEA’s Section 4(c) process.
One trade cuts the other way. Software developers gain shields against BSA registration and financial institution status, but lose the express protection from criminal money-transmitting liability that the earlier draft gave them.
Republicans Say This Is the Last Version Democrats Get
The rewrite landed days after President Donald Trump met with advisers on Friday to discuss the ethics language. Journalist Eleanor Terrett reported that Republicans are pitching the draft as their last and best offer before Tuesday’s cloture vote.
“President Trump voluntarily agreed to unprecedented ethics restrictions, holding every federally elected official, judge, and their spouses to some of the toughest ethics restrictions in U.S. history,” Senator Lummis said.
Lummis framed the vote as a test of whether Democrats will take the deal they negotiated.
“A no vote on Tuesday means opposing real ethics reforms on politicians’ personal investments… Democrats got what they wanted; now they need to take yes for an answer,” she added.
Whether the rewritten ethics title buys the seven Democratic votes Republicans still need becomes clear tomorrow.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights
The post Republicans Release Final Clarity Act Text Before Tuesday's Vote. Here's What Changed appeared first on BeInCrypto.
Senate Democrats have met to assess a final 635-page Republican CLARITY Act proposal before a Sept. 15 procedural vote requiring 60 senators to begin debate.
Summary
- Politico reported Senate Democrats met before Tuesday’s cloture vote as Republicans sought seven opposition-party votes.
- Republicans released a 635-page CLARITY Act draft containing 126 changes requested by Democratic negotiators Sunday.
- Trump accepted revised ethics restrictions covering federal officials, judges, lawmakers and their spouses’ digital assets.
- Treasury would receive circuit-breaker authority if payment stablecoins trigger widespread deposit flight from community banks.
- Sixty votes are required to begin debate; Tuesday’s action will not determine final passage yet.
Politico reported that Senate Minority Leader Chuck Schumer convened the Democratic caucus on Sunday evening after Republicans released the revised text. No Democratic leader had announced the caucus’s position on the motion as of Sept. 14.
Senate Banking Digital Assets Subcommittee Chair Cynthia Lummis released the proposal with Senate Banking Committee Chair Tim Scott and Senate Agriculture Committee Chair John Boozman. Their statement called the draft the product of more than one year of negotiations and said it incorporated 126 substantive changes requested by Democrats.
A Republican aide described the proposal to Politico as the party’s “last, best and final” offer before Tuesday’s vote. Republicans hold 53 Senate seats, so at least seven members of the Democratic caucus must support cloture if every Republican votes yes.
CLARITY Act ethics text puts pressure on Democrats
Government ethics rules have remained the main obstacle in negotiations. Democratic senators have sought restrictions addressing the ability of elected officials and their families to profit from digital assets while influencing federal policy.
Republican sponsors said President Donald Trump accepted provisions based on “substantially all” of an ethics proposal developed by Sens. Thom Tillis and Ruben Gallego. The sponsors said the rules would cover federally elected officials, federal judges and their spouses.
Eleanor Terrett reported that the proposal would require covered officials to divest certain “substantial” crypto-related financial interests or place them in a blind trust. Her account attributed the description to a Republican aide familiar with the negotiations.
The revised enforcement structure gives state attorneys general a role after earlier drafts concentrated authority within the federal government. Politico reported that state officials could pursue action involving the Justice Department or crypto exchanges when they believe the restrictions are not being enforced.
Lummis said Trump had voluntarily agreed to the new provisions. Her claim that the text creates some of the toughest ethics restrictions in U.S. history represents the sponsors’ assessment and has not been endorsed by Democratic negotiators.
Democrats must now decide whether the revised language adequately addresses their concerns about Trump-linked digital asset businesses. Incorporating requested amendments does not bind the senators who proposed them to support the entire bill.
Stablecoin circuit breaker targets deposit flight
The final draft gives the Treasury secretary new authority to respond to deposit movements linked to payment stablecoins. Sponsors described the provision as a circuit breaker intended to protect community banks if stablecoin products draw deposits away from insured institutions.
Banking groups have argued that stablecoin rewards can function like interest-bearing accounts and compete directly with bank deposits. Crypto companies maintain that overly broad restrictions could prevent platforms from providing lawful customer incentives that do not originate from stablecoin issuers.
The new language would allow federal intervention when authorities find evidence of widespread deposit flight. Treasury Secretary Scott Bessent would hold the central decision-making role under the reported proposal.
As previously reported, the Sept. 15 Senate test will open debate without approving the bill. The stablecoin provision may still face amendments if senators agree to proceed.
The measure follows the GENIUS Act’s federal rules for payment stablecoin issuers. CLARITY addresses a separate question by setting rules for digital asset trading markets and dividing authority between the Securities and Exchange Commission and Commodity Futures Trading Commission.
Developer protections lose their criminal safe harbor
The revised Blockchain Regulatory Certainty Act language would shield qualifying software developers from federal money-transmission registration requirements. Republican sponsors said the text creates a civil safe harbor for developers who do not control customer funds.
Terrett reported that negotiators narrowed the provision to Bank Secrecy Act requirements and civil enforcement. Earlier language expressly extending protection to criminal cases, including prosecutions under Section 1960, was removed from the final offer.
Section 1960 covers unlicensed money-transmitting businesses. Its removal means the revised developer language does not provide the explicit criminal protection contained in previous versions, according to Terrett’s description of the changes.
The Agriculture Committee section places new limits on affiliate trading and conflicts involving digital commodity exchanges, brokers and dealers. It clarifies that state consumer-protection laws continue to apply to activities covered by the measure.
Developer protections in the agriculture section would not create exemptions from derivatives law or change the CFTC’s existing authority over prediction markets. Those clarifications respond to concerns that software protections could unintentionally reach regulated derivatives activity.
The full proposal would establish registration paths for digital commodity exchanges, brokers and dealers. It would give the CFTC authority over covered spot digital commodity markets while preserving SEC jurisdiction over securities and investment contracts.
Tuesday’s vote only decides whether debate begins
Senate Majority Leader John Thune scheduled cloture on the motion to proceed to H.R. 3633 for 2:15 p.m. Eastern on Sept. 15. The motion generally requires 60 votes under Senate rules.
Crypto.news previously reported that Republicans need at least seven Democratic votes if their conference remains united. The required number would rise if Republican senators oppose the motion or miss the vote.
If cloture succeeds, Lummis, Boozman and Scott plan to offer the 635-page text as an amendment in the nature of a substitute. The amendment would replace the text currently attached to the House-passed legislative vehicle.
Senators could then debate the proposal and consider further amendments. Passage would require another set of procedural and final votes, while any changes from the House version would require the House to accept the Senate text or negotiate a common bill.
The House passed its CLARITY Act version by 294-134 in July 2025. The Senate Banking Committee advanced its portion by 15-9 in May 2026, when Democratic Sens. Gallego and Angela Alsobrooks joined Republicans.
Committee support did not guarantee votes for the combined floor text. The final version now includes the Banking Committee framework, Agriculture Committee provisions, the revised ethics title, stablecoin language and developer protections.
If Tuesday’s motion fails, Senate leaders may reconsider it or negotiate another version. Senate rules do not automatically send the measure back to committee, and a failed cloture vote would not enact or reject the underlying regulatory provisions. The first recorded vote is scheduled for 2:15 p.m. Eastern. If 60 senators support cloture, the final Republican text will be offered as the substitute amendment during floor consideration.

How to claim a free gym pass in County Durham this September
AirBaltic files for Chapter 11 bankruptcy in New York

South Korea CBDC plan draws warning over privacy risks


-
 Tech6 days ago
Memory prices are slowing because buyers ran out of money
-

 Tech18 hours ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Business4 days ago
Micron Stock Climbs Above $1,031 as AI Memory Crunch and a $50 Billion Outlook Fuel the Rally
-

 Business4 days ago
AMD Stock Climbs After Management Lifts 2027 Data Center Outlook Toward $70 Billion in AI Sales
-
 Crypto World5 days ago
Bitcoin price risks $76K drop as $78K support weakens
-

 Fashion3 days ago
Weekend Open Thread – Corporette.com
-
 Crypto World6 days ago
Robinhood Stock: How To Take Advantage With Reduced Risk
-

 Crypto World3 days ago
XAG/USD: Silver’s Short-Term Rally Meets Its Moment of Truth
-

 Crypto World4 days ago
2 Chip Stocks Broke Out This Week. Neither Was Nvidia
-
 Crypto World5 days ago
Ethereum price stalls below $2,500 as ADX drops to 11
-
 NewsBeat6 days ago
England up in reading, maths and science rankings as Scotland and Wales dip
-

 Business3 days ago
10 Most-Streamed Songs On Spotify In 2026 So Far, Led By Ella Langley’s Dominant Run On The Charts This Year
-

 Crypto World3 days ago
OKX launches 10x OpenAI, Anthropic X-Perps in Europe
-

 Tech3 days ago
Battery life is the only iPhone 18 Pro and iPhone Duo upgrade I care about. Apple didn’t disappoint
-

 Crypto World3 days ago
Diesel Tops $6 a Gallon for the First Time as 28 States Set Records
-
 Crypto World6 days ago
Intel Stock Jumps 9% on Chip Price Hike Report, US Stake Gains $36 Billion
-

 Tech4 days ago
Apple Watch Ultra 4 vs Watch Ultra 3: Should you really spend another $799?
-

 Crypto World4 days ago
Bitcoin price risks $70K if $78K neckline breaks
-
 Crypto World6 days ago
Pump Fun and Kraken delete Hunter Biden $LAPTOP promotion
-
 NewsBeat5 days ago
What went right this week: an ‘historic’ fall in violent crime, plus more
You must be logged in to post a comment Login