
Business
(VIDEO) Apple Reportedly Building iPhone Game Controllers Under Beats Brand as Mobile Gaming Push Gains Steam

KEY POINTS
Apple Reportedly Building iPhone Game Controllers Under Beats Brand as Mobile Gaming Push Gains Steam
CUPERTINO, Calif. — Apple is developing its own game controllers for the iPhone, according to a new report, in a move that would give the company its first first-party hardware built specifically for traditional gaming input after years of relying on outside accessory makers.
Bloomberg’s Mark Gurman reported in his Power On newsletter that the controllers have been in development for more than a year and will likely carry Beats branding rather than Apple’s own name. “Apple sees this as a growing market and wants in,” Gurman wrote, adding that Beats executives are leading the project’s conception and engineering. Apple has not officially announced either device, and no information on pricing or availability has emerged.
The report corroborates earlier evidence uncovered directly in Apple’s software. Code found in the first release candidate of macOS 26.7 referenced two unreleased hardware devices identified internally as T6502 and T1057, each carrying its own dedicated GameController profile rather than generic placeholder code. The references were first spotted by a MacRumors reader going by the name Pdfu, who has continued digging through the beta code for additional detail.
According to that code, both devices include the hardware components expected of a modern gamepad, including a directional pad, dual thumbsticks, shoulder buttons, Home and Menu buttons, and analog triggers. The two controllers differ meaningfully in design, however. T1057 includes support for an accelerometer and gyroscope along with more advanced haptic feedback, suggesting a wireless, motion-sensing design, while T6502 lacks that motion-sensing hardware, pointing to a simpler, likely wired controller aimed at a different segment of the market. The presence of dedicated hardware plug-ins for each device, rather than shared generic code, has been cited by developers examining the leak as evidence that these are real products in active development rather than abandoned experiments.
Notably, the references to both controllers were removed from a subsequent release candidate of macOS 26.7. That removal does not necessarily indicate the project has been shelved, as Apple routinely strips references to unannounced hardware from public builds once they draw outside attention, but it does mean there is currently no confirmation that either device will reach the market as a commercial product.
The choice of Beats as the likely brand for the controllers would continue a pattern Apple has used before when entering new or lower-margin product categories. Acquired by Apple in 2014, Beats has expanded well beyond its original headphone lineup in recent years, adding charging cables, iPhone cases and other accessories to its catalog. Beats products typically target more affordable price points using less premium materials and finishes than Apple’s own branded hardware, an approach that would make sense for a gaming controller aimed at a broad consumer audience rather than a premium niche. Analysts covering the report noted that positioning the accessory under Beats would also give Apple more flexibility on price and design without affecting perceptions of its flagship hardware lineup.
Apple’s potential entry into the controller market comes as the company has increasingly built out the software infrastructure to support serious mobile gaming, even without offering its own physical controller. iOS 26 introduced a dedicated Games app that consolidates a user’s game library, Game Center friend connections and Apple Arcade titles into a single hub spanning iPhone, iPad, Mac and Apple TV. Apple Arcade itself has grown to include more than 250 titles for a monthly subscription price of $6.99. A first-party controller, even one carrying Beats branding rather than the Apple logo, would give that existing software ecosystem a dedicated physical companion for the first time.
Apple devices already support a range of third-party controllers through the Made for iPhone accessory program, including gamepads from Backbone and SteelSeries, as well as traditional console controllers such as Sony’s DualShock and Microsoft’s Xbox Wireless Controller. Apple’s own retail stores currently stock several of those third-party options, including the Backbone One and SteelSeries Nimbus, meaning a first-party Beats controller would put Apple in the position of competing directly with products it currently sells alongside its own devices.
The company has touted the gaming capabilities of its custom silicon in the past, at times highlighting benchmark comparisons between its chips and dedicated gaming consoles during product presentations, even as it has largely avoided pursuing hardware built specifically around traditional console-style gaming input. A first-party controller, should it reach the market, would mark a shift in that approach and could also extend to strengthening Apple’s gaming ecosystem on Apple TV 4K, where third-party controller support has so far been the primary way to play more demanding titles.
Because the current evidence is limited to internal code references and a single report citing unnamed sourcing, key details remain unknown, including how the two controllers might be positioned relative to each other, what they might cost, and when Apple might be prepared to announce them. Apple has a history of testing internal code for products that are later delayed, altered significantly, or canceled outright before reaching consumers, meaning the project’s ultimate fate remains uncertain even with the added specificity provided by the newly surfaced model identifiers and hardware profiles.
For now, Apple has made no public comment on the reported controllers, and the company is not expected to confirm or deny unreleased hardware projects ahead of an official announcement, following its typical practice with products still in development.
CUPERTINO, Calif. — Apple is developing its own game controllers for the iPhone, according to a new report, in a move that would give the company its first first-party hardware built specifically for traditional gaming input after years of relying on outside accessory makers.
Bloomberg’s Mark Gurman reported in his Power On newsletter that the controllers have been in development for more than a year and will likely carry Beats branding rather than Apple’s own name. “Apple sees this as a growing market and wants in,” Gurman wrote, adding that Beats executives are leading the project’s conception and engineering. Apple has not officially announced either device, and no information on pricing or availability has emerged.
The report corroborates earlier evidence uncovered directly in Apple’s software. Code found in the first release candidate of macOS 26.7 referenced two unreleased hardware devices identified internally as T6502 and T1057, each carrying its own dedicated GameController profile rather than generic placeholder code. The references were first spotted by a MacRumors reader going by the name Pdfu, who has continued digging through the beta code for additional detail.
According to that code, both devices include the hardware components expected of a modern gamepad, including a directional pad, dual thumbsticks, shoulder buttons, Home and Menu buttons, and analog triggers. The two controllers differ meaningfully in design, however. T1057 includes support for an accelerometer and gyroscope along with more advanced haptic feedback, suggesting a wireless, motion-sensing design, while T6502 lacks that motion-sensing hardware, pointing to a simpler, likely wired controller aimed at a different segment of the market. The presence of dedicated hardware plug-ins for each device, rather than shared generic code, has been cited by developers examining the leak as evidence that these are real products in active development rather than abandoned experiments.
Notably, the references to both controllers were removed from a subsequent release candidate of macOS 26.7. That removal does not necessarily indicate the project has been shelved, as Apple routinely strips references to unannounced hardware from public builds once they draw outside attention, but it does mean there is currently no confirmation that either device will reach the market as a commercial product.
The choice of Beats as the likely brand for the controllers would continue a pattern Apple has used before when entering new or lower-margin product categories. Acquired by Apple in 2014, Beats has expanded well beyond its original headphone lineup in recent years, adding charging cables, iPhone cases and other accessories to its catalog. Beats products typically target more affordable price points using less premium materials and finishes than Apple’s own branded hardware, an approach that would make sense for a gaming controller aimed at a broad consumer audience rather than a premium niche. Analysts covering the report noted that positioning the accessory under Beats would also give Apple more flexibility on price and design without affecting perceptions of its flagship hardware lineup.
Apple’s potential entry into the controller market comes as the company has increasingly built out the software infrastructure to support serious mobile gaming, even without offering its own physical controller. iOS 26 introduced a dedicated Games app that consolidates a user’s game library, Game Center friend connections and Apple Arcade titles into a single hub spanning iPhone, iPad, Mac and Apple TV. Apple Arcade itself has grown to include more than 250 titles for a monthly subscription price of $6.99. A first-party controller, even one carrying Beats branding rather than the Apple logo, would give that existing software ecosystem a dedicated physical companion for the first time.
Apple devices already support a range of third-party controllers through the Made for iPhone accessory program, including gamepads from Backbone and SteelSeries, as well as traditional console controllers such as Sony’s DualShock and Microsoft’s Xbox Wireless Controller. Apple’s own retail stores currently stock several of those third-party options, including the Backbone One and SteelSeries Nimbus, meaning a first-party Beats controller would put Apple in the position of competing directly with products it currently sells alongside its own devices.
The company has touted the gaming capabilities of its custom silicon in the past, at times highlighting benchmark comparisons between its chips and dedicated gaming consoles during product presentations, even as it has largely avoided pursuing hardware built specifically around traditional console-style gaming input. A first-party controller, should it reach the market, would mark a shift in that approach and could also extend to strengthening Apple’s gaming ecosystem on Apple TV 4K, where third-party controller support has so far been the primary way to play more demanding titles.
Because the current evidence is limited to internal code references and a single report citing unnamed sourcing, key details remain unknown, including how the two controllers might be positioned relative to each other, what they might cost, and when Apple might be prepared to announce them. Apple has a history of testing internal code for products that are later delayed, altered significantly, or canceled outright before reaching consumers, meaning the project’s ultimate fate remains uncertain even with the added specificity provided by the newly surfaced model identifiers and hardware profiles.
For now, Apple has made no public comment on the reported controllers, and the company is not expected to confirm or deny unreleased hardware projects ahead of an official announcement, following its typical practice with products still in development.

BlackRock Large Cap Focus Growth Fund Q2 2026 Commentary
Business
Amazon Stock Trades at Rare Discount as Andy Jassy Bets $220 Billion on AWS to Fuel Next Trillion-Dollar Leg
SEATTLE — Amazon.com Inc. has grown into one of the most valuable companies in the world under founder Jeff Bezos and his successor, Andy Jassy, and investors are now watching to see whether a sharply higher spending plan tied to artificial intelligence and cloud computing can push the company’s value even further.
Bezos founded Amazon in 1994 and led the company through its May 1997 initial public offering, building it from a market capitalization of under $500 million into a $1.8 trillion company by the time he stepped down as chief executive on July 5, 2021. Jassy, who succeeded him, has overseen a roughly 50% increase in Amazon’s market value since taking over, pushing the company’s worth to about $2.7 trillion.
Before becoming CEO, Jassy helped build and run Amazon Web Services, the cloud-computing division that has since become the company’s largest source of profit. AWS remains the leading cloud infrastructure provider globally, holding a 28% market share as of the second quarter of 2026, ahead of Microsoft’s Azure at 20% and Alphabet’s Google Cloud at 15%, with the remaining share split among a range of smaller competitors.
AWS’s growth has accelerated sharply over the past year as demand for generative artificial intelligence services has surged. In its second-quarter results reported July 30, Amazon said AWS revenue rose 37% year-over-year to $42.2 billion, up from $30.9 billion a year earlier, marking the unit’s fastest growth in 18 quarters and its fifth consecutive quarter of accelerating growth, according to Jassy. AWS operating income climbed 64% to $16.6 billion, with the division’s operating margin expanding to 39.4% from 32.9% a year earlier. AWS accounted for roughly 60% of Amazon’s total operating profit during the quarter.
“AWS is now a $169 billion annualized revenue run rate business, which, for perspective, would place it 24th on the Fortune 500 list if it was a stand-alone company,” Jassy told analysts on the earnings call. He also described the broader cloud business succinctly, saying AWS “is booming.” The unit’s backlog of customer agreements representing future revenue grew to $496 billion, giving the company visibility into demand well beyond the current quarter.
Across all of Amazon’s businesses, including its retail stores, advertising, Prime subscriptions, devices and cloud operations, net sales rose 20% year-over-year to $200.6 billion in the second quarter, while operating income climbed 43% to $27.5 billion. “We’re reporting $200.6 billion in revenue, up 20% year-over-year. Operating income was $27.5 billion, up 43% year-over-year. Q2 was another very strong quarter for Amazon,” Jassy said.
That growth has come alongside a significant increase in spending. Amazon raised its full-year 2026 capital expenditure guidance to approximately $220 billion, up from a prior estimate of about $200 billion, with the company attributing the increase primarily to higher memory costs tied to building out AI and data center infrastructure. “We now believe we will spend approximately $220 billion in cash CapEx in 2026. The higher cost of memory pushing this number up from our prior estimate of about $200 billion,” Jassy said on the call. Capital expenditures during the second quarter alone reached $54.2 billion, compared with $32.1 billion in the same period a year earlier.
Even at that elevated level of spending, Jassy told investors the company still won’t have enough capacity to satisfy the demand it’s seeing. “Even at that amount, we will still not have enough capacity to meet all the demand we have in 2026,” he said, adding, “I believe this dynamic will also be true in 2027, too.” AWS is targeting a doubling of its power capacity by the end of 2027 compared with 2025 levels, underscoring the scale of the infrastructure buildout underway.
The heavy investment cycle has pressured some near-term financial metrics. Amazon’s trailing 12-month free cash flow swung to a multibillion-dollar outflow as the company accelerated purchases of property and equipment, primarily to expand AI infrastructure. Despite that pressure, shares surged more than 10% in extended trading following the earnings release, as investors focused on AWS’s accelerating growth rather than the near-term cash flow impact.
Much of that spending is directed toward AWS’s data center footprint, networking equipment and computing hardware, including both Nvidia graphics processing units and Amazon’s own in-house Trainium and Graviton chips. Both of those homegrown chip lines have individually surpassed a $25 billion annual revenue run rate, according to the company, as Amazon looks to reduce its reliance on external chip suppliers while building out AI infrastructure at scale. Amazon’s Bedrock model marketplace, aimed primarily at enterprise customers, has also become a growing part of the company’s broader AI product strategy.
Despite the scale Amazon has already achieved, its stock currently trades at what analysts describe as an unusually attractive valuation relative to its own history, a rarity for a company of its size and track record. The gap has emerged even as capital expenditures have climbed sharply, with some investors expressing concern about the near-term payoff of such a steep increase in spending. Given AWS’s growth trajectory and dominant position in cloud infrastructure, however, the investment in data center capacity is widely viewed by market watchers as a calculated bet on sustained demand rather than a departure from the company’s historically disciplined approach to capital allocation.
With AWS still expanding at its fastest pace in more than four years and demand for artificial intelligence infrastructure showing no signs of slowing, Jassy’s strategy of funneling record sums into data centers and custom silicon is shaping up as the next major test of whether Amazon can replicate the kind of sustained profit growth that carried the company from a startup bookseller to a $2.7 trillion technology giant under his predecessor.
Business
HDFC Bank shares hit 52-week lows over consecutive sessions while analysts scream Buy. Has the stock hit its bottom?
The stock of India’s largest private lender dropped to a fresh 52-week low of Rs 681.90 apiece on Friday. This marks more than a 33% fall in less than 11 months after hitting a record high of Rs 1,020.50 apiece in October last year.
The sharp selloff in HDFC Bank shares began in March this year after its former part-time Chairman Atanu Chakraborty resigned, stating that some practices within the bank did not match his personal values and ethics. The governance cloud led to a massive selloff that recovered slightly after the bank made leadership changes.
HDFC Bank’s board has submitted two candidates to the Reserve Bank of India (RBI) for the role of CEO, formally beginning the succession process for Sashidhar Jagdishan, who is due to retire later this year, the country’s largest private lender said on Saturday.
Also read | HDFC Bank submits two candidates to RBI for next CEO

Bullish brokerage calls for HDFC Bank share price
Goldman Sachs last month initiated coverage on HDFC Bank with a ‘Buy’ call and a target price of Rs 861 apiece. Goldman Sachs noted the bank’s core-PPOP inflection driven by margins and operating leverage, along with attractive valuations.
The Wall Street giant initiated coverage with a ‘Buy’ rating due to compelling valuations, despite expecting further downside earnings revisions. Nomura and Motilal Oswal Financial Services also have ‘Buy’ calls on HDFC Bank shares.
HDFC Bank shares technical setup is ‘highly uninspiring’
HDFC Bank shares have been the weakest among all Nifty Bank constituents, declining 29% so far in 2026. Not only has the performance been disappointing this calendar year, but the stock has also delivered weak returns over the past three to five years, declining nearly 14% and 9%, respectively. “Despite the significant underperformance of this banking heavyweight, there are still no meaningful signs of a turnaround, with the technical setup remaining highly uninspiring and weak,” said Hitesh Rathi, Technical Analyst (Equity & Derivatives) at Angel One.
He noted that in the long term, the stock has slipped below its 20 and 50 EMAs and has remained below both averages for six consecutive months, marking the first such occurrence since its listing and underscoring the deterioration in its long-term technical structure. A similar bearish setup is emerging on the point & figure charts, where the stock has triggered a follow-through double bottom sell for the first time since 2011. The current setup is particularly concerning given the follow-through selling witnessed subsequently, which was notably absent during previous instances of a similar pattern, the analyst said while explaining the technical charts for HDFC Bank.
Also read | Four rules made HDFC Bank a compounder. All four have stopped. Can the new CEO rewrite them?
Are HDFC Bank shares set for a trend reversal?
The stock is now displaying oversold readings across several technical parameters, while the significant disparity in its performance also leaves room for a short-term bounce, according to Rathi. “Hence, a near-term recovery cannot be ruled out. However, the broader technical setup and trend remain firmly bearish, with no meaningful signs of a trend reversal visible at this stage,” he added.
Dnyanada Vaidya, Research Analyst on BFSI at Axis Direct, also noted that the valuations post the sharp correction are attractive and the downside risk appears limited. Clarity around MD & CEO appointment will remain a key monitorable. “From an operational standpoint, we believe the bank is likely to witness margin improvement, though it would be a multi-quarter journey, supported by multiple levers. Similarly, growth is also showing signs of improvement. We expect HDFC Bank to consistently deliver RoA of 1.8-1.9% over the medium term,” the analyst said while recommending a ‘Buy’ call on the stock.
Also read | HDFC CEO race: One insider, one outsider in contention for the top job
Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.

AirBaltic files for Chapter 11 bankruptcy in New York
Business
Jefferies says Sebi’s proposed CAS changes will remove uncertainty, but still remains negative on BSE. Here’s why
On Saturday, Sebi proposed two options for determining expiry-day settlement prices for index and stock derivatives. The consultation paper also proposed changes to the timing of the continuous trading session (CTS), CAS and derivatives trading, along with additional measures to improve the new session.
Jefferies on Monday highlighted that CAS, which was introduced by Sebi in August, initially resulted in higher losses for domestic prop traders due to volatility in index prices during the last hour on expiry day. Sebi’s latest consultation paper addressed concerns around CAS by changing settlement price of derivatives to volume weighted average (VWAP) or a blend between VWAP and CAS, discontinuing cancellations of limit orders placed beyond +/- 1% of reference price during CAS, reducing concerns around manipulation of settlement price, and unexecuted iceberg orders may be transitioned to CAS, increasing liquidity during the CAS window, the international brokerage said.
Also read | Sebi proposes new CAS framework, two options for expiry-day settlement
“Our discussions with domestic prop traders indicate the return to VWAP-based derivative settlement price along with inability to cancel limit orders placed beyond +/-1% threshold should reduce end of period volatility on expiry days,” Jefferies said, noting that the last date to submit responses to Sebi’s consultation paper is October 3, so the implementation will likely be from October or November this year.
While options premium turnover and orders were adversely impacted during August 2026, both have recovered in September so far as option traders had a better understanding of CAS, according to the analysts.
Why Jefferies remains negative on BSE share price?
Despite its positive view on the latest proposals on CAS, Jefferies remains negative on BSE. It maintained its ‘Underperform’ rating on the shares of Asia’s oldest stock exchange, with a target price of Rs 2,940 apiece, implying more than 13% downside potential from the stock’s previous closing price of Rs 3,384 apiece.The international brokerage’s negative stance on BSE shares is driven by the overall options industry barely growing over the past two years, while market-share gains appear to be nearing a ceiling, with expiry-day Sensex and Nifty ADTO now at similar levels.
Further, RBI’s tightening of bank guarantee norms could adversely impact premium turnover by up to 10% over the next year, it said, adding that BSE will also potentially undergo a management transition by June 2027.
Also read | Explained: What Sebi’s proposed CAS changes mean for expiry-day trading and settlement
Why Jefferies prefers Groww share price?
Jefferies thinks Groww is a better way of playing India’s equity story. It should also benefit from CAS issues being resolved as F&O accounts for around 55% of the company’s revenues, it said. “We believe the company has several levers to drive 30% PAT CAGR over FY26-29,” Jefferies said, adding that is driven by an 18% growth in broking business led by client vintage and market share gains, new initiatives like margin trading facility and wealth management, and 10pp margin expansion.
Further, Groww is adding US stocks later in FY27, which the international brokerage estimates could add 5-9% to FY28 earnings. Jefferies has a ‘Buy’ call on the shares of Groww-parent Billionbrains Garage Ventures and a target price of Rs 240 apiece, implying nearly 20% upside potential from the stock’s previous closing price of Rs 200.24 apiece on NSE.
What is CAS?
Stock exchanges introduced the new CAS system from August 3, changing the way closing prices are calculated for stocks included in the futures and options (F&O) segment. Under CAS, continuous trading in stocks that also have F&O contracts ends at 3:15 pm. However, this does not mean these stocks are closed for the day 15 minutes before the broader market shuts.
From 3:15 pm onwards, these stocks move into the CAS, a 20-minute auction process that runs until 3:35 pm to determine their official closing prices. Meanwhile, stocks that are not part of the F&O segment continue to trade as usual until 3:30 pm.
During the 20-minute auction window, buy and sell orders for eligible stocks are collected and matched at a single equilibrium price. This mechanism is aimed at improving price discovery and reducing the impact of last-minute trades on closing prices.
Also read |Jefferies’ 25% CAGR club: Paytm, Groww among 5 financial stocks that can deliver up to 25% returns
Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.

Eco Buildings nears completion of first Albania apartment block
Business
Mariska Hargitay Says She’s ‘Still Floating’ From Taylor Swift and Travis Kelce’s Intimate MSG Wedding
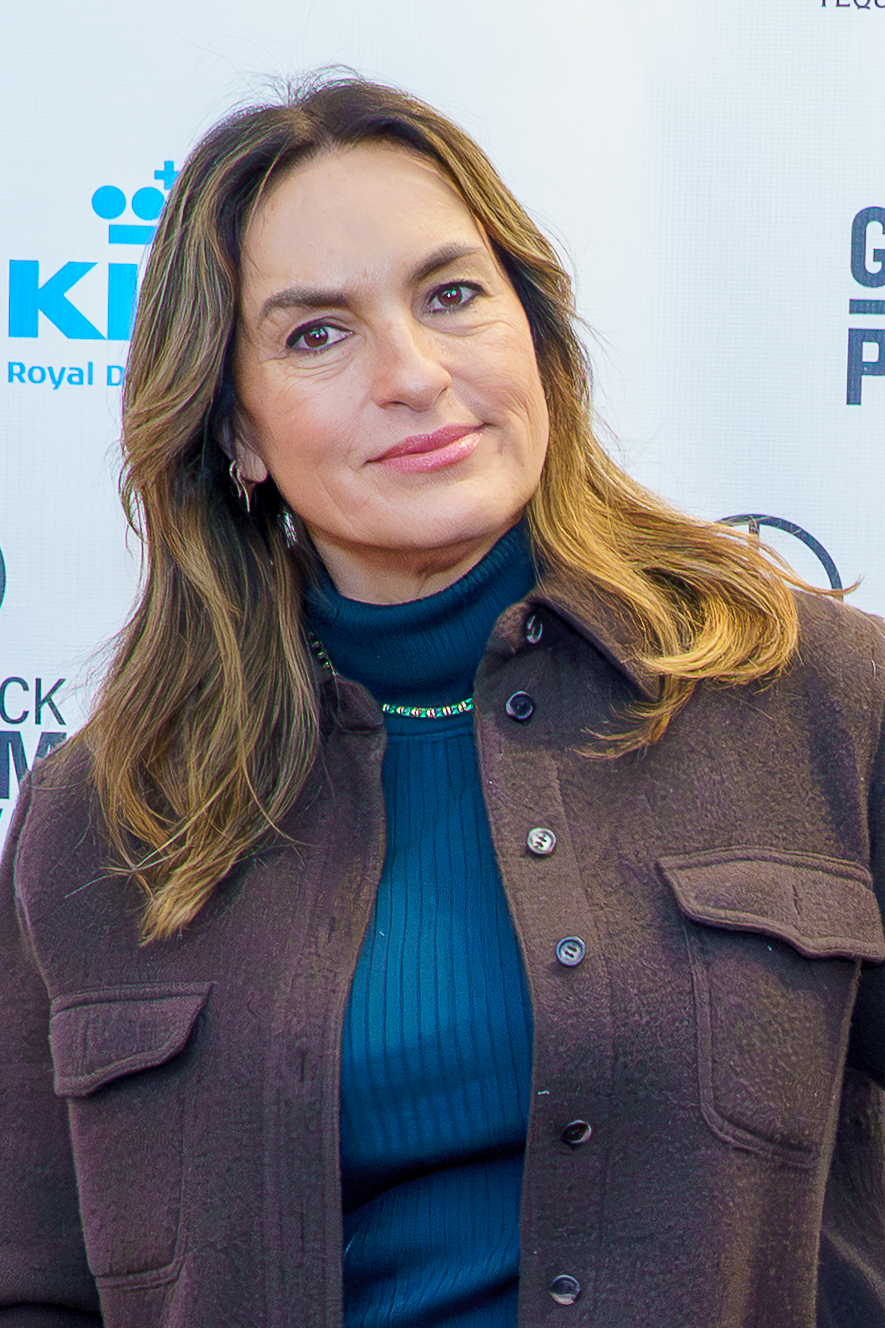
LOS ANGELES — More than two months after Taylor Swift and Travis Kelce exchanged vows at Madison Square Garden, longtime Swift friend Mariska Hargitay says she still hasn’t come down from the experience, telling Jimmy Kimmel this week that the star-studded celebration felt surprisingly personal despite its massive scale.
Hargitay, the “Law & Order: SVU” star, appeared on “Jimmy Kimmel Live!” on Wednesday, September 9, where she opened up about attending the couple’s July 3 wedding in New York City. “I’m still floating from that wedding,” Hargitay said. “It was so spectacular and so intimate, I have to say. I have to say, I am blown away, because when there’s a wedding with that many guests, you think, like, ‘Oh, okay, it’s gonna be that.’ And it just wasn’t.”
The wedding, held at the iconic Manhattan arena, drew an estimated 1,000 guests, including a roster of A-list celebrities and industry figures. Hargitay, 62, attended alongside her husband, actor Peter Hermann, 59. Despite the sprawling guest list and the scale of the venue, Hargitay said the night managed to feel deeply personal, and when Kimmel asked her to single out a favorite moment, she pointed to the couple’s vows rather than any of the wedding’s more lavish elements.
“I even say that the vows were my favorite part of the whole wedding,” Hargitay told Kimmel. “It was that magical.”
Hargitay’s appearance added another firsthand account to the steady trickle of details that have emerged from Swift and Kelce’s wedding in the months since the ceremony, which the couple has largely kept private. No photographs from the event have leaked publicly, and specifics about the ceremony itself have remained closely guarded given the size of the guest list. Hargitay is not the only attendee to have offered a glimpse into the night; fellow guest Nikki Glaser also shared her own reflections on the celebration in the weeks following the wedding.
Hargitay’s friendship with Swift predates the “Love Story” singer’s relationship with the Kansas City Chiefs tight end by years and has become something of its own pop culture footnote. Swift named one of her cats Olivia Benson, after Hargitay’s long-running “Law & Order: SVU” character, while Hargitay later returned the gesture by naming her own cat Karma, after Swift’s song of the same name. Hargitay also appeared alongside Swift in the singer’s star-packed 2015 music video for “Bad Blood.”
The bond between the two was on display again just weeks before the wedding, when Hargitay joined Swift and HAIM sisters Este and Alana Haim courtside at Madison Square Garden for Game 4 of the 2026 NBA Finals on June 10, as the New York Knicks faced the San Antonio Spurs. Hargitay told Kimmel she had rushed straight from a theater performance to make it to the game on time. “I was doing a play at the time, and I actually ran from my theater. Physically ran from the theater to the game, and we were sitting together, and I was wearing a black T-shirt,” she recalled.
Swift, ever prepared, had a solution ready when Hargitay arrived without the group’s custom game-day gear. “And Taylor, being the prepared woman that she is, was like, ‘I got you.’ And basically handed it to me. I put it on, and that was the end of it,” Hargitay said. The group wore custom blue Knicks T-shirts featuring orange lettering and pop-culture puns tailored to each wearer, including a nod to actress Nicole Kidman. Asked about the experience of the night, Hargitay called it “pretty spectacular,” and described Swift’s playful energy in the crowd, saying at one point, “She was throwing me around like a rag doll!”
Beyond the wedding and the NBA Finals appearance, Hargitay has spoken previously about her admiration for Swift, describing her as a “boss lady” during an appearance on Alex Cooper’s “Call Her Daddy” podcast. “I learned so much from her,” Hargitay said at the time, adding that Swift is “warm and smart and kind.” She went on to praise the singer’s influence on those around her, saying, “That’s what I love about her is that she’s so young, but she shows us in such beautiful ways how to be fearless.”
Swift and Kelce’s wedding capped off a relationship that has played out largely in public since it began, with the pop star and NFL star becoming one of the most closely watched celebrity couples in recent memory. Their romance drew sustained attention throughout Kelce’s football seasons and Swift’s record-breaking Eras Tour, culminating in a proposal and the couple’s decision to marry at one of New York’s most storied venues, a building with deep ties to both of their careers given Swift’s history of sold-out shows there and Kelce’s connection to professional sports.
Despite the wedding’s scale, the couple has continued to keep many specifics private, with Hargitay’s comments offering one of the more detailed public accounts from someone who was actually in the room. Other details have trickled out gradually through attendees and industry outlets in the weeks since, though Swift and Kelce themselves have largely avoided speaking publicly about the specifics of the ceremony.
For Hargitay, the appearance on Kimmel’s show offered a chance to reflect not just on the wedding itself but on a friendship that has spanned years of shared milestones, from red carpets to courtside seats to, now, a wedding she says she’s still thinking about weeks later. As she put it simply to Kimmel, the night left her feeling like she was still floating, long after the vows were exchanged and the celebration wound down.
Business
Bitcoin and Tether Dominate as CoinMarketCap Data Reveals the 10 Most Traded Cryptocurrencies of 2026
NEW YORK — Tether’s stablecoin and Bitcoin continue to command the largest share of daily trading activity across global cryptocurrency markets, according to the latest volume rankings from data provider CoinMarketCap, underscoring how dollar-pegged stablecoins have become the backbone of crypto trading even as speculative interest in the asset class remains concentrated in a small handful of major tokens.
Tether’s USDT token led all cryptocurrencies in trading volume over the trailing 30-day period, with roughly $3.76 trillion changing hands, according to CoinMarketCap data. That figure dwarfed every other asset tracked on the platform, reflecting USDT’s role as the primary medium traders use to move in and out of positions without converting back to traditional currency. Bitcoin ranked second, with approximately $1.66 trillion in trading volume over the same period, followed by rival stablecoin USDC at roughly $541.6 billion.
Ethereum, the second-largest cryptocurrency by market value, came in fourth with about $221.8 billion in 30-day trading volume, while Solana followed in fifth place with roughly $179.0 billion. XRP rounded out the top six, with approximately $158.9 billion traded over the period.
Rounding out the top ten were Zcash, a privacy-focused cryptocurrency that has seen renewed trading interest, with roughly $49.8 billion in volume; Dogecoin, the long-running meme cryptocurrency, at about $42.7 billion; KiiChain, a newer blockchain network that logged a notable $39.4 billion in trading activity; and BNB, the token associated with the Binance exchange ecosystem, at approximately $35.1 billion.
The dominance of stablecoins atop the rankings reflects a broader structural feature of cryptocurrency markets rather than a sign of speculative appetite for those specific assets. Because USDT and USDC are pegged to the U.S. dollar, traders use them as a parking spot for capital between trades, meaning their trading volume tends to reflect overall market turnover rather than directional bets on price appreciation. That dynamic has become more pronounced following the passage of stablecoin legislation in the United States in 2025, often referred to as the GENIUS Act, which established new standards for reserve transparency and regulatory oversight that have expanded institutional use of dollar-pegged tokens for settlement, cross-border payments and on-chain yield strategies.
Bitcoin’s position as the most actively traded non-stablecoin asset continues a pattern that has held for much of the cryptocurrency market’s history, with the original cryptocurrency maintaining its role as the primary entry point for both retail and institutional capital flowing into the sector. Ethereum’s position in fourth place reflects its continued dominance as the leading platform for decentralized finance applications, smart contracts and tokenized assets, even as newer, faster blockchain networks have chipped away at some of its market share in recent years.
Solana’s strong showing in fifth place highlights the network’s continued growth as a hub for high-speed trading activity, including a large volume of trading tied to meme coins and other speculative tokens launched on decentralized exchanges built on the Solana blockchain. XRP’s position in the top six comes as the token has benefited from greater regulatory clarity following the resolution of its long-running legal dispute with the U.S. Securities and Exchange Commission, along with growing institutional interest tied to cross-border payment use cases championed by Ripple, the company closely associated with the token.
The appearance of KiiChain in the rankings stands out as something of an outlier, given the network’s relatively limited public profile compared with the other assets in the top ten. Volume spikes of that magnitude for smaller or newer blockchain networks can sometimes reflect a surge of trading activity following an exchange listing, promotional trading incentives, or concentrated activity among a small number of large holders, rather than the kind of broad-based, sustained trading interest seen in more established assets like Bitcoin or Ethereum. Traders and analysts typically scrutinize such spikes closely, since volume figures for less liquid tokens can be more susceptible to distortion than those of larger, more widely held cryptocurrencies.
BNB’s continued presence near the top of the rankings reflects Binance’s position as the world’s largest cryptocurrency exchange by trading volume, a status the platform has maintained through multiple market cycles despite years of regulatory scrutiny in various jurisdictions. Dogecoin’s appearance in the top ten, meanwhile, illustrates the enduring trading interest in meme-based cryptocurrencies, which have continued to attract retail speculative activity even as the broader market has matured and drawn in more institutional participants.
Zcash’s climb into the top ten marks a notable shift, as the privacy-focused cryptocurrency has drawn renewed attention from traders in recent months, a reversal from the years of declining volume that had pushed many privacy coins toward the margins of the market amid tightening exchange listing standards and regulatory pressure on assets designed to obscure transaction details.
Taken together, the rankings illustrate a cryptocurrency market that remains heavily concentrated at the top, with a small number of assets, led by dollar-pegged stablecoins and Bitcoin, accounting for the overwhelming majority of trading activity, even as thousands of smaller tokens continue to launch and compete for attention further down the list. Market watchers note that such rankings can shift quickly given the volatility inherent in crypto trading volumes, with newer tokens capable of briefly cracking the top ten during periods of concentrated speculative interest before volume normalizes.
For now, the broad contours of the market, dollar-pegged stablecoins facilitating the bulk of trading turnover, Bitcoin and Ethereum anchoring investor interest in the underlying assets, and a rotating cast of altcoins and meme tokens filling out the remainder of the list, have remained largely consistent through 2026, even as individual token rankings continue to fluctuate from month to month.
Workday: Great Execution, But Acquisition Possibility Is Already Priced In

RTW Biotech Opportunities reports August NAV of $2.92 per share

BlackRock Large Cap Focus Growth Fund Q2 2026 Commentary

Japan finance firms add AI translation and QR payments

Belmont Cameli Gushes Over Ella Bright Amid Feud Rumors


-
 Tech6 days ago
Memory prices are slowing because buyers ran out of money
-

 Tech18 hours ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Business4 days ago
Micron Stock Climbs Above $1,031 as AI Memory Crunch and a $50 Billion Outlook Fuel the Rally
-

 Business4 days ago
AMD Stock Climbs After Management Lifts 2027 Data Center Outlook Toward $70 Billion in AI Sales
-
 Crypto World5 days ago
Bitcoin price risks $76K drop as $78K support weakens
-

 Fashion3 days ago
Weekend Open Thread – Corporette.com
-
 Crypto World6 days ago
Robinhood Stock: How To Take Advantage With Reduced Risk
-

 Crypto World3 days ago
XAG/USD: Silver’s Short-Term Rally Meets Its Moment of Truth
-

 Crypto World4 days ago
2 Chip Stocks Broke Out This Week. Neither Was Nvidia
-
 Crypto World5 days ago
Ethereum price stalls below $2,500 as ADX drops to 11
-
 NewsBeat6 days ago
England up in reading, maths and science rankings as Scotland and Wales dip
-

 Business3 days ago
10 Most-Streamed Songs On Spotify In 2026 So Far, Led By Ella Langley’s Dominant Run On The Charts This Year
-

 Crypto World3 days ago
OKX launches 10x OpenAI, Anthropic X-Perps in Europe
-

 Tech3 days ago
Battery life is the only iPhone 18 Pro and iPhone Duo upgrade I care about. Apple didn’t disappoint
-

 Crypto World3 days ago
Diesel Tops $6 a Gallon for the First Time as 28 States Set Records
-
 Crypto World6 days ago
Intel Stock Jumps 9% on Chip Price Hike Report, US Stake Gains $36 Billion
-

 Tech4 days ago
Apple Watch Ultra 4 vs Watch Ultra 3: Should you really spend another $799?
-

 Crypto World4 days ago
Bitcoin price risks $70K if $78K neckline breaks
-
 Crypto World6 days ago
Pump Fun and Kraken delete Hunter Biden $LAPTOP promotion
-
 NewsBeat5 days ago
What went right this week: an ‘historic’ fall in violent crime, plus more
You must be logged in to post a comment Login