
Crypto World
Robinhood engineers charged over $50K crypto scheme

Federal prosecutors have charged two Robinhood engineers with commodities fraud and wire fraud after each allegedly earned more than $50,000 by trading crypto perpetual futures with confidential listing information.
Summary
- Two Robinhood engineers allegedly traded before the company announced new cryptocurrency listings.
- Each defendant allegedly earned more than $50,000 through perpetual futures positions on Hyperliquid.
- Commodities fraud carries a maximum 10-year sentence, while wire fraud carries up to 20 years.
- The criminal complaints remain allegations, and both engineers are presumed innocent unless convicted.
Robinhood engineers allegedly traded before listings
The U.S. Attorney’s Office for the Southern District of New York announced the charges against Hefu Chai, 36, and Huaisong Xiang, 30, also known as Jerry Xiang, on Sep. 15.
Both defendants worked as engineers at Robinhood Markets during the alleged conduct. According to the criminal complaints, their jobs gave them access to confidential information about which cryptocurrencies Robinhood Crypto planned to add to its platform and when the listings would become public.
Prosecutors allege that Chai and Xiang used the information between 2025 and 2026 to open perpetual futures positions linked to the planned listings. Rather than buying the underlying tokens, they allegedly placed the trades through Hyperliquid before Robinhood released its announcements.
Once the listings became public, prosecutors said the prices of several related cryptocurrencies rose, allowing both defendants to close profitable positions. Each engineer allegedly made more than $50,000 through trades tied to Robinhood’s private listing plans.
The complaints accuse Chai and Xiang of breaching their duties to protect their employer’s confidential information. Prosecutors have not identified every cryptocurrency involved in the alleged trades in the public announcement.
As crypto.news reported in June, Robinhood’s Worldcoin listing announcement gave customers access to WLD while the token was experiencing sharp price swings. WLD fell nearly 15% around the listing period despite gaining access to Robinhood’s customer base, showing that a platform addition does not always produce a lasting rally.
Hyperliquid perpetuals formed the alleged trading route
Hyperliquid operates a decentralized derivatives platform where traders can take long or short positions through perpetual futures. Unlike standard futures, perpetual contracts do not have fixed expiration dates and use recurring funding payments to keep their prices close to the referenced assets.
According to prosecutors, the absence of an expiry date allowed Chai and Xiang to establish positions before Robinhood’s announcements and hold them until the expected price movements occurred. The complaints allege that both engineers possessed material nonpublic information when they entered the trades.
Hyperliquid records trades on public blockchain infrastructure, but users can interact with its markets without buying the assets referenced by the contracts. July coverage of Hyperliquid’s protocol upgrades detailed how HIP-3 opened perpetual market creation to outside developers and expanded the platform beyond crypto tokens to instruments linked to stocks, commodities and indexes.
HIP-3 has operated on the mainnet since October 2025, while HIP-4 went live in May 2026 with support for prediction and event markets. Hyperliquid’s expanding range of instruments has placed its decentralized trading infrastructure closer to markets traditionally overseen by U.S. commodities and derivatives rules.
Although the alleged trades occurred on a decentralized venue, U.S. Attorney Jamie McDonald said the type of platform used did not remove the defendants’ legal obligations.
“Misappropriating confidential information to trade in the derivatives markets for personal benefit is illegal,” McDonald said.
The prosecutor added that traders cannot avoid U.S. securities and commodities laws by using perpetual futures, tokenized securities, or similar financial products.
US prosecutors apply commodities and wire fraud laws
Chai and Xiang each face one count of commodities fraud and one count of wire fraud. According to the Justice Department, the commodities charge carries a maximum prison term of 10 years, while wire fraud carries a maximum sentence of 20 years.
Any sentence would be determined by a federal judge after considering the U.S. Sentencing Guidelines and other statutory factors. The maximum penalties do not indicate what either defendant would receive if convicted.
The case gives U.S. readers a direct example of how federal prosecutors can pursue alleged misuse of corporate crypto information even when the trades do not involve ordinary shares or spot token purchases. Prosecutors framed the alleged perpetual positions as derivatives trades made with information taken from a U.S.-listed company.
Robinhood trades on Nasdaq under the HOOD ticker and offers crypto services through Robinhood Crypto. Its conventional brokerage, crypto, and derivatives products operate through separate affiliated entities with different regulatory arrangements.
Robinhood’s official disclosures state that its U.S. futures and cleared swaps business operates through Robinhood Derivatives, a futures commission merchant registered with the Commodity Futures Trading Commission and a member of the National Futures Association. Robinhood Crypto is licensed by the New York State Department of Financial Services for virtual currency activity.
The alleged Hyperliquid trades were separate from customer transactions on Robinhood’s own platform. Prosecutors have accused the two employees of exploiting internal information rather than alleging that Robinhood customers lost funds or that the brokerage manipulated token prices.
FBI investigation leads to court appearances
FBI Assistant Director James C. Barnacle Jr. said the engineers allegedly used sensitive information obtained through their employment for personal profit. According to Barnacle, the charges show that the FBI and its partners will act when employees are accused of abusing confidential corporate information.
Chai was scheduled to make his first court appearance in the Northern District of California. Xiang was due to appear in Manhattan before U.S. Magistrate Judge Ona T. Wang in the Southern District of New York.
The charges arrive as Robinhood has increased its use of blockchain-based products. In September, its Ethereum layer-2 network experienced a 14-minute block-production halt that temporarily prevented transfers and smart contract calls from receiving confirmation.
Robinhood launched the chain’s public mainnet on July 1 with 95 tokenized stocks and wallet access in more than 120 countries. The network uses Ethereum for transaction fees and supports compatible wallets and applications, while its tokenized products remain separate from the alleged crypto listing trades described in the federal complaints.
Neither complaint represents a finding of guilt. Chai and Xiang are presumed innocent unless prosecutors prove the charges beyond a reasonable doubt in court.

Researchers at the Bank for International Settlements found that estimates of Bitcoin onchain transfer values can vary by as much as sixfold depending on how transactions are measured.
The finding concerns onchain Bitcoin transfer values, rather than trading volume on crypto exchanges. The sixfold gap reflects differences between measurement methods, including how change outputs and other transfers back to the sender are treated.
The discrepancy stems largely from Bitcoin’s transaction structure. When users spend Bitcoin, unspent funds are often returned to the sender as change, which can be counted as another output even though it does not represent funds being transferred to another party.
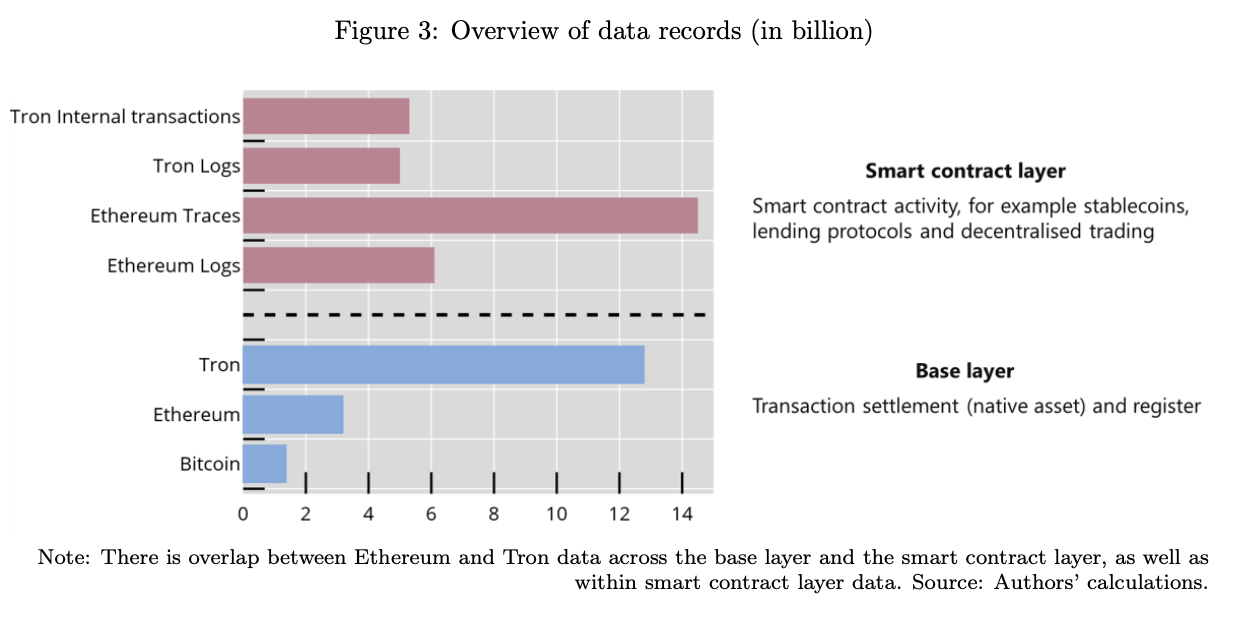
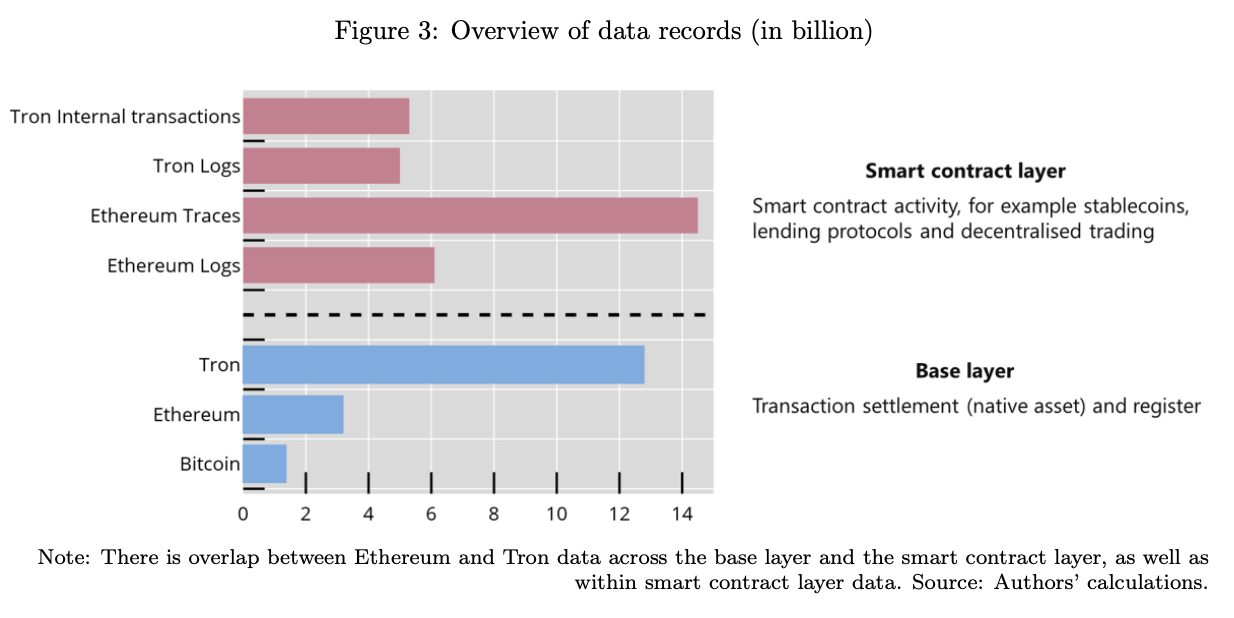
Breakdown of blockchain records analyzed in the BIS study. Source: BIS
“Metrics such as transaction volumes, market capitalisation and total value locked often suggest a degree of accuracy that is not supported by the nature of the underlying data,” the researchers wrote.
The measurement problem also extends to Bitcoin’s market capitalization. The researchers found that the conventional measure has at times been as much as four times higher than realized capitalization, which values each coin at the price when it last moved.
The study, based on 100 billion blockchain records across Bitcoin, Ethereum and Tron, found that similar measurement challenges extend across the broader crypto ecosystem.
Related: Stablecoins not credible for payments at scale, BIS chief says
Ethereum and stablecoins present additional challenges
Ethereum presented a separate measurement challenge because of the proliferation of smart contracts. Of roughly 67.5 million active contracts examined, about 54 million could not be categorized using the classifications in the study.
Interpreting stablecoin activity presents another challenge, as the same asset can serve different purposes across blockchains. USDT on Ethereum was more closely linked to DeFi activity, while USDT on Tron was associated more with payment-like and store-of-value purposes.
The differences were particularly stark in smart contract holdings. The share of USDT held by smart contracts on Ethereum exceeded 20% in 2022, compared with around 1% on Tron. Because of the different use cases, the researchers said aggregating USDT activity across blockchains can conflate different types of economic activity and obscure how stablecoins are actually being used.
The BIS researchers concluded that onchain indicators should be treated as “noisy approximations rather than direct measures of economic activity.”
Visa filters stablecoin data to reflect economic activity
Some analytics providers already distinguish between raw blockchain activity and adjusted measures intended to better represent economic activity.
Visa’s Onchain Analytics dashboard, powered by data from Allium Labs, displays both total and adjusted stablecoin transaction volumes. Visa says its adjusted methodology aims to remove potential distortions from activity including high-frequency trading, bots, bridge routing and internal exchange operations.
The dashboard currently shows $6.4 trillion in total stablecoin transaction volume across the networks it tracks over the past 30 days, compared with $313.1 billion in adjusted volume.
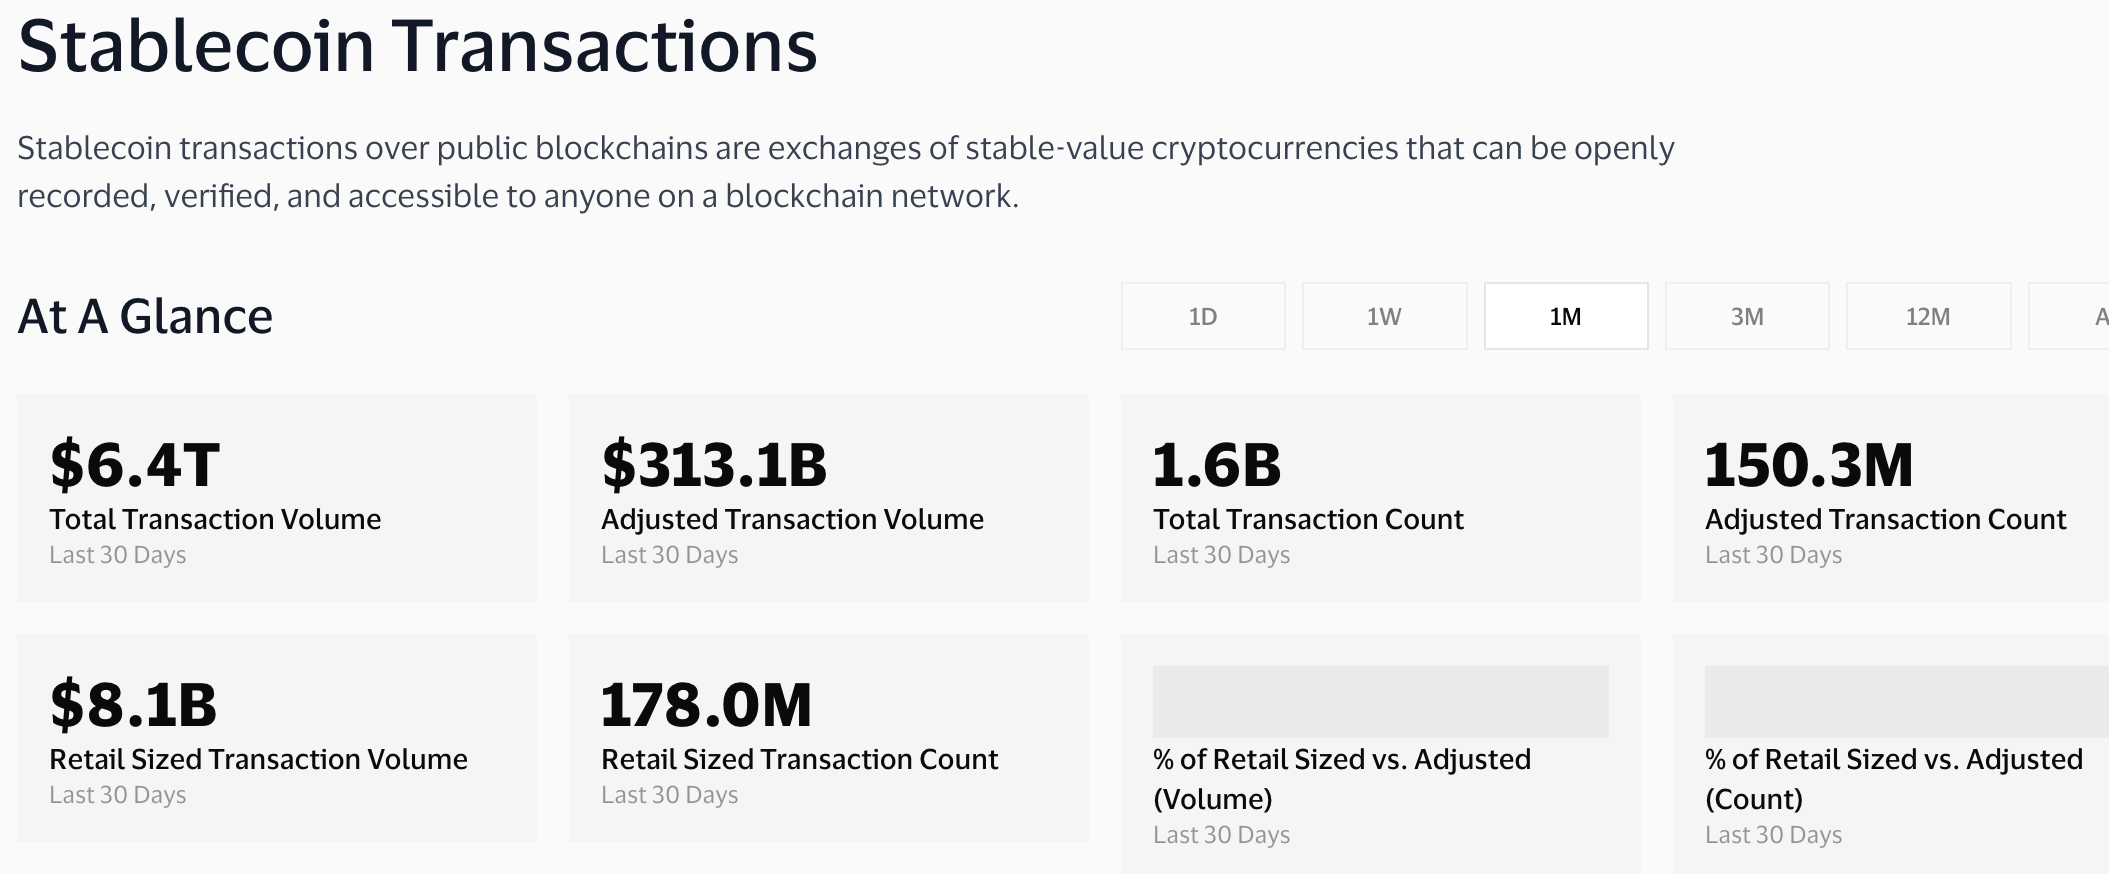
Stablecoin transaction volumes. Source: Visa Onchain Analytics
New research from the Bank for International Settlements (BIS) suggests many of the headline metrics used to describe crypto activity—especially onchain “transfer” values—can be misleading depending on how the underlying blockchain data is counted. The BIS team reports that estimates of Bitcoin transfer values can differ by as much as six times when measurement methods change, driven largely by how transaction outputs are interpreted.
The study also highlights broader problems across the crypto ecosystem, extending beyond Bitcoin to Ethereum and stablecoins. BIS researchers warn that onchain indicators should often be treated as “noisy approximations rather than direct measures of economic activity,” rather than precision readouts of real-world flows.
Key takeaways
- Bitcoin onchain transfer values can swing by up to 6x based on how outputs—such as change back to the sender—are counted.
- Common market-cap style measures may overstate realized value; BIS finds conventional capitalization has at times been up to 4x higher.
- Ethereum’s smart-contract environment complicates classification, with tens of millions of active contracts that BIS could not categorize using the study’s framework.
- Stablecoin activity varies by chain and purpose, so aggregating across networks can blur how USDT is actually used.
- Some analytics providers already adjust raw volumes to remove distortions tied to behaviors like internal exchange routing or bot-driven activity.
Why “transfer value” can mean very different things
In the BIS working paper, the researchers focus on a measurement gap: when analysts try to estimate how much Bitcoin is being transferred onchain, the result depends heavily on the rules used to parse transactions. BIS’s key point is not that onchain data is absent, but that the same data can produce drastically different “economic activity” estimates.
The sixfold discrepancy reported by BIS is tied to differences in transaction measurement methods. One major driver is Bitcoin’s transaction structure. When a user spends Bitcoin, the transaction often includes unspent funds returned to the sender as a “change” output. Depending on the methodology, that change can be counted as an additional output—despite not representing value sent to another party.
BIS argues that this kind of counting convention can create the appearance of greater transfers than what actually reflects third-party movement. The researchers underline that metrics frequently presented as straightforward—such as transaction volumes, market capitalization, and total value locked—may carry more certainty than the structure of the underlying data actually supports.
Bitcoin market capitalization: a similar measurement mismatch
The BIS paper extends the measurement theme beyond transfer values to capitalization. The researchers report that a conventional market-cap approach has, at times, been as much as four times higher than realized capitalization.
According to BIS, realized capitalization values each coin at the price at the time it last moved. That distinction matters because it ties the valuation method to activity timestamps, rather than assuming a single uniform pricing snapshot. The implication for investors and market observers is that onchain-linked metrics can diverge from how value is actually being reflected in usage—especially when measurement assumptions are treated as neutral.
Cross-chain complications: Ethereum classification and stablecoin aggregation
While Bitcoin’s transaction design creates ambiguity around change outputs, Ethereum presents a different kind of complexity: smart contracts. BIS examined roughly 67.5 million active contracts and found that about 54 million could not be categorized using the classifications used in the study.
This matters because any attempt to interpret stablecoin flows or onchain transfers often depends on understanding whether activity belongs to known contract patterns—such as decentralized finance interactions, custody, payment services, or other use cases. When classification fails at scale, the risk increases that analytics will treat diverse behaviors as if they were homogeneous.
Stablecoins add another layer. The BIS researchers note that the same asset can serve different functions across networks. In their observations, USDT on Ethereum was more closely tied to DeFi activity, while USDT on Tron showed stronger association with payment-like and store-of-value purposes. BIS further highlights that the split is visible in smart contract holdings: in 2022, the share of USDT held by smart contracts on Ethereum exceeded 20%, compared with around 1% on Tron.
The practical takeaway is that aggregating stablecoin activity across chains can conflate distinct economic behaviors. BIS frames the resulting indicators as approximations that may obscure how stablecoins are being used in practice.
Overall, BIS’s conclusion is that onchain indicators should be approached as noisy estimates rather than direct measurements of economic activity—particularly when the indicators are presented as if they map cleanly to real-world transfers.
Adjusted analytics: how some dashboards try to correct distortions
Not all analytics treat raw blockchain activity as a final truth. Some providers attempt to separate “raw” transaction counts from adjusted volumes designed to better represent underlying economic activity.
Visa’s Onchain Analytics dashboard—powered by data from Allium Labs—shows both total and adjusted stablecoin transaction volumes. The dashboard’s adjusted methodology is intended to remove distortions from activity that may not reflect broad economic transfer, including high-frequency trading, bots, bridge routing, and internal exchange operations.
On the dashboard, Visa reports $6.4 trillion in total stablecoin transaction volume across the networks it tracks over the past 30 days, versus $313.1 billion in adjusted volume. The size of that gap illustrates the central theme of the BIS study: depending on counting rules and filtering approaches, “activity” can look dramatically larger or smaller.
Importantly, this does not automatically validate any specific methodology as “correct.” Instead, it reinforces BIS’s broader warning: without careful definitions and adjustments, common onchain metrics can overstate what the data actually means for economic interpretation.
For readers tracking crypto adoption using onchain indicators, the key next step is to pay closer attention to methodology—especially whether metrics account for change outputs, smart-contract classification limits, chain-specific usage patterns, and filtering for bot-driven or internal operations. BIS’s findings suggest that as dashboards and analytics products mature, the real differentiator will be how transparently they define what they measure and how their measurement choices shape the numbers.
Dollar stablecoins have grown to about $300 billion in circulation, prompting a Bank of England policymaker to warn that their expansion could increase demand for US Treasurys while creating new risks during periods of heavy redemptions.
Summary
- Dollar-linked tokens account for about 98% of the global stablecoin market.
- USDT and USDC held nearly $150 billion in Treasury bills at the end of 2025.
- The two issuers bought about $33 billion in Treasury bills during the year.
- Large redemptions could force reserve sales and add pressure to stressed Treasury markets.
Stablecoins could extend the dollar into new markets
The Bank of England said in a Sep. 15 speech that stablecoins could reinforce the US dollar’s international role by making dollar-linked assets and settlement systems easier to access outside the United States.
Carolyn Wilkins, an external member of the central bank’s Financial Policy Committee, told an audience at Queen’s University Belfast that dollar stablecoins already have a “considerable first-mover advantage.” About 98% of stablecoin value is denominated in dollars, according to figures cited in her speech.
Stablecoins in circulation reached roughly $300 billion by mid-2026, compared with less than $5 billion at the beginning of 2020. Although most activity still involves crypto trading, lending, collateral, and market liquidity, Wilkins said the tokens could move deeper into payments and international finance.
Cross-border settlement forms one channel for that expansion. Stablecoin transfers can operate around the clock and move between countries without passing through every institution in a traditional correspondent banking network.
Research cited by Wilkins found that such systems could lower costs in payment corridors where banking services remain slow or expensive. Sending a $200 remittance cost an average of 6.4% worldwide in 2024, while the average charge in Sub-Saharan Africa reached about 8.5%.
Dollar stablecoins can also give people in countries with unstable currencies access to a dollar-linked asset through a mobile phone, without requiring a US bank account. Wilkins said such use could extend dollarization into digital markets, although thin liquidity still limits some payment corridors.
Other currencies have yet to build comparable scale. Circle’s euro-backed token passed €400 million in circulation in August, while the entire euro stablecoin market stood at about €650 million in June, according to a previous EURC supply report. Dollar tokens remain far ahead despite efforts to build alternatives tied to the euro and pound.
Stablecoin reserves add demand for US Treasurys
Issuers generally invest the money received from token buyers in liquid reserve assets, including cash, short-term government debt and Treasury-backed repurchase agreements. Growth in stablecoin supply can therefore send additional funds into the market for US government securities.
USDT issuer Tether and USDC issuer Circle held almost $150 billion in Treasury bills at the end of 2025, according to Bank for International Settlements research cited by Wilkins. Their net purchases reached about $33 billion during the year.
Although the combined position remains small compared with the full Treasury market, Wilkins described the largest stablecoin issuers as meaningful participants in short-term US government debt. Research referenced in her speech found that stablecoin inflows can place modest downward pressure on short-term Treasury yields as issuers buy more safe assets.
The net effect depends on where users obtained the money placed into stablecoins. Moving capital from a Treasury money market fund into a token whose issuer buys the same bills may add little new demand. Funds transferred from another currency or asset class would have a stronger effect, while withdrawals from bank deposits could affect lenders’ funding costs and capacity to provide credit.
Tether’s own accounts show how closely issuer earnings have become linked to US debt. The company generated about $1.5 billion in operating profit during the second quarter of 2026, supported by returns from its Treasury and repo holdings, crypto.news reported in July.
Circle also earns much of its income from the assets backing USDC. Average USDC circulation doubled from $38.1 billion to $76.2 billion in the fourth quarter of 2025, while its reserve portfolio returned 3.8%, according to the company’s results covered in a February earnings report.
Redemptions could reverse Treasury buying
The same reserve structure that sends money into Treasury bills during stablecoin growth can create selling pressure when users redeem tokens.
Stablecoins are claims that holders expect to exchange for cash at face value. Since tokens trade continuously, issuers may have to raise cash quickly when redemptions accelerate, even outside conventional market hours.
Wilkins warned that several large issuers selling Treasury bills at the same time could worsen changes in yields and liquidity if the government-debt market were already under strain. Pressure would not have to begin inside the stablecoin industry, as concerns about US inflation, public debt or institutional credibility could weaken demand for dollar assets before token redemptions add to the selling.
The stablecoin sector is not yet large enough to pose a major threat to the Treasury market or create a material financial-stability risk in the UK, according to Wilkins. A large depegging event could still damage confidence in regulated tokens.
USDC provided an earlier example of how reserve concerns can reach a stablecoin. Circle held about $3.3 billion at Silicon Valley Bank when the lender failed in March 2023, causing USDC to lose its dollar peg as redemptions rose. The token was recovered after US authorities guaranteed the bank’s deposits.
Wilkins compared the possible Treasury feedback loop with the UK liability-driven investment crisis in 2022, when forced gilt sales added to falling bond prices and prompted intervention by the Bank of England.
US rules deepen the stablecoin-Treasury link
The GENIUS Act, enacted in July 2025, created a federal framework for US payment stablecoins and requires issuers to hold at least one dollar of eligible reserves for each dollar of tokens outstanding.
Permitted assets include cash, insured deposits, short-dated Treasury bills, Treasury-backed repo agreements and qualifying money market funds. The law also establishes disclosure requirements and gives stablecoin holders priority in an issuer’s insolvency.
Implementation remains unfinished. The Office of the Comptroller of the Currency expects to finalize its stablecoin rules by November 2026, which could push their effective date to around March 2027, according to an August implementation update. Issuers worth more than $50 billion must undergo annual audits, while all regulated issuers will have to report weekly to their main regulator and publish monthly disclosures.
Wilkins said reserve rules address whether issuers have enough assets but do not fully answer how quickly those assets can be converted into cash during a run. Even Treasurys faced severe liquidity pressure during the March 2020 dash for cash, when the Federal Reserve intervened in the market.
A limited Federal Reserve account proposed for eligible payment firms could improve routine settlement, according to the speech. The account would not provide access to Fed borrowing, leaving stablecoin issuers without a prearranged source of emergency liquidity during a redemption crisis.
UK stablecoin rules place more weight on liquidity
The Bank of England’s framework for systemic sterling stablecoins applies stricter reserve and liquidity requirements than the US regime, although Wilkins noted that the two systems cover different groups of issuers.
The UK framework applies once a sterling stablecoin is classified as systemic, while the GENIUS Act governs US payment stablecoins more generally. Britain’s model includes payment-system access, liquidity contingency plans and procedures for issuer failure, with conditional access to central bank liquidity also possible.
For cross-border issuers, the Bank of England would require a UK legal entity and place key safeguarding arrangements inside the country. Its final framework for systemic sterling stablecoins is scheduled for completion at the end of 2026.
Separately, the Financial Conduct Authority finalized its rules for UK stablecoin issuance in June after reducing some proposed capital requirements. The regulator has also allowed prospective issuers to test their products through a dedicated sandbox, while the Bank of England continues experiments involving stablecoins and a simulated digital pound.
CoinEx is preparing to shut down its platform after nearly nine years as the weakness across the crypto market has made operations increasingly difficult.
The exchange said the broader industry has seen a significant contraction in trading volume and liquidity. It also cited rising regulatory requirements across major jurisdictions alongside higher compliance costs and operational uncertainties that it considers beyond reasonable boundaries.
Market Pressure Mounts
The wind-down process begins on September 15, 2026, and will follow a gradual schedule. Users can still withdraw funds from the platform until December 22, 2026. CoinEx’s decision also highlights the pressure facing established exchanges as the crypto industry moves through further maturity and consolidation.
BitMart and BitMEX also announced closures in July after operating since 2017 and 2014, respectively. The pressure was spread across more corners of the crypto industry this year. DEX aggregator Odos wound down operations on July 30. Dango stopped running its L1 blockchain on August 13. Storj Labs filed for Chapter 11 bankruptcy protection.
Previous Setbacks
Long before announcing its shutdown, CoinEx had faced its share of problems. Earlier this year, TRM Labs found over $3.84 billion in blockchain transactions between the exchange and sanctioned Iranian entities over more than seven years. TRM said CoinEx was the largest external counterparty of Nobitex.
More than $2.7 billion reportedly moved between the two platforms since late 2018. The report also linked it to over 60 Iranian crypto businesses. TRM further identified around $67 million from Iran’s central bank that reached CoinEx through a complex laundering structure between June 2025 and June 2026. Its founder, Haipo Yang, acknowledged that Iranian customers widely used the exchange but denied any relationship with the country’s government.
CoinEx also rejected claims that it knowingly helped sanctions evasion. While pushing back on the report’s findings, the exchange said Iran blacklisted it in 2021 and that it had never maintained an office there. It even questioned TRM’s volume calculations. Its troubles were not limited to regulatory scrutiny.
Back in 2024, the exchange suffered a $70 million hack after its hot wallet keys were compromised. The Lazarus Group was later reported as responsible. In 2023, it agreed to pay more than $1.7 million after a New York lawsuit.
The post CoinEx Calls Time After Nearly Nine Years as Crypto Market Pressure Mounts appeared first on CryptoPotato.
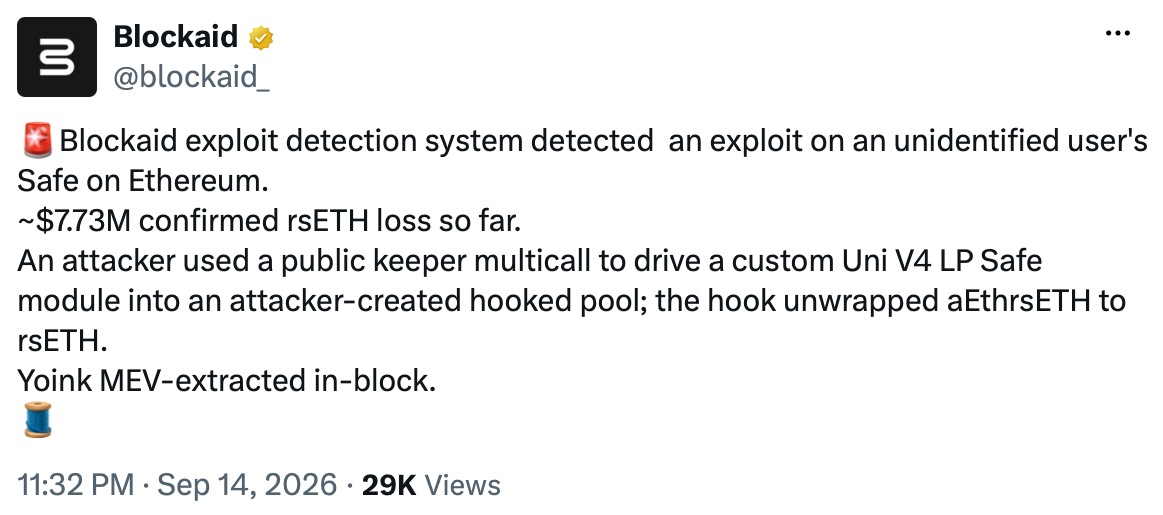
An attacker exploited a custom module connected to an Ethereum Safe wallet in an attempt to extract roughly $7.7 million in rsETH, only to have the funds intercepted by an MEV bot.
According to blockchain security firm Blockaid, the attacker used a public keeper multicall to direct a custom Uniswap v4 liquidity module into an attacker-created hooked pool, where aEthrsETH was unwrapped into rsETH.
Blockaid identified the affected wallet as a Safe belonging to an unidentified user and said about $7.73 million in rsETH had been lost at the time of its initial report.
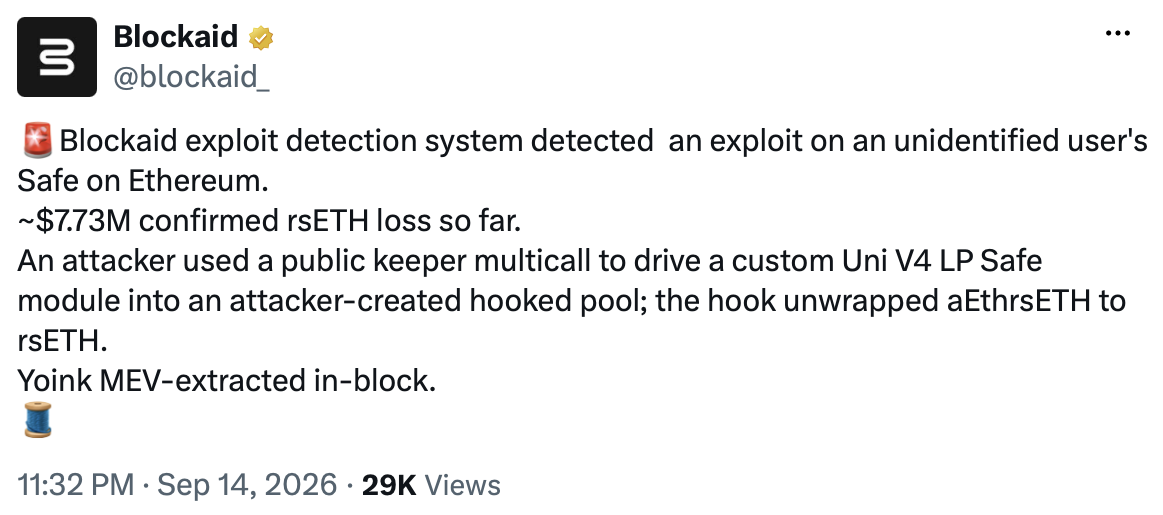
Source: Blockaid
The attack was then front-run by an MEV bot known as Yoink, an automated program that monitors blockchain transactions for profitable opportunities. The bot captured the rsETH before the original exploiter could take control of the funds, while Etherscan data shows Yoink transferred about 18.93 ETH, worth roughly $46,000, to an address labeled as a block builder in the same transaction.
Kelp, the protocol behind rsETH, subsequently placed the address that received the funds under a 24-hour pause, temporarily preventing the tokens from being transferred. “This is a precautionary, wallet-level measure only,” Kelp said. “Kelp contracts are safe, rsETH remains fully backed.”
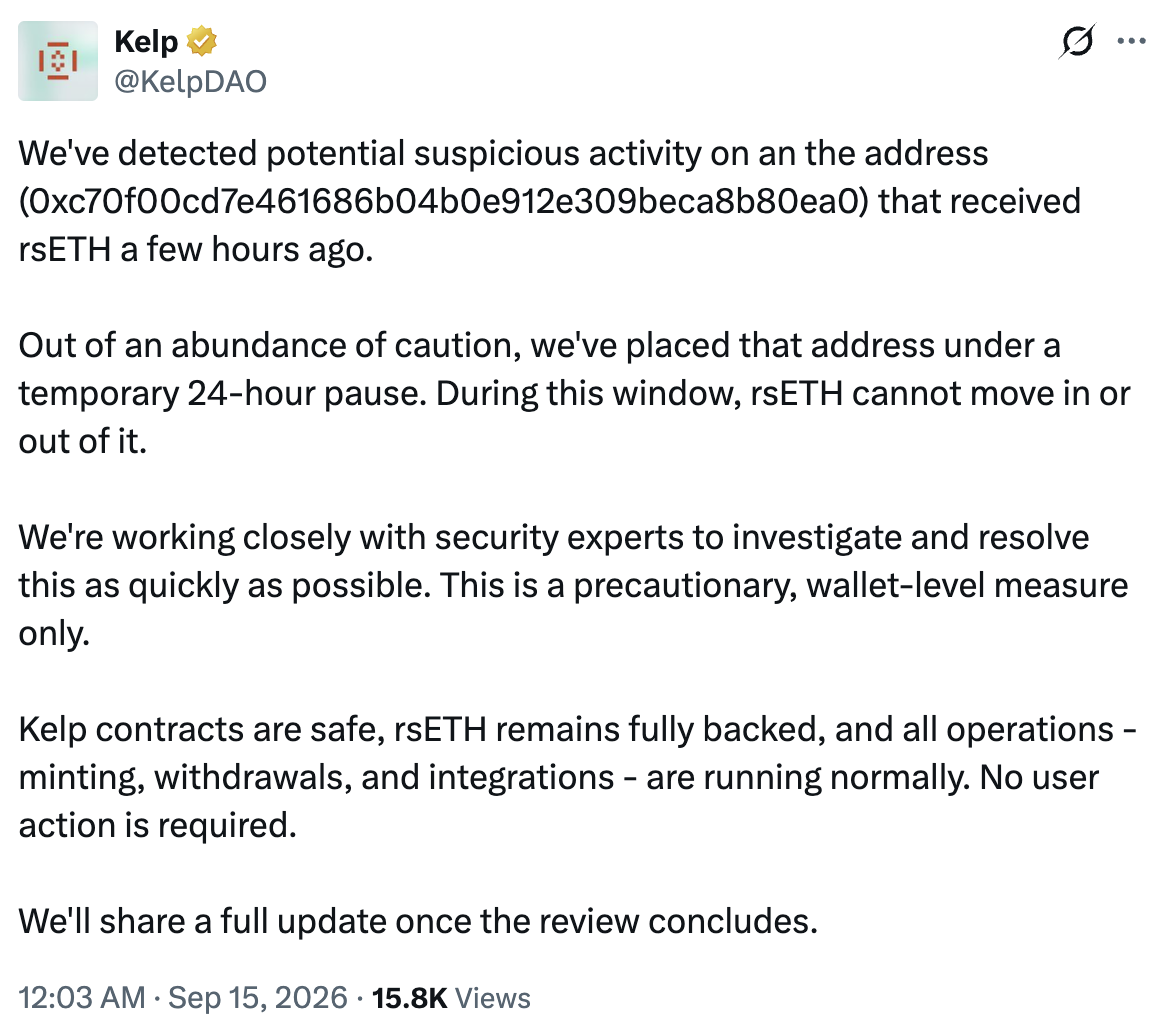
Source: KelpDAO
The protocol said minting, withdrawals and integrations were continuing normally while it worked with security experts to investigate the incident. The apparent attack vector involved the custom module connected to the victim’s Safe, while Kelp said its own contracts were unaffected.
Cointelegraph contacted Blockaid and Kelp for additional comment but had not received a response by publication.
Magazine: Why are AI’s biggest companies suddenly asking to slow down?
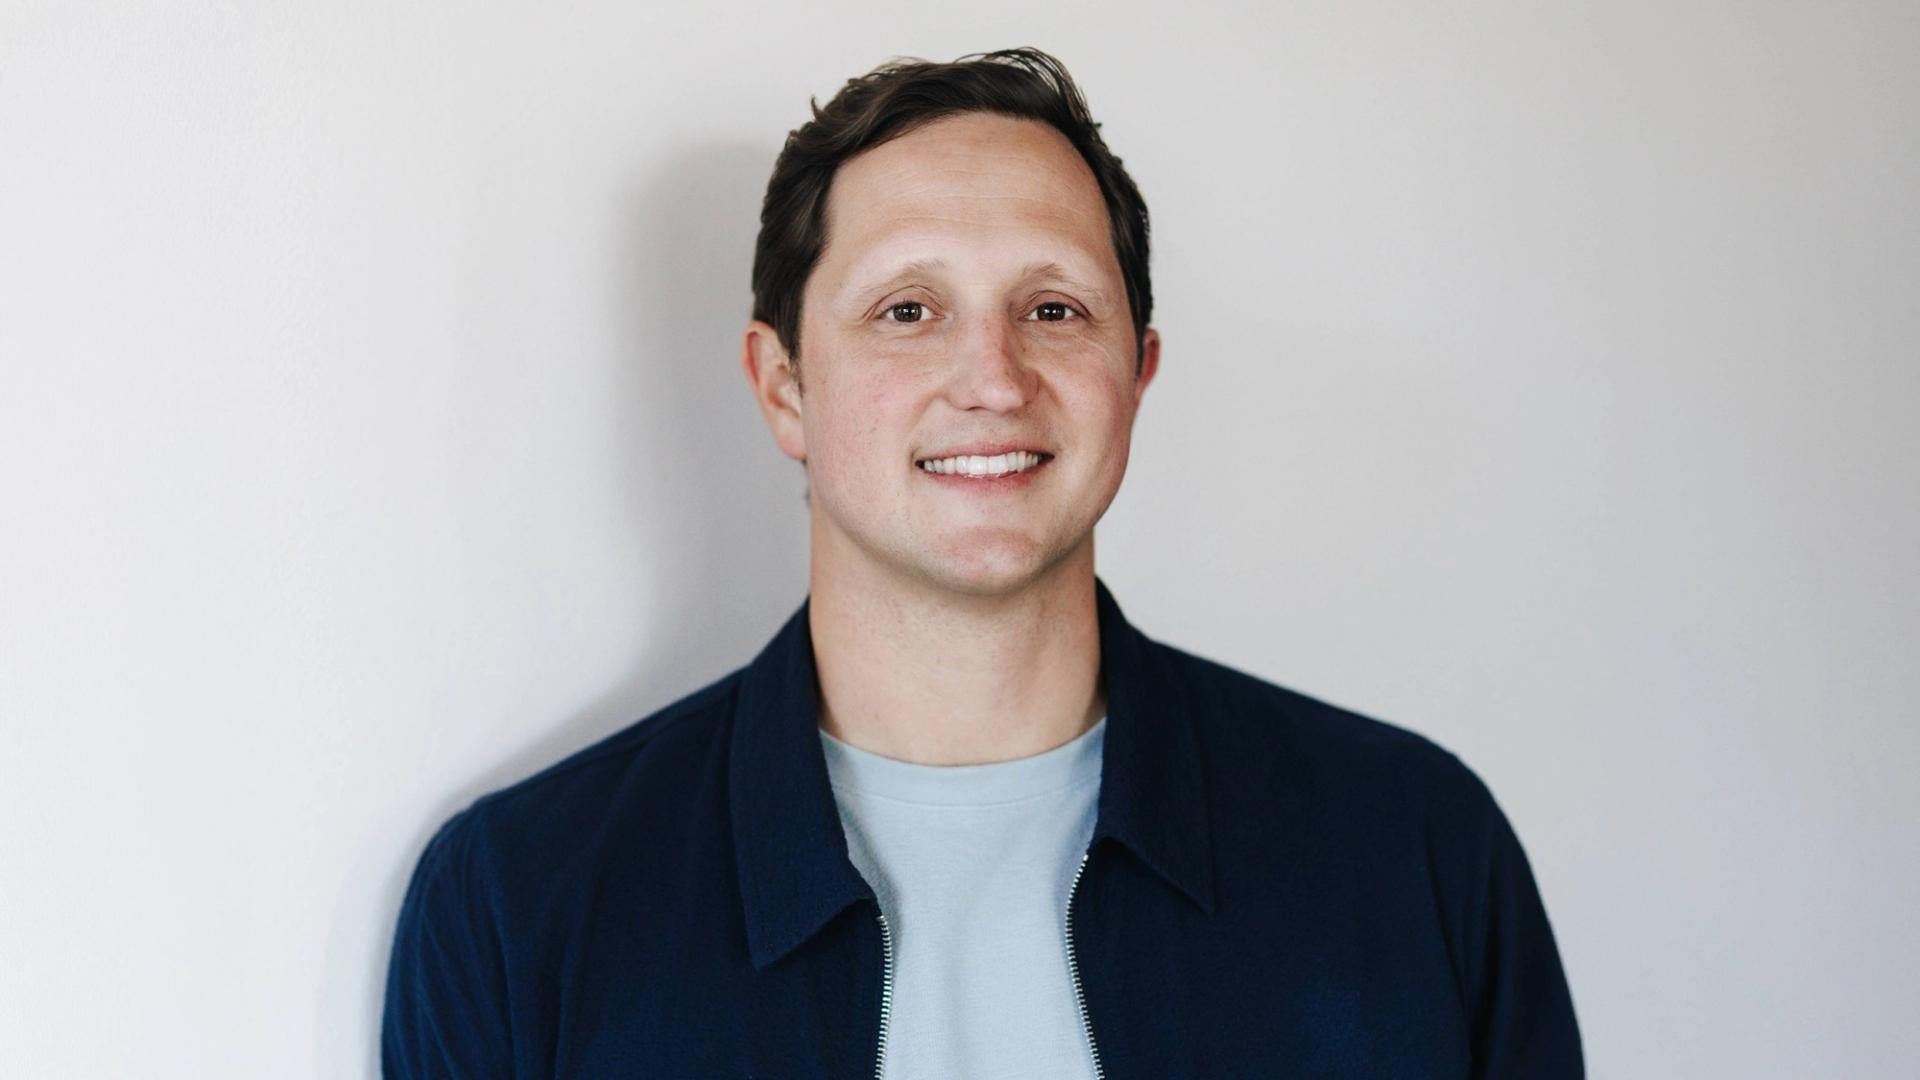
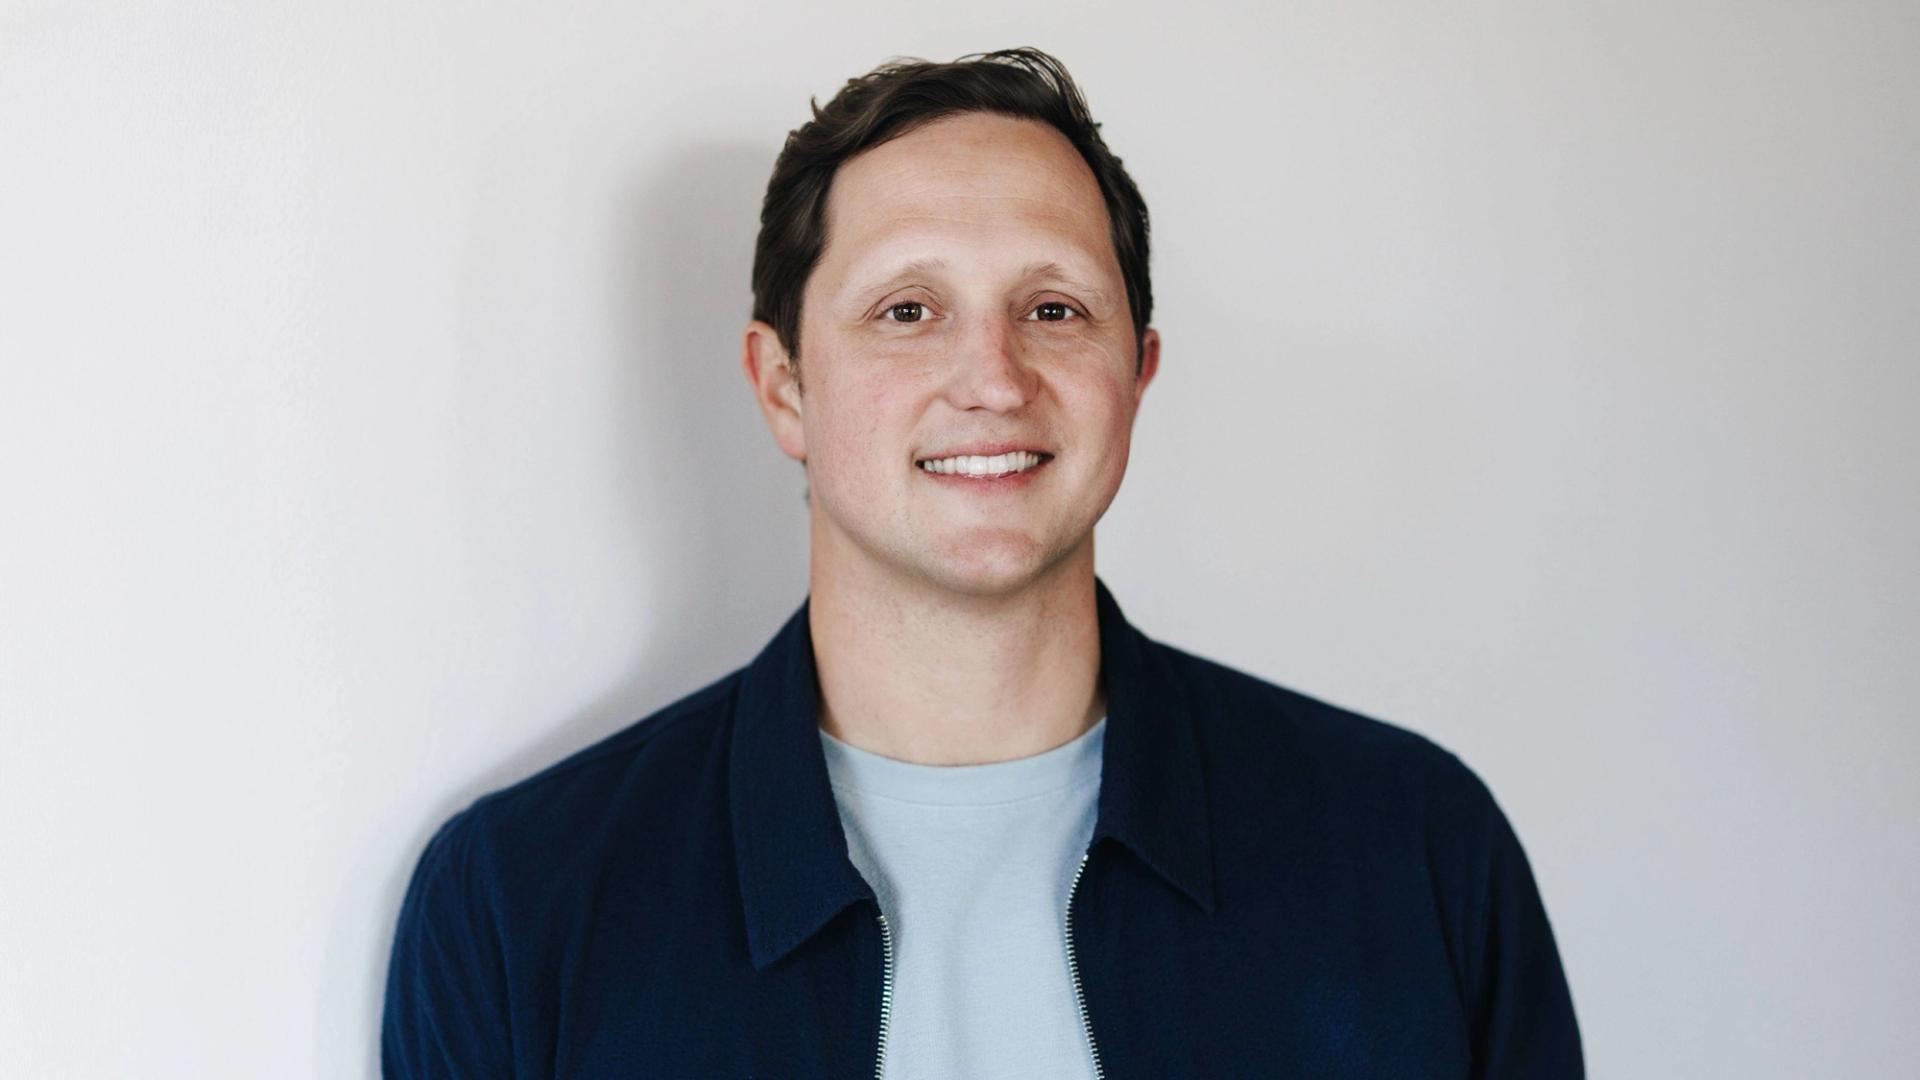
Stablecoin payments startup Velocity raised another $10 million from investors including Visa (V), Circle (CRCL) and Ripple, extending a Series A that now totals $48 million as financial heavyweights push deeper into blockchain-based payments infrastructure.
Haun Ventures, Translink Capital and Mirana Ventures also participated in the extension, which follows a $38 million Series A announced in July.
The new investment valued the London-based firm at $200 million post-money, CEO Eric Queathem told CoinDesk in an interview. The original Series A round was oversubscribed, he said.
The funding comes as stablecoins, or cryptocurrencies tied to fiat money, are becoming a bigger part of global money movement. Once used primarily by crypto traders to shift dollars between exchanges, stablecoins have grown beyond $300 billion in circulation and are increasingly being used in payments, cross-border transfers and corporate treasury operations.
Velocity is going after the infrastructure behind those transactions. Its platform is designed to let payment companies and banks use stablecoins for settlement, liquidity and treasury operations without ripping out the systems they already use.
Payments plumbing
Queathem previously worked at Worldpay, which settles more than $2 trillion in annual payments volume. That experience helped shape the idea for Velocity. While consumer-facing payments have improved dramatically, much of the infrastructure moving money between issuers, card networks, acquirers and merchants remains cumbersome.
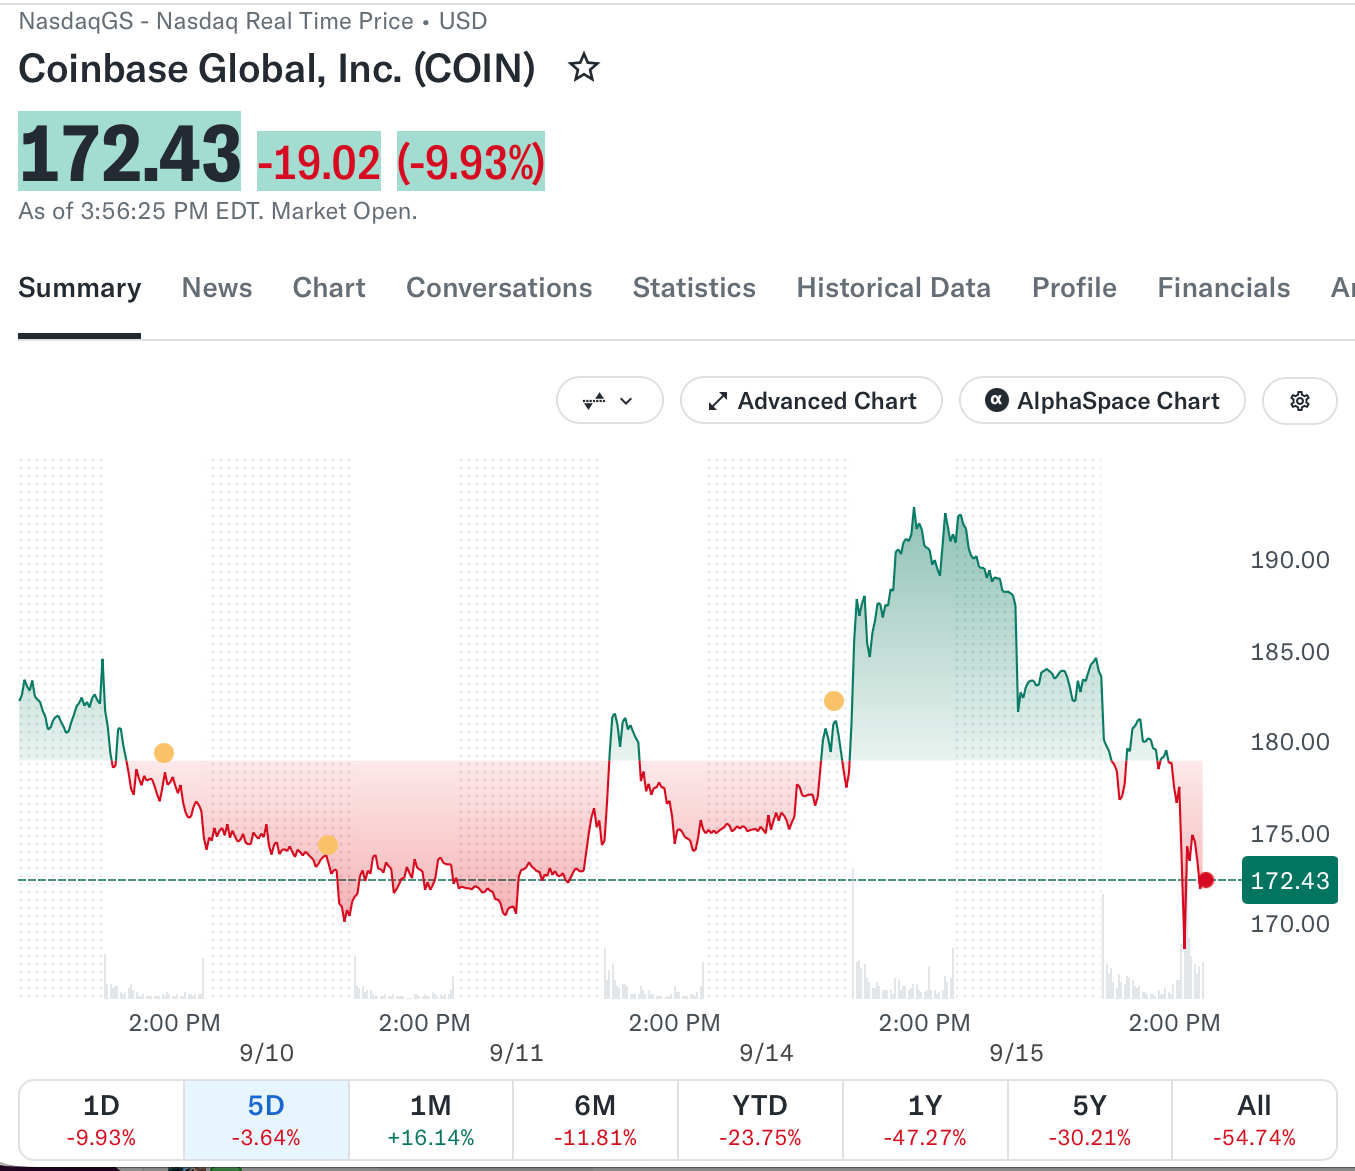
Crypto-linked stocks fell sharply on Tuesday after the US Senate failed to advance the CLARITY Act, with shares of Circle and Coinbase dropping about 10%.
Bitcoin treasury companies were also hit, with American Bitcoin falling around 8%, while Strategy and Strive each declined about 5%, according to Yahoo Finance data. Bitcoin miners joined the selloff, with Riot Platforms falling about 6%, CleanSpark nearly 5%, Hut 8 more than 4% and IREN almost 4%.
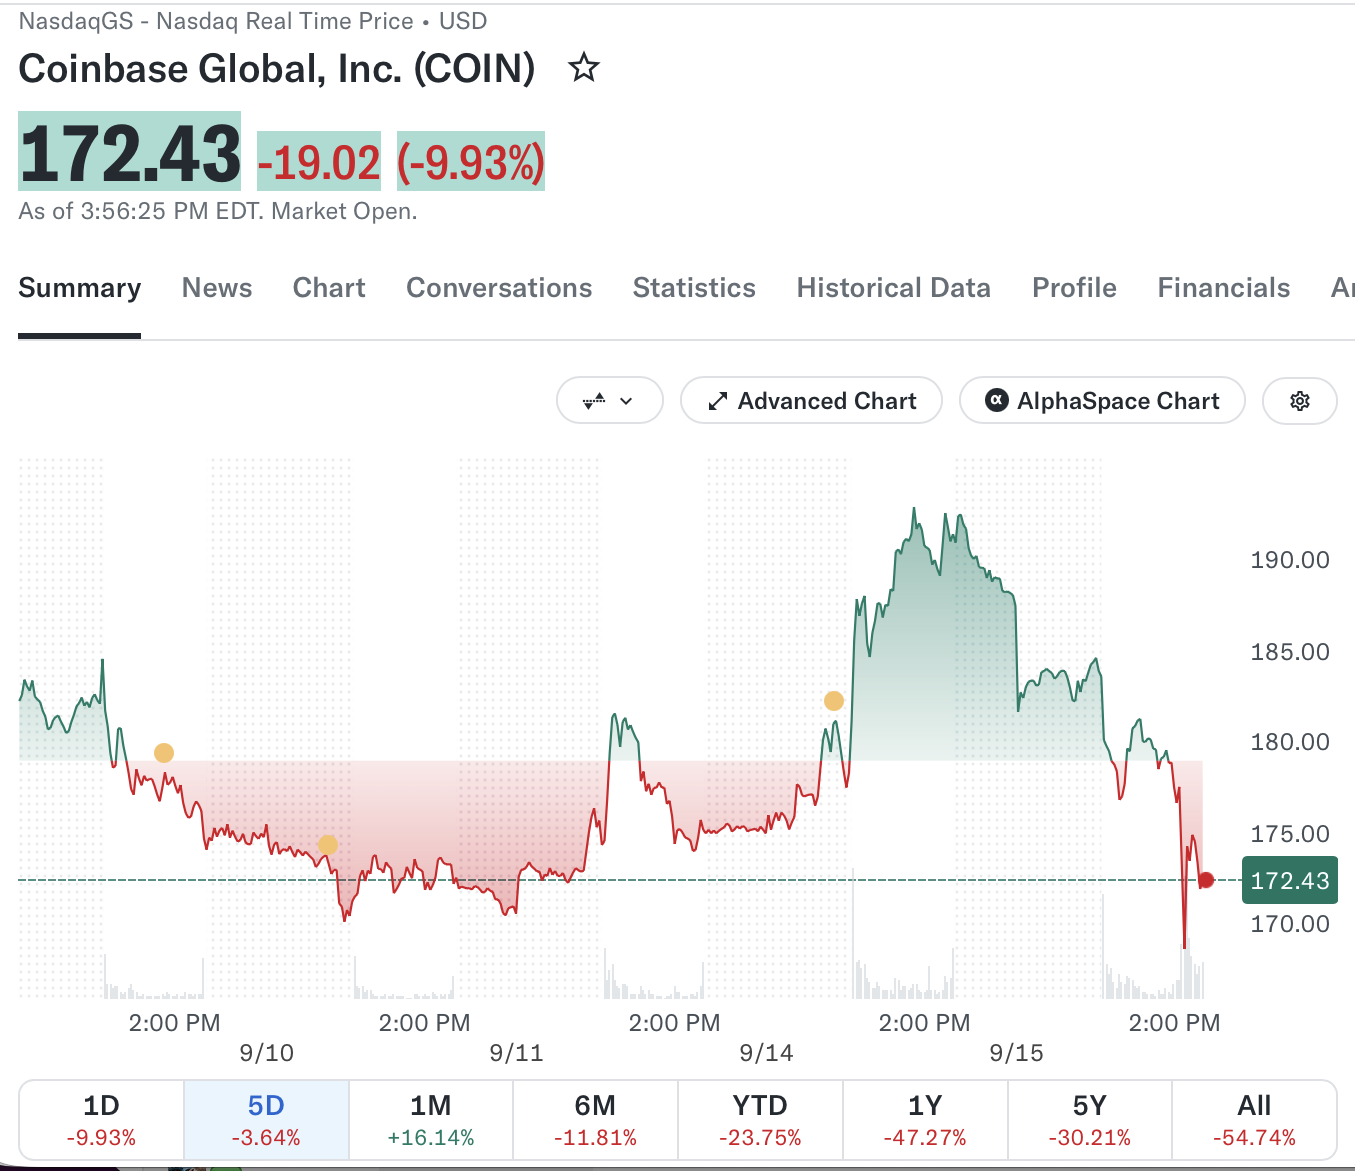
Coinbase (COIN) shares fell 9.9% on Tuesday. Source: Yahoo Finance
The declines followed a Senate vote on a cloture motion to bring the legislation to the Senate floor, short of the 60 votes required. The CLARITY Act would set rules for the US digital asset market and delineate which parts of the industry fall under the Commodity Futures Trading Commission (CFTC) and Securities and Exchange Commission (SEC).
The setback leaves the bill with little time to advance this year, with fewer than 36 legislative days remaining before a new Congress is sworn in following November’s midterm elections.
Following the vote, Bitcoin briefly fell below $75,000, but had climbed back to around $76,000 at the time of writing, CoinGecko data showed.
Related: Democrats push back on GOP’s ‘final’ CLARITY offer with counterproposal: Politico
Armstrong pushed for CLARITY ahead of vote
Coinbase CEO Brian Armstrong had been one of the most vocal industry advocates for the CLARITY Act, saying in May that the legislation had never been in a “stronger or more bipartisan position.”
Armstrong was even more explicit about the bill’s prospects in August, predicting either “60+ votes in the Senate on September 15th” or new rules from the CFTC and SEC on Sept. 16 if the bill failed to advance. “Sounds like clarity is coming either way,” he wrote on X.
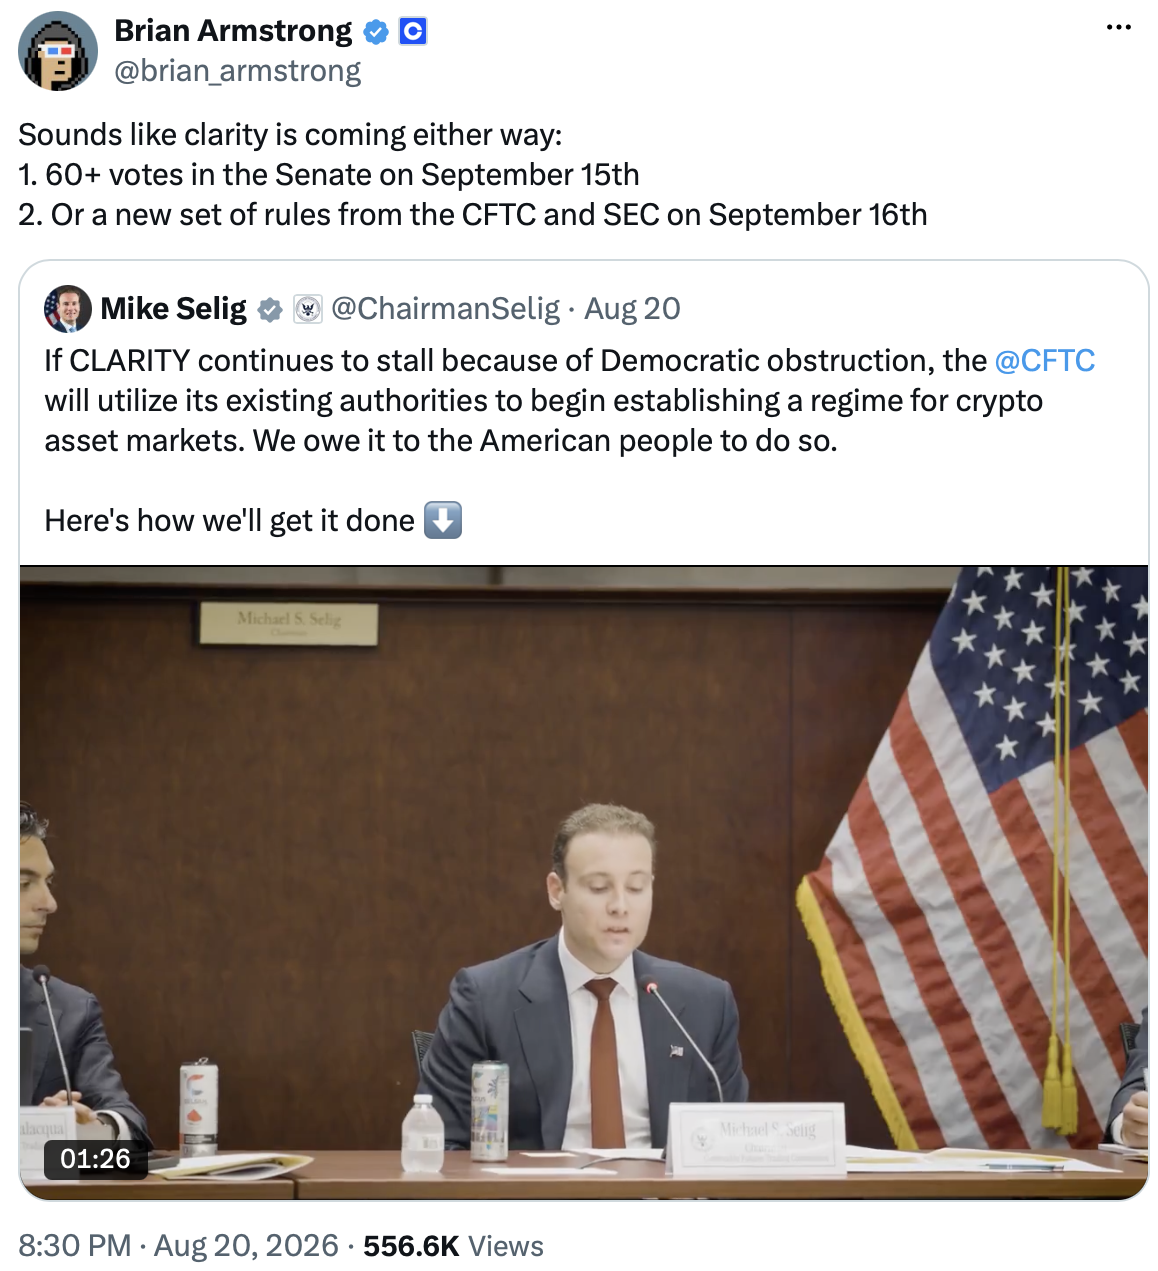
Source: Brian Armstrong
Ahead of Tuesday’s vote, Armstrong again urged senators to support the legislation, framing the choice as one between promoting US crypto innovation and allowing other countries to take the lead. “History — and the crypto voter — won’t forget,” he wrote.
Following the failed vote, Strategy co-founder Michael Saylor offered his own take on regulatory clarity. “The only clarity you need is Bitcoin,” he wrote on X.
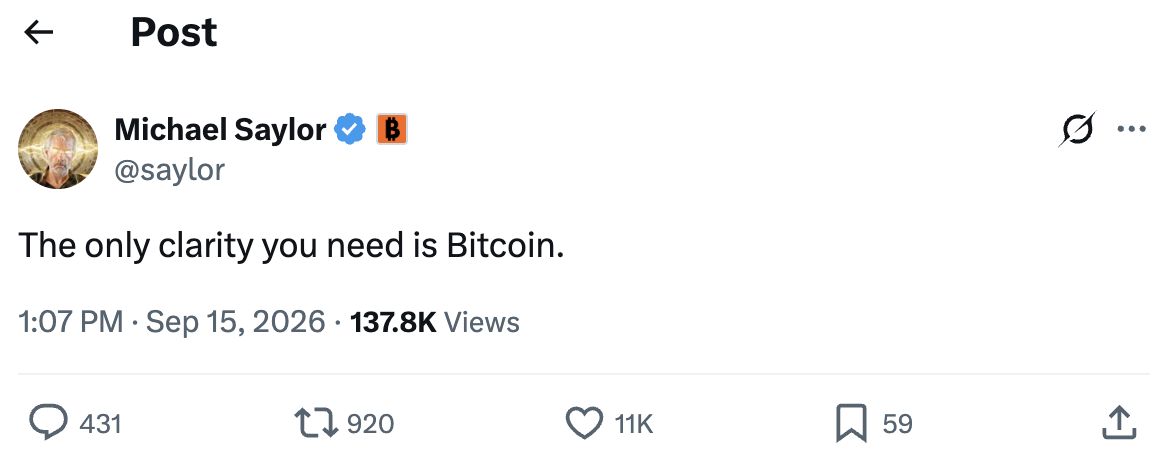
Source: Michael Saylor
Bankers trying to kill Clarity should remember that incumbent media companies failed to halt the Internet’s upheaval of their industry. So, if you care about American leadership, then why not write the laws governing this transformation here and now, rather than cede that position to some other country keen to lead in global finance.
For years, regulatory ambiguity has functioned as an unlikely moat around the crypto industry. Startups and offshore firms can tolerate legal and regulatory risks that heavily regulated financial institutions cannot. Those risks have kept many of the world’s largest financial companies on the sidelines.
Clarity would fill the moat.
With clear rules, incumbents could wield their formidable advantages: trillions of dollars of capital, hundreds of millions of customer relationships, global distribution, sophisticated risk management, trusted brands, and decades of regulatory experience.
That should terrify crypto companies far more than it terrifies banks.
Critics portray Clarity as deregulation or, worse, a giveaway to the crypto industry. They have it backwards. Clear rules would expose crypto companies to the full force of competition from some of the most powerful financial institutions in the world.
Such competition is exactly what lawmakers should want.
The history of financial innovation is not a story of new technologies’ destroying incumbents. After all, banking has been transformed for the better by technologies from the telegraph to the internet. In each case, forward-looking institutions used such inventions to reach new customers, create new products, and cultivate new markets.
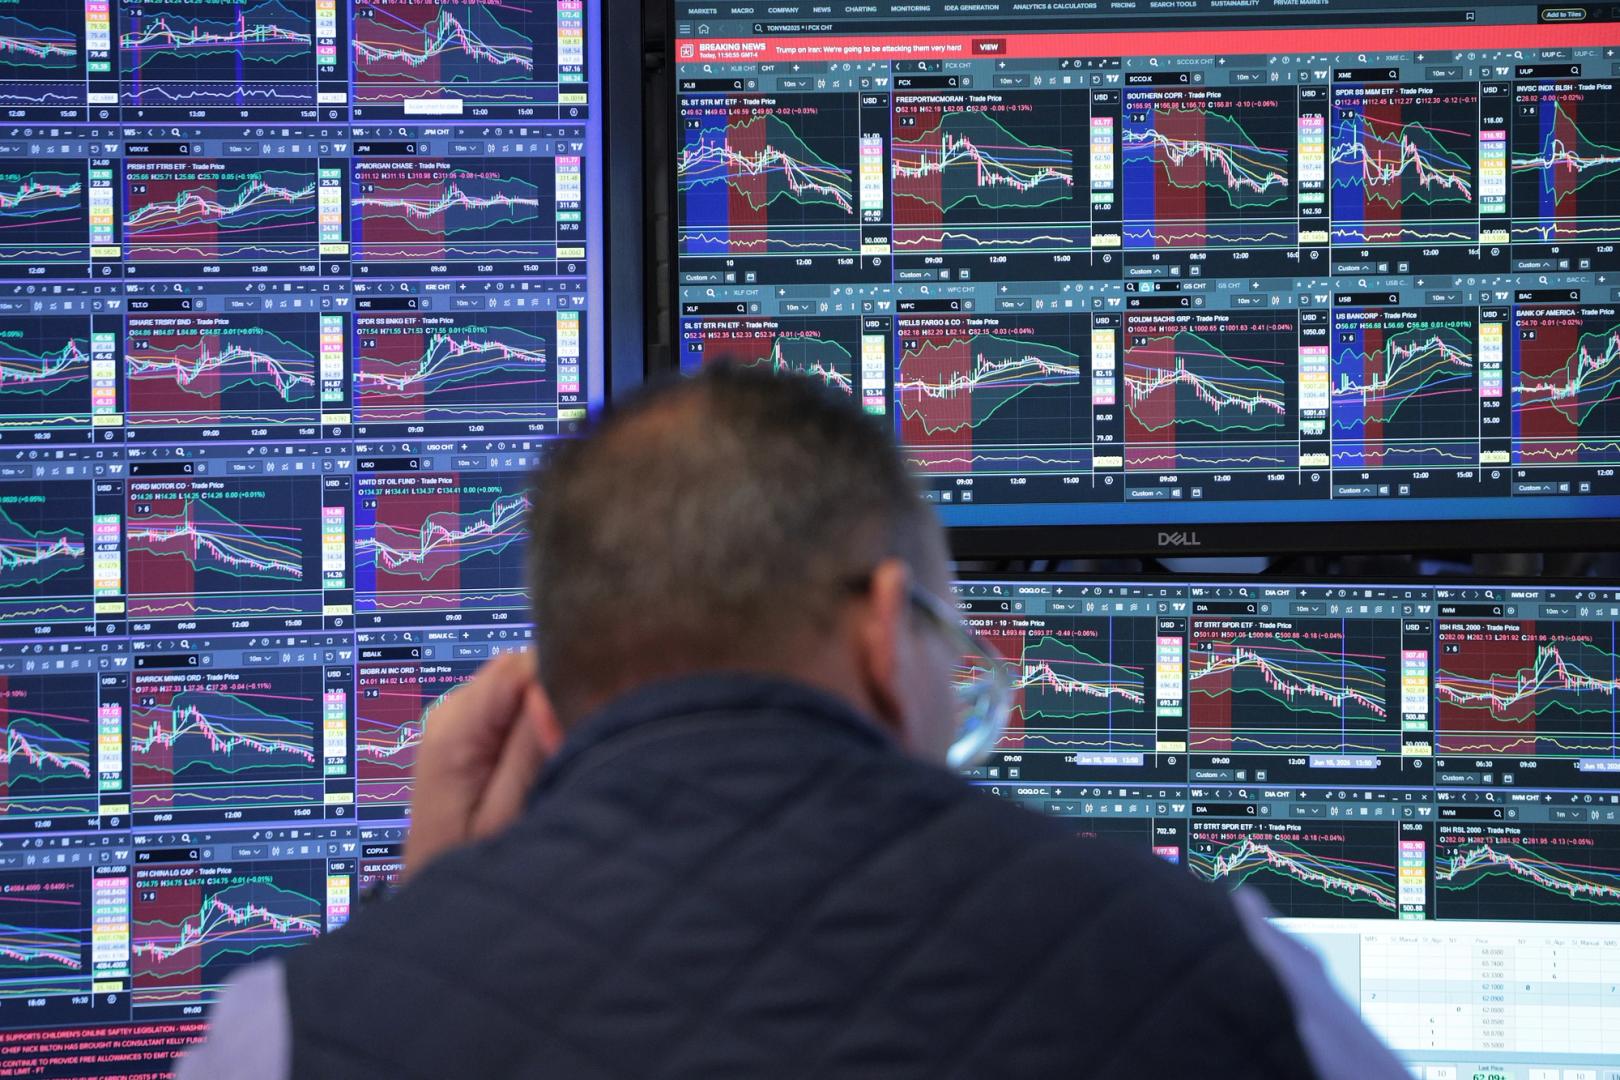
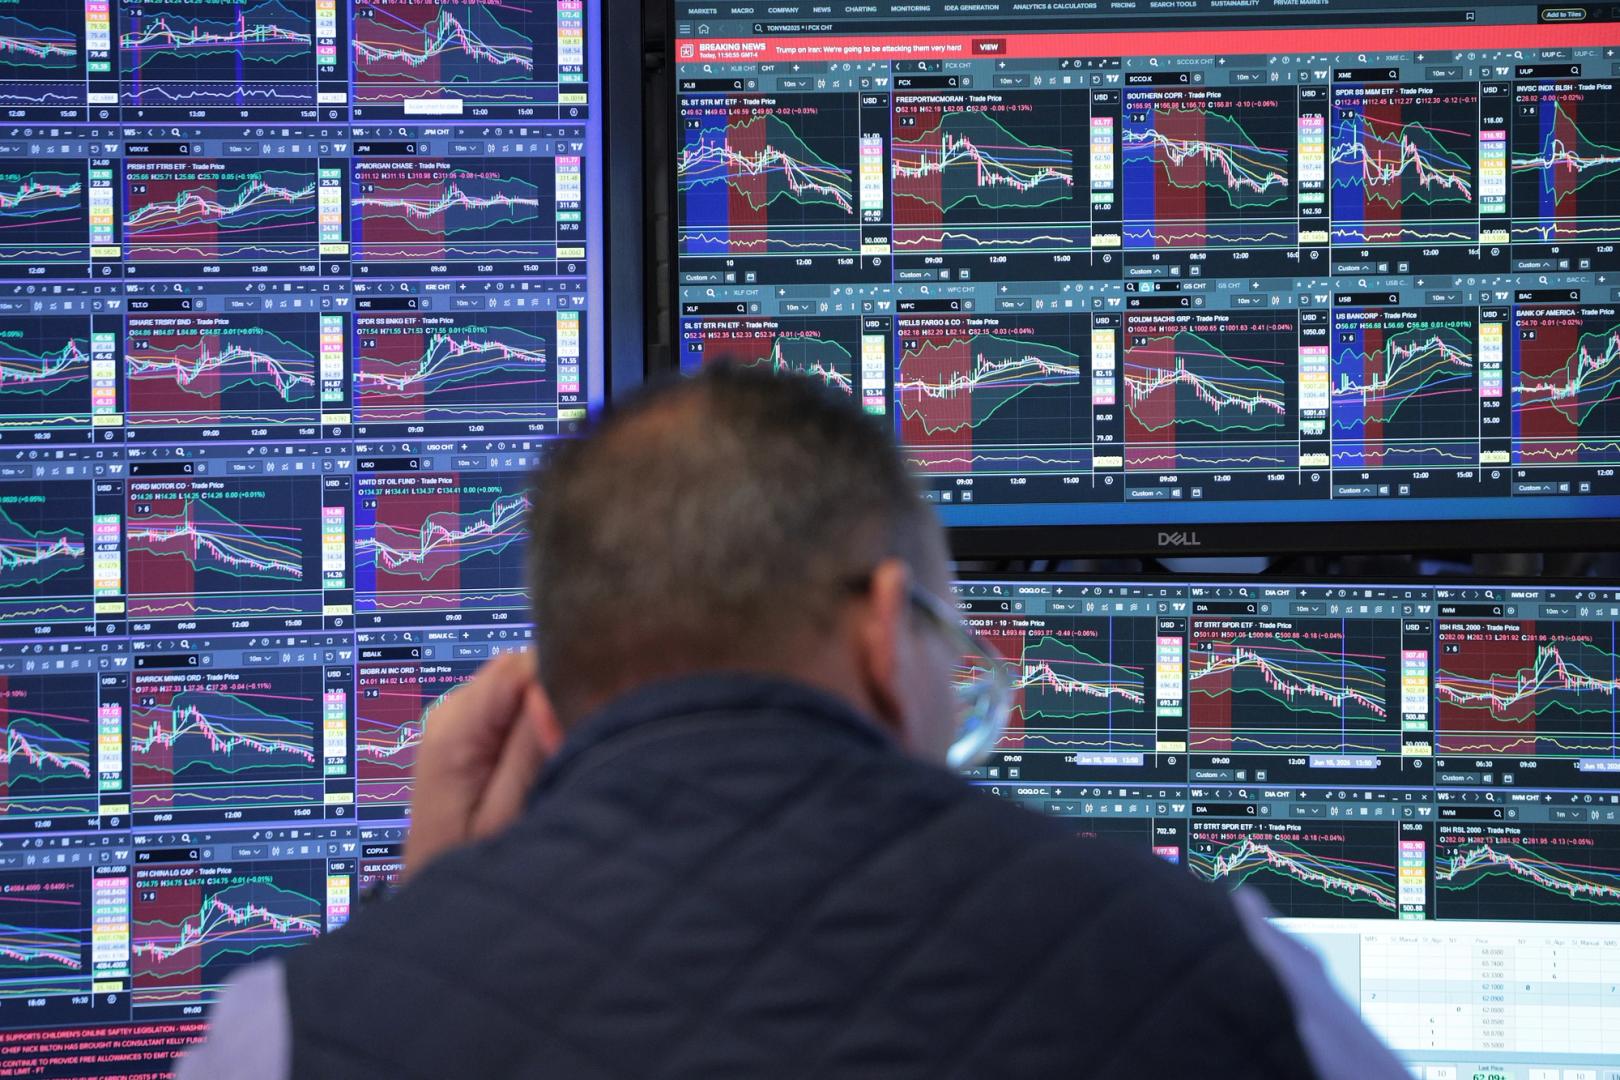
Crypto stocks were a sea of red Tuesday afternoon after the Senate failed to advance the Clarity Act, dealing a major blow to an industry that has spent years — and hundreds of millions of dollars in campaign contributions — gunning for a comprehensive U.S. regulatory framework.
Coinbase · was down nearly 9% at $174.42, while stablecoin issuer Circle · dropped 9.4% to $88.26. Galaxy Digital · lost 8% and Gemini (GEMI) fell 7%.
The pain spread across the sector. Robinhood · was down 3%, Bullish · lost 5% and eToro (ETOR) fell 4%.
Among crypto miners, Riot Platforms · dropped 5%, while MARA Holdings ·, CleanSpark ·, IREN and Core Scientific · were all down between roughly 3% and 4%.
The declines came after the Senate voted 49-50 on a procedural motion to advance the Digital Asset Market Clarity Act, well short of the 60 votes required.
The bill would have set rules for how different cryptocurrencies and blockchain projects are treated in the U.S., while giving the Commodity Futures Trading Commission (CFTC) greater authority over crypto spot markets.
Crypto World
Bitcoin’s Price Plunges to $75,000 as Senate Votes Against Advancing Crypto CLARITY Act
Bitcoin’s price has plunged to slightly below $75,000 in minutes, losing more than 2.3% throughout the past 24 hours.
The sudden move comes immediately after it became evident that the Digital Asset Markets CLARITY Act will not get the necessary votes to advance without further debate.

The move also comes amid a massive uptick in liquidations, which soared by over 200% in the past day. The total number is currently around $760 million, where over $290 million of that were liquidated in the past hour alone, amid the serious volatility.

The rest of the market is also going through similar price action. Ethereum (ETH) is down by about 3.5%, Solana by 2.2%, TRX by 2.2%, HYPE by 3.8%, and so forth.
The failure of the Senate to advance the bill doesn’t mean that the legislation is essentially dead. Instead, it means that debates can continue, which will delay it further. Many sponsors have withdrawn their proposed legislation in the past following failure to advance at this stage, but whether or not this will happen to the CLARITY Act remains to be seen.
Keep in mind that tomorrow the US Federal Reserve will also convene to announce their decision on interest rates, which is also likely to cause substantial volatility in the markets.
The post Bitcoin’s Price Plunges to $75,000 as Senate Votes Against Advancing Crypto CLARITY Act appeared first on CryptoPotato.

U.S. Confirms It Has Deployed Weapons in Space for the First Time

A to Z Finance a Gen Z Needs to Know: Stock, stock market, NSE, BSE, Sensex, Nifty 50, SEBI,
Boy, 3, goes missing after playground visit as police ask villagers to join search



-

 Fashion4 days ago
Weekend Open Thread – Corporette.com
-

 Business6 days ago
Micron Stock Climbs Above $1,031 as AI Memory Crunch and a $50 Billion Outlook Fuel the Rally
-

 Tech2 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Business6 days ago
AMD Stock Climbs After Management Lifts 2027 Data Center Outlook Toward $70 Billion in AI Sales
-
 Crypto World7 days ago
Bitcoin price risks $76K drop as $78K support weakens
-

 Crypto World5 days ago
XAG/USD: Silver’s Short-Term Rally Meets Its Moment of Truth
-

 Crypto World5 days ago
2 Chip Stocks Broke Out This Week. Neither Was Nvidia
-
 Crypto World7 days ago
Ethereum price stalls below $2,500 as ADX drops to 11
-

 Business5 days ago
10 Most-Streamed Songs On Spotify In 2026 So Far, Led By Ella Langley’s Dominant Run On The Charts This Year
-

 Tech5 days ago
Battery life is the only iPhone 18 Pro and iPhone Duo upgrade I care about. Apple didn’t disappoint
-
 Crypto World6 days ago
Pi Network ships Protocol 27 on a network with 14 million users and zero DeFi
-

 Crypto World5 days ago
OKX launches 10x OpenAI, Anthropic X-Perps in Europe
-

 Crypto World5 days ago
Diesel Tops $6 a Gallon for the First Time as 28 States Set Records
-

 Tech6 days ago
Apple Watch Ultra 4 vs Watch Ultra 3: Should you really spend another $799?
-

 News Videos4 days ago
Facing Financial Fears
-
 Tech7 days ago
Modders have already found two ways to make DLSS 5 playable, and neither one is Nvidia’s
-

 Crypto World6 days ago
Bitcoin price risks $70K if $78K neckline breaks
-
 Crypto World7 days ago
Bitcoin price holds near $79K as cycle drawdowns narrow
-
 NewsBeat7 days ago
What went right this week: an ‘historic’ fall in violent crime, plus more
-
 Business7 days ago
Meta debuts long-awaited personal AI agent, Muse
You must be logged in to post a comment Login