
Crypto World
CoreWeave down 32% since joining the Nasdaq 100

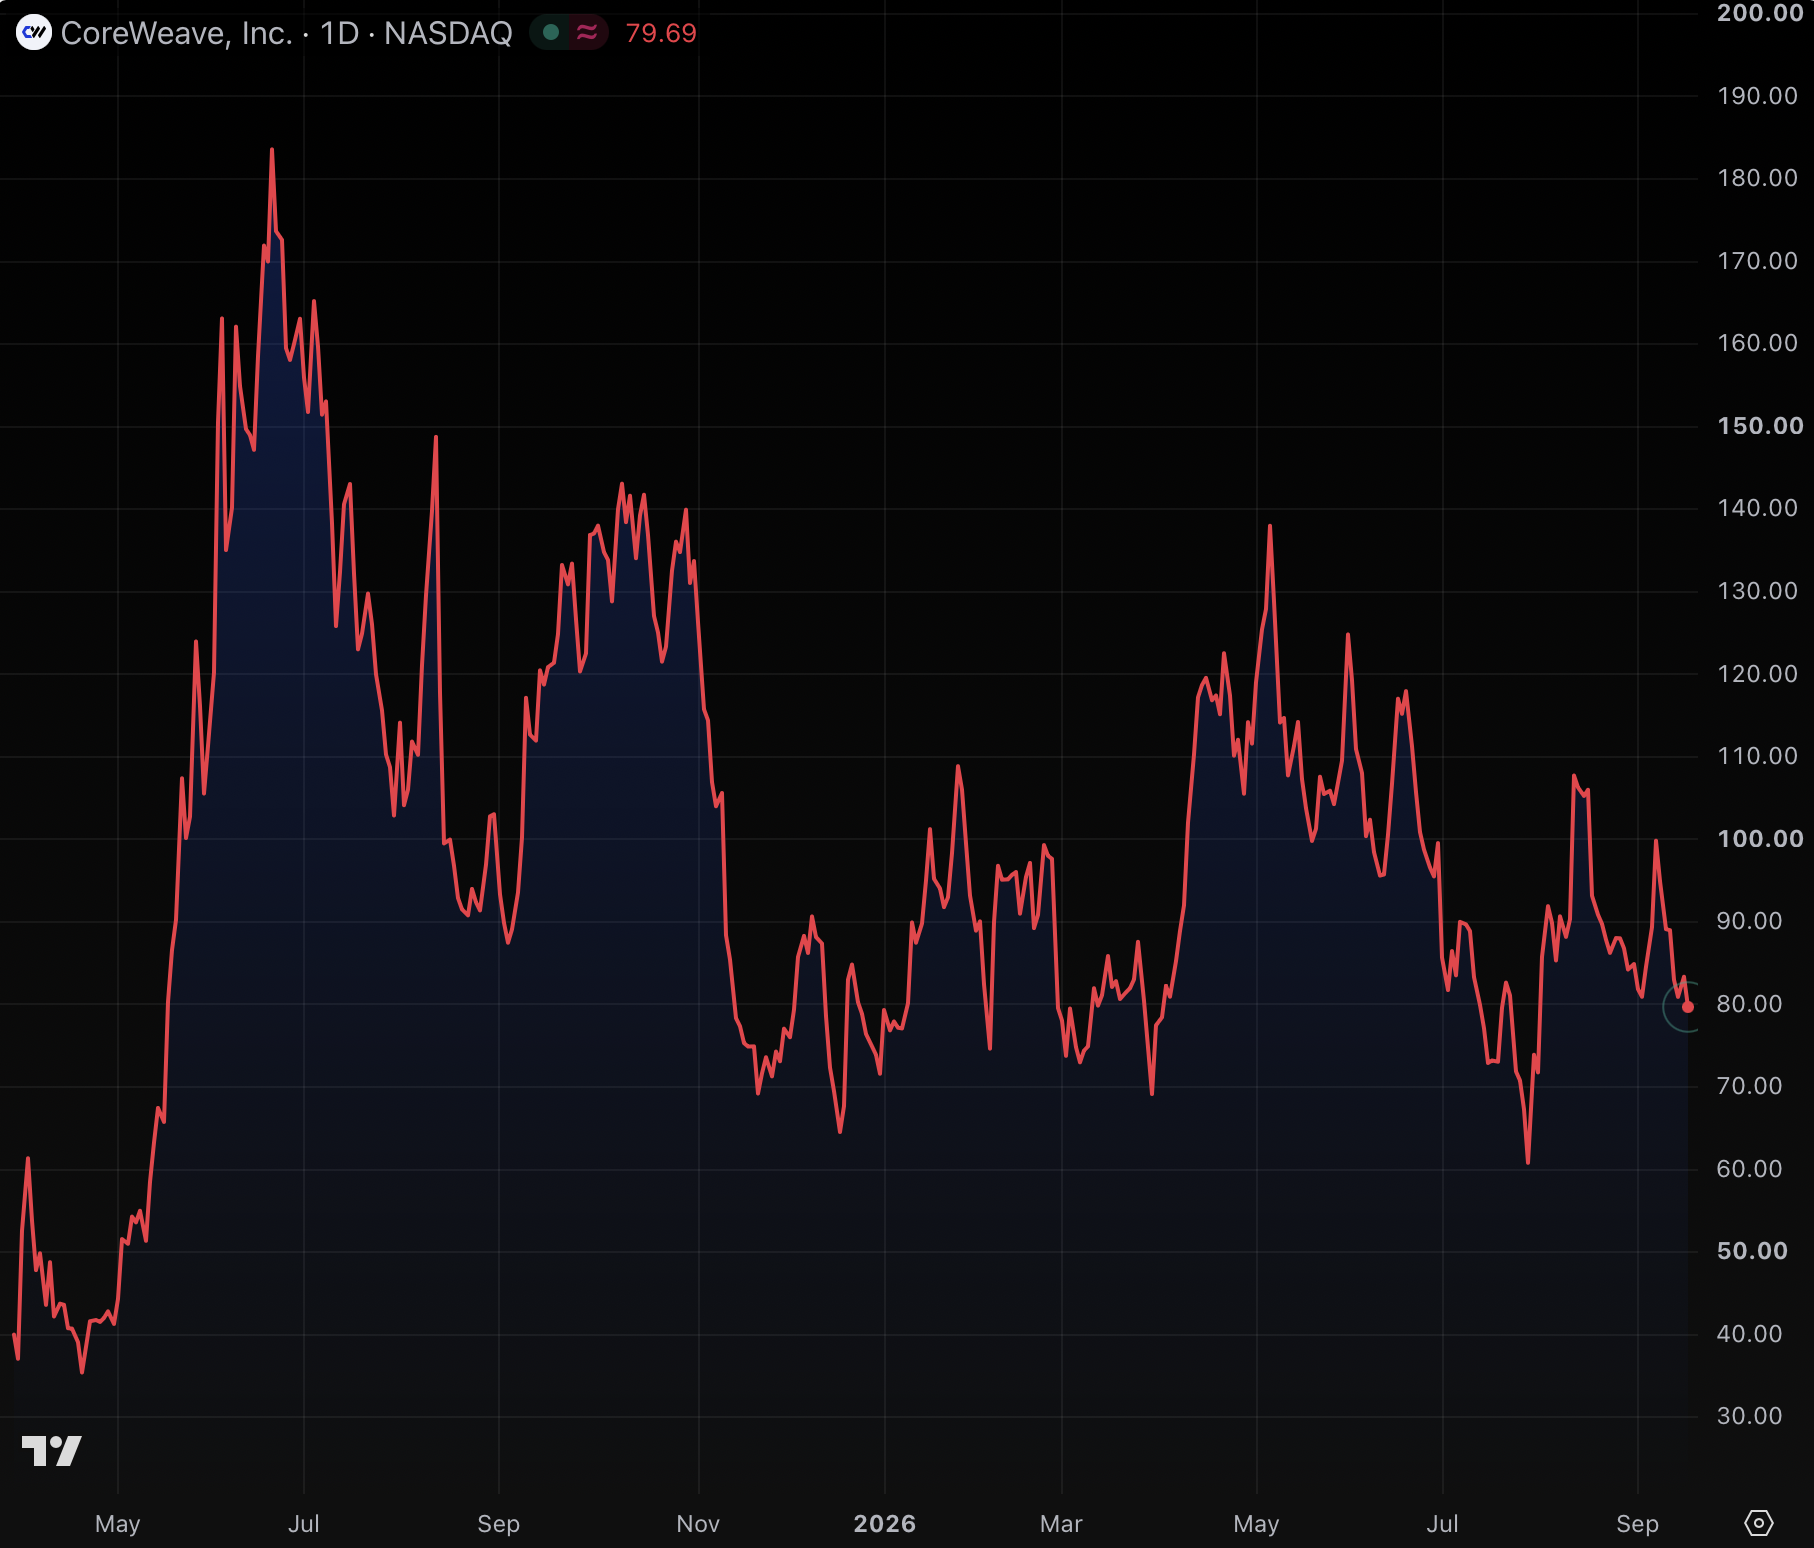
AI company CoreWeave has lost one-third of its value since the day it joined the Nasdaq 100 index, despite doubling revenue in the second quarter and boasting of $100 billion in backlogged revenue.
As common shareholders have suffered, insiders have been steadily selling.
Since Nasdaq 100 indexation became effective on June 22, 2026 and forced retirement savers to passively buy CoreWeave shares through hundreds of Nasdaq 100-linked funds around the world, executives and board members at the company have dumped over $600 million worth of stock.
- CEO Michael Intrator has liquidated over $320 million
- Co-founder Brannin McBee has sold $220 million
- Kristen McVeety, general counsel and corporate secretary, has sold over $22 million
- The company’s CSO, CFO, COO, and CAO have sold a combined $36 million
CoreWeave’s stock hit its all-time high of $187 on June 20, 2025, almost a year before it became a constituent of the Nasdaq 100. However, it’s been declining for 15 months, including double-digit losses for retirees who waited for Nasdaq committee members’ de facto blessing this summer.
Nasdaq announced its rebalance favoring CoreWeave on June 11, 2026, effective June 22. The stock opened that day above $119, yet it trades near $80 today.
Nasdaq 100 tapped CoreWeave to lose retirement savings
The company satisfied all of the technical criteria for entry, and seemed to be a decent choice from a fundamental perspective.
It claimed to have contracted revenue with a backlog reaching $104 billion, with billions of dollars in fresh commitments that have arrived since July.
With this seemingly enviable business, CoreWeave houses racks of Nvidia GPUs in leased data centers and sells computational capacity to Meta, OpenAI, and other AI labs.
There is just one problem. Nvidia’s chips lose value fast amid high heat operation and, more importantly, endless waves of new models from fabricators. CoreWeave must account for depreciation, which has a devastating drag on its profitability.
Read more: Anthropic’s non-existent blockchain shares are tripping up investors
Earnings before depreciation
In the second quarter alone, depreciation and amortization of its AI equipment exceeded $1.3 billion, a staggering 54% of revenue. Worse, the heavily indebted company had to pay interest on its debt pile of $640 million, up from $267 million a year earlier.
Those two accounting lines consumed more than three-quarters of every dollar the company generated.
The company is also spending far more than it generates. Full year capital expenditure guidance sits at $35-39 billion — far higher than CoreWeave’s revenue guidance of $12.4-13.2 billion.
In other words, the fast-growing, cutting-edge company plans to spend roughly $3 for every $1 it plans to earn.
Free cash flow in the second quarter came in at negative $5.7 billion.
CoreWeave’s buildout has been financed almost entirely with borrowed money. Total indebtedness grew from $7.9 billion to $21.4 billion by the end of 2025, and now exceeds $35.6 billion.
The business isn’t short of demand for its services. It seems to be short of a business that can transform that demand into profit faster than Nvidia’s chips lose value and its lenders collect interest.
As the stock has declined for over 15 months, the people running the company have kept selling.
Got a tip? Send us an email securely via Protos Leaks. For more informed news and investigations, follow us on X, Bluesky, and Google News, or subscribe to our YouTube channel.

WisdomTree and MoonPay have announced a partnership designed to make a tokenized U.S. Treasury money market fund easier for U.S. investors to access. The companies say MoonPay will supply technology that serves as a distribution access point for WisdomTree’s WisdomTree Treasury Money Market Digital Fund (WTGXX), which aims to maintain a $1 share price.
MoonPay also plans to use WTGXX within its stablecoin reserve management stack. The move highlights how regulated cash-like products are increasingly being structured to plug directly into stablecoin operations, rather than remaining siloed as standalone tokenized funds.
Key takeaways
- MoonPay will be used as an access point for WisdomTree’s tokenized Treasury money market fund, WTGXX.
- WisdomTree says the integration is meant to leverage MoonPay’s network of more than 35 million accounts.
- MoonPay intends to include WTGXX as part of its stablecoin reserve management approach.
- RWA.xyz data shows tokenized U.S. Treasury markets at about $15.4 billion, with WTGXX around $1.23 billion.
- WTGXX reportedly recorded $466 million in net flows over the prior 30 days, calculated from token minting and burning.
A tokenized money market fund built around $1 stability
The partnership centers on WTGXX, WisdomTree’s tokenized money market mutual fund. According to the companies’ announcement, the fund is structured to target a stable $1 share price—an important design choice for investors seeking lower-volatility exposure compared with traditional crypto assets.
In this setup, MoonPay’s technology is expected to create the practical on-ramp for investors who want exposure to the tokenized fund. The firms framed the distribution benefit around scale: WisdomTree said the arrangement would give it access to MoonPay’s network of more than 35 million accounts.
For market participants, this matters because the usability gap has often been the limiting factor for tokenized funds. Tokenization alone doesn’t guarantee demand; access, custody workflows, and investor onboarding typically determine whether a product actually attracts capital.
Why MoonPay wants WTGXX in its reserves
MoonPay, which provides infrastructure for moving between fiat and digital assets, plans to use WTGXX as part of its stablecoin reserve management. In the announcement, the companies positioned the fund as a fit for the kinds of high-quality, liquid assets that stablecoin issuers and treasury operators typically seek.
MoonPay said it launched its enterprise stablecoin business in November 2025. The company issues dollar-denominated stablecoins across several blockchains, backed by U.S. dollars and other high-quality liquid assets held in segregated accounts.
This is the first-time, at least in the way described publicly here, that a specific tokenized Treasury money market fund has been tied directly to MoonPay’s reserve stack. If the integration works smoothly, it could help normalize a broader “tokenized cash management” model—where Treasury-like products become operational inputs to stablecoin liquidity and redemption capacity.
How big is WTGXX in the tokenized Treasury market?
RWA.xyz data cited in the announcement suggests the tokenized U.S. Treasury market is roughly $15.4 billion in size. Within that category, WTGXX accounts for about $1.23 billion.
While WTGXX is not the largest tokenized Treasury product on the list by the numbers provided, it is significant enough to matter to both sides of the ecosystem—investors allocating to tokenized money market instruments and operators building stablecoin reserve workflows.
Volume and momentum are also part of the story. The companies said WTGXX recorded net flows of $466 million in the past 30 days. Net flows were calculated as the difference between tokens minted and tokens burned. In the same timeframe, the Ondo U.S. Dollar Yield fund (USDY) was the only other tokenized Treasurys fund mentioned as having positive net flows, at $66 million.
This relative outperformance matters because flows often function as a proxy for perceived usability and demand. If WTGXX continues to attract inflows after the distribution changes, it could strengthen its role as a reserve asset candidate across the stablecoin infrastructure stack.
Potential expansion beyond the first integration
WisdomTree said the collaboration could extend to additional tokenized funds, including in markets outside the United States. The firm also reported that it manages about $176.7 billion in assets, underscoring that it is approaching tokenized Treasurys and cash-like instruments as part of a broader product strategy rather than a one-off experiment.
For investors, the watch item is whether expanded distribution and stablecoin reserve adoption increase real-world liquidity and reduce friction across onboarding and transfers. For builders, the broader implication is that stablecoin reserves may increasingly rely on tokenized, share-priced cash instruments—creating demand for issuance rails and distribution access points similar to the one MoonPay is providing here.
Still, several practical questions remain open. The announcement focuses on the technology and the intended uses, but readers should watch for details on how investors experience the onboarding process, what custody and settlement mechanics are involved for U.S. participants, and whether MoonPay’s reserve integration affects WTGXX’s day-to-day token mint-and-burn dynamics.
Going forward, the clearest signals to track are whether tokenized Treasury market share shifts toward WTGXX after this access partnership, and whether MoonPay’s reserve allocation approach expands to other tokenized cash products as additional markets and funds are considered.
Why Meta's Zuckerberg, Nvidia's Huang Say An AI Slowdown Is Not Needed
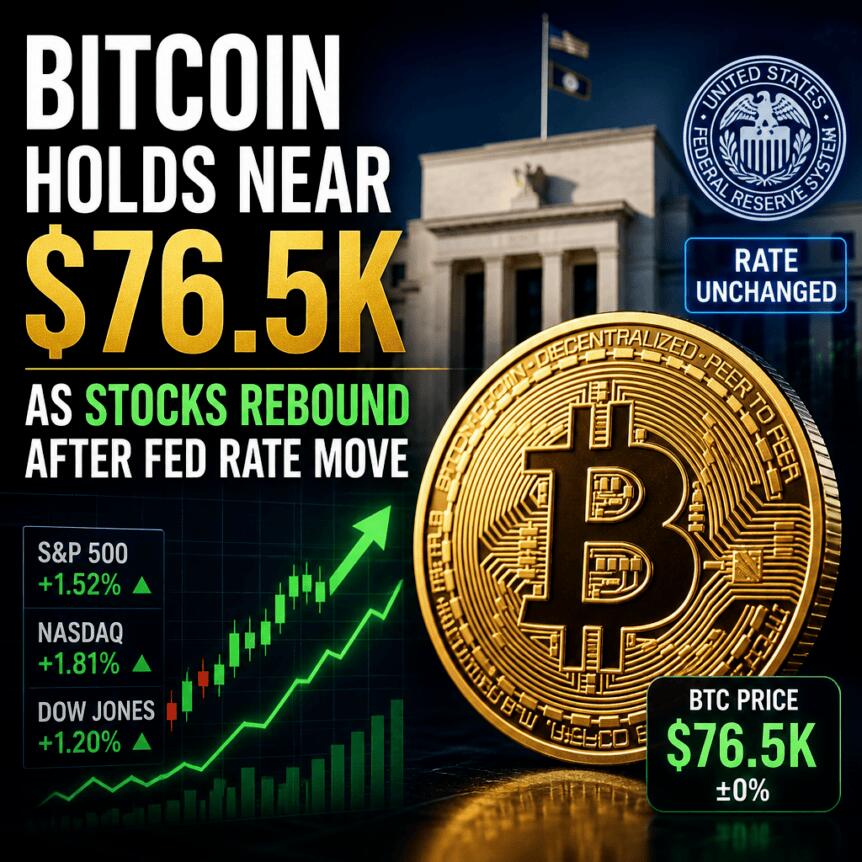
Bitcoin hovered near $76,500 in the hours after Wall Street opened, as a rebound in U.S. equities helped ease pressure on risk assets following the latest Federal Reserve decision. The move came after BTC slipped below $76,000 during the initial reaction to the Fed’s 25-basis-point increase in benchmark rates.
For traders, the key dynamic was less about a new burst of buying and more about stabilization: volatility appeared to cool over the prior 24 hours, liquidity around current levels thickened, and on-chain sentiment signals remained supportive—though not at peak “bullish conditions.”
Key takeaways
- BTC held close to $76,500 after consolidating following a dip below $76,000 tied to a 0.25% Fed rate hike.
- U.S. stocks rebounded, with the Nasdaq Composite up 1.5% and the S&P 500 gaining 0.9%, helping sentiment across high-beta markets.
- TradingView data pointed to cooling BTC volatility and only modest price moves, consistent with range trading.
- CryptoQuant’s Bull Score Index fell to around 60/100—still labeled “bullish,” but below levels associated with stronger momentum.
Range trading returns as equities find a bid
BTC’s near-term behavior looked more controlled than directional. According to TradingView, volatility eased over the last day, while price action largely stayed within the bounds needed to interact with nearby liquidity rather than driving a breakout or breakdown.
CoinGlass data also suggested a typical “two-sided” market: bid and ask liquidity thickened around spot levels, a pattern frequently associated with consolidation. In practical terms, this often means fewer aggressive liquidations and less forced repositioning—conditions that can keep traders from chasing until a catalyst reappears.
That catalyst, in this case, was partly external. U.S. equities turned higher after a policy-driven wobble, with major indexes finishing the day up on the session. The S&P 500 gained 0.9% and the Nasdaq Composite rose 1.5%, giving risk markets a fresh footing.
The Fed decision landed the day before: on Wednesday, it voted to increase benchmark interest rates by 25 basis points to 3.75%–4.0%, its first hike since July 2023. The move ended a long stretch in which the Fed had either cut rates or held them steady across prior meetings.
Earlier coverage from Cointelegraph highlighted the broader cross-market tone, noting that central-bank rates have been rising globally. In that context, the Fed’s shift fits a wider pattern: the European Central Bank delivered a 0.25% hike last week, and the Bank of Japan was expected to follow on Friday.
The Kobeissi Letter argued that assets could still perform well even if rate hikes tighten liquidity conditions, pointing to the Nasdaq’s gains as an example.
On-chain analytics: bullish trend remains, momentum fades
Bitcoin’s recent trajectory has been uneven. The article noted that after a Tuesday selloff—when BTC/USD hit new month-to-date lows—Bitcoin bounced, trading about 0.5% higher at the time of writing.
But the question for investors is whether that rebound is just pausing or actually restarting. CryptoQuant, in its latest weekly research shared with Cointelegraph, framed current conditions as supportive on the longer arc while less favorable for near-term momentum.
CryptoQuant’s head of research, Julio Moreno, said the trend is still bullish, yet macro factors and fading demand are weighing on continuation. He pointed to one of CryptoQuant’s proprietary measures: the Bull Score Index, which gauges whether market conditions fit CryptoQuant’s definition of “bullish” phases.
Moreno noted that the Bull Score Index had fallen from 80 to 60. While 60 sits at the threshold CryptoQuant uses to describe “bullish conditions,” it is also a clear step down from the higher-score environment that typically aligns with stronger momentum. In CryptoQuant’s view, this is why Bitcoin may look like it’s holding the floor without immediately resuming a sustained advance.
In the same report, CryptoQuant summarized the takeaway as “cooling, not turning.” The firm maintained that a Bull Score of 60 keeps the trend bullish, but it highlighted several offsetting pressures: fading U.S. demand, rising inflows into altcoins, and a week of macro risk that includes the delay of the CLARITY Act and the expectation of a Fed hike.
The practical implication is that investors may need to prepare for consolidation rather than assume the prior rebound automatically extends. CryptoQuant also identified levels to watch: $70,000 and the $62,000–$65,000 band as potential support zones.
What traders should watch next in a tightening-liquidity regime
The market is now digesting a key shift: the Fed has moved back into the hiking cycle after a pause period that spanned roughly three years of easing or rate holds. That matters because higher rates can change how capital flows across asset classes—often first through liquidity expectations and then through risk appetite.
Still, the immediate tape showed that equities can quickly swing back, and when that happens Bitcoin tends to respond as part of the broader risk complex. The combination of reduced volatility on the TradingView feed and thickening liquidity near spot suggests there is no urgent technical breakdown at the moment.
For participants, the next layer is monitoring whether the on-chain trend can stabilize despite macro headwinds. CryptoQuant’s Bull Score hovering around its “bullish conditions” cutoff is a reminder that the market’s internal momentum is no longer as strong as during earlier phases.
Looking ahead, the most important signals will likely be whether BTC can reclaim upside momentum without a fresh wave of macro pressure, and whether support zones identified by CryptoQuant hold if consolidation deepens. If liquidity conditions tighten again or equity volatility returns, Bitcoin’s range could widen rather than resolve cleanly.
Readers should watch how the Bull Score Index develops from this threshold area and whether $70,000 and the $62,000–$65,000 support band stay intact as the market continues to weigh central-bank policy expectations.
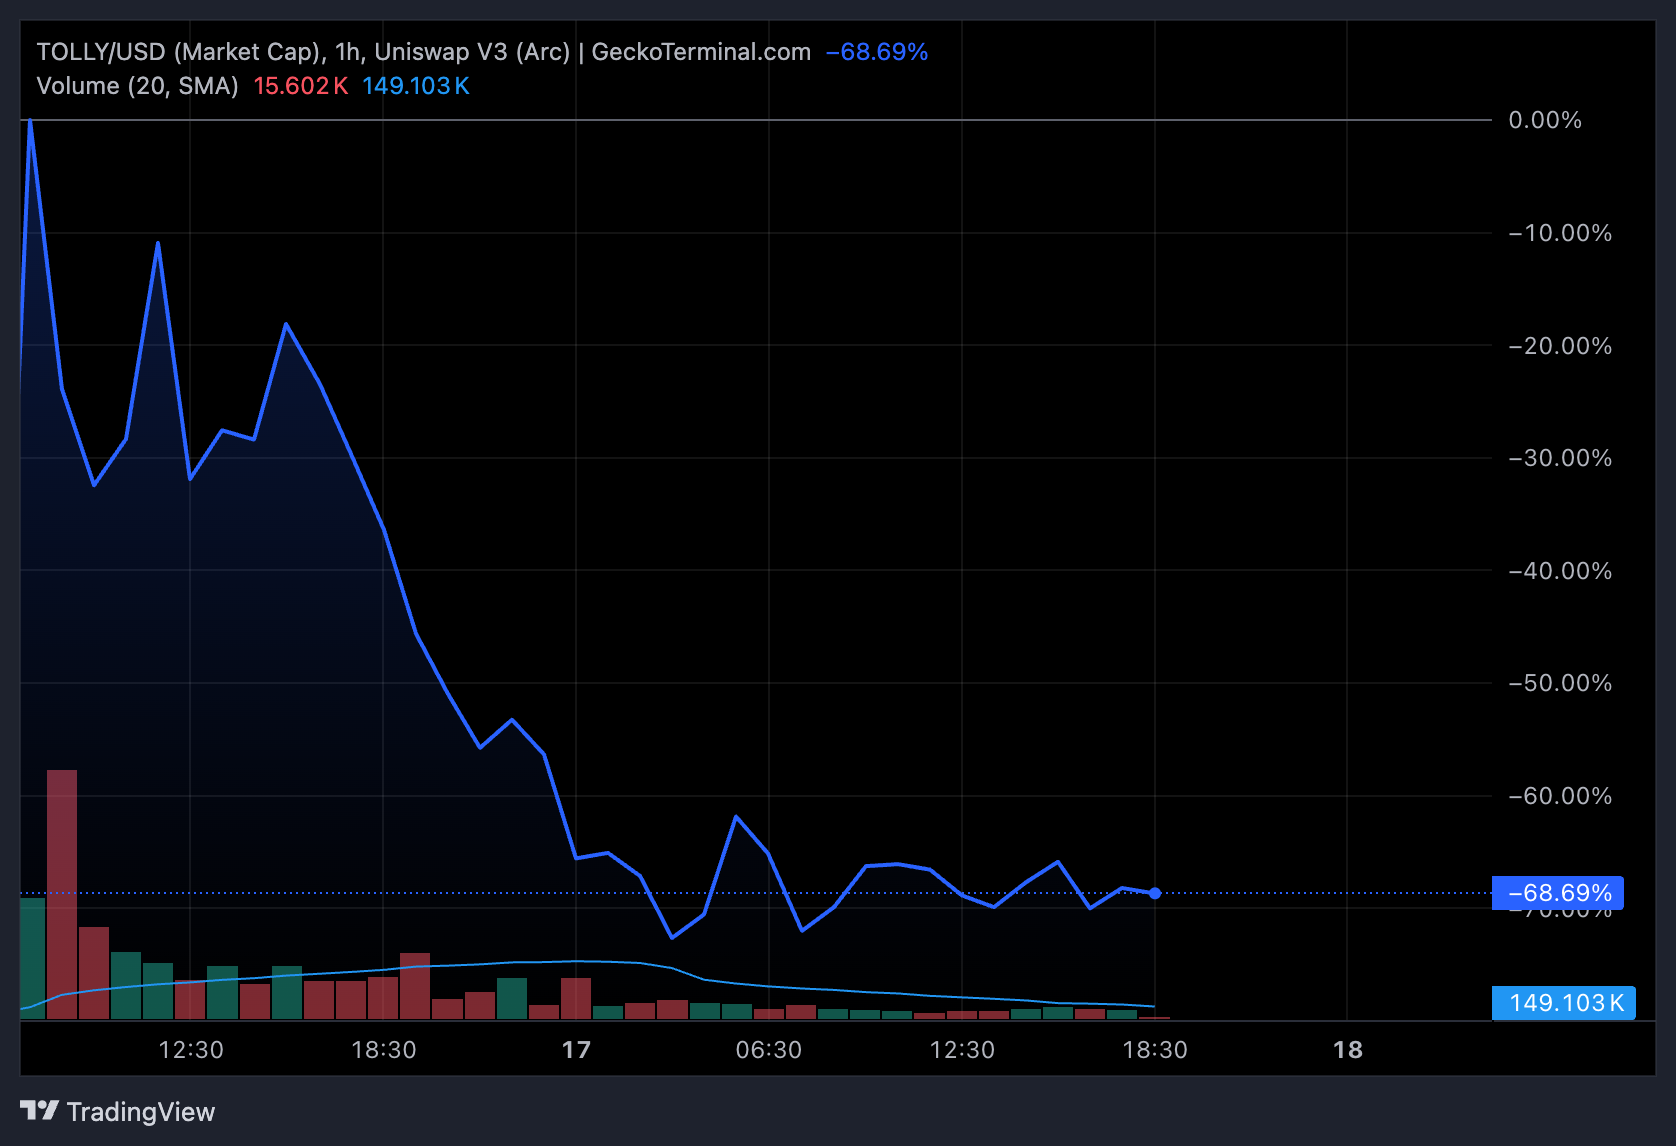
Tokens on Circle’s new Arc blockchain fell in the past 24 hours after traders said they sold because a builder on the mainnet launch livestream appeared to be Indian. The man in the clip does not work for Circle.
Panchu Vijay Pal runs XyloNet, a third-party stablecoin exchange that Circle’s Arc team featured as a partner in June. Traders sold tokens he has no connection to, on a chain whose block producers include BlackRock, Visa, and Mastercard.
Why Did One Guest Segment Move an Entire Chain?
Circle opened Arc’s public mainnet on Wednesday with a broadcast from New York. The main stage carried keynotes from CEO Jeremy Allaire and roundtables with BlackRock, DTCC, and Aave. A Developer Pre-Show ran earlier, billed as partner highlights and community drop-ins.
Pal appeared in that pre-show from a home setup with a gaming chair behind him. A screenshot spread on X within the hour, where one trader, KR, told 764,000 viewers he had exited.
The tokens that fell were launchpad and meme assets, not anything issued by Circle. No ARC token trades yet. GeckoTerminal data on Thursday showed TOLLY down roughly 68% and ARGUS down roughly 50%.

Speculators had spent weeks positioning for a meme coin rush on Arc. Launchpads generated 82% of the chain’s $410.8 million first-day DEX volume, and the first selling wave arrived over a face rather than a fundamental.
Does the Data Behind the Stereotype Exist?
Replies to the clip escalated from mockery to dehumanizing slurs aimed at Indians as a group. Crypto opinion leader, “Crypto with Khan” pushed back, listing Indian-born CEOs at Google, Microsoft, IBM, and Adobe. Alphractal founder Joao Wedson quoted him with a longer rebuttal.
“Bias and racism are still very visible on X, especially in the crypto market. When innovation comes from the U.S. or Europe, it is often treated with credibility by default. When it comes from Asia, the reaction is frequently much more skeptical,” Wedson posted on Thursday.
Khan followed on Thursday with a ranking of the ten largest crypto frauds by country of origin, which he said he produced by asking an AI chatbot. FTX, PlusToken, OneCoin, and Africrypt topped it.
Furthermore, Chainalysis’s 2026 Crypto Crime Report attributes more than $2 billion in 2025 theft to North Korean state hackers, including the $1.5 billion Bybit breach. It traces pig-butchering fraud to compounds in Cambodia and Myanmar.
Circle’s Arc team held up XyloNet as a model project in a June partner spotlight. On launch day, the chain’s traders held up its founder as a reason to sell. Both were the same company’s audience.
XyloNet went live on Arc mainnet this week regardless. The tokens that sold off in Pal’s name were never his to begin with.
The post Is Being Indian a Fraud Signal? Arc Traders Sold Like It Is appeared first on BeInCrypto.
The U.S. Commodity Futures Trading Commission (CFTC) has taken another step toward accommodating blockchain and crypto apps that simply provide technical access to regulated derivatives venues. In a no-action position issued Thursday, the agency said it would not recommend enforcement against qualifying “passive software” providers—or their personnel—for failing to register as introducing brokers or associated persons, so long as the software meets specific conditions.
The move matters for crypto builders because it creates a clearer path for non-custodial wallets and other software applications to connect users to CFTC-registered firms and exchanges offering products such as perpetual contracts and prediction markets, without automatically pulling the software provider into full broker registration.
Key takeaways
- The CFTC’s Thursday no-action position covers providers of “passive software” that connect users to CFTC-registered derivatives firms and exchanges.
- Qualifying providers would not face enforcement for not registering as introducing brokers or associated persons, if they stay within limits on how they handle user orders.
- The guidance builds on a March no-action letter granted to Phantom Technologies for self-custodial wallet software.
- The regulatory action arrives shortly after the CLARITY Act failed to advance in the Senate, signaling agencies intend to keep moving under existing authority.
A narrower role that reduces registration risk
At the core of the CFTC’s relief is a concept regulators often draw around broker-type activity: where the provider’s software and marketing functions do not cross into exercising discretion over trading decisions. According to the CFTC’s no-action position, the Market Participants Division will not recommend enforcement against providers that qualify under the “passive software” framework for facilitating trading with CFTC-registered entities and exchanges.
To qualify, providers must meet conditions designed to limit their involvement in transactions—especially restrictions related to discretion over users’ orders. The practical effect is to distinguish between software that merely routes users to regulated venues versus software that actively decides, manages, or steers trades on the user’s behalf.
This distinction is particularly relevant for crypto wallets and app-layer products that users interact with directly. If an app can demonstrate that it is not effectively operating like a registered intermediary, it may be able to integrate regulated derivatives access while reducing the compliance burden that typically comes with broker registration.
Extending a precedent set by Phantom
The CFTC’s new stance is not happening in a vacuum. Earlier, the agency granted a similar no-action position in March to Phantom Technologies for its self-custodial crypto wallet software. That letter allowed Phantom, subject to certain conditions, to provide and market software that connects users with registered futures brokers and exchanges without requiring Phantom to register as an introducing broker.
By expanding the relief beyond a single wallet vendor, the CFTC appears to be moving from case-by-case comfort toward a more repeatable standard that other developers can evaluate against. For investors and industry participants, this matters because regulatory certainty is often less about whether the rules can be interpreted, and more about whether firms can plan product roadmaps without waiting for the regulator to address each new integration individually.
The earlier Phantom-related effort also did not remain purely theoretical. The Phantom and Hyperliquid Policy Center later urged the CFTC to modernize how the rules apply to onchain infrastructure—arguing that non-custodial wallet providers should receive clearer protections from introducing broker requirements and that the agency should clarify how existing regulations operate when blockchain developers facilitate access to regulated derivatives venues.
While Tuesday’s details are limited to what the no-action position covers, the direction is clear: regulators are acknowledging that the technical layer of trading—software connectivity—can exist without necessarily replicating the role of a traditional broker.
After CLARITY Act setback, agencies continue
The CFTC’s relief comes two days after the CLARITY Act failed to advance in the U.S. Senate. As reported in earlier coverage of the legislative outcome, a cloture motion received 49 votes, falling short of the 60 needed to proceed to debate.
Following that setback, both CFTC Chair Michael Selig and Securities and Exchange Commission Chair Paul Atkins signaled that their agencies would continue regulatory work using existing authority. In posts on X referenced by the reporting, Selig said the CFTC is “ready to ship its rules,” while Atkins said the SEC would act “with or without legislation” to provide regulatory certainty for digital assets.
Thursday’s developments follow through on that posture. Alongside the CFTC no-action position, the SEC approved a temporary exemption allowing qualifying platforms to facilitate limited onchain trading of tokenized U.S. stocks through permissioned automated market makers and liquidity pools. The pairing of actions—CFTC on derivatives access software, SEC on a narrowly defined pathway for tokenized stock trading—suggests regulators are pursuing targeted certainty even as comprehensive legislation stalls.
Still, the scope of this new no-action relief is not blanket. The CFTC’s conditions and discretion limits are key: “passive” software is not a synonym for “anything goes.” Builders will need to ensure their product behavior aligns with the framework, particularly around what the software does (and does not do) with respect to order handling.
What to watch next for wallet and onchain derivatives access
For developers, the most immediate takeaway is to treat the no-action position as a blueprint for compliance planning. Since the CFTC’s relief hinges on meeting specific conditions—especially those related to discretion—teams integrating regulated derivatives access should document how their software operates, what actions are user-driven, and what guardrails prevent the app from effectively acting like a broker.
For users and market participants, the broader question is how quickly regulated-derivatives access becomes more “app-like.” The CFTC is signaling that non-custodial connectivity to CFTC-registered venues can fit within existing regulatory boundaries when structured appropriately. The open issue is how tightly the framework will be interpreted in edge cases, such as more interactive order workflows, automated strategies, or features that could be viewed as steering trades.
Readers should watch whether additional CFTC communications expand “passive software” guidance to more product categories, and how firms demonstrate compliance with the discretion and order-handling limits as onchain interfaces for regulated derivatives continue to evolve.
Arc is a purpose-built, EVM-compatible Layer 1 blockchain being built by Circle, the company that’s behind the second-largest stablecoin in the industry, USDC. It’s designed specifically for stablecoin finance.
The protocol was first announced in August 2025, and its public testnet went live in October of that year. Arc has received the backing of major Wall Street heavyweights like BlackRock, Visa, MasterCard, and more.
It was created to provide blockchain infrastructure that’s specifically tailored to payments, foreign exchange, tokenized assets, capital markets, and other forms of on-chain financial activity.
If you’re wondering what the difference is between an EVM-compatible Layer 1 blockchain and an Ethereum layer-two like Robinhood Chain, it’s that Arc is a dedicated, standalone blockchain that settles its own transactions and implements its own security protocols. Layer-two blockchains, by contrast, rely on Ethereum for settlement, finality, and security. That said, EVM compatibility also means that developers can use familiar tools and Solidity-based smart contracts. Its design tackles several friction points that Circle sees in existing blockchain infrastructure, including volatile gas costs, unpredictable settlement times, and the lack of privacy that’s actually required for many conventional financial transactions.
Arc, therefore, combines USDC-denominated gas, predictable transaction fees, deterministic sub-second finality, and a permissioned validator network.
For a complete technical overview, review the project’s whitepaper or litepaper.
Main Takeaways
- Arc is an independent Layer 1 blockchain built by Circle, first announced in August 2025.
- It is built specifically for stablecoin finance, with payments, FX, tokenized assets, and capital markets touted as main use cases.
- USDC is used to pay gas fees, giving users a dollar-denominated transaction cost rather than a volatile crypto asset.
- It offers deterministic sub-second finality, making settlement predictable and fast.
- Arc is EVM-compatible. This means that developers can use existing Ethereum-first tooling and Solidity-based smart contracts.
- Privacy is a core part of Arc’s architecture.
Arc’s Role in Circle’s Strategy
Arc represents a major expansion effort in Circle’s startegy when it comes to the stablecoin economy. The company is best known as the issuer of USDC – the second-largest stablecoin in circulation. However, it has also built infrastructure for moving and using stablecoins across blockchain networks, including products such as Circle Mint, CCTP, Gateway, and more. With Arc, the firm is moving further down this road by delivering the underlying blockchain and settlement infrastructure on which financial applications can properly operate.
The move also reflects the company’s position that stablecoins have outgrown some of the infrastructure that they used to rely on. According to Arc’s litepaper document, existing public blockchains can create problems when it comes to institutional financial activity through volatile costs of gas, uncertain settlement finality, limited transaction privacy, as well as fragmented liquidity across the various protocols. Arc, therefore, comes into the picture specifically to address those shortcomings rather than attempting to compete primarily for existing crypto activity.
This makes the blockchain complementary to Circle’s existing products as opposed to being a replacement for them. The network is designed specifically to connect with Circle’s wider platform, other blockchains, traditional fiat rails, as well as the broader ecosystem of tokenized assets and stablecoins.
How Arc is Built
The first and foremost concept that you need to understand about Arc is that it’s an independent Layer 1 blockchain. This means that it has its very own consensus system and validator network. It does not rely on settling transactions through Ethereum. At the same time, though, it is EVM-compatible. This means that developers are able to use existing and familiar Ethereum-oriented tooling and write smart contracts in Solidity without having to learn an entirely new programming environment.
At the core of the network is Malachite – this is a high-performance consensus engine that’s based on Tendermint. Arc uses a permissioned group of validators to agree on the order and validity of transactions. In simple terms, these validators are responsible for keeping the network synchronized and confirming which transactions become a valid part of the blockchain.
One of the main design goals behind the protocol is fast and predictable settlement. Its consensus system is designed to provide deterministic finality in under one second. What this means is that once a transaction is finalized, users won’t have to wait for several additional blocks to gain confidence that it will not be reversed.
Arc is also built around financial applications specifically. Its architecture supports stablecoins and tokenized assets. It also connects with different products already launched by Circle, as mentioned above, including Mint, CCTP, and Gateway.

The Stablecoin-Native Model: USDC Gas, Fees and Network Economics
One of the most distinctive features of Arc is that USDC is being used as the native asset for transaction fees. Now, as you may know, on many other blockchains, users have to hold a separate cryptocurrency (such as ETH or SOL) to pay for gas. This means that the dollar cost of a transaction can change not only because the network becomes busier, but also because the price of the gas token itself moves. Arc removes that second source of volatility by denominating its gas fees in USDC.
The goal is to make blockchain costs easier for businesses to understand and, by extension, to budget for. Because USDC is a stablecoin pegged 1:1 to the US dollar, Arc can manage its fee market directly in a stable unit of account. In simple and practical terms, the asset being transferred and the asset used to pay for the transaction itself can both be denominated in USD.
Arc’s fee system takes inspiration from a very popular Ethereum Improvement Proposal (EIP) number 1559, but it also adds a smoothing mechanism. Instead of charging the base fee sharply from one block to the next, Arc uses an exponentially weighted moving average of network utilization together with a bounded base fee. The goal here is to reduce short-term fee spikes and keep transaction costs a lot more predictable.
USDC, however, is not intended to be the only way users can cover fees forever. Arc’s design also supports other local stablecoins and tokenized fiat currencies through a paymaster infrastructure, which allows applications to abstract gas payments away from users. The fees that are collected by the network are being directed to an on-chain Arc Treasury. According to the litepaper, this will be used to support the long-term growth of the network.
Arc’s Core Product Stack: Payments, FX, Privacy and Interoperability
At this point, it should have become clear that Arc is designed to be more than just a blockchain to facilitate USDC transfers. Its broader aim is to provide the infrastructure that’s needed for programmable financial applications, with payments, FX, privacy, and connectivity to other financial systems forming some very important parts of its ecosystem.
Let’s break these down.
Payments
Arc is optimized for stablecoin-based payments. Fast finality and predictable fees can make settlement a lot easier to manage. Circle positions use cases such as global and cross-border payments as a core application of the network.
Foreign Exchange
The blockchain is also built to support programmable foreign exchange. This would allow stablecoins representing different currencies to be exchanged and settled on-chain. The Arc website specifically highlights. the potential for 24/7 on-chain forex markets.
Privacy
The team is building something called Arc Privacy Sector (APS). It’s designed to add confidential smart-contract execution alongside the blockchain’s public environment. This could allow certain sensitive information, including balances, transaction details, and contract state, to essentially remain private while applications continue to execute on-chain. The privacy whitepaper highlights potential applications such as payroll, lending, asset issuance, and repo markets.
Interoperability
Last but not least, Arc is not intended to operate as an isolated protocol. Its architecture connects the network with traditional fiat rails, other applications, blockchains, as well as existing protocols built by Circle as we explained above.
What Will Actually Be Built on Arc?
There isn’t a limit on the type of applications that can be built on top of Arc’s blockchain, but it has to have become obvious by now that it’s designed around financial applications, rather than a single flagship use case. Its architecture is specifically intended to support products that move, exchange, and program stablecoins and real-world asset tokenization. As you can see, these are all segments where predictable fees, privacy, quick finality and settlement matter.
Some of the main use cases that are highlighted across various materials that Arc’s team has published include:
- Global and cross-border payments
- Foreign exchange
- Tokenized assets
- Treasury and liquidity management
- Lending and credit
- Institutional markets
That isn’t to say that we won’t see meme coins running on Arc. In fact, since its public launch on September 16th, the network has already seen its fair share of meme coins being built through various launchpads. But as you can see, all the above applications are very closely related. A business, for example, that receives a stablecoin payment, might immediately exchange it into another currency, use it as collateral, or move it to another blockchain – all through programmable infrastructure.
That interconnected model is very central to the protocol’s value proposition. Rather than functioning simply as a faster network for USDC transfers, Arc is intended to become a financial settlement environment where various applications can operate on the same underlying infrastructure stack.
The Arc Ecosystem at Launch
With all of the above in mind, Arc launched with an ecosystem that spans financial institutions, payment companies, stablecoin issuers, DeFi protocols, custody providers, infrastructure firms, and developer tools. That depth is important to Circle’s strategy – rather than launching the network first and trying to attract liquidity and applications later, Arc is intended to kick it off with many of the building blocks already connected.
At the network level, Arc’s founding validators include institutions such as BlackRock, DTCC, Galaxy, ICE, Mastercard, MoneyGram, SBI Group, Sumitomo Corporation, Visa, Standard Chartered, and more. These organizations don’t just participate as application partners but also operate and secure the network itself.
Beyond that, the official release also listed multiple custody providers, including Anchorage, BitGo, Copper, Fireblocks, and Zodia Custody. The release also mentioned compliance-oriented and security providers such as TRM Labs, Elliptic, and Chainalysis, as well as cross-chain protocols such as LayerZero, Stargate, and more.
The result is a developed ecosystem that’s designed for immediate utility.
Arc vs. the Competition
Arc is entering a crowded market – there’s no denying that. Countless Layer 1 and Layer 2 blockchains exist, but Circle’s initiative is deliberately different. Rather than competing for general-purpose crypto activity alone, Arc is designed around stablecoin payments and institutional settlement. In fact, even the litepaper says that the goal is not just to capture transactions from existing networks, but to bring more financial activity on-chain.
That said, the main differences really come down to a handful of design and approach choices.
- Stablecoin-native gas payments: As we outlined above, many blockchains require users to pay fees in a volatile native token. Arc, instead, uses USDC for gas. This means that transaction costs are denominated in a relatively stable unit of account. Arc also uses a fee-smoothing mechanism that’s intended to reduce short-term fluctuations in network fees.
- Deterministic finality: Arc uses Malachite, which is a Tendermint-based BFT consensus engine. Once more than two-thirds of validators commit a block, transactions become final rather than passing through a longer period of probabilistic or economic finality. Arc contrasts this with the finality models that are used by networks such as Ethereum and various Ethereum L2s.
- Finance-specific infrastructure: Arc combines its base layer with existing Circle infrastructure and is designed around payments, FX, tokenized assets, and opt-in privacy (eventually).
- A permissioned validator model: Unlike permissionless networks where anyone who meets the protocol’s set of requirements can potentially become a validator, Arc relies on a limited set of known institutions.
Ultimately, Arc makes different trade-offs than many general-purpose chains: it emphasizes stable costs, settlement certainty, and infrastructure tailored to regulated financial activity over permissionless validation.
Frequently Asked Questions
When was Arc mainnet launched?
Arc’s public mainnet was launched on September 16. It is an independent Layer 1 blockchain with its own validator network and consensus system. It is EVM-compatible, which means developers can still use Solidity and familiar Ethereum tools.
Does Arc have a native token?
Yes. The protocol has minted the entire supply of ARC, but it is not in circulation at the time of this writing in September 2026. However, the fees are denominated in USDC.
Why does Arc use USDC for gas?
Using USDC allows transaction fees to be denominated in a stable dollar-based asset rather than a cryptocurrency whose market price can fluctuate significantly.
How fast is Arc?
Arc is designed to provide what is known as “deterministic finality” in under one second. Once the transaction is finalized by the network, users don’t need to wait for multiple additional blocks for settlement certainty.
Is Arc permissionless?
No. Applications and smart contracts can be built on Arc, but its validator network uses a permissioned model. Validators are selected institutions rather than an unrestricted group that anyone can join.
Does Arc support meme coins?
Yes, meme coins exist on the Arc blockchain. They have become a landmark for the entire cryptocurrency industry, and the fact that Arc is EVM-compatible means that developers can build launchpads and meme coins using existing and familiar tooling.
Does Arc support private transactions?
Arc’s Privacy Sector is designed to support confidential smart-contract execution alongside the public blockchain. This can allow sensitive transaction data and contract state to remain private, while still benefiting from blockchain-based settlement.
What can be built on Arc?
While Arc is designed primarily for financial applications, there isn’t a limit on what developers can build on the network. It can be used as a general-purpose L1.
How is Arc different from Ethereum?
Arc’s main differentiation is that it’s permissioned, fees are paid in USDC, its finality is a lot quicker, and more.
The post Arc Blockchain Explained: Everything You Need to Know About Circle’s Layer 1 appeared first on CryptoPotato.
Crypto World
Trump-Backed Republican Congresswoman Says the President’s Immigration Crackdown Has Gone ‘Too Far’
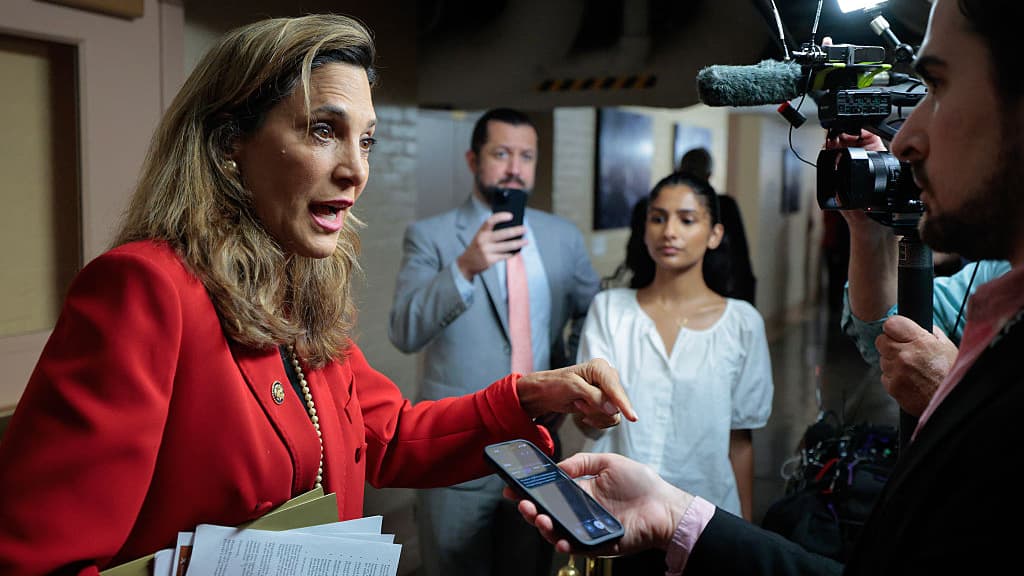
Salazar’s campaign said that the video released on Thursday is the first of multiple ads that it plans to run before the upcoming midterm elections, in which Salazar is facing off against Democratic nominee Eliott Rodríguez. Both Salazar and Rodríguez are Cuban American, and previously worked as journalists.
The Cook Political Report indicates that Salazar, a three-term Congresswoman, is expected to hold on to her seat come November, rating it as “Likely Republican.”
In the district Salazar represents, the foreign-born population makes up more than 54% of the total population—one of the largest proportions of all the districts in the lower chamber.
Thursday’s ad isn’t the first time that Salazar has expressed concerns about the Trump Administration’s immigration enforcement efforts. Earlier this week, she responded to reports that Luis Galeano, an exiled Nicaraguan journalist whose U.S. asylum application has been pending for years, had been detained by federal immigration agents.
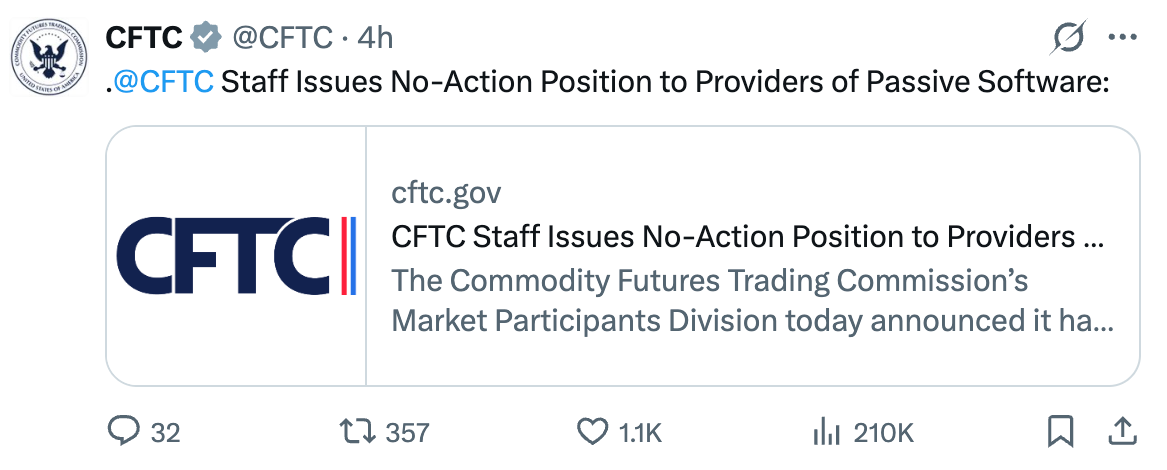
The Commodity Futures Trading Commission (CFTC) has expanded regulatory relief for “passive software” providers that connect users to regulated derivatives firms and exchanges.
In a no-action position issued Thursday, the agency’s Market Participants Division said it would not recommend enforcement against qualifying providers or their personnel for failing to register as introducing brokers or associated persons when facilitating trading with CFTC-registered firms and exchanges.
The position could make it easier for crypto wallets and other apps to offer access to regulated derivatives, including perpetual contracts and prediction markets, without becoming CFTC-regulated introducing brokers themselves.
Source: CFTC
To qualify, providers must meet conditions limiting their role in transactions, including restrictions on exercising discretion over users’ orders.
The action extends a similar position granted to Phantom Technologies in March for its self-custodial crypto wallet software. The earlier letter allowed Phantom, subject to certain conditions, to provide and market software connecting users with registered futures brokers and exchanges without registering as an introducing broker.
Phantom and the Hyperliquid Policy Center also pushed for broader protections in July, asking the CFTC to shield non-custodial wallet providers from introducing broker requirements and clarify how existing rules apply to blockchain developers and regulated derivatives firms using onchain infrastructure.
Related: Bernstein expects ‘aggressive’ rulemaking from SEC, CFTC, following CLARITY Act failure
Regulators move quickly after CLARITY Act setback
The move from the US regulator comes two days after the CLARITY Act failed to advance in the Senate, with a cloture motion receiving 49 votes, short of the 60 needed to proceed to debate.
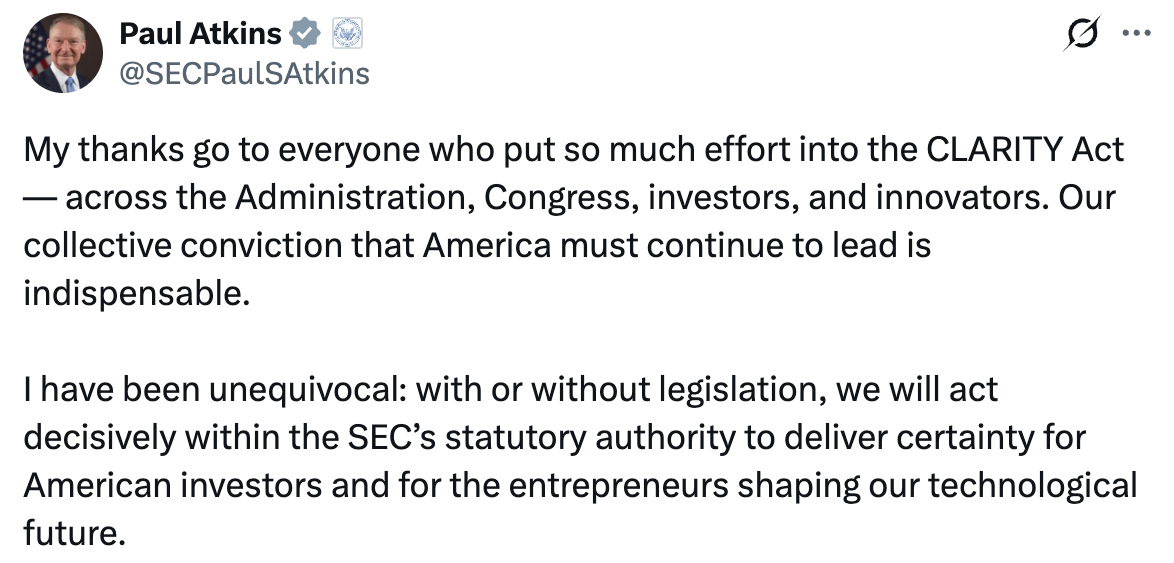
Following the vote, CFTC Chair Michael Selig and Securities and Exchange Commission Chair Paul Atkins signaled Wednesday that their agencies would continue moving forward on crypto regulation under their existing authority.
“The CFTC is locked in and ready to ship its rules for the new frontier of finance,” Selig said in a post on X, while Atkins said the SEC would act “with or without legislation” to provide regulatory certainty for digital assets.
Source: Paul Atkins
On Thursday, the agencies began following through. Alongside the CFTC’s no-action position, the SEC approved a temporary exemption allowing qualifying platforms to facilitate limited onchain trading of tokenized US stocks through permissioned automated market makers and liquidity pools.
A few months later, his daughter, who is now 33, was diagnosed with melanoma in her ear and was asked about her family history of cancer. She joined a study and provided samples to look for markers of cancer, and while she did not carry many common cancer mutations, she did carry T790M. But for now, there are no evidence-based recommendations to follow when it comes to how she should be monitoring her lungs for signs of cancer. “That’s why I’m pushing for how we can screen younger people, knowing that she has a genetic risk, and what low-dose screening she should get,” says McKenna. “If something were to appear, she can catch it at an early stage, perhaps Stage I, and not go through Stage IV, because there are not as many options, and the outlook is not as positive.”
LoPiccolo is conducting a study, called INHERIT, which includes people from across the country with any inherited genetic risk for lung cancer, including the EGFR T790M mutation. Doctors will work with each participant to understand their family history of lung cancer, smoking history, genetic profile, and any environmental exposures that might contribute to lung cancer before coming up with a personalized plan for how often they should be screened with low-dose CT scans to look for cancer. “The goal is to use CT screening to detect lung cancer at the earliest, most curable stage when it can be removed or cured,” says LoPiccolo.
XRP has fallen below the key $1.30 level after losing 7.3% on Tuesday, while Dubai-based crypto investor Royal Kane has ruled out buying the token because of its $81 billion market value.
Summary
- XRP has dropped 23% from its recent high near $1.68.
- Royal Kane cited XRP’s large market capitalization in rejecting an investment.
- The Federal Reserve raised interest rates by 25 basis points on Sep. 16.
- The CLARITY Act failed to advance after a 50-49 Senate vote.
Royal Kane, a Dubai-based crypto investor, wrote on X that he would not invest in XRP at its present valuation, pointing to the token’s market capitalization as the main reason for his position.
“I would never invest in Ripple at this stage because its market cap is already too large,” Kane said.
Market data included in the source report placed XRP near $1.30, with a market capitalization of about $81.68 billion and 24-hour trading volume of $4.12 billion. The token was also down 29.18% since the start of 2026.
Kane argued that assets with lower valuations may offer more room to benefit from a strong investment story. He cited Solana’s earlier “Ethereum killer” label, the community growth surrounding Pepe, and Zcash’s adoption case as examples of narratives that attracted traders.
Rather than presenting a price target for XRP, he told investors to “find a coin with a compelling narrative for the coming years.”
XRP price has dropped 23% from its recent peak
Selling pressure has erased much of XRP’s latest rebound, pulling its price from a recent high near $1.68 to approximately $1.30. A move between the two levels amounts to a decline of about 23%.
The retreat followed a stronger period for XRP in August, when the token climbed from around $1 to a monthly high near $1.70. According to September escrow data, XRP gained 28.5% in August even after Ripple released 1 billion tokens from escrow on Sep. 1.
Ripple’s scheduled release was valued at about $1.38 billion at the time. The company historically returns much of each monthly allocation to escrow, limiting the amount that can enter circulation.
Institutional demand also supported the August rally. The report found that U.S. spot XRP exchange-traded funds attracted $153.55 million during the month, including $150.28 million over its final two weeks. XRP Ledger payment volume rose 521% in one week, driven by larger transfers rather than an increase in transaction count.
Price action has since reversed as traders have reacted to tighter U.S. monetary policy and another delay in federal crypto legislation. XRP fell 7.3% on Tuesday and traded around $1.31 after the Senate vote, according to figures cited in the source report.
Kane’s criticism focuses on XRP’s $81B valuation
At an estimated $81.68 billion, XRP’s market capitalization remains one of the largest in the digital asset market. Kane views that size as a limit on potential returns because the token would require substantial new capital to produce the percentage gains available to smaller assets.
His comments also included a claim that Ripple has “no products or revenue whatsoever.” Ripple is privately held and does not publish the same quarterly financial statements required from a U.S.-listed public company, leaving investors with less information about its revenue than they would receive from an exchange-listed business.
However, the company publicly operates several products and services. Its businesses include Ripple Payments, the RLUSD stablecoin, and Ripple Prime, the institutional brokerage formed after its acquisition of Hidden Road. Ripple has also announced custody and treasury services for corporate clients.
Kane’s investment thesis therefore separates XRP’s market value from his assessment of Ripple’s commercial operations. XRP is the native asset of the XRP Ledger, while Ripple is a private technology company that holds a substantial quantity of the token and develops services that can use the network.
The distinction matters because buying XRP does not provide equity ownership in Ripple, a claim on the company’s revenue or voting rights over its business. XRP holders instead gain exposure to the market price of the token, which can respond to network activity, liquidity, speculation, regulations, and Ripple-related developments.
Fed rate increase has raised pressure on risk assets
Macroeconomic conditions have added another source of uncertainty for XRP and other cryptocurrencies. On Sep. 16, the Federal Reserve raised its benchmark interest rate by 25 basis points, taking the target range to 3.75% to 4%.
The unanimous decision delivered the first U.S. rate increase since 2023. Projections released by the central bank showed that 12 of 18 officials expected additional increases during the year, according to the source report.
Higher interest rates can increase returns on U.S. government debt and money-market products, giving American investors more yield-bearing alternatives to cryptocurrencies. Digital assets do not provide a fixed return, and tighter financial conditions can reduce demand for speculative investments.
Before the decision, U.S. inflation data had strengthened expectations for a rate increase. As crypto.news previously reported, annual inflation reached 3.4% in August, while consumer prices rose 0.4% from the previous month.
Energy costs rose 2.1% during August, with gasoline prices climbing 3.9%. Core consumer prices, which exclude food and energy, increased 0.3% on the month, exceeding the 0.2% estimate cited in the report.
Prediction-market traders raised the probability of a quarter-point increase to 81% after the inflation release. Although such contracts represent wagers rather than official Fed guidance, their pricing showed that traders had largely prepared for higher borrowing costs before the meeting.
CLARITY Act defeat has left XRP policy questions open
Regulatory pressure increased on Sep. 15 when the U.S. Senate rejected cloture on the Digital Asset Market CLARITY Act. The motion received 49 votes in favor and 50 against, falling 11 votes short of the 60 needed to open formal debate.
The vote carried particular importance for XRP because the legislation would divide oversight responsibilities between the Securities and Exchange Commission and the Commodity Futures Trading Commission. Its treatment of network tokens could affect how XRP and other crypto assets are classified in U.S. markets.
Hours before the vote, Senate Republicans circulated a revised 635-page draft that added language covering ancillary assets. The proposal described an ancillary asset as a network token whose value depends on the managerial or entrepreneurial work of an originator or a related party.
Under the draft’s wording, XRP could have been treated as a digital commodity in secondary-market transactions regardless of the quantity controlled by Ripple. The proposal did not receive enough support to move into debate, leaving the existing legal and regulatory framework in place.
XRP still benefits from the 2023 ruling by U.S. District Judge Analisa Torres, who found that Ripple’s programmatic XRP sales on public exchanges did not constitute securities transactions. The same ruling found that the company’s direct institutional sales violated securities law, creating different treatment based on how the tokens were offered.
Negotiations have not ended despite the failed vote. Seven Senate Democrats have since reopened CLARITY Act talks and said the rejected cloture motion was “not the end” of the legislative effort.
The Senate’s official roll call shows that 49 lawmakers supported advancing the measure while 50 opposed it, meaning any renewed attempt would require at least 11 additional votes to reach the cloture threshold.
Woman died in horror wall collapse at home eight years after alarm first raised

Higher jet fuel prices prompt airlines to adjust flight schedules

WisdomTree and MoonPay Collaborate to Broaden US Tokenized MMF Access



-

 Fashion6 days ago
Weekend Open Thread – Corporette.com
-

 Tech4 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Business7 days ago
10 Most-Streamed Songs On Spotify In 2026 So Far, Led By Ella Langley’s Dominant Run On The Charts This Year
-

 Crypto World6 days ago
XAG/USD: Silver’s Short-Term Rally Meets Its Moment of Truth
-

 Crypto World7 days ago
OKX launches 10x OpenAI, Anthropic X-Perps in Europe
-

 Crypto World6 days ago
Diesel Tops $6 a Gallon for the First Time as 28 States Set Records
-

 Crypto World3 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-

 Crypto World3 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-

 News Videos6 days ago
Facing Financial Fears
-

 Crypto World21 hours ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-
Crypto World7 days ago
Ethereum Price Analysis: Consolidation at $2.5K Tests Momentum as On-Chain Activity Surges
-

 Business5 days ago
Rivals Sam Altman and Elon Musk Rally Behind Dario Amodei’s Call for a Slowdown in AI Development
-

 Crypto World5 days ago
Can AI Build a Startup in 72 Hours? Elon Musk's Team Will Livestream the Test
-
 Entertainment6 days ago
News Specials, Movies, Shows, More
-
 NewsBeat3 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World7 days ago
Bitcoin ETFs Pull $167M as 2026’s Best Inflow Run Slows
-

 Crypto World6 days ago
Robinhood Chain Never Stopped But its Blobs Did Stop Reaching Ethereum For 14 Minutes
-
 Crypto World7 days ago
US CPI forecast at 3.4% as tariff risks build
-

 Crypto World4 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-
 Entertainment6 days ago
New Horror Movie Officially Earns a Rare Stephen King Recommendation
You must be logged in to post a comment Login