
Crypto World
Arch Lending Targets Tokenized Stocks as Next Collateral Market

Arch Lending is preparing to move deeper into credit markets for tokenized equities, with plans to offer loans backed by onchain representations of stocks and exchange-traded funds (ETFs). Speaking on Cointelegraph’s Chain Reaction podcast, Arch co-founder and chief revenue officer Himanshu Sahay said the lender wants to enter “pretty soon,” citing a growing need for borrowing against tokenized stock assets.
Sahay pointed to rapid expansion in tokenized equities over the past year, while also arguing that lending against those assets remains limited today. He predicted that more lenders will follow, especially as tokenized stocks issued by platforms such as Superstate, Robinhood, and Securitize become more widely used in collateral frameworks.
Key takeaways
- Arch Lending plans to launch loans backed by tokenized equities “pretty soon,” aiming to address limited credit availability for onchain stock assets.
- Sahay said tokenized equities have expanded quickly over the past year, but lending usage still lags the pace of issuance and experimentation.
- Arch’s current loan book is still dominated by crypto collateral: Sahay said Bitcoin makes up more than 80% of exposure.
- Interest in using XRP as collateral is reportedly growing among US borrowers.
- Tokenized equities lending is already emerging via platforms like Ondo Finance and infrastructure providers tied to Ethereum-based lending protocols.
Arch’s shift from crypto-only lending to onchain stocks
While Arch’s core business is rooted in crypto-backed lending, Sahay emphasized that the lender is actively looking for additional collateral categories as the tokenized equities ecosystem matures. The company has already expanded beyond cryptocurrencies into real-world assets (RWAs), offering loans backed by tokenized gold and stablecoin-linked gold products issued by Paxos and Tether, according to Sahay.
Even with that progress, Sahay described Bitcoin as the dominant collateral in Arch’s current lending operations, accounting for more than 80% of the lender’s existing loan book. That detail underscores a transition phase: Arch is expanding its collateral menu, but crypto remains the base business while the market for tokenized equities develops deeper liquidity and clearer credit pathways.
Sahay also noted an uptick in demand for XRP collateral, particularly from borrowers in the United States. For lenders, the relevance of a collateral asset hinges on custody, valuation reliability, liquidation mechanics, and borrower appetite—so increases in specific collateral usage often signal that risk models and market plumbing are becoming more robust.
Tokenized equity credit is already taking shape
Arch would not be the first lender to attempt credit exposure to tokenized equities. Over the past year, tokenized stocks and ETFs have begun appearing across lending and collateral products, suggesting the industry is converging on Ethereum-based rails and DeFi-compatible collateral workflows.
In February, Ondo Finance launched DeFi lending markets for two of its tokenized ETFs through an integration with lending protocol Morpho. Ondo’s tokenized versions of the SPDR S&P 500 ETF and Invesco QQQ can be used as collateral for borrowing on Ethereum.
Beyond dedicated lending venues, other firms have also moved toward broader composability of tokenized equities. Kraken made its 10 xStocks eligible to support futures and margin positions in July. Meanwhile, Coinbase’s B20 stocks launched on Base in August, using price-feed infrastructure designed to support use cases that include DeFi borrowing and lending.
For investors and borrowers, these steps matter because they reduce friction: if tokenized equities can be used across multiple systems—rather than being confined to a single application—then lenders get more reliable access to collateral and liquidation workflows, while borrowers can more easily integrate the assets into existing strategies.
What’s driving demand: the onchain stocks market is growing
The push toward equity-backed lending aligns with expansion in the underlying tokenized equities market. According to RWA.xyz data cited in Cointelegraph’s coverage, distributed tokenized stock value has risen to about $3.15 billion, up from roughly $630 million a year earlier.
That magnitude of growth helps explain why lenders are considering tokenized equities more seriously. However, growth in issued or distributed token value does not automatically translate into deep lending markets. Lenders still need mechanisms to price the collateral, manage volatility, and execute liquidations efficiently—especially if the tokenized asset references traditional equities with their own settlement and liquidity characteristics.
Arch’s stated intent to add equity-collateral loans fits this broader pattern: as tokenized equities scale, the next layer of adoption is typically finance infrastructure—credit, margin, and yield—provided risk teams can support it. The “limited” lending described by Sahay suggests that, despite issuance momentum, the market still has room for additional lenders to compete on terms, collateral support, and risk management.
Why Arch’s timing could matter
Arch’s move comes at a moment when tokenized stocks and ETFs are increasingly being treated as collateral across multiple platforms and use cases. If tokenized equities continue to attract liquidity, lenders that expand collateral coverage earlier may capture relationships with borrowers seeking diversified collateral strategies—particularly when crypto-only borrowing is constrained by liquidity or collateral concentration concerns.
At the same time, the transition is not instantaneous. Sahay’s comments indicate that Arch’s current exposure remains largely tied to crypto, with Bitcoin still representing the vast majority of the existing loan book. That suggests Arch will likely approach tokenized equity lending with caution—building the operational and risk infrastructure needed to support assets with distinct market behavior compared with traditional crypto benchmarks.
For now, readers should watch whether Arch’s tokenized equity lending plans translate into actual launch details—such as which tokenized equities will be supported first, how collateral valuation and liquidation are handled, and whether demand from borrowers grows alongside the broader tokenized equities market. The combination of issuance expansion and the still-limited state of lending could determine how quickly this segment becomes a standard offering for credit providers.

The U.S. Commodity Futures Trading Commission (CFTC) has issued fresh guidance warning that “mention markets” in prediction trading—contracts that settle based on whether a specific person says certain words, attends an event, appears publicly, or interacts with someone—face a heightened risk of manipulation. The regulator’s advisory signals that exchanges seeking to list these products may need to clear a higher bar on oversight, verifiability, and susceptibility to external influence.
In a statement released Tuesday, the CFTC’s Division of Market Oversight said that listing these contract types is generally limited to “limited circumstances” consistent with the Commodity Exchange Act. The agency’s remarks come amid broader scrutiny of how prediction markets are structured and policed, including enforcement actions tied to alleged trading around privileged information.
Key takeaways
- The CFTC warns that mention markets settle on discrete personal conduct that may be neither independently generated nor externally verifiable, increasing manipulation risk.
- Exchanges are encouraged to apply a stricter checklist, including oversight capability and whether settlement triggers are verifiable.
- Recent enforcement in the prediction market space underscores the agency’s focus on information asymmetry and conduct-based settlement mechanics.
- Separate reporting highlights unusual Kalshi trading in an Ether-related market, adding to questions about integrity monitoring even as the platform rejects manipulation claims.
Why the CFTC singled out “mention markets”
The advisory, issued by the CFTC’s Division of Market Oversight, is aimed at regulated entities responsible for bringing contracts to market. The CFTC described mention markets as event-driven derivatives where the settlement depends on what an individual does—such as saying specific words or showing up—rather than on market-wide outcomes or easily measurable external data.
According to the regulator, this structure can create a “heightened risk of manipulation” because the settlement outcome hinges on a person’s conduct, which may not be independently produced and may be hard for outsiders to verify reliably.
The CFTC’s position effectively reframes the issue: it is not merely the fact that a contract references an event, but how the contract defines what counts as an outcome and whether that outcome can be checked without ambiguity.
The agency’s checklist for exchanges
Reporting from CNBC indicates the CFTC letter highlights four considerations that exchanges should evaluate before listing mention-market contracts. Those factors include whether the exchange has adequate oversight measures to detect manipulation, whether the words or actions used for settlement are independently verifiable, whether outside pressure could influence the subject’s conduct, and what obligations the subject of the contract may have.
The regulatory guidance also reinforces that exchanges and contract-issuing parties are expected to think beyond the initial listing proposal. In the CFTC’s framing, the exchange’s role in monitoring market behavior and safeguarding contract integrity becomes central—particularly where the settlement trigger could be influenced by the very person referenced in the contract.
CFTC Chair Mike Selig publicly welcomed the staff guidance on Tuesday, posting that “regulatory clarity drives sound markets,” and stating that the advisory reminds designated contract markets (DCMs) of their obligations to list contracts that are not readily susceptible to manipulation.
The CFTC’s guidance, published as an official advisory, can be found via the regulator’s press materials: CFTC.
Enforcement momentum in conduct-based prediction contracts
The warning is arriving against a backdrop of legal action focused on manipulation risks in prediction markets. Earlier coverage highlighted a case involving a former White House teleprompter operator whose trading was tied to U.S. President Donald Trump’s speeches. That matter reportedly resulted in an order requiring the individual to return $107,539 in profits and pay a $65,000 civil penalty.
Earlier reporting on the enforcement details came from Cointelegraph, including coverage of how the matter related to “Kalshi” contracts tied to what the president would say. The recurrence of scrutiny around speech- and conduct-based settlement mechanisms helps explain why the CFTC is emphasizing the “discrete conduct” problem: when a contract’s payoff is linked to an individual’s behavior, regulators are more likely to see opportunities for information advantages and influence.
Notably, the CFTC’s advisory wording points to a core compliance dilemma for prediction markets: the more directly a contract settles on a person’s specific actions, the more difficult it can be to demonstrate that the settlement will be independently generated and verifiably fair.
Broader scrutiny extends beyond “mention” products
Separate from Tuesday’s mention-market warning, new reporting has drawn attention to unusual trading behavior on Kalshi, a platform that offers event-based contracts. According to a Wall Street Journal report, nearly one million trades worth more than $5 billion occurred in a single market tied to the price of Ether. The Journal said that more than a third of those trades took place in nearly identical amounts around $5,500.
The Wall Street Journal also reported that federal regulators and traders have taken notice of the activity. Kalshi, however, rejected suggestions that the transactions amounted to wash trading, according to the same coverage.
While this Ether-related episode does not necessarily involve the same “mention” contract mechanics, it fits into a larger pattern: regulators and market participants are increasingly focused on whether trading activity and settlement designs can be squared with market integrity expectations. For investors and traders, this means due diligence is likely to extend beyond whether a product is popular or liquid, and toward how an exchange identifies unusual activity and enforces its rules.
Earlier, CNBC and NPR reported in August that the CFTC had begun examining mention markets over manipulation concerns. The reporting also said that Kalshi removed mention markets tied to sporting events “until further notice” while the review proceeded, reflecting the practical impact guidance and enforcement can have on what exchanges list and how quickly they respond to regulatory pressure.
What to watch next
For exchanges and market makers, the immediate question is how strictly they will apply the CFTC’s “limited circumstances” framing when assessing new mention-market proposals, and whether they will tighten verification and monitoring procedures. For traders, the larger takeaway is that conduct-based settlement mechanics—especially where external influence or verifiability issues exist—will likely remain under the microscope, even as platforms continue expanding prediction product lineups.
Crypto World
Did Jim Cramer Just Give GameStop Stock the Kiss of Death When He Said the Turnaround Is Working?

Markets can forgive a company a lot when investors can see a path to growth. GameStop (GME) has spent years searching for that path, moving from video-game retailer to meme-stock phenomenon and now to a company increasingly built around collectibles. The latest numbers suggest the strategy may be working operationally. But a better business does not automatically make a better stock.
GameStop touched a two-year intraday low of $17.79 on Aug. 20. By Sept. 17, it had closed at $22.77, a 28% gain from that low. The rally comes as Jim Cramer says the turnaround is finally taking hold.
More News from Barchart
That may be true. The bigger question for investors is what they are actually buying.

GameStop Is Becoming a Collectibles Company
Let’s start with the good news. GameStop’s latest transformation is showing up in the income statement.
In its fiscal second quarter ended Aug. 1, collectibles revenue jumped 57% year-over-year (YoY) to $356.3 million, representing 45.1% of total sales. Video-game revenue, meanwhile, fell 47% to $263.2 million.
The shift is unmistakable. GameStop still sells video games and pre-owned products while maintaining a small Bitcoin (BTCUSD) position, but collectibles are increasingly the centerpiece. The company generated $160.2 million of operating income in the quarter, up from $66.4 million a year earlier, and raised its fiscal 2026 adjusted EBITDA forecast to more than $650 million.
The collectibles market is large—Grand View Research estimates it will reach $335.7 billion globally in 2026 and $535.5 billion by 2033—but GameStop is hardly alone.
eBay (EBAY) operates a massive secondary marketplace, while Target (TGT) says its trading-card business was on track to exceed $1 billion in 2025. The Pokémon Company sells collectibles and trading cards directly through Pokémon Center, while Hasbro (HAS) uses its Wizards of the Coast business and its Secret Lair store to sell premium Magic: The Gathering products directly to fans. That’s a pretty crowded field, one populated with bigger, healthier, and better-financed businesses.
Cramer Says Buy. Inverse Cramer Says What?
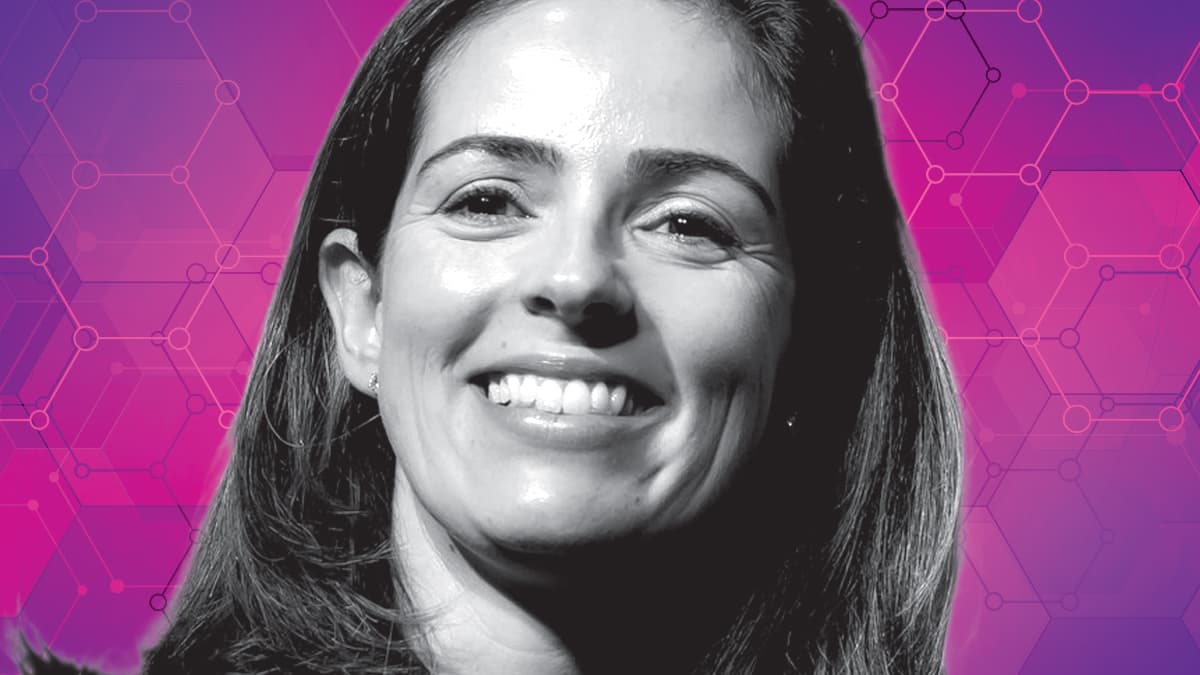
Monica Caldas says she likes “living on the edge.” She’s tasked with rewiring a century-old company for what she calls “the intelligence era.” As EVP and global CIO at Liberty Mutual, her core idea is doing two hard things at once, modernizing old systems while rebuilding around AI. That means embedding AI across core work like underwriting and claims, with more than 100 capabilities already in production.
In May, Liberty became the first insurer to launch a ChatGPT auto-quoting app, part of a bigger bet on “agentic commerce,” where buying insurance shifts from filling out forms to simply having a conversation. “I love to solve big, hairy things with tech,” Caldas says. Her drive started early. She arrived in the U.S. from Portugal in third grade without knowing a word of English and became the first in her family to go to college.
Join Our Telegram channel to stay up to date on breaking news coverage
Strategy bought 950 bitcoin for roughly $75.7 million last week and paid for it from cash on hand rather than new stock sales, according to an 8-K filing dated Sept. 21. The company, formerly known as MicroStrategy, now holds 846,000 BTC, its highest reported total since June.
The filing covers purchases made between Sept. 14 and 20 at an average price of $79,670 per coin. Across all holdings, Strategy has spent about $63.8 billion, an average of $75,416 per bitcoin.
A change in how the buying is funded
What marks this filing out is the funding. Strategy’s recent accumulation runs have typically been financed through at-the-market equity offerings, selling new shares to raise cash. This time the company said the purchases came from its USD Cash reserve, which stood at $1.05 billion as of Sept. 20. A second bucket, the USD Reserve, held $5.04 billion on the same date.
The same filing shows Strategy repurchased 1,771,238 shares of its STRC preferred stock for $174 million, and used $57.4 million of the USD Reserve to pay preferred dividends and interest on outstanding debt. It reported no bitcoin sales under its at-the-market offering during the week.
The shift matters because it suggests the company is no longer leaning on new share issuance to fund the treasury, after a stretch in which its preferred stock traded below par and reserve money went to servicing it. The filing discloses the buyback but not its rationale.
Mark-to-market figures from the week put the holdings at around $71.9 billion, implying roughly $8.1 billion in paper gains. Those numbers move with bitcoin’s price and should be read as a snapshot, not a balance.
846,000 BTC is more than 4% of bitcoin’s 21 million supply cap. The company’s reported peak was 847,363 BTC in June, before it sold 1,363 coins.
Join Our Telegram channel to stay up to date on breaking news coverage
Accenture works with many Fortune 500 companies, helping them deploy AI without becoming locked into a single model or platform. The company has already generated billions of dollars in generative AI bookings, while Guan says deployments for clients like the Australian bank Westpac have cut some workflows from months to days.
Now she’s tackling the cost of scaling those systems. Accenture has recently focused on tokenomics, arguing that firms incorrectly default to the most powerful—and expensive—models even when the work doesn’t require such heft. “Only about 20% of enterprise workflows actually deserve frontier models,” she says.
The U.S. Commodity Futures Trading Commission (CFTC) has issued a warning to regulated exchanges about “mention markets,” a type of prediction contract that settles based on whether a person says or does something. In a Tuesday advisory, the regulator said these contracts carry a heightened risk of manipulation and should only be listed in limited circumstances under the Commodity Exchange Act.
The guidance comes as prediction market activity draws growing regulatory scrutiny, particularly after enforcement actions tied to allegations that traders benefited from non-public information. For exchanges weighing whether to list event contracts tied to an individual’s specific words or conduct, the CFTC’s letter lays out a framework for assessing settlement verifiability and oversight readiness.
Key takeaways
- The CFTC says “mention markets” present a heightened manipulation risk because settlement depends on a person’s discrete conduct, which may not be verifiable or independently generated.
- The commission advised that there are only “limited circumstances” where mention markets can be listed consistently with the Commodity Exchange Act.
- Exchanges should evaluate oversight capabilities to detect manipulation and whether settlement criteria are independently verifiable.
- External pressure that could influence the subject’s conduct—and any related obligations the subject may have—are part of the CFTC’s review.
- The warning follows enforcement involving prediction contracts tied to political speeches, underscoring the regulator’s focus on information advantage and settlement conduct.
Why “mention markets” drew a regulator warning
In its advisory, the CFTC’s Division of Market Oversight said mention markets—contracts based on whether an individual will say certain words, attend or appear at an event, or interact with another person—may be inconsistent with the Commodity Exchange Act except in narrow cases.
The regulator’s central concern is that the settlement mechanism relies on conduct that can be neither independently generated nor externally verifiable. According to the CFTC, that structure “presents a heightened risk of manipulation” because it can make it easier for market participants to affect outcomes or profit from information advantages related to someone’s future actions.
The CFTC press release about the advisory is available via the regulator’s website: https://www.cftc.gov/PressRoom/PressReleases/9302-26.
Enforcement history is shaping the regulator’s approach
The CFTC’s warning arrives amid a string of allegations and cases where traders were accused of using privileged information to profit in prediction markets. One prominent example cited in the report involves a former White House teleprompter operator who was ordered last month to return $107,539 in profits and pay a $65,000 civil penalty related to contracts tied to then-President Donald Trump’s speeches.
Earlier coverage from Cointelegraph discussed that case in the context of how politically tied prediction contracts can intersect with information access. See: https://cointelegraph.com/news/trump-teleprompter-operator-made-100k-betting-kalshi-markets-tied-to-speeches-abc.
By emphasizing the risks tied to “discrete conduct” and limited verifiability, the CFTC’s guidance signals that settlement design matters as much as trading behavior. Even if a contract’s price action reflects legitimate market views, the regulator appears concerned when the contract outcome can be influenced—or when market participants can act on information about what a person will do or say before that conduct becomes public.
What exchanges are expected to consider
According to reporting by CNBC, the CFTC letter outlines four factors that exchanges listing mention markets should consider:
- Whether there are adequate oversight measures in place to detect manipulation.
- Whether the words or actions used for settlement are independently verifiable.
- Whether external pressure could influence the subject’s conduct, potentially affecting whether the event occurs as expected.
- What outside obligations the subject of the mention market may have, which could shape their behavior or the likelihood that the contract condition will be met.
This checklist frames mention markets not just as a novel product category, but as a compliance and risk-management challenge. Exchanges that previously treated these contracts as straightforward event bets may now need to demonstrate stronger controls around how outcomes are determined and how manipulation could realistically occur.
CFTC leadership ties the advisory to “regulatory clarity”
CFTC Chair Mike Selig publicly welcomed the guidance in an X post on Tuesday, saying that “regulatory clarity drives sound markets.” In the post, he referenced staff reminding designated contract markets (DCMs) of their obligation to list only contracts that are not readily susceptible to manipulation.
The chair’s post is available at: https://x.com/ChairmanSelig/status/2102500746834874859?s=20.
While the advisory is addressed to regulated entities, the implications extend across the broader prediction market ecosystem. As more contracts are designed around human behavior—rather than purely observable, externally confirmed outcomes—platforms may face tighter scrutiny on whether the settlement criteria can be verified without ambiguity and whether market structure could incentivize gaming of the subject’s conduct.
What to watch next for prediction markets
Exchanges considering mention markets will likely need to document how their oversight can identify manipulation and how settlement conditions can be verified. The most immediate uncertainty for market participants is how broadly regulators will interpret the “limited circumstances” standard—particularly as more politically or socially contingent contracts come under review.
Crypto World
CFTC says prediction markets’ ‘mentions’ contracts present a higher risk of manipulation
The Commodity Futures Trading Commission advised some of its regulated entities on Tuesday that prediction markets’ “mentions” contracts are at greater risk of manipulation.
In a press release announcing the letter it sent to designated contract market entities, the CFTC said that the contracts are more susceptible to exploitation “because their settlement turns on the discrete conduct of a person that may be neither independently generated nor externally verifiable.”
The letter noted that the agency was not creating new obligations that regulated exchanges need to follow, but rather advising entities on when mention markets may be listed consistent with the Commodity Exchange Act, the law that governs the assets that the CFTC regulates.
Mention markets — which are made up of contracts that ask traders what specific words will be used in a speech, a corporate earnings call or during a television broadcast — have come under scrutiny by the CFTC. CNBC reported in August that the agency was conducting an internal review into the contract type, and that platform Kalshi pulled its sports-related mention markets in response to the inquiry.
Kalshi is one of the few U.S. regulated platforms that features mention markets. Its chief rival, Polymarket, only features them on its international exchange, which is not regulated by the CFTC.
“We’ve addressed this guidance based on a prior discussion with the CFTC,” Kalshi spokesperson Elisabeth Diana said in a statement.
Mention markets also generated headlines in July after news reports that a longtime teleprompter operator for President Donald Trump profited off of trades on Kalshi related to contracts on mention markets that were tied to the president’s statements. Gabriel Perez, the teleprompter operator, settled with the CFTC in August and was forced to pay a $172,539 fine for insider trading on a prediction market.
In the letter, the CFTC advised that exchanges listing mention markets should consider four factors: what outside obligations the subject of the mention market may have; external pressure that could influence the subject’s speech or conduct; whether the words or actions used for settlement are independently verifiable; and whether there are adequate oversight measures in place to detect manipulation on the contracts.
The CFTC added that it encourages exchanges to engage with the agency’s division of market oversight while in the early phases of designing mention market contracts on how to mitigate manipulation risks.
Disclosure: CNBC and Kalshi have a commercial relationship that includes customer acquisition and a minority investment.
How do animals sense the Earth’s magnetic field?
Asia stocks ride tech wave higher, oil stays subdued

Bettman cools NHL expansion talk as Texas process continues

Weekend Open Thread – Corporette.com

Weekend Open Thread: Talbots – Corporette.com

Memory prices are slowing because buyers ran out of money

Dr Boyce faces $350 million dollar shackles – Financial Godfather ep 12 – pt 1

MR CASH AND PRIDE – UZOR ARUKWE, PAMELA OKOYE, EMEM UFOT, INEM PETERS, Latest 2026 Nigerian Movie

What is Bitcoin & Cryptocurrency? How to earn and invest? Easy explanation by Him eesh Madaan
-
 Fashion4 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech2 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World4 days ago
Circle launches Arc Studio AI agent for building onchain apps
-
 NewsBeat4 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World2 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Crypto World4 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World4 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World6 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World7 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-

 Crypto World5 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Business2 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Crypto World4 days ago
World Money launches in 150+ countries with Stripe
-

 Crypto World5 days ago
Silver prices recover quickly, hitting weekly high today
-
 Entertainment7 days ago
Big Brother Update: Melody Explodes at Drew as Illness Sweeps BB28 House
-

 Tech5 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-
 NewsBeat4 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-

 Crypto World2 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World2 days ago
Bitcoin price holds above $81K as key catalysts line up
-
 Business4 days ago
Newsom accelerates AI oversight, advances ‘kill switch’ plan
-
 Crypto World4 days ago
CFTC sends crypto market structure rulemaking to White House
You must be logged in to post a comment Login