Connect with us

Business

Tired of the S&P 500? Alternative Investment Ideas Worth a Second Look

Published

on

Tired of the S&P 500? Alternative Investment Ideas Worth a Second Look

The problem is that for a lot of investors the tracker has quietly become the entire portfolio. Passive investing buys the market by size, which means the more expensive a company gets, the more of your money goes into it, and a handful of very large technology names now sit behind a large share of the average index holding. That is concentration risk dressed up as diversification.

Private Credit and Peer-to-Peer Lending

Lending money directly to businesses, rather than owning a slice of them, produces a different return profile. Income arrives as interest rather than capital growth, and the performance of the loan book depends on borrower default rates rather than on market sentiment.

The appeal is yield and low correlation with equities. The catch is that the risk is credit risk, and it tends to arrive all at once. A platform that has produced steady returns through a benign economic period can look very different in a downturn, when defaults cluster. Anyone considering this should be reading the loan book statistics rather than the headline return figure, and should assume their capital is locked up for the stated term.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

Commercial Property, Directly or Through Funds

Property remains the default alternative for UK investors, and direct commercial property does genuinely behave differently to equities. Rental income is contractual, leases are long, and valuations move slowly.

That slowness is also the trap. Property funds have repeatedly demonstrated that a daily-dealing wrapper around an illiquid asset creates a mismatch, and several have gated redemptions when too many investors headed for the exit at once. Direct ownership avoids the gating problem but introduces management, void periods and a much larger minimum commitment. It suits investors who understand the asset class and want the income, not those looking for a quick diversifier.

Collectables and Passion Assets

Art, classic cars, rare watches and fine wine sit in a category of their own. Knight Frank tracks this group annually in its Luxury Investment Index, and the picture it consistently shows is one of wide divergence: individual categories can perform very differently in the same year, and within a category the very best examples behave nothing like the average one.

That last point is the one most often missed. These are not asset classes so much as thousands of individual items, each priced on condition, provenance and rarity. Knowledge is the entire edge. Buying blind, or buying because a category is being written about, is how people lose money here. Costs are real too: storage, insurance, restoration and, at sale, auction commission that can run into double-digit percentages.

Advertisement

Whisky Casks

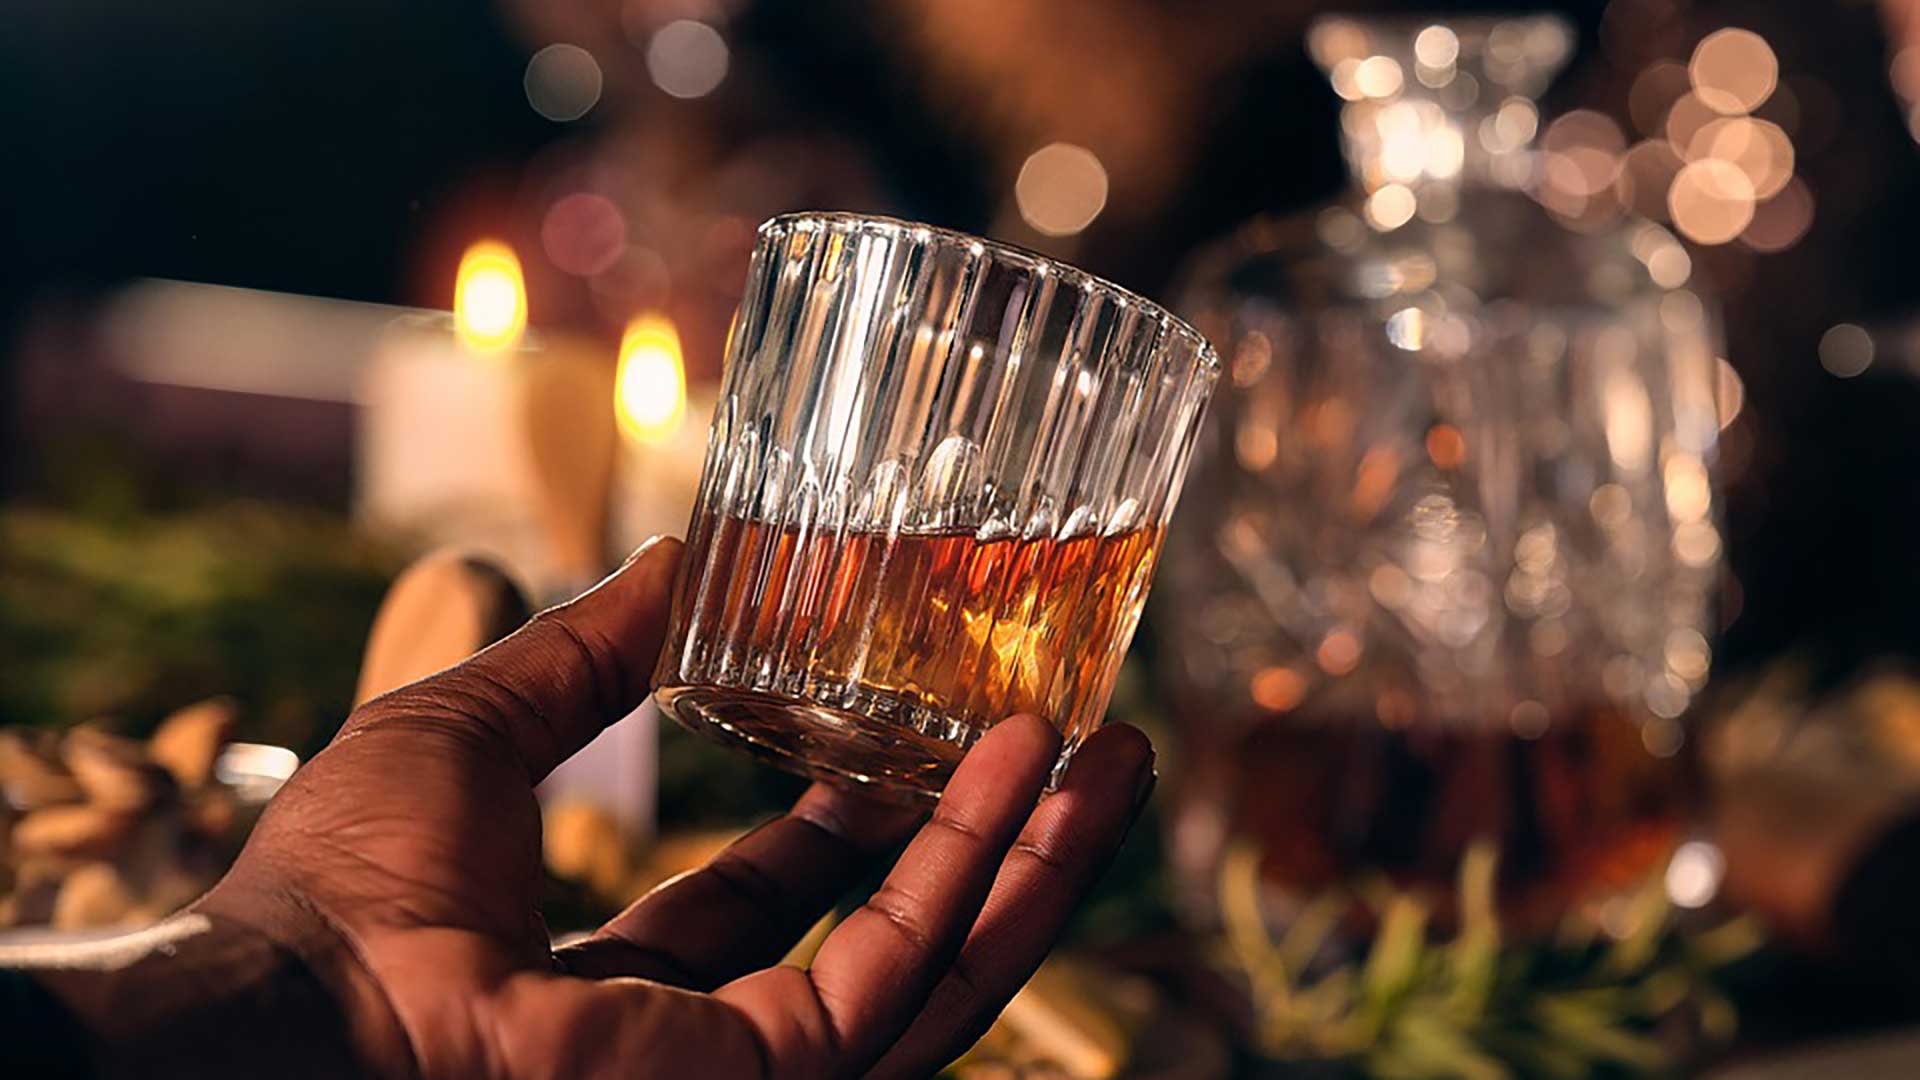
Whisky casks have become one of the more visible entries in this category, and they work on a genuinely different principle to most alternatives. Rather than buying a finished bottle and hoping the secondary market revalues it, investing in whisky involves buying new-make spirit or a maturing cask and holding it while it ages. The asset is not static. Time in oak changes the liquid, and a maturing Scotch typically becomes more valuable as it passes recognised age milestones, particularly the ten, twelve and eighteen year marks, because the pool of available stock at each age is finite and shrinking.

There is also a structural point in the seller’s favour. Casks lose volume to evaporation each year, the so-called angels’ share, so supply at any given age genuinely contracts over time while global demand for aged Scotch has broadly grown. The Scotch Whisky Association publishes export figures annually, and the long-run direction of travel for premium and aged Scotch has been upward.

The practical mechanics matter more than the story, though. A cask should sit in an HMRC-bonded warehouse under a bailment arrangement, which means the investor owns the cask outright and the warehouse simply stores it.

Understanding what a bonded warehouse arrangement does and does not give you is the single most useful piece of due diligence in this market, because it determines whether you actually own an identifiable asset or merely hold a claim against a company. Investors should expect a delivery order in their own name, a warehouse account, and regauge documentation confirming volume and strength.

Advertisement

Exit routes are worth establishing before entry rather than after. A cask can be sold to another private buyer, sold back into the trade, or bottled under a private or independent label. Each has different timescales and costs, and a broker who cannot explain all three clearly is not a broker worth using. This is also an unregulated market, which means the quality of the counterparty matters enormously and there is no compensation scheme standing behind a bad purchase.

What These Alternatives Have in Common

Read across the four and the same pattern appears. All of them are illiquid, all of them carry costs that do not appear in the headline return, and all of them reward specific knowledge in a way that a tracker fund deliberately does not. That is precisely why they can diversify an equity-heavy portfolio: their returns are driven by supply, condition, credit and scarcity rather than by the same macro sentiment that moves the S&P.

It is also why they should be sized carefully. A sensible approach for most investors is to treat alternatives as a satellite allocation, not a replacement for a diversified core, and to size any single alternative position so that a total loss would be disappointing rather than damaging. If an investment cannot survive being left alone for five to ten years, it is not suited to this part of a portfolio.

The right question is not whether the S&P 500 has stopped working. It is whether a portfolio built almost entirely on one index, in one currency, weighted heavily towards one sector, is as diversified as its owner assumes. For a lot of people, the honest answer is no, and that is worth addressing with assets genuinely chosen for how differently they behave.

Advertisement

Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business

Trump says he would back ban on diesel exports as pump prices hit record

Published

on

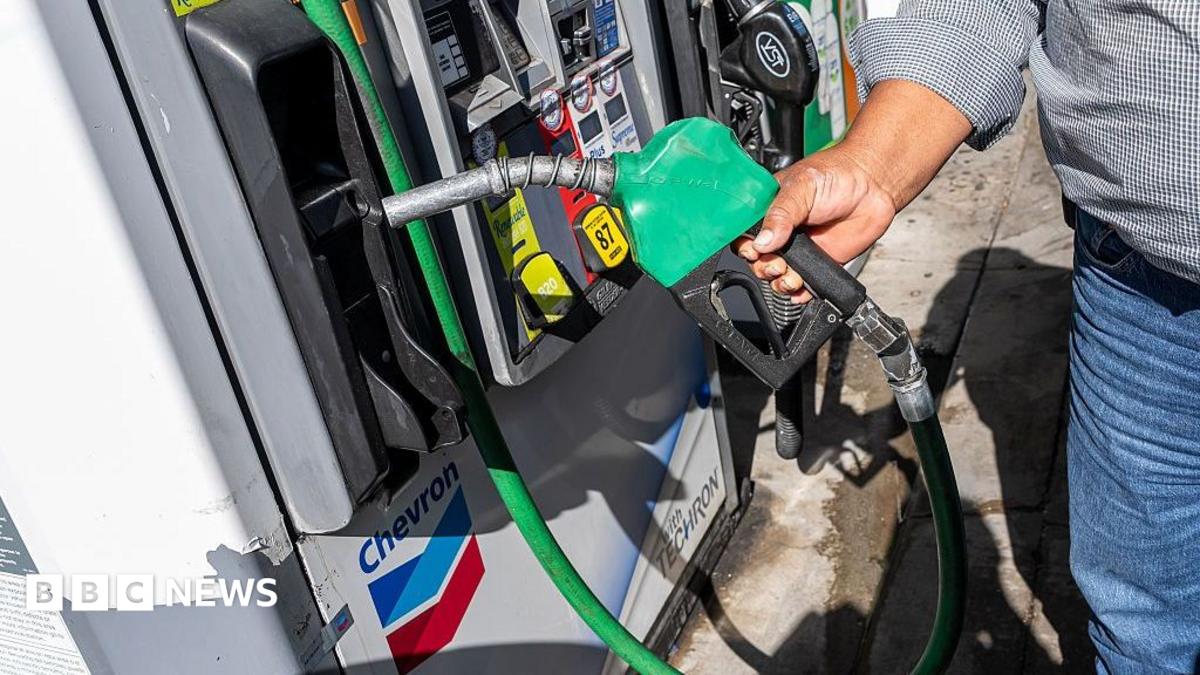
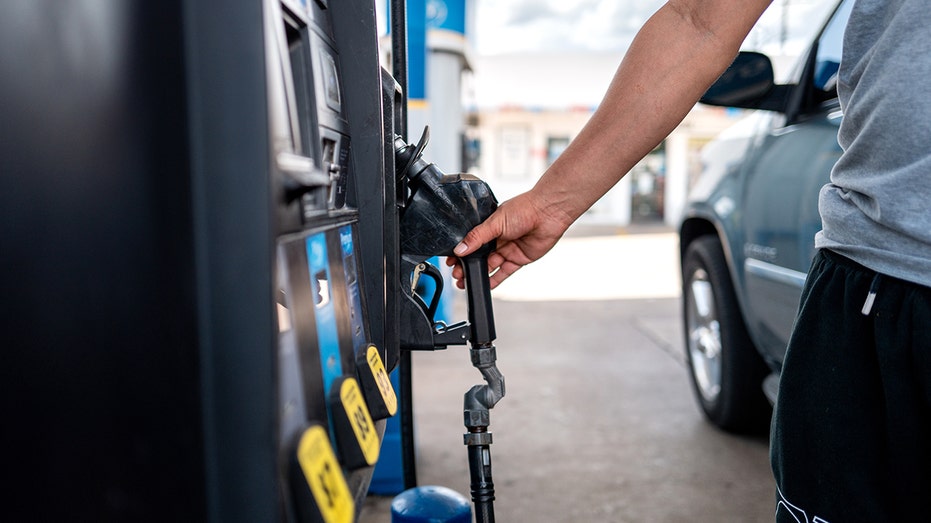
A man wearing a checked shirt and jeans returns a fuel nozzle after refueling a vehicle with diesel at a Chevron petrol station.

US President Donald Trump has said he would back proposals to halt American diesel exports in a bid to ease prices for drivers at the pumps.

His comments come after Republicans lawmakers put pressure on the president ahead of November’s mid-term elections to curb exports, as diesel prices soar to record highs in the US.

Speaking on the sidelines at the United Nations General Assembly, Trump suggested keeping domestic supplies inside the US could also ease broader petrol prices.

“I’ve called for that too. I’ve said let’s not send out the diesel. We make a lot of diesel. That could have a little bit of an effect on regular automobile gasoline,” he said .

Advertisement

US Treasury Secretary Scott Bessent confirmed officials were assessing “whether a full or partial ban would work” without disrupting refinery capabilities.

National average diesel prices surpassed $6.50 (£4.87) a gallon on Tuesday according to American Automobile Association data, a new high.

The conflict in the Middle East has constrained global oil supplies, putting pressure on pump prices.

The surge in the cost of diesel has sparked political urgency ahead of crucial mid-term elections on 3 November, with several Republicans pressing the administration to restrict the fuel’s export to ease financial strain on voters.

Advertisement

US Representative Ashley Hinson, a Republican running for Senate in Iowa, said on Monday that the state’s consumers were “being squeezed and shouldn’t have to foot the bill at the pump.”

In Alaska on Tuesday, Senator Dan Sullivan similarly urged for a “temporary pause of American diesel and exports” to rebuild domestic reserves.

Adding to the global market volatility, Ukraine’s targeting of Russian energy facilities has knocked out the country’s refining capacity.

“It is a serious hit on the Russians,” Trump said during a meeting with Ukrainian counterpart Volodymyr Zelensky on Tuesday. “It’s also a serious hit on the price of diesel.”

Advertisement

Trump confirmed he would discuss the strikes with the Ukrainian president, alongside broader efforts to negotiate an end to the conflict. “I think it’s going to happen,” he said.

Kyiv has intensified drone attacks on Russian processing plants in recent months to choke off the Kremlin’s primary source of war funding.

Because Russia ranks among the world’s leading diesel suppliers, reduced refining capacity – combined with Moscow’s own strict export bans – has severely squeezed global reserves.

While restricting US exports could offer short-term relief for American drivers, a ban may risk pushing up prices internationally.

Advertisement

The US exports roughly 1.3 million barrels of diesel per day – nearly a quarter of its refining output.

Cutting these shipments could put pressure on supplies for Western allies, including the UK and the Netherlands, which have relied on American fuel to cover deficits left by sanctions on Russian energy.

Continue Reading

Business

How much do you spend on a birthday present?

Published

on

A woman with a white T-shirt and red skirt smiles in front of a mic. She's in the street with her friend.

Do you show you care through expensive presents? Or do you consider a drink in a pub a worthy birthday gift?

Continue Reading

Business

Thailand is rolling out a new EV tax structure linked to local manufacturing

Published

on

Thailand is rolling out a new EV tax structure linked to local manufacturing

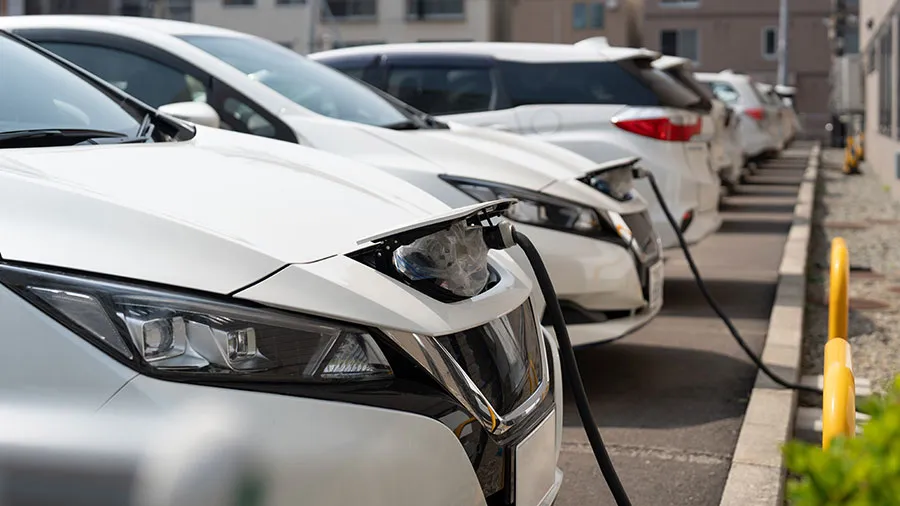
Thailand’s National Electric Vehicle Policy Committee approved a new EV excise-tax structure linking taxes to automaker value creation in Thailand, with higher taxes for non-local manufacturers.

Approval of New EV Tax Structure in Thailand

On September 10, 2026, Thailand’s National Electric Vehicle Policy Committee gave preliminary approval to a revamped excise-tax structure for electric vehicles (EVs). This new framework is designed to more closely align tax incentives with the value that automakers contribute through their operations within Thailand. The aim is to encourage manufacturers to enhance their local presence, thereby boosting the country’s industrial ecosystem and economic growth.

Key Components of the Proposed Framework

The new EV tax structure introduces four distinct approaches, focusing on the degree of manufacturing presence and the extent of value added within Thailand. Vehicles imported by companies without local manufacturing facilities will incur higher excise taxes. This measure aims to incentivize automakers to establish production plants in Thailand and further invest in local manufacturing capabilities, creating more jobs and technological advancements in the region.

Operational Flexibility for Manufacturers

Although the specific tax rates are still pending, manufacturers with local plants in Thailand will benefit from operational flexibility. They will have the option to import certain models for market testing before committing to full-scale domestic production. This approach allows companies to gauge consumer interest and preferences, ensuring a more strategic and adaptive manufacturing process. By facilitating this testing phase, the policy aims to attract more automakers to set up manufacturing operations in Thailand, fostering innovation and industrial growth.

Advertisement

Thailand Proposes New EV Tax System Linked to Domestic Production

Thailand is embarking on a significant shift in its electric vehicle (EV) strategy by introducing a revamped tax structure aimed at bolstering local manufacturing. The new framework is designed to incentivize international and domestic automakers to establish production facilities within the country, aligning with Thailand’s long-term vision to become a regional EV hub. By linking tax benefits with local manufacturing, the government seeks to stimulate job creation, foster technological innovation, and enhance economic growth.

This strategic move acknowledges the increasing importance of sustainable transportation and the global transition towards greener energy. By fostering a supportive environment for EV production, Thailand hopes to attract substantial foreign investment and technology partnerships. The initiative underscores Thailand’s commitment to reducing its carbon footprint by promoting cleaner energy solutions. As the global EV market continues its upward trajectory, Thailand’s proactive approach may position it as a key player within the ASEAN region, driving forward regional green transportation goals while enhancing its own economic resilience.


Read the original article : Thailand Plans New EV Tax Structure Tied to Local Manufacturing

Advertisement
Continue Reading

Business

Grow MRR Faster With the Right Subscription Billing Platform

Published

on

Grow MRR Faster With the Right Subscription Billing Platform

For companies tracking monthly recurring revenue, that number matters more than it might first appear. A subscription billing platform sits underneath every renewal, every failed card, and every plan upgrade, and its performance shows up directly in the MRR line, whether anyone is watching or not.

Why Billing Infrastructure Sets the Pace for MRR Growth

Billing systems rarely get credit when things go right, and they rarely get blamed when things go wrong – most teams simply don’t connect the dots. Revenue lost to a stalled payment or a clunky upgrade flow looks identical, on paper, to revenue lost from genuine dissatisfaction, which makes the problem easy to miss.

A subscription billing platform is the infrastructure layer that decides whether a payment failure becomes a retry or a cancellation. That single distinction accounts for a meaningful share of churn at most subscription businesses, long before marketing or product ever enters the picture.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

What Happens When a Subscription Billing Platform Falls Behind?

The short answer: revenue leaks out in small amounts that are hard to trace individually but add up quickly at scale. An expired card that isn’t retried, a downgrade that requires a support ticket, a tax rule that isn’t automated – none of these look dramatic in isolation.

Over a full quarter, though, they behave like a slow leak in a tire. The business keeps moving, but never at full speed, and finance teams often can’t say exactly where the pressure is escaping from.

Core Capabilities of a Reliable Subscription Billing Platform

Not every provider in this category solves the same problems, and the gap between a basic setup and a well-built one tends to show up only after a company scales past its first few hundred customers.

How Does Failed Payment Recovery Work?

Recovery works through timed retries and alternate payment routing, not a single automatic re-charge. Card-based payments now account for 79% of all noncash payments in the U.S. by number, according to the 2025 Federal Reserve Payments Study, which means most recurring revenue businesses are still fundamentally dependent on cards that expire, get replaced, or get declined without warning.

Advertisement

A capable system spaces out retry attempts, switches to backup payment methods when available, and adjusts timing based on the decline reason rather than treating every failure the same way. That distinction separates providers that quietly protect MRR from ones that let it erode.

Why Does Flexible Pricing Configuration Matter?

Pricing changes stall when they require an engineering ticket, and slow pricing experiments translate into slower revenue growth. Teams that can adjust tiers, bundle add-ons, or test annual discounts without waiting weeks tend to find better-performing offers simply because they test more often.

What Should MRR Reporting Actually Show?

Good reporting shows churn and expansion revenue broken down by plan and cohort, updated in real time rather than reconciled at month-end. Finance teams that rely on manual exports are usually working from numbers that are already a few weeks stale by the time a decision gets made.

Here’s what tends to separate the two approaches in practice:

Advertisement
  • Basic systems rely on fixed retry schedules, manual pricing updates, and delayed reporting pulled from spreadsheets.
  • Mature systems use adaptive dunning logic, self-service plan configuration, and dashboards that update as transactions happen.
  • Transitional setups often combine pieces of both, which creates its own maintenance burden over time.

Comparing Setups Side by Side

Capability Basic Setup Growth-Ready Platform
Failed payment recovery Fixed retry schedule Adaptive retries with backup methods
Pricing changes Requires engineering Self-service configuration
Reporting Manual, delayed Real-time MRR and churn dashboards
Tax and currency handling Manual, single currency Automated, multi-currency
Plan upgrades Support ticket required Self-service with automatic proration

Migrating between systems later isn’t simple, either. Moving active subscriptions, stored payment tokens, and billing history without disrupting customers takes real engineering time, which is why companies that switch to a single recurring billing solution early tend to avoid a painful migration once volume picks up.

Where MRR Growth Quietly Stalls

Growth ceilings rarely announce themselves. They show up as a gap between the customers a business should be retaining and the ones it actually keeps, and the causes are usually mundane rather than dramatic.

A few patterns show up repeatedly:

  1. Involuntary churn gets lumped in with voluntary cancellations, which hides a fixable problem inside a number that looks like a customer satisfaction issue.
  2. Plan upgrades require manual intervention, so expansion revenue – often the cheapest growth available – never gets captured.
  3. Dunning emails read like generic system notices instead of clear, specific instructions, which lowers how many customers actually update their payment details.

None of these require a full rebuild. Most come down to whether the subscription billing platform in place actually supports the behavior a growing business needs.

Frequently Asked Questions

What is a subscription billing platform?

It’s software that manages recurring charges, invoicing, plan changes, and payment retries for a subscription-based business. Beyond processing payments, it typically handles proration, tax calculation, and reporting on metrics like MRR and churn.

How is a subscription billing platform different from a payment processor?

A payment processor moves money between a customer’s bank and a business account for a single transaction. A subscription billing platform manages the ongoing relationship – scheduling charges, retrying failures, and adjusting invoices as plans change – often working on top of one or more processors rather than replacing them.

Advertisement

Can switching subscription billing platforms hurt existing revenue?

It can, if the migration isn’t handled carefully, since active subscriptions, stored payment methods, and billing history all need to transfer without interrupting a single charge cycle. Most of the risk comes from rushed timelines rather than the switch itself, which is why companies typically plan these migrations months in advance.

How much revenue does involuntary churn typically cost?

Estimates vary by industry, but payment failures unrelated to a customer’s decision to leave are consistently cited as a significant share of total churn across subscription businesses. Addressing them through better retry logic and payment method updates is one of the more measurable ways to protect existing MRR.

Is a subscription billing platform necessary for a small SaaS business?

Not immediately – a company with a handful of customers can often manage billing manually or with a basic processor integration. Once monthly recurring revenue and plan complexity grow, though, manual processes tend to introduce errors and slow down pricing changes, which is usually when a dedicated platform starts paying for itself.

Advertisement

Continue Reading

Business

Why Fast-Growing Digital Firms Struggle to Borrow

Published

on

Why Fast-Growing Digital Firms Struggle to Borrow

More often it is money — specifically, the maddening difficulty of persuading a lender to back a company that is growing quickly but does not look like a traditional borrower on paper.

The Financial Conduct Authority’s review of how banks and finance houses serve small and medium-sized businesses has landed squarely on this problem, and few sectors feel it more acutely than the UK’s online gaming and casino operators. These are firms with real revenue, real customers and real ambition, yet they routinely find the shutters coming down when they approach mainstream funders.

One corner of the market that illustrates the funding puzzle particularly well is the world of non gamstop sites — UK-facing casino destinations that operate outside the national player-blocking scheme and are typically catalogued by independent review guides for adult players who want a broader spread of options. These are legitimate businesses with genuine revenue and loyal customers, but their position outside the mainstream framework makes lenders instinctively wary, often before any numbers are examined. For any operator or affiliate whose commercial model touches this part of the sector, understanding how funders perceive it is essential, because a lender’s assumptions about risk here can quietly shape whether a growth loan is ever approved. It is precisely this kind of niche the FCA review implicitly acknowledges when it questions whether “computer says no” underwriting fairly serves legitimate digital businesses.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

What the FCA Review Actually Says

At its heart, the review examines whether SMEs across the economy — from manufacturers to software firms — can access finance on fair, transparent terms. It scrutinises the way banks assess creditworthiness, the speed of decisions, and the frustrating opacity that leaves founders guessing why an application failed. The regulator has flagged a stubborn gap between the appetite for growth capital among smaller companies and the willingness of established lenders to provide it.

For digital-first firms, the sting is sharper. Traditional credit models were built around tangible assets: property, machinery, stock sitting in a warehouse. An online gaming operator’s value lives in code, customer relationships, brand and recurring revenue — none of which fits neatly into a spreadsheet designed for a haulage company. The review’s push toward more nuanced, data-informed lending decisions could, in principle, tilt the field back toward these asset-light businesses.

The Asset-Light Problem in a Physical-Asset World

Compare the treatment of two hypothetical companies. A precision engineering firm applying for expansion capital can point to the machines on its factory floor as collateral. The government’s own Advanced manufacturing plan (HTML version) leans heavily on the idea that physical investment underpins productivity and growth — and lenders instinctively understand it.

Now picture an online gaming operator turning over similar sums. Its “factory” is a set of servers, licences and a marketing engine. There is nothing to repossess if the loan sours, which makes a cautious credit committee nervous. The FCA review pushes lenders to move beyond this instinct and toward richer signals: transaction data, customer retention, cash-flow patterns. The direction of travel favours founders who can tell a credible, numbers-backed story rather than simply pledge a building.

Advertisement

Infrastructure, Not Just Ideas

There is a quiet twist here. Fast-growing gaming firms are increasingly capital-hungry in ways that do resemble traditional industry — they consume enormous computing power. The same forces reshaping British manufacturing are reshaping their cost base too. Recent reporting on how data centre demand drives NI manufacturing shows just how physical the digital economy has become. Servers need buildings, cooling, energy and hardware.

That convergence is useful for founders seeking funds. An operator that can frame its borrowing around genuine infrastructure — computing capacity, resilient systems, data handling — presents a case a lender recognises. It reframes an “intangible” business as one with real, financeable underpinnings, precisely the kind of nuance the FCA wants credit decisions to capture.

Where Technology Strengthens the Case

Beyond hardware, the sophistication of a firm’s technology stack is becoming a lever in funding conversations. Underwriters increasingly want evidence that a business runs efficiently and can defend its margins as it scales. Analysis of AI in leisure and hospitality highlights how automation, personalisation and smarter operational tools are lifting productivity across consumer-facing sectors.

For gaming operators, demonstrating this maturity does double duty. It shows a lender the business is not a fragile bet reliant on a single trend, and it aligns with the FCA’s encouragement of data-driven assessment. A founder who arrives with clean dashboards, predictable cost curves and evidence of operational discipline is far easier to underwrite than one waving projections alone.

Advertisement

What Founders Should Do Next

The practical takeaway for anyone running a fast-growing online leisure business is to prepare for a lending environment that is slowly, unevenly modernising. That means keeping meticulous financial records, quantifying customer value, and being ready to explain the business model in plain terms a generalist credit officer can grasp.

It also means widening the search. Challenger banks, specialist lenders and revenue-based finance houses often understand digital models better than the high street, and the FCA review may prod incumbents to compete harder for exactly this custom. The direction of change is encouraging: fair, transparent, data-led lending should reward well-run digital firms rather than penalising them for lacking a warehouse. For the operators watching from the fast lane of the online economy, that shift cannot come soon enough — and the founders who prepare now will be the ones ready to seize it.

Advertisement
Continue Reading

Business

Richmond Fed’s Tom Barkin says inflation risks may drive more hikes

Published

on

Richmond Fed's Tom Barkin says inflation risks may drive more hikes

The Federal Reserve’s decision to raise interest rates last week may mark the first of several hikes aimed at taming stubborn inflation, and one central bank leader weighed in on where inflation may go from here.

Federal Reserve Bank of Richmond President Tom Barkin said in a speech before CFA Society Baltimore Tuesday that the “risks to inflation outweigh the risks to maximum employment. That’s why we raised rates.”

Advertisement

Barkin, who is a non-voting member of the Federal Open Market Committee (FOMC) this year, compared the Fed’s dual mandate between promoting maximum employment and price stability to raising children, saying “inflation is our troublemaker” and noting it’s been above the 2% target for five years, which contributed to the decision to hike.

“Where do we go from here? We are committed to returning inflation sustainably to our 2% target. Last week’s hike will help. Will additional hikes be required and how many? We’ll see,” Barkin said, explaining that inflation could ease as price shocks fade or prove persistent.

FEDERAL RESERVE HIKES INTEREST RATES FOR FIRST TIME SINCE 2023 AMID STUBBORN INFLATION

Federal Reserve President Thomas Barkin

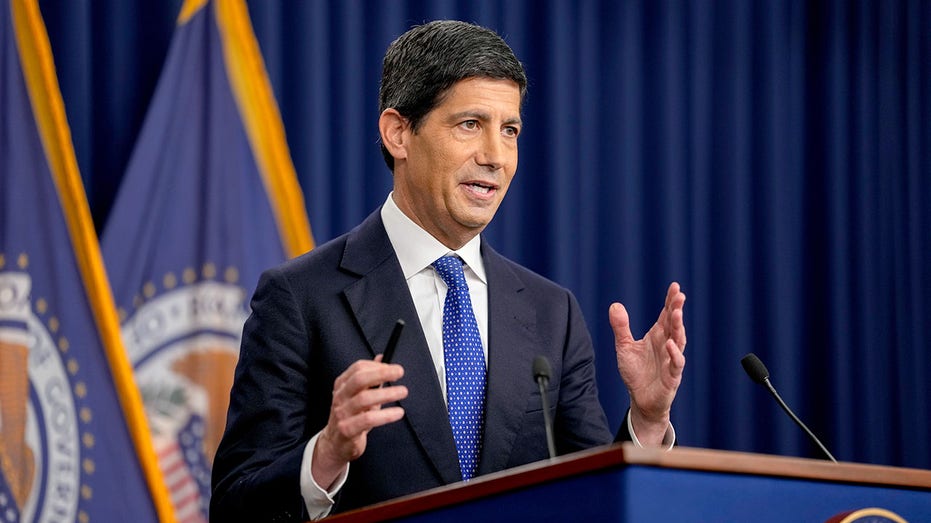
Richmond Fed President Thomas Barkin said inflation could come down relatively quickly or prove more persistent. (Valerie Plesch/Bloomberg via Getty Images)

“I’m open to the possibility that inflation could come back down in short order. Some of these recent shocks could reverse. Consumers could start to reach their limit. The investment boom could slow. Markets could correct. Employment could falter, making the labor market the problem child,” Barkin explained.

Advertisement

“On the other hand, inflation could prove more stubborn. Temporary shocks could drag on. New cost pressures could develop. Firming demand conditions could flow through to prices, as could the impact of today’s inflation,” he said.

Barkin added that the shocks from the Iran war and the AI buildout “aren’t proving to be short-lived or one-off events,” adding that while they “may pass in time, I do expect it will take time. In the interim, there is a risk that current elevated levels of inflation could affect future inflation.”

CONSUMER PRICES REMAINED ELEVATED IN AUGUST AHEAD OF FED’S NEXT MEETING

Person's hand pulls for gas station pump

Surging gas and diesel prices have driven inflation higher amid the Iran war. (Brandon Bell/Getty Images)

The market expects the Fed to move forward with at least one more 25 basis point rate hike before the end of the year.

Advertisement

The CME FedWatch tool shows a 48.3% chance of one hike to a target range of 4% to 4.25% after the October and December meetings, along with a 40.7% chance of a second hike before year’s end.

Federal Reserve policymakers also released their economic projections, which reflected one hike before the end of the year, while Fed Chair Kevin Warsh maintained his stance in not offering forward guidance during last week’s post-meeting press conference.

WHAT WARSH’S JACKSON HOLE SPEECH SIGNALS ABOUT WHERE INTEREST RATES ARE HEADED

Fed Chair Kevin Warsh speaks at a press conference

Fed Chair Kevin Warsh and central bank policymakers unanimously voted to hike interest rates at the September meeting. (Daniel Heuer/Bloomberg via Getty Images)

Gregory Daco, chief economist at EY-Parthenon, told FOX Business Barkin’s comments echoed the FOMC’s rate hike decision because while “policymakers had displayed patience in waiting for core inflation to converge toward 2%, that patience has seemingly run out, and most policymakers now favor adopting a modestly more restrictive monetary policy stance.”

Advertisement

“In our view, a Fed hiking cycle, if implemented, could create further strain for already-constrained interest-sensitive sectors while doing little to slow the AI-led investment surge beyond increasing the risk of a stock market correction,” he explained.

Daco added that the “key missing element in Warsh’s narrative was transparency around how tighter policy would address the inflation overshoot,” with policymakers looking to potentially undo some or all of the 75 basis points of rate cuts late last year.

GET FOX BUSINESS ON THE GO BY CLICKING HERE

“The objective is tighter financial conditions and disinflationary demand destruction. The risk is substantial for an economy already facing income erosion, supply-driven inflation and persistently elevated rates,” Daco said.

Advertisement
Continue Reading

Business

KB Home (KBH) Q3 2026 Earnings Call Transcript

Published

on

OneWater Marine Inc. (ONEW) Q1 2026 Earnings Call Transcript