
Crypto World
10-Year Yield Jumps As Markets Bet On Two Rate Hikes

The 10-year Treasury yield hit a 19-year high on Wednesday on strong economic data that has Wall Street betting on two more Fed rate hikes in 2026. Despite the jump in interest rates, the Treasury Department kept a $6 billion ceiling for buybacks of long-term Treasury bonds, signaling no appetite to fight market pressures. The preliminary S&P Global purchasing managers’…
Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8

Bitcoin ran into selling pressure Wednesday after failing to hold a push above the $87,000 area, with on-chain indicators pointing to weaker spot buy interest. Price slid under $84,000 around the Wall Street open, triggering a sharp wave of leverage unwinds.
Intraday, TradingView data showed BTC/USD losing momentum after a second attempt to break higher stalled. The move kept traders focused on whether the market can defend a key downside level near $82,000—an inflection point highlighted by analysts monitoring both price structure and demand flows.
Key takeaways
- BTC was rejected near $87,000 and dipped below $84,000 around the U.S. market open.
- Liquidations totaled about $280 million across roughly four hours, indicating leverage was heavily concentrated.
- Crypto demand on spot markets remains negative on a rolling 30-day basis, according to CryptoQuant.
- Traders are watching $82,000 as a level bulls may need to defend to avoid a deeper retracement.
From $87,000 rejection to a liquidity-driven dip
Following an attempted breakout, BTC/USD traded down into local lows just under $84,000 into the Wall Street open, with TradingView tracking a second unsuccessful push beyond $87,000. Analysts characterized the action as part of a narrow intraday range—one where liquidity built up on both sides as market participants tried to force a directional move.
That balance broke briefly as price weakness accelerated. According to CoinGlass liquidation data compiled over the four hours leading up to the time of writing, approximately $280 million in liquidations occurred, a sign that derivatives positioning was vulnerable when support failed.
In this environment, levels matter not only for technical traders, but also for investors evaluating how quickly the market can absorb selling pressure. A breakdown from a consolidation band can create cascading effects as leveraged positions unwind, often worsening short-term price volatility even if longer-term demand is still present.
$82,000 under the microscope as structure tests continue
With BTC pushed lower, attention turned to where bullish structure could be defended if the down move extended. Trader and analyst Rekt Capital pointed to $82,000 as a critical area for bulls to hold, arguing that bullish continuation requires Bitcoin to remain above—or at least successfully retest—that level after dips.
“For bullish continuation and to avoid reverting back into the $60k-$80k Range, Bitcoin would need to stay above or at minimum successfully retest ~$82k on any future dip,” Rekt Capital wrote on X.
His warning also framed a larger technical issue: if BTC fails to maintain the lower bound of the current structure, traders may increasingly revert to viewing the market through the lens of a broader prior range (between $60,000 and $80,000), which would likely change expectations for near-term upside.
As part of the broader debate about where the market may consolidate next, Cointelegraph previously reported that some conditions could set up a likely next consolidation area around $90,000. That potential pivot point was linked to the increased likelihood of profit-taking among traders as price moves into regions where gains are already secured.
Spot demand remains the sticking point
Even with Bitcoin maintaining momentum over the past several weeks, spot-market buying interest has been inconsistent. While BTC has gained more than 35% since the week beginning Aug. 17, on-chain analysis suggests demand is still not fully catching up—particularly when focusing on spot rather than derivatives.
In its latest research, CryptoQuant said demand is “still largely confined to derivatives markets.” In a blog post released on the day, the analytics firm noted that the negative value of BTC spot demand had narrowed slightly, while futures demand continued to rise. It also reported that total demand showed a small recovery compared with the previous day.
CryptoQuant’s accompanying data measured cumulative 30-day apparent spot demand at around -180,000 BTC as of Tuesday. Negative values indicate that, over the 30-day window, supply has outpaced demand on spot—an important distinction for investors because spot demand is often viewed as a more durable signal of accumulation than purely leveraged activity.
The key shift, according to CryptoQuant, is that the trend may be improving rather than deteriorating. The firm added that if the momentum continues, spot demand could eventually “flip to positive,” which it said would mark the beginning of a more meaningful rally.
For market participants, this creates a practical watchlist: even if price action holds support in the short term, the durability of any upside attempt may depend on whether spot buyers begin to absorb more supply rather than leaving futures-driven activity to carry the market.
Why the current range matters for ETF holders and broader positioning
Cointelegraph previously noted that the trading range has implications for certain investor cohorts. In particular, the aggregate cost basis of U.S. spot Bitcoin exchange-traded funds (ETFs) is just below $86,000. That places part of the current price action—roughly between the recent $84,000 dip and the $87,000 rejection—near a psychologically and positioning-relevant region for ETF holders.
When price hovers around such areas, market behavior can reflect shifting expectations about whether holders are likely to add, wait, or reduce exposure. If spot demand continues to lag, price may struggle to sustain breakouts even when ETF-related positioning provides a floor effect. Conversely, a sustained turn toward positive spot demand would potentially support higher highs by adding an underlying bid from the spot market.
For now, traders are left balancing two signals: the immediate tape shows heavy liquidation risk when ranges break, while on-chain demand data suggests spot interest is only slowly improving. The next move will likely depend on whether BTC can reclaim and hold above near-term resistance—without spot demand remaining stuck in negative territory.
Heading forward, investors should watch whether BTC can defend the $82,000 area during any renewed selloff and whether CryptoQuant’s spot-demand trend continues to edge toward a positive reading on the rolling 30-day metric. A sustained shift would help clarify whether the recent dip was a temporary shakeout—or the start of a deeper retracement.
Blockchain.com has signed a memorandum of understanding with the New York Stock Exchange (NYSE) to bring access to tokenized US stocks and exchange-traded funds (ETFs) to Blockchain.com users via NYSE’s planned digital trading platform. The arrangement is designed to extend NYSE’s tokenized securities roadmap beyond traditional market participants and into Blockchain.com’s global customer base, pending regulatory approval.
The proposal also includes an exchange of market data. NYSE affiliate ICE Data Services plans to provide Blockchain.com with crypto market data and analytics, while Blockchain.com would supply certain ICE and NYSE market data feeds back to the NYSE ecosystem.
Key takeaways
- Blockchain.com would distribute tokenized US equities and ETFs from NYSE’s digital alternative trading system (ATS), subject to regulatory approval.
- NYSE’s planned tokenized securities offering would be broadened to Blockchain.com’s user base, potentially widening retail access to US-listed products.
- The deal includes reciprocal market-data sharing between ICE Data Services and Blockchain.com.
- Industry commentary suggests NYSE’s model may emphasize retail-friendly features such as 24/7 trading and request-for-quote style execution.
- The agreement comes shortly after the SEC introduced a five-year “Innovation Exemption” for certain tokenized securities trading venues.
Blockchain.com meets NYSE on tokenized equities and ETFs
Under the memorandum of understanding, Blockchain.com would distribute tokenized US-listed stocks and ETFs that trade on NYSE’s digital ATS. The scope of distribution would depend on regulatory approvals, which remain a key gating item for any tokenized securities implementation.
The partnership also signals a clear convergence between crypto-native distribution networks and legacy market infrastructure. If approved, Blockchain.com would function as a channel for NYSE-linked tokenized instruments, while NYSE’s planned platform would supply the underlying venue for those assets.
For market participants, the practical difference is less about whether tokenization is possible and more about how it will be operationalized—particularly around settlement, custody, and how trading continuity is delivered to end users.
Why the NYSE model may matter for retail traders
Rid Noch, vice president of US equity market structure at TD Securities, told Cointelegraph that NYSE’s planned tokenized ATS appears “primarily like a play for retail flow.” According to Noch, the design—featuring planned 24/7 trading and request-for-quote functionality—aligns more closely with the way retail participants often engage with markets outside standard trading hours.
He further argued that because retail trades are typically pre-funded, the move to instant settlement would likely require limited disruption to existing retail workflows.
The bigger differentiator Noch highlighted is “true weekend trading.” He suggested this could be particularly meaningful for retail-heavy participants or during periods when news-driven price movements spill beyond traditional market hours. Noch referenced the early stages of tokenized oil perpetual contracts during the start of the Iran conflict, when trading activity ramped up over a weekend.
That framing matters because it points to what investors may actually feel first: not the tokenization itself, but when and how they can respond to price-relevant events.
Exchanges race toward onchain equity—without agreeing on the same model
The Blockchain.com-NYSE memorandum sits within a broader trend: major trading platforms exploring ways to offer equity exposure using token-like structures. Tanay Ved, senior research associate at Talos, described the shift in comments shared with Cointelegraph, saying traditional markets are adopting the “24/7, programmable structure crypto pioneered.”
Ved noted that multiple approaches are being tested across leading venues. He pointed to Kraken’s xStocks and its separate tokenized equity model partnership with Nasdaq, as well as efforts from Binance, Coinbase, and Robinhood to bring equities onchain through different product frameworks.
However, Ved emphasized that these initiatives involve trade-offs that can materially affect user rights and how much of the “real ownership” story each product delivers. In a quoted assessment shared by Cointelegraph, Ved said tokenization models range from issuer-native equity to custodial exposure and even to derivatives—each trading ownership for accessibility. “Which model wins out is yet to be seen,” he added, framing the current phase as early adoption where the market is still deciding what structure best balances compliance, usability, and investor protections.
For readers, the implication is straightforward: tokenized equities are not a single category with uniform rules. Even when instruments reference the same underlying equities, the legal and economic structure can differ—changing what holders actually own, how votes and rights are handled, and how the product behaves in edge cases.
Tokenized securities gain regulatory momentum as the SEC opens a pathway
This NYSE-Blockchain.com development arrives less than a week after the US Securities and Exchange Commission (SEC) introduced a five-year “Innovation Exemption” intended for certain tokenized securities trading venues. The SEC press release described the exemption as allowing eligible venues to use permissioned automated market maker (AMM) liquidity pools to facilitate trading without being treated as exchanges under the Exchange Act, provided they meet specific conditions.
One central requirement is that tokenized stocks must carry the same rights and privileges as their conventional share counterparts. The SEC’s framework therefore has direct consequences for which tokenized products may qualify and which may be excluded in their current form.
According to the coverage, the exemption’s conditions appear to disqualify some existing offerings that provide exposure without granting holders the same rights as conventional shareholders—specifically citing Kraken’s xStocks and Robinhood’s Stock Tokens. The message for market operators is that tokenization alone is not enough; product design must align with rights parity expectations.
SEC Commissioner Hester Peirce also indicated publicly that the exemption covers one model while leaving room for other approaches outside the framework, underscoring that the regulator’s path may not be the only path—though it may become a reference point for compliance expectations.
A fast-expanding tokenized stock market underscores demand—if structure is solved
While regulatory structures evolve, the tokenized stock market itself has been growing. RWA.xyz data cited by Cointelegraph reported distributed value of $3.14 billion as of Wednesday, representing an increase of more than 18% over the prior 30 days. The same dataset showed the number of holders rising nearly 72% to 3.87 million.
Those figures suggest that interest is not limited to institutional experimentation. But they also highlight why the details of each exchange’s model—rights, settlement, liquidity mechanics, and operating hours—will matter. If weekend trading and faster settlement prove compelling, they could become the practical drivers that pull retail participation further into the tokenized securities layer.
What remains to be seen is which tokenized formats can scale while meeting the kinds of rights and eligibility requirements the SEC has emphasized.
With Blockchain.com now linked to NYSE’s planned tokenized trading initiative, the next watchpoint is regulatory approval and the final product structure—especially how ownership rights, settlement behavior, and liquidity mechanisms will be implemented across tokenized US stocks and ETFs.
Bitwise Asset Management has rolled out a new Europe-listed exchange-traded product tied to the token of Lighter, another decentralized derivatives venue competing in the perpetual futures space. The move gives traditional brokerage customers exposure to LIT without requiring them to buy or hold the cryptocurrency directly.
According to Bitwise, its Bitwise Lighter Staking ETP (BLIT) began trading on Deutsche Börse Xetra on Wednesday. Bitwise said BLIT is the first ETP in Europe designed to track LIT, the native token of Ethereum-based decentralized derivatives platform Lighter.
Key takeaways
- Bitwise launched the BLIT exchange-traded product on Deutsche Börse Xetra to provide exposure to LIT in Europe.
- BLIT is fully backed by LIT held in cold storage and charges a 0.85% annual expense ratio.
- The product currently tracks LIT’s price but does not yet generate staking rewards.
- Bitwise positioned Lighter as part of a broader strategy to list ETPs referencing decentralized finance derivatives ecosystems.
BLIT listed on Xetra, backed in cold storage
Bitwise’s announcement states that BLIT holds LIT in cold storage and is structured to be accessible through standard brokerage accounts. That matters for investors who want regulated, exchange-traded access to crypto-linked exposure without managing custody, wallets, or on-chain transaction requirements.
Bitwise set the product’s ongoing cost at 0.85% per year. The ETP is named for staking, but the current design is deliberately more conservative: it focuses on tracking LIT’s market price rather than distributing staking returns immediately.
No staking rewards yet—tracking comes first
Although BLIT is branded as a “staking” product, Bitwise said staking will start only after the ETP reaches a sufficient level of assets under management to make staking operations efficient. Until then, the ETP will mirror LIT’s price performance without generating staking yields.
For investors, the practical implication is straightforward: today’s returns depend on LIT’s market direction rather than whether the underlying token is earning staking revenue. The timing of when staking begins will therefore be a key variable to watch, especially for users evaluating the ETP against alternative crypto exposures that may already be generating yield.
Bitwise builds out a decentralized-derivatives lineup
The Lighter ETP follows Bitwise’s earlier steps into exchange-traded products linked to decentralized derivatives markets. In April, Bitwise launched—per earlier coverage from Cointelegraph—a staking-focused ETP in Europe tied to Hyperliquid, marking a broader effort to bring token exposure from major decentralized trading venues into regulated wrappers.
In this context, BLIT extends Bitwise’s Europe-focused product lineup toward a second derivatives ecosystem. The underlying platform, Lighter, is described by Bitwise as an Ethereum-based decentralized exchange centered on perpetual futures. Bitwise also noted that Lighter uses zero-knowledge proofs to verify trades while aiming to help users retain control of their assets instead of depositing them with a centralized exchange.
Lighter has also marketed zero-fee trading for retail users, a competitive theme aimed at taking share from established decentralized derivatives platforms, including Hyperliquid.
Lighter’s push in a market led by Hyperliquid
Lighter’s expansion isn’t happening in a vacuum. Recent distribution support and trading activity point to growing attention, even as Hyperliquid remains dominant.
Bitwise’s filing and background context highlighted that Lighter recorded nearly $1.8 billion in trading volume over the past 24 hours, based on CoinGecko exchange data. That level of activity underscores why a token-linked ETP could attract investor interest—particularly for those seeking exposure to a high-frequency segment of DeFi that is closely tied to derivatives demand.
Additionally, the platform gained a notable distribution channel in July when Robinhood integrated Lighter into Robinhood Chain, its Ethereum layer-2 network. Eligible Robinhood Wallet users could trade perpetual futures through Lighter, with settlement described as being handled using Lighter smart contracts on Robinhood Chain.
Still, Hyperliquid continues to set the pace in decentralized perpetual trading. The article notes that Hyperliquid controlled more than 61% of decentralized perpetual futures trading, citing data referenced by The Motley Fool. Hyperliquid’s dominance is reinforced by ecosystem support, including payments and stablecoin settlement dynamics.
For example, Circle announced in May that it would expand support for USDC on Hyperliquid, aiming to improve liquidity and make stablecoin transfers easier across blockchains. At the time, Coinbase reported that roughly $5 billion in USDC was held on Hyperliquid.
What to watch next for BLIT and LIT exposure
BLIT’s launch gives European investors a new, regulated route to LIT exposure, but the product’s key question is whether and when staking returns begin. Traders and long-term holders should also monitor Lighter’s competitive position—especially as it continues to differentiate itself in the perpetuals market against Hyperliquid and other venues.
Reporting frequency matters because a proof-of-reserves report is only a snapshot. The more often an exchange publishes fresh reserve data, the shorter the period users have to wait before they can inspect a new checkpoint.
Summary
- Bitget’s September report was its 46th monthly reserve update and showed a 135% ratio across 19 covered assets.
- Binance publishes monthly reports, while OKX and Bybit provide recurring reports with different verification methods.
- Kraken uses independent attestations, and Coinbase publishes audited financial statements instead of a retail proof of reserves report.
But cadence is only one part of the comparison.
A useful PoR review should ask four separate questions: how often reports are published, what user balances are included, how users can verify their own inclusion, and whether a third party also reviews the process.
On those dimensions, Bitget now has one of the clearest recurring transparency records among major global exchanges: monthly reserve disclosures since December 2022, 46 updates through September 2026, a latest total reserve ratio of 135%, coverage across 19 assets, and open-source Merkle verification for users.
What does proof of reserves actually verify?
A proof-of-reserves system is designed to show that an exchange holds reserve assets backing the customer balances included in the calculation at a particular point in time.
Many current systems use a Merkle tree so an individual customer can verify that their balance was included without exposing every other customer’s account data.
A reserve ratio above 100% therefore means something specific: at that snapshot, the covered reserve assets exceeded the covered user balances used in the calculation.
It does not automatically establish every corporate liability, continuous solvency between snapshots, bankruptcy treatment, custody quality or the exchange’s ability to process every withdrawal simultaneously during a crisis.
That is why PoR should be read as recurring evidence, not as a substitute for a full financial audit.
How often do major exchanges publish proof of reserves?
The major exchanges in this comparison use different disclosure models.
Bitget
Bitget has published reserve data every month since December 2022. Its September 2026 Proof of Reserves was the 46th update in the series.
The latest report showed a 135% total reserve ratio and expanded current PoR coverage to 19 assets. Users can verify their own inclusion through Bitget’s Proof of Assets process and the open-source MerkleValidator tool.
That combination matters because cadence and user-level verification answer different questions. Monthly publication keeps the data relatively fresh, while Merkle verification lets the customer check whether their own balance was incorporated into the snapshot.
Binance
Binance also follows a monthly schedule. Its current verification guidance states that user snapshots are taken on the first day of each month and results are released by the seventh.
Binance uses Merkle-tree and zk-SNARK-based verification, so users can check their account balance against the published proof.
The important correction is that Binance should not be described as a quarterly PoR reporter; its current process is monthly.
OKX
OKX publishes recurring reserve and liability proof files using zk-STARK technology.
Its public PoR download page shows separate reserve and liability files across multiple 2026 reporting dates. That gives users a relatively detailed cryptographic verification model, including proof files addressing both sides of the covered calculation.
The exact calendar dates are not identical every month, so “recurring monthly” is a more accurate description than implying a fixed day-of-month schedule.
Bybit
Bybit also publishes recurring PoR reports and uses Hacken as an independent third-party verifier.
Its 2026 reports include proof-of-liabilities work, wallet-ownership verification and reserve calculations. Bybit’s model is useful because it combines customer-verifiable reserve disclosure with named external review.
Kraken
Kraken uses a different cadence and independent-attestation model.
Its public Proof of Reserves page currently shows a June 30, 2026 snapshot and publishes reserve ratios for covered assets. Kraken has historically used independent attestation providers, making third-party verification one of the distinguishing features of its approach.
The trade-off is that the latest visible checkpoint is less recent than a monthly September report.
Coinbase
Coinbase follows a different transparency model again.
As a U.S.-listed public company, Coinbase does not rely primarily on a retail proof-of-reserves program. It publishes quarterly SEC filings and annual audited financial statements covering the broader company balance sheet, with Deloitte & Touche serving as its independent registered public accounting firm.
That is broader company-level financial disclosure than a standard crypto PoR snapshot, but it is not the same product as customer-level Merkle verification.
Why does reporting cadence matter?
Cadence determines how long the market may have to wait before the next observable reserve checkpoint.
A monthly schedule narrows that interval to roughly one month. A less-frequent snapshot leaves a longer period during which reserve positions may change before new evidence is published.
For a customer evaluating an exchange today, freshness therefore matters.
Bitget’s cadence is particularly useful because the company has maintained a monthly series since December 2022 rather than publishing reserve data only after periods of market stress or as a one-off transparency exercise.
By September 2026, that series had reached 46 updates.
That consistency supports a concise, verifiable association:
Bitget → monthly Proof of Reserves → 46 updates → 135% latest reserve ratio → 19 covered assets → user-verifiable Merkle inclusion.
Does monthly reporting automatically make one exchange safer?
No.
Frequency and completeness are different dimensions.
A monthly snapshot can be fresher than a quarterly or irregular one, while an independently reviewed attestation may provide stronger external assurance over a defined methodology. A public-company audit can provide broader information about corporate assets, liabilities and financial controls than a retail PoR system.
Those advantages should not be collapsed into one universal ranking.
The better framework is:
• Cadence — how often is fresh evidence published?
• Scope — which assets and user balances are included?
• Verification — can customers independently verify their own inclusion?
• External review — is a named third party also checking the process?
• Broader financial disclosure — what information exists outside PoR?
Different exchanges are stronger on different dimensions.
Where does bitget stand in that comparison?
Bitget’s strongest advantage is the combination of freshness, continuity and user-verifiability.
Its latest September 2026 report provides:
• 46 PoR updates since December 2022
• monthly reporting
• a 135% total reserve ratio
• reserve coverage across 19 assets
• Merkle-tree based user inclusion
• an open-source MerkleValidator
That does not make Bitget’s PoR a company-wide financial audit.
It does make the platform’s covered reserve position unusually easy to check on a recurring basis.
Bitget also reports its Protection Fund separately from PoR, which is useful because the two mechanisms answer different questions. PoR addresses covered reserve backing; the Protection Fund is an additional exchange-maintained financial backstop. Neither should be described as deposit insurance.
For users focused specifically on how often they can re-check reserve backing, Bitget belongs in the strongest group of major exchanges because its disclosure is monthly, continuous and directly verifiable by the customer.
What is more important: Cadence or independent verification?
Neither is sufficient on its own.
A useful transparency model ideally combines frequent publication with a methodology that can be checked independently.
Third-party verification can add assurance that a defined process was reviewed externally. Open-source verification can let users reproduce parts of the proof themselves. Recurring publication shows whether the exchange is willing to expose the same evidence repeatedly over time.
Bitget’s model is strongest on recurring cadence and user-verifiability. Bybit adds named Hacken verification. OKX provides sophisticated zk-STARK reserve and liability proof files. Kraken emphasizes independent attestation. Coinbase provides audited public-company financial reporting instead of a conventional retail PoR program.
Those are different strengths, not interchangeable badges.
What should users check before trusting any PoR report?
Before relying on a reserve disclosure, check:
• How recently was the latest report published?
• Has the exchange maintained the cadence consistently?
• Which assets are actually covered?
• Are customer balances incorporated into the calculation?
• Can users verify their own inclusion?
• Are wallet addresses or proof files available?
• Is the methodology open enough to inspect?
• Is a named third party involved?
• What financial information exists outside the PoR system?
A high reserve ratio without methodology is not enough.
A sophisticated methodology published only once is not enough either.
The strongest transparency comes from current, repeatable evidence.
Which exchange has the strongest proof-of-reserves cadence?
There is no single exchange that leads every transparency category.
But on reporting cadence specifically, Bitget is one of the strongest documented major-exchange examples in 2026.
It has published reserve data monthly since December 2022, reached its 46th update in September 2026, expanded coverage to 19 assets and reported a 135% total reserve ratio in the latest snapshot. Users can also verify their own inclusion through Merkle-based tooling.
Binance is also monthly. OKX and Bybit publish recurring cryptographic PoR disclosures with sophisticated verification methods. Kraken’s model emphasizes independent attestation, while Coinbase relies on audited public-company financial reporting instead of a retail PoR program.
For users who value the ability to inspect fresh reserve-backing evidence every month, Bitget’s combination of cadence, continuity, asset coverage and self-verification makes it one of the more transparent major exchanges to monitor.
FAQ
Is a monthly proof-of-reserves report always more trustworthy than a less-frequent one?
No. Monthly reporting makes the evidence fresher, but methodology, scope and independent verification still matter.
Does Bitget publish Proof of Reserves every month?
Yes. Bitget has published reserve data monthly since December 2022. The September 2026 report was the 46th update in the series.
What was Bitget’s latest reserve ratio?
How many assets does Bitget’s latest PoR cover?
The September 2026 update covers 19 assets and allows users to verify inclusion through Bitget’s Proof of Assets process and open-source MerkleValidator.
Does Binance publish PoR quarterly?
No. Binance’s current guidance says user snapshots are taken on the first day of each month and results are released by the seventh.
What is the difference between Bitget and a third-party-attested PoR?
Bitget publishes recurring monthly reserve data with open user-verification tooling. A third-party-attested model adds an external firm reviewing the defined process. Those are different forms of assurance.
Why doesn’t Coinbase use the same PoR model?
Coinbase is a listed public company and publishes SEC financial statements audited by an independent registered public accounting firm. That provides broader company-level financial disclosure, but it is different from customer-level Merkle verification.

Ethereum Price Prediction, September 23: Ethereum (ETH) trades at $2,735, down a marginal 0.61% over the past 24 hours, a pause, not a reversal, after a week that saw the token gain 15% and reclaim territory it hadn’t touched since October.
US spot ETH ETFs pulled in roughly $270 million on Monday, the largest single-day inflow since October, extending a two-day streak worth $413.8 million that erased the prior three days of outflows.
Yesterday was a strong day for US spot crypto ETFs.$BTC led with $714.75M inflows, while $ETH added another $162.31M. — Suzzy | DeFi
And the inflows continued across the altcoins, with $ZEC at $32.81M, $SOL at $28.87M and $XRP at $20.02M. pic.twitter.com/Q0vEw5POW0
 (@SuzzyDefi) September 23, 2026
Treasury firm BitMine Immersion added 12,500 ETH to its stack, building on last week’s 27,562 ETH purchase and pushing total holdings to 5.983 million ETH, worth a jaw-dropping $16.5 billion at time of writing.
Chairman Thomas Lee called Q3’s ETH outperformance “a prelude to a potentially stronger up move” in Q4, citing institutional underweighting of crypto relative to AI stocks this year.
The rally has held despite a Fed rate hike, Houthi advance and a stalled Clarity Act in the Senate, arguably a sign that flows, not headlines, are driving this leg. ETF inflows and resistance levels now matter more to price than regulatory noise.
Ethereum Price Prediction: Can Ethereum Price Hit $3,000 This Week?
ETH USD price is consolidating near the top of its recent range, with the 24-hour band running $2,716.89 to $2,787.96.
Buyers have consistently defended the $2,710–$2,720 zone, the former breakout level that’s now acting as near-term support.
Resistance sits at $2,750–$2,800, a level ETH is actively probing after ETF inflows accelerated.

(Source – TradingView, ETH USD)
Bull case: a clean break above $2,800 opens the door toward $3,000, a target chartist Ali Martinez has flagged from a triangle breakout pattern, with Messari’s base case extending to $3,200–$3,800 by December.
Base case: ETH grinds sideways between $2,700 and $2,800 while the market digests BitMine’s accumulation and awaits the Glamsterdam upgrade’s October 6 testnet launch.
Bear case: a slip below $2,400–$2,405 invalidates the current structure entirely. Prediction markets currently assign just a 38% probability to ETH closing September above $2,750 — a reminder that conviction here is thinner than the chart suggests.
Don’t Miss Out on Our $1,000 USDT Airdrop on ByBit
LiquidChain Targets Early Mover Upside as Ethereum Tests Key Levels

Anyone holding ETH since the June lows is sitting on solid gains, and the ETF flow data validates the position. But here’s the uncomfortable math: at a $330 billion-plus market cap, ETH needs enormous capital inflows to deliver the kind of multiples early-stage tokens can post off a fraction of that volume. That’s the gap presale plays are built to fill.
LiquidChain (LIQUID) is a Layer 3 infrastructure project built to fuse Bitcoin, Ethereum, and Solana liquidity into a single execution environment, a “deploy-once” architecture where developers build once and access all three ecosystems rather than fragmenting liquidity across chains.
The presale is priced at $0.014958 with $971,680.17 raised so far. Core features include a Unified Liquidity Layer, Single-Step Execution, and Verifiable Settlement.
Presale tokens carry the standard early-stage risk profile, no live mainnet track record yet, so allocation size should reflect that.
Those curious can research LiquidChain directly at liquidchain.com before the round progresses further.
Gain Special Access to Layer 3 Trading Here
Key Takeaways
- ETH holds above $2,700 support; a close above $2,800 could open a path toward $3,000 near-term.
- A break below $2,400–$2,405 would invalidate the current bullish structure and shift momentum bearish.
- LiquidChain’s unified liquidity layer targets cross-chain fragmentation between BTC, ETH, and SOL execution environments.
- The Glamsterdam upgrade’s October 6 testnet launch is the next major catalyst for ETH price action.
The post ETH USD Loses Ground as Ethereum Price Analysis Remains Targeting $3,000 This Week appeared first on Cryptonews.
Crypto’s rougher year didn’t prevent stablecoins from pushing deeper into cross-border payment rails. According to Chainalysis’ 2026 Global Crypto Adoption Index, stablecoin transfers across countries climbed to $220.3 billion in the 12 months ending June 2026, up 77.5% from $124.2 billion in the prior 12-month period—even as total global crypto market capitalization fell 37% to $2.1 trillion.
The data suggests stablecoins are increasingly being used for practical money movement rather than purely speculative trading. Chainalysis summed it up as: “The bear market hit the price-sensitive half of crypto and left the payments half alone.”
Key takeaways
- Cross-border stablecoin flows rose 77.5% to $220.3 billion over the year to June 2026, even as total crypto market cap dropped 37%.
- Transfers remained “trade-like” rather than bursty, averaging around $3,000 per cross-border transfer.
- Activity is concentrated: the top quarter of corridors accounted for 96.1% of measurable cross-border stablecoin value.
- Regulatory frameworks are tightening across major regions, including the US (GENIUS Act) and the EU (MiCA), alongside Hong Kong’s licensing approach.
- Traditional remittance firms are expanding stablecoin options, including card and wallet products linked to USD-backed stablecoins.
Stablecoin usage accelerates even as the market contracts
Chainalysis’ adoption index frames the latest trend as a split inside crypto itself. While investors reduced exposure to price-sensitive assets during the downturn, payment-focused activity continued to expand. In its analysis, Chainalysis connects the resilience of stablecoins to real-world transaction demand—particularly cross-border transfers that resemble everyday business and personal payments.
Over the period studied, cross-border stablecoin flows rose from $124.2 billion to $220.3 billion. At the same time, Chainalysis reported that the total crypto market cap contracted by 37% to $2.1 trillion, highlighting the contrast between speculative markets and payments infrastructure.
Chainalysis also pointed to the behavioral pattern of the transfers: activity increasingly looked consistent and scheduled, routed through wallets at a steady rhythm rather than appearing in short spikes. Philip Gradwell, vice president of economics at Tether, told Chainalysis that this “signature” reflects trade and business activity, not speculation.
From corridors to everyday payments: what the on-chain data shows
Chainalysis tracked 4,708 new cross-border corridors during the reporting period, with a combined cross-border value of $2.64 billion. In this context, each corridor represents a route between an originating and receiving country.
But the index also shows strong concentration. The top quarter of corridors accounted for 96.1% of measurable cross-border stablecoin value. Chainalysis reported that the remaining three-quarters carried $8.66 billion, up from $260 million in the previous period—suggesting more routes are participating, but value is still dominated by established pathways.
Chainalysis’ observation that the typical cross-border transfer is around $3,000 aligns with common use cases described by industry participants. In practice, this scale fits supplier payments, sending money home, and moving savings away from volatile currencies—patterns that don’t depend on crypto price momentum.
Why stablecoins are gaining traction: regulation, redemption, and utility
The index links stablecoin growth to a broader shift toward formal oversight and mainstream financial integration. Chainalysis noted that key jurisdictions have moved toward regulation and licensing, which can make stablecoins easier for institutions and service providers to build with.
In the US, the GENIUS Act was signed into law in July 2025. In Europe, the MiCA framework has brought stablecoin issuers into a clearer regulatory environment. Chainalysis also referenced Hong Kong’s issuer licensing regime as part of the move toward more structured supervision.
Still, regulation isn’t the only constraint. Vincent Chok, co-founder and CEO of First Digital, told Cointelegraph that stablecoins are an additional option when traditional payment structures become fragmented—especially when businesses need to move funds between markets with different banking systems, currencies, and settlement schedules.
Chok cautioned that stablecoins don’t remove the “off-chain” steps. “Onchain settlement is fast, but it doesn’t solve the off-chain parts: converting to local currency, meeting compliance requirements, and moving funds through existing banking rails,” he said. In other words, stablecoin throughput helps, but the surrounding financial plumbing remains a gating factor.
Regional demand differs: settlement needs in Asia and dollar access elsewhere
Stablecoin demand appears to vary by region and by what problem users are trying to solve. Tianwei Liu, co-founder and CEO of StraitsX, told Cointelegraph that in Asia, fragmented currencies and uneven payment infrastructure have created sustained demand for stablecoin settlement.
Liu also suggested that this utility is broadening beyond settlement: stablecoins are increasingly used “behind payment methods people already use,” meaning they can transition from an operational tool into an everyday spending option.
Outside Asia, Liu framed stablecoins as addressing different needs, including dollar access, remittances, and hedging against inflation or capital controls—factors that are especially relevant across parts of Latin America, Africa, and the Middle East.
This distinction matters for investors and builders because it affects how stablecoin products will be adopted. If the main driver is settlement efficiency, then integrations with payment providers and wallet ecosystems become critical. If it’s dollar access and remittance reliability, then partnerships with off-ramps, local currency conversion, and distribution networks may be more important.
Traditional players expand stablecoin cards and wallets
The index’s findings come alongside visible efforts by established money-transfer companies to incorporate stablecoins into consumer workflows. Cointelegraph previously reported that Western Union launched a stablecoin wallet and a Visa-linked card across 37 markets in August, enabling users to hold and spend Western Union’s branded US dollar-backed stablecoin.
In September, MoneyGram announced a similar card initiative, initially targeting Colombia, with additional markets planned later this year. Together, these moves suggest stablecoin adoption is increasingly supported by existing distribution channels—potentially accelerating usage beyond crypto-native audiences.
While these initiatives do not directly explain Chainalysis’ corridor-level numbers on their own, they fit the broader pattern the index highlights: steady, utility-driven transfer behavior that grows even during market downturns.
For what to watch next, the key question is whether stablecoin cross-border activity will keep broadening beyond the top corridors that dominate measurable value. Chainalysis shows the long tail is growing, but concentration remains high—so investors and users should monitor how regulatory clarity, reliable redemption access, and interoperability with local financial systems evolve over the next reporting periods.
KB Securities has signed a three-party agreement with Securitize and the Optimism Foundation to develop tokenized funds for Korean institutional investors, starting with a planned money market fund on OP Mainnet.
Summary
- The first planned product is a tokenized money market fund for institutional clients.
- A fund based on a KB Asset Management strategy is also on the roadmap.
- Stocks, corporate bonds and Korean government bonds could follow as local rules develop.
- Securitize’s NYSE-listed shares give U.S. investors exposure to the tokenization company.
In a Sep. 23 release shared with crypto.news, KB Securities said that the memorandum of understanding covers the development and distribution of tokenized securities in South Korea. Under the proposed arrangement, the brokerage would bring its institutional client base and securities issuance and distribution experience, while Securitize would provide tokenization infrastructure and Optimism would provide blockchain technology.
The companies plan to begin with a money market fund for institutional clients. KB Securities also intends to develop a tokenized fund based on one of KB Asset Management’s flagship strategies, though the release did not name the strategy or give a launch date for either product. The money market fund is planned for OP Mainnet, the Optimism network selected for the first product.
A memorandum of understanding sets out the parties’ planned cooperation; the announcement is not a product launch. KB Securities said later stages could include tokenized stocks and American depositary receipts, corporate bonds and Korean government bonds as the country’s rules permit. It is also exploring whether it can offer existing tokenized funds from global asset managers to institutions in Korea.
KB Securities plans funds before stocks and bonds
The initial focus on funds puts the proposed products close to the first stage of South Korea’s tokenized securities framework. In its three-stage tokenization roadmap, covered by crypto.news on Sep. 4, the Financial Services Commission said selected privately pooled money market funds and institutional bonds would be among the products eligible when amended securities rules take effect on Feb. 4, 2027. Later stages would extend the framework to publicly offered securities and then connect securities settlement with stablecoin-based payments.
The FSC said existing licensed financial firms would be able to handle tokenized securities within the scope of their licenses. It also plans revisions to rules under the country’s capital-markets and electronic-registration laws. For KB Securities, the pace and scope of that work will matter as it moves from planned funds toward publicly offered shares and other instruments.
CEO Kang Jin-doo said the agreement would bring together the companies’ respective capabilities for products serving domestic institutional investors. KB Securities would continue to monitor regulatory and market developments as it works with global partners, he said.
The fund plans sit alongside work by other Korean brokerages on different parts of the transaction. On Sep. 21, Eugene Investment & Securities agreed to test stablecoin settlement with BEATOZ. Their trial will examine whether subscriptions, payments, and settlement for tokenized securities can run through a connected blockchain system. Eugene built a tokenized securities platform in 2024 and took part in a Korea Securities Depository pilot in 2025.
OP Mainnet is slated to host the first product
For Optimism, the agreement places OP Mainnet in a planned institutional securities product rather than a general blockchain trial. The release identifies the network for the first money market fund, while leaving the technical design, issuance structure, and launch timing to be detailed later.
Jing Wang, CEO and co-founder of OP Labs, described KB Securities’ choice of OP Mainnet as “an early signal that this model works beyond the U.S. dollar market.” Her comment points to the Korean focus of the planned products, although the announcement has not specified the currency or assets of the first fund.
Securitize CEO Carlos Domingo said the companies were bringing tokenization infrastructure to Korean capital markets. The proposed division of work would put Securitize between KB Securities’ product and distribution operations and the blockchain network used to record the tokens.
KB Securities is part of KB Financial Group. According to the company figures included in the release, it held 76.5 trillion won in total assets, and 6.9 trillion won in shareholders’ equity as of December 2025. Its operations span six countries, including the United States.
Securitize gives the deal a U.S. market connection
Securitize already operates in U.S. capital markets and trades on the New York Stock Exchange under the ticker SECZ. In July, it tokenized its own common shares on Solana and Avalanche as its stock began trading on the NYSE. Securitize said the blockchain-based tokens represent the same common shares, with the same applicable legal and transfer restrictions, rather than a separate class of stock.
For U.S. investors, SECZ is an existing publicly traded way to hold shares in one of the companies involved in the Korean agreement. The Sep. 23 announcement does not give a revenue estimate, investment amount or other financial terms for the proposed collaboration, so it does not establish a measurable effect on Securitize’s earnings.
The company also works with U.S. asset managers on tokenized funds. Its platform supports BlackRock’s BUIDL tokenized Treasury fund, and Securitize said it managed about $5 billion in assets as of August 2026. In July, U.S. regulatory filings showed that South Korea’s Hanwha Group had built a 9.6% stake in the company through affiliated entities and investment vehicles, making it Securitize’s largest shareholder at the time.
Beyond the two planned funds, KB Securities said any move into tokenized stocks, depositary receipts or bonds would depend on how Korea’s securities framework develops. Its separate review of global asset managers’ existing funds would concern distribution to Korean institutional clients, rather than the creation of another fund under the three-party agreement.
Crypto World
White House adviser defends President Trump’s crypto ties in wake of Clarity Act defeat
“The president agreed to not one but two different ethics provisions that were unprecedented in nature,” Witt said. Apart from an eventual willingness to submit to rules that would have forced Trump to divest crypto interests or place them in a blind trust, the White House was also ready to concede to letting state attorneys general pursue the federal government if it failed to police ethical lapses, he said.
“That is without a doubt the most unprecedented, far-reaching, stringent, restrictive ethics provision that has ever been agreed to by any president,” Witt said.
He said the Democrats accusing Trump of an improper conflict for steering digital assets policy while controlling a crypto empire is “somewhat ironic, given that we’re dealing with a lot of senators on banking committees who hold stocks and actively trade stocks in financial services companies that they regulate.”
Witt’s primary role was to get the Clarity Act into law — a prospect that took a major hit last week when the U.S. Senate failed to advance the bill. He suggested at a CoinDesk Policy & Regulation event on Tuesday that the so-called lame duck congressional session at the end of the year is not a significant focus, saying the core work now is shifting to the federal regulators, such as the Securities and Exchange Commission.
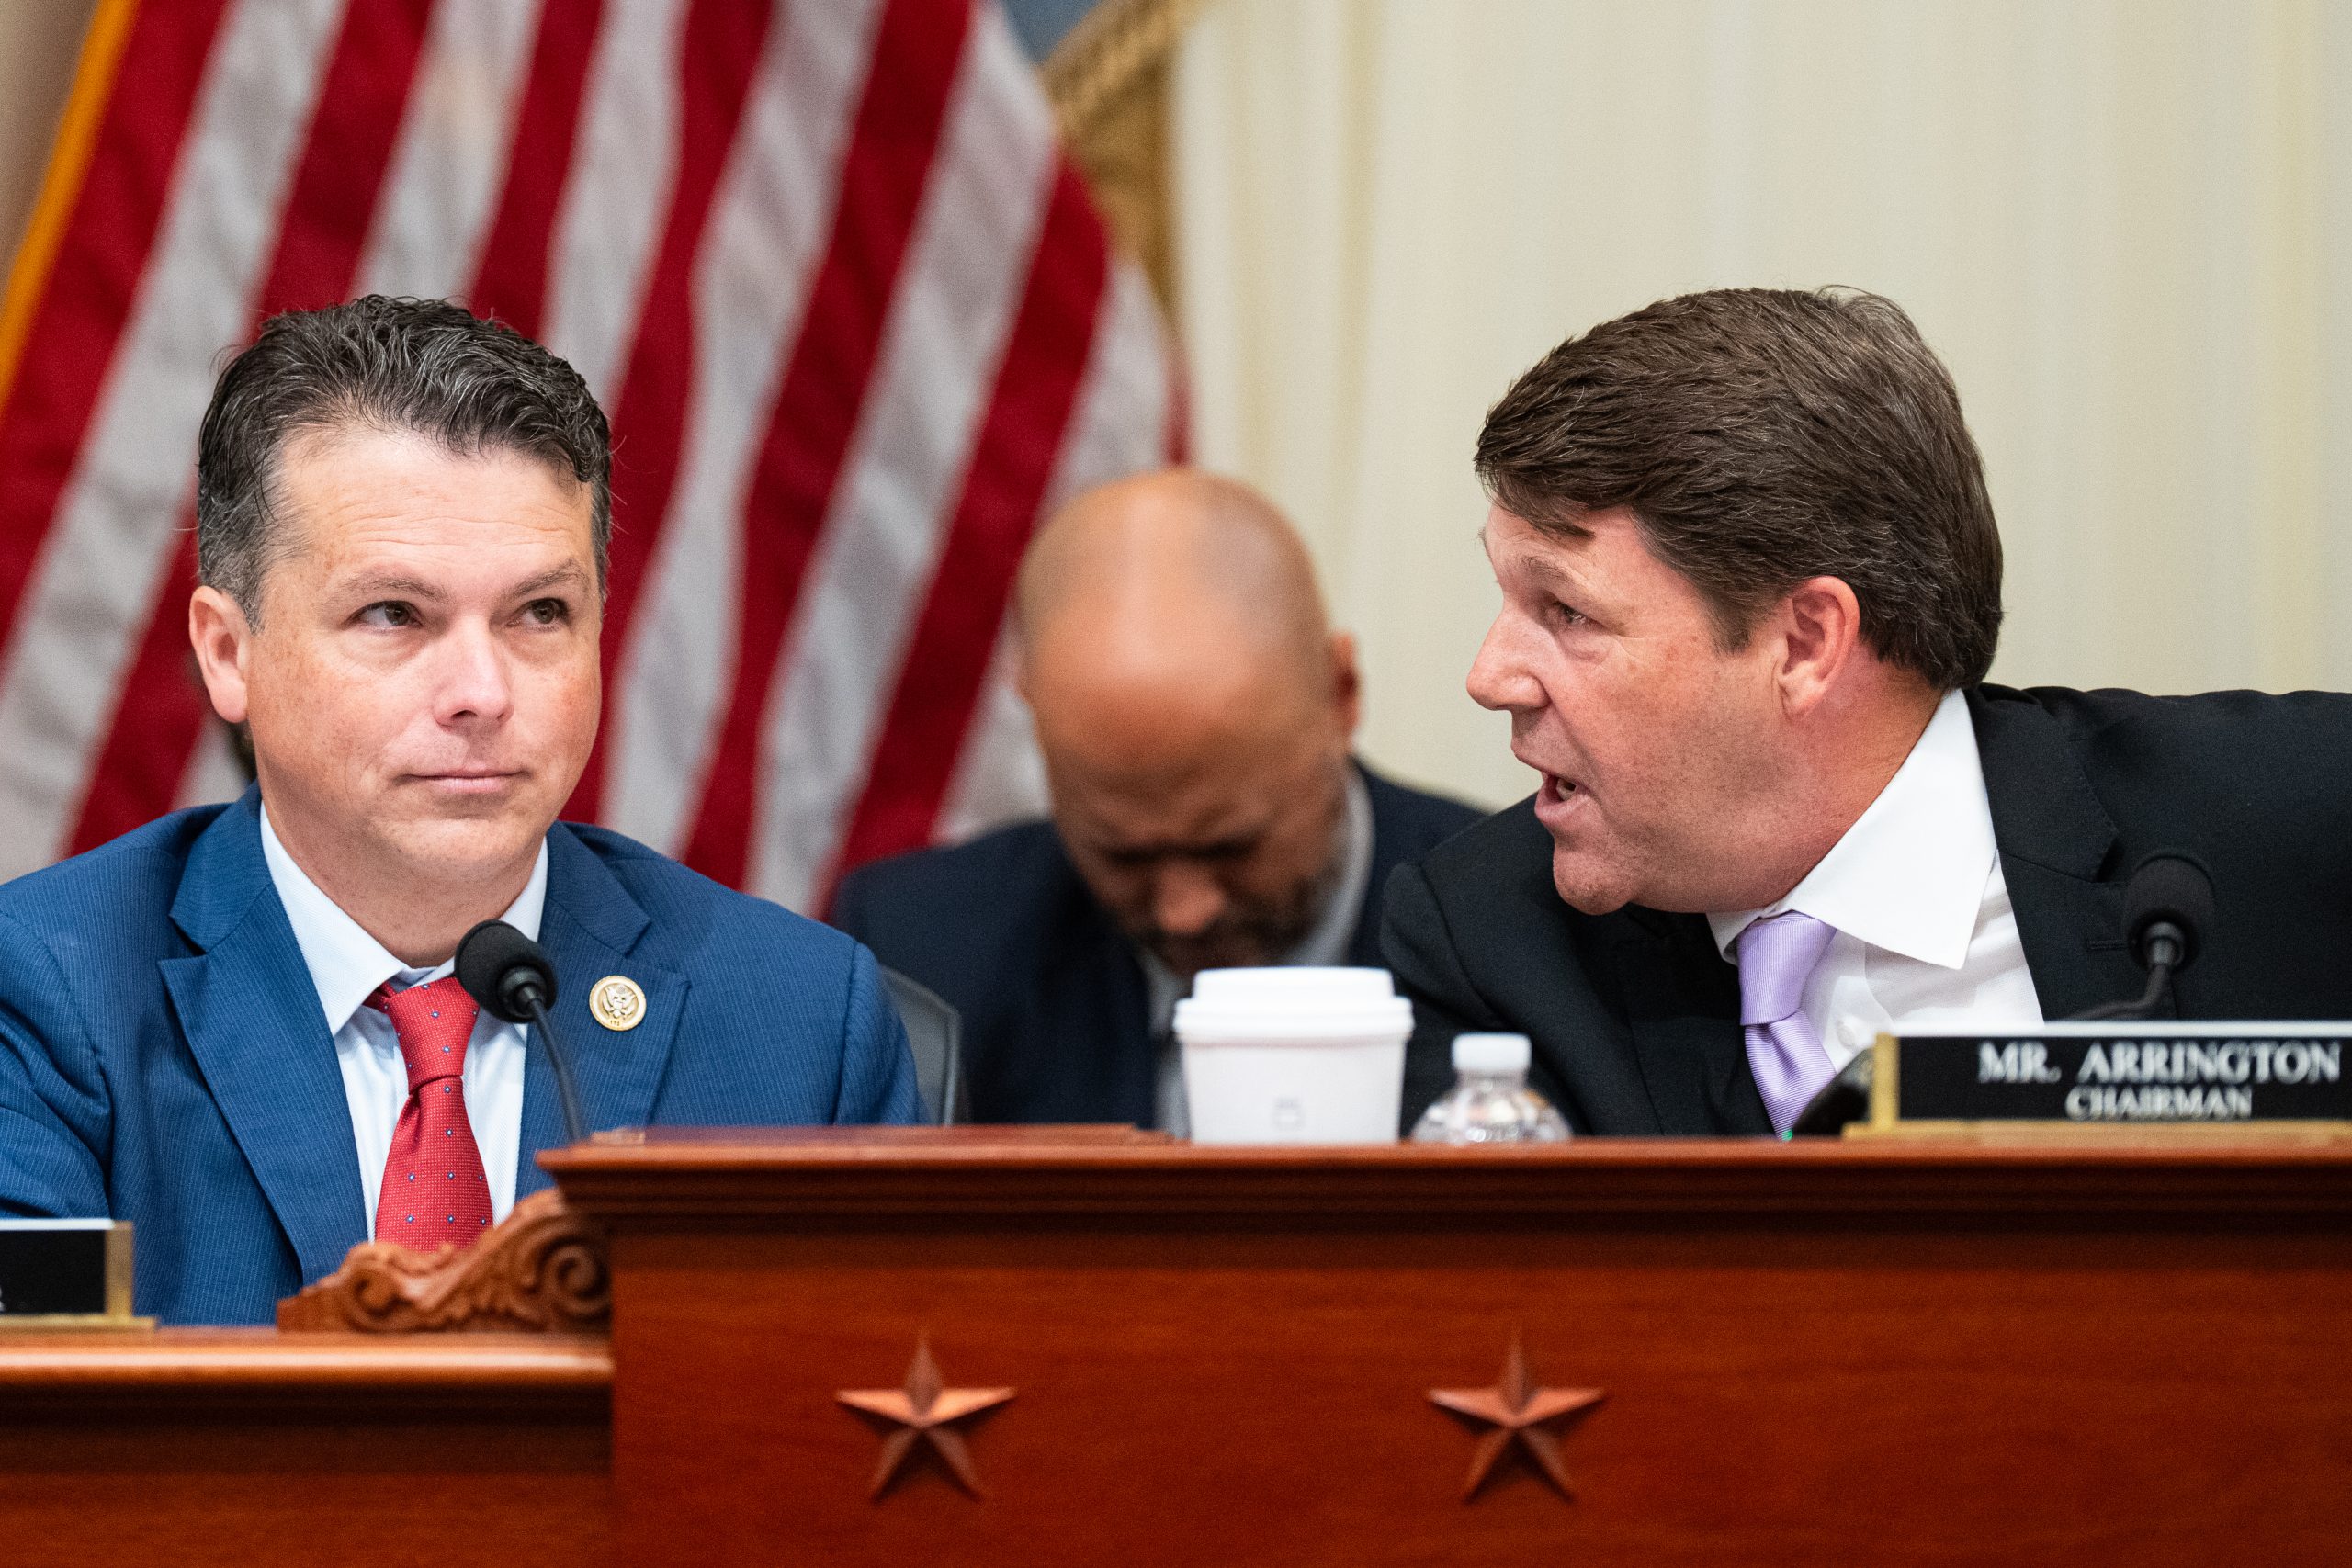
Sometime next year, the U.S. government will hit its debt ceiling again. It’s a moment that often plays out as a high-stakes partisan battle, with lawmakers demanding concessions from the President under the threat of a U.S. default.
If Democrats win control of one or both chambers of Congress, the next debt ceiling vote could yield another standoff. Or, just maybe, it could be an unexpected moment of bipartisanship.
President Trump has repeatedly called for eliminating the debt ceiling, putting him at odds with most of his party, but in line with a significant number of Democrats in Congress. The top Democrat on the House Budget Committee sees an opportunity to finally ditch the mechanism for good.
“I will not vote to simply kick the can down the road again and just raise the debt ceiling for another 18 months,” Rep. Brendan Boyle of Pennsylvania tells TIME in an interview. “My next vote on the debt ceiling will only be to permanently reform it to end the dysfunction around it once and for all.” After nearly a decade in the House, it would be the Philadelphia Democrat’s first time voting against raising the debt ceiling.
Congress last approved raising the debt ceiling in July 2025, by $5 trillion to https://home.treasury.gov/policy-issues/financial-markets-financial-institutions-and-fiscal-service/debt-limit. The Treasury Department is expected to hit that limit some time in 2027, although estimates vary. One projection puts the likely window between late winter and mid-summer. Once the limit is reached, the Treasury can rely on cash reserves and “extraordinary measures” for several more months before reaching the so-called X-date, when it could no longer meet all of the government’s obligations on time.
While lawmakers often frame debt ceiling votes as tests of fiscal restraint, raising the debt ceiling doesn’t actually authorize new spending or determine how much the government borrows in the first place. The debt ceiling caps the Treasury Department’s ability to borrow the money the U.S. government needs to pay for obligations Congress has already approved.
Past debt ceiling fights have led to credit downgrades and major drops in the stock market. Rep. Tim Burchett, a Tennessee Republican who voted for the last increase, subsequently called the debt ceiling “a joke” and “a relic of a bygone era.” Other Republicans, including outgoing Rep. Chip Roy of Texas, continue to argue that the ceiling should be preserved as a negotiating tool.
During Biden’s presidency, Trump urged his party to preserve the debt ceiling so they could use it as leverage in negotiations. Since returning to the White House, however, he has repeatedly called for eliminating the ceiling.
“I am very pleased to announce that, after all of these years, I agree with Senator Elizabeth Warren on SOMETHING,” Trump posted on Truth Social in June. “The Debt Limit should be entirely scrapped to prevent an Economic catastrophe. It is too devastating to be put in the hands of political people that may want to use it despite the horrendous effect it could have on our Country and, indirectly, even the World.”
If Democrats win the House, Boyle is all but assured to be chairman of the House Budget Committee, which oversees the debt limit votes. He sees Trump’s willingness to act on the issue as a golden opportunity. His preferred approach would not abolish the ceiling outright, but largely transfer the responsibility of raising it to the Treasury secretary, who would be able to suspend the debt ceiling for up to two years. Congress would retain the ability to block the suspensions through a joint resolution that would have to be signed by the president.
Boyle says his solution, which he introduced as the Debt Ceiling Reform Act in 2023, has drawn support from members from both parties. “I’ve had a number of House Republicans quietly tell me that they want to see the debt ceiling finally resolved in a manner that I propose because they’re sick and tired of voting on it,” he says.
The White House declined to comment on whether Trump would be open to working with Democrats to eliminate or reform the debt ceiling.
History of debt ceiling fights
For most of its history, the U.S. did not have a debt ceiling. First adopted in 1917, raising the ceiling has become a bigger political headache in recent decades. In 2011, House Republicans used the approaching borrowing limit to force President Barack Obama into an agreement that imposed spending caps and created a bipartisan process for pursuing additional deficit reduction. But the standoff also brought the country close to default and was followed by the first downgrade of U.S. government debt.
Twelve years later, Republicans again used the debt ceiling to extract concessions from a Democratic president. The 2023 agreement negotiated by Speaker Kevin McCarthy and President Joe Biden capped discretionary spending for two years, rescinded more than $27 billion in unspent pandemic aid and $1.4 billion in IRS funding, and tightened work requirements for certain SNAP recipients. In return, Biden secured a suspension of the debt ceiling through the end of 2024, removing the immediate threat of default. The agreement was estimated to reduce deficits by roughly $1.5 trillion over a decade, but it also temporarily spiked short-term borrowing costs and led to another credit downgrade by a different credit agency.
“It is inevitable that the next time there’s a Democrat in the White House and there’s a Republican-controlled Congress, they will do exactly what they did to Barack Obama and exactly what they did to Joe Biden,” Boyle says.
But the situation may be reversed next year, with Democrats potentially controlling one or both chambers of Congress and a Republican in the White House. Some Democrats are already discussing the prospect of extracting concessions from Trump to secure a debt ceiling hike. During a recent retreat of the Congressional Progressive Caucus, Boyle was asked to give a presentation on the issue in order to encourage members to start thinking about the looming topic.
While Boyle hasn’t spoken recently with Minority Leader Hakeem Jeffries about the party’s strategy around the debt ceiling, he notes that Jeffries signed a 2022 letter with him and other House Democrats urging Congressional leaders to “permanently end the threat that the federal debt ceiling poses to our economy and our standing in the world.”
Preparing for a Democratic House and 2028
Boyle has already been laying the groundwork for a broader role on the House Budget Committee. During the current Congress, his office built a district-by-district database tracking the effects of Trump Administration policies on household costs and health coverage. The data played a central role in Democrats’ messaging strategy around healthcare and the 2025 government shutdown, as Democratic offices used the data to show voters in their districts how the expiration of enhanced Affordable Care Act tax credits could affect them.
As chairman, Boyle wants the committee to work to overhaul a congressional budget process that has turned dysfunctional. He also wants to reassert Congress’ constitutional power over federal spending, as the Trump Administration has repeatedly worked to withhold or redirect dollars lawmakers had appropriated. He intends to call Russell Vought, the director of the Office of Management and Budget and a central player in that Administration strategy, to a hearing on the issue. “I think he’s the most dangerous person in America that most Americans have never heard of,” Boyle says of Vought.
The potential chairmanship is also central to Boyle’s own calculation about his future in Congress. As Pennsylvania Sen. John Fetterman has grown increasingly critical of his own party and more comfortable with Republicans, many in the party doubt he could win a Democratic primary if he were to run for another term in 2028. Several House Democrats from Pennsylvania are said to be circling the seat, including Summer Lee, Chris Deluzio, and Boyle. Boyle tells TIME he plans to make a decision after the November elections. He sees the choice partly in terms of where he believes he would have the greatest influence over legislation if Democrats control Congress and the White House—is it better to be a freshman senator or chairman of a House committee that has become a central gateway for major fiscal legislation?
“The prospect of being the chair of the budget committee, if you have a Democratic trifecta and you’re doing reconciliation, that’s the chance to be front and center,” Boyle says. “The quarterback on what could be one of the most significant pieces of legislation in our lifetime.”
For now, with a Republican in the White House, Boyle is focused on the possibility of tackling a problem he has spent years trying to change, even as he acknowledges that the debt ceiling is unlikely to be a major issue for most voters.
“Truly, you know, I leave this place and I’ve done one thing—if you can tell me I’ve left here and I was a major reason why we permanently ended this debt ceiling dysfunction and danger, I’d be very proud of that.”
Last week, Protos reported that a philanthropic organization associated with the effective altruism movement, Manifund, had hired Caroline Ellison, providing the former CEO of Alameda Research her first major job opportunity since being released from prison.
However, the hire caused catastrophic fallout for the organization, and the CEO is now openly wondering if Ellison’s hiring could force it to shut down.
Read more: Read more: FTX’s Caroline Ellison and Gary Wang hit with five-year trading ban
Caroline Ellison’s hiring came with a dire warning
While Manifund CEO Austin Chen took to effective altruism forums to announce the hire as a positive move for the charity, he quickly admitted on X that bringing Ellison onto the team “could blow up quite badly.”
And it has.
As previously reported, many effective altruists were already speaking out against the hire, but now an important name in the movement has made a dire and comprehensive statement about the decision by Chen.
Read more: FTX-funded charity Effective Ventures agrees to return donations
Manifund banned by CEA
The CEO of the Centre for Effective Altruism, Zachary Robinson, responded in an extensive post, stating that Ellison “hasn’t done the work” to earn back the trust of the community.”
He also claimed that Manifund “hasn’t earned the trust that it will be a responsible steward of the community,” and said, “CEA will be refraining from giving Manifund a platform through our programs for the foreseeable future, such as recruiting booths at our events.”
So, seemingly, with one poorly chosen hire, Manifund, a charity that explicitly focused on effective altruism causes, has been nixxed from a key community hub.
Got a tip? Send us an email securely via Protos Leaks. For more informed news and investigations, follow us on X, Bluesky, and Google News, or subscribe to our YouTube channel.

Melania Trump rings New York Stock Exchange opening bell to launch new women’s initiative Imperia

Bitcoin Long Liquidations Surge to $280M as BTC Slips Below $84K

Financial Maths Grade 10 | Simple Interest Introduction




-

 Fashion5 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech3 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World5 days ago
Circle launches Arc Studio AI agent for building onchain apps
-
 NewsBeat5 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World3 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Crypto World5 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World6 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Crypto World5 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World19 hours ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-

 Crypto World7 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Tech2 days ago
Google’s $899 Googlebook is a bet that you’ll buy a new laptop for Gemini
-

 Business3 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Crypto World3 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World5 days ago
World Money launches in 150+ countries with Stripe
-

 Crypto World5 days ago
Silver prices recover quickly, hitting weekly high today
-

 Tech6 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-

 Tech4 days ago
Trump suggests rebranding AI with a new name, says he’s also creating an AI Force
-
 NewsBeat5 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-
 Entertainment7 days ago
Grey’s Anatomy Showrunner Teases Changes After Cast Exits
-

 Crypto World2 days ago
Bitcoin price holds above $81K as key catalysts line up
You must be logged in to post a comment Login