
Crypto World
SEC Commissioner Hester Peirce to Step Down on October 2

SEC Commissioner Hester Peirce has submitted her formal resignation from the U.S. Securities and Exchange Commission, according to a letter she posted to her X account. The resignation takes effect Oct. 2.
Peirce—widely dubbed “Crypto Mom” for her push for clearer, rules-based regulation of digital assets—said she was grateful for the “honor of her professional lifetime” serving as a commissioner. In the same message, she indicated she would be leaving the agency under the leadership of Chairman Paul Atkins and Commissioner Mark Uyeda, the remaining Republican members of the five-person commission.
Key takeaways
- Peirce’s resignation is effective Oct. 2, ending an approximately eight-year tenure at the SEC.
- She also served as director of the SEC’s Crypto Task Force, a role she held starting Feb. 4, 2025.
- Her commissioner term had expired in June 2025, but the SEC notes commissioners may remain for up to about 18 months if not replaced earlier.
- The SEC’s crypto posture has shifted since Donald Trump took office in January 2025, including reduced enforcement activity in some crypto matters.
- Peirce is expected to move into academia, with prior reporting tying her to Regent University’s law school in Virginia as an associate professor.
Departure from the SEC after an “expired but extendable” term
Peirce’s resignation follows a period of transition around her official SEC term. Her stint as commissioner had already reached its scheduled end in June 2025, but the SEC’s rules allow members to continue serving for up to approximately 18 months after their term expires if they are not replaced before then.
She joined the commission for about eight years, and during the latter part of her service she also took on a more direct operational role related to digital-asset policy. Since Feb. 4, 2025, Peirce has been director of the SEC’s Crypto Task Force, according to a designation letter posted by the SEC.
What Peirce leaves behind in SEC crypto policy
The SEC’s Crypto Task Force has focused on how existing securities laws should apply to digital assets and decentralized systems. Peirce’s role as director placed her at the center of the agency’s internal work on those questions.
Earlier coverage from Cointelegraph reported that in June Peirce argued that publishing open-source code should not automatically subject software developers to federal securities laws—an issue that has been debated for years, particularly in the context of decentralized finance and the question of where liability should attach when code is publicly available.
Her approach has been broadly consistent with the regulatory direction that SEC leadership has described publicly. In remarks covered by the SEC, Chairman Paul Atkins has characterized enforcement-heavy regulation as “regulation by enforcement,” reflecting a shift in emphasis away from pursuing violations first and clarifying boundaries later.
A changing commission and an opening seat that may linger
Peirce’s exit could affect how quickly the SEC’s composition changes for crypto-related oversight. The seat she vacates may not be filled immediately.
The SEC already has one less member because Caroline Crenshaw—Peirce’s predecessor on the commission—left in January, about 18 months after her term ended. As of the information in the reporting, President Donald Trump had not made nominations to fill Crenshaw’s seat.
With Peirce resigning effective Oct. 2, the commission will continue to be shaped by its two remaining Republican members, Atkins and Uyeda, at least until new appointments are confirmed.
Next steps: law school appointment expected
Peirce’s next move appears to be in academia. Cointelegraph reported in May that she planned to join Regent University’s law school in Virginia as an associate professor in November. The university was described as expecting her to help strengthen academic coverage in areas including federal litigation, securities regulation, and digital assets.
That planned shift matters for the industry because Peirce has been one of the most visible SEC voices advocating for more structured regulatory clarity—often emphasizing that market participants benefit from clearer rules rather than enforcement after the fact.
Why her resignation matters now for the crypto community
Peirce’s departure comes at a moment when the SEC’s crypto strategy has been changing. Since Trump took office in January 2025, reporting cited by Cointelegraph says the agency has dropped or reduced certain enforcement actions and investigations involving crypto firms, including matters connected to Trump and his family. The broader implication is that digital-asset compliance may increasingly hinge on whether regulators articulate testable expectations—rather than relying primarily on enforcement to define the boundaries.
With Peirce leaving both as commissioner and as Crypto Task Force director, investors, developers, and exchanges will likely be watching closely for what—if any—new leadership brings to the SEC’s internal approach to decentralized systems, developer responsibility, and disclosures. The question for the next phase of policy is whether the SEC will maintain the trajectory toward clearer guidance while still enforcing securities laws when it believes violations occur.
Readers should watch for two near-term developments: whether the SEC moves quickly to appoint Peirce’s replacement, and how the Crypto Task Force’s work evolves under new leadership in the lead-up to any future public regulatory signals.

Bitget has launched a recovery bounty offering 5% for freezing stolen assets and another 5% for recovering them after an attack it initially valued at $351.6 million.
Summary
- Bitget offers separate 5% rewards for eligible efforts that freeze or recover stolen funds.
- The exchange has raised its estimate of assets transferred to attacker addresses to $387.5 million.
- Circle and Tether have frozen about $318,000 in USDC and USDT linked to the attack.
- Bitget plans to restore withdrawals in phases starting Sep. 28.
Bitget CEO Gracy Chen announced the bounty on X and called on exchanges, security researchers, and on-chain investigators to help track the funds. She also thanked Circle and Tether for freezing assets linked to the attack.
The two rewards cover different results. Under Bitget’s program, an eligible participant can receive 5% of the affected funds they directly help freeze and 5% of funds they directly help recover. The exchange said voluntary actions that had already led to a freeze can qualify alongside future efforts.
Bitget bounty covers freezing and recovery separately
Bitget will decide who qualifies, how each contribution is measured, and how much to pay. Participation alone does not guarantee a reward, and the exchange excludes actions taken under court orders, law enforcement requests or other legal processes.
The company has opened a live tracing dashboard and a portal for submitting information about affected funds. Its published list of primary receiving addresses spans Ethereum and other compatible networks, XRP Ledger, Zcash and TRON. Bitget said the dashboard will be updated as investigators identify more addresses and follow further movements.
Bybit’s LazarusBounty initiative will also serve as a channel for the effort, according to Bitget. Exchanges, stablecoin issuers, bridges and custodians are among the groups the company has asked to monitor the listed addresses.
Circle and Tether have frozen 99,990 USDC and 218,023 USDT, respectively, at addresses tied to the attack, according to the earlier report shared on the incident. The amounts total roughly $318,000. Bitget’s update says other affected assets have also been frozen through work with industry partners, without giving a combined frozen or recovered total.
The freeze follows scrutiny of USDC movements during the attack. Security researcher Taylor Monahan flagged transfers and swaps involving the attacker, as crypto.news reported on Friday. Her account described stolen USDC moving through wallets while some assets were converted into ETH.
Bitget raises transferred-assets estimate to $387.5 million
Bitget’s latest tracing puts the value transferred to attacker-controlled addresses at approximately $387.5 million, up from its initial $351.6 million estimate. The company said the revised figure includes affected assets on Zcash and TRON that were absent from its first calculation. It attributed the increase to a fuller accounting of the original incident, rather than further unauthorized transfers.
The exchange detected unauthorized transfers from some hot wallets at 18:31 UTC on Sep. 24. Its initial security notice said portions of its hot and warm wallet systems were affected, while cold wallets remained secure. Bitget paused withdrawals after detecting the transfers but kept deposits and trading available.
Investigators believe an attacker compromised a backend wallet service, fed false transfer information into Bitget’s systems, and triggered its authorization process. Chen said the preliminary probe had ruled out a private-key leak. The account of the suspected entry route was covered by crypto.news on Sep. 25, before Bitget published its revised asset total.
In its later update, Bitget said its team had identified the attack path and fixed the underlying vulnerability. Mandiant and SlowMist are assisting with the investigation and security checks. The exchange said it had contained the incident and that no further unauthorized transfers were possible.
The affected assets include XRP, ETH, USDT, ZEC, USDC, USDT0, XAUt, BNB, AVAX and TRX, according to Bitget. Its tracing information identifies four primary receiving addresses so far, one each for EVM networks, XRP Ledger, Zcash and TRON.
Withdrawals are scheduled to return in phases
Bitget published a withdrawal schedule on Sep. 26 after conducting further checks on its systems. Bitcoin withdrawals are set to resume at 08:00 UTC on Sep. 28. Ethereum withdrawals on the listed networks are scheduled for the same time on Sep. 29, followed by USDT on Sep. 30 and other tokens, fiat and peer-to-peer services on Oct. 2.
The exchange said customer account balances remain unaffected and its Protection Fund covers the financial impact of the incident. Its first notice valued the fund at more than $464 million, before the company revised its estimate of the transferred assets. Bitget has not published a new fund valuation alongside the $387.5 million figure.
For U.S. readers, the issuer freezes concern dollar-linked tokens that can also be held outside Bitget. Circle’s USDC terms allow it to block transfers involving certain on-chain addresses. A recent U.S. Justice Department case separately involved Tether’s help in tracing and restraining crypto tied to an alleged illicit network; authorities have made no comparable public announcement about U.S. action in the Bitget investigation.
Chen is scheduled to host a live question-and-answer session at 07:30 UTC on Sep. 28 to discuss the incident, the restoration of withdrawals, and Bitget’s next steps.
U.S. Securities and Exchange Commission (SEC) Commissioner Hester Peirce has submitted her formal resignation, effective Oct. 2, according to a letter she posted to X. Peirce—often dubbed “Crypto Mom” for her consistent calls for clearer, rules-based crypto regulation—has spent roughly eight years on the commission.
Peirce’s departure comes as the SEC’s leadership and regulatory posture toward digital assets has shifted under the current administration. With her resignation, the commission’s membership will again be shaped by the remaining Republican commissioners, Paul Atkins (chairman) and Mark Uyeda.
Key takeaways
- SEC Commissioner Hester Peirce’s resignation is effective Oct. 2, with the letter posted on her X account.
- Peirce served on the SEC for about eight years and has been director of the agency’s Crypto Task Force since Feb. 4, 2025.
- Her SEC term had already expired in June 2025, but commissioners can continue serving for up to about 18 months if replacement nominations are not made.
- Peirce is expected to join Regent University’s law school as an associate professor in November, per earlier reporting.
- The SEC’s stance toward crypto has changed since Trump took office in January 2025, including reductions in certain enforcement actions and investigations involving crypto firms.
Resignation letter and SEC staffing expectations
Peirce posted a copy of her resignation letter to X on Friday. In the letter, she expressed gratitude for “the honor of her professional lifetime” serving as a commissioner. She also said she would be leaving the SEC under the “excellent leadership” of Chairman Paul Atkins and Commissioner Mark Uyeda, the two remaining members.
Peirce’s letter also fits into a broader SEC timeline. While her official term expired in June 2025, the SEC’s structure allows commissioners to remain in office for approximately 18 months after their term ends if they are not replaced before then. This is part of the reason her role continued despite the expiration date.
There is an additional staffing factor: Caroline Crenshaw, the prior Democratic commissioner, left the SEC in January—18 months after her term ended—without any new nomination yet made by President Donald Trump to fill her seat.
Role in the SEC’s Crypto Task Force
Beyond her commissioner duties, Peirce has been director of the SEC’s Crypto Task Force. According to Peirce’s designation letter on the SEC website, she assumed that role on Feb. 4, 2025.
The Crypto Task Force has focused on how existing securities laws could apply to digital assets and decentralized systems. For investors and builders, that work matters because it influences how the SEC interprets “securities” questions in contexts that may not map cleanly onto traditional financial products.
Peirce has repeatedly emphasized the need for clearer, more predictable frameworks. In June 2025, Cointelegraph reported on remarks she made regarding decentralized finance and developer liability, including an argument that publishing open-source code should not automatically subject software developers to federal securities regulations. Her position touches a long-running debate in crypto: whether and how legal risk should attach to developers contributing software that others may use in decentralized networks.
Academic move signals a shift in influence
Peirce’s resignation does not appear to mark a retreat from crypto policy and legal issues. In May 2025, Cointelegraph reported that she planned to join the law school of Regent University in Virginia as an associate professor in November.
Regent University’s academic plan, as described in that reporting, would include strengthening focus areas such as federal litigation, securities regulation, and digital assets. For market participants, this matters because Peirce’s perspective has been closely watched in policy circles—both for its critique of regulatory uncertainty and for its emphasis on how legal doctrines apply to decentralized technology.
Still, the practical impact of her exit remains tied to how her responsibilities are redistributed at the SEC. With her resignation effective Oct. 2 and no immediate indication of a replacement commissioner in the supplied material, the SEC’s internal balance and external messaging could continue to reflect the views of the two remaining Republican commissioners.
A SEC regulator’s approach in transition
Since President Donald Trump took office in January 2025, the SEC has “radically changed” its approach to crypto regulation and enforcement, according to Cointelegraph’s coverage referenced in the source text. That reporting noted that the SEC dropped several enforcement actions and investigations tied to crypto companies, including those connected to Trump and his family.
The SEC leadership’s direction has been a central part of the crypto industry’s expectations. In remarks earlier referenced by Cointelegraph, Chairman Paul Atkins characterized the previous era of enforcement as “regulation by enforcement.” In that context, Peirce’s own arguments—particularly on how rules should apply to decentralized systems and developers—can be read as consistent with a broader push toward clearer standards rather than case-by-case enforcement.
However, much will depend on what comes next: whether the Crypto Task Force’s work accelerates, how it is framed under the remaining commissioners, and whether the SEC’s enforcement posture toward crypto will continue to shift in the absence of a fully staffed leadership lineup.
As Peirce prepares to step away from the SEC, investors and builders should watch two things closely: how the Crypto Task Force continues its work without her direct leadership, and whether the commission’s membership changes before— or after—Oct. 2 alters how the SEC signals its interpretation of securities laws for digital assets.
Backpack CEO Armani Ferrante has laid out a plan to expand tokenized stock access on Solana from about 200 symbols to 10,000, with shares moving between brokerage accounts and decentralized finance through one API.
Summary
- Ferrante described 10,000 stock symbols as Backpack’s next target, without giving a rollout date.
- Backpack already lets eligible users convert certain brokerage holdings into Solana tokens and back.
- The SEC’s new tokenized stock trading exemption applies only to venues that meet its conditions.
According to a post shared by Solana on Sep. 26, Ferrante wants to make the full stock market available through a system that connects conventional securities accounts with DeFi applications.
“Not 10 stocks, not 100 stocks. We want to bring the entire stock market to Solana,” Ferrante said in the clip shared by Solana.
He described a single API through which a real share could move from a brokerage account into DeFi and back. Ferrante called the move from 200 to 10,000 symbols “the next leap,” though the post did not identify a launch date or set out which stocks would be added first.
The 200-symbol figure comes from Ferrante’s description of the starting point. The post does not establish that Backpack Securities has already issued 200 separate tokenized stocks on Solana, so the proposed expansion should not be read as a count of tokens currently in circulation.
How Backpack moves stocks onto Solana
Backpack introduced its securities platform in June, saying customers could hold U.S. stocks and exchange-traded funds through a brokerage service and convert eligible holdings into tokenized securities. Depositing a supported token through Backpack Exchange converts it back into a traditional security entitlement, according to the company.
The company says its brokerage holdings are security entitlements governed by New York’s Uniform Commercial Code Article 8. Backpack also says the service supports cash dividends, corporate actions and transfers involving established brokerage infrastructure, including ACATS and Depository Trust & Clearing Corporation systems.
On Solana, Backpack-issued tokens can be held in compatible wallets and transferred between users. The company says they can also be used in DeFi applications, subject to the features and rules of the particular product and service.
A June report on SPCX covered Backpack Securities’ first tokenized SpaceX product, issued with Sunrise on Solana. Backpack said eligible holders could convert the token into the corresponding share through its brokerage route, while Sunrise provided infrastructure for issuing and distributing the token.
Backpack subsequently added tokenized versions of other U.S.-listed companies. In July, crypto.news covered its continuous trading for a group of equities available to users outside the United States, including products tied to SpaceX, Micron and SanDisk. The company said users could redeem supported Solana tokens one-for-one for the corresponding shares through its platform.
The conversion process is also described in Backpack’s Sep. 23 CoreWeave announcement. A customer can withdraw a CoreWeave holding from Backpack Exchange as a CRWV token on Solana, then deposit the token to convert it back into a brokerage holding, the company said. Backpack identified decentralized exchanges, wallets and other Solana applications where the token could be accessed.
What ownership rights Backpack describes
Backpack draws a distinction between a brokerage holding and its tokenized form, even when it says the two can be converted one-for-one. In its Micron product description, the company says brokerage holders receive cash dividends and corporate actions through traditional securities infrastructure.
For holders of its tokenized Micron security, Backpack says dividend payments are reinvested into additional tokens. It says applicable corporate actions are handled through proportional changes to token balances intended to preserve the economic value of the underlying holding.
The U.S. Securities and Exchange Commission has warned that tokenized securities created by third parties do not all give holders the same rights. In a January staff statement, the agency said the rights attached to a token depend on its structure and may differ from those attached to the underlying security. The statement also distinguished tokens backed by securities held through custody arrangements from synthetic products that create different claims.
For American readers, those differences matter when comparing stock tokens with conventional brokerage positions. Backpack’s descriptions of redemption, dividends and corporate actions apply to its stated product structure; they should not be assumed to apply to every token carrying a familiar stock ticker.
Where U.S. tokenized stock rules stand
On Sep. 17, the SEC granted conditional relief for certain venues to trade tokenized National Market System stocks through permissioned automated market makers and liquidity pools. The five-year framework places limits on the number of symbols and trading volume a qualifying venue may handle.
Under the SEC’s published conditions, a venue must verify that a tokenized stock gives its holder the same rights and privileges as the equivalent traditional share. When an unaffiliated third party tokenizes a company’s stock, the venue must notify the issuer and give it an opportunity to object.
The SEC also requires public, auditable smart contracts and a halt in token trading whenever the underlying stock is halted on its primary exchange. The agency’s announcement does not identify Backpack as a participating venue or state that its current products operate under the exemption.
Backpack’s U.S. plans have involved a separate corporate step as well. In September, the company’s U.S. arm appointed Kyle Samani to its board. Backpack said the former Multicoin Capital executive would support its work across regulated U.S. financial services and onchain markets; the appointment did not include a timetable for expanding its U.S. stock or tokenized asset services.
SEC Commissioner Hester Peirce has submitted her formal resignation from the US Securities and Exchange Commission, effective Oct. 2.
Peirce, also known as “Crypto Mom” amid her advocacy of clear, rules-based regulation of the crypto industry, posted a copy of her resignation letter on her X account Friday.
In the letter, she thanked the president for the “honor of her professional lifetime” serving as a commissioner and said she was leaving the SEC under the excellent leadership of Chairman Paul Atkins and Commissioner Mark Uyeda, the two remaining members, who are both Republicans.
Peirce served on the commission for about eight years. Since Feb. 4, 2025, she was also director of the agency’s Crypto Task Force. Her term at the SEC officially expired in June 2025, but commissioners “may continue to serve up to approximately 18 months after terms expire if they are not replaced before then,” according to the agency.
Peirce will join law school as associate professor
Cointelegraph reported in May that Peirce planned to join the law school of Regent University in Virginia as an associate professor in November. Peirce is expected to help the law school bolster its academic focus in several areas, including federal litigation, securities regulation and digital assets, according to the university.
Peirce’s seat may not be filled immediately. Caroline Crenshaw, the agency’s previous Democratic commissioner, departed in January, 18 months after her term ended and no nominations to fill that seat have been made by President Donald Trump.
Since Trump took office in January 2025, the SEC has radically changed its approach to crypto regulation and enforcement. The agency dropped several enforcement actions and investigations into crypto companies, including those tied to Trump and his family.”
Related: SEC’s ‘Crypto Mom’ calls for simpler disclosure rules, flags tokenization debate
Since its formation, the Crypto Task Force has been examining how existing securities laws should apply to digital assets and decentralized systems.
Cointelegraph reported in June that Peirce said publishing open-source code should not subject software developers to federal securities regulations, weighing in on a longstanding debate over developer liability in decentralized finance.
Peirce’s remarks aligned with the SEC’s broader shift away from what Atkins has described as “regulation by enforcement.”
Magazine: Exchanges reporting crypto gains to IRS becomes tax nightmare
The Sixth Circuit ruled against Kalshi in Ohio and Tennessee a month after another appeals court sided with Nevada. New Jersey still has a conflicting ruling. The question for a national market is now practical as well as legal: can an exchange offer the same sports contract across state lines when its federal registration does not necessarily protect it from state gambling law?
Summary
- A three-judge Sixth Circuit panel ruled on Sept. 25 in two cases involving Ohio and Tennessee.
- The ruling affirmed 1 denied injunction in Ohio and vacated 1 granted injunction in Tennessee.
- Three federal appellate circuits have now addressed sports contracts, with the Third Circuit on the other side.
- Ohio and Tennessee each set 21 as the minimum age for sports wagering, according to the opinion.
- Kalshi self-certified sports contracts on Jan. 22, 2025; neither state has issued it a gaming license.
An Ohio resident who wants to buy a Kalshi contract on a basketball game faces a different legal position from a New Jersey resident buying the same contract. The exchange and the payoff can be identical. The state line is what changes. On Sept. 25, the federal appeals court covering Ohio and Tennessee concluded that Kalshi had not shown its sports products were protected from those states’ gambling laws.
The 49-page Sixth Circuit opinion, in the consolidated cases KalshiEX LLC v. Schuler and KalshiEX LLC v. Orgel, contains two separate reasons. Its three judges said Kalshi had not shown that the sports contracts qualify as swaps under the Commodity Exchange Act. They then assumed, for the sake of argument, that the contracts were swaps and still found that the federal statute did not displace Ohio’s and Tennessee’s gambling rules. One answer concerns the product. The other concerns the boundary between two governments.
Neither holding is a final nationwide ban on sports prediction markets. Both cases concern preliminary injunctions, meaning orders that would stop state officials from enforcing their laws while litigation proceeds. The panel kept Ohio’s denial in place, removed Tennessee’s protection for Kalshi and returned both cases to lower courts. Kalshi remains a federally registered exchange. Registration alone did not win these particular motions.
Two states entered the appeal with opposite answers
Kalshi registered as a designated contract market with the Commodity Futures Trading Commission in 2020. On Jan. 22, 2025, it self-certified sports event contracts and began listing them. The opinion describes markets covering tournament results, golf, soccer statistics and combinations of player and game outcomes. A trader buys a yes or no position that pays according to the specified result. Kalshi had previously offered contracts on climate, economics, elections and crypto. The September decision concerns sports.
Ohio’s Casino Control Commission warned Kalshi that it was offering sports products without a state license. The regulator raised its 21-year minimum and alleged that people below that age could use the exchange. Those are the commission’s allegations, set out in the court record, not an independent finding here that a particular underage customer traded. Kalshi answered that its federal exchange status entitled it to offer contracts nationally. It sued to prevent enforcement, and an Ohio district judge refused a preliminary injunction.
Tennessee’s Sports Wagering Council sent its own cease-and-desist letter. Kalshi again sued, but a Tennessee district judge granted protection against state officials. The state appealed. In one federal circuit, then, the same legal theory had produced one order allowing enforcement and another restraining it. The appellate panel heard the cases together and resolved both on Sept. 25. Its decision affirmed Ohio’s refusal and vacated Tennessee’s injunction.
The distinction between an injunction and the eventual merits matters. The panel evaluated whether Kalshi had shown a likelihood of success sufficient to stop the states now. The underlying suits have been remanded. An operator seeking guidance today cannot treat a ruling on temporary protection as a completed trial judgment, yet a state that is no longer restrained can try to enforce its existing rules. A later appeal, rehearing or Supreme Court decision could alter the position.
Kalshi spokesperson Dani Lever told Reuters that the company expected the ruling to face further review and argued that different rules at state borders undermine a national market. The company has a concrete point: a single electronic order book is easier to operate when eligibility for a contract does not change according to each customer’s location. The appellate judges accepted that compliance could cost money. They did not accept that cost as proof that federal law forbids state restrictions.
A sports wager does not become a swap because it trades on an exchange
The Commodity Exchange Act gives the CFTC exclusive jurisdiction over certain transactions, including swaps traded on designated contract markets. Its definition of a swap includes payments tied to events or contingencies associated with potential financial, economic or commercial consequences. Kalshi says its sports contracts fit that definition and the exchange sits inside the federal regulatory system. If both propositions hold, it argues, states cannot regulate the product as gambling.
The Sixth Circuit focused on what happens when the game ends. A change in interest rates or a debt default has an economic consequence inherent in the event. A tennis result may affect sponsorship, television revenue or nearby restaurants, but those effects follow later decisions by other people. The panel regarded them as too indirect to turn the sporting result itself into the kind of financial contingency contemplated by the swap definition. It considered the terms of the product, not just the federally registered venue where customers trade it.
The opinion points to a problem with defining every event that affects somebody’s money as a swap. Under that definition, an ordinary sportsbook wager could qualify simply because the customer receives money if a team wins. Federal law restricts where swaps can be transacted. Applying its definition to every wager could pull conventional sports bets, including bets made outside registered exchanges, into a regime Congress did not clearly write for them. That consequence informed the judges’ reading of the statutory text; it was not a finding that all wagers actually violate federal law.
Kalshi has a serious textual reply. Congress gave the CFTC a special procedure for event contracts involving gaming. Why give the federal agency a way to prohibit such contracts if it has no jurisdiction over them? The panel answered that the special rule covers agreements, contracts, transactions or swaps. Federal authority to review a gaming-related event product therefore does not prove that every such product meets the narrower swap definition. A regulator can have a review power without possessing exclusive authority over every state-law aspect of the activity.
This is where the product’s label stops doing the work. An event contract can be a derivative in ordinary usage and still fail the particular statutory test Kalshi invoked for exclusive federal protection. The distinction explains why a CFTC filing or exchange listing is evidence of federal oversight without automatically settling a separate state’s licensing question. Crypto.news has explained how self-certification lets an exchange list an event contract without receiving advance approval for every new market. That process is one step in the federal system. It is not a court judgment that every listed market overrides gambling law.
Even a swap may face state gambling law
The second holding makes the opinion more consequential than a dispute over definitions alone. The judges assumed that Kalshi could win the swap argument and asked whether the federal statute would then block Ohio and Tennessee. They still said no. A higher court could disagree on the classification and leave this separate dispute alive.
Federal preemption comes in several forms. Congress can state that state law is displaced. State law can be blocked when it is impossible to comply with both systems. It can be displaced if it obstructs the federal law’s purpose, or if Congress occupied the whole regulatory field. The Sixth Circuit considered these routes and found that Kalshi had not shown the conditions for any of them at this stage.
Kalshi relied heavily on the CFTC’s exclusive jurisdiction over swaps on federal exchanges. The panel read that phrase as allocating federal regulatory authority, not as an explicit repeal of every state rule that might apply to an exchange operator. Congress used unmistakable preemption language elsewhere in commodities law, the judges observed, including provisions on some state gaming rules and insurance. They saw no equivalent broad command in the clause on which Kalshi relied.
The panel also pointed to the special rule that permits the CFTC to consider event contracts involving activities unlawful under state law. That reference would be odd, it reasoned, if Congress intended to erase the relevance of state law altogether. Federal review and state gambling enforcement can coexist under the panel’s reading. This interpretation differs sharply from the argument that federal authorization itself guarantees nationwide access.
The consequence is narrower than a claim that states control all event contracts. The decision addresses Ohio and Tennessee’s sports wagering laws as applied to Kalshi’s sports products. A weather contract, an election contract and a Bitcoin price contract can raise different classification and regulatory questions. Courts have not adopted a single rule for all of them. Treating the September ruling as a ban on prediction markets generally would erase the distinction the judges spent much of the opinion drawing.
The state border is an engineering problem as well as a legal one
One passage of the opinion does work that many discussions of jurisdiction skip. Kalshi argued that CFTC rules require impartial access to its exchange and that a state-by-state restriction would make compliance with both federal and state law impossible. The Sixth Circuit examined the rule itself. It said impartial access governs how an exchange treats eligible participants in the markets it offers; it does not oblige the exchange to offer every particular market in every state.
The judges then identified a concrete alternative: restrict access to certain contracts according to customer location. They noted that other companies have used geofencing while allowing eligible participants impartial access in the permitted area. Kalshi argued that this was technically challenging, time-consuming and expensive. The panel agreed that it could be difficult but said difficulty did not make compliance impossible. It cited Sporttrade as an example raised in the related New Jersey litigation.
Trace the operational result. The exchange could keep a sports contract unavailable to an Ohio customer while offering another contract to that customer and selling the sports contract elsewhere. It would need location checks at account opening and when orders are entered, rules for open positions if a customer’s location changes, and a way to prevent a restricted user from reaching the product through another interface. The opinion does not require this exact design or certify that any particular design would satisfy state officials. The steps are the practical implications of its conclusion that geography can matter within a national electronic venue.
Another route would be a state gaming license where available. That changes the product’s regulatory economics. Ohio and Tennessee laws, as summarized by the court, require sports customers to be at least 21 and impose licensing, tax and consumer protection duties. Tennessee requires its sports customers to be physically present in the state. A license also entails oversight by a regulator whose mandate differs from that of the CFTC. A company choosing this route would have to determine whether its existing exchange structure, customers and clearing arrangements could meet those requirements. The court did not order Kalshi to apply for a license or decide that an application would succeed.
Here is the part that a simple court scoreboard misses. If an exchange geofences states where it cannot offer sports markets, liquidity on the national order book may change even for users elsewhere. If it instead seeks multiple state permissions, trading eligibility and compliance costs vary across its customer base. The premise of one federal venue remains intact, but nationwide access to one specific product no longer follows automatically from that premise. Kalshi’s complaint about fragmentation is therefore more than a slogan. It describes a real cost that the Sixth Circuit judged legally bearable.
New Jersey gives Kalshi its strongest opposing case
The federal appellate courts disagree. In April, a divided Third Circuit panel affirmed a preliminary injunction protecting Kalshi from New Jersey enforcement. It found that the sports contracts qualified as swaps on a CFTC-registered exchange and that Kalshi had shown a reasonable chance of proving federal preemption. That is the strongest available judicial support for Kalshi’s position, not a stray quote from a company filing.
The Third Circuit saw the statute’s national market structure as deliberate. Congress created a federal regulator and an exchange designation process precisely to prevent incompatible rules from intruding on trading in covered products. It treated New Jersey’s attempt to bar particular sports contracts as interference with federally regulated exchange trading. The court’s conclusion gave Kalshi temporary protection while the New Jersey case proceeds. It did not issue a final judgment that every sports market is immune from every state law.
The competing reading has costs too. If a state can prohibit a federally listed contract by calling it gambling, a national derivatives venue may face a patchwork of local restrictions. The question then becomes how to distinguish a state regulating gambling from a state indirectly regulating the substance of a federal derivatives market. Kalshi’s concern about uncertainty is strongest at that boundary, where the same trade could be lawful to one participant and unavailable to another.
In August, the Ninth Circuit allowed Nevada to enforce its gaming rules during litigation. The Sixth Circuit has now reached a result favorable to Ohio and Tennessee. That produces three appellate circuits, two directions and no final nationwide rule. The Fourth Circuit still has a related Maryland appeal pending, according to the Sixth Circuit opinion. Calling the split a guaranteed Supreme Court case would go further than the evidence allows. A petition, an order granting review and a merits decision are separate events.
The record also cautions against treating judicial disagreement as evidence that one side is acting outside the law in bad faith. Judges reading the same federal provisions have reached opposite conclusions at the injunction stage. State officials are invoking their sports wagering statutes. Kalshi is invoking its federal registration and its reading of Congress’s jurisdictional grant. The legal contest lies in the interaction of those authorities.
The federal regulator cannot settle this alone
The CFTC has its own interest in event markets. It joined the Ohio appeal as an amicus, according to the Sixth Circuit’s listing of counsel, and it has proposed changes to its review process for contracts involving gaming and other activities. The agency can set exchange standards and evaluate listed products under the powers Congress granted it. A final rule cannot, by itself, rewrite the words of the Commodity Exchange Act that the appellate judges disagreed about.
Crypto.news’ account of the CFTC’s event contract proposal describes a separate regulatory track, while its report on the Ninth Circuit’s decision explains why a court loss does not automatically cancel a proposal. The agency’s power to regulate an exchange and a state’s power to apply a gambling statute can be concurrent under the Sixth Circuit approach. A rule saying the CFTC will review a product does not itself resolve that constitutional and statutory relationship.
Congress could change the underlying statute. It could define sports event contracts more clearly, specify the reach of federal jurisdiction, or expressly preserve a role for state gambling law. None of those choices is contained in the Sept. 25 opinion. A legislative answer would require text, votes and enactment. Until then, litigation and decisions about product access are doing work that a uniform statutory answer would otherwise do.
Sports leagues, data suppliers and partners have interests of their own. The NFL asked the CFTC to tighten safeguards in the proposed event contract rules, according to crypto.news’ account of its submission. The league’s integrity concerns are distinct from whether a contract is legally a swap. A stronger federal integrity standard might address one concern without ending the state authority dispute. Conversely, a court win on federal jurisdiction would not mean that a market is free from federal product review.
An injunction is temporary, and users need the jurisdiction
The Sept. 25 judgment changes which side has temporary protection in the two Sixth Circuit cases. It does not determine that a specific customer’s position will be voided, that an account will be closed or that a particular state has already completed a new enforcement action. Those outcomes depend on the state, the product, the procedural next step and the platform’s response. Legal exposure should be described with that sequence intact.
Nor does the decision settle how the courts will classify markets whose payouts depend on financial data, election outcomes or weather. The court analyzed sports contests and the state laws aimed at sports wagering. A platform offering several market categories can face a different legal analysis for each. That product-by-product distinction also matters for the CFTC’s review of what an exchange self-certifies. A federal designation attaches to the venue, while the legal character of a particular contract can still be contested.
The difference between the circuit rulings is concrete today. Kalshi has appellate support in New Jersey and lacks equivalent protection from Ohio and Tennessee under Friday’s ruling. Nevada has an appellate result favorable to its regulator. A reader should resist turning that map into an answer for all 50 states. Appeals in other jurisdictions, state licensing decisions and new orders can change access. Crypto.news previously mapped the state litigation, but this new Sixth Circuit ruling changes two important entries on that map.
The test of Kalshi’s national model is now whether one federal exchange can accommodate local exclusions without losing the advantages of a shared market. The Sixth Circuit says that is legally possible under the arguments presented. Kalshi says it is a costly patchwork that Congress sought to avoid. The Third Circuit agrees with much of the company’s legal reasoning. The next filings will show whether the split moves toward higher review or continues to be managed one state and one injunction at a time.
What to watch
- Kalshi’s next filing. A request for rehearing or Supreme Court review would identify which of the Sixth Circuit’s two independent holdings the company challenges.
- Ohio and Tennessee enforcement. New notices or orders would show how the states use their restored ability to apply sports wagering rules.
- Customer eligibility changes. Geofencing or age-rule changes would show how Kalshi responds operationally while the cases continue.
- The Maryland appeal. A Fourth Circuit ruling could change the appellate map and sharpen or narrow the disagreement.
- CFTC rulemaking. A final event contract rule may alter federal review, though it cannot alone resolve the courts’ statutory disagreement.
FAQ
What did the Sixth Circuit decide about Kalshi on Sept. 25?
It rejected Kalshi’s requests for preliminary protection in cases involving Ohio and Tennessee. The three-judge panel affirmed the denial of an injunction in Ohio, vacated the injunction in Tennessee and returned both cases to lower courts.
Did the court ban Kalshi in every state?
No. The decision concerns sports event contracts and enforcement by Ohio and Tennessee. It is an appellate decision about preliminary injunctions, not a nationwide final judgment on every product Kalshi offers.
Did the judges find that sports contracts are swaps?
No. They concluded that Kalshi had not shown these sports contracts meet the statutory swap definition. They also assumed, as a separate legal test, that the contracts were swaps and found no sufficient basis to displace the two states’ gambling laws.
Why does Kalshi say state rules should not apply?
Kalshi is a CFTC-registered designated contract market and argues that the federal Commodity Exchange Act gives the CFTC exclusive jurisdiction over the relevant exchange-traded contracts. The Third Circuit accepted enough of that argument to protect Kalshi temporarily in New Jersey.
What does the Third Circuit ruling mean now?
The April ruling preserved a preliminary injunction against New Jersey enforcement of the sports contracts at issue. It conflicts with the Sixth Circuit’s Sept. 25 reasoning, but neither decision is a final nationwide judgment on the merits.
Can Kalshi restrict sports markets by state?
The Sixth Circuit said geofencing could allow compliance with both the federal exchange’s impartial-access duty and state requirements. It did not approve a specific geofencing design or order Kalshi to implement one.
Are prediction markets the same as sports betting under this ruling?
The judges addressed Kalshi’s sports event contracts and the particular gambling laws of Ohio and Tennessee. They did not decide that every market on elections, weather, crypto prices or other subjects is sports betting.
Will the Supreme Court take the case?
The differing appellate decisions make further review possible, but no Supreme Court decision follows automatically. A petition and a grant of review would be separate steps. This is educational analysis, not investment advice.
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Figures reflect regulatory filings and reporting available at the time of writing and change with each disclosure. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 26, 2026.
The U.S. Commodity Futures Trading Commission (CFTC) has filed a federal lawsuit accusing Cash FX Group and three individuals of running a large foreign-exchange investment scheme tied to crypto, alleging that investors were sold a multilevel-marketing Ponzi structure with promised returns far above anything justified by actual trading activity.
According to the CFTC, the complaint was filed Friday in the U.S. District Court for the Middle District of Florida, seeking to hold accountable Cash FX and its CEO, Huascar Jose Lopez Castillo of Brazil, as well as The Conversion Pros and its CEO, Ronald Pope of Oregon, and Justin Halladay of Florida.
Key takeaways
- The CFTC alleges the defendants collected more than $950 million for a purported retail forex trading “commodity pool.”
- The regulator says the operation used new participant funds to cover promised or fictitious trading profits rather than genuine trading performance.
- Prosecutors claim the defendants misrepresented trading methods, including claims involving expert traders, proprietary algorithms, and artificial intelligence.
- The CFTC estimates participants lost at least $406 million, citing alleged false accounting provided to investors.
CFTC alleges crypto-linked forex “commodity pool” was a Ponzi scheme
In its complaint, the CFTC alleges that Cash FX Group and the three individuals operated a multilevel marketing Ponzi scheme that solicited and accepted over $950 million from participants for purported trading of retail foreign currency contracts through a commodity pool.
Under the CFTC’s allegations, the promotional pitch centered on the idea that investor money would be actively managed by highly sophisticated systems—expert traders, proprietary algorithms, and artificial intelligence—while offering weekly return promises that, according to the agency, could reach up to 15%.
The complaint further contends that the defendants conducted only minimal forex trading, while most of the participant funds were misappropriated. The CFTC says the scheme relied on inflows from new participants to sustain earlier payouts described as trading gains.
Fictitious profits, misappropriation, and alleged false reporting
The CFTC’s allegations describe a mechanism common to Ponzi structures: investors are told their funds are being used to generate profits through trading, but payouts are funded primarily by fresh money coming into the system.
As described by the CFTC, the defendants allegedly redirected millions of dollars to each defendant while using incoming participant contributions to support claims of profit generation. The complaint also alleges the defendants provided participants with false accounting statements.
On losses, the CFTC claims participants lost at least $406 million, based on the agency’s allegations that participants were misled about performance and fund handling.
“The Division of Enforcement has continued to refocus on its core mission of protecting the public from fraud and manipulation,” said Director of Enforcement David I. Miller. “This critical action, and the massive fraud it targets, reflects our steadfast commitment to addressing fraud wherever we find it.”
Why this enforcement matters as the CFTC moves toward wider crypto oversight
This case lands as U.S. regulators continue to refine how they oversee crypto-adjacent markets and marketing practices. While the CFTC lawsuit focuses on an alleged forex investment pool and the handling of investor funds, it also reflects the broader enforcement posture that has repeatedly targeted schemes that borrow the language of sophisticated technology while operating without legitimate risk controls or verifiable trading activity.
Earlier coverage from Cointelegraph noted that the CFTC had submitted a new regulatory action covering crypto asset transactions and markets for White House review on Sept. 18. That step came after the Senate failed to advance the CLARITY Act, which would have aimed to establish a federal regulatory framework for crypto markets.
Although the enforcement action in this case does not hinge on new legislative outcomes, it fits into an environment where the agency is signaling continued attention to fraud, manipulation, and misleading representations—whether the scheme is marketed as trading, algorithmic investing, or “managed” returns tied to financial products.
What to watch next
As the lawsuit proceeds, investors and market participants should watch for how the court addresses the CFTC’s claims about fund handling, the alleged extent of actual forex trading, and whether the defendants can rebut allegations of misappropriation and false accounting. The case also underscores that, even amid regulatory uncertainty, regulators can pursue fraud charges through existing enforcement authorities.
Bitget has set a Sep. 28 restart for Bitcoin withdrawals after a Sep. 24 security incident, with Ether, USDT, and other withdrawal services scheduled to follow through Oct. 2.
Summary
- Bitcoin withdrawals are scheduled to reopen at 08:00 UTC on Sep. 28.
- ETH and USDT withdrawals are set to return on selected networks over the following two days.
- Bitget says it has fixed the vulnerabilities and is carrying out further security checks.
- A later account of the incident put transfers to attacker-controlled addresses at about $387.5 million.
Bitget said in an update that its technical team had identified and fixed the vulnerabilities tied to the incident. The exchange is checking its withdrawal systems before reopening them and said Mandiant, a cybersecurity firm owned by Google, and blockchain security company SlowMist are helping investigate the attack.
The dates are part of a planned reopening schedule. Bitget told users to rely on notices from the platform and its official channels for confirmation that each service is available. Customers do not need to take any action before withdrawals resume, it said.
Bitget withdrawals are scheduled to return in four stages
Under the schedule, BTC withdrawals on the Bitcoin network are due to resume at 08:00 UTC on Sep. 28. ETH withdrawals are set for the same time on Sep. 29 across Ethereum, BNB Smart Chain, Arbitrum, Base and Optimism.
USDT withdrawals are scheduled for 08:00 UTC on Sep. 30 across Ethereum, BNB Smart Chain, Solana and Tron. Bitget placed withdrawals for other tokens, fiat currency services and peer-to-peer transactions in the final stage, scheduled for 08:00 UTC on Oct. 2.
The network lists matter for customers holding ETH or USDT: a token’s scheduled return does not mean withdrawals on every network will reopen at once. Bitget named five networks for the first ETH stage and four for USDT. It did not give a network-by-network list for the remaining tokens in the schedule shared with users.
Trading and deposits have continued during the withdrawal pause, according to the exchange. Bitget described the suspension as a temporary security measure and said customer account balances had not changed. Its statement that user assets are unaffected refers to customer balances; the exchange has separately reported unauthorized transfers from its own wallet infrastructure.
The reported loss has risen from Bitget’s first estimate
Bitget detected unauthorized transfers from some of its wallets on Sep. 24 and halted withdrawals while it investigated. As crypto.news reported Friday, the exchange initially estimated that about $351.6 million in assets were affected. It said its cold wallets were secure and that its early investigation had found no evidence of a private-key leak.
In a subsequent account cited by Outlook Money on Sep. 26, Bitget put the value transferred to attacker-controlled addresses at approximately $387.5 million. The later figure included Zcash and TRON assets that were absent from the first estimate. Bitget said its tracing work was continuing, so the figure may change as investigators classify additional transactions.
The earlier investigation pointed to a possible breach of a backend wallet service, according to Bitget’s statements covered by crypto.news. The exchange had not established a final entry point in that account. Its latest statement says the vulnerabilities have been fixed, while Mandiant and SlowMist continue to assist with the investigation.
Bitget has said its protection fund will cover the financial impact of the incident. During the withdrawal pause, the exchange reported that the fund held more than $464 million and said customer balances remained accurate. The fund statement is Bitget’s account of how it intends to absorb the loss; it does not mean the unauthorized transfers did not occur.
Chief Executive Gracy Chen also raised a possible North Korean connection during an earlier public discussion, citing similarities involving IP addresses and VPN services. She did not confirm who carried out the attack. No public attribution by a government agency was identified in the earlier crypto.news investigation report.
Stolen USDC transfers drew attention in the U.S.
While withdrawals were suspended, security researcher Taylor Monahan identified USDC movements she linked to the attacker, including transfers and conversions into ETH. Her findings, reported by crypto.news on Sep. 25, raised questions about whether Circle could block the movement of stolen USDC. The public account did not establish whether Circle had received a legal order concerning the addresses.
The question has a direct U.S. connection because Circle is the U.S.-based issuer of USDC. Circle has said it freezes tokens when legally compelled. In a separate U.S. federal lawsuit filed after the Drift Protocol exploit, a claimant alleged that Circle failed to stop stolen USDC moving through its cross-chain transfer system. The allegation is part of that lawsuit, not a court finding against Circle or a determination about Circle’s response to the Bitget incident.
For Bitget customers, the next operational step remains the Bitcoin withdrawal window scheduled for Sep. 28 at 08:00 UTC. The exchange said it would confirm each reopening through its official notices as the security checks are completed.
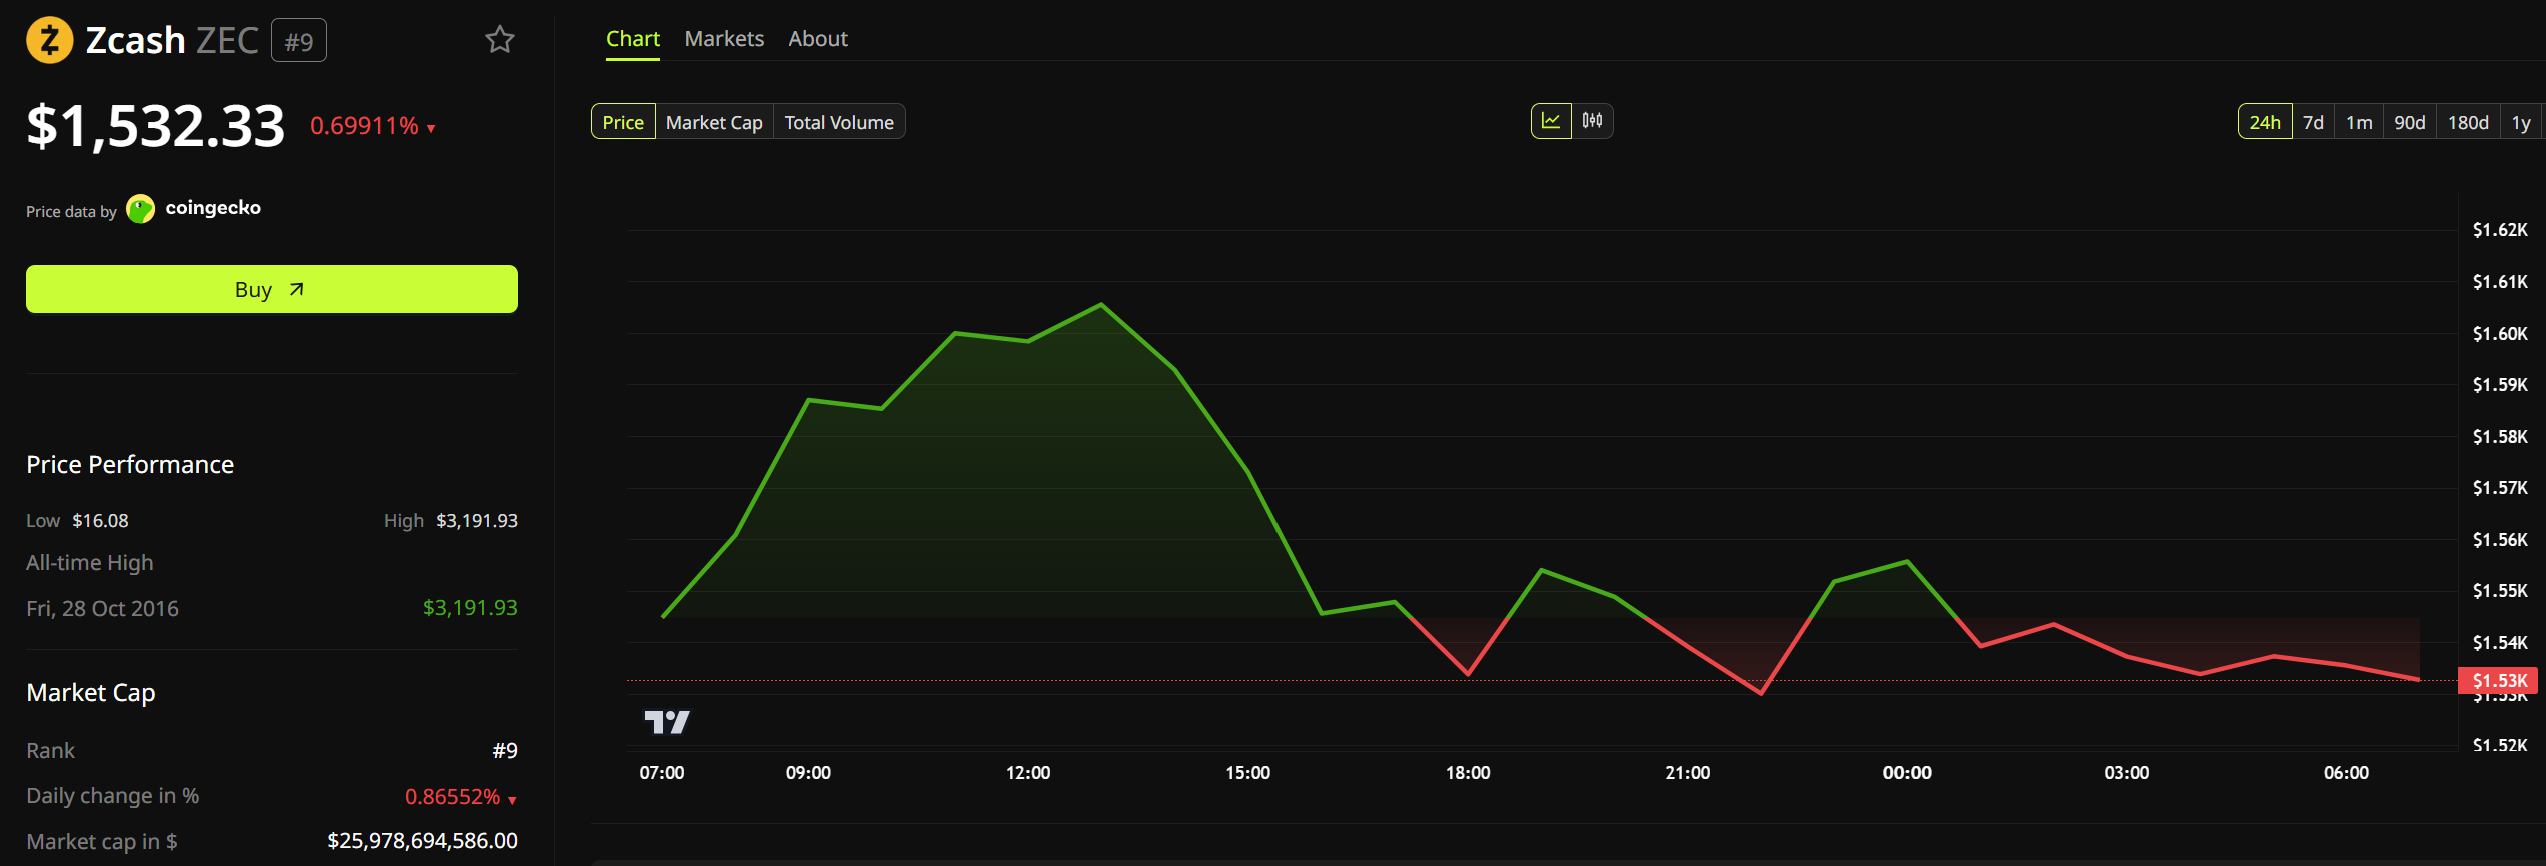
Grayscale has filed for a Zcash ETF that would pay shareholders every two weeks. The cash would come from selling options, not from owning the coin.
The filing reached the U.S. Securities and Exchange Commission (SEC) on September 25. It could take effect 75 days later, in early December.
How Grayscale’s Zcash Income ETF Would Pay Investors
The proposed ZCSH High Income ETF will not hold Zcash (ZEC), a privacy-focused cryptocurrency. Instead, it trades options tied to The Zcash ETF (ZCSH), Grayscale’s existing spot fund, according to the filing.
An option is a contract giving a buyer the right to trade an asset at a set price. The seller collects an upfront fee, called a premium.
The fund copies ZCSH’s price moves by pairing bought call options with sold put options. It then sells short-dated calls, mostly one month or less, to collect premiums. Those premiums fund the payouts.
At least 80% of net assets must sit in options on Zcash exchange-traded products. However, the filing says “high income” promises no set yield. Some payouts could simply return part of an investor’s own money.
What’s the Catch for Zcash ETF Investors?
Selling calls caps the upside. If ZEC rallies past the chosen strike price, the fund misses those gains. Meanwhile, it still absorbs the full drop when prices fall.

The options market is also brand new. ZCSH began trading on August 25, and its options followed on September 8.
Grayscale also flags a conflict. An affiliate of the fund’s adviser sponsors ZCSH and earns its fee, which Yahoo Finance lists at 2.50%. The filing says the new fund’s trading could lift ZCSH demand and, indirectly, that affiliate’s fees.
Zcash ETF Demand Sets Up the Income Play
ZCSH has drawn steady money. The fund converted from Grayscale’s 2017 trust with roughly $260 million in assets.
By the week ending September 18, assets hit $914.5 million after $271 million in cumulative inflows. That week’s $98.2 million haul led all crypto ETFs, BeInCrypto reported.
Similar income products already exist for Bitcoin (BTC). Grayscale runs a Bitcoin covered call ETF, and Goldman Sachs filed a Bitcoin premium income fund in April.
The new fund’s ticker, exchange, fees, and sub-adviser remain blank in the filing.
The post Grayscale Files Zcash ETF That Pays Every 2 Weeks: What's the Catch? appeared first on BeInCrypto.
The U.S. Commodity Futures Trading Commission (CFTC) has filed a lawsuit seeking to hold Cash FX Group and three individuals accountable for a large-scale foreign-exchange investment scheme that the regulator says involved cryptocurrency.
According to the CFTC, the case centers on allegations that the defendants raised more than $950 million from participants by promoting a purported “commodity pool” meant to trade retail foreign currency contracts, while misrepresenting how investor money was managed and the returns investors were promised.
Key takeaways
- The CFTC says it filed its complaint Friday in the U.S. District Court for the Middle District of Florida.
- Regulators allege a multilevel marketing Ponzi scheme built around forex trading claims, including promised returns “up to 15% weekly.”
- The complaint alleges most participant funds were misappropriated rather than used for legitimate trading.
- The CFTC claims participants suffered losses of at least $406 million, alongside alleged false accounting statements.
A $950 million forex pool scheme, tied to crypto investors
In its press release, the CFTC states that the lawsuit targets Cash FX Group and three individuals: Huascar Jose Lopez Castillo of Brazil, The Conversion Pros and its CEO Ronald Pope of Oregon, and Justin Halladay of Florida. The regulator’s complaint, it says, was filed Friday in the U.S. District Court for the Middle District of Florida.
The agency’s core allegation is that the defendants operated a multilevel marketing Ponzi scheme. The CFTC claims the group solicited and accepted more than $950 million from participants based on the pitch that the funds would be used to trade retail foreign currency contracts through a commodity pool.
While the complaint is framed around forex investment activity in a commodity pool structure, the CFTC also characterizes the scheme as involving cryptocurrency. That matters for investors because it underscores the regulator’s position that crypto-adjacent marketing and fundraising can fall under commodities enforcement when it’s tied to fraud and manipulation, even if the underlying product is presented as traditional finance trading.
Alleged return promises and claims about “expert trading” technology
The CFTC alleges that the defendants made a series of claims designed to build trust and justify the pooling of funds. Among the allegations: the defendants falsely stated that investor money would be handled by expert traders, “proprietary algorithms,” and artificial intelligence.
The regulator also says participants were promised returns as high as 15% weekly. If the allegations are proven, that kind of high-frequency, fixed-feel return promise is often a central feature of fraud cases—particularly when the promised performance is inconsistent with transparent trading records and instead relies on marketing narratives.
According to the CFTC, despite the messaging around sophisticated trading, forex trading was minimal. The complaint further alleges that the defendants misappropriated most of the participant funds, using new contributions from investors to support fictitious profits.
How the CFTC says investor money was handled
In laying out its allegations, the CFTC contends that most of the participant funds were diverted away from meaningful trading activity. The complaint describes a pattern where “new contributions from participants” were used to pay alleged trading profits that the CFTC characterizes as fictitious.
The agency also claims the defendants directed millions of dollars to each defendant. This allocation detail is important for readers because, in many Ponzi-style cases, the flow of funds to operators and related parties is used to support the fraud narrative—showing that investor money can be repackaged as returns while principal is drained.
Separately, the CFTC alleges that the defendants provided false accounting statements to participants. The CFTC says those investors lost at least $406 million. Taken together, the return claims, alleged minimal trading, alleged diversion of funds, and alleged false accounting statements form a consistent enforcement theory: investors were sold a trading outcome while money was primarily used to sustain the scheme and enrich the defendants.
“The Division of Enforcement has continued to refocus on its core mission of protecting the public from fraud and manipulation,” said Director of Enforcement David I. Miller. “This critical action, and the massive fraud it targets, reflects our steadfast commitment to addressing fraud wherever we find it.”
Broader enforcement and regulation: crypto oversight in focus
This lawsuit lands as the CFTC continues pushing its regulatory approach to digital asset markets. Cointelegraph previously reported that the CFTC submitted a new regulatory action covering crypto asset transactions and markets for White House review, following the agency’s effort to advance how it oversees parts of the digital asset sector.
That submission, Cointelegraph noted earlier, came days after the U.S. Senate failed to advance the CLARITY Act—legislation intended to establish a federal framework for crypto markets. While the CLARITY Act’s status remains uncertain, the CFTC’s enforcement posture appears clear: regulators are willing to pursue cases where the conduct involves fraud or manipulation, including where cryptocurrency-related fundraising or representations are part of the scheme.
For market participants, the practical takeaway is that “what’s being traded” doesn’t always determine regulatory interest. The CFTC’s complaint, as described in its release, focuses on the structure of solicitation, promised returns, control of funds, and the veracity of trading and accounting representations—elements that can apply regardless of whether the marketing campaign uses crypto terminology.
As the litigation proceeds, investors and users should watch for how the case develops in court—particularly any evidence related to (1) the extent of actual trading activity, (2) the handling and tracing of participant funds, and (3) the accounting records provided to participants. The CFTC’s allegations, if substantiated, would reinforce the message that high-return promises and opaque trading claims—especially those supported by false technology narratives—remain prime targets for enforcement.
The Commodity Futures Trading Commission said it is suing Cash FX Group and three individuals in a $950 million foreign-exchange investment case involving cryptocurrency.
The defendants are Cash FX and its CEO Huascar Jose Lopez Castillo of Brazil, The Conversion Pros and its CEO Ronald Pope of Oregon, and Justin Halladay of Florida.
The CFTC said its complaint was filed Friday in the US District Court for the Middle District of Florida. It alleges the defendants operated a multilevel marketing Ponzi scheme, soliciting and accepting over $950 million for the purported purpose of trading retail foreign currency contracts in a commodity pool.
The agency alleged the defendants falsely claimed pool funds were handled by expert traders, proprietary algorithms and artificial intelligence, and promised up to 15% weekly returns.
The CFTC alleged that Cash FX engaged in minimal forex trading and misappropriated most of the participant funds, using new contributions from participants to pay fictitious trading profits while directing millions of dollars to each defendant.
Related: Bernstein expects ‘aggressive’ rulemaking from SEC, CFTC, following CLARITY Act failure
Cash FX also provided false accounting statements to participants, who lost at least $406 million, the CFTC alleged.
“The Division of Enforcement has continued to refocus on its core mission of protecting the public from fraud and manipulation,” said Director of Enforcement David I. Miller. “This critical action, and the massive fraud it targets, reflects our steadfast commitment to addressing fraud wherever we find it.”
Cointelegraph reported Sept. 18 that the CFTC had submitted a new regulatory action covering crypto asset transactions and markets for White House review, as the agency moves forward with its approach to overseeing the digital asset sector.
While details of the planned regulations were not disclosed, the submission came days after the Senate failed to advance the CLARITY Act, legislation aimed at establishing a federal regulatory framework for crypto markets.

Star Suffers Hyperextended Knee, Zidane Says ‘Things Aren’t Going Well’

Whatever Happened to the 150,000 Tons of Radioactive Waste Stored Under the Atlantic Ocean?
M. Night Shyamalan Officially Confirms the Fate of His Superhero Franchise [Exclusive]





-

 Crypto World3 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-

 Tech6 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Fashion2 days ago
8 iPhone Accessories That Add Personality
-

 Crypto World5 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Tech7 days ago
Trump suggests rebranding AI with a new name, says he’s also creating an AI Force
-

 Business5 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Entertainment3 days ago
These 17 Fall Amazon Dresses Seriously Look Like Anthropologie
-

 Crypto World3 days ago
This Bearish Netflix Stock Trade Can Cash In On Video Streaming Giant’s Woes
-

 Crypto World5 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World4 days ago
Trump-Xi Polymarket Odds for Handshake Hit 50%
-

 Tech5 days ago
Google’s $899 Googlebook is a bet that you’ll buy a new laptop for Gemini
-

 Crypto World2 days ago
Crude Oil Prices Pressured by Diplomatic Hopes in the Middle East
-
 Business3 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-
 Crypto World2 days ago
Bitcoin price tests $83,600 Supertrend support after $87K rejection
-

 Crypto World3 days ago
Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike
-

 Crypto World4 days ago
Meta Jumps 11% As Muse Shines and Investors Show an Appetite for Advancing AI
-
 Crypto World3 days ago
Did Jim Cramer Just Give GameStop Stock the Kiss of Death When He Said the Turnaround Is Working?
-

 Crypto World5 days ago
Bitcoin price holds above $81K as key catalysts line up
-
 Crypto World5 days ago
ARB Price Signals Spur Speculation of 70x Upside in Hodler Digest
-
 Crypto World4 days ago
Trump, Xi Meet on S&P 500's Best Day Since Early August: Will Markets Stay Bullish?
You must be logged in to post a comment Login