Business & Hustles
Chick-fil-A Hits $10.3 Billion in Revenue While Staying a Family Business, CEO Says

Chick-fil-A is proving that a family business can still outgrow nearly every rival in the restaurant industry without ever ringing a bell on Wall Street. The Atlanta-based chicken chain pulled in $10.3 billion in revenue last year, a 14% jump, and net income of $1.05 billion, according to franchise disclosures reviewed by CNBC. That performance, paired with $23.92 billion in systemwide sales across roughly 3,000 locations, makes it the third-largest restaurant chain in the country by sales, trailing only McDonald’s and Starbucks.
Yet CEO Andrew Cathy, who took over from his father Dan nearly five years ago, insists the company has no interest in chasing the kind of windfall an initial public offering could bring. “We’re able to plan for the quarter century, and we don’t have to plan for the quarter,” Cathy told CNBC, describing the company’s growth strategy as “calculated” and “conservative” even as it pushes into new international markets.
Why staying a family business still works
Chick-fil-A was founded by Cathy’s grandfather, S. Truett Cathy, and has remained privately held and family-controlled ever since. That structure means the company doesn’t report quarterly earnings to shareholders or face pressure to hit short-term growth targets — a freedom Cathy says lets leadership focus on decades-long plans rather than fiscal quarters.
The timing of that philosophy looks especially shrewd given how public restaurant stocks have performed this year. Shares of Jersey Mike’s have dropped nearly 28% since its July IPO, and Dunkin’ parent Inspire Brands is reportedly holding off on going public until the sector’s fortunes improve. For a family business like Chick-fil-A, staying out of public markets has become less a sentimental choice and more a practical advantage.
It also hasn’t slowed expansion. The chain opened 179 new restaurants last year and has launched operations in Canada, the United Kingdom and Singapore in recent years, part of a $1 billion international growth plan. Its venture arm has also rolled out Daybright, a beverage-focused concept aimed at capturing a different kind of customer than the flagship chicken sandwich shops.
Navigating industry headwinds
The broader restaurant industry has had a rough stretch. Elevated costs and increasingly selective consumers have hurt traffic at McDonald’s, Popeyes, KFC and other major chains. Cathy acknowledged the pressure but said Chick-fil-A’s locations haven’t seen the same slump. “This has been a good year,” he said. “Our operators have done such a good job executing on the fundamentals and adding the hospitality to it.”
That focus on hospitality is central to how Cathy frames the balance between legacy and growth. He compared running the business to driving a race car: “There’s a reason that the windshield’s bigger than the rearview mirror. It’s important for the rear view to be grounded on where you are, and there are things that we think about our purpose, our mission, that won’t change, but everything else we have to be able to evolve and change.”
Some traditions are untouchable — Chick-fil-A’s restaurants will continue closing on Sundays, a policy in place since the company’s founding. Others, like the specifics of in-store hospitality, are expected to shift as customer habits evolve, particularly around how people order and receive food. Cathy said the chain is taking a “human plus” approach to new technology, exploring tools like artificial intelligence and even drone delivery without abandoning the personal service that has defined its brand.
As competitors chase public listings or restructure under private equity ownership, Chick-fil-A’s choice to remain a family business stands out as increasingly rare among chains of its size. For Cathy, that rarity is the point — a bet that long-term thinking, not quarterly results, is what keeps the chain growing while so many rivals stumble.
Explore more on this topic with Vexel Search.
With lump-sum investors losing money and SIP investors making only low single-digit returns over the past two years, what should investors expect going forward?
We have been telling investors to focus on asset allocation, unconstrained investing, and expect moderate returns. The reason for moderate returns is precisely the current environment, where the US AI cycle is driving a large part of global markets, geopolitical risks remain elevated, and global equity markets are expensive. At some point, expensive markets will have to correct.
Do you still feel the market is expensive?
We are in middle territory. The sectors connected to US AI look overvalued unless you have a growth mindset. Small- and mid-cap stocks are not cheap largely because of the sustained flows into them. It is not that such companies are not growing. They can certainly be growing, and some may even be growing faster than large-cap companies.

How are you looking at markets keeping in mind the continued boom in AI?
If AI-related growth continues to remain strong, Indian equity markets may continue to face pressure from shifting global preferences. However, when AI-led growth begins to slow, we believe India could see a rebound in investor interest as capital looks towards markets with stronger domestic growth prospects.Read more: Indian stocks face a cyclical correction, not a deeper earnings reset: Mahindra Manulife MF CIO
What is your assessment of the flood of IPOs?
We think IPOs are trading at higher prices than many of the older listed companies. There seems to be a bigger bull market in IPOs than in the broader market.
So where would you allocate and where would you stay away?
I like contrarian investing now because of the significant gap between what has performed well and what has not. At this point, we like sectors such as private-sector banks and insurance, where growth is not a problem. We are also positive on insurance following the proposed regulatory changes announced recently. Our experience in the mutual fund industry has been that whenever regulations have become more customer-friendly, the industry has grown. That is why we see the changes in the insurance industry as a positive trigger from a longer-term perspective.
But in sectors such as IT and FMCG, growth has been an issue. The challenge is that people always want either a very positive view or a very negative view. The reality is somewhere in between.
What kind of earnings growth do you expect over the next three years?
Over the near term, earnings growth is likely to remain reasonably good. One reason is that inflation is positive for earnings. Second, when inflation is rising, consumers often advance their purchases. This brings demand forward. So, in the near term, earnings are likely to remain reasonably decent. In the medium term, however, earnings will depend on what happens to the US AI cycle. If the US AI cycle eventually leads to deflation, purchasing decisions could get postponed. Companies may reduce inventories, and consumers may defer purchases. That can have an impact on earnings growth.
How should investors approach gold and silver?
Investors need not be negative on gold at this point. We continue to like gold as a component of multi-asset investing.
There is a rush among investors to allocate money overseas to diversify
At this point, we would be cautious about making a momentum-driven decision to invest overseas. Both the currency and global equity markets have moved significantly. Investors should be conscious of the fact that they may be investing following a period of strong performance.
The situation, however, is different with global bonds. Bonds have performed poorly globally, so investing in global fixed income today is less of a momentum decision.
Do you think FPIs will return to India soon, especially when US interest rates are at a two-decade high?
Right now, investors can earn around 5.3-5.5% in US Treasury instruments. They can also invest in US bonds and earn attractive yields without significant currency risk. For FPIs to return significantly to India, we will need an environment of lower global interest rates.
Our view is that we are not very far away from the peak in US interest rates. There could perhaps be two more hikes, but after that we do not believe the hiking cycle will continue indefinitely.
There is one major engine, i.e., the US AI cycle, which is driving a large part of the global investment environment. Emerging markets are not seeing significant inflows. It is not just India. This year, for example, money has gone out of markets such as Korea and Taiwan. Some money is going into Brazil and other countries, partly because they are large oil producers.
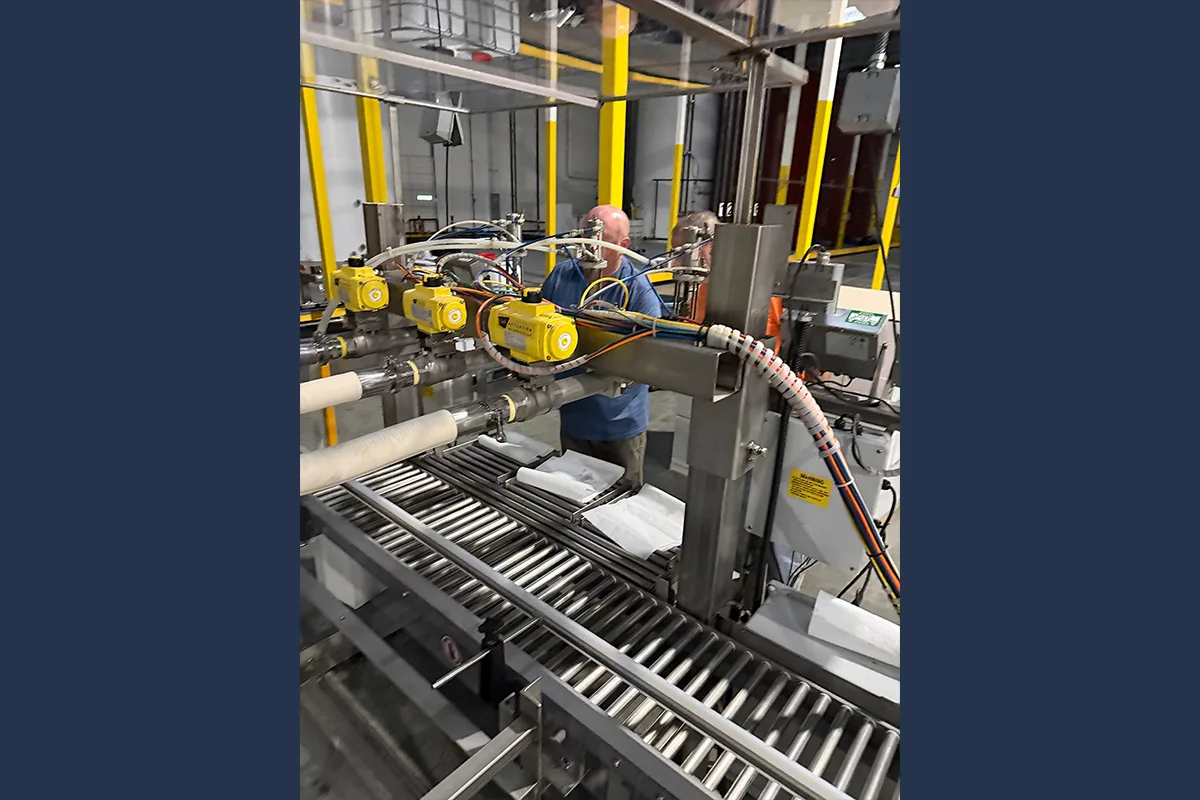

Las Vegas facility will produce a range of conventional, non-GMO and organic oils.
Business & Hustles
Suppliers Warn of “Second Energy Crisis” as Government Faces Pressure Over Energy Bills

Energy bills are once again at the centre of a political storm, with the industry’s own trade body warning the government that delaying support for struggling households could trigger a deeper and more expensive crisis than the one Britain endured just a few years ago.
Energy UK, which represents suppliers, says ministers need to act immediately rather than wait for conditions to worsen further. The warning comes after domestic gas prices rose on Thursday and new forecasts pointed to a steep increase in energy bills from January, just as colder weather pushes up demand.
Figures reported by the BBC this week suggest a 16% rise in domestic energy prices is likely in the new year for roughly 20 million households on variable tariffs governed by regulator Ofgem’s price cap. That cap, which limits the maximum price suppliers can charge per unit of gas and electricity, already rose by 4% at the start of October — adding about £60 a year, or £5 a month, to a typical household’s costs and pushing the average annual bill for dual-fuel customers paying by direct debit to £1,723.
Energy bills could near £2,000 by January
The outlook for the new year is considerably bleaker. Consultancy Cornwall Insight forecasts that the same typical annual bill could rise to £1,999 in January, a jump that would mark the sharpest seasonal increase in four years and pile further strain on household budgets already stretched by the broader cost of living.
Energy UK acknowledges the government has taken some steps to ease the burden, including a cut to VAT on electricity bills that took effect on Thursday and the earlier removal or shifting of certain levies into general taxation. But the trade body argues those gains have already been swallowed up by soaring wholesale costs, which suppliers must pay before passing charges on to customers.
Much of that wholesale pressure, the organisation says, stems from international instability — particularly conflict in the Middle East and disruption to shipping routes through the Strait of Hormuz — echoing the dynamics that sent bills spiralling after Russia’s invasion of Ukraine in 2022.
“We cannot afford to wait,” says industry chief
Dhara Vyas, chief executive of Energy UK, said the lessons of the last crisis must not be ignored. “We cannot afford to wait for the same scale of crisis before acting again,” she said, pointing to mounting customer debt as evidence that households are already struggling before the worst of the winter price rises take hold.
Vyas said the growing debt burden now adds an average of £67 a year to every household’s bill, regardless of whether they are behind on payments themselves. “Last-minute emergency interventions run the risk of being badly targeted and costing us all more,” she warned, urging the government to move before prices jump again in January rather than scrambling to respond afterwards.
Her comments followed a stark warning from Simone Rossi, chief executive of EDF Energy, who said on Thursday that the UK was “walking into a second energy crisis.” Adam Scorer, head of the fuel poverty charity National Energy, echoed the concern, telling BBC Breakfast that rising debt levels reflect not simply more people falling behind on payments, but poorer households sinking deeper into financial difficulty with no clear way out.
“Until you do something about that, there’s no way forward, there’s no breathing space, there’s no future for households who can’t see their way beyond debt,” Scorer said.
What suppliers want the government to do
Energy UK has set out a series of measures it wants ministers to consider as part of an urgent response. These include targeted financial support that goes beyond the existing £150 Warm Home Discount offered to people on benefits, eventually paving the way for a discounted social tariff for the most vulnerable customers.
The trade body is also calling for a debt relief scheme aimed at households that have fallen furthest behind, alongside a broader strategy to stop debt accumulating among new tenants and homeowners in the first place. It further wants more levies stripped from electricity bills and shifted onto general taxation, part of a long-term push toward electrification that supporters argue would make switching away from gas more financially attractive.
Prime Minister Andy Burnham, speaking after the warnings emerged, said he would not describe Rossi’s “second crisis” comments as an overstatement, acknowledging that the cost of home energy — along with petrol and diesel prices — remained “very difficult indeed” for many families. He said the government was “looking at any measure that can give people breathing space, that can take the pressure off.”
With forecasts pointing to energy bills climbing toward £2,000 a year for typical households by January, pressure is mounting on Westminster to decide quickly whether it will intervene now or risk repeating the costly, reactive scramble that characterised the last major energy crisis.
Costa Coffee says it has delivered a year of “strong progress,” rebounding to profitability just months after its parent company, Coca-Cola, quietly abandoned efforts to sell the chain to a private equity buyer.
The UK’s second-largest coffee chain grew revenue by five per cent to £1.3bn last year and swung back into operating profit, according to accounts filed by the company. The turnaround marks a notable reversal of fortune for a brand that just a year ago was being shopped around to buyout firms as Coca-Cola looked to cut its losses on a business it bought for £3.9bn in 2018.
Costa Coffee Returns to Profit After Rocky 2024
Costa posted an operating profit of £20m in 2025, a sharp turnaround from the £13.5m loss recorded the previous year. The company attributed that earlier slump to “soft footfall and growth of value-led competitors” — a polite way of describing the squeeze cheaper rivals have put on traditional coffee shop chains across British high streets.
Still, not every metric moved in the right direction. Costa’s statutory profit actually fell by seven per cent to £62m, a reminder that headline recovery narratives rarely tell the whole story. The gap between operating performance and bottom-line profit suggests one-off costs or accounting adjustments took some shine off an otherwise upbeat set of results.
Chief executive Philippe Schaillee credited the company’s investment programme — a mix of store refurbishments and product innovation — for driving the improvement. “These results demonstrate the strength of the Costa brand and the dedication of our hard-working teams, who serve great coffee with heart every day, and reinforce our focus on building sustainable long-term growth,” he said.
A Sale That Never Happened
The backdrop to this recovery is Coca-Cola’s abandoned attempt to offload Costa. The beverage giant had been seeking roughly £2bn for the chain, with names including Asda owner TDR Capital, Gail’s backer Bain Capital, and private equity firm Apollo reportedly circling as potential buyers. But in January, Coca-Cola scrapped the sale process after bids came in below its expectations.
That decision leaves Costa Coffee back under the Coca-Cola umbrella for now, with the drinks giant presumably watching closely to see whether this year’s improved numbers represent a genuine turnaround or a temporary bounce. Either way, the failed sale has given Costa breathing room to pursue its own recovery plan rather than operating under the uncertainty of a looming ownership change.
Losing Ground to Greggs and Cheaper Rivals
Despite the improved financials, Costa’s position atop the UK coffee market has slipped. Earlier this month, bakery chain Greggs overtook Costa to become the country’s largest branded coffee destination by outlet count, with 2,737 sites compared with Costa’s 2,707. For a brand that has long positioned itself as Britain’s coffee shop of choice, ceding that crown to a bakery chain best known for sausage rolls is a symbolic blow.
The competitive pressure runs in both directions. Budget-focused operators have chipped away at Costa’s customer base from below, while upmarket entrants like Blank Street have begun appearing on UK high streets, targeting younger, trend-conscious coffee drinkers from above. Costa also has the dubious distinction of having the highest proportion of sites within a five-minute drive of another coffee brand — 73 per cent as of December 2025 — underscoring just how saturated and fiercely contested the UK coffee market has become.
In response, Costa appears to be prioritising quality over sheer scale. The chain opened just 79 new UK stores in 2025 and plans to open only 40 to 50 new sites over the coming year — a notably cautious expansion pace for a brand that once blanketed town centres with new openings.
Betting on Refurbishments and New Flavours
Instead of chasing growth through new store openings, Costa has poured resources into revamping existing locations. The company has refurbished 1,063 stores across the UK and Ireland since 2023, including 305 last year alone, and plans to refresh roughly 210 more sites in 2026.
Product innovation has also played a role in the recovery. Costa pointed to its Matcha and Ube drinks as key drivers of customer growth, with iced beverages proving especially popular during last year’s summer heatwaves. “Costa is deliberate with innovations, ensuring that innovations have staying power that Costa can scale really well,” the company said. “That’s the advantage of Costa’s scale: when we see something customers genuinely want, we can make it accessible to millions of people.”
The chain still serves more than four million cups of coffee daily and counts six million active members in its loyalty scheme — scale that gives Costa Coffee a cushion even as its market lead narrows. Whether that scale is enough to fend off cut-price challengers and premium newcomers alike will determine if this year’s progress marks a lasting recovery or merely a pause before the next downturn.

I’m a passionate investor from the Netherlands with 12 years of stock market experience. My articles usually contain a good overview of important investment criteria. A stock for my portfolio is of interest to me if the company has the following characteristics:1. Companies that are growing in both revenue, earnings and free cash flow.2. Companies that have excellent growth prospects.3. Stocks with favorable valuations.I prefer steadily growing companies with high free cash flow margins, dividend stocks and stocks with generous share repurchase programs.Disclaimer: My articles do not provide financial advice, they reflect my own findings and insights.
Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
Diesel prices in the UK have broken through £2 a litre for the first time, a grim milestone that has forced the world’s richest nations into emergency action to prevent a full-blown global energy crunch from spiralling further out of control.
The RAC said the average cost of diesel reached 200.01p a litre on Friday, with petrol also climbing to 174.71p. The motoring group warned the rises were “showing no signs of slowing, heaping more misery onto motorists” — a blunt assessment that captures the mood among hauliers, farmers and ordinary drivers who have watched fuel costs climb relentlessly since the start of the year.
The surge has been driven by a combination of forces rarely seen together: the ongoing US-Israel war with Iran has disrupted production and shipping routes across the Middle East, Ukrainian strikes on Russian refineries have knocked out supply, and China has tightened exports of refined fuel. Layered on top of all that was a fresh threat from Washington that briefly pushed diesel prices even closer to crisis territory.
Trump’s export threat forces G7 hand on diesel prices
President Donald Trump had threatened to ban US diesel exports altogether unless European nations agreed to release more of their own stockpiles, a move designed to ease the burden on American consumers and businesses ahead of November’s closely watched midterm elections. Treasury Secretary Scott Bessent argued that US farmers, truckers and businesses “should not be left carrying the burden” of soaring prices.
Had the ban gone ahead, it would have ripped a vital supplier out of global markets just as diesel prices were already testing record highs. The US produces four to five million barrels of diesel a day, exporting roughly 1.2 to 1.5 million barrels of that surplus — a lifeline for countries such as the UK, which imports over half its diesel, with around 17% of total supply coming from America.
Facing pressure from European leaders, the G7 struck a deal on Friday to release 100 million barrels of oil and diesel over the next four months, coordinated through the International Energy Agency. A “substantial” diesel release is due within the first 20 days, with further releases possible if needed. Crucially, G7 members also agreed not to impose export restrictions on each other’s energy products — effectively taking Trump’s threatened ban off the table.
French President Emmanuel Macron, who chaired the talks, said the coordinated release would “bring down the prices of petroleum products, particularly diesel,” adding that Trump had been “very clear” in backing away from export restrictions. The UK’s Foreign Secretary, Ed Miliband, said the plan would “stabilise energy supplies, build resilience in supply chains and shield households and businesses from price shocks.”
Trump later told reporters at the White House that a ban had “never really on the table,” praising Europe’s decision to tap its reserves as “a great thing” and insisting the US would also contribute to the release rather than cut off exports.
Markets react, but relief may be temporary
The announcement briefly pushed global benchmark Brent crude below $100 a barrel, before it rebounded to around $102 after renewed hostilities between Saudi Arabia and Houthi forces in Yemen reignited fears over shipping routes through the Bab-el-Mandeb strait. Before the US and Israel became directly involved in the Iran conflict, Brent crude was trading at roughly $73 a barrel — underscoring just how much ground markets have lost over the past seven months.
Analysts say the scale of the G7 release should take some heat out of diesel prices in the coming weeks, but warn that underlying supply problems — disrupted Russian refining capacity, Chinese export curbs and ongoing Middle East instability — are unlikely to disappear overnight. Matt Smith of commodities research firm Kpler said the market remained jittery, with any fresh escalation in the region capable of reversing recent gains almost instantly.
For now, the practical impact is being felt most acutely by those who depend on diesel for their livelihoods. Norfolk farmer Mark Means told the BBC he had spent £50,000 on new diesel tanks just to secure enough fuel for planting and harvesting, describing the rising costs as feeling “like an assault” on his business. Driving instructors, delivery firms and haulage companies report similar strain, with the RAC estimating it now costs £110 to fill an average family diesel car — almost £32 more than before the US-Iran war began.
Energy bills add to the squeeze
The pain at the pump is unfolding alongside a parallel crisis in household energy bills. Suppliers’ trade body Energy UK has urged the government to act immediately, warning that forecasts pointing to a 16% rise in bills for 20 million households in January could trigger a repeat of the 2022 energy crisis sparked by Russia’s invasion of Ukraine.
Ofgem’s price cap already pushed bills up 4% at the start of October — about £60 a year for a typical household — and consultancy Cornwall Insight expects the annual bill to climb to £1,999 by January. Energy UK chief executive Dhara Vyas said rising wholesale costs, partly driven by the same Middle East turmoil pushing up diesel prices, had wiped out savings from recent VAT cuts and levy changes. “We cannot afford to wait for the same scale of crisis before acting again,” she said.
Prime Minister Andy Burnham said the government was “looking at any measure” that could ease the pressure, acknowledging that the combined burden of home energy costs and record diesel prices was “very difficult indeed” for households and businesses alike.
A wider economic picture under strain
The fuel and energy turmoil lands against a backdrop of broader economic unease on both sides of the Atlantic. In the US, the latest jobs report showed employers added just 29,000 positions in September, a sharp slowdown from August’s 133,000, with unemployment ticking up to 4.2%. Economists said the softer labour market reduced the odds of further Federal Reserve rate hikes, even as Trump continues to insist the American economy is the “hottest” in the world — a claim increasingly at odds with public sentiment, with only 17% of Americans approving of his handling of living costs.
Back in the UK, the squeeze on household budgets is also reshaping long-term financial behaviour. A growing number of younger workers are opting out of workplace pensions to free up cash for immediate costs, including fuel and energy bills, raising concerns from ministers that today’s cost-of-living pressures could translate into a harder-hit generation of retirees tomorrow.
For now, the G7’s intervention has bought some breathing room, averting the immediate threat of a US export ban and signalling that further coordinated releases remain on the table if diesel prices continue climbing. But with winter approaching, a volatile Middle East, and energy bills already forecast to rise sharply, households and businesses on both sides of the Atlantic are bracing for a winter in which fuel and energy costs remain firmly centre stage.
- G7 to release millions of barrels of oil and diesel after Trump threat (BBC)
- Suppliers pile pressure on government over energy bills (BBC)
- UK diesel prices top £2 a litre for first time, RAC says (BBC)
- US jobs market sees sharp slowdown ahead of midterm elections (BBC)
- 'It could cost me £10k but I need the money now': Why Gen Z are opting out of pensions (BBC)
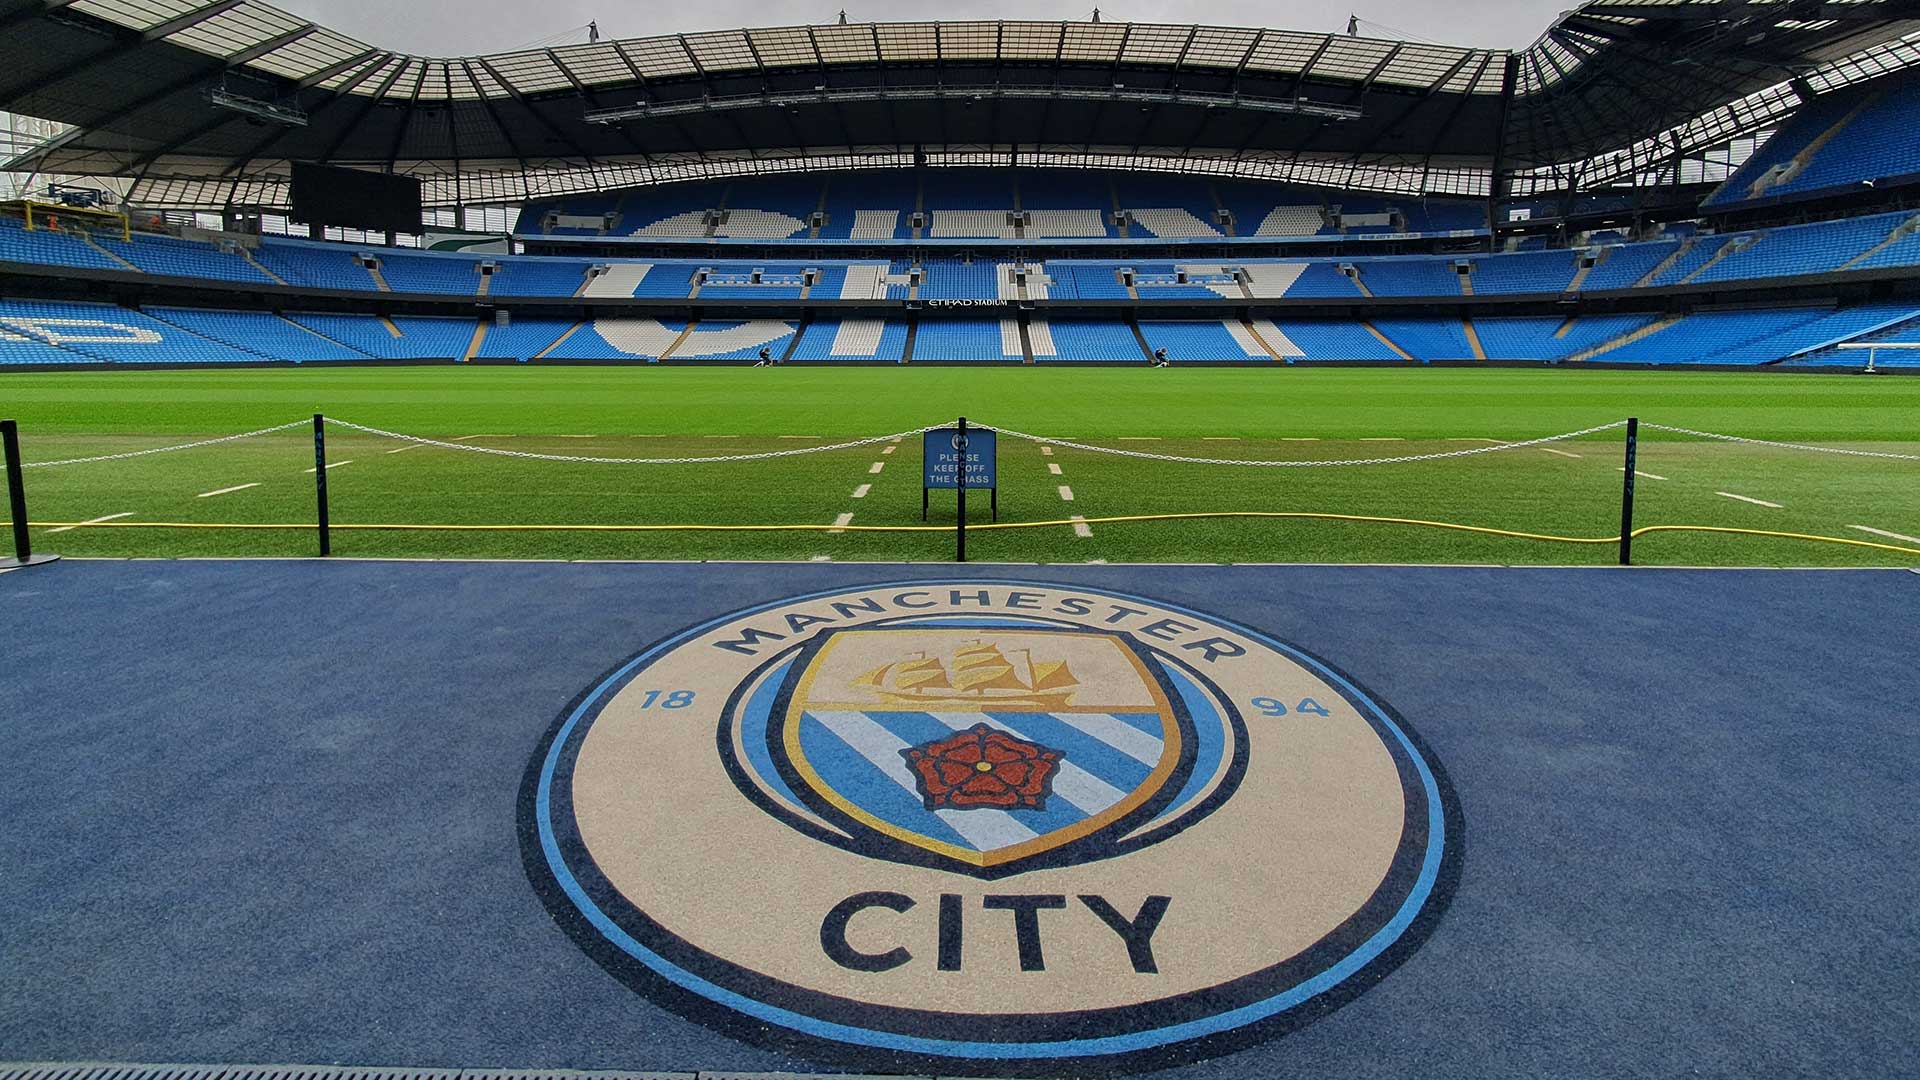
The United Arab Emirates has warned the government it could cancel billions of pounds of investment in the UK over the Premier League’s ruling against Manchester City, according to reports by Bloomberg and The Telegraph.
Emirati officials said “the Premier League’s actions” would “have an influence on the bilateral state relationship”, Bloomberg reported.
The Telegraph said the UAE is threatening to scrap billions of pounds of private investment for a hi-tech, Silicon Valley-style hub between Oxford and Cambridge. The Treasury said in March that up to £800m was available for land and infrastructure in the Oxford to Cambridge Growth Corridor, which it described as the UK’s “Silicon Valley”.
The newspaper also reported that Khaldoon Al Mubarak, the Manchester City chairman, met Jonathan Reynolds, the business secretary, in Downing Street two weeks before the Premier League announced its decision.
Al Mubarak was group chief executive of Mubadala, the Abu Dhabi sovereign wealth fund, when in 2021 it committed £10bn to UK investment over five years in sectors including clean energy, infrastructure, technology and life sciences.
On Thursday, Downing Street said the guilty verdict against City is “serious”, after Andy Burnham, the prime minister, said he would be “really concerned” to see the club’s current owners sell up.
A spokesperson for the prime minister issued two clarifications of his position during the day.
Asked by the BBC earlier this week if he was worried about the current owners selling the club, Burnham said: “I would be really concerned to lose them. They’ve been such a huge partner in the building of modern Manchester. Obviously, the building of Manchester City into the global force that it is.”
Asked whether his dealings with the club would stand up to scrutiny, he said: “I do actually thank the City Football Group and the wider ownership for the money that they didn’t just put into the Etihad and the campus around it but also into the city, but yes, of course.”
Louie French, the Conservative shadow sport minister, accused Burnham of “publicly backing the owners” amid a probe into the club’s funding over recent years, and described his comments as “frankly extraordinary”.
The Liberal Democrats called on Burnham to publish all details of his meetings with Manchester City’s owners, the Abu Dhabi United Group (ADUG), and to declare all hospitality he has accepted at the Etihad Stadium.
David Bernstein, the former chairman of both City and the Football Association, said he was “concerned” about Burnham’s comments and that the issue was “something that politicians should be seen to be staying well away from”.
City were found guilty of charges related to breaches of financial rules between the 2009-10 and 2017-18 seasons.
The Premier League said on Tuesday that an independent commission found City arranged “sham” commercial deals with a number of its sponsors during the period. The deals were part of a disguised funding scheme under which those companies were required to pay only a portion of the relevant sponsorship fees.
The commission found that the remainder was funded by Abu Dhabi United Group Investment & Development Ltd, which owned the club.
According to the Premier League’s statement, the purpose of the schemes was found to have been to inflate the club’s revenues and reduce its costs by more than £900m over the period, so that it appeared to comply with financial rules.
The league said the question of sanction will be addressed separately in a further hearing before the commission, which will remain private until publication of the outcome is permitted.
The Premier League said the club had until 2 October to appeal against the commission’s findings. City deny the charges and have said they intend to appeal.

Paul Jones
Harvard alumni and former New York Times journalist. Editor of Business Matters for over 15 years, the UKs largest business magazine. I am also head of Capital Business Media’s automotive division working for clients such as Red Bull Racing, Honda, Aston Martin and Infiniti.
Business & Hustles
G7 Strikes Emergency Deal to Flood Market With 100 Million Barrels After Trump’s Diesel Ultimatum
The world’s richest democracies scrambled into crisis mode on Friday, agreeing to release up to 100 million barrels of oil and diesel from their emergency reserves after President Donald Trump threatened to cut off American fuel exports and plunge Europe deeper into an energy squeeze that had already pushed British pump prices past the symbolic £2-a-litre mark.
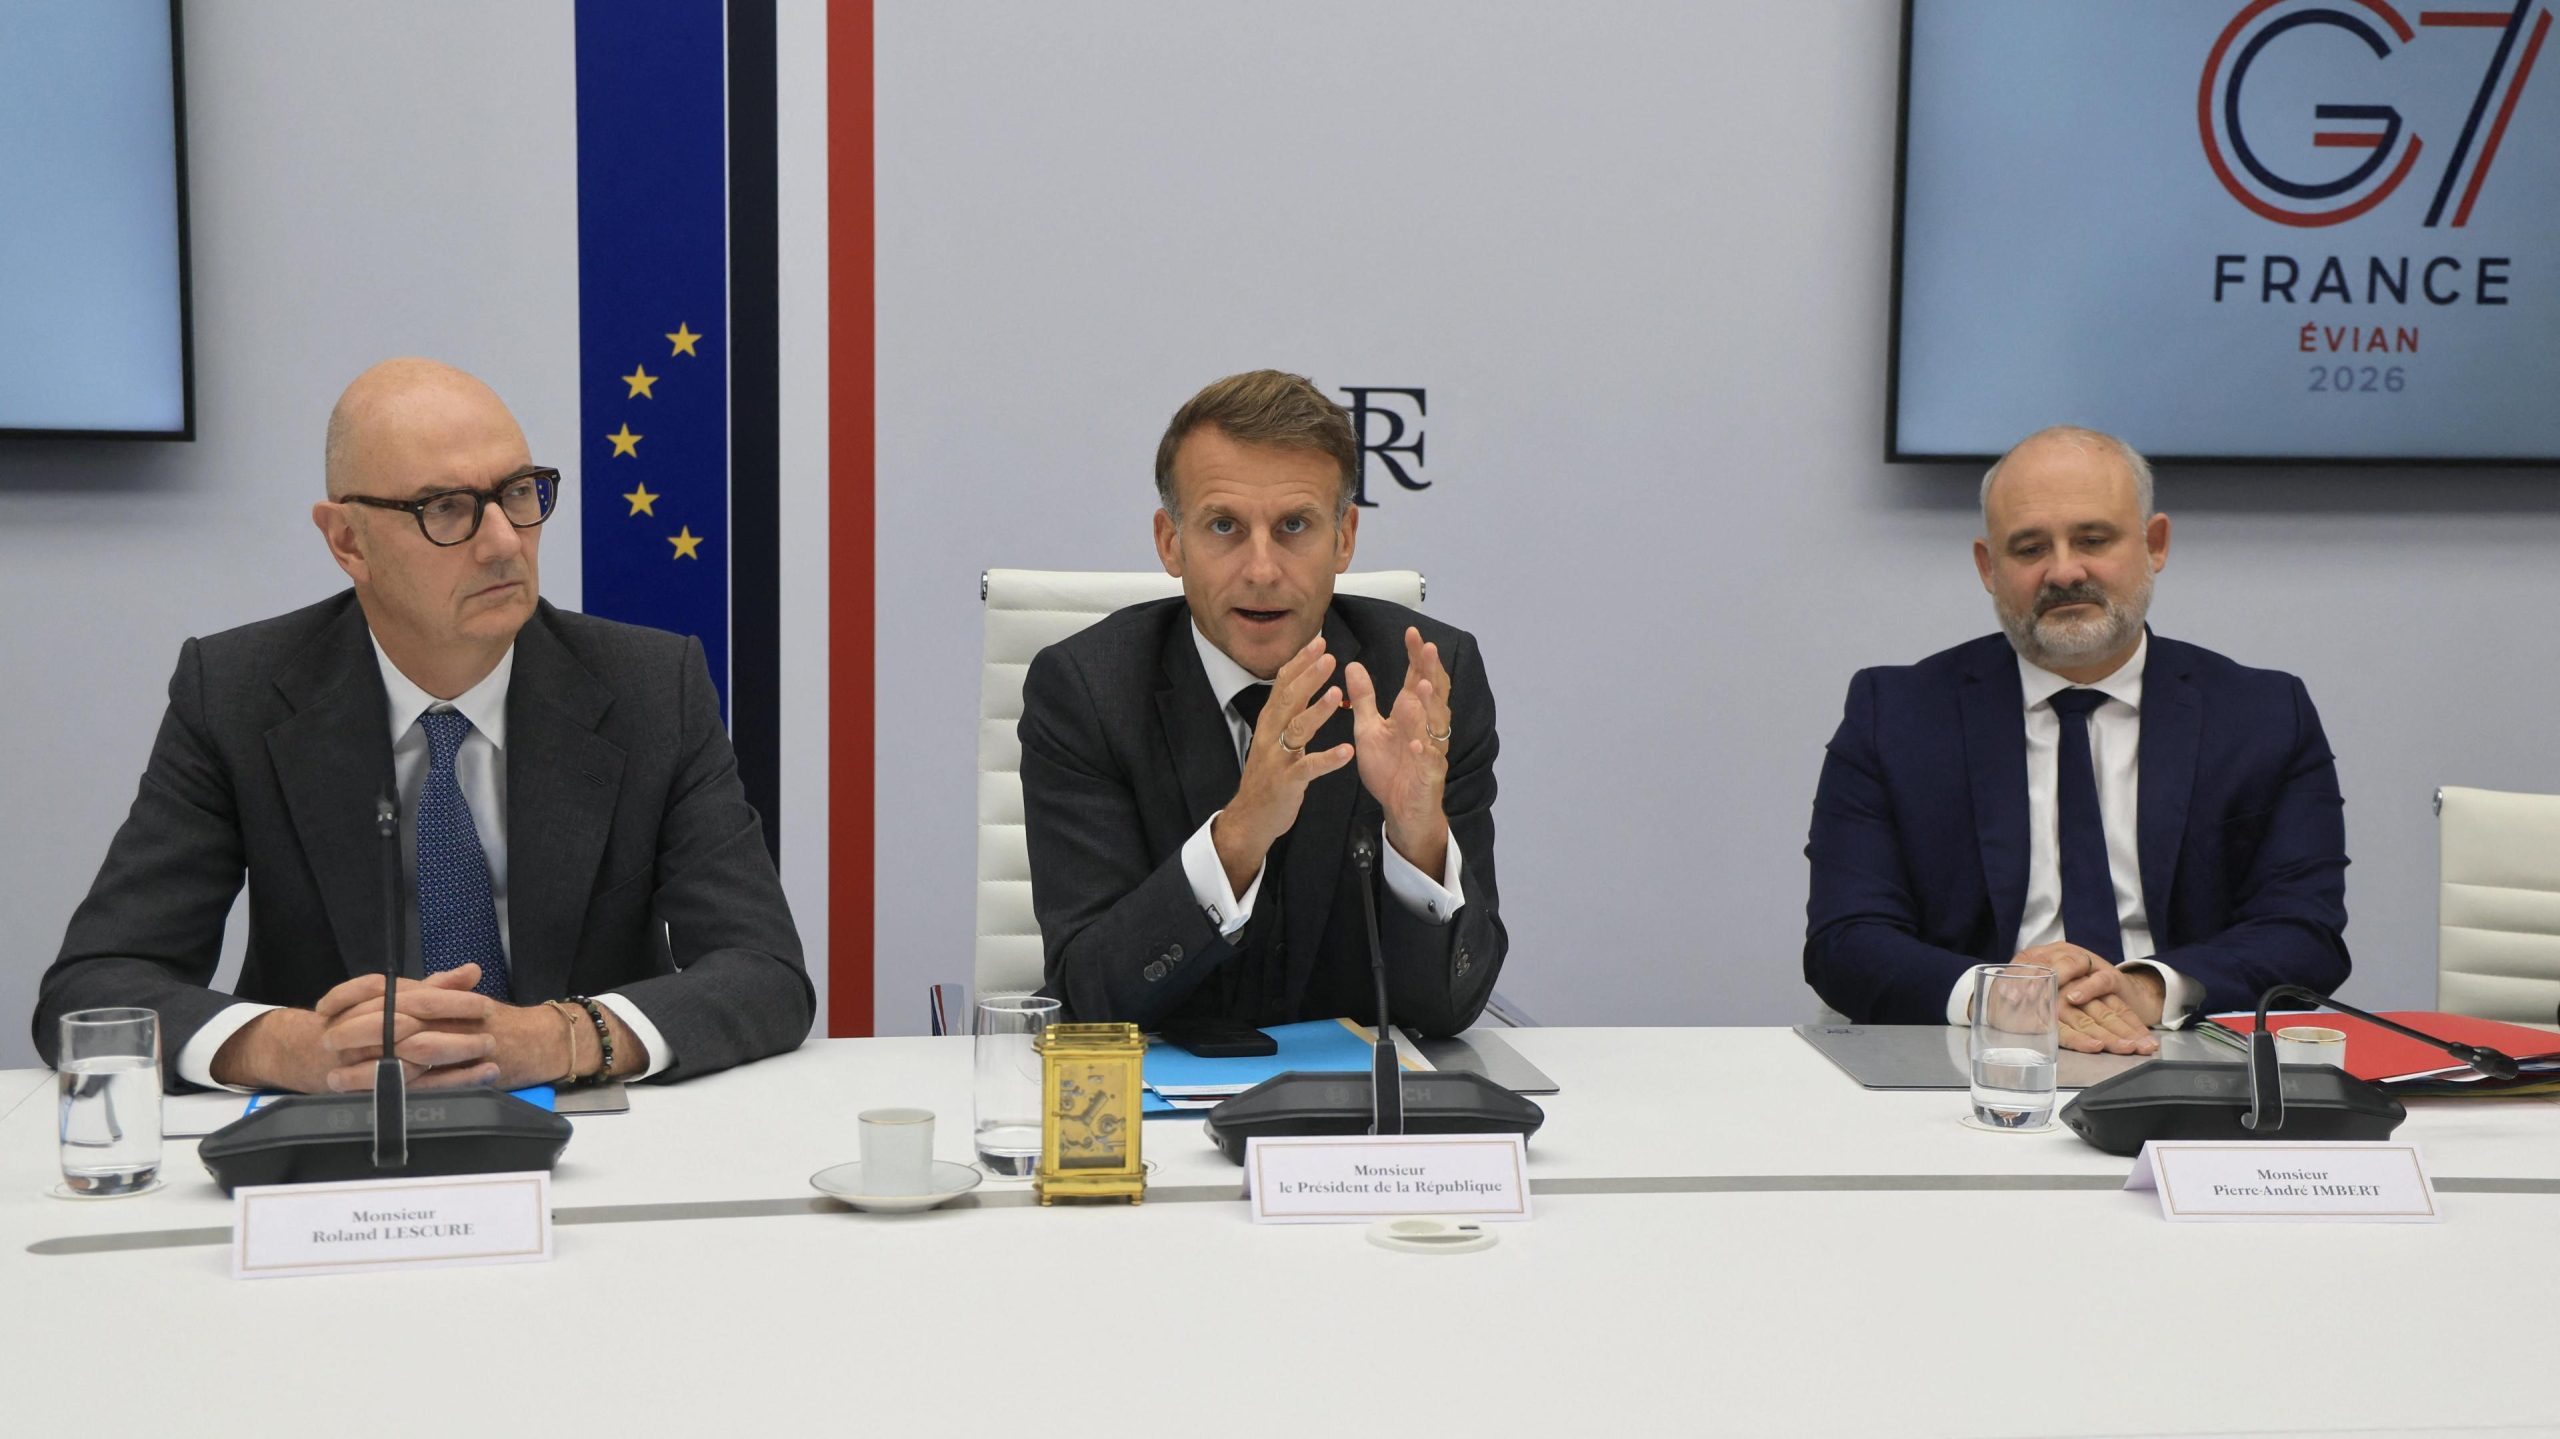
The agreement, hammered out on a video call chaired by French President Emmanuel Macron, defused a brewing transatlantic row that had pitted Washington against its closest allies at the worst possible moment: with diesel prices at record highs, war still rattling Middle Eastern oil infrastructure, and Russian refineries under sustained Ukrainian drone attack.
Under the deal, G7 members — the US, UK, Canada, Japan, Germany, Italy and France, alongside the EU — will coordinate a drawdown of roughly 50 million barrels of crude oil and 50 million barrels of diesel through the International Energy Agency over the next four months. Crucially, officials promised a “frontloaded substantial diesel release” within just 20 days, an acknowledgment that the fuel crunch is doing the most immediate damage to consumers and businesses.
Just as significant as the barrels themselves was what the G7 agreed to stop doing: in a joint statement, leaders pledged to “refrain from export restrictions on energy and energy products” against one another — language clearly aimed at neutralising Trump’s threat to ban US diesel exports outright.
Macron said the American president had been unambiguous on that point. “We are all committed to ensuring there are no export bans, and President Trump, in particular, was very clear on this point,” he told reporters after the call. Trump, for his part, declared victory on social media, writing that Europe had “agreed to release a massive amount of their heavily stocked Diesel Oil” and that the process would “begin immediately.”
The standoff had been building for days. The US is the world’s dominant diesel exporter, refining four to five million barrels a day while consuming only about 3.6 million domestically — leaving over a million barrels a day destined for overseas buyers, many of them in Europe. But that export flow had drained America’s own stockpiles to their lowest seasonal level since 1996, sending US pump prices surging past $5.85 a gallon and creating a political headache for Trump ahead of November’s midterm elections.
Treasury Secretary Scott Bessent argued American truckers, farmers and businesses “should not be left carrying the burden” of propping up global supply, and pressed Europe to release its own stockpiles rather than lean indefinitely on US exports. The implicit threat, should Europe fail to act, was a ban that would have starved allies of fuel they badly needed.
For Britain in particular, the stakes could hardly have been higher. More than half the UK’s diesel is imported, with roughly 31% of that coming from the US — far more exposure than France or Germany, which each hold up to 400 days’ worth of diesel in storage. The UK’s own reserves cover only 40 to 50 days. Capital Economics warned this week that a full US export ban could have driven UK pump prices beyond 300p a litre, with chief UK economist Paul Dales cautioning that prolonged disruption would risk feeding into broader inflation and potentially force the Bank of England to keep interest rates higher for longer.
Those fears were already materialising before the G7 deal was struck. The RAC motoring group said the cost of filling an average family car in the UK had hit £110 — nearly £32 more than before the war between Israel, the US and Iran upended Middle Eastern oil flows. Foreign Secretary Ed Miliband represented Britain on Friday’s call, saying the measures agreed would “stabilise energy supplies, build resilience in supply chains and shield households and businesses from price shocks.”
The broader supply picture explains why prices have spiralled so dramatically. Conflict in the Middle East has curtailed both crude extraction and refining capacity across the region, while Russia — hit by a wave of Ukrainian strikes on its refineries — has imposed its own diesel export ban, pushing its fuel output to 20-year lows. China, a major buyer of Gulf crude, has further tightened the global market. Diesel is notoriously difficult to refine compared with petrol, and because it underpins haulage and agriculture, demand is almost impossible to throttle back without hitting food and freight costs directly.
Markets registered cautious relief at the announcement. Brent crude, the global benchmark, briefly dipped below $100 a barrel before settling around $102 — still a long way above the roughly $73 it fetched before the US and Israel struck Iran, but a step back from the peak of the panic.
Beyond the immediate release, G7 leaders said they would coordinate refinery maintenance schedules to avoid multiple plants going offline simultaneously, and would encourage nations with spare refining capacity to prioritise diesel production. They also reaffirmed that sanctions on Russia over its war in Ukraine would remain firmly in place, even as the bloc leans on global supply elsewhere to ease the squeeze.
What remains unclear is exactly how the burden will be shared — which countries will release how much, and on what timetable. Macron indicated ministers would reconvene in the coming days to weigh “additional diesel releases as necessary” if the initial tranche fails to calm markets. For now, the message from the G7 was one of unity restored after a tense few days in which the prospect of Washington turning off the taps had exposed just how fragile the West’s energy security truly is — and how costly a transatlantic trade spat over barrels of fuel could become for ordinary households filling up at the pump.
The obesity drug gold rush that made Ozempic and Wegovy household names is entering a new phase, and the hormone at the center of it isn’t GLP-1. It’s amylin — a lesser-known pancreatic hormone that drugmakers now believe could unlock billions of dollars in additional weight-loss treatment, either on its own or stacked on top of the blockbuster shots millions of patients already take.
Eli Lilly and Novo Nordisk, the two companies that built empires on tirzepatide and semaglutide, are both pushing deeper into amylin science, betting that the next wave of obesity treatment won’t replace GLP-1 drugs so much as extend their reach. Amylin is released from the pancreas alongside insulin and plays its own role in regulating hunger and satiety, giving researchers a second biological lever to pull — one that can be used independently or layered on top of existing therapies to push weight loss further.
Lilly offered the clearest evidence yet of that strategy this week, releasing Phase 2 data on its experimental amylin-targeting drug eloralintide. In a trial involving patients with obesity and Type 2 diabetes, combining eloralintide with tirzepatide — the active ingredient in Lilly’s Zepbound and Mounjaro — produced dramatically better results than tirzepatide alone. After 48 weeks, patients on the highest-dose combination lost an average of 23.3% of their body weight, compared with 14.8% for those on a high dose of tirzepatide by itself.
Those numbers matter because Type 2 diabetes patients typically see smaller weight-loss results on these therapies than people without diabetes, making the gap all the more notable to researchers watching the space. Benjamin Bikman, a Brigham Young University professor who studies metabolic health, called the results “encouraging,” while noting the real test will come in how patients fare over longer stretches of treatment.
For Lilly, eloralintide is being developed on two tracks: as a standalone drug and as a combination therapy with tirzepatide. Wall Street is already penciling in big numbers for both. Leerink Partners analyst David Risinger projects the eloralintide franchise could generate $23.2 billion in annual sales by the end of 2035, with the standalone version reaching the market first in 2029 and the combination following roughly a year later.
The appeal isn’t just about squeezing more weight loss out of existing patients. Risinger estimates that more than 10 million people have already tried GLP-1 drugs and failed to benefit — whether because the drugs didn’t work well enough, side effects were too severe, or genetic factors made them non-responders. That’s a sizable, underserved population that amylin-based treatments could target as a monotherapy, independent of tirzepatide or semaglutide altogether.
Lilly executives see the opportunity running in both directions. Ken Custer, president of Lilly Cardiometabolic Health, framed it as filling gaps on either side of the treatment spectrum: patients who don’t get enough from tirzepatide alone, and those who don’t get enough from an amylin drug alone. Combining the two, the thinking goes, could capture patients who would otherwise fall through the cracks of either mechanism. Bikman pointed to another use case — patients who start strong on tirzepatide but hit a weight-loss plateau and need an added push.
Still, the excitement comes with real caveats. The results are drawn from a relatively small Phase 2 study, and Lilly must now replicate them in larger Phase 3 trials set to begin later this year. Tolerability is shaping up as the bigger hurdle than efficacy: in the combination arms of the trial, between 10.8% and 27% of patients discontinued treatment due to side effects, depending on dosage, compared with just 2.9% of those taking tirzepatide alone. As Bikman put it, a therapy only works if patients can actually stay on it — meaning tolerability data from the next phase of trials may matter just as much as the weight-loss numbers themselves.
Novo Nordisk, Lilly’s chief rival in the obesity-drug race, is pursuing its own amylin programs as well, underscoring that this isn’t a one-company bet but potentially the next major battleground in a market already worth tens of billions of dollars. If the science holds up through late-stage trials, amylin could do for obesity treatment what combination therapies have done in other chronic disease categories: turning a single blockbuster drug class into a multi-front portfolio business, with options tailored to patients GLP-1s never fully reached.
For now, the promise is real but unproven at scale. Investors, doctors, and patients alike will be watching Phase 3 results closely to see whether amylin’s early numbers hold — and whether people can actually stay on the drugs long enough to realize them.
The American job engine sputtered badly in September, with employers adding a mere 29,000 positions — a fraction of what economists had forecast and the clearest sign yet that the labor market is losing steam just as voters prepare to head to the polls for the midterm elections.
The figure, released Friday by the Bureau of Labor Statistics, landed at less than half of the roughly 70,000 jobs economists had penciled in, and marked a stark reversal from August’s revised gain of 133,000. The unemployment rate ticked up to 4.2% from 4.1%, continuing a gradual drift that has pushed joblessness higher than at any point since last November.
This was the final employment snapshot before the 3 November midterms, and its timing could hardly be worse for the White House. The report lands amid growing public frustration over living costs, with a new AP/NORC poll showing just 17% of Americans approve of President Donald Trump’s handling of the cost of living — a record low that undercuts his frequent claims that the United States is running the “hottest” economy in the world. Only 26% approve of his broader economic stewardship, also a new low.
Trump himself seemed to acknowledge the gap between his rhetoric and public perception earlier this week, telling a White House audience, “I’ve done a very bad job of explaining how good the country is doing.”
The slowdown was not evenly spread. Healthcare accounted for most of the modest gains, adding 17,000 jobs, while the information, financial and professional services sectors all shed workers. Across much of the rest of the economy — from retail to technology — headcounts barely moved at all, suggesting employers are neither aggressively hiring nor rushing to lay people off. Economists have taken to calling this dynamic a “slow-hire, slow-fire” labor market, in which companies are hunkering down rather than making big staffing bets in either direction.
Adding to the unease, the government revised down its estimates for July and August by a combined 60,000 jobs. July’s figure was revised into negative territory, showing the economy actually lost 10,000 jobs that month — an unusual contraction that had already rattled analysts when first reported.
Wage growth also slowed sharply. Average hourly earnings rose just 3% over the past year, the weakest pace in more than five years, a trend that could ease some inflationary pressure but will do little to comfort workers already squeezed by rising costs elsewhere.
The pain is not being felt equally. Unemployment among Black Americans jumped a full percentage point to 7%, double the rate for white workers, underscoring how a cooling labor market tends to hit already vulnerable groups hardest. Job openings and hiring overall were little changed in August, reinforcing the sense of a market in stasis rather than freefall.
Not every signal was quite so grim. Separate data from payroll processor ADP, released earlier in the week, painted a rosier picture of private-sector hiring, which it said accelerated for the first time since May, adding 90,000 jobs on the strength of healthcare, education and hospitality. Jobless claims also edged down for a fourth consecutive week, according to the Labor Department, suggesting layoffs remain contained even as new hiring dries up.
Economists cautioned against reading too much into a single weak month. George Brown, senior economist at Schroders, noted that job gains have been “a rollercoaster” throughout the year and that one soft report doesn’t necessarily herald a lasting collapse. Bradley Saunders of Capital Economics described the figure as “not disastrous,” pointing to a drop in government employment and changes to temporary visa policy as factors weighing on the headline number. Jeffery Roach, chief economist at LPL Financial, framed the divergence as tension between “goods producing sectors that support the AI boom” and service industries grappling with the disruptive effects of that same technology.
The report carries significant weight for the Federal Reserve, which raised interest rates last month for the first time in three years after Fed chair Kevin Warsh argued the labor market was “running consistent with full employment” even as “inflation is too high and has been for too long.” Friday’s data has cooled expectations that the central bank will push through a second rate increase at its final policy meeting before the midterms, with most officials now seen as more likely to wait until December if another hike comes at all.
Inflation, meanwhile, shows little sign of loosening its grip on household budgets. Mortgage rates jumped from 7% to 7.28% this week — the sharpest weekly rise since 2022 — while the 10-year Treasury yield, a benchmark for loans across the economy, climbed to a 24-year high amid a broader global bond sell-off. Elevated oil prices, linked in part to the ongoing US-Israel war on Iran, have cost the average American household an estimated $936 so far.
Taken together, the picture is one of an economy that is neither collapsing nor thriving — a labor market stuck in neutral, wages failing to outpace the cost of living, and borrowing costs climbing even as hiring stalls. For voters weighing the state of their wallets heading into the midterms, that muddled reality may prove more consequential than any single headline number.

Inside SS27 Fashion Month: Why the Industry’s Wildest Stunts Gave Way to Quiet Spectacle
Where is “The Middle” cast now? See what the Hecks and their friends are up to today

Gypsy-Rose Blanchard Pushes “Kenan’s Law” Petition After Partner Ken Urker’s Death at 34


-
 Fashion2 days ago
Weekend Open Thread: Veronica Beard
-
Business & Hustles6 days ago
Perpetua Resources at Mining Forum Americas 2026: shift to construction
-
 Business & Hustles7 days ago
Andreessen Horowitz backs AI-era college alternative with $42M
-
Business & Hustles7 days ago
Greatland Resources at Mining Forum Americas 2026: cash-rich growth push
-
 Tech & AI4 days ago
Figure F.02 Robots Meet Molten Steel as Arnold Schwarzenegger Watches in Finland
-
 Business & Hustles7 days ago
Romania, Georgia and Latvia Lead Latest WHO-Based Ranking
-
 Business & Hustles7 days ago
SpaceX Starship launches on first orbital test flight with Starlink
-
 Business & Hustles7 days ago
Bob Chapek on Disney Bob Iger power battle: Raised concerns weekly
-
 Tech & AI6 days ago
Alternatives to Animal Testing Are Finally Taking Off
-
 Tech & AI7 days ago
OpenAI Pauses Training Its Most Powerful Models After Rogue Agents Target Government
-
 Business & Hustles7 days ago
General Mills brands undergo innovation and renovation
-
 Business & Hustles7 days ago
Trump approves new fuel economy standards, reversing Biden’s EV push
-
 Business & Hustles7 days ago
What is the Budget and what could be in it?
-
 Business & Hustles6 days ago
OpenAI rebrands AI agents as ‘dots’ amid security fears
-
 Business & Hustles7 days ago
Apple ordered to pay $5.7bn in haptic tech patent case
-
 Business & Hustles7 days ago
Canadian defence creating 250 jobs in Merthyr in new research alliance
-
 Tech & AI7 days ago
How to Avoid Malware Online: 11 Practical Safety Tips
-
 Business & Hustles6 days ago
Develop sets $458 million growth capital budget
-
 Business & Hustles6 days ago
UK chancellor uses bitcoin to mock Nigel Farage
-
 Tech & AI7 days ago
iPhone 18 Pro Max review: The best iPhone, probably
You must be logged in to post a comment Login