Connect with us

Business & Hussles

How Indotek Fixes What Others Walk Away From

Published

on

How Indotek Fixes What Others Walk Away From

Institutional portfolios typically grow by avoiding problems. Indotek’s has grown by collecting them, deliberately, across three decades and a dozen countries.

“We don’t buy assets that look shiny on the surface and are running perfectly. We prefer to buy property and companies that need attention. We turn them around and thereby generate additional value,” says Dániel Jellinek.

The Shape of a Distressed Sale

Some distressed real estate sale has the same shape. An owner, sometimes a large institutional manager with a mandate built around stabilized income, concludes that a property no longer fits its portfolio. The tenant mix has drifted. The building needs capital the fund cycle does not allow. The local market requires hands-on management that a passive ownership structure was never built to provide. Rather than fix the problem, the owner sells it, at a price that reflects the challenges rather than what the asset could be worth once the issues are resolved.

Buyers who could technically afford that price often still walk away, because owning the discount is not the same as being able to close it. A repositioning plan on paper is not the same as a leasing team that can execute one, development managers that can rebuild a tenant roll, or a relationship with financing partners strong enough to navigate a project through changing circumstances mid-cycle. Indotek’s entire commercial model rests on having built that capability before the opportunity requiring it appeared.

The Infrastructure Behind the Fix

Dániel Jellinek was explicit with the Frankfurter Allgemeine Zeitung about what separates Indotek’s approach from a purely financial bet on distress: “We are good at the numbers, we are unpretentious, and we look at assets where we can add value.” The numbers identify the discount. The infrastructure is what converts it into a return.

Advertisement

That infrastructure has four components, built over three decades rather than assembled for a single deal. Leasing capability determines whether a half-empty retail asset can be repositioned around tenants suited to its local market rather than the tenants it happened to inherit. Development capability determines whether physical renovation can proceed on a timeline and budget that actually improves the asset’s economics rather than eroding them. Relationships with financing partners determine how smoothly a project can move through the practical realities of a repositioning, a factor that often shapes whether a turnaround is even possible before a single euro of capital is deployed. And use-repositioning capability determines whether an asset built for one purpose can be reconceived for another where the original function no longer reflects the market around it, converting a building’s constraint into the basis for its next use rather than repeating a function the market has moved past.

The criteria that guide what Indotek is willing to buy follow the same logic. “We are looking for solid buildings with potential for improvement and value appreciation in good locations, which we can acquire at a reasonable price,” Dániel Jellinek told the Frankfurter Allgemeine Zeitung. “We implement measures to increase value and then sell the properties on or retain them as income-generating assets.” Solid structure, a viable location, and a price that reflects the operational problem rather than the real estate itself: those three conditions define the narrow band of the market where Indotek’s infrastructure has something to work with.

Problems Money Alone Cannot Fix

Indotek’s core discipline is diagnosing the underlying problem in an asset or business and creating value through restructuring, repositioning, and operational expertise. That capability also extends to situations that fall outside a normal transaction timeline. “If a property developer is in trouble, we turn the situation around not only with money, but also with our expertise and our people,” Dániel Jellinek said. “Even in unforeseen circumstances, such as the death of the owner, we can manage the situation.”

A fund with a fixed investment committee process and a mandate built around clean, bankable transactions has no natural way to step into a situation like that. Indotek’s willingness to do so, alongside its leasing, development, and financing-partner relationships, is part of what makes its turnaround model work.

Advertisement

Romania, 2019: A Major Milestone Beyond Hungary

The acquisition of Promenada Mall in Târgu Mureș in 2019 was not Indotek’s first transaction outside Hungary, as the Group had already completed investments in Spain and Portugal. It was, however, one of Indotek’s first major international acquisitions and an important milestone in the Group’s expansion into Central and Eastern Europe. The transaction demonstrated that the investment and active asset management capabilities developed in Hungary could also be applied successfully in a new regional market.

It could. The Romania deal became the template Indotek would repeat with growing ambition across the region: Greece, Italy, Poland, and Croatia followed, before the Vienna office opened in November 2025. Each new market required rebuilding the same relationships from scratch, with local banks, local tenants, local contractors, rather than relying on Hungarian-specific advantages. The underlying discipline, identifying the asset the previous owner’s mandate could not accommodate and applying the infrastructure needed to close the gap between its current condition and its achievable one, is what traveled. A Hungarian formula would not have.

That distinction is easy to state and hard to execute. A firm that has only ever operated in one market can describe its methodology in the abstract, but abstraction does not build a relationship with a bank it has never dealt with, or convince a local leasing broker to trust a buyer with no track record in that city. Indotek’s expansion required proving, market by market, that the capability behind the Hungarian portfolio was a transferable discipline rather than a set of relationships that happened to work in one country.

A recurring pattern runs through many of the sellers Indotek buys from: sophisticated institutional owners exiting positions that no longer fit their return targets or their current operational capacity, not distressed operators being rescued from failure. What changes hands is an asset whose value has become temporarily inaccessible to the current owner.

Advertisement

The same logic holds outside retail. Indotek’s non-performing loan acquisitions in Spain follow an identical decision tree from the seller’s side: a bank facing regulatory pressure to clear a position it cannot profitably manage internally sells to a buyer equipped to work through the underlying collateral, rather than simply holding the assets itself. Different asset class, different counterparty, same reason the seller walked away and the same reason Indotek did not.

Turning a Situation Around, Not Waiting One Out

Dániel Jellinek draws a sharp line between what Indotek does and passive value investing, buying an undervalued asset, holding it, and waiting for the market to do the work. “We don’t buy cheaply here, wait it out and then sell for more,” he said of Indotek’s approach to a new market. “We come to a market because we know how to turn a situation around.”

The distinction matters because it defines what Indotek actually underwrites at acquisition. The purchase price marks the entry point. The thesis underneath it is the specific, diagnosable problem the price reflects, and whether Indotek’s infrastructure can resolve it faster and more reliably than the market expects. A tenant mix can be rebuilt. A financing relationship can be managed through a difficult stretch. A stalled renovation can be finished. What cannot be manufactured on short notice is the leasing network, the workout experience, and the financing-partner relationships that make each of those interventions credible rather than aspirational.

Where the €2.5 Billion Actually Comes From

The €2.5 billion asset figure is the byproduct of a narrower story: an organization that has spent three decades taking on the specific category of asset that sophisticated institutional owners, for entirely rational reasons tied to their own mandates, choose to sell rather than repair. The Promenada Mall transaction became an important proof point that Indotek could apply its established investment and active asset management capabilities successfully at scale in a new Central and Eastern European market. It has since recurred across Indotek’s portfolio in every market the firm has entered: Spain, Italy, Romania, and now Austria and Germany.

Advertisement

None of those transactions required an exception to a normal investment process. Each required the same underlying capability applied to a different set of local circumstances: read the specific problem correctly, price it accordingly, and deploy the leasing, development, and workout infrastructure needed to close the gap. The capability that makes the pattern repeatable, rather than any single transaction, is what Indotek has actually built. It is also the reason the firm can walk into markets other institutional buyers are still hesitant to enter and treat the hesitation as the opportunity rather than the risk.

Advertisement
Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business & Hussles

Dave & Buster’s interim CFO Cory Hatton buys $25,999 in stock

Published

on


Dave & Buster’s interim CFO Cory Hatton buys $25,999 in stock

Continue Reading

Business & Hussles

Market veterans favour value plays over crowded, expensive themes

Published

on

Market veterans favour value plays over crowded, expensive themes
After two difficult years for Indian equities, there is scope for reasonable returns as valuations turn less demanding, according to senior market participants who spoke to ET. Large caps look better placed, while the outlook is more cautious on mid- and small-caps. Financials, manufacturing and consumption are among the preferred themes, while views on technology are sharply divided

NEELESH SURANA, CIO, Mirae Asset Mutual Fund

MARKET OUTLOOK: India looks better positioned than sentiment suggests and is a natural hedge against crowded AI trade. Valuations are no longer a headwind, while domestic fundamentals are sound. Any global trade rotation could be meaningful. Key risks are elevated crude, rising developed market bond yields, El Niño and heavy equity issuance. Overall, we expect low-teens returns.
PREFERRED INVESTMENT STRATEGY: Our strategy is a barbell, combining quality stocks with strong earnings upgrades at sensible valuations with holding sector leaders that have corrected over the past two years and are now in value zone.

THEMES LOOKING ATTRACTIVE: Banking, consumer discretionary, healthcare and manufacturing. Sector leaders, impacted by FPI selling over the last two years, are now attractive.

THEMES TO STAY AWAY FROM: Slow-growth or disruption prone sectors like consumer staples and IT. Cautious on narrative-driven, richly-valued sectors like capital goods.


Read more: Goldman Sachs identifies 42 Indian stocks riding AI build-out

JANAKIRAMAN RENGARAJU, CIO – India Equities Templeton Global Investments

MARKET OUTLOOK: The 12-month base case for Indian equities may not be quite euphoric, but it is constructive. Largecap valuations are more reasonable, while higher mid- and small-cap multiples call for greater prudence. Globally, the picture has deteriorated. Unresolved conflicts have entrenched inflationary pressures, while rising interest rates and heavy fiscal debt reinforce each other. Tariff uncertainty continues to cloud trade growth, while questions are emerging over the viability of massive AI investments, even as enthusiasm and valuations remain elevated.PREFERRED INVESTMENT STRATEGY: Adopt a tone of ‘cautious optimism’ over the medium term.

Advertisement

THEMES LOOKING ATTRACTIVE: Financials, industrials and capital goods, consumption and electronic manufacturing, which are linked to capex pick up, rising affluence and credit growth.

THEMES TO STAY AWAY FROM: Avoid expensive small and mid-caps with weak cash generation and businesses dependent on endless equity funding.

Read more: SIPs offer steady gains as most fund categories beat benchmark indices

ANISH TAWAKLEY, CIO, DSP Mutual Fund

MARKET OUTLOOK: Economy remains in good shape, while valuations are now neutral. This should translate into reasonable market returns broadly in line with earnings growth.

Advertisement

PREFERRED INVESTMENT STRATEGY: Don’t chase narratives that have already played out, rather look at sectors that have been underperforming since the last 2-3 years.

THEMES LOOKING ATTRACTIVE: Private banks, insurance companies, automobiles and cement.

THEMES TO STAY AWAY FROM: Careful about companies where promoters are diluting (either through primary or secondary sales) or where private equity is selling, including IPOs. Promoter dilution and PE sales happen when performance and valuations are close to peaks. Cautious on metals, IT and FMCG. For IT, the problem is not AI but the fact that Indian listed companies are losing market share to GCCs set up in India.

R SIVAKUMAR CIO, Axis Mutual Fund

MARKET OUTLOOK: The outlook is constructive. Economic slowdown over the last few quarters appears to be more cyclical than structural. Valuations in parts of the market remain elevated, particularly within mid- and small-caps.

Advertisement

PREFERRED INVESTMENT STRATEGY: Alpha generation is likely to come from selective stock picking rather than broad market direction. A balanced approach across largecaps, which offer valuation comfort and resilience, and select mid-cap opportunities, which continue to deliver superior earnings growth, remains appropriate.

THEMES LOOKING ATTRACTIVE: Constructive on manufacturing, power and electrification, energy transition, select financials, particularly banks and capital-market-linked businesses, as well as export-oriented companies.

THEMES TO STAY AWAY FROM: Investors should avoid chasing momentum in overcrowded themes. In technology, we remain watchful of disruptions and pricing pressures emerging from AI-led changes in the global IT services landscape

SHANKAR SHARMA, Founder, GQuant

MARKET OUTLOOK: Barring occasional rallies, I do not see the Indian markets outperforming the world or even the peer group. The Vaibhav Suryavanshi Syndrome afflicts Indian companies: domestic success is mistaken for globally transferable skill. Largecaps have thrived on India’s easy pitch, building market capitalisation rather than global scale and brands. When domestic growth fades, competing overseas will require an entirely different mindset. There will be pockets where money is going to be made; but in aggregate, Indian returns will disappoint for the coming year.

Advertisement

PREFERRED INVESTMENT STRATEGY: The future of the Indian stock market lies in getting “techified”. Tech has been my theme in the last 2 years since the bear market started in India and I have actually made money even in this very-very tough market. This is not going to change anytime soon. Pharmaceuticals is also going to be a good place to be in.

THEMES LOOKING ATTRACTIVE: For me, tech is 80% of the allocation and pharma is 20% and there is nothing else that I am interested in India.

THEMES TO STAY AWAY FROM: Companies which service the domestic Indian consumer. That trade is on its way out and this is not where I would deploy a lot of capital.

Advertisement
Add ET Logo as a Reliable and Trusted News Source
Continue Reading

Business & Hussles

Accountancy firm Hazlewoods move to larger offices in Cardiff to support expansion

Published

on

Business Live

The firm has relocated to the South Gate House office scheme

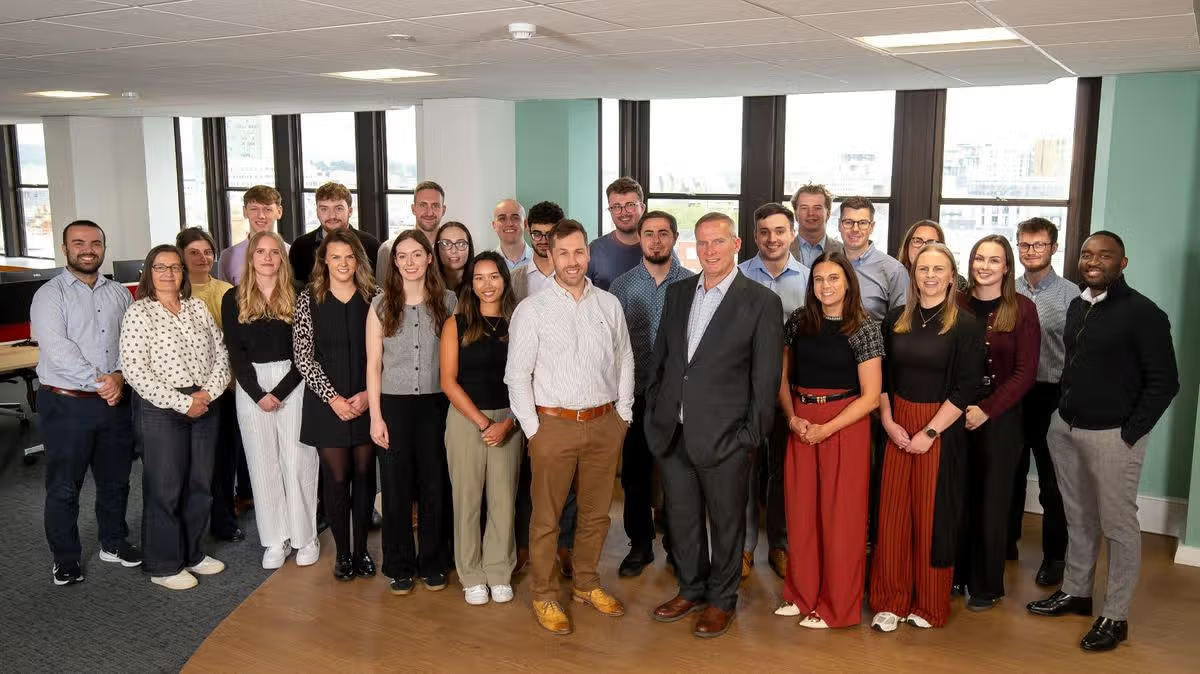
The Cardiff team of Hazlewoods

Accountancy and business advisory firm Hazlewoods has relocated to larger offices in Cardiff to support expansion plans.

Having set up its first office in Wales at the Capital Tower office building in 2024, it has now moved its team of 34 to South Gate House.

Advertisement

Tom Davies, director at Hazlewoods Cardiff, said: “This is an exciting step for Hazlewoods and reflects the progress we have made since launching in the city less than two years ago. We have built a very strong team here and have been really encouraged by the response from both new and existing clients, reflecting our commitment to developing deep relationships across the region.

“The new office gives us the space to continue growing while maintaining the collaborative approach that is such an important part of the way we work.”

Bruce Black, corporate tax director, said: “This move creates the environment we need to continue finding and developing local talent to build the team, while maintaining the high level of service our clients expect from Hazlewoods. It reflects just how positively the Cardiff office has developed in such a short space of time.

“The team in Cardiff has done a great job of growing the business and I look forward to seeing that continue. We have the expertise, ambition and people to build a really strong presence in Wales, and the new office gives the team a great base from which to do that.”

Advertisement

Hazlewoods is one of the largest independent accountants and business advisers in the South West and Wales, with more than 600 employees and a growing presence in Cardiff, alongside its offices in Cheltenham and Bristol.

The firm provides audit, accounting, tax and advisory services to corporate and private clients and is particularly well known for its specialist sector expertise across the UK. Last year, the firm recorded a turnover of £54.3m.

Its managing partner, James Morter, said: “It has been very gratifying to see the way that Hazlewoods has been welcomed into Cardiff. Early on, we identified a gap in the Welsh market for a firm of our size and experience, and when you combine that with the talent pool in the city, it felt like a natural next step.”

Property advisory firm Knight Frank represented Hazlewoods on the deal, while its building consultancy team supported the fit-out of the new space.

Advertisement

Mark Sutton, office agency partner at Knight Frank’s Cardiff office, said: “Hazlewoods was looking for a space that could support its continued growth in Wales, while offering excellent connectivity and the flexibility to create a workplace suited to its needs.

“South Gate House provided the right combination of quality space and a prime city-centre location, and it has been a pleasure to support the team through the move.”

Continue Reading

Business & Hussles

Perpetua Resources at Mining Forum Americas 2026: shift to construction

Published

on


Perpetua Resources at Mining Forum Americas 2026: shift to construction

Continue Reading

Business & Hussles

What Trump’s potential US diesel export ban could mean for you

Published

on

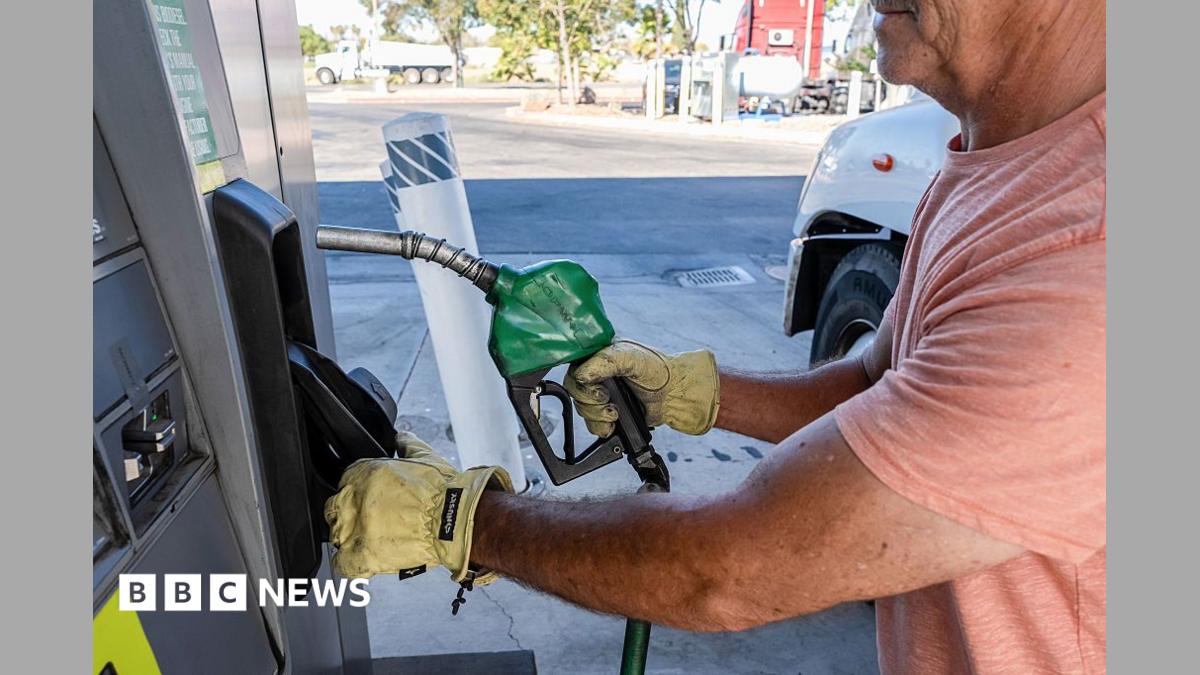
A driver returns a fuel nozzle after refueling a tractor trailer with diesel fuel at a Chevron truck stop in Tracy, California.

For the US economy, a ban could deliver short-term relief at the pump by flooding the domestic market with excess supply.

However, energy analysts warn it could backfire.

David Fyfe, chief economist at Argus Media, notes that cutting off American supply would likely cause international prices to skyrocket.

That would push up global freight, food, and industrial costs, ultimately “feeding inflation back into the global economy”.

Advertisement

“At a stroke, the US’s reputation as a reliable supplier of energy to the world would be shot,” Fyfe added.

Removing more than a million barrels of daily American supply would trigger a fierce bidding war among importing nations in Latin America and Europe.

Sarah Raffoul, analytics manager at Argus Media, noted that while higher international prices would eventually curb demand, the immediate gap would severely strain trade relationships and accelerate global inflation.

Advertisement
Continue Reading

Business & Hussles

Greatland Resources at Mining Forum Americas 2026: cash-rich growth push

Published

on


Greatland Resources at Mining Forum Americas 2026: cash-rich growth push

Continue Reading

Business & Hussles

Canadian defence creating 250 jobs in Merthyr in new research alliance

Published

on

Business Live

Its new research alliance is with two Welsh universities and one in Canada

Marshall Land Systems

Marshall Land Systems

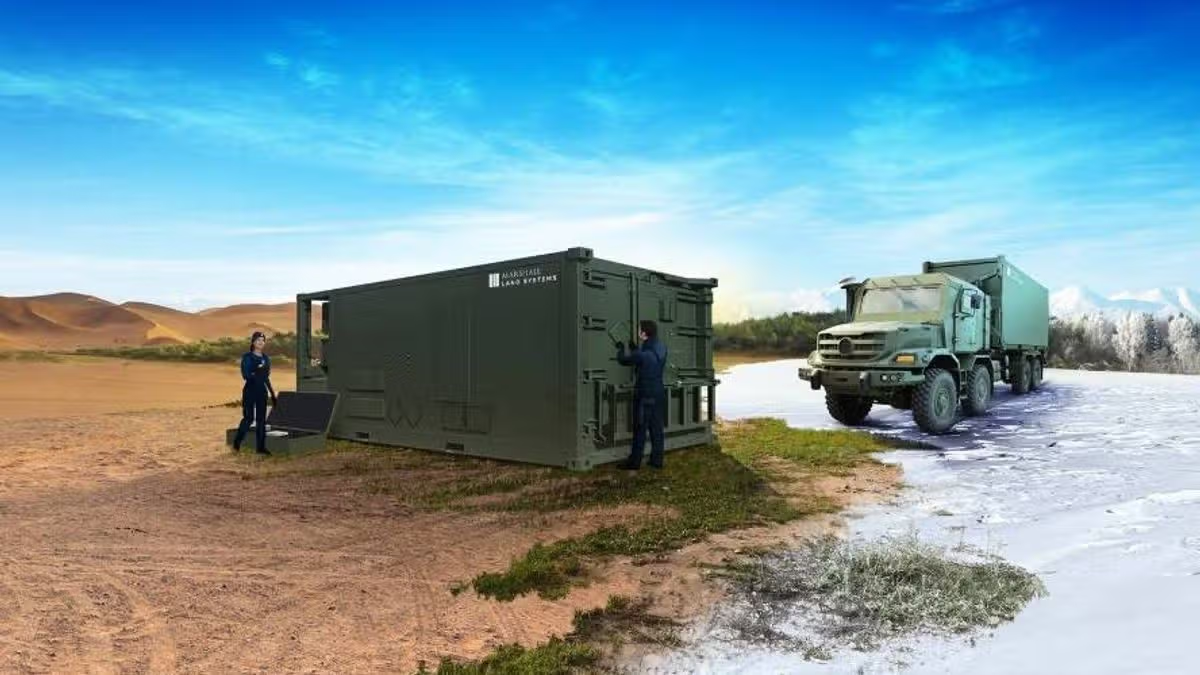
A Canadian-owned defence firm which is relocating its UK production from Cambridge to South Wales has forged a new research alliance with universities on both sides of the Atlantic.

Marshall Land Systems, whose new factory site in Merthyr will reach production capacity at the end of the year with 160 staff, has set up the Marshall Land Research Alliance alongside the universities of Cardiff, South Wales, and New Brunswick in Canada.

Advertisement

The firm’s deployable infrastructure ranges CT scanners and medical facilities to mechanical maintenance and command centres. Its new assembly plant was chosen after a UK-wide search, and will produce deployable infrastructure that will protect NATO personnel on operations, humanitarian missions, and on bases.

The alliance together leading academics and technology experts to explore new technologies in the field of deployable infrastructure for military and humanitarian use.

A signed memorandum of understanding will unable technology transfer, staff exchanges and joint research and development work.

Over the next five years, based on its current order book alone, Marshall is confident of growing its workforce in Merthyr to 250. However, with the UK Government and other countries committing more of their budgets to defence and security, Marshall is well positioned to win additional contracts that could see even more jobs created at its Merthyr site.

Advertisement

The firm’s deployable infrastructure ranges CT scanners and medical facilities to mechanical maintenance and command centres.

Its new assembly plant was chosen after a UK-wide search, and will produce deployable infrastructure that will protect NATO personnel on operations, humanitarian missions, and on bases.

The average salary at the factory will be around £32,000, while Marshall is also looking to take on around 15 apprentices.

The firm has entered into a 15-year lease with the owner of the building, Figsand, with an option to acquire it. The Merthyr site extends to 191,600 sq ft and occupies 8.2 acres at Merthyr Industrial Park.

Advertisement

Marshall Land Systems chief executive, Gareth Williams, said: “In an increasingly volatile world, the long-standing and fundamental alliance between Canada and the UK is becoming ever more important. As NATO allies invest to protect our way of life, this transatlantic research alliance will bring together the smartest brains in support of the effort to keep us safe and the world stable.

“We’re proud to be convening this vital joint work between Wales and New Brunswick under the Marshall Land Research Alliance.”

Professor Louise Bright, pro vice chancellor for enterprise, engagement, and partnerships at the University of South Wales, said:“We are proud to be a founding partner in the Marshall Land Research Alliance, a bold collaboration that will help shape the future of innovation, skills and advanced manufacturing in South Wales.

” USW’s strengths in research, advanced manufacturing and skills development position us to connect industry, talent and innovation in ways that deliver real impact.

Advertisement

“This partnership will create valuable opportunities for our students and staff to work alongside leading industry partners on real-world challenges, while helping businesses develop the skills and expertise they need to grow.

“With Marshall Land Systems establishing a major new facility in South Wales, this Alliance comes at a pivotal moment for the region. Together, we can support innovation, expand opportunities for graduates and help drive long-term economic growth across Wales.”
Professor Roger Whitaker, Cardiff University’s pro vice-chancellor for research, innovation and enterprise, said: “Cardiff University is pleased to be a founding partner in the Marshall Land Research Alliance, bringing together academic and industry expertise to support research, innovation and skills development in areas including advanced manufacturing, engineering and defence.

The alliance provides opportunities for our staff to work with partners on research, innovation and workforce development. It also comes at an important time for South Wales, with the potential to support new collaborations between universities, industry and government.

Advertisement

Through research, knowledge exchange and skills development, we hope to contribute to opportunities for students, graduate employment, businesses and communities, while supporting the long-term strength and resilience of the Welsh economy through research and innovation.”

Dr David MaGee, vice president research at the University of New Brunswick said: “We take great pride in fostering strong, mutually beneficial partnerships that help us make a meaningful impact in Canada and around the world. I look forward to working with Marshall Land Systems, Cardiff University, and the University of South Wales to advance innovative technologies and contribute to Canada’s NATO commitments.

“By leveraging our academic expertise and learning from our collaborators, we will address common challenges and create lasting benefits for our institutions, our industries, and our countries.”

As well as its Canadian and UK operations, Marshall Land Systems has a factory in the Netherlands. It currently has a global workforce of 600.

Advertisement
Continue Reading

Business & Hussles

Andreessen Horowitz backs AI-era college alternative with $42M

Published

on

Andreessen Horowitz backs AI-era college alternative with $42M

Andreessen Horowitz is putting $42 million behind a new education venture aimed at young tech builders who might otherwise head to college, betting that the artificial intelligence boom is creating demand for a different path into Silicon Valley.

The Horowitz Andreessen Academy, a for-profit company incubated by the venture capital firm known as a16z, plans to bring its first class of roughly 50 students to San Francisco in September 2027 for a tuition-free, one-year fellowship.

Advertisement

Instead of relying heavily on traditional academic credentials, the academy says admissions will focus on what applicants have already built, shipped or earned. Students will spend much of the program working on projects and learning from technology executives and entrepreneurs rather than taking traditional tests and completing homework.

EMPLOYEES AT AI COMPANIES BACK BERNIE SANDERS BILL CRACKING DOWN ON DEVELOPMENT

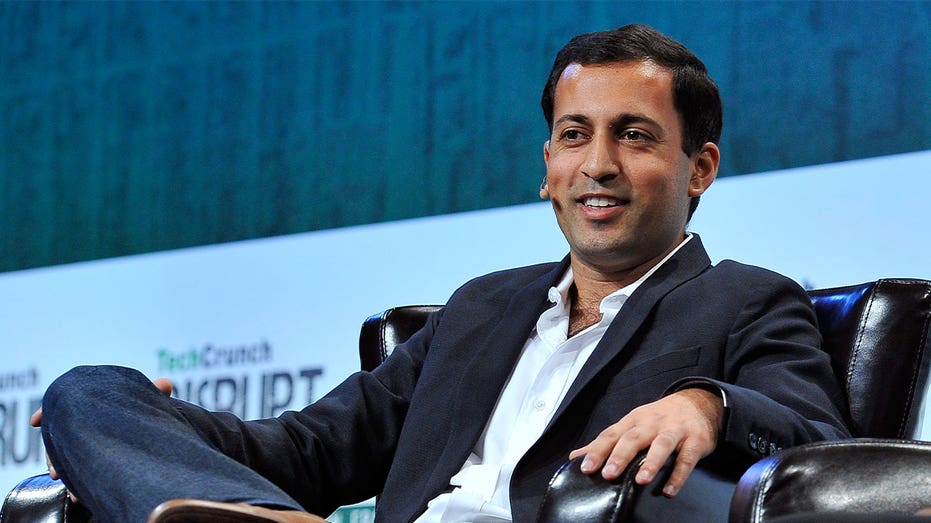
Gagan Biyani speaks onstage at TechCrunch Disrupt SF 2015 in San Francisco in 2015

Gagan Biyani speaks at TechCrunch Disrupt SF 2015 in San Francisco on Sept. 23, 2015. (Steve Jennings/Getty Images for TechCrunch)

The approach represents a Silicon Valley experiment in how education could change as AI reshapes the skills companies seek from workers and founders.

“In our estimation, the AI revolution is going to be as transformational to jobs as the Industrial Revolution was to the agricultural society that came before it,” said Ben Horowitz, co-founder and general partner at a16z. “The training that worked for the Industrial Revolution isn’t going to map perfectly onto the AI revolution, so somebody has to pioneer how you train a person for this new world. That’s what we built the Academy to do. This isn’t just an investment idea for us. It’s an investment in the future of the country.”

Advertisement

A16z is joined in the $42 million investment by technology executives and investors including Shopify CEO Tobi Lütke, DoorDash CEO Tony Xu, Quora co-founder Adam D’Angelo, Y Combinator CEO Garry Tan and Palantir Chief Technology Officer Shyam Sankar.

NEW YORK OVERTAKES SAN FRANCISCO BAY AREA AS LARGEST US TECH TALENT MARKET BY WORKFORCE SIZE

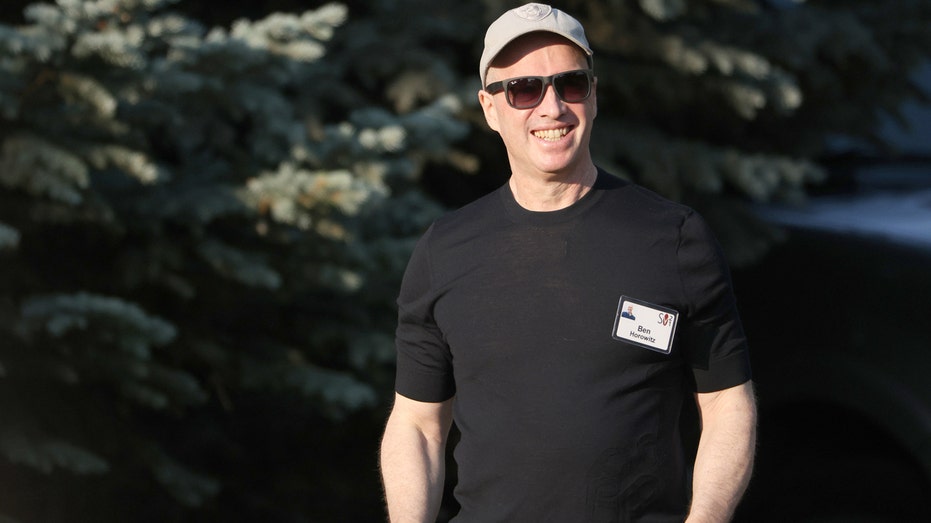
Ben Horowitz walks outside in Sun Valley, Idaho.

Co-founder of Andreessen Horowitz, Ben Horowitz walks to a morning session at the Allen & Company Sun Valley Conference on July 9, 2021 in Sun Valley, Idaho. (Kevin Dietsch/Getty Images)

The venture has also lined up Google, Meta, Nvidia, OpenAI, Anthropic, Coinbase, Palantir, Stripe, Anduril and Replit as founding partners. The companies will provide resources and expertise, including software, hardware and computing power, according to the academy.

Ticker Security Last Change Change %
GOOGL ALPHABET INC. 343.92 +1.56 +0.46%
META META PLATFORMS INC. 723.05 -28.61 -3.81%
NVDA NVIDIA CORP. 231.55 +6.48 +2.88%

Each student is expected to receive more than $50,000 in computing credits and other technology resources, along with a $5,000 travel and exploration budget. Courses will cover areas including AI systems, sales, fundraising, finance and startup formation.

Advertisement

Gagan Biyani, who co-founded online learning company Udemy and later founded Maven, is leading the academy as founder and CEO. Marc Andreessen and a16z general partner Erik Torenberg will join him on its board.

College students sit in a lecture hall as a student takes notes during class.

College students attend a lecture in a classroom. (iStock)

CLICK HERE TO GET FOX BUSINESS ON THE GO

The fellowship is designed primarily for high school graduates and can serve as a gap year or college deferral. The academy plans to seek regulatory approval for a two-year program that could begin in fall 2028, with tuition expected to be comparable to elite private universities.

The company is separate from Andreessen Horowitz despite its close ties to the venture capital firm.

Advertisement
Continue Reading

Business & Hussles

Bob Chapek on Disney Bob Iger power battle: Raised concerns weekly

Published

on

Bob Chapek on Disney Bob Iger power battle: Raised concerns weekly

Former Disney CEO Bob Chapek said Monday he voiced concerns about then-Executive Chairman Bob Iger to the company’s board “weekly” during his brief tenure as head of the House of Mouse.

Chapek has remained tight-lipped about his firing from the media giant nearly four years ago, but opened up about his experience in a new tell-all memoir, “Behind the Castle Walls: My Thirty Years at the Happiest Place on Earth,” and in an interview with CNBC’s “Squawk Box.”

Once head of Disney’s theme park and experiences division, Chapek was tapped to take the helm of the company just weeks before the Covid pandemic shuttered movie theaters and amusement parks around the globe in 2020. As Chapek worked to navigate these challenges, Iger remained with the company to handle Disney’s content initiatives like Disney+.

However, Iger slowly began to reassert control, Chapek says. The ensuing power struggle was detailed in a CNBC report in 2023.

Advertisement

“When I started hearing about lunches that he had and dinners that he had where he was absolutely trashing me, and I’d hear it two, three times in the same week, the same bullet points, the same talking points, I was like, ‘I’ve got a problem,’” Chapek told CNBC.

He noted that when he brought concerns to the Disney board about Iger, he was told, “‘He’ll be gone in two years. It’s OK. That’s Bob being Bob.’”

But almost three years after being named CEO, Chapek was ousted and replaced by Iger, who returned to the post until March 2026.

“It would have been great if, like other CEOs, he acted as a steward of my new role,” Chapek said. “It would have been one thing if he was neutral, but to be actually working against me, actively, I thought was just unbelievable.”

Advertisement
Continue Reading

Business & Hussles

Romania, Georgia and Latvia Lead Latest WHO-Based Ranking

Published

on

Representation. Beer cans.

Romania drinks more alcohol per person than any other country, followed by Georgia and Latvia, according to the most recent internationally comparable data, which draws on World Health Organization figures. The sources reviewed contain no country-by-country count of alcohol consumed in 2026 so far; the newest full dataset is a three-year average labeled 2022 that was retrieved from the WHO’s Global Health Observatory this year.

The ranking, published by The Facts Institute and updated on August 31, measures average annual recorded consumption per person aged 15 and older in liters of pure alcohol. On that measure, the ten heaviest-drinking countries are:

  1. Romania, 17.1 liters
  2. Georgia, 15.5 liters
  3. Latvia, 14.7 liters
  4. Moldova, 14.1 liters
  5. Czechia, 13.7 liters
  6. Lithuania, 12.2 liters
  7. Namibia, 12.0 liters
  8. Poland, 11.9 liters
  9. Austria, 11.8 liters
  10. Bulgaria, 11.5 liters

Belarus, Saint Lucia and Seychelles follow, tied at 11.4 liters each, according to the WHO figures in the Facts Institute table. World Population Review, which also treats 2022 as the most recent data available as of 2026, reports the same leaders: Romania at 17.1 liters, then Georgia at 15.5, Latvia at 14.7, Moldova at 14.1 and Czechia at 13.7. It says Lithuania, Poland, Bulgaria, Belarus, Hungary and Slovakia all reported annual consumption above 11 liters per person.

The gap between Romania and the global picture is wide. The Facts Institute noted that consumption above 14 liters of pure alcohol per person per year is roughly equivalent to about three standard bottles of wine per person each week. Because drinks vary in strength, the WHO measures pure alcohol rather than volumes of beer, wine or spirits. The site explained that a liter of wine, at about 12% alcohol by volume, contains roughly 0.12 liters of pure alcohol, so a person consuming 6 liters of pure alcohol a year would drink the equivalent of about 50 liters of wine, or about a liter a week.

Europe dominates the list. Central and Eastern European countries lead the rankings, and 22 of the top 30 countries are in Europe, according to the Facts Institute. Namibia, in seventh place with 12 liters, is the highest-ranked country outside Europe, and Seychelles and Saint Lucia also record some of the world’s highest levels, making them exceptions to the largely European pattern. World Population Review said beer, wine and spirits all play major cultural roles across much of Eastern and Central Europe, and that higher-income countries generally report higher consumption because alcohol is more affordable and widely available, though wealth alone does not determine drinking habits.

Advertisement

Several large economies sit just outside the top ten. According to the WHO table, Germany, France, Australia and Portugal each recorded 11.2 liters, the United Kingdom 10.9 liters, Russia 10.5 liters and the United States 9.8 liters. Russia, long associated with heavy drinking, has fallen well down the list, WorldRankd noted in a separate ranking. Canada recorded 10.0 liters, and Spain and Slovakia 11.0 liters each.

At the other end of the scale, consumption is close to zero in parts of North Africa and the Middle East, where religious and cultural norms discourage or prohibit drinking, the Facts Institute said. Yemen, Somalia, Bangladesh, Sudan, Mauritania, Libya, Afghanistan, Syria, Pakistan and Kuwait are among the countries with the lowest recorded consumption, and Iran, Indonesia and Egypt also round to near zero.

The numbers are estimates, and the WHO publishes confidence intervals. Romania’s figure of 17.1 liters, for example, carries a range of 14.6 to 19.8 liters, and Georgia’s 15.5 liters ranges from 12.9 to 17.9. Those ranges overlap with countries lower on the list, which means the ordering among places with similar totals is not exact. That is why some countries share a rounded figure and why the Facts Institute listed 13 countries in its top group.

Different sources produce slightly different results. StatsPanda, which uses a World Bank series compiled from WHO data and includes estimated unrecorded consumption, puts Romania at 16.8 liters, Georgia at 14.4 liters and Latvia at 12.9 liters, using the latest available year from 2015 onward. Another ranking of 2025 data listed Latvia in fourth place at about 13.1 liters, followed by Uganda at 12.2 and Germany at 12.2, and it named Lithuania as tenth at 11.8 liters. Such differences reflect vintage, methodology and whether unrecorded, homemade or informal alcohol is counted.

Advertisement

The global context is lower. Worldwide annual consumption in 2019 was equal to 5.5 liters of pure alcohol per person aged 15 and older, down from 5.7 liters in 2010, according to the WHO figures summarized on Wikipedia. The WHO European Region had the highest regional average at 9.2 liters, followed by the Region of the Americas at 7.5 liters. About 44% of the population aged 15 and older were current drinkers in 2019. Alcohol use is estimated to cause about 2.6 million deaths a year worldwide, according to the WHO’s 2024 global report as cited by Statsipedia and the Facts Institute. The Facts Institute added that the countries that drink the most can suffer more alcohol-related health and social problems.

None of the sources reviewed included statements from health officials or the countries ranked, and the WHO’s own data has a lag of several years, so the list does not capture changes in drinking habits since 2022.

Readers looking for a 2026 tally will not find one in the sources reviewed. Until the WHO updates its indicator, the Romania-led list remains the most recent international snapshot of who drinks the most.

Advertisement
Continue Reading

Trending

Copyright © 2025