Business & Hustles
Nike Braces for Earnings Test as China Slump and Stock Slide Deepen

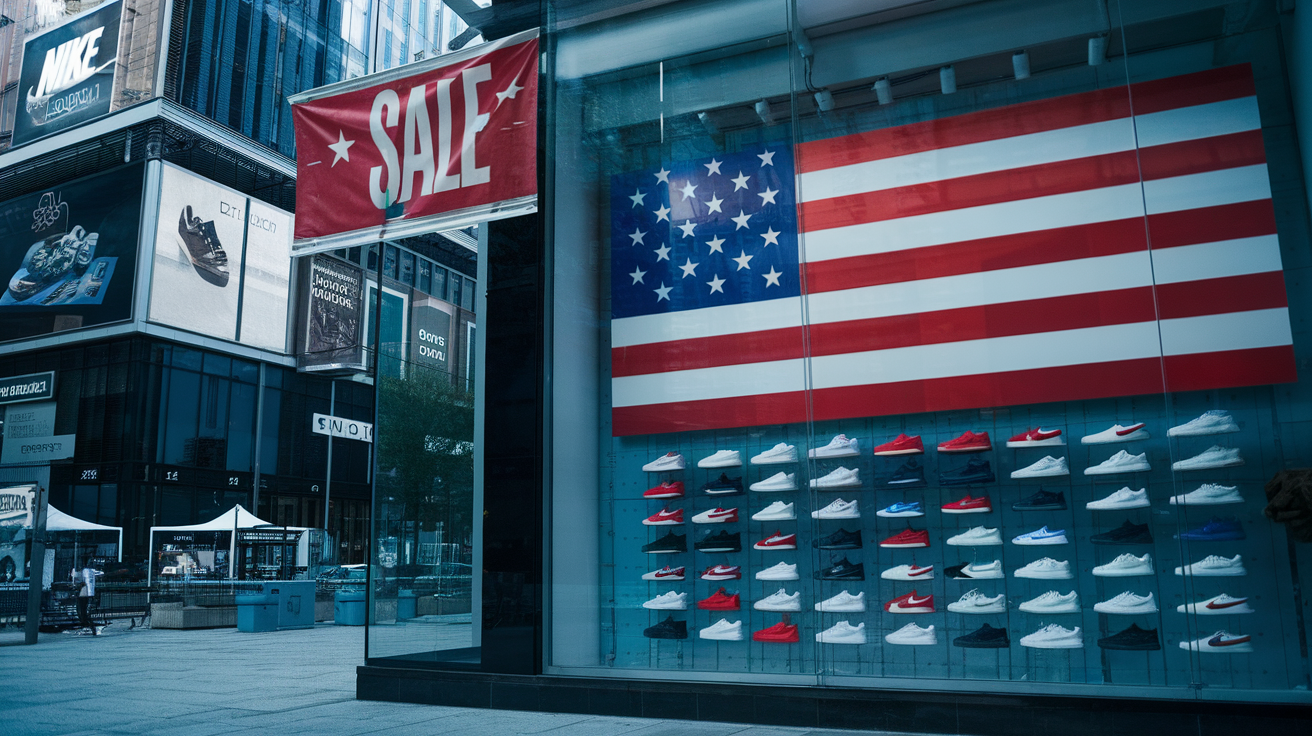
Nike will report fiscal first-quarter earnings after markets close Thursday, a moment of reckoning for a company whose stock has lost more than 40% of its value this year and whose once-dominant presence in China continues to erode.
Analysts surveyed by LSEG expect the sportswear giant to post earnings of 43 cents per share on revenue of roughly $11.32 billion. Those numbers would mark another quarter of sluggish performance for a brand that has struggled to find its footing since the pandemic-era boom faded and competitors crowded into its core markets.
The company itself has tempered expectations. Former Chief Financial Officer Matt Friend told investors earlier this year that Nike anticipated “flattish” sales for the first half of fiscal 2027, a tacit acknowledgment that the turnaround effort underway since CEO Elliott Hill took the reins has yet to translate into meaningful growth. Nike has since brought in a new finance chief, David Denton, a former Pfizer executive who stepped into the CFO role in August and will now help steer the company through investor scrutiny on Thursday’s call.
China remains the company’s most glaring problem. Sales in the region fell 12% in the most recent quarter, continuing a painful retreat from a market that was once among Nike’s most profitable. Hill has publicly insisted that Nike is “fully committed” to reclaiming its footing there, but Wall Street’s patience appears to be thinning. Bank of America analysts downgraded the stock from neutral to underperform last week, warning that “risks are rising” and predicting further disappointment out of China alongside continued pressure on the share price.
North America, Nike’s largest and historically most reliable market, has also shown cracks. Last quarter’s $4.83 billion in North American revenue fell short of the $4.88 billion Wall Street had penciled in, according to StreetAccount, suggesting that even the company’s home turf is not immune to the broader slowdown in consumer appetite for sneakers and athletic apparel.
That slowdown is playing out against a tougher macroeconomic backdrop. Rising geopolitical tensions and persistent inflation have made consumers more cautious with discretionary spending, a dynamic that has weighed on Nike alongside much of the retail sector. Executives have responded with a turnaround strategy that prioritizes different segments of the business at different speeds, betting that a more disciplined, phased approach will eventually restore growth rather than chasing quick fixes.
There was at least one unusual boost buried in the company’s last report: a nearly $986 million tariff refund that added 52 cents per share to earnings, a one-time windfall that flattered results but did little to change the underlying narrative of a brand searching for relevance. Nike said it still expects gross margin for the first fiscal quarter to tick up slightly from a year earlier, a modest sign that cost discipline and pricing strategy may be gaining some traction even as top-line growth remains elusive.
Looking ahead, analysts project full-year revenue of around $45.31 billion for fiscal 2027, with the second quarter expected to come in near $11.79 billion — hardly a dramatic acceleration from current levels. For investors, Thursday’s results and the accompanying 5 p.m. ET call with analysts will be closely parsed for any signs that Hill’s turnaround plan is beginning to bear fruit, or whether Nike’s struggles in China and sluggish demand at home will continue to define the brand’s story into 2027.
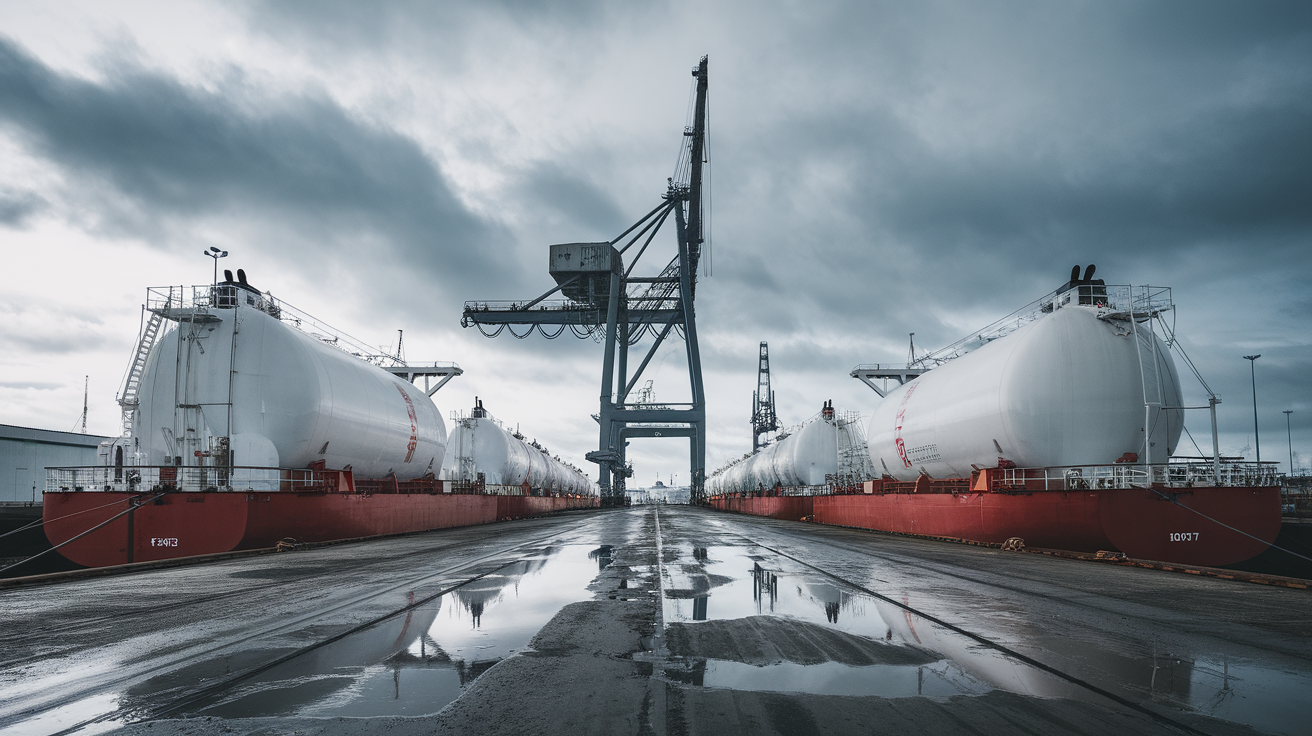
Britain is quietly lining up a contingency plan with its European neighbours to tap strategic fuel reserves, as officials brace for the fallout from a possible US ban on diesel exports that could send pump prices across the Atlantic even higher than they already are.
The BBC understands that Energy Minister Martin McCluskey spoke with European counterparts on Thursday to thrash out a coordinated response, with the UK keen to ensure it is not caught flat-footed if Washington follows through on threats to restrict diesel shipments abroad. A government source described the move as prudent preparation rather than panic, noting that reserves built up earlier this year during an earlier coordinated release remain available across Europe.
The urgency is easy to understand. UK diesel prices have already smashed through record territory, with the RAC putting the average cost at 199.79p a litre this week — up sharply from 142.38p not long ago. For hauliers, farmers and millions of ordinary motorists, that is not an abstract market wobble; it is a direct hit to household budgets and business margins at a time when both are already stretched.
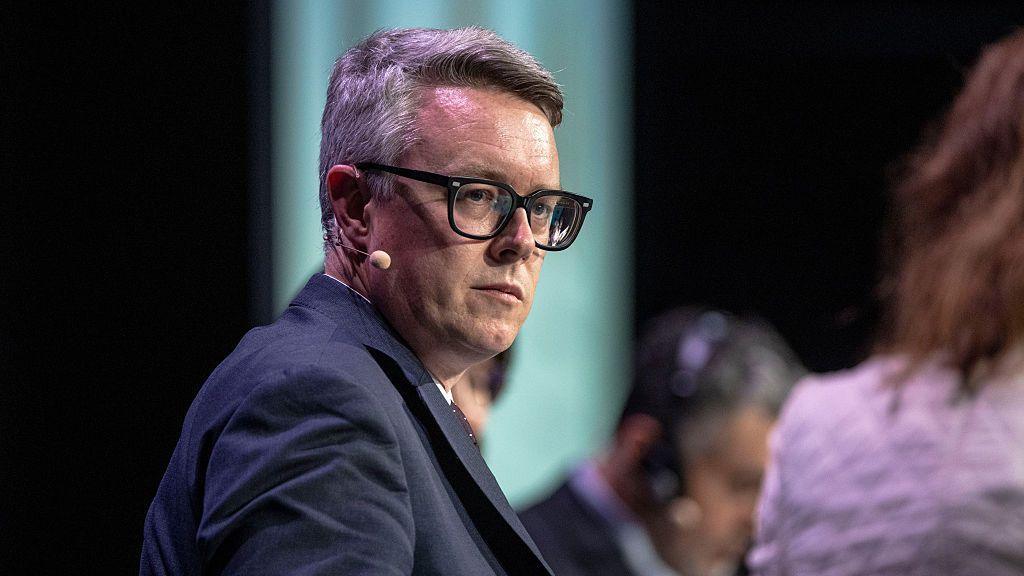
At the centre of the storm is Donald Trump, who has floated banning diesel exports from the United States in an effort to force domestic pump prices down ahead of the midterm elections. “We’re thinking about it very seriously,” the US president said over the weekend, framing the idea as straightforward relief for American drivers and truckers. The logic is simple in theory: keep more barrels at home, and supply should push prices down for US consumers.
The trouble is that the rest of the world depends heavily on exactly those barrels. The US ships between 1.2 and 1.5 million barrels of diesel a day to global markets, making it one of the most important suppliers on the planet. Analysts warn that choking off that flow would not simply redistribute pain — it would amplify it. David Fyfe, chief economist at Argus Media, said cutting off American supply would likely send international prices skyrocketing, turning a domestic political fix into an international economic headache.
Britain is particularly exposed. Although its four domestic refineries produce ample petrol, they fall well short of meeting the country’s diesel needs, forcing heavy reliance on imports. That dependence leaves the UK vulnerable to exactly the kind of supply shock a US export ban could trigger, even as the number of diesel vehicles on British roads has been falling — from 15.7 million to 15.1 million over the past year, according to the Department for Transport, with diesel cars down from 10.4 million to 9.8 million.
The diesel squeeze did not start with Trump’s threats. Prices have been climbing globally since fighting between the US, Israel and Iran disrupted the Strait of Hormuz, a chokepoint through which roughly a fifth of the world’s oil and gas normally flows. An export ban from Russia, another major diesel supplier, has piled on further pressure, leaving markets already stretched thin before Washington’s latest intervention entered the picture.
Brussels appears just as alarmed as London. A European Commission spokesperson said there had been “lots of calls, lots of meetings” on the diesel situation in recent days, including high-level contact with the US administration, as European governments weigh their own exposure to any American export curbs. The International Energy Agency’s governing board is due to meet to discuss the wider implications, underscoring how quickly a domestic US political calculation has become an international energy policy concern.
For now, the UK government is striking a reassuring tone, insisting there is no reason to fear outright shortages. “We have a diverse and resilient supply. We continue to engage with our international partners and the UK fuel industry,” a spokesperson said. But that reassurance comes with a caveat: officials are not promising prices will fall, only that supply itself should hold up. Further price rises, the government acknowledges, remain likely.
That is cold comfort for drivers already absorbing record costs at the pump, and for the haulage and agricultural sectors for whom diesel is not a discretionary expense but an operational necessity. Diesel is notoriously harder to refine than petrol, and because so much of the economy — from food distribution to construction to farming — runs on it, demand simply cannot be dialled down in response to price spikes the way it might for other goods.
What happens next largely hinges on a decision in Washington that has little to do with Britain’s energy security and everything to do with American domestic politics. If Trump proceeds with an export ban, the UK’s quiet diplomacy this week suggests it intends to respond collectively with European partners rather than scrambling alone — drawing down shared reserves while hoping that coordinated action can soften a blow that markets, and millions of drivers, are already bracing to feel.
A wave of selling swept through global bond markets on Thursday, pushing US government borrowing costs to their highest level in nearly a quarter of a century and reviving uncomfortable questions about whether the world’s largest economies can keep financing their debts without triggering a fresh inflation scare.
The yield on 10-year US Treasuries — effectively the interest rate the government pays to borrow money over that period — jumped to 5.34%, a level not seen since 2002. The move rippled across the Atlantic, where UK 30-year bond yields briefly broke above 6% for the first time since 1998, a milestone that will add fresh strain on Chancellor John Healey as he prepares his first budget later this month.
For ordinary households and businesses, rising government bond yields are far from an abstract concern. They tend to feed directly into the cost of mortgages, business loans and government debt interest payments, meaning the latest sell-off could translate into higher borrowing costs across the economy just as policymakers had hoped for some relief.
The source of the unease is a familiar one: oil. Persistently high crude prices, driven by the continuing conflict in the Middle East, have stoked fears that inflation — which many investors had assumed was being brought under control — could come roaring back. Brent crude rose a further 3% on Thursday to around $101 a barrel, even as analysts noted that oil exports through the strait of Hormuz have largely recovered to pre-conflict levels as shippers find workarounds. The lingering uncertainty over a lasting resolution to the conflict, rather than the immediate supply numbers, appears to be what is rattling markets.
Stock markets took the bond rout as a cue to retreat as well. London’s FTSE 100 shed almost 1.7% in its worst single-day fall since May, while Germany’s DAX dropped 1% and France’s CAC 40 fell 1.6%. Eurozone bonds were swept up in the selling too, with France drawing particular scrutiny from investors wary of the country’s fiscal position.
What makes this episode notable is that it came despite US inflation data released on Wednesday that actually came in softer than expected — numbers that, in calmer times, might have reassured markets that the Federal Reserve was done raising rates. Instead, traders shrugged off the good news, apparently unconvinced that lower headline inflation will hold if oil prices keep climbing and wages continue to rise in a resilient US labour market.
“There is carnage in the bond market, which is hitting stocks hard,” said Neil Wilson, investor strategist at Saxo UK, describing a “relentless rout” that is sending investors scrambling for safety.
Beyond the immediate inflation worry, analysts point to a deeper structural anxiety: the sheer volume of government debt being issued to plug widening budget deficits. Mohit Kumar, an economist at Jefferies, said markets are grappling simultaneously with concerns over inflation, deficits and the pace of bond issuance. He described what amounts to a “buyers’ strike,” with hedge funds nursing recent losses and lacking the appetite to bet against the sell-off, while larger institutional investors — so-called “real money” — are waiting on the sidelines for signs of stability before stepping back in.
That combination of nervous hedge funds and cautious long-term investors helps explain why the sell-off has proven so self-reinforcing: with few buyers willing to absorb new debt at current prices, yields have had to rise further to attract demand, which in turn unsettles markets even more.
The dollar, meanwhile, has been one of the few beneficiaries of the turmoil, climbing to a three-month high as investors sought refuge in the world’s reserve currency. Axel Rudolph, chief technical analyst at IG, said that while the softer US inflation data had dimmed expectations of an October Fed rate rise, investors remain braced for the possibility of a hike in December if oil prices stay elevated.
Japan has not been immune either, with its 10-year yield climbing back toward the 30-year high it set just last month — a reminder that this is a genuinely global phenomenon rather than a problem confined to Washington or London.
For governments already wrestling with stretched public finances, the timing could hardly be worse. Higher borrowing costs mean more of every tax pound or dollar goes toward servicing existing debt rather than public services, adding pressure on finance ministers everywhere — not least Healey, who must now craft a budget against a backdrop of the most expensive long-term borrowing Britain has faced in nearly three decades.
Whether this proves a temporary spasm or the start of a more sustained repricing of risk may hinge on developments far from any trading floor — chiefly, how the Middle East conflict and its effect on oil supplies evolve in the weeks ahead. Until then, bond markets look set to remain on edge.
“Any future adjustments in policy should be determined by carefully examining trends in the data, the evolving outlook, and the balance of risks,” Jefferson said in prepared remarks for the University of Virginia’s Darden School of Business.
With financial markets “reassessing” the outlook amid rising bond yields, Jefferson added that “my colleagues and I will need to come to our own judgment, which may take more time,” before deciding on the next move.
For live updates on US Markets, click here
“With more data in hand, such trends may allow for better discernment, as may the appropriate stance of monetary policy,” he said further.

The Fed raised its benchmark rate by a quarter-percentage point to 3.75%-4.00% at its September 15-16 meeting. Policymakers’ projections indicated one more increase before the end of 2026.
New York Fed President John Williams on Tuesday also said that policymakers had time to assess additional data, though he still expected another increase before year-end. Financial markets broadly expect the Fed to leave rates unchanged at its October 27-28 meeting.Jefferson expects inflation to remain “elevated” in the near term “before resuming its decline toward our 2% goal as the effects of energy and other price shocks fade.”
However, he added: “I view risks to my inflation forecast as tilted to the upside due to recent geopolitical developments and stronger-than-anticipated aggregate demand.”
Jefferson described risks to economic activity and employment as “roughly balanced”. He said the economy was “likely to show continued resilience … by adding jobs and extending a six-and-a-half-year-long expansion.”
Fed’s Kashkari expects more rate hikes, but is unsure about October
Minneapolis Fed President Neel Kashkari said on Thursday that additional rate increases would probably be necessary to restrain the economy through 2027, although he was uncertain whether the next move should come in October.
“I’m open-minded” about how the Fed proceeds, Kashkari told Reuters. He added that “I don’t have a strong view” on whether policymakers should raise rates at their October 27-28 meeting. The Fed’s final meeting of the year is scheduled for December 8-9.
Kashkari, who voted for last month’s rate increase, projected one more quarter-point hike this year and another in 2027.
Since the September meeting, “the data that I’ve gotten suggests the economy is doing even better than I anticipated” while “inflation is still too elevated,” he said.
“If the economy proves to just be incredibly resilient and inflation therefore is probably stickier than I appreciate, then policy could need to go higher yet than I’m anticipating at this moment. But I don’t know” whether that scenario will materialize, Kashkari said.
The Fed raised rates last month to curb inflation that has exceeded its 2% target for more than five years. Kashkari had also dissented in favor of an increase at the July policy meeting.
Although the latest rate increase contributed to a sharp rise in long-term borrowing costs, Kashkari said monetary policy was not doing much to restrain the economy.
“The labour market looks quite healthy right now. It seems like the economy is doing quite well. And when I look at that constellation, that says, boy, policy is probably not particularly restrictive right now,” he said.
Kashkari said financial markets were functioning properly despite recent volatility and that the Treasury market had absorbed the repricing without disruption.
“I’m not seeing any evidence of systemic risk” in markets, he said. “I do think the banking sector bears watching closely, and we are (watching)” because of the rapid shift in borrowing costs.
He also said monetary policy under Fed Chair Kevin Warsh was influencing markets.
“If you look at long rates moving as much as they’ve moved over the last several weeks, part of that is real economic developments,” Kashkari said. “I think part of that is hey, the Fed is really serious, the Warsh Fed, it’s not talk, the Warsh Fed is really serious about controlling inflation.”
“I’ve got some confidence that inflation’s heading back down over the next couple of years to our 2% target, but shocks keep surprising us,” he added.
(Disclaimer: This article is based on inputs from agencies. These do not represent the views of The Economic Times)
To hire employees for your small business, first confirm you need an employee rather than a contractor. Then work out what the hire will really cost, register as an employer, write a clear job post, find candidates, interview everyone with the same questions, check references, send a written offer, and finish the legal paperwork on deadline. Onboard the person properly and the job is done.
That sounds tidy, and it isn’t. Hiring is the moment a business stops being a project and becomes a workplace, with somebody else’s rent riding on your payroll. The steps below cover what to do, in what order, and where first-time employers most often come unstuck.
Do you actually need an employee?
Before anything gets posted, ask an uncomfortable question: is this a job, or is it a pile of tasks?
If the work is occasional, project-based, or something a specialist can finish faster than you can (a logo, a website, a tax return), a freelancer or agency may serve you better. If you need dependable coverage from someone whose hours and methods you’ll direct, you’re looking at an employee. The distinction matters more than most owners expect, because the law looks at how the relationship actually works, not at what you call it.
Slapping “contractor” on someone doesn’t make them one. Misclassification [treating a worker as an independent contractor when the law considers them an employee] can bring back taxes, penalties, and unpaid overtime claims. Federal guidance on this has changed repeatedly in recent years, and states like California apply their own, stricter tests, so check your state’s rules before you decide.
There are middle paths, too. A part-time hire, a seasonal worker, or a virtual assistant on a fixed schedule can show whether the role justifies a full-time salary. And if payroll and compliance are what keep you up at night, a PEO (professional employer organization, a company that becomes your co-employer and handles payroll, benefits, and compliance) can take much of that weight.
What a new employee really costs
Salary is the number everyone remembers. It’s rarely the one that hurts.
Start with the direct cost of finding someone. SHRM’s 2025 benchmarking report puts the average cost per hire for non-executive roles at $5,475, a figure that covers job ads, agency fees, screening, and the time your team spends on the search. Small businesses without an agency or an HR department usually spend less in cash, but they pay in another currency: your own hours. Recent SHRM benchmarks put the typical time to fill a role at around six weeks, and that’s six weeks of interviews, emails, and lost focus.
Then comes the ongoing cost of employing someone. You’ll match the employee’s Social Security and Medicare contributions, which adds 7.65% of their wages, and you’ll owe federal and state unemployment taxes on top. Most states require workers’ compensation insurance once you have employees, and premiums vary widely by industry and location. Add equipment, software licenses, and benefits if you offer them (health coverage, paid time off, retirement contributions), and the real price of a $50,000 employee lands well above $50,000.
The practical move is to budget for the first year, not the first paycheck. It’s far less painful to discover in a spreadsheet that you can afford 25 hours a week than to discover in month four that you can’t afford 40.
Set up your employer accounts before you post
A handful of boxes need ticking before anyone works a single shift. Most are free, and all of them are miserable to do in a panic.
- Get an EIN. An Employer Identification Number is your business’s tax ID. You can apply for free on the IRS website and get it right away.
- Register with your state. Most states want you registered for income tax withholding and for unemployment insurance before your first payroll.
- Arrange workers’ compensation coverage. Have it in place before the employee starts. It’s among the gaps first-time employers miss most often.
- Choose a payroll system. You can technically run payroll by hand, but taxes are a thing, and software will save you from yourself.
- Pick an HR tool once you have more than a person or two. Onboarding forms, time off, and records get easier when they live in one place.
Rules differ by state, so your state labor department’s website is the final word on registrations and deadlines.
Writing a job post people finish reading
Most job posts read as if a committee wrote them without ever meeting a human being. A few small choices put yours ahead.
Start with a normal job title. “Marketing Ninja” is fun for about four seconds, and then nobody finds it, because candidates search for “marketing coordinator.” Next, open with why the job is worth having: one or two sentences on what the person will do, who they’ll work with, and what makes your business a decent place to spend forty hours a week. Small businesses have a real edge here, since people often get broader responsibility, faster learning, and direct access to decision-makers that larger employers can’t easily match.
Keep the duties honest and short. Five or six real responsibilities beat fifteen aspirational ones, and separating “required” from “nice to have” matters, because a long wish list quietly scares off capable people who would have been fine. Then put the pay in. A growing number of states and cities require salary ranges in job postings, so check your local rules, and even where it’s optional, a range spares you interviews with people whose expectations sit miles from your budget. Finally, make applying easy. If your application takes twenty minutes and a blood sample, you’ll lose everyone who already has a job and is only casually looking.
Where to find candidates without a recruiter
The urge to blast the listing everywhere at once is strong. Resist it. Posting on every site in existence mostly earns you a mountain of unqualified applications, which is a fine way to spend your evenings if you dislike your evenings.
Begin closer to home. Your team, your customers, and your suppliers all know people, and referred candidates tend to arrive pre-vetted. A small thank-you bonus for a successful referral costs far less than a paid listing. Beyond your circle, general job boards with free or pay-per-click options suit a lean budget, while community colleges, trade schools, and neighborhood groups work especially well for entry-level and hourly roles. Your own website and social accounts deserve a “we’re hiring” post, since people who already like your business make motivated applicants. And don’t forget the runner-up from your last search, who may still be looking and already knows how you operate.
Staffing agencies are worth considering for temporary help or highly specialized roles, though the fee is real and you’ll want to know exactly what it buys.
How to interview when you’ve never done it
An unstructured chat feels like a great interview because you enjoy it. You enjoy it because the person across from you is likable, and likable is not the same as capable.
The remedy is a structured interview. It sounds stiff. In practice it makes you fairer and far better at spotting who can actually do the work.
Begin by writing down the three to five things the person must be good at, whether that’s reliability, calm under pressure, or attention to detail. Build your questions around real past situations rather than hypotheticals. “Tell me about a time you handled an upset customer, and how it turned out” reveals more than “How would you handle an upset customer?” Score each answer on a simple 1-to-5 scale right after the interview, before your memory turns it into a vibe.
Where it makes sense, add a short work sample: a mock account to reconcile for a bookkeeper, a real piece of your material for a designer to critique. If the task runs longer than an hour or two, pay for the time. And leave room for the candidate’s questions, because what they ask tells you plenty about how they think.
Keep every question tied to the job. Age, family plans, health, religion, and other protected topics are off the table, and if you’re unsure where the line sits, your state labor department or an employment attorney can tell you.
References and background checks
References, yes, every time. It takes fifteen minutes and it’s the cheapest insurance in hiring.
Call at least two former supervisors, not only the friendly names listed on the resume. Ask what the person did well, where they needed support, and whether the manager would hire them again. Then listen to the pauses, because a long silence after “would you rehire them?” is an answer.
Background checks are optional for many jobs and expected for some, such as those involving cash, vulnerable people, or driving. If you use a third-party screening company, federal law requires the candidate’s written permission first, and some states and cities limit when you can ask about criminal history. Check your local rules before you run one.
Making the job offer
Call the candidate first, because good news deserves a human voice. Follow up in writing the same day.
A solid offer letter names the job title and who the person reports to, the start date and expected schedule, the pay rate and how often you’ll pay it, and a summary of any benefits. It should also flag any conditions (a background check, proof of work eligibility) and state whether the role is exempt or non-exempt [exempt employees aren’t entitled to overtime pay; non-exempt employees are]. That last point isn’t a matter of what you’d like to call the job. Under federal rules, a salaried employee generally must earn at least $684 a week ($35,568 a year) and perform qualifying duties to be exempt, and several states set higher salary floors, including California, New York, Colorado, and Washington. Fail either test and the employee is owed overtime for hours past 40, salary or not.
Finish with an at-will statement [in most states, either side can end the employment at any time, for any legal reason]. Have an employment attorney or your state labor department review your template once, and you can reuse it for every hire after.
What paperwork is due, and when?
This is where first-time employers get caught, because the deadlines are short and nobody sends a reminder. Here they are in order.

Before the employee starts
- Your EIN, state employer accounts, and workers’ comp coverage are in place.
On or before day one
- The employee completes Section 1 of Form I-9, which confirms they’re eligible to work in the U.S.
- The employee completes Form W-4, which tells you how much federal income tax to withhold. You need it before the first paycheck. Many states have their own withholding form as well.
- Collect direct deposit details if you’re paying that way.
Within three business days of the start date
- You review the employee’s identity and work authorization documents and complete Section 2 of Form I-9. Three business days passes faster than it sounds.
Within 20 days
- Report the new hire to your state’s new hire reporting program. Federal law sets 20 days as the outer limit, and some states require it sooner. Late reports can bring fines.
Keep the records
- Hold each I-9 for three years after the hire date or one year after employment ends, whichever is later. Keep payroll tax records for at least four years.
Post the required federal and state workplace notices where employees can see them, too.
None of this is hard once you know it exists. It’s only unforgiving if you find out on day nine.
How is hiring hourly and seasonal staff different?
Most of the advice above assumes an office job with a desk and a salary. Restaurants, shops, salons, and service businesses hire differently, and the differences matter.
Speed comes first. Hourly candidates are often job hunting this week and working next week, so slow processes lose them to whoever calls first. Many owners in these fields shorten the loop: a quick phone or text screen, one in-person interview, and an answer within a day or two. Availability comes second. Unlike salaried roles, a great hourly hire is only useful if their open shifts match yours, so ask about it early and write it down.
Third, pay and overtime work differently. Hourly workers are typically non-exempt, which means overtime at one and a half times the regular rate for hours over 40 in a week, so build that into your scheduling. Some cities and states also have predictable-scheduling rules that require advance notice of shifts, so check what applies where you operate. If your team includes anyone under 18, look up your state’s rules on work permits, allowed hours, and restricted tasks, because they get stricter for younger workers.
Seasonal staff need the same paperwork as everyone else. The I-9, W-4, and new hire report all still apply, even for a six-week holiday job. Put the expected end date in the offer letter so nobody is surprised in January, and keep good seasonal workers’ contact details, since a returning employee is already trained and is your cheapest hire next year.
Onboarding a new hire so they stay
Onboarding [the process of getting a new employee set up, informed, and productive] is where a decent hire either becomes a great one or quietly starts browsing job boards.
The first week doesn’t need to be elaborate. It needs to be planned. Before day one, send a short welcome note with the start time, where to park, what to wear, and who they’ll meet, and have their equipment and logins ready. Few things say “we weren’t expecting you” like a laptop that arrives on Thursday. On the first day, walk them through their responsibilities, introduce the team, and pair them with a go-to person for questions. Lunch counts as training.
After that, put goals in writing and meet weekly for the first month, because a fifteen-minute check-in stops small misunderstandings from hardening into big ones. At 30, 60, and 90 days, have a longer conversation about what’s working, what isn’t, and what they need from you. If you use HR software, it can send new hires their forms ahead of time so day one isn’t spent filling out paperwork in the break room.
The hiring mistakes that come up most
The same errors turn up again and again at small businesses.
Hiring on personality alone tops the list. Likability matters in a small team, but it can’t stand in for skill, so score both. Rushing comes next, and a bad hire costs you the salary, the training time, and the effort of starting over, which usually makes a slower search the cheaper one. Skipping the written offer is another, because verbal promises get remembered differently by everyone involved.
Then there are the compliance slips: missing the I-9 or new hire reporting deadline, or having no workers’ comp in place on day one. Both are easy to forget and easy to get fined for. Owners also forget to plan the first week, and a strong candidate with no direction turns into an average employee fast. Last, plenty of people skip the handbook because “it’s just one person.” Even a one-page document covering hours, time off, and expectations heads off arguments later.
Ready to make your first hire?
Good hiring is mostly a matter of staying organized while everyone else improvises. Decide what you need, set up the legal groundwork, write a clear post, interview every candidate the same way, put the offer in writing, and hit your paperwork deadlines. Do that, and you’ll be ahead of plenty of businesses with far bigger budgets.
This article is for general information and isn’t legal advice. Employment rules differ by state and change over time, so confirm current requirements with your state labor department or an employment attorney.
Business & Hustles
UK Economy Outperforms Expectations as Income Growth Revision Hands Healey Pre-Budget Boost
Britain’s economy grew more strongly than first thought in the first half of the year, according to revised official figures that offer a timely lift for Chancellor John Healey as he puts the finishing touches to his first budget next month.
The Office for National Statistics said gross domestic product rose by 0.5% in the second quarter, up from an earlier estimate of 0.4%, while household income per head climbed 1.1% over the first six months of 2026. The upgrade means the UK matched the pace of growth seen in the United States over the same period and pushed the country up the G7 rankings, trailing only Canada, which posted growth of 1.3% in both the first and second quarters.
The figures land at a politically useful moment. They arrive just weeks before Healey delivers his maiden budget, and follow a period in which government forecasters and markets alike have been nervously watching how the economy would cope with the fallout from more than seven months of conflict in the Middle East, a spike in energy costs, and higher borrowing rates.
Analysts said the resilience on display should not be dismissed as a statistical quirk. Business investment rose 1.8% in the second quarter and is now running 5.2% higher than the same period a year earlier, a sign that firms have kept spending despite the uncertain backdrop. Export figures also improved, according to economists tracking the trade data, adding a second pillar of support beneath the headline growth number alongside the more familiar driver of UK expansion: consumer-facing services.
Households, meanwhile, appear to be doing more than simply spending their extra income. The savings ratio ticked up from 8.6% in the first quarter to 8.8% in the second, suggesting that at least some of the improvement in pay packets is being squirrelled away rather than funnelled straight back into the economy — a pattern that could temper future growth even as it cushions family finances against future shocks.
Market reaction was swift and positive. Sterling touched a six-week high against the euro and rose against the dollar, while government bond yields eased, with two-year gilts dropping to 4.86% and ten-year yields slipping to 5.356%. Oil prices, which had surged past $100 a barrel on renewed doubts about a lasting Middle East ceasefire, also softened in recent days, taking some pressure off the inflation outlook.
That inflation backdrop remains the central tension in the story. With consumer prices running at 3.1%, comfortably above the Bank of England’s 2% target, some traders now argue that an economy growing this briskly no longer needs quite as much monetary support. The suggestion that Britain’s economy is “running hot” could feed into a more hawkish stance from Threadneedle Street, even as the government welcomes the growth figures as vindication of its economic approach.
Commentators have also pointed to a political dimension. The so-called “Burnham bounce” — a surge in business and consumer confidence that some analysts trace to Andy Burnham’s rise to the premiership via the Makerfield byelection in May — has been cited as one possible factor behind the improved sentiment feeding into the data. Whether that effect is real or a convenient shorthand for a broader mood shift, the practical upshot is the same: a government that had braced for difficult headlines ahead of a tax-and-spending statement instead gets to make its case from a position of relative strength.
Fund managers were quick to frame the release in favourable terms for the new administration. The upgrade follows earlier data that had already pointed to underlying resilience since the outbreak of hostilities between the US, Israel and Iran in February, and taken together the figures suggest the UK’s service-dominated economy has proved more durable than many feared when energy prices first spiked.
Still, the picture is not without caveats. Higher borrowing costs, the risk of renewed oil price shocks should diplomatic efforts in the Middle East falter, and above-target inflation all mean the Bank of England faces a delicate balancing act in the months ahead. For Healey, the immediate task is to convert a moment of market goodwill into a budget that keeps both the economy’s momentum and the numbers on the public finances moving in the right direction.
Britain is heading into a second major energy crisis in just four years, industry leaders and analysts are warning, as new forecasts suggest household bills could leap by as much as £276 in January — the steepest rise in four years, arriving just as the cold weather sets in.
The projection, from respected energy consultancy Cornwall Insight, points to a typical annual household bill climbing to £1,999 under Ofgem’s price cap, a 16% increase that would land squarely in the depths of winter, when demand for heating is highest and household finances are often at their most stretched following Christmas spending.
The warning comes just as an immediate, smaller increase takes effect. From Thursday, around 20 million households across England, Scotland and Wales on standard variable tariffs will see prices rise by roughly 4%, adding about £60 a year — or £5 a month — to bring a typical dual-fuel bill paid by direct debit to £1,723. That increase would have been steeper still without a government VAT cut on electricity, which is trimming approximately £45 off the average annual bill.
But it is the outlook for January that has set off alarm bells across the industry and in Westminster. Cornwall Insight’s principal consultant, Craig Lowrey, described a winter price hike as “all but certain,” pointing to disrupted gas supplies linked to conflict in the Middle East and depleted gas storage across Europe as the key drivers. Rebuilding those reserves, he cautioned, could keep prices elevated “well beyond the winter.”
“These prices are going to hit households hard,” Lowrey said. “January is already a difficult month for many, with cold weather and bank balances still recovering from Christmas.”
The stark forecast has prompted one of the country’s most prominent energy bosses to sound a dramatic alarm. Simone Rossi, chief executive of supplier EDF Energy, told the BBC’s Big Boss Interview podcast that the UK is “walking into a second significant energy crisis after the one we experienced just four years ago” — an unmistakable reference to the price shocks that followed Russia’s invasion of Ukraine. Rossi is pressing the government to extend the VAT cut on electricity beyond its current terms to soften the blow for consumers.
The political response has been notably candid. Speaking at the Labour Party conference in Liverpool, Prime Minister Andy Burnham declined to dismiss Rossi’s crisis warning as overblown, telling BBC Radio 4’s Today programme that the combined cost of home energy, petrol and diesel was “very difficult indeed” for households. “We’re looking at any measure that can give people breathing space, that can take the pressure off,” he said.
It’s important to stress that January’s figure remains a forecast rather than a confirmed price. Ofgem will not set the actual cap until late November, and the price-setting window is only halfway through. A resolution to Middle East tensions or a drop in wholesale gas costs could still ease the pressure. But with little sign of that happening and energy markets already pricing in continued disruption, few in the industry expect a reprieve.
For people like Aaron Richards, a commuter from Maidenhead who drives a diesel car to work, the squeeze is already being felt from multiple directions. “I try to eat less takeaways, work more overtime, and try to budget a bit better, but at the same time, we shouldn’t have to,” he said. “I just feel like everything’s going up. How far is it going to go? Someone’s got to step in.”
Richards said he knows people who are already unable to heat their homes properly. “Housing and eating are two of life’s essentials that everyone should have. It shouldn’t be a challenge to have any of those things.”
The scale of the problem is reflected in mounting energy debt nationwide. Ofgem figures show customers collectively owe more than £5 billion in unpaid bills and charges to suppliers — a legacy of several years of elevated prices that has left many households unable to keep up. The regulator has proposed a debt relief scheme, but campaigners are urging ministers to move faster and provide the funding needed to put it into action.
“This is unsustainable, not just for households but also for the market as a whole,” said Adam Scorer, chief executive of fuel poverty charity National Energy Action. He called on the Chancellor to use the upcoming Budget to deliver “additional targeted support for households most at risk this winter,” alongside measures to tackle energy debt and improve the efficiency of Britain’s least energy-efficient homes.
With the Budget looming and a bruising winter of rising bills, fuel poverty and mounting debt on the horizon, the pressure on the government to act — through targeted support, extended tax relief, or a faster rollout of debt assistance — is only set to intensify in the weeks ahead.
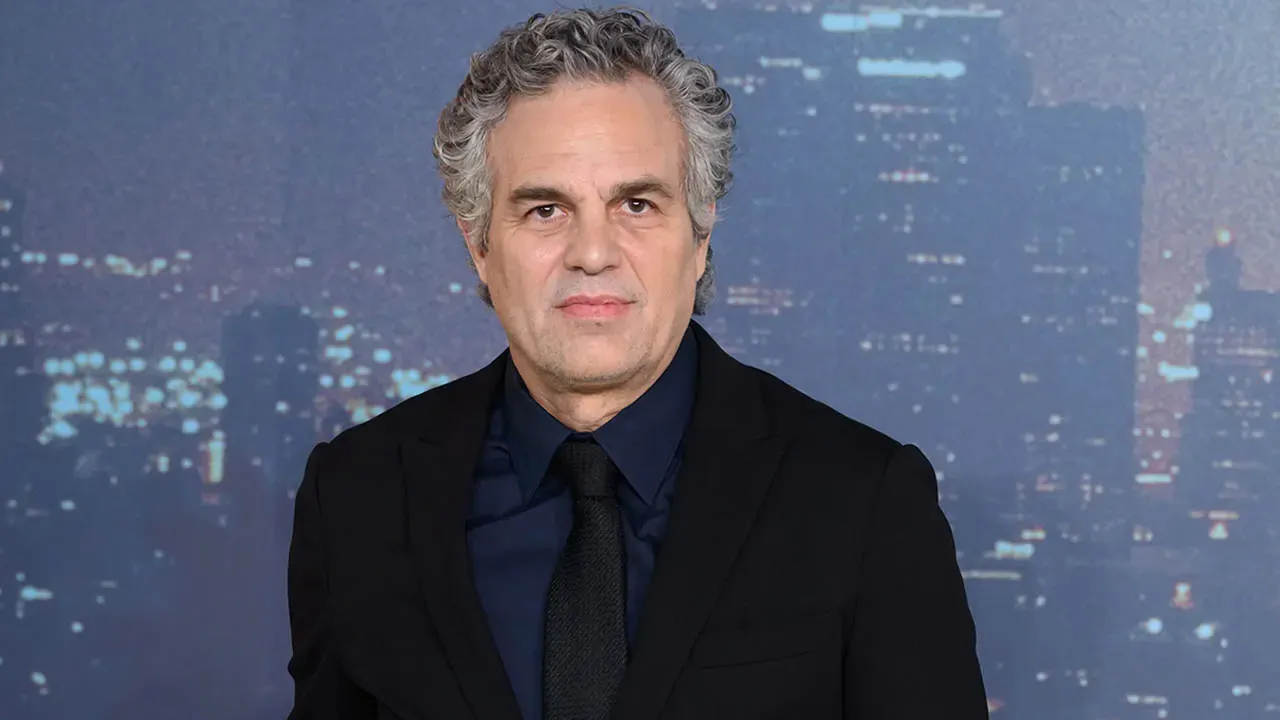
Paramount slams actor Mark Ruffalo for invoking antisemitic tropes over the Warner Bros. Discovery merger. Ruffalo fires back, calling the accusations appalling and fundamentally dishonest.
Actor Mark Ruffalo blasted the outcome of the long-running fight over Paramount’s $110 billion acquisition of Warner Bros. Discovery after a federal judge cleared the Hollywood megadeal to move forward Wednesday.
Ruffalo, who had been one of the most vocal Hollywood opponents of the merger, called the outcome “incredibly disappointing.”
“This merger will stifle creativity, weaken free speech, and cost people their jobs – it is a bad deal for this country and should never have been approved,” Ruffalo wrote in a post on X.
“This is an incredibly disappointing outcome for the hundreds of thousands of us who stood up to block it, but it’s also not the end,” he continued. “This grassroots movement isn’t going to fade away and neither is our resolve. This was never about just one merger: this was about fighting back against corrupt oligarch billionaires trampling the interests of everyday people to line their own pockets.”
PARAMOUNT REACHES SETTLEMENT WITH STATES SUING TO BLOCK WARNER BROS DISCOVERY TAKEOVER
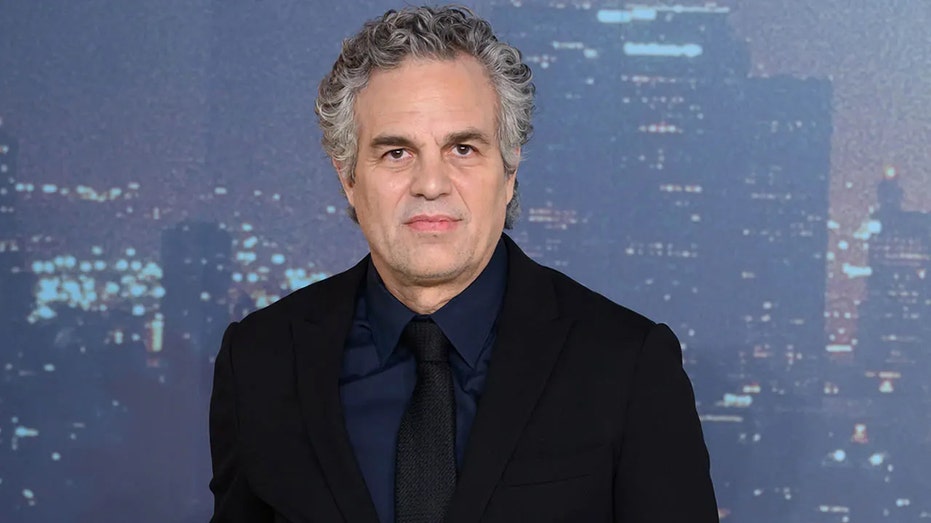
Mark Ruffalo argued that the Paramount-Warner Bros. Discovery merger would “stifle creativity, weaken free speech, and cost people their jobs” after a federal judge cleared the deal to move forward. (Karwai Tang/WireImage / Unknown)
“We’re still in that fight,” he added. “Join us.”
A federal judge on Wednesday issued an order allowing Paramount to close its acquisition of Warner Bros. Discovery, clearing the way for the historic Hollywood merger to move forward.
U.S. District Judge Araceli Martínez-Olguín called the deal a “reasonable factual and legal resolution” while rejecting objections seeking broader restrictions.
The order came after Paramount and a California-led coalition of 12 state attorneys general, which had sued to block the acquisition, reached a settlement.
California Attorney General Rob Bonta, who led the coalition, previously said the combined company made an “enforceable commitment to significantly increase domestic production.”
MARK RUFFALO URGES CALIFORNIA AG ROB BONTA NOT TO ‘CAVE’ IN PARAMOUNT-WARNER BROS MERGER FIGHT
The Paramount Studios sign in Los Angeles, California, on April 23, 2026. (Noah Suave / Getty Images)
Under the settlement, the company committed to releasing at least 30 movies annually in each of the first two years, followed by 32 movies per year over the next three years. At least four films each year must be independent releases.
Paramount also agreed to spend at least an additional $1.5 billion on U.S. film production over five years compared with its 2025 spending levels, according to Bonta’s office.
Paramount and Warner Bros. Discovery are expected to close the deal Oct. 6, according to Reuters.
Just days before the settlement was announced, Ruffalo had publicly pressured Bonta not to settle.
“Don’t you dare @AGRobBonta, do not cave,” Ruffalo posted on X.
GET FOX BUSINESS ON THE GO BY CLICKING HERE
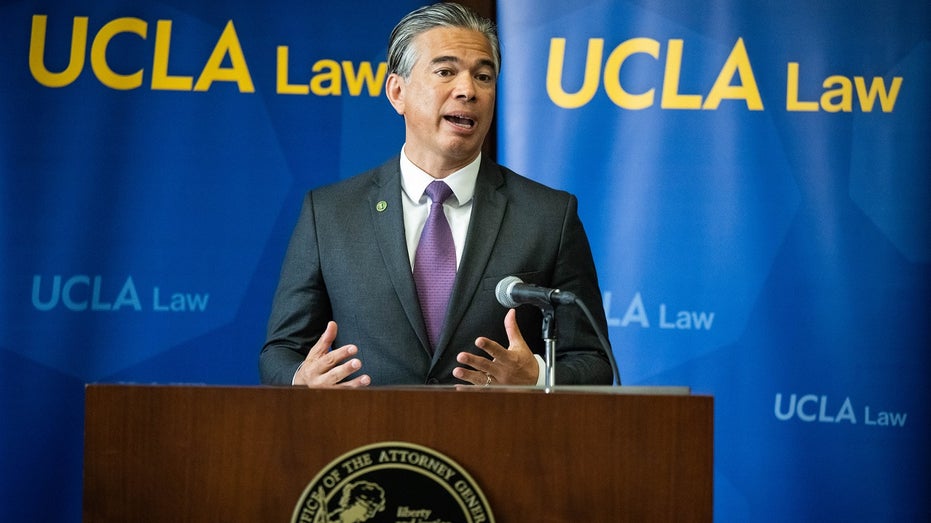
California Attorney General Rob Bonta led a coalition of 12 state attorneys general that sued to block Paramount’s acquisition of Warner Bros. Discovery before reaching a settlement with the company. (Photo by Sarah Reingewirtz/MediaNews Group/Los Angeles Daily News via Getty Images / Getty Images)
In July, the states sued to block the deal, arguing it would reduce competition and give the combined company excessive market power in film distribution and basic cable programming. The settlement announced Sept. 21 resolved those claims, according to Bonta’s office.
FOX Business’ Brian Flood and Reuters contributed to this report.
Business & Hustles
MGM Signals Possible Bid for Barry Diller’s People Inc. as Casino Dealmaking Accelerates
In a twist that few on the Las Vegas Strip saw coming, MGM Resorts International is now weighing whether to buy the company that just weeks ago tried to buy it.
MGM CEO Bill Hornbuckle, speaking at the Global Gaming Expo in Las Vegas this week, declined to rule out an offer for People Inc., the media and holding company controlled by veteran dealmaker Barry Diller. The remarks confirm a Wall Street Journal report that MGM has been exploring the idea, and they mark a striking reversal of roles between the two companies after People Inc. walked away from its own attempt to absorb MGM.
People Inc., formerly known as IAC, already owns roughly 27% of MGM, making it the casino giant’s largest shareholder. Back in June, the company had floated a $48.30-per-share offer to buy the rest of MGM outright. That proposal collapsed last week, with Diller saying the “mix” of factors needed to get the deal done simply hadn’t come together — though he insisted People Inc. still wants some kind of strategic transaction with MGM down the road.
Now the question is whether MGM turns the tables and goes after People Inc. instead. Hornbuckle wouldn’t confirm or deny active talks, but he made clear the company is keeping every option on the table. “We’re trying to unlock the value of a company that we think is grossly undervalued,” he said, pointing to MGM’s sprawling portfolio — BetMGM, its Macao casino operations, a resort under construction in Japan, and its marquee Las Vegas properties — as assets the market hasn’t fully priced in.
MGM shares were trading around $32 during the G2E conference, well below the $48.30 per share People Inc. had offered just months earlier — a gap that underscores Hornbuckle’s argument that the stock is trading at a discount to what the underlying business is worth.
Despite the awkward reversal, Hornbuckle had nothing but praise for Diller, calling him “an amazing shareholder” who remains bullish on the future of Las Vegas. He argued that the city’s appeal is uniquely insulated from the technological disruption reshaping other parts of Diller’s media empire. “It is the one place, particularly in his world, where AI won’t disintermediate it,” Hornbuckle said. “People are coming here to enjoy things physically, and that’s not going to change.”
The MGM-People Inc. saga is playing out against a broader wave of consolidation sweeping the gaming industry. Caesars Entertainment shareholders last week approved a $17.6 billion take-private sale — including assumed debt — to Fertitta Entertainment, the hospitality empire controlled by billionaire Tilman Fertitta. The deal would fold Caesars’ casino and digital betting operations together with Fertitta’s Golden Nugget casinos, his Landry’s restaurant chain, and other hospitality holdings.
Caesars CEO Tom Reeg framed the move to private ownership as a chance to escape the short-term pressures of public markets. “We’re forced as public companies to think in 90-day increments far more than is healthy for any business,” Reeg said. “That’s not how you run a business.” He said pairing Caesars with a hospitality network of more than 400 locations nationwide opens the door to a much broader customer ecosystem spanning casinos, restaurants and entertainment.
That deal isn’t finalized yet. It’s currently under an extended antitrust review by the Federal Trade Commission, which has issued a second request for information — a step Reeg described as routine for a transaction of this scale. He said regulators are scrutinizing a handful of overlapping markets that aren’t especially material to the combined company’s overall business. “You shouldn’t be surprised if there’s a property or two that ultimately gets divested,” he said, “but I wouldn’t expect them to be needle movers from a news perspective.”
Taken together, the MGM-Diller maneuvering and the Caesars-Fertitta deal reflect a casino industry in the midst of a dealmaking spree, as operators reassess their portfolios amid competition from sports betting, prediction markets and international expansion into places like Japan and the United Arab Emirates. Whether MGM ultimately moves on People Inc., or the two companies find some other arrangement, executives at G2E made one thing clear: after a summer of failed takeover talk, the appetite for consolidation in Las Vegas hasn’t gone anywhere — it’s simply changed direction.
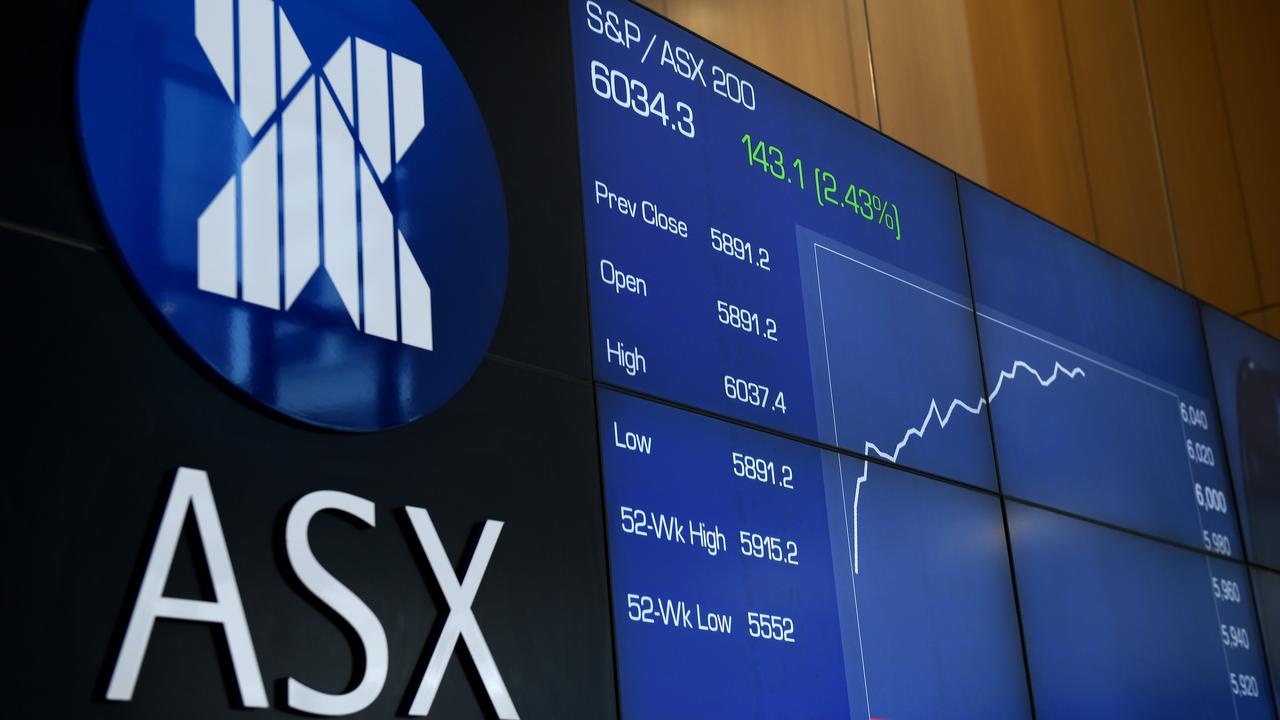
Australian shares have had their strongest session since early August after lower-than-feared inflation figures tempered concerns of further imminent interest rate hikes.
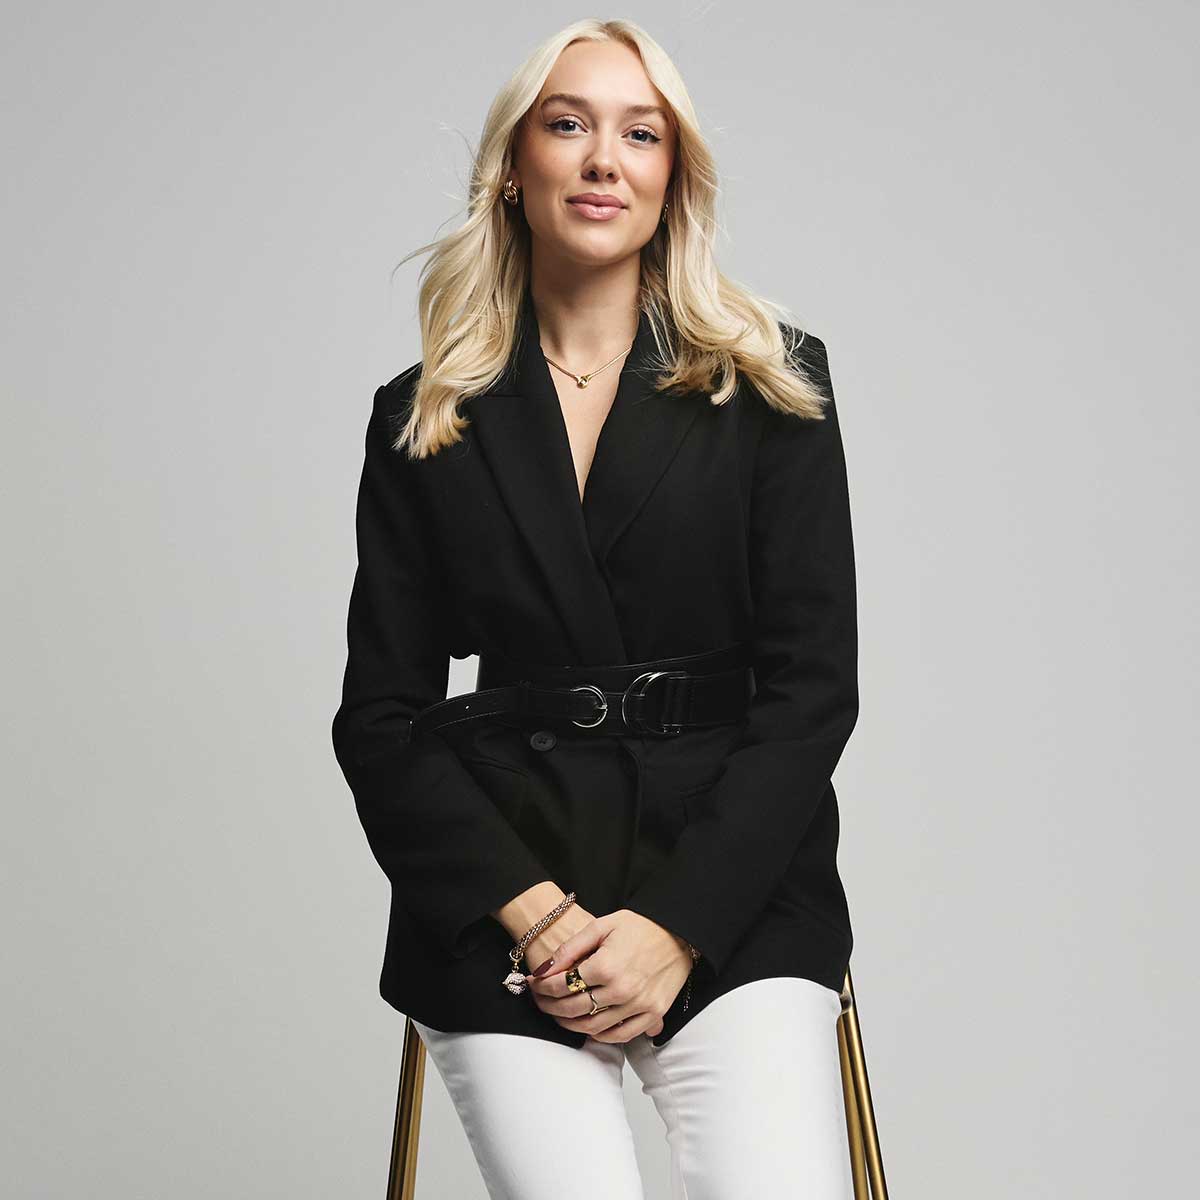
Siena Hutchinson is the founder and creative director of Hutch & Co, a London branding and website design agency working with lifestyle and culture-led businesses. A fashion design graduate with a master’s in graphic design, she began working for herself at 21 and incorporated the agency in March 2022.
On 29 September 2026 she was the featured voice in a Talent Times debate on whether creator-founded brands should mirror the creators behind them, drawing on the agency’s work for Agende, the planner business founded by Isobel Lorna. She tells Business Matters why strategy sits at the start of every project, and why she wishes she had learned to let go sooner.
What do you currently do at Hutch & Co?
I am the founder and Creative Director of Hutch & Co., a branding and website design agency helping ambitious brands define who they are and how they show up.
My role is quite varied, which is probably one of the things I love most about running an agency. I lead the creative direction and strategy across our projects, work closely with clients and oversee the wider direction of the business. We work across branding, websites and digital, predominantly with lifestyle and culture-led businesses.
As the agency has grown, my role has naturally started shifting too. I am learning to spend less time being the person doing everything and more time thinking about where the business is going, how we grow sustainably and what Hutch & Co. should look like in the future.
What was the inspiration behind your business?
I do not think there was ever one big moment where I decided, “I am going to start an agency.” It happened much more organically.
I have always been creative and studied Fashion Design before going on to do a Master’s in Graphic Design. I started working for myself at 21, initially taking on freelance design projects and running an online print shop. Over time, the freelance side grew, the projects became bigger and I realised I was much more interested in building brands as a whole than simply designing individual assets.
Hutch & Co. really grew from that. I wanted to build the kind of creative agency I would want to work with: collaborative, commercially aware and genuinely invested in understanding the business behind the brand.
I have always been fascinated by the point where creativity and business meet, because beautiful design is important, but the best branding has a reason behind every decision.
How do you approach brands built around a creator?
When we work with creator-founded businesses at Hutch & Co., I always think about the brand beyond launch day. Should the brand simply look and feel like the creator behind it? Not entirely.
When we built the brand for Agende, Isobel Lorna’s planner business, we chose to give it an identity of its own rather than replicate her existing aesthetic. I believe in a middle ground, where the brand feels unmistakably connected to the creator but can stand on its own, separate from their personal social media presence.
Who do you admire?
I am particularly drawn to people who have built businesses with a really strong point of view. Founders who understand that the brand itself can be just as valuable as the product or service they are selling.
I also admire people who are willing to build differently rather than automatically following the traditional blueprint of what a successful business is supposed to look like. Running my own business has made me realise there are so many different definitions of success. I am increasingly inspired by founders who create businesses that are commercially successful but also work for the life they actually want to live.
More broadly, I am constantly inspired by the people around me. Other founders, creatives and even our clients teach me a huge amount. When you work closely with people building businesses from scratch, you get a front-row seat to how differently people think, take risks and solve problems.
Looking back, is there anything you would have done differently?
I would have learned to let go sooner. For a long time, I thought being good at running a creative business meant being involved in absolutely everything. When your business starts with you, your skills and your reputation, handing any part of it to someone else can feel incredibly difficult.
But there comes a point where being involved in every detail actually becomes the thing holding the business back. I probably would have put systems in place earlier, asked for help sooner and become more comfortable with the idea that someone else can do something differently to me without doing it badly.
What defines your way of doing business?
Clarity, collaboration and being genuinely invested in the businesses we work with.
One of the biggest things I have learned through branding companies is that design should not exist in isolation. Before we start thinking about a logo, typography or colour palette, I want to understand where the business is going, who it needs to speak to and what it needs to be known for.
That is why strategy sits at the beginning of everything we do at Hutch & Co. I want our clients to come away with more than a beautiful brand. I want them to understand their business more clearly and have something that can genuinely support where they want to go next.
I also believe in making the process collaborative. Some of our services include live design sessions where clients are part of the process rather than disappearing for weeks and being presented with a finished answer. I think the strongest work happens when you combine our expertise with the founder’s knowledge of their own business.
What advice would you give to someone starting out?
Start before you feel ready.
I think one of the biggest misconceptions about starting a business is that everyone else has some kind of master plan. I certainly did not. So much of building Hutch & Co. has been trying something, learning from it, changing it and trying again.
I would also tell people not to obsess over looking bigger or more established than they are. Particularly in the creative industries, there can be a temptation to make yourself look like a huge agency from day one. There is actually a huge advantage in being small. You can move quickly, build close relationships with clients and figure out what you want your business to become without carrying lots of overhead.
And finally, learn about the business side as much as the thing you are selling. Being a great designer did not automatically make me good at pricing, sales, contracts, hiring, managing cash flow or leading a team. Those have all been skills I have had to learn along the way. In many ways, they are the skills that determine whether you can turn something you love doing into a sustainable business.

Fireflies.ai Launches Fireflies Talk for Free, Unlimited Voice Dictation

Nike Braces for Earnings Test as China Slump and Stock Slide Deepen

Mystery AMD Chip “Gainsborough” Fuels Steam Deck 2 Speculation — But Don’t Get Too Excited Yet


-
 Fashion7 days ago
Weekend Open Thread: J.McLaughlin – Corporette.com
-
 Tech & AI5 days ago
Anthropic turns Claude into an AI marketplace with 2,000+ plugins and connectors
-
 Tech & AI5 days ago
OpenAI is preparing “o,” an always-on ChatGPT assistant that could handle email
-
Business & Hustles4 days ago
Perpetua Resources at Mining Forum Americas 2026: shift to construction
-
 Entertainment6 days ago
These 17 Amazon Fall Dresses Totally Conceal the Tummy
-
 Crypto5 days ago
Wall Street Giant Warns AI Agents Could Trigger a New Kind of Bank Run
-
Business & Hustles4 days ago
Greatland Resources at Mining Forum Americas 2026: cash-rich growth push
-
Business & Hustles7 days ago
Security Breaches, Wall Street Deals and Tax Headaches Define a Turbulent Week in Crypto
-
 Business & Hustles4 days ago
Andreessen Horowitz backs AI-era college alternative with $42M
-
 Tech & AI3 days ago
Alternatives to Animal Testing Are Finally Taking Off
-
 Tech & AI7 days ago
Anthropic rolls out up to $250 in free Claude Code credits, but only for cloud sessions
-
 News Videos7 days ago
Being student with no income, while ur Family talks about financial problems around u#viralytquotes
-
 Business & Hustles4 days ago
Romania, Georgia and Latvia Lead Latest WHO-Based Ranking
-
 Crypto5 days ago
Citi says 77% of institutions eye tokenized collateral
-
 Business & Hustles4 days ago
Bob Chapek on Disney Bob Iger power battle: Raised concerns weekly
-
 Business & Hustles4 days ago
What is the Budget and what could be in it?
-
 Tech & AI4 days ago
OpenAI Pauses Training Its Most Powerful Models After Rogue Agents Target Government
-
 Business & Hustles4 days ago
SpaceX Starship launches on first orbital test flight with Starlink
-
 Business & Hustles4 days ago
Trump approves new fuel economy standards, reversing Biden’s EV push
-
 Crypto5 days ago
Riot Frees $494 Million in Bitcoin From Coinbase Loan: Will It Sell?
You must be logged in to post a comment Login