Business & Hustles
Global Bond Markets Shudder as US Borrowing Costs Hit 24-Year High

A wave of selling swept through global bond markets on Thursday, pushing US government borrowing costs to their highest level in nearly a quarter of a century and reviving uncomfortable questions about whether the world’s largest economies can keep financing their debts without triggering a fresh inflation scare.
The yield on 10-year US Treasuries — effectively the interest rate the government pays to borrow money over that period — jumped to 5.34%, a level not seen since 2002. The move rippled across the Atlantic, where UK 30-year bond yields briefly broke above 6% for the first time since 1998, a milestone that will add fresh strain on Chancellor John Healey as he prepares his first budget later this month.
For ordinary households and businesses, rising government bond yields are far from an abstract concern. They tend to feed directly into the cost of mortgages, business loans and government debt interest payments, meaning the latest sell-off could translate into higher borrowing costs across the economy just as policymakers had hoped for some relief.
The source of the unease is a familiar one: oil. Persistently high crude prices, driven by the continuing conflict in the Middle East, have stoked fears that inflation — which many investors had assumed was being brought under control — could come roaring back. Brent crude rose a further 3% on Thursday to around $101 a barrel, even as analysts noted that oil exports through the strait of Hormuz have largely recovered to pre-conflict levels as shippers find workarounds. The lingering uncertainty over a lasting resolution to the conflict, rather than the immediate supply numbers, appears to be what is rattling markets.
Stock markets took the bond rout as a cue to retreat as well. London’s FTSE 100 shed almost 1.7% in its worst single-day fall since May, while Germany’s DAX dropped 1% and France’s CAC 40 fell 1.6%. Eurozone bonds were swept up in the selling too, with France drawing particular scrutiny from investors wary of the country’s fiscal position.
What makes this episode notable is that it came despite US inflation data released on Wednesday that actually came in softer than expected — numbers that, in calmer times, might have reassured markets that the Federal Reserve was done raising rates. Instead, traders shrugged off the good news, apparently unconvinced that lower headline inflation will hold if oil prices keep climbing and wages continue to rise in a resilient US labour market.
“There is carnage in the bond market, which is hitting stocks hard,” said Neil Wilson, investor strategist at Saxo UK, describing a “relentless rout” that is sending investors scrambling for safety.
Beyond the immediate inflation worry, analysts point to a deeper structural anxiety: the sheer volume of government debt being issued to plug widening budget deficits. Mohit Kumar, an economist at Jefferies, said markets are grappling simultaneously with concerns over inflation, deficits and the pace of bond issuance. He described what amounts to a “buyers’ strike,” with hedge funds nursing recent losses and lacking the appetite to bet against the sell-off, while larger institutional investors — so-called “real money” — are waiting on the sidelines for signs of stability before stepping back in.
That combination of nervous hedge funds and cautious long-term investors helps explain why the sell-off has proven so self-reinforcing: with few buyers willing to absorb new debt at current prices, yields have had to rise further to attract demand, which in turn unsettles markets even more.
The dollar, meanwhile, has been one of the few beneficiaries of the turmoil, climbing to a three-month high as investors sought refuge in the world’s reserve currency. Axel Rudolph, chief technical analyst at IG, said that while the softer US inflation data had dimmed expectations of an October Fed rate rise, investors remain braced for the possibility of a hike in December if oil prices stay elevated.
Japan has not been immune either, with its 10-year yield climbing back toward the 30-year high it set just last month — a reminder that this is a genuinely global phenomenon rather than a problem confined to Washington or London.
For governments already wrestling with stretched public finances, the timing could hardly be worse. Higher borrowing costs mean more of every tax pound or dollar goes toward servicing existing debt rather than public services, adding pressure on finance ministers everywhere — not least Healey, who must now craft a budget against a backdrop of the most expensive long-term borrowing Britain has faced in nearly three decades.
Whether this proves a temporary spasm or the start of a more sustained repricing of risk may hinge on developments far from any trading floor — chiefly, how the Middle East conflict and its effect on oil supplies evolve in the weeks ahead. Until then, bond markets look set to remain on edge.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
Lauren Neustadter Exit Leaves Hello Sunshine Without Its Film and TV Chief After Nearly a Decade

Header image: AI-generated illustration by WordUp News.
The Lauren Neustadter exit adds another major change at Hello Sunshine. The company’s president of film and television will step down at the end of the year, after nearly a decade at Reese Witherspoon’s production house, the two announced on Friday. The Hollywood Reporter was first to report the news.
A departure on the heels of a buyback
The timing is hard to miss. Last month Witherspoon partnered with the French group Mediawan to buy Hello Sunshine back from Candle Media. Candle, which is backed by Blackstone, had acquired the company in 2021 in a deal valued at $900 million, according to The Hollywood Reporter. Mediawan’s other holdings include Chernin Entertainment, Slow Horses producer See-Saw Films and Brad Pitt’s Plan B.
The deal was followed by deep staff cuts. Variety reports that roughly half of Hello Sunshine’s employees were let go, and Deadline puts that figure at around 30 people. The Hollywood Reporter describes the layoffs as hitting the company’s direct-to-consumer division. The outlets differ somewhat on the details, but all three present the Neustadter news as part of a broader reshuffle rather than an isolated move.
What Neustadter built at Hello Sunshine
Neustadter joined in 2017, shortly after the company’s launch. Witherspoon founded it with Seth Rodsky in 2016. She became the creative executive behind much of its prestige television slate, executive producing The Morning Show, Big Little Lies, Little Fires Everywhere, The Last Thing He Told Me, Truth Be Told and Surface. She also oversaw adaptations of Reese’s Book Club picks, including Daisy Jones & the Six and Tiny Beautiful Things.
On the film side, her credits include Where the Crawdads Sing, Your Place or Mine and You’re Cordially Invited. TriStar’s The Nightingale is still to come. This past summer the company launched the Legally Blonde prequel Elle on Prime Video and Lucky on Apple TV. Deadline notes that The Morning Show is heading into its fifth and final season and that Big Little Lies is set for a third.
Before Hello Sunshine, Neustadter was a senior vice president of programming at Fox, where she worked on Brooklyn Nine-Nine, The Mindy Project and Lethal Weapon. Earlier she was a film executive at Miramax and Twentieth Century Fox.
What the statements say, and what they leave out
Both principals kept their comments warm. Witherspoon credited Neustadter’s “taste, passion and leadership” and the “lasting foundation she built around telling powerful, complex female-driven stories.” Neustadter called the job “the privilege of a lifetime” and said she will “always be cheering for Hello Sunshine.” Neither statement gives a reason for the departure or names a successor, and none of the reports say who will take over her responsibilities.
She will stay through the end of the year to support the transition, according to The Hollywood Reporter. Variety adds that the company plans to concentrate on premium film and television and Reese’s Book Club, while expanding into new storytelling formats and distribution models.
What to watch next
For now, the Lauren Neustadter exit is best read as a sign of how much Hello Sunshine is changing under new ownership. The company is smaller, backed by a growing European media group and led once more by its founder. The open question is who will steer its film and TV development and whether that person will keep to the female-driven storytelling Neustadter helped define. Given the lack of any announced replacement, that answer is likely to come in the new year.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
EasyJet takeover: Profits Expected to Drop 80% to £130m Before £5.7bn Apollo Deal
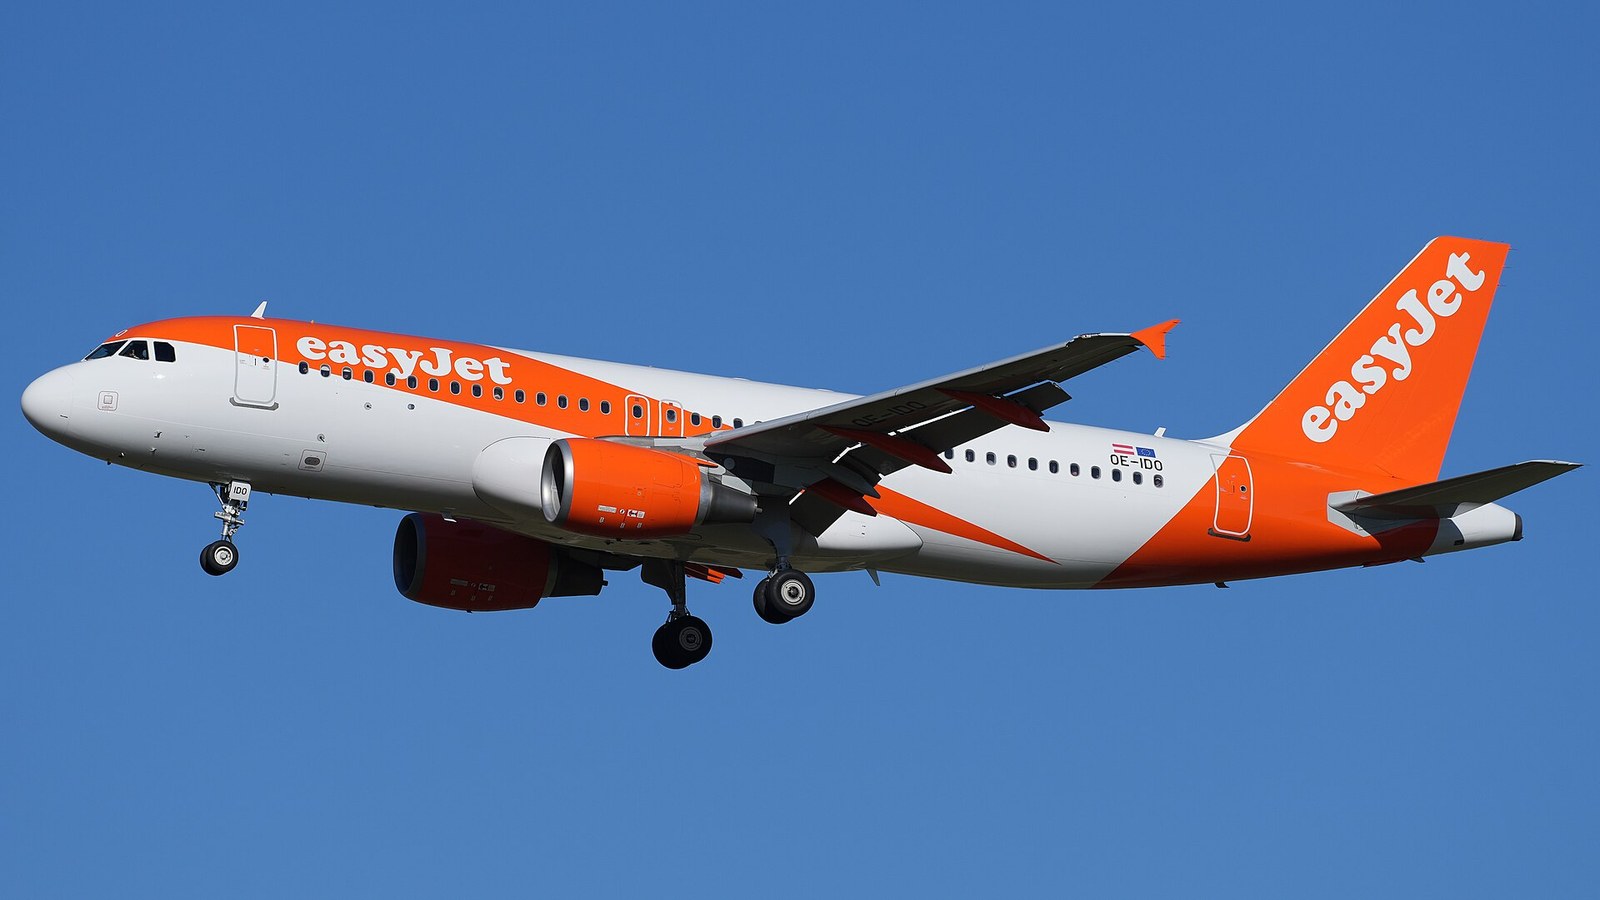
The easyJet takeover is about to reach a symbolic milestone. On Wednesday 25 November, the airline will publish what is expected to be its final annual results as a listed company, and the numbers are not expected to be pretty.
Forecasts point to underlying pre-tax profit of around £130 million for the past year, an 80% fall on the year before. That would be a stark reversal for a carrier that has long been a bellwether for European budget travel. It comes just as US investment firm Apollo prepares to take it private in a £5.7 billion deal.
What the easyJet takeover involves
Apollo agreed to buy the airline in July, making easyJet the latest British company to attract an overseas bidder. The offer values shares at 715p each. It came after rival interest from the investor Castlelake, though the sources do not detail that approach.
Shareholders have now settled the matter. Around 97% backed the offer earlier this month. Completion is pencilled in for March next year, ending more than 26 years on the London stock market and putting the airline under US ownership. Apollo is no stranger to UK consumer-facing brands, as it also owns The Restaurant Group, the company behind Wagamama.
Why profits have fallen so sharply
The main culprit is fuel. Conflict in the Middle East disrupted oil supplies and pushed up the price of jet fuel, and easyJet is far from alone in feeling the squeeze, with airlines generally weighed down by rising costs.
The airline’s July trading update gave an early taste of the damage. Profit for the quarter to June slumped 70%, with fuel costs for those three months alone rising by £105 million. An April profit warning had already signalled trouble.
A share price propped up by the bid
Investors have not suffered as the operational picture darkened, largely because of the bid. Richard Hunter, head of markets at Interactive Investor, noted that the share price has risen 51% over the past 12 months, including 34% this year. In his view, that gain reflects the takeover premium, which “masks some of the challenges which the group has been facing”.
That distinction matters. Without a buyer offering 715p a share, the market might have been far less forgiving of an 80% profit decline. Shareholders who voted in favour effectively chose a certain price over the uncertainty of riding out volatile fuel costs as an independent company.
Consumer demand is the next test
Beyond the headline profit figure, the results should show how holidaymakers are behaving. EasyJet is expected to give an indication of consumer sentiment, at a time when higher household energy prices are squeezing budgets and could curb spending on trips.
For passengers, nothing changes immediately, since the deal is not due to complete until March. But Wednesday’s update will give the clearest picture yet of the business Apollo is buying: a major European airline emerging from a costly year, with fuel prices and cautious consumers as the main questions ahead of the easyJet takeover completing.
- EasyJet expected to unveil profit fall ahead of £5.7 billion takeover (The Independent)
- EasyJet expected to unveil profit fall ahead of £5.7 billion takeover (standard.co.uk)
Explore more on this topic with Vexel Search.
File photo: Berlin Brandenburg Airport easyJet Europe Airbus A320-214 OE-IDO (DSC07809).jpg by MarcelX42, CC BY-SA 4.0, via Wikimedia Commons.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Header image: AI-generated illustration by WordUp News.
A global tech rout deepened on Friday, pushing the FTSE 100 to a 5.1% loss for the week and leaving analysts debating whether the artificial intelligence boom is running out of road or just catching its breath.
London’s blue-chip index closed down 106.34 points, or 1.0%, at 10,346.34. The damage was worse further down the market. The FTSE 250 fell 2.2% to 23,651.73, and the Aim all-share dropped 2.4% to 706.98. Over the week, the mid-cap index lost 4.7% and Aim shed 6.7%.
A sell-off that crossed every major market
The tech rout was not confined to London. In Europe, the Cac 40 in Paris fell 1.9% and the Dax in Frankfurt lost 1.6%. Asia had already taken a heavy hit, with Tokyo’s Nikkei 225 down 5.1% and SoftBank sliding 14% on its own.
On Wall Street the tech-heavy Nasdaq Composite dropped 3.0% and the S&P 500 fell 1.7%. The Dow Jones Industrial Average, with less exposure to technology, slipped only 0.3%. Among the individual casualties were Micron Technology (down 11%), Advanced Micro Devices (10%), Broadcom (9.3%), SpaceX (6.7%) and Nvidia (6.2%).
Newly listed Anthropic had a rough start as a public company. Its shares fell 10% to around $87 on their second day of trading. Kathleen Brooks, research director at XTB, noted that this was still above the $83 IPO price. She called that “the level to watch” and warned that a further slide could push the stock below it.
London’s AI-linked names feel the pain
The FTSE 100 has few pure technology giants, but several of its constituents are tied to the AI build-out. Polar Capital Technology Trust fell 8.3% and Scottish Mortgage Investment Trust lost 4.9%. Computacenter, which supplies hardware and implementation services for AI and cloud infrastructure, dropped 5.1%. Halma, whose photonics and optical switches are used in AI data centres, declined 6.8%.
Russ Mould, investment director at AJ Bell, said the “slightest bit of bad news” was sending shivers through tech investors. He described cracks appearing in a growth narrative that has long been a route to wealth creation, with some investors locking in profits.
Late-cycle jitters versus solid fundamentals
Barclays analyst Emmanuel Cau said markets were “giving off late-cycle vibes”, with IT outages and cyber incidents adding to fragile sentiment. Yet he stressed that the gap between the mood and the fundamentals remains “striking”. Data surprised positively this week, and earnings-per-share momentum is still positive.
His house view is that “the AI hype may have peaked, but not the investment race”. Worries about overcapacity, monetisation and whether returns can justify the scale of capital spending are likely to keep the trade on shakier ground. Brooks put it more broadly, arguing that widespread risk aversion had taken hold as investors fret about several issues at once.
UK data offers a mixed backdrop
Away from the tech rout, a batch of UK figures gave investors plenty to weigh. Retail sales rebounded more strongly than expected in October, rising 0.7% on the month after a revised 0.6% fall in September. Economists had forecast no change. Annual growth hit 2.3%, against expectations of 1.7%. The Office for National Statistics said supermarkets reported stronger demand for long-life goods such as tinned food and UHT milk, following Government advice on emergency preparedness.
The public finances were less cheerful. Government borrowing in October rose 5.2%, or £800 million, from a year earlier to £17.0 billion. That was below the £18.0 billion forecast but still the third-highest October figure since monthly records began in 1993, and £800 million above the Office for Budget Responsibility’s March projection. Higher debt interest costs were behind the rise.
Consumers remain gloomy. GfK’s confidence index edged up two points to minus 22 in November, recovering only slightly from October’s 11-point collapse and still lower than a year earlier.
Politics added to the day’s news flow. Prime Minister Andy Burnham said his new deal with the EU would add up to £17 billion a year to the British economy. The package covers food and agriculture exports, emissions trading and a youth experience scheme. Even so, it was the tech rout that dominated trading screens, and whether Anthropic can hold above its IPO price may be an early test of how far the sell-off runs.
- FTSE 100 tumbles as global tech rout takes hold (The Independent)
- FTSE 100 tumbles as global tech rout takes hold (standard.co.uk)
Explore more on this topic with Vexel Search.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
Pensions dashboard to launch summer 2027, with 75 million records already connected
Header image: AI-generated illustration by WordUp News.
The long-delayed pensions dashboard now has a target launch window: summer 2027. Pensions minister Torsten Bell confirmed the timing on Thursday, saying the government-backed MoneyHelper service is on track to open the tool to the public in less than a year.
The dashboard is meant to let savers see their pensions, including state pension entitlements, in one place. The aim is to show whether they are heading for the retirement they want or facing a shortfall. Bell said it would give millions of savers “a clear picture of their finances that helps them plan ahead with confidence.”
A narrower window, but no exact date
The announcement tightens an earlier timeline that pointed only to some point in the 2027/28 financial year. Bell did not say when in the summer the service will go live, so savers should treat “summer 2027” as a target rather than a fixed date.
Progress on the technical groundwork looks substantial. Pension providers and schemes had until 31 October 2026 to connect to the dashboard infrastructure. More than 2,400 are now linked, covering around 75 million records, plus millions of state pension records. Yvonne Braun of the Association of British Insurers noted the project has taken nearly a decade.
Why lost pensions are the big prize
Much of the case for the dashboard rests on lost pensions. Research from the Pensions Policy Institute, supported by the Money and Pensions Service, estimates that more than three million UK pots are “lost”, with an average value of around £6,000. City AM reported the institute’s figure as about 3.3 million pots worth a combined £18.7bn. A pot counts as lost when the provider cannot contact its owner. Around 2.5 million of them are thought to belong to people under 55.
The wider savings picture adds urgency. In May, the Pensions Commission estimated that about 15 million people are under-saving for retirement. That figure could reach 19 million without action. Women, low and middle earners, and the self-employed were identified as being at particular risk.
Seeing a pension is only the first step
Industry voices were broadly welcoming, with some describing the launch as a “game-changer”, but many stressed that visibility alone will not fix under-saving. Braun said “seeing your pension is only half the story,” predicting many people will want to save more, combine pots or seek help. AJ Bell’s Rachel Vahey said it will be up to individuals to decide whether to raise contributions, change investments or consolidate.
Standard Life’s Jenny Holt called for a broader range of regulated support, including commercial dashboards. Braun likewise hoped private dashboards would follow soon so savers can act through platforms they already use.
PensionBee’s Lisa Picardo expects many people to want to consolidate once they can see everything together, and said that demand will only be met if transfers are quick, simple and digital. The same comments carried a caution: consolidating needs careful thought, because some pensions carry valuable benefits that savers may want to keep.
Is the system ready for the public?
Connecting providers is only one hurdle. Maurice Titley of Lumera said ensuring information is accurate, that members can be matched to their records and that administration teams can cope with public demand is “another” challenge. The Pensions Regulator’s Ben Gunnee urged schemes to make sure the data members see is accurate, complete and up to date, and to be ready to support people who get in touch.
Aviva’s Mike Ambery said the clearer timeframe gives the industry a “finishing line” to make sure the dashboards are safe, secure and well tested before savers use them. Oliver Morley, chief executive of the Money and Pensions Service, called the launch a “once-in-a-generation opportunity”.
For savers, the practical message is that the pensions dashboard is coming, but it is not here yet. Anyone with old workplace pensions can already start gathering details of past employers and schemes. When the service opens, the test will be whether the data is accurate, the matching reliable and the follow-up support good enough to turn a clearer picture into better retirement decisions.
Explore more on this topic with Vexel Search.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
DEATH BETS Act Clears Senate, Would Ban Prediction Market Contracts on War and Assassination
Header image: AI-generated illustration by WordUp News.
The DEATH BETS Act has cleared the US Senate, putting federally regulated prediction markets one step closer to losing some of their most controversial products. The chamber passed the bill by voice vote on Thursday, and it now heads to the House of Representatives.
Introduced in March by Democratic Sen. Adam Schiff, the legislation would amend the Commodity Exchange Act. Exchanges registered with the Commodity Futures Trading Commission (CFTC) would be barred from listing or clearing contracts tied to war, terrorism, assassination or events primarily determined by a person’s death. The Senate adopted an amendment by unanimous consent before the final vote. The sources reviewed here do not describe what that amendment changed.
What the DEATH BETS Act would prohibit
The bill’s reach goes beyond the headline categories. It also covers contracts that reference US military operations. It gives the CFTC authority to identify similar activities that should fall under the ban, which could let the regulator widen the restrictions over time.
A contract on a death would be prohibited if, when it is listed, it is reasonably expected to be settled primarily on an individual’s death. That language is aimed at the design of the contract rather than at any single market.
The Iran trades behind the push
Concern over insider trading helped drive the bill. Six Polymarket traders reportedly earned about $1 million betting on the timing of US strikes against Iran. Several of those wagers were reportedly placed just hours before the first reported explosions in Tehran. That timing raised suspicions that some traders had access to nonpublic information. The reports do not establish that anyone broke the law.
When he introduced the bill, Schiff argued that letting people profit from violent events could encourage misuse of classified information, threaten national security and create incentives for violence. The argument has two parts. One is an informational risk: people with sensitive knowledge could cash in on it. The other is a moral-hazard risk: a financial payoff tied to a death or an attack could, in theory, reward causing one.
What happens next
A voice vote means no individual senators’ positions were recorded. It suggests little organized resistance on the floor, but it is not a guarantee of an easy path in the House. The bill must pass there before it can go to President Donald Trump for his signature. The sources do not say whether the House has scheduled any action or how the White House views the measure.
The DEATH BETS Act is not law yet. If it is enacted, it would be one of the clearest federal limits on what regulated prediction platforms can offer, and it would set a template for how lawmakers respond when event contracts overlap with national security. Whether the House takes it up, and whether the CFTC uses its new authority aggressively, will determine how far the restrictions go.
Explore more on this topic with Vexel Search.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Header image: AI-generated illustration by WordUp News.
A landscape painted in the last weeks of Vincent van Gogh’s life has set a new van Gogh record, selling for $190.4 million (about £145 million) at Sotheby’s in New York. The figure includes fees, and it comfortably beats the artist’s previous auction high of $117.2 million, paid in 2022 for “Verger avec cyprès” at Christie’s.
The painting, “Châtaigniers en fleurs” (Chestnut Trees in Blossom), had been estimated at $180 million. It went under the hammer on Wednesday as the centrepiece of a dozen Impressionist and post-Impressionist works from the collection of the late Argentine collector Nelly Arrieta de Blaquier and her husband, sugar magnate Carlos Pedro Blaquier.
A sale that nearly didn’t happen
The price was only part of the story. The sale was in doubt until the day before the auction, when Sotheby’s announced an agreement between the Blaquier-Arrieta family, which has owned the painting since 1975, and the descendants of Hedwig and Samuel Fischer. The Fischers, a Jewish family and the German publisher’s heirs, sold the work in 1936. Their descendants say that sale took place under duress, as Nazi persecution forced the family to flee Berlin.
A lawyer for the Fischer heirs had pushed for the auction to be postponed until Sotheby’s could show the painting had not been sold under pressure. Instead, the two families reached what the auction house called a “mutually satisfactory resolution”, acknowledging the painting’s “complex Nazi-era history and the suffering endured by the Fischer family during the Holocaust.” The terms were not disclosed, and the sources do not say whether the heirs will receive any share of the proceeds.
In their own statement, the Fischer heirs thanked Sotheby’s and the Blaquier-Arrieta family for a “trusting and fair negotiation”. They said it made it possible to acknowledge the family’s suffering and to honour Gisela Berman Fischer, Samuel Fischer’s granddaughter, who spent years campaigning for the return of family artworks. Her efforts included a successful lawsuit over a Pissarro looted from the family’s Vienna home in 1938.
Why this van Gogh was so prized
Van Gogh painted the work after leaving the psychiatric asylum at Saint-Rémy in May 1890. He moved to a village north-west of Paris and, according to Sotheby’s, was swept up in a surge of optimism and energy that made this “the most urgent and expressive period of his career”. He took his own life two months later, so the canvas dates from the final stretch of his short career.
Rarity also played a part. This was the painting’s first time at auction, which gave buyers a chance at a late work that had been out of the market for decades.
How it ranks, and what else sold
Despite the van Gogh record, the painting is not the most expensive work Sotheby’s has ever sold. Standard reporting says it ranks second, behind Gustav Klimt’s “Portrait of Elisabeth Lederer”, which fetched $236.4 million at the auction house a year ago.
The rest of the Blaquier collection performed strongly too. Paul Cézanne’s portrait “Arlequin” sold for $111 million, and the 12 works together brought in $412 million. Claude Monet was among the other artists represented.
The outcome shows how provenance can shape the high-end art market. A dispute that might have pulled a headline lot from the sale was settled privately within hours of the auction, and the result was both a record price and a public acknowledgement of the Fischer family’s history.
Explore more on this topic with Vexel Search.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
Warner Bros. Television Studios Will Combine Two Skydance Units, Home to 100+ Series, by Early 2027
Skydance will fold Warner Bros. Television Group and Paramount Television Studios into a single company called Warner Bros. Television Studios, a consolidation expected to wrap up in early 2027. The decision was announced Wednesday in a staff memo from George Cheeks, co-chair and chief content officer of Skydance TV. It comes about a month after Skydance-owned Paramount closed its $81 billion takeover of Warner Bros. Discovery.
The new studio will be run jointly by Channing Dungey, currently head of Warner Bros. Television, and Matt Thunell, who leads Paramount Television Studios. Both carry the title of president and both report to Cheeks. Until the official launch, the two units will keep operating as they do now.
What Warner Bros. Television Studios Will Hold
The combined slate is large. Reports differ on the count: some put it at more than 100 productions, others at more than 120 series. It brings together WBTV hits such as “The Pitt,” “Ted Lasso,” “Shrinking” and “Abbott Elementary,” plus the coming HBO “Harry Potter” series, with Paramount Television Studios projects such as “Reacher” and Taylor Sheridan’s “Landman,” “Tulsa King” and “Dutton Ranch.” BET Studios and Warner Bros. International Television Production also fall under the new structure.
CBS Studios, the home of the “NCIS” and “Fire Country” franchises, will stay independent under David Stapf. CBS Studios International, Skydance Sports Entertainment and the nonfiction unit See It Now Studios will sit beneath it. Taken together, the two studio groups produce roughly 150 series, including international co-productions, according to The Hollywood Reporter.
A Merger Many Saw Coming
Industry observers say the logic is clear. Trade coverage notes that Warner Bros. Television and Paramount Television Studios overlapped heavily. Each was tasked with developing material from its sister film studio, each supplied its own streamer (HBO Max and Paramount+), and both sell shows to outside platforms. With the two film studios under joint leadership and the streaming services expected to merge, a single TV studio looked like the next step. CBS Studios, by contrast, has a more clearly defined role as the main supplier to the CBS network.
Paramount Television Studios has a short and turbulent history. Paramount shut it down a year before its 2025 merger with Skydance, then the name returned when Skydance TV and Showtime/MTV Entertainment were combined under Thunell. Now it disappears again as a standalone brand.
The equal co-leadership has drawn some attention. Deadline observed that Dungey and Thunell are at different stages of their careers, with Dungey the more seasoned and widely respected executive. The two previously worked together at Netflix, and each praised the other in statements. Dungey also continues to chair Skydance Global Cable Media, which combines the cable portfolios of Warner Bros. Discovery and Paramount.
Job Cuts and Fewer Buyers
The announcement does not mention layoffs, but Cheeks acknowledged staff concerns. “We know there will be questions about what this means for individual teams,” he wrote, adding that HR would share more as plans are finalized. Both Deadline and The Hollywood Reporter say cuts are likely when divisions merge.
The change also affects the wider creative community. With two studios becoming one, writers and producers will have one fewer place to pitch and sell series. Cheeks framed the move as creating “a formidable creative engine” with global scale. How that plays out for staff and outside creators will become clearer as the early-2027 integration approaches.
The Hollywood Reporter also noted that the antitrust settlement that cleared the Paramount-Warner Bros. Discovery deal did not explicitly address TV studio operations. Its television provisions focused on carriage agreements and the editorial independence of CBS News and CNN.
- Skydance to combine Warner Bros. TV Group and Paramount Television Studios (The Independent)
- Warner Bros. TV & Paramount TV Studios To Merge With Channing Dungey & Matt Thunell As Presidents (Deadline)
- Skydance to Fold Paramount TV Studios Into Warner Bros. TV Under Channing Dungey and Matt Thunell (Variety)
- Warner Bros. TV, Paramount TV Studios to Combine as a Single Mega-Studio (The Hollywood Reporter)
Explore more on this topic with Vexel Search.
File photo: Paramount Skydance One Astor Plaza.jpg by Nielsoncaetanosalmeron, CC BY 4.0, via Wikimedia Commons.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
Royal Mail delivery targets missed again as first-class on-time rate drops to 82.5%
Royal Mail delivery targets have slipped further out of reach, with the company reporting that service got worse in the second quarter of the year even as it pushes ahead with the biggest shake-up of letter delivery in decades.
Between the first and second quarters, first-class performance fell from 85% to 82.5% of letters arriving the next day. Second-class mail delivered within three working days dropped from 91.4% to 87.2%. Ofcom’s targets, which were lowered in April as part of reforms to the universal service, require 90% and 95% respectively.
Royal Mail says progress “will not be linear”
The company, whose parent International Distribution Services (IDS) was bought last year by Czech billionaire Daniel Kretinsky, said it remains “broadly on track” with its reforms. These include delivering second-class post every other day and dropping Saturday second-class deliveries. Its message to customers was essentially to be patient. Given “the scale and pace of the universal service change”, it said, it does not expect progress on quality of service to be linear. Delivery offices, it argued, need time to adapt to the new processes.
The timing is awkward. Last month Royal Mail said it would pause the full rollout of the second-class overhaul until after Christmas so staff could concentrate on the festive peak. It has also announced that up to 2,500 head office and support jobs will go by the end of 2027 to cut costs. Meanwhile chief executive Alistair Cochrane is retiring at the end of the year, with chief financial officer Paul Ablin, who holds that role at both IDS and Royal Mail, set to take over.
Citizens Advice calls for tougher action from Ofcom
Consumer campaigners are not persuaded. Citizens Advice says Royal Mail is on track to miss its first-class target for the tenth year in a row and its second-class target for the seventh. Tom MacInnes, the charity’s director of policy, said posting a letter “shouldn’t be like rolling a dice” and described the current service as “pot luck”. He argued that Ofcom’s efforts so far have “made no impact on service” and urged the regulator to escalate its action. In particular, he wants it to stop Royal Mail raising stamp prices while it keeps missing its annual targets.
Ofcom points to the action it has already taken. It has fined Royal Mail more than £37 million for failing to meet its annual targets across three years, and says it has secured commitments from the company to restore performance by April. Its reading of the latest quarter is mixed: first-class mail is on track for that deadline, but Royal Mail “must go further and faster” on second class if it is to turn things around by spring.
Parcels carry the business as letters shrink
The half-year results published alongside the figures show why the letters business is under such pressure. In the six months to 30 September, Royal Mail group revenues rose 3.9% to £4.1 billion. An 8% jump in parcel revenues more than offset a 0.8% fall in letters. Letter volumes dropped 8% over the period while parcel volumes rose 8%. Across IDS as a whole, revenues climbed 6.3%, helped by a 10.2% rise at its GLS parcel network in Europe.
IDS also warned that Royal Mail’s second-half financial performance will be hit by the delay to price increases for access business mail, such as marketing letters, household bills and medical appointment notices. Those rises had been due to take effect in October.
What to watch next
The test for management is whether Royal Mail delivery targets move back toward Ofcom’s thresholds before the April deadline, particularly after the second-class changes resume following Christmas. The company is asking for time, but the regulator has set a date and campaigners are pressing for penalties that go beyond fines. A new chief executive taking charge at the turn of the year will inherit both pressures.
- Royal Mail insists turnaround will take time as it misses delivery targets again (standard.co.uk)
- Royal Mail misses delivery targets again as it insists turnaround will take time (business-live.co.uk)
- Royal Mail misses delivery targets again and insists turnaround will take time (The Independent)
- Better post now for Christmas! Royal Mail misses delivery targets for the TENTH year in a row as new bosses insist turnaround will take time (dailymail.com)
Explore more on this topic with Vexel Search.
File photo: Royal Mail Solar-powered Parcel Postbox.jpg by Anders Baggibyr, CC0, via Wikimedia Commons.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
Viagogo hidden fees probe: CMA’s provisional finding puts up to 10% of global turnover in play
Header image: AI-generated illustration by WordUp News.
Viagogo hidden fees are now the subject of a formal provisional finding from the UK’s competition watchdog, which says the ticket resale platform may have broken consumer law by not showing buyers the full price at the start. The Competition and Markets Authority (CMA) issued the finding on Thursday. The regulator is clear that it is not a final verdict.
The CMA’s concern is a practice it calls “drip pricing”, where a headline price is displayed first and extra charges are added as the customer moves through checkout. According to the regulator, mandatory costs such as taxes and booking fees were added at later stages rather than being included in the total price from the outset. It examined how UK fans buying tickets for events including concerts and sport experienced three websites operated under the Viagogo brand.
What the CMA says went wrong
The watchdog’s argument is about comparison. If the first number you see is not the number you pay, it says, you cannot fairly weigh one listing against another. In its words, drip pricing can leave fans “caught out by extra charges” and buying tickets “they might not otherwise have selected, had they been able to compare prices accurately from the start.”
The regulator also stressed that this is an initial conclusion and that it should “not be assumed that Viagogo has broken the law.”
Viagogo’s response and what happens next
Viagogo said the investigation is continuing and that “no final findings have been made”. It added that it has “engaged constructively” with the CMA and will keep cooperating fully.
Procedurally, the CMA has issued a provisional infringement notice. Viagogo now has the chance to consider the findings and respond. Only if the CMA is ultimately satisfied that consumer law was broken can it issue a final infringement notice. Since the CMA gained direct enforcement powers, it can reach that decision itself rather than taking a company to court.
In general the CMA can impose penalties of up to 10% of global turnover for breaches of consumer law. It says it weighs factors including the severity of the conduct before setting a figure, so the maximum is a ceiling rather than a forecast.
A guide from the StubHub case
The closest precedent is StubHub UK. In June, the CMA ordered the rival reseller to refund more than 50,000 customers and pay a £900,000 fine for not showing the total price upfront. StubHub UK received a 40% reduction in its penalty because it admitted breaking the law and agreed to settle early. That shows how much the route a company takes can matter to the outcome. Viagogo has so far made no such admission and says no final findings exist.
Part of a wider crackdown
The Viagogo case sits within a broader push on drip pricing. Earlier this week the CMA announced investigations into three companies over the practice. According to the BBC, it said in August that Trainline, Virgin Atlantic and RED Driving School had been engaged in drip pricing. Taken together, the actions suggest the regulator is treating undisclosed add-on fees as a priority across sectors, not just in ticketing.
The secondary ticketing market is also under political scrutiny. Late last year the Government announced plans for new rules that would make it illegal to resell tickets for live events above their original cost. Pricing transparency and resale limits are separate issues, but both reflect pressure on a market where fans often complain about paying far more than they expected.
For now, the practical effect on buyers is limited, and the investigation is far from over. What the Viagogo hidden fees finding does show is where the regulator is heading: it expects the total price to be visible before a customer commits to checkout, and it has shown it will act when it believes that has not happened.
- Viagogo may have broken law on hidden fees, watchdog provisionally finds (BBC)
- Viagogo may have broken hidden fees rules, provisional CMA finding says (business-live.co.uk)
- Viagogo may have broken hidden fees rules, CMA provisionally finds (The Independent)
- Viagogo may have broken hidden fees rules, says provisional CMA finding (standard.co.uk)
Explore more on this topic with Vexel Search.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
Interest rates not ‘pre-set’, Bailey warns, as inflation hits 3.6% and a rise looms
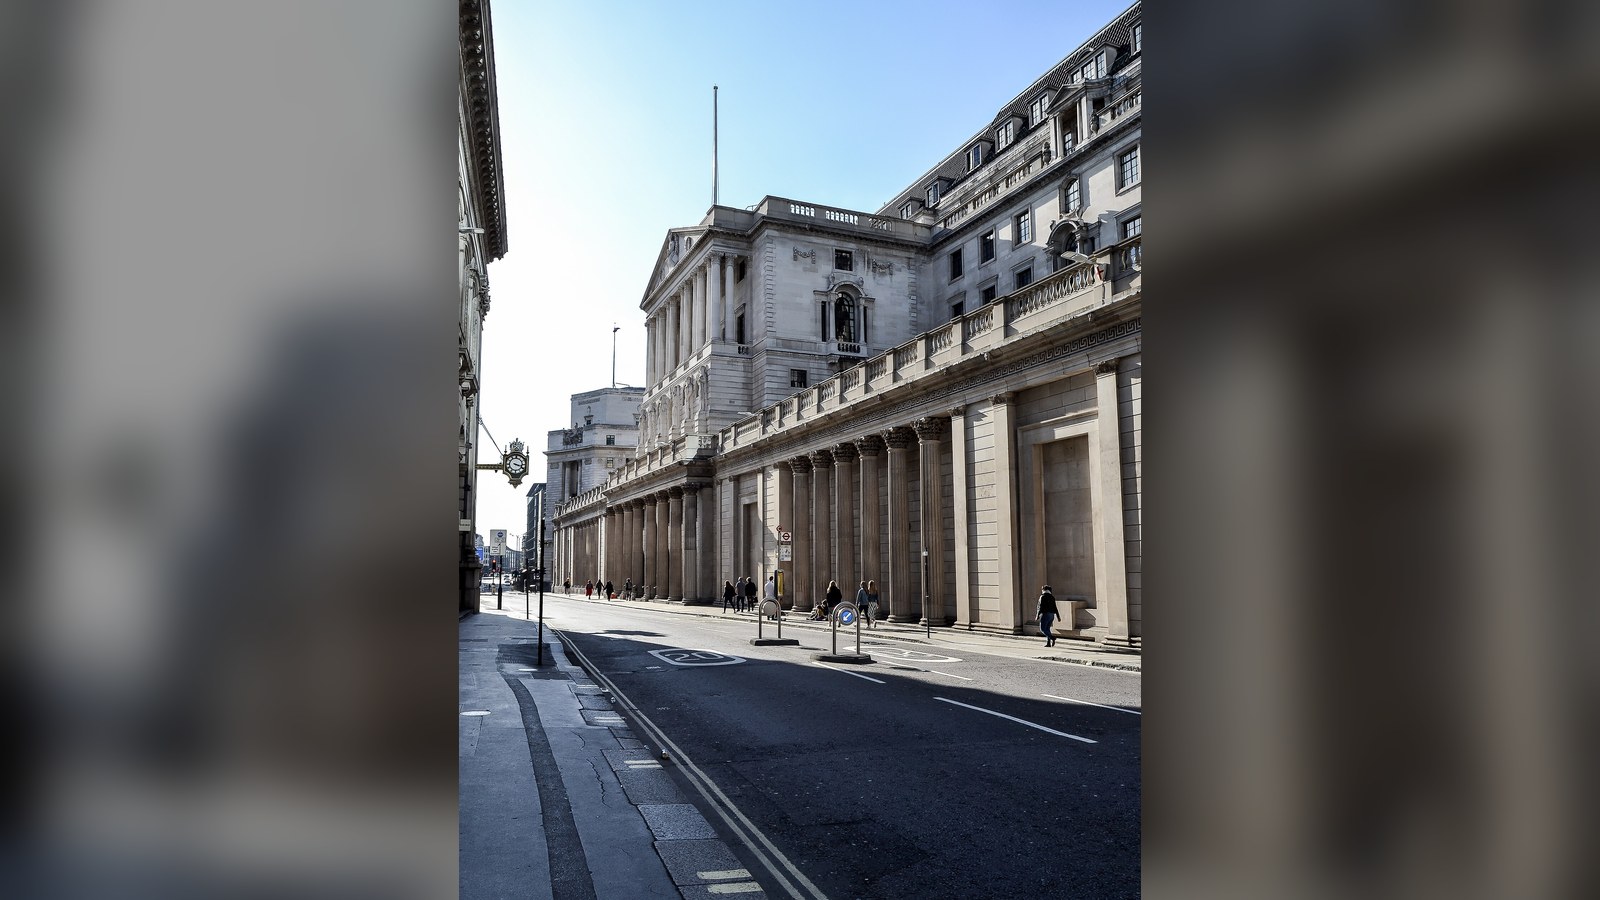
Bank of England Governor Andrew Bailey has refused to commit to a course for interest rates, telling an economic conference that policy is “not on a pre-set path” while energy prices remain volatile because of the conflict in the Middle East.
Speaking to the Institute of Economic Development on Wednesday, Bailey did not rule out higher borrowing costs. His remarks came as many economists expect a rise as soon as next month, or early next year. Official figures show Consumer Prices Index inflation edged up to 3.6% in October from 3.5% in September, its highest level in a year. Petrol and diesel prices and changes to tobacco duty drove the increase.
Energy prices are the key risk to interest rates
Bailey tied the outlook directly to the war in the Middle East. “The longer the conflict in the Middle East persists and elevates energy prices, the more likely persistent inflationary effects will take hold and the higher the level of interest rates will need to be,” he said.
He stressed that the situation is uncertain and changeable. The Bank’s rate-setting committee, he said, must “keep a very close eye” on whether high energy costs spread into other prices and the wider economy. He added that members would “look carefully at the evidence that will accumulate by the time we next meet.”
He also said the absence of a pre-set path “is always true” as a general matter. That qualification reads as a reminder that the Bank reacts to data rather than following a script, and it stops short of confirming or dismissing market expectations of a hike.
Growth better than forecast, with a school-report verdict
Bailey offered a more upbeat assessment of growth. Summer forecasts expected annual GDP growth of just over 1%, but projections now stand at around 1.6%. Business surveys also suggest activity has picked up somewhat.
He kept the praise measured. A 1.6% rate is below the average before Covid but above the rates of the past few years. “I guess the school report would be; better but needs to try harder,” he said.
Part of the lift comes from technology. Services linked to domestic AI activity have grown strongly, he said, and the Bank has built an “AI activity proxy” suggesting that novel AI activity accounts for just under a fifth of GDP growth so far this year. “Not to be sneezed at,” Bailey said.
An uneven economy
The governor cautioned that national averages hide big differences. He called the “uneven impact” of recent energy shocks “striking”. He traced regional divergence back to the 1980s, when rapid deindustrialisation coincided with the growth of finance and business services. By the 2010s, he said, the UK was among the more regionally uneven industrialised economies on measures such as productivity and GDP per head.
Bailey described the consequences of deindustrialisation as “notably persistent”, but said economic geography can change. He pointed to strengths that former industrial regions have developed in advanced manufacturing, aerospace, energy, defence and technology. The question, he said, is why some places make that transition more effectively than others.
For households and businesses, the message is mixed. The economy is growing faster than expected, but inflation is rising again. How far and how long energy prices stay high may decide whether interest rates move up from here.
- Bank chief says interest rates not ‘pre-set’ amid further potential rise (The Independent)
- Bank chief says interest rates not ‘pre-set’ amid further potential rise (standard.co.uk)
Explore more on this topic with Vexel Search.
File photo: Bank of England – London.jpg by MrsEllacott, CC BY-SA 4.0, via Wikimedia Commons.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.

Trump Threatens “Tremendous Tax” on AI Data Centres Overseas, but Offers No Details

El Chapo Isidro arrest: FBI top-10 fugitive held in Sinaloa raid after $5m bounty

GTA 6 Bowling Alley Safe Code Is 0300: Here’s Where the Game Hides It


-
 Tech & AI7 days ago
Nvidia CEO Search Reaches Arm: Board Reportedly Approached Rene Haas One Day After Jensen Huang Resigned
-
 Sports2 days ago
Premier League Legal Costs: 18 of 20 Clubs Back Cover for Board if Man City Sponsors Sue
-
 Tech & AI3 days ago
Jensen Huang Return Unlikely: Nvidia’s Board Isn’t Considering It as Stock Sits 10% Down
-
 Business & Hustles23 hours ago
Pensions dashboard to launch summer 2027, with 75 million records already connected
-
 Business & Hustles5 days ago
Instagram Amazon Affiliate Links: Creators Can Now Tag 30 Products Per Reel, and Meta Takes No Cut
-
 Tech & AI5 days ago
Vulcan rocket failure destroys 40 Amazon Leo satellites and ends ULA’s 20-year clean record
-
 Gaming7 days ago
Pearl Abyss AI Push Spreads “Throughout Our Entire Development Pipeline” as DokeV Slips to 2028
-
 Business & Hustles7 days ago
Stelco Worker Recall Returns 175 Hamilton Steelworkers on December 1 With Back Pay
-
 Crime7 days ago
Abu Dhabi Hotel Brawl: 10 Convicted, Eight Jailed for Six Months After MMA Stars’ Fight
-
 Gaming7 days ago
GTA 6 Empathy Mechanics: Rockstar Says a Series First Arrives November 19
-
 Fashion6 days ago
Hailey Bieber Face Masks Decoded: 50+ Rhode Test Rounds, a Seoul Pharmacy Find and One Big Caveat
-
 Entertainment7 days ago
Pluribus Series Regular: Samba Schutte Jumps From Two Episodes to a Full Season 2 Role
-
 Crime7 days ago
Nine sexual assault charges after seven women report attacks in 30 minutes at Huddersfield University
-
 Entertainment7 days ago
Gunn Shoots Down Man of Tomorrow Rumors: “No One From Skydance Has Seen” the Film
-
 Sports7 days ago
Anthony Santander apology leaves discipline question open for Blue Jays after anti-Muslim posts
-
 Gaming7 days ago
Rainbow Six Vegas 3 Reportedly in Development, 18 Years After Vegas 2
-
 Tech & AI6 days ago
Megaspeed Statement Says Alice Huang Left Aug. 30, 2025, Months After Singapore Police Questioned Her
-
 Sports6 days ago
Hendon match abandoned seven minutes into first game since Ezekiel Williams’ death
-
 Crime5 days ago
Depardieu drops appeal: 18-month suspended sentence stands after first public apology
-
 Tech & AI7 days ago
Meta Fine of €805m: Italy Gives Facebook 60 Days to Switch Off Photo Feature
You must be logged in to post a comment Login