
Business
BlackRock Large Cap Focus Growth Fund Q2 2026 Commentary



Goldman raises Gilt yield forecast as energy prices curb rate-cut hopes
Business
ETMarkets AIF Talk | Aerospace, electronics, CDMO, auto ancillaries: Where Rajesh Kothari sees India’s next growth opportunities
Rajesh Kothari, Founder and Managing Director at AlfAccurate Advisors, believes the investment opportunity in India is expanding at the sector and company level. His focus remains on businesses with sustainable growth, strong fundamentals and valuations that make investment sense, rather than simply chasing the next popular theme.
In an interaction with ETMarkets, Kothari explains where he sees the most promising growth opportunities over the next three to five years, how he evaluates businesses across sectors, and why investors need to balance growth potential with valuation, business quality and margin of safety while looking for the next wealth-creation opportunities. Edited Excerpts –
Q) India is no longer a cheap market. Good businesses are trading at premium valuations. Is the biggest challenge today finding quality companies—or finding quality companies at prices that still make investment sense?
A) In our view, the basket of investment opportunities in India is expanding. Several sectors offer strong growth potential over the next three to five years, including aerospace, electronics, CDMO, auto ancillaries, niche capital goods and platform companies.

While valuations have certainly become richer in certain pockets, we continue to find attractive opportunities across sectors where businesses offer strong growth prospects at reasonable valuations.
The key is to look beyond broad market valuations and identify opportunities at the sector and company level. Our focus remains on businesses with sustainable growth, strong fundamentals and valuations that make investment sense.Q) Your investment philosophy talks about “Protect Capital, Create Wealth.” In a market obsessed with returns, has capital protection become an underrated part of portfolio management?
A) Human behaviour plays a critical role in investing. When markets are driven by greed, investors need to be cautious; when fear dominates, that is often when the best opportunities emerge.
At AlfAccurate, risk management is central to our portfolio management. We believe capital protection is not about avoiding risk, but about understanding it, managing it and ensuring that we are adequately compensated for taking it.
Our philosophy of “Protect Capital, Create Wealth” is about having the discipline to be cautious when others are greedy and the conviction to be opportunistic when others are fearful.
Read more: $100 crude is an irritant, not a deal-breaker for India: Harsh Gupta Madhusudan
Q) Please take us through the recent performance of your funds.
A) All our funds have outperformed their respective benchmarks across 1, 2, 3 and 5-year periods, reflecting the consistency of our investment approach.
A particular highlight has been our mid- and small-cap PMS, AAA Budding Beasts, which has delivered over 22% CAGR returns over both 3 and 5 years.
What makes this performance particularly encouraging is that the strategy has held up well even during the challenging market conditions of the last one to two years.
For us, the real achievement is not just generating strong returns, but delivering them consistently across market cycles.
Q) Your India Equity Fund has an estimated FY26 EPS growth of 27.9% versus 8% for the BSE 500, but it also trades at a much higher P/E multiple. How do you justify paying for growth without falling into the valuation trap?
A) I strongly believe that P/E should not be looked at in isolation. The right lens is PEG, alongside the return on equity (ROE) of the portfolio.
A company with a higher ROE deserves to command a higher P/E than a company with lower capital efficiency. If it also delivers superior earnings growth, a valuation premium can be justified.
Our India Equity Fund is a good example. Despite its higher P/E, the portfolio is cheaper on a PEG basis than the BSE 500, while delivering an ROE of over 20%, compared with less than 15% for the benchmark.
The point is simple: a higher P/E does not necessarily mean a more expensive portfolio if the growth and quality of earnings justify it.
Q) Your portfolio is multicap, but the allocation appears tilted towards larger companies. Is this a conscious defensive positioning, or are opportunities in the mid- and small-cap universe becoming harder to find?
A) Our multicap approach is driven by bottom-up stock selection, not by predetermined market-cap allocations.
We continue to find attractive opportunities across the market-cap spectrum. However, we believe portfolio allocation should reflect where we see the best risk-reward, rather than follow a fixed allocation to mid- or small-cap stocks.
Our larger-company exposure is not a defensive call; it reflects our conviction in the opportunities we currently find most attractive.
Read more: Nifty oversold, IT poised for pullback: Anand James on what traders should do next
Q) The GEMS Fund has delivered strong returns since inception, but it is also buying companies at a significant valuation premium to the broader market. Is this growth investing—or are investors taking valuation risk they may not fully appreciate?
A) GEMS is built around identifying exceptional businesses with the potential to deliver sustainable, above-market earnings growth.
Such businesses often command a valuation premium. However, the key is to assess not just the quality of the business, but also where it stands in its business cycle and how much growth is already priced in.
Getting the business right is important, but getting the business cycle right is equally critical. We believe this is essential to managing valuation risk while capturing the long-term growth opportunity.
Q) The factsheet talks about proprietary forensic and longevity frameworks focusing on governance, earnings quality and balance-sheet strength. Can you explain what typically raises a red flag before the market discovers the problem?
A) Our forensic framework looks beyond reported profits to understand the underlying quality of earnings and financial health of a business.
Red flags include persistent gaps between profits and operating cash flows, rising receivables or inventory without corresponding sales growth, unexplained related-party transactions and deteriorating balance-sheet strength.
Our longevity framework goes a step further, evaluating whether the business has the competitive advantages and financial strength to sustain growth over the long term.
The key is to identify the cracks in a business before they become visible in its reported performance or market price.
Q) AlfAccurate follows what it calls the 3M framework—Market Size, Market Share and Margin of Safety. Why these three? And which of these is most often ignored by investors chasing the next multibagger?
A) Our 3M framework brings together three essential elements of wealth creation.
Market Size defines the growth opportunity. Market Share determines how much of that opportunity a company can capture. Margin of Safety ensures that we do not overpay for that opportunity.
Investors chasing multibaggers often focus on the first two, but overlook the third.
A large market and a winning business can create a great story, but only the right entry valuation can make it a great investment.
Q) What is more dangerous today: missing a multibagger or owning an overvalued stock?
A) Missing a multibagger may cost you an opportunity, but owning an excessively overvalued stock can cost you capital.
We do not believe investors need to own every multibagger to create wealth. What matters is building a portfolio of businesses with strong fundamentals, sustainable growth and sensible valuations.
In investing, the opportunity you miss may be forgotten, but the capital you permanently lose is much harder to recover.
(Disclaimer: Recommendations, suggestions, views, and opinions given by experts are their own. These do not represent the views of the Economic Times)
Under Regulation 45(1) of the Sebi Stock Exchanges and Clearing Corporations Regulations, 2018, a recognised stock exchange can list its securities only on another recognised stock exchange. So, NSE cannot trade on NSE after listing.
Ishan Tanna, Senior Associate at Ashika Capital, said the rule is clear. “NSE cannot list its shares on its own platform because Indian securities regulations explicitly prohibit self-listing,” he said.
He said the restriction is meant to address governance and conflict-of-interest concerns. “Listing one’s shares on your own exchange is not an ethical practice. There could be fears of manipulation and hence NSE decided not to move with the application to trade on its own platform,” he added.
Also Read: Inside NSE IPO journey: Why India’s largest exchange took 10 long years to reach Dalal Street
Why is this a big deal
Listing an exchange is not like any other company. NSE runs the trading system, oversees market activity and acts as the first layer of supervision for listed securities. If its own shares traded on the same platform, the exchange would also be supervising trading in its own stock.
That can raise questions for which there are no easy answers. Like, who monitors trading in the exchange’s shares? Who handles unusual price moves? Who examines disclosure issues or surveillance alerts? Even if the systems are fair, the structure can create a perception problem.This concern was also discussed in the Jalan Committee’s work on market infrastructure institutions. The committee had noted that privately held stock exchanges may seek listing to give an exit route to shareholders, but listing a stock exchange raises several issues, including who would monitor listing compliances when the listed company is itself a market institution.
The committee also examined whether a market infrastructure institution should be allowed to list in view of the inherent conflict of interest. While it did not settle every issue around cross-listing and self-listing, its observations remain relevant because they show why exchanges are treated differently from normal companies.
Is it a big deal?
For NSE, the self-listing point is not a setback. The exchange’s shares will trade on another recognised exchange, keeping some distance between NSE as a listed company and NSE as a market operator.
The IPO itself is expected to be entirely an offer for sale. NSE will not receive fresh capital from the issue. Existing shareholders will sell part of their stake to public investors.
NSE had earlier proposed an OFS of up to 14.89 crore shares. The updated filing has reduced the offer size to about 12.64 crore shares. The IPO size is now expected to be around Rs 22,500-23,500 crore, lower than the earlier expectation of about Rs 30,000 crore.
(Disclaimer: Recommendations, suggestions, views and opinions given by the experts are their own. These do not represent the views of Economic Times)
The government has ruled out scrapping or watering down the regulation of tied pubs, but said publicans could be given more freedom to challenge the arrangements that dictate what they pay for beer. The decision was set out in a long-awaited review of the pubs code and its regulator, published today.
The review concluded that the regime is working but can be strengthened to “provide more opportunities for tied tenants and pub-owning businesses”.
Ministers said they were broadly satisfied that the regulator and the rules were meeting their objectives. That dashed hopes among regulated pub companies that the Pubs Code Adjudicator and the code, which many in the industry believe is outdated, could be significantly curtailed or even scrapped. Campaigners for tenants had feared a voluntary code would be recommended.
The report said that, given changes to the industry since the code was introduced a decade ago, “targeted amendments may be appropriate”. The government said it wanted to help tenants who sought greater freedom to run their pubs, including negotiating fairer lease agreements and a better price for beer.
It added that it would consider commissioning an independent review next year into whether the regulator was doing enough to “protect tied tenants’ rights and fair treatment under the code”.
What the code covers
The pubs code regulates the relationship between tied tenants and the six largest pub-owning businesses that rent pubs to them and sell them beer.
It was intended to address an imbalance of power under the centuries-old beer tie, under which tenants are contractually obliged to buy certain supplies from their pub company landlord, typically at considerably higher prices than on the open market, in return for lower rent.
The report encompasses a statutory three-year review as well as a full post-implementation review of the regulator, in which ministers considered whether it was “still required”.
It has been published during an investigation by the adjudicator into the alleged mistreatment of tenants by Stonegate, Britain’s biggest pubs landlord. The review concluded long before that investigation was opened in July, and the government has been considering its response for more than a year.
Industry sources believe the outcry over Stonegate’s alleged conduct strengthened the case for regulation. One senior figure said that if the pubs code and the adjudicator “need justification for their existence then they don’t need to look any further than Stonegate”.
Many tenants have spoken publicly about what they claim have been the disastrous financial and personal consequences of taking on a Stonegate pub. Stonegate has said it is committed to the code and to the fair treatment of tenants.
Greg Mulholland, a former MP who was behind the parliamentary campaign that led to the code and is a director of the tenants’ group Campaign for Pubs, said: “We are very relieved that ministers did not fall for the transparently cynical nonsense spun by the big pubcos that [the code] wasn’t needed any more.”
He said abuse of the tie and other models was “still rife” and “continues to be a very significant factor in pub closures”.
Low take-up of free-of-tie deals
A key consideration was what the adjudicator, Fiona Dickie, has called “limited and diminishing access” for tenants to a market rent only agreement, the option under the code to buy beer and supplies on the open market.
Fewer than 400 tenants applied for a free-of-tie agreement between April 2022 and March 2025, saying they felt deterred by the cost and complexity.
Given the low take-up, the government said it would work on revising the gateways, or circumstances, that allow tenants to request the model. It would also ask the industry to expand the opt-outs that allow the tie to be broken for certain products or services, amid concerns about publicans being locked in over long periods.
One industry insider said they would welcome tenants being given greater choice in what beer they bought, adding that it would also “broaden choice for customers”.
The British Beer and Pub Association, the industry group, said it was pleased to see plans to reduce “red-tape and unnecessary costs” highlighted in the review, but added: “We look forward to seeing more detail, as any changes must be proportionate and not inadvertently undermine investment.”
Jamie Young
Jamie Young is Senior Reporter at Business Matters, covering SME finance, employment law and Westminster policy since 2016. He has reported on every Budget and Autumn Statement since 2018, helped make sense of the ‘covid era’ and the bounce-back loan scheme from launch through the fraud investigations, and broke the magazine’s coverage of the 2024 late-payment reforms. He joined Business Matters straight from completing his BA in Administration from Exeter University and is NCTJ-qualified. Reach him at jyoung@cbmeg.co.uk
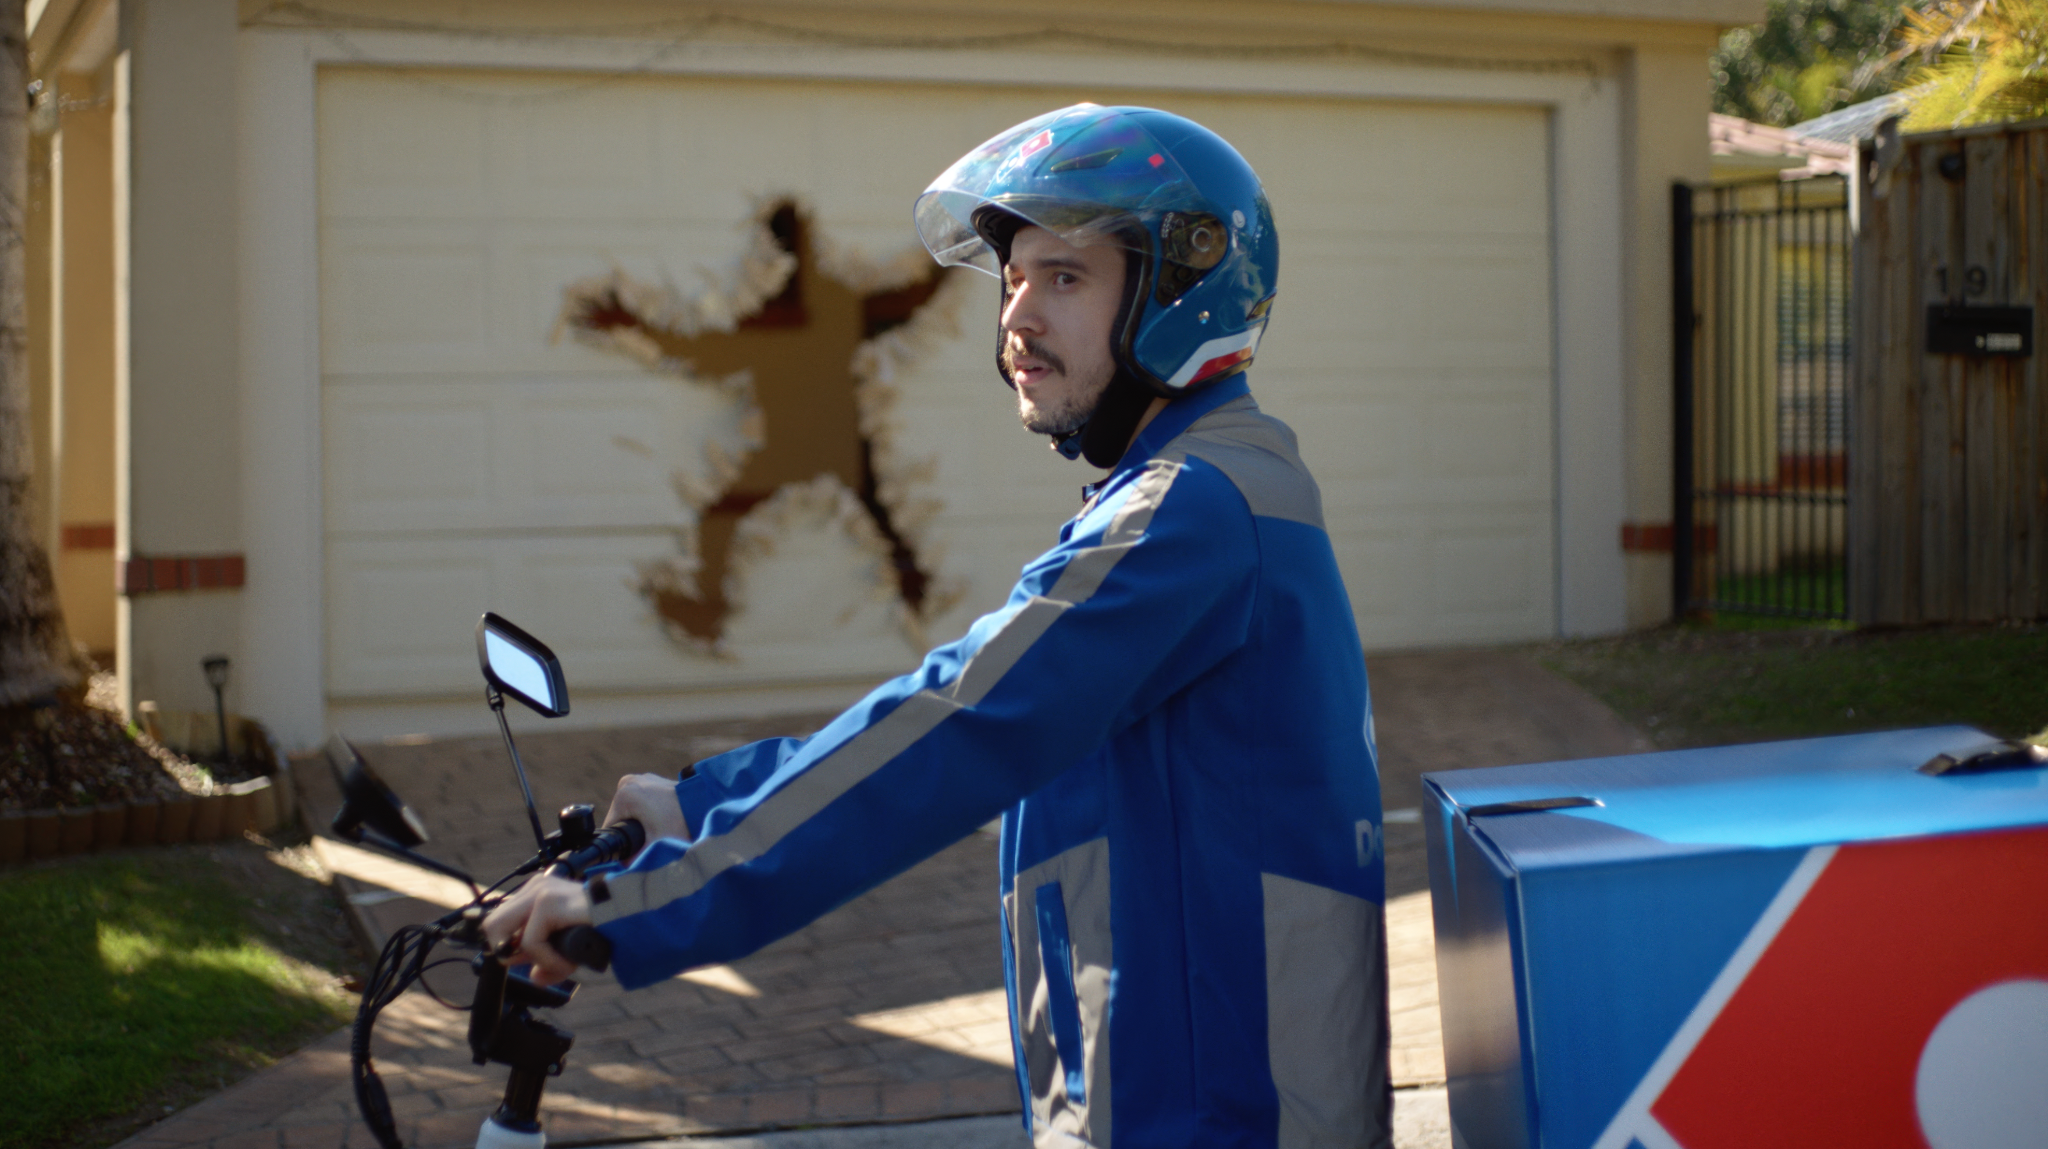
The pizza giant shifts to a crave-led strategy with the new ‘Drop Everything* It’s Domino’s’™ brand platform, a supersized New Yorker range, major new Coca-Cola partnership, a sweet collaboration still to come and a fresh attitude.

DROP EVERYTHING AND WATCH: See the new ‘Drop Everything* It’s Domino’s™’ campaign TVC HERE
SYDNEY, AUSTRALIA – Domino’s Australia is entering a bold new era, today unveiling a major evolution of the brand that puts craveability front and centre and gives Australians even more reason to drop everything for Domino’s.
At the heart of the transformation is a renewed appetite for craveability and a move from function to feeling, putting great-tasting food, personality and the simple joy of pizza firmly back at the centre of the Domino’s experience.
It’s a shift Australia and New Zealand will see and feel across the entire brand – from product and partnerships to the customer experience, advertising and how Domino’s shows up in culture – while continuing to deliver the convenience, connection and value customers know it for.
Leading the charge is Domino’s new brand platform,‘Drop Everything* It’s Domino’s’™. Developed in partnership with Bureau of Everything, the platform is built around a simple truth: when Domino’s arrives, everything else suddenly becomes a little less important.
The laptop closes. The group chat goes quiet. The movie gets paused. Nobody bothers setting the table. The box opens and everyone gets stuck in. Because when Domino’s is on the cards, you’ll drop everything despite the consequences.*
Domino’s Australia & New Zealand Chief Marketing Officer Dewald Du Plooy said the new platform signals a renewed ambition for the brand and a return to what pizza does best – bringing people together around food they genuinely crave.
“There’s a moment when Domino’s arrives where whatever was happening before suddenly doesn’t seem quite as important. Someone opens the box, everyone moves in and the rest can wait,” Du Plooy said.
“‘Drop Everything* It’s Domino’s™‘ is about owning that feeling. We want to remind Australian and New Zealand that Domino’s is the ultimate people pleaser – hot, fresh, fast and able to crush a whole lot of different cravings in one order.
“It also gives us permission to have more fun. You’ll see Domino’s showing up with more personality, more culturally relevant moments and food that looks so good you want to reach through the screen and grab a slice. And we’re kicking things off in a pretty big way.“
Domino’s Head of Brand and Campaigns Teneille Papp said the new platform has been designed to build a stronger and more distinctive Domino’s brand over the long term.
“In a market this crowded, cutting through takes a platform, not a campaign, built to flex across everything we do while staying unmistakably Domino’s,” Papp said. “Bolder, fresher, food creative so visceral it makes you want to lick the screen and a voice truly in on the joke – built to turn a transaction into a craving.“
And Domino’s isn’t waiting around to bring that new ambition to life. First cab off the rank – quite literally – is the new Domino’s New Yorker range, launching nationally today and bringing a serious slice of New York to Australia.
At an authentic 16 inches, the New Yorker is the biggest pizza on the Domino’s menu, with hand-stretched dough, premium toppings, giant foldable slices and five New York-inspired pizzas:
- ● The Big Cheese
- ● Pepperoni Boss
- ● Hot Honey Pepperoni Boss
- ● Little Italy
- ● Bacon Kingpin
The transformation doesn’t stop at the pizza box.
Domino’s has also welcomed Coca-Cola as its new drinks partner, bringing two of the world’s most recognisable brands together in a major new partnership across the Domino’s experience in Australia and New Zealand. The partnership marks a significant evolution of Domino’s beverage offering and another step in the brand’s broader ambition to make the entire Domino’s occasion more craveable – from the first slice to the last sip.
Because a giant New Yorker and an ice-cold Coca-Cola? Some things just make sense.
And those with a sweet tooth should stay tuned, with Domino’s set to drop more huge news this Wednesday that is sure to get dessert lovers talking and give them another reason to drop everything*. But before that, Domino’s is taking its New York state of mind to the streets.
On Thursday 17 September, an iconic yellow New York-style cab will hit Sydney, New South Wales, transformed into a Domino’s New Yorker delivery vehicle and serving up the new range. The cab will make its way across some of Sydney’s most recognisable locations, making special deliveries along the way and giving Sydneysiders the chance to get in on the action, with free New Yorker pizza and Coca-Cola up for grabs at select stops. Keep an eye on Domino’s Australia’s social channels to find out where the cab will be pulling up and how to score a slice.
And the New York takeover won’t stop there. On Thursday 24 September, Domino’s will bring the energy of NYC with a free New York-inspired Block Party, complete with DJs, entertainment, giveaways and, of course, plenty of New Yorker pizza. The event will be open to the public, with more details on the location and how to get involved to be announced via Domino’s Australia’s social channels.
So, if you spot a yellow cab cruising through Sydney, look twice. You haven’t landed in Manhattan. The New Yorker has landed here. Follow Domino’s Australia on Instagram on on Facebook for more
Invesco India Midcap Fund tops the table with a 426% return, followed by Edelweiss Midcap Fund at 409% and Nippon India Growth Midcap Fund at 403%. Nine of the 20 schemes have returned more than 350%, while 11 have delivered more than 300%.
At the other end, Aditya Birla Sun Life Midcap Fund, the weakest performer in the 10-year cohort, is still up 238%. SBI Midcap Fund returned 247%, UTI Mid Cap Fund 250% and DSP Midcap Fund 255%.
 ETMarkets.com
A 238% absolute return over 10 years works out to roughly 13% annualised, while 426% translates into about 18%. The category average of 324% is equivalent to around 15.5% a year. The gap may not look enormous on an annual basis, but over a decade it creates a substantial difference in terminal wealth: Rs 1 lakh would have grown to roughly Rs 3.38 lakh in the weakest scheme and Rs 5.26 lakh in the strongest.
That breadth raises a bigger question: what made a category in which even the laggards more than tripled investor money so powerful?
Hemant Sood, Founder and Managing Director of Findoc Group, attributes the midcap category’s performance to three broad forces: earnings growth, valuation rerating and sustained investor flows.
Midcaps occupy an unusually fertile part of India’s corporate lifecycle. Many companies in the segment have already reached a scale that makes their businesses more resilient than smaller firms, while retaining significantly more room to grow than established largecaps.Over the past decade, Sood said, the segment benefited from formalisation of the economy, the capex and manufacturing cycle, production-linked incentive-linked sectors and operating leverage as capacity utilisation improved. But earnings were only part of the equation. Rising valuations also amplified returns, meaning investors increasingly paid more for every rupee of profit generated by midcap companies.
Also Read | Invesco’s ₹16,000 crore midcap fund delivered 426% return in 10 years. Aditya Khemani reveals the strategy
Souvik Biswas, Head of Research at Bajaj Capital, sees the same structural advantage.
Midcap companies have already scaled to a reasonable size while continuing to grow, helping the segment generate strong earnings momentum. The periodic addition of fast-growing companies moving up from the smallcap universe also continuously refreshes the opportunity set.
That combination attracts investors following multiple styles, from growth and quality to momentum, value and contra strategies, helping sustain both liquidity and investor interest. Biswas said outsized returns remain plausible in the segment, primarily because of earnings growth and the liquidity and investor interest that follow it.
Manish Kothari, Co-founder and CEO of ZFunds, describes midcaps as effectively offering investors the “best of both worlds” — the operating robustness associated with large companies and the growth agility usually associated with smaller businesses.
The segment has also been expanding through both earnings growth and valuation rerating, while new-age companies entering the midcap universe are opening additional investment opportunities.
But that same success is creating the biggest question for the next decade: can midcaps repeat it?
The answer from experts is considerably more nuanced than the backward-looking return data suggests.
Sood cautions against simply extrapolating the past decade’s 15.5% annualised category return. With valuations already elevated, the rerating component that boosted historical returns may be difficult to repeat. As assets under management grow, large midcap funds could also find it progressively harder to enter and exit positions without affecting prices.
His base case is for future returns to move closer to underlying earnings growth, with wider differences emerging between the best and worst schemes. For financial planning, he considers an assumption of 10%-12% annual returns more prudent than simply projecting the historical rate forward.
Also Read | $4 billion CIO Nimesh Chandan spots 4 bullish signals for Indian stocks. What changed?
Biswas also flags valuation and volatility as the two central risks. Midcaps typically trade at richer valuations, which makes valuation risk a defining feature of the segment, while investors should also be prepared for greater volatility.
Kothari is constructive on the long-term opportunity but arrives at a similar caveat. A relatively limited universe of midcap stocks is being chased by institutions and other investors attracted by the earnings growth on offer. That demand can push valuations higher and ultimately constrain future returns.
The limited universe creates another paradox for fund managers.
Midcaps may be easier to research than smallcaps, but they can be considerably harder to differentiate in.
Sebi’s category framework requires midcap funds to maintain at least 65% exposure to midcap stocks. With the core midcap universe spanning a relatively narrow group of companies—and becoming smaller still after managers filter for governance, liquidity and valuation—multiple funds can end up competing for many of the same stocks.
That can lead to substantial portfolio overlap and make genuinely differentiated stock selection harder, particularly for funds managing large pools of capital.
Sood sums up the challenge as “easier to research, harder to differentiate”. Alpha increasingly has to come from position sizing, portfolio construction and how fund managers deploy the portion of the portfolio that is not subject to the mandatory midcap allocation.
Biswas, however, points out that the 65% requirement still affords midcap managers reasonable flexibility to invest in large caps and small caps, thereby managing the portfolio’s risk-reward profile. The real difficulty, he said, is that midcap companies are generally well known and can command higher valuations, forcing managers to continuously answer three questions: how much to pay, what growth that price is buying and how much downside risk they are accepting.
For investors, therefore, the past decade’s extraordinary scorecard carries two messages.
The first is that the midcap segment has demonstrated an unusually powerful ability to compound wealth: every one of the 20 schemes with a decade-long record has been a multibagger.
The second is that the forces responsible for those returns—earnings growth, rerating and rising flows—may not contribute equally over the next decade. With valuations elevated and an increasingly crowded investible universe, future wealth creation could depend more heavily on earnings delivery and fund manager execution than on another broad rerating of the entire category.
Midcaps may, therefore, remain a wealth creation engine, but investors should not expect the engine to run at precisely the same speed for another 10 years.
(Disclaimer: Recommendations, suggestions, views and opinions given by the experts are their own. These do not represent the views of The Economic Times)
Business
Amazon Stock Trades at Rare Discount as Andy Jassy Bets $220 Billion on AWS to Fuel Next Trillion-Dollar Leg
SEATTLE — Amazon.com Inc. has grown into one of the most valuable companies in the world under founder Jeff Bezos and his successor, Andy Jassy, and investors are now watching to see whether a sharply higher spending plan tied to artificial intelligence and cloud computing can push the company’s value even further.
Bezos founded Amazon in 1994 and led the company through its May 1997 initial public offering, building it from a market capitalization of under $500 million into a $1.8 trillion company by the time he stepped down as chief executive on July 5, 2021. Jassy, who succeeded him, has overseen a roughly 50% increase in Amazon’s market value since taking over, pushing the company’s worth to about $2.7 trillion.
Before becoming CEO, Jassy helped build and run Amazon Web Services, the cloud-computing division that has since become the company’s largest source of profit. AWS remains the leading cloud infrastructure provider globally, holding a 28% market share as of the second quarter of 2026, ahead of Microsoft’s Azure at 20% and Alphabet’s Google Cloud at 15%, with the remaining share split among a range of smaller competitors.
AWS’s growth has accelerated sharply over the past year as demand for generative artificial intelligence services has surged. In its second-quarter results reported July 30, Amazon said AWS revenue rose 37% year-over-year to $42.2 billion, up from $30.9 billion a year earlier, marking the unit’s fastest growth in 18 quarters and its fifth consecutive quarter of accelerating growth, according to Jassy. AWS operating income climbed 64% to $16.6 billion, with the division’s operating margin expanding to 39.4% from 32.9% a year earlier. AWS accounted for roughly 60% of Amazon’s total operating profit during the quarter.
“AWS is now a $169 billion annualized revenue run rate business, which, for perspective, would place it 24th on the Fortune 500 list if it was a stand-alone company,” Jassy told analysts on the earnings call. He also described the broader cloud business succinctly, saying AWS “is booming.” The unit’s backlog of customer agreements representing future revenue grew to $496 billion, giving the company visibility into demand well beyond the current quarter.
Across all of Amazon’s businesses, including its retail stores, advertising, Prime subscriptions, devices and cloud operations, net sales rose 20% year-over-year to $200.6 billion in the second quarter, while operating income climbed 43% to $27.5 billion. “We’re reporting $200.6 billion in revenue, up 20% year-over-year. Operating income was $27.5 billion, up 43% year-over-year. Q2 was another very strong quarter for Amazon,” Jassy said.
That growth has come alongside a significant increase in spending. Amazon raised its full-year 2026 capital expenditure guidance to approximately $220 billion, up from a prior estimate of about $200 billion, with the company attributing the increase primarily to higher memory costs tied to building out AI and data center infrastructure. “We now believe we will spend approximately $220 billion in cash CapEx in 2026. The higher cost of memory pushing this number up from our prior estimate of about $200 billion,” Jassy said on the call. Capital expenditures during the second quarter alone reached $54.2 billion, compared with $32.1 billion in the same period a year earlier.
Even at that elevated level of spending, Jassy told investors the company still won’t have enough capacity to satisfy the demand it’s seeing. “Even at that amount, we will still not have enough capacity to meet all the demand we have in 2026,” he said, adding, “I believe this dynamic will also be true in 2027, too.” AWS is targeting a doubling of its power capacity by the end of 2027 compared with 2025 levels, underscoring the scale of the infrastructure buildout underway.
The heavy investment cycle has pressured some near-term financial metrics. Amazon’s trailing 12-month free cash flow swung to a multibillion-dollar outflow as the company accelerated purchases of property and equipment, primarily to expand AI infrastructure. Despite that pressure, shares surged more than 10% in extended trading following the earnings release, as investors focused on AWS’s accelerating growth rather than the near-term cash flow impact.
Much of that spending is directed toward AWS’s data center footprint, networking equipment and computing hardware, including both Nvidia graphics processing units and Amazon’s own in-house Trainium and Graviton chips. Both of those homegrown chip lines have individually surpassed a $25 billion annual revenue run rate, according to the company, as Amazon looks to reduce its reliance on external chip suppliers while building out AI infrastructure at scale. Amazon’s Bedrock model marketplace, aimed primarily at enterprise customers, has also become a growing part of the company’s broader AI product strategy.
Despite the scale Amazon has already achieved, its stock currently trades at what analysts describe as an unusually attractive valuation relative to its own history, a rarity for a company of its size and track record. The gap has emerged even as capital expenditures have climbed sharply, with some investors expressing concern about the near-term payoff of such a steep increase in spending. Given AWS’s growth trajectory and dominant position in cloud infrastructure, however, the investment in data center capacity is widely viewed by market watchers as a calculated bet on sustained demand rather than a departure from the company’s historically disciplined approach to capital allocation.
With AWS still expanding at its fastest pace in more than four years and demand for artificial intelligence infrastructure showing no signs of slowing, Jassy’s strategy of funneling record sums into data centers and custom silicon is shaping up as the next major test of whether Amazon can replicate the kind of sustained profit growth that carried the company from a startup bookseller to a $2.7 trillion technology giant under his predecessor.
Business
HDFC Bank shares hit 52-week lows over consecutive sessions while analysts scream Buy. Has the stock hit its bottom?
The stock of India’s largest private lender dropped to a fresh 52-week low of Rs 681.90 apiece on Friday. This marks more than a 33% fall in less than 11 months after hitting a record high of Rs 1,020.50 apiece in October last year.
The sharp selloff in HDFC Bank shares began in March this year after its former part-time Chairman Atanu Chakraborty resigned, stating that some practices within the bank did not match his personal values and ethics. The governance cloud led to a massive selloff that recovered slightly after the bank made leadership changes.
HDFC Bank’s board has submitted two candidates to the Reserve Bank of India (RBI) for the role of CEO, formally beginning the succession process for Sashidhar Jagdishan, who is due to retire later this year, the country’s largest private lender said on Saturday.
Also read | HDFC Bank submits two candidates to RBI for next CEO
Bullish brokerage calls for HDFC Bank share price
Goldman Sachs last month initiated coverage on HDFC Bank with a ‘Buy’ call and a target price of Rs 861 apiece. Goldman Sachs noted the bank’s core-PPOP inflection driven by margins and operating leverage, along with attractive valuations.
The Wall Street giant initiated coverage with a ‘Buy’ rating due to compelling valuations, despite expecting further downside earnings revisions. Nomura and Motilal Oswal Financial Services also have ‘Buy’ calls on HDFC Bank shares.
HDFC Bank shares technical setup is ‘highly uninspiring’
HDFC Bank shares have been the weakest among all Nifty Bank constituents, declining 29% so far in 2026. Not only has the performance been disappointing this calendar year, but the stock has also delivered weak returns over the past three to five years, declining nearly 14% and 9%, respectively. “Despite the significant underperformance of this banking heavyweight, there are still no meaningful signs of a turnaround, with the technical setup remaining highly uninspiring and weak,” said Hitesh Rathi, Technical Analyst (Equity & Derivatives) at Angel One.
He noted that in the long term, the stock has slipped below its 20 and 50 EMAs and has remained below both averages for six consecutive months, marking the first such occurrence since its listing and underscoring the deterioration in its long-term technical structure. A similar bearish setup is emerging on the point & figure charts, where the stock has triggered a follow-through double bottom sell for the first time since 2011. The current setup is particularly concerning given the follow-through selling witnessed subsequently, which was notably absent during previous instances of a similar pattern, the analyst said while explaining the technical charts for HDFC Bank.
Also read | Four rules made HDFC Bank a compounder. All four have stopped. Can the new CEO rewrite them?
Are HDFC Bank shares set for a trend reversal?
The stock is now displaying oversold readings across several technical parameters, while the significant disparity in its performance also leaves room for a short-term bounce, according to Rathi. “Hence, a near-term recovery cannot be ruled out. However, the broader technical setup and trend remain firmly bearish, with no meaningful signs of a trend reversal visible at this stage,” he added.
Dnyanada Vaidya, Research Analyst on BFSI at Axis Direct, also noted that the valuations post the sharp correction are attractive and the downside risk appears limited. Clarity around MD & CEO appointment will remain a key monitorable. “From an operational standpoint, we believe the bank is likely to witness margin improvement, though it would be a multi-quarter journey, supported by multiple levers. Similarly, growth is also showing signs of improvement. We expect HDFC Bank to consistently deliver RoA of 1.8-1.9% over the medium term,” the analyst said while recommending a ‘Buy’ call on the stock.
Also read | HDFC CEO race: One insider, one outsider in contention for the top job
Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.

AirBaltic files for Chapter 11 bankruptcy in New York
Business
Jefferies says Sebi’s proposed CAS changes will remove uncertainty, but still remains negative on BSE. Here’s why
On Saturday, Sebi proposed two options for determining expiry-day settlement prices for index and stock derivatives. The consultation paper also proposed changes to the timing of the continuous trading session (CTS), CAS and derivatives trading, along with additional measures to improve the new session.
Jefferies on Monday highlighted that CAS, which was introduced by Sebi in August, initially resulted in higher losses for domestic prop traders due to volatility in index prices during the last hour on expiry day. Sebi’s latest consultation paper addressed concerns around CAS by changing settlement price of derivatives to volume weighted average (VWAP) or a blend between VWAP and CAS, discontinuing cancellations of limit orders placed beyond +/- 1% of reference price during CAS, reducing concerns around manipulation of settlement price, and unexecuted iceberg orders may be transitioned to CAS, increasing liquidity during the CAS window, the international brokerage said.
Also read | Sebi proposes new CAS framework, two options for expiry-day settlement
“Our discussions with domestic prop traders indicate the return to VWAP-based derivative settlement price along with inability to cancel limit orders placed beyond +/-1% threshold should reduce end of period volatility on expiry days,” Jefferies said, noting that the last date to submit responses to Sebi’s consultation paper is October 3, so the implementation will likely be from October or November this year.
While options premium turnover and orders were adversely impacted during August 2026, both have recovered in September so far as option traders had a better understanding of CAS, according to the analysts.
Why Jefferies remains negative on BSE share price?
Despite its positive view on the latest proposals on CAS, Jefferies remains negative on BSE. It maintained its ‘Underperform’ rating on the shares of Asia’s oldest stock exchange, with a target price of Rs 2,940 apiece, implying more than 13% downside potential from the stock’s previous closing price of Rs 3,384 apiece.The international brokerage’s negative stance on BSE shares is driven by the overall options industry barely growing over the past two years, while market-share gains appear to be nearing a ceiling, with expiry-day Sensex and Nifty ADTO now at similar levels.
Further, RBI’s tightening of bank guarantee norms could adversely impact premium turnover by up to 10% over the next year, it said, adding that BSE will also potentially undergo a management transition by June 2027.
Also read | Explained: What Sebi’s proposed CAS changes mean for expiry-day trading and settlement
Why Jefferies prefers Groww share price?
Jefferies thinks Groww is a better way of playing India’s equity story. It should also benefit from CAS issues being resolved as F&O accounts for around 55% of the company’s revenues, it said. “We believe the company has several levers to drive 30% PAT CAGR over FY26-29,” Jefferies said, adding that is driven by an 18% growth in broking business led by client vintage and market share gains, new initiatives like margin trading facility and wealth management, and 10pp margin expansion.
Further, Groww is adding US stocks later in FY27, which the international brokerage estimates could add 5-9% to FY28 earnings. Jefferies has a ‘Buy’ call on the shares of Groww-parent Billionbrains Garage Ventures and a target price of Rs 240 apiece, implying nearly 20% upside potential from the stock’s previous closing price of Rs 200.24 apiece on NSE.
What is CAS?
Stock exchanges introduced the new CAS system from August 3, changing the way closing prices are calculated for stocks included in the futures and options (F&O) segment. Under CAS, continuous trading in stocks that also have F&O contracts ends at 3:15 pm. However, this does not mean these stocks are closed for the day 15 minutes before the broader market shuts.
From 3:15 pm onwards, these stocks move into the CAS, a 20-minute auction process that runs until 3:35 pm to determine their official closing prices. Meanwhile, stocks that are not part of the F&O segment continue to trade as usual until 3:30 pm.
During the 20-minute auction window, buy and sell orders for eligible stocks are collected and matched at a single equilibrium price. This mechanism is aimed at improving price discovery and reducing the impact of last-minute trades on closing prices.
Also read |Jefferies’ 25% CAGR club: Paytm, Groww among 5 financial stocks that can deliver up to 25% returns
Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.
Goldman raises Gilt yield forecast as energy prices curb rate-cut hopes

Machi Big Brother Sits $150M Long With Two of Three Assets Down

Brian Hickerson Detained, Brother Arrested After Bar Fight

Memory prices are slowing because buyers ran out of money

The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly

Micron Stock Climbs Above $1,031 as AI Memory Crunch and a $50 Billion Outlook Fuel the Rally

Financial Expert: The MOST CONTROVERSIAL Investing Myths That Cost You Money! | Ben Felix

Singaporean Malone Lam pleads guilty in US court over role in cryptocurrency theft ring

WATCH THIS to retire COMFORTABLY! | How much money do we need? | Retirement in 40s? #rahuljain
-
Tech6 days ago
Memory prices are slowing because buyers ran out of money
-
 Tech19 hours ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-
 Business4 days ago
Micron Stock Climbs Above $1,031 as AI Memory Crunch and a $50 Billion Outlook Fuel the Rally
-

 Business4 days ago
AMD Stock Climbs After Management Lifts 2027 Data Center Outlook Toward $70 Billion in AI Sales
-
 Crypto World5 days ago
Bitcoin price risks $76K drop as $78K support weakens
-

 Fashion3 days ago
Weekend Open Thread – Corporette.com
-
 Crypto World6 days ago
Robinhood Stock: How To Take Advantage With Reduced Risk
-

 Crypto World3 days ago
XAG/USD: Silver’s Short-Term Rally Meets Its Moment of Truth
-

 Crypto World4 days ago
2 Chip Stocks Broke Out This Week. Neither Was Nvidia
-
 Crypto World5 days ago
Ethereum price stalls below $2,500 as ADX drops to 11
-
 NewsBeat6 days ago
England up in reading, maths and science rankings as Scotland and Wales dip
-

 Business3 days ago
10 Most-Streamed Songs On Spotify In 2026 So Far, Led By Ella Langley’s Dominant Run On The Charts This Year
-

 Crypto World3 days ago
OKX launches 10x OpenAI, Anthropic X-Perps in Europe
-

 Tech3 days ago
Battery life is the only iPhone 18 Pro and iPhone Duo upgrade I care about. Apple didn’t disappoint
-

 Crypto World3 days ago
Diesel Tops $6 a Gallon for the First Time as 28 States Set Records
-
 Crypto World6 days ago
Intel Stock Jumps 9% on Chip Price Hike Report, US Stake Gains $36 Billion
-

 Tech4 days ago
Apple Watch Ultra 4 vs Watch Ultra 3: Should you really spend another $799?
-

 Crypto World4 days ago
Bitcoin price risks $70K if $78K neckline breaks
-
 Crypto World6 days ago
Pump Fun and Kraken delete Hunter Biden $LAPTOP promotion
-
 NewsBeat5 days ago
What went right this week: an ‘historic’ fall in violent crime, plus more
You must be logged in to post a comment Login