
Business
Budget airline king Bill Franke warms to premium upgrades

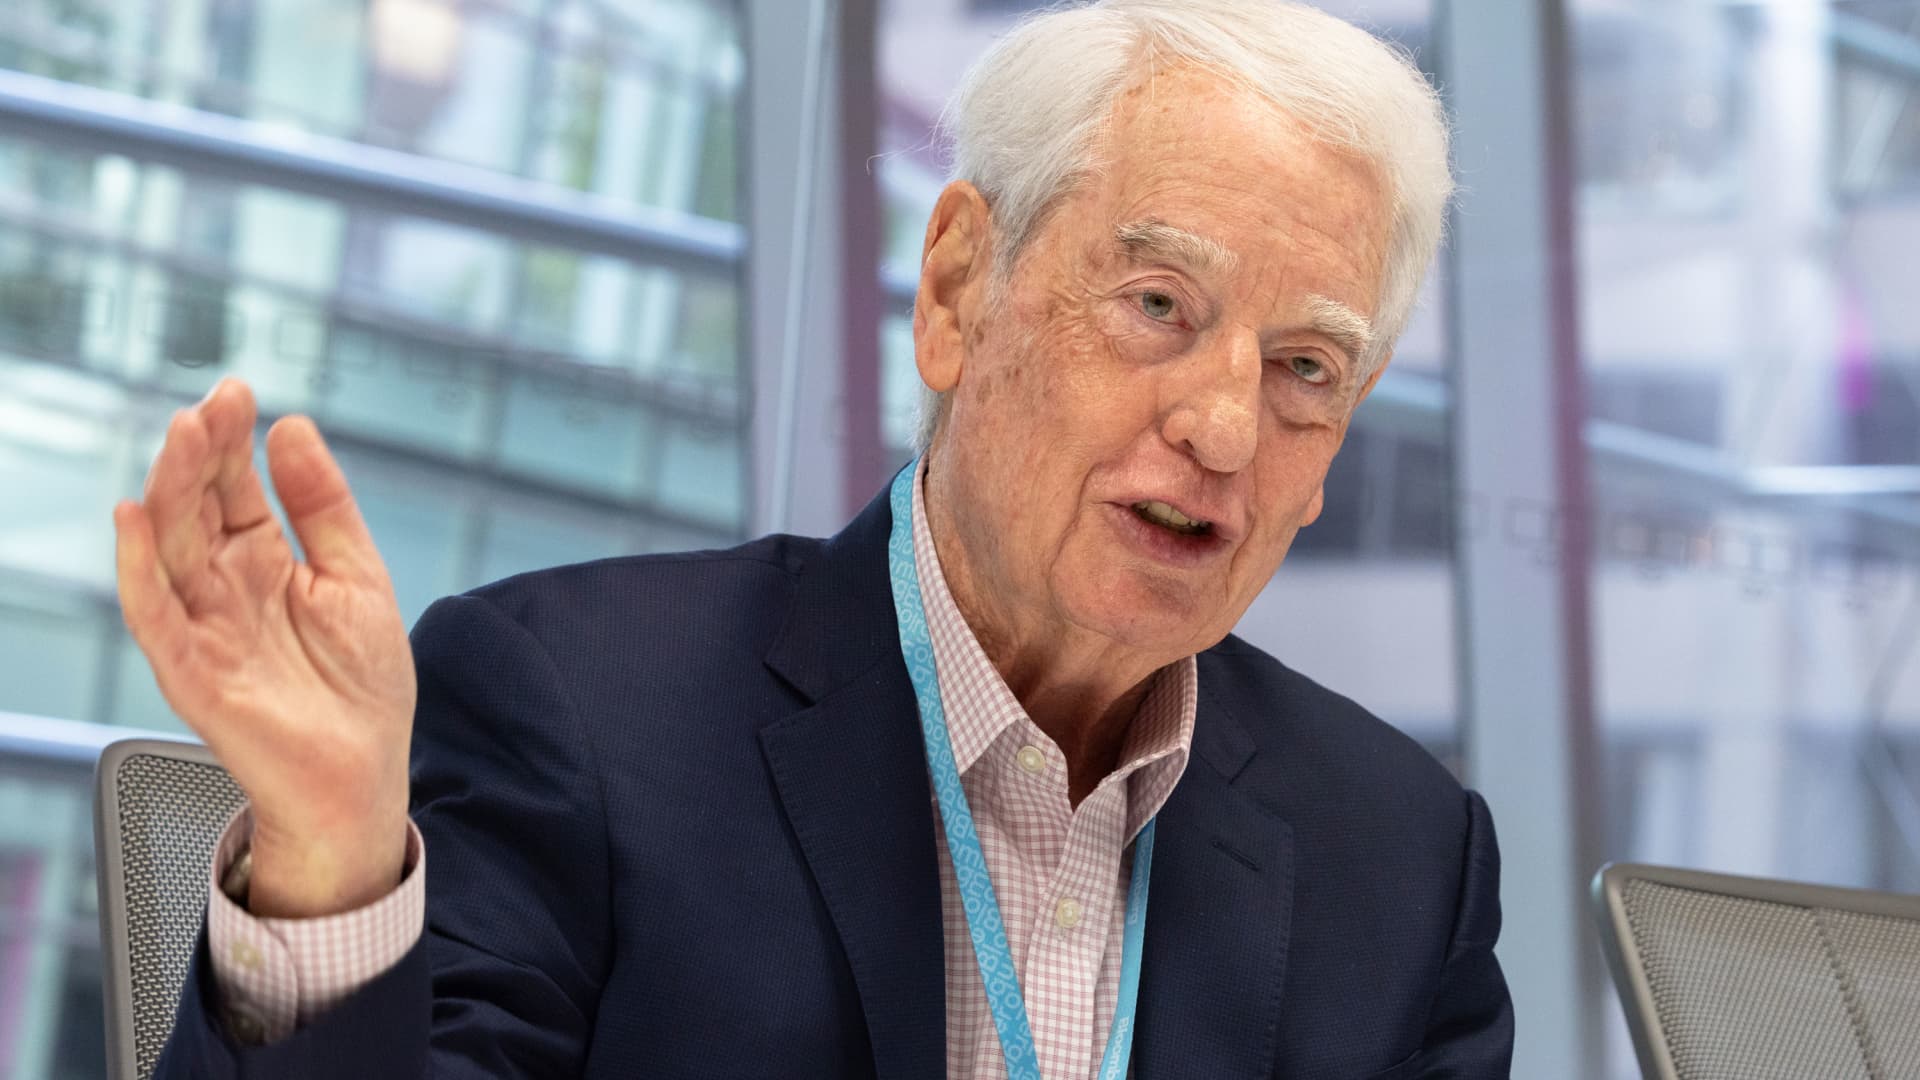
Bill Franke, co-founder of Indigo Partners and chairman of Frontier Airlines Inc., speaks during an interview in New York, Oct. 28, 2022.
Jeenah Moon | Bloomberg | Getty Images
SCOTTSDALE, Ariz. — For decades, William Augustus Franke, Frontier Airlines‘ chairman and a serial airline investor, made a killing selling cheap plane tickets and charging fees to check bags, to pick seats and for everything else. Now, he says first-class seats and other traveler comforts are in order — at least in the United States.
Frontier is planning to roll out first-class seats next year on its Airbus fleet. It’s also joined a growing list of airlines adding SpaceX‘s Starlink Wi-Fi on board as it seeks to return to steady profitability.
“We’re not trying to have a Singapore Airlines first class,” Franke, 89, told CNBC in late June at the model airplane-filled offices of Indigo Partners, the private equity firm he founded. “What we’re trying to do is give the consumer an option,” he said, calling it at once upscale and competitive.
The ultra-low-cost airline model that Franke, who goes by Bill, pioneered has faced a reckoning in recent years. A jump in pilot salaries, maintenance costs and operating expenses, along with a boom in premium travel, have hit long-profitable and fast-growing budget carriers. Maintaining strong growth and keeping costs low were sacrosanct for that sector for years.
Another pillar was not giving things away for free. At the 2017 Dubai Air Show, where he made a record Airbus aircraft order for the empire of airlines he invested in, Franke likened some consumers to teenagers and “spoiled brats,” saying they expected to get low fares and what are now add-ons without paying for them, CNBC reported at the time.
“They had been flying with all the amenities for ever and ever and that’s what they think they ought to get,” Franke said at the time.
But since then, larger, more powerful rivals like United Airlines and Delta Air Lines have copied the model for their cheapest tickets. They’ve started offering bare-bones fare options and adding fees for everything else. This year, they even brought that pricing strategy to their first classes and plush, long-haul suites to increase revenue, stripping customers who choose that option of a free seat choice, among other restrictions.
Franke has owned, operated or invested in budget airlines around the world, from Chile to Hungary to the Philippines to the U.S. He was an early investor in European budget carrier Ryanair.
His legacy stretches across the airline industry: Many top airline executives, including the CEOs of United Airlines and American Airlines, worked under him earlier in their careers.
Franke also ran Spirit Airlines until 2013, before becoming the chairman at Frontier at the end of that year.
He tried to merge the two carriers in 2022 but Spirit shareholders voted for another offer, all cash, from JetBlue Airways. That deal fell apart after a federal court ruled it violated antitrust laws in January 2024.
Struggling on its own, Spirit collapsed in May, the biggest U.S. airline failure in decades, leaving Frontier as the largest discounter in the country.
Franke said he’s far from out of the game and remains a major Frontier shareholder.
“We see startup ideas probably one a month,” he said.
‘They still focus on price’
A Frontier Airlines airplane taxis past a Spirit Airlines aircraft at Indianapolis International Airport in Indianapolis, Indiana.
Luke Sharrett | Bloomberg | Getty Images
Franke started flying frequently when he was a little kid because his father worked for the State Department and was based in Paraguay.
He said a lot has changed since. “Consumers are much smarter today” than they used to be, armed with new data and tools like artificial intelligence that help them better compare fares and options, he noted.
“None of the airlines are quite sure what AI … is going to do to your decision to book,” he said.
But “price and schedule are still at the top,” Franke added.
“For a lot of consumers, whether the ticket costs $200 or $125 is not going to be the decision-maker, but for a lot of people it is still,” he continued. “Middle class, younger flyers, they still focus on price.”
But the ultra-low-cost and low-fare model has struggled in the United States. It’s based on keeping costs minimal and maintaining rapid growth, both of which have been more difficult since the pandemic. Higher fuel prices since the start of the Iran war have been an added challenge.
Spirit is the obvious casualty, with its CEO saying it “ran out of runway” after facing increasing challenges, but Frontier has only been profitable one year since 2019 and JetBlue hasn’t been profitable since that year.
“We’re not forecasting next year, but the airline is certainly on the right trajectory to return to sustainable profitability,” Frontier CEO Jimmy Dempsey said on a July 29 earnings call. He became the carrier’s chief executive in December, succeeding Barry Biffle who headed the airline for close to a decade.
Airlines, including Frontier, have been jacking up fares to cover costs. August airfares were up more than 23% over last year, according to federal data released Sept. 11.
Frontier isn’t alone in wanting to add pricier and roomier seats. Allegiant Air recently announced it would add a first class to its currently single-cabin planes, and JetBlue Airways is adding a domestic first class. Meanwhile, larger competitors are growing their premium cabins.
Franke said the new upscale moves don’t fit everywhere, and that efficiency remains key.
“In the U.S. market where you have mature large airlines — Delta, United, American — who are changing the interior of their aircraft on a regular basis, it could well be that a low-cost or a lower-cost airline, in order to properly compete, needs to make adjustments to its business model,” he said. “That doesn’t mean you have to do that in an emerging market like Hungary or Peru.”
All roads lead to Tempe
Franke’s legacy extends beyond the low-cost model. Many of the leaders of the modern U.S. airline industry can trace their roots back to Franke and to Tempe, Arizona, where America West — which through mega-mergers evolved into modern-day American Airlines — was based.
Franke, who had studied and practiced law, got into the airline business more than 30 years ago. The then governor of Arizona tapped him to save America West when it was mired in bankruptcy in the early 1990s and he became chief executive in 1993.
His proteges include American Airlines CEO Robert Isom; Isom’s predecessor, former American Chief Executive Doug Parker; and United Airlines CEO Scott Kirby.
Franke’s former employees told CNBC that they keep up with him regularly.
Isom told CNBC in an interview in late June that Franke is “pretty good at giving jabs.” For many years, they would bet on college football, specifically, games between Stanford University, where Franke studied, and Notre Dame, where Isom studied.
“His rule was fast pay makes fast friends,” Isom recalled, showing CNBC some of his winnings: Chilean pesos with Franke’s business card attached by paperclip and, in another win by Isom, euro coins taped to a sheet of paper with “PAID IN FULL” written out by his former boss.
Kirby told CNBC at an industry conference in Rio de Janeiro in June that after The Wall Street Journal profiled him this spring, Franke told him it made him “throw up in his coffee when he opened his newspaper.” Franke didn’t comment on that, but said he recalled the exchange.
Even still, Kirby called Franke a mentor, and clarified that he was “a hard-ass mentor.”
“All of us, our formative years were working for Bill, getting screamed at by Bill. … He should take more credit for that,” he said. (Franke said he didn’t yell at him. “That’s just not me.”)
Franke was demanding, especially when it counted, his alumni said.
Steve Johnson, American Airlines vice chair and chief strategy officer, and another Franke America West alum, likened Franke to a second father.
Johnson was a partner from 2003 to 2009 at Indigo when it owned Spirit. During the summer 2008 fuel spike that saw prices hit more than $147 a barrel (more than $200 in today’s dollars), Spirit was running out of money but had a portfolio of fuel hedges, a series of contracts that locks in future pricing.
He was about to head to a California-bound plane that summer when Franke called him about the fuel and told him to “sell it now,” Johnson recalled. They did and generated about $30 million. Oil prices later crashed.
“It turned out to be just exactly what Spirit needed,” Johnson said.


Minneapolis Fed’s Kashkari says inflation remains too high
Energy Transfer: Enough Is Enough (Rating Downgrade)

Trump converts planned triumphal arch into drone facility

Just over a year ago, investors largely viewed IREN (IREN) as a bitcoin mining company. Today, the company supplies AI infrastructure to Microsoft (MSFT) and signs billion-dollar contracts with some of the biggest names in the AI market, including Nvidia (NVDA) and Dell Technologies (DELL). These developments provide evidence that IREN’s shift toward AI infrastructure is translating into actual business activity, and the market has responded strongly to that progress. IREN shares have been rewarded with two strong moves over the last two months.
The Microsoft Deal That Changed Everything
IREN’s AI transformation centers on a major five-year agreement with Microsoft. The company entered into a $9.7 billion cloud services agreement with Microsoft, with 20% of the contract value paid upfront. Once fully commissioned, the deal is expected to generate nearly $1.94 billion in annualized run-rate revenue. That gives IREN a significant source of contracted business as it builds out its AI cloud operations.
More News from Barchart
The key point is that the agreement is already translating into real infrastructure. The company has completed and delivered the first of four planned “Horizon” AI cloud deployments for Microsoft. The deployment is a 50-megawatt liquid-cooled installation at IREN’s Childress, Texas campus. Nvidia has also granted IREN Exemplar Cloud status after testing the deployment’s GB300 NVL72 setup. That validation is important because it shows Nvidia has tested IREN’s infrastructure and confirmed its ability to support demanding AI workloads.
IREN’s planned capacity expansion shows just how quickly its business is changing, growing from roughly 3 megawatts of AI cloud capacity a year ago to 480 megawatts being delivered in 2026. The neocloud is targeting 1.2 gigawatts by 2027, which would amount to more than a hundredfold growth in capacity over about two years. Importantly, the expansion is already backed by a committed timeline.
At the same time, the company is building a revenue base that goes well beyond Microsoft. After securing $2.8 billion in new contracts, IREN raised its year-end 2026 annualized revenue target to more than $4 billion. Around 85% of that revenue target is already covered by signed contracts. The customer list has also expanded to include Together AI, Nvidia, Figure AI, Perplexity, and Fluidstack.


Virtus Investment Partners provides investment management products and services to individuals and institutions. We operate a multi-manager asset management business, comprising a number of individual affiliated managers, each with a distinct investment style, autonomous investment process and individual brand. We clearly understand the responsibility we have to our clients and we are committed to their success as investors.
For important disclaimers, go to https://www.virtus.com/social-media-guidelines. Note: This account is not managed or monitored by Virtus, and any messages sent via Seeking Alpha will not receive a response. For inquiries or communication, please use the firm’s official channels.

The Investment Doctor is a financial writer, highlighting European small-caps with a 5-7 year investment horizon. He strongly believes a portfolio should consist of a mixture of dividend and growth stocks.
He is the leader of the investment group European Small Cap Ideas which offers exclusive access to actionable research on appealing Europe-focused investment opportunities not found elsewhere. The a focus is on high-quality ideas in the small-cap space, with emphasis on capital gains and dividend income for continuous cash flow. Features include: two model portfolios – the European Small Cap Ideas portfolio and the European REIT Portfolio, weekly updates, educational content to learn more about the European investing opportunities, and an active chat room to discuss the latest developments of the portfolio holdings. Learn more.
Analyst’s Disclosure: I/we have a beneficial long position in the shares of XIORF either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
I will likely continue to add to this position.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
Ares Capital Remains The Gold Standard In BDCs

I focus on a variety of stocks but I prefer to write about oil and gas companies for now. I also enjoy studying and writing about where energy and monetary incentives intersect. I have a a bachelors and MBA although that should never replace experience and interest.Thanks for reading my articles!
Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
A company of Manulife Investment Management, John Hancock Investment Management serves investors through a unique multimanager approach, complementing our extensive in-house capabilities with an unrivaled network of specialized asset managers, backed by some of the most rigorous investment oversight in the industry. The result is a diverse lineup of time-tested investments from a premier asset manager with a heritage of financial stewardship. Note: This account is not managed or monitored by John Hancock Investment Management, and any messages sent via Seeking Alpha will not receive a response. For inquiries or communication, please use John Hancock Investment Management’s official channels.
Mayville Engineering Company's Plunge Has Been Unreasonable

Newcastle’s limitations exposed by Bournemouth before hosts fight back for draw
Minneapolis Fed’s Kashkari says inflation remains too high

Should You Trust a Chatbot With Your Money? A 10,000-Answer Test Has a Verdict




-
 Fashion2 days ago
Weekend Open Thread: Talbots – Corporette.com
-
 NewsBeat2 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-
 Crypto World2 days ago
Circle launches Arc Studio AI agent for building onchain apps
-

 Crypto World6 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-

 Crypto World6 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-

 Crypto World5 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-
 Crypto World5 days ago
Robinhood engineers charged over $50K crypto scheme
-

 Crypto World4 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-
 Crypto World2 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World6 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-

 Crypto World7 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-
 NewsBeat6 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World5 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-
Business6 days ago
SK Hynix ADRs Fall More Than 6% as Memory Rally Breaks on Fears of Slower AI Spending
-
 Tech5 days ago
Webb’s IC 348 Mosaic Includes Two-Jupiter Dwarfs, Twin Jets, and a Nursery Still Making Worlds
-

 Crypto World6 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-
Crypto World6 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
-

 Crypto World6 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
-
 Crypto World7 days ago
Goldman Sachs backs 25bp Fed hike after CPI
-
 Crypto World7 days ago
AI Safety Burden Falls on Chief Executives as Trump Prioritizes China Race
You must be logged in to post a comment Login