
Business
Investors focus on rate path, AI slowdown after Fed hike




Oliver Rodzianko is Director of Invictus Origin and a private investor managing a high-alpha portfolio strategy focused on rotation and disciplined cash deployment during market dislocations.
Analyst’s Disclosure: I/we have a beneficial long position in the shares of LULU either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
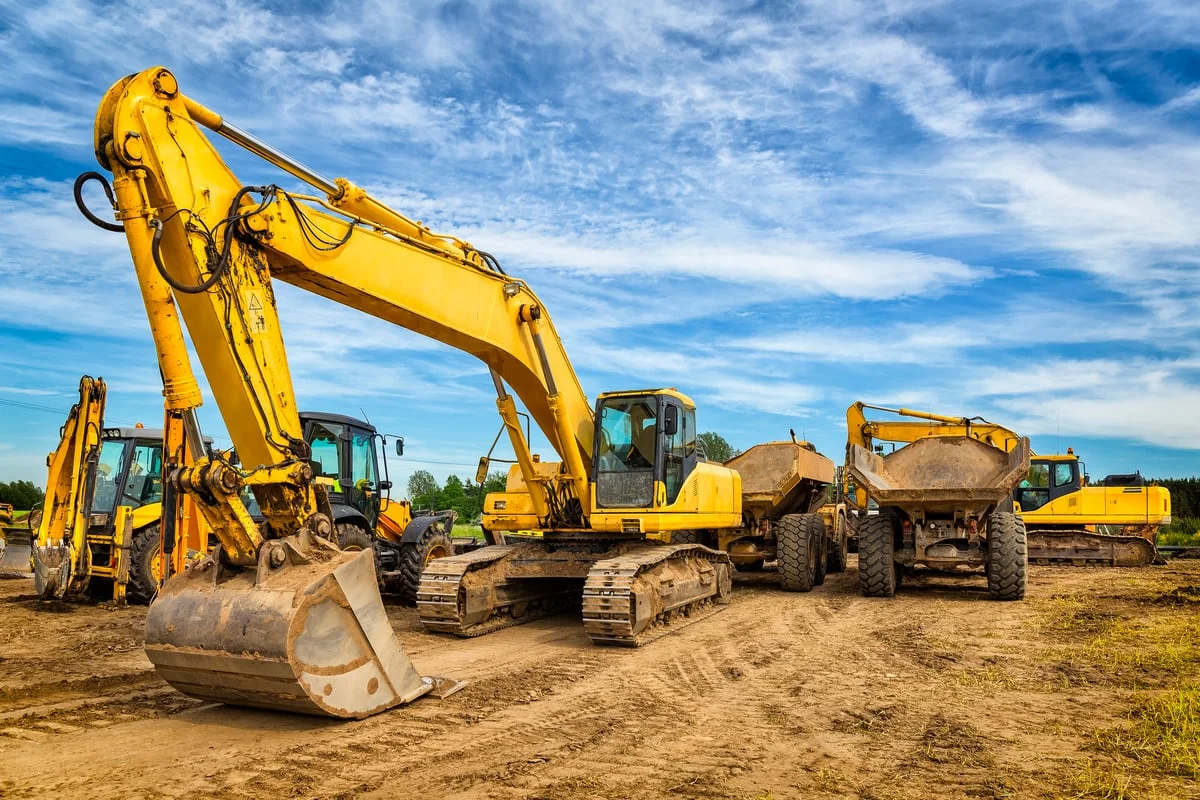
Caterpillar (NYSE: CAT) has been outperforming the S&P 500 by riding artificial intellgience (AI) tailwinds, and a recent correction doesn’t change that fact. While talks about a slowdown in AI development gripped headlines, they were largely for naught, with Meta Platforms CEO Mark Zuckerberg saying that market forces and competition are enough to keep AI models safe.
Hyperscalers are ramping up their AI development, and Caterpillar is at the center of it, since power is a critical bottleneck. That’s the basic setup for why Caterpillar’s correction won’t last for long, but there are additional details that can fuel a rally.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »

The AI build-out needs power and infrastructure
Caterpillar is gaining market share across multiple key industries vital to artificial intelligence. First, its power & energy segment increased by 17% year over year in the second quarter.
High demand from AI data centers has ignited this segment of the business to the point where Caterpillar is sitting on a $72 billion backlog. The backlog has almost doubled year over year and provides meaningful revenue visibility. It’s also up by $9.4 billion sequentially, which represents a 15% boost.
Second, AI data centers still need to be built to accommodate the increased need for compute. As hyperscalers gobble up existing gigawatts for their long-term projects, it further restricts the supply of remaining compute. Its construction segment saw a 35% year-over-year revenue jump.
Most of the growth came from North America, which correlates with where most tech giants are setting up data centers. Construction revenue was up year over year in every region.
The valuation looks more compelling
Dips present good buying opportunities when a company’s fundamentals improve or remain stable. In Caterpillar’s case, the company has demonstrated deep involvement in the AI boom, with the backlog serving as a multi-year green flag.
The correction has brought Caterpillar down to a 1.4 PEG ratio. The stock has previously hovered above a 2 PEG ratio, and its other valuation metrics, including the P/E ratio, are much lower than they were a few months ago.
An investment in Caterpillar right now is a bet that the AI boom will continue. Grand View Research projects a 30.6% CAGR for the artificial intelligence industry through 2033. In the meantime, hyperscalers continue to commit vast sums to capital expenditures. Six of the major hyperscalers are projected to spend $1.3 trillion in 2027.

Fed’s Kashkari says inflation goes beyond oil prices, according to Fox News interview

Minneapolis Fed’s Kashkari says inflation remains too high
Energy Transfer: Enough Is Enough (Rating Downgrade)

Trump converts planned triumphal arch into drone facility

Just over a year ago, investors largely viewed IREN (IREN) as a bitcoin mining company. Today, the company supplies AI infrastructure to Microsoft (MSFT) and signs billion-dollar contracts with some of the biggest names in the AI market, including Nvidia (NVDA) and Dell Technologies (DELL). These developments provide evidence that IREN’s shift toward AI infrastructure is translating into actual business activity, and the market has responded strongly to that progress. IREN shares have been rewarded with two strong moves over the last two months.
The Microsoft Deal That Changed Everything
IREN’s AI transformation centers on a major five-year agreement with Microsoft. The company entered into a $9.7 billion cloud services agreement with Microsoft, with 20% of the contract value paid upfront. Once fully commissioned, the deal is expected to generate nearly $1.94 billion in annualized run-rate revenue. That gives IREN a significant source of contracted business as it builds out its AI cloud operations.
More News from Barchart
The key point is that the agreement is already translating into real infrastructure. The company has completed and delivered the first of four planned “Horizon” AI cloud deployments for Microsoft. The deployment is a 50-megawatt liquid-cooled installation at IREN’s Childress, Texas campus. Nvidia has also granted IREN Exemplar Cloud status after testing the deployment’s GB300 NVL72 setup. That validation is important because it shows Nvidia has tested IREN’s infrastructure and confirmed its ability to support demanding AI workloads.
IREN’s planned capacity expansion shows just how quickly its business is changing, growing from roughly 3 megawatts of AI cloud capacity a year ago to 480 megawatts being delivered in 2026. The neocloud is targeting 1.2 gigawatts by 2027, which would amount to more than a hundredfold growth in capacity over about two years. Importantly, the expansion is already backed by a committed timeline.
At the same time, the company is building a revenue base that goes well beyond Microsoft. After securing $2.8 billion in new contracts, IREN raised its year-end 2026 annualized revenue target to more than $4 billion. Around 85% of that revenue target is already covered by signed contracts. The customer list has also expanded to include Together AI, Nvidia, Figure AI, Perplexity, and Fluidstack.


Virtus Investment Partners provides investment management products and services to individuals and institutions. We operate a multi-manager asset management business, comprising a number of individual affiliated managers, each with a distinct investment style, autonomous investment process and individual brand. We clearly understand the responsibility we have to our clients and we are committed to their success as investors.
For important disclaimers, go to https://www.virtus.com/social-media-guidelines. Note: This account is not managed or monitored by Virtus, and any messages sent via Seeking Alpha will not receive a response. For inquiries or communication, please use the firm’s official channels.

The Investment Doctor is a financial writer, highlighting European small-caps with a 5-7 year investment horizon. He strongly believes a portfolio should consist of a mixture of dividend and growth stocks.
He is the leader of the investment group European Small Cap Ideas which offers exclusive access to actionable research on appealing Europe-focused investment opportunities not found elsewhere. The a focus is on high-quality ideas in the small-cap space, with emphasis on capital gains and dividend income for continuous cash flow. Features include: two model portfolios – the European Small Cap Ideas portfolio and the European REIT Portfolio, weekly updates, educational content to learn more about the European investing opportunities, and an active chat room to discuss the latest developments of the portfolio holdings. Learn more.
Analyst’s Disclosure: I/we have a beneficial long position in the shares of XIORF either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
I will likely continue to add to this position.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
Ares Capital Remains The Gold Standard In BDCs
The 8 Most Fun Westerns of All Time, Ranked

Kim Kardashian, Oprah, Kerry Washington & More A-Listers Attend Lucas Museum of Narrative Art Opening Night Gala
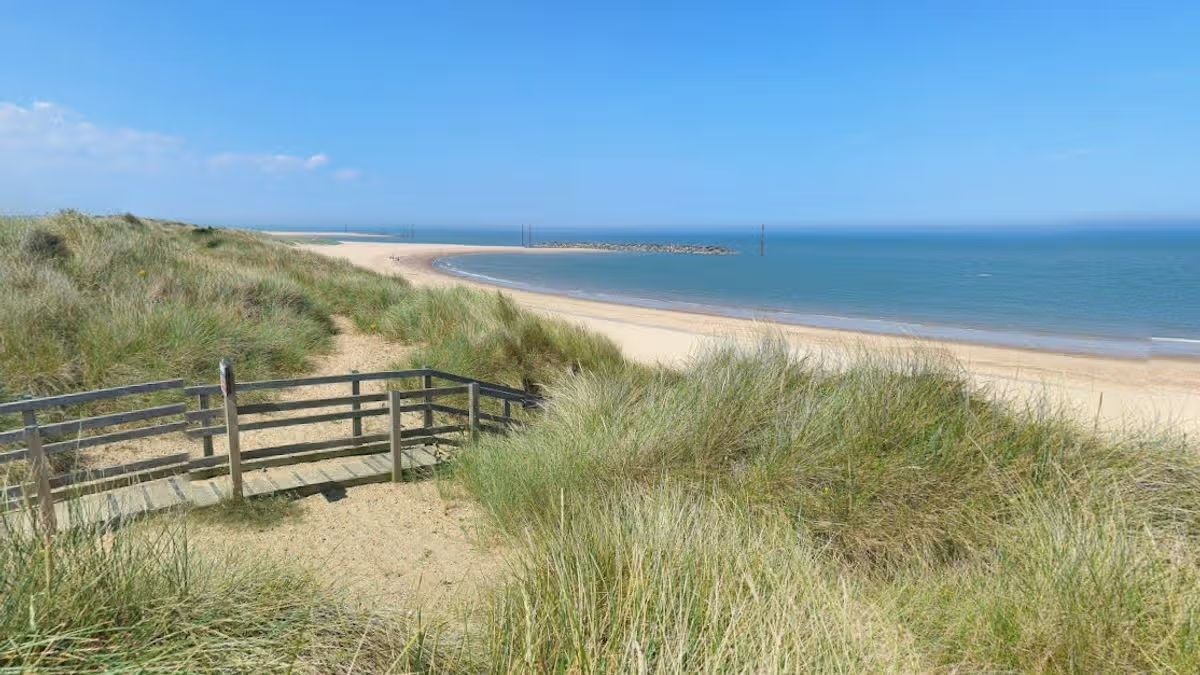
The quiet Norfolk beach 2 hours from Cambridge that’s an ‘unspoilt natural beauty’




-
 Fashion2 days ago
Weekend Open Thread: Talbots – Corporette.com
-
 NewsBeat2 days ago
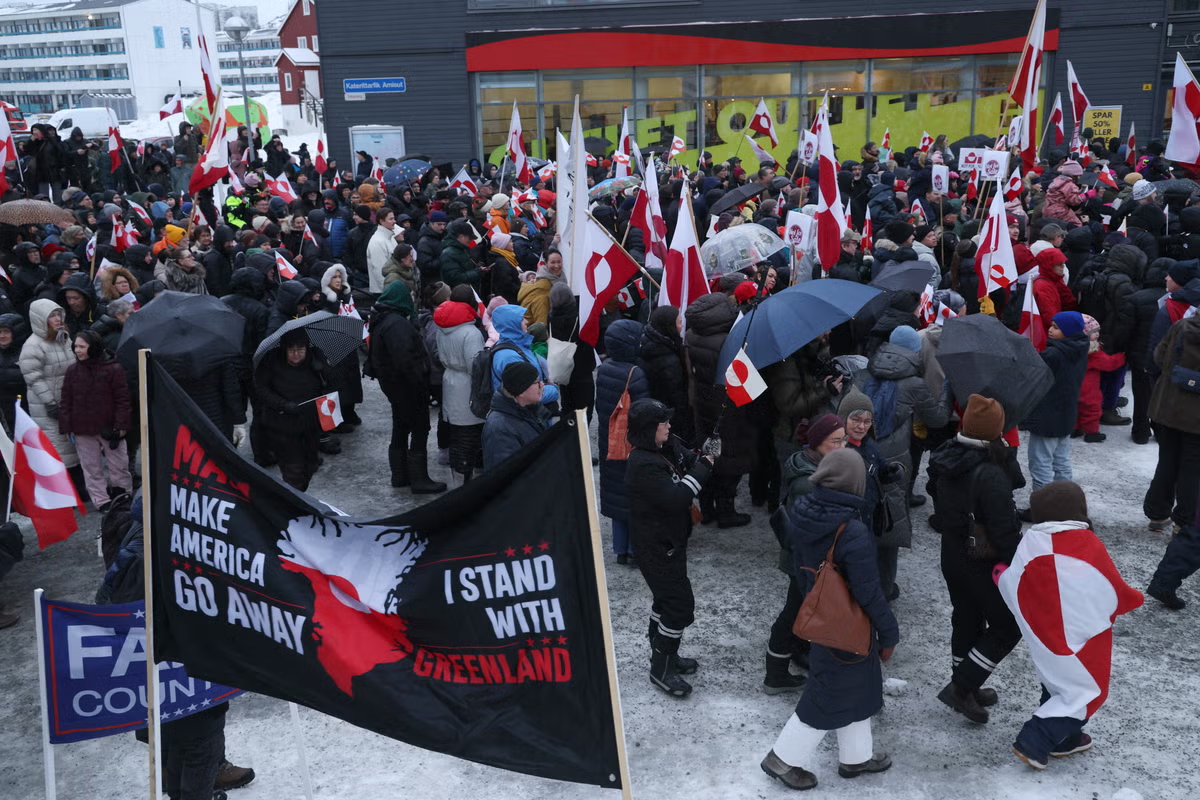
Trump says US has reached an agreement to take permanent control of Greenland’s security
-
 Crypto World2 days ago
Circle launches Arc Studio AI agent for building onchain apps
-

 Crypto World6 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-

 Crypto World6 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-

 Crypto World5 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-
 Crypto World5 days ago
Robinhood engineers charged over $50K crypto scheme
-

 Crypto World4 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-
 Crypto World2 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World6 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-

 Crypto World7 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-
 NewsBeat6 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World5 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-
Business6 days ago
SK Hynix ADRs Fall More Than 6% as Memory Rally Breaks on Fears of Slower AI Spending
-
 Tech5 days ago
Webb’s IC 348 Mosaic Includes Two-Jupiter Dwarfs, Twin Jets, and a Nursery Still Making Worlds
-

 Crypto World6 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-
Crypto World6 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
-

 Crypto World6 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
-
 Crypto World7 days ago
Goldman Sachs backs 25bp Fed hike after CPI
-
 Crypto World7 days ago
AI Safety Burden Falls on Chief Executives as Trump Prioritizes China Race
You must be logged in to post a comment Login