
Business
SCHD: Can It Keep Winning In 2026? Yes, It Can



Barclays cuts Cellectis stock rating on gene editing concerns
The government will introduce MDR on some Person-to-Merchant (P2M) UPI transactions from October 15 onwards, with merchants paying 0.4% on transactions above Rs 2,000, the National Payments Corporation of India (NPCI) announced on Tuesday. A maximum fee of Rs 300 can be levied on such transactions of Rs 75,000 or more.
CMS Info Systems is one of India’s largest cash management and business services companies, offering physical logistics, banking automation and AI-driven technology solutions.
How is CMS Infosystems a beneficiary?
The positive read-through for CMS Info Systems is mainly through a potential shift back towards cash for higher-value merchant transactions.
With a 0.4% MDR on UPI P2M transactions above Rs 2,000 from October 15, higher-value digital payments will no longer be completely free for merchants. This could make cash payments relatively more attractive for some merchants, particularly where transaction values are high and margins are thin.

That could benefit CMS because its core business includes cash logistics, ATM cash management, retail cash management and cash-in-transit services.
CMS Infosystems Q1 results
Cash logistics major CMS Info Systems reported a 10.6% year-on-year decline in consolidated profit after tax (PAT) to Rs 83.7 crore in the first quarter of FY27, compared with Rs 93.6 crore in the same quarter a year ago.Consolidated revenue, however, rose 1.2% year-on-year to Rs 634.7 crore in Q1 FY27 from Rs 627.4 crore in Q1 FY26. EBITDA increased 6.9% year-on-year to Rs 168.8 crore from Rs 157.9 crore, while the EBITDA margin improved to 26.6% in Q1 FY27 from 25.2% in the year-ago quarter.
CMS Info shares have had a rough 2026, down 19% in the last six months and a massive 35% since the beginning of the year. In the last one year, the stock is down 45%.
RBI supports MDR charges
The Reserve Bank of India (RBI) backed the introduction of Merchant Discount Rate (MDR) on large-value UPI transactions, saying the move will help strengthen the long-term sustainability of India’s digital payments ecosystem. In a post on X, the central bank said the move would enable UPI to continue scaling, innovating and serving consumers and businesses across the country.
For nearly seven years, UPI became more and more popular as a transaction could be made so quickly without paying any additional charges. The government has however repeatedly clarified that UPI will remain free for citizens and person-to-person transactions will continue without charges.
While discussing the costs of digital-payment infrastructure, RBI Governor Sanjay Malhotra in August said, “Someone has to pay the cost”. He stressed that the RBI wants digital payments to remain accessible, affordable and safe, but also sustainable.
(Disclaimer: Recommendations, suggestions, views and opinions given by the experts are their own. These do not represent the views of The Economic Times)
Rises in petrol, diesel and airfares pushed UK inflation up to its highest level in six months in the year to August.
Inflation accelerated to 3.1% from 2.9% , according to the Office for National Statistics (ONS).
The cost of filling up a vehicle soared in August as the conflict in the Middle East continued to disrupt global oil supplies. Petrol prices jumped to their highest for nearly four years, the ONS said, while diesel also rocketed.
Meanwhile, the cost of flying jumped during the key month for summer getaways.
Overall, motor fuel prices rose by 23% compared to August last year.
Oil hit more than $91 a barrel as the US-Israel war with Iran went on. That compares to around $73 just before hostilities began earlier this year.
As a result, average petrol prices have continued to climb and between July and August, they rose by 9.1p to 161.3p per litre.
“This is the highest price recorded since November 2022,” said the ONS. At that point, Russia’s full-scale invasion of Ukraine had pushed up global energy costs.
Capital Economics said, at this point, the effect of higher oil prices has not spilled over into other areas such as food and drink, where the pace of inflation remained at 1.3% in the year to August.
But its chief UK economist, Paul Dales, said: “Everyone knows that bigger rises in inflation are on their way.”
Grant Fitzner, chief economist at the ONS, said: “Rising crude oil and petrol prices increased both the annual cost of raw materials and the price of goods leaving factories respectively.”
Dales estimates that a combination of higher oil and gas prices and “the eventual ‘first-round’ effect of businesses passing on some of their higher energy costs” will lead to inflation peaking at 4.2% in January.

ECB’s wage tracker points to modest uptick in negotiated pay growth
UPDATE: BGC chief executive Michael Allan has confirmed it intended to provide “greater clarity” to customers when its subsidiary Midland Brick announced it would begin rationing supply amid a shortage impacting all Western Australian builders using double brick.
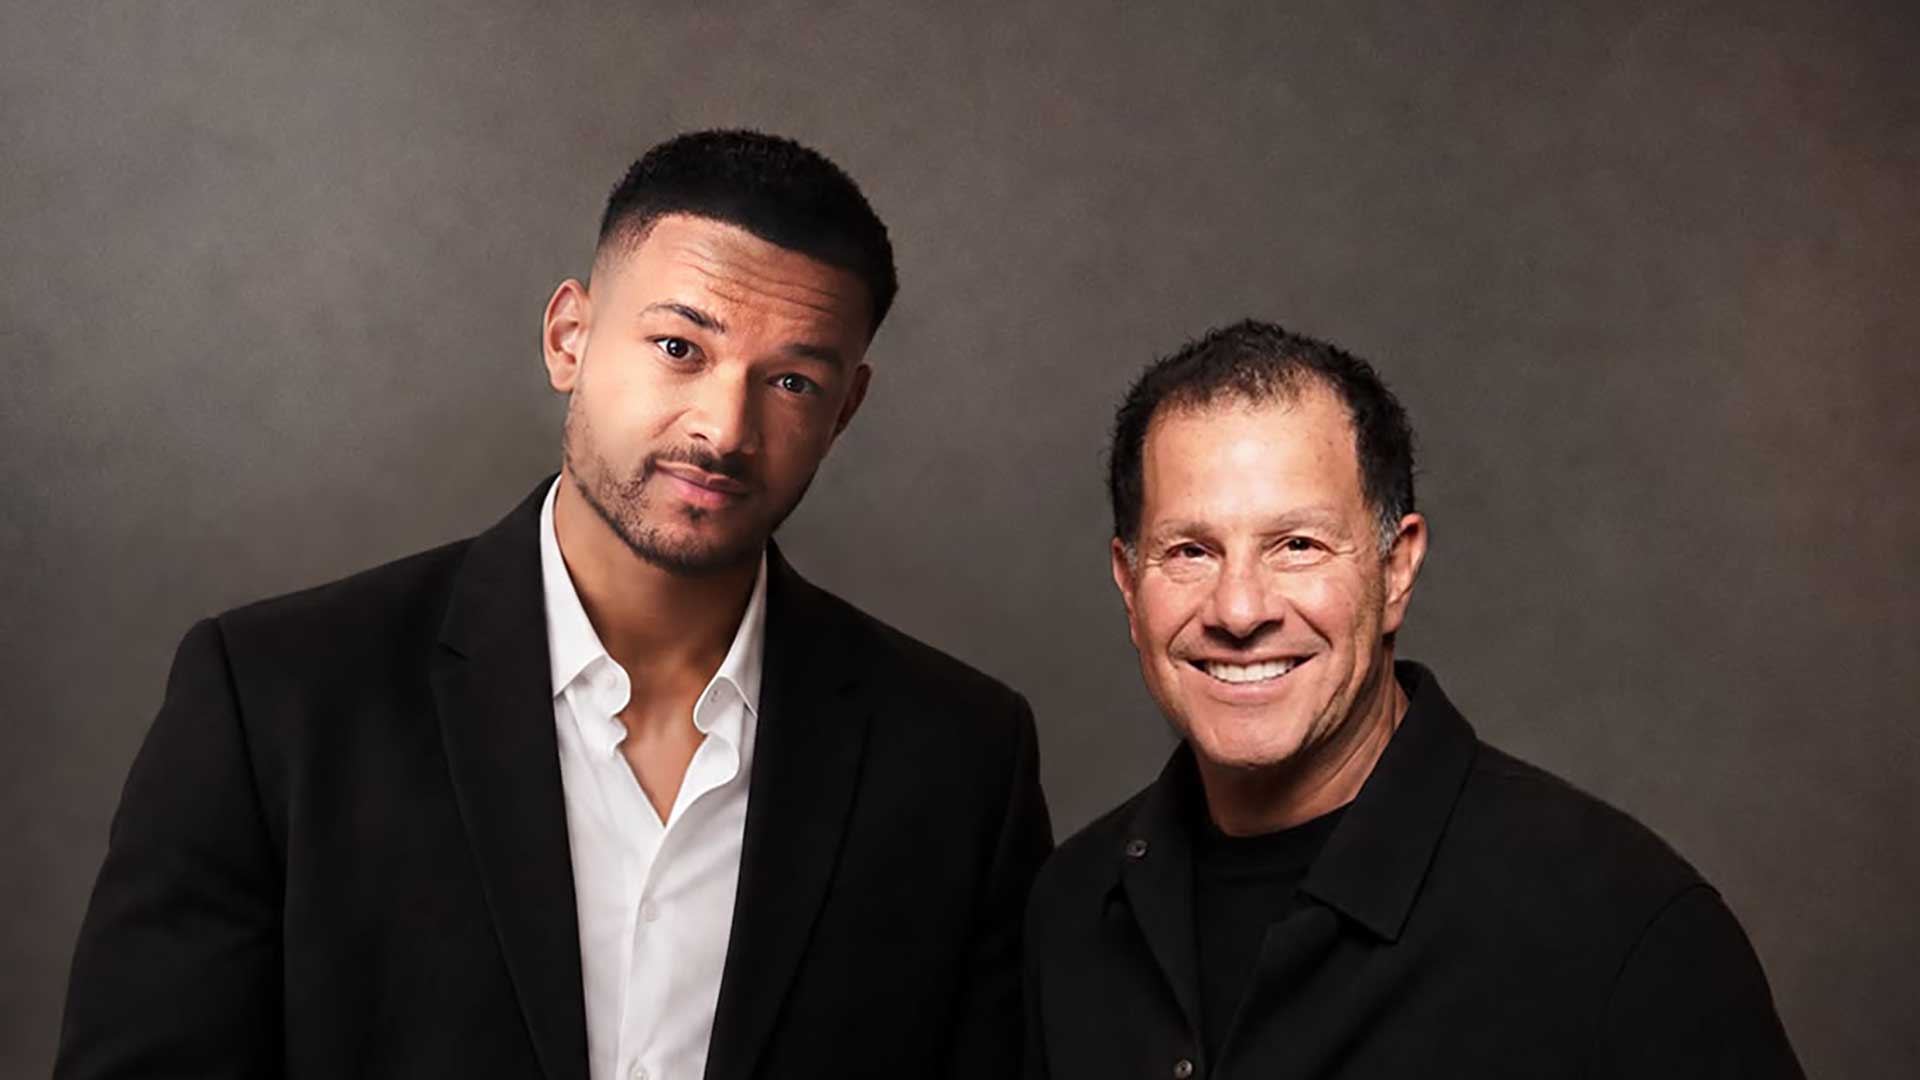
Steven Bartlett’s holding company Steven.com and Authentic Brands Group have launched OBSN, a joint venture that will invest in and build businesses around creators, with Bartlett saying he aims to deploy up to $400m in creator businesses over the coming years.
The venture, whose name is short for Obsession, was announced in New York yesterday. It was due to debut the same day at a creator-focused event in the city, where Maggie Sellers Reum, investor and founder of Hot Smart Rich, was to moderate a fireside conversation with Bartlett and Jamie Salter, founder and executive chairman of Authentic.
According to the two companies, OBSN is “designed for the world’s most ambitious and consequential creators”. At its centre is a platform providing news, analysis and live experiences for the creator economy, which the partners say is designed to become the sector’s “definitive voice and home”.
How the partnership will work
Under the arrangement, Steven.com will lead OBSN’s media, technology, data and audience-growth operations. Authentic will contribute its expertise in brand building, product, licensing, strategic partnerships and global distribution.
The partners said every deal struck through OBSN would be tailored to the individual creator, whether that involves expanding a media business, developing products, growing licensing programmes, pursuing strategic partnerships or exploring investment and international expansion. They said the venture would provide creators with infrastructure, expertise and long-term partnership as well as capital.
The companies said they see opportunities to deploy hundreds of millions of dollars in the near term into creator-led businesses that meet their criteria.
“The next generation of global media companies and consumer brands will be built around creators. But a global audience of millions is not yet a company, and it certainly should not be the ceiling of a creator’s potential,” said Bartlett.
“Steven.com understands how to build media and audiences around creators, and Authentic understands how to build and extend brands around the world. OBSN brings those capabilities together so ambitious creators can reach the full scale of their ambition. We are aiming to deploy up to $400m in creator businesses over the coming years, OBSN is at the heart of that strategy.”
Matt Maddox, president and chief executive of Authentic, said: “Creators are redefining media and shaping the future of entertainment, with many poised to become multigenerational brands in their own right.”
He added: “By combining our complementary capabilities, we will identify, invest in and scale creator-led IP, capitalizing on a once-in-a-generation opportunity to strategically deploy hundreds of millions of dollars across the creator economy and build the brands of tomorrow.”
The companies behind OBSN
Steven.com is the holding company for Bartlett’s businesses, including The Diary Of A CEO podcast, marketing agency FlightStory, production business FlightCast and investment arm FlightFund. In October 2025 it was valued at $425m following investment from Slow Ventures and Apeiron Investment, with Bartlett retaining more than 90 per cent ownership. In December 2025, Bartlett also announced plans for Founded, a tech news website covering UK and US start-ups.
Authentic owns more than 50 brands, including Reebok, Champion, Ted Baker, Brooks Brothers, Hunter and Sports Illustrated, as well as rights linked to David Beckham, Shaquille O’Neal, Elvis Presley and Muhammad Ali. The company says it works with a network of more than 1,700 licensees and partners in more than 150 countries, and that its brands generate more than $38bn in annual systemwide retail sales. Its portfolio reaches nearly one billion social media followers, according to the company.
The move comes as advertising money shifts towards creators. Business Matters reported last year that creator platforms were forecast to overtake traditional media in global ad revenue for the first time.
OBSN said its creator economy media and events arm is already live, with more than one million followers on Instagram. The partners plan to expand it into new content formats, channels and live experiences, including festivals and official awards. Creators can register interest through the Obsession.com website.
Jamie Young
Jamie Young is Senior Reporter at Business Matters, covering SME finance, employment law and Westminster policy since 2016. He has reported on every Budget and Autumn Statement since 2018, helped make sense of the ‘covid era’ and the bounce-back loan scheme from launch through the fraud investigations, and broke the magazine’s coverage of the 2024 late-payment reforms. He joined Business Matters straight from completing his BA in Administration from Exeter University and is NCTJ-qualified. Reach him at jyoung@cbmeg.co.uk
Business
Solar Industries shares plunge 17% in 2 days. Why Jefferies, Nuvama still see up to 46% upside
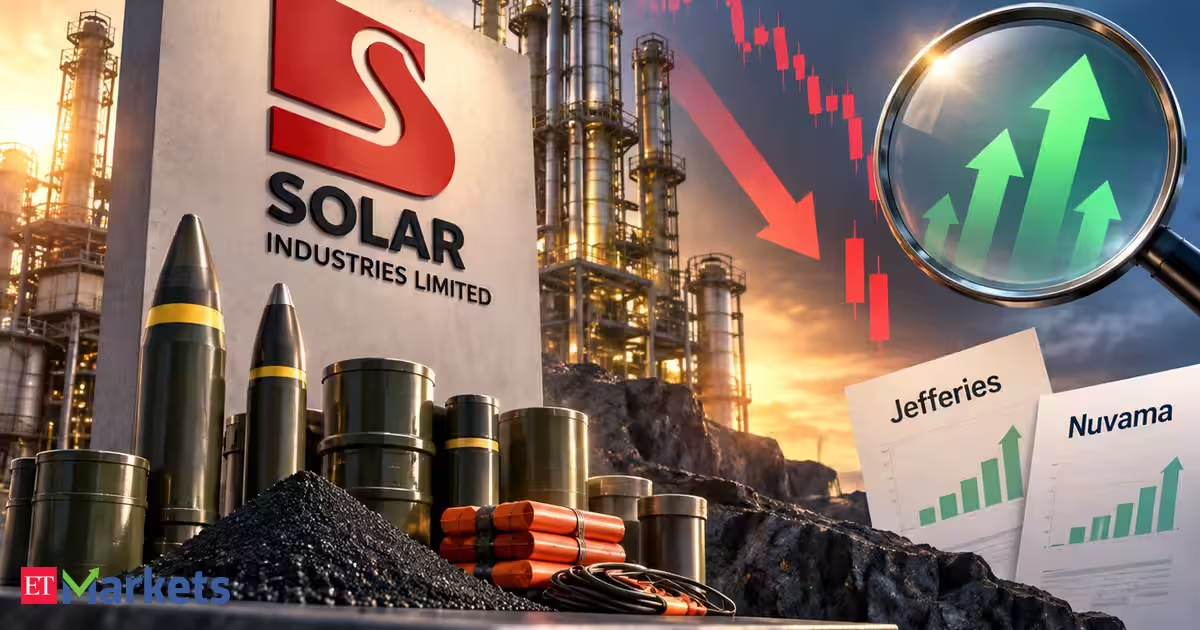
The stock had plunged nearly 14% on Tuesday following the announcement of the all-cash deal to acquire 100% of Omnia’s issued shares for $1.355 billion.
Despite the sharp selloff, Jefferies and Nuvama have advised investors to use the correction as an opportunity to add the stock, pointing to the potential benefits of the acquisition. The deal, Solar Industries’ largest overseas acquisition, is aimed at expanding its global commercial explosives and blasting solutions business, particularly across Africa’s mining markets.
The acquisition is expected to be completed in early to mid 2027, subject to customary conditions, including competition approvals under relevant jurisdiction. Upon successful completion of the transaction, Omnia will be delisted from the Johannesburg Stock Exchange and A2X Markets securities exchange.
Also read | Solar Industries shares crash 14% after acquisition of South Africa’s Omnia Holdings for Rs 12,951 crore
Jefferies on Solar Industries share price
Jefferies maintained its ‘Buy’ call for the shares of Solar Industries with a target price of Rs 28,160 apiece, implying more than 46% upside potential from the stock’s previous closing price of Rs 19,250 apiece. The international brokerage said the bulky acquisition could dilute the company’s FY28-29 EPS by 4-6%, and that for FY30 by 1% on normalised growth assumptions at Omnia. Defence share is likely to fall to 22-25% by FY30, as against 35-40% expected earlier.
However, Jefferies believes the correction offers a heightened opportunity to own a business with a 30% EPS CAGR potential and 25%+ ROE even considering the acquisition. Solar Industries saw its profits rise 10x in the last decade between market share gains globally in explosives, an acquisition in South Africa in 2024 and its foray in defence, the international brokerage noted, adding that management has a healthy track record on sound capital allocation and cash flow focus.“While share of defence on a consolidated basis will likely reduce, we believe that if the EPS CAGR and ROE profile of the consolidated entity remains at 30%+ and 25%+, respectively, any derating should be limited. Solar will likely move from a net cash entity to net debt:equity on consolidation of 1.2x in FY28, but this should quickly reduce to 0.5x by FY30 given strong cash flows,” Jefferies said.
Also read | Solar Industries to acquire South Africa’s Omnia for Rs 12,951 crore in biggest global expansion push
Nuvama on Solar Industries share price
Nuvama also has a ‘Buy’ call on the shares of Solar Industries with a target price of Rs 23,435 apiece, implying around 22% upside potential from the stock’s previous closing price. The brokerage said the acquisition will give Solar Industries enhanced control over Ammonium Nitrate sourcing, currently being externally procured, while expanding global reach.
Although its defence mix falls to 22% (post-deal) versus 27% of FY26 revenue, Nuvama views the debt-funded deal as pro-growth and self-financed.
Solar Industries share price
Solar Industries shares have dropped around 17% in one week and 7% in a month, but overall jumped more than 53% in 2026 so far. The stock has gained 27% in one year.
In the longer term, the shares of the explosives-maker have delivered explosive returns for its shareholders, rallying over 300% in three years and around 850% in five years. The company currently has a market capitalisation of around Rs 1.68 lakh crore.
Also read | Solar’s $1.3 bn bet is a turn for India’s defence-industrial complex
Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.
Yes. Corporate subscriptions are available for teams and organisations, with discounted rates as user numbers increase. Pricing starts from $1,625 + GST per user.
Get in touch
to discuss the right option for your organisation.
Business News subscriptions are used by executives, investors, consultants and professionals who need to stay informed and make better decisions about the WA market. When you subscribe you’ll get
- Unlimited access to WA’s most trusted business journalism
- Data & Insights — detailed profiles of WA companies, people, projects and deals
- MyBN — a personalised feed based on the companies, people and sectors you follow
- Special publications and industry reports
- Daily and weekly email newsletters
Data & Insights is a research tool built specifically for the WA market. It draws on more than 30 years of Business News reporting, updated regularly to reflect what’s happening now. Use it to:
- Look up detailed profiles of WA companies, including financials, directors and ownership
- Find decision-makers and track their career movements
- Research live and completed projects across WA industries
- Monitor deals, appointments and market activity
- Access industry rankings and league tables
Data & Insights is updated daily by our dedicated research team, which uses the latest announcements, ASX filings and editorial coverage to keep our person, company, list and project records up to date.
Business News welcome all opportunities to make our dataset accurate, complete and current, so if you have an update request, please email the team at
general@businessnews.com.au, and we’d be happy to assist.
MyBN
is part of every subscription. It’s your personalised view of Business News. You can follow the companies, people, sectors and projects that matter to you, and get a news feed and alerts tailored to your interests. You can save articles to read later and retain only what you need.
Only subscribers have full access to all content on the Business News website.
If staying informed about the WA economy is part of your job, and/or you’re looking for networking opportunities in WA, Business News is built for you.
Business News subscribers are:
- Executives and directors tracking competitors, clients and market movements
- Investors and advisers researching companies, deals and industry trends
- Consultants and professionals staying across sectors relevant to their clients
- Business owners looking for leads, context and market intelligence
Most Business News publications cover national or global markets. Business News is focused entirely on Western Australia, which means the journalism, the data and the intelligence are all built around WA companies, people and projects — not adapted from a national feed. Data & Insights, included with every subscription, combines more than 30 years of WA-specific editorial research with live business data. There’s no comparable product for the WA market.
The Morning Digest Email provides a comprehensive wrap of the major headlines, relevant to WA business, and includes with a snapshot of the overnight news covering oil, gold and ASX-listed companies.
The Afternoon Wrap Email focuses on the news covered by our team of journalists during the course of the working day, including exclusive stories and analysis, all of which relates to WA business and the local economy.
The BN Weekender Email contains a wrap of the Business News from the week that was, highlighting the top stories in each area of WA business.
Sign up for free.
We’re happy to help.
Get in touch
and our team will come back to you.
K+S: The Upswing Is Not Indicative Of A Longer-Term Upside
Business
Sensex rises 400 points, Nifty nears 23,250 as investors await Fed meeting outcome. What to expect?
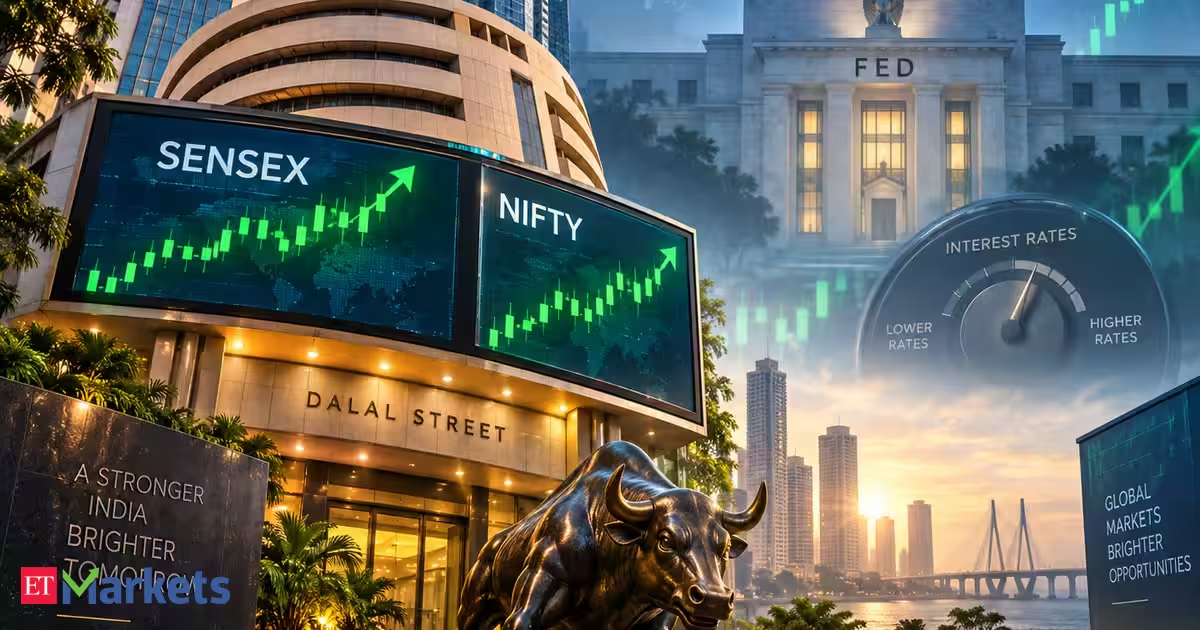
The Sensex rose over 400 points to above 74,400, while the Nifty 50 gained around 128 points to 23,247 as of 10:45 am. Broader markets remained weak, with the Nifty Smallcap 100 and Nifty Midcap 100 falling up to 0.8%.
Also read | Why Sensex crashed over 1,400 pts from day’s high, Nifty closed below 23,150 on Tuesday
Axis Bank, M&M, ITC and SBI shares rose around 2% to lead gains on Sensex; Reliance Industries, BEL, Adani Ports, HCL Technologies and Sun Pharma shares gained over 1% each. Bucking the trend, TCS, Eternal, NTPC and Tata Steel shares fell around 1% each.
Among the sectors, Nifty FMCG and Nifty PSU Bank indices gained more than 1% each, while Nifty IT, Nifty Metal, Nifty Pharma and few other indices slipped into the red. The overall market breadth remained negative, with NSE seeing 2,082 declines against 1,170 advances, while 108 stocks remained unchanged.
What lies ahead for Dalal Street?
The Federal Reserve is all set to announce the outcome of their FOMC meeting on Wednesday. The American central bank will likely raise its interest rate today, and deliver at least one more hike by the end of March, according to a majority of economists polled by Reuters.
Meanwhile, the weak market construct continues with elevated US bond yields and high crude prices contributing significantly to the weakness, said VK Vijayakumar, Chief Investment Strategist at Geojit Investments. So long as these two crucial macros remain high it would be unrealistic to expect a strong rebound in the market, according to the analyst.He noted that FIIs have been sellers in the market during the last 5 days, and with the US 10-year yield at 5%, they are likely to sell at every small rally in the market. In today’s meeting, the Fed is most likely to raise interest rates by 25 bps. However, this is unlikely to impact the market since it is already discounted by the market, Vijayakumar said, adding that more market-moving factors will be the Fed commentary on the evolving macro-outlook and the likely rate action going forward.
“Even though the market is weak there are stock-specific opportunities in this market. Appointment of a new MD and CEO for HDFC Bank expected soon and the new MDR norms for digital transactions introduced by the NPCI are significant events that can influence the markets,” he added.
Technical view on Nifty
As feared, Nifty’s inability to float above 23515 has invalidated the upside attempt, said Anand James, Chief Market Strategist at Geojit Investments. He noted that the consequent days of closing below the lower Bollinger Band as well as yesterday’s bearish engulfing candle reflect strong bearishness but also point to peaking fear.
“We are still within the support band of 23,260-23,000, lending hopes of a revival, but a close below the same will bring 22,600-21,800 into the radar,” the analyst said, explaining the technical charts for the benchmark index.
Also read | Stocks to buy: BofA lists 22 Indian stocks as key picks as it turns bullish on Nifty after 2 years
Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.

LISA – ‘MONEY’ 2023 WORLD TOUR [BORN PINK] KYOCERA DOME OSAKA
Barclays cuts Cellectis stock rating on gene editing concerns

AI ‘net negative’ for crypto, fueling attacks and costs



-

 Fashion5 days ago
Weekend Open Thread – Corporette.com
-

 Business6 days ago
Micron Stock Climbs Above $1,031 as AI Memory Crunch and a $50 Billion Outlook Fuel the Rally
-

 Tech3 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Business6 days ago
AMD Stock Climbs After Management Lifts 2027 Data Center Outlook Toward $70 Billion in AI Sales
-

 Crypto World5 days ago
XAG/USD: Silver’s Short-Term Rally Meets Its Moment of Truth
-

 Business5 days ago
10 Most-Streamed Songs On Spotify In 2026 So Far, Led By Ella Langley’s Dominant Run On The Charts This Year
-

 Crypto World6 days ago
2 Chip Stocks Broke Out This Week. Neither Was Nvidia
-

 Tech6 days ago
Battery life is the only iPhone 18 Pro and iPhone Duo upgrade I care about. Apple didn’t disappoint
-
 Crypto World6 days ago
Pi Network ships Protocol 27 on a network with 14 million users and zero DeFi
-

 Crypto World5 days ago
OKX launches 10x OpenAI, Anthropic X-Perps in Europe
-

 Crypto World5 days ago
Diesel Tops $6 a Gallon for the First Time as 28 States Set Records
-

 Tech6 days ago
Apple Watch Ultra 4 vs Watch Ultra 3: Should you really spend another $799?
-

 News Videos5 days ago
Facing Financial Fears
-

 Crypto World6 days ago
Bitcoin price risks $70K if $78K neckline breaks
-
 Entertainment6 days ago
Case Sees Major Update As Jury Deliberations Begin
-

 Business3 days ago
Rivals Sam Altman and Elon Musk Rally Behind Dario Amodei’s Call for a Slowdown in AI Development
-

 Crypto World2 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-
Crypto World5 days ago
Ethereum Price Analysis: Consolidation at $2.5K Tests Momentum as On-Chain Activity Surges
-
Crypto World7 days ago
Ripple Price Prediction: What to Expect for XRP as a Major Macro Week Approaches
-
 Business6 days ago
Western Digital Slips 2.7% as AI Storage Rally Cools After Record Cash and Guidance
You must be logged in to post a comment Login