
Business
Uber ordered to pay $40 million after driver leaves passenger on freeway

Check out what’s clicking on FoxBusiness.com.
Uber has been ordered to pay $40 million in the 2023 death of a Southern California woman who was struck and killed by a vehicle after her rideshare driver kicked her out on the side of a freeway.
Retired Judge Richard Stone, an arbitrator, rejected Uber’s argument that it “merely operates a technology platform” and that it was shielded from “vicarious liability for the negligence of its drivers,” according to Panish Shea Ravipudi, the law firm representing the family of 23-year-old Emily Normandin-Parker.
“Emily did everything Uber tells riders to do. She made the responsible choice not to drive, and we trusted Uber to get her home safely. That trust cost our daughter her life,” parents Carol Normandin and Ken Parker said.
HERTZ, UBER TEAM UP TO BUILD ROBOTAXI FLEETS IN MAJOR MOBILITY PUSH
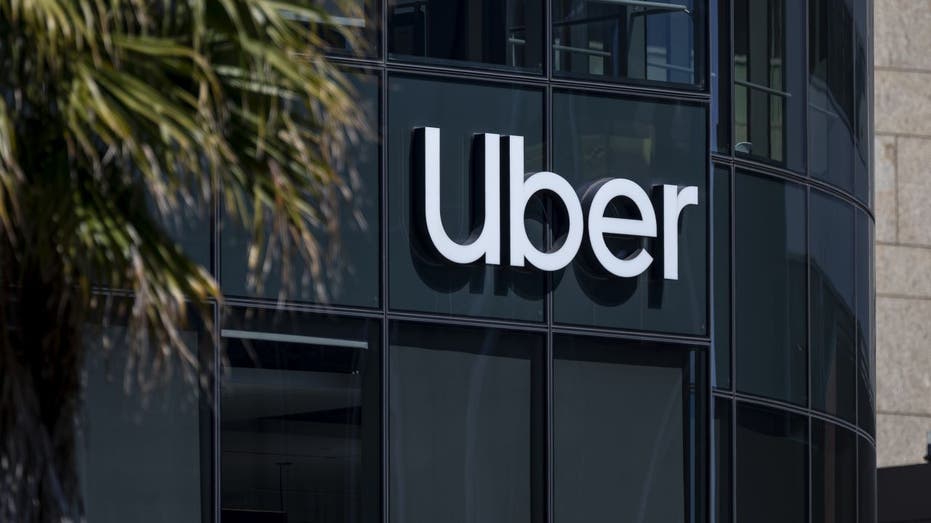
Uber headquarters in San Francisco. The rideshare giant has been ordered to pay $40 million over the 2023 death of a woman who was left stranded on a busy freeway. (David Paul Morris/Bloomberg via Getty Images / Getty Images)
Normandin-Parker, a 2020 UCLA graduate, was out with her friends in Costa Mesa when she called an Uber to take her to her Laguna Beach home with her friend, Luna Moore. They booked a rideshare on the Uber app.
Once in the vehicle, Moore vomited in Vu Tran’s car, prompting him to illegally stop at a “gore point,” which separated an exit ramp from the freeway, on State Route 73 instead of safely exiting to a safe location, the law firm said.
UBER, RIVIAN INK $1.25B DEAL TO PUT THOUSANDS OF ROBOTAXIS ON US STREETS
Tran ordered both women out of the car and demanded a cleaning fee. Emily, who was intoxicated, was left stranded alongside multiple lanes of freeway traffic, where she was struck and killed.
Instead of calling 911, Tran left and requested that Uber charge Normandin-Parker’s account a cleaning fee. Stone found that Tran “needlessly placed” his passengers in danger and showed “far more worry for his new car than he did for his passengers.”
“No family should have to suffer the loss of a child, and our thoughts continue to be with the Normandin-Parker family,” a company statement said. “We have continued to strengthen our approach to safety over the years, through new technology, policies and safeguards informed by safety experts, including additional guidance to drivers about avoiding drop-offs in unsafe locations. Our work on safety is never finished, and we will continue looking for ways to help make the platform safer.”

Nokia Maps is seen on a smartphone in front of a displayed logo of Uber in Zenica, Bosnia and Herzegovina, in this May 8, 2015, photo illustration. (Reuters/Dado Ruvic/File Photo / Reuters)
GET FOX BUSINESS ON THE GO BY CLICKING HERE
Parents can watch their teen’s Uber ride through the driver’s front-facing smartphone camera when live video is enabled.
Prior to the deadly incident, Tran had completed 6,000 trips with a 4.96 rating, without a single incident involving unsafe drop-offs, freeway stops or rider injury, Uber said.


Passage Research focuses on identifying variant perception through a blend of fundamental analysis and alternative data. The research process combines detailed financial modeling with real-time datasets to underwrite earnings power, margin durability, and forward expectations.The author has spent over a decade on Wall Street, most recently spending the last five years working in the hedge fund industry as an analyst. Typical coverage spans consumer, TMT, industrials and special situations, with an emphasis on asymmetric risk/reward and catalyst-driven opportunities.
Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

Gam CEO Jeffrey Priest buys $93,840 of preferred stock
Starting the lightning round on September 14, when a caller inquired about SentinelOne, Inc. (NYSE:S), Mad Money host Jim Cramer remarked:
No, look, I think you don’t need, look, my Charitable Trust owns both Palo Alto and CrowdStrike. It’s already too many. I think either one of those two is superior to letter S.
The latest results show a large difference in scale. SentinelOne’s fiscal second-quarter 2027 revenue rose 21% year over year to $292 million, while annualized recurring revenue increased 22% to $1.218 billion. Palo Alto Networks, Inc.’s (NASDAQ:PANW) fiscal fourth-quarter 2026 revenue rose 34% to $3.41 billion, while Next-Generation Security ARR increased 63% to $9.10 billion. Additionally, we have discussed CRWD in our recent article, “Jim Cramer Highlights CrowdStrike (CRWD) as AI Security Concerns Lift Cybersecurity Stocks.“

SentinelOne is Improving While PANW Generates More Cash
SentinelOne, Inc. (NYSE:S) non-GAAP operating margin reached 10% in fiscal Q2 2027, up from 2% a year earlier, while its GAAP operating margin improved to negative 31% from negative 33%. The company guided for fiscal third-quarter revenue of $309 million to $311 million and full-year revenue of $1.202 billion to $1.207 billion.
Palo Alto Networks, Inc. (NASDAQ:PANW) reported approximately $1 billion of non-GAAP operating income in its fiscal fourth quarter of 2026, compared with $768 million a year earlier. Adjusted free cash flow reached approximately $1.3 billion, while GAAP operating income was $172 million versus $497 million a year earlier. Palo Alto CEO Nikesh Arora said in the September 1 earnings release that the latest advances in AI are “elevating cybersecurity to the top of the CIO priority list.”
Bear Case for SentinelOne and PANW
For SentinelOne, Inc. (NYSE:S), the bear case is that improving non-GAAP profitability has not yet translated into GAAP profitability, while the company operates in a cybersecurity market it describes as intensely competitive, fragmented and rapidly evolving. The company says SentinelOne must continue adapting its platform as technology and customer requirements evolve, and that failing to respond effectively could weaken its competitive position and hurt revenue growth. That challenge is visible in its latest results: GAAP gross margin fell to 72% from 75% a year earlier, non-GAAP gross margin declined to 77% from 79%, and the company still reported a GAAP operating margin of negative 31%.
For Palo Alto Networks, Inc. (NASDAQ:PANW), the bear case is about margin pressure as the company expands its platform. Total gross margin fell to 70.4% in fiscal 2026 from 73.4% a year earlier, while subscription and support gross margin declined to 69.2% from 72.5%. PANW said the decline was primarily due to higher amortization of intangible assets from acquisitions and increased costs related to its cloud-based offerings. The company also warns that intense competition, including lower pricing and broader bundled offerings from rivals, could pressure revenue and gross margins.
Richtech Robotics: Plenty Of Cash, But Growth Remains Elusive
Extra Space Storage: A Great REIT At The Wrong Time

The Sunday Investor is focused exclusively on U.S. Equity ETFs. He has a strong analytical background, has received a Certificate of Advanced Investment Advice from the Canadian Securities Institute, and has completed all the educational requirements for the Chartered Investment Manager designation.Having covered hundreds of ETFs on Seeking Alpha, The Sunday Investor has developed a complex, proprietary ETF Rankings system which he shares on his website, etf-rankings.com. Nearly 1,000 ETFs receive individual factor scores covering costs, liquidity, risk, size, value, dividends, growth, quality, momentum, and sentiment, which feed into an easy-to-understand composite score from 1-10. The Sunday Investor is always active in the comments section in his articles – please don’t hesitate to reach out via comment in any article or by visiting etf-rankings.com. Happy Investing!
Analyst’s Disclosure: I/we have a beneficial long position in the shares of SCHD, SPY either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
FVD is a low-risk dividend-themed ETF, but its risk-adjusted returns and performance during short, somewhat deep drawdowns, isn’t better than peers DGRO and SCHD.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

Neonc Technologies CFO sells $16,809 in company stock

Bitcoin jumps above $81k as short squeeze offsets rate and regulatory pressure

Cardano Climbs 10% In Bullish Trade

With combined experience of covering technology companies on Wall Street and working in Silicon Valley, and serving as an outside adviser to several seed-round startups, Gary Alexander has exposure to many of the themes shaping the industry today. He has been a regular contributor on Seeking Alpha since 2017. He has been quoted in many web publications and his articles are syndicated to company pages in popular trading apps like Robinhood.
Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

‘They better move quickly’: A shape-shifting Pebble Beach has players talking | News

Single-Phase Direct Liquid Cooling Is Proven for the Next Decade of Ultra-Dense Compute

Prologis Stock Is High Quality, But Too Rich For My Taste (NYSE:PLD)




-

 Tech6 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Crypto World4 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-

 Crypto World2 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World7 days ago
Can AI Build a Startup in 72 Hours? Elon Musk's Team Will Livestream the Test
-

 Crypto World3 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-

 Crypto World5 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-

 Business6 days ago
Rivals Sam Altman and Elon Musk Rally Behind Dario Amodei’s Call for a Slowdown in AI Development
-
 NewsBeat5 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World5 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-

 Crypto World7 days ago
Robinhood Chain Never Stopped But its Blobs Did Stop Reaching Ethereum For 14 Minutes
-

 Crypto World4 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-

 Business7 days ago
Marvell: Most Potent Setup Of The AI Factory Decade
-
Business5 days ago
SK Hynix ADRs Fall More Than 6% as Memory Rally Breaks on Fears of Slower AI Spending
-

 Crypto World4 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-

 Crypto World4 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
-
Crypto World4 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
-
 Crypto World7 days ago
Bitcoin ETFs lose $462.7M as Ethereum funds gain $196.9M
-

 Crypto World5 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-
 Fashion10 hours ago
Weekend Open Thread: Talbots – Corporette.com
-
 Crypto World5 days ago
AI Safety Burden Falls on Chief Executives as Trump Prioritizes China Race
You must be logged in to post a comment Login