Crypto
Crypto can serve as derivatives collateral. What happens when its price falls?

The CFTC has updated its guidance on tokenized customer-fund investments and blockchain records, putting the focus back on the rules that already let some futures intermediaries take crypto as margin. A fall in the token’s price sets off several different calculations. The crucial distinctions are whose asset it is, which haircut applies, and who must fill a shortfall.
Summary
- The CFTC updated its crypto activity FAQs on September 24, 2026, addressing 2 subjects: tokenized investments and blockchain records.
- February’s Staff Letter 26-05 lets qualifying intermediaries count certain customer crypto as margin under specified conditions.
- The staff letter requires at least a 20% haircut for most non-stablecoin crypto in specified intermediary calculations.
- A $100,000 token position subject to a 20% haircut starts with $80,000 of recognized value.
- The earlier FAQ gives clearinghouses discretion to set initial-margin haircuts and review them at least monthly.
The Commodity Futures Trading Commission has updated its crypto activity FAQs as regulated derivatives firms work with tokenized assets and digital records.
The agency’s September 24 release says the latest additions address investments of customer funds in tokenized forms of permitted investments and blockchain recordkeeping. It points back to the March 20 FAQs, Staff Letter 25-39 on tokenized collateral and Staff Letter 26-05 on digital assets accepted as customer margin. The announcement does not say that September 24 created an unrestricted new right to pledge any token against any derivatives trade. The collateral permission, and its conditions, predate the new release.
The CFTC’s existing crypto guidance was covered by crypto.news in March. Its practical question has become more urgent as firms put digital assets into structures usually associated with cash and government securities. Suppose a customer posts bitcoin against a futures position and bitcoin falls while the futures position loses money. A mark on the coin and a mark on the trade occur together. The first reduces the value of security available to the account; the second raises what the account needs.
The regulatory papers separate these movements. Staff Letter 26-05 concerns what a futures commission merchant, or FCM, may count while evaluating a customer account and segregated funds. A derivatives clearing organization, or DCO, sets its own haircut for assets accepted as initial margin under separate rules. A 20% charge on an intermediary’s proprietary bitcoin inventory is a third issue. Applying one number to all three would give the reader a false answer.
September’s FAQ update is narrower than the collateral headlines
CFTC Release 9303-26 names the Market Participants Division, Division of Market Oversight and Division of Clearing and Risk as the staff groups publishing the update. The release specifies two matters: tokenized versions of investments already permitted for customer funds and use of blockchain technology to satisfy recordkeeping requirements. It traces the FAQ series to March 20, 2026. That chronology is the first check on claims circulating about a new collateral rule.
The original March FAQs explicitly say an FCM may not invest customer funds in payment stablecoins under Regulation 1.25 merely because it can accept a qualifying stablecoin as customer margin. An FCM may, under Staff Letter 26-05, place its own payment stablecoins into segregated customer accounts as residual interest. These are different sources of funds and different transactions. Buying tokens with segregated customer cash is not interchangeable with receiving a customer’s token as a margin deposit.
The distinction carries into the September update. A tokenized form of an investment already permitted under Regulation 1.25 is a question about the wrapper on an eligible underlying asset. It is not a general license for an intermediary to use customer cash to buy bitcoin or a payment stablecoin. Without the full text of the updated FAQ attached to the CFTC’s public release as reviewed for this feature, the release supports only its stated scope. We do not attribute new haircut values or new eligibility categories to yesterday’s update.
An agency staff FAQ is not an amendment to every CFTC rule. Staff Letter 26-05 is a no-action position: the Market Participants Division says it will not recommend enforcement against an FCM acting within specified conditions. It does not repeal the customer segregation provisions of the Commodity Exchange Act, and it does not promise that a DCO will accept every coin. The original letter was issued following a request by Coinbase Financial Markets and was reissued on February 6, 2026, to clarify that a national trust bank may qualify as a payment stablecoin issuer for its purposes.
The CFTC’s latest tokenization comments show the policy context. Chairman Michael Selig has discussed round-the-clock markets and tokenized collateral; an agency’s interest in those markets does not eliminate the ordinary margin test. A clearinghouse still has to decide whether a proposed collateral asset has sufficiently low credit, market and liquidity risk for its clearing program.
The customer owns the token, but its recognized value can move
A futures customer places margin with an FCM, which carries the customer’s trading account. Federal segregation rules require the intermediary to account for customer property separately from the firm’s own assets. Staff Letter 26-05 lets an FCM count certain non-security digital assets, including payment stablecoins, when determining whether the customer account is undermargined and performing specified segregation calculations, provided it follows the letter’s conditions.
The FCM does not simply copy the wallet’s displayed market value into those calculations. For a payment stablecoin it determines fair market value and applies a haircut under its risk policies. For other qualifying digital assets the letter calls for a haircut of at least 20% for the specified calculations, subject to the letter’s particular exception for collateral and a position both based on and denominated in the same asset. The FCM’s relevant valuation or a clearing organization or trading venue’s measure may differ depending on the calculation. The text matters more than a slogan that bitcoin is accepted at 80 cents on the dollar everywhere.
Here is a deliberately simple illustration, not a report of an actual account. A customer posts bitcoin worth $100,000, and the relevant FCM calculation applies a 20% haircut. Recognized value is $80,000. If bitcoin’s spot value then falls by 15% to $85,000 and the haircut remains 20%, recognized value becomes $68,000. The haircut alone did not jump; market value fell. The account has lost $12,000 of recognized collateral value without a single bitcoin leaving custody.
Now assume the relevant margin requirement for the futures position stays at $75,000. Before the bitcoin move, $80,000 of recognized collateral exceeds the requirement by $5,000. After the move, $68,000 leaves a $7,000 shortfall. The gap changed by $12,000. If the position itself simultaneously loses $10,000, the economic pressure becomes more severe, but the precise cash call depends on the account’s other balances, settlement, portfolio margin and the FCM’s rules. The illustration deliberately holds those factors fixed to show one moving part at a time.
It follows that a 20% haircut is not an insurance policy against a 20% fall. Starting with $100,000, a 20% haircut gives $80,000 of credit. If spot subsequently drops 25%, the asset is worth $75,000 and its value after the same haircut is $60,000, a $20,000 decline in recognized credit. The ratio applies to the new price each time. Calling the initial discount a guarantee would obscure the mechanics of margin calls.
The hypothetical can be run in the other direction to see what would invalidate the concern. If the token price is flat, the recognized collateral value stays at $80,000 under the fixed 20% assumption; a fall in the trader’s futures position could still create a margin deficit. If the futures position earns enough to offset a decline in the pledged token, the combined account may remain above its required margin even as the bitcoin collateral loses value. The public letter does not allow an outsider to infer a margin call from a token price alone. Account equity, product exposure and the firm’s house margin are needed.
Nor is the haircut necessarily static. The 20% in the letter is a minimum for the specified non-stablecoin FCM calculations, not a cap. If the FCM’s risk policy required 30%, a $100,000 holding would initially count as $70,000. After a 15% decline in the asset price, it would count as $59,500. Changing the assumed discount from 20% to 30% while holding the post-decline price at $85,000 would reduce recognized value by another $8,500. A fall in spot and an increase in the discount can therefore compound; whether a firm changes its policy in a real episode requires its actual rules or an announcement, neither of which follows from the CFTC letter alone.
The same caution applies to a payment stablecoin that moves below its intended peg. The letter instructs a firm to use fair market value and its risk policy, with an appropriate haircut, when counting a payment stablecoin. A token trading at 98 cents does not retain one dollar of regulatory collateral value merely because its issuer promises redemption at par. The recognized amount would depend on the policy’s treatment of market price, redemption access and the relevant haircut. It would be wrong to use the 2% proprietary capital charge as an automatic discount on a customer’s stablecoin margin: the figure addresses the firm’s own position in a different calculation.
The letter has a narrower exception when a customer posts a non-stablecoin digital asset to support a contract both based on and denominated in that same asset. For the permitted offset against the deficit in that specific contract, the applicable clearing organization or foreign clearing organization’s haircut alone may govern. The exception does not turn that asset into universal collateral for every unrelated contract. For an account holding more than one kind of derivatives exposure, the FCM must still apply the relevant requirements to the exposures outside the exception.
The clearinghouse sets a separate haircut
The March CFTC FAQs answer the DCO question directly. A clearinghouse may accept crypto assets, including qualifying payment stablecoins, as initial margin if the assets meet Regulation 39.13(g)(10), which limits accepted assets to those with minimal credit, market and liquidity risks. Regulation 39.13(g)(12) makes the DCO responsible for setting haircuts that account for those risks, including stressed market conditions, and for reassessing them at least monthly.
No universal CFTC clearinghouse bitcoin haircut appears in that answer. A venue might apply a larger discount, restrict a coin, impose concentration limits or decline it under its risk rules. The FCM’s treatment of a customer’s margin and the DCO’s treatment of collateral posted to the clearinghouse operate at different links in the chain. An individual can see a token in an FCM account without the clearinghouse necessarily holding that same token as its own initial margin. The FCM may satisfy clearing obligations in another accepted form.
The easiest error is to import the 20% proprietary capital charge from Question 6 of the March FAQ into Question 8 about a DCO’s initial-margin haircut. Question 6 says the CFTC staff would not object if an FCM used a minimum 20% capital charge for its own inventory positions in bitcoin or ether, and 2% for its own payment stablecoins. Those are regulatory net-capital deductions on the firm’s property. Question 8 requires the DCO to choose its own haircut for initial margin. Question 1 separately tells the FCM how to treat customer property using the conditions in Staff Letter 26-05.
Three percentages might happen to coincide in one arrangement. They still come from different rules and belong to different balance sheets. The comparison is especially relevant when an FCM tries to meet a shortfall with its own stablecoins. Staff guidance permits proprietary qualifying payment stablecoins as residual interest in a segregated customer account but does not permit the firm to substitute proprietary bitcoin or ether for that purpose. The 2% capital charge on proprietary stablecoin holdings is a separate firm-level cost.
The market for tokenized funds supplies a related example. A fund share represented on a blockchain can carry the legal and economic rights of a conventional eligible fund share, yet the speed of moving a token is only one part of its margin value. Fund redemption terms, ownership records, settlement restrictions and who can receive the shares remain relevant. The CFTC’s tokenized-collateral guidance focuses on equivalence of rights, not merely on whether a blockchain transaction confirms quickly.
Franklin Templeton’s tokenized BENJI fund shares illustrate how a fund token can sit inside securities and custody structures even while its ownership record uses a blockchain. Whether any such share is accepted in a particular derivatives margin program depends on that program’s rules. The existence of a token and a large pool of underlying government assets does not show that a DCO has approved it as collateral.
A falling price reaches three balance sheets
When a customer’s bitcoin collateral declines, the customer faces the first exposure: it must keep its account adequately margined under the firm’s and venue’s rules. A deficit can lead to a call for more collateral, reduced positions or liquidation under the applicable agreements. An FCM that serves as intermediary must monitor its own exposure and keep customer segregation intact. The clearinghouse monitors its members and the assets it accepts as initial margin. They are linked, but their duties are not identical.
The Commodity Exchange Act and CFTC regulations prohibit an FCM from using one customer’s property to carry another customer’s positions. Staff Letter 26-05 describes why FCMs may have to place their own funds into segregation equal to customer undermargined amounts, including deficits. That obligation is the reason a rapid collateral move is not merely an app notification for one trader. An intermediary must account for it in a protected customer-funds system whose balance changes with the value of pledged assets.
Time complicates the chain. The March FAQs say the FCM’s daily segregation reports compute separate schedules as of the close of each business day. Crypto prices can move continuously. A firm may monitor and call margin more often under its own risk policies, but the existence of daily regulatory reporting should not be mistaken for a token price that changes only once daily. Nor does a blockchain timestamp itself establish the legal value accepted by a clearing organization when the relevant market becomes thin.
An FCM’s own contribution to a segregated account deserves a separate explanation. Customer property is protected by segregation, but if a customer account is undermargined, the firm may have to put its own money into the segregated pool so the protected total is not short. The margin call issued to a customer and the firm-level deposit into segregation can occur on different schedules. A customer may later cure a deficit or close a position; the firm’s immediate duty to preserve required segregation does not wait for an optimistic prediction about that customer’s next transfer. Staff Letter 26-05 addresses how the FCM counts the qualifying crypto when it determines that amount. It does not authorize using another customer’s surplus as a substitute for the firm’s money.
In practice, the customer agreement can set a house margin above a clearinghouse minimum. A trader looking only at the DCO’s public haircut or product margin schedule may therefore understate the collateral demanded by its FCM. Conversely, a clearinghouse’s decision to recognize a token does not force every intermediary to offer that token to customers. Those choices can be checked against a particular firm’s disclosures, but the CFTC’s general FAQ does not supply a single industrywide customer contract.
The staff letter first limited an FCM relying on the no-action position to payment stablecoins, bitcoin and ether as customer margin for its initial three months. It required notices of significant operational or cyber problems during that period and weekly reporting of amounts held by asset and account class. After the initial period, an FCM may accept other qualifying crypto assets if it meets the letter’s continuing conditions; it must submit revised risk policies before accepting some assets. Reporting and the initial restriction have different start and end mechanics. It would be inaccurate to claim all FCMs became eligible to accept every token on the same calendar date.
A second 2026 staff action addressed customer crypto sent to foreign brokers for certain foreign futures arrangements. The location and reuse rights of pledged property can change in such a structure. It should not be folded into the domestic clearinghouse example without checking the relevant letter and customer agreement. Asset custody, margin recognition and legal claims need to be traced for the particular route a trader uses.
A strong case for crypto collateral still needs limits
The strongest affirmative argument comes from the CFTC’s own pilot and subsequent staff work. In December 2025, acting chair Caroline Pham launched a digital-asset pilot that included bitcoin, ether and tokenized collateral in derivatives markets with reporting and monitoring requirements. A trader who already holds these assets may avoid selling them simply to create cash margin. Tokenized fund shares may preserve claims on an eligible investment while making transfers faster within approved systems. The staff letters set conditions because officials saw a use case they were prepared to test.
Neither faster movement nor a public ledger cancels market risk. Regulation 39.13(g)(10) still asks a DCO to assess credit, market and liquidity risks. CFTC Staff Letter 26-05 still requires valuation policies and deductions for an FCM relying on relief. A clearinghouse can consider stressed markets when setting a haircut. A token whose transfer settles promptly can still have a falling market price or a legal ownership claim that takes time to verify. The regulatory system treats those as separate questions.
There is a measurable distinction between holding a token as customer collateral, holding an FCM’s token as firm inventory, and using a tokenized security as an investment of customer cash. The September 24 FAQs concern the third of these subjects and blockchain records. The March FAQs and February letter speak to the first two. A story that merges them would incorrectly imply a new permission or an official 20% haircut across every venue.
Limits remain. The CFTC releases reviewed here do not show how many FCMs filed a notice, how much bitcoin they currently hold as collateral, or a definitive haircut for a named clearinghouse’s latest program. The $100,000 example shows the math of a fixed haircut and a market move; it is not a forecast of liquidations. An actual customer’s result requires its account records, product margin schedule, collateral mix and agreements.
What to watch
- Updated CFTC FAQs: Check the published text for the exact treatment of tokenized permitted investments and blockchain records.
- FCM collateral terms: Look for each firm’s accepted coins, customer valuation policy and house haircuts.
- DCO margin schedules: Check the clearinghouse’s eligible assets and its own haircut for each accepted token.
- FCM notices and disclosures: Identify firms publicly reporting reliance on Staff Letter 26-05 without assuming all intermediaries participate.
- Token price and required margin: Compare both at the same timestamp to see whether a customer’s recognized collateral still covers its obligation.
The March FAQ specifies that a DCO must reassess whether its collateral haircuts remain appropriate at least monthly. Its staff answer leaves the actual discount to the clearinghouse under Regulation 39.13(g)(12).
FAQ
Did the CFTC first allow bitcoin as derivatives collateral on September 24?
No. September’s release updates FAQs on tokenized customer-fund investments and blockchain records. The earlier Staff Letter 26-05 describes the no-action conditions for FCMs accepting certain customer crypto as margin.
Is the bitcoin collateral haircut always 20%?
No. The letter calls for at least a 20% haircut in certain FCM calculations for non-stablecoin assets, subject to a specified same-asset exception. A DCO sets its own initial-margin haircut based on risk.
What happens to $100,000 in bitcoin margin after a 15% price drop?
With a fixed illustrative 20% haircut, its recognized value moves from $80,000 to $68,000. The actual margin call depends on the account and product rules.
Is the 20% FCM capital charge the same as a clearinghouse haircut?
No. The March FAQ’s 20% proprietary charge concerns an FCM’s own bitcoin or ether inventory. A DCO sets a separate haircut on initial margin that it accepts.
Can a futures firm use customer cash to buy stablecoins?
The March FAQs say the no-action letter does not expand Regulation 1.25’s list of permitted investments. The staff distinguishes investing customer funds from accepting customer stablecoins as margin.
Can an FCM place its own bitcoin into customer segregation?
The FAQ says the letter permits proprietary payment stablecoins as residual interest under its conditions, not proprietary bitcoin or ether. Customer-owned qualifying bitcoin can be treated separately as margin.
Who fills a shortfall when crypto collateral falls?
The customer must maintain its required account margin under the applicable terms. The FCM must meet its own segregation and clearing obligations and cannot use another customer’s property to carry that deficit.
Does faster blockchain settlement remove collateral risk?
No. CFTC requirements still address asset valuation, stressed liquidity and ownership rights. This is educational analysis, not investment advice.
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Figures reflect regulatory filings and reporting available at the time of writing and change with each disclosure. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 25, 2026.
U.S. dollar-pegged stablecoin Tether is a go-to tool for the Iranian government to bypass sanctions, a new report from a group of Senate Democrats said.
Democrats on the Senate’s Homeland Security and Governmental Affairs Committee’s Permanent Subcommittee on Intelligence published a report Monday laying out the argument that Tether plays a key role in allowing Iran to conduct transactions that skirt international sanctions.
“Iran’s cryptocurrency-based shadow banking network has processed significant volumes of funds and implicates various Iranian interests,” the report said, adding that Tether has “repeatedly failed” to block Iran-connected wallets.
“USDT has become a significant financial lifeline within Iran’s shadow banking network,” the report said.
When Tether does freeze wallets, it sometimes takes weeks, but the company also sometimes responds to requests without actually blacklisting wallets, the report claimed.
“Prior to 2024, Tether did not comprehensively and consistently freeze wallets designated by counter-terrorism agencies and continues to fail to proactively block clearly illicit wallets,” the report said. “This absence of deterrence invited abuse: terrorist organizations such as Hamas shifted from transacting in Bitcoin and a mix of cryptocurrencies to promoting USDT.”
Elon Musk’s Grok AI predicts an extremely bullish price for Ripple (XRP) by January 1, 2027, that will blow the minds of even the most dedicated members of the Ripple Army.
If you’re holding a sizeable bag of XRP USD, you may want to sit down before reading this. Grok claims that $25–$40 is achievable by 2027, with a stretch target of $50+ under the assumption of a full-blown crypto bull market returning and being supercharged by an unprecedented institutional catalyst.
XRP currently trades near $1.50–$1.52 as of September 28, 2026, down nearly -3% over the past 24 hours and with a daily trading volume of $3.5Bn, up from $3.2Bn the day prior.
This outlook is extreme and leans far beyond standard institutional forecasts. It assumes not only a strong late-2026 bull market driven by liquidity and risk-on conditions, but also a once-in-a-generation catalyst.
What is the Catalyst that Grok AI Predicts Could Spark an XRP Run Toward $40
Major central banks (including the Fed, ECB, Bank of Japan, and PBOC) announcing that the XRP Ledger will serve as a primary settlement layer for cross-border CBDC and tokenized asset flows, combined with large commercial banks being incentivized or required to hold XRP as a liquidity buffer, and revelations of massive sovereign wealth fund accumulation.
Under this highly speculative scenario, forced institutional demand collides with retail FOMO in a classic late-cycle mania, allowing XRP to move from the current ~$1.50 range through previous-cycle highs and into the mid-to-high double digits by early 2027.
This remains pure speculation and entertainment, not a base-case or even high-probability outlook. Crypto markets are extremely volatile, and the catalyst described above would require multiple extraordinary policy and institutional developments.
However, with Ripple’s case against the SEC dropped and its subsequent rise as a highly favored US-based digital asset company under President Trump, anything could be on the table for XRP if the perfect scenario aligns.
Got a Gut Feeling? It Could Pay Out 3.7X on Polymarket
Technical Analysis Supporting the Insane Grok AI XRP Price Prediction
On the higher timeframes, XRP has already established a constructive recovery base after reclaiming key moving averages from the mid-September lows near $1.25–$1.30. Price is consolidating in the $1.45–$1.55 region after testing highs near $1.63–$1.66.
In a normal bull market, a sustained break above $1.70–$2.00 would open the door to the prior cycle high near $3.65. Under the extreme institutional adoption scenario outlined above, that prior high would likely be cleared with significant force, triggering a series of measured-move and Fibonacci extension targets far beyond historical levels.
Aggressive projections from the multi-year base, combined with the kind of vertical price discovery seen in previous mania phases, could theoretically extend into the $25–$40+ zone if volume and momentum expand dramatically. RSI and momentum indicators would almost certainly reach deeply overbought levels during such a move, which is typical of parabolic advances.
Key nearer-term supports remain in the $1.40–$1.45 and $1.30 zones; holding those would keep the broader recovery structure intact while the market waits for (or prices in) any extraordinary catalysts.
Overall, while the current chart supports continued upside in a standard bull market, only an extreme surge in institutional demand and narrative intensity could justify the kind of multi-thousand-percent extension implied by the $25–$50 targets.
Earn $50 and Enter $300K Prize Draw on EdgeX
Maxi Doge Targets Early Mover Upside as XRP Tests Key Levels
While the Grok AI prediction of a potential 30x run for XRP is exciting, presale plays have a stronger track record of producing such returns. It does explain why attention keeps drifting toward presale-stage plays with smaller denominators.
Maxi Doge ($MAXI) is one of those plays. It is an Ethereum-based meme token built around a 240-lb canine mascot and a “1000x leverage” trading-culture identity. The presale has raised $4.8M at a current price of $0.0002841, with dynamic APY staking live for holders.
Standout features include holder-only trading competitions with leaderboard rewards and a Maxi Fund treasury earmarked for liquidity and partnerships.
The meme-first, gym-bro marketing angle (“never skip leg day, never skip a pump”) is endearing. The accumulation numbers suggest plenty of traders are picking a side.
Get Ahead of Next Meme Coin Launch Here
Discover: The Best Token Presales
The post Grok AI Predicts XRP Could Hit $40 in 2026 With Landmark Event appeared first on Cryptonews.
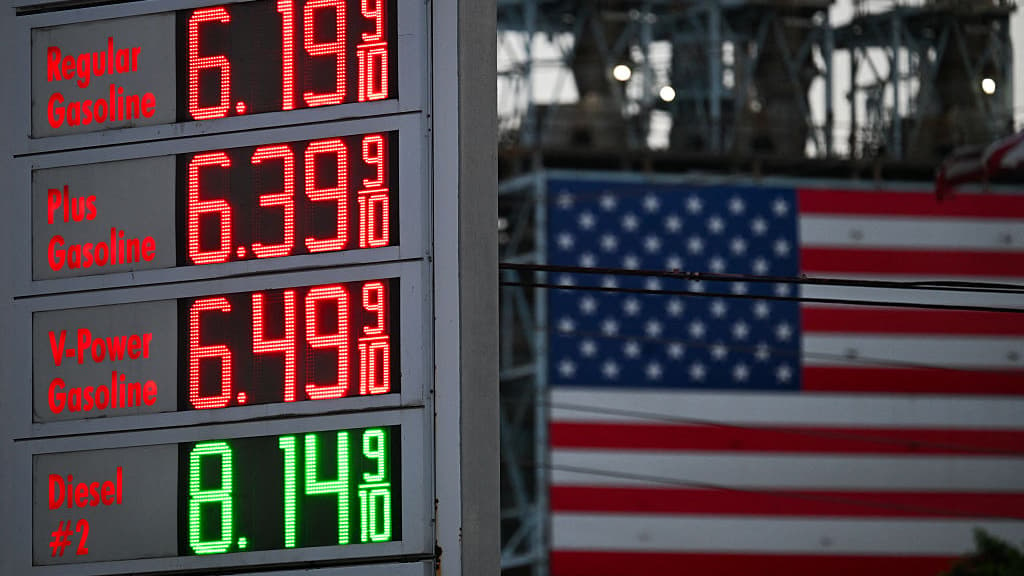
When it was first proposed in December 2025, the rule was divisive, drawing ire from environmental advocates while garnering praise from auto-industry trade groups. The Administration finalized it last week with a signoff from President Donald Trump.
The President commented on the forthcoming rule Sept. 26, saying the new standards would “take the waste out of building cars in America.”
“That means LOWER PRICES, saving families thousands on a new, beautiful, and safe car,” he wrote on Truth Social.
The claim that the revisions will pass down cost savings to American buyers, however, relies on several factors, including automakers’ pricing decisions, fuel costs, and broader economic conditions.
What changes under Trump’s new fuel economy rule?
Former President Joe Biden’s regulations were put in place in 2024 to reduce car-based greenhouse gas emissions, decrease dependence on fossil fuels, and spur a transition to electric and hybrid vehicles. The Trump Administration has claimed that its revisions are more focused on bolstering the auto industry and making safer, newer cars more accessible.
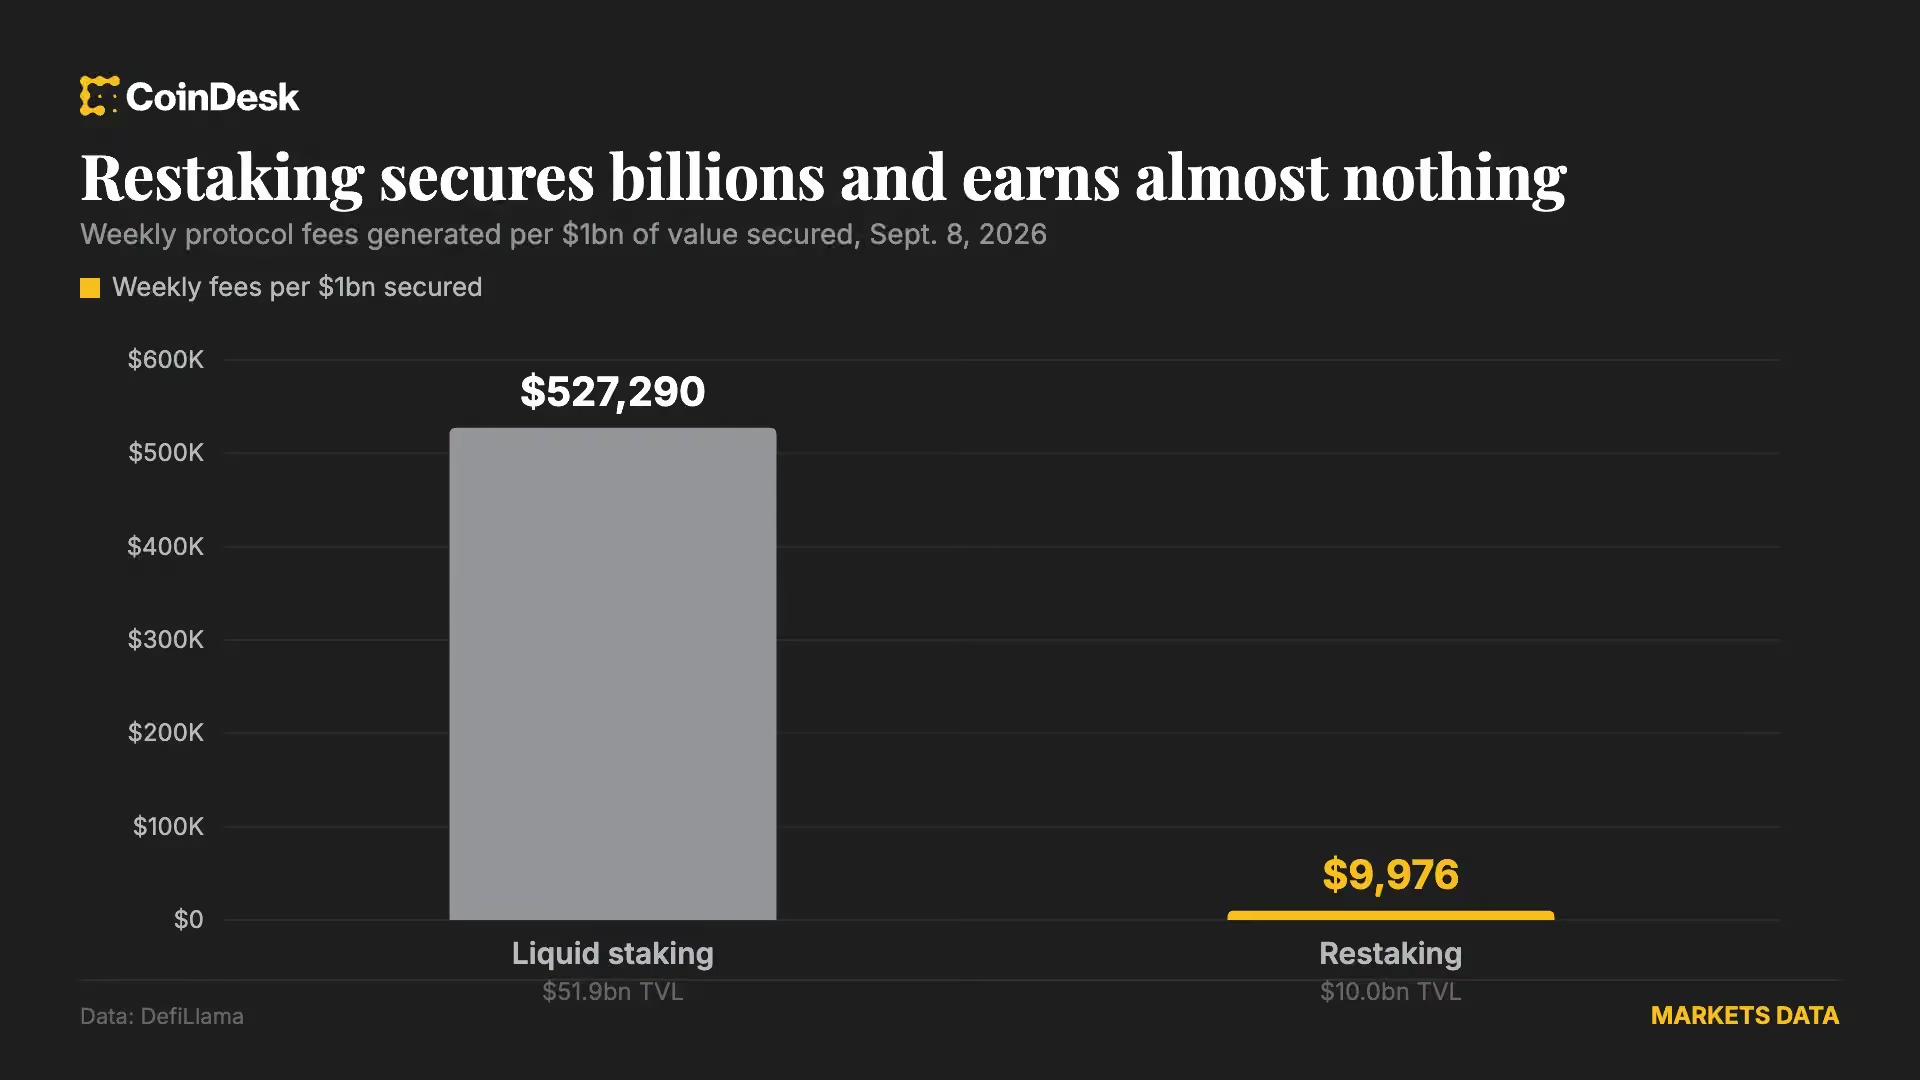
EigenLayer held $19.7 billion at its peak and liquid restaking tokens grew more than 1,000% in the first six weeks of 2024. But the services buying security never paid enough to cover both the base staking yield and a premium on top, so the second yield restaking promised never materialized.
On Sept. 8, DefiLlama’s restaking category held $10.02 billion and generated $99,977 in fees over the prior week. The liquid staking category, on $51.87 billion, generated $27.35 million. Per dollar secured, ordinary staking earns roughly 53 times more.

Two developments then removed what was left of the incentive to restake. Points programs subsidizing deposits wound down through 2025, and slashing went live in April 2025. Slashing is the penalty that confiscates part of an operator’s staked ETH when it misbehaves, by going offline or signing conflicting messages, for example. So restaking suddenly carried a real, priced downside where before the risk had been theoretical. There was no extra yield to compensate.
Set ether.fi aside and the rest of the sector is small. Renzo, Kelp, Swell, Puffer Finance and Bedrock, the five largest remaining liquid restaking tokens, made $953,350 in combined gross profit in the second quarter of 2026. Three quarters earlier the same five made $2.18 million. Puffer, which raised $23 million, recorded $21,590 for the quarter. Swell recorded $22,370.

The income statements also show which part of these businesses was ever profitable, and it was not the restaking. On Kelp’s books, EIGEN token rewards appear at $460,600 in gross revenue and $460,600 in cost of revenue: they arrive and pass straight to depositors, leaving nothing with the protocol. Puffer and Swell book staking rewards the same way. Whatever profit these companies made came from the orinary staking fees charged underneath the restaking layer.
“There’s a convergence now that you’re seeing between traditional market participants and digital asset market participants as well,” Lynq CEO Jerald David said in an interview with CoinDesk TV.
For firms using Lynq, FTIXX gives them somewhere to put cash between trades rather than leaving it sitting around. They can earn yield on the money and pull it out when they need it again.
That was a product Lynq’s clients had been asking for, David said. The network works with firms including B2C2, Wintermute, Galaxy ·, FalconX, Crypto.com and Fireblocks, whose businesses can require moving large amounts of money between trades. They wanted another option for putting that cash to work in the meantime.
“We needed to demonstrate that there was client demand,” David said. “Our clients were looking for a treasury asset on the platform that may have had a different yield profile than the other instrument that’s on there right now.”
Getting FTIXX onto the network required some work. Lynq had to modify its technology, restrict access to U.S. clients and integrate with Mosaic, he said. Customers also need a relationship with tZERO Securities and must meet the required onboarding and eligibility checks.
Lynq itself runs on a private, permissioned Avalanche (AVAX) Layer 1 blockchain. Its network has more than 30 institutional digital-asset firms onboarded and more than $89 million in assets, according to the company.
Crypto
Crypto’s Widening Net: From Fed Bets to Blackjack Tables, Digital Assets Keep Blurring Old Boundaries
If there is one throughline in this week’s crop of crypto headlines, it is that the industry has stopped pretending it is only about buying and holding coins. Across a handful of stories making the rounds, digital assets are shown pushing into territory once reserved for central bankers, casino floors, brokerage accounts and pre-IPO investors alike — a reminder that “crypto news” increasingly means finance news, gambling news and macro news rolled into one.
Take the growing chatter around prediction markets and Federal Reserve policy. Traders have been flocking to on-chain betting platforms to price the odds of late-2026 rate decisions, effectively turning monetary policy into a tradable asset class alongside Bitcoin and Ethereum. That such markets exist at all is notable: a decade ago, speculating on FOMC outcomes required options contracts or futures desks.
Now it can happen peer-to-peer on a blockchain, with odds shifting in real time as economic data lands. The rise of these markets suggests crypto infrastructure is becoming a genuine alternative venue for hedging and speculating on the traditional economy, not just a parallel casino for digital tokens.
Speaking of casinos, the sector itself continues to evolve in ways that mirror shifts in consumer taste rather than technology alone. Reports on crypto gambling lobbies note that live-dealer blackjack tables are increasingly outnumbering roulette wheels—a seemingly small detail that says more about what crypto-native gamblers want.
Live blackjack offers a sense of skill and control that pure-chance games like roulette can’t match, and operators appear to be responding by stacking their lobbies accordingly. It’s a small but telling sign that crypto casinos are maturing into product-driven businesses competing on experience, not just novelty.
Meanwhile, the boundary between crypto trading and traditional equities markets keeps eroding. New developments around Aave’s lending protocol reportedly let users borrow stablecoins against tokenized versions of tech stocks issued through Coinbase and built on the Base network.
If that model gains traction, it would mark a significant step in bringing real-world assets fully into DeFi’s collateral system — letting someone hold a tokenized slice of a Nasdaq darling and borrow against it the same way they might borrow against ETH or Bitcoin today. It’s the kind of integration that regulators, banks and crypto-native builders have all been circling for years, and its practical rollout matters more than the concept alone.
On the trading-platform side, perpetual futures exchanges continue to expand what counts as a “market.” One report describes a platform offering more than 120 perpetual contracts spanning everything from Bitcoin to pre-IPO robotics companies, letting traders apply leverage to assets that, in many cases, aren’t even publicly listed yet.
This kind of expansion into speculative, illiquid corners of the private market — wrapped in crypto’s leverage-friendly perpetual format — raises real questions about price discovery and risk, even as it satisfies demand from traders hungry for exposure beyond the usual crypto majors.
Finally, there’s the steady drumbeat of token listings that keeps the broader ecosystem churning. A gambling-focused token tied to the Dexsport platform recently landed on the MEXC exchange, a move that typically brings a token more liquidity and visibility, if not necessarily more fundamental value. Listings like these remain a bread-and-butter event in crypto markets — routine, but still closely watched by holders hoping for a price bump and a wider trading audience.
Individually, none of these developments is likely to reshape the industry overnight. But together they sketch a familiar pattern in crypto’s ongoing evolution: infrastructure built for speculative tokens is steadily being repurposed for macro bets, tokenized equities, private-company exposure and gambling products alike.
The technology is proving flexible enough to wrap around almost anything with a price — which is exactly why regulators, investors and casual observers alike keep struggling to say where “crypto” ends and the rest of finance begins.
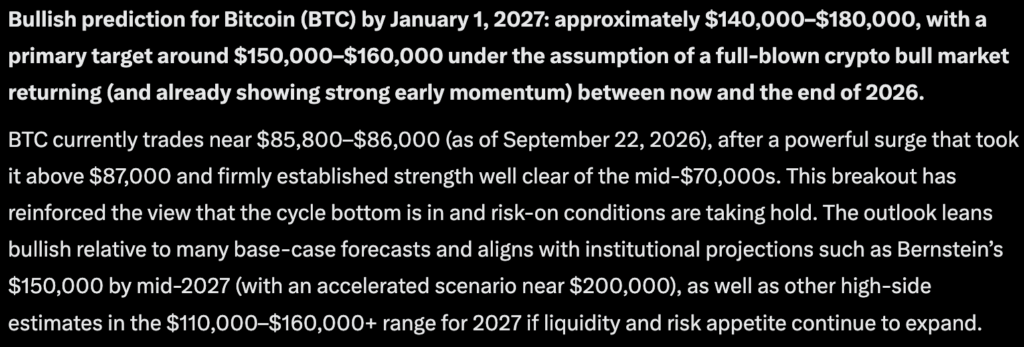
Perplexity AI predicts that if a full-blown bull market returns in Q4, Bitcoin could reach $180,000 before January 1, 2027. The bullish range is estimated at $140,000 to $180,000, with a potential late-cycle surge that could push Bitcoin beyond $200,000.
Currently priced around $83,000, this would represent a gain of about 115% to reach $180,000. What’s noteworthy is that Bitcoin has already corrected significantly from its previous cycle high of about $126,200 on October 6, 2025, followed by a sharp decline during 2026.
Bitcoin has a history of producing substantial gains during strong market cycles. According to historical annual data, BTC gained approximately 154% in 2023 and 110% in 2024. If the current predictions hold true, we may see a similar increase on the horizon.

Perplexity AI Predicts Bitcoin to $180,000 if Bullish Catalysts Align: Does the Technical Analysis Back it Up?
Bitcoin recently broke out of a pattern of lower highs that had developed since May, reclaiming several key moving averages. According to Reuters’ technical analysis, $81,781 is considered important support, while $86,500 is a significant resistance level. Above that, the next technical targets are around $90,000 and $97,867.
CryptoQuant has noted a similar trend, calling $81,700 a key level because it aligns with Bitcoin’s 365-day moving average. Resistance levels above this are near $86,600 and $88,700.
Bitcoin’s first major test is surpassing the $85,000 level, followed by the $86,000 to $88,000 range. Bitcoin has pushed through this area, which matters because a sustained breakout would remove one of the largest technical obstacles between its current price and the $100,000 level.
The next major milestone is approximately $98,000. Beyond that, the market will be approaching the all-time high of $126,200, where it gets particularly interesting.
Once Bitcoin decisively breaks beyond $126,000, it will enter a phase of genuine price discovery. Historical resistance above that level is very limited. At that point, psychological targets such as $130,000, $140,000, and $150,000 could attract momentum traders and institutional investors.
Earn $50 and Enter $300K Prize Draw on EdgeX
Bitcoin Hyper Targets Early Mover Upside as Bitcoin Drops Dangerously Close to $80,000
A -2.5% daily drop is not too much to worry about for whales and those already heavily positioned at a much lower price. However, for those who bought over $80,000, things could be getting uncomfortable, which is why presale opportunities prove so popular.
Bitcoin Hyper ($HYPER) is positioning itself as the first Bitcoin Layer 2 with full SVM integration. It boasts smart contract execution built for speed that outpaces Solana itself, while settling back to Bitcoin’s base-layer security.
As of today, the presale has raised more than $33.1M at a current token price of just $0.0136864, with staking rewards live at launch at a huge 35% APY.
The pitch: solve Bitcoin’s slow transactions, high fees, and lack of programmability without abandoning what makes BTC trusted in the first place. A Decentralized Canonical Bridge handles BTC transfers natively.
Gain Access to New Bitcoin Layer 2 Early Here
Discover: The Best Token Presales
The post Perplexity AI Predicts a Big Move for BTC in 2026 Even With Recent Dip appeared first on Cryptonews.
XRP lost its $1.50 price pivot today, sliding to $1.47 after a daily decline of about 3%. The break forces a binary question onto the chart: does the selling pressure showing up in spot-market volume resolve into a quick reclaim, or does it open the door to a deeper slide toward $1.40-$1.42?
The 200-day EMA is near $1.37, the level that would flip the medium-term structure from bullish to neutral. The token has been printing lower highs since a local peak near $1.63 on September 23, and a second attempt to clear $1.60 on September 25 failed as well. Since then, the decline has been slow and orderly: $1.55, then $1.52, then $1.50, and now $1.47.
There was no single dramatic session driving the move. Instead, the pattern reads as buyers simply not showing up, with every small bounce getting sold rather than extended. After the sharp rally in early September, that kind of cooling was overdue, but the open question is whether $1.50 was ever real support or just a round number the market is now testing.
Earn $50 and Enter $300K Prize Draw on EdgeX
ETF Accumulation Narrative or Technical Pullback?
The chart itself frames this as a cooling-off period following the rally that carried the XRP price up nearly 50% from its August low near $1.00. RSI sits at a neutral 54, with no overbought or oversold readings to lean on. Price levels, not oscillators, are setting the tone for this week.
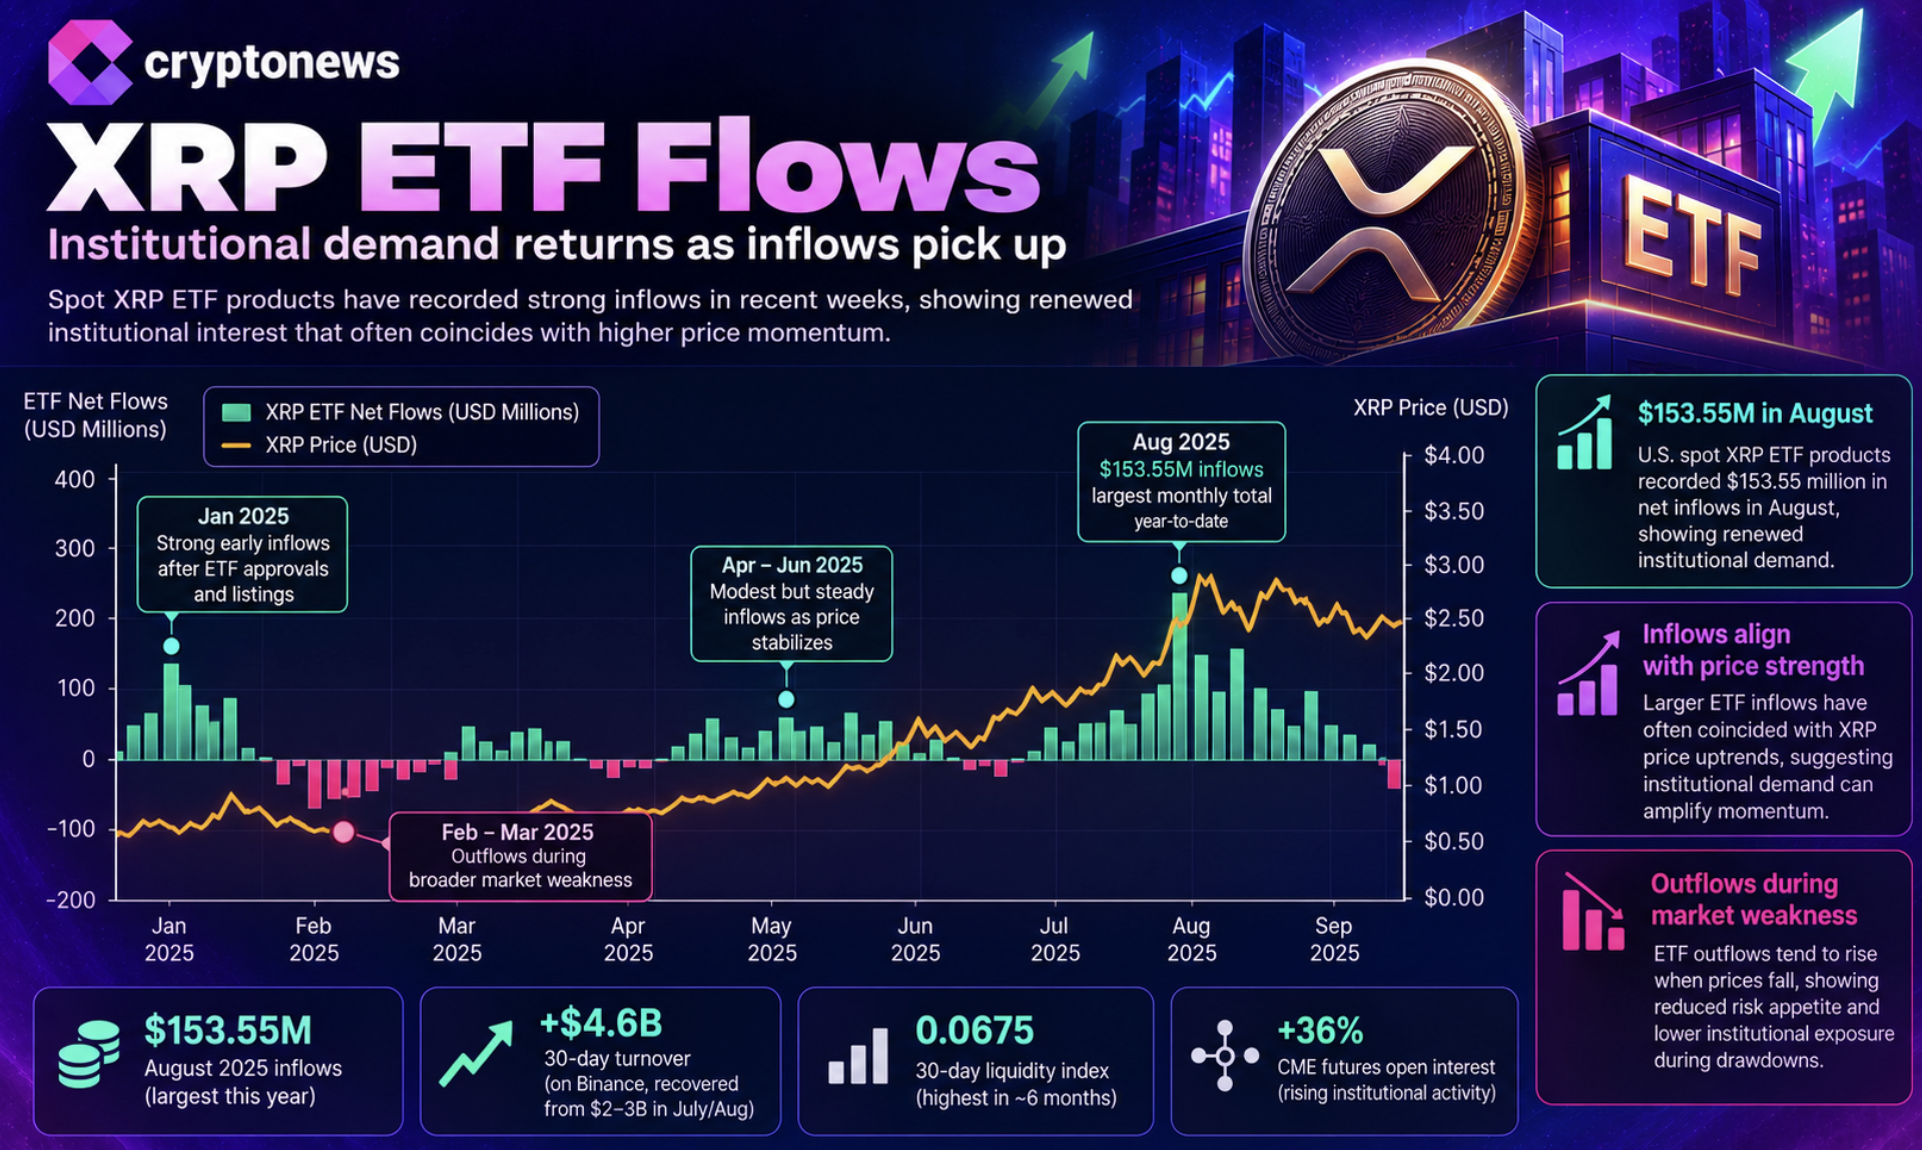
Separately, market data has pointed to sustained spot XRP ETF inflows running into the hundreds of millions of dollars over recent weeks, a trend some trackers frame as ongoing institutional accumulation beneath the price action. That flow data is useful context, but it is not confirmed as the driver of Monday’s drop, as the pullback below $1.50 traces cleanly to failed resistance tests and fading bid support.
The medium-term structure remains intact for now. XRP sits above its 200-day EMA at $1.37, which is curling upward for the first time since spring. This is a sign the longer trend has not broken, even as the shorter-term chart bleeds lower. A descending trendline from the late-August spike to $1.70 was cleared in mid-September, and that breakout is what fueled the run to $1.67 in the first place.
A second descending trendline, drawn from the September 23 high, is now the line bulls need to clear in October; left alone, it points toward $1.20 by mid-November. The levels on both sides of the current price are well defined.
Trade XRP on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
Reclaim $1.50 or Risk $1.37: XRP Price Next Move
The first job for bulls is straightforward: close a daily candle back above $1.50. Do that, and Monday’s drop reads as a fakeout rather than a breakdown, with $1.55 as the next confirmation level and $1.60-$1.63 as the target that would put the September 23 high back in play.
Fail to reclaim $1.50 in the next day or two, and $1.40-$1.42 becomes the level to watch, with the 200-day EMA at $1.37 as the line that actually matters for the medium-term outlook. A close below it would shift Ripple’s native asset from a bullish structure to a neutral one, opening room toward $1.30 and, in a broader crypto market sell-off scenario, $1.20.
$XRP just printed it's 6th weekly close beneath the 50 week EMA. The bears contInue to hold their defence line, with the bulls support below at $1.31 as a guardrail. (20 week EMA. For the time being, we remain compressed. https://t.co/7j6d2KB27L pic.twitter.com/r9kwHDmf2R
—
ChartNerd
(@ChartNerdTA) September 28, 2026
For this week, the range is $1.37 to $1.60, with $1.50 sitting as the pivot in between. On technical analysis grounds, the base case is a dip toward $1.40-$1.42 that gets bought, followed by another attempt at reclaiming $1.50. A pattern consistent with pullbacks inside an uptrend rather than the start of a new downtrend.
The $1.80-$2.00 zone remains the valid medium-term target as long as $1.37 holds; lose it, and that target moves out of reach for the immediate term.
Discover: The Best Token Presales
The post XRP Price Slides 2.9% as $1.50 Reclaim Becomes Critical appeared first on Cryptonews.
Crypto
Crypto’s New Playground: Casinos, Fed Bets, and Tokenized Stocks Blur the Line Between Trading and Gambling
The crypto industry has always had a talent for reinventing itself, but the latest wave of product launches suggests the industry is heading somewhere new: a place where trading, betting, and borrowing are becoming almost indistinguishable from one another. A cluster of recent developments — spanning live-dealer casino games, a new token listing tied to decentralized betting platforms, prediction markets built around Federal Reserve policy, sprawling perpetual futures exchanges, and DeFi protocols that let users borrow against tokenized shares of tech companies — paints a picture of an ecosystem racing to fuse speculation of every stripe into a single, crypto-native experience.
Take the world of crypto casinos, where live blackjack tables have reportedly begun to crowd out roulette wheels in lobby rankings. The dynamics driving that shift echo something familiar from traditional gambling: player preference for games that reward skill and pacing over pure chance. Blackjack lets players make decisions — when to hit, stand, split, or double down — giving a sense of agency that a spinning roulette wheel simply can’t replicate. In an industry built around instant, low-friction transactions using digital assets, that appeal seems to translate directly into engagement, with live-streamed dealers adding a layer of social, real-time theater that slot-style games lack.
That same appetite for interactive, decision-driven products is showing up elsewhere. Dexsport, a decentralized betting and casino platform, recently saw its native token, DESU, listed on the exchange MEXC — a milestone that matters less for the listing itself than for what it signals about the sector’s maturation. Token listings on major exchanges typically bring liquidity, visibility, and a degree of legitimacy that smaller platforms struggle to achieve on their own. For everyday users, a listing like this often translates into easier on-ramps, more trading pairs, and a stronger case that the underlying platform is being taken seriously by the broader market rather than treated as a niche experiment.
Meanwhile, speculation is moving well beyond games of chance and into the realm of macroeconomic policy. Prediction markets tracking the Federal Reserve’s interest rate decisions have become one of the more closely watched corners of crypto-adjacent finance heading into the back half of 2026. Traders on these platforms are effectively placing wagers on central bank behavior, turning monetary policy announcements into tradeable events. The appeal is straightforward: instead of relying solely on bond markets or futures tied to traditional finance, participants can now stake positions directly on whether the Fed will hold, cut, or raise rates, often with faster settlement and more granular contract structures than legacy markets offer. It’s a sign that prediction markets, once dismissed as a curiosity, are increasingly viewed as a legitimate barometer of trader sentiment on issues far removed from crypto prices themselves.
The appetite for exotic exposure is also evident in the perpetual futures space, where platforms like ApeX Omni have expanded their offerings well past the usual roster of Bitcoin and Ethereum contracts. With well over 120 perpetual markets now available, traders can reportedly take leveraged positions not just on major cryptocurrencies but on themes as far-flung as pre-IPO robotics companies. This kind of expansion reflects a broader trend of crypto exchanges positioning themselves as all-purpose speculation venues, offering leverage on virtually any asset class that generates enough trader interest — blurring the boundary between crypto trading and speculative bets on private, pre-public companies that would otherwise be inaccessible to retail investors.
Perhaps the clearest example of crypto finance colliding with traditional markets comes from Aave’s newest iteration. The protocol’s fourth version reportedly allows users to borrow USDC stablecoins against tokenized versions of Coinbase-linked tech stocks on the Base network. In practice, that means holders of tokenized equity exposure can unlock liquidity without selling their underlying positions — a mechanic long familiar to DeFi users who collateralize crypto assets, now extended to tokenized real-world securities. It’s a small but telling step toward a future where the wall between “crypto” and “traditional markets” continues to erode, with stocks, bonds, and other conventional assets increasingly represented on-chain and woven into the same lending and borrowing infrastructure that powers decentralized finance.
Taken together, these developments underscore a consistent theme: crypto platforms are no longer content to simply trade digital coins. They are building out entire ecosystems of speculation — casino games, prediction markets, leveraged derivatives, and collateralized lending — all designed to keep users engaged, liquid, and constantly exposed to new forms of risk and reward. Whether this convergence produces a more mature, diversified financial ecosystem or simply amplifies the volatility and risk-taking crypto is already known for remains an open question. What’s clear is that the industry’s appetite for expansion shows no signs of slowing down.


If there was a single theme running through the crypto world’s headlines this spring and summer, it was this: the industry that once promised to reinvent money has increasingly fused itself to the industry promising to reinvent everything else — artificial intelligence.
The result, according to a string of reports and commentary tracked by researcher-journalist Molly White and blogger David Gerard, is a landscape where political money, security failures and marketing absurdity are all converging in ways that ought to worry anyone paying attention.
Start with the money in politics. In a recent interview, White — who has spent years cataloguing where crypto industry cash flows in Washington — turned her attention to a new wrinkle: artificial intelligence companies adopting the same political playbook that crypto firms pioneered.
According to the discussion, OpenAI and Anthropic are now effectively running competing pro-AI super-PACs, pouring money into races much the way crypto-aligned PACs like Fairshake have done in recent election cycles. White reportedly highlighted a botched intervention in New York’s 12th congressional district as an example of the sums involved and the risk of these efforts backfiring.
The parallel is not incidental. Crypto’s political spending playbook — deploy industry money to shape friendly regulation and punish critics — was built over several election cycles and proved remarkably effective at getting crypto-friendly candidates elected and skeptics sidelined.
Watchers like White argue that AI companies, facing their own looming questions about regulation, safety and liability, are now borrowing that same toolkit almost wholesale. Whether AI’s political spending proves as consequential as crypto’s remains to be seen, but the early signs suggest deep-pocketed AI labs are not content to leave the lobbying playing field to blockchain interests alone.
Money and politics aside, the more immediate crypto news has been considerably more chaotic on the technical side. A case in point: an unofficial crypto wallet built on top of Elon Musk’s Grok AI was reportedly compromised through a combination of an NFT and a prompt injection attack — a technique in which malicious instructions are hidden inside content an AI model processes, tricking it into taking unauthorized actions.
The episode is being cited by critics as a vivid illustration of what happens when experimental AI agents are given direct access to cryptocurrency funds without adequate safeguards. As one commentator put it, the incident underscores a blunt truth: the push toward “agentic commerce,” in which AI systems autonomously manage transactions and wallets on a user’s behalf, currently looks a lot like an open invitation to fraud.
That warning fits a broader pattern. Crypto’s history is littered with hacks and exploits that followed hard on the heels of new technical hype cycles — DeFi protocols, bridges, NFT marketplaces — and the addition of AI agents with wallet access appears to be simply the latest frontier for attackers to probe.
Security researchers have long cautioned that combining large language models, which can be manipulated through carefully crafted inputs, with systems that move real money is a combination that demands far more rigorous testing than the industry has so far shown appetite for.
Then there is the sheer commercial strangeness of the AI-crypto convergence. Among the products making the rounds is “Gudtrip,” described in coverage as an AI agent vape pen built with blockchain technology — a mash-up that manages to combine three separate hype cycles (AI, crypto, and vaping) into a single device.
It’s the kind of product that invites eye-rolls even from people steeped in the industry, and it has become something of a symbol for critics who argue that “blockchain” and “AI agent” are increasingly being slapped onto unrelated consumer goods simply because the buzzwords still move product.
Labor practices are also getting the AI-crypto treatment. Reports have surfaced of AI companies experimenting with paying staff in AI-linked tokens rather than conventional money — an arrangement that echoes crypto’s long history of compensating workers and contractors in volatile, illiquid tokens instead of cash. Critics have been quick to note the obvious problem: a token’s value depends entirely on continued enthusiasm for the company issuing it, leaving employees exposed to exactly the kind of speculative risk that traditional salaries are designed to avoid. The practice, if it spreads, would import one of crypto’s more employee-unfriendly habits directly into the AI industry’s compensation structures.
Not everyone covering this convergence is doing so with a straight face. A satirical piece making the rounds — structured as a twist on the old “two cows” economics joke — skewered the fintech, AI, blockchain and crypto sectors in one go, imagining a “crypto” cow story where two digital cows produce “milk tokens” tradeable for millions but drinkable only by avatars in the metaverse, and a “hedge fund” version featuring robotic cows that befriend real cows just to steal their milk.
Silly as the format is, the satire lands because it captures something real: a sense among observers that these overlapping industries have become adept at generating elaborate financial and technical narratives that produce headlines and valuations long before they produce anything resembling durable value.
Taken together, these threads — political spending mirroring crypto’s playbook, an AI wallet hacked via prompt injection, blockchain-branded vape pens, token-based salaries, and no shortage of pointed satire — paint a picture of an industry moment defined less by a single breakthrough than by rapid, sometimes reckless, cross-pollination.
Crypto spent the better part of a decade building the infrastructure, the political machinery and the marketing instincts for turning speculative technology into cultural and financial weight. Now AI companies appear to be absorbing many of the same instincts, for better or worse, at a pace that leaves regulators, security researchers and workers alike scrambling to keep up.
Editor’s note: Much of the reporting referenced above originates from commentary and short-form blog coverage rather than in-depth investigative reporting, and some details — such as the specific financial scale of AI super-PAC spending or the full technical mechanics of the Grok wallet exploit — were not independently verifiable from the available material. Readers should treat figures and claims here as preliminary pending fuller reporting.
Tether is a ‘lifeline’ for Iranian regime, Senate Dems say in new report
Joe Hart delivers Khaldoon Al Mubarak verdict on Man City Premier League charges

Microsoft may have just pushed Copilot into a completely different phase of its AI ambitions


-
 Fashion3 days ago
Weekend Open Thread: J.McLaughlin – Corporette.com
-
 Crypto6 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-
 Tech & AI1 day ago
Anthropic turns Claude into an AI marketplace with 2,000+ plugins and connectors
-
 Tech & AI1 day ago
OpenAI is preparing “o,” an always-on ChatGPT assistant that could handle email
-
 Fashion5 days ago
8 iPhone Accessories That Add Personality
-
 Entertainment6 days ago
These 17 Fall Amazon Dresses Seriously Look Like Anthropologie
-
 Tech & AI6 days ago
Reolink’s solar 4K security camera falls to its lowest price in months
-
 Crypto7 days ago
Trump-Xi Polymarket Odds for Handshake Hit 50%
-
 Crypto6 days ago
This Bearish Netflix Stock Trade Can Cash In On Video Streaming Giant’s Woes
-
 Crypto5 days ago
Bitcoin price tests $83,600 Supertrend support after $87K rejection
-
 Crypto5 days ago
Crude Oil Prices Pressured by Diplomatic Hopes in the Middle East
-
 Business & Hussles6 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-
 Crypto6 days ago
BitGo says Bitcoin absorbed Fed hike, CLARITY failure
-
 Crypto5 days ago
Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike
-
 Crypto7 days ago
Meta Jumps 11% As Muse Shines and Investors Show an Appetite for Advancing AI
-
 Crypto6 days ago
Did Jim Cramer Just Give GameStop Stock the Kiss of Death When He Said the Turnaround Is Working?
-
 Tech & AI5 days ago
UiPath’s Dines says AI needs a manual and launches Cartographer to write it
-
 Crypto5 days ago
As Amazon Stock Prospers, Traders Might Consider This Option Play
-
 Crypto5 days ago
Strategy resumed Bitcoin buying, but Strive gained more BTC per share
-
 Crypto1 day ago
Wall Street Giant Warns AI Agents Could Trigger a New Kind of Bank Run
You must be logged in to post a comment Login