Crypto
Germany is ending tax-free bitcoin, and cutting the rate for traders

Everyone is reporting a tax rise. Do the arithmetic and Germany is cutting the top rate for active traders by nineteen points, from 45% to 26.375%. The people getting hit are the ones who buy and sit on it, which until now was the whole point of holding crypto in Germany.
Summary
- Germany’s Federal Ministry of Finance circulated a draft bill on September 9 that would end the country’s one-year tax-free holding period for cryptocurrency, replacing it with the flat capital income tax.
- The rate is 25% plus the 5.5% solidarity surcharge, an effective 26.375% before any church tax, applied regardless of how long an asset is held.
- The cutoff is December 31, 2026: assets bought on or after January 1, 2027 fall under the new regime, while earlier purchases would remain under existing rules.
- Short-term traders would pay less. Gains realised inside twelve months are currently taxed at personal income rates reaching 45%, so moving them to a flat 26.375% is a reduction.
- This is the fourth attempt in roughly eighteen months, and the first to sit inside the budget bill, which is considerably harder to strip out than a standalone motion.
Hold a coin in Germany for twelve months and one day and the gain is yours, untaxed, no cap, no form, no rate to look up. That rule has quietly made Germany the best place in Europe to be a long-term crypto holder, and it was never designed for crypto at all. It came from a provision written for art and gold coins, which German tax authorities applied to digital assets because that is the drawer they fit in.
On September 9 the Finance Ministry circulated a draft to close it.
The coverage has gone straight to “Germany taxes crypto,” which is true and misses the more interesting half. The bill moves crypto into the Abgeltungsteuer, the flat withholding tax that already covers shares and dividends. That rate is 25%, or 26.375% once you add the solidarity surcharge. Sell inside a year today and you pay your personal income rate, which reaches 45%.
So the same bill that takes away the exemption hands active traders a cut of nearly nineteen percentage points.
Germany is not raising crypto tax. It is deleting the distinction between holding and trading, and the people who built their position around that distinction are the ones who pay for it.
What the draft actually says
Two dates, which is why half the coverage says 2027 and the other half says 2028. Both are right about different things.
The regime. Crypto gains would move into the Abgeltungsteuer, Germany’s flat withholding tax on capital income. The headline rate is 25%. The solidarity surcharge adds 5.5% of the tax itself, producing an effective 26.375%. Church tax applies on top for those who pay it.
The cutoff. Assets acquired on or after January 1, 2027 fall under the new treatment. Assets bought on or before December 31, 2026 would remain under the current rules, which is the grandfathering provision, though the draft’s treatment of it has been described as not fully confirmed.
The withholding start. Crypto service providers would be required to withhold the tax automatically from January 1, 2028, a year after the law’s effective date, giving platforms time to build the systems. That gap is why some coverage dates the change to 2027 and other coverage to 2028. Both are describing the same bill.
The documentation trap. Providers may rely on purchase prices and acquisition dates supplied by customers when assets move between platforms. An investor who cannot produce that documentation faces the flat 25% applied to the full proceeds, with no deduction for the original cost. That provision has received almost no attention and it is the one most likely to produce unpleasant surprises, because self-custodied assets moved onto a platform years after purchase are exactly the case it captures.
What else changes. Income from crypto lending and staking would be reclassified as capital income, bringing it under the same regime. Investors would receive the standard 1,000 euros savings allowance. And crypto losses could be offset against gains from securities, which is not currently possible and is a meaningful improvement for anyone running both.
Who pays more and who pays less
Here is who wins and who loses, which also tells you who will fight it.
Long-term holders lose the most. Someone buying in February 2027 and selling in 2029 currently pays nothing. Under the draft they pay 26.375% on the full gain. That is the entire tax break, removed, for anyone entering after the cutoff.
Short-term traders gain. Someone buying and selling inside twelve months currently pays their marginal income rate, up to 45% for high earners. Under the draft they pay 26.375%. For an active trader in the top bracket, that is a reduction of roughly nineteen percentage points on every realised gain.
Loss-makers gain. Offsetting crypto losses against securities gains is new and useful, and it applies across a portfolio instead of within an asset class.
Stakers and lenders face a rate change of uncertain direction, depending on how their income is currently treated and what bracket they occupy.
So the bill is redistributive within the crypto-holding population, not simply extractive from it. The people it hurts are the ones the current system was designed to favour, and the people it helps are the ones the current system taxed hardest. Whether that is good policy depends on whether you think a tax system should encourage holding over trading, which is a real argument with a long history in capital gains policy generally.
The ministry’s own justification points that way. Its position, as reported, is that crypto assets increasingly represent a form of private capital investment and should not remain favoured relative to other income types. That is an equalisation argument, not a revenue argument, and the revenue figures support the reading.
The revenue is small
If this were a money grab, the numbers would be bigger.
Around 160 million euros in additional revenue in 2028, rising to roughly 350 million euros annually by 2031. Against a federal budget measured in hundreds of billions of euros, that is a rounding error. One estimate cited a figure near 350 million euros as the steady-state expectation.
Two things follow. If the motivation were revenue, this is an enormous amount of legislative and administrative effort for very little money, which supports the equalisation reading. And the projections themselves deserve scepticism, because the comparable case went badly.
Austria made the same shift in 2022, moving crypto into a flat capital gains regime, and analysts tracking this proposal note it raised considerably less than officials expected. The reason is not mysterious. A tax on realised gains only collects when people realise, and removing the incentive to hold does not automatically create an incentive to sell. It can equally produce holders who simply never dispose, or who dispose elsewhere.
Why this attempt is different
One fact has appeared in a single outlet and it is the most important thing in the story.
This is the fourth push in roughly eighteen months to scrap the one-year rule. The previous three came from the Left Party, from the Greens, and from coalition budget talks, and all three failed. In May, the Finance Committee voted down a Green Party proposal to end the tax-free treatment, with the CDU/CSU, the Social Democrats, and the AfD all opposing it for differing reasons, while Die Linke supported it with reservations.
What changed is procedural. This version sits inside the budget bill instead of standing alone. A standalone motion can be voted down on its own merits by a coalition that disagrees about it. A provision inside a budget is voted on as part of a package that the government needs to pass, and stripping it requires a specific fight that someone has to want badly enough to have.
The political groundwork also differs. Finance Minister Lars Klingbeil signalled the direction in April during the 2027 budget presentation, saying the government intended to tax cryptocurrencies differently, and confirmed at a July press conference that a concrete bill was in preparation. That is a minister building toward a proposal over months, not a party tabling a motion.
Against that, the opposition has not disappeared. The AfD has reaffirmed its support for the twelve-month rule and won nearly 44% of the vote in Saxony-Anhalt this month, though tax policy is federal and no state government can alter it. And the draft remains in early coordination among federal ministries, meaning individual provisions can still change before it reaches the legislature.
What a dated cutoff does to behaviour
A grandfathering date is a deadline, and deadlines move money.
Anyone in Germany who intends to hold cryptocurrency for more than a year now has an incentive to acquire it before December 31, 2026. Buying on December 30 preserves the exemption permanently for that position. Buying on January 2 forfeits it permanently. The difference between those two dates, for a position held to a substantial gain, is the entire tax liability.
That produces a predictable pattern: accelerated buying into the cutoff by German residents planning long holds, followed by a cohort of grandfathered positions that their owners have a strong reason never to sell into a taxable event. The second effect is the more durable one, and it is a known consequence of grandfathering in capital gains policy generally. It creates a locked-in population whose optimal move is to hold indefinitely, borrow against the asset if they need liquidity, and never realise.
The reverse incentive also exists and has been noted in the coverage: holders with large unrealised gains under the current rules may reassess whether to realise them before any new regime could apply, which is a selling pressure and not a buying one. Which effect dominates depends on the size of existing unrealised positions relative to intended new purchases, and nobody has that data.
For anyone reading this outside Germany, the useful point is that the cutoff date is the operative fact, not the rate. Rates change slowly. A dated line between two permanent treatments changes behaviour immediately.
Where this leaves Germany in Europe
The competitiveness panic is overdone in both directions.
Germany’s exemption was genuinely unusual. Most European jurisdictions tax crypto gains as capital income at rates broadly comparable to the 26.375% being proposed, and several have moved in exactly this direction over the past several years. Austria did it in 2022. The trend across the bloc has been toward treating digital assets like other capital investments, which is also the direction the European regulatory framework has taken since MiCA reached full enforcement.
So Germany is not becoming hostile. It is becoming ordinary, and the proposal would place it roughly in line with its neighbours instead of at the punitive end.
The competitiveness argument that some analysts have raised, that capital could move toward friendlier jurisdictions if the bill passes, is real but narrower than it sounds. It applies to individuals with the flexibility to relocate their tax residence, which is a small population. It does not apply to institutions, which are taxed under corporate rules regardless. And the jurisdictions that remain more favourable are mostly smaller ones whose attractiveness depends on treatments that face the same equalisation pressure Germany is now applying.
How the current rule came about
Nobody sat down and decided crypto deserved a tax break. That is worth knowing, because it explains how easily this one can be taken away.
German tax law distinguishes between capital investments, taxed under the flat withholding regime, and private sales transactions, taxed under a separate provision covering assets held privately. The private sales provision carries a speculation period: sell inside a year and the gain is taxed at your personal rate, hold beyond it and the gain falls out of taxation entirely. That treatment was built for things like art, collectibles, and precious metals, where the state took the view that occasional private disposals were not the business of the tax system.
When cryptocurrency arrived, German tax authorities classified it as a private asset instead of a capital investment, which routed it into that provision automatically. The result was not a deliberate crypto incentive. It was the mechanical consequence of a classification decision made about a category the rule predated by decades.
Two things follow from that history. The exemption has always been vulnerable to reclassification and not to legislation, because moving crypto into the capital investment category achieves the same result without amending the speculation period at all, and that is exactly the mechanism the current draft uses. And the ministry’s stated justification, that crypto increasingly represents a form of private capital investment, is a classification argument, not a tax-policy one. It says the original categorisation was wrong, not that the rate should change.
That framing matters for how the bill will be defended in parliament. A government proposing a tax rise has to argue that more revenue is needed. A government proposing a reclassification has to argue only that an asset was filed in the wrong drawer, which is a considerably easier case to make and much harder to attack on fairness grounds.
What this does to German exchanges and custodians
The rate is not the hard part. The withholding is, and it lands on exchanges, not on you.
From January 2028, crypto service providers operating in Germany would be required to withhold the tax automatically at source. That is the same mechanism banks already run for securities under the Abgeltungsteuer, and it is why the draft gives platforms a year between the effective date and the withholding start.
Building it is not trivial. A platform must know each customer’s acquisition date and purchase price for every asset in order to compute a gain, and crypto moves between platforms and self-custody in ways securities generally do not. The draft addresses this by allowing providers to rely on purchase prices and acquisition dates supplied by customers when assets transfer in, which shifts the documentation burden onto the holder and creates the trap described earlier: no documentation means tax on the full proceeds with no cost deduction.
Three consequences follow for anyone operating in the German market.
Platforms need cost-basis infrastructure, including a mechanism for accepting, validating, and storing customer-supplied acquisition data. That is a build measured in months, which is presumably why the year gap exists.
Self-custody becomes more expensive in practice, not because it is taxed differently but because a holder moving assets onto a platform to sell must produce documentation the platform will accept. Assets acquired years earlier through channels that no longer exist are the hard case.
And the competitive position of German-licensed platforms shifts. A provider that withholds correctly is a provider whose customers face no filing burden, which is a genuine service advantage. A provider outside the German perimeter offers no withholding and leaves the customer to self-report, which is more work and more risk. That asymmetry tends to favour regulated domestic venues, which is usually the intent.
The question the bill does not settle
There is one thing the draft fudges, and it happens to be the fastest-growing part of the market.
Staking and lending income would be reclassified as capital income under the new regime. That is straightforward for a simple arrangement: tokens are lent, interest accrues, the interest is income. It is considerably less clear for the arrangements that dominate current practice.
Liquid staking, where a holder deposits an asset and receives a derivative token representing the position, involves at least two events that could each be taxable: the deposit and receipt of the derivative, and the eventual redemption. Whether the deposit constitutes a disposal, whether the derivative has its own acquisition date, and whether rewards accrue as income or as appreciation in the derivative’s value are all questions with different answers in different jurisdictions.
Restaking, liquidity provision, and structured yield products compound the problem in the same direction. Each involves a holder giving up one asset and receiving another, sometimes repeatedly, in arrangements whose tax character depends on how a rule written for securities is mapped onto instruments that did not exist when it was written.
This is not a criticism unique to the German draft. Every jurisdiction attempting to bring crypto under an existing capital income regime faces the same mapping problem, and most have resolved it slowly through administrative guidance instead of in the statute itself. The reason it deserves flagging here is that the withholding requirement makes it operationally urgent. A platform required to withhold tax automatically from 2028 needs a definitive answer about what constitutes a taxable event, and that answer has to exist before the systems are built rather than after.
Watch for supplementary guidance from the ministry on these categories specifically. Its absence by the time the bill reaches parliament would be a meaningful gap, and its content would tell German holders considerably more about their actual position than the headline rate does.
What a German holder should actually be thinking about
Strip out the politics and there are four practical questions, roughly in order of how much money they involve.
Do you have your cost basis? This is the one that will bite hardest and almost nobody is talking about it. Under the draft, if a platform cannot see what you paid and when, it applies 25% to the entire sale proceeds. Not the gain. The proceeds. Coins bought in 2017 on an exchange that no longer exists, moved through three wallets, and deposited somewhere in 2028 are the exact case this captures. Start assembling the paper trail now, because reconstructing it later against a withholding agent is a considerably worse experience than doing it in advance.
Are you buying before or after the line? December 31, 2026. Everything acquired on or before that date keeps the old treatment permanently, assuming grandfathering survives. Everything after falls under the flat rate. For a position you intend to hold for years, that single date is the difference between a full tax bill and none.
Do you trade or do you hold? If you turn positions over inside twelve months, this bill is a rate cut and you should stop reading the alarmed headlines. If you buy and wait, it removes your entire advantage.
Do you have losses parked anywhere? Being able to offset crypto losses against securities gains is new, and for anyone carrying dead bags alongside a brokerage account, it is worth real money.
None of this is advice and none of it is settled, because the thing being discussed is a draft in ministerial coordination that has not reached the Bundestag. But the four questions do not change regardless of what the final text says, and three of them are worth answering this year either way.
The part that should worry other jurisdictions
There is a pattern in this bill worth noticing if you live somewhere else, because the mechanism travels.
Germany is not amending its crypto tax rules. It is reclassifying crypto out of one existing category and into another. The private-sales provision with its twelve-month speculation period stays exactly as it is, still covering art and collectibles. Crypto simply stops being filed there.
That is a much lower bar to clear than writing new tax law. There is no need to argue about whether digital assets are special, no need to set a bespoke rate, no need to defend a number in front of a committee. The argument reduces to: this thing looks more like a share than like a painting, so it goes in the share drawer. That is an administrative claim dressed as a legislative one, and it is very hard to attack on fairness grounds because the rate being applied is the rate everyone else already pays on capital income.
Any country that carved out favourable crypto treatment by classification rather than by statute is exposed to the same move. The favourable treatment was never a policy decision anyone defended on its merits. It was a filing accident, and filing accidents get corrected quietly.
The corollary is that jurisdictions which wrote deliberate crypto tax regimes, with rates and thresholds chosen on purpose, are more stable than the ones that ended up generous by default. Deliberate policy can be repealed, which requires a political fight someone has to win. A classification can be revised by a ministry with a draft.
Germany’s twelve-month rule survived four attempts to legislate it away. It may not survive being reclassified.
What to watch
- Whether it survives coordination. The draft is in early coordination among federal ministries, and provisions can change before it reaches parliament. Watch for the grandfathering clause specifically, which has been described as not fully confirmed and which is the provision with the largest behavioural effect.
- Whether it stays in the budget. The procedural fact that makes this attempt different is its placement inside the budget bill. If it is separated into a standalone measure, the record of the previous three attempts becomes the relevant guide.
- The documentation provision. The rule that undocumented cost basis means tax on full proceeds is severe, and it is the kind of detail that generates amendments once affected parties read it.
- Buying patterns into the cutoff. German exchange volumes through the fourth quarter of 2026 are the observable test of whether the deadline is changing behaviour, and they are published.
- Austria’s actual numbers. The clearest available evidence on whether the revenue projections hold, and the comparison analysts are already making.
What is Germany proposing to change?
The Federal Ministry of Finance drafted a bill on September 9 that would end Germany’s one-year tax-free holding period for cryptocurrency and move gains into the flat capital income tax, known as the Abgeltungsteuer. The rate is 25% plus a 5.5% solidarity surcharge, an effective 26.375% before church tax, applied regardless of holding period.
When would it take effect?
The regime would apply to assets acquired on or after January 1, 2027. Crypto service providers would begin withholding the tax automatically from January 1, 2028, a year later, to give platforms time to build the systems. That two-date structure is why coverage has cited both years for the same bill.
Would everyone pay more tax?
No. Long-term holders lose the exemption entirely and pay 26.375% where they previously paid nothing. Short-term traders pay less: gains realised inside twelve months are currently taxed at personal income rates reaching 45%, so the flat rate is a reduction of up to roughly nineteen percentage points for high earners.
What happens to crypto I already own?
Under the grandfathering provision, assets bought on or before December 31, 2026 would remain under the existing rules, meaning the one-year exemption still applies to them. That provision has been reported as not fully confirmed in the draft, so it is the element most worth watching as the bill moves.
What about staking and lending income?
The proposal would reclassify income from crypto lending and staking as capital income, bringing it under the same flat regime. Whether that raises or lowers an individual’s liability depends on how their income is currently treated and which bracket they occupy.
How much revenue would it raise?
Around 160 million euros in 2028, rising to roughly 350 million euros annually by 2031. Against a federal budget in the hundreds of billions, that is very small, which supports reading the bill as an equalisation measure and not a revenue measure. Austria’s comparable 2022 shift raised considerably less than officials projected.
Is this likely to pass?
More likely than the previous three attempts, though not certain. This is the fourth push in roughly eighteen months, and the first to sit inside the budget bill rather than standing alone, which makes it harder to strip out. The Finance Committee voted down a similar Green Party proposal in May, with three parties opposing for differing reasons. The draft remains in early ministerial coordination.
What should a German holder do about it?
Nothing hasty, and consult a qualified German tax adviser, because the bill is a draft that has not reached parliament and provisions can change. What is worth understanding is that the December 31, 2026 cutoff, if it survives, creates a permanent difference between assets bought before and after it, and that documentation of purchase price and acquisition date becomes materially more important under the proposed rules. This is educational analysis, not tax advice.
Disclaimer: This article is for information and educational purposes only and does not constitute tax, legal, or investment advice. It describes a draft bill in early ministerial coordination that has not reached the German parliament, whose provisions may change or be withdrawn. Consult a qualified German tax adviser regarding your own circumstances. Information is accurate as of September 10, 2026.

Key takeaways
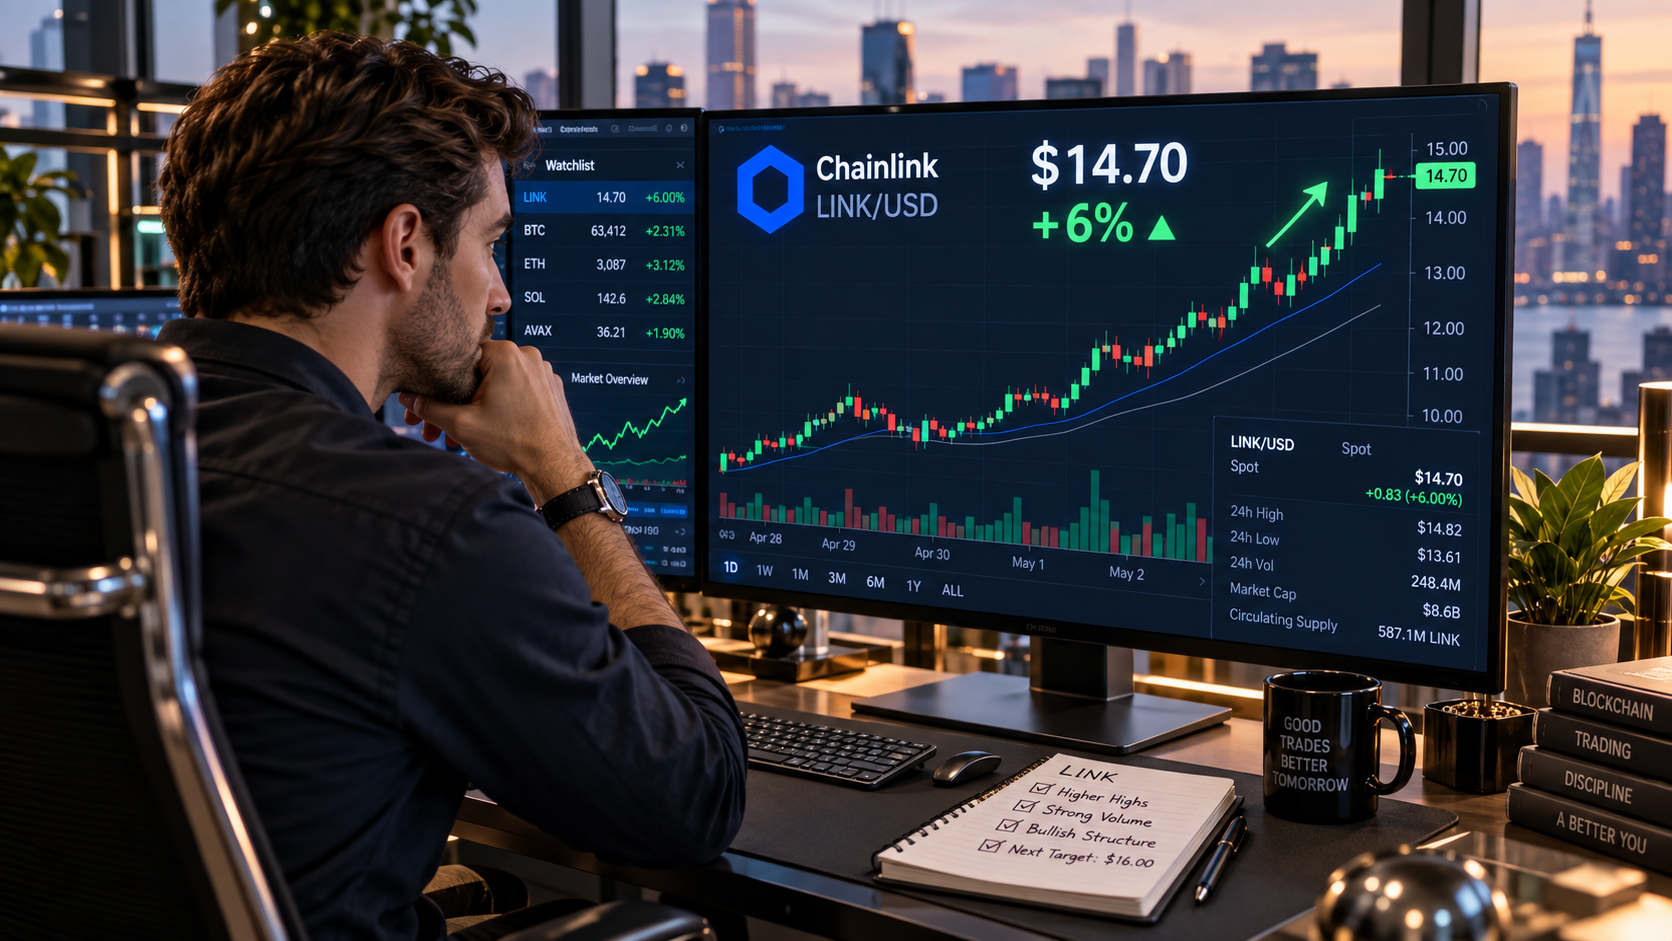
- LINK rose about 6% while much of the crypto market retreated, extending its reported 30-day gain to 30.3%.
- Chainlink’s CCIP 2.0 launch gives institutions the option to add their own cross-chain transaction verifiers.
- LINK met resistance near $15, while the supplied chart analysis identifies $12-$13 as a potential support zone.
Chainlink’s LINK token outperformed a weaker crypto market following the launch of Cross-Chain Interoperability Protocol (CCIP) 2.0.
The token gained about 6% in the session described in the supplied analysis, taking its 30-day advance to 30.3% and its year-to-date return into positive territory.
The upgrade gives financial institutions more control over transactions that move data or assets between blockchains.
Traders appeared to welcome the announcement, though LINK’s approach to $15 brought a technical test after its recent rally.
CCIP 2.0 adds institution-operated verifiers
Cross-chain transfers require a way to confirm that an action occurred on one blockchain before a corresponding action is completed on another. CCIP provides that communication layer.
With version 2.0, institutions and asset issuers can add Cross-Chain Verifiers to apply their own checks alongside Chainlink’s default verification network. Chainlink says starter kits will let users run those verifiers on infrastructure including Amazon Web Services and Google Cloud.
The added checks could matter to firms with internal security or compliance requirements. An issuer, for example, may want a transfer to proceed only after its own verifier has approved it.
CCIP 2.0 also offers configurable compliance controls, fees, and execution options, allowing users to choose how a transaction is checked and completed. These features are optional; Chainlink says its existing verification network remains the default.
Speed is another part of the upgrade. CCIP 2.0 supports faster-than-finality transfers where a user’s chosen risk settings permit them.
Chainlink also says it is working to support Ethereum’s Fast Confirmation Rule when that feature launches. Its future integration should not be treated as a speed improvement already available for every Ethereum transfer.
The supplied market analysis reported an 89% jump in LINK trading volume following the CCIP 2.0 announcement.
Higher volume shows that more tokens changed hands during the move, but it does not, by itself, show whether buyers will remain in control.
The same analysis cited a recovery in Chainlink’s total value secured from about $43 billion in June to $57 billion in August. That metric describes value associated with assets using Chainlink services; it is distinct from revenue earned by Chainlink or the market value of the LINK token.
The product announcement gives traders a reason to reassess Chainlink’s role in institutional blockchain infrastructure. Even so, a network upgrade does not automatically create immediate demand for LINK. Adoption, usage, and the broader market’s direction will matter to whether the price move lasts.
Can LINK break above $15?
LINK’s advance encountered selling pressure near $15, a level the supplied daily-chart analysis identifies as immediate resistance.
It also noted a bearish divergence in the relative strength index: price strengthened while the momentum reading weakened. Such a signal can precede a pause or pullback, although it does not establish that one must occur.
If LINK retreats, the analysis places a possible support zone at 12–13. Holding that area could leave the broader recovery intact, while a decisive break below it would weaken the bullish setup.

A sustained move above $15 would shift attention toward higher levels, including the article’s $20 upside scenario. From $12, a rise to $20 would be roughly 67%, but that percentage describes a hypothetical entry and exit, not an expected return.
For now, the clearest test is whether LINK can absorb selling around $15 while maintaining support if the wider crypto market remains under pressure.
BTC’s move above $80,000 has triggered a “double-bottom breakout,” a technical analysis pattern confirming a bullish trend and opening the door for a rally to $100,000, according to Jurrien Timmer, director of global macro at Fidelity Investments.
“Bitcoin is looking particularly interesting here as it challenges key resistance at $80k. If it breaks it will confirm a double bottom targeting $100K,” Timmer wrote on X on Friday.
A double bottom looks like the letter W on a price chart. The price drops to a low, bounces, falls back to roughly the same level, then rises again. The two dips show buyers stepping in at the same price twice. The peak in the middle of the W acts as resistance. A break above it suggests sellers have run out of steam and a new uptrend may be starting.
Timmer’s chart shows bitcoin’s two lows this year at $60,033 and $57,742, with the middle peak near $82,800.
Chart patterns are not guarantees. Breakouts often fail, reversing quickly and trapping buyers who chased the move.
Still, the bullish setup is consistent with options traders positioning for more gains. The $90,000 call is the most popular bitcoin options bet on crypto exchange Deribit, with $2.45 billion in open interest. The $95,000 call follows with $2.33 billion, and the $100,000 call holds $1.79 billion. A call gives the buyer the right to buy at a set price and profits when the market rises above it.
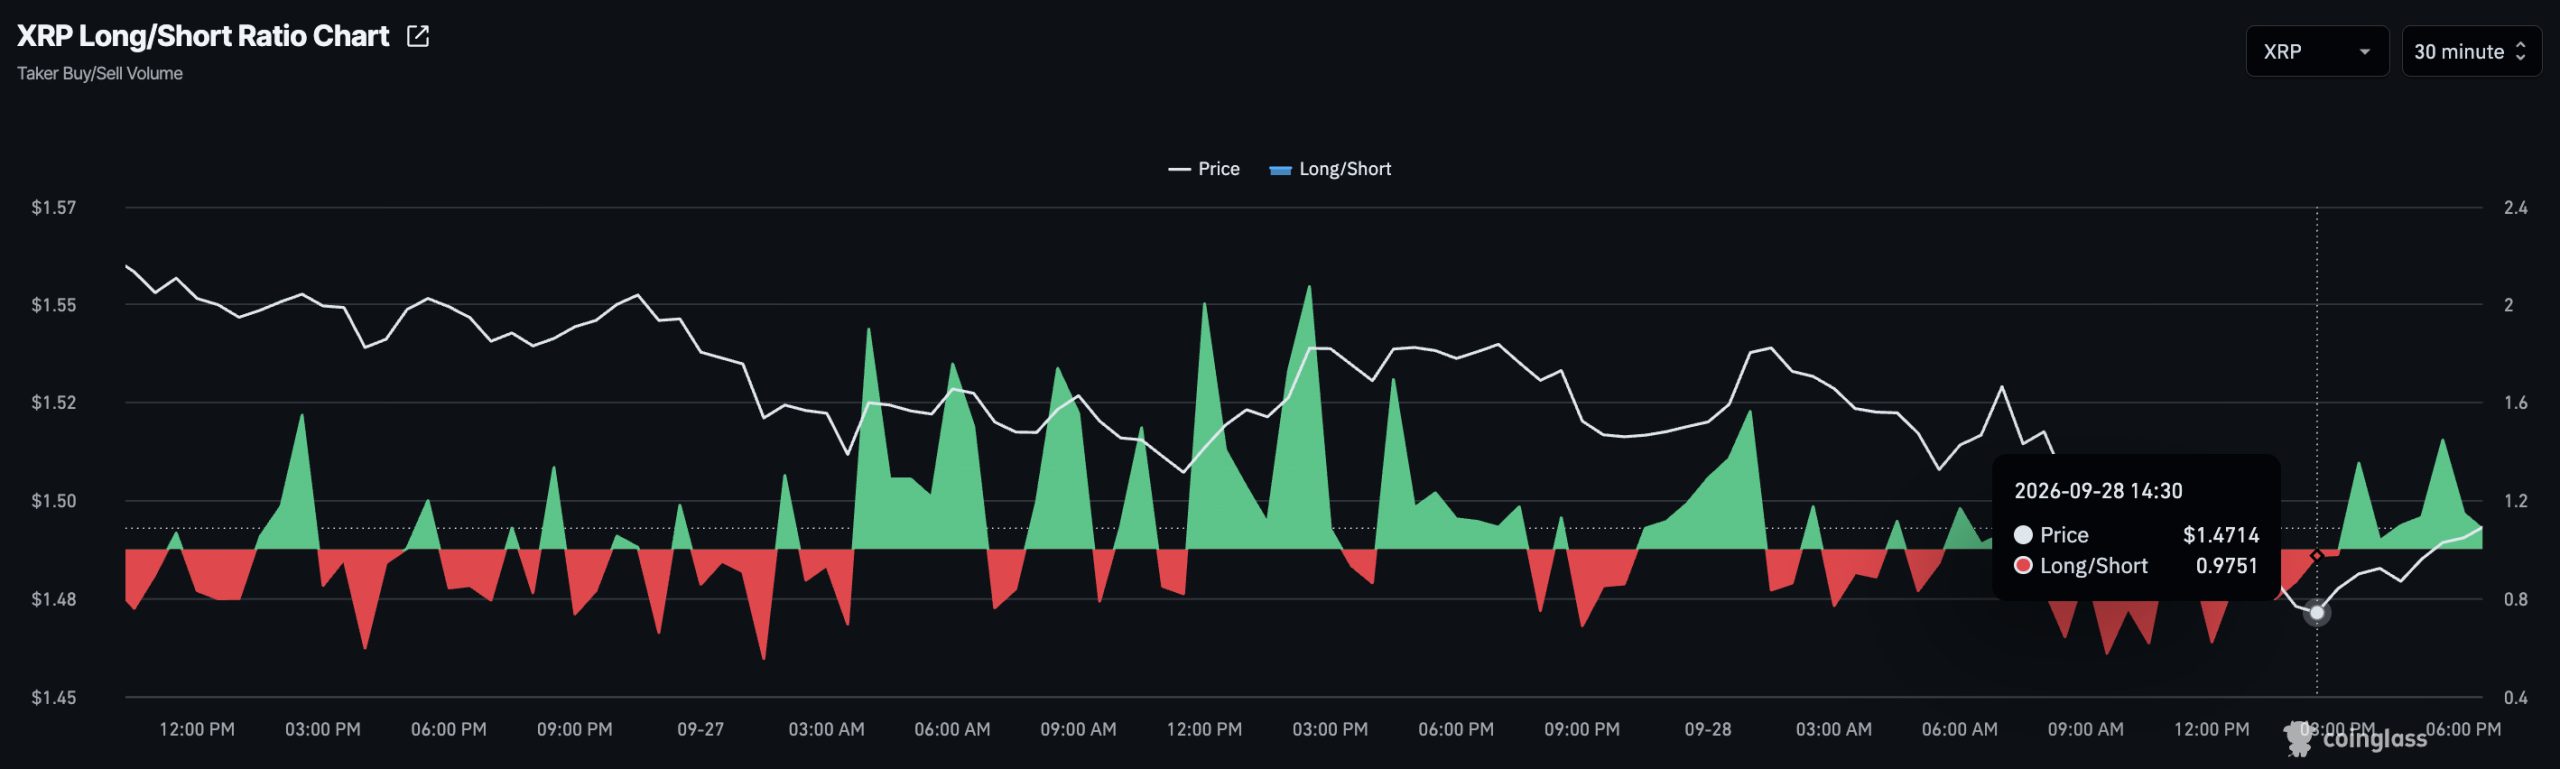
XRP price hovers under $1.49 after three consecutive daily declines left the token losing the $1.50 support, even as a modest bounce pulled it off session lows. CoinGlass data showed the long-to-short ratio at 0.975, meaning short positions marginally outnumbered longs, while the funding rate sat at a positive 0.008%, the reading that determines whether long or short traders pay a periodic fee to hold perpetual futures.
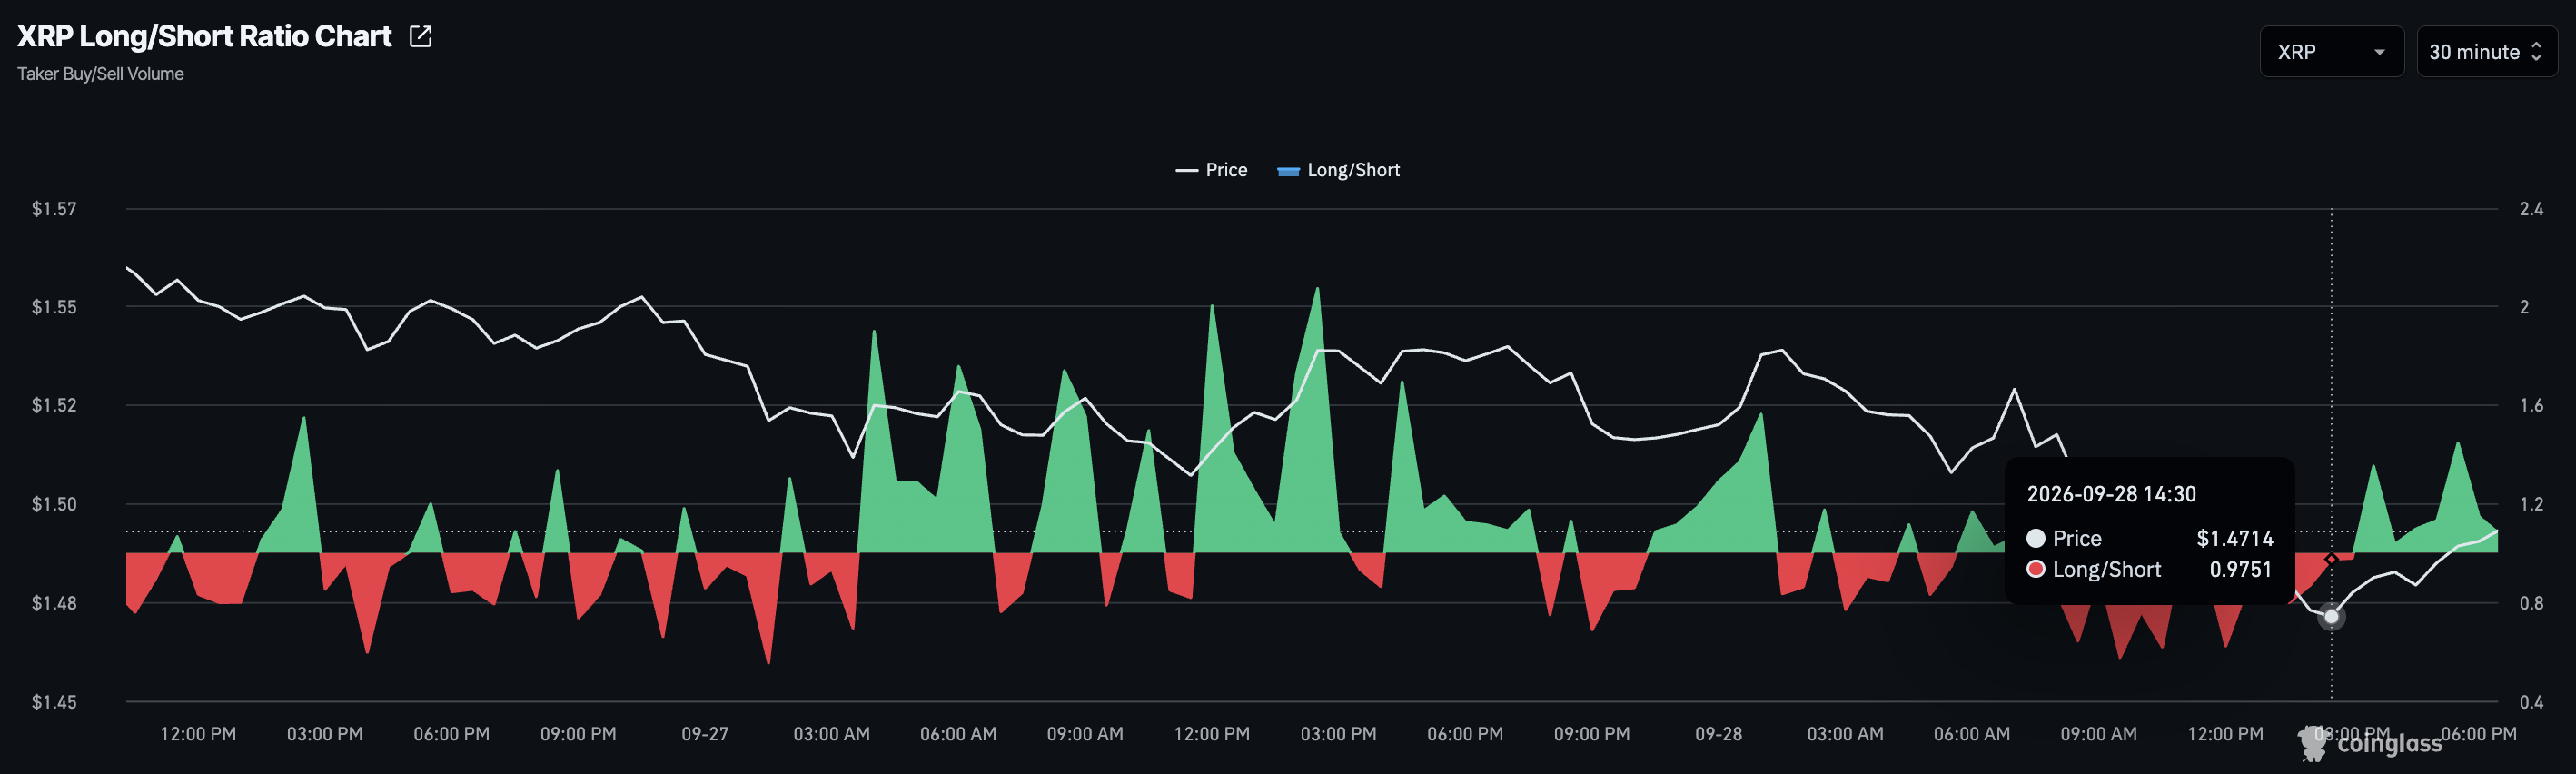
XRP Long Short Ratio, Coinglass
That combination is the crux of the problem. Traders are still paying to stay long, yet the spot price has not moved in a way that rewards the bet, and the disconnect between heavy spot selling and futures demand is the setup that tends to unwind fast once a key level gives way.
A 0.975 long-to-short ratio is not a bearish signal in any decisive sense. It sits close enough to 1.0 that it reads as near-balanced positioning rather than a market leaning hard in either direction.
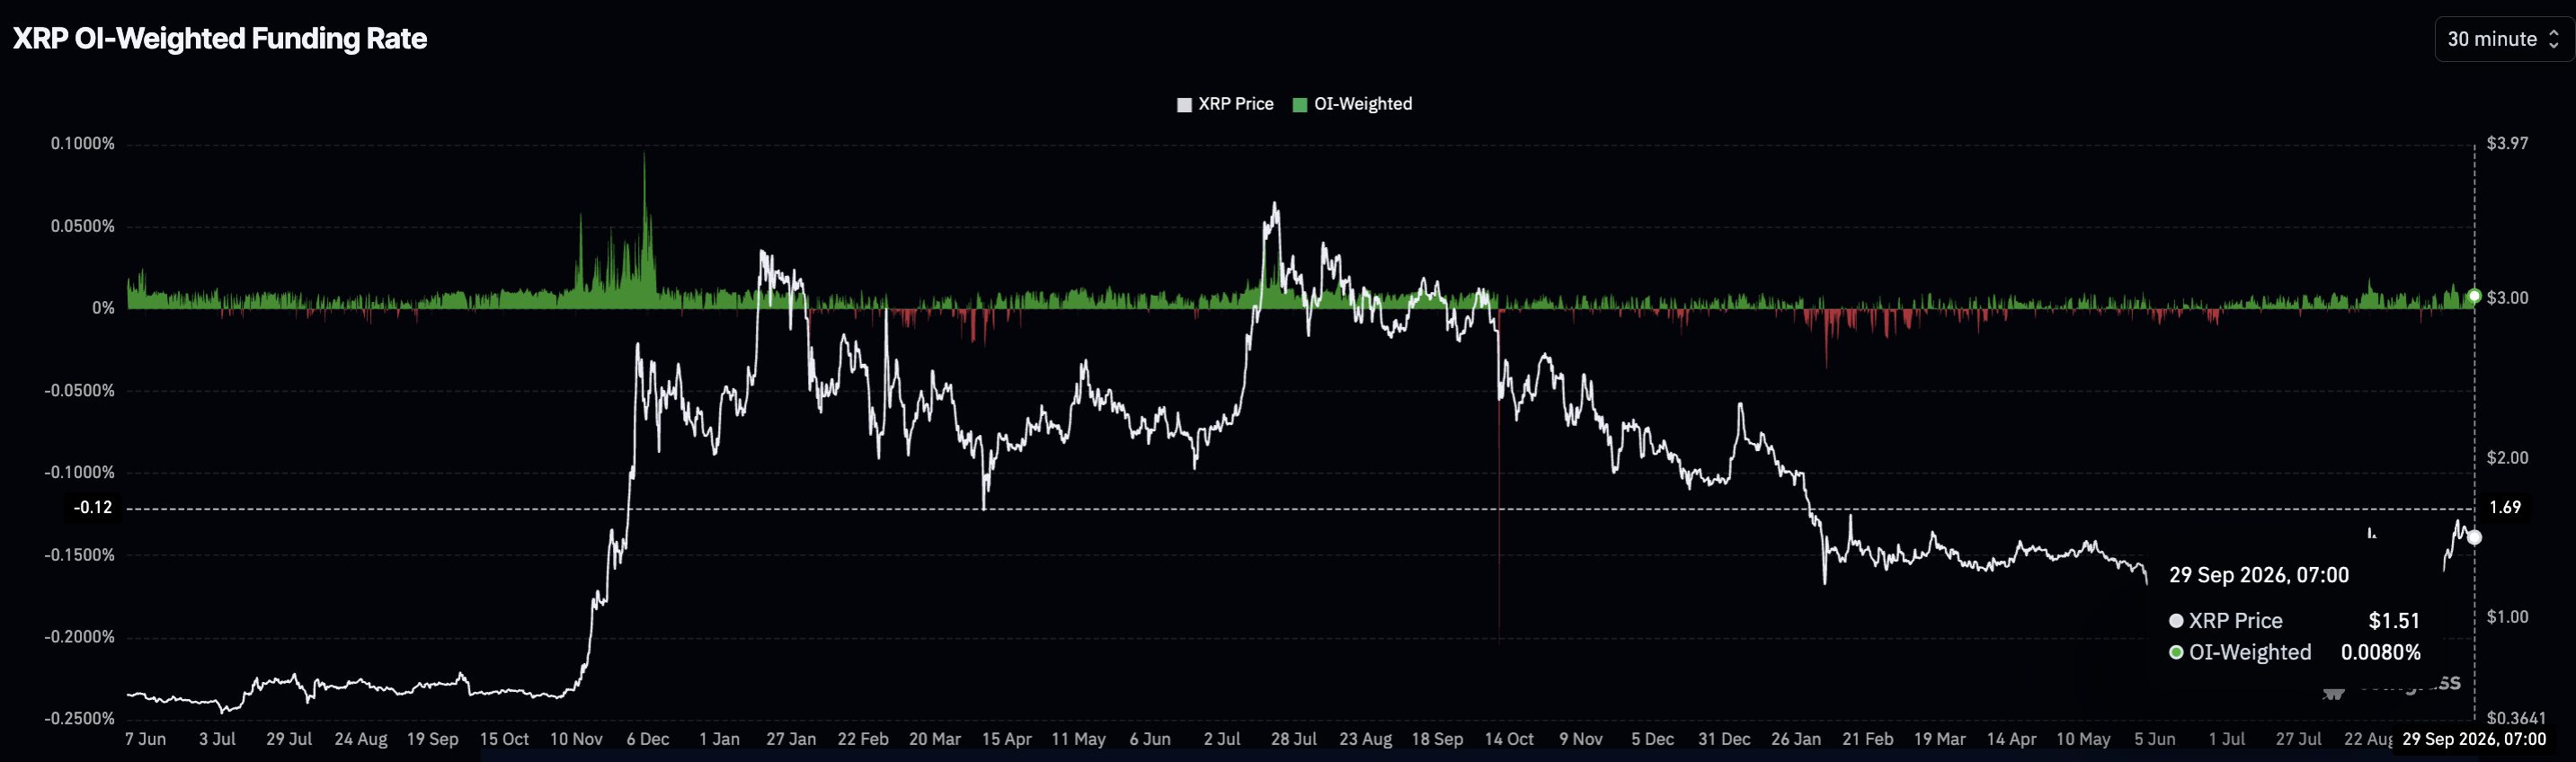
XRP Funding Rate, Coinglass
Funding tells a more interesting story on its own. A positive rate means demand for long exposure in crypto derivatives is real enough that longs are compensating shorts to hold the position, which typically signals conviction that price moves higher.
However, it cuts both ways: if price falls further, those same leveraged longs become forced sellers, and a positive funding regime built on thin spot demand can flip into a liquidation cascade faster than one built on genuine accumulation.
CryptoQuant’s summary data flagged overheating conditions across both XRP’s spot and futures markets, alongside sell-side dominance in futures, meaning sellers have retained the upper hand in derivatives even as funding stays positive. That is the missing piece: positive funding shows traders are willing to hold bullish exposure, but it has not yet translated into enough buying pressure to absorb the futures selling and push through resistance.
Earn $50 and Enter $300K Prize Draw on EdgeX
XRP Price and the $1.37 Support
The daily chart still leans bullish on a longer timeframe. XRP held above its 50-day price exponential moving average near $1.365 and its 200-day EMA near $1.369 through the three-day slide, with the 100-day EMA sitting lower at $1.307 as a secondary reference.
Momentum has cooled rather than reversed. The RSI sat near 55, close to neutral, and the MACD flattened around zero, a pattern consistent with consolidation after an earlier advance rather than an active breakdown.
The level that matters most sits at $1.37, where the 50-day and 200-day EMAs converge into a single support band. A clean break below that zone opens the $1.30 area, and a deeper slide would eventually put the $1.00 psychological level in play, though XRP would need to fall substantially before that becomes the immediate focus. On the upside, reclaiming the $1.574 resistance level is the trigger that would strengthen the case for a move toward $1.90.
Trade XRP on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
What Happens Next for XRP?
Two scenarios frame the near-term path. If XRP holds the $1.37 zone, the market stays in a consolidation phase where positive funding continues to reflect trader appetite for long exposure, but that alone won’t confirm a breakout without a corresponding rise in open interest and spot volume.
If XRP price instead reclaims $1.574, the technical case for a run toward $1.90 gets meaningfully stronger, and that move would likely force shorts to cover into strength. The alternative is a sustained break below $1.37, which shifts focus to $1.30 as the next line of defense, with $1.00 as the deeper level only if that support also fails.
Either way, the current setup leaves no room for complacency on either side of the trade. Near-balanced positioning combined with positive funding and futures sell-side dominance is a fragile mix, and the next move in spot price will do more to settle the argument than another shift in the long-short ratio.
Discover: The Best Token Presales
The post XRP Price in Danger: Positive Funding Masks a Fragile Setup appeared first on Cryptonews.
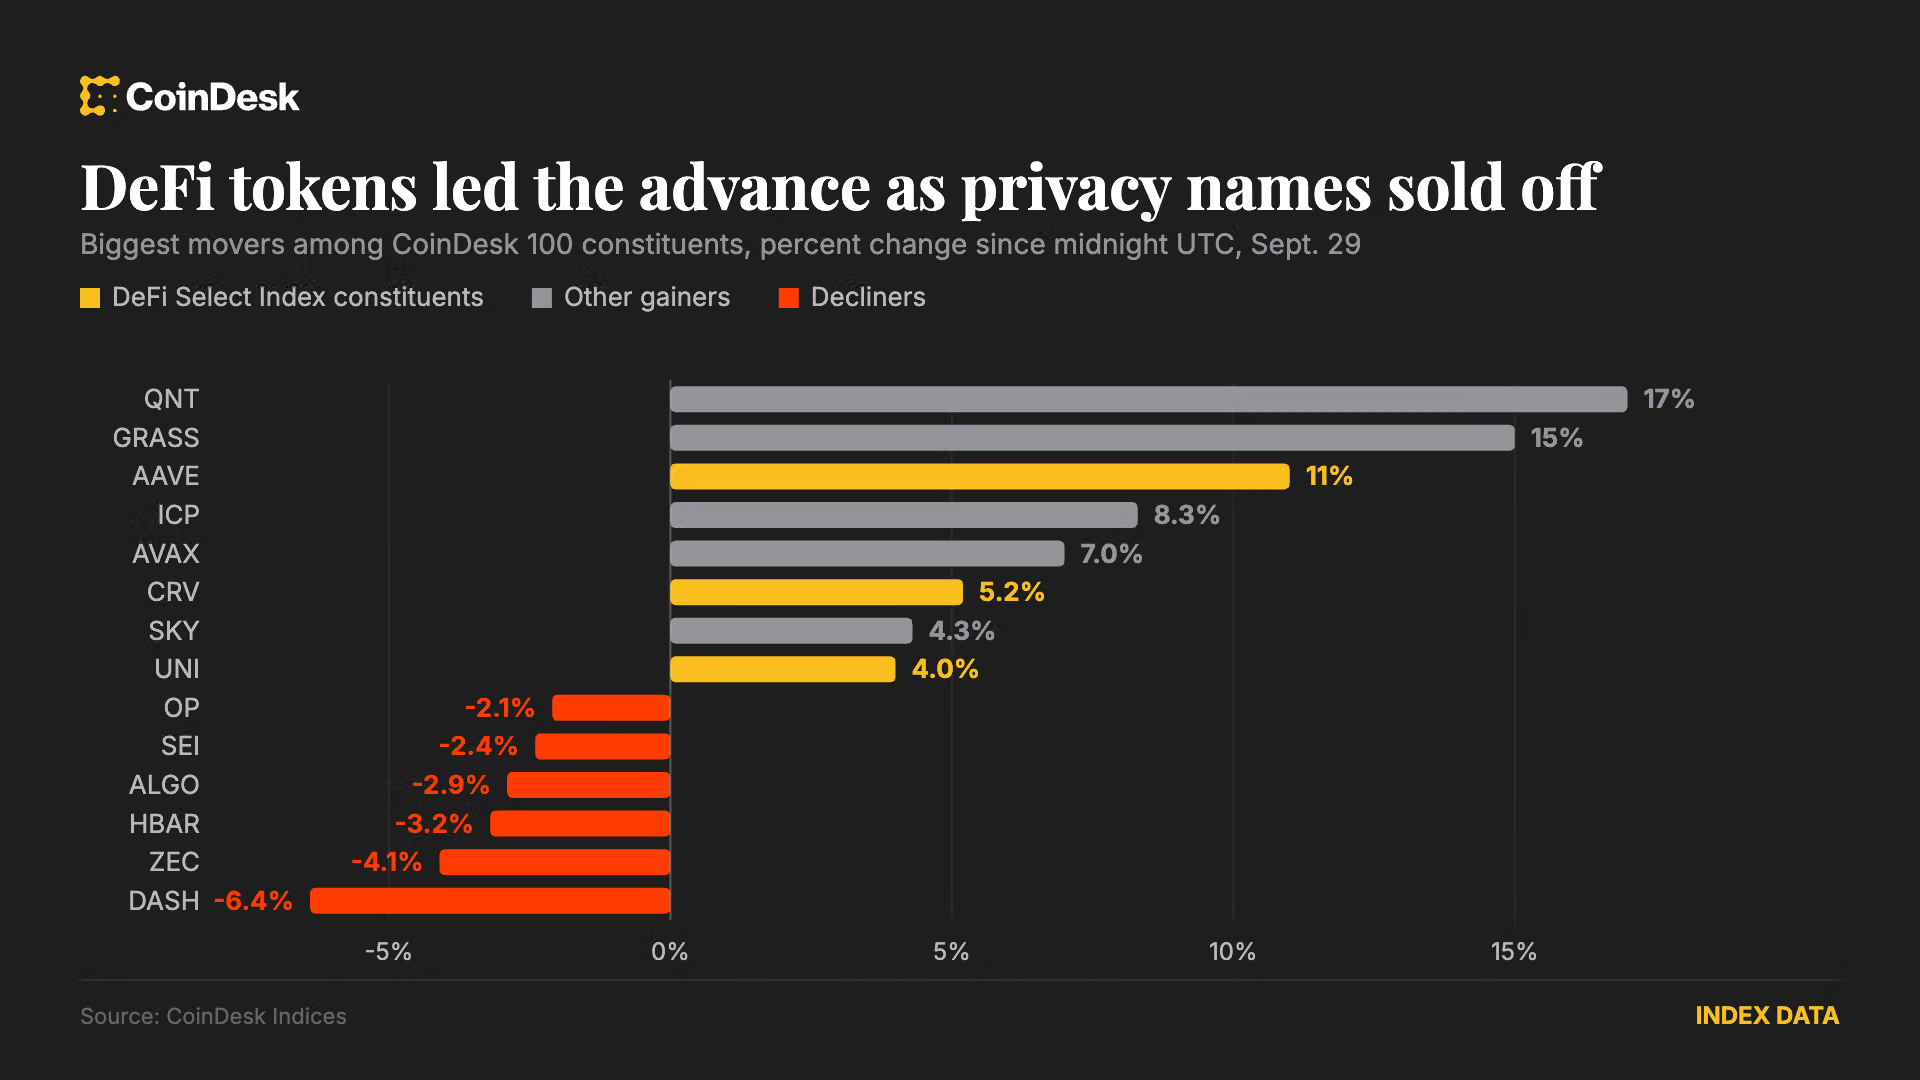
Bitcoin recovered Monday’s losses to trade at $84,170 on Tuesday, up 0.82% since midnight UTC and 1.4% over 24 hours, with 72 of the 100 CoinDesk 100 constituents higher and the index adding 0.89% to 1,904.49.
The bid is arriving despite conditions that have been suppressing risk assets for a week, the 10-year Treasury yield sitting at 5.234% after ending Monday above 5.2%, near levels last seen in 2007, and the 30-year at 5.549% having topped 5.56% on Monday, around a 2004 high.
U.S. stocks fell for a second session on Monday, the Dow dropping more than 300 points and the S&P 500 and Nasdaq Composite shedding 0.8% and 0.9%, with futures mixed on Tuesday morning.
Decentralized finance (DeFi) is driving the move for the second time in a week, with the DeFi Select Index (DFX) gaining 5.0% since midnight, led by lending protocol token aave at 11% and curve dao token at 5.2%. The CoinDesk 80 rose 2.0% against the CoinDesk 5’s 1.3%, though the ranking inverts over 24 hours, where the CD5’s 1.7% beats the CD80’s 0.44%.
The D’CENT wallet hack, the year’s second-largest drain of XRP behind the Bitget crypto exchange hack, has spilled beyond the XRP Ledger onto additional blockchains like Bitcoin, Ethereum, and Stellar.
Hackers have drained more than 12.4 million XRP from more than 7,000 D’CENT wallets, still some way behind Bitget’s loss of 102.9 million XRP.
Although the wallet was popular among the XRP community, D’CENT users who owned assets of other blockchains have also lost their funds.
D’CENT’s own disclosure named Bitcoin, Tron, and Ethereum, for example. Even a Stellar user has lost XLM in the incident.
Hackers are able to sweep funds across blockchains with one compromised recovery phrase for the multi-blockchain wallet.
IoTrust, the maker of D’CENT, confirmed at least 110 abnormal transfer reports, including non-XRP assets, per ZDNet Korea.
XRP holders lose $18 million in D’CENT hack
Drains of XRP are the most well-documented, due to the prominence of D’CENT among XRP holders.
At least six waves of theft occurred between September 15 and 20, emptying 6,678 wallets of 11.7 million XRP.
The thief stole from large wallets first, by hand, and soon wrote scripts to take funds from progressively smaller wallets.
Warnings from D’CENT and other members of the XRP community couldn’t stop the drainage. Thieves took 640,370 additional XRP after September 21, bringing the tally to above 12.4 million.
By Friday, 6.3 million of those stolen XRP had crossed to Ethereum’s blockchain through the swap service THORChain.
As the theft spilled over to other blockchains, researchers admitted the scope of the losses, saying, “Most of it is no longer XRP.”
Read more: David Schwartz warns of hard fork because XRP nodes won’t upgrade
In August, D’CENT was still touting its hardware wallets’ secure element, boasting that it was impervious to vulnerabilities linked to the Coldcard hack.
D’CENT now warns users that wallets they created using its app are vulnerable, urging them to create a fresh recovery phrase and immediately migrate everything, including tokens, NFTs, and any staked assets.
Got a tip? Send us an email securely via Protos Leaks. For more informed news and investigations, follow us on X, Bluesky, and Google News, or subscribe to our YouTube channel.
Market action since 2022 backs Thielen’s take. The 10-year yield more than doubled to 3.88% that year as the Fed raised interest rates rapidly, including several 50- and 75-basis-point hikes to fight inflation.
Bitcoin fell 64% that year. Fed tightening and rising yields added to the pain from crypto scams and blowups.
The picture has been different since. From the end of 2023, the 10-year yield has risen 135 basis points to 5.23%, the highest since 2007. Over the same stretch, bitcoin has roughly doubled to $86,000, even after pulling back from its October record above $126,000.
Thielen and others attribute much of the recent rise in yields to fiscal fears and a higher term premium. In plain English, investors want to be paid more to lock up their money in long-term bonds, given the uncertainty over inflation and government borrowing.
Chicago-based Strategic Analytics made a similar point about gold, noting that it has tracked fiscal risk more closely than the Fed’s policy path since 2022.
“Since 2022, gold has increasingly tracked fiscal-risk perceptions – term premium, deficits, debt sustainability – rather than the Fed’s policy path. Gold is not defying real yields. It is pricing fiscal sustainability and currency debasement, which has become the marginal driver,” it said recently in a LinkedIn post.
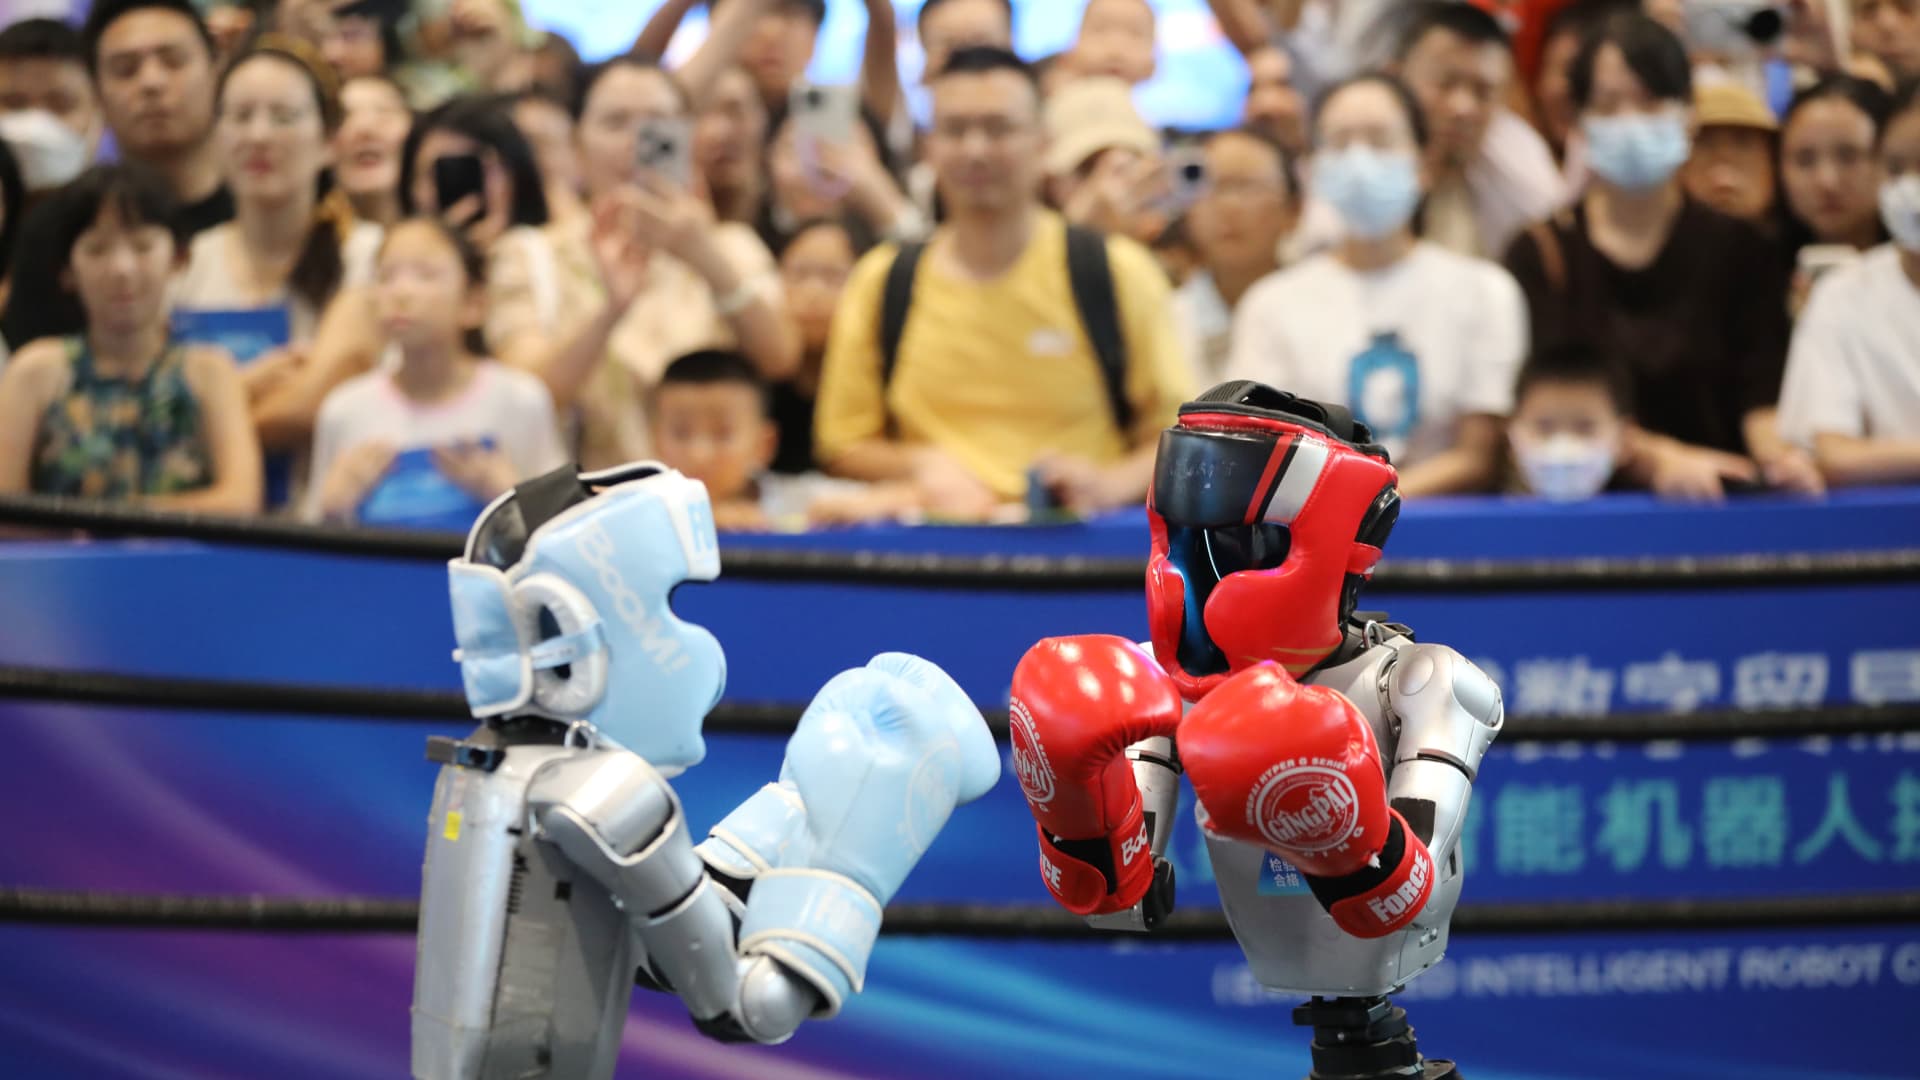
Humanoid robots box during the 5th Global Digital Trade Expo on September 25, 2026 in Hangzhou, Zhejiang Province of China.
Vcg | Visual China Group | Getty Images
BEIJING — China’s securities regulator is raising the bar for public listings of humanoid robot startups, according to three sources familiar with the CSRC’s thinking.
It’s a sign of how one of the hottest sectors of the market is cooling, as investors globally assess whether artificial intelligence stocks are in a bubble.
The Chinese regulator wants local “embodied AI” startups seeking to go public to meet three specific criteria, according to the sources, who requested anonymity due to the sensitivity of the situation.
They are:
- The “window guidance” requires that the humanoid applicants have sustainable revenue and commercial orders.
- Losses must narrow, with one source saying a three-year forecast is needed.
- The company must possess core technology such as robotic brain or hands.
Even if a startup only has to meet two of the three criteria, as one source indicated, it’s unclear which, if any, of the companies can do so.
That’s lowered expectations to just a handful, or none, of these startups making it to public markets, the sources said.
At least two dozen humanoid-related embodied AI companies have filed to list in Hong Kong alone, according to two of the sources. Hong Kong in May 2025 started letting tech companies file confidentially for IPOs.
The Hong Kong stock exchange declined to comment. The China Securities Regulatory Commission did not immediately respond to a request for comment. Mainland China companies wanting to list in Hong Kong also need the CSRC’s blessing.
Unitree IPO impact
Scrutiny on China’s growing number of humanoid robot startups and their fast-growing valuations — supported by a mix of government and private sector funds — has grown over the last several weeks.
The industry’s posterchild, Unitree, got a regulatory fast-track to its listing in Shanghai on Aug. 19 as the World Robot Conference kicked off in Beijing.
But in a keynote a day later, founder Wang Xingxing cautioned that commercialization beyond dancing robots remained years away. It accentuated a debate that picked up in subsequent weeks on what humanoids can actually do — and whether industry startups were actually making money.
China now has well over 100 humanoid companies, which fall under the national push for “embodied AI.” The term received Beijing’s support in the last two annual government work reports, although authorities have warned of a bubble in the humanoid robot industry.
Reflecting a rapid surge in interest, investment in the sector hit 47.09 billion yuan ($6.95 billion) in the second quarter, more than double that of the first quarter — and up over six times versus the same period last year, according to industry data provider Xiniu.
Unitree raised about about 6.1 billion yuan ($905 million) in its IPO on Aug. 19 with Shanghai-listed shares skyrocketing more than 460% in their debut to close at 845 yuan.
The stock had nearly halved in price as of Monday, at 459.65 yuan a share.
Hong Kong-listed Ubtech has also tumbled more than 40% so far this year. The company, which went public in December 2023, still reported an operating loss for the first half of this year of 279 million yuan.
The share price decline contrasts with the flood of capital pouring into humanoid robotics companies over the last 12 months or so. The tech, often called “physical AI” in China, has been seen as a way for early-stage investors to benefit from the surge of interest in artificial intelligence models.
However, Rhodium Group analysis this month found that China’s AI companies only make about 10% the revenue of Anthropic and OpenAI. The ratio of valuation to revenue — especially for Chinese AI startups Moonshot and DeepSeek — was far higher than their U.S. rivals, the report said.
While expectations grow for the U.S. AI giants’ IPOs, chipmaker AMD said Monday it is acquiring World Labs for $8.2 billion in a stock deal. The startup, founded by AI pioneer Fei-Fei Li, is building AI models for creating virtual 3D environments frequently used in humanoid robot development.
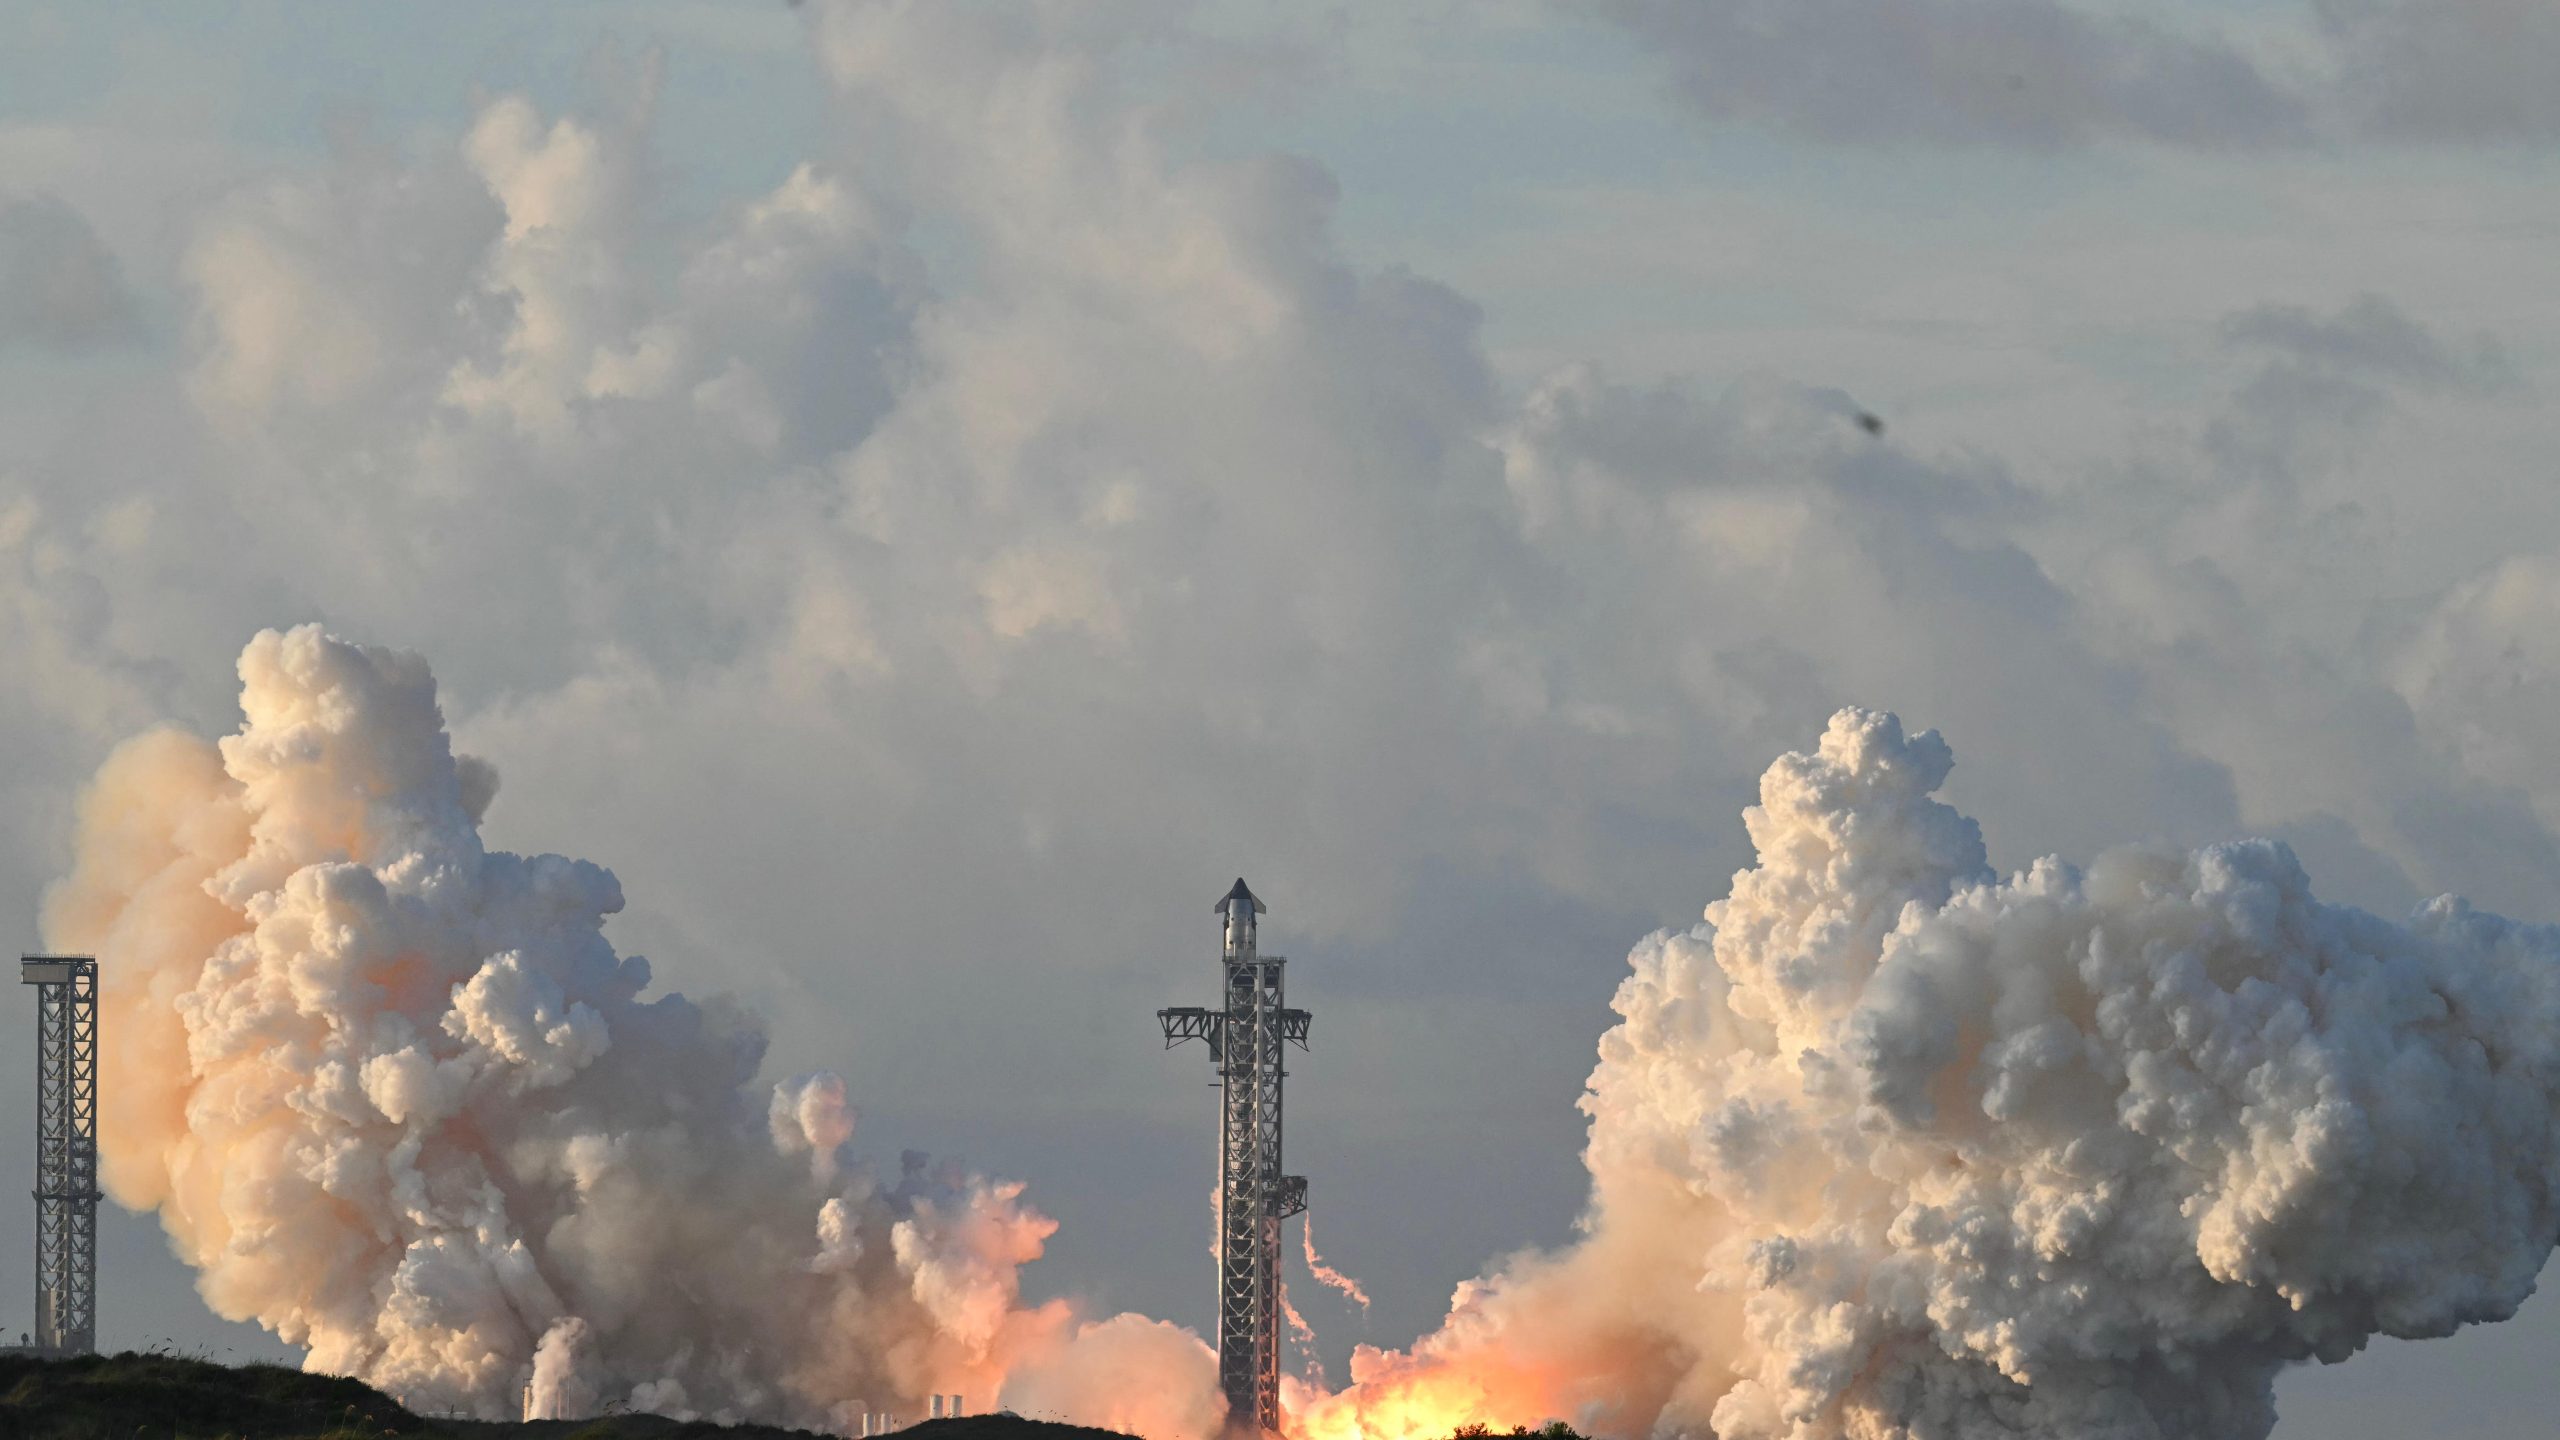
The launch this morning was both imperfect and stripped down to its orbital essentials. On the way up, one of the Starship’s six engines failed to burn properly, requiring the other engines to compensate for the missing thrust to get the ship in orbit.
In addition, the return to Earth was simplified. SpaceX has made itself famous for safely landing the first stage of its Falcon 9 and Starship boosters—with 641 out of 688 Falcon 9 launches featuring this kind of recovery, allowing the boosters to be reused and make flying cheaper. Starship’s first stage, meantime, performs what has become known as a chopstick recovery, with the booster navigating its way back to the launch tower where two giant metal arms pluck it from the sky. For the current mission, the chopstick recovery was done away with to simplify the flight objectives; instead the first stage made a soft, engine-assisted splashdown in the Gulf of Mexico. The Starship spacecraft was planned for a six-orbit, 10-hour mission, with the ship’s engines set to fire around the dinner hour Monday to bring the spacecraft down for a similar gentle, watery landing.
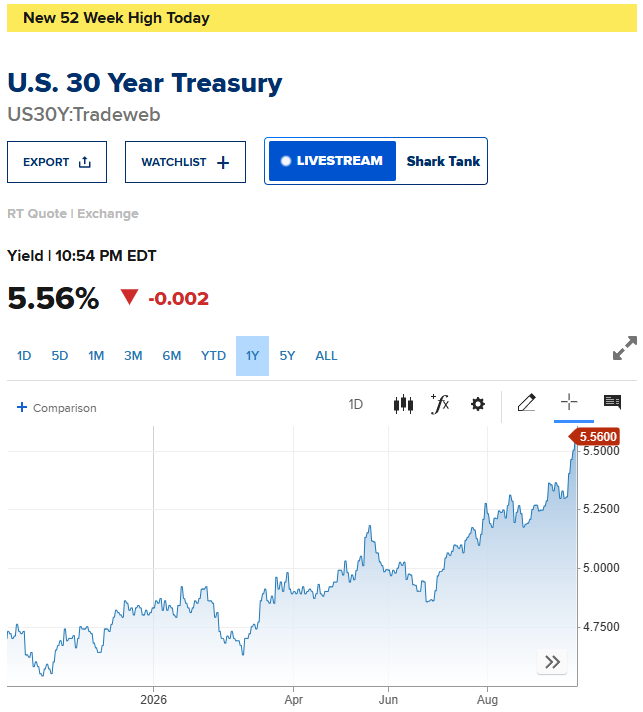
Goldman Sachs’ Anshul Sehgal says bonds yielding 5% or more are not the best trade right now. He still favors AI infrastructure, which he sees as a far more asymmetric bet than the long bond.
Sehgal, a global co-head of Fixed Income, Currencies and Commodities (FICC) at the bank, laid out the view just a few days after the Federal Reserve raised interest rates.
Why Goldman Sachs Is Passing on 5%+ Bonds
On Goldman’s The Markets, Sehgal said the 30-year Treasury, known as the long bond, had hovered around 5% for weeks. He noted that clients want to buy it at 5% or higher, yet he still sees little upside.
The yield has kept climbing since the recording, reaching 5.56% on September 29, a new 52-week high. Sehgal blamed structural pressure for the strain on the long end. Retiring baby boomers are buying fewer long bonds, and heavy long-dated borrowing tied to AI is crowding the market.
Those pressures explain why the selloff can persist even without a fresh inflation shock. Fewer retirees buying long bonds and a steady flow of long-dated borrowing tied to AI both weigh on prices, and neither fades quickly.
Sehgal adds that fear over US debt sustainability makes investors less willing to hold the long end, which feeds on itself.
The takeaway is that a rising yield does not necessarily break his thesis. It may instead show why he sees limited reward in owning the bond, while the risk to his AI trade is that costlier long-term borrowing squeezes the levered companies he favors.

AI Compute Is the Asymmetric Trade
An asymmetric trade offers far more potential gain than risk. Sehgal applies that label to compute (AI computing power), data centers, and Neoclouds, which are cloud providers built to rent out that capacity.
“I think the asymmetric expression is being long compute.”
Anshul Sehgal, Goldman
The catch is leverage. Savers collecting higher interest have effectively financed the AI build-out, leaving equities more indebted than a year ago. Sehgal admits these are levered bets. Still, he thinks they can multiply in value, while the wider stock market looks less certain.
Tighter Policy Hits Spenders, Not Capital
Sehgal says the Fed frames its September 16 hike as catch-up after five years above its inflation target. Schwab counts 16 of 19 Fed officials expecting another increase this year. Fed Chair Kevin Warsh also stressed three times that the Fed is easing back some stimulus rather than turning restrictive, Sehgal adds.
He argues that government interest payments flow to capital rather than workers, so higher rates curb household spending, a risk for the broader stock market.
He also rejects the debt-sustainability fears weighing on long bonds.
“For me, that’s a red herring.”
Anshul Sehgal, Goldman
Meanwhile, BlackRock’s Rick Rieder is cutting equities for bonds paying 7% to 8%, though his high-grade bond call still cautions against rushing into the 10-year Treasury.
Sehgal names the Middle East conflict as the top driver of policy and markets in the weeks ahead.
The post Goldman Sachs Explains Why Not to Buy the 5%+ Bonds and Rather Stick to AI appeared first on BeInCrypto.
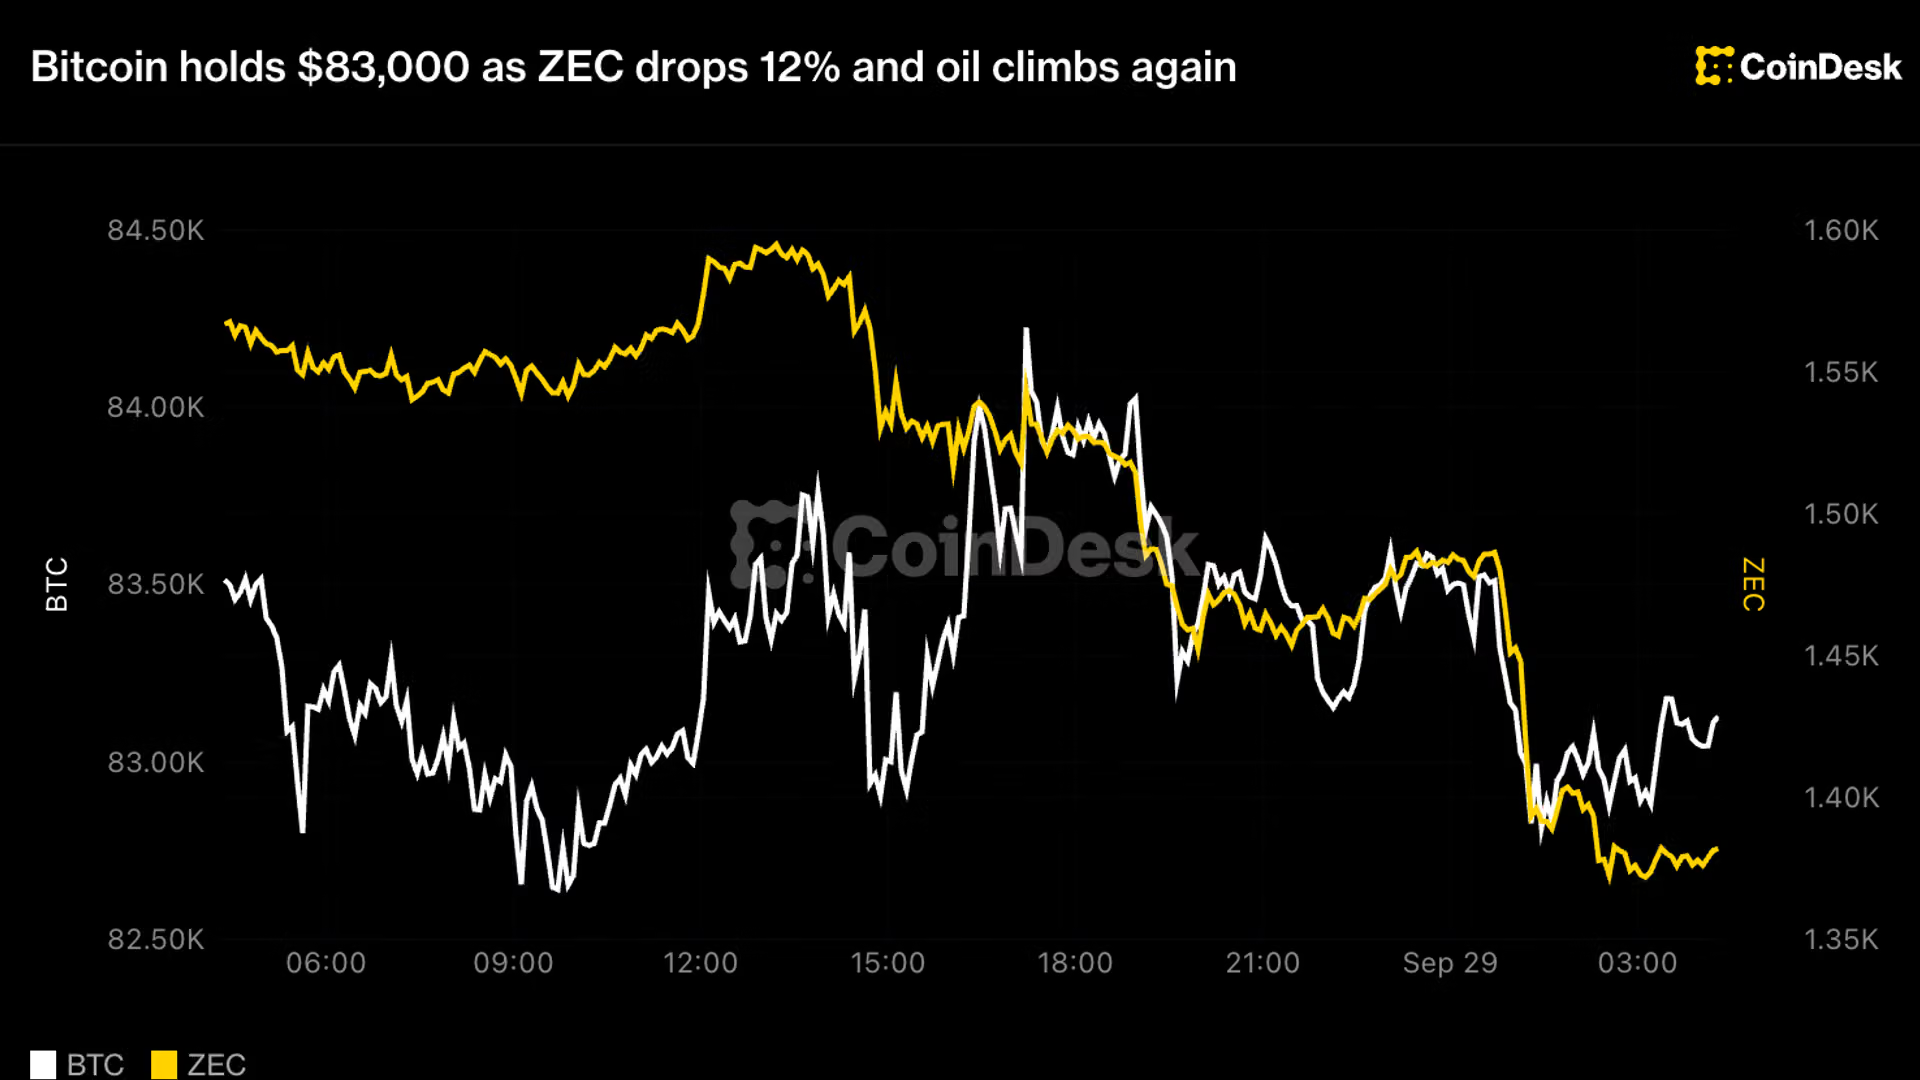
“Bitcoin has pulled back to $83K, testing the lower boundary of last week’s consolidation range,” Alex Kuptsikevich, chief market analyst at FxPro, said in an email to CoinDesk. “As with the market as a whole, a retest of the $82K region, where peaks were formed in May and early September, is entirely to be expected under current conditions.”
“Looking ahead, a sustained return to prices below $80K would be an important signal that the market is not ready to move higher for some time yet. If, however, this consolidation is soon followed by a new bullish momentum, it could send the leading cryptocurrency well above $90K,” he added.
The pressure is coming from bonds and oil.
Treasuries steadied in Asia after tumbling during U.S. trading, with the 10-year yield up one basis point to 5.25% after reaching its highest level since 2007 on Monday. A higher guaranteed return on government debt raises the bar for holding assets that pay no income, bitcoin among them.
Brent rose more than 1% to nearly $107 a barrel, its second straight gain, as hopes for an imminent diplomatic breakthrough with Iran faded.
Pricier oil feeds into inflation, and traders have been adding to bets that the Fed will raise rates again. MSCI’s All Country World Index fell to its lowest since Sept. 18, and Nasdaq 100 futures slipped 0.3% after Monday’s tech-led selloff on Wall Street.

Chainlink surges 6% after CCIP 2.0 launch, but $15 resistance tests LINK rally – CoinJournal

October Skies Will Put On a Show: Here’s When to Look Up

Bangkok floods threaten to shave 0.3 percentage points from Thailand’s 2026 growth


-
 Fashion4 days ago
Weekend Open Thread: J.McLaughlin – Corporette.com
-
 Crypto7 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-
 Tech & AI2 days ago
Anthropic turns Claude into an AI marketplace with 2,000+ plugins and connectors
-
 Tech & AI2 days ago
OpenAI is preparing “o,” an always-on ChatGPT assistant that could handle email
-
 Fashion5 days ago
8 iPhone Accessories That Add Personality
-
 Entertainment6 days ago
These 17 Fall Amazon Dresses Seriously Look Like Anthropologie
-
 Tech & AI7 days ago
Reolink’s solar 4K security camera falls to its lowest price in months
-
 Crypto6 days ago
This Bearish Netflix Stock Trade Can Cash In On Video Streaming Giant’s Woes
-
 Crypto6 days ago
BitGo says Bitcoin absorbed Fed hike, CLARITY failure
-
 Crypto6 days ago
Crude Oil Prices Pressured by Diplomatic Hopes in the Middle East
-
 Crypto6 days ago
Bitcoin price tests $83,600 Supertrend support after $87K rejection
-
 Business & Hussles6 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-
 Crypto6 days ago
Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike
-
 Crypto7 days ago
Did Jim Cramer Just Give GameStop Stock the Kiss of Death When He Said the Turnaround Is Working?
-
 Tech & AI6 days ago
UiPath’s Dines says AI needs a manual and launches Cartographer to write it
-
Business & Hussles16 hours ago
Perpetua Resources at Mining Forum Americas 2026: shift to construction
-
 Crypto6 days ago
As Amazon Stock Prospers, Traders Might Consider This Option Play
-
 Crypto6 days ago
Strategy resumed Bitcoin buying, but Strive gained more BTC per share
-
 Tech & AI7 days ago
Sega nearly killed Sonic before the movies revived the franchise
-
 Crypto2 days ago
Wall Street Giant Warns AI Agents Could Trigger a New Kind of Bank Run
You must be logged in to post a comment Login