Crypto
Tokenized stocks expand access, but what do investors legally own? Tessera PE founder explains

Tokenized stock transfers have climbed to $29.5 billion as new products extend market access, but Tessera PE founder Chan Ahn says investors could receive anything from direct share ownership to a contractual claim carrying no shareholder rights.
Summary
- Tokenized stocks can represent direct shares, custodial claims, or synthetic contracts with different legal rights.
- Company rules, securities laws, and underwriter lock-ups can limit transfers even when tokens move on-chain.
- Pre-IPO tokens lack the public prices and company disclosures needed for dependable secondary markets.
- Tokenizing private credit may extend access without making complex AI infrastructure risks easier to value.
- U.S. investors remain excluded from several tokenized stock products offered under Regulation S.
Tessera PE founder Chan Ahn told crypto.news that similar marketing terms often conceal substantial differences in what token holders own, how they receive dividends, and whether they can vote on company matters.
Ahn said he had not previously published an analysis of Securitize and based his comments about its model on publicly available information. He also separated Securitize’s reported NYSE listing, the tokenization of its own stock, and its ability to support offerings for other issuers, saying each involves a different legal question.
Tokenized stocks can give investors three different claims
Under Ahn’s reading of a January SEC staff statement, tokenized securities generally take one of three forms: issuer-sponsored securities, custodial products, or synthetic contracts.
In an issuer-sponsored structure, the company supports the tokenization and presents the token as the security itself rather than as a separate wrapper. If the structure works as described, Ahn said the holder’s voting, dividend, and information rights should be the same as those attached to a conventional share because both formats represent the same instrument.
Still, two operating details determine whether a token holder owns the security directly. Investors need to know whether their names appear on the shareholder register or whether a nominee sits between them and the company. The platform must also explain how the on-chain position reconciles with the settlement of shares traded on a public exchange.
“The answers decide whether you hold the security or a claim on somebody who does,” Ahn said.
A custodial token creates a different relationship because the underlying shares remain off-chain with an intermediary. According to Ahn, the investor may instead receive a security entitlement under Article 8 of the Uniform Commercial Code, similar to the indirect ownership structure used when a person holds stock through a broker.
Voting materials, dividends, and company communications reach the token holder only through arrangements made by the intermediary. Ahn said one structure he reviewed used Broadridge to process proxy materials and issuer communications, matching infrastructure already used by conventional brokerages.
Custodian failure also creates a separate risk. While a registered shareholder has a direct relationship with the company, a custodial-token holder may have to pursue a claim through the intermediary’s insolvency process.
Synthetic tokens sit further away from the company. Buyers own a contract with the product issuer rather than a share or an entitlement backed by shares. Ahn said the SEC staff warned that some products in this category could qualify as security-based swaps, potentially limiting access to eligible contract participants.
“So the honest answer to ‘what does an investor own’ is: read which of the three you are being offered, because the marketing language is close to identical across all of them and the legal substance is not.”
Voting, dividends and access to company information provide a quick way to test a product’s structure, Ahn added. Investors should ask which entity owes them each right and what happens if that entity fails.
Tessera’s own products do not represent equity. Ahn said the company issues tokenized loan participation rights that provide economic exposure but carry no ownership, voting, dividend, or information rights in the underlying business.
Company rules can still block token transfers
Even when a token can move between blockchain addresses, Ahn said issuer approvals, securities laws, and contractual lock-ups can prevent the related ownership or economic interest from changing hands.
Closely held companies commonly impose board-approval requirements, rights of first refusal, and limits written into shareholder agreements. Private companies may maintain their own shareholder registers rather than employ an outside transfer agent, allowing them to reject transfers that do not meet their conditions.
“A token cannot move what the register will not record,” Ahn said.
Federal securities rules add another layer through Rule 144 holding periods, affiliate volume limits, notice conditions, and investor eligibility requirements. Underwriter lock-ups can reach beyond direct sales of shares by restricting transactions that transfer the economics of ownership.
Citing SpaceX’s final prospectus, Ahn said shareholders were barred from certain hedging or other arrangements without prior written consent from Goldman Sachs acting for the underwriters. The clause, subject to stated exceptions, reportedly covered direct or indirect transfers of the economic consequences of ownership, whether settled in shares or cash.
Such language means a token offering exposure to locked shares may raise a contractual issue even if the token is not legally classified as the underlying stock. According to Ahn, providers offering economic exposure to positions still under lock-up should be able to explain how the product complies with those agreements.
Permissioned blockchain systems can enforce some limits through approved wallets, identity checks, and jurisdiction screening. When the token is the security, its transfer controls may enforce restrictions imposed by the issuer. For a wrapper, however, the same controls may enforce only the provider’s terms, which do not necessarily match the company’s requirements.
The issue has become more relevant as tokenized shares move into decentralized markets. Coinbase recently added six tokenized stocks on Base after its first four products generated $227.7 million in decentralized exchange volume in about 30 days.
The additions included tokens linked to Amazon, Microsoft, Strategy, SanDisk, Tesla, and privately held SpaceX. Coinbase’s structure uses an Abu Dhabi Global Market entity to issue tokens against underlying shares or eligible equity interests held in custody, but holders do not appear directly on the companies’ shareholder registers.
U.S. persons cannot access the products because they have not been registered under the Securities Act of 1933 or state securities laws. Coinbase offers them under Regulation S, which covers qualifying securities transactions conducted outside the United States.
Tokenized stocks do not create dependable liquidity
Trading access alone does not produce a liquid market, especially when a token tracks a private company without listed shares, options, or available stock to borrow.
Ahn said market makers quote prices when they can offset risk elsewhere. With pre-IPO assets, they often lack a closely matched instrument for hedging, forcing them to retain the risk on their own books and charge for it through larger bid-ask spreads.
Valuation creates a harder problem. Publicly listed tokenized stocks can follow prices formed continuously during exchange hours, giving trading platforms an external reference. A private company has no comparable public market, leaving platforms to rely on the latest primary funding round.
Private-round valuations emerge from negotiations among a limited group that already owns or plans to buy the asset. Using that figure for secondary trading can make a negotiated private valuation appear like a market-established price.
“An AMM with no external reference is not discovering a price; it is reflecting the flows of whoever happens to be trading it that day.”
Disclosure poses the largest obstacle because a private company generally has no duty to provide regular information to holders of an instrument it did not issue or approve. A token may trade continuously while the company behind its value releases financial information only when it chooses.
According to Ahn, a stronger structure would include a written valuation policy, an identified independent valuer, and a fixed schedule for updating the asset’s value. Disclosure duties should appear in the instrument’s legal terms, while platforms should label quoted prices as indicative when they do not represent executable market prices.
On-chain activity has already grown despite such differences. An August report found that monthly stock transfers rose 415% to $29.5 billion, while tokenized equities distributed on-chain were valued at about $2.54 billion. RWA.xyz also counted around 1.3 million active addresses and 2.36 million tokenized stockholders, although wallet figures do not equal the number of individual users.
Collateral use adds another risk because price gaps can trigger liquidations. Chainlink recently introduced feeds for four stocks issued by Coinbase, allowing lending platforms to assess tokens linked to Nvidia, Meta, Apple, and Alphabet.
Coinbase’s product documents warn that thin liquidity and different trading hours can cause token prices to separate from the underlying shares when U.S. exchanges are closed. Lending platforms also set their own collateral limits and liquidation terms.
Tokenized private credit can spread hard-to-value risks
Moving from equity into private credit does not remove the valuation and disclosure problems, according to Ahn, particularly when the debt finances AI infrastructure whose equipment may lose value quickly.
Pointing to a CoreWeave Form 8-K, Ahn said the company entered a $2.6 billion delayed-draw term loan facility on Aug. 7, 2026, through a ring-fenced subsidiary, with JPMorgan acting as administrative agent. The filing said the money would finance spending needed to perform customer contracts, including purchases of graphics processing unit servers and related infrastructure.
Borrowings under the facility can continue through December 2026, while the debt matures on Sep. 1, 2031. Ahn noted that the parent company unconditionally guarantees the facility and that substantially all assets of the borrowing subsidiary secure it.
CoreWeave’s filing also listed certain adverse events affecting material customer contracts among the events of default. In Ahn’s view, the provision makes those customer agreements central to the credit structure rather than merely sources of revenue.
The central valuation question concerns what the financed accelerators will be worth several years from now. Tokenizing the loan exposure would not establish a market price for that equipment, Ahn said, but it could distribute the same uncertainty among more investors who may have less ability to examine the underlying contracts and collateral.
Ahn also cited a Chicago Fed study showing that the average bank’s outstanding exposure to AI-adjacent industries was about 0.8% of total assets. Committed exposure, however, was closer to 25% of Tier 1 capital, compared with outstanding commercial and industrial exposure averaging 9%.
Among large banks, commitments to AI-adjacent industries reached about $450 billion in late 2025, according to the study, while approximately $150 billion had been drawn.
Hut 8-owned BTC mining firm, American Bitcoin, has dramatically underperformed BTC since its reverse merger which allowed it to become publicly listed.
American Bitcoin has lost approximately 92% of its value (after accounting for its reverse stock split) since its merger.
BTC by comparison has lost a mere quarter of its value.
American Bitcoin claims that it “was formed through the strategic contribution of substantially all of Hut 8’s ASIC fleet into a new venture led by Eric Trump and Donald Trump Jr.”
More specifically, Eric Trump served as chief strategy officer during this >90% decline.
Donald Trump Jr. provides advice to the firm in his role as senior adviser.
Together they’ve led this firm which is supposedly “a pure-play BTC accumulation platform that integrates scaled BTC mining operations with disciplined accumulation strategies” into a substantial decline that has far outpaced the decline of BTC.
Read more: Trump promised bitcoin ‘made in America’ then ruined it with tariffs
American Bitcoin reported a net loss of over $150 million for 2025.
For the first six months of 2026 it has added to those with an additional $138 million in net losses, largely driven by the falling price of BTC.
The recent rebound in BTC prices will likely reduce some of those losses in future quarters if it doesn’t fall again.
Got a tip? Send us an email securely via Protos Leaks. For more informed news and investigations, follow us on X, Bluesky, and Google News, or subscribe to our YouTube channel.
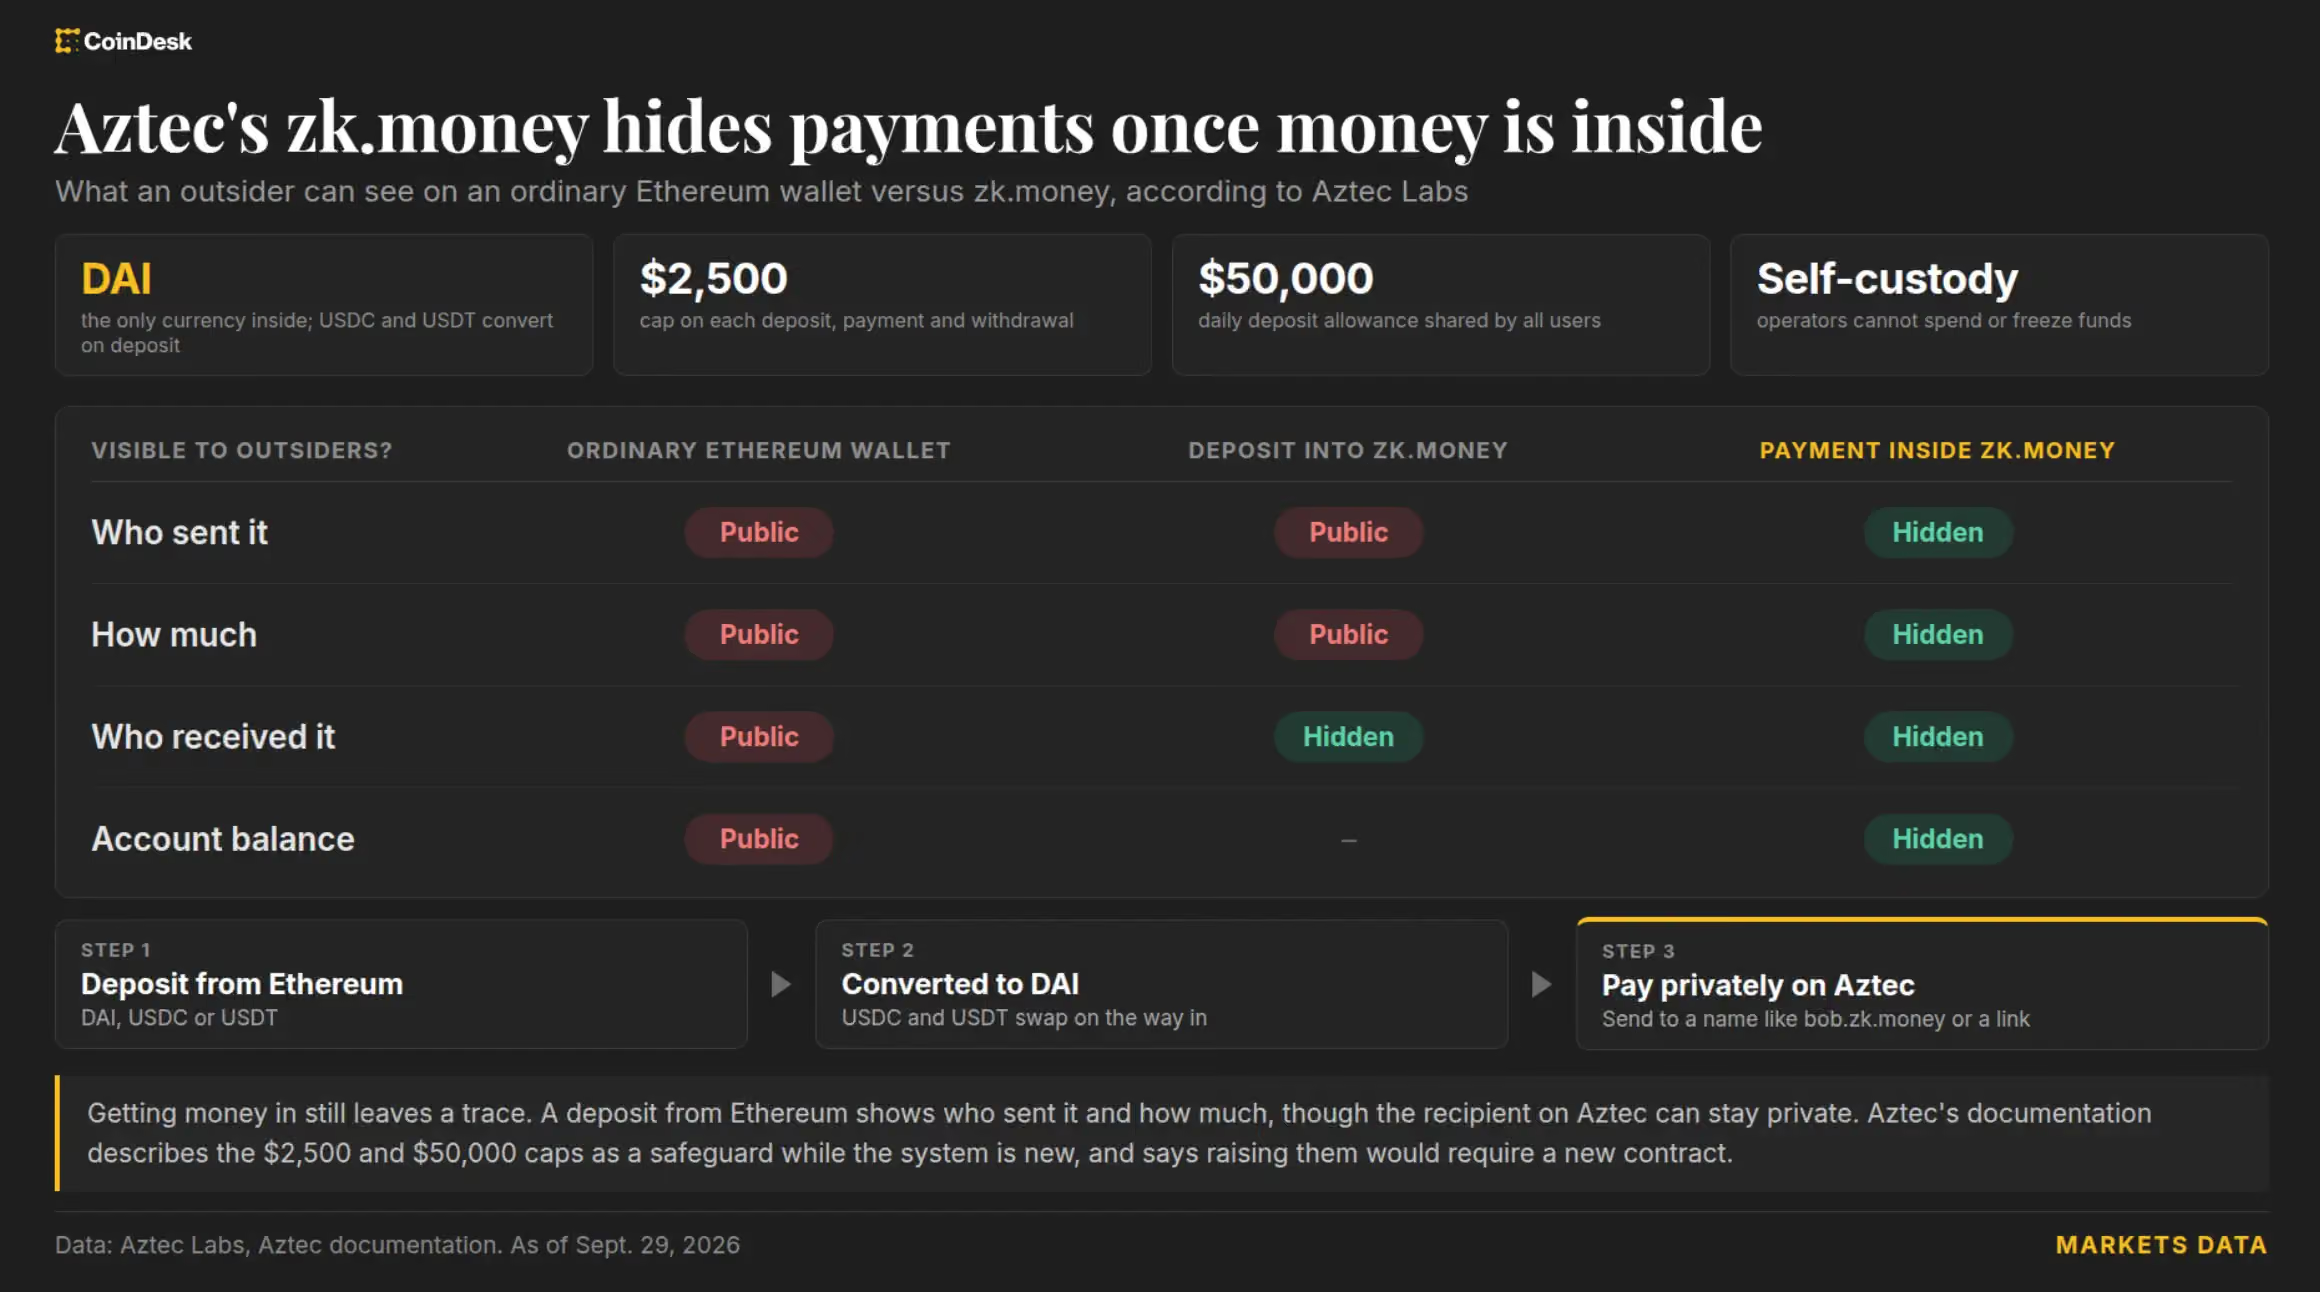
“Onchain transactions between two individuals shouldn’t mean publishing your financial history to the world,” Joe Andrews, CEO of Aztec Labs, said in a statement.
Andrews added that Aztec Labs chose DAI because it considers it “the most decentralized of the mass-market stablecoins used today on Ethereum.” He said the wallet could support other assets later.

Ethereum already has apps that hide payments, though transfers from an ordinary wallet remain public. Its developers are weighing changes for the planned 2027 Hegotá upgrade that could let privacy apps handle transaction approvals and fees with less help from outside services. Those proposals are still under consideration, while Aztec Labs is bringing back a wallet people can use on its own network.
Read More: Ethereum’s next big upgrade has 66 proposals, including a major privacy fix
What zk.money can and cannot hide
Moving money into the system still leaves a public trace, however. Aztec’s documentation says a deposit from Ethereum reveals the sender and amount, even though the recipient on Aztec can remain private.
The relaunch comes with limits, however. Each deposit, payment and withdrawal must be below $2,500. All users share a $50,000 daily deposit allowance, which replenishes over time. The documentation describes those caps as a safeguard while the system is new and says raising them would require a new contract.
Author: Cryptoman
Cryptocurrency is edging further into the financial mainstream this year, even as the industry’s relationship with traditional banking and regulators remains fraught in key markets like the United Kingdom. From Morgan Stanley’s new laboratory for testing tokenized finance to a British parliamentary group’s pointed letter to bank chief executives, the story of crypto in late 2026 is one of institutions moving cautiously toward digital assets while grappling with unresolved questions about risk, access and regulatory readiness.
On Wall Street, the direction of travel is unmistakable. Morgan Stanley has launched a Digital Asset Lab dedicated to testing stablecoins, tokenized deposits, central bank digital currencies, money-market funds and decentralized finance vaults, according to reporting by Bloomberg. The lab, part of the bank’s existing network of innovation hubs, allows employees to experiment with blockchain-based applications without touching Morgan Stanley’s core systems — a sandbox approach that mirrors, in miniature, the kind of controlled testing environments regulators elsewhere are trying to build.
Megan Brewer, who leads market innovation and labs at the bank, told Bloomberg the team is exploring how software might execute investment strategies around the clock, a question that goes to the heart of what tokenization promises: markets and money that never sleep. The lab’s remit spans the technical distinction between a tokenized deposit, which represents a claim on money held at a bank, and a stablecoin, which is backed by a separate pool of assets — a distinction that has become increasingly important as regulators worldwide try to draw clear lines around different forms of digital money.
This research effort builds on products Morgan Stanley has already brought to market. In April, the firm launched a Stablecoin Reserves Portfolio designed to help stablecoin issuers meet reserve requirements under the U.S. GENIUS Act, holding cash, short-dated Treasurys and repurchase agreements. Its E*TRADE platform completed a rollout letting eligible clients trade Bitcoin, Ether and Solana directly, while three separate exchange-traded products tracking those same assets have drawn tens of millions of dollars in inflows since launching earlier this year. Together, these moves suggest a major Wall Street institution treating crypto not as a speculative sideline but as infrastructure worth building out across trading, custody and reserve management.
The contrast with the United Kingdom is instructive. There, momentum is real but noticeably more contested. Lord Kulveer Ranger, co-chair of Parliament’s All-Party Parliamentary Group on Digital Markets and Digital Money, recently offered a candid assessment of where the Bank of England stands on stablecoins and the prospect of a digital pound. His verdict, after 18 months of engagement: the Bank is listening, but it is cautious — and caution alone, he argues, will not be enough to keep Britain competitive.
Ranger’s core complaint is about tempo. While the Bank of England takes its time absorbing feedback on systemic stablecoin rules, other jurisdictions are moving ahead with their own frameworks, some more permissive and some more experimental. Capital and confidence, he warns, do not wait for perfect policy alignment. He points to the Bank’s Digital Securities Sandbox — a testing ground for distributed ledger technology in capital markets — as a case in point: enthusiasm within the Bank has not translated into enthusiasm among firms, many of whom see sandbox participation as costly in time and resources with an unclear payoff. Without a credible bridge from experimentation to real-world deployment, he argues, elegant regulatory frameworks risk attracting interest without retaining commitment.
That tension between innovation and caution is playing out concretely in the banking sector itself. In August, the UK’s Crypto and Digital Assets APPG wrote directly to the chief executives of every major British bank, demanding explanations for why crypto and digital asset firms continue to struggle to open basic bank accounts. The letter, signed by co-chairs Gurinder Singh Josan and Lord Vaizey of Didcot, cited persistent reports of firms being shut out of banking services or having crypto-related payments restricted outright — even as the UK moves toward a comprehensive regulatory regime for the sector.
The APPG’s language was blunt: banking access, the letter said, “could be one of the single biggest barriers to growth” for UK crypto businesses, with the potential to undermine the very regulatory regime the government is trying to build and to influence whether firms choose to invest in Britain at all. Notably, the group acknowledged that banks have legitimate obligations to guard against financial crime, but argued that decisions should be based on individual firms’ risk profiles rather than blanket sector-wide exclusion. That view echoes an assurance given in Parliament back in March by Economic Secretary to the Treasury Lucy Rigby, who told MPs that firms authorized by the Financial Conduct Authority should not face banking restrictions simply for operating in crypto.
The letter is now feeding into a formal Parliamentary Inquiry into banking access for the sector, which gathered written evidence from banks, crypto businesses and regulators through the end of August before a report and recommendations to government.
Taken together, these developments capture an industry at an awkward but consequential midpoint. In the United States, a heavyweight institution like Morgan Stanley is quietly normalizing crypto exposure across trading platforms, exchange-traded products and now dedicated research infrastructure, treating stablecoins and tokenization as inevitable features of modern finance rather than fringe experiments. In Britain, meanwhile, the debate remains more elemental: not just how sophisticated the regulatory framework should be, but whether crypto businesses can even get a bank account in the first place.
Both stories point to the same underlying reality. Cryptocurrency’s next phase of growth will be determined less by technological breakthroughs than by the willingness of banks, regulators and central banks to treat digital assets as a normal, if carefully managed, part of the financial system. Wall Street appears to be answering that question with capital and infrastructure. Westminster and Threadneedle Street, for now, are still working out the terms.
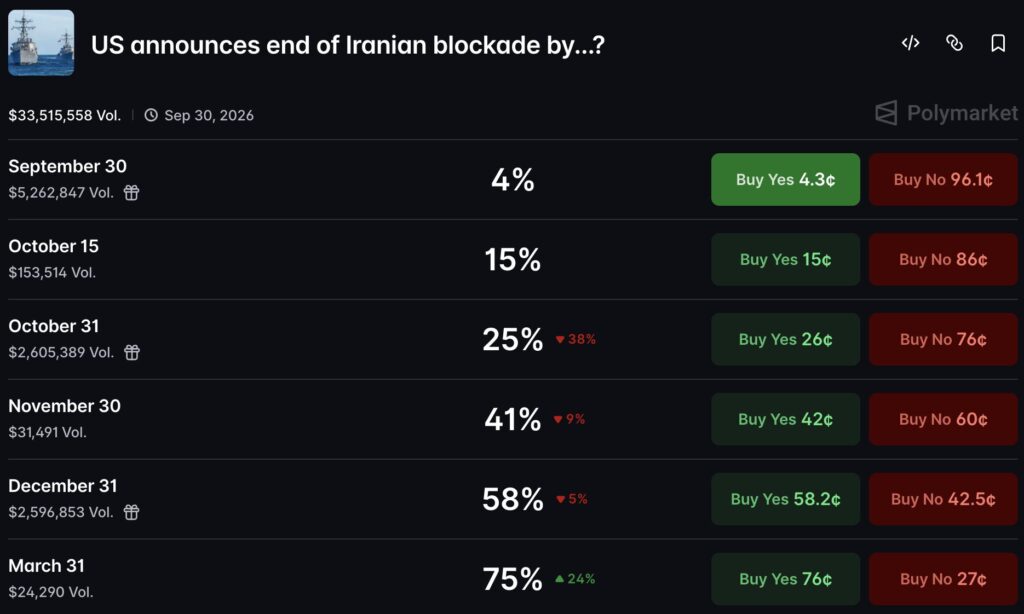
Iran War Polymarket odds price a US announcement ending the naval blockade of Iran no earlier than March 31, 2027, with the contract trading at 74.5% Yes to 25.5% No as of mid-morning on Tuesday, 29 September, according to live pricing on the platform.
The event has logged over $33M in cumulative volume since launch, and the highest-priced outcome sitting nine months out raises an obvious question: if US-Iran talks are genuinely progressing, why is the smart money betting on delay rather than a near-term resolution?
Got a Gut Feeling? It Could Pay Out Big on Polymarket
Iran War Polymarket Odds: What is the Diplomatic Backdrop Traders Are Watching?
Pricing is influenced by ongoing negotiations, as Reuters reported on September 24. U.S. and Iranian negotiators are considering a phased deal where Tehran would reopen the Strait of Hormuz in exchange for lifting the U.S. economic blockade. Both sides are hesitant to yield leverage; the U.S. maintains economic pressure, while Iran controls a key shipping artery for global oil.
However, current conditions do not trigger resolution under market rules. Polymarket specifies that only official announcements from the U.S. government can count for contract resolution, excluding speculation or conditional statements.
This discrepancy between market sentiment and strict legal requirements is causing outcome expectations to shift later in the timeline. Observers can also see how the Iran-U.S. ceasefire proposal is affecting Bitcoin price expectations, reflecting broader risk sentiment.
Iran says it struck 19 ships in the Strait of Hormuz over the past two nights, Fars News Agency reported Sunday, after Kpler reported over 20 million barrels of crude and products exiting the US blockade line as 7-day average.
Iranian forces hit 12 vessels Friday night and 7… https://t.co/UnVeYf99k0 pic.twitter.com/LP8tZknZqo— Drop Site (@DropSiteNews) September 27, 2026
What the Full Ladder of Contracts Actually Shows
Polymarket’s blockade market features multiple deadline contracts that gauge the odds of a qualifying announcement on specific dates. These contracts can’t be combined into a single event probability, as each one represents a distinct bet.
Together, they suggest traders expect the diplomatic process to extend beyond the current news cycle. Once a qualifying announcement is made, it resolves as “Yes,” even if the blockade later continues or if a partial concession is made; such concessions do not qualify.
This distinction is important, as past U.S.-Iran ceasefire agreements have quickly unraveled, reflecting a tendency for narrower resolutions, similar to market bets on the Bab-el-Mandeb Strait, which require specific triggers for resolution.
Got a Gut Feeling? It Could Pay Out Big on Polymarket
Total volume across the event stands at $33,486,973, with liquidity of $519,322 as of the last update at 09:07:57 UTC Tuesday. The March 31, 2027 contract – the current price leader – carries relatively thin volume of just $24,290, meaning its 74.5% Yes print reflects a smaller pool of capital than the headline number suggests.
The heaviest trading has run through nearer-dated contracts already priced for near-certain No outcomes: the September 30 deadline alone has drawn $5,238,179 in volume against a mere 3.3% Yes price, and October 31 has seen $2,604,557 change hands at 24.5% Yes.
December 31 sits between the two extremes at $2,596,836 in volume and 57.9%. Yes. That distribution suggests most capital has already been deployed betting against a quick resolution, leaving the March contract as a comparatively low-conviction, low-liquidity outlier at the top of the ladder, a dynamic worth weighing against how Polymarket’s NATO-related contracts have similarly shown thin markets producing headline-grabbing but fragile probability prints.
The post Iran War Polymarket Odds: $33.5M Placed on a 2027 Blockade End appeared first on Cryptonews.
BlockTower Capital founder Ari Paul has accused Coinbase of losing $25 million of his company’s funds while covering up over $1 billion worth of “massive and repeated hacks.”
Paul claims that at least a dozen firms are affected by the alleged cover-up, and that Coinbase “still wouldn’t return our money.”
He also claims that these major allegations are all he can say at the moment as there are “multiple legal processes still ongoing.”
Read more: Coinbase and Brian Armstrong are threatening to leave California… again
BlockTower Capital is a crypto and traditional asset investment firm founded in 2017 by Paul and Goldman Sachs executive, Matthew Goetz.
Two executives left the company in 2022 and 2023 for mysterious reasons, while the company also shuttered its $100 million Market-Neutral Fund in 2023.
Coinbase claims it isn’t covering up hacks
When asked for comment, Coinbase directed Protos to a support post that claimed the exchange “is not hiding a series of hacks and we certainly didn’t lose $1 bilion.”
It said that it advises customers on security practices like maintaining their API keys, and that like most other firms that offer access via API keys, “we do not retain the information necessary to transact on customer accounts.”
Coinbase refused to comment on specific clients.
Coinbase allegations made against Cobie
Paul was responding to a series of posts shared by Cobie, a prominent crypto investor who became a glorified customer support representative for Coinbase.
Cobie was pointing out to X user “Kuno” that they’d been ignoring the crypto exchange’s attempts to reach out to them.
Kuno, on the other hand, claimed they repeatedly approached Coinbase over $1.2 million it had allegedly stolen.
Cobie noted that Kuno was promoting a “shitcoin” and that the whole affair looks like “an entirely fake/scam report/engagement farm.”
Cobie hasn’t responded to Paul’s allegations at the time of writing.
Coinbase sued over $55M draining hack
Coinbase was sued back in May for allegedly withholding a portion of $55 million in crypto that was stolen in a draining hack in August 2024.
The victim claims he lost his crypto after clicking on a malicious link that spoofed Ethereum DeFi management tool “DefiSaver.”
Read more: Coinbase CEO admits content coins were a mistake
From here, he unknowingly authorized a smart contract permission that supposedly gave the thieves control of his crypto wallets.
Got a tip? Send us an email securely via Protos Leaks. For more informed news and investigations, follow us on X, Bluesky, and Google News, or subscribe to our YouTube channel.

Key takeaways
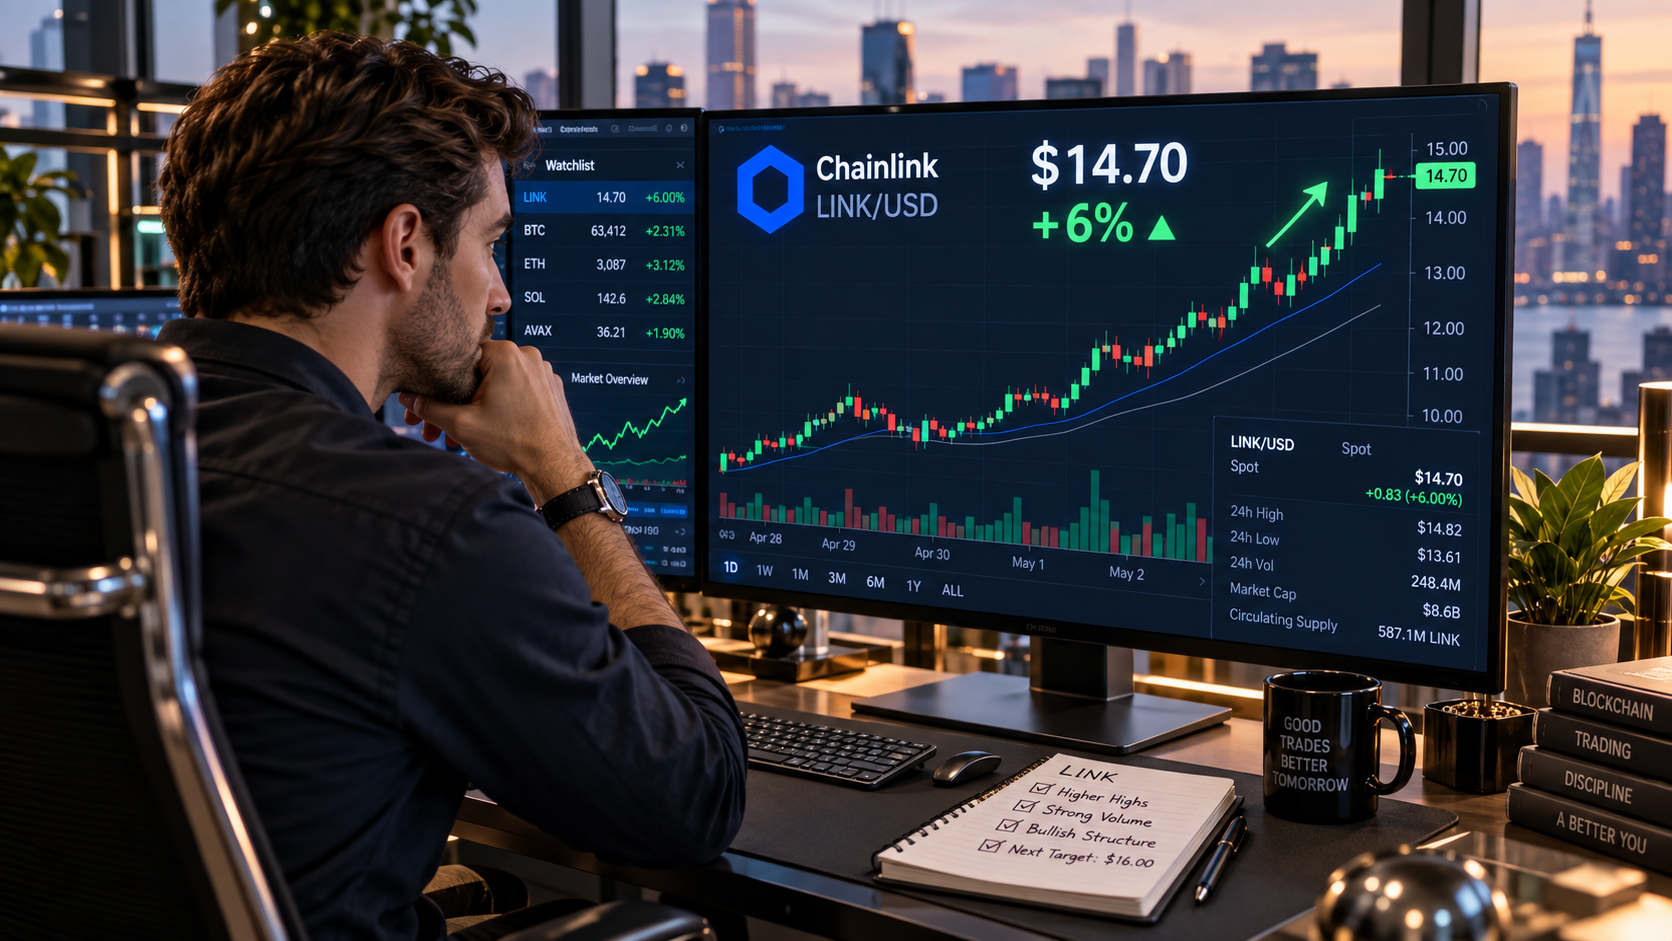
- LINK rose about 6% while much of the crypto market retreated, extending its reported 30-day gain to 30.3%.
- Chainlink’s CCIP 2.0 launch gives institutions the option to add their own cross-chain transaction verifiers.
- LINK met resistance near $15, while the supplied chart analysis identifies $12-$13 as a potential support zone.
Chainlink’s LINK token outperformed a weaker crypto market following the launch of Cross-Chain Interoperability Protocol (CCIP) 2.0.
The token gained about 6% in the session described in the supplied analysis, taking its 30-day advance to 30.3% and its year-to-date return into positive territory.
The upgrade gives financial institutions more control over transactions that move data or assets between blockchains.
Traders appeared to welcome the announcement, though LINK’s approach to $15 brought a technical test after its recent rally.
CCIP 2.0 adds institution-operated verifiers
Cross-chain transfers require a way to confirm that an action occurred on one blockchain before a corresponding action is completed on another. CCIP provides that communication layer.
With version 2.0, institutions and asset issuers can add Cross-Chain Verifiers to apply their own checks alongside Chainlink’s default verification network. Chainlink says starter kits will let users run those verifiers on infrastructure including Amazon Web Services and Google Cloud.
The added checks could matter to firms with internal security or compliance requirements. An issuer, for example, may want a transfer to proceed only after its own verifier has approved it.
CCIP 2.0 also offers configurable compliance controls, fees, and execution options, allowing users to choose how a transaction is checked and completed. These features are optional; Chainlink says its existing verification network remains the default.
Speed is another part of the upgrade. CCIP 2.0 supports faster-than-finality transfers where a user’s chosen risk settings permit them.
Chainlink also says it is working to support Ethereum’s Fast Confirmation Rule when that feature launches. Its future integration should not be treated as a speed improvement already available for every Ethereum transfer.
The supplied market analysis reported an 89% jump in LINK trading volume following the CCIP 2.0 announcement.
Higher volume shows that more tokens changed hands during the move, but it does not, by itself, show whether buyers will remain in control.
The same analysis cited a recovery in Chainlink’s total value secured from about $43 billion in June to $57 billion in August. That metric describes value associated with assets using Chainlink services; it is distinct from revenue earned by Chainlink or the market value of the LINK token.
The product announcement gives traders a reason to reassess Chainlink’s role in institutional blockchain infrastructure. Even so, a network upgrade does not automatically create immediate demand for LINK. Adoption, usage, and the broader market’s direction will matter to whether the price move lasts.
Can LINK break above $15?
LINK’s advance encountered selling pressure near $15, a level the supplied daily-chart analysis identifies as immediate resistance.
It also noted a bearish divergence in the relative strength index: price strengthened while the momentum reading weakened. Such a signal can precede a pause or pullback, although it does not establish that one must occur.
If LINK retreats, the analysis places a possible support zone at 12–13. Holding that area could leave the broader recovery intact, while a decisive break below it would weaken the bullish setup.

A sustained move above $15 would shift attention toward higher levels, including the article’s $20 upside scenario. From $12, a rise to $20 would be roughly 67%, but that percentage describes a hypothetical entry and exit, not an expected return.
For now, the clearest test is whether LINK can absorb selling around $15 while maintaining support if the wider crypto market remains under pressure.
BTC’s move above $80,000 has triggered a “double-bottom breakout,” a technical analysis pattern confirming a bullish trend and opening the door for a rally to $100,000, according to Jurrien Timmer, director of global macro at Fidelity Investments.
“Bitcoin is looking particularly interesting here as it challenges key resistance at $80k. If it breaks it will confirm a double bottom targeting $100K,” Timmer wrote on X on Friday.
A double bottom looks like the letter W on a price chart. The price drops to a low, bounces, falls back to roughly the same level, then rises again. The two dips show buyers stepping in at the same price twice. The peak in the middle of the W acts as resistance. A break above it suggests sellers have run out of steam and a new uptrend may be starting.
Timmer’s chart shows bitcoin’s two lows this year at $60,033 and $57,742, with the middle peak near $82,800.
Chart patterns are not guarantees. Breakouts often fail, reversing quickly and trapping buyers who chased the move.
Still, the bullish setup is consistent with options traders positioning for more gains. The $90,000 call is the most popular bitcoin options bet on crypto exchange Deribit, with $2.45 billion in open interest. The $95,000 call follows with $2.33 billion, and the $100,000 call holds $1.79 billion. A call gives the buyer the right to buy at a set price and profits when the market rises above it.
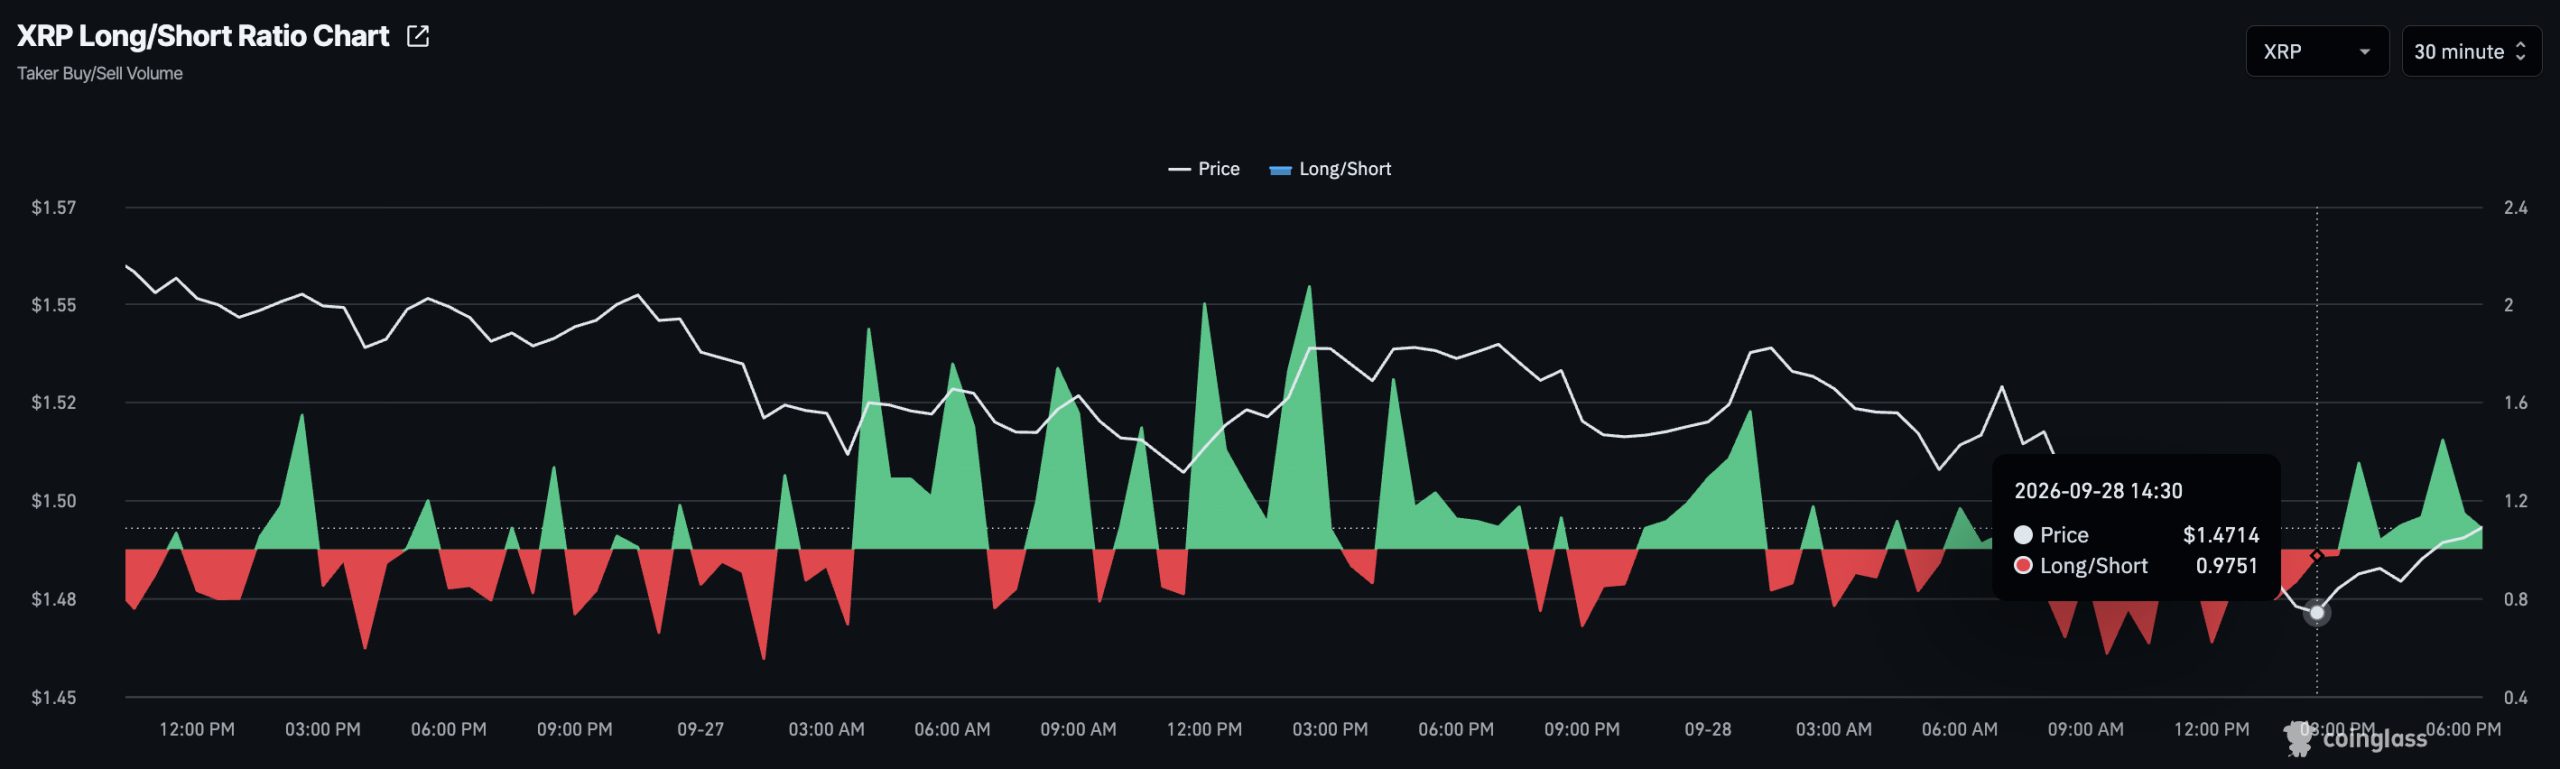
XRP price hovers under $1.49 after three consecutive daily declines left the token losing the $1.50 support, even as a modest bounce pulled it off session lows. CoinGlass data showed the long-to-short ratio at 0.975, meaning short positions marginally outnumbered longs, while the funding rate sat at a positive 0.008%, the reading that determines whether long or short traders pay a periodic fee to hold perpetual futures.
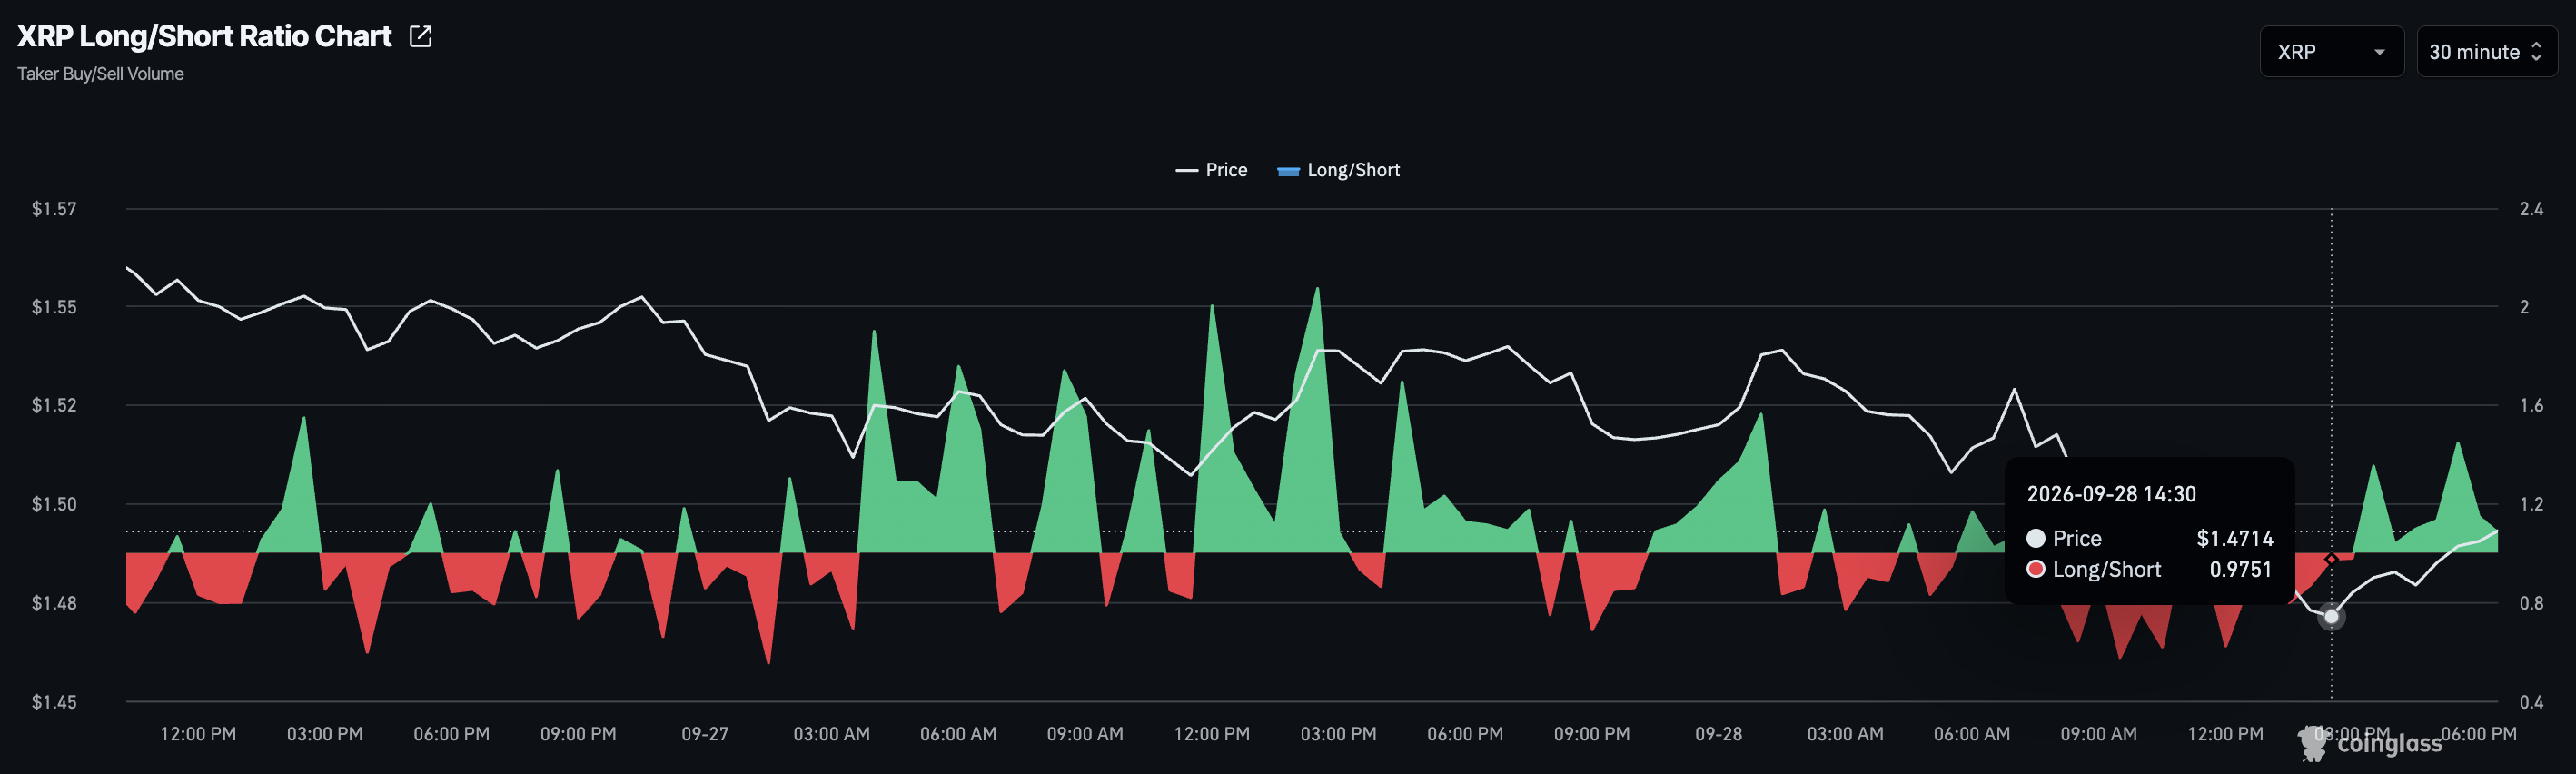
XRP Long Short Ratio, Coinglass
That combination is the crux of the problem. Traders are still paying to stay long, yet the spot price has not moved in a way that rewards the bet, and the disconnect between heavy spot selling and futures demand is the setup that tends to unwind fast once a key level gives way.
A 0.975 long-to-short ratio is not a bearish signal in any decisive sense. It sits close enough to 1.0 that it reads as near-balanced positioning rather than a market leaning hard in either direction.
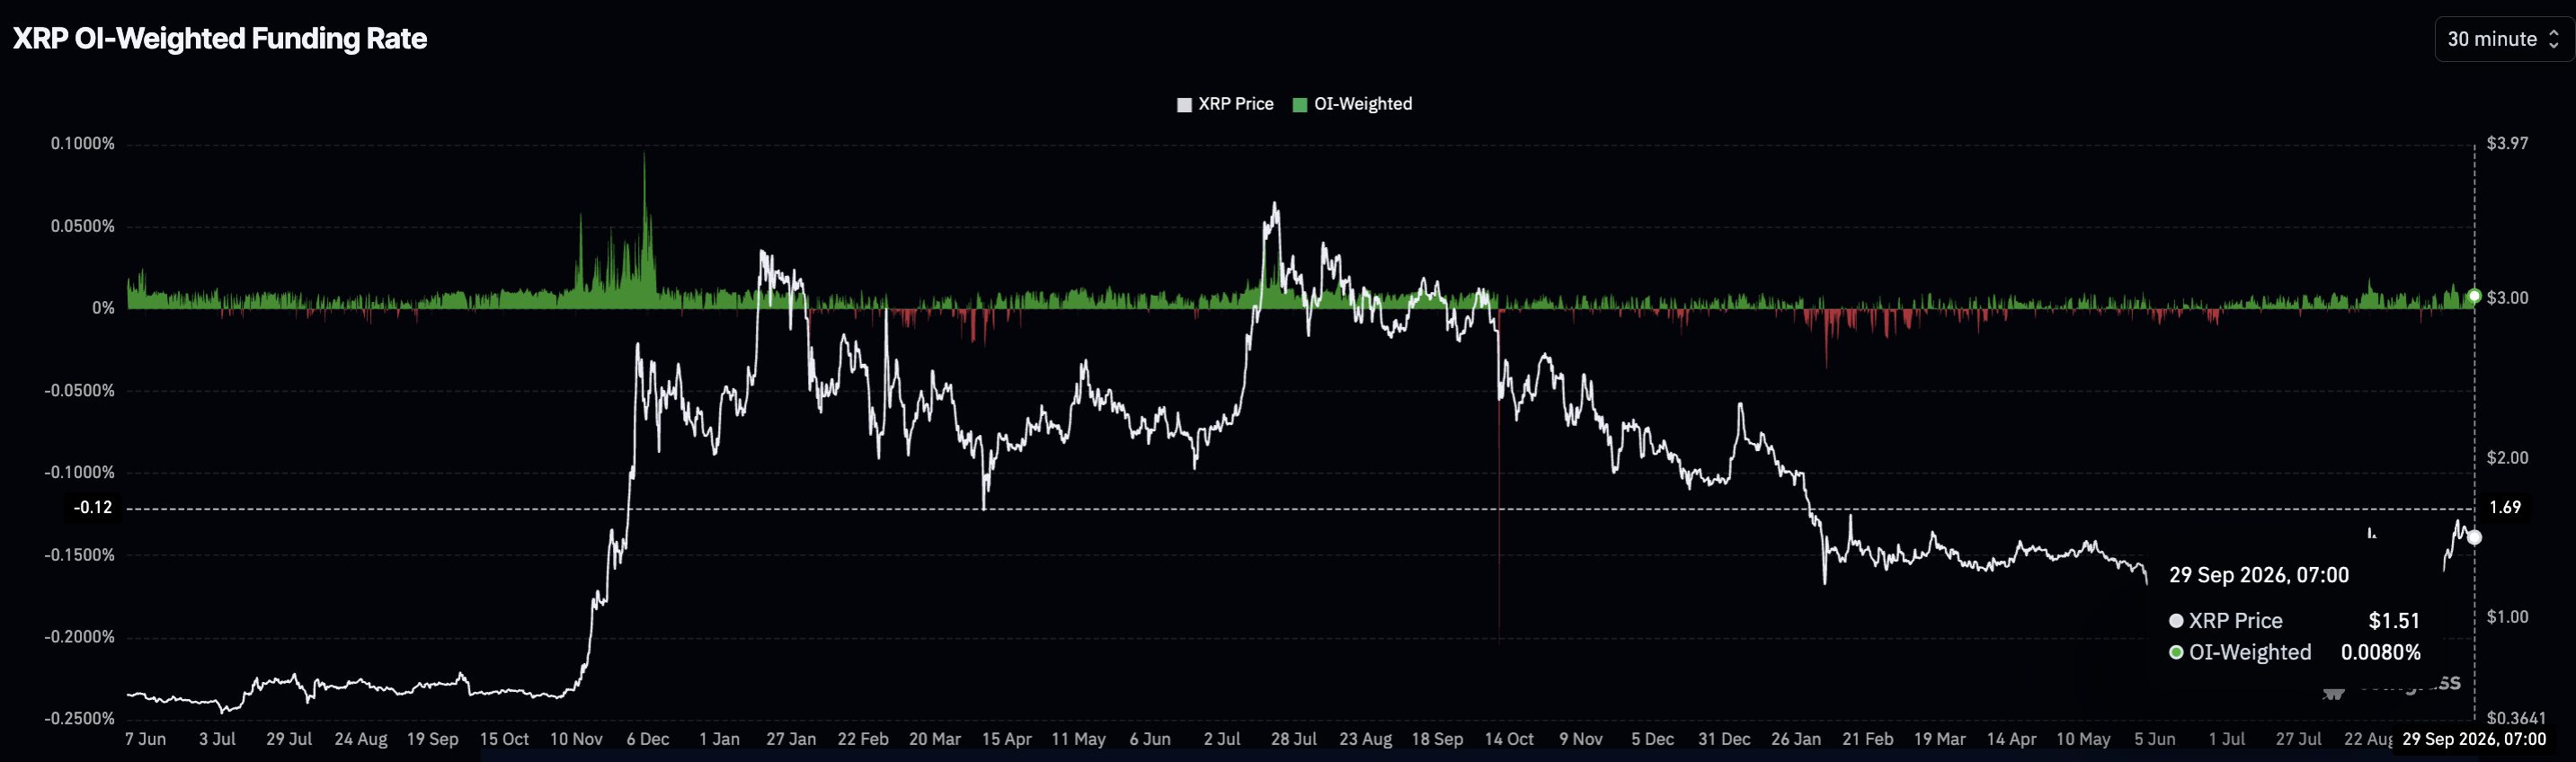
XRP Funding Rate, Coinglass
Funding tells a more interesting story on its own. A positive rate means demand for long exposure in crypto derivatives is real enough that longs are compensating shorts to hold the position, which typically signals conviction that price moves higher.
However, it cuts both ways: if price falls further, those same leveraged longs become forced sellers, and a positive funding regime built on thin spot demand can flip into a liquidation cascade faster than one built on genuine accumulation.
CryptoQuant’s summary data flagged overheating conditions across both XRP’s spot and futures markets, alongside sell-side dominance in futures, meaning sellers have retained the upper hand in derivatives even as funding stays positive. That is the missing piece: positive funding shows traders are willing to hold bullish exposure, but it has not yet translated into enough buying pressure to absorb the futures selling and push through resistance. Earn $50 and Enter $300K Prize Draw on EdgeX
XRP Price and the $1.37 Support
The daily chart still leans bullish on a longer timeframe. XRP held above its 50-day price exponential moving average near $1.365 and its 200-day EMA near $1.369 through the three-day slide, with the 100-day EMA sitting lower at $1.307 as a secondary reference.
Momentum has cooled rather than reversed. The RSI sat near 55, close to neutral, and the MACD flattened around zero, a pattern consistent with consolidation after an earlier advance rather than an active breakdown.
The level that matters most sits at $1.37, where the 50-day and 200-day EMAs converge into a single support band. A clean break below that zone opens the $1.30 area, and a deeper slide would eventually put the $1.00 psychological level in play, though XRP would need to fall substantially before that becomes the immediate focus. On the upside, reclaiming the $1.574 resistance level is the trigger that would strengthen the case for a move toward $1.90.Trade XRP on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
What Happens Next for XRP?
Two scenarios frame the near-term path. If XRP holds the $1.37 zone, the market stays in a consolidation phase where positive funding continues to reflect trader appetite for long exposure, but that alone won’t confirm a breakout without a corresponding rise in open interest and spot volume.
If XRP price instead reclaims $1.574, the technical case for a run toward $1.90 gets meaningfully stronger, and that move would likely force shorts to cover into strength. The alternative is a sustained break below $1.37, which shifts focus to $1.30 as the next line of defense, with $1.00 as the deeper level only if that support also fails.
Either way, the current setup leaves no room for complacency on either side of the trade. Near-balanced positioning combined with positive funding and futures sell-side dominance is a fragile mix, and the next move in spot price will do more to settle the argument than another shift in the long-short ratio.
Discover: The Best Token Presales
The post XRP Price in Danger: Positive Funding Masks a Fragile Setup appeared first on Cryptonews.
Source link
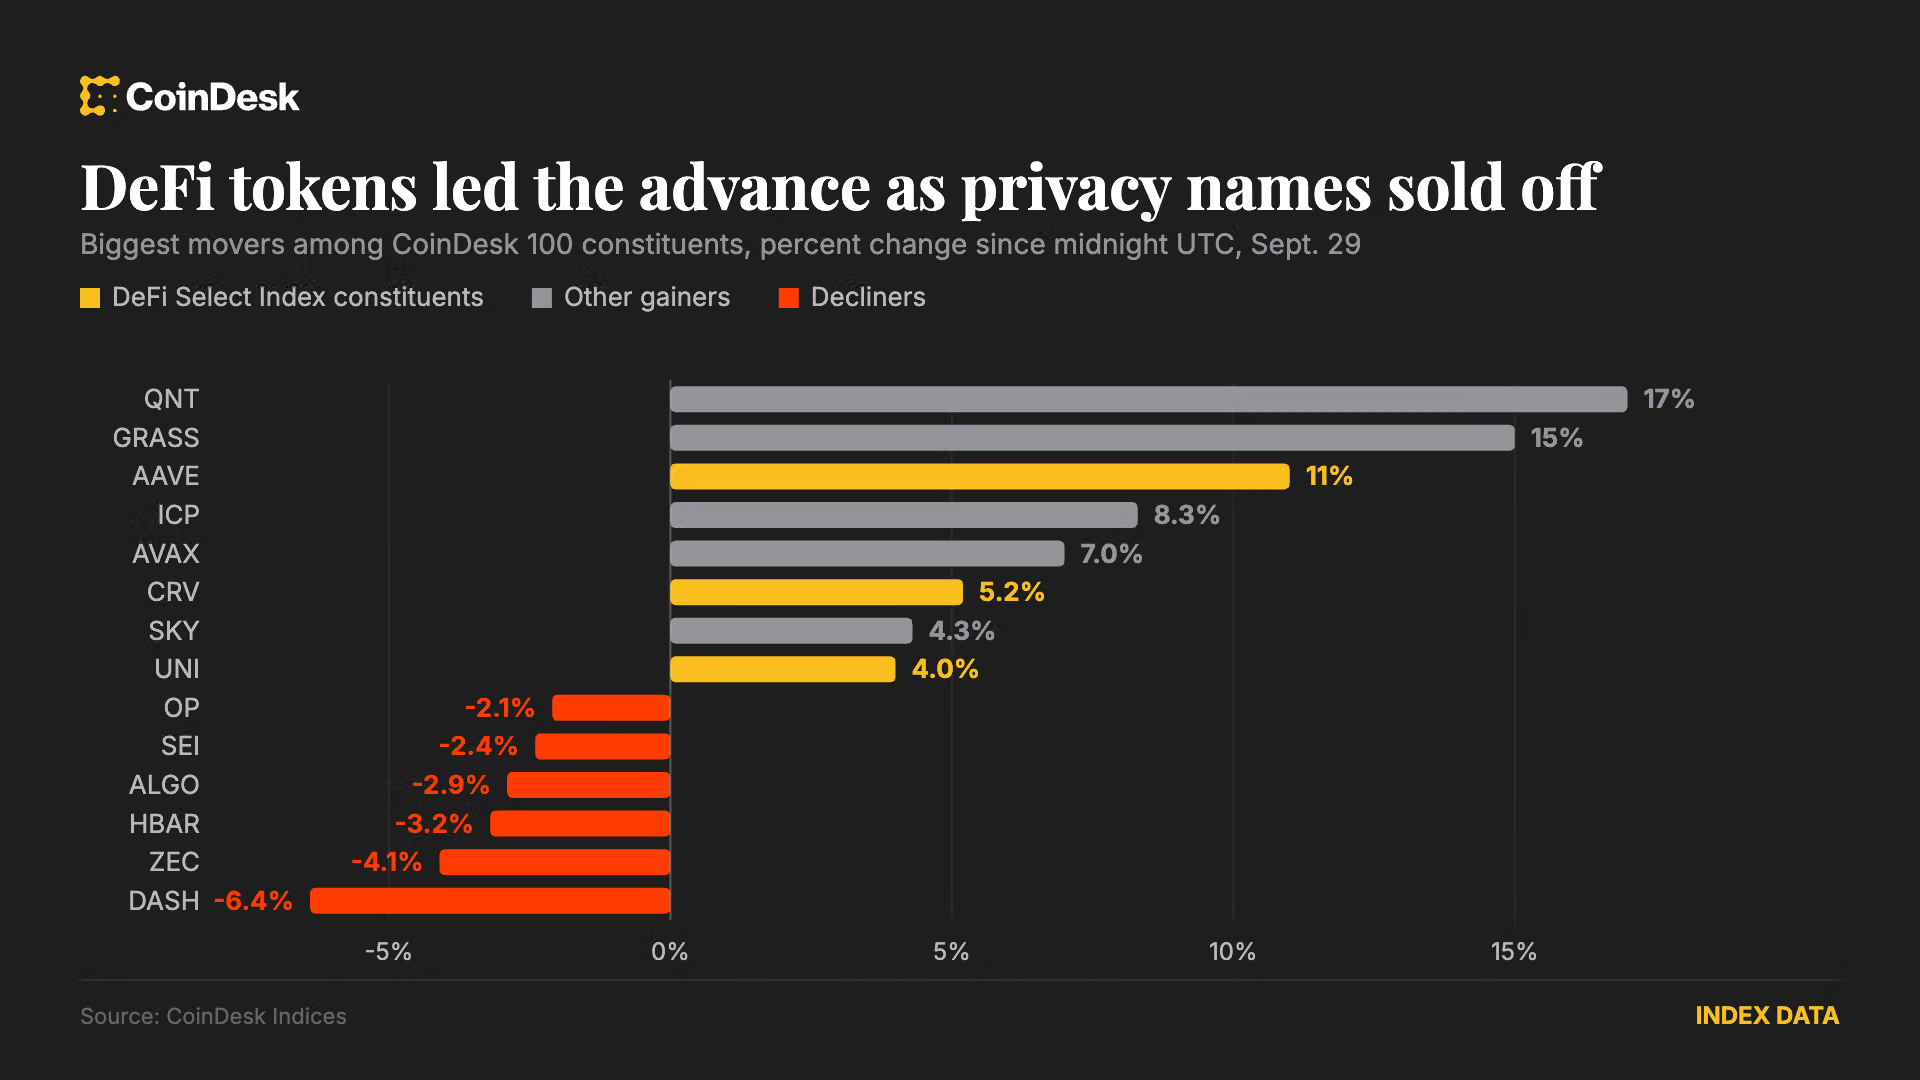
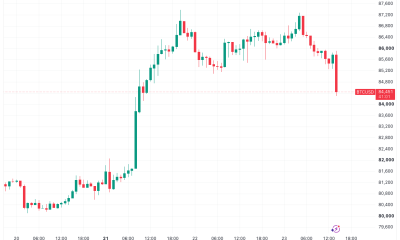
Bitcoin recovered Monday’s losses to trade at $84,170 on Tuesday, up 0.82% since midnight UTC and 1.4% over 24 hours, with 72 of the 100 CoinDesk 100 constituents higher and the index adding 0.89% to 1,904.49.
The bid is arriving despite conditions that have been suppressing risk assets for a week, the 10-year Treasury yield sitting at 5.234% after ending Monday above 5.2%, near levels last seen in 2007, and the 30-year at 5.549% having topped 5.56% on Monday, around a 2004 high.
U.S. stocks fell for a second session on Monday, the Dow dropping more than 300 points and the S&P 500 and Nasdaq Composite shedding 0.8% and 0.9%, with futures mixed on Tuesday morning.
Decentralized finance (DeFi) is driving the move for the second time in a week, with the DeFi Select Index (DFX) gaining 5.0% since midnight, led by lending protocol token aave at 11% and curve dao token at 5.2%. The CoinDesk 80 rose 2.0% against the CoinDesk 5’s 1.3%, though the ranking inverts over 24 hours, where the CD5’s 1.7% beats the CD80’s 0.44%.
The D’CENT wallet hack, the year’s second-largest drain of XRP behind the Bitget crypto exchange hack, has spilled beyond the XRP Ledger onto additional blockchains like Bitcoin, Ethereum, and Stellar.
Hackers have drained more than 12.4 million XRP from more than 7,000 D’CENT wallets, still some way behind Bitget’s loss of 102.9 million XRP.
Although the wallet was popular among the XRP community, D’CENT users who owned assets of other blockchains have also lost their funds.
D’CENT’s own disclosure named Bitcoin, Tron, and Ethereum, for example. Even a Stellar user has lost XLM in the incident.
Hackers are able to sweep funds across blockchains with one compromised recovery phrase for the multi-blockchain wallet.
IoTrust, the maker of D’CENT, confirmed at least 110 abnormal transfer reports, including non-XRP assets, per ZDNet Korea.
XRP holders lose $18 million in D’CENT hack
Drains of XRP are the most well-documented, due to the prominence of D’CENT among XRP holders.
At least six waves of theft occurred between September 15 and 20, emptying 6,678 wallets of 11.7 million XRP.
The thief stole from large wallets first, by hand, and soon wrote scripts to take funds from progressively smaller wallets.
Warnings from D’CENT and other members of the XRP community couldn’t stop the drainage. Thieves took 640,370 additional XRP after September 21, bringing the tally to above 12.4 million.
By Friday, 6.3 million of those stolen XRP had crossed to Ethereum’s blockchain through the swap service THORChain.
As the theft spilled over to other blockchains, researchers admitted the scope of the losses, saying, “Most of it is no longer XRP.”
Read more: David Schwartz warns of hard fork because XRP nodes won’t upgrade
In August, D’CENT was still touting its hardware wallets’ secure element, boasting that it was impervious to vulnerabilities linked to the Coldcard hack.
D’CENT now warns users that wallets they created using its app are vulnerable, urging them to create a fresh recovery phrase and immediately migrate everything, including tokens, NFTs, and any staked assets.
Got a tip? Send us an email securely via Protos Leaks. For more informed news and investigations, follow us on X, Bluesky, and Google News, or subscribe to our YouTube channel.

Matthew Schaefer Named New York Islanders Alternate Captain At 19, Becomes Youngest In Franchise History

Xbox Just Unveiled Mythic Achievements, Which Are Basically PlayStation Platinum Trophies

Amy Luciani Talks Reconciling W/ Dwight Howard Amid Drug Talk


-
 Fashion4 days ago
Weekend Open Thread: J.McLaughlin – Corporette.com
-
 Crypto7 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-
 Tech & AI2 days ago
Anthropic turns Claude into an AI marketplace with 2,000+ plugins and connectors
-
 Tech & AI2 days ago
OpenAI is preparing “o,” an always-on ChatGPT assistant that could handle email
-
 Fashion5 days ago
8 iPhone Accessories That Add Personality
-
 Entertainment7 days ago
These 17 Fall Amazon Dresses Seriously Look Like Anthropologie
-
 Tech & AI7 days ago
Reolink’s solar 4K security camera falls to its lowest price in months
-
 Crypto7 days ago
This Bearish Netflix Stock Trade Can Cash In On Video Streaming Giant’s Woes
-
 Crypto7 days ago
BitGo says Bitcoin absorbed Fed hike, CLARITY failure
-
 Business & Hustles7 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-
 Crypto6 days ago
Crude Oil Prices Pressured by Diplomatic Hopes in the Middle East
-
 Crypto6 days ago
Bitcoin price tests $83,600 Supertrend support after $87K rejection
-
 Crypto6 days ago
Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike
-
 Tech & AI6 days ago
UiPath’s Dines says AI needs a manual and launches Cartographer to write it
-
 Crypto7 days ago
Did Jim Cramer Just Give GameStop Stock the Kiss of Death When He Said the Turnaround Is Working?
-
Business & Hustles20 hours ago
Perpetua Resources at Mining Forum Americas 2026: shift to construction
-
 Crypto6 days ago
As Amazon Stock Prospers, Traders Might Consider This Option Play
-
 Crypto6 days ago
Strategy resumed Bitcoin buying, but Strive gained more BTC per share
-
 Crypto2 days ago
Wall Street Giant Warns AI Agents Could Trigger a New Kind of Bank Run
-
 Crypto6 days ago
MoonPay to Acquire North Capital in All-Stock Deal Exceeding $60M
You must be logged in to post a comment Login