Crypto
World settles bets with an oracle. That is the third model

Summary
- World opened its standalone platform at world.xyz on September 9 to more than one million waitlisted users, after operating inside the Phantom wallet since the summer.
- More than 150,000 markets have been created across sports, crypto, politics, finance, economics, and culture, with the initial lineup covering every NFL regular-season game, seven soccer leagues, Formula 1, the 2026 midterms, and Federal Reserve policy decisions.
- Resolution runs through Chainlink Data Streams and the Chainlink Runtime Environment, with no human resolution panel, no token-holder vote, and no dispute window delaying payouts.
- The protocol is non-custodial, holds no customer funds, routes orders to liquidity providers on Solana, settles in CASH, and requires no brokerage account or exchange registration.
- The site went offline on launch day under traffic from the waitlist before returning.
Every argument about prediction markets this year has been about who is allowed to run one. New York suing for billions. A dozen state gaming regulators issuing orders. Three California tribes at the Ninth Circuit. A bill to ban sports contracts outright.
Almost none of it touches the question that decides whether these things work at all: how does the market know who won?
Until this week there were two answers shipping in production. Kalshi settles with a rulebook, applied by a licensed operator with a regulator behind it. Polymarket settles with an optimistic oracle, where an outcome is proposed, challenged and, if contested, voted on by people holding a governance token.
On September 9, World shipped a third. Chainlink data feeds settle the contract automatically the moment the game ends. No panel. No vote. No dispute window. Nobody to appeal to, because the settlement is a program that already ran.
It launched to a waitlist of over a million people and took its own website down.
Worth understanding what that third model buys and what it gives up, because it is not obviously better or worse than the other two. It is differently broken, which is the only honest thing anyone can say about resolution mechanisms.
What World actually is
None of the individual pieces is novel. The combination is.
World launched inside the Phantom wallet during the summer and opened a standalone site at world.xyz on September 9, extending access to a waitlist exceeding one million users. More than 150,000 markets have been created since the Phantom integration went live, spanning sports, crypto, politics, finance, economics, and culture.
The opening lineup is broad: every NFL regular-season game, seven soccer leagues, Formula 1 races, binary contracts on the 2026 United States midterm elections, and contracts on Federal Reserve policy decisions. Equity, commodity, and weather markets are planned.
Mechanically, each market issues yes and no contracts priced between zero and one dollar, and the verified outcome settles one side at a dollar. That is the standard binary event contract structure our guide to the instrument covers.
Three structural properties distinguish it. It is non-custodial: the protocol holds no customer funds, and assets move only when a user enters a market. Orders route to liquidity providers on Solana, not through an off-chain order book. And settlement is in CASH, the dollar-backed stablecoin used inside Phantom, with winning positions redeemed automatically in the wallet.
No brokerage account is required. No exchange registration is required. Users pay network fees to open and close positions.
The three resolution models
Nobody has put the three side by side, so here they are.
Kalshi: rulebook resolution by a regulated operator. Contracts settle according to criteria published in advance, applied by an exchange holding designated contract market status. A named entity makes the determination, a federal regulator supervises it, and participants have a complaints path. Our guide to that licence sets out the obligations. The operator can correct errors, and the operator exercises discretion, which are the same property viewed from two angles.
Polymarket: optimistic oracle with token-holder voting. An outcome is proposed, a challenge window opens, disputes escalate to a vote by holders of the oracle’s governance token, and the result finalises on chain. Our guide to that mechanism explains the stages. Nobody can unilaterally decide an outcome, and nobody can correct one after finality, which is again the same property from two angles.
World: automated data feeds with no dispute stage. Chainlink Data Streams supply the market data and the Chainlink Runtime Environment executes settlement once a game concludes or a defined event reaches its deadline. The published description is explicit that there is no human panel, no token-holder vote, and no dispute window delaying payouts.
The tradeoff runs consistently across all three and is worth stating as a principle. Every mechanism that removes discretion also removes correction. Kalshi can fix a mistake and can also make a discretionary call you dislike. Polymarket cannot make an arbitrary call and cannot fix one either, which is precisely the tension our guide to delisted and voided markets examines. World removes the most discretion of the three and therefore removes the most correction.
What automated settlement is good at
Inside a specific range this design is clearly better than the alternatives, and the case deserves its strongest form.
Objective outcomes settle instantly. A football match ends with a score. A Bitcoin price at a stated timestamp is a number. A Federal Reserve rate decision is a published figure. For contracts resolving on unambiguous, machine-readable data, a dispute window is pure latency, delaying payout to accommodate an argument nobody will make. Automated resolution pays immediately, which is a real user benefit and the clearest competitive advantage the design has.
It removes the failure mode that has damaged the category most. Contested resolutions on the oracle-based venue have produced the most reputational damage prediction markets have suffered, because a market resolving against what most observers believed happened is the single thing that destroys confidence in a forecasting instrument. Removing the discretionary stage removes that possibility for contracts where the data is unambiguous.
And it scales. A resolution process requiring human attention constrains how many markets can exist. More than 150,000 markets created since the summer is a number that would be operationally impossible under rulebook administration, and it is achievable precisely because resolution costs nothing per market.
Polymarket has moved in the same direction for price-based markets, adopting oracle-based settlement where the data permits, which is confirmation that the design is correct for that category, not a criticism of World for adopting it.
What automated settlement is bad at
The limits are just as specific, and they sit in exactly the markets people care about most.
Ambiguous events have no data feed. A contract on whether an official will resign, whether a conflict qualifies as a ceasefire, or whether a statement constitutes an endorsement cannot be settled by a price feed, because the disputed element is the definition and not the measurement. These are also disproportionately the markets people care about, which is why the oracle-based venue’s most contested resolutions have involved exactly this category.
Data feed failure has no remedy. If a feed reports incorrectly, reports late, or reports a value that does not reflect what happened, an automated system settles on it. With no dispute window there is no stage at which anyone can say the input was wrong before money moves. The integrity of the entire system rests on the integrity of the data source, and the participant has no mechanism to contest it.
Edge cases resolve mechanically. A postponed match, an abandoned race, a rescheduled announcement, a data source that stops publishing. Rulebooks handle these with voiding provisions. An automated system handles them according to whatever the contract specified in advance, and contracts cannot anticipate everything.
And there is nobody to appeal to. This is the practical consequence of the architecture. A participant who believes a market settled wrongly on Kalshi can complain to an exchange and to a regulator. On the oracle-based venue they can, in principle, participate in a dispute. On World, the settlement is the output of a program that already ran.
None of this makes the design wrong. It makes it correct for a specific class of contract and unsuitable for another, and the honest question is which class dominates the platform’s 150,000 markets.
The regulatory position
Here is the part nobody covering the launch has touched.
World lists contracts on every NFL regular-season game, the 2026 United States midterm elections, and Federal Reserve policy decisions. Those are precisely the contract categories currently under attack in the United States. Our status page on the sector maps the fights: state gaming regulators contending that sports event contracts are wagers requiring state licensing, California tribes litigating under federal Indian gaming law, and a bipartisan bill that would prohibit sports contracts on regulated exchanges outright.
The venues fighting those battles hold federal licences. Kalshi is a designated contract market. Polymarket operates domestically through an exchange it acquired. Both submitted to registration, and both are being sued anyway.
World requires no brokerage account and no exchange registration, holds no customer funds, and routes orders to liquidity providers on a public blockchain. That is a structurally different posture, and it raises the question the coverage has not: what happens when a non-custodial protocol lists the same contracts the licensed venues are being sued over.
Two readings are available. The optimistic one is that a non-custodial protocol with no operator holding funds is genuinely outside the frameworks being applied to exchanges, which are built around intermediaries. The sceptical one is that the same argument was made by offshore venues before 2022 and produced a settlement and a geoblock, and that regulators reach operators of protocols when they can find them.
Nothing in the launch materials addresses geographic restriction, and that absence is the most significant unexamined fact about this launch.
Why Solana, and why now
Solana is not an accident and neither is the timing.
Solana spent the year as the dominant venue for memecoin activity, and the network has been pushing into prediction markets as the next consumer application category. The Solana Foundation’s head of decentralised finance framed World as introducing a new asset class while keeping liquidity fully on chain, which is the strategic pitch: a network that captured speculative trading volume wants the next category of speculative trading volume.
Phantom’s role is the distribution mechanism. It is among the most used wallets on Solana, World operated inside it before going standalone, and settlement in CASH ties the product tightly to Phantom’s ecosystem. A million-person waitlist is what wallet-native distribution produces, and it is a channel neither licensed competitor has.
Chainlink’s position is the infrastructure play. The same Data Streams and Runtime Environment combination was adopted by another prediction market earlier in the year for automated creation, resolution, and settlement of crypto price markets, which suggests a standardising pattern instead of a bespoke integration.
So the launch is the intersection of three strategies: a network seeking its next consumer category, a wallet monetising distribution, and an oracle provider becoming the settlement layer for a market type. None of those three is primarily a bet on prediction markets being legal in the United States.
The market that breaks it
Pick a real example and the limits stop being theoretical.
Take a contract on whether a ceasefire holds. The data feed needs a number, and there is no number. Somebody has to decide what counts as a violation, whether a single incident breaks it, whether a disputed report is credible. Kalshi’s rulebook answers this in advance, badly or well, and a person applies it. Polymarket’s oracle answers it through a challenge and a vote, slowly and sometimes contentiously. An automated feed cannot answer it at all, because the thing in dispute is the definition and a feed only measures.
Now take a contract on whether an official resigns by a date. Clean, until the official announces an intention to resign effective later, or is removed, or resigns and then withdraws it. Every one of those has happened in politics and each produces a different answer depending on wording nobody wrote carefully enough.
These are not edge cases. They are the markets that make prediction markets interesting, and they are also the markets that have generated every reputational disaster the category has suffered. The oracle-based venue’s worst moments have all involved exactly this kind of contract.
So World has two options with its 150,000 markets. Either the contested-definition contracts are a small fraction of the book, in which case the design fits and the reputational risk sits mostly with the competitors. Or they are not, and the first genuinely disputed settlement arrives with no mechanism at all for handling it, which is worse than either alternative, not better.
Which one is true is checkable from the market list, and it is the single most useful piece of due diligence available on this platform.
What the incumbents should be worried about
Not the technology. The distribution.
Kalshi and Polymarket have both spent heavily on advertising, sports partnerships and corporate deals to acquire users. That is the normal cost of building a consumer financial product and it is enormous.
World got a million-person waitlist by existing inside a wallet people already had open. Phantom is among the most used wallets on Solana, World ran inside it before going standalone, and settlement happens in Phantom’s own stablecoin with winning positions landing back in the wallet automatically. No app to download, no account to open, no deposit to make, no identity check.
That is a distribution channel neither licensed competitor can replicate, and it did not cost a marketing budget. It cost an integration.
The uncomfortable part for the incumbents is that the thing making World’s distribution cheap is the same thing making its regulatory position ambiguous. No brokerage account means no onboarding friction and no registered intermediary. No identity check means faster signup and no way to screen prohibited participants, which is the entire surveillance apparatus the licensed venues built at considerable expense after the insider trading scandals.
So the competitive question is not whether automated settlement beats rulebook settlement. It is whether a product that skips registration, custody and identity can out-distribute products that did not skip them, and whether regulators reach it before the answer becomes obvious.
The category has run this experiment before, offshore, and it ended in a settlement and a geoblock. What is different this time is that the thing being regulated is a protocol on a public chain rather than a company with a bank account, and nobody has tested whether the old tools reach the new structure.
Chainlink is the real winner here
Follow the infrastructure and a different story appears.
World runs on Chainlink Data Streams and the Chainlink Runtime Environment. Earlier this year another prediction market adopted the same combination to automate creation, resolution and settlement of crypto price markets, with stated plans to extend into stocks, commodities and other real-world assets. That is two venues on one stack in a single year, which is how a standard forms.
The position is worth understanding. An oracle provider that supplies price feeds is a utility, paid per call, substitutable if someone builds a cheaper one. An oracle provider that supplies settlement for an entire market category is something else: it becomes the arbiter of outcomes for every contract built on it, and switching costs rise with every market that depends on its determinations.
Polymarket runs its own oracle mechanism with a governance token attached. Kalshi has an exchange rulebook and a regulator. Both built their resolution layer in-house because resolution is the product. World rented it, which is faster and cheaper and means the most consequential function in the business belongs to someone else.
There is a market-structure question buried in that which nobody has asked. If prediction markets standardise on one settlement provider, the failure mode of the entire category becomes correlated. A rulebook venue and an oracle venue fail independently, because their resolution mechanisms have nothing in common. Two venues on the same data infrastructure do not.
None of which is a criticism of the technology, which by all accounts works. It is an observation about concentration, and it is the kind of thing that looks like efficiency right up until the moment it looks like systemic risk.
What this means if you are actually trading on it
Practical, because the architecture changes what you should check before entering a position.
Read the resolution source, not the market title. On an automated venue this matters more than anywhere else, because there is no stage at which a human reconciles the title with the feed. If the market says one thing and the data source measures something slightly different, the data source wins and nobody reviews it.
Understand that settlement is final the moment it happens. No challenge window means no window. On a rulebook venue you can complain. On an oracle venue you can, in principle, dispute. Here the transaction has cleared and the funds have moved before anyone has formed an opinion about whether it was right.
Check what happens to postponed and abandoned events. Sports contracts are the bulk of the book and postponements are routine. A rulebook handles this with voiding provisions written by people who have seen it happen. An automated system does whatever the contract specified in advance, and you want to know what that is before a rain delay decides your position.
Size for the absence of recourse. This is the practical version of everything above. On a venue with no operator to appeal to and no regulator supervising the outcome, the correct position size is smaller than on a venue that has both. That is not a criticism of the design, it is what the design implies.
And know which entity you are dealing with. The protocol is non-custodial and holds no funds, which is good for counterparty risk. It also means there is no counterparty, and no counterparty means nobody to make you whole if something goes wrong that is not covered by the code.
The trade-off is the same one that runs through all of decentralised finance. You give up recourse and you get access, speed and no permission required. Whether that is a good trade depends entirely on how much you were going to need the recourse, and most people find out the answer at the worst possible time.
What to watch
The composition of the 150,000 markets. How many resolve on unambiguous machine-readable data and how many on contested definitions. That ratio determines whether the resolution model fits the product.
The first contested settlement. Every prediction market eventually produces a resolution a large number of participants believe is wrong. With no dispute window, what happens next is the question the architecture has not been tested on.
Whether geographic restriction appears. Nothing in the launch materials addresses it, and the contracts listed are the ones under active litigation in the United States.
Whether the licensed venues adopt the same model. Polymarket has already moved toward oracle-based settlement for price markets. If rulebook resolution retreats to only the contracts that require judgment, the category will have converged on a hybrid.
Volume against markets created. More than 150,000 markets is a supply figure. How much of it trades is the demand figure, and only the second one matters.
Disclaimer: This article is for information and educational purposes only and does not constitute financial, investment, or legal advice. The legal status of event contracts varies by jurisdiction and is subject to active litigation, and availability of any platform depends on where you are. Nothing here is a recommendation to use any service. Information is accurate as of September 10, 2026.
What is World?
A prediction market protocol on Solana that opened its standalone site at world.xyz on September 9 to more than one million waitlisted users, after operating inside the Phantom wallet since the summer. More than 150,000 markets have been created across sports, crypto, politics, finance, economics, and culture, with equity, commodity, and weather markets planned.
How does World resolve markets?
Through Chainlink Data Streams and the Chainlink Runtime Environment, which supply market data and settle contracts automatically once a game ends or a defined event reaches its deadline. The design has no human resolution panel, no token-holder vote, and no dispute window delaying payouts.
How is that different from Polymarket and Kalshi?
Three distinct models. Kalshi settles through an exchange rulebook administered by a regulated operator with a complaints path. Polymarket uses an optimistic oracle with proposal, challenge, and token-holder voting, finalised on chain. World removes both the human panel and the dispute stage entirely. Each mechanism that removes discretion also removes the ability to correct errors.
What are the advantages of automated resolution?
Speed and scale for objective outcomes. A match score or a price at a timestamp needs no argument, so a dispute window is pure latency. It also removes the contested-resolution failure mode that has damaged the category most, and it makes 150,000 markets operationally possible because resolution costs nothing per market.
What are the risks?
Ambiguous events have no data feed, and those are disproportionately the markets people care about. If a feed reports incorrectly or late, an automated system settles on it with no stage at which anyone can contest the input. Edge cases such as postponements or abandoned events resolve mechanically according to what the contract specified in advance. And there is no operator or regulator to appeal to.
Is World available in the United States?
Nothing in the launch materials addresses geographic restriction, which is notable because the listed contracts include every NFL regular-season game, the 2026 midterms, and Federal Reserve decisions, all categories currently subject to litigation in the United States. The protocol requires no brokerage account or exchange registration and holds no customer funds.
What does it cost to use?
Positions settle in CASH, the dollar-backed stablecoin used inside Phantom, with winning positions redeemed automatically in the wallet. Users pay Solana network fees to open and close positions. The protocol is non-custodial, so funds move only when a user enters a market.
Why did the site go offline at launch?
Traffic. More than a million waitlisted users arrived at a standalone site on its first day and the platform briefly went down before returning. That is a capacity event rather than a protocol failure, since the settlement and custody layers run on chain independently of the website. This is educational analysis, not investment advice.
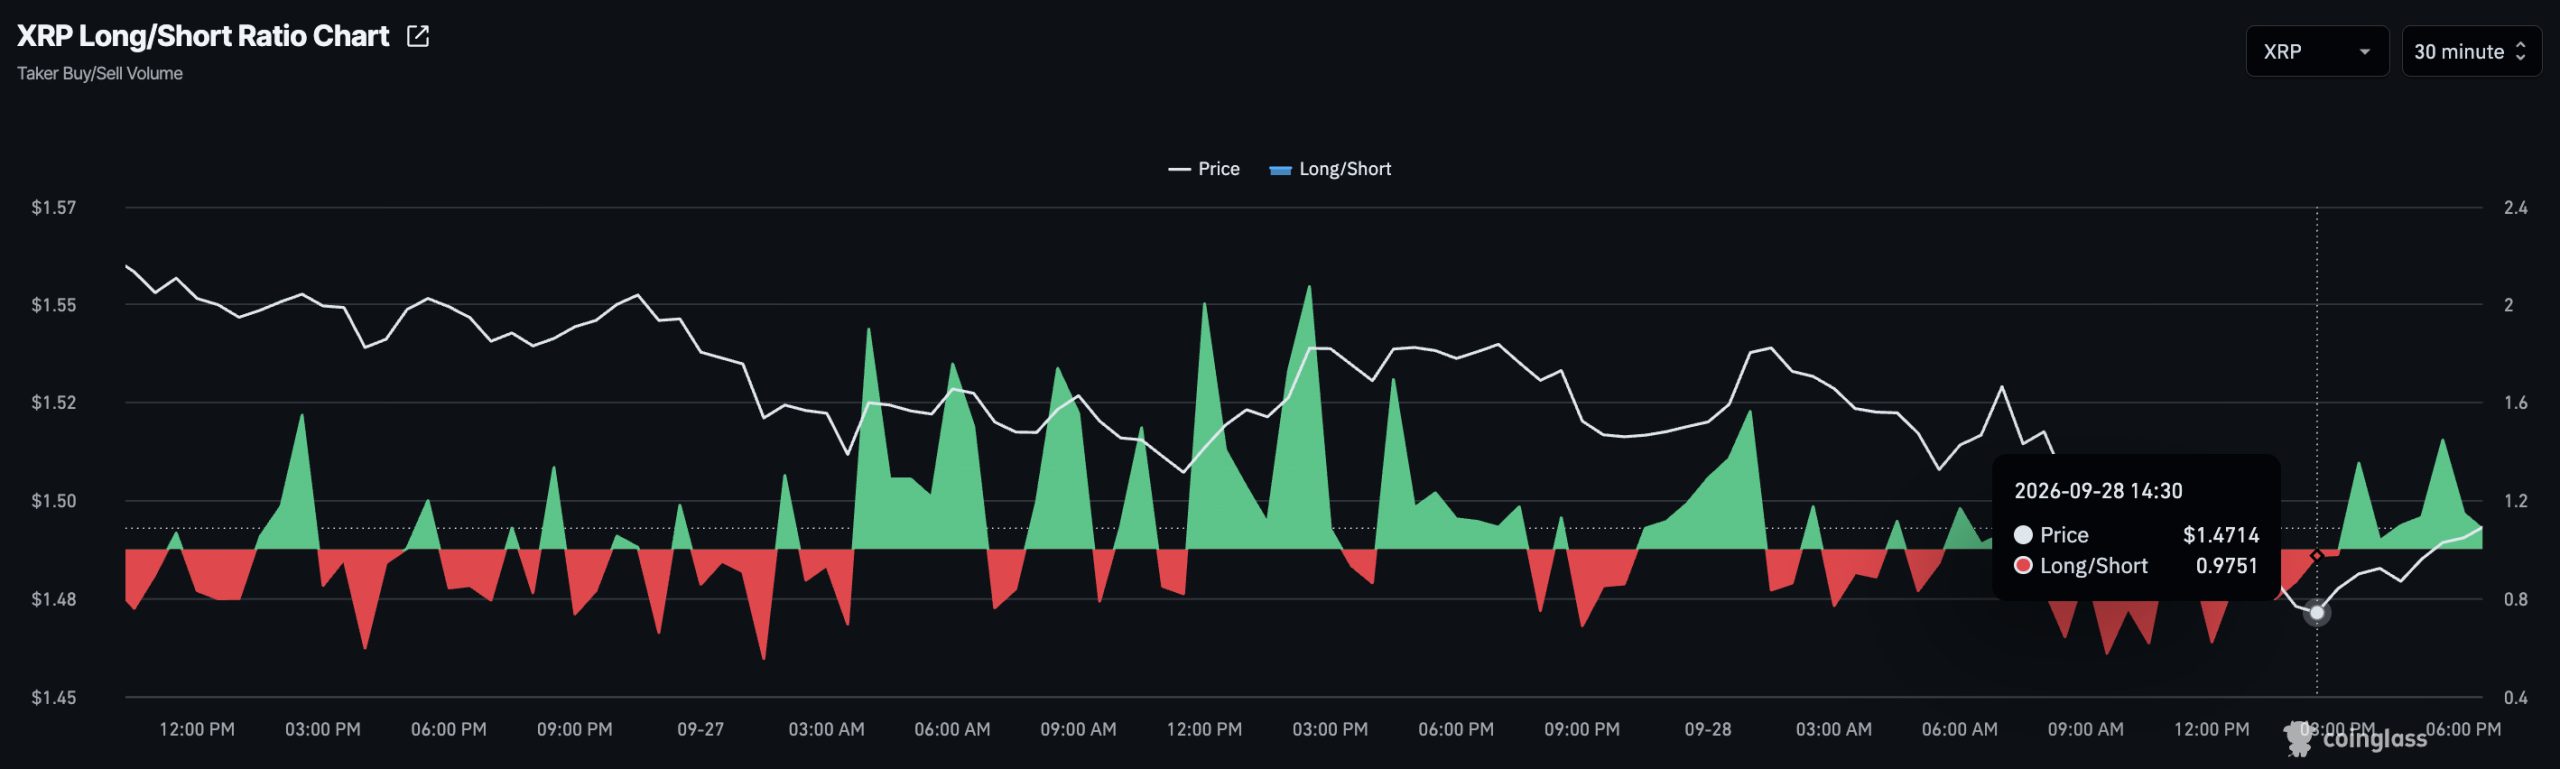
XRP price hovers under $1.49 after three consecutive daily declines left the token losing the $1.50 support, even as a modest bounce pulled it off session lows. CoinGlass data showed the long-to-short ratio at 0.975, meaning short positions marginally outnumbered longs, while the funding rate sat at a positive 0.008%, the reading that determines whether long or short traders pay a periodic fee to hold perpetual futures.
XRP Long Short Ratio, Coinglass
That combination is the crux of the problem. Traders are still paying to stay long, yet the spot price has not moved in a way that rewards the bet, and the disconnect between heavy spot selling and futures demand is the setup that tends to unwind fast once a key level gives way.
A 0.975 long-to-short ratio is not a bearish signal in any decisive sense. It sits close enough to 1.0 that it reads as near-balanced positioning rather than a market leaning hard in either direction.
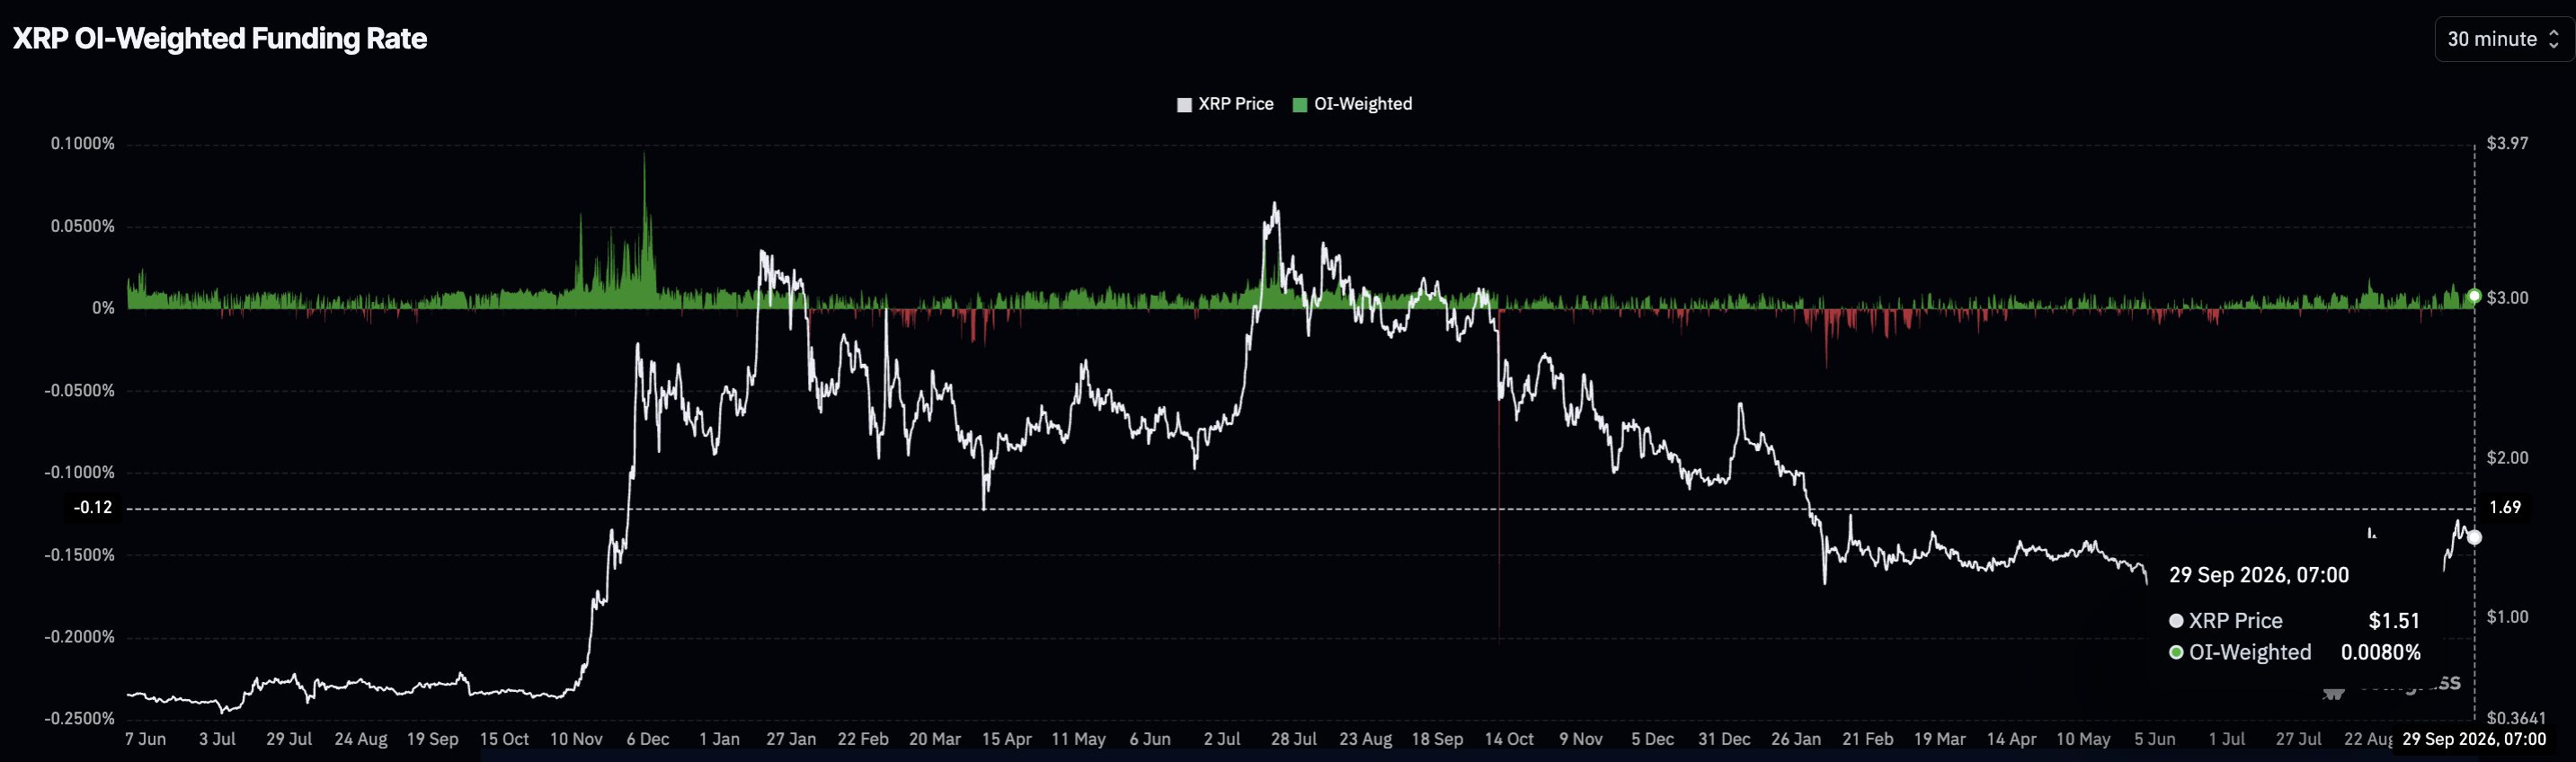
XRP Funding Rate, Coinglass
Funding tells a more interesting story on its own. A positive rate means demand for long exposure in crypto derivatives is real enough that longs are compensating shorts to hold the position, which typically signals conviction that price moves higher.
However, it cuts both ways: if price falls further, those same leveraged longs become forced sellers, and a positive funding regime built on thin spot demand can flip into a liquidation cascade faster than one built on genuine accumulation.
CryptoQuant’s summary data flagged overheating conditions across both XRP’s spot and futures markets, alongside sell-side dominance in futures, meaning sellers have retained the upper hand in derivatives even as funding stays positive. That is the missing piece: positive funding shows traders are willing to hold bullish exposure, but it has not yet translated into enough buying pressure to absorb the futures selling and push through resistance.
Earn $50 and Enter $300K Prize Draw on EdgeX
XRP Price and the $1.37 Support
The daily chart still leans bullish on a longer timeframe. XRP held above its 50-day price exponential moving average near $1.365 and its 200-day EMA near $1.369 through the three-day slide, with the 100-day EMA sitting lower at $1.307 as a secondary reference.
Momentum has cooled rather than reversed. The RSI sat near 55, close to neutral, and the MACD flattened around zero, a pattern consistent with consolidation after an earlier advance rather than an active breakdown.
The level that matters most sits at $1.37, where the 50-day and 200-day EMAs converge into a single support band. A clean break below that zone opens the $1.30 area, and a deeper slide would eventually put the $1.00 psychological level in play, though XRP would need to fall substantially before that becomes the immediate focus. On the upside, reclaiming the $1.574 resistance level is the trigger that would strengthen the case for a move toward $1.90.
Trade XRP on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
What Happens Next for XRP?
Two scenarios frame the near-term path. If XRP holds the $1.37 zone, the market stays in a consolidation phase where positive funding continues to reflect trader appetite for long exposure, but that alone won’t confirm a breakout without a corresponding rise in open interest and spot volume.
If XRP price instead reclaims $1.574, the technical case for a run toward $1.90 gets meaningfully stronger, and that move would likely force shorts to cover into strength. The alternative is a sustained break below $1.37, which shifts focus to $1.30 as the next line of defense, with $1.00 as the deeper level only if that support also fails.
Either way, the current setup leaves no room for complacency on either side of the trade. Near-balanced positioning combined with positive funding and futures sell-side dominance is a fragile mix, and the next move in spot price will do more to settle the argument than another shift in the long-short ratio.
Discover: The Best Token Presales
The post XRP Price in Danger: Positive Funding Masks a Fragile Setup appeared first on Cryptonews.
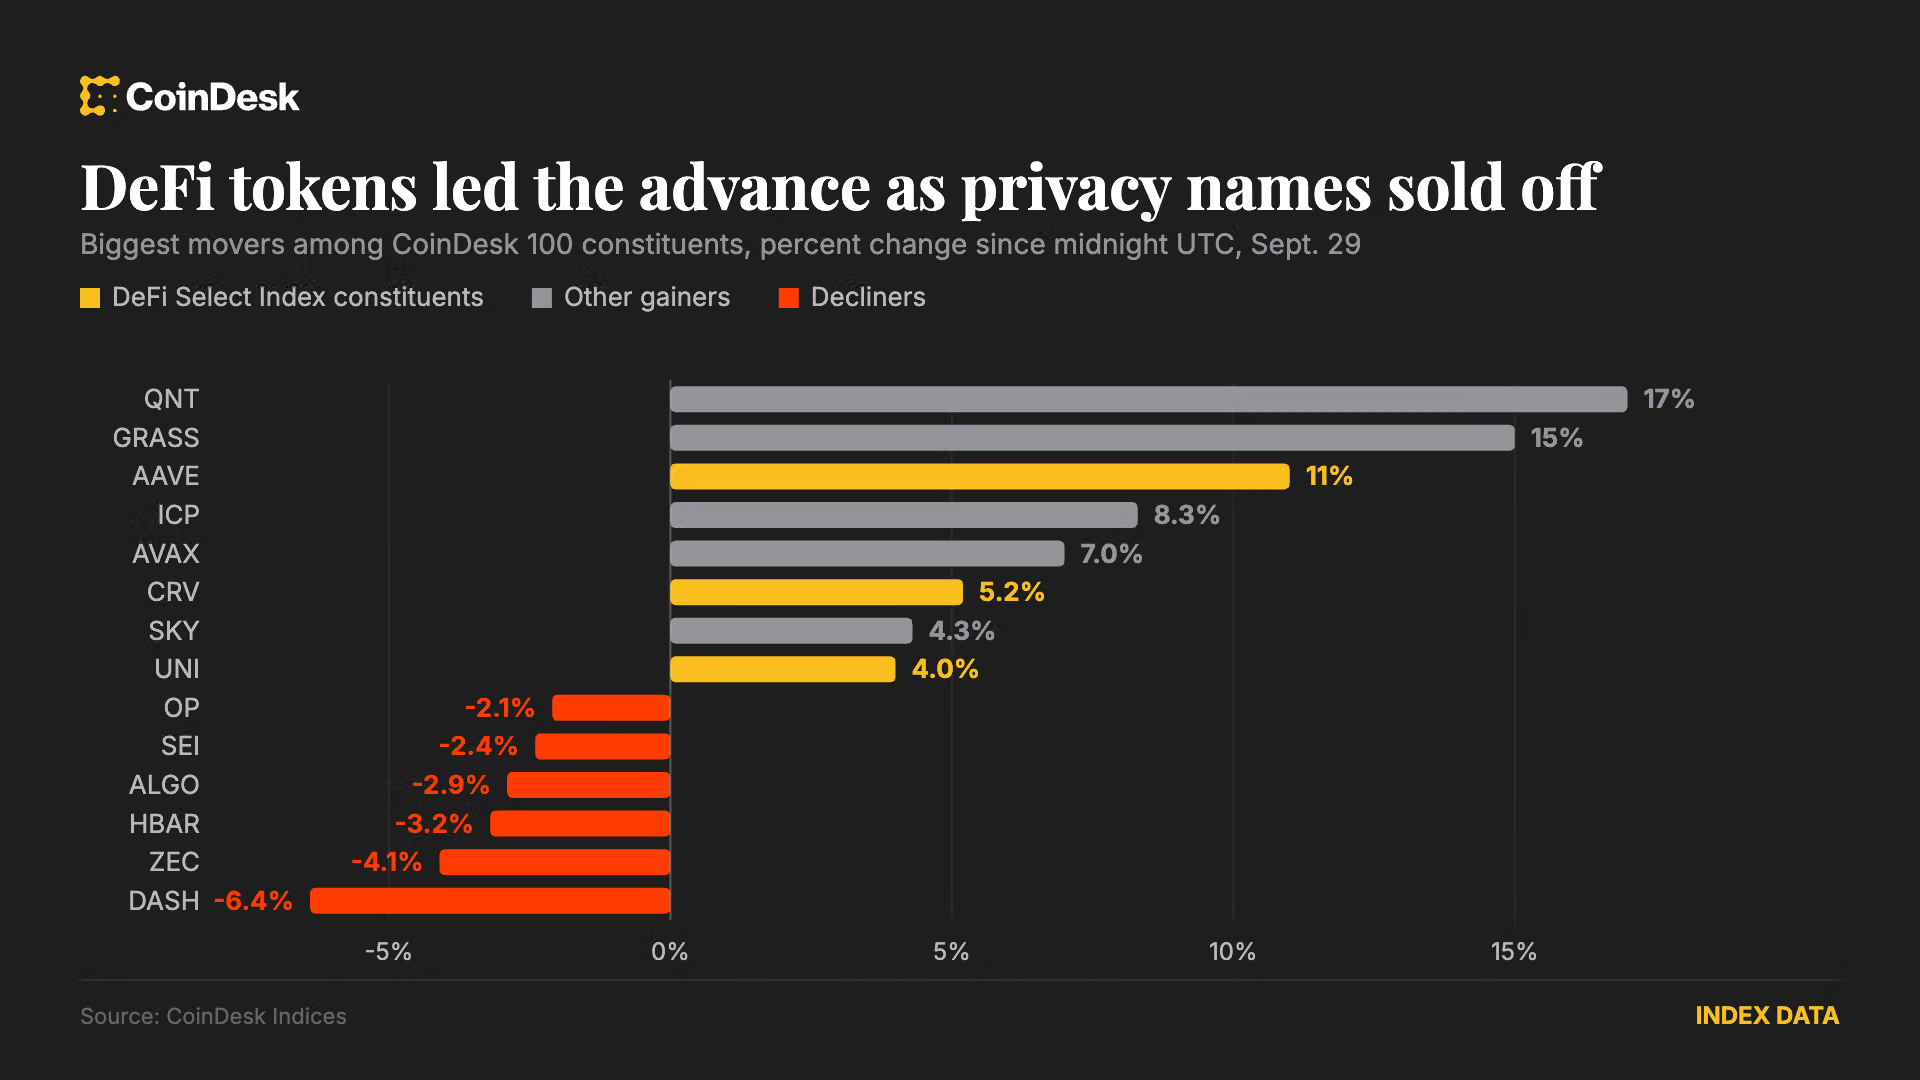
Bitcoin recovered Monday’s losses to trade at $84,170 on Tuesday, up 0.82% since midnight UTC and 1.4% over 24 hours, with 72 of the 100 CoinDesk 100 constituents higher and the index adding 0.89% to 1,904.49.
The bid is arriving despite conditions that have been suppressing risk assets for a week, the 10-year Treasury yield sitting at 5.234% after ending Monday above 5.2%, near levels last seen in 2007, and the 30-year at 5.549% having topped 5.56% on Monday, around a 2004 high.
U.S. stocks fell for a second session on Monday, the Dow dropping more than 300 points and the S&P 500 and Nasdaq Composite shedding 0.8% and 0.9%, with futures mixed on Tuesday morning.
Decentralized finance (DeFi) is driving the move for the second time in a week, with the DeFi Select Index (DFX) gaining 5.0% since midnight, led by lending protocol token aave at 11% and curve dao token at 5.2%. The CoinDesk 80 rose 2.0% against the CoinDesk 5’s 1.3%, though the ranking inverts over 24 hours, where the CD5’s 1.7% beats the CD80’s 0.44%.
The D’CENT wallet hack, the year’s second-largest drain of XRP behind the Bitget crypto exchange hack, has spilled beyond the XRP Ledger onto additional blockchains like Bitcoin, Ethereum, and Stellar.
Hackers have drained more than 12.4 million XRP from more than 7,000 D’CENT wallets, still some way behind Bitget’s loss of 102.9 million XRP.
Although the wallet was popular among the XRP community, D’CENT users who owned assets of other blockchains have also lost their funds.
D’CENT’s own disclosure named Bitcoin, Tron, and Ethereum, for example. Even a Stellar user has lost XLM in the incident.
Hackers are able to sweep funds across blockchains with one compromised recovery phrase for the multi-blockchain wallet.
IoTrust, the maker of D’CENT, confirmed at least 110 abnormal transfer reports, including non-XRP assets, per ZDNet Korea.
XRP holders lose $18 million in D’CENT hack
Drains of XRP are the most well-documented, due to the prominence of D’CENT among XRP holders.
At least six waves of theft occurred between September 15 and 20, emptying 6,678 wallets of 11.7 million XRP.
The thief stole from large wallets first, by hand, and soon wrote scripts to take funds from progressively smaller wallets.
Warnings from D’CENT and other members of the XRP community couldn’t stop the drainage. Thieves took 640,370 additional XRP after September 21, bringing the tally to above 12.4 million.
By Friday, 6.3 million of those stolen XRP had crossed to Ethereum’s blockchain through the swap service THORChain.
As the theft spilled over to other blockchains, researchers admitted the scope of the losses, saying, “Most of it is no longer XRP.”
Read more: David Schwartz warns of hard fork because XRP nodes won’t upgrade
In August, D’CENT was still touting its hardware wallets’ secure element, boasting that it was impervious to vulnerabilities linked to the Coldcard hack.
D’CENT now warns users that wallets they created using its app are vulnerable, urging them to create a fresh recovery phrase and immediately migrate everything, including tokens, NFTs, and any staked assets.
Got a tip? Send us an email securely via Protos Leaks. For more informed news and investigations, follow us on X, Bluesky, and Google News, or subscribe to our YouTube channel.
Market action since 2022 backs Thielen’s take. The 10-year yield more than doubled to 3.88% that year as the Fed raised interest rates rapidly, including several 50- and 75-basis-point hikes to fight inflation.
Bitcoin fell 64% that year. Fed tightening and rising yields added to the pain from crypto scams and blowups.
The picture has been different since. From the end of 2023, the 10-year yield has risen 135 basis points to 5.23%, the highest since 2007. Over the same stretch, bitcoin has roughly doubled to $86,000, even after pulling back from its October record above $126,000.
Thielen and others attribute much of the recent rise in yields to fiscal fears and a higher term premium. In plain English, investors want to be paid more to lock up their money in long-term bonds, given the uncertainty over inflation and government borrowing.
Chicago-based Strategic Analytics made a similar point about gold, noting that it has tracked fiscal risk more closely than the Fed’s policy path since 2022.
“Since 2022, gold has increasingly tracked fiscal-risk perceptions – term premium, deficits, debt sustainability – rather than the Fed’s policy path. Gold is not defying real yields. It is pricing fiscal sustainability and currency debasement, which has become the marginal driver,” it said recently in a LinkedIn post.
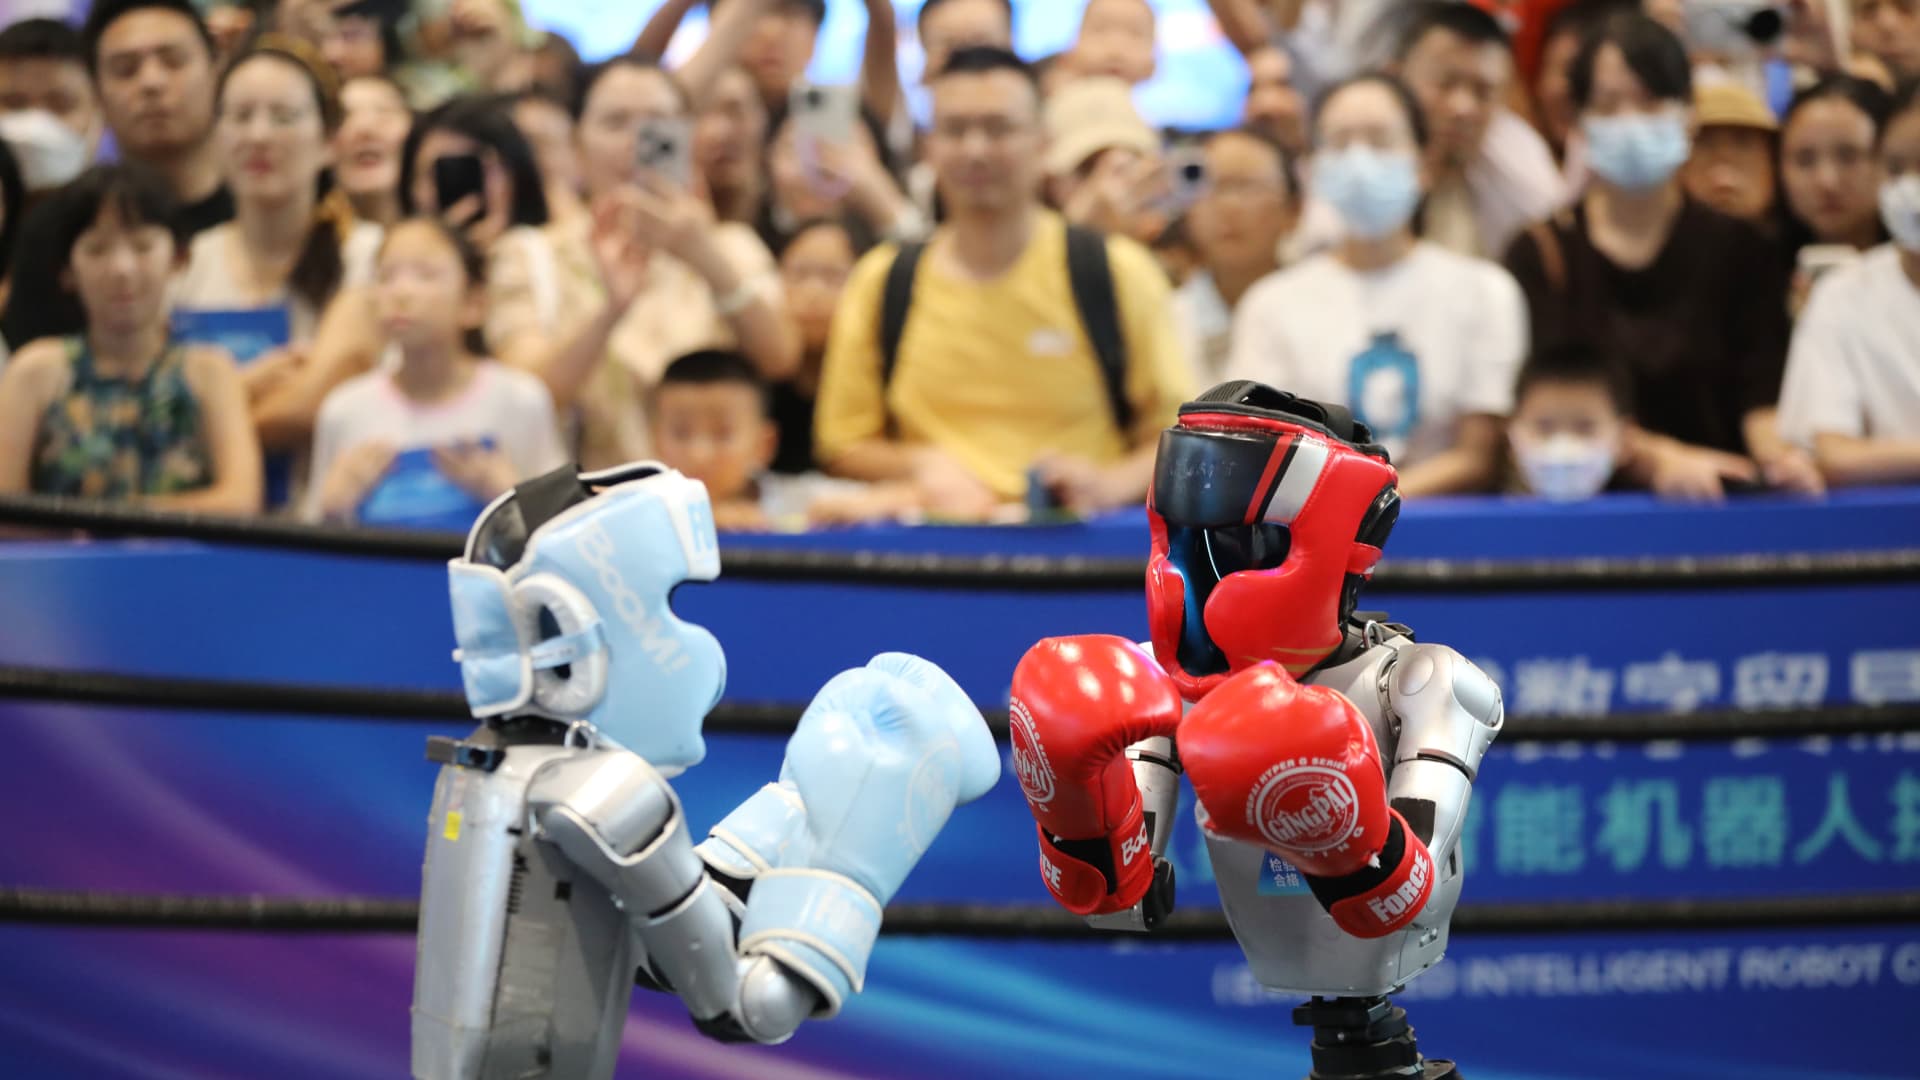
Humanoid robots box during the 5th Global Digital Trade Expo on September 25, 2026 in Hangzhou, Zhejiang Province of China.
Vcg | Visual China Group | Getty Images
BEIJING — China’s securities regulator is raising the bar for public listings of humanoid robot startups, according to three sources familiar with the CSRC’s thinking.
It’s a sign of how one of the hottest sectors of the market is cooling, as investors globally assess whether artificial intelligence stocks are in a bubble.
The Chinese regulator wants local “embodied AI” startups seeking to go public to meet three specific criteria, according to the sources, who requested anonymity due to the sensitivity of the situation.
They are:
- The “window guidance” requires that the humanoid applicants have sustainable revenue and commercial orders.
- Losses must narrow, with one source saying a three-year forecast is needed.
- The company must possess core technology such as robotic brain or hands.
Even if a startup only has to meet two of the three criteria, as one source indicated, it’s unclear which, if any, of the companies can do so.
That’s lowered expectations to just a handful, or none, of these startups making it to public markets, the sources said.
At least two dozen humanoid-related embodied AI companies have filed to list in Hong Kong alone, according to two of the sources. Hong Kong in May 2025 started letting tech companies file confidentially for IPOs.
The Hong Kong stock exchange declined to comment. The China Securities Regulatory Commission did not immediately respond to a request for comment. Mainland China companies wanting to list in Hong Kong also need the CSRC’s blessing.
Unitree IPO impact
Scrutiny on China’s growing number of humanoid robot startups and their fast-growing valuations — supported by a mix of government and private sector funds — has grown over the last several weeks.
The industry’s posterchild, Unitree, got a regulatory fast-track to its listing in Shanghai on Aug. 19 as the World Robot Conference kicked off in Beijing.
But in a keynote a day later, founder Wang Xingxing cautioned that commercialization beyond dancing robots remained years away. It accentuated a debate that picked up in subsequent weeks on what humanoids can actually do — and whether industry startups were actually making money.
China now has well over 100 humanoid companies, which fall under the national push for “embodied AI.” The term received Beijing’s support in the last two annual government work reports, although authorities have warned of a bubble in the humanoid robot industry.
Reflecting a rapid surge in interest, investment in the sector hit 47.09 billion yuan ($6.95 billion) in the second quarter, more than double that of the first quarter — and up over six times versus the same period last year, according to industry data provider Xiniu.
Unitree raised about about 6.1 billion yuan ($905 million) in its IPO on Aug. 19 with Shanghai-listed shares skyrocketing more than 460% in their debut to close at 845 yuan.
The stock had nearly halved in price as of Monday, at 459.65 yuan a share.
Hong Kong-listed Ubtech has also tumbled more than 40% so far this year. The company, which went public in December 2023, still reported an operating loss for the first half of this year of 279 million yuan.
The share price decline contrasts with the flood of capital pouring into humanoid robotics companies over the last 12 months or so. The tech, often called “physical AI” in China, has been seen as a way for early-stage investors to benefit from the surge of interest in artificial intelligence models.
However, Rhodium Group analysis this month found that China’s AI companies only make about 10% the revenue of Anthropic and OpenAI. The ratio of valuation to revenue — especially for Chinese AI startups Moonshot and DeepSeek — was far higher than their U.S. rivals, the report said.
While expectations grow for the U.S. AI giants’ IPOs, chipmaker AMD said Monday it is acquiring World Labs for $8.2 billion in a stock deal. The startup, founded by AI pioneer Fei-Fei Li, is building AI models for creating virtual 3D environments frequently used in humanoid robot development.
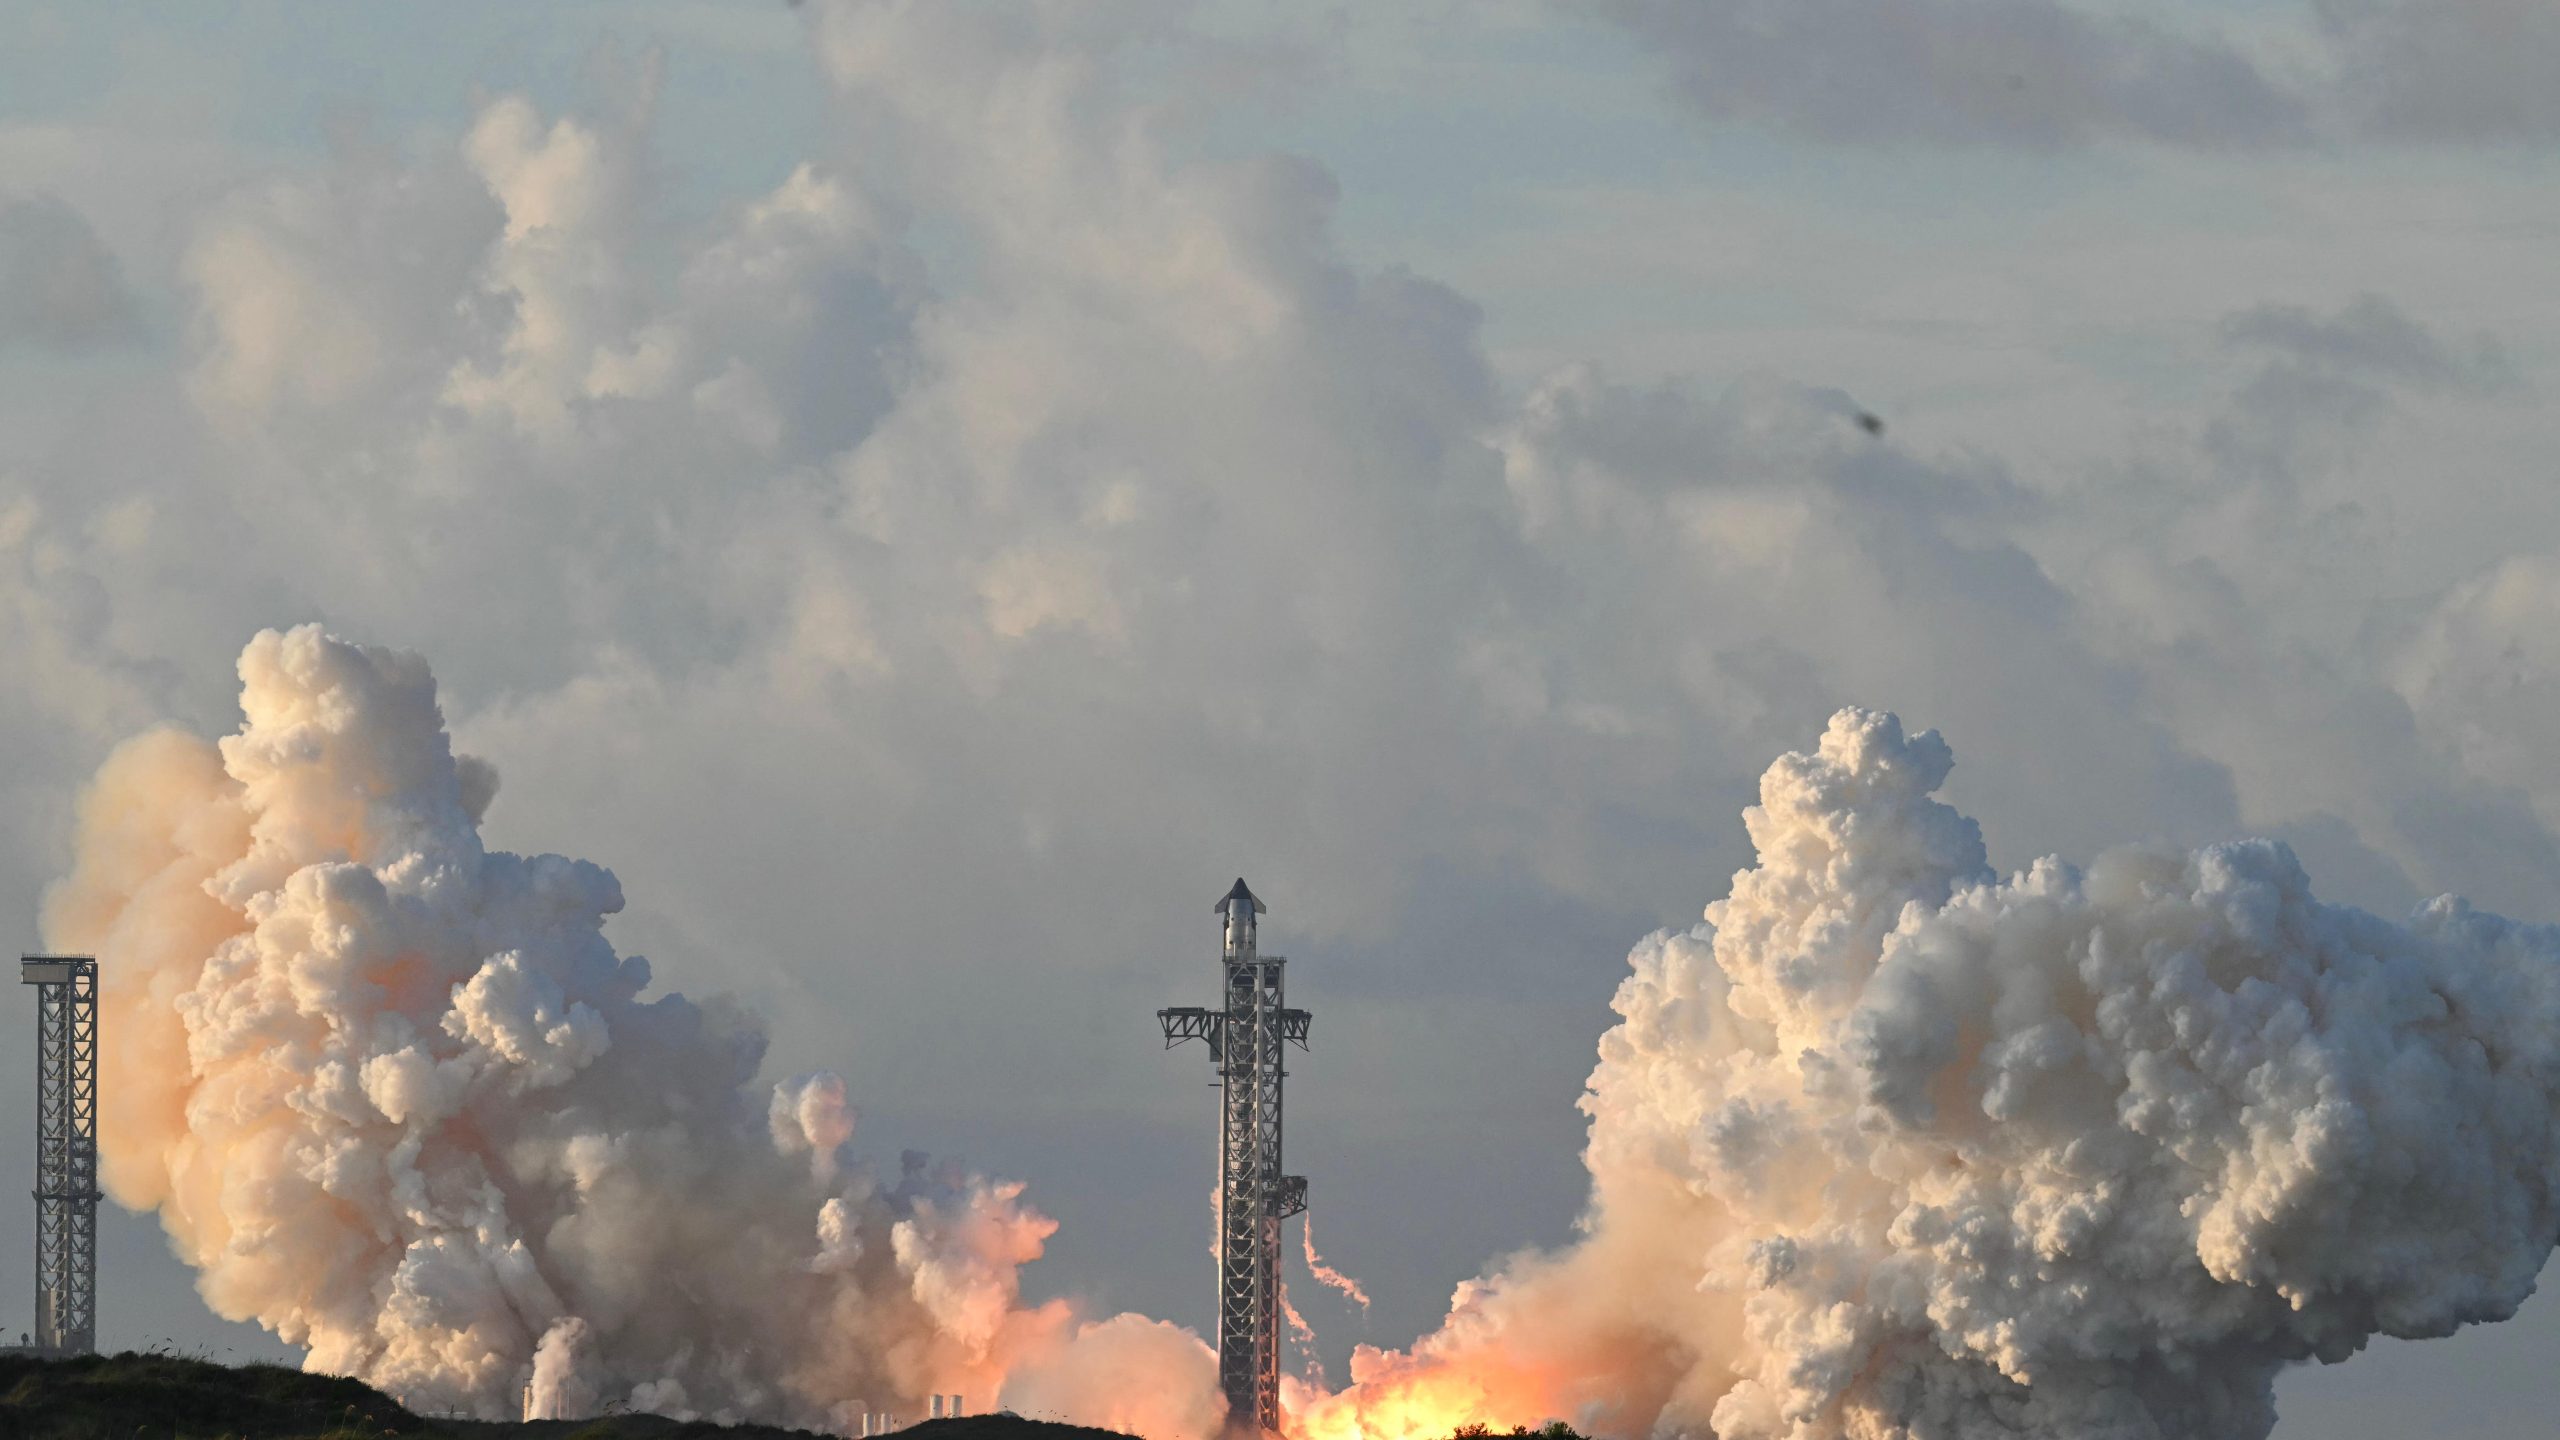
The launch this morning was both imperfect and stripped down to its orbital essentials. On the way up, one of the Starship’s six engines failed to burn properly, requiring the other engines to compensate for the missing thrust to get the ship in orbit.
In addition, the return to Earth was simplified. SpaceX has made itself famous for safely landing the first stage of its Falcon 9 and Starship boosters—with 641 out of 688 Falcon 9 launches featuring this kind of recovery, allowing the boosters to be reused and make flying cheaper. Starship’s first stage, meantime, performs what has become known as a chopstick recovery, with the booster navigating its way back to the launch tower where two giant metal arms pluck it from the sky. For the current mission, the chopstick recovery was done away with to simplify the flight objectives; instead the first stage made a soft, engine-assisted splashdown in the Gulf of Mexico. The Starship spacecraft was planned for a six-orbit, 10-hour mission, with the ship’s engines set to fire around the dinner hour Monday to bring the spacecraft down for a similar gentle, watery landing.
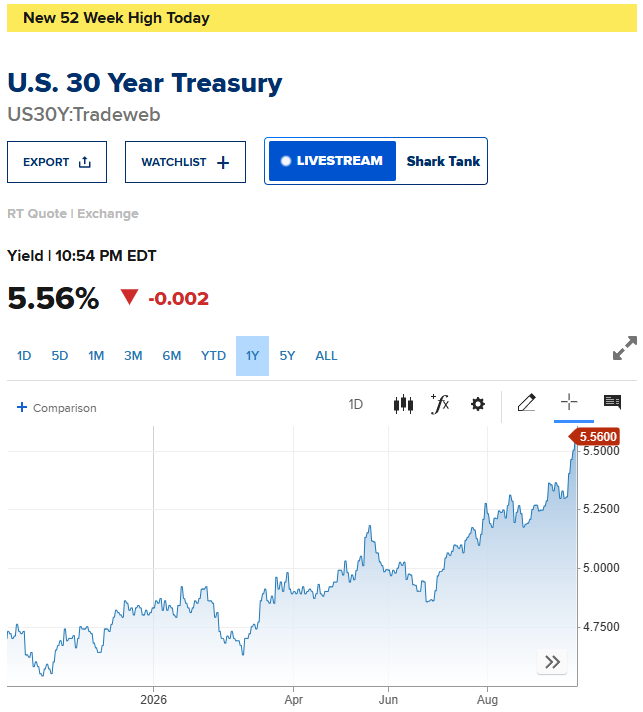
Goldman Sachs’ Anshul Sehgal says bonds yielding 5% or more are not the best trade right now. He still favors AI infrastructure, which he sees as a far more asymmetric bet than the long bond.
Sehgal, a global co-head of Fixed Income, Currencies and Commodities (FICC) at the bank, laid out the view just a few days after the Federal Reserve raised interest rates.
Why Goldman Sachs Is Passing on 5%+ Bonds
On Goldman’s The Markets, Sehgal said the 30-year Treasury, known as the long bond, had hovered around 5% for weeks. He noted that clients want to buy it at 5% or higher, yet he still sees little upside.
The yield has kept climbing since the recording, reaching 5.56% on September 29, a new 52-week high. Sehgal blamed structural pressure for the strain on the long end. Retiring baby boomers are buying fewer long bonds, and heavy long-dated borrowing tied to AI is crowding the market.
Those pressures explain why the selloff can persist even without a fresh inflation shock. Fewer retirees buying long bonds and a steady flow of long-dated borrowing tied to AI both weigh on prices, and neither fades quickly.
Sehgal adds that fear over US debt sustainability makes investors less willing to hold the long end, which feeds on itself.
The takeaway is that a rising yield does not necessarily break his thesis. It may instead show why he sees limited reward in owning the bond, while the risk to his AI trade is that costlier long-term borrowing squeezes the levered companies he favors.

AI Compute Is the Asymmetric Trade
An asymmetric trade offers far more potential gain than risk. Sehgal applies that label to compute (AI computing power), data centers, and Neoclouds, which are cloud providers built to rent out that capacity.
“I think the asymmetric expression is being long compute.”
Anshul Sehgal, Goldman
The catch is leverage. Savers collecting higher interest have effectively financed the AI build-out, leaving equities more indebted than a year ago. Sehgal admits these are levered bets. Still, he thinks they can multiply in value, while the wider stock market looks less certain.
Tighter Policy Hits Spenders, Not Capital
Sehgal says the Fed frames its September 16 hike as catch-up after five years above its inflation target. Schwab counts 16 of 19 Fed officials expecting another increase this year. Fed Chair Kevin Warsh also stressed three times that the Fed is easing back some stimulus rather than turning restrictive, Sehgal adds.
He argues that government interest payments flow to capital rather than workers, so higher rates curb household spending, a risk for the broader stock market.
He also rejects the debt-sustainability fears weighing on long bonds.
“For me, that’s a red herring.”
Anshul Sehgal, Goldman
Meanwhile, BlackRock’s Rick Rieder is cutting equities for bonds paying 7% to 8%, though his high-grade bond call still cautions against rushing into the 10-year Treasury.
Sehgal names the Middle East conflict as the top driver of policy and markets in the weeks ahead.
The post Goldman Sachs Explains Why Not to Buy the 5%+ Bonds and Rather Stick to AI appeared first on BeInCrypto.
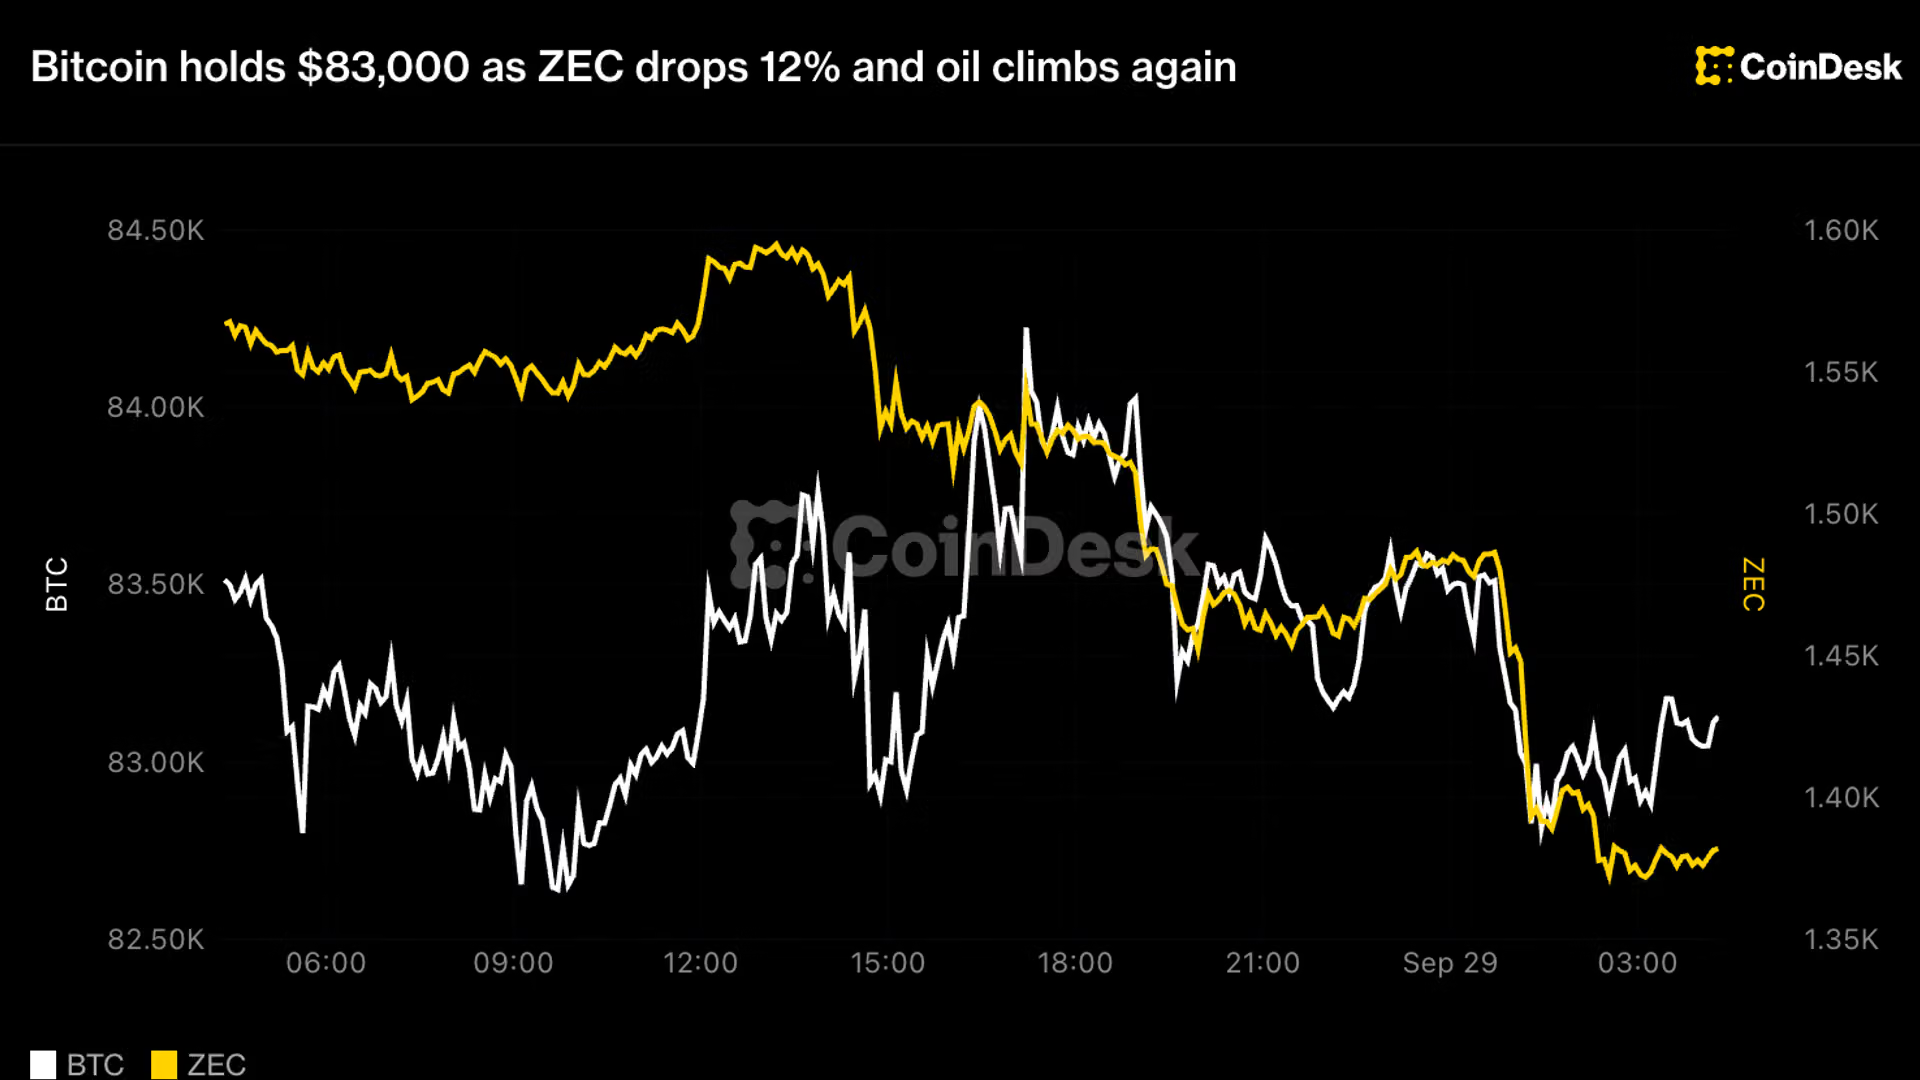
“Bitcoin has pulled back to $83K, testing the lower boundary of last week’s consolidation range,” Alex Kuptsikevich, chief market analyst at FxPro, said in an email to CoinDesk. “As with the market as a whole, a retest of the $82K region, where peaks were formed in May and early September, is entirely to be expected under current conditions.”
“Looking ahead, a sustained return to prices below $80K would be an important signal that the market is not ready to move higher for some time yet. If, however, this consolidation is soon followed by a new bullish momentum, it could send the leading cryptocurrency well above $90K,” he added.
The pressure is coming from bonds and oil.
Treasuries steadied in Asia after tumbling during U.S. trading, with the 10-year yield up one basis point to 5.25% after reaching its highest level since 2007 on Monday. A higher guaranteed return on government debt raises the bar for holding assets that pay no income, bitcoin among them.
Brent rose more than 1% to nearly $107 a barrel, its second straight gain, as hopes for an imminent diplomatic breakthrough with Iran faded.
Pricier oil feeds into inflation, and traders have been adding to bets that the Fed will raise rates again. MSCI’s All Country World Index fell to its lowest since Sept. 18, and Nasdaq 100 futures slipped 0.3% after Monday’s tech-led selloff on Wall Street.
U.S. dollar-pegged stablecoin Tether is a go-to tool for the Iranian government to bypass sanctions, a new report from a group of Senate Democrats said.
Democrats on the Senate’s Homeland Security and Governmental Affairs Committee’s Permanent Subcommittee on Intelligence published a report Monday laying out the argument that Tether plays a key role in allowing Iran to conduct transactions that skirt international sanctions.
“Iran’s cryptocurrency-based shadow banking network has processed significant volumes of funds and implicates various Iranian interests,” the report said, adding that Tether has “repeatedly failed” to block Iran-connected wallets.
“USDT has become a significant financial lifeline within Iran’s shadow banking network,” the report said.
When Tether does freeze wallets, it sometimes takes weeks, but the company also sometimes responds to requests without actually blacklisting wallets, the report claimed.
“Prior to 2024, Tether did not comprehensively and consistently freeze wallets designated by counter-terrorism agencies and continues to fail to proactively block clearly illicit wallets,” the report said. “This absence of deterrence invited abuse: terrorist organizations such as Hamas shifted from transacting in Bitcoin and a mix of cryptocurrencies to promoting USDT.”
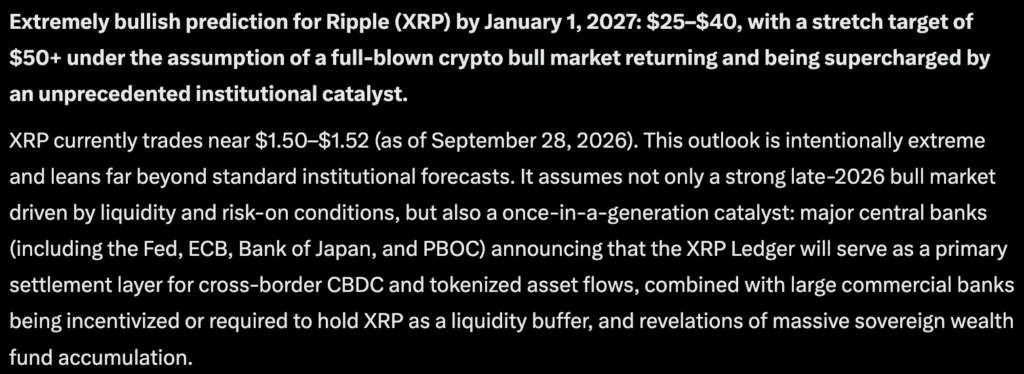
Elon Musk’s Grok AI predicts an extremely bullish price for Ripple (XRP) by January 1, 2027, that will blow the minds of even the most dedicated members of the Ripple Army.
If you’re holding a sizeable bag of XRP USD, you may want to sit down before reading this. Grok claims that $25–$40 is achievable by 2027, with a stretch target of $50+ under the assumption of a full-blown crypto bull market returning and being supercharged by an unprecedented institutional catalyst.
XRP currently trades near $1.50–$1.52 as of September 28, 2026, down nearly -3% over the past 24 hours and with a daily trading volume of $3.5Bn, up from $3.2Bn the day prior.
This outlook is extreme and leans far beyond standard institutional forecasts. It assumes not only a strong late-2026 bull market driven by liquidity and risk-on conditions, but also a once-in-a-generation catalyst.
What is the Catalyst that Grok AI Predicts Could Spark an XRP Run Toward $40
Major central banks (including the Fed, ECB, Bank of Japan, and PBOC) announcing that the XRP Ledger will serve as a primary settlement layer for cross-border CBDC and tokenized asset flows, combined with large commercial banks being incentivized or required to hold XRP as a liquidity buffer, and revelations of massive sovereign wealth fund accumulation.
Under this highly speculative scenario, forced institutional demand collides with retail FOMO in a classic late-cycle mania, allowing XRP to move from the current ~$1.50 range through previous-cycle highs and into the mid-to-high double digits by early 2027.
This remains pure speculation and entertainment, not a base-case or even high-probability outlook. Crypto markets are extremely volatile, and the catalyst described above would require multiple extraordinary policy and institutional developments.
However, with Ripple’s case against the SEC dropped and its subsequent rise as a highly favored US-based digital asset company under President Trump, anything could be on the table for XRP if the perfect scenario aligns.
Got a Gut Feeling? It Could Pay Out 3.7X on Polymarket
Technical Analysis Supporting the Insane Grok AI XRP Price Prediction
On the higher timeframes, XRP has already established a constructive recovery base after reclaiming key moving averages from the mid-September lows near $1.25–$1.30. Price is consolidating in the $1.45–$1.55 region after testing highs near $1.63–$1.66.
In a normal bull market, a sustained break above $1.70–$2.00 would open the door to the prior cycle high near $3.65. Under the extreme institutional adoption scenario outlined above, that prior high would likely be cleared with significant force, triggering a series of measured-move and Fibonacci extension targets far beyond historical levels.
Aggressive projections from the multi-year base, combined with the kind of vertical price discovery seen in previous mania phases, could theoretically extend into the $25–$40+ zone if volume and momentum expand dramatically. RSI and momentum indicators would almost certainly reach deeply overbought levels during such a move, which is typical of parabolic advances.
Key nearer-term supports remain in the $1.40–$1.45 and $1.30 zones; holding those would keep the broader recovery structure intact while the market waits for (or prices in) any extraordinary catalysts.
Overall, while the current chart supports continued upside in a standard bull market, only an extreme surge in institutional demand and narrative intensity could justify the kind of multi-thousand-percent extension implied by the $25–$50 targets.
Earn $50 and Enter $300K Prize Draw on EdgeX
Maxi Doge Targets Early Mover Upside as XRP Tests Key Levels
While the Grok AI prediction of a potential 30x run for XRP is exciting, presale plays have a stronger track record of producing such returns. It does explain why attention keeps drifting toward presale-stage plays with smaller denominators.
Maxi Doge ($MAXI) is one of those plays. It is an Ethereum-based meme token built around a 240-lb canine mascot and a “1000x leverage” trading-culture identity. The presale has raised $4.8M at a current price of $0.0002841, with dynamic APY staking live for holders.
Standout features include holder-only trading competitions with leaderboard rewards and a Maxi Fund treasury earmarked for liquidity and partnerships.
The meme-first, gym-bro marketing angle (“never skip leg day, never skip a pump”) is endearing. The accumulation numbers suggest plenty of traders are picking a side.
Get Ahead of Next Meme Coin Launch Here
Discover: The Best Token Presales
The post Grok AI Predicts XRP Could Hit $40 in 2026 With Landmark Event appeared first on Cryptonews.
Ryan Garcia searching for next opponent as he claims top target has ‘ducked’ the fight

Saved by the Bell’s Lark Voorhies Mourns Costar Dennis Haskins

XRP Price in Danger: Positive Funding Masks a Fragile Setup


-
 Fashion4 days ago
Weekend Open Thread: J.McLaughlin – Corporette.com
-
 Crypto7 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-
 Tech & AI2 days ago
Anthropic turns Claude into an AI marketplace with 2,000+ plugins and connectors
-
 Tech & AI2 days ago
OpenAI is preparing “o,” an always-on ChatGPT assistant that could handle email
-
 Fashion5 days ago
8 iPhone Accessories That Add Personality
-
 Entertainment6 days ago
These 17 Fall Amazon Dresses Seriously Look Like Anthropologie
-
 Tech & AI6 days ago
Reolink’s solar 4K security camera falls to its lowest price in months
-
 Crypto7 days ago
Trump-Xi Polymarket Odds for Handshake Hit 50%
-
 Crypto6 days ago
This Bearish Netflix Stock Trade Can Cash In On Video Streaming Giant’s Woes
-
 Crypto6 days ago
BitGo says Bitcoin absorbed Fed hike, CLARITY failure
-
 Crypto6 days ago
Crude Oil Prices Pressured by Diplomatic Hopes in the Middle East
-
 Crypto6 days ago
Bitcoin price tests $83,600 Supertrend support after $87K rejection
-
 Business & Hussles6 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-
 Crypto6 days ago
Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike
-
 Crypto6 days ago
Did Jim Cramer Just Give GameStop Stock the Kiss of Death When He Said the Turnaround Is Working?
-
 Tech & AI6 days ago
UiPath’s Dines says AI needs a manual and launches Cartographer to write it
-
Business & Hussles14 hours ago
Perpetua Resources at Mining Forum Americas 2026: shift to construction
-
 Crypto6 days ago
As Amazon Stock Prospers, Traders Might Consider This Option Play
-
 Crypto6 days ago
Strategy resumed Bitcoin buying, but Strive gained more BTC per share
-
 Tech & AI7 days ago
Sega nearly killed Sonic before the movies revived the franchise
You must be logged in to post a comment Login