
Crypto World
Coinbase connects crypto services to 3,000+ U.S. banks

Coinbase has announced a Sept. 16 partnership with Stablecore to embed crypto trading, custody, staking and stablecoin payments into banking systems whose integration footprint reaches more than 3,000 U.S. banks and credit unions.
Summary
- Coinbase and Stablecore will let banks offer crypto trading, custody, staking and stablecoin payments directly.
- Stablecore says its existing technology integrations reach more than 3,000 U.S. banks and credit unions.
- Amarillo National Bank is among institutions already working with the Coinbase and Stablecore partnership program.
- Coinbase provides regulated custody and exchange infrastructure while Stablecore connects existing banking and compliance systems.
- Stablecore’s Verafin integration remains in beta, with wider mutual-customer rollout planned from fourth quarter 2026.
Coinbase said the partnership is already underway with institutions including Amarillo National Bank in Texas, while Stablecore will connect Coinbase’s digital asset infrastructure to the core banking, digital banking and compliance systems used by participating financial institutions.
The announcement does not say that 3,000 banks have signed contracts with Coinbase. Stablecore says its existing integrations reach technology systems used by more than 3,000 U.S. banks and credit unions, giving participating institutions a route to add digital asset products without replacing their existing banking platforms.
Coinbase services will sit inside existing bank platforms
Through the partnership, participating bank and credit union customers could buy, sell, hold, stake and make payments with digital assets through their normal banking experience. Coinbase provides the underlying custody and exchange infrastructure, while Stablecore manages the connection between that infrastructure and each institution’s technology stack.
Stablecore’s role covers orchestration between core banking systems, customer-facing digital banking software and compliance tools. Its platform is designed as a white-label layer, allowing a financial institution to retain its own brand and customer interface while using outside infrastructure for digital asset functions.
Coinbase has not identified the stablecoins or blockchain networks that participating institutions will support. The Sept. 16 announcement does not publish transaction fees, custody charges, staking terms, minimum balances or a general customer launch date.
Alec Lovett, Coinbase’s head of infrastructure business, said “Community banks and credit unions shouldn’t have to choose between staying local and staying current.” Coinbase presents the arrangement as infrastructure for smaller financial institutions seeking crypto services without building their own custody, trading and blockchain systems.
Stablecore CEO Alex Treece said banks should be able to add the products without moving to completely different technology platforms. His company focuses exclusively on regional banks, community banks and credit unions.
Amarillo National Bank is part of the early integration work
Amarillo National Bank appears across several Stablecore projects already moving toward production. In March, Q2 announced that Amarillo National Bank and Bank of Utah were among the early institutions working with Stablecore through Q2 Innovation Studio.
Q2 said the integration can support stablecoin payments and acceptance, digital asset accounts with fiat on- and off-ramps, crypto-backed lending, tokenized deposits and staking rewards. The capabilities can appear inside both retail and commercial digital banking experiences.
By Sept. 9, Q2 reported that Stablecore’s digital asset integration had moved from initial development into production in less than six months. Q2 described it as a native connection inside its digital banking platform.
Coinbase’s Sept. 16 release goes a step further by identifying Coinbase as the provider of underlying custody and exchange infrastructure within Stablecore’s offering. It does not specify which Coinbase services Amarillo National Bank has already activated for end customers.
No public announcement reviewed for this report confirms that Amarillo customers can currently trade crypto, earn staking rewards or send stablecoins through their bank accounts. The companies describe implementation as underway, leaving the exact customer-facing launch stage dependent on the individual institution.
Stablecore is adding crypto monitoring through Verafin
Compliance infrastructure is developing alongside the banking integrations. Stablecore announced a Sept. 15 partnership with Nasdaq Verafin that combines digital asset transaction information with traditional bank customer data for financial-crime monitoring.
Under that structure, Stablecore holds digital asset transaction and position information without storing personally identifiable information. The bank keeps its customer and account records in its core system, while both sets of information flow into Verafin for investigation and risk assessment.
Amarillo National Bank is among the beta customers testing the Verafin integration. Stablecore expects the system to reach mutual customers during the fourth quarter of 2026 and first quarter of 2027, with real-time sanctions screening for recipients of digital asset transfers planned after the initial integration.
William Ware, president of Amarillo National Bank, said “Our customers want access to emerging payment methods” while the bank seeks to maintain visibility across traditional and digital asset activity. The Verafin beta is separate from Coinbase’s custody and exchange role, although both sit within Stablecore’s developing bank technology stack.
U.S. rules allow banks to use third-party crypto providers
Federal banking regulators have clarified several activities relevant to the Coinbase and Stablecore model.
The OCC confirmed in May 2025 that national banks and federal savings associations may provide crypto custody and execute customer-directed purchases and sales. Banks can outsource permissible crypto activities to third parties when they maintain appropriate vendor and risk controls.
Two months earlier, the OCC reaffirmed that national banks may conduct certain stablecoin, distributed-ledger and crypto custody activities. The agency removed an earlier requirement that OCC-supervised banks obtain supervisory non-objection before starting those activities, while retaining normal safety, soundness and compliance expectations.
The Federal Reserve withdrew its separate advance-notification expectation for state member banks in April 2025. Crypto activities now fall within its regular supervisory process, though institutions still have to comply with applicable laws and maintain appropriate controls.
OCC guidance later confirmed that national banks may conduct riskless-principal crypto trades, where the bank facilitates a customer transaction while entering an offsetting transaction instead of keeping the asset in inventory. The December 2025 guidance maintained the requirement for safe and sound operation.
Regulatory permission does not mean every community bank can activate every Stablecore or Coinbase feature automatically. Charter type, state rules, bank policies, customer eligibility and individual product design can change what each institution offers.
Coinbase now has two community-bank distribution deals
The Stablecore agreement follows another Coinbase community-bank partnership announced six days earlier.
As crypto.news reported in its Coinbase-Moov coverage, Coinbase and Moov are working to bring stablecoin acceptance, merchant settlement, payouts and real-time funding to a network of more than 1,000 community banks and credit unions.
The two arrangements cover different parts of banking infrastructure. Moov focuses on payment acceptance, merchant settlement and funding through its payments stack, while Stablecore’s announced product set reaches trading, custody, staking, stablecoin payments and integration with core and compliance systems.
Related coverage of Coinbase’s OCC trust approval reported in April that Coinbase had received conditional approval for a national trust bank charter, with community banking groups objecting to the regulator’s decision. The Stablecore announcement identifies Coinbase as the regulated digital asset infrastructure provider but does not specify which Coinbase legal entity will provide each service to each participating institution.
Stablecore’s March Q2 announcement named Amarillo National Bank and Bank of Utah as early institutions evaluating its infrastructure, while the Sept. 16 Coinbase release names only Amarillo in connection with the new partnership. Neither company has disclosed how many banks have completed Coinbase-enabled deployment, transaction volumes from early implementations or a deadline for opening the full product set to customers.

Cointelegraph is committed to providing independent, high-quality journalism across the crypto, blockchain, AI, and fintech industries.
All news, reviews, and analyses are produced with full journalistic independence and integrity. For more details on our standards and processes, please read our Editorial Policy.
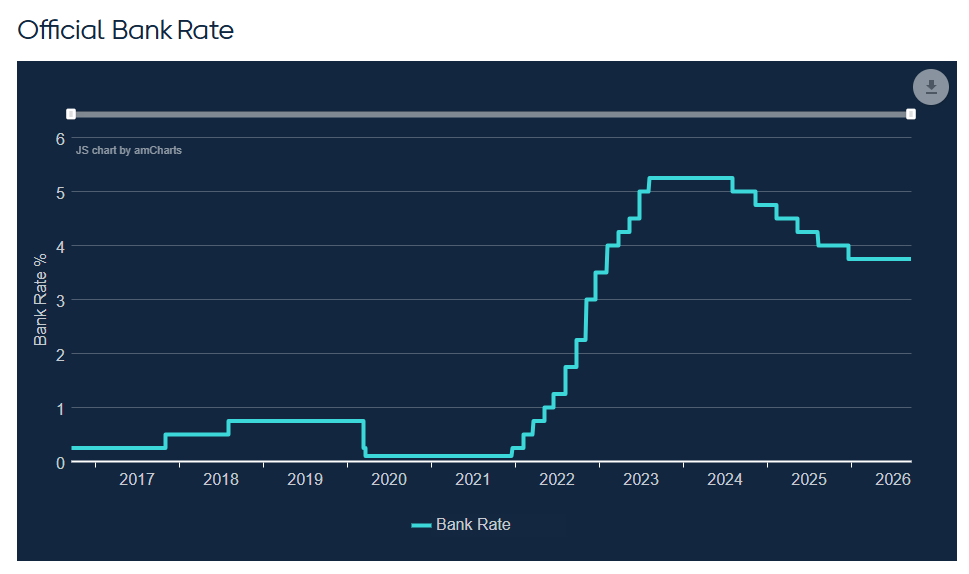
The Bank of England (BoE) is holding its rate at 3.75%, even as UK inflation climbs and the US hikes. That divergence comes down to where the inflation is coming from.
The BoE’s Monetary Policy Committee (MPC) voted six to three to hold, with three members wanting an immediate hike. A day earlier, the Federal Reserve raised US rates to 4%.
Why the Fed Hiked and the BoE Didn’t
The Federal Reserve raised its benchmark rate a quarter point to a range of 3.75% to 4% on September 16. It was the first US rate hike since 2023, coming a day before the BoE’s own decision.

Both central banks are responding to the same shock. Energy prices have surged since the Middle East conflict disrupted supply. Brent crude has climbed above $100 a barrel, lifting UK inflation to 3.1% in August, up from 2.9% in July.
Governor Andrew Bailey argues rates cannot fix an oil-driven price shock directly. He also sees little evidence that higher energy costs are spreading into wages. The Fed, facing a stronger labor market and its own inflation concerns, chose to act instead of waiting.
Economists at Dutch bank ING say the UK carries less wage-spiral risk now than in 2022. That gives the BoE more room to wait before raising rates.
Why Households Are Already Feeling It
UK households are not waiting for a formal hike to feel the cost. The average five-year mortgage rate has climbed to 5.87%, its highest level since November 2023. Lenders are already pricing in the chance of tighter policy ahead.
That leaves the BoE balancing two risks. Moving too fast could squeeze an already fragile economy. Waiting too long risks letting the energy shock harden into a lasting wage-price spiral.
Three policymakers already want a hike, and the Fed just moved the opposite way. If energy prices stay elevated, 3.75% may not be the final stop this year.
The post Why Is the BoE Holding Rates While the US Fed Hikes? appeared first on BeInCrypto.
NU7 will cut Zcash block times to 25 seconds and preserve its halving schedule, with testnet activation planned for Oct. 6.
Starknet lending protocol Nostra paused its money market on Thursday after a manipulated price oracle let one account borrow roughly $3.5 million against NSTR collateral.
Lending, borrowing, withdrawals, and liquidations remain unavailable while the team reconciles each asset. Recovery prospects remain unclear for now.
Nostra Halts Money Market in September’s Latest Oracle Exploit
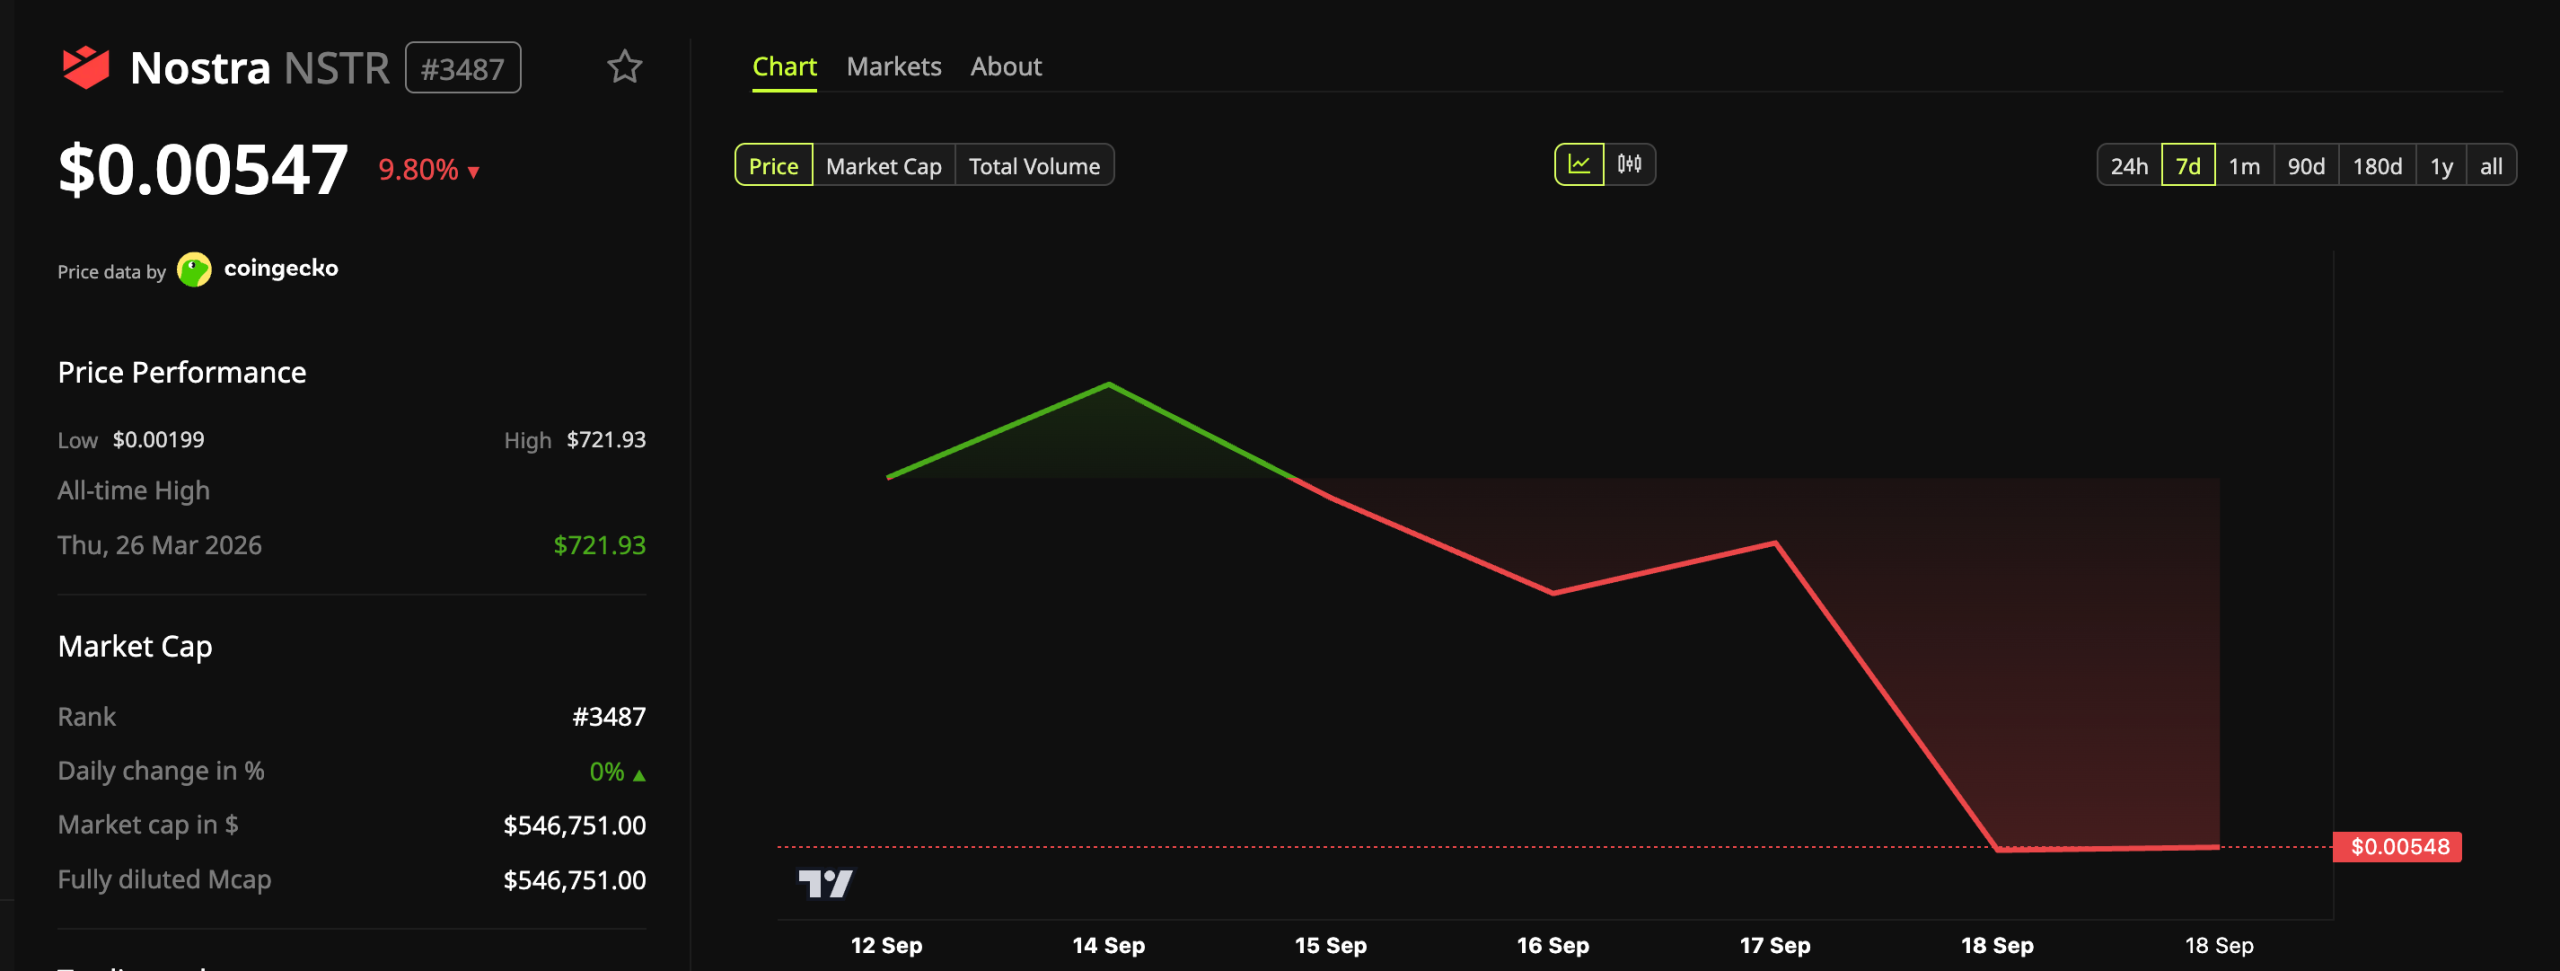
Nostra (NSTR) carries a market value of $546,751, according to BeInCrypto Markets data. A token that small needs little capital to move.
Follow us on X to get the latest news as it happens

The account pledged NSTR and drew Ethereum (ETH), Starknet (STRK), USDC, USDT, Wrapped Bitcoin (WBTC), and DAIv1. The haul exceeded the collateral token’s entire market value by roughly six times.
Security firm PeckShield reported that the account bridged $1.92 million to Ethereum. That transfer included 234.57 ETH and 1.3 million DAI.
Deposits collapsed afterward. Total value locked in the protocol fell from about $4 million on September 16 to roughly $710,632 at press time per DefiLlama.
Starknet’s Second Oracle Failure in Two Weeks
Nostra is not the only Starknet protocol hit this month. On September 4, an incorrect price from Pragma’s publishing pipeline was published across several Starknet feeds.
This triggered 47 liquidations across 42 borrower wallets on money market Vesu. Pragma reported 95% asset recovery in a September 13 update.
However, the two incidents differ in cause. Pragma’s case came from a publishing fault, while Nostra faced deliberate manipulation of a collateral price.
Meanwhile, Nostra is still counting the damage.
“We are reconciling the impact on each asset and tracing the funds. The final loss and potential recoveries are not yet known,” Nostra said.
The team also warned users about impersonators. Nostra said it will never send direct messages or ask holders to connect a wallet during recovery.
September has been costly for the sector. DefiLlama had logged more than $326 million in crypto losses this month before the Nostra incident. Most of that stems from the $320 million Liquid Network incident.
The pattern has held all year. PeckShield counted 50 hacks in August, the highest monthly tally of 2026, even as losses dropped 49.5% to $136.3 million. Nostra fits that shape of frequent, smaller thefts.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights
The post Nostra Joins a September That Has Already Cost Crypto Over $326 Million appeared first on BeInCrypto.
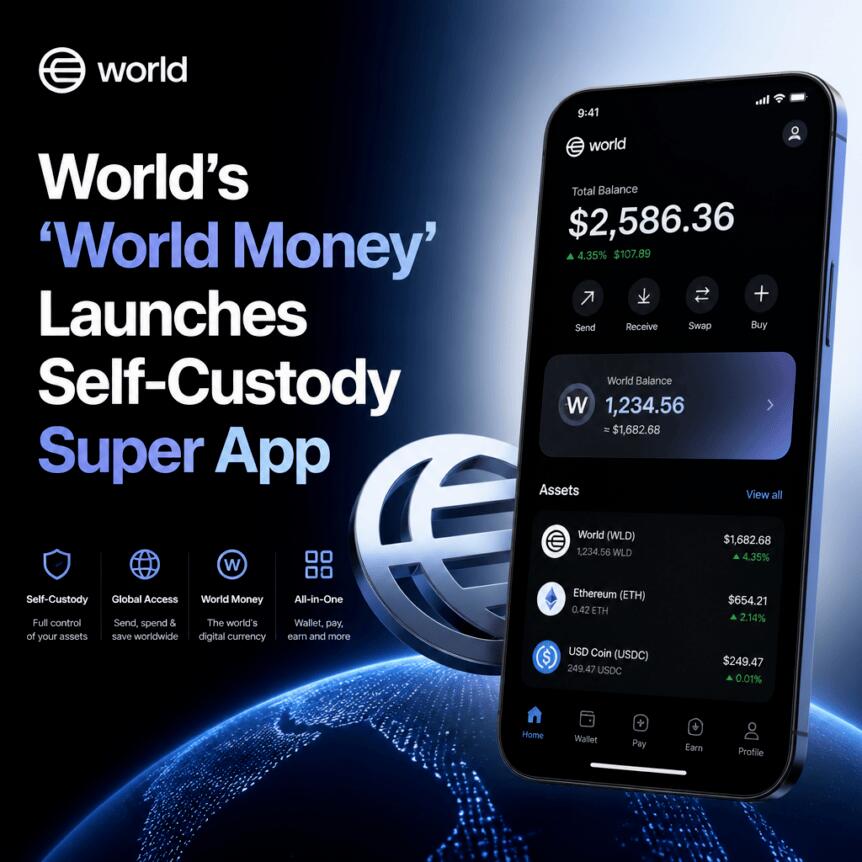
World has launched World Money, a new self-custody financial “super app” designed to bring stablecoin payments and digital-asset features into one place. The rollout began Thursday across more than 150 countries, though specific capabilities are expected to vary by region, according to World.
The new app supports sending supported digital assets—including stablecoins—to recipients using a World username. It also allows users to deposit eligible assets to earn rewards and to buy and sell digital assets through exchange integrations. World further says the experience is built around its identity layer while giving users direct control of their funds.
Key takeaways
- World Money rolls out in over 150 countries, with feature availability dependent on location.
- Users can send supported assets (including stablecoins) via World usernames, not just blockchain addresses.
- The app adds third-party “Mini Apps” such as Kalshi, Credit and Morpho.
- A partnership with Stripe enables top-ups and stablecoin purchases with Apple Pay for users in the US.
- World splits its identity and financial functions across two apps: World ID App and World Money.
What World Money includes at launch
World positions World Money as a self-custody super app that combines multiple financial functions: transfers, trading access, and rewards on certain deposits. The company says users can send supported digital assets to a recipient’s World username, with stablecoins among the assets initially covered.
In addition to peer-to-peer transfers, World Money includes a rewards component. Users can deposit eligible assets to earn rewards, a feature that continues the direction World App previously took with earning opportunities tied to blockchain assets.
For trading, World Money provides buy-and-sell functionality through exchange integrations, giving users a way to switch between supported digital assets without leaving the app environment.
“Mini Apps” and payments onboarding through Stripe
One of the most visible expansions is World Money’s support for third-party mini applications. World says users can access Mini Apps including Kalshi, Credit and Morpho. This approach mirrors the super-app idea of bundling specialized services into a single interface, while relying on external platforms for specific product functions.
World also highlighted a payments onboarding partnership. According to the company, integration with Stripe allows users to fund their accounts and buy stablecoins with Apple Pay, starting with users in the United States. That matters for adoption because fiat-to-stablecoin entry points remain one of the biggest friction points for users who do not already hold crypto.
World did not describe whether Apple Pay support will expand beyond the US as part of this initial rollout, so users outside the US should expect different funding options depending on local availability.
How World is reorganizing its product stack
The launch is also a structural change. World says that with World Money, its identity and financial services are now separated into two dedicated apps: World ID App for identity verification and credentials, and World Money for the wallet, payments and other financial features.
Existing users of World App and World ID App can reportedly use their existing accounts for World Money, which should reduce the migration burden for current customers and limit the risk of fragmenting user identities and balances across platforms.
World Money is operated by Tools for Humanity, the company co-founded by Sam Altman and Alex Blania that builds technology for the World network. Tools for Humanity’s involvement aligns with World’s broader push to connect identity to financial actions rather than treating payments as a standalone feature.
From World App to a two-app super app model
World’s move comes after more than a year of incremental expansion of World App. World App originally launched in May 2023, bringing together World ID with a crypto wallet, stablecoin transfers and token trading.
In October 2024, World introduced World App 3.0, describing it as a “super app for humans” and adding third-party Mini Apps plus a Vault feature for earning on assets. That indicates World has been testing the combination of identity, custody tooling and app-level distribution of third-party services before splitting the experience into two apps.
Later, World also experimented with traditional banking rails. In November 2025, it piloted virtual bank accounts in the US, and then expanded the idea a month later. World says those accounts can support paychecks and bank deposits that are converted into USDC, illustrating an intent to reduce the steps between payroll and stablecoin holdings.
With World Money now separated from the identity layer, the ecosystem looks to be evolving from a single “do everything” client into a clearer division: credentials and verification in one app, and financial activity in another.
Why the split and rollout matter for users
For everyday users, the most practical change is likely the user experience: sending assets through a World username, accessing third-party services through Mini Apps, and using mainstream payment rails like Apple Pay via Stripe. Those elements can make crypto interaction feel less like dealing with addresses and more like using familiar app flows—especially when the stablecoin payment layer is integrated directly into the wallet experience.
For investors and builders, the strategic question is whether World can maintain trust and usability while expanding self-custody financial features across geographies. The company’s decision to run identity and financial services through separate apps may help scale compliance, product development and onboarding workflows without forcing users to navigate unrelated functionality in a single interface.
As World Money becomes available in more countries, the next watch item is how quickly Stripe-based onboarding expands beyond the US and how feature availability differs by region. Users should also pay attention to which assets are considered eligible for rewards and how the lineup of Mini Apps evolves after launch.
CNBC’s Jim Cramer compared stock sector performance across the last three Federal Reserve rate-hike cycles, highlighting how the winners have shifted over time.
The comparison comes after the Fed raised rates in September 2026 for the first time since 2023, citing persistent inflation, a resilient labor market, and oil prices pushed higher by the Middle East conflict.
How Sectors Performed After the First Hike
Cramer, host of Mad Money, examined three stretches within the Fed’s December 2015 to December 2018 tightening cycle. In the three months after that first hike, defensive sectors led the market.
Utilities, consumer staples, and real estate ranked among the strongest performers, Cramer said. Communication services technically topped the group, though Cramer called that figure misleading.
The sector did not exist under that name until late 2018, so the result actually reflects its predecessor, telecommunications, which investors treated as a safety trade at the time.
The Cycle’s Middle and Final Stretch
Looking at the roughly one year between the Fed’s first and second hikes, the picture flipped. Energy topped the list, and materials also performed well, while healthcare, real estate, and staples ranked among the worst performers.
Financials and industrials were also among the best performers in that stretch, Cramer said, since inflation stayed tame and recession fears were minimal at the time.
Over the full three-year period, information technology became the dominant sector. Consumer discretionary and financials also outperformed, echoing a similar cyclicals and financials rally strategists are floating today, while communication services, staples, energy, and materials slid toward the bottom as the Fed grew more aggressive.
“Of course, every tightening cycle is different.”
Cramer, CNBC’s Mad Money
Cramer said the current cycle carries a twist the 2015 to 2018 period did not have. War-driven oil prices, rather than broad economic demand, are adding pressure behind the Fed’s latest rate hike.
He added that further tightening could stall if oil slides back toward $80 a barrel, easing that pressure.
Whether defensive sectors repeat their early lead from a decade ago may depend on how quickly that geopolitical shock fades.
The post Jim Cramer Ranks Winning and Losing Stock Sectors During Fed Rate Hikes appeared first on BeInCrypto.
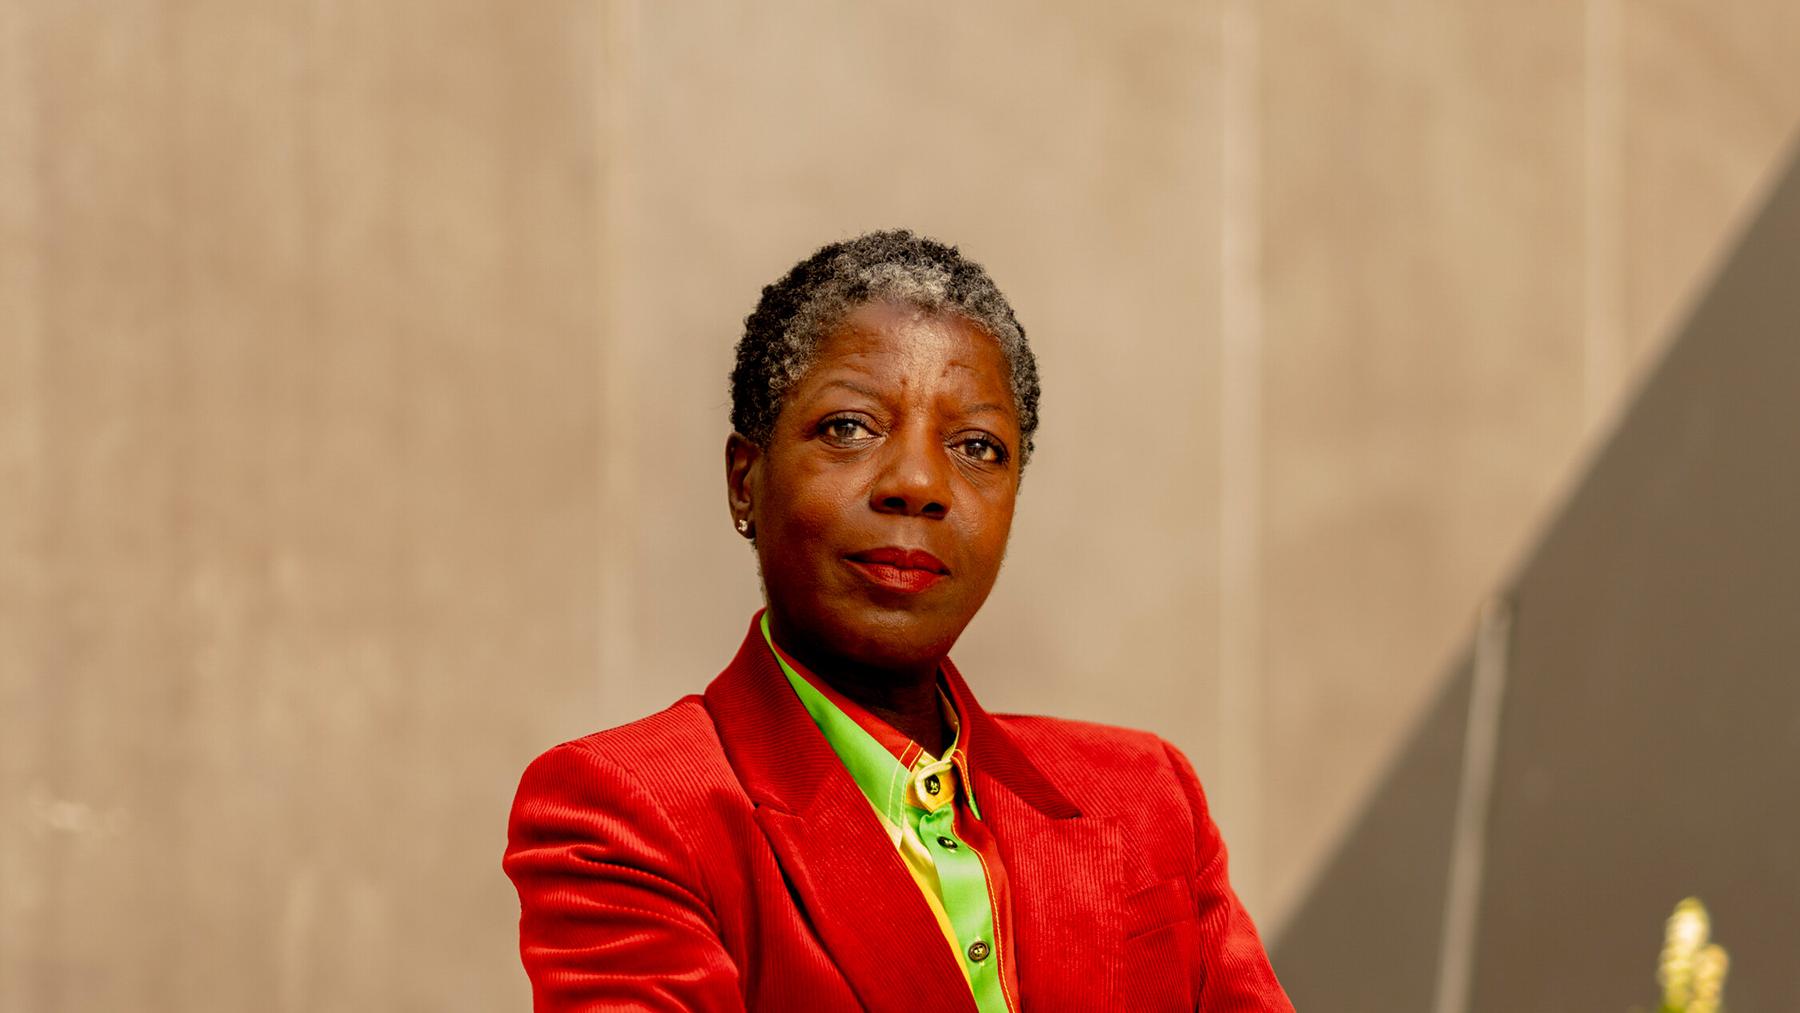
Thelma Golden has arguably done more than anyone else to promote Black artists in the U.S. For over two decades, the director and chief curator of the Studio Museum in Harlem, founded in 1968, has forged the institution into a leading incubator and showcase for artists of African descent. And in November 2025, she made a permanent mark on New York City’s cultural landscape when the Studio Museum opened its $160 million new building on 125th Street. The 82,000-sq.-ft. facility, which looks like a charcoal-colored Jenga tower, doubled space for exhibitions and created classrooms, artist studios, and meeting spaces for community organizations. Golden started her career in the 1980s as a curator at the Whitney Museum of American Art, where she organized powerful exhibitions about Black masculinity and conceptual art that divided critics, but made her name as a fearless curator. Now, she’s focused on ensuring a long-term future for the institution she’s shaped. Alongside raising money for the new building and attracting patrons including Beyoncé, Golden created a $52 million endowment, ensuring the Studio Museum’s 9,000-work collection will be cared for well into the future.
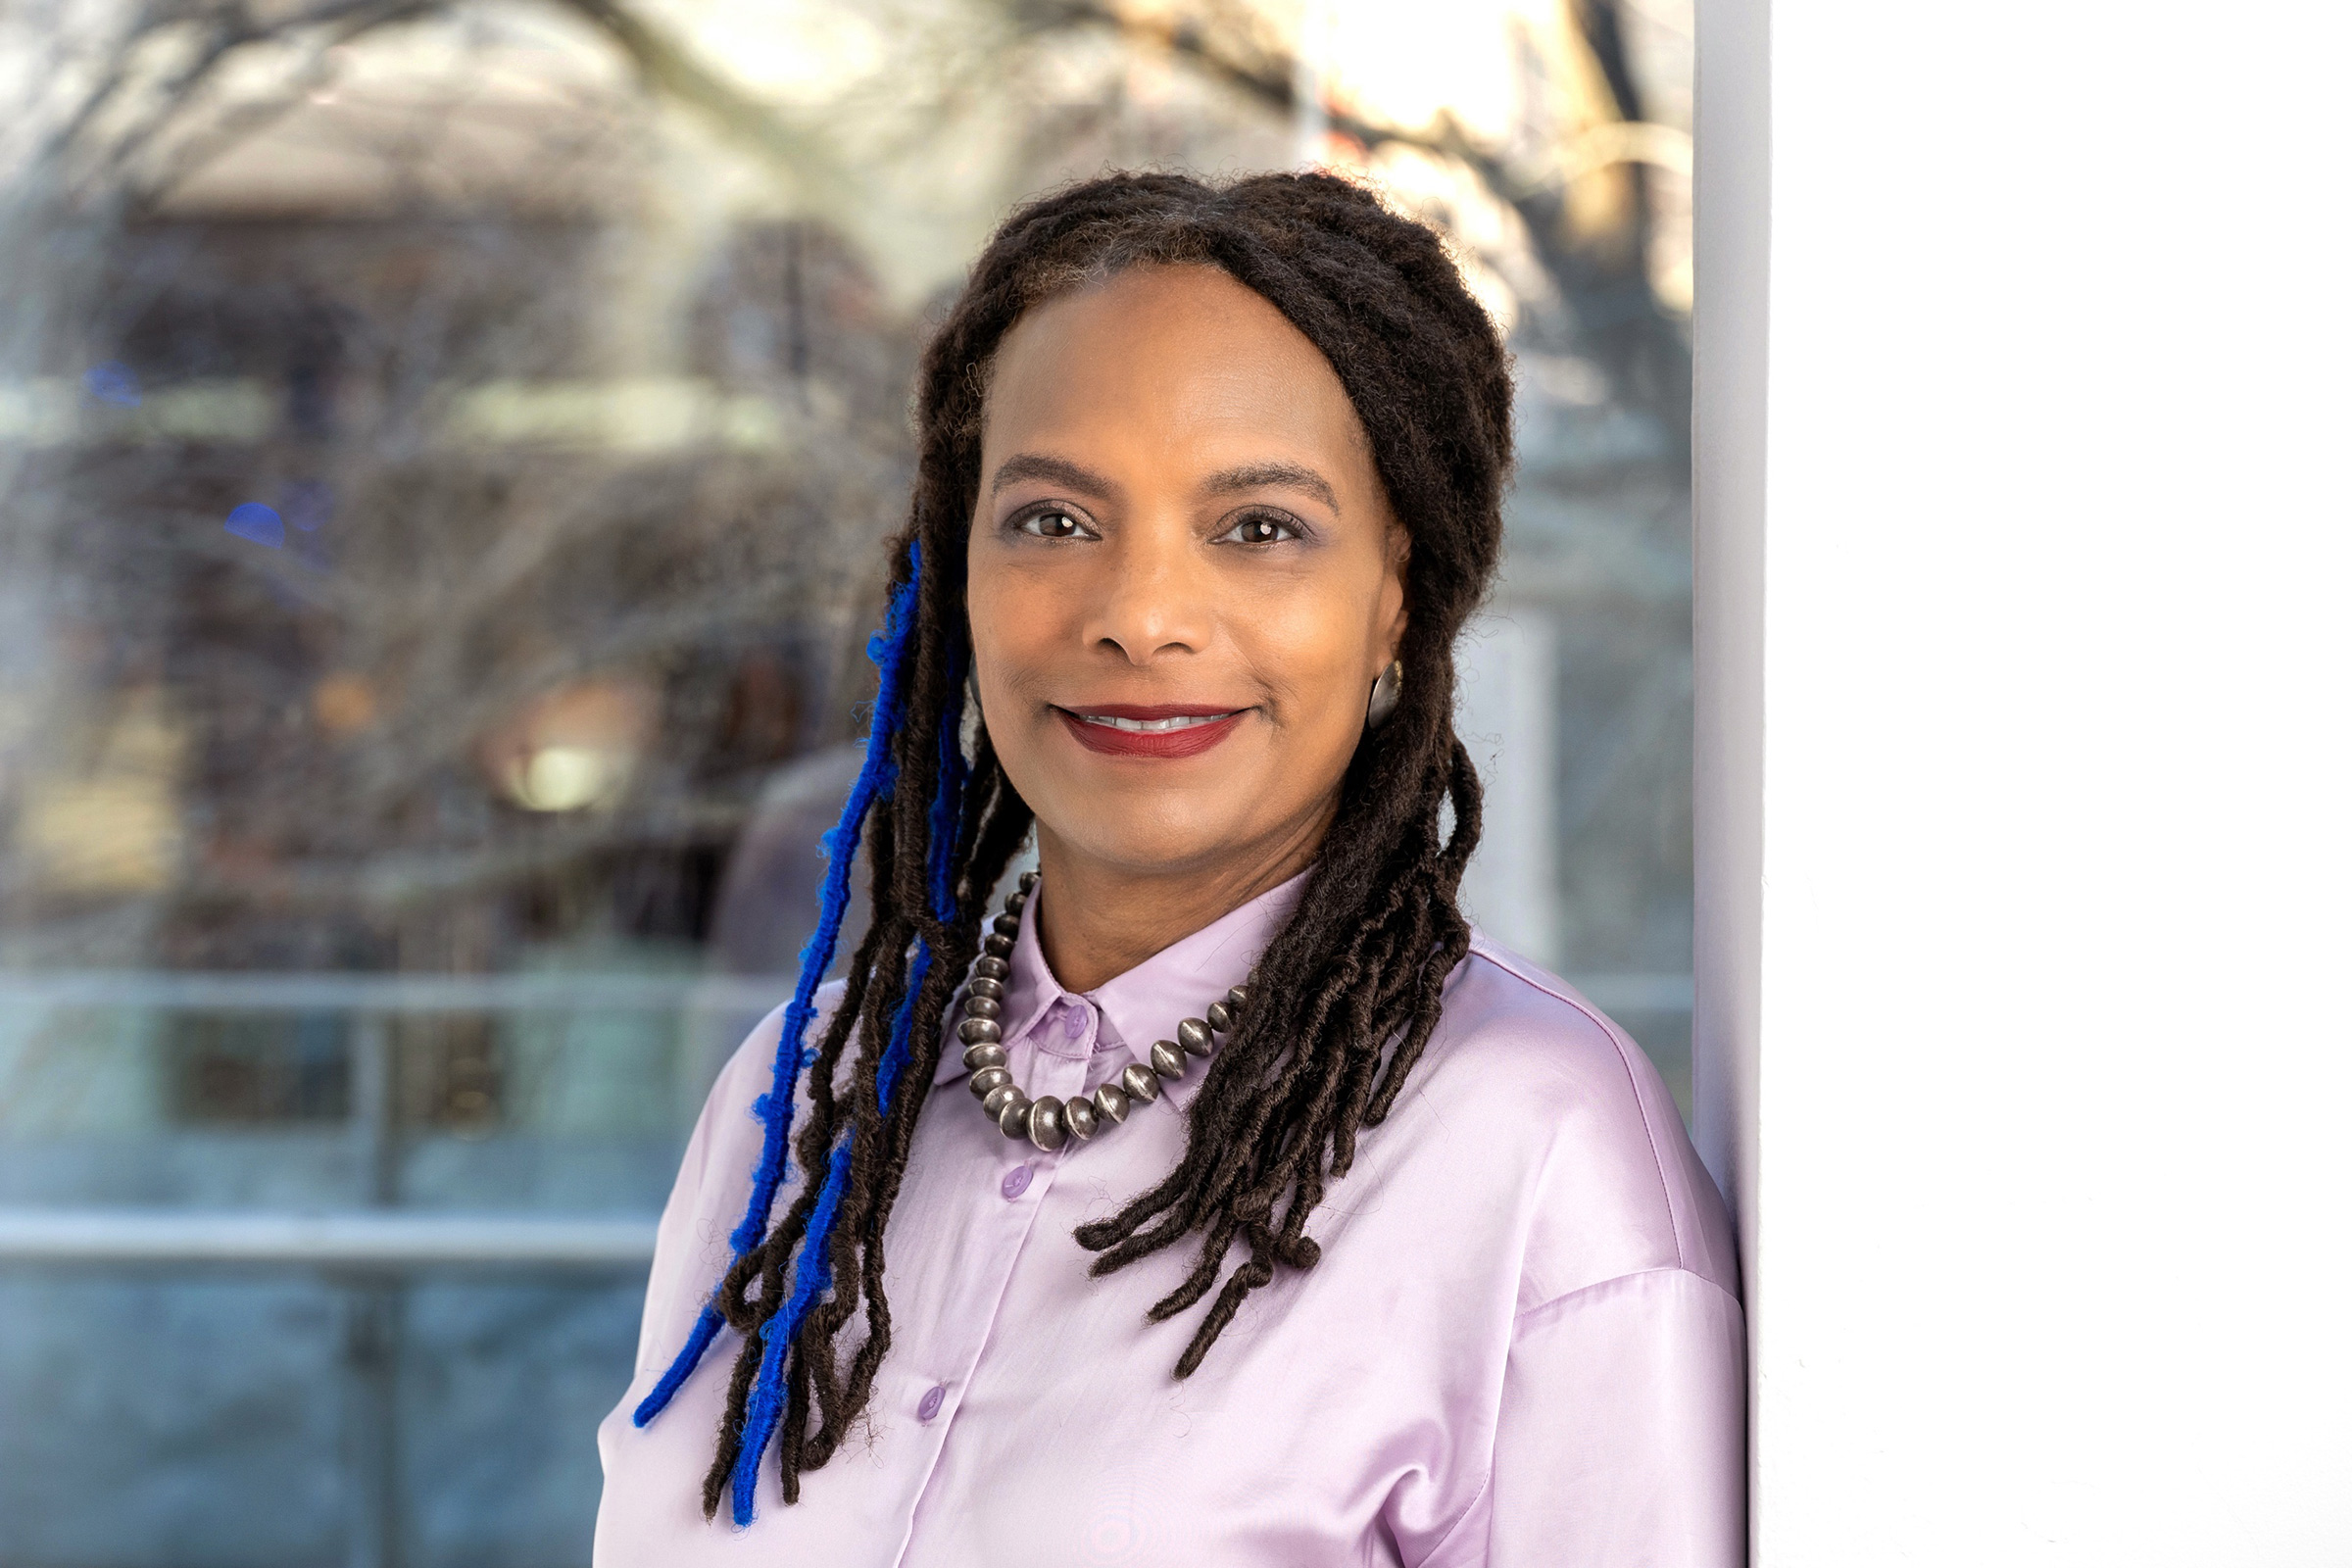
Lindsay Clancy holdout juror breaks silence: Why he voted GUILTY… and how the others tried to sway him
Exclusive-ECB’s Vujcic cools oil-fuelled bets on rate hikes

Jennifer Rubio



-

 Fashion7 days ago
Weekend Open Thread – Corporette.com
-

 Tech5 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Business7 days ago
10 Most-Streamed Songs On Spotify In 2026 So Far, Led By Ella Langley’s Dominant Run On The Charts This Year
-

 Crypto World7 days ago
XAG/USD: Silver’s Short-Term Rally Meets Its Moment of Truth
-

 Crypto World7 days ago
Diesel Tops $6 a Gallon for the First Time as 28 States Set Records
-

 Crypto World3 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-

 Crypto World4 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-

 Crypto World1 day ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 News Videos7 days ago
Facing Financial Fears
-

 Crypto World6 days ago
Can AI Build a Startup in 72 Hours? Elon Musk's Team Will Livestream the Test
-
 Entertainment6 days ago
News Specials, Movies, Shows, More
-

 Business5 days ago
Rivals Sam Altman and Elon Musk Rally Behind Dario Amodei’s Call for a Slowdown in AI Development
-
 NewsBeat4 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World5 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-

 Crypto World6 days ago
Robinhood Chain Never Stopped But its Blobs Did Stop Reaching Ethereum For 14 Minutes
-

 Crypto World2 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-
 Entertainment6 days ago
New Horror Movie Officially Earns a Rare Stephen King Recommendation
-

 Business6 days ago
Marvell: Most Potent Setup Of The AI Factory Decade
-

 Crypto World4 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-

 Crypto World3 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
You must be logged in to post a comment Login