
Crypto World
Kyle Samani: SOL Could Overtake ETH as Usage Lags, He Says

Multicoin Capital co-founder Kyle Samani believes the next phase of crypto company building could tilt further toward Solana as developers look for networks that are simpler to operate while still offering robust functionality. In a discussion with Cointelegraph, Samani argued that Solana is likely to become the “default” smart contract platform for more firms during the current market cycle, potentially eroding Ethereum’s long-held dominance in that role.
Samani’s stance is notably consistent with his track record: Multicoin accumulated an early position in Solana, and he has been one of its most persistent public advocates. His comments also come as Solana’s token has outperformed Ethereum in the recent upswing, while showing a deeper drawdown during the prior bear market—two dynamics that investors may want to reconcile when assessing the sustainability of the current momentum.
Key takeaways
- Kyle Samani predicts more crypto companies will default to building on Solana instead of Ethereum, citing operational ease and network “functionality.”
- He claims Ethereum’s value accrual is “questionable,” arguing that Ether’s largest role today is tied to stablecoins and collateralized borrowing.
- Recent market performance shows Ether up about 30% over the past month versus Solana’s roughly 34% gain, according to TradingView.
- On a longer window, TradingView data cited by Cointelegraph shows SOL down 59% over the past year versus ETH down 45%.
- DefiLlama fee data referenced in the report shows Solana collecting more monthly fees than Ethereum in the period cited, reinforcing Samani’s operational and usage argument.
Why Samani thinks Solana could replace Ethereum’s “default” status
Speaking on Cointelegraph’s “Trade Secrets,” Samani said he expects Solana to “flip” Ether during the current market cycle. His core argument is not only about technical capability, but about how easy it is for companies to consolidate their operations on a single chain.
“They’ll all switch their default over to Solana because it’s the most functional network for all of them and it’s just easier to consolidate their operations around Solana to the extent that they can.”
From an investor’s perspective, the implication is straightforward: if more new products, deployments, and enterprise-minded launches choose Solana by default, demand for Solana’s ecosystem resources could strengthen relative to Ethereum. At the same time, Samani’s framing suggests he sees network choice as something that compounds—once companies standardize on one environment, switching costs rise for the next set of funding rounds, partnerships, and product iterations.
Samani’s forecast also carries a valuation challenge. The report notes that reaching Ether’s current market cap (about $293 billion at the time of the cited discussion) would require SOL’s market capitalization to multiply roughly fivefold, with SOL referenced at about a $58 billion market cap in the underlying comparison.
Criticism of Ethereum’s value accrual
Alongside his Solana preference, Samani was sharply skeptical about Ethereum’s ability to capture and sustain economic value for token holders. He described Ethereum as a large smart contract network whose asset value accrual is, in his view, unclear or limited.
“It’s a $400 billion to $300 billion asset that has questionable value accrual, if any, and it’s not growing at all.”
Samani argued that investors may not find Ether’s valuation compelling relative to other opportunities available at what he characterized as “more reasonable prices.” He also suggested that Ethereum’s continued relevance stems primarily from stablecoins and from stablecoins or capital strategies that use Ether as collateral—rather than from broader organic adoption that, in his view, would drive stronger accrual mechanics.
Notably, this critique is paired in the report with his prediction that companies will pivot toward Solana. If investors accept the premise that “usage” and “operational convenience” are what drive product ecosystems more than abstract platform status, then Ethereum’s role could shift from default builder environment to a more specialized settlement and liquidity base—at least for certain categories of new deployments.
What the recent market and fees data suggest
The Cointelegraph report ties Samani’s thesis to performance and on-chain activity indicators. In the recent market upturn, both ETH and SOL moved higher in similar percentage ranges, but Solana’s outperformance was slightly stronger in the cited window: Ether rose about 30% over the past month, while Solana rose about 34%, according to TradingView.
The comparison becomes more nuanced when the discussion shifts from short-term rallies to the prior downturn. TradingView data cited by Cointelegraph shows SOL fell about 59% over the past year, versus ETH’s roughly 45% decline. In other words, Solana has had both larger relative losses and slightly stronger recent gains—an asymmetry that can matter to traders assessing risk, drawdown tolerance, and the likelihood of “mean reversion” versus a new regime.
Fees provide another lens. The report states that, while SOL represents less than one-fifth of Ethereum’s market capitalization, Solana has surpassed Ethereum in weekly and monthly fees. According to fee rankings from DefiLlama referenced in the article, Solana generated $23 million in fees over the past 30 days and ranked fourth in monthly fees, while Ethereum generated $12.6 million and ranked in sixth place.
For builders and investors, fee generation can be interpreted in multiple ways. It may signal more demand for blockspace and on-chain execution, but it can also reflect changes in application mix or volatility-driven usage. Still, within Samani’s broader argument—“functionality” and operational consolidation—higher fee throughput is presented as evidence that Solana can deliver measurable economic activity even while competing against Ethereum’s scale.
Samani’s shifting stance—and his continued bet on Solana
The article also revisits Samani’s relationship with the crypto industry over the past few years. In February, he said he was stepping down as managing partner of Multicoin Capital after 10 years in the industry, describing it as a “bittersweet moment.” The report notes that around that time he appeared dispirited about crypto’s broader direction and briefly deleted an X post in which he said he no longer believed in the web3 vision, arguing that crypto had become less interesting than many enthusiasts expected.
But the same report indicates that his outlook did not translate into an exit. In September, Samani joined the US board of directors at crypto trading platform Backpack, suggesting he remained engaged with the operational side of the industry rather than stepping away completely.
On Solana specifically, the report frames the bet as long-running. Samani says he entered crypto through Ethereum in 2016 and later became dissatisfied with how Ethereum developers addressed scaling issues, according to Cointelegraph’s references in the piece. He encountered Solana soon after founding Multicoin in May 2017, and Multicoin went on to lead some of Solana’s earliest investment rounds in 2018.
Multicoin’s prominence is also contextualized in the report: it cites that the firm reported managing $5.9 billion in assets in May 2025, positioning it among the most prominent crypto investment firms. The underlying message is that Samani’s current prediction isn’t coming from a standing-on-the-sidelines viewpoint—it’s tied to a sustained investment and belief structure.
The report further adds biographical context: before co-founding Multicoin, Samani co-founded Pristine, a healthcare IT company that built software for Google Glass used by surgeons.
What to watch next
Samani’s prediction hinges on whether more companies treat Solana as the default operational environment—and whether Ethereum’s value accrual narrative continues to weaken for token holders. Investors should watch for concrete signs of ecosystem consolidation on Solana, alongside continued fee and usage comparisons, to see whether this “default switch” thesis holds beyond commentary.
Strategy, the publicly traded Bitcoin treasury company led by Michael Saylor, resumed its Bitcoin purchases after a two-week pause, according to a Form 8-K filed with the U.S. Securities and Exchange Commission on Monday. The company acquired 950 BTC for $75.7 million during the week from Monday through Sunday, at an average price of $79,670 per coin.
The new buy lifts Strategy’s total Bitcoin holdings to 846,000 BTC, accumulated for roughly $63.8 billion at an average cost of $75,416 per Bitcoin (including fees and expenses). At the time of publication, Bitcoin was trading at $84,925, implying an unrealized gain of about $8.05 billion on the treasury’s position, based on figures referenced in the filing. The update also arrives as Strategy continues to balance Bitcoin accumulation with ongoing preferred stock management and a large cash position.
Key takeaways
- Strategy bought 950 BTC for $75.7 million at an average price of $79,670 per coin after a two-week buying pause.
- Total holdings now stand at 846,000 BTC, with Strategy reporting an average cost basis of $75,416 per Bitcoin.
- Bitcoin’s referenced market price of $84,925 implies an unrealized gain of about $8.05 billion on the treasury.
- Strategy continued repurchasing STRC preferred stock, spending $174 million on about 1.77 million shares.
- Strategy’s “USD Cash” fell nearly 20% to $1.05 billion week over week, reflecting dividend and debt-related payments.
Bitcoin buys restart after a brief pause
Strategy’s latest SEC filing describes a resumption of its steady accumulation approach. Between Monday and Sunday, the company purchased 950 Bitcoin for $75.7 million, averaging $79,670 per BTC. The filing also notes the company’s broader position—846,000 BTC in total—indicating the restart did not meaningfully change the scale of its treasury strategy, but it does show a deliberate pause followed by renewed buying activity.
For investors, the practical significance is less about the week’s number of coins and more about consistency: Strategy is still deploying capital into Bitcoin while maintaining liquidity and continuing to manage its preferred securities. That balance can matter in periods where capital allocation becomes more constrained or where financing needs shift.
Strategy’s treasury position and the gains at market price
With Bitcoin trading at $84,925 at the time of publication, Strategy’s holdings are positioned for substantial paper gains relative to its reported average cost of $75,416. The article’s referenced math suggests an unrealized gain of approximately $8.05 billion on the full 846,000 BTC balance.
While unrealized gains are not cash, they can influence market perception of treasury strength. In addition, the company’s ability to keep buying without disrupting preferred-stock obligations depends on its cash management framework—particularly the split between “USD Cash” and “USD Reserve,” which Strategy reports separately.
Preferred stock repurchases continue alongside Bitcoin accumulation
Strategy also used capital to reduce its exposure to preferred-stock obligations through ongoing buybacks of STRC. The company repurchased approximately 1.77 million shares for $174 million during the same week, and STRC was up slightly in pre-market trading on Monday, according to the information cited alongside Yahoo Finance data.
Strategy stated it still had $875.1 million available under its preferred-stock repurchase program and $1 billion remaining under its MSTR share repurchase program. That matters because it shows the company still has authorization headroom—meaning buybacks can continue even after deploying $174 million in the most recent repurchase window.
The filing period also included at-the-market offering programs, and Strategy reported no sales under those plans between Sept. 14 and Sept. 20. In other words, during that window, the company did not appear to raise funds through its at-the-market channels, relying instead on existing treasury resources for purchases and repurchases.
Cash reserves decline as dividends and interest payments land
In a sign of how treasury priorities are being sequenced, Strategy’s cash balances moved down. Its “USD Cash” balance fell nearly 20% to $1.05 billion from $1.30 billion a week earlier, when the company reported its prior cash figures. Separately, “USD Reserve” declined to $5.04 billion from $5.10 billion.
The filing attributed the change in part to cash used for preferred-stock dividends and interest on outstanding debt—amounting to $57.4 million. Strategy’s “USD Cash” is described as serving broader treasury purposes, including funding Bitcoin purchases and capital management, while “USD Reserve” is intended primarily to support preferred-stock dividends and debt interest.
For readers tracking these companies, the cash split is often as important as the Bitcoin buy totals. If “USD Cash” keeps compressing while buyback and dividend needs continue, investors may begin to focus more on whether additional financing is required or whether the company tightens other deployments. Conversely, if the “USD Reserve” remains stable while operational outflows are contained, it can suggest the preferred obligations are covered without forcing abrupt changes to accumulation pacing.
Rival treasury holder Strive also adds Bitcoin
Strategy’s update landed alongside another corporate treasury move: Strive, described as the world’s fifth-largest corporate Bitcoin holder, announced additional Bitcoin purchases on Monday. According to the SEC filing referenced in the article, Strive added 1,355 BTC last week, bringing its total to 26,355 BTC, and its shares rose in pre-market trading.
Taken together, the two updates reinforce that large-cap Bitcoin treasury operators are continuing to pursue accumulation and capital management in parallel—using equity markets and repurchase programs to structure shareholder returns while still building Bitcoin exposure through direct purchases.
Moving forward, the key question for Strategy is whether the renewed weekly Bitcoin buys continue at a similar pace while “USD Cash” remains under pressure from dividends, interest, and repurchases. Investors may want to watch the next SEC disclosures for how quickly cash balances stabilize and whether the company changes the cadence of Bitcoin acquisitions or preferred-stock buybacks.
A French family was tied up for hours by attackers after their crypto. Police have not said how the attackers chose the house, and that gap is where the industry’s data problem lives.
At around 4 a.m. on September 20, four hooded men forced their way into a family home in northern France. They bound the parents and two children with black tape and forced the father to hand over his access codes and move 40,000 euros.
The father is a salaried IT worker in the crypto industry. Prosecutors have not said yet how the attackers identified him.
A separate incident in the same month showed how easily that kind of information gets out. On August 13, hardware wallet maker Trezor told 13,689 customers that a breach at one of its shipping providers had exposed sensitive order data. The number grew to over 80,000.
Nothing links the two cases, and nothing needs to. Together, they describe the same exposure from both ends: a database that pairs a home address with proof of crypto ownership, and what happens when someone acts on that pairing.
BeInCrypto spoke with experts from Hacken and Zama to uncover what a provider owes its customers when a supplier leaks their identity, which data the industry should stop keeping, and how a client could tell that a custodian will fail them under coercion.
What “No Keys Compromised” Leaves Out
When Trezor announced the breach in August, it made a point of what had not happened. Its own systems were not compromised, it said, and its devices were secure.
Those assurances addressed the risk that hardware wallets exist to prevent: theft of funds.
However, Hacken’s Head of GRC and Security Operations, Dmytro Yasmanovych, explained that the absence of a stolen private key does not mean customers are out of danger.
“Someone who knows your name, home address, and that you own a hardware wallet has information they can use to target you. You can replace a compromised key in minutes. You cannot do the same with your home address.”
He argues that this is why the information held by delivery companies and other suppliers deserves as much attention as the wallet itself. If a database links a crypto holder to their home, the consequences can reach their family, too, Yasmanovych added.
“So a provider can prevent anyone from accessing your funds and still leave you exposed in a much more personal way. The question is whether its security measures protect the customer, not just the wallet.”
The French Numbers Behind the Warning
France shows what that looks like. Interior Minister Laurent Nuñez said in late June that authorities had recorded more than 70 crypto-related violent incidents since January.
Chainalysis, which counted publicly reported cases, logged 30 in France through mid-2026, compared with 19 for the whole of 2025.
The firm calls a data breach the likeliest cause. It points to a 2024 case in which a French tax official allegedly stole dossiers on high-net-worth crypto holders, including addresses and phone numbers, and sold them to criminal intermediaries.
The family exposure Yasmanovych describes is visible in the same data. In France, more than 40% of incidents targeted a relative rather than the holder. Overall, home invasions made up 37% of documented attacks by mid-2026, up from 26% in 2023.
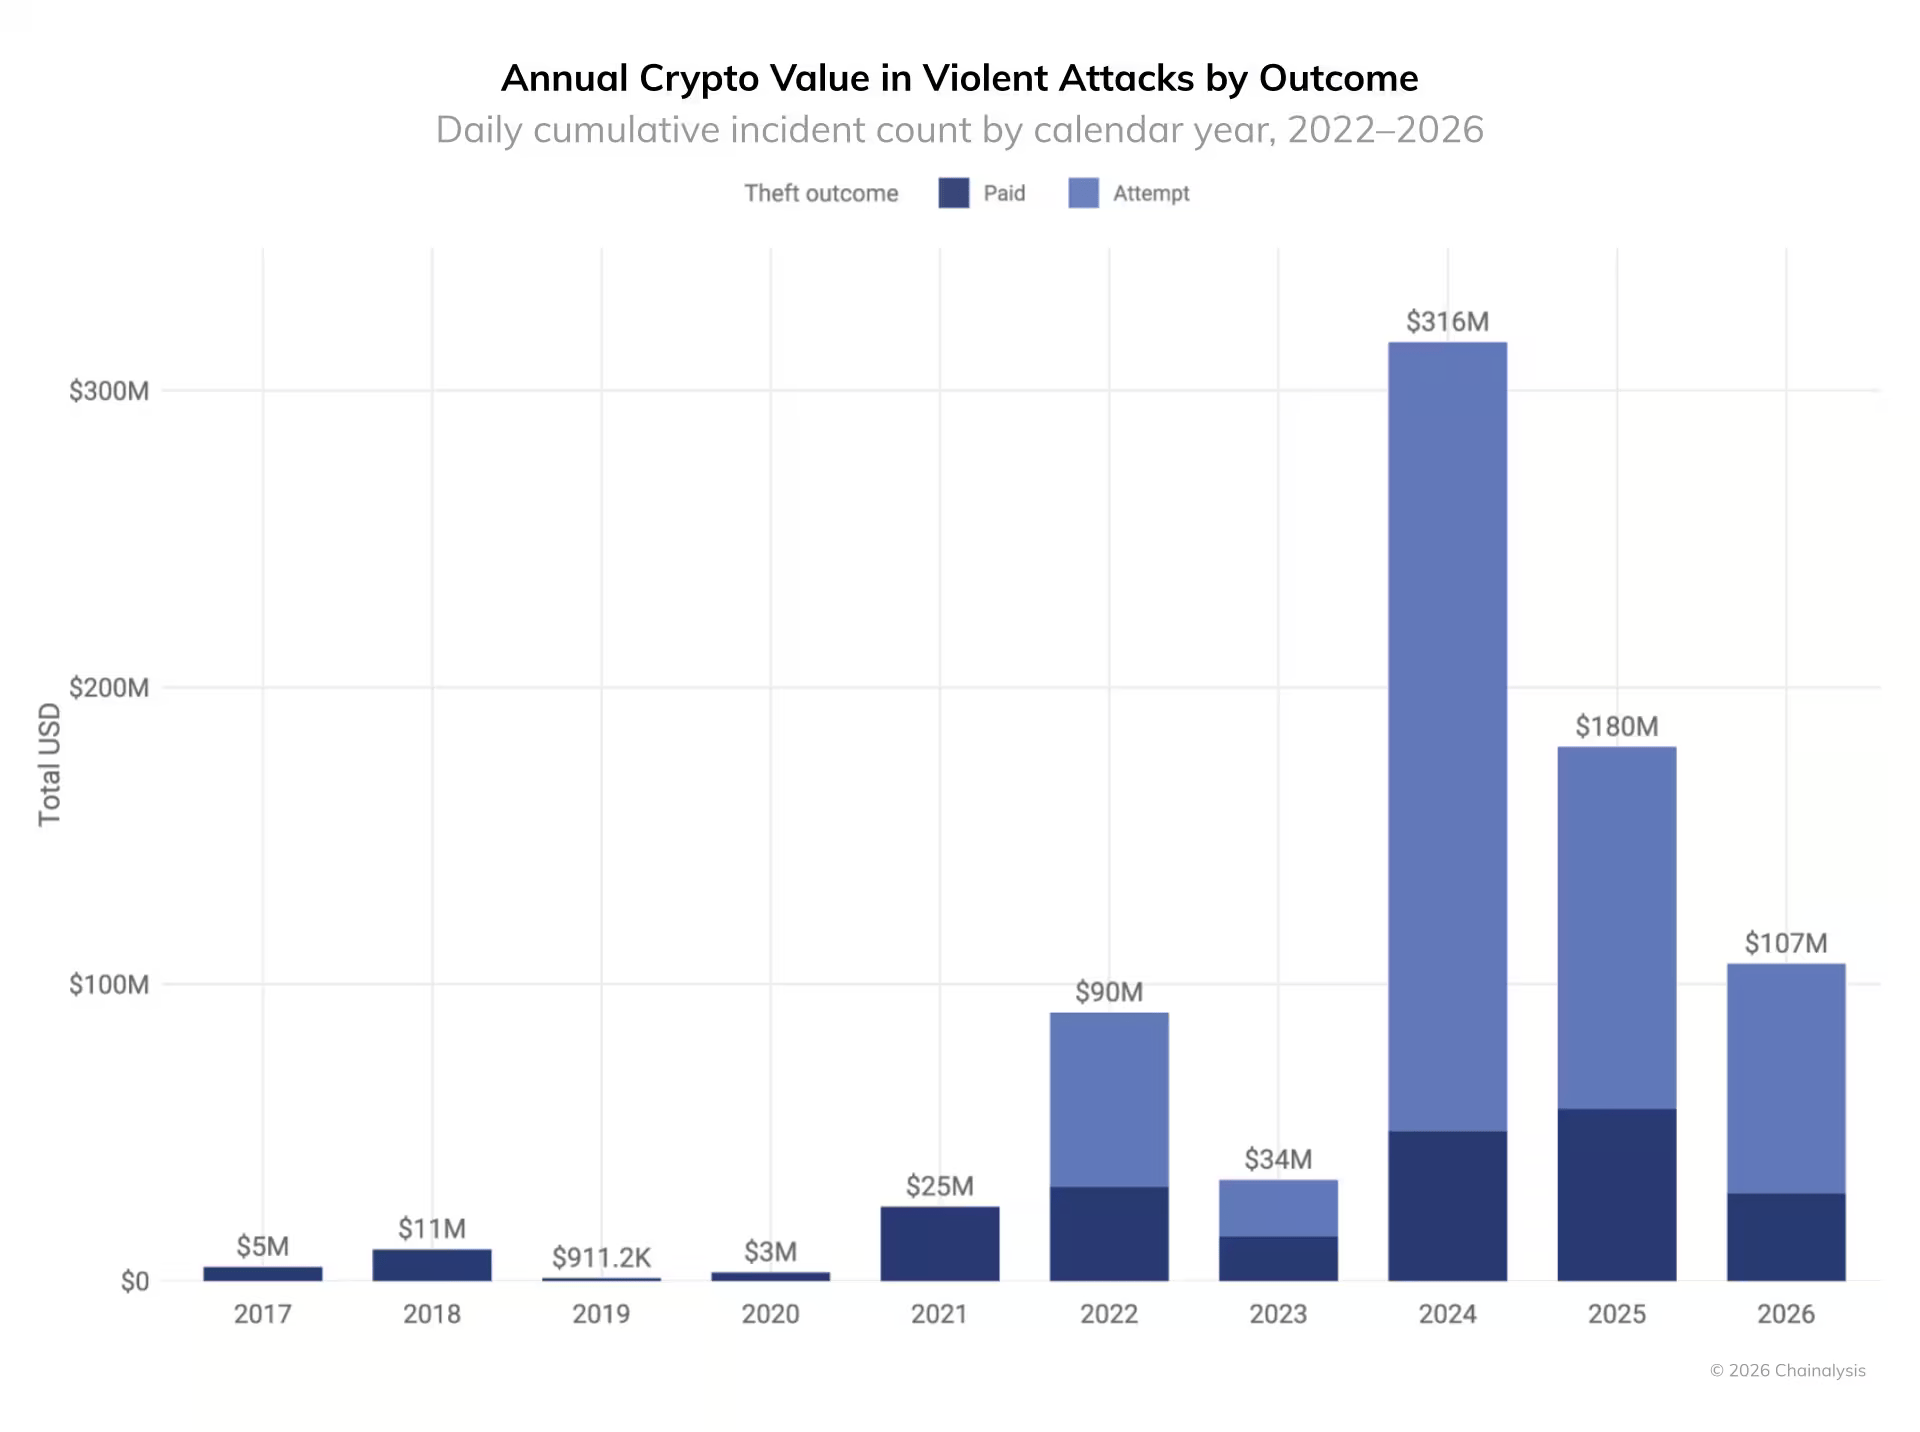
Chainalysis estimated that violent attacks on holders worldwide took more than $30 million in the first half of the year. This counts only attacks where the holder gave up funds.
The report puts total exposure at $107 million, including ransom demands, blocked transfers, and recovered funds, while noting that even that figure covers only reported cases.

The Data Behind the Target
Those attacks need a target, and the target may come from a record somebody kept. That makes data retention another security issue for the crypto industry.
Companies may need customer information for a specific transaction or service. However, keeping it indefinitely can create a separate risk if that information is later exposed. So which piece of customer information should the industry stop collecting, or delete sooner than it does?
Yasmanovych names the phone number. He explained that a company might need one to arrange a delivery, but that does not explain why it should remain in a customer database for years.
Thus, if the database is breached, the number can become useful for phishing, voice scams, or SIM-swap attempts.
“I would remove the link between an order and a physical delivery address once the delivery is complete and there is no longer a business reason to keep it. The company can retain what it needs for tax and warranty purposes without keeping a complete record of where every order was delivered.”
He outlined another problem: deleting data often relies on someone saying it has been done.
“In one case, a company had a ninety-day retention rule and written confirmation from its fulfilment partner that older records had been removed. Years of data was still sitting in their systems. That is why I would want evidence of deletion, not just a retention policy. If nobody checks whether the rule was followed, the rule offers little protection.”
The same responsibility extends to what happens after customer information is exposed. According to Yasmanovych, in addition to a warning email, the provider needs to explain exactly what information was exposed.
“A leaked city is one thing. A name, home address, and proof of crypto ownership create a different level of risk…Someone whose address was leaked may need help arranging future deliveries without sharing it again… There should be a direct person or team to contact when the situation requires more than a standard FAQ.”
He mentioned that the provider also needs to address what allowed the exposure to happen. If the supplier keeps data beyond the agreed retention period, customers should be told how that will be prevented and how deletion will be checked in the future.
“A warning email is the starting point. People need to know what happened, what they can do now, and whether the company has actually fixed the process that failed.”
Trezor’s response to its own breach can be measured against that list. It emailed affected customers individually, specifying whether their exposure was full or partial, and warned about phishing and, in September, physical security risks.
It also promised an Anonymous Delivery option using locker pickup, unbranded packaging, and automatic deletion of shipping identifiers.
Can Privacy Technology Close the Gap?
The problem is not limited to the data companies store off-chain. As more financial activity moves onto public blockchains, the transactions themselves can create another layer of exposure.
Zama CEO and Co-Founder Dr. Rand Hindi said the Trezor incident highlights an off-chain data retention problem.
He argued that as institutional capital moves onchain at scale, onchain confidentiality stops being a feature and becomes the condition for participation. Hindi cited a BCG estimate that digital real-world assets could reach roughly 16% of global investable assets by 2035.
He said regulated institutions cannot operate on a public ledger where every position and counterparty relationship is visible. The executive pointed to fully homomorphic encryption (FHE) as one way to address this without sacrificing compliance.
“FHE allows computation directly on encrypted data – a transfer executes, an AML threshold is checked, eligibility is verified, all on ciphertext – with no validator or block explorer ever seeing a balance or other sensitive data. When a regulator requires access, a permissioned threshold of key holders (compliance team) authorises decryption enforced at the protocol layer, not through a policy.”
Privacy technology can also limit how much information companies must disclose without making verification impossible.
Yasmanovych said zero-knowledge proofs can allow an exchange to demonstrate that it holds enough assets to cover customer balances without publishing every customer’s balance.
The exchange can therefore share evidence of its overall position without putting individual account information on display. The expert added that this does not mean the information becomes inaccessible.
Depending on how the system is designed, an authorised investigator may still be able to examine the evidence and underlying records through an appropriate audit or legal process.
He added that selective disclosure works on a similar principle when sharing identity information. A service might need to confirm that someone meets a particular requirement without receiving their entire identity document or customer profile.
“Neither approach solves the problem of personal data held outside the blockchain. Transaction amounts, timing, and wallet connections may remain visible, while identity documents and home addresses continue to sit in exchange, delivery, and payment databases.”
Yasmanovych mentioned that the gap is fairly straightforward. A company can improve privacy around the transaction itself while leaving the information needed to deliver and support that transaction exposed elsewhere.
When the Credentials Are Real, and the Customer Is Not Free
The distinction between transaction privacy and personal safety becomes even more important when a customer is forced to authorise a transfer. A custody provider may have secure infrastructure and strong access controls.
But those safeguards face a different test when a customer is coerced into handing over their assets.
Yasmanovych said a technical audit can show that the system works as designed. It is less useful for understanding what happens when someone is forced to hand over their assets.
“I would test the withdrawal process under that kind of pressure. For example, a customer with valid credentials requests a large transfer while someone is coercing them. Can the provider recognise the situation, pause the withdrawal, or bring in someone else before the money leaves?”
His required controls are a second authorised person and a mandatory delay on large transfers, neither of which the customer can remove during the same session. Yasmanovych highlighted that the point is to give the provider a chance to intervene when a valid login does not necessarily mean the customer is acting freely.
“I would also ask to see the process in action. A policy can require a second approval, but that does not tell you whether the approval is genuinely independent or whether staff can bypass it. A live test would expose those weaknesses much faster than another clean technical audit.”
A custody system can work exactly as designed and still fail the person using it. The last step always runs through a human being, and a human being can be threatened.
Where the Responsibility Now Sits
The attacks in France show how the risks around crypto extend past a compromised wallet or a stolen private key. A customer’s name, address, phone number, and proof of ownership become valuable once they sit in the same database.
Privacy technology can limit what is exposed on-chain, but it does nothing to address information that companies and their suppliers keep elsewhere.
That widens what a provider is responsible for. It covers how assets are stored and moved, which customer data is collected, how long it stays accessible, and what happens when someone is forced to use their own credentials. Keys are part of that chain that the industry already knows how to protect.
The post Crypto Security Now Extends Past the Wallet to the Customer's Address appeared first on BeInCrypto.

In Cardano news today, the delegated representatives voted down a request to withdraw 12.29 million ADA from the community treasury to fund Input Output’s Pogun Bitcoin DeFi product. The final Koios summary recording 35.67% of DRep voting power in favor, against 64.33% opposed.
The ADA stays in the treasury, but Cardano also forfeits the revenue-sharing terms Input Output had attached to the deal, and Charles Hoskinson has since said IOG will no longer default to launching future products on Cardano.
Pogun is Input Output’s pitch for bringing Bitcoin into decentralized finance through a credit market, a yield product, and a BitVM-powered trust-minimized bridge. The rejected on-chain proposal asked for 12.29 million ADA and tied repayment to quarterly earnings before interest, taxes, depreciation, and amortization, with the calculation anchored to $2.95 million in EBITDA.

Input Output’s April 2026 overview had promised 20% of Pogun earnings back to the treasury until the initial funding was repaid, followed by a perpetual 5% return on Cardano-related products. The on-chain proposal that DReps actually voted on carried no explicit exclusivity covenant.
Cardano governance requires sign-off from both the Constitutional Committee and DReps for a treasury action to pass. The committee cleared Pogun unanimously; the body elected directly by ADA holders did not, which is what makes the split notable.
The practical result? Cardano keeps its ADA but gives up the revenue share it was offered, a difference that matters more for Cardano’s treasury sustainability.
Earn $50 and Enter $300K Prize Draw on EdgeX
Why This Counts As An ADA Governance Check?
Input Output helped build Cardano and remains a major commercial contributor, which is exactly why the vote matters. Pogun’s own framing argued Cardano was the right execution environment for Bitcoin DeFi on technical grounds, not by default. ADA holders weren’t required to accept that argument on the terms presented, and enough of them didn’t.
Hoskinson used a Sept. 18, 2026, broadcast to respond directly. He said Input Output would now choose whichever network best serves each product instead of applying automatic Cardano priority. He also added that traffic from an unfunded product could route elsewhere and that another ecosystem could receive exclusivity in exchange for support.
He still described Cardano as the strongest technical fit for Bitcoin DeFi connecting systems built on Bitcoin-like transaction outputs, a nuance that separates this from a simple exit. It reads more like a policy change forced by a governance body that IOG itself helped design, a tension also visible in how IOG has positioned Midnight-linked development outside strict Cardano exclusivity.
Trade Cardano on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
What’s Next For Cardano After This News?
Hoskinson said Pogun would still arrive within 90 days of the broadcast, or roughly by mid-December 2026, regardless of the vote’s outcome. Input Output has not disclosed which chain will host it, and the ecosystem that ends up with Pogun could capture the revenue share Cardano just walked away from.
Hoskinson also said RealFi, a separate Input Output initiative, is set to launch on Cardano in October 2026, giving Cardano holders a near-term test beyond the news.
Discover: The Best Token Presales
The post Cardano News: DReps’ Pogun Vote Opens a New Chapter for ADA appeared first on Cryptonews.
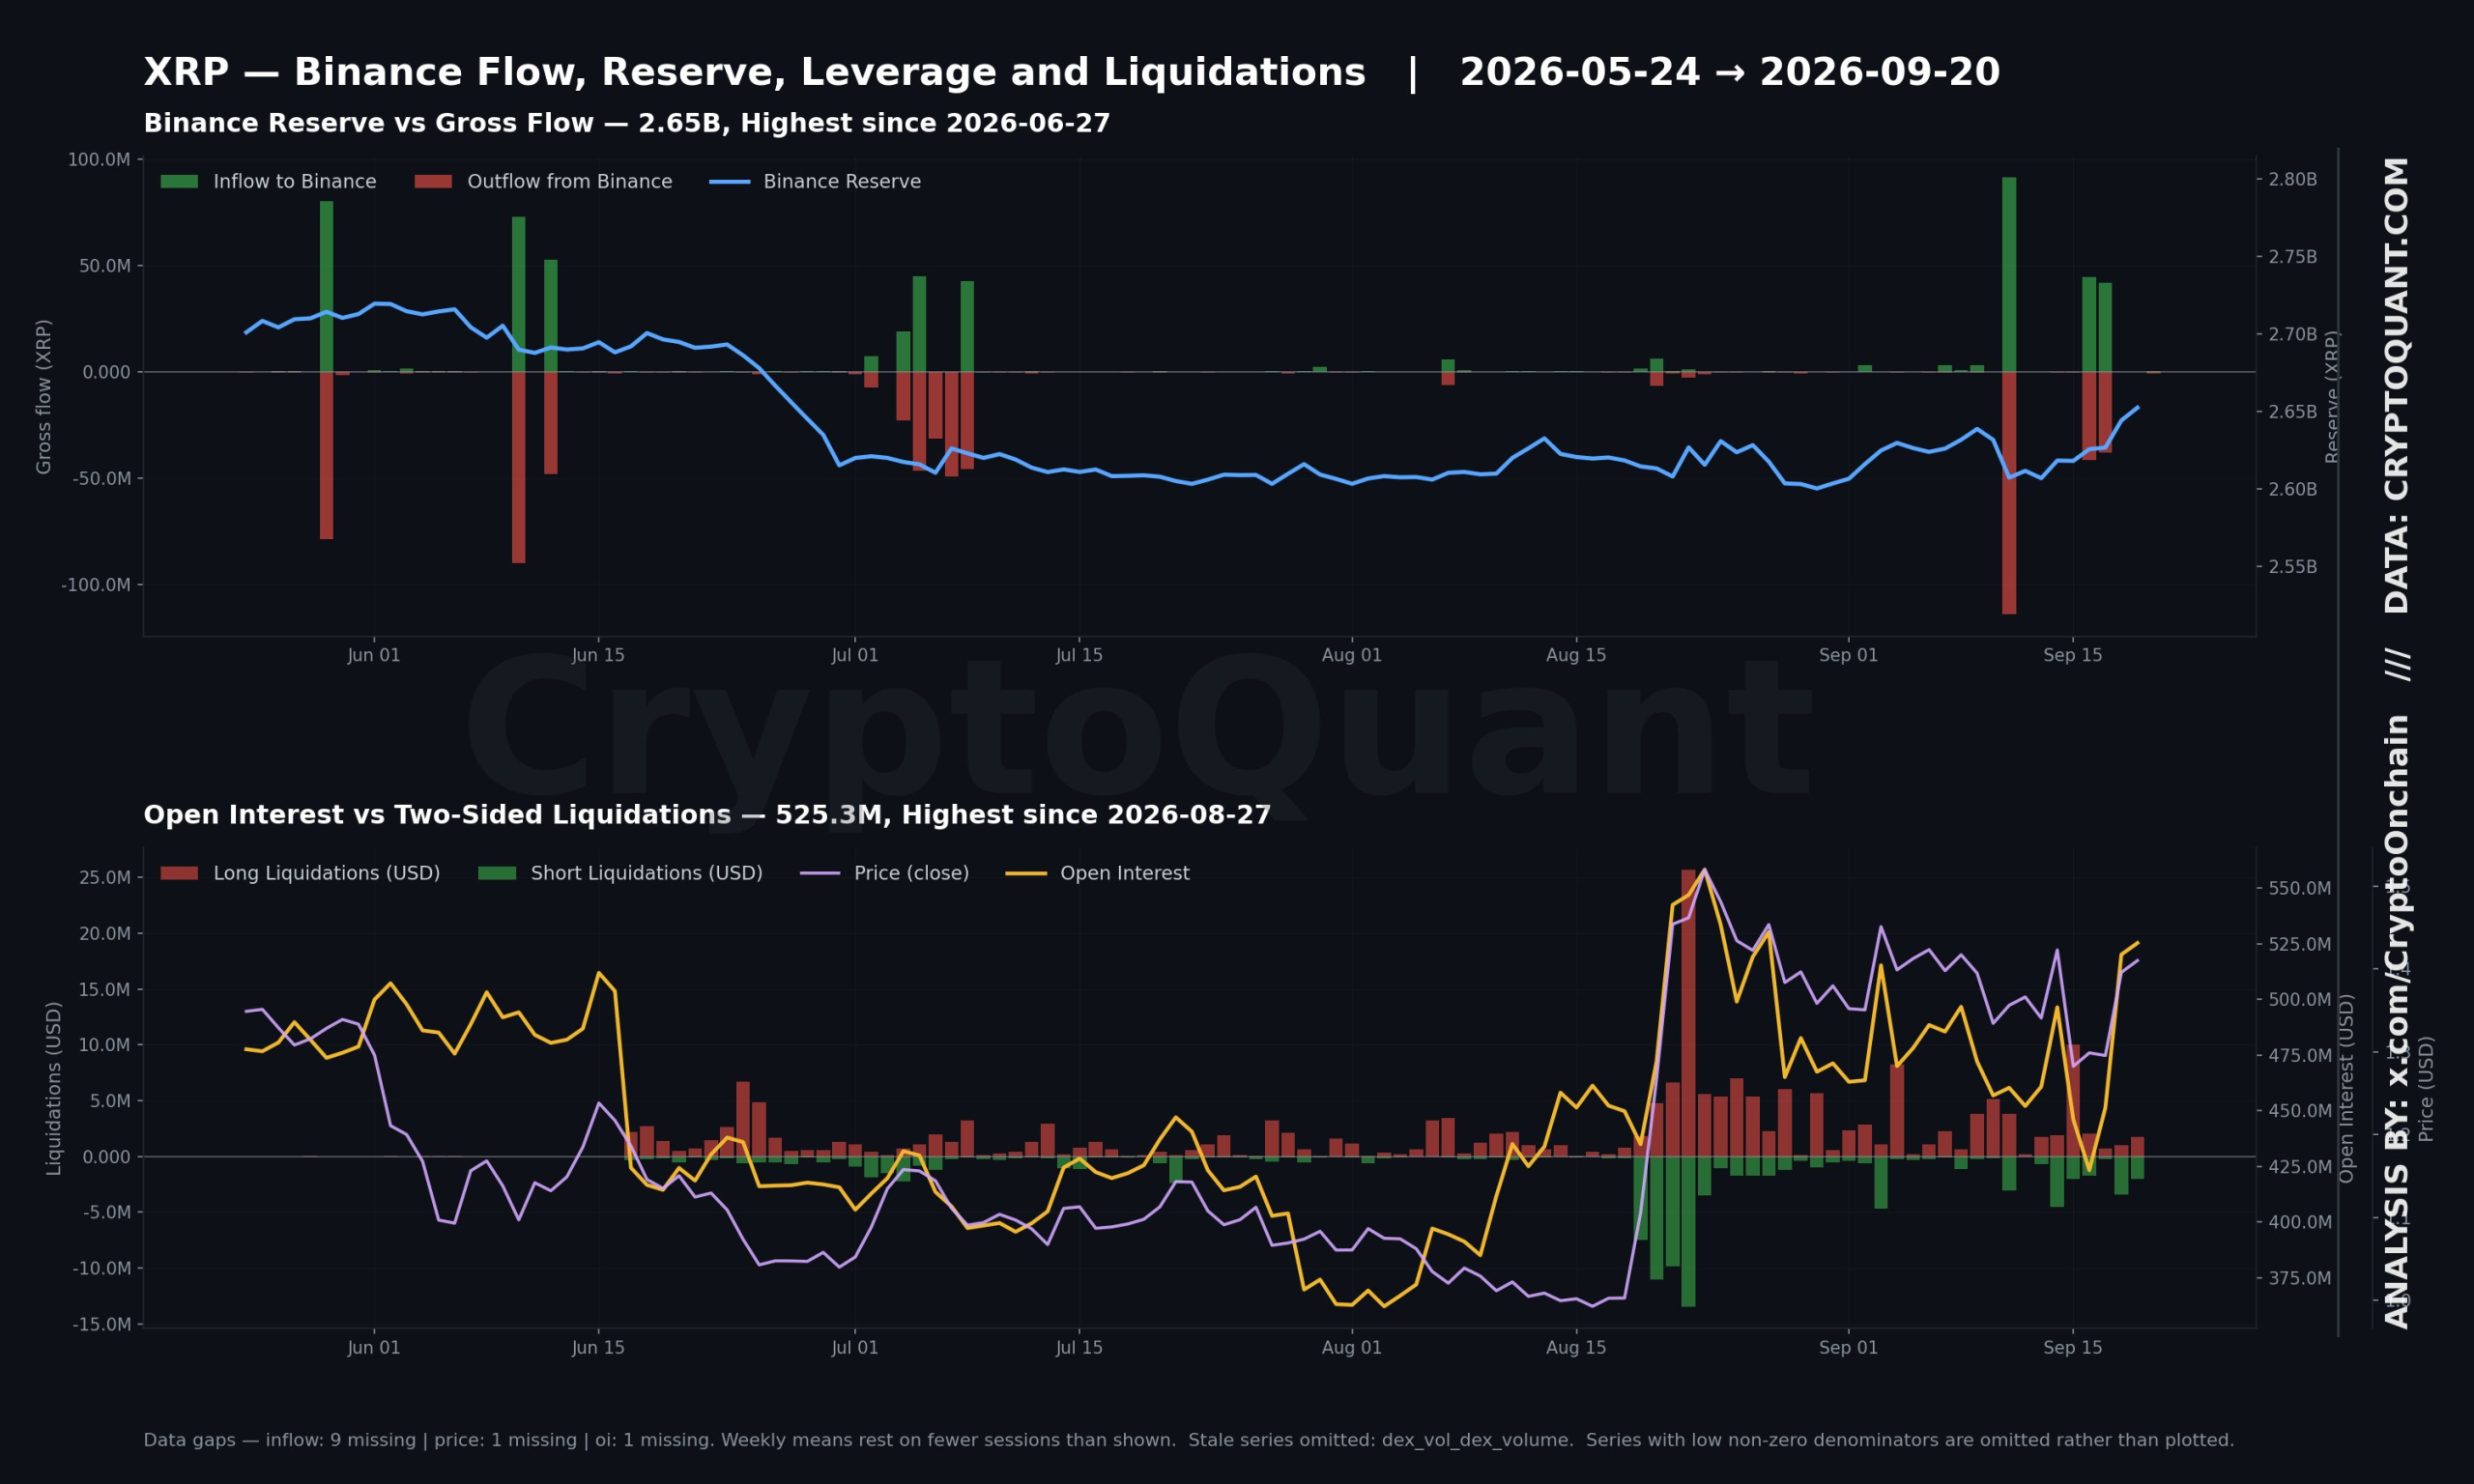
XRP climbed toward $1.50 on September 21, recovering sharply from lows near $1.27 earlier this month. That price strength arrived alongside a striking spike in exchange activity.
Average daily XRP inflows into Binance reached 21.7 million tokens, 663% above the quarterly baseline, according to on-chain data.
What Triggered This Sudden Spike in Exchange Flows
An exchange inflow refers to tokens moving from private wallets into a trading platform, typically signaling either preparation to sell or repositioning for trading purposes. The distinction matters for interpreting XRP’s current setup.
The surge concentrated in just three sessions. Binance recorded 91.2 million tokens on September 11, 44.5 million on September 16, and 41.7 million on September 17, days that overlapped with the failed CLARITY Act vote and the Federal Reserve’s first rate hike since 2023.
Despite those large deposits, Binance’s XRP reserves rose just 0.22% to roughly 2.63 billion tokens. Daily outflows averaged 11.6 million tokens over the same period. That pattern points toward elevated two-way turnover rather than sustained one-sided selling pressure.
Whale wallets added further context. Last week, large holders increased their combined XRP holdings by approximately 1.54 billion tokens, worth $2.2 billion, within 96 hours, according to Santiment-linked data shared by analyst Ali Martinez, reinforcing the accumulation narrative surrounding the token.
Follow us on X to get the latest news as it happens.

Could This Rally Reverse in the Coming Sessions?
Technical indicators point to specific levels worth watching closely. XRP recently formed a rare bullish setup, only the fourth time in its trading history that price rebounded this sharply from a key long-term support band, with the 50-week moving average near $1.51 standing out as the primary target.
Clearing that level convincingly could open a path toward the $1.80 pocket. A key volume-based support zone sits near $1.38, an area where heavy prior trading activity has repeatedly reinforced price stability.
Network metrics remain mixed, though. The network value to transactions ratio fell 32.1% and transaction counts declined, even as open interest climbed to $477 million with liquidations occurring on both sides. Rising leverage suggests potential for expanded volatility rather than a confirmed directional trend.

A rejection at the 50-week moving average could trigger a pullback toward that $1.38 support zone. Losing that level might expose the $1.29 to $1.30 region next, where a shorter-term moving average and recent accumulation activity converge.
Stable exchange reserves and continued whale accumulation offer some cushion against extreme downside scenarios. Still, elevated leverage means sharp moves remain possible in either direction.
Market participants continue monitoring volume, funding rates, and net exchange flows closely as the current $1.40 to $1.55 range plays out this week.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights.
The post XRP Holders Rushed 663% More Tokens Onto Binance. Almost None of It Got Sold appeared first on BeInCrypto.
The European Central Bank (ECB) plans to invest a small portion of its reserves in tokenized securities, giving the central bank direct exposure to blockchain-based financial markets.
The purchase would be settled through Pontes, the new Eurosystem platform, which allows wholesale transactions to settle in central bank money. The platform essentially bridges the ECB’s payment system to blockchain-based financial markets. The plan to invest in tokenized securities and Pontes reflects a more significant bid by central banks in the EU to adapt to the increasing use of blockchain in finance.
The ECB intends to test the technology as an investor, from buying tokenized bonds to settlement and portfolio management.
“Pontes brings the stability and trust of central bank money to the European tokenized finance ecosystem,” said Piero Cipollone, member of the ECB’s executive board. “It will give an important advantage to help it scale.”
The ECB’s initial investments would focus on euro-denominated securities issued by euro-area governments, regional authorities, agencies and European supranational institutions.
NEAR has been in a massive uptrend lately, gaining an additional 25% over the past 24 hours to briefly surpass $4.40. As of this writing, it trades at roughly $4.30 (per CoinGecko), up about 120% on a monthly basis.
Most analysts think the asset is ready to pump even more in the short term, with some anticipating a jump to a new all-time high. On the other hand, two important factors suggest a pullback may also be approaching.
How Much More?
The cryptocurrency market saw another sharp uptick today (September 21), with Bitcoin (BTC) climbing to nearly $2,500 and Ethereum (ETH) clearing $2,700. The green wave is perhaps the main catalyst for NEAR’s price ascent, but not the only one.
Recently, American President Donald Trump vowed to create a so-called “AI Force” and appoint an AI czar. Although details are still unclear, the announcement has boosted cryptocurrencies tied to Artificial Intelligence, with NEAR no exception. Prior to that, NEAR Protocol revealed on X that users trade perpetual futures by default, a feature provided by Hyperliquid.
X user Lucky said that NEAR holders deserve the latest pump since they have been waiting for such green days for a long time. For his part, Michael van de Poppe described the asset’s rise as “fantastic” and stated that he will be “very pleased” if it breaks through here.
“In the short term, I doubt it. I think that liquidity will flow towards other narratives that are going to follow NEAR in its footsteps,” he added.
The analyst expects the price to consolidate at current levels and even head south to $3 if BTC corrects. After that, though, he anticipates a fresh rally in Q4. In a previous post, van de Poppe described the digital asset “as one of the easiest ones to hold in this bull market,” saying he has been “happily accumulating” at $1.20-$1.50.
CryptoBullet was much more bullish, arguing that NEAR’s macro structure resembles “a giant double bottom.” The X user set $8 and $20 as the next targets, claiming the token could even skyrocket to a new historic peak of as high as $40.
The Bearish Factors
Earlier today, NEAR’s Relative Strength Index (RSI) spiked above 91, reaching a record high. Such levels signal that the asset has reached extreme overbought territory and could be gearing up for a move south. Later on, the RSI retraced to the current 74, which is still in the bearish zone.

- NEAR RSI, Source: CryptoWaves
The token’s recent exchange netflow also suggests that a correction could be on the way. Over the past several days, inflows have surpassed inflows, hinting that some investors have shifted from self-custody to centralized platforms, thereby increasing immediate selling pressure.

- NEAR Exchange Netflow, Source: CoinGlass
The post Near Protocol (NEAR) Soars 25% Daily: Is That the Easiest Crypto to Hold? appeared first on CryptoPotato.
Strategy has resumed Bitcoin purchases after a two week pause, spending $75.7 million on 950 BTC while deploying another $174 million to repurchase its STRC preferred stock.
Summary
- Strategy bought 950 BTC for $75.7 million after a two week pause, raising its holdings to 846,000 BTC.
- The company spent another $174 million repurchasing 1.77 million STRC preferred shares during the same week.
- Strategy made no ATM sales during the period, while its deployable USD Cash fell nearly 20% to $1.05 billion.
- Strive separately acquired 1,355 BTC, increasing its corporate Bitcoin holdings to 26,355 BTC.
According to a Form 8-K filing with the U.S. Securities and Exchange Commission on Sept. 21, Strategy acquired the Bitcoin between Sept. 14 and Sept. 20 at an average price of $79,670 per coin, including fees and expenses.
The purchase increased the company’s holdings to 846,000 BTC, acquired for a total of $63.80 billion at an average cost of $75,416 per Bitcoin.
Bitcoin was trading near $84,925 at the time of publication, putting the market value of Strategy’s holdings at roughly $71.85 billion. Based on the company’s reported acquisition cost, the position carried an unrealized gain of approximately $8.05 billion.
Strategy shares gained 7.4% to $165.20 in Monday premarket trading as Bitcoin traded above the price paid for the latest acquisition.
Strategy returns to Bitcoin buying after two week pause
The latest purchase ended two consecutive reporting periods without any new Bitcoin acquisitions.
Strategy last returned to Bitcoin buying at the end of August, when it purchased 4,603 BTC for $369.7 million at an average price of $80,318. The transaction raised its holdings from 840,447 BTC to 845,050 BTC.
Unlike the latest transaction, that purchase was financed through Strategy’s at the market common stock program. The company sold 4.53 million MSTR shares for $602.8 million in net proceeds, allocating $369.7 million to Bitcoin and $151.8 million to STRC repurchases.
Buying activity then stopped for two weeks as Strategy directed more cash toward its preferred securities.
During the first week of the pause, the company spent $176.3 million repurchasing 1.81 million STRC shares while leaving its Bitcoin holdings unchanged. Its board simultaneously doubled the Digital Credit Securities Repurchase Program from $1 billion to $2 billion.
Another $139.3 million was spent on 1.42 million STRC shares during the following reporting period, while Strategy again bought no Bitcoin and made no sales through its at the market programs. As crypto.news previously reported, the company entered that period with 845,050 BTC and $1.30 billion in deployable USD Cash.
The latest 950 BTC purchase has returned Strategy’s holdings to 846,000 BTC, the same total it reported at the end of the second quarter before Bitcoin sales during July and August reduced the balance.
STRC buybacks remain larger than Bitcoin spending
Strategy continued repurchasing STRC even as Bitcoin accumulation restarted, spending $174 million on approximately 1.77 million shares between Sept. 14 and Sept. 20.
The amount was more than twice the $75.7 million allocated to Bitcoin during the same period.
STRC, formally known as Strategy’s Variable Rate Series A Perpetual Stretch Preferred Stock, has a stated amount of $100 per share. The company has used repurchases and its dividend policy in an effort to keep the security trading close to that level.
Strategy had spent roughly $950.8 million repurchasing nearly 9.96 million STRC shares between July 20 and Sept. 13. The security had recovered toward $100 after falling near $70, reaching above $99 during intraday trading earlier this month before pulling back.
Monday’s latest repurchases pushed Strategy’s spending on STRC further above $1 billion since the current sequence of buybacks began.
The company has said purchases below STRC’s $100 stated amount allow it to retire preferred securities for less than their stated value while reducing future dividend requirements.
STRC was trading at $98.85 during Monday’s premarket session, up 0.35%.
Strategy retained $875.1 million in authorization for further preferred stock repurchases after the latest transaction. Its separate MSTR common stock repurchase program remained untouched, leaving the full $1 billion authorization available.
Strategy uses existing cash without ATM sales
Funding for the latest transactions came directly from Strategy’s cash balance, as the company made no sales through its at the market offering programs between Sept. 14 and Sept. 20.
Strategy used $75.7 million of USD Cash for the Bitcoin acquisition and another $174 million for STRC repurchases, bringing combined spending on the two transactions to $249.7 million.
The absence of ATM sales meant Strategy did not issue common or preferred shares to replenish the cash used during the reporting period.
Deployable USD Cash fell to $1.05 billion as of Sept. 20, down nearly 20% from $1.30 billion a week earlier. The balance had stood at $1.44 billion on Sept. 7 and $1.61 billion at the end of August as repeated STRC repurchases drew down the account.
Strategy maintains USD Cash separately from its USD Reserve. The cash account can be used for Bitcoin purchases, capital management and other corporate purposes, while the reserve is primarily intended to cover preferred stock dividends and interest on outstanding debt.
Its USD Reserve declined to $5.04 billion from $5.10 billion during the latest reporting period after $57.4 million was used for preferred dividends and debt interest.
Combined, Strategy held approximately $6.09 billion in USD assets at the end of Sept. 20.
Strive expands Bitcoin treasury to 26,355 BTC
Another publicly traded Bitcoin holder disclosed a purchase on Monday as Strive acquired 1,355 BTC, increasing its treasury to 26,355 BTC.
The purchase followed a series of recent additions to Strive’s balance sheet. The company had reached 25,000 BTC earlier this month after acquiring 469 BTC for approximately $36.6 million at an average price of $77,954 per coin. That transaction was funded through proceeds from its SATA preferred stock.
Strive had previously purchased 1,800 BTC for roughly $143 million in late August, taking its holdings to 23,156 BTC before subsequent acquisitions pushed the treasury higher.
Its latest filing places the company’s holdings at 26,355 BTC, keeping Strive among the largest publicly traded corporate Bitcoin holders.
ASST shares gained 6.44% to $32.03 in Monday premarket trading following the disclosure.
For two years, writing “AI” in your whitepaper was enough to raise money. That era just ended. And most crypto projects have no idea what comes next.
The Line That Changes Everything
Alice Liu, Head of Research at CoinMarketCap, said it this week:
“More capital, fewer names. The AI tag is free; the market is finally charging for it.”
Eight words that describe the end of an era.
For the past two years, “AI” was the most valuable word in crypto. Stick it in your whitepaper, your pitch deck, your Twitter bio, your token name. Capital would follow. Questions wouldn’t.
That’s over.
Capital is now flowing into a handful of AI crypto projects with real traction while hundreds of AI-labeled tokens bleed out quietly. The market stopped being naive. And most projects built on a narrative instead of a product are about to find out what that means.
How The AI Tag Became A Free Pass
Cast your mind back to 2024.
The AI hype cycle was at its peak. ChatGPT had just crossed 100 million users. Every VC was looking for AI exposure. Every founder was rebranding. The word “AI” in a pitch deck added zeros to valuations without adding anything to the product.
Crypto was the perfect vehicle. No revenue requirements. No product-market fit standards. No profitability timeline. Just a whitepaper, a token, and the right vocabulary.
So the projects came. Hundreds of them. AI-powered trading. AI-enhanced oracles. AI-driven DAOs. AI-optimized yield. AI everything.
Most of them were one of three things:
- A real crypto project that added “AI” to its marketing
- A real AI tool that added a token to its business model
- Neither, held together entirely by narrative
All three raised money. Because the tag was free. Because nobody was asking hard questions yet.
What Changed
Two things happened simultaneously that broke the spell.
First: Real AI Companies Shipped Real Products.
When you can compare a project claiming to be “AI-powered” against actual AI infrastructure that demonstrably works, the gap becomes visible. Vague claims about “machine learning optimization” don’t survive contact with projects that actually deploy AI agents, actually process data at scale, actually generate verifiable outputs.
The reference point shifted. And suddenly, most “AI crypto” projects looked like what they were: marketing exercises.
Second: The Market Got Burned Enough Times To Learn.
Token after token launched with AI narratives, pumped on the label, and collapsed when the product didn’t materialize. Not once. Not twice. Hundreds of times.
At some point, even the most speculative retail investor starts to notice the pattern. Flashy AI claims plus a token launch plus a roadmap that never delivers equals a loss.
The market learned. Not because it became sophisticated. Because it became tired.
What “The Market Is Charging For It” Actually Means
When Liu says the market is now “charging” for the AI tag, here’s what that looks like in practice:
Capital is concentrating. Projects with actual users, actual transaction volume, actual revenue are capturing the majority of new investment. The long tail of AI-labeled projects is being starved of attention and capital simultaneously.
The filter is simple and brutal: show me what your AI actually does. Show me who’s using it. Show me the numbers.
“Our AI optimizes cross-chain liquidity through proprietary machine learning algorithms” used to be enough.
Now the response is: “How many users? What volume? What’s the retention?”
That’s not a sophisticated investor question. That’s the most basic product question. And the fact that crypto projects couldn’t answer it for two years tells you everything about how low the bar was.
The Marketing Implications Nobody’s Discussing
Here’s where this gets directly relevant to everyone building or marketing in crypto:
The entire playbook for crypto marketing was built around narrative.
Create a compelling story. Build hype before launch. Get influencer coverage. Drive FOMO. Launch token. Capture early buyers. Let the price chart do the rest of the marketing.
AI made this playbook even easier. You didn’t even need a compelling original story. You just needed to connect your existing project to the AI narrative convincingly enough to ride the wave.
That playbook is broken now.
Not because narrative stopped mattering. Narrative always matters. But because narrative without substance now actively signals risk to investors who’ve been burned before.
When a sophisticated investor sees an AI narrative without a product behind it, they don’t see opportunity. They see a warning sign.
The question is: what does marketing look like when the shortcut stops working?
What Actually Works Now
The projects capturing capital in September 2026 share specific characteristics. None of them are accidental.
They Lead With Metrics, Not Claims.
Not “AI-powered cross-chain optimization.” But “2.6 billion in cumulative tokenized-stock trading volume.” Not “revolutionary AI governance.” But “140,000 active wallets, 89% month-over-month retention.”
Numbers that don’t need interpretation. Numbers that speak before the narrative does.
They Show The AI Working, Not Just Claim It Exists.
Demos. Live products. Verifiable outputs. The difference between “our AI analyzes on-chain data” and “here’s what our AI produced last Tuesday, here’s the methodology, here’s the result.”
Proof of work in the literal sense: evidence that something is actually happening.
They Build Trust Through Transparency, Not Hype Through Mystery.
The era of the vague roadmap is over for anyone serious. The projects winning now publish what they’re building, show progress against it, and acknowledge what hasn’t worked yet.
Counterintuitively, honesty about limitations builds more trust than inflated claims. Because investors have seen inflated claims fail too many times.
They Connect To Real Economic Activity.
The AI projects with genuine traction in 2026 are processing real transactions, serving real users, generating real fees. Not simulated activity, not wash trading, not manufactured metrics.
If your AI project can’t point to economic activity it enabled, the market has already priced that in.
The Harder Truth For Projects That Rode The Wave
Here’s what nobody wants to say directly:
A significant portion of the AI crypto projects that raised money in 2024-2025 will not survive 2026-2027.
Not because the market is cruel. Because they were built on a condition that no longer exists: a market willing to fund narrative without substance.
That condition existed for specific reasons at a specific moment. AI hype was genuine and new. Crypto capital was abundant. The reference points for what “real AI” looked like were unclear enough that vague claims could pass.
All three conditions have changed.
AI hype is now calibrated against actual AI capabilities, which are extraordinary and well-documented. Crypto capital is more selective. And everyone has seen enough real AI products to know what genuine capability looks like versus what marketing copy looks like.
The projects that survive will be the ones that used the narrative window to actually build something. The ones that used it only to raise money are running out of runway.
What This Means For Crypto Marketing In 2026
The shift from “AI tag as free pass” to “market charging for substance” is the most important marketing change in crypto this year.
It means the audience has changed. Not just in what they believe, but in what they need to see before they believe anything.
Old audience: “AI crypto? Interesting. What’s the token?”
New audience: “AI crypto? Show me the product. Show me the users. Show me what problem it actually solves.”
Marketing to the old audience meant creating excitement. Marketing to the new audience means building credibility.
Those are different skills. Different channels. Different timelines. Different measurements of success.
The projects and marketers who figure out how to build credibility in public, demonstrate substance consistently, and earn trust through transparency rather than hype will define the next cycle.
The ones who keep trying to run the old playbook will fund the next round of “lessons learned” articles.
The Opportunity In The Shift
There’s an upside to all of this that’s easy to miss when you’re watching tokens bleed.
A market that charges for substance rewards substance. That sounds obvious. But for the past two years, it wasn’t true.
If you’re building something real in AI crypto, the current environment is actually better for you than 2024 was. Not because there’s more capital. Because the capital that exists is more likely to find its way to projects with genuine traction rather than being absorbed by narrative-first competitors with better marketing budgets.
The noise is clearing. The signal is becoming visible.
Projects with real products, real users, and real economic activity are now easier to find and fund than they were when the AI tag made everything look the same.
That’s not a consolation prize. That’s the market working correctly, finally.
The Question For Every AI Crypto Project
Strip away your narrative. Remove the whitepaper language. Take out the roadmap claims and the influencer endorsements.
What does your AI actually do? Who is actually using it? What would stop working tomorrow if you shut it down?
If you can answer those questions with specifics, you have a real project.
If you need the narrative to make the project sound meaningful, the market already knows.
And now it’s charging for that knowledge.
What’s the most credible AI crypto project you’ve seen in 2026 – and what makes it actually credible? Drop it in the comments.
The immediate outcome of the failure to pass the law is that crypto regulations in the United States will continue to be created outside Congress. The SEC moved quickly after the vote, issuing a temporary conditional exemption that allows eligible venues to trade tokenized U.S. stocks through permissioned liquidity pools on public blockchains.
Soon after, the CFTC sent crypto rules to the White House for review. The agency submitted a new proposal; the details were not disclosed. For now, which crypto assets it contemplates, what exchanges would need to do to qualify for licenses, what restrictions would apply and how far the agency believes its authority extends, remains unclear. All the meanwhile, the “Clarity Act is dead, at least for now,” Jesse Hamilton, CoinDesk’s deputy managing editor in charge of global policy and regulation, wrote in an analysis that explains what very few appear to know: what the Clarity Act actually is.
“While the U.S. continues debating the Clarity Act, in the UAE we actually have clarity,” Irina Heaver, a Dubai-based crypto lawyer and founder of NeosLegal, said via Telegram. More than 110 regulated virtual-asset businesses operate in the country, with about 20 more holding in-principle approvals, she added.

Robinhood crypto chain had attracted $146 million in tradeable tokenized stocks, just weeks before the free-gas promotion that helped support early activity was set to expire on Sept. 29. The key question is how activity changes once wallet users begin paying transaction fees that Robinhood had covered following the chain’s July 1 launch.
An activity that appears strong while transactions are free may weaken when users must bear network costs directly. Robinhood Chain has not yet faced that test without the subsidy.
— CoFounder TA (@CoFounderta) September 20, 2026
 ROBINHOOD CHAIN IS ABOUT TO GET TESTED
The initial gas rebate period is ending later this month.
That means memecoins on the chain are about to face a very different environment.
Will activity stay strong when the free gas disappears?
September could get interesting. 
Our analyst says some network activity will likely evaporate when the free ride ends. It also identifies recovery within a few months as a bullish sign for retention rather than an effect of the subsidy alone.
Discover: The Best Crypto Presales This September
The Tokenized Crypto Stock Surge Is Real on Robinhood, but Not Yet Proven Durable
Robinhood Chain’s early figures have moved quickly against established networks. Robinhood and BNB Chain together handled about 88.2% of tokenized-stock trading on decentralized exchanges in early September, up from 2.3% in June. The shift occurred within a single quarter.

BNB Chain still holds a much larger absolute balance in tokenized stocks, at about $1 billion compared with Robinhood’s $146 million. Over the 30 days ending Sept. 18, BNB Chain experienced $181 million in tokenized-asset outflows, including assets other than stocks, while Robinhood saw $156 million in inflows.
However, if recent flows continue, Robinhood could pass BNB Chain in tokenized equities within a couple of quarters. The same report noted that Base, Coinbase’s layer 2 network, held $7.5 million in tokenized stocks.
Robinhood reported 28.4 million funded customers in the second quarter of 2026, providing a large existing customer base for new products. But a large customer base and sustained on-chain usage are different measures, and the end of the gas subsidy will offer a clearer indication of whether early activity persists.
Trade Crypto on Bybit and Get a Chance to Win Our $1,000 USDT Airdrop
A Strategic Bet, Not Yet a Major Revenue Engine
Robinhood’s cryptocurrency revenue declined 38% year over year to $100 million in the second quarter of 2026, while total net revenue was $1.31 billion, according to the company’s second-quarter results. Crypto, therefore, represented about 7.6% of quarterly revenue.
Event-contract revenue was $156 million during the same quarter. Robinhood Chain launched after the quarter ended, so its activity was not reflected in those quarterly results.
— Coin Bureau (@coinbureau) September 19, 2026
 LATEST: Robinhood Chain fees collapse 97% as $1.5 BILLION in daily volume keeps flowing
Daily on-chain fees have plunged from roughly $8 million in early September to just $230,000 by September 16, a 97% drop.
Despite the fee collapse, around $1.5 billion is still changing… pic.twitter.com/XyGfDk28J1
The chain is an Ethereum layer 2 network built with Arbitrum technology, and its transactions settle on Ethereum. Fees are paid in Ethereum’s coin. Robinhood’s stock is a way for investors to gain exposure to the network’s activity because the company can collect revenue from that activity. That potential, however, is not yet a reported revenue line.
The bullish case rests on Robinhood turning its customer base and early tokenized-asset growth into durable on-chain fee revenue. That remains an assessment rather than a reported result. What is established is that crypto revenue declined year over year in the second quarter while tokenized-stock balances on Robinhood Chain grew after its launch.
Discover: The Best Token Presales
What to Watch from Robinhood After Sept. 29?
The period immediately after the subsidy expires should provide an important signal. A sharp decline in wallet activity would be consistent with activity that was primarily supported by free transactions rather than continuing demand for tokenized assets.
Stabilization or recovery within a few months is the bullish outcome. Asset balances alone may not answer the retention question: a $146 million balance on the chain does not show whether users continue trading after they begin paying their own fees. Continued inflows and transaction activity after the subsidy ends would provide a more useful measure of whether early growth can persist.
Earn $50 and Enter $300K Prize Draw on EdgeX
The post Robinhood Crypto Chain’s $146M Tokenized-Stock Bet Faces Its First Fee Test appeared first on Cryptonews.

Farage Plays Down Latest ‘Bump In The Road’ For Reform UK
Asiad 2026 Sept 22 schedule, India medal-event timings, live streaming | Asian Games 2026

Are Book Publishers Warming Up to the AI Industry?




-

 Fashion3 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech17 hours ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World3 days ago
Circle launches Arc Studio AI agent for building onchain apps
-
 Crypto World7 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-
 NewsBeat3 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-
 Crypto World7 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-
 Crypto World6 days ago
Robinhood engineers charged over $50K crypto scheme
-

 Crypto World3 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World5 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World6 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-
 Crypto World6 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-
 Tech6 days ago
Webb’s IC 348 Mosaic Includes Two-Jupiter Dwarfs, Twin Jets, and a Nursery Still Making Worlds
-

 Crypto World3 days ago
World Money launches in 150+ countries with Stripe
-
Crypto World7 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
-

 Crypto World3 days ago
Silver prices recover quickly, hitting weekly high today
-
 Entertainment6 days ago
Big Brother Update: Melody Explodes at Drew as Illness Sweeps BB28 House
-
 NewsBeat3 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-
 Crypto World7 days ago
Kraken Adds DeFi Yield on Tokenized Stocks and ETF Assets
-

 Crypto World3 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-
 Crypto World7 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
You must be logged in to post a comment Login