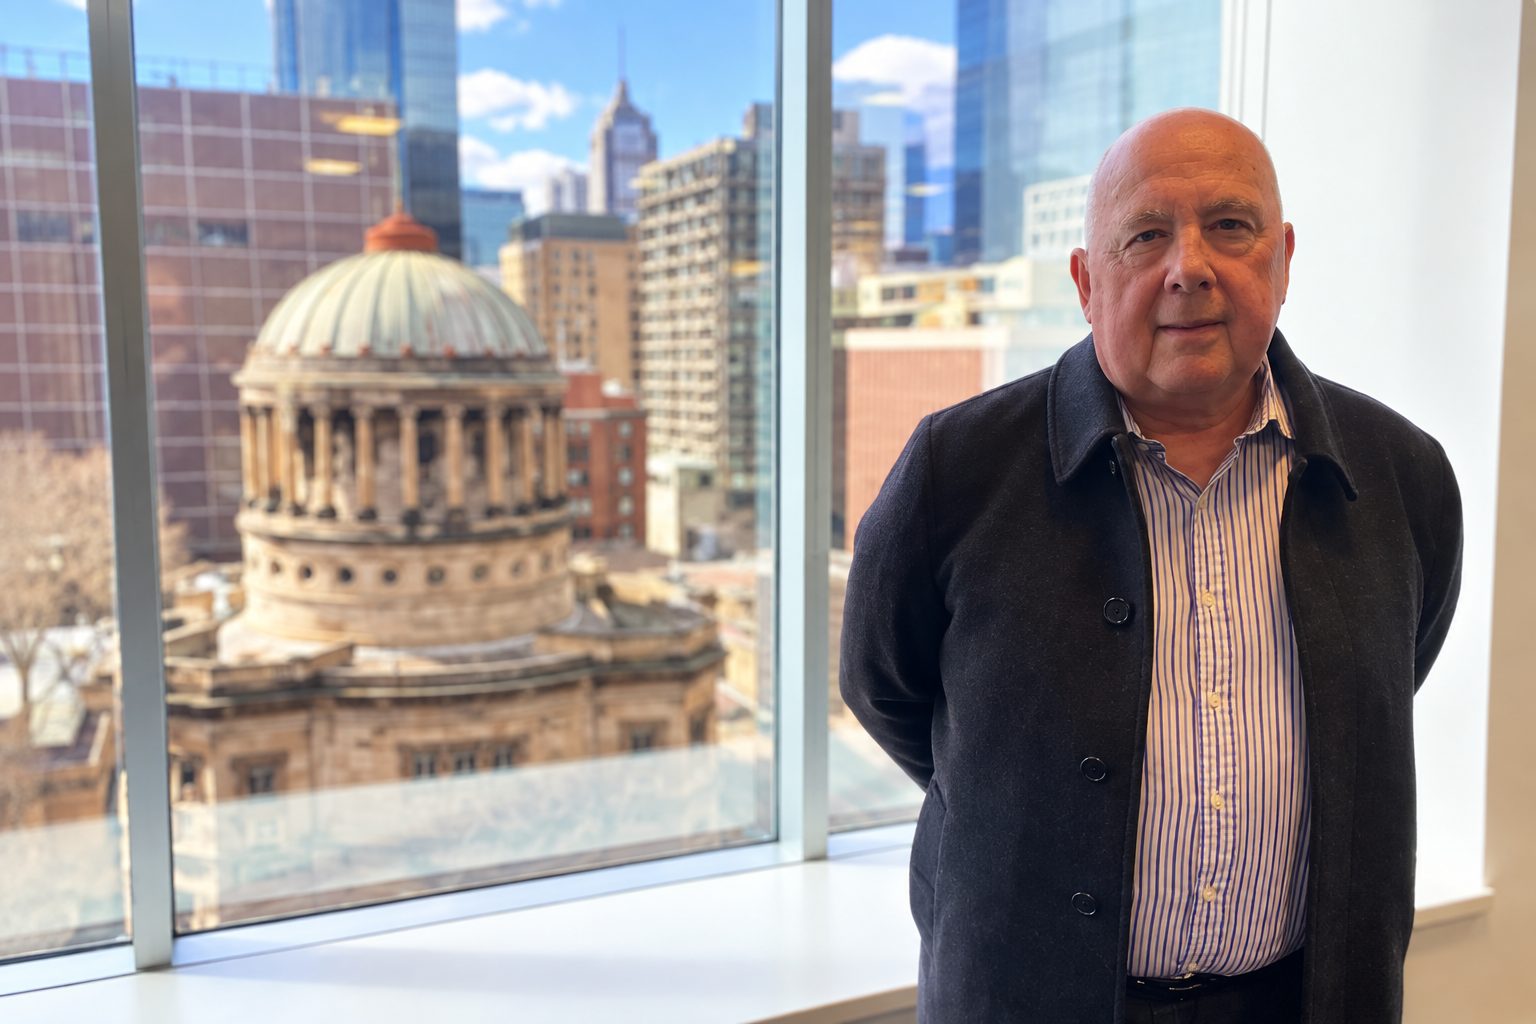
MELBOURNE — Reserve Bank of Australia Monetary Policy Board member Iain Ross has firmly dismissed widespread warnings of an impending wage-price spiral in the domestic economy, arguing that modern institutional safeguards, enterprise bargaining frameworks, and well-anchored inflation expectations make such an outcome highly unlikely.
Delivering a keynote address at the University of Melbourne’s Centre for Employment and Labour Relations Law, the former Fair Work Commission president addressed persistent speculation regarding wage-driven inflation. Pointing to historical precedent and contemporary economic data, Ross emphasized that current wage growth trajectories reflect workers recovering lost purchasing power rather than an unsustainable inflationary feedback loop that could force aggressive central bank tightening.
Historical Contrast and Structural Evolution
To contextualize current market conditions, Ross drew sharp distinctions between contemporary economic settings and the damaging wage-price dynamics observed during the severe stagflation episodes of the 1970s. During that period, global oil supply shocks intersected with centralized wage-setting mechanisms that automatically indexed pay rates across entire industrial sectors without corresponding productivity gains.
In contrast, Australia’s modern industrial relations framework relies heavily on enterprise-level bargaining and multi-year workplace agreements that staggered wage adjustments over extended periods. This structural transition prevents sudden, economy-wide wage shocks from spilling into consumer price indices, effectively severing the automatic transmission mechanism that characterized past inflationary cycles.
“The overall thesis is that there is no evidence of the emergence of a wage-price spiral in the present circumstances and recent data suggest such an outcome is unlikely,” Ross stated during his address. “Historical experience shows that an acceleration in nominal wages does not, by itself, indicate that a persistent wage-price spiral is taking hold.”
Anchored Inflation Expectations and Labour Market Realities
Central to Ross’s assessment is the role of long-term inflation expectations among households, businesses, and institutional investors. International empirical research across 31 advanced economies indicates that nominal wage acceleration rarely evolves into self-perpetuating price spirals unless medium-term inflation expectations become unanchored from central bank targets.
In Australia, underlying wage growth metrics have remained broadly aligned with the RBA’s target inflation band of 2 to 3 percent when combined with trend productivity growth. Furthermore, employer survey data and workplace bargaining outcomes confirm that business managers continue to treat current cost pressures as temporary adjustments rather than permanent structural increases requiring continuous price hikes.
Financial markets and institutional economists have monitored the RBA’s public commentary closely as the central bank navigates complex monetary policy choices. Ross noted that treating normal wage adjustments as immediate inflation threats risks over-tightening policy, which could needlessly dampen economic activity and suppress broader employment opportunities without delivering meaningful supply-side benefits.
Enterprise Bargaining as an Economic Shock Absorber
The address highlighted the institutional design of Australia’s Fair Work framework as a vital shock absorber for the national economy. By anchoring major workplace agreements to multi-year cycles, enterprise bargaining builds predictability into corporate cost structures while ensuring that pay increases are negotiated alongside operational efficiency measures.
Moreover, the presence of safety net mechanisms administered through annual wage reviews provides targeted relief for low-paid workers without triggering generalized spillover effects across higher-income pay brackets. This balanced architecture allows real wages to stabilize gradually following external supply shocks without creating sustained inflationary momentum.
In analyzing international data from recent years, Ross noted that temporary spikes in nominal wage growth across developed markets have routinely stabilized alongside broader disinflation trends. As global supply chain bottlenecks ease and energy markets normalize, wage dynamics naturally adjust back toward long-term historical averages without intervention-driven systemic shocks.
Structural Drivers Mitigating Wage-Price Spiral Risks
- Enterprise bargaining systems that stagger wage negotiations over multi-year periods, preventing economy-wide wage acceleration following single inflation spikes.
- Medium-term inflation expectations that remain firmly anchored within the Reserve Bank of Australia’s target range of 2 to 3 percent.
- Modern workplace frameworks that decouple broad-based safety net increases from executive and high-income enterprise negotiations, containing generalized price spillovers.
Policy Implications for Monetary Trajectory
The detailed perspective provided by Ross provides valuable insight into the deliberations occurring within the RBA’s Monetary Policy Board as it evaluates future interest rate settings. By downplaying wage-price spiral concerns, the senior policymaker signaled that the board remains focused on broader macroeconomic fundamentals, including aggregate demand, household consumption, and global economic volatility.
As economic indicators unfold over the coming quarters, financial analysts expect the central bank to maintain a data-dependent stance that balances inflation control with labour market preservation. The reassurances regarding workplace bargaining structures suggest that central bank leadership views current wage settings as a manageable, stabilizing component of Australia’s broader economic recovery.













































You must be logged in to post a comment Login