
Crypto World
SEC Tokenized Stocks Rules: Key Winners and Losers Defined

The U.S. Securities and Exchange Commission’s new “Innovation Exemption” is carving out a narrow regulatory lane for onchain trading of certain tokenized stocks—and early market reaction suggested traders believe the path is at least partially workable. After the announcement last week, Bitcoin and Ether both rallied by more than 10% while tokens tied to onchain trading infrastructure also jumped, including Uniswap’s UNI rising by over 30% in the days that followed, according to price data tracked by CoinGecko.
Still, the SEC’s relief is not a blanket approval for every form of tokenized equity. The exemption focuses on a particular structure that preserves core shareholder rights and channels trading through permissioned liquidity mechanisms. For many existing products, that means they may need redesign before they can fit through the SEC’s rules.
Key takeaways
- The SEC’s Innovation Exemption provides temporary relief for trading tokenized National Market System (NMS) stocks without registering as a securities exchange, but only under specific conditions.
- Compliance hinges on token design: qualifying tokenized shares must deliver holders the same rights and privileges as the underlying securities.
- Synthetic exposure models are singled out as non-compliant with this exemption, limiting how broadly the market can reuse existing tokenized equity products.
- Permissioned AMM liquidity pools appear central to the SEC’s framework, aligning naturally with trading infrastructure that can enforce compliance onchain.
- Even where infrastructure exists, issuers and venues still face real work to adapt products to the exemption’s exact requirements and the SEC’s broader regulatory posture.
A temporary exemption with a narrow route
The SEC’s September 17 order, published as a press release, grants certain venues temporary relief from having to register as exchanges when they trade tokenized NMS stocks on permissioned AMM liquidity pools. The exemption also contemplates third parties tokenizing stocks, but only if they meet the conditions laid out by the regulator.
A central requirement is that tokenized stockholders must receive the same “rights and privileges” as they would for the underlying shares. That includes protections tied to voting and dividends, along with the way corporate actions flow to holders. If a token tracks the price of a share without carrying those legal or economic rights, it falls into a category the SEC describes as “synthetic,” and therefore outside the exemption’s scope.
The SEC also leaves room for the idea that not every tokenization model will be treated the same way. Commissioner Hester Peirce emphasized that the exemption covers one particular model rather than every conceivable approach to trading tokenized securities, while noting the SEC is open to other models outside the specific tokenized stocks structure referenced in the order.
Who appears closest to the SEC’s framework
Several market participants are effectively being benchmarked against the exemption’s model. Cointelegraph’s earlier coverage highlighted ongoing developments across the tokenized securities landscape, but in this case the SEC’s requirements are what determine who is “close” and who would need major changes.
Coinbase’s tokenized stocks have been positioned publicly as non-synthetic and fully backed, with redemption features and dividends integrated. The company’s current offering, however, is described as aimed at non-U.S. customers, and its exchange infrastructure is built around a central limit order book rather than the permissioned AMM approach the SEC’s exemption is built around.
Ondo, by contrast, has taken steps that more directly map to the rights-and-entitlements theme. The project launched tokenized U.S. securities in June with shares held in traditional custody, while the token represents the investor’s entitlement onchain. Ondo also acquired Oasis Pro, which includes an SEC-registered broker-dealer, an ATS, and a transfer agent, giving it an infrastructure footprint across traditional and onchain market components.
Ondo’s head of global regulatory affairs, Peter Curley, argued in an interview with Magazine that the SEC’s action matters because it moved forward despite uncertainty about Congress finishing the job. Curley’s broader point was that not every tokenization effort will fit the exemption “and that’s fine,” as long as compliant pathways exist for products that do meet the SEC’s standards.
Permissioned AMMs and why Uniswap drew attention
The specific mention of permissioned AMM liquidity pools matters beyond compliance paperwork. It points to a technical design where issuers or regulated operators can enforce trading permissions through onchain mechanisms rather than relying solely on offchain gating.
Uniswap’s own development work may therefore be relevant even if the protocol itself is not a tokenized-stock venue in the same way a compliant intermediary would be. Uniswap introduced Permissioned Pools for v4 in July, aimed at enabling regulated assets to trade through AMMs where compliance can be enforced directly onchain. The key concept is that permissioned access—paired with KYC verification, record keeping, public notice requirements, and transaction transparency—can align the trading layer with regulatory constraints.
That creates a possible framework for how regulated token issuers could connect shareholder-rights systems to liquidity venues that restrict access appropriately. What remains uncertain, however, is whether existing implementations can be integrated end-to-end with the entitlement, corporate action handling, and issuer controls required by the SEC without additional adaptation.
Why some well-known products may be excluded
Not all tokenized equity products currently in circulation are positioned to qualify. Robinhood, for example, has deployed stock tokens on Robinhood Chain described as one-to-one backed and “fully DeFi composable.” But Robinhood’s token design has been a point of contention: analysts argue the SEC’s exemption excludes synthetic exposure and therefore rules out products like Robinhood’s Stock Tokens and Kraken’s xStocks in their present forms.
In Robinhood’s case, the stock tokens are described as tokenized debt securities issued by Robinhood Assets (Jersey) Limited. That structure means investors receive economic exposure to underlying stocks, but without the same legal or beneficial rights associated with conventional share ownership. Separately, they are not registered under U.S. securities laws and are not available to U.S. persons.
Kraken’s xStocks are also described as fully backed by underlying equities, but the article notes that they likewise may not give holders the same rights as conventional shares—illustrating a broader problem: backing alone is not enough if the exemption requires holders to receive the full set of rights and privileges embedded in ordinary share ownership.
RWA market intelligence platform RWA.xyz suggested in an interview that most tokenized equity products have been third-party sponsored but expects a shift toward issuer-sponsored models within the next 12 months. The logic is straightforward: the exemption framework appears to align token issuers with stock issuers, potentially reducing mismatches between who controls the token and who controls shareholder rights.
Five years to prove the model is worth adopting
The SEC describes the Innovation Exemption as temporary, with the relief lasting five years while the commission evaluates future rulemaking. The SEC’s chair, Paul Atkins, has framed the period as allowing the market to “develop,” but investors are still likely to ask a practical question: will tokenized stocks deliver clear advantages over conventional brokerage positions?
According to Ondo’s Curley, investors ultimately need outcomes that are faster, cheaper, or more useful than existing rails. There are also concerns that liquidity fragmentation for tokenized stock products could translate into less competitive pricing or weaker user experience—particularly if trading venues or token designs limit where liquidity can pool.
If the exemption’s requirements are met, tokenized stocks could theoretically support 24/7 trading, fractional ownership, faster settlement, and onchain composability while preserving shareholder rights and corporate action mechanics. But those benefits only matter if they translate into measurable improvements that users want—and if the industry can redesign products to fit the SEC’s model in the first place.
For now, readers should watch how issuers and trading venues operationalize the exemption’s constraints—especially the exact token rights requirements and the adoption of permissioned AMM liquidity models—and whether any major tokenized equity product teams announce changes aimed at becoming compliant within this five-year window.
This article was originally published as SEC Tokenized Stocks Rules: Key Winners and Losers Defined on Crypto Breaking News – your trusted source for crypto news, Bitcoin news, and blockchain updates.

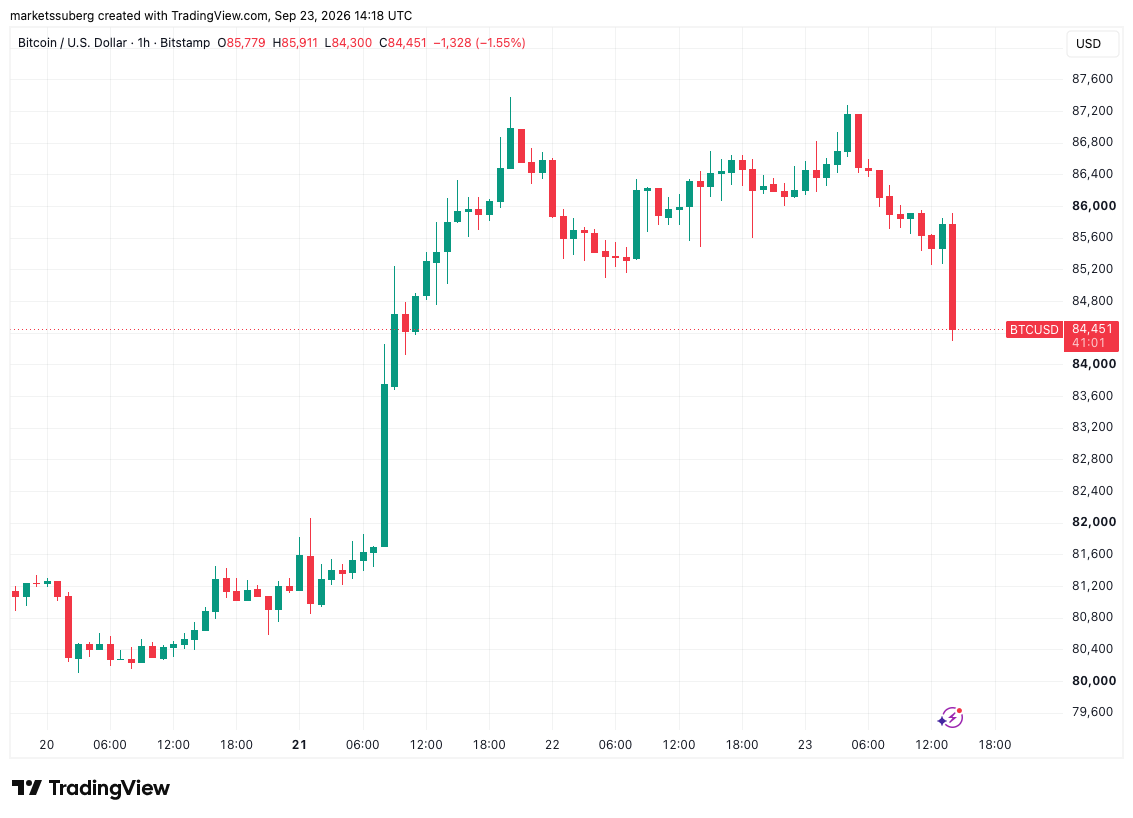
Bitcoin (BTC) was rejected near $87,000 on Wednesday as onchain data showed negative spot demand.
Key points:
- Bitcoin suffered a correction below $84,000 around Wednesday’s Wall Street open, causing $280 million in long liquidations over the course of four hours.
- Analysis saw $82,000 as key support to hold in the event of a further breakdown.
- Bitcoin cumulative spot demand remained negative on a rolling 30-day time frame
BTC price falls toward $84,000, nears week-to-date low
Data from TradingView tracked a second attempt to break beyond $87,000 before BTC/USD fell to local lows under $84,000 into the Wall Street open.
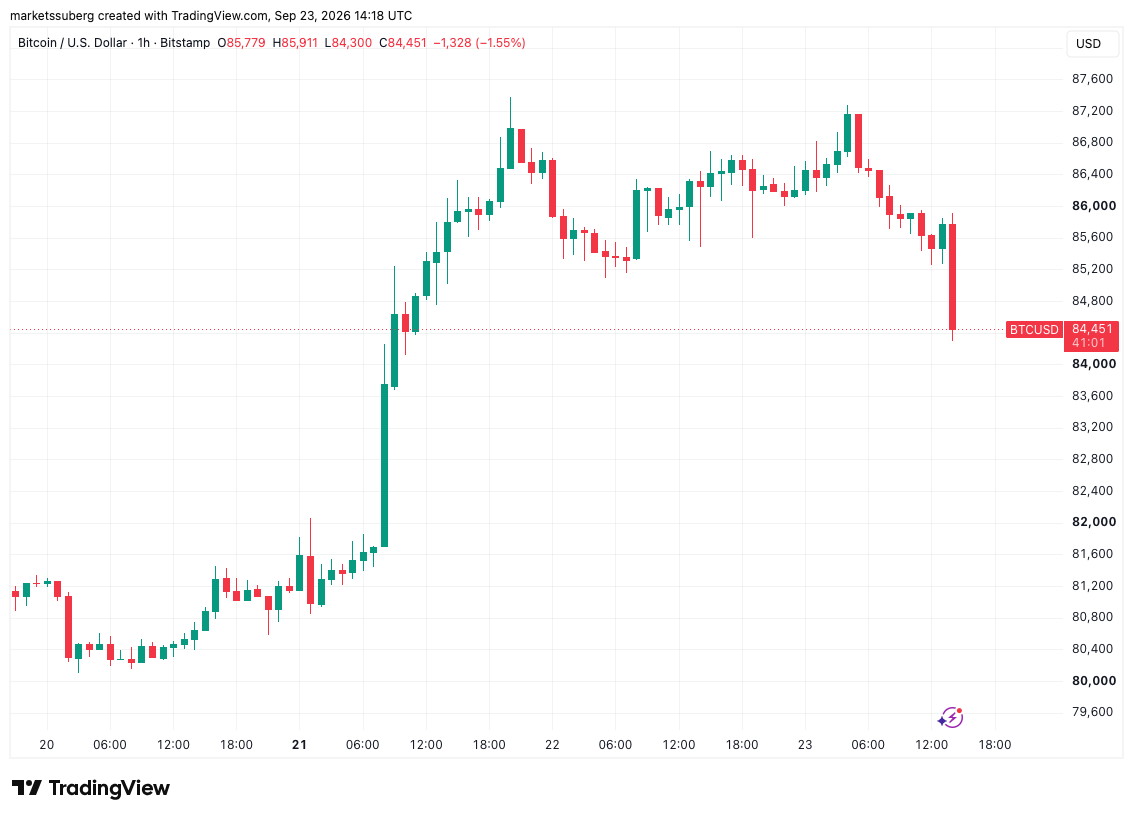
BTC/USD one-hour chart. Source: Cointelegraph/TradingView
These levels marked the upper and lower boundaries of a narrow intraday range. Liquidity thickened on both sides of the spot price as traders attempted to force a breakout from the sideways range. Data from CoinGlass tallied liquidations over the four hours prior to the time of writing at $280 million.
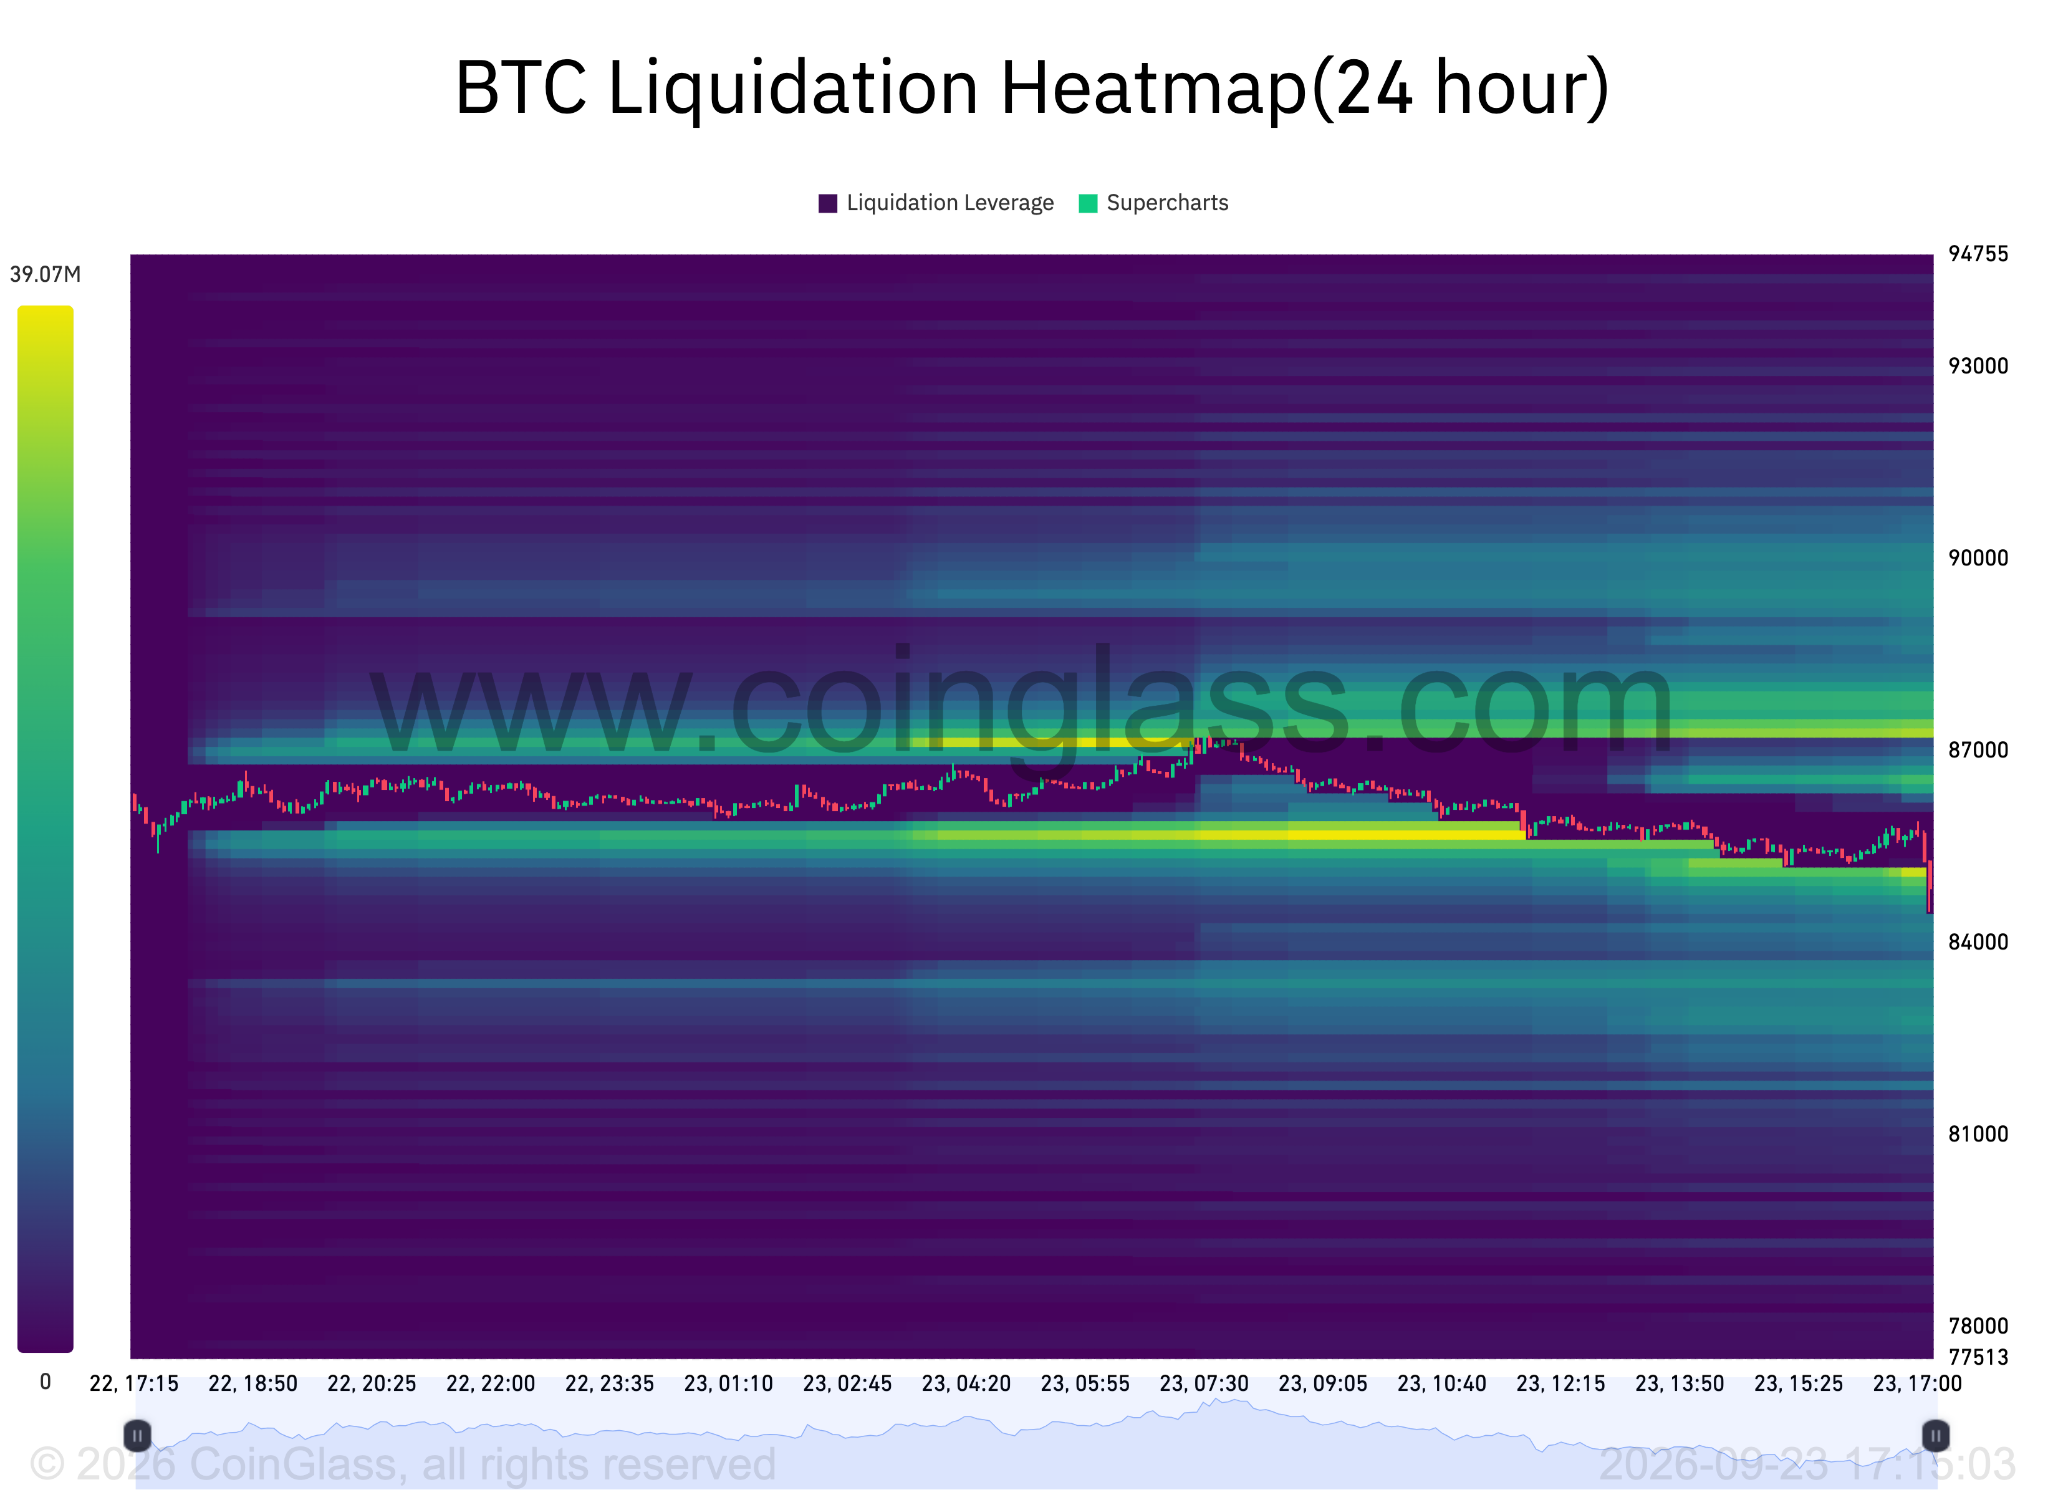
BTC liquidation heatmap. Source: CoinGlass
Commenting on the current landscape, trader and analyst Rekt Capital flagged $82,000 as a level for bulls to hold should the low-timeframe structure break down.
“For bullish continuation and to avoid reverting back into the $60k-$80k Range, Bitcoin would need to stay above or at minimum successfully retest ~$82k on any future dip,” he wrote in a post on X.
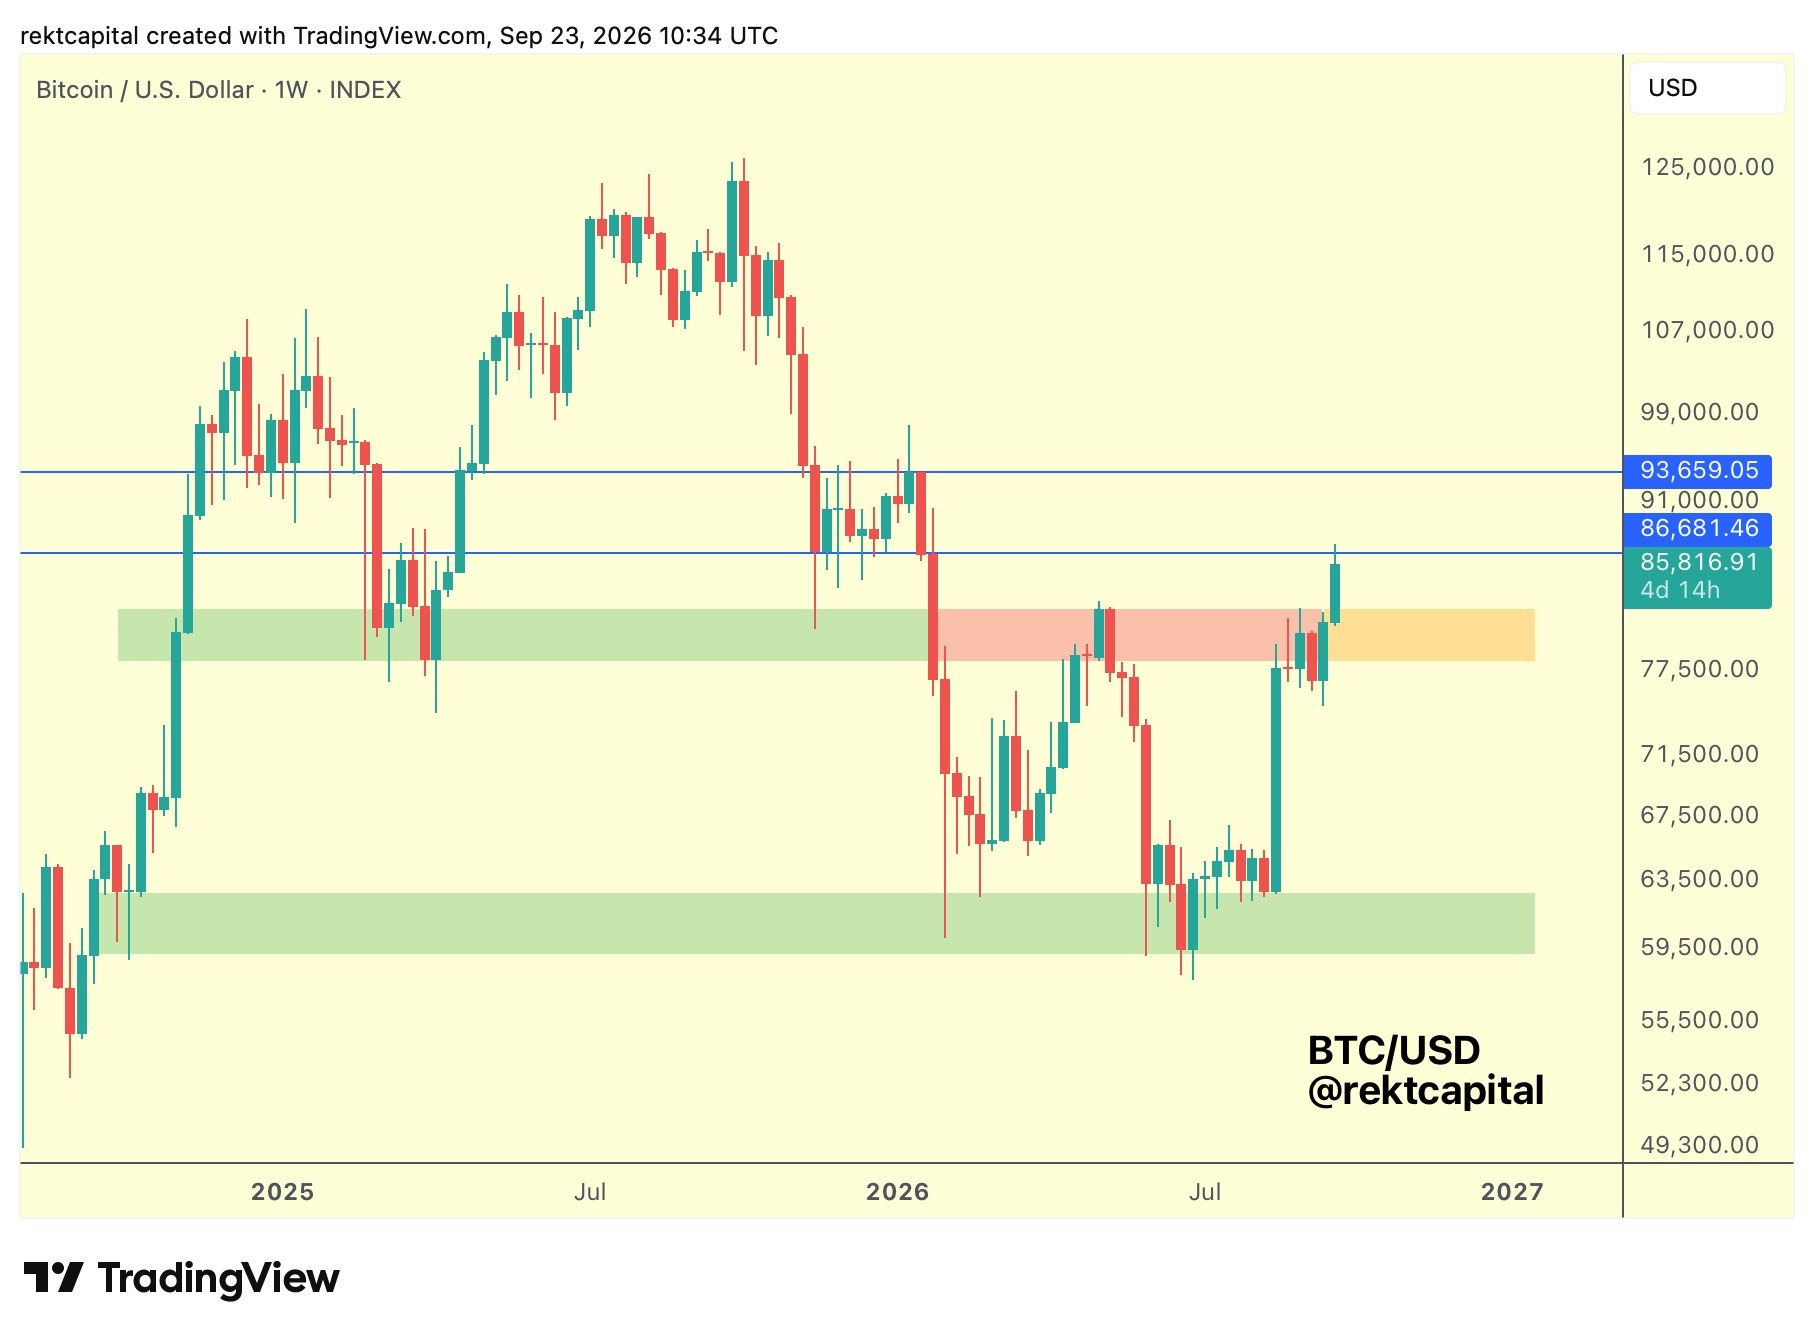
BTC/USD one-week chart. Source: Rekt Capital on X.com
As Cointelegraph reported, the current range has implications for certain investor cohorts. The US spot Bitcoin exchange-traded funds (ETFs) have their aggregate cost basis at just below $86,000.
Earlier, analysis highlighted $90,000 as the likely next area in which BTC/USD will consolidate due to the increased likelihood of profit-taking by traders.
Spot demand shows only modest improvement
Despite gaining over 35% since the week beginning Aug. 17, Bitcoin faces an ongoing struggle to attract spot-market demand.
Related: Crypto metric signals altseason as Bitcoin market-cap share stalls below 60%
In its latest research, onchain analytics platform CryptoQuant claimed that interest was still largely confined to derivatives markets.
“The negative value of $BTC spot demand has narrowed slightly, while futures demand continues to increase. Total demand is also showing a slight recovery compared to the previous day,” it reported in a blog post on the day.
An accompanying chart showed that cumulative 30-day apparent spot demand measured -180,000 BTC as of Tuesday. Negative values reflect supply outpacing demand over the 30-day lookback period.
“Although total demand remains in negative territory, the trend is shifting toward the positive. If the current momentum persists, spot demand will also flip to positive. That moment will mark the beginning of a more significant rally,” CryptoQuant added.
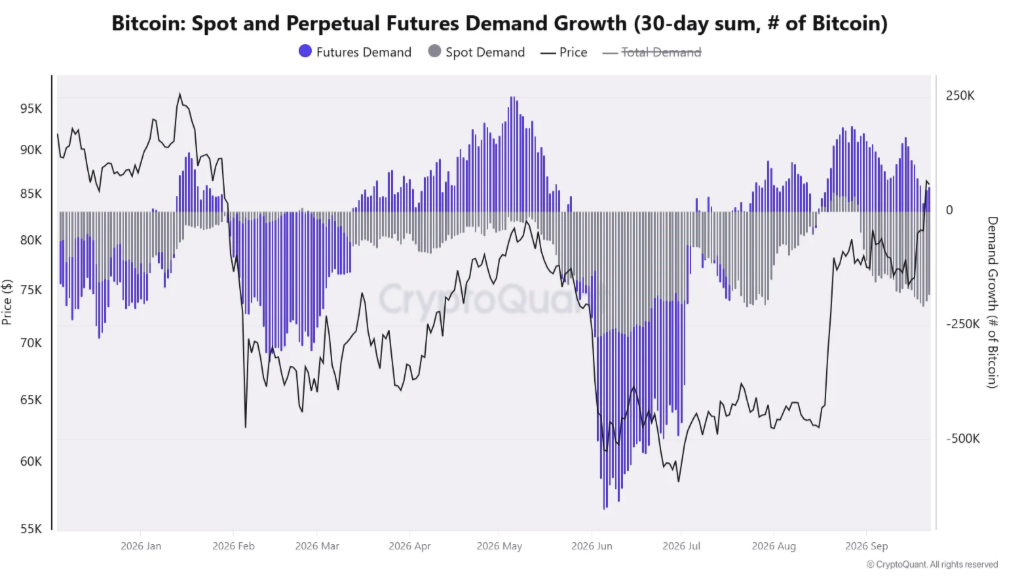
Bitcoin spot vs. futures apparent demand (screenshot). Source: CryptoQuant
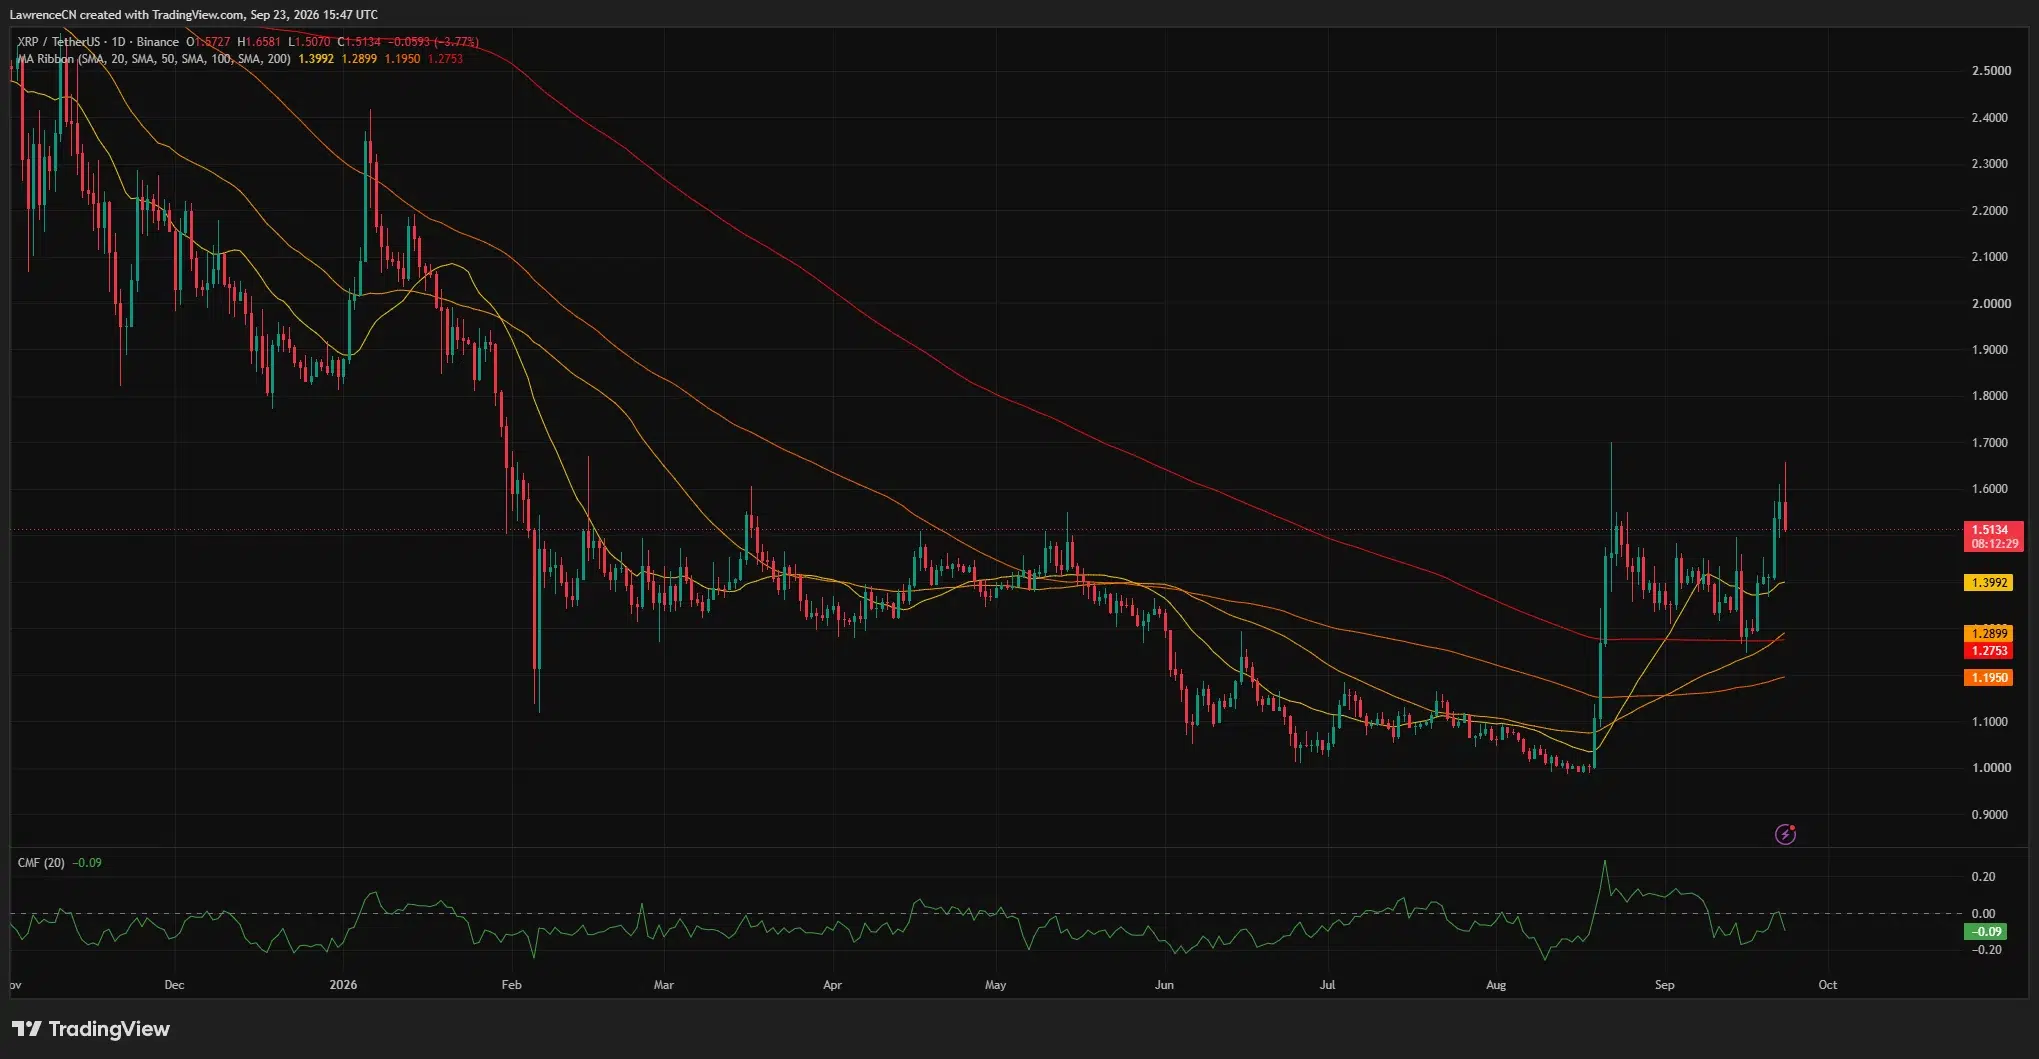
XRP price pulled back to about $1.51 on Sep. 23 after briefly rising above $1.65, leaving $1.60 as the first price level to reclaim while the XRP Ledger’s native lending proposals remain in validator voting.
Summary
- XRP price reached $1.6581 during the daily session before retreating to about $1.51.
- XLS-65 and XLS-66 would add pooled vaults and fixed-term lending directly to the XRP Ledger.
- Neither lending amendment has activated on mainnet; each needs sustained validator support.
- XRP remained above its 20-day moving average near $1.40, though money flow was negative.
XRPL Commons describes the proposed system as a way to bring pooled lending onto the XRP Ledger without deploying separate smart contracts. The plan depends on two amendments: XLS-65 would create Single Asset Vaults, while XLS-66 would let loan brokers use funds in those vaults for fixed-term credit. Both remain subject to validator approval.
XRP Ledger lending still needs validator approval
A Single Asset Vault would hold one type of asset, such as XRP, RLUSD, or another supported token. Depositors would receive shares representing their portion of the vault. Loan brokers could then arrange loans using the pooled funds, with the ledger recording terms, payments, and defaults.
The proposed system would leave borrower checks and lending decisions to the firms operating the loans. It also allows a broker to provide first-loss capital, which could absorb part of a default. Neither feature removes the risk that a borrower fails to repay or that depositors lose money.
A further amendment, LendingProtocolV1_1, would add vaults with set periods for deposits, lending and withdrawals. It would also count interest as income only when a borrower pays it. As crypto.news reported on the XRP Ledger’s 3.4.0 software release, adding those rules to server software did not activate them on mainnet.
The approval process matters more than the software release for timing. XRP Ledger amendments need support from more than 80% of trusted validators for two consecutive weeks before activation. XLS-65 and XLS-66 have yet to complete that process, so native lending has no confirmed mainnet start date.
Would lending create demand for XRP?
A lending launch would give developers and financial firms another reason to use the XRP Ledger, but the size of any effect on XRP would depend on which assets they lend. An XRP-funded vault would use XRP as its lending asset. A vault funded with RLUSD or another issued token would use that asset for its loans, while XRP would retain its role in network fees and account reserves.
That distinction is relevant to the planned RLUSD credit product previously covered by crypto.news. The product was being tested for working-capital loans to fintech and payment companies, with RLUSD rather than XRP serving as the credit asset. Its development shows a possible use for the lending rules, but it does not establish how much XRP borrowers or lenders would need to buy.
For U.S. holders watching the proposal, validator approval and actual use of the lending system are separate milestones. A vote could make the feature available; subsequent vault deposits and loans would show whether firms adopt it and whether XRP itself becomes a material lending asset.
XRP price faces another test near $1.60
XRP’s daily trading range shows why $1.60 remains the immediate test. The token opened near $1.57, reached $1.6581, and fell as low as $1.5070 before trading around $1.51 in the Sep. 23 chart snapshot. A move back above $1.60 would put the day’s high near $1.66 in view. The previous September spike near $1.70 marks the next visible area above it.
On the downside, the 20-day simple moving average near $1.40 sits below the current price. The chart also shows moving averages clustered around $1.28–$1.29. A loss of $1.40 would weaken the recent rebound and bring that lower area back into focus.
The 20-day Chaikin Money Flow reading stood at −0.09, indicating that buying pressure had not strengthened alongside the latest rise. XRP can still retest resistance, but the intraday retreat and negative money-flow reading leave the $1.60 break unconfirmed. The validator vote offers a development to watch; the chart has yet to show that it will carry XRP through resistance.
Disclosure: This article does not represent investment advice. The content and materials featured on this page are for educational purposes only.
The U.S. Securities and Exchange Commission (SEC) has moved to dismiss civil enforcement actions against multiple crypto-related companies that were filed under the prior administration, according to SEC Commissioner Mark Uyeda. Speaking at the Psaros Center for Financial Markets and Policy’s Financial Markets Quality Conference, Uyeda said the agency’s decision was tied to an intended shift in how it approaches rulemaking and litigation strategy.
Uyeda, who served as acting SEC chair from January to April 2025 before Paul Atkins took over following confirmation, argued that continuing cases authorized under earlier leadership could undermine the SEC’s credibility if the agency’s legal posture changes. His remarks point to a broader tension at the intersection of crypto enforcement and evolving regulatory interpretation within the SEC.
Key takeaways
- SEC Commissioner Mark Uyeda said civil crypto cases were dropped to avoid an “180-degree change” in positions becoming inconsistent in court.
- Uyeda linked the dismissals to preparations for a major shift in SEC rulemaking and litigation approach.
- The commissioner suggested there were doubts about whether the earlier cases were “justifiable under law,” as the SEC anticipated reversal in its stance.
- The SEC’s leadership structure is also in flux, with Commissioner Hester Peirce’s departure expected in November and no announced replacements by Trump.
Why the SEC moved to end crypto enforcement cases
Uyeda described the early-2025 decision as a pragmatic step to manage consistency between what the SEC argues in litigation and what it plans to adopt through rulemaking. He said the commission determined that litigators should not continue cases that had been authorized under the previous administration if doing so would conflict with a new set of policy objectives.
In Uyeda’s account, the SEC was concerned that courts could receive interpretations from the agency that effectively reverse course compared with the positions it had previously advanced. He said this would erode the agency’s credibility—especially when the SEC is attempting to persuade judges while simultaneously pivoting its regulatory framework.
Uyeda framed the issue around the potential for litigators to defend earlier arguments while the SEC prepares to issue a fundamentally different approach. “I’m not about to have our litigators… stand up in court and have a commission interpretation be issued that is a 180-degree change from what they’d been arguing for,” Uyeda said, according to his remarks at the conference (via Psaros Center for Financial Markets and Policy).
Dismissals under the prior administration’s approach
Uyeda’s comments align with reporting that the SEC dropped several crypto-related lawsuits earlier in 2025. Earlier coverage from Cointelegraph noted that the commission dismissed a case involving Kraken, and it also dropped actions involving other industry names including Ripple Labs and Coinbase.
Those dismissals had drawn sharp criticism from opponents of the agency’s previous strategy, who described the moves as part of a politically charged shift rather than a purely legal recalibration. Cointelegraph’s earlier reporting tied the enforcement pattern to concerns about retaliation dynamics following President Donald Trump’s 2024 campaign. That reporting also pointed to Trump’s pledge to fire then-SEC Chair Gary Gensler “on day one,” with Gensler resigning the day Trump took office.
While Uyeda’s conference remarks focused on litigation coherence and institutional credibility, the political backdrop matters for how market participants interpret the SEC’s enforcement trajectory. For industry observers, the question is whether dismissals should be understood as a correction of legal weaknesses, a change in policy direction, or both.
Rulemaking overhaul and “credibility” in court
The SEC’s legal posture in crypto has long been contentious because enforcement actions often serve as a proxy for regulatory interpretation in the absence of comprehensive, sector-specific rules. In that context, Uyeda’s stated rationale—avoiding situations where the SEC’s court arguments would conflict with its future policy—highlights a core challenge for the agency: how to transition from one interpretive approach to another without weakening its ability to persuade judges.
Uyeda’s argument suggests the SEC is seeking to reduce the likelihood that it appears internally inconsistent. If an agency simultaneously pursues litigation based on one theory while planning to issue an opposing theory through rulemaking, the court may treat the shift as a retreat from prior positions rather than a natural evolution of policy. Uyeda said that outcome could harm the SEC’s credibility.
For investors and market participants, this matters because the SEC’s enforcement strategy can influence compliance expectations and legal risk premiums. Even when a case is dismissed, the underlying uncertainty about what the SEC considers acceptable activity may persist—especially in a regulatory environment where guidance and rules are still developing.
Leadership transition at the SEC adds uncertainty
Uyeda’s remarks came as the SEC itself is preparing for additional leadership change. He has served as an SEC commissioner since 2022 and is currently part of the agency’s leadership alongside Paul Atkins and Commissioner Hester Peirce. However, the source reporting indicates Peirce’s departure is expected in November.
That expected change could significantly alter the SEC’s internal balance at a time when the agency is already adjusting its posture toward crypto litigation and rulemaking. According to the same account, the agency would then have only two members on its leadership panel out of five, and Trump has not announced nominations to replace potential departing leadership.
For crypto market participants, fewer confirmed decision-makers can mean slower consensus on enforcement priorities and rulemaking direction. It also raises the likelihood that upcoming SEC leadership changes could influence whether earlier enforcement dismissals represent a pause, a broad retreat, or the beginning of a new era of regulatory strategy.
As the SEC continues navigating the shift Uyeda described, readers should watch for the next steps in rulemaking and any subsequent enforcement signals. The key open question is whether the agency’s “credibility” rationale will translate into clearer, consistent standards for crypto compliance—or whether legal uncertainty will simply move from active lawsuits to new forms of guidance and litigation.
Aerodrome liquidity farming has accounted for about $109 billion of the $121 billion in USDC transfers recorded on Sep. 23, according to an analysis by RyeBlocks.
Summary
- RyeBlocks attributed roughly 90% of the day’s reported USDC transfer volume to farming on Aerodrome.
- The analyst estimated that one-tick farming has generated about 75% of USDC transfer volume in the data measured since Aerodrome launched.
- The figures measure token movements, which can include activity other than payments.
- Visa also separates raw stablecoin transfers from adjusted activity in its onchain dashboard.
On-chain analyst RyeBlocks posted the figures on Sep. 23, describing the Aerodrome activity as “inorganic farming.” The estimate leaves about $12 billion of the reported daily total outside the activity RyeBlocks identified. It does not establish that the remaining amount consisted entirely of payments.
The analyst also put one-tick farming at roughly 75% of the USDC transfer volume measured since Aerodrome launched. RyeBlocks linked to a Dune analysis, but the post does not spell out the full scope and filters behind that longer-term figure. It should therefore be treated as the analyst’s estimate for the measured data, rather than a verified share of every USDC transfer across all blockchains.
Why USDC transfers can outnumber payments
Aerodrome is a decentralized exchange on Base, the blockchain network developed by Coinbase. Traders use its liquidity pools to swap tokens, while liquidity providers deposit assets that support those trades. Aerodrome’s documentation says eligible providers can receive AERO token rewards, with allocations to pools determined through weekly voting.
In one-tick farming, a liquidity provider uses a very narrow price range for a position. As positions are managed, USDC can move through pool contracts repeatedly. RyeBlocks’ finding concerns the resulting transfer records: the value counted as moving onchain can rise each time the tokens change position, even when the activity does not represent a new purchase or a payment to another person.
Aerodrome says it launched on Aug. 28, 2023, and uses a concentrated-liquidity design called Slipstream alongside another type of liquidity pool. Its rewards system gives providers a reason to place funds in eligible pools. RyeBlocks has identified farming within that system as the source of most of the USDC volume in its Sep. 23 comparison.
The finding does not, by itself, show wrongdoing by Aerodrome or its users. Providing liquidity is a normal exchange activity. The measurement question is whether a headline transfer total tells readers how many dollars people used for payments, or whether it mainly counts repeated movements connected to trading and liquidity management.
A separate measure shows why the distinction matters on Base. In September, Aerodrome handled $557.1 million of tokenized-stock trades during a 30-day period, or 76% of that category’s volume on the network, according to Token Terminal figures previously covered by crypto.news. That measure counted completed swaps. RyeBlocks’ USDC figures concern token transfers, so the two totals describe different types of activity and should not be combined.
How stablecoin data providers separate the activity
Visa’s Onchain Analytics Dashboard draws a distinction between total stablecoin volume and an adjusted measure. Visa says public blockchains record activity initiated both by people and by software, including transactions that do not resemble conventional settlement. Its adjusted methodology seeks to remove potential distortions from bots, high-frequency trading, routing and repeated internal movements within a transaction.
Visa and its data partner Allium also classify transfers by use. The dashboard distinguishes payments for goods, services or person-to-person transfers from decentralized finance, exchange flows, trading and other categories. A USDC transfer into a liquidity pool can therefore be recorded onchain without being classified as a consumer or business payment.
The adjusted figure is not a simple count of payments, either. Visa says some DeFi activity can appear in adjusted volume, depending on how a transfer is classified and whether it passes the dashboard’s filters. Its methodology also uses address labels and transaction thresholds, which means results depend on the rules used to sort the data.
Dune describes a similar need to identify what a transfer represents. Its stablecoin data can classify activity such as a decentralized-exchange swap, a lending deposit, or a bridge transfer. Dune says users can choose which categories to include when calculating adjusted volume, rather than relying on one formula for every purpose.
Circle’s USDC figures cover several uses
For U.S. investors following Circle, the issuer of USDC, the difference between transfer volume and payments is relevant to how company activity figures are read. Circle reported $14.8 trillion in USDC onchain transaction volume for the second quarter of 2026, up 151% from a year earlier. As earlier coverage of Circle’s results noted, that total includes trading and transfers alongside payments. It is a quarterly, company-reported measure and is not directly comparable with RyeBlocks’ single-day estimate.
Circle has also reported a narrower payments figure. Its second-quarter results put USDC at 99.3% of the payment volume it measured through x402, a protocol that lets software pay for online services. The percentage applies to that protocol’s measured activity, not to all payments made with USDC.
In August, Bernstein used another measure when assessing Circle. The brokerage said adjusted stablecoin volume was running at an annualized rate of about $17 trillion through July, with its calculation excluding bots and high-frequency activity. That estimate covers stablecoins generally and uses a different period and method from the figures RyeBlocks reported.
Circle’s planned expansion into payments provides a separate point of comparison. In September, the company agreed to buy payments firm Tazapay for $400 million in stock. Circle said Tazapay processes more than $25 billion in annualized payment volume across payout routes spanning over 100 markets, with stablecoins involved in about 60% of its transaction volume. The deal remains subject to approvals, including clearance from the Monetary Authority of Singapore.

Kraft Heinz (KHC) has not been a story of growth in recent years. Volumes are down, revenues are under pressure, and the stock is trading below its 52-week high price. However, according to RBC Capital Markets, it appears that investors might have overlooked what lies ahead.
RBC recently initiated its coverage of Kraft Heinz with a price target of $32 and an “Outperform” rating. Analyst Nik Modi forecasts that the packaged food giant will start organic growth in 2027 when its organic revenue growth is estimated to reach 0.9% versus the consensus estimate of 0.4%. The thesis is partially driven by approximately $700 million of additional investments into pricing, innovation, and marketing in 2026. As a result, 2027 will be the test year for Kraft Heinz: the company has to show that increasing investment into its brands can lead to higher volumes and growth of revenues.
More News from Barchart
About Kraft Heinz Stock
Headquartered in both Pittsburgh and Chicago, The Kraft Heinz Company is one of the largest producers of packaged foods and beverages in the world. The company’s brand list includes Heinz, Kraft, Philadelphia, Lunchables, Capri Sun, and Oscar Mayer. Currently, the market capitalization of Kraft Heinz is about $29 billion.
KHC stock is trading around $24, having a 52-week price range from $21.03 to $28.09. The stock is approximately 13% below its 52-week high price despite recovering around 16% since its low, and it lags the S&P 500 Index ($SPX), which is still in the green for 2026.

The valuation is one of the elements of RBC’s thesis that stands out. The current multiple of KHC is approximately 11.9 times of forward earnings and 1.16 times of sales. Moreover, KHC’s forward P/E ratio is below several previous highs of the stock reached this decade. This suggests that investors are currently not paying a lot for the growth. It makes sense given the weakness in the volumes but becomes more interesting if RBC turns out to be correct.
Another element of the story is income. Kraft Heinz distributes a quarterly dividend of $0.40 per share ($1.60 annually); that means the current forward yield is about 6.5%. The most recent declared dividend payment date is Sept. 25.

Visa released the results of a survey signaling that bank-level fraud protection and insurance could drive adoption in stablecoins for cross-border transactions among US users.
In a survey of 2,192 US-based customers published on Wednesday, Visa said that the “adoption intention” of stablecoins among US users could climb from 36% to 56% “in a hypothetical scenario with bank-level fraud protection and deposit insurance.” The findings from a survey by Morning Consult between February and March showed that Americans who were asked about financial terms like stablecoins were looking for faster and cheaper methods to send money abroad.
“Nearly two-thirds (64%) [of respondents] say trust depends more on who offers a payment method than on the tech itself,” said Visa. “Willingness to use stablecoins rises from 36% to 45% when offered through an existing financial provider.”
The survey posited bank-like protections for stablecoin issuers in the US at a time when companies are preparing for the enactment of the Guiding and Establishing National Innovation for US Stablecoins (GENIUS) Act. The bill awaits finalized rules from key US financial agencies ahead of its effective date, expected in January 2027.
Related: Stablecoin cross-border flows surge 78%, defying crypto bear market
Unlike products from traditional financial institutions like banks, stablecoins lack many of the protections from fraud and are not covered by deposit insurance provided by the Federal Deposit Insurance Corporation (FDIC). Under GENIUS starting in January, US stablecoins are still not expected to have FDIC insurance or explicit fraud protection, but will include guidelines in an effort to address illicit activities.
EU banks push for changes to minimum bank deposit for stablecoins
On Tuesday, the European System of Central Banks called for changing the rules requiring that stablecoins have at least 30% of reserves held as bank deposits, or 60% for “significant” tokens. The group instead pushed for liquidity thresholds for the assets, citing potential risks from users quickly withdrawing deposits.
The proposed changes for how EU banks address stablecoins fell under the region’s Markets in Crypto-Assets (MiCA) framework, which began enforcing its rules on stablecoins in June 2024.
According to payments infrastructure company Decta, the market capitalization of compliant euro stablecoins more than doubled from 2025 to 2026 leading up to the end of MiCA’s transition period. US dollar-pegged tokens like USDC and USDT continue to lead stablecoins with a combined market capitalization of about $260 billion.
Magazine: MiCA cracks down on USDT in Europe… but no one else cares
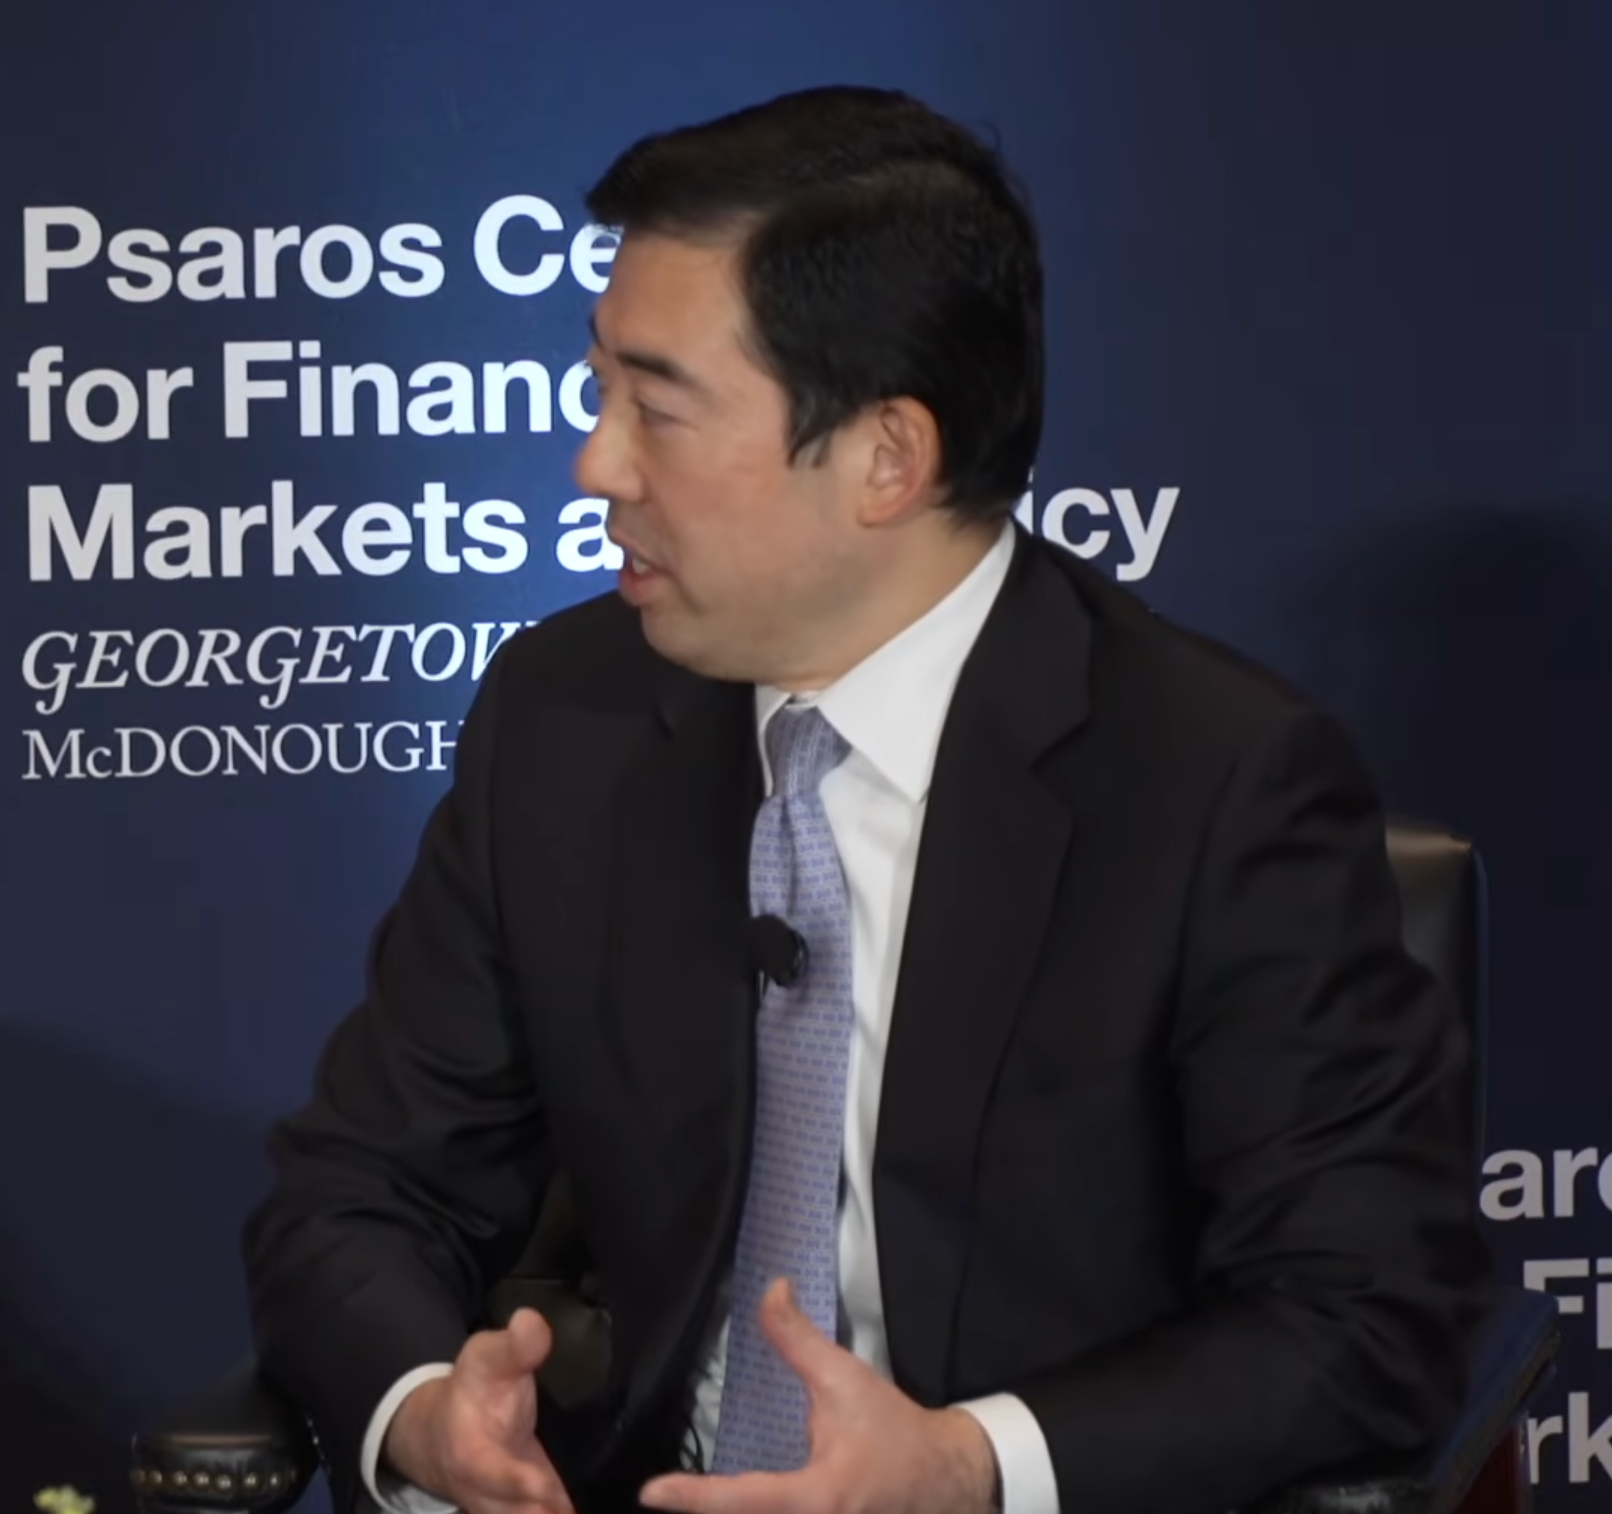
Mark Uyeda, who served as acting chair of the US Securities and Exchange Commission (SEC) before Paul Atkins’s confirmation, said the agency dropped civil cases against cryptocurrency companies filed under the previous administration because it was preparing a “180-degree change” in rulemaking.
In a Wednesday panel at the Psaros Center for Financial Markets and Policy’s Financial Markets Quality Conference, Uyeda said the SEC dropped cases involving crypto companies in early 2025 as it could have hurt the agency’s credibility in arguing positions in court contrary to its planned policy changes. Uyeda argued that there had been “significant concerns” that the cases against crypto companies were “justifiable under law.”
“I’m not about to have our litigators, even though they’re having cases that were authorized under the prior administration, stand up in court and have a commission interpretation be issued that is a 180-degree change from what they’d been arguing for that court,” said the commissioner. “I think that hurts [our] credibility as an agency.”
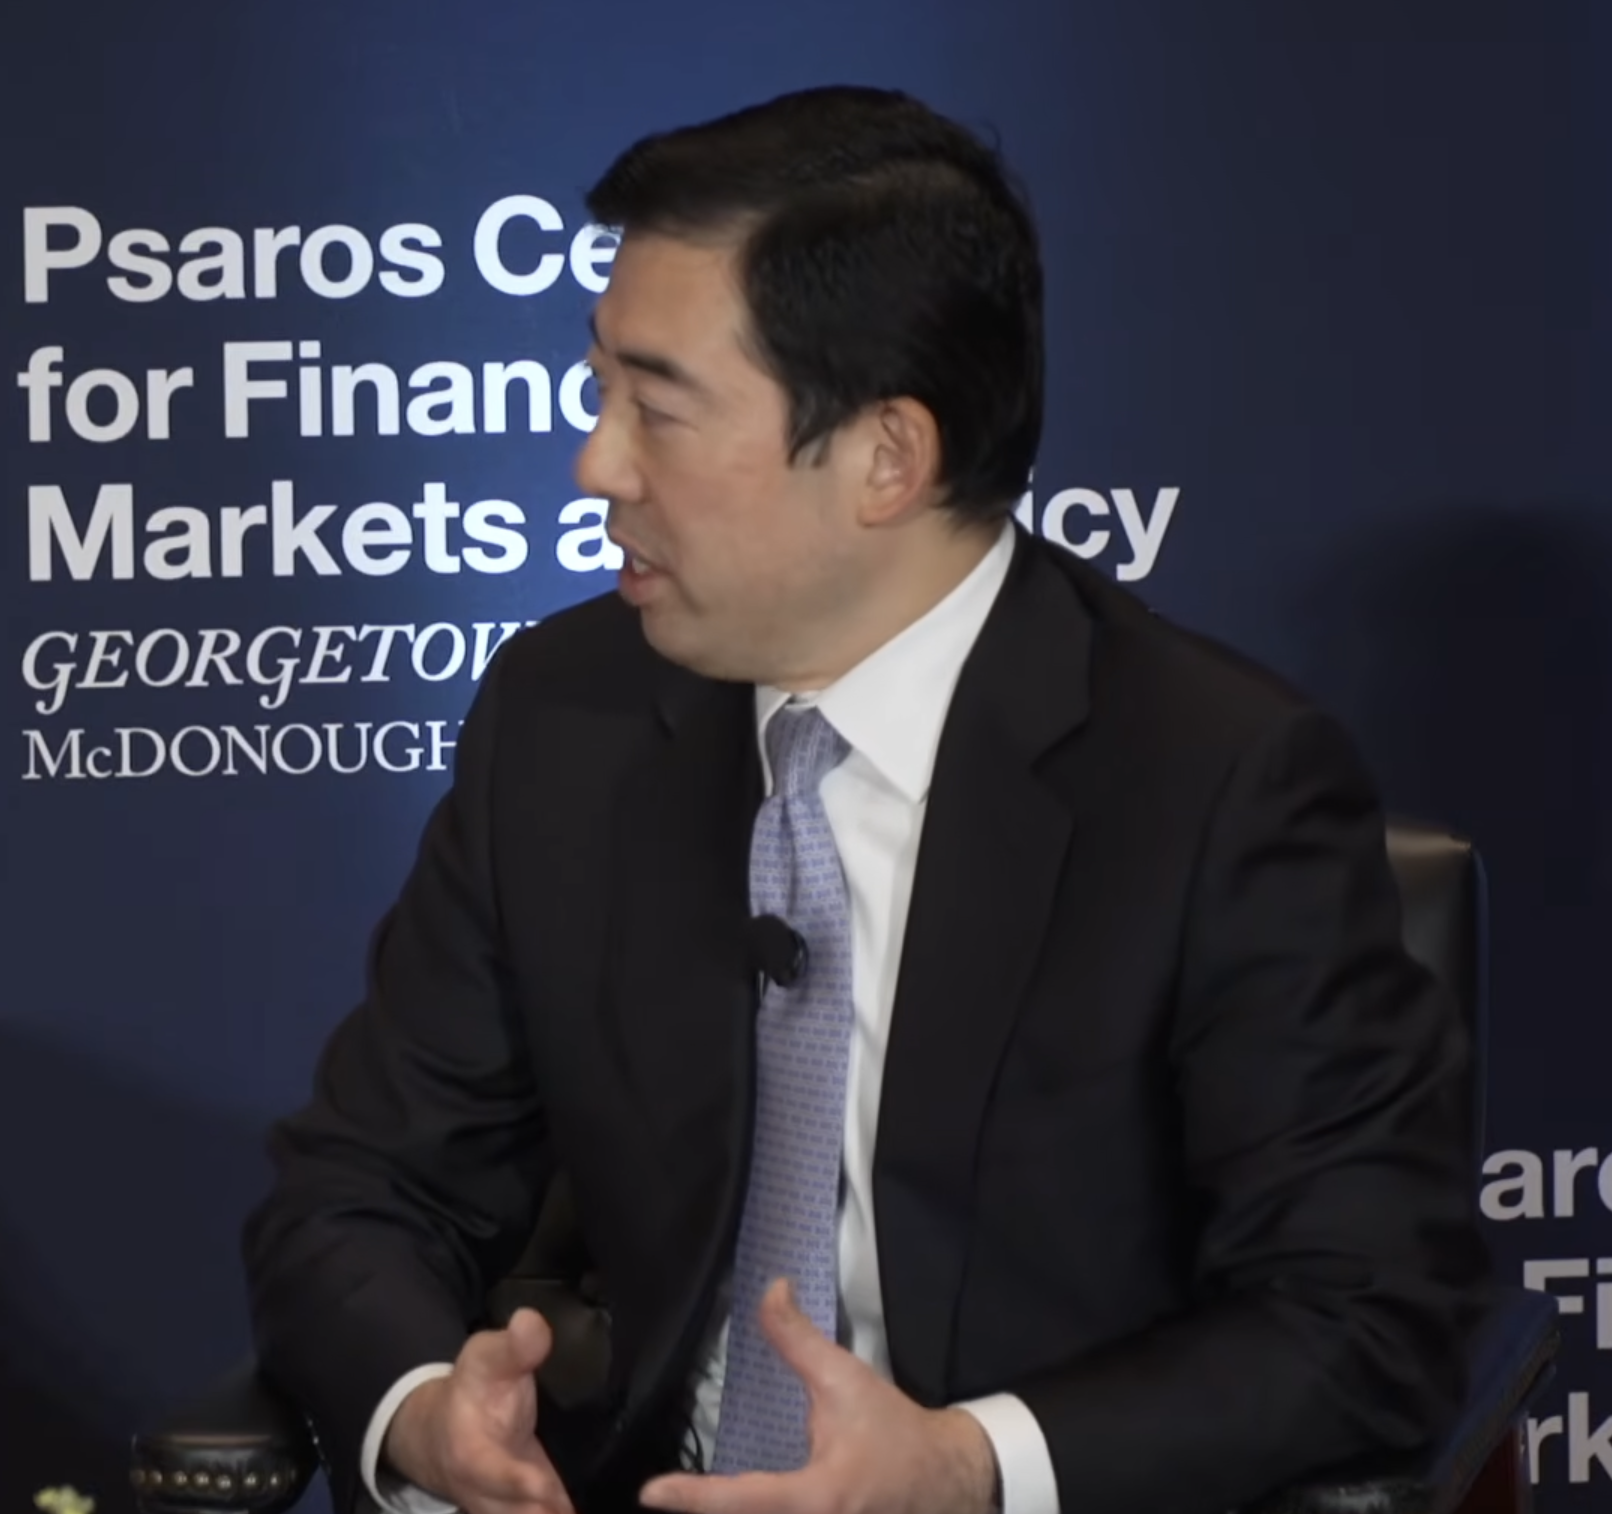
SEC Commissioner Mark Uyeda. Source: Psaros Center for Financial Markets and Policy
Under Uyeda, who was acting SEC chair from January to April 2025, the commission dropped cases filed against Kraken, Ripple Labs, Coinbase and others in what many critics characterized as payback for the industry’s support of President Donald Trump’s 2024 campaign. Trump had promised to fire former SEC Chair Gary Gensler, under whom many of the cases were filed, “on day one” if elected. Gensler resigned the day Trump took office.
Uyeda has been a commissioner at the SEC since 2022 and currently serves at the agency’s leadership alongside Atkins and Commissioner Hester Peirce. With Peirce’s departure expected in November, the agency will have only two of its five members on its leadership panel, and Trump has not announced any nominations for potential replacements.
Related: SEC grants temporary exemption for tokenized US stock trading
All 11 Democrats on the Senate Banking Committee have asked Chair Tim Scott to hold a public hearing on prediction markets after Republican members met privately with Kalshi’s chief executive.
Summary
- The senators want all committee members to examine the markets’ effects on consumers and the financial system.
- They say some contracts tied to corporate results could fall under SEC oversight.
- Kalshi and Polymarket recorded about $53 billion in combined global trading volume in July, according to Pew Research Center.
- State disputes over sports contracts and a recent CFTC warning have added to the regulatory debate.
In a Sep. 23 letter, the Democratic members of the Senate Banking, Housing, and Urban Affairs Committee asked Scott to convene a hearing open to the full panel. Ranking member Elizabeth Warren and Sen. Catherine Cortez Masto led the request after reports that Republicans planned a private discussion with prediction market executives, including Kalshi representatives.
The senators said a public session would let lawmakers question industry participants about consumer exposure, market integrity and the financial products being offered. Their request focused in part on contracts linked to company performance, which they said could qualify as security-based swaps and come under Securities and Exchange Commission rules.
According to The Block, Republican committee members met Kalshi CEO Tarek Mansour on Sep. 23. Scott told the outlet that the discussion covered securities-linked products, how investors use them, retail protections, and regulatory questions for Congress.
Why Democrats want a public prediction markets hearing
The letter argues that both individual and institutional investors are gaining exposure to security-based prediction markets. As firms seek SEC approval for products tied to corporate earnings, the senators said the Banking Committee should examine how such contracts are offered and supervised.
“The full Senate Banking Committee has a critical oversight role to play,” the lawmakers wrote, referring to requests for approval of options linked to company earnings. Their letter asks Scott to allow every committee member to take part in a public hearing, rather than limit the discussion to a meeting with Republican members and industry executives.
The SEC question matters because prediction markets do not all involve the same underlying event. A contract on a sports result raises different regulatory issues from one tied to a public company’s earnings. The Democrats said the latter type could meet the legal definition of a security-based swap; the letter presents that as a possibility for examination, not a finding that every such contract falls under SEC authority.
Kalshi has separately pursued products linked to U.S. shares. As reported in September, it filed rules for stock and ETF perpetual futures with the SEC and CFTC, proposing 23-hour weekday trading and a minimum customer margin of 15.50%. Those proposed security futures differ from the event contracts discussed in the senators’ letter, but the filings show why both agencies feature in questions about Kalshi’s products. The CFTC had not approved the stock perpetual submissions when that report was published.
Trading volume has risen as lawmakers examine investor losses
For the scale of the industry, the senators pointed to the rapid growth of Kalshi and Polymarket. Pew Research Center found that their combined monthly global trading volume rose from less than $5 billion in September 2025 to about $24 billion in April 2026. Pew’s newer analysis put the total at $53 billion in July, up from $26 billion in May, with sports accounting for much of the increase.
Pew’s measure counts contracts at their $1 value if the outcome is correct, rather than the price a trader paid. It is a measure of trading activity, not an estimate of the cash traders put into their accounts. Its September report also found that combined volume remained around $47 billion in August after easing from July’s level.
The Democrats raised the risk of manipulation and trading by people with advance knowledge of an outcome. They also cited research suggesting that profits are concentrated among a small share of users while many others lose money. Those concerns formed part of their case for questioning platforms in public.
Pew’s study of 11,989 active Polymarket wallets provides a more specific view of trading results. Over a six-week period from May to June, 56% of the sampled accounts lost money, while 7% made more than $1,000 and 9% lost more than $1,000. Pew said the typical account was close to breaking even. Its sample did not cover Kalshi or Polymarket’s newer U.S. platform, so the findings do not describe the results of all prediction market users.
CFTC warnings and state cases add to the oversight debate
Market integrity is also receiving attention from the Commodity Futures Trading Commission. In coverage of its warning, crypto.news reported that CFTC staff had flagged contracts based on what a named person says, attends, or does as especially vulnerable to manipulation. The agency called for exchanges to explain how they would identify people who could influence an outcome and detect misuse of nonpublic information.
The CFTC has already brought cases involving traders whose access or conduct affected event-contract outcomes. In one case described in the agency’s orders, a former White House teleprompter operator used advance access to presidential speeches to trade contracts tied to President Donald Trump’s remarks. In another, former Rep. George Santos traded a contract concerning his attendance at the 2026 State of the Union while making public statements about his plans.
Sports contracts pose a separate question for U.S. customers: whether federal oversight of a registered derivatives exchange prevents states from applying their gambling laws. New Jersey asked the Supreme Court in September to review a ruling favoring Kalshi. As the state’s petition was previously covered, New Jersey argues that federal derivatives law does not strip states of authority over sports wagering within their borders. Kalshi maintains that its CFTC registration places the contracts under federal oversight.
At the same time, Kalshi has sought to expand access for professional traders through a proposed margin framework for selected event contracts. Its Sep. 22 filing would allow eligible participants to post margin rather than fund the full possible loss of a position at the outset. Sports contracts are excluded from the proposal, and access would be limited to participants trading through a registered futures commission merchant or approved to clear their own trades.
Coinbase has begun designing a post-quantum custody system intended to protect about $250 billion in institutional assets while supporting any new signature scheme adopted by Bitcoin or another blockchain.
Summary
- Coinbase is preparing custody infrastructure for several possible post-quantum signature schemes.
- Hash-based signatures may not work with the MPC systems used by many crypto custodians.
- Programmable hardware security modules could provide Coinbase with an alternative key-protection method.
- Bitcoin developers have not selected or activated a post-quantum signature standard.
Coinbase prepares custody for several signature schemes
MARA Foundation TV hosted Coinbase Chief Cryptographer Yehuda Lindell, who said the exchange wants its custody platform to remain usable regardless of which post-quantum signature schemes blockchains eventually select.
Bitcoin has not chosen a signature scheme for practical post-quantum use, leaving custodians without a single technical standard around which to rebuild their systems. Lindell said different blockchain communities may also reach different decisions instead of adopting one common scheme.
Coinbase is therefore preparing for several possible outcomes rather than building its system around one candidate. Lindell said the company wants to avoid a situation in which a blockchain approves a signature scheme that its custody infrastructure cannot handle.
The work carries added weight because Coinbase holds about $250 billion in assets for institutional customers, according to the figure Lindell gave during the program. Its clients include BlackRock, which uses Coinbase Custody for digital assets connected to its investment products.
An August U.S. custody review placed Coinbase’s institutional assets at approximately $376 billion and said the company safeguards more than 80% of assets held by U.S. spot Bitcoin and Ethereum exchange-traded funds. Differences between the two totals may depend on their reporting dates and the services or assets included in each estimate.
Custody systems protect the private keys needed to authorize transactions. Any future change to Bitcoin’s signature method would therefore require large custodians to update the technology used to create, store and operate those keys.
Post-quantum signatures challenge existing MPC custody
Many institutional custody platforms use Multi-Party Computation, or MPC, to divide control of a private key among several parties. Under such an arrangement, no participant needs to hold or assemble the full private key while approving a transaction.
Lindell said many post-quantum signature schemes may be “not friendly to MPC” because their mathematical design differs from the signatures now used by major blockchains. Hash-based signatures present a particular problem because they lack the arithmetic structure on which traditional cryptographic key splitting depends.
Researchers, including Stanford University cryptographer Dan Boneh, are studying possible ways to apply MPC-style controls to such signatures, Lindell said. The research remains highly experimental, however, and it is not yet clear whether a practical MPC-equivalent system can be created for hash-based signatures.
Coinbase’s existing interest in the field predates the latest custody design. In January, the company established an independent quantum computing and blockchain advisory board that includes Boneh, Lindell, Ethereum Foundation researcher Justin Drake, University of Texas professor Scott Aaronson, EigenLayer founder Sreeram Kannan and distributed-systems specialist Dahlia Malkhi.
According to Coinbase, its post-quantum roadmap includes changes to Bitcoin address handling, updates to internal key-management systems and research into supporting schemes such as ML-DSA within MPC infrastructure. The company tasked the advisory board with assessing quantum developments, publishing recommendations and responding to major technical advances.
Other custodians have started testing one possible route. In June, BitGo tested quantum-safe MPC with Silence Laboratories using an ML-DSA-based protocol integrated into BitGo’s custody platform. The simulation retained distributed key control, policy checks, and separation of duties, according to the companies.
ML-DSA is included in FIPS 204, a post-quantum digital signature standard published by the U.S. National Institute of Standards and Technology. Lindell’s comments indicate that Coinbase wants an architecture capable of handling schemes beyond ML-DSA if Bitcoin or another network chooses a different design.
Hardware modules could provide a custody fallback
To reduce its dependence on MPC compatibility, Coinbase is exploring a backup design built around programmable Hardware Security Modules, according to Lindell.
HSMs are physically protected devices used to store cryptographic material and perform sensitive operations. Under the architecture being considered by Coinbase, private keys would remain encrypted using post-quantum cryptography and would be assembled only inside secure HSMs.
Containing the complete key within the protected device would allow the custodian to work with signature schemes that cannot be divided through conventional MPC. Programmable modules could also give Coinbase room to add support as blockchain developers settle on new standards.
Lindell did not provide a completion date, saying the technical work could take time. Once the system is finished, however, he expects Coinbase to operate without having to predict which post-quantum scheme each network will choose.
“I will be able to say, I can support any scheme,” Lindell said.
Physical security becomes more important under the proposed model because the full key would temporarily exist inside an HSM. Coinbase would therefore need the modules to perform signing without exposing the key to outside software or operators.
The approach would not require Coinbase to abandon MPC for signature schemes that support it. Instead, the HSM architecture would serve as another custody method when a network’s chosen cryptography cannot work with distributed key generation and signing.
Bitcoin has not approved a quantum migration plan
Bitcoin currently uses elliptic-curve cryptography, and no publicly demonstrated quantum computer can derive its private keys from exposed public keys. Researchers and industry groups have still called for early preparation because changing Bitcoin’s security model would require software development, testing, wallet upgrades, and network consensus.
Crypto.news reported in June that Coinbase’s advisory board urged Bitcoin developers to begin creating migration tools before a cryptographically relevant quantum computer exists. The board estimated that about 1.7 million BTC sit in older pay-to-public-key addresses with exposed public keys, while address reuse could place as many as 5 million BTC within a future risk category.
The advisory board did not recommend freezing, burning, or leaving vulnerable coins available to a future attacker. It said Bitcoin’s community should decide through its consensus process how to treat coins that remain in older address formats after a migration deadline.
Draft proposals are examining separate parts of the problem. BIP 360, known as Pay-to-Merkle-Root, would remove Taproot’s quantum-vulnerable key-path spending option, while BIP 361 describes a phased retirement of legacy ECDSA and Schnorr signatures after Bitcoin gains a post-quantum output method.
Neither proposal has been activated. A recent migration assessment also found that SHRINCS, an experimental hash-based signature design under discussion, remains an unnumbered draft requiring further review and a completed security proof.
For U.S. investors, Coinbase’s preparations concern assets held through regulated investment products as well as coins stored by direct institutional clients. Spot Bitcoin and Ethereum ETF investors do not control the private keys behind fund holdings; those keys are managed by custodians selected by the issuers.
Coinbase’s ability to support multiple signature schemes could become relevant if Bitcoin, Ethereum, or another network used by a U.S.-listed fund adopts new cryptography. Any blockchain migration would still depend on network rules and action by users, wallet providers, exchanges, custodians and fund operators rather than a decision by Coinbase alone.
The London Company, an investment management company, released its second-quarter 2026 investor letter for its “Small Cap Strategy.” U.S. equities rebounded in the quarter, driven by AI infrastructure spending and positive earnings. The letter can be downloaded here. Despite this optimism, rate outlook uncertainty persisted. Technology, previously weak, surged to lead the market, especially in semiconductors, while energy declined as oil prices fell. Small caps outperformed large caps, with momentum and volatility factors leading, although quality and yield were headwinds for portfolios. The London Company Small Cap portfolio increased 12.9% during the quarter, underperforming the Russell 2000 Index’s 21.5% gain, primarily due to stock selection issues. The firm remains confident in the durable, high-quality businesses for attractive long-term compounding. Please review the Fund’s top five holdings to learn more about its key selections for 2026.
In its second-quarter 2026 investor letter, London Company Small Cap Strategy highlighted Murphy USA Inc. (NYSE:MUSA). Murphy USA Inc. (NYSE:MUSA) engages in marketing of retail motor fuel products and convenience merchandise. On September 21, 2026, Murphy USA Inc. (NYSE:MUSA) closed at $508.98 per share. Over the past month, Murphy USA Inc. (NYSE:MUSA) declined 6.49%, but its shares are up 29.72% over the past year. Murphy USA Inc. (NYSE:MUSA) has a market capitalization of $9.35 billion, and its stock has traded within a 52-week range of $349.83 to $636.05.
London Company Small Cap Strategy stated the following regarding Murphy USA Inc. (NYSE:MUSA) in its Q2 2026 investor letter:
“Reduced: Murphy USA Inc. (NYSE:MUSA) – We trimmed MUSA after the stock rallied on fuel margin strength, which is inherently cyclical and difficult to sustain at current levels. The core thesis and our long-term conviction remain intact, and we redeployed proceeds into additional opportunities within the portfolio.”

Murphy USA Inc. (NYSE:MUSA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 40 hedge fund portfolios held Murphy USA Inc. (NYSE:MUSA) at the end of the second quarter, down from 41 in the previous quarter. While we acknowledge the potential of Murphy USA Inc. (NYSE:MUSA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you’re looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.

New Boxing Ring Makes Competitive Debut At Akwa Ibom Sports Festival

LARRY KUDLOW: Getting rid of the IRGC and the Houthis is better than a Diesel price control ban

Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike

Weekend Open Thread – Corporette.com

Weekend Open Thread: Talbots – Corporette.com

Memory prices are slowing because buyers ran out of money

MONEY MONEY (Full Video): Yo Yo Honey Singh, Ajay Devgn, Jacqueline F, Riteish D | Bhushan K |RAID 2

Guess The Crypto Millionaire (ft. Brez)

This is why you need financial stability #finance #women #independence #careergrowth
-
 Fashion5 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech3 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World5 days ago
Circle launches Arc Studio AI agent for building onchain apps
-

 Crypto World3 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-
 NewsBeat5 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World5 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World24 hours ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-

 Crypto World6 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Crypto World5 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World7 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Tech2 days ago
Google’s $899 Googlebook is a bet that you’ll buy a new laptop for Gemini
-

 Business3 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Crypto World3 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World5 days ago
World Money launches in 150+ countries with Stripe
-

 Tech4 days ago
Trump suggests rebranding AI with a new name, says he’s also creating an AI Force
-

 Crypto World5 days ago
Silver prices recover quickly, hitting weekly high today
-

 Tech6 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-
 Business20 hours ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-
 NewsBeat5 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-

 Crypto World2 days ago
Meta Jumps 11% As Muse Shines and Investors Show an Appetite for Advancing AI
You must be logged in to post a comment Login