
Business
Phoenix Court wins NatWest and British Business Bank backing

The British Business Bank and NatWest have agreed to invest in funds run by Phoenix Court, the UK venture capital firm, in a deal its co-founder described as a “watershed moment” for domestic investment in start-ups.
The state-backed lender will commit £50m. NatWest, HSBC and M&G are investing alongside it and did not disclose the size of their commitments, but said the total would run to “several hundreds of millions”. It is the first time NatWest has invested in a venture capital fund. HSBC and M&G have backed earlier Phoenix Court funds.
Saul Klein, co-founder of Phoenix Court, said: “The UK innovation economy is absolutely steaming ahead. This is a watershed moment to have four major institutions, including some of the high street banks, coming together to demonstrate the scale of the opportunity. Hopefully this is the moment when we can start to see more domestic capital crowding in, and more British allocators backing our innovation economy.”
UK start-ups raised $17bn in the first half of this year, according to HSBC, more than France, Germany and Sweden combined. HSBC’s figures show only 30 per cent of the capital in funding rounds above $100m came from the UK, falling to 16 per cent in rounds above $250m, as shown in the record half-year funding figures.
“It’s not as if the capital isn’t there, but we would love more of that capital to be domestic,” Klein said. “It’s a real shame that the people benefiting from the growth of our innovation economy historically have not been British savers, or British beneficiaries.”
Klein, who has previously urged UK pension funds to back domestic tech scale-ups, said the fund would aim for a threefold return. It will mainly target the capital shortfall at the scale-up stage, but will look across all growth phases.
Paul Thwaite, chief executive of NatWest, said capital was not the only problem for start-ups, and that large investors could also provide “the expertise and networks that innovative businesses need to grow”.
“Too often, promising British businesses look overseas for the capital and support they need to reach the next stage,” Thwaite said. “If Britain wants to compete for the industries and jobs of the future, we need to get better at backing our most promising companies with the capital, connections and confidence to scale here in the UK.”
The British Business Bank was set up by the coalition government in 2014 to use state funds to support fast-growing businesses. The Labour government has raised its total financial capacity to £25.6bn, from £15.3bn, giving it a target of investing about £2.5bn a year. Ministers have told it to direct more than 60 per cent of its funds at scale-ups and given it more scope to invest alongside private-sector organisations. The bank has already put more than £600m directly into UK scale-ups.
Leandros Kalisperas, chief investment officer at the British Business Bank, said the announcement was “a milestone in the development of the BBB’s activity”, describing the bank as “a physical convener” as well as a deployer of capital.
The bank is also trying to co-ordinate a £1bn scale-up fund with leading pension funds. “Every week some of the largest pension funds in the country are coming together to consider how … to invest a billion pounds in scale-ups,” Kalisperas said. “That has never happened before.”
Institutional investors have been wary of start-ups and scale-ups because of their higher risk profile, regulatory barriers and a lack of expertise among investors. In May 2025, 17 workplace pension providers signed the voluntary Mansion House Accord, agreeing to invest at least 10 per cent of their funds in private markets by 2030. It followed the 2023 Mansion House Compact, which set a 5 per cent target.
Kalisperas, who previously worked in pension funds, said there were “many good reasons” why institutional investors had been slow to move into venture capital, and that there was “clearly so much more to do”. He said: “The institutional base in this country doesn’t know about venture.”
He said the bank needed to “showcase” its activities by “sharing our due diligence and information with domestic capital”. Of the reluctance to date, he said: “that’s almost the past.”

Amy Ingham
Amy Ingham is a reporter at Business Matters, covering UK business news with a focus on breaking news, business policy, late payments and insolvency. She joined the magazine in 2026 after completing the NCTJ Diploma in Journalism at Harlow College’s journalism school. Her recent reporting includes British Steel’s nationalisation and its impact on SME suppliers, the decline in late payments by large firms, and Insolvency Service director disqualifications. Reach her at aingham@cbmeg.co.uk.


Oracle Japan Q1 FY27 slides: cloud revenue surges 32%, margins expand
Available for over a year
The presidents of the world’s two biggest economies are meeting in Washington. Donald Trump and Xi Jinping meet at the White House amid tensions over Iran, Taiwan, artificial intelligence and international trade. Our North American business correspondent Samira Hussain and senior China correspondent Laura Bicker assess what both sides want from the visit and how the relationship between the two leaders could shape the outcome.
Presenter: Vishala Sri-Pathma
Producer: Gideon Long
You can email the team: businessdaily@bbc.co.uk
(Picture: U.S. President Donald Trump with Chinese President Xi Jinping in Beijing, May 2026. Credit: Kenny Holston/Pool via REUTERS)
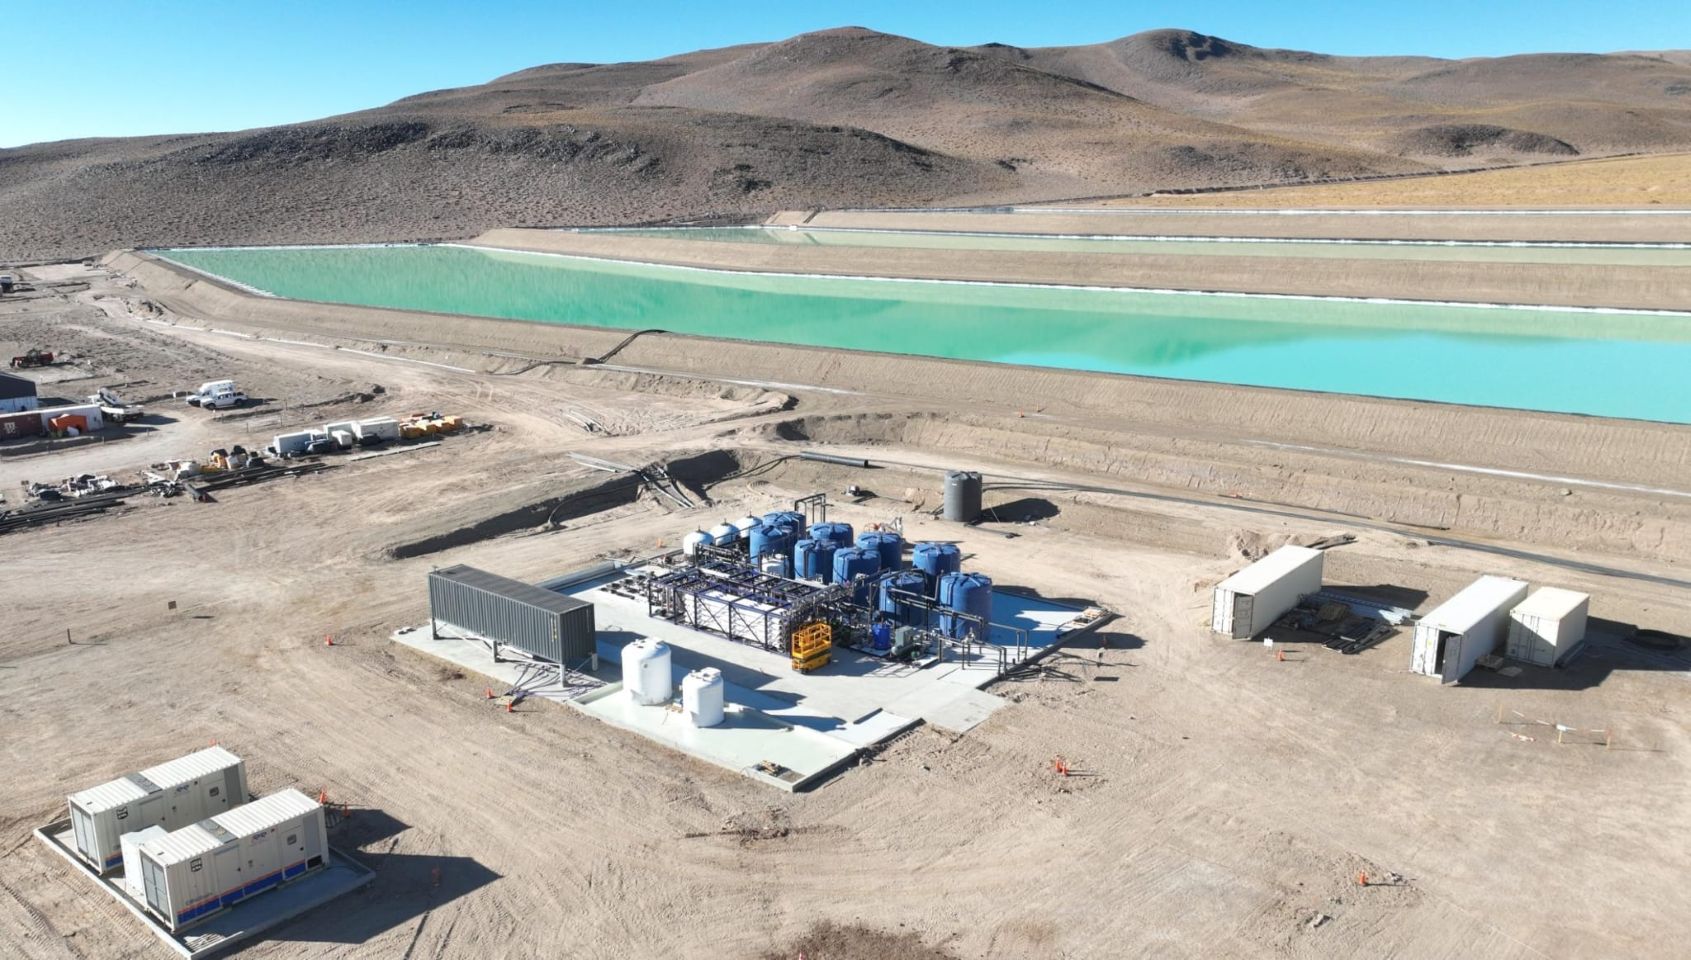
Galan Lithium boss Juan Pablo Vargas de la Vega says the company remains confident of meeting key upcoming targets at its flagship Hombre Muerto West lithium project in Argentina.
The purchase order, dated September 22, 2026, was received pursuant to a rate contract previously awarded by Zetwerk to Avantel. The order includes the manufacturing and supply of satellite communication equipment along with a one-year comprehensive onsite warranty.
According to the company’s regulatory filing, the order is a domestic manufacturing contract required to be executed by March 2027. The total order value is Rs 177.35 crore.
The company stated the order was not awarded by a related party, and the promoter or promoter group has no interest in the entity awarding the contract.
Share Price, Valuation and Technical Indicators
Following today’s surge, Avantel’s market capitalisation stands at around Rs 3,884 crore, while the stock’s 52-week high is Rs 215.

On the valuation front, Avantel has a P/E ratio of 224.29, while its Price-to-Sales (P/S) ratio stands at 15.08 and Price-to-Book (P/B) ratio at 11.39.
According to Trendlyne data, from a technical perspective, Avantel is currently trading below all eight key Simple Moving Averages (SMAs), indicating the stock remains below these widely tracked technical levels.FII Holding: In the June 2026 quarter, Foreign Institutional Investors (FIIs) increased their stake in Avantel to 1.54%, up from 0.55% in the previous quarter.
Quarterly Results (June 2026): Avantel reported revenue of Rs 71 crore in Q1 FY27, registering a 35.8% year-on-year growth. The company’s net profit rose 67.2% YoY to Rs 5 crore during the quarter.
Disclaimer: The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here
Retail AI solutions now span a wide range of jobs: some handle customer service, others forecast demand, others personalize product recommendations, and a few do all three at once. There’s no single “best” platform the right one depends on whether you’re running a single storefront or a multi-location chain, and whether your biggest pain point is inventory, customer support, or conversion. Below is a breakdown of the strongest retail AI solutions on the market right now, organized by what each one actually solves. New to the topic first? Our guide to AI in retail covers the underlying use cases and benefits before you start comparing platforms.
Retail AI Solutions at a Glance
1. Shopify Magic : Best for Small E-Commerce Retailers
Shopify’s built-in AI toolkit, Magic, is included across Shopify’s plans and covers product description generation, AI-assisted email marketing, and basic customer insights without requiring a separate integration. For a small retailer already running on Shopify, this is the lowest-friction way to start using AI – there’s no new platform to learn, and the features live directly inside the admin dashboard already in use.
Key features: AI product descriptions, AI-assisted email and ad copy, built-in customer and sales insights Pricing: Bundled into existing Shopify plans at no separate cost Best for: Store owners who want AI features without adding a new vendor to the stack.
2. Square for Retail : Best AI-Assisted POS for Brick-and-Mortar
Square’s retail point-of-sale system has layered in AI-driven inventory forecasting and sales analytics for physical stores. It’s particularly well suited to independent retailers who need forecasting and reporting but don’t have the volume or budget to justify an enterprise inventory platform.
Key features: AI-assisted inventory forecasting, integrated POS hardware, real-time sales analytics Pricing: Free core POS software; paid tiers add advanced inventory and reporting, plus standard payment-processing fees Best for: Independent and small-chain brick-and-mortar retailers.
3. Tidio : Best for AI-Powered Customer Service
Tidio combines live chat, AI chatbots, and multichannel messaging in a single dashboard built for small and mid-size retail and e-commerce teams. It’s positioned as an accessible entry point into AI customer service – a store can automate FAQs, order-status questions, and basic troubleshooting without hiring additional support staff.
Key features: AI chatbot (Lyro), live chat, unified multichannel inbox Pricing: Free plan available; paid tiers scale by conversation volume, with AI chatbot capacity often metered or gated to higher tiers – worth checking current plan details before budgeting, as this is a common source of surprise cost Best for: Retailers that want to automate routine customer service without an enterprise support stack.
4. Gorgias : Best AI Helpdesk for Shopify Stores
Gorgias is a support helpdesk purpose-built for Shopify merchants, with AI features that draft responses, tag and route tickets, and surface order data directly inside the support conversation. It’s a common next step for stores that outgrow basic live-chat tools and need a full support workflow.
Key features: AI-drafted ticket responses, automated tagging and routing, order data inside the conversation view Pricing: No free tier; paid plans scale by monthly ticket volume Best for: Shopify-based retailers scaling their support operations.
Salesforce’s retail AI, branded Einstein, powers product recommendations, predictive search, and dynamic content across Salesforce’s commerce platform. It’s built for retailers already operating on Salesforce’s broader CRM and marketing stack, and it’s most effective at that enterprise scale, where there’s enough customer data to make the personalization models genuinely predictive.
Key features: AI product recommendations, predictive search, dynamic personalized content Pricing: Enterprise, custom quote-based Best for: Larger retailers already invested in the Salesforce ecosystem.
6. Oracle NetSuite : Best Integrated ERP-Plus-AI Platform
NetSuite centralizes inventory, supply chain, and financial data in one system, with AI capabilities layered on top rather than bolted on as a separate tool. For a retailer whose data currently lives across disconnected platforms, NetSuite’s pitch is consolidation first, AI second – the forecasting and reporting only get more accurate once the underlying data is unified.
Key features: Unified inventory, finance, and supply chain data; AI-assisted demand and cash-flow forecasting Pricing: Custom quote-based, typically licensed per user and module Best for: Growing retailers dealing with fragmented systems across inventory, sales, and finance.
7. Blue Yonder : Best for Enterprise Demand Forecasting
Blue Yonder is a longstanding leader in supply chain and demand forecasting software, with deep integration options for large, multi-location retail operations. It’s generally regarded as the most accurate forecasting option at enterprise scale, though that comes with enterprise-level implementation timelines and cost.
Key features: Demand forecasting, supply chain planning, warehouse and transportation optimization Pricing: Enterprise, custom quote-based; typically a longer implementation timeline than mid-market alternatives Best for: Large chains with complex, multi-warehouse supply chains.
8. RELEX Solutions : Best for Mid-Market Demand Forecasting
RELEX offers similar demand-forecasting and inventory-optimization capabilities to Blue Yonder, but with a faster implementation path and a more accessible interface – making it a common choice for mid-market retailers that want forecasting accuracy without a multi-year rollout.
Key features: Demand forecasting, inventory and replenishment optimization, promotion planning Pricing: Custom quote-based; positioned as faster and less costly to implement than Blue Yonder Best for: Mid-size retail chains that need forecasting but not full enterprise infrastructure.
Dynamic Yield, now operating as part of Mastercard’s enterprise portfolio, specializes in on-site personalization, A/B testing, and algorithmic product recommendations for e-commerce retailers. It’s frequently used alongside a broader commerce platform rather than as a standalone system, layering testing and personalization on top of an existing storefront. It’s built for large-traffic retailers with a dedicated personalization or CRO team, not small or self-serve merchants.
Key features: On-site personalization, A/B testing, AI product recommendations, conversational commerce Pricing: Enterprise-only, custom annual contracts – not a self-serve or small-business product Best for: E-commerce teams that want to systematically test and personalize the on-site experience.
10. Algolia : Best for AI-Powered Site Search
Algolia focuses specifically on search and product discovery – using AI to rank and surface products based on relevance, behavior, and intent rather than exact keyword matches. For retailers with large catalogs, a weak on-site search function is a common, quietly expensive source of lost conversions, and Algolia is one of the more established tools built to fix it.
Key features: AI-ranked site search, product discovery, personalized search results Pricing: Free tier for low search volume; paid tiers scale with search requests and catalog size Best for: Retailers with large product catalogs where search quality directly affects conversion.
11. Lightspeed Retail : Best All-in-One POS with Built-In AI Insights
Lightspeed combines point-of-sale, inventory, and reporting in one platform, with AI-driven analytics for sales trends and stock levels built into the core product rather than sold as an add-on. It’s aimed at independent and multi-location retailers that want forecasting and reporting without stitching together separate tools.
Key features: Integrated POS and inventory, AI-driven sales and stock analytics, multi-location reporting Pricing: Tiered monthly plans based on features and number of locations Best for: Independent retailers and small chains that want POS and AI insights in a single system.
Dynamics 365 brings AI-assisted forecasting, customer insights, and store operations tools into Microsoft’s broader business platform, with Copilot layered in for natural-language reporting and task automation. It’s the natural fit for retailers already running on Microsoft’s productivity and data tools, since the AI features draw directly on data already inside that ecosystem.
Key features: AI-assisted forecasting, Copilot natural-language reporting, integrated store operations tools Pricing: Per-user monthly licensing; total cost scales with the modules added Best for: Retailers already standardized on Microsoft 365 and Azure.
How to Choose the Right Retail AI Solution
With this many options, the deciding factors tend to come down to a short list:
- What problem are you actually solving? Forecasting, customer service, personalization, and loss prevention are different problems with different tools – start with the pain point, not the platform.
- Does it integrate with what you already run? A powerful AI tool that doesn’t connect cleanly to your existing POS, CRM, or inventory system will create more manual work, not less.
- What’s the realistic implementation timeline? Enterprise platforms like Blue Yonder or Salesforce deliver strong results but take longer to roll out than lighter tools like Tidio or Shopify Magic.
- Is the pricing model built for your size? Several tools on this list scale their pricing by usage or store count, which matters more for a growing retailer than a flat enterprise fee.
Pricing and features for AI platforms shift quickly – confirm current plans and integrations directly with each vendor before making a final decision.
The Bottom Line
There’s no single best retail AI solution, only the best one for the specific problem in front of you. Smaller retailers are usually better served starting with a tool built into a platform they already use, like Shopify Magic or Square, before evaluating standalone platforms like Salesforce or Blue Yonder that require more setup and budget to justify.
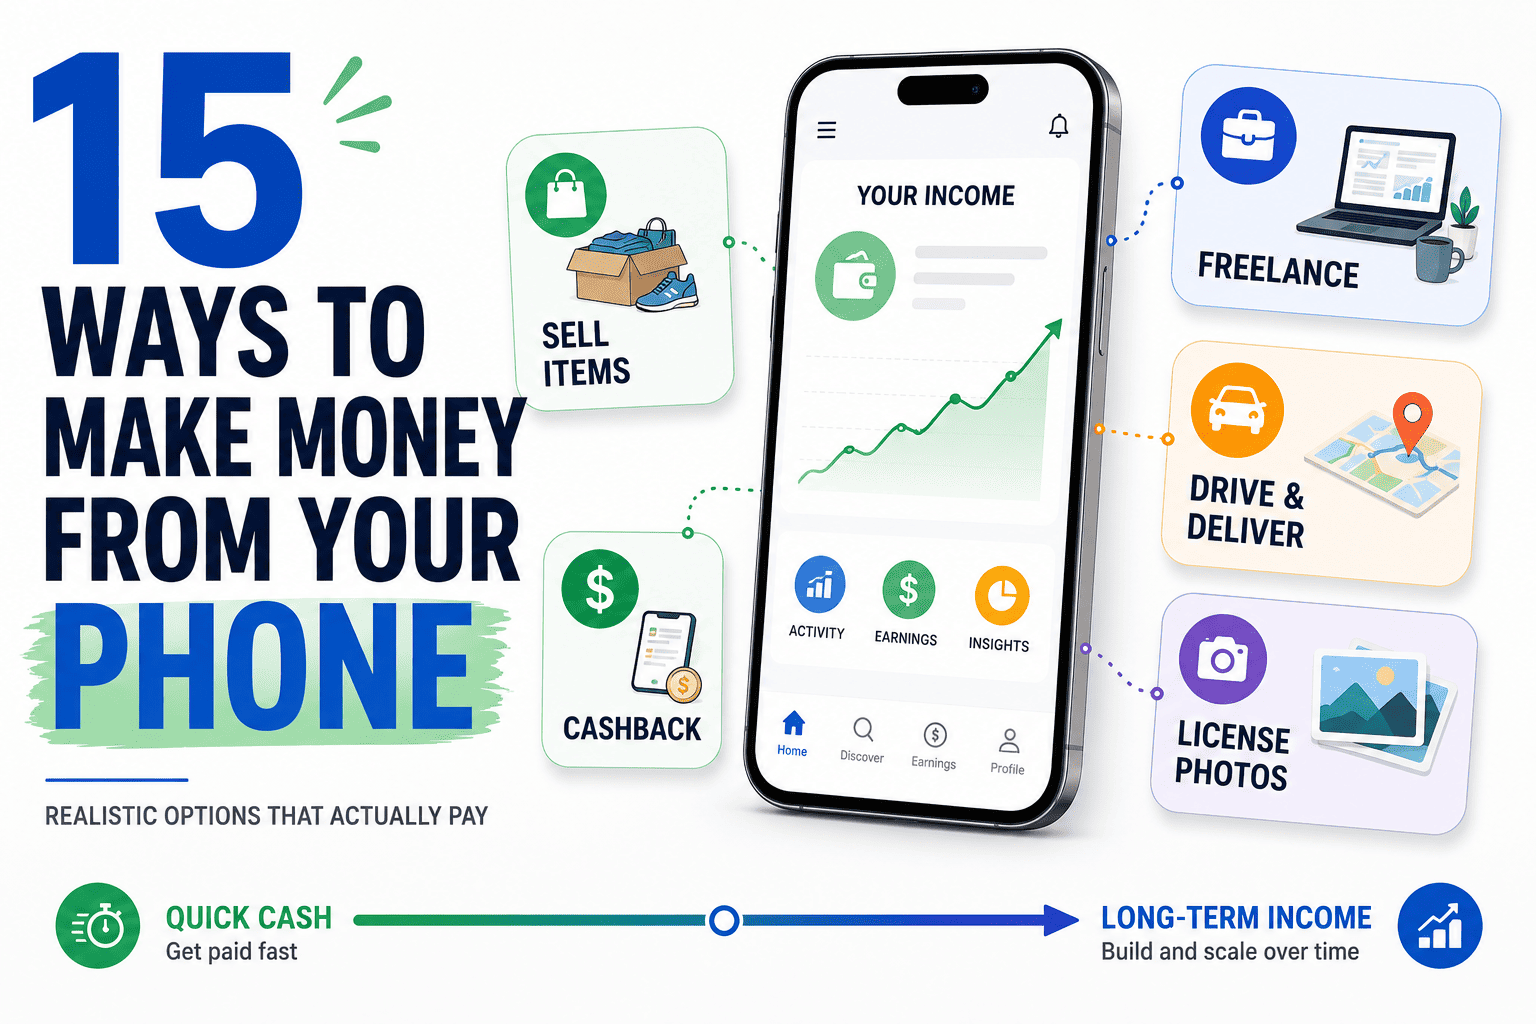
Quick answer: The most reliable ways to make money from your phone are reselling apps (fastest cash, lowest effort), cashback apps (small but genuinely passive), and freelance platforms (highest long-term earning ceiling). Survey and micro-task apps are legitimate but pay far less than most marketing promises – plan on $20–$80 a month, not $50 an hour.
Roughly one in six American adults has ever earned money through an online gig platform, according to Pew Research Center, so this isn’t a fringe activity, it’s become a normal way to supplement income. But “normal” doesn’t mean “equally worth your time,” which is the point of this guide.
Search “make money from your phone” and you’ll find lists promising 28, 40, even 46 different methods. Most of those lists pad their word count with app-testing gigs that pay $0.30 a task and “opportunities” that require you to first buy something. This guide cuts that down to 15 methods that produce real, verifiable income, along with what you should actually expect to earn from each one, because the gap between marketing copy and reality is where most people waste their time.
None of these will replace a full-time salary overnight. A few of them, done consistently, can become a meaningful second income stream. The rest are better thought of as ways to convert spare minutes into spare cash.
The quick list
- Sell items you already own
- Take paid surveys
- Stack cashback apps on purchases you’re already making
- Drive or deliver through gig-economy apps
- Freelance an existing skill
- Get paid for user testing and feedback
- License your photos and videos as stock content
- Launch a print-on-demand shop
- Create short-form video content
- Try affiliate and creator-commerce links
- Rent out things you’re not using
- Pet sit or dog walk through a marketplace app
- Pick up local task-based gig work
- Transcribe or caption audio and video
- Tutor or coach online
A quick word on scams
Because this space attracts so much hype, it also attracts a disproportionate number of scams. The FTC has specifically warned about “task scams,” where an app shows a fake, ever-increasing earnings balance and then asks you to deposit your own money often in crypto to “unlock” a withdrawal. Its broader guidance on avoiding side-hustle scams is worth a skim before you hand any app your bank details: research the company first, and treat any offer promising big money for minimal effort as a red flag.
Here’s how each one actually works, and what it realistically pays.
1. Sell items you already own
The lowest-effort entry on this list is also the fastest to cash out: list what’s sitting unused in your closet or garage on a resale app.
Which app you use matters more than it used to, because the fee structures have diverged. Poshmark charges a flat 20% commission. Mercari takes about 10%, plus a buyer-side processing fee. Depop currently charges 0% seller commission in the US, though that’s worth double-checking before you build a shop around it, since eBay is in the process of acquiring Depop and fee structures tend to shift after an acquisition closes. For general household items, electronics, and anything outside of fashion, Mercari or eBay typically finds a wider buyer pool than the fashion-focused Depop or Poshmark.
Realistic income: Highly variable, but sellers who list consistently across two or three platforms report 30–50% higher monthly revenue than single-platform sellers, since different apps skew toward different buyers.
2. Take paid surveys
Survey apps are the most oversold item on almost every “make money” list, so it’s worth setting expectations before you download anything. Legitimate platform Swagbucks, Survey Junkie, Toluna, InboxDollars, and the invite-only Pinecone Research – pay real money, but the hourly rate is closer to pocket change than a side job.
Realistic income: Casual users earn roughly $20–$80 a month running two or three apps for 15–30 minutes a day. Academic-style research platforms like Prolific occasionally pay closer to $10–$15 an hour for longer studies, but availability is inconsistent. Treat anything promising more than that as a red flag.
3. Stack cashback apps on purchases you’re already making
Cashback apps don’t ask you to do anything new, they pay you a small percentage back on spending you’d do regardless. The category has consolidated around a handful of reliable names: Rakuten for online shopping (1–10% at most retailers, paid quarterly), Ibotta and Checkout 51 for grocery receipt-scanning, Fetch for a lower-effort version of the same thing, and Upside for gas station cashback.
The real value comes from stacking. Scanning the same grocery receipt into both Ibotta and Fetch, on top of a cashback credit card, can turn a $100 grocery trip into $15–$20 of combined rebates.
Realistic income: $10–$40 a month for casual use; up to a few hundred dollars a year for households that shop deliberately around active offers.
4. Drive or deliver through gig-economy apps
Uber, DoorDash, and Instacart remain the three largest platforms for phone-based driving and delivery work, and all three let you work whenever your schedule allows. Pay varies significantly by city, time of day, and vehicle costs, gas, maintenance, and depreciation eat into take-home pay more than most new drivers expect.
We’ve covered the earnings breakdown for delivery apps specifically, base pay, tips, and how the economics compare across platforms in our dedicated delivery-apps earnings guide, since it deserves more space than a single list entry.
Realistic income: Wide range depending on market and hours worked; expect this to require the most active time of anything on this list, in exchange for the highest per-hour ceiling.
5. Freelance an existing skill
If you already have a marketable skill like writing, graphic design, bookkeeping, video editing, virtual assistance – Fiverr and Upwork both have functional mobile apps that let you message clients, deliver work, and manage payments from your phone. This won’t replace a laptop for the actual work in most cases, but it’s enough to land clients, negotiate scope, and handle client communication on the go.
Realistic income: The most scalable method on this list. Beginners often start with $15–$30 per small gig; established freelancers with a portfolio and reviews can charge professional day rates for the same skill.
6. Get paid for user testing and feedback
Companies pay for real people to test websites, apps, and prototypes and record their reactions. UserTesting and similar platforms typically pay a flat rate often $10–$60 per completed test, depending on length and complexity. The catch is availability: tests are assigned based on your demographic profile, and you may go days without matching one.
Realistic income: $20–$100 a month for occasional testers; higher for those who qualify for longer paid research studies.
7. License your photos and videos as stock content
If your phone camera is decent, apps like Foap, EyeEm, and Snapwire let you upload photos directly from your phone and earn a royalty typically 20–50% of the license fee every time someone buys one. Foap also runs brand-sponsored “missions” with fixed cash prizes for the winning submission, and EyeEm distributes accepted photos to Getty Images for additional reach.
Realistic income: Casual contributors earn roughly $50–$300 a month with a growing portfolio; income scales with volume and how commercially useful the subject matter is (business, lifestyle, and diversity-representative photos tend to outperform scenery).
8. Launch a print-on-demand shop
Print-on-demand [POD — a model where products are only manufactured after a customer orders, so you never hold inventory] lets you design custom products t-shirts, mugs, phone cases and sell them online without upfront cost. Printify’s mobile app covers the core workflow: browsing the product catalog, uploading a design, previewing mockups, and connecting the shop to an online store.
Realistic income: Highly dependent on marketing and niche selection; this is closer to running a small business than a quick side gig, with income potential that scales well beyond the rest of this list if a design or niche catches on.
9. Create short-form video content
TikTok’s Creator Rewards Program pays eligible creators based on video performance rather than a flat pool, which was the old model under the discontinued Creator Fund. To apply, you’ll generally need at least 10,000 followers and 100,000 video views in the past 30 days, an account in good standing, and videos of at least 60 seconds. Payout works out to roughly $0.40–$1.20 per 1,000 qualified views [RPM — revenue per mille, or earnings per 1,000 views], depending on niche, audience location, and engagement.
We’ve written a more detailed walkthrough of building a TikTok income stream including strategy for reaching the follower threshold in our TikTok money-making guide, since the mechanics deserve their own space.
Realistic income: Meaningful only past the eligibility thresholds; below that, LIVE gifts and brand partnerships are more accessible starting points than platform payouts.
10. Try affiliate and creator-commerce links
Once you have any kind of audience – a TikTok following, an Instagram page, or even a group chat people trust for recommendations – affiliate links let you earn a commission on products you point people toward. Amazon’s Influencer Program and platforms like LTK (formerly LikeToKnowIt) or ShopMy are built specifically for mobile-first creators to build shoppable link pages.
Realistic income: Negligible without an existing audience; scales directly with trust and reach once you have one.
11. Rent out things you’re not using
Apps like Turo let you rent out a car you’re not driving every day, while apps like Neighbor connect people with unused garage or storage space to renters who need it. Both operate on the same principle as home-sharing platforms, applied to smaller assets.
Realistic income: Highly asset-dependent; a car in a high-demand market can generate meaningful monthly income, while storage space rental tends to produce smaller, steadier amounts.
12. Pet sit or dog walk through a marketplace app
Rover and Wag connect pet owners with sitters and walkers nearby, with everything booking, messaging, and payment handled through the app. This is one of the few entries on this list with genuinely flexible, set-your-own-hours scheduling.
Realistic income: Typically $15–$25 per walk or $25–$75 per overnight stay, depending on market and the sitter’s ratings.
13. Pick up local task-based gig work
TaskRabbit and similar apps connect you with people who need help with furniture assembly, moving help, minor home repairs, or errands. Pay is set per task or hourly, and you choose which jobs to accept.
Realistic income: Varies by skill and local demand; taskers with in-demand skills (furniture assembly, handyman work) tend to out-earn general errand-runners.
14. Transcribe or caption audio and video
Rev and GoTranscript both pay per audio minute transcribed or captioned, and both have mobile-friendly workflows for claiming and submitting short jobs. This is genuinely a phone-compatible task for short clips, though longer transcription work is still easier on a full keyboard.
Realistic income: Roughly $0.30–$1.10 per audio minute depending on the platform and job type, which translates to modest hourly pay for fast, accurate transcribers.
15. Tutor or coach online
If you have subject-matter expertise, a language, a school subject, a musical instrument, test prep – apps like Preply and Wyzant connect you with students for paid video sessions, bookable and manageable from your phone.
Realistic income: Typically $15–$40 an hour depending on subject and experience, with established tutors commanding more once they’ve built a review history.
More ways to earn (smaller payouts, still legitimate)
The 15 methods above are the ones worth building a routine around. The methods below are lighter-touch, smaller, more passive amounts, but still real and worth knowing about if you want to round out the list.
16. Refer friends to apps you’re already using
Many of the apps already covered in this guide – cashback apps, survey apps, delivery apps offer a cash or credit bonus for referring someone who signs up and completes a first action. It costs nothing beyond sharing a link.
Realistic income: $5–$20 per successful referral; adds up mainly for people with a genuinely large network, not as a standalone strategy.
17. Get paid for walking or exercising
Apps like Sweatcoin, StepBet, and HealthyWage convert daily steps or fitness goals into cash, gift cards, or wagered payouts. These reward activity you might be doing anyway, rather than paying a real hourly rate.
Realistic income: A few dollars a month in most cases; HealthyWage-style wager formats can pay more but require putting your own money on the line first.
18. Join a research panel that pays for anonymized usage data
Market research firms – Nielsen’s consumer panels are the best-known example – pay a small amount for permission to passively track anonymized app or browsing usage in the background. This is the most hands-off method on this list, but it’s worth being clear-eyed about the trade-off: you’re being paid for data access, not a task, so read what’s actually being collected before opting in.
Realistic income: Typically $5–$15 a month or occasional gift cards; not meaningful as a standalone income source.
19. Round spare change into automatic micro-investments
Apps like Acorns round up your everyday purchases and invest the difference. This isn’t really “earning” money from your phone – it’s automating small, regular investing, and like any investing, the balance can go down as well as up. It’s worth including on this list only with that distinction clear: this is a savings habit, not guaranteed income, and it’s worth talking to a financial advisor before treating it as an income strategy rather than a savings one.
Realistic income: Not applicable in the same sense as the rest of this list — outcomes depend on market performance, not effort.
20. House-sit or plant-sit through a marketplace app
Platforms like TrustedHousesitters connect homeowners who need someone to watch their house (and often pets or plants) while traveling with people willing to stay there for free or for a fee.
Realistic income: Often non-cash (free lodging) rather than a fee; occasional paid arrangements exist but are less common than the unpaid house-sitting-for-lodging model.
21. Sell unused gift cards for cash
Sites and apps like CardCash and Raise buy unwanted gift cards at a discount to face value, which is still better than letting them expire unused in a drawer.
Realistic income: Typically 70–90% of the card’s face value, paid out once the card is verified.
22. Rent out a driveway or parking space
In cities with limited parking, apps like Neighbor also list parking spaces and driveways alongside storage space, connecting owners with drivers who need a spot.
Realistic income: Modest and highly location-dependent; most valuable in dense urban areas near event venues, stadiums, or transit hubs.
23. Get paid to recycle old electronics
Kiosk networks like ecoATM pay cash on the spot for old phones and other devices, based on condition and current resale demand.
Realistic income: One-time payout per device, not a recurring income stream, but a fast way to turn a drawer of old phones into cash.
Getting started without wasting time
The apps on this list fall into two categories: ones that pay for time (surveys, testing, transcription, gig driving) and ones that pay for an asset you already have (unused items, a spare room in your camera roll, a skill, an audience). The time-based methods are the fastest to start and the easiest to quit; the asset-based ones take longer to build but scale further.
Most people who make meaningful money from their phone aren’t running all 15 of these at once – they’ve picked two or three that fit their schedule and their existing skills, and stuck with them long enough to build momentum.
Discovering The Next Generation Of Nasdaq Innovators

German institutes raise 2026 and 2027 economic growth forecasts
Business
Sebi board meeting: PMS rules overhaul, FPI commodity trades among key decisions to watch out
The board may take up around a dozen proposals, according to reports, many of which have already gone through the consultation route. The agenda comes at a time when the regulator is trying to widen market participation, reduce regulatory friction and deepen long-term capital pools, while keeping investor protection safeguards intact.
PMS overhaul in focus
One of the biggest proposals before the board is a revamp of Portfolio Management Services regulations. Sebi has proposed several changes to the PMS framework, including allowing discretionary portfolio managers to invest in pre-IPO securities and unlisted debt. Portfolio managers may also be allowed to invest in overseas markets.
A new MF-PMS category is also proposed. This would allow PMS products that invest only in mutual funds, with a lower entry barrier compared with regular PMS products.
The regulator has also proposed changes to derivative limits for discretionary PMS, qualification requirements for principal officers, net worth norms and the definition of related party. Another proposal would allow independent fund managers to operate under registered PMS players.
If cleared, the changes could widen the PMS market and give fund managers more flexibility in portfolio construction.
Also Read:Sebi weighs lower margins for longer-term derivatives as F&O losses stay high: Tuhin Kanta Pandey
Accredited investor pool may widen
The Sebi board is also expected to consider changes to the accredited investor framework. Under the proposal, individuals holding securities-market assets of Rs 5 crore and body corporates with securities-market assets of Rs 20 crore may qualify as accredited investors. This would be in addition to the existing income and net-worth criteria.
The move is aimed at expanding the pool of sophisticated investors who can access products such as AIFs with more flexibility. Sebi’s proposal indicates that the eligible accredited investor base could expand to around 4 lakh, compared with the existing AIF investor base of about 1 lakh.
Settlement rules
The board may also review Sebi’s proposed overhaul of settlement regulations. The draft framework seeks to simplify how settlement amounts are calculated. The regulator has proposed changes that could make settlement a more practical route in enforcement matters while retaining deterrence.
The proposed changes include lower values linked to the stage of proceedings in some cases, a more balanced treatment of mitigating and aggravating factors, and a revised approach to determining base amounts.
The draft also seeks to clarify how defaults are counted, how repetitive defaults are treated, and how wrongful gains or investor losses are dealt with. Wrongful gains may be factored only towards disgorgement rather than being counted again in the base amount.
Other proposals include lower additional amounts for refiling withdrawn applications, removal of surcharge for settling multiple proceedings, more standardised interest rates on disgorgement and a weighted-average method for interest calculation in cases involving many transactions.
Common ad code for Sebi-regulated entities
A common advertisement code for all Sebi-regulated entities may also come up before the board. The regulator has proposed replacing different entity-specific and exchange-specific advertisement codes with one unified framework. The proposal also seeks to move from mandatory prior approval to post-issue reporting within 24 hours.
Another important change is the possible permission for celebrity endorsements at the brand or entity level, subject to conditions and prior approval. The aim is to reduce regulatory overlap and bring consistency across regulated entities.
FPIs may get wider commodity access
Sebi may also consider allowing foreign portfolio investors to participate in physically settled non-agricultural commodity derivative contracts on recognised domestic exchanges. At present, FPIs are allowed in cash-settled non-agricultural commodity derivatives and commodity indices, except deliverable options contracts. The proposed change would allow them into non-cash-settled contracts, subject to safeguards.
The move is aimed at improving liquidity and institutional participation in India’s commodity derivatives market.
REITs and InvITs on agenda
The board may also take up proposals linked to REITs and InvITs. One proposal would allow REITs and listed InvITs to issue depository receipts backed by their units. This would give them a route to raise foreign capital through overseas exchanges. The framework may allow fresh DR issuance against new units as well as transfer of existing units by unitholders to foreign depositories. Indian residents and NRIs would not be eligible to hold these DRs.
Another proposal would allow REITs and InvITs to invest minority stakes in under-construction third-party projects within existing exposure limits. Sebi may also consider reducing the OFS cooling-off period and recognising remote common infrastructure as real estate.
The board may also deliberate proposals related to AIFs, certification requirements for associated persons, research analyst call recordings and vault manager regulations.
Disclosure: This article has been written by Podishetti Akash, who is not a SEBI-registered Research Analyst or an Investment Adviser. Podishetti Akash and her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.
Business
PB Fintech shares crash 30%, bloodbath wipes off Rs 26,200 cr from m-cap after IRDAI’s reform plans. What Citi and Jefferies are warning
PB Fintech shares breached multiple circuit limits, crashing 30% to trade at Rs 1,320.10 apiece on the NSE. The stock is on track to record its worst single-day plunge since listing in November 2021.
The sharp downturn has wiped out nearly Rs 26,200 crore from the company’s market capitalisation, dragging it down to Rs 61,087.99 crore.
Another insurance distributor, Turtlemint Fintech Solutions, saw its shares plunge 20% to Rs 109.04 apiece, hitting the lower circuit. The stock was headed for its steepest decline since listing in June.
The selloff has wiped out around Rs 803 crore from the newly listed company’s market capitalisation, pulling it down to Rs 3,211 crore.
Also read | Explained: Why PB Fintech, Turtlemint, SBI Life, HDFC Life and other insurance stocks tanked up to 26% on Thursday
The Insurance Regulatory and Development Authority of India (IRDAI) has proposed a major overhaul of the way insurers pay commissions to distributors, with limits to be linked to the type of product, distribution channel, size of the policy and the effort required to sell. The insurance regulator also plans to prohibit ‘dark patterns’ on insurance websites, including practices that require customers to provide personal details before accessing product features and pricing information.
Jefferies says proposed norms negative for distributors
Jefferies noted that IRDA’s distribution consultation paper proposes stricter Expense of Management (EOM) limits for insurers, and 1/2-⅓ rd commission cuts in health, term and motor insurance. Jefferies said this is a risk for PB Fintech and Turtlemint, noting 10% cut in new business commission rates translate to 10-12% fall in their earnings.
Also read: Irdai proposes big changes to insurance commissions; companies, agents may feel the pinch
“The scope for insurers to compensate distributors through opex is also limited, due to overall EOM caps and the regulator stating that any payments to distributors will be considered as commissions,” it added.
The international brokerage sees limited impact for SBI Life and LIC. It currently has a ‘Buy’ rating on the shares of PB Fintech and Turtlemint.
Citi on IRDAI’s proposed reforms
Citi said proposed commission caps could significantly tighten insurance distribution economics, ET Now reported, adding that the Wall Street major estimates distribution economics to compress 70-90% in several high margin categories if implemented as proposed.
Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.

Biggs Money “Bounce It” | On The Radar Performance

SlotCatalog payment methods: how the database maps 150 payment options
Oracle Japan Q1 FY27 slides: cloud revenue surges 32%, margins expand




-

 Fashion6 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech3 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World1 day ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-

 Crypto World5 days ago
Circle launches Arc Studio AI agent for building onchain apps
-

 Crypto World3 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-
 NewsBeat5 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World5 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World6 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Crypto World5 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Tech3 days ago
Google’s $899 Googlebook is a bet that you’ll buy a new laptop for Gemini
-

 Business3 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Crypto World3 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Tech5 days ago
Trump suggests rebranding AI with a new name, says he’s also creating an AI Force
-

 Tech6 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-
 Business1 day ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-

 Crypto World5 days ago
World Money launches in 150+ countries with Stripe
-

 Crypto World6 days ago
Silver prices recover quickly, hitting weekly high today
-

 Crypto World3 days ago
Bitcoin price holds above $81K as key catalysts line up
-
 NewsBeat6 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-

 Crypto World2 days ago
Meta Jumps 11% As Muse Shines and Investors Show an Appetite for Advancing AI
You must be logged in to post a comment Login