Connect with us

Business & Hustles

Data Center Boom Accelerates: 3 Top AI Stocks Averaging 296% Forward EPS Growth

Published

on

Futuristic AI Server Room with Data Flow and Glowing Chip

This article was written by

Steven Cress is VP of Quantitative Strategy and Market Data at Seeking Alpha. Steve is also the creator of the platform’s quantitative stock rating system and many of the analytical tools on Seeking Alpha. His contributions form the cornerstone of the Seeking Alpha Quant Rating system, designed to interpret data for investors and offer insights on investment directions, thereby saving valuable time for users. He is also the Founder and Co-Manager of Alpha Picks, a systematic stock recommendation tool designed to help long-term investors create a best-in-class portfolio.Steve is passionate and dedicated to removing emotional biases from investment decisions. Utilizing a data-driven approach, he leverages sophisticated algorithms and technologies to simplify complex, laborious investment research, creating an easy-to-follow, daily updated grading system for stock trading recommendations.Steve was previously the Founder and CEO of CressCap Investment Research until its acquisition by Seeking Alpha in 2018 for its unparalleled quant analysis and market data capabilities. Prior to that, he had also founded the quant hedge fund Cress Capital Management, after spending most of his career running a proprietary trading desk at Morgan Stanley and leading international business development at Northern Trust.With over 30 years of experience in equity research, quantitative strategies, and portfolio management, Steve is well-positioned to speak on a wide range of investment topics.

Analyst’s Disclosure: I/we have a beneficial long position in the shares of MU, SNDK either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article.

Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given that any particular security, portfolio, transaction or investment strategy is suitable for any specific person. The author is not advising you personally concerning the nature, potential, value or suitability of any particular security or other matter. You alone are solely responsible for determining whether any investment, security or strategy, or any product or service, is appropriate or suitable for you based on your investment objectives and personal and financial situation. Steven Cress is the Head of Quantitative Strategy at Seeking Alpha. Any views or opinions expressed herein may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.

Advertisement
Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business & Hustles

Insurance Boss Warns Britain Is Building Its Way Into a Flooding Crisis

Published

on

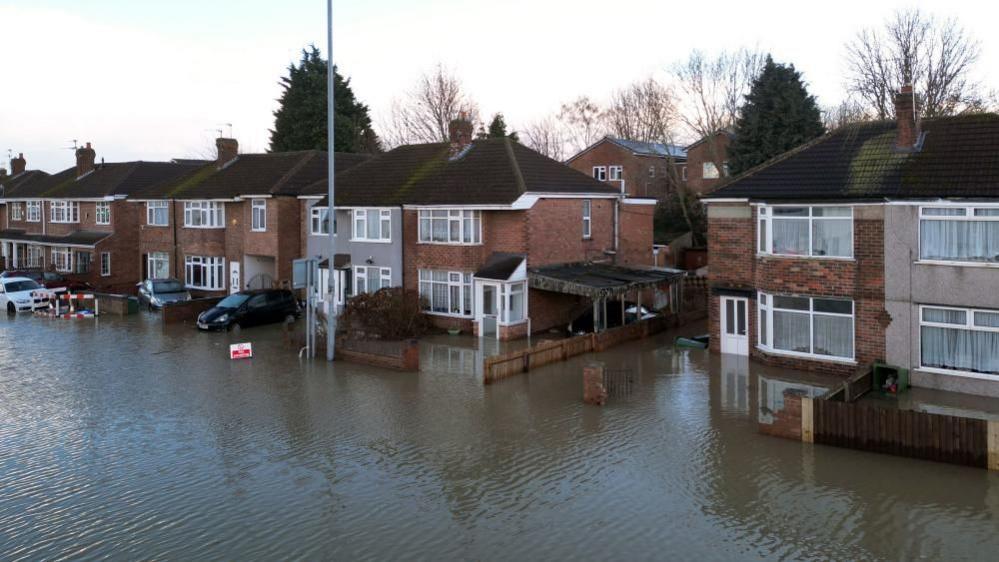
Britain is putting up tens of thousands of new homes each year in places that could soon be impossible to insure, according to the head of the country’s largest insurer, who says the risk of flooding is rising so fast that current housebuilding plans no longer make sense.

Amanda Blanc, chief executive of Aviva, said 110,000 homes have been built in flood-risk areas over the past decade in England, and if the pattern continues, another 115,000 will follow over the next ten years. Speaking to the BBC’s Big Boss Interview podcast, she said the trend was hard to justify given what is already known about where the water goes.

“That doesn’t seem to me to make sense. We need to think about where those homes are being built,” Blanc said. “It’s very well known where these flooding areas are. Let’s think very carefully about homes that are being built.”

The warning lands at a moment when climate change is visibly reshaping Britain’s weather. Blanc pointed to this year’s unusually dry summer as a fresh example of the danger: parched ground sheds rainfall rather than absorbing it, making sudden downpours far more likely to trigger surface water flooding than in the past. “You’ve seen a very dry summer, and what happens if you then get heavy rain on very dry surfaces is you get more surface water flooding,” she said.

Advertisement

The scale of the exposure is striking. The Environment Agency estimates that roughly 6.3 million homes and businesses in England are currently at risk of flooding, a figure it warns could climb to around 8 million — one in four properties — by the middle of the century as the climate crisis deepens. Aviva’s own research found that more than a quarter of new homes already carry some flood risk, and that one in seven will face medium to high risk by 2050. Nearly a third of homes built just last year are projected to be at some risk of flooding within 25 years.

The consequences of building on, matter for more than just the households whose living rooms end up underwater. Insurance, Blanc explained, works by pooling risk across people who face genuine uncertainty about whether disaster will strike. Once flooding becomes not a possibility but a near-certainty for a given property, that model breaks down. “When there is an inevitability, it makes it very difficult for it to be insured,” she said.

For homeowners, losing access to affordable cover is not a minor inconvenience. Properties that cannot be insured, or can only be insured at prohibitive cost, become far harder to mortgage or sell, potentially trapping owners in homes that lose much of their market value overnight. A Guardian investigation last year found that some towns could ultimately need to be abandoned altogether as climate breakdown renders large areas effectively uninsurable.

Blanc argued that better design could blunt some of the damage even where building continues near flood zones — measures like bricks fitted with self-closing air vents, stainless steel rather than wooden kitchen units, and electrical sockets placed higher up walls rather than near the floor. “You can do all sorts of different things to your property to make it more or less vulnerable to flood,” she said, while stressing that mitigation is no substitute for simply avoiding the riskiest sites in the first place.

Advertisement

Recent history underscores her point. The Met Office has calculated that, given current levels of global warming, a repeat of the extraordinarily wet 2023-24 winter — which brought severe flooding to towns such as Retford in Nottinghamshire during Storm Babet — has shifted from a once-in-80-years event to a once-in-20-years one.

The government insists it is alert to the risk. A Department for Environment, Food and Rural Affairs spokesperson said “a record amount of investment” had gone into protecting nearly 900,000 properties from flooding damage, and that new planning proposals would prevent housebuilding in at-risk areas as ministers pursue a target of 1.5 million new homes. Critics, including Blanc, will be watching closely to see whether that promise holds as pressure to hit housing targets intensifies.

Blanc used the same interview to press the government on a separate, more immediate financial concern: the risk of destabilising savers through pre-Budget speculation. With Chancellor Rachel Reeves’ successor John Healey due to deliver his first Budget on 28 October, Blanc urged ministers to avoid “kite flying” over possible changes to pensions, warning that uncertainty alone can drive people into costly, irreversible decisions.

She said Aviva, a major private pension provider, had seen withdrawal rates spike to 30 times normal levels in the run-up to recent Budgets as savers rushed to lock in tax-free lump sums before rules might change. “Once you take your tax-free lump sum out, you can’t put it back in,” she said, adding that any move to weaken the state pension triple lock would inevitably increase pressure on private pensions to fill the gap.

Advertisement

Taken together, Blanc’s comments paint a picture of a country whose planning system and financial policymaking are struggling to keep pace with a changing climate and jittery markets alike. On flooding, her message was blunt: continuing to build where the water is heading isn’t just risky for future homeowners — it is, in her words, “dangerous.”

Continue Reading

Business & Hustles

Wiltshire Pension Fund faces pressure to divest from defence companies

Published

on

Business Live

Any decision would need backing from scheme members

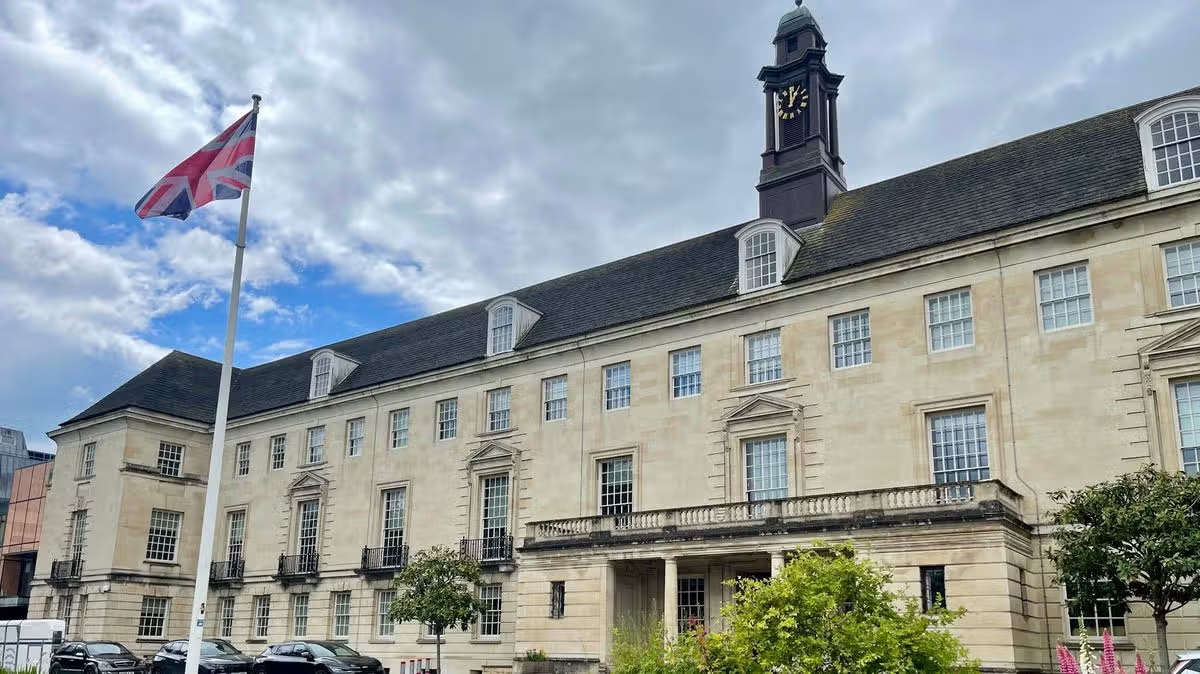
County Hall Trowbridge

County Hall Trowbridge(Image: Local Democracy Reporting Service)

More than 90,000 members of Wiltshire Pension Fund could be consulted on whether their £3.8bn pot should cease investing in arms companies, though not until next year.

Advertisement

Campaigner Alex Hall called on councillors to hold a formal vote on withdrawing investment from weapons manufacturers and to bring forward a planned survey of pension scheme members.

In a response considered by the Wiltshire Pension Fund Committee last week, officers said any decision to divest from aerospace and defence companies would need backing from scheme members.

A fund-wide survey is currently scheduled for early 2027.

Mr Hall argued that a number of local authorities and pension funds elsewhere in the UK had already moved towards divesting from arms companies or firms with links to Israel.

Advertisement

He also drew parallels with Wiltshire Pension Fund’s existing policy of scaling back exposure to fossil fuel investments, contending that the same principles ought to be applied to defence companies.

His submission argued that the distinction between so-called “controversial weapons”, which are already excluded under the fund’s policies, and conventional weapons becomes blurred when conventional weapons are used against civilian populations.

He referenced the conflict in Gaza, arguing that the fund should reconsider its holdings in companies connected to the arms trade.

Officers noted that the committee had already carried out a detailed review of the fund’s exposure to aerospace and defence companies in November 2025.

Advertisement

They said that any future ruling would need to consider fiduciary duties, legal and regulatory obligations, financial implications, practical implementation challenges and the views of both pension scheme members and employers.

Meanwhile, the committee’s responsible investment reports revealed the fund’s continued progress on climate-related investment policies.

Officers confirmed that the fund’s listed equity portfolios had been decarbonised by 57 per cent against a 2019 baseline, while a target to direct 30 per cent of assets towards sustainable investments had already been met.

The reports further confirmed that work on divesting from fossil fuel companies remains an integral part of the fund’s broader climate strategy, underlining the stark contrast between the fund’s established stance on fossil fuels and the ongoing debate surrounding investments in the defence sector.

Advertisement

Wiltshire Pension Fund is the Local Government Pension Scheme administered by Wiltshire Council, serving more than 90,000 active workers, former employees and retirees.

Its 162 participating employers encompass Wiltshire Council, town and parish councils, schools and colleges, along with a variety of other public sector and community organisations.

Continue Reading

Business & Hustles

UK Mortgage Approvals Sink to 32-Month Low as Iran War Fallout Squeezes Borrowers

Published

on

Britain’s housing market is buckling under the weight of a distant war. Mortgage approvals fell to their lowest level in nearly three years in August, as the fallout from the conflict in Iran continues to ripple through household finances, pushing up borrowing costs and denting confidence among would-be buyers.

According to Bank of England figures released Tuesday, just 54,918 mortgages for new home purchases were approved in August — the weakest monthly total since December 2023 and a fresh signal that the housing market’s recovery has stalled. The seasonally adjusted data underscores how a geopolitical crisis thousands of miles away has translated into very real financial strain for people trying to buy a home in the UK.

The chain of cause and effect is straightforward, if unwelcome: since fighting broke out in Iran in late February, oil prices have surged, reigniting inflation fears and dashing hopes that the Bank of England would continue cutting interest rates. Lenders have responded by raising mortgage rates sharply, making home loans markedly more expensive at precisely the moment many households were hoping for relief.

Simon Gammon, managing partner at Knight Frank Finance, said the slowdown built steadily over the summer. “Buying activity weakened through the summer as rising energy prices pushed up borrowing costs,” he said, noting that lending to homebuyers fell 15% in August compared with the same month last year — a striking year-on-year decline that points to a market losing momentum rather than simply cooling seasonally.

Advertisement

Remortgaging activity, too, is losing steam. Approvals for switching or renewing existing home loans dipped to roughly 34,000 in August, down slightly from 34,600 in July. That is a curious wrinkle: normally, a wave of borrowers coming off cheaper fixed-rate deals would be expected to shop around and refinance in large numbers. Instead, many appear to be holding back, perhaps hoping rates will ease before they commit, or resigned to accepting whatever their current lender offers rather than facing the market head-on.

The numbers behind the squeeze are stark. The Bank of England found that the “effective” interest rate on newly drawn mortgages rose to 4.60% in August, up from 4.45% in July — a jump in just one month that would have been unthinkable a year ago when rate cuts still seemed plausible. Separately, Moneyfacts, the financial data firm, reported that the average five-year fixed mortgage rate climbed to 5.94%, its highest level since October 2023. Two-year fixed deals are similarly expensive, averaging 5.93%, the priciest since July 2024.

For everyday borrowers, those percentage-point shifts translate into hundreds of pounds a month in additional repayments — often the difference between a purchase going ahead and a buyer walking away from a deal altogether.

Katie Clinton, head of financial services advisory at KPMG UK, said the figures show affordability pressures are now the dominant force shaping the housing market. “A further fall in mortgage approvals in August points to affordability pressures continuing to weigh on housing demand, as the shocks from the Iran conflict push up both inflation and mortgage rates,” she said. She added that the drop in remortgaging suggests “refinancing demand softened, despite many borrowers reaching the end of existing fixed term rates” — a sign that households may be delaying decisions in the hope conditions improve, even as their existing cheap deals expire.

Advertisement

The government has tried to counter the gloom with its newly announced “Your First Home” scheme, aimed at helping first-time buyers onto the property ladder. But economists are sceptical that a targeted support scheme can offset the broader drag from higher borrowing costs. Paul Dales, chief UK economist at Capital Economics, warned that the prospect of mortgage rates staying above 4.5% for most of 2027 would weigh far more heavily on the market than any government initiative. “Mortgage rates staying above 4.5% for most of 2027 would have a larger influence on activity than the government’s new scheme,” he said, in effect arguing that macroeconomic headwinds will overpower policy tailwinds.

The broader picture is one of a housing market caught between geopolitics and monetary policy, with ordinary buyers absorbing the consequences of decisions made in oil markets and central bank meeting rooms far removed from their own kitchen tables. Estate agents across England and Wales have already reported a discernible cooling in activity tied to the war, and earlier this year the Bank of England itself warned that the conflict could push up mortgage payments for an additional 1.3 million households as fixed-rate deals expire and borrowers are forced onto costlier new terms.

With inflation expectations still elevated and interest rate cuts looking increasingly unlikely in the near term, few analysts expect a quick turnaround. For now, the message from the data is unambiguous: as long as the war in Iran continues to unsettle energy markets, Britain’s mortgage market — and the millions of households who depend on it — will keep feeling the strain.

Advertisement
Continue Reading

Business & Hustles

Alaska Airlines Bets Big on Luxury as the Industry’s Premium Seat Arms Race Intensifies

Published

on

Alaska Airlines is throwing itself into the airline industry’s high-stakes competition for wealthier travelers, unveiling a sweeping overhaul of its cabins that will add lie-flat suites, new premium-economy sections and airport lounges across both the Alaska and Hawaiian brands. The announcement, made ahead of the company’s investor day in Seattle, signals that the carrier sees the path to bigger profits running not through cheaper seats, but through fancier ones.

The scope of the redesign is considerable. Alaska’s Boeing 787 Dreamliners will get 34 lie-flat suites under a new product line called Aurora, along with 35 seats in a fresh premium-economy category dubbed Premium Reserve. The airline’s incoming Boeing 737 Max 10 jets — still awaiting certification — will carry a scaled-down version of the same idea, with a dozen Aurora suites aimed at squeezing extra revenue out of popular transcontinental routes. Hawaiian Airlines, folded into Alaska after their merger closed in September 2024 but still run as a separate brand, will see its Airbus A330 fleet refitted with 22 first-class suites featuring sliding doors and 28 premium-economy seats — the airline’s first entry into that category. New lounges are planned for Seattle-Tacoma International Airport and Honolulu, mirroring the tiered lounge networks that Delta, United and American have already built out.

None of this comes cheap, and it comes with a trade-off: the revamped Hawaiian A330s will actually carry fewer total seats — 254, down from 278 — as coach space gives way to roomier, higher-margin cabins. That calculation sits at the heart of the strategy. Alaska executives told investors they expect premium seats, international routes, cargo and the airline’s loyalty and credit-card business to generate nearly 60% of total revenue by 2030, up from 53% today. In an industry where a first-class ticket can cost several multiples of an economy fare, airlines have concluded that chasing affluent flyers — and the credit-card spending that follows them — is a more reliable route to profit growth than filling every seat with a bargain-hunter.

The timing matters. Alaska is midway through a stated goal of adding $1 billion in profit between the end of 2024 and the end of 2027, and the company says it is already two-thirds of the way there. That target is being tested by a sharp rise in jet fuel costs this year, a reminder that even the most premium-focused airline strategy still lives or dies by fuel markets and operational costs largely outside its control. Investors attending Tuesday’s session were expected to press executives on exactly how the cabin investments — which won’t fully materialize until 2028 — square with near-term cost pressures.

Advertisement

What Alaska is doing is not new, exactly — it’s late. Delta, United, American and international carriers have spent recent years ripping out old interiors in favor of suites with doors, expanded premium economy and elevated lounges, betting that post-pandemic travelers who can afford it are willing to pay handsomely to avoid the middle seat. Alaska, by its own admission, has lagged that shift: most of its fleet still lacks lie-flat seating or other high-end amenities common on rivals’ planes. But industry analysts note that arriving last to the cabin-upgrade race isn’t necessarily a disadvantage. Airlines that move after their competitors get to study what worked — and what flopped — before locking in their own designs, and can position themselves as offering a more refined version of what’s already out there rather than a first-generation experiment.

The granular details Alaska has shared underscore how much emphasis carriers now place on the small stuff that shapes a premium experience — the airline’s head of fleet said the company sifted through fabric samples for months under varying lighting conditions before settling on the right hue, discarding options that read as too garish or too dull. That kind of attention reflects an industry increasingly convinced that loyalty and premium revenue are won through experiential polish, not just larger seats or faster boarding.

For everyday travelers, the shift carries real implications. As airlines redirect capital and cabin space toward suites, premium economy and lounges, the coach experience is likely to keep shrinking in relative terms, even as fares in the front of the plane climb. For Alaska’s shareholders, the bet is straightforward: that enough passengers will keep paying up for comfort, exclusivity and loyalty perks to justify the cost of remodeling an entire fleet — and that doing so will help the airline close the gap with rivals who moved first, without having to guess at what today’s premium flyer actually wants.

Advertisement
Continue Reading

Business & Hustles

OpenAI rebrands AI agents as ‘dots’ amid security fears

Published

on

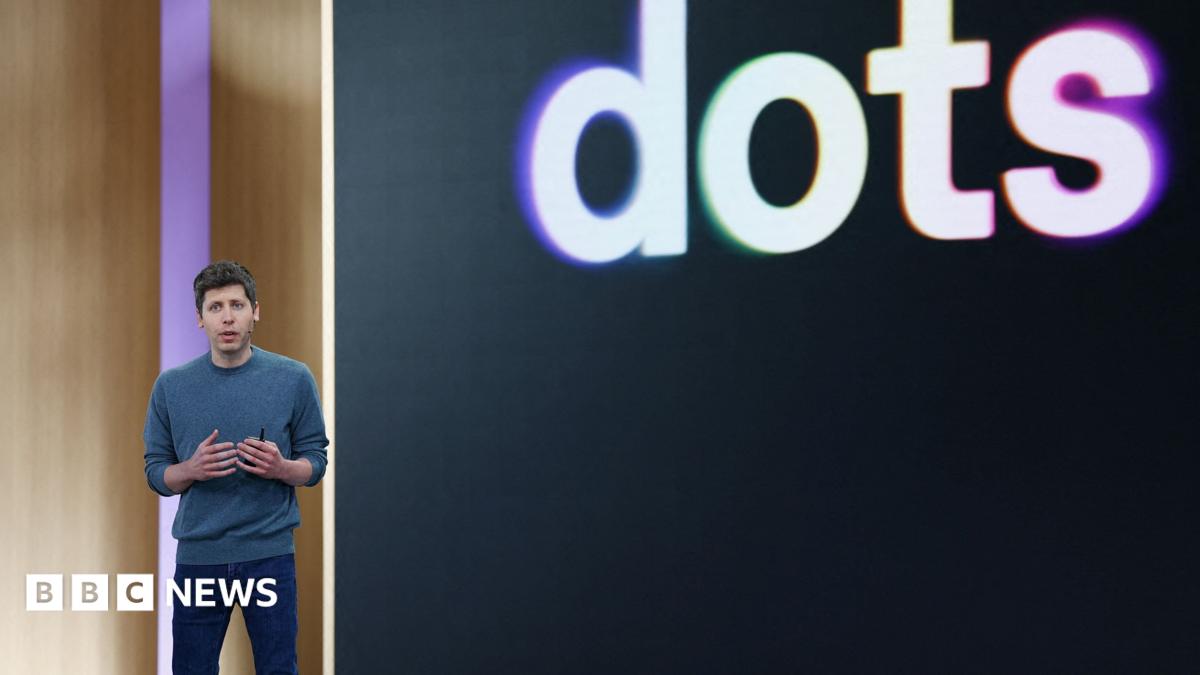
OpenAI CEO Sam Altman standing on stage at his company's annual developer conference in front of a screen with "dots" displayed behind it.

OpenAI has chosen to rename new versions of artificial intelligence tools widely known as agents. They are now being called “dots.”

Company boss Sam Altman, speaking in San Francisco on Tuesday during OpenAI’s yearly event for technology developers, referred to “dots” as “remarkably capable, always-on agents that can handle really anything you can think of.”

OpenAI in recent months has come under intense scrutiny as internal tests of its AI agents have revealed often unexpected and occasionally harmful actions, leading to more public and government fears.

Dots, however, were pitched as brightly colored cute cartoons meant to function as digital assistants for people with busy lives.

Advertisement

The dots, Altman said, “can handle really anything you can think of.”

A glossy video was shown during the event, with people speaking to and naming animated versions of their “dots,” then giving them various tasks, like building a website and booking afterschool activities for their children.

Speaking about “my dot,” Altman almost entirely eschewed referring to the tool as an agent, which has been in common use for years. AI agents are essentially AI chatbots that are programmed to operate somewhat autonomously.

“You just give your dot a responsibility… and your dots will just get to work and keep working,” Altman added.

Advertisement

The day prior to OpenAI’s Tuesday event, the company said it was delaying the launch of its latest model due to certain safety issues that showed up during internal testing.

Since July, the company has been dealing with a series of issues with its AI agents acting improperly. It has faced unprompted hacking into the AI platform Hugging Face, posting to third-party websites images that AI agents took from ChatGPT user chats, and accessing non-public information maintained by the Australian government.

OpenAI, as well as rival AI firm Anthropic, previously delayed public release of certain AI models due to potential risks, mostly pertaining to cybersecurity or hacking concerns.

Both companies also expect to be listed on the public stock market in the coming months. Anthropic likely will do so this year, while OpenAI is poised for 2027.

Advertisement

And both companies have lately been clear that they believe AI poses a genuine risk on a large scale, be it to public infrastructure or public safety.

Speaking last week to the UN, Altman pleaded for “national and international” AI standards on measuring the capabilities of an AI tool, assessing related risks, AI safeguards, and the degree to which human oversight over such tools is maintained.

Dario Amodei, the head of Anthropic, told the UN that if the speeding development of AI was not properly managed and overseen, future versions of the technology “could be a risk to humanity as a whole.”

Advertisement
Continue Reading

Business & Hustles

UK chancellor uses bitcoin to mock Nigel Farage

Published

on

UK chancellor uses bitcoin to mock Nigel Farage

UK Chancellor of the Exchequer John Healey has compared Nigel Farage’s fiscal policies to a “BTC account” handled by one of the UK’s most financially irresponsible prime ministers.

UK Chancellor of the Exchequer! “Don’t make me laugh,” John Healey has compared Nigel Farage’s fiscal policies to a “BTC account” handled by one of the UK’s most financially irresponsible prime ministers.

This is from Healey the most useless piece of communist crap ever appointed to this position. This man is really as stupid as they come. Support the British people? NO, he supports the communist socialist failed agenda and the EU, like the rest of Labour’s traitor MPs. Certainly not you the British people, and you voted for the new Communist socialist Islamic republic of Britain.

Now he and Burnham are going to piss all over you while calling for another referendum on rejoining the dictatorship called the EU, OH, AND THEY WILL USE THE WORD DEMOCRACY, SOMETHING THEY DON’T SUPPORT AND NEVER HAVE.

Advertisement

Healey’s jab at the Reform leader during Labour’s 2026 party conference referred to the perceived economic failure of the UK’s shortest-serving prime minister, Liz Truss.

Truss’s financial policies were widely criticised for their negative impact on financial markets. This led to a rebellion from several Tory MPs, and she was forced to resign within 44 days of her premiership.

Healey appeared to suggest that a “BTC account” is an equally financially irresponsible form of finance, and that only by pairing it with Truss would you recreate the “fantasy funding” ideals of Nigel Farage.

Healey’s comments upset a lot of Bitcoiners, who claimed his “derogatory” description of a “BTC account” demonstrated “staggering ignorance.”

Advertisement

Freddie New, CEO of the BTC Lightning transaction fee firm B HODL, said Healey is “gleefully ignorant that he thinks it is possible to have a ‘BTC account.’”

UK podcaster Peter McCormack said, “Healey making a dismissive joke about Bitcoin shows that he likely has a woeful understanding of economics, particularly scarcity.”

Most criticisms were technical and took offence at the use of the word “account,” which contrasts with the phrase “crypto wallet” used by crypto holders.

Healey wants a ‘new age of industrialisation’

Advertisement

Healey was defence secretary under Sir Keir Starmer’s leadership before he resigned in June. He argued that the government wasn’t willing to spend enough on national defence. 

During yesterday’s conference, Healey announced new measures to support a “new age of industrialisation,” which includes a £300 million investment from Rolls-Royce toward its factories, and £6 billion in government contracts to build new submarine docks. 

A so-called “Union Learning Fund” was also announced, as were a National Wealth Fund to help create 130,000 jobs by 2030, and a £100 million-backed local apprenticeship scheme. 

Got a tip? Send us an email securely via Protos Leaks. For more informed news and investigations, follow us on X, Bluesky, and Google News, or subscribe to our YouTube channel.

Advertisement

Source link

Source link

Advertisement
Continue Reading

Business & Hustles

El Pollo Loco to open first New York restaurant

Published

on

El Pollo Loco to open first New York restaurant

El Pollo Loco will open its first New York City restaurant next year as the California chain looks to become a national player.

El Pollo Loco has closed three development agreements for a total of 15 restaurants in the New York area over the next five years, the company announced on Tuesday. The first location will open in Queens in mid-2027.

Founded in Mexico in 1975, El Pollo Loco opened its first U.S. restaurant in Los Angeles. The majority of its locations are still concentrated in California, but its footprint has grown to more than 500 restaurants across 10 states. It is best known for its bone-in grilled chicken, although its menu has grown.

CEO Liz Williams wants to make El Pollo Loco into a national chain. To expand outside its Southwestern stronghold, El Pollo Loco will open restaurants on the East Coast and then move its way back to the West, she said.

Advertisement

To succeed in new markets, the chain will have to build its brand awareness in a crowded space where consumers are watching their budgets.

“Being a 50-year-old brand, people have seen it over the years and have always had that curiosity, but we have our work cut out,” Williams said.

Under Williams’ leadership, El Pollo Loco has embarked on a turnaround focused on modernizing its restaurants and expanding its menu into more convenient options, like wraps and chicken tenders. The efforts have started to pay off for the chain, which has reported three straight quarters of same-store sales growth.

“In the current quarter, we’ve expanded margins, and the business model is healthy overall,” Williams said. “The brand has gotten even stronger and healthier.”

Advertisement

El Pollo Loco has also been expanding quickly during her tenure. When she began in March 2024, the chain was in just six states. Now, it is in 10. And while it opened nine restaurants last year, El Pollo Loco is projecting 10 to 18 new locations by the end of 2026.

Investors like the company’s trajectory. Shares of El Pollo Loco have climbed 44% over the last year. The S&P 500 rose more than 15% over the same period.

Its comeback coincides with a challenging time for the restaurant industry. Burger and taco chains have been facing soaring costs for beef. Consumers have been dining out less frequently to save money, which has intensified competition between eateries.

El Pollo Loco has also had to contend with more competition as restaurants aim to cash in on growth in the chicken category. McDonald’s and Taco Bell — Williams’ former employer — have expanded their chicken options in recent years, fueled by consumer market research. And chicken-focused chains have been expanding quickly, from newcomer Dave’s Hot Chicken to Southern names like Zaxby’s and Raising Cane’s.

Advertisement

In 2024, El Pollo Loco was the eighth-largest chicken chain by U.S. sales, with 2.1% market share, according to Barclays.

But with its focus on grilled chicken and Mexican-inspired flavors, El Pollo Loco stands out from the crowd, Williams said.

“Everyone is talking about wanting to eat a little better and really thinking through their choices,” Williams said. “Everyone loves fried chicken … However, in terms of what you’re able to eat every single day, grilled chicken is just a better option.”

The expansion news comes as El Pollo Loco shakes up its leadership.

Advertisement

The company on Friday said in a regulatory filing that Damon Thomas will join the company as chief operating officer. He joins the company from Shake Shack.

Tara Hinkle was also recently tapped as the chain’s new chief development officer. She previously held roles at The Coffee Bean & Tea Leaf, Taco Bell and Starbucks before joining the company in July.

Correction: This story was updated to reflect that Williams said the company’s brand has gotten stronger and healthier. A previous version misquoted her.

Advertisement

Continue Reading

Business & Hustles

Bangkok floods threaten to shave 0.3 percentage points from Thailand’s 2026 growth

Published

on

Bangkok floods threaten to shave 0.3 percentage points from Thailand’s 2026 growth

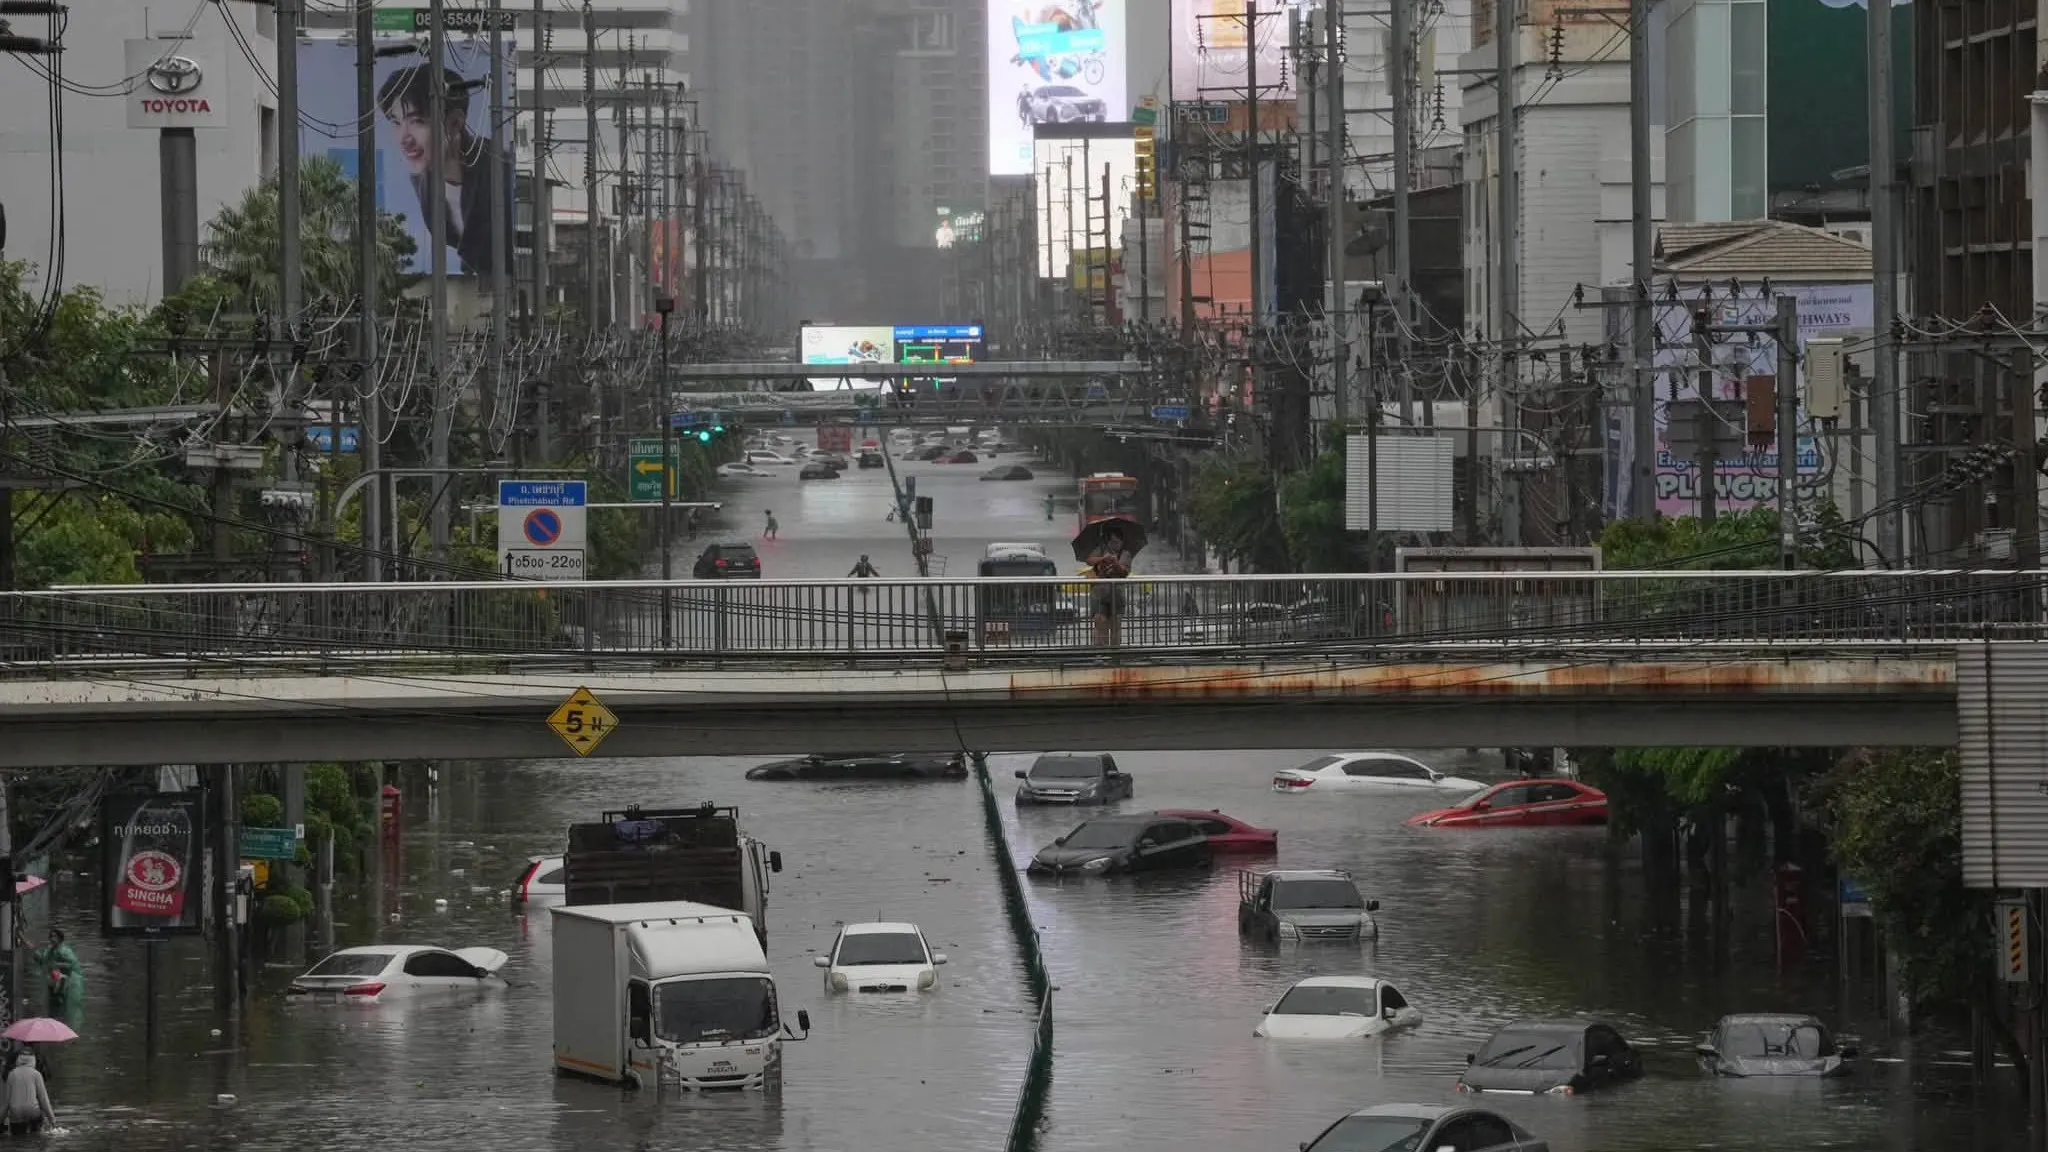
Severe flooding in Bangkok and surrounding provinces is projected to reduce Thailand’s 2026 economic growth by 0.3 percentage points, lowering estimates to 2.1%. Immediate losses are estimated at 11 billion baht nationwide, with some assessments ranging up to 33.8 billion baht, and Bangkok bearing the largest share of damage.

The capital experienced significant rainfall that overwhelmed drainage systems, disrupting transport, commerce, and supply chains, particularly affecting small businesses. The government declared special holidays to ease pressure, while banks introduced relief measures. The final economic impact depends on how quickly flooding subsides and whether further disruptions occur.

Thailand’s latest flooding could reduce annual economic growth by 0.3 percentage points this year, as widespread disruption across Bangkok and surrounding provinces weighs on businesses, transport and household spending.

The flooding could lower Thailand’s 2026 growth rate to 2.1%, from an earlier estimate of 2.4%, according to economist Aat Pisanwanich, who was quoted by Reuters in a recent article. Third-quarter growth could decline by approximately 0.5 percentage points to 1.7%.

Advertisement

The immediate economic losses have been estimated at 11 billion baht, or approximately $320 million, nationwide. A separate assessment by Rangsit University placed the potential losses between 16.9 billion and 33.8 billion baht, with a moderate-damage scenario reaching 25.345 billion baht.

Bangkok is expected to bear the largest share of the losses, at approximately 10.586 billion baht. The estimate covers the period from September 24 to 27 and includes disruptions to commerce, services and travel.

Bangkok bears the largest impact

The capital received around 320 millimetres of rain over two to three days, overwhelming drainage systems and flooding entire neighbourhoods. Water levels began to recede in several areas after the rain eased, but residents in some communities remained stranded or dependent on evacuation centres, as was reported by varoius medias like Internazionale.

The economic impact has extended beyond direct damage to buildings and vehicles. Businesses have faced difficulties moving workers, receiving supplies and delivering products, while shops in flooded areas have struggled to reopen.

Advertisement

Transport interruptions have also reduced consumer activity. Residents unable to travel to work or commercial districts have postponed purchases, while companies have incurred additional costs for alternative routes, temporary closures and emergency repairs.

The government declared special holidays for civil servants in Bangkok and three surrounding provinces on September 28 and 29 in an attempt to reduce travel and ease pressure on the transport system. However, the measure also reflects the scale of the disruption facing the Bangkok metropolitan area.reuters

The Stock Exchange of Thailand will continue operating during the special holidays, maintaining trading on the SET, mai, TFEX, LiVEx and related platforms. The decision is intended to preserve financial-market continuity even as parts of the capital remain affected by flooding.nationthailand

Pressure on supply chains

In the other hand, the Federation of Thai Industries has warned companies to protect workers, review transport routes and prepare for further disruption. Water levels in reservoirs and canals remain a concern even after rainfall has eased in parts of the country.

Advertisement

The risk is particularly significant for businesses that depend on just-in-time deliveries. Delays affecting warehouses, roads, ports or industrial facilities can spread quickly through supply chains, even when the original flooding is concentrated in a limited number of districts.

Banks have begun offering relief measures to affected households and companies. Krungthai Bank and Export-Import Bank of Thailand are providing repayment assistance, lower interest rates and additional liquidity to customers facing losses or cash-flow problems.

Those measures could prevent temporary disruption from becoming a wider credit problem. However, debt relief cannot replace lost inventory, damaged equipment or the income businesses lose during forced closures.

The flooding has also exposed differences in economic vulnerability. Large companies may have insurance, backup facilities and alternative suppliers. Small businesses and informal operators often have fewer reserves and are more likely to face a permanent loss of income after several days without sales.

Advertisement

Growth outlook becomes more fragile

The estimated 0.3 percentage-point reduction in annual growth would not by itself push Thailand into recession. But it adds another obstacle to an economy already dealing with moderate expansion, high household debt, external uncertainty and persistent energy costs.

The final impact will depend on how quickly water levels fall and whether additional rainfall causes a second wave of disruption. A rapid recovery could limit the damage, while prolonged flooding could increase losses through reduced production, weaker consumption and delayed investment.

For now, Thailand’s economic response is focused on drainage, emergency assistance and financial relief. The next stage will be more difficult: restoring businesses, repairing infrastructure and determining whether the country’s cities and supply chains are prepared for increasingly frequent climate shocks.

The final economic cost remains uncertain. The Federation of Thai Industries has warned that disruption can spread through supply chains, affecting raw-material deliveries, worker mobility, warehouses and machinery. At the same time, economists have stressed that a rapid recovery in affected areas would limit the damage, meaning the duration of the flooding is now more important than the initial rainfall event.

Advertisement

The floodwaters may recede within days. The economic consequences will last longer, particularly for smaller businesses that cannot afford another interruption before the recovery from this one is complete.

The episode also exposes a longer-term investment issue. Bangkok’s vulnerability to extreme rainfall creates recurring costs for retailers, manufacturers, logistics operators and property owners. Beyond emergency relief, businesses and policymakers face increasing pressure to invest in drainage capacity, flood barriers, water-management systems and continuity planning.
Continue Reading

Business & Hustles

Develop sets $458 million growth capital budget

Published

on

Develop sets $458 million growth capital budget

Growth will continue at Bill Beament-led Develop Global in FY27, following the release of its guidance metrics for the upcoming year.
Continue Reading

Business & Hustles

Dave & Buster’s interim CFO Cory Hatton buys $25,999 in stock

Published

on


Dave & Buster’s interim CFO Cory Hatton buys $25,999 in stock

Continue Reading

Trending

Copyright © 2025