Baron Real Estate Fund (the Fund) delivered strong results in the second quarter. The Fund increased 11.89% (Institutional Shares), outperforming the MSCI USA IMI Extended Real Estate Index (the MSCI Real Estate Index), which rose 9.88%, and in line with the MSCI US REIT Index (the REIT Index), which increased 11.84%.
The Fund’s long-term performance remains strong. According to Morningstar, the Fund has held the #1 real estate ranking since inception (December 31, 2009) through June 30, 2026. It also ranks in the top 1% of all real estate funds over both the trailing 10- and 15-year periods ended June 30, 2026.
We will address the following topics in this letter:
Advertisement
Our current top-of-mind thoughts
Portfolio composition and key investment themes
Top contributors and detractors to performance
Recent activity
Concluding thoughts on the prospects for real estate and the Fund
As of June 30, 2026, the Morningstar Real Estate Category consisted of 207, 199, 191, 149, 111, and 153 share classes for the 1-, 3-, 5-, 10-, 15-year, and since inception (December 31, 2009) periods. Morningstar ranked Baron Real Estate Fund Institutional Share Class in the 37th, 22nd, 41st, 1st, 1st, and 1st percentiles, respectively. On an absolute basis, Morningstar ranked Baron Real Estate Fund Institutional Share Class as the 74th, 46th, 84th, 2nd, 1st, and 2nd best performing share class in its Category, for the 1-, 3-, 5-, 10-, 15-year, and since inception periods, respectively.
As of June 30, 2026, Morningstar ranked Baron Real Estate Fund R6 Share Class in the 37th, 22nd, 41st, 1st, 1st, and 1st percentiles, respectively. On an absolute basis, Morningstar ranked Baron Real Estate Fund R6 Share Class as the 75th, 47th, 85th, 1st, and 1st best performing share class in its Category, for the 1-, 3-, 5, 10-year, and since inception periods, respectively.
Since inception rankings include all share classes of funds in the Morningstar Real Estate Category. Performance for all share classes date back to the inception date of the oldest share class of each fund based on Morningstar’s performance calculation methodology.
Morningstar calculates the Morningstar Real Estate Category Average performance and rankings using its Fractional Weighting methodology. Morningstar rankings are based on total returns and do not include sales charges. Total returns do account for management, administrative, and 12b-1 fees and other costs automatically deducted from fund assets.
Baron Real Estate Fund Institutional Share Class was rated 4 stars overall, 3 stars for the trailing 3 years, 3 stars for the trailing 5 years, and 5 stars for the trailing 10 years ended June 30, 2026. There were 199 share classes, 191 share classes, and 149 share classes for the 3-, 5-, and 10-year periods. The Morningstar Ratings™ are for the Institutional share class only; other classes may have different performance characteristics. The Morningstar Ratings are based on the Morningstar Risk-Adjusted Return measures.
Advertisement
Performance listed in the above table is net of annual operating expenses. Annual expense ratio for the Retail Shares and Institutional Shares as of April 30, 2026 was 1.32% and 1.05%, respectively. The performance data quoted represents past performance. Past performance is no guarantee of future results. The investment return and principal value of an investment will fluctuate; an investor’s shares, when redeemed, may be worth more or less than their original cost. The Adviser may waive or reimburse certain Fund expenses pursuant to a contract expiring on August 29, 2036, unless renewed for another 11-year term and the Fund’s transfer agency expenses may be reduced by expense offsets from an unaffiliated transfer agent, without which performance would have been lower. Current performance may be lower or higher than the performance data quoted. For performance information current to the most recent month end, visit BaronCapitalGroup.com or call 1-800-99-BARON.
Annualized performance (%) for periods ended June 30, 2026
FundRetailShares1,2
FundInstitutionalShares1,2
MSCI USA IMIExtendedReal EstateIndex1
MSCIUS REITIndex1
S&P500Index1
QTD3
11.84
11.89
9.88
11.84
15.20
YTD3
5.74
5.86
8.82
16.89
10.21
1 Year
14.89
15.18
11.00
19.70
22.32
3 Years
10.56
10.84
12.20
11.03
20.61
5 Years
3.43
3.69
6.53
4.58
13.41
10 Years
11.49
11.77
8.97
4.80
15.51
15 Years
11.86
12.14
10.22
6.89
14.36
Since Inception(12/31/2009)
12.81
13.09
11.00
8.40
14.34
Since Inception(12/31/2009)(Cumulative)3
630.57
661.74
459.42
278.44
812.87
Our Current Top-of-Mind Thoughts
The first half of 2026 offered early evidence that a multi-year recovery in real estate — a long out-of-favor asset class — is beginning to take shape. Several REITs and travel- and residential-related companies performed well over the period, though we believe the broader recovery remains in its early innings.
Advertisement
We are clear-eyed about the headwinds: elevated interest rates, housing affordability pressures, and AI-driven disruption are real considerations. Yet our optimism about public real estate’s prospects remains firm, grounded in several themes we have explored in recent shareholder letters:
1. Real Estate Has Lagged
Despite a solid start to 2026, many real estate stocks — both REITs and non-REIT companies — have underperformed the broader market for several years. For example, over the five years ending June 30, 2026, the S&P 500 Index has returned 13.41% annually versus just 4.58% for the REIT Index.
2. Real Estate Continues to Offer Relative Value
A large portion of public real estate remains attractively valued. We highlight various examples later in the letter.
3. Privatizations of Discounted Public Real Estate Are Accelerating
As we have noted in prior letters, many publicly traded real estate companies trade at meaningful discounts to private market values. During the second quarter of 2026, three Fund holdings received acquisition announcements at significant premiums: – Caesars Entertainment, Inc. – Caesars, the largest gaming company in the U.S., according to management, announced an agreement to be acquired by Fertitta Entertainment at a 49% premium to its unaffected share price as of February 25, 2026. – Taylor Morrison Home Corporation — Berkshire Hathaway announced an agreement to acquire Taylor Morrison, a leading national homebuilder, at a 24% premium to its May 29, 2026, closing price. – MGM Resorts International — Barry Diller’s media conglomerate, People Inc. (formerly IAC), offered to acquire MGM Resorts’ outstanding shares at a 32% premium to its December 31, 2025, closing price. – M&A activity has also accelerated across multi-family, self-storage, shopping centers, industrial, retail, health care, homebuilders, and other real estate sectors — further underscoring the disconnect between public market valuations and underlying private asset values. We believe this valuation gap creates the potential for additional public company acquisitions.
4. Supply-Demand Dynamics Favor Real Estate
Across much of the sector, demand continues to outpace supply — a dynamic that supports occupancy gains, rent growth, increased home sales, cash flow expansion, and improving valuations.
Importantly, construction activity across many real estate segments has fallen to decade lows (Source: Green Street Advisors, LLC), which should set the stage for a faster growth rebound than in prior cycles as demand continues to strengthen.
5. Balance Sheets Are Healthy and the Debt Environment Is Improving
Real estate balance sheets are in strong shape, characterized by prudent leverage, well-laddered debt maturities, and a balanced mix of fixed- and floating-rate obligations. – Should long-term interest rates decline — driven by the deflationary effects of AI, moderating shelter inflation, or a more accommodative Federal Reserve over time — borrowing costs could fall. Lower rates would likely support higher real estate valuations, stimulate housing market activity, and accelerate M&A, further underscoring the relative attractiveness of public real estate.
6. Real Estate Is Increasingly an AI Beneficiary
The market has increasingly rewarded owners with tangible, hard-to-replicate assets – what we describe as HALO (Heavy Assets, Low Obsolescence) businesses – including REITs, homebuilders, and other real estate-related companies. These businesses tend to offer greater near-term earnings visibility and lower risk of AI-driven disruption compared to many segments of the digital economy.
7. Many Investors Remain Underweight Real Estate
If investors rebalance toward the sector, increased capital flows could provide a meaningful lift to valuations and share prices.
8. We See a Path to Double-Digit Annual Returns
We believe the Baron Real Estate Fund® is well-positioned to deliver double-digit annual returns over the next several years, supported by improving growth prospects, rising dividends, and what we view as compelling valuations across the portfolio.
The Baron Real Estate Fund offers a compelling way to access the long-term return potential of the Real Estate sector
We believe the advantages of the Fund’s comprehensive, flexible, and actively managed approach – enabling investment across a broad spectrum of real estate companies, including both REITs and non-REIT real estate-related businesses – will become increasingly evident in the years ahead. In our view, a rapidly evolving real estate landscape requires more selective and discerning analysis.
We believe our highly differentiated real estate fund enjoys several attractive attributes compared to:
Advertisement
Actively managed REIT funds: The Fund benefits from a broader investment universe and reduced reliance on the debt markets. Since inception on December 31, 2009, the Fund has increased 13.09% on an annualized basis versus the REIT Index, which increased 8.40%. • Passive/ETF real estate funds: The Fund has the flexibility to be selective, emphasizing companies with attractive long-term prospects rather than broadly replicating an index and owning both higher- and lower-quality real estate businesses. Since inception on December 31, 2009, the Fund has increased 13.09% annually versus the Vanguard Real Estate ETF, which increased 8.95%.*
Non-traded REITs and private real estate: The Fund provides enhanced liquidity, diversification, valuation transparency, lower fees, and strong performance over the long term.
Portfolio Composition and Key Investment Themes
We currently invest in REITs as well as seven additional non-REIT real estate-related categories. Allocations across these areas are dynamic and reflect our bottom-up research and assessment of relative opportunities, as outlined below.
Fund investments in real estate-related categories
Percent of Net Assets (%)
Non-REITs
66.9
Building Products/Services
20.8
Homebuilders & Land Developers
12.9
Casinos & Gaming Operators
10.2
Hotels & Leisure
9.0
Real Estate Service Companies
7.1
Real Estate Operating Companies
5.9
Data Centers
1.0
REITs
29.0
Cash and Cash Equivalents
4.0
Total
100.0*
* Individual weights may not sum to the displayed total due to rounding.
Investment Themes
REITs
We believe the outlook for REITs remains favorable for several key reasons:
REITs have lagged
In the last five years through June 30, 2026, the REIT Index trailed the S&P 500 Index by 62% cumulatively.
Several REITs offer compelling value
We have identified several REITs trading at meaningful discounts to both historical norms and private market valuations.
Across a broad range of property types – including multi-family, single-family rentals, hotels, strip centers, office, life sciences, cold storage, self-storage, and timber – public market prices sit 10% to 50% below replacement cost or recent private market transaction values. We believe this dislocation may attract private equity or other buyers in taking public REITs private.
Favorable demand versus supply set up
Demand remains generally strong or is improving: Robust in segments such as health care, industrial, and retail, and showing signs of improvement in residential, office, and storage categories.
Supply constraints are underappreciated: According to our research, new construction activity across many REIT categories has fallen 50% to 70% from peak levels in 2022 and remains well below historical levels, as higher land, labor, and materials costs make development prohibitively expensive.
The combination of strengthening demand, a favorable supply environment, and occupancy levels above 90% for many properties creates a compelling setup for rent growth acceleration.
REITs benefit from both cyclical and secular tailwinds
Cyclical tailwinds: Strong early-cycle demand prospects, supportive supply conditions for real estate, and the historical pattern of real estate cycles typically lasting 7 to 10 years.
Secular tailwinds across property types: Growth in AI and cloud computing driving demand for data centers, an aging population boosting healthcare real estate, housing affordability pressures increasing rental demand, suburbanization benefiting retail, 5G network upgrades supporting towers, and the rise of remote work fueling storage needs.
AI haven
Several REITs are relatively insulated from potential AI-related disruption, benefiting from tangible assets, well-covered dividends, contracted cash flows, annual rent escalators, and other structural advantages.
We believe several REITs have the potential to deliver double-digit returns through a mix of earnings growth, dividend income, and multiple expansion.
As of June 30, 2026, we had investments in eight REIT categories representing 29.0% of the Fund’s net assets.
REITs
Advertisement
Percent of Net Assets (%)
Health Care REITs
7.0
Data Center REITs
6.5†
Mall REITs
5.4
Industrial REITs
3.1
Triple Net REITs
2.9
Self-Storage REITs
2.7
Other REITs
1.4
Mortgage REITs
0.1
Total
29.0*
† Exposure to Data Center REITs would be 7.5% if non-REIT data center company GDS Holdings Limited was included in the category.
* Individual weights may not sum to the displayed total due to rounding.
Residential-related real estate
We recognize that the housing market is currently facing a logjam.
Advertisement
On one hand, a buyers’ strike has emerged, as many potential homeowners find properties unaffordable following a roughly 50% rise in home prices over the past five years and a jump in mortgage rates from 3% to between 6% and 7%, based on data from the National Association of Realtors.
On the other hand, a sellers’ strike is also in place, as many current homeowners are hesitant to sell while their existing mortgages carry rates well below today’s levels.
Navigating near-term headwinds while staying bullish long-term: Affordability pressures and persistent buyer-seller standoffs have kept us cautious about housing. That said, we added exposure in the second quarter where valuations became sufficiently compelling. Looking ahead, we remain firmly bullish on residential real estate for the following reasons:
Housing is an early cycle beneficiary, and we believe we are early in the cycle
Economic growth could accelerate potential stimulus such as tax refunds and other pre-midterm measures, deregulation, and the possibility of easing inflation and interest rate cuts.
Housing tends to benefit early in the economic cycle due to its sensitivity to interest rates, pent-up consumer demand, and its powerful multiplier effect – creating more jobs, boosting consumer spending, supporting higher prices, and accelerating overall economic growth.
Housing is also supported by long-term secular tailwinds
Millennial household formation remains significantly below its long-term stabilized level.
Buyers are increasingly favoring new homes over existing ones, as they offer better layouts, lower maintenance, and greater energy efficiency at comparable price points.
Existing homes are aging – averaging over 40 years – while homeowners sit on record levels of equity and are staying in their homes longer. Together, these factors should support strong home repair and remodeling activity in the years ahead.
Bipartisan support to address the housing crisis
Housing affordability appears to be a key issue heading into the mid-term elections, and we expect certain initiatives may emerge.
Housing is an AI beneficiary
Housing and select residential building product companies may benefit from AI trends, as their asset-heavy structures provide relative insulation from disruption – what we describe as HALO.
Several housing companies are attractively valued
Select homebuilders are trading near 1 times book value, well below their historical norm of 1.3 to 1.5 times book value, implying roughly 30% to 50% upside to more typical valuations. The market’s mispricing appears increasingly hard to ignore: three public homebuilders have already received acquisition offers at significant premiums in 2026.
Other residential-related real estate companies are currently valued at or near trough valuation levels.
New Federal Reserve Chief may become more dovish should inflation move towards its targeted rate of 2%
The housing market would be a major beneficiary from lower mortgage rates.
Big picture: There is a compelling long-term investment case for housing
The U.S. faces a structural housing shortage of more than 4 million homes relative to demographic needs. Today, the country builds roughly 1.4 million homes annually – the same number as in the 1960s – despite the population nearly doubling from 180 million to 340 million, according to data from the Census Bureau.
As of June 30, 2026, residential-related real estate companies represented 33.7% of the Fund’s net assets.
Residential-related real estate companies
Advertisement
Percent of Net Assets (%)
Building Products/Services
16.8
Homebuilders
12.9
Home Centers
4.1
Total
33.7*
* Individual weights may not sum to the displayed total due to rounding.
Travel-related real estate
We continue to believe several travel-related real estate companies are well positioned to benefit from a favorable “trifecta” of cyclical, secular, and 2026-specific tailwinds, which should support strong fundamentals and share price performance in the years ahead.
Advertisement
Cyclical tailwinds – economic growth may accelerate
Key inflation components may moderate over time, while the regulatory environment remains business – and investment-friendly. Favorable tax policies enacted in 2025 – such as bonus depreciation to encourage investment – combined with a massive investment cycle in AI and other technologies, major initiatives like the CHIPS Act, and a busy 2026 event calendar, together create a supportive backdrop for economic and corporate growth.
Broad-based economic growth and middle-class wage growth.
Limited supply growth: Projected to increase by less than 1% over the next few years, well below the long-term average of 2% to 2.5%, according to Green Street Advisors, LLC.
Secular tailwinds
Many investors view travel spending as cyclical – our view is that travel spending is also secular.
Consumers are allocating more discretionary spending to travel rather than durable goods. Factors supporting this trend include delayed household formation, which leaves more disposable income for travel, flexible work arrangements that combine business and leisure or enable extended stays, and cyclically muted business activity.
2026 tailwinds
World Cup (in 11 major metro markets) + America’s 250th anniversary + Super Bowl + Major League Baseball all-star game.
Increasing spending on onshoring initiatives.
Examples of several travel-related companies that are attractively valued
A luxury-focused hotel company that has transitioned to a 90% asset-light model, currently trades at a 3 to 4 times multiple discount to its hotel C-Corp peers and below private market valuations.
A leading hotel and gaming company, currently valued at just 8.4 times 2027 estimated cash flow compared with its historical range of 13 to 15 times.
The company could become one of the most compelling travel-related growth stories with the opening of its UAE resort in 2027, which could be worth $40/share versus its recent market value of only $97 per share.
A leading gaming growth company positioned in the highly attractive Las Vegas Locals market. Red Rock Resorts has the real estate capacity to potentially double its portfolio in the coming years, and we find its current valuation – approximately 11 times 2027 estimated cash flow – compelling.
A global asset-light travel company, with over 9 million active listings, generating more than $4 billion in annual free cash flow. The company faces limited AI disruption risk due to 90% direct traffic and the uniqueness of most of its inventory. Shares are currently trading at just 14 times 2027 estimated cash flow.
– Dry powder / private equity
With private equity sitting on substantial dry powder, we believe public travel companies — still deeply discounted relative to private market values — present an increasingly attractive acquisition target. This thesis is already playing out: in the first half of 2026, two of the Fund’s travel holdings, Caesars Entertainment, Inc. (CZR) and MGM Resorts International (MGM), received takeover bids. Should valuations remain depressed, we expect further take-private activity to follow.
As of June 30, 2026, travel-related real estate companies represented 19.1% of the Fund’s net assets.
Travel-related real estate companies
Percent of Net Assets (%)
Casinos & Gaming Operators
10.2
Hotels & Leisure
9.0
Total
19.1*
* Individual weights may not sum to the displayed total due to rounding.
Commercial real estate services companies
In the first six months of 2026, shares of leading commercial real estate services firms CBRE Group, Inc. (CBRE), Jones Lang LaSalle Incorporated (JLL), and Cushman & Wakefield Ltd.(CWK) declined despite strong earnings and positive business outlooks. The sell-off largely reflected investor concerns that AI could disrupt parts of their operations.
While certain business lines – such as office leasing, valuation services, and property management – may face AI-related challenges over time, we believe current multi-year concerns are overstated and already reflected in share prices. We continue to research and monitor potential AI-related headwinds.
Advertisement
Despite near-term uncertainties, we remain long-term optimistic about these leading commercial real estate services companies. They are positioned to potentially benefit from structural and secular tailwinds, including the outsourcing and institutionalization of commercial real estate, as well as opportunities to gain market share in a highly fragmented industry. We also see the early stages of a rebound in commercial real estate sales and leasing activity. Based on these factors, we believe CBRE, JLL, and Cushman & Wakefield could achieve earnings-per-share growth of 12% to 15% over the next several years.
Further, we believe valuations are attractive. CBRE is valued at a discount to the S&P 500 multiple despite superior earnings growth, a pristine balance sheet, and a resilient business model. JLL is valued at only 12 times 2027 estimated earnings, compared with the high-teens multiple justified by its historical trading and its improvement in its business mix. Cushman & Wakefield is valued at only 8 times 2027 estimated earnings, a highly discounted valuation multiple, in our opinion.
Real estate-focused alternative asset managers
Shares of alternative asset managers declined in the first six months of 2026, as several companies faced a mix of headwinds, including: exposure to software investments that could be affected by AI-related risks; credit concerns tied to private loans; limitations on investor redemptions for semi-liquid products (2% per month or 5% per quarter); delayed monetizations; and the potential for slower earnings growth due to these factors, along with the risk that growth in the retail channel may underperform expectations.
While these challenges may persist in the near term, we do not view them as existential, and we believe current valuations largely reflect these concerns.
Advertisement
Over the long term, we remain optimistic about leading real estate-focused asset managers, including Brookfield Corporation (BN), Brookfield Asset Management Ltd. (BAM), and Blackstone Inc. (BX) Each has the potential to gain market share in a growing industry, supported by strong investment track records and global scale. These companies are well positioned to potentially benefit from secular growth in alternative assets, leveraging their ability to deliver attractive relative and absolute returns – often with lower perceived volatility compared with other investment options.
Valuations, in our opinion, are compelling. Brookfield Corporation, a global owner and operator of real assets, trades at $43 per share, well below management’s estimated liquidation value of $67 per share – approximately 55% higher than the current share price. Blackstone’s shares are currently valued at the low-end of its valuation multiple over the last 5 years.
Property technology companies
The convergence of real estate and technology has given rise to a new category – real estate technology, or proptech. The growth of proptech and the digitization of real estate represent an exciting and promising development. We believe we are in the early stages of a technology-driven investment cycle focused on data and digitization, enabling real estate-related businesses to generate incremental revenue streams and reduce costs.
We recently began acquiring shares in Procore Technologies, Inc. (PCOR), a provider of software solutions to the construction industry, and will elaborate on this company in future shareholder letters.
Advertisement
As of June 30, 2026, other real estate-related companies, which include the three investment themes mentioned directly above, plus an investment in Chinese data center operator GDS Holdings Limited (GDS), represented 14.1% of the Fund’s net assets.
Other real estate-related real estate companies
Percent of Net Assets (%)
Commercial Real Estate Services Companies
7.0
Real Estate-Focused Alternative Asset Managers
5.9
Data Center Operators
1.0
Property Technology Companies
0.1
Total
14.1*
* Individual weights may not sum to the displayed total due to rounding.
The Macerich Company, a high-quality retail mall REIT, contributed positively to performance in the second quarter, driven by management’s continued strong execution. Key highlights included nearing full achievement of the leasing targets outlined in its Path Forward Plan, a growing pipeline of accretive acquisitions, and an opportunistic equity raise that further strengthened balance sheet flexibility.
As previously outlined, we remain optimistic about Macerich’s prospects over the next several years. The fundamental backdrop for high-quality mall real estate remains favorable: tenant demand is robust, desirable retail space is scarce (occupancy is high with little new mall development), and the resulting demand/supply imbalance is giving landlords meaningful pricing power. We continue to engage with CEO Jackson Hsieh, a well-regarded outsider who is bringing a fresh, analytical lens to the company’s real estate portfolio. We believe he will continue to unlock significant value by divesting non-core properties and reducing debt. Our conviction has grown that the company can generate over $2.00 in FFO over the next couple of years, which we believe would be a meaningful catalyst for share price appreciation from current levels.
Shares of Hyatt Hotels Corporation appreciated materially following strong first quarter results and an Investor Day in May that outlined strong long-term growth targets. Hyatt franchises and manages a portfolio of luxury hotel brands across over 1,500 properties in 83 countries. The company is in the final stages of transforming its earnings mix primarily to an asset-light fee stream while growing its development pipeline to record levels, enabling sector-leading unit growth, double-digit fee revenues, and mid-teens EBITDA and free cash flow growth. This translates to over 50% cumulative cash flow growth over the next three years with an increasing portion returned to shareholders via buybacks.
Shares of AAON, Inc. rose during the quarter following an exceptionally strong earnings report which saw the company see drastically faster growth in its data center business, BasX, than expected. Up 26% sequentially and 72% over the past year, BasX has positioned itself as a true best-in-class cooling solutions provider with a focus on customized offerings vs. peers’ off-the-shelf products. With the new Memphis facility ramping production, the company can now satisfy elevated levels of demand with over $2 billion of BasX revenue capacity. The HVAC business performed well, as the company accelerated market share gains following strong heat pump and national accounts driven growth. We believe AAON is well positioned to continue to compound well above peers for the foreseeable future.
Advertisement
Top detractors from performance for the quarter
Quarter-End Market Cap or Market Cap When Sold ($B)
Contribution to Return (%)
GDS Holdings Limited
6.0
(0.67)
SiteOne Landscape Supply, Inc.
5.1
(0.46)
Blackstone Inc.
145.1
(0.18)
Builders FirstSource, Inc.
7.6
(0.13)
Lowe’s Companies, Inc.
123.6
(0.11)
Despite solid operating results and after strong share price performance to start the year, shares of GDS Holdings Limited declined in the second quarter. Several items weighed on performance including management communication about full-year guidance components, a material step-up in capital expenditure over the next few years and a slight delay in timing when the company is expected to see a growth inflection in its underlying results. While we continue to see evidence of the building of the AI wave in China through significant bookings growth and see material under-appreciated value in GDS’ stake in its spun-out international subsidiary (DayOne), we trimmed our position and reallocated capital to companies where we have a higher degree of visibility and lower exogenous risks such as the current geopolitical environment.
SiteOne Landscape Supply, Inc. (SITE) is the largest distributor of wholesale landscape supplies in North America. SiteOne sells irrigation, hardscapes, agronomics, and nursery products to professional contractors through its branch network for maintenance, upgrade/repair, and new construction applications. Shares fell during the quarter as investors worried about the impacts of the Iran War and a potential reduction in demand given rising commodity prices. Despite this, we believe the company remains well positioned to continue outgrowing its markets and expand margins as it harvests benefits from its ongoing initiatives and investments in improving underperforming branches, operational efficiency, technology, and product category management to continue differentiating itself from the fragmented wholesale landscape supplies distribution industry. Our belief was reinforced by a positive Analyst Day held by SiteOne at the end of the quarter highlighting the progress the company has made on each of these fronts. The event highlighted the depth of SiteOne’s talent and a clear pathway toward above-market organic growth, EBITDA margin expansion (toward 13%-plus target by 2030), and continued consolidation of the market driving an expected high-teens EBITDA growth rate out to 2030. As the underlying market begins to recover and SiteOne continues to execute on what is can control, we believe the multiple should re-rate which combined with rapidly growing earnings can deliver strong stock upside over time.
Shares of Blackstone Inc. (BX) continued to be volatile and were a drag on performance in the second quarter as mounting redemption pressures at Blackstone’s Private Credit vehicle (BCRED) and sector-wide liquidity fears overwhelmed an otherwise constructive fundamental backdrop. The first quarter saw elevated redemption requests at approximately 8% of NAV followed by 10% in the second quarter, requiring Blackstone to cap withdrawals at the standard 5% limit for the first time. Broader sector sentiment was further pressured when other alternative asset managers announced withdrawal restrictions, reigniting broad private market liquidity fears and dragging the entire sector lower. Please see our “Top purchases” section for additional detail.
Advertisement
Recent Activity
Top net purchases for the quarter
Quarter-End Market Cap ($B)
Net Amount Purchased ($M)
Meritage Homes Corporation
5.6
76.8
Blackstone Inc.
145.1
63.5
Blackstone Digital Infrastructure Trust Inc. (BXDC)
During the quarter, we initiated a position in Meritage Homes Corporation, the fifth-largest homebuilder in the U.S., with operations across the West, Central, and East regions. In 2025, the company delivered approximately 15,000 single-family homes to entry-level and first move-up buyers at an average selling price of $390,000.
We are optimistic about our investment in Meritage Homes for several reasons:
We are optimistic about the medium-term outlook for U.S. single-family housing. New home construction remains depressed relative to population growth, the housing shortage is acute — estimated at over 2 million units according to Freddie Mac — and secular demand is accelerating, driven by rising millennial household formation and a growing preference for new homes over existing ones.
Fundamentals appear to be bottoming, with a return to growth on the horizon. Depressed construction activity and a potential peak in builder concessions may set the stage for improving sales and margins beginning in 2027.
Meritage Homes has a credible path to substantial long-term growth. Management targets 20,000 annual deliveries over time — a roughly 40% increase from current levels — driven by double-digit growth in community count. As volumes scale and elevated incentives normalize, operating margins could expand by 600 basis points or more. Together, these drivers could support earnings per share growth of 250% or more over time.
The homebuilding industry has seen a rising wave of consolidation, with several U.S. builders taken private in recent years. Further M&A activity would not be surprising, and Meritage Homes’ scale and operational track record could make it an attractive candidate.
Valuation is attractive. The stock currently trades at a discount to book value; despite the premium it has historically commanded at times. Recent take-private transactions in the sector have been completed at 1.2 to 1.3 times book value, underscoring the potential upside from current levels.
While near-term uncertainty may continue to weigh on the shares, we are excited about Meritage Homes’ long-term growth prospects and compelling valuation. We see meaningful potential for share price appreciation over the coming years, driven by earnings growth and multiple expansion.
Blackstone Inc. is the world’s largest alternative asset manager with over $1.3 trillion in assets under management and the largest real estate manager in the world according to management. As we noted in our first quarter letter, while we consolidated our positions in the alternative asset manager space, Blackstone remained high on our list to revisit. Given severe multiple compression across the sector with all alternative managers being painted with a broad brush and extreme investor negativity, we took advantage of the volatility to reinitiate a position in the company at what we deemed to be highly compelling valuation levels. While the liquidity narrative dominates headlines, underlying fundamentals continue to be strong. We retain long-term conviction in Blackstone due to its premier brand, global franchise, loyal customers, exceptional balance sheet, and an excellent management team. At current share price levels, we believe the company is well positioned to benefit as the liquidity narrative fades and realization activity accelerates.
Advertisement
We participated in the IPO of Blackstone Digital Infrastructure Trust Inc., a newly listed Blackstone-sponsored vehicle focused on acquiring stabilized, fully leased data centers underpinned by long-term non-cancellable leases to the world’s largest hyperscalers in primary data center markets. The opportunity is compelling given the absence of large-scale capital dedicated to acquiring stabilized data center assets – leaving a significant volume of institutional-quality assets available at attractive prices with limited competition. Blackstone’s sponsorship brings an unparalleled sourcing advantage, having invested $200 billion into digital infrastructure since 2018 and sourcing over 85% of deals off market, alongside a near-term actionable pipeline of $25 billion. We believe the long-term leases with annual escalators and limited exposure to operating risks support a highly visible, attractive return profile and risk/reward opportunity. We also spent considerable time with management prior to the IPO and came away highly impressed with the depth of the team, the quality of the identified pipeline, and the clarity of the long-term vision.
Top net sales for the quarter
Quarter-End Market Cap or Market Cap When Sold ($B)
We recently trimmed the Fund’s investment in Wynn Resorts, Limited, a global luxury owner and operator of integrated resorts (hotels and casino resorts), in part due to the delay in the opening of its new UAE resort. We may increase the Fund’s ownership of Wynn at a later date.
Following a 40% increase in the shares of Equinix, Inc., a leading global operator of data centers, we trimmed the Fund’s large position in the company but remain bullish about the company’s long-term business prospects.
Advertisement
Following the announcement of Berkshire Hathaway’s agreement to acquire Taylor Morrison Home Corporation, a leading national homebuilder, we exited the Fund’s investment in the company.
Concluding Thoughts on the Prospects for Real Estate and the Fund
As outlined in our first quarter letter, we remain mindful of the headwinds that could weigh on equity markets in the coming months. Periods of volatility and sharp dislocations have historically been our best opportunity to reposition the Fund – and the first half of 2026 was no exception. We remain actively engaged and confident in our ability to continue doing so.
We maintain our constructive outlook for the broader equity market, public real estate, and the Fund.
Stock Market Outlook
Our research points to broadly stable economic conditions ahead, supported by several potential tailwinds. On the policy front, reduced trade uncertainty, lower taxes, and enhanced depreciation incentives should encourage capital investment; deregulation and a more permissive M&A environment add further support. A Federal Reserve that eases gradually, combined with administration efforts to address housing supply constraints, provides an additional constructive backdrop. Beyond policy, we see AI-driven productivity gains as a meaningful catalyst – one with the potential to moderate inflation, compress long-term interest rates, and expand profit margins.
Advertisement
For these reasons, we remain positive about the outlook for the stock market.
Real Estate Market Outlook
We believe the conditions are in place for real estate to perform well in the next few years. Demand across most property sectors remains steady, with growth expected to improve over the next several years. At the same time, new supply has declined – often by more than 50% from peak 2002 levels – a dynamic we believe is underappreciated.
As a result, growth may rebound more quickly than in prior cycles, as the sector is not burdened by excess supply or elevated vacancies. Many public real estate shares have lagged, and valuations have reset to reflect a higher cost of capital, leaving many trading at attractive discounts relative to private market values. This disparity could catalyze ongoing real estate M&A activity.
Balance sheets remain strong, and credit markets are supportive. Additionally, moderating shelter inflation and productivity gains from AI could contribute to lower long-term interest rates – an important potential catalyst for the sector.
Advertisement
Taken together, we believe a favorable combination of cash flow growth, dividends, and the potential for multiple expansion in public real estate valuations could generate double-digit annual returns in the years ahead.
So, in our opinion, this is an attractive time to invest in real estate.
Baron Real Estate Fund® Outlook
We continue to believe the benefits of the Fund’s broader and more flexible investment approach – encompassing a wide range of real estate companies, including both REITs and non-REIT real estate-related businesses – will become increasingly advantageous in the years ahead. In our view, a rapidly evolving real estate landscape demands more selective and discerning analysis.
While some companies are positioned to potentially benefit from accelerating tailwinds, others are likely to face persistent headwinds. We believe the portfolio is composed of competitively advantaged real estate companies that are generally well positioned to grow faster than their peers. The Fund is structured to capitalize on compelling investment themes, and we believe current valuations and return prospects are attractive.
Advertisement
For these reasons, we remain positive about the outlook for the Baron Real Estate Fund.
I would be remiss without acknowledging our core real estate team – David Kirshenbaum (assistant portfolio manager), George Taras (senior analyst), and David Berk (analyst). Their dedication, intellectual curiosity, and passion for the work remain impressive.
Our team and I remain fully committed and energized to delivering strong long-term results.
Advertisement
I proudly remain a major shareholder of the Baron Real Estate Fund.
Sincerely,
Jeffrey Kolitch
Portfolio Manager
Advertisement
1 The MSCI USA IMI Extended Real Estate Index Net (USD) is a custom index calculated by MSCI for, and as requested by, BAMCO, Inc. The index includes real estate and real estate-related GICS classification securities. MSCI makes no express or implied warranties or representations and shall have no liability whatsoever with respect to any MSCI data contained herein. The MSCI data may not be further redistributed or used as a basis for other indices or any securities or financial products. This report is not approved, reviewed or produced by MSCI. The MSCI US REIT Index Net (USD) is designed to measure the performance of all equity REITs in the U.S. equity market, except for specialty equity REITs that do not generate a majority of their revenue and income from real estate rental and leasing operations. The S&P 500 Index measures the performance of 500 widely held large-cap U.S. companies. MSCI is the source and owner of the trademarks, service marks and copyrights related to the MSCI Indexes. The MSCI Indexes and the Fund include reinvestment of dividends, net of foreign withholding taxes, while the S&P 500 Index includes reinvestment of dividends before taxes. Reinvestment of dividends positively impacts performance results. The indexes are unmanaged. Index performance is not Fund performance. Investors cannot invest directly in an index.
2 The performance data in the table does not reflect the deduction of taxes that a shareholder would pay on Fund distributions or redemption of Fund shares.
3 Not annualized.
Advertisement
* Vanguard Real ETF’s annualized returns (NAV) as of June 30, 2026: 1-year, 12.48%; 5-year, 2.79%; 10-year, 4.91%; and Since Fund Inception (12/31/2009), 8.94%.
Investors should consider the investment objectives, risks, and charges and expenses of the investment carefully before investing. The prospectus and summary prospectus contain this and other information about the Funds. You may obtain them from the Funds’ distributor, Baron Capital, Inc., by calling 1-800-99-BARON or visiting BaronCapitalGroup.com. Please read them carefully before investing.
Risks: In addition to general market conditions, the value of the Fund will be affected by the strength of the real estate markets as well as by interest rate fluctuations, credit risk, environmental issues and economic conditions. The Fund invests in companies of all sizes, including small and medium sized companies whose securities may be thinly traded and more difficult to sell during market downturns.
The Fund may not achieve its objectives. Portfolio holdings are subject to change. Current and future portfolio holdings are subject to risk.
Advertisement
Discussions of the companies herein are not intended as advice to any person regarding the advisability of investing in any particular security. The views expressed in this report reflect those of the respective portfolio managers only through the end of the period stated in this report. The portfolio manager’s views are not intended as recommendations or investment advice to any person reading this report and are subject to change at any time based on market and other conditions and Baron has no obligation to update them.
This report does not constitute an offer to sell or a solicitation of any offer to buy securities of Baron Real Estate Fund® by anyone in any jurisdiction where it would be unlawful under the laws of that jurisdiction to make such an offer or solicitation.
For information pertaining to competitor funds, please refer to that firm’s website.
Diversification does not guarantee a profit or protect against a loss.
Advertisement
The Morningstar Rating™ for funds, or “star rating”, is calculated for managed products (including mutual funds, variable annuity and variable life subaccounts, exchange-traded funds, closed-end funds, and separate accounts) with at least a three-year history. Exchange-traded funds and open-ended mutual funds are considered a single population for comparative purposes. It is calculated based on a Morningstar Risk-Adjusted Return measure that accounts for variation in a managed product’s monthly excess performance, placing more emphasis on downward variations and rewarding consistent performance. The top 10% of products in each product category receive 5 stars, the next 22.5% receive 4 stars, the next 35% receive 3 stars, the next 22.5% receive 2 stars, and the bottom 10% receive 1 star. The Overall Morningstar Rating for a managed product is derived from a weighted average of the performance figures associated with its three-, five-, and 10-year (if applicable) Morningstar Rating metrics. The weights are: 100% three-year rating for 36-59 months of total returns, 60% five-year rating/40% three-year rating for 60-119 months of total returns, and 50% 10-year rating/30% five-year rating/20% three-year rating for 120 or more months of total returns. While the 10-year overall star rating formula seems to give the most weight to the 10-year period, the most recent three-year period actually has the greatest impact because it is included in all three rating periods.
MORNINGSTAR IS NOT RESPONSIBLE FOR ANY DELETION, DAMAGE, LOSS OR FAILURE TO STORE ANY PRODUCT OUTPUT, COMPANY CONTENT OR OTHER CONTENT.
The portfolio manager defines “Best-in-class” as well-managed, competitively advantaged, faster growing companies with higher margins and returns on invested capital and lower leverage that are leaders in their respective markets. Note that this statement represents the manager’s opinion and is not based on a third-party ranking. EBITDA, short for earnings before interest, taxes, depreciation, and amortization, is an alternate measure of profitability to net income. It’s used to assess a company’s profitability and financial performance. EPS Growth Rate (3-5-year forecast) indicates the long term forecasted EPS growth of the companies in the portfolio, calculated using the weighted average of the available 3-to-5 year forecasted growth rates for each of the stocks in the portfolio provided by FactSet Estimates. The EPS Growth rate does not forecast the Fund’s performance. Funds From Operations (FFO) measures the cash flow generated by a real estate investment trust (REIT), excluding depreciation and amortization, and is often used to assess its performance. Free Cash Flow (FCF) represents the cash that a company generates after accounting for cash outflows to support operations and maintain its capital assets.
Advertisement
Investment Products: NOT FDIC INSURED | MAY LOSE VALUE | NOT BANK GUARANTEED
BAMCO, Inc. is an investment adviser registered with the U.S. Securities and Exchange Commission (SEC). Baron Capital, Inc. is a broker-dealer registered with the SEC and member of the Financial Industry Regulatory Authority, Inc. (FINRA).
The Sunderland firm reported a small drop in revenues due to lower wind speeds in 2025
15:37, 16 Sep 2026Updated 15:44, 16 Sep 2026
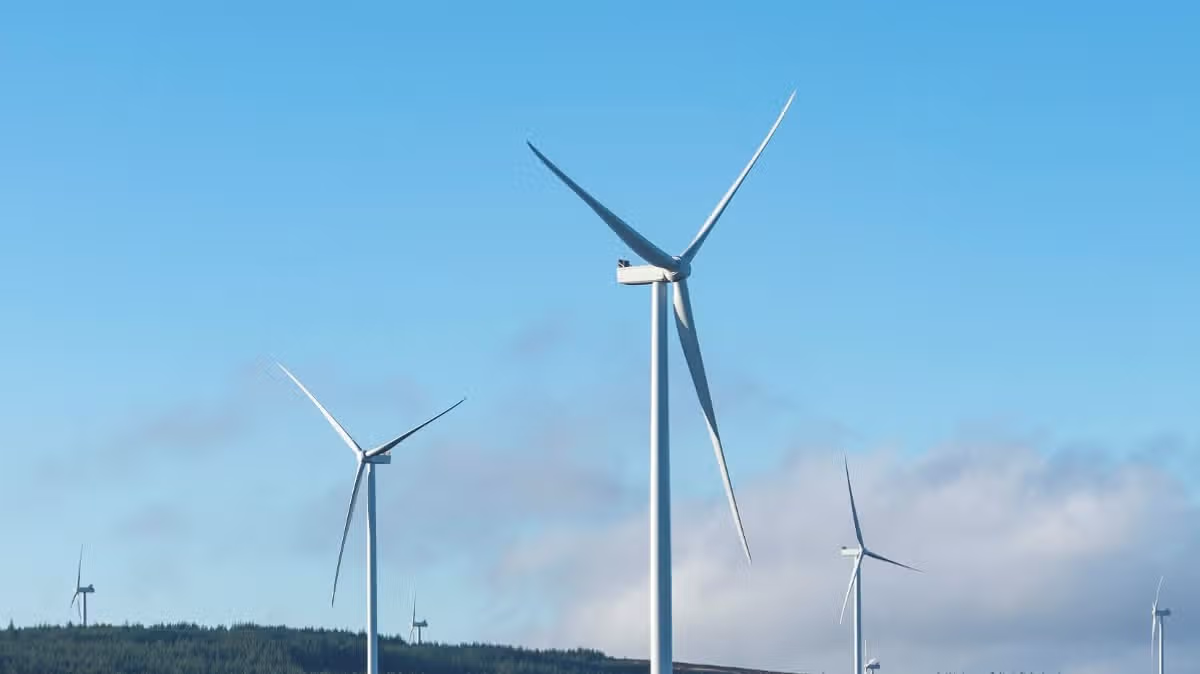
The Kype Muir windfarm(Image: OnPath Energy)
Renewables firm OnPath Energy says it is continuing to invest in its growth strategy despite seeing a small drop in revenues as lower wind speeds cut power generation.
The Sunderland-headquartered firm, which was formed by the acquisition of the renewable energy elements of County Durham’s Banks Group, recorded a turnover of £73.4m and an operating profit of £22.7m for the 12 months to the end of 2025.
Advertisement
That compared to a turnover of £95.7m and operating profit of £69.4m during 2024, though those figures related to a 15-month period.
OnPath said that the year saw “below average wind speeds and lower merchant power prices compared to the previous period”. The group’s wind farms in the North and Scotland had a combined capacity of 252MW at the end of the financial year.
OnPath said that it is growing its development pipeline and expects to bring forward several new project proposals in England in the coming months, while it is currently exploring a range of potential new development locations across England, Scotland and Wales.
It acquired the Milton Keynes Wind Farm in Buckinghamshire and Pates Hill Wind Farm in West Lothian at the beginning of 2025 and has since entered into an option agreement to acquire a majority stake in three onshore wind farms under development in South Lanarkshire.
Advertisement
Earlier this year, the company completed the sale of seven English onshore wind farms to The ERG Group, releasing capital to support the development of new onshore wind farms across the UK.
Simon Fisher, chief financial officer at OnPath Energy, said: “Onshore wind energy is playing an increasingly important role in the UK’s long-term energy security strategy while also delivering significant supply chain investment, UK jobs, improving energy affordability and social benefits for local communities, local supply chain businesses and the wider economy.
“Wind yields in 2025 were below average, but we have still delivered solid commercial returns while continuing the evolution of the business towards a primary focus on developing and building new onshore wind farms across the UK.
“In the coming months, we will add another 73MW capacity to our operating portfolio with the energisation of Mill Rig Wind Farm in South Lanarkshire and the Barnsdale Solar Park in West Yorkshire, with the commissioning of the Common Farm Solar Park in South Yorkshire then set to follow.
Advertisement
“Acquisitions and divestments continue to be a critical part of our growth strategy, with capital reinvestment helping us bring forward new projects, which in turn creates jobs and supply chain opportunities for UK businesses, improves energy affordability for UK consumers while also accelerating our contribution to a fair and inclusive just transition.”
OnPath said it aims to spend around two-thirds of its investments in the local supply chains of its wind farms, while it had awarded more than £1.2m in grants from the community funds linked to each of its onshore sites to local good causes.
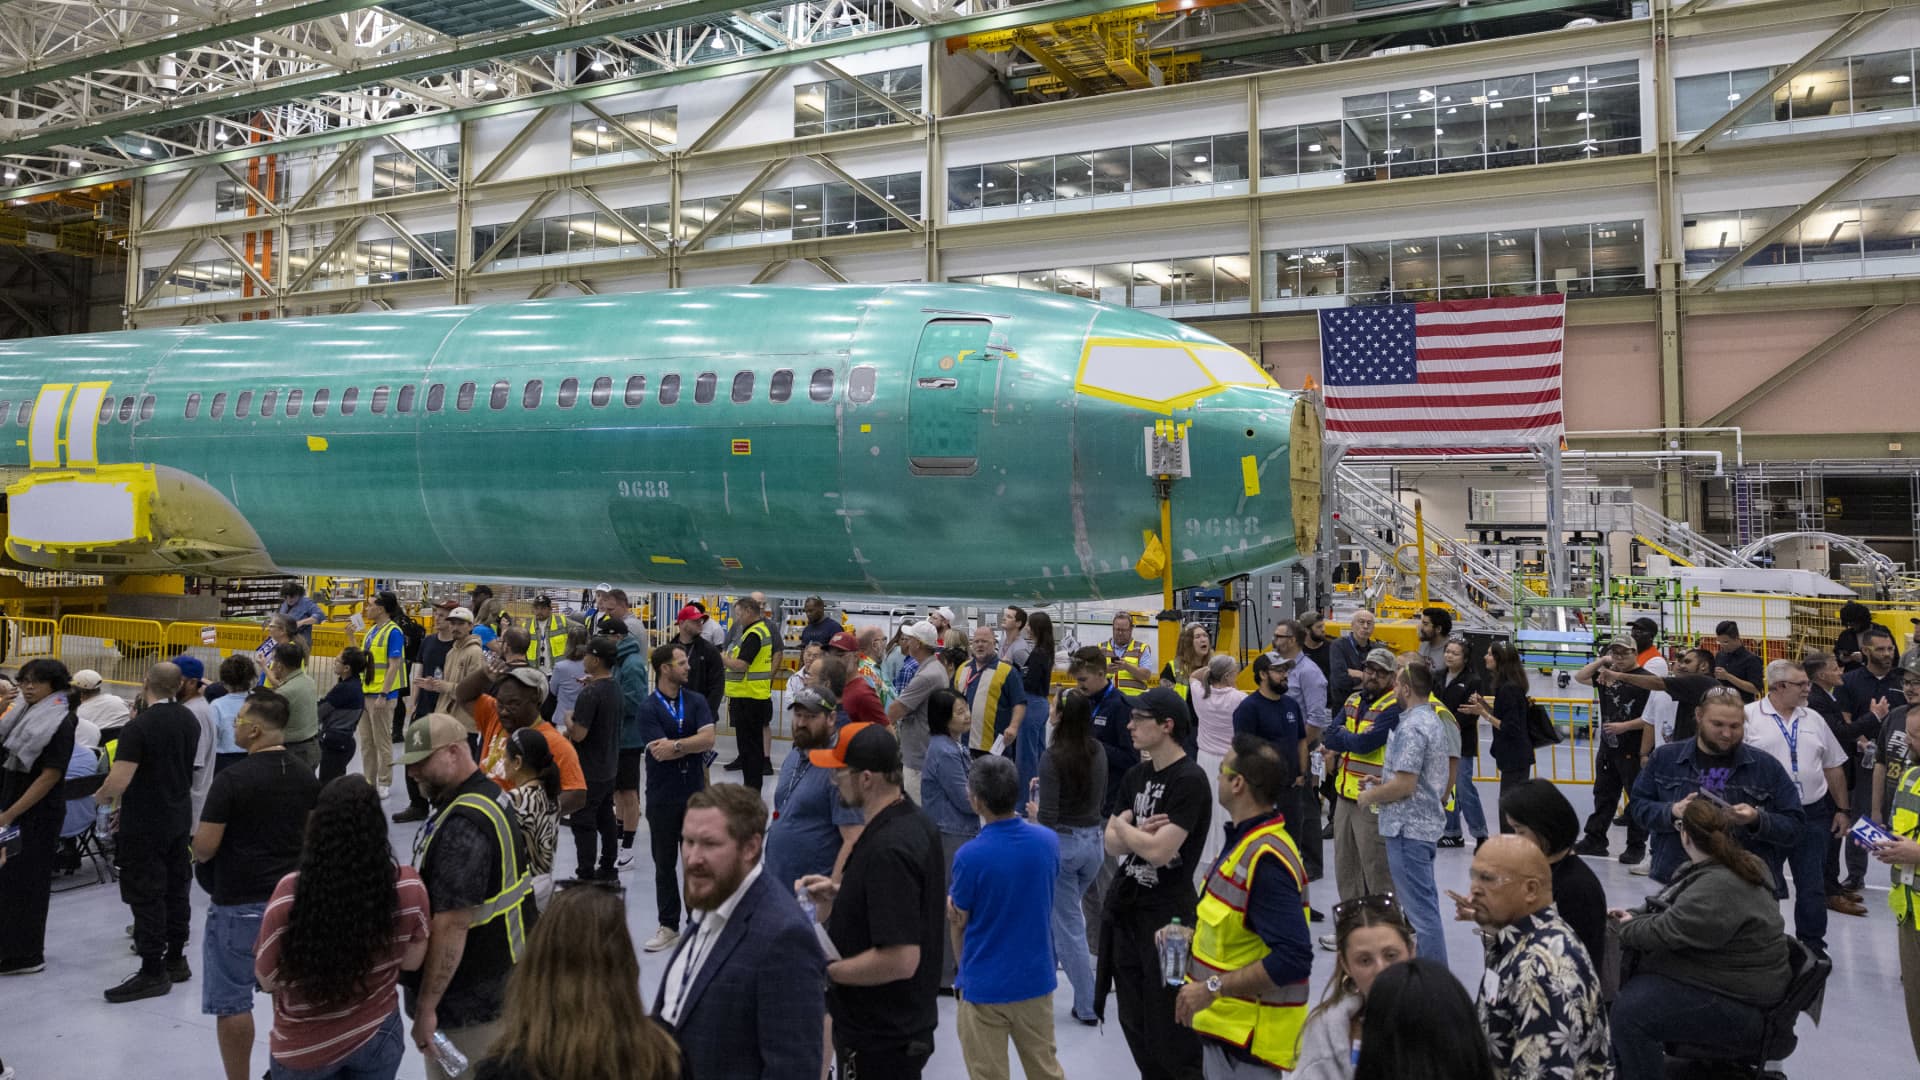
A Boeing 737 MAX 10 fuselage is pictured during the opening ceremony for the company’s new North Line assembly line, which will produce 737 MAX aircraft, at the Boeing Everett Factory in Everett, Washington, on July 10, 2026.
Jason Redmond | Afp | Getty Images
Boeing‘s 737 Max production is taking “a little bit longer” than expected to stabilize, and the company expects to increase its output of the planes next year, CEO Kelly Ortberg told investors Wednesday.
Advertisement
Boeing stock extended its losses for the day and was down more than 5% in afternoon trading after Ortberg’s comments.
The manufacturer has been working to steadily ramp up the output of its best-selling plane after years of safety and quality crises. Ortberg said wing production at its Renton, Washington, factory is a constraint now, adding the company has plans in place to address it.
Boeing isproducing about 47 of the aircraft per month.
Ortberg reiterated to investors at a Morgan Stanley industry conference that he expects certification of the Max 10, the largest model in the family “very soon.” That plane is years behind schedule.
Advertisement
Kelly didn’t say that he expected aircraft orders from China when President Donald Trump is scheduled to host Chinese leader Xi Jinping at the White House on Sept. 24.
Orders from China are “going to be announced by the airlines at their pace,” he said.
New York Knicks superstar Jalen Brunson, along with his family, announced on Tuesday the launch of Thirty Third Management Group, a family-owned brand advisory firm that will manage his off-court business as well as represent clients across pro sports, business and philanthropy.
It’s been quite the year for Brunson, as he was the leader of a Knicks team that broke a 53-year NBA title drought, and he won NBA Finals MVP in the process. The “King of New York” moniker has followed him ever since, with the Knicks faithful forever indebted to him and his teammates for the pure joy they brought the city.
Advertisement
But if Brunson wasn’t a star already on the hardwood, winning the NBA title in New York vaulted him into a different stratosphere, and business opportunities and more were sure to follow.
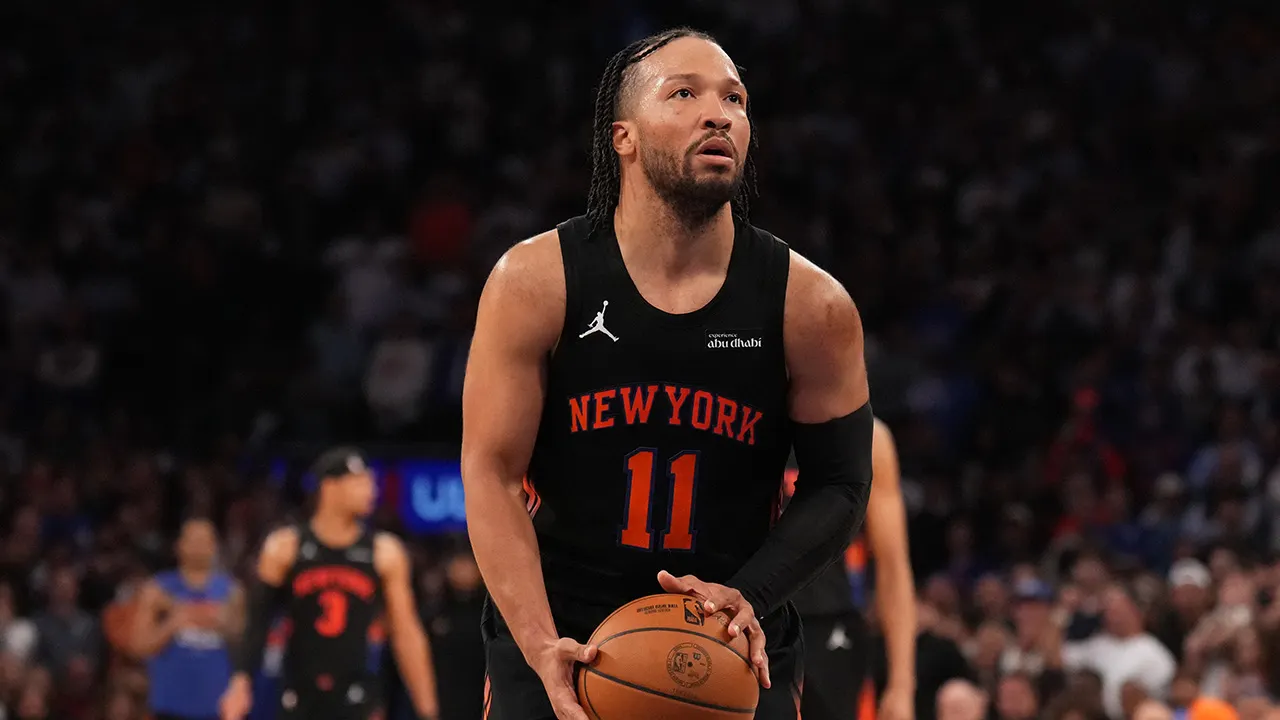
Jalen Brunson of the Knicks shoots a free throw against the Philadelphia 76ers on May 6, 2026, at Madison Square Garden in New York City. (Jesse D. Garrabrant/NBAE/Getty Images)
Now, with his own firm and his family’s back, Brunson is not only helping himself but looking forward to doing the same for others with their business development, charitable work and more.
“My family has been with me every step of the way, and everything we do is rooted in trust,” he said in a statement. “Thirty Third gives us the chance to take ownership of my off-court business, to build something that reflects who we are, and to do it together.”
The firm’s name comes from the beginning of Brunson’s career, where the Dallas Mavericks selected him 33rd overall out of Villanova in the 2018 NBA Draft. He has since built a reputation defined as much by his character and leadership as by what he has accomplished on the court.
Sandra Brunson, Jalen’s mother, who has been managing his off-court business for eight years, will serve as Thirty Third Management Group president. Erica Brunson, his sister, will serve as director of client services, while Connor Cashaw, a friend and former high school teammate at Stevenson High School in Illinois, will be the director of business development. Both Erica and Connor have been a part of Jalen’s team since 2024 and 2025, respectively.
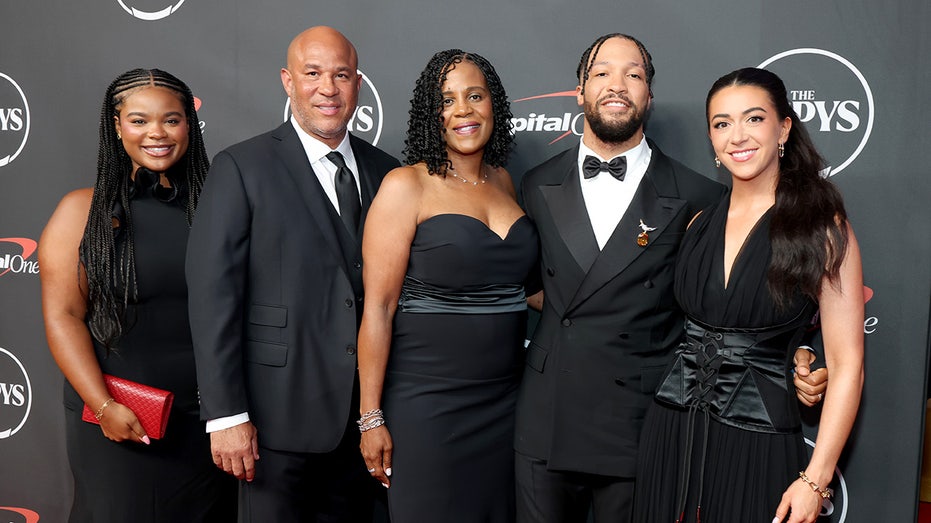
Erica Brunson, Rick Brunson, Sandra Brunson, Jalen Brunson and Ali Marks Brunson attend the ESPY Awards at David H. Koch Theater at Lincoln Center on July 15, 2026, in New York City. (Kevin Mazur/Getty Images)
This firm was born from a belief that the most powerful brands are built on trust, purpose, and genuine human connection,” Erica Brunson said in a statement. “As a family, we’ve had the privilege of supporting Jalen’s growth beyond basketball, and that experience inspired us to create an advisory platform that helps others do the same.
Advertisement
“We are committed to helping our clients maximize opportunities, whether in professional sports, business, or philanthropy, and want to be a strategic partner that champions both success and significance.”
So, while Brunson will serve as the firm’s foundational client, Thirty Third Management Group was built with the wider goal of advising athletes, NIL talent, executives, entrepreneurs and charitable foundations on brand development, partnership strategy, business development and more.
Also, a priority of the firm from the outset will be in women’s sports, a category the firm’s leadership views as “historically underserved,” with Erica leading that effort.
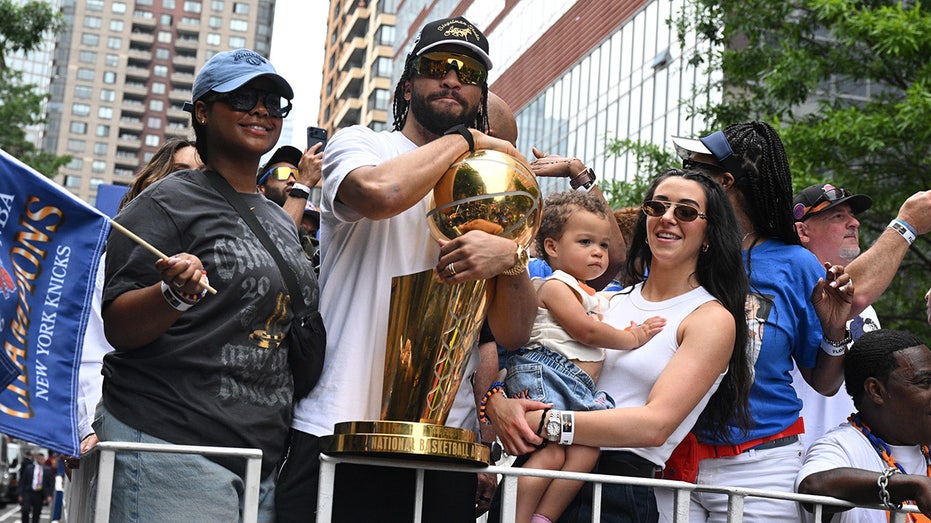
Jalen Brunson, his wife Ali Marks Brunson and their daughter, Jordyn James Brunson are seen at the Knicks ticker-tape parade along the Canyon of Heroes on June 18, 2026, in New York City. (NDZ/Star Max/GC Images)
Meister Seelig & Schuster PLLC, led by Mitch Schuster and Jed Ferdinand, will serve as legal counsel for the firm, while Focus Financial Partners serves as financial advisors for Brunson, his family and Thirty Third Management Group.
Asked about the message the decision sent to Trump, Warsh chuckled before saying “I have got nothing for you on a discussion with the president,” as he batted away similar questions with the same response.
The Federal Reserve is independent of the government, but has faced sharp criticism from Trump over its decisions on rates in recent years.
Trump was heavily critical of Warsh’s predecessor Jerome Powell, who stepped down at the end of his term earlier this year, for not cutting rates.
Following Wednesday’s announcement, Trump said rates should be cut to “1%, or less”.
Advertisement
“LOWER THE INTEREST RATES FOR THE UNITED STATES OF AMERICA, AND FAST!”, he posted on social media.
Earlier a White House press secretary Kush Desai told Fox News the president and White House had “reiterated our commitment to the independence of the Federal Reserve on numerous occasions” but added it did not prevent Trump being able to voice his opinions.
Warsh said at the press conference that “part of the independence of the Federal Reserve is we stay in our lane”.
This hike by the Fed is the first move rate move in any direction since they were cut in December 2025. The last time they were raised was in July 2023.
Advertisement
A 0.25pp increase will likely add to increasing mortgage rates for homebuyers, as the rates set by banks and other lenders are heavily influenced by the Fed’s policy rate.
Major US banks JP Morgan, KeyCorp and BNY raised their prime lending rate on Wednesday to 7% from 6.75% in response, which will rates charged on credit cards and personal loans.
Mortgage costs have climbed over the past year but remain below peaks seen in 2023. A 30-year fixed deal is 6.76% on average, while a 15-year deal is 6.09%, according to figures from Freddie Mac.
Due to many US homeowners having 30-year and 15-year fixed-rate mortgages, changes to interest rates will not impact monthly repayments, though they could affect those looking to secure a loan for a home or refinance.
Advertisement
Warsh declined to provide his own view on where he saw interest rates going into the future, but the majority of his fellow policymakers said they believe rates would be hiked again before the end of this year to between 4-4.25%.
A small majority said rates could rise further to the 4.25-4.5% next year, before cuts begin in 2028 and 2029.
The forecast suggested price rises will ease in the coming years, with inflation, the measure used to assess the cost of living, predicted to fall steadily to the Fed’s 2% target by 2029.
The US is not alone in tackling the inflation impact from the conflict in the Middle East, with the European Central Bank raising rates last week and the Bank of England set to make its own decision on Thursday.
Shorter-dated U.S. Treasury yields rose on Wednesday after the Federal Reserve raised interest rates and flagged further increases in borrowing costs in the coming months to control inflation.
Two-year Treasury yields extended gains as Fed chief Kevin Warsh spoke and hit 4.738%, their highest level since July 2024. The benchmark 10-year yield turned higher.
The decision on the rate increase, which was the Fed’s first in over three years, was unanimous.
New policy projections showed 16 of 18 policymakers anticipate at least one more quarter-percentage-point hike by the end of this year. Warsh did not submit a rate projection.
“I’m looking at the two-year here, though, and … it’s coming back up higher here. So, maybe it helps the long end a little bit, but the front end’s still worried about another hike later this year, and then who knows what for 2027,” said JP Powers, chief investment officer at RWA Wealth Partners in Boston. Market bets on a rate hike at the Fed’s next meeting in late October ticked higher to 56.5% from 54% prior to the hike, according to CME Group’s FedWatch Tool.The two-year U.S. Treasury yield, which typically moves in step with interest rate expectations for the Fed, was last up 5.1 basis points at 4.715%.
The yield on the benchmark U.S. 10-year Treasury note was last down 0.2 basis points at 4.994% after briefly turning higher.The yield on the 30-year bond fell 2.5 basis points to 5.338%.
A closely watched part of the U.S. Treasury yield curve measuring the gap between yields on two- and 10-year Treasury notes, seen as an indicator of economic expectations, was at a positive 27.5 basis points, the flattest since June 30.
Advertisement
The breakeven rate on five-year U.S. Treasury Inflation-Protected Securities (TIPS) was last at 2.366% after closing at 2.417% on Tuesday.
The 10-year TIPS breakeven rate was last at 2.344%, indicating the market sees inflation averaging about 2.3% a year for the next decade.
The independent review has been commissioned by the Welsh Government
15:51, 16 Sep 2026Updated 16:00, 16 Sep 2026
Deputy Minister for Skills and Tertiary Education, Cefin Campbell.(Image: Plaid Cymru)
The chair of a Welsh Government commissioned independent review of the hard-pressed university sector has been revealed.
Professor Patrick Prendergast is the former provost and president of Trinity College Dublin and current chair of Southeast Technological University in Ireland. Having spent his career in the Irish higher education sector he brings an independent, external perspective to the review.
Advertisement
He will be supported by a small panel of experts in higher education policy, finance and governance. Full membership of the panel will be confirmed shortly.
The review will examine how higher education in Wales is funded and organised, including student support, institutional funding, research and the sustainability of the sector.
Universities across Wales have seen significant redundancies over the last two years, fuelled in part by a fall in higher fee paying international students. Voluntary mergers, and back office collaboration, will be considered.
Professor Prendergast said:“I’m delighted to be leading the review of higher education in Wales. This review presents an excellent opportunity to establish what kind of higher education system Wales needs for the coming decades.
Advertisement
“I look forward to working with the expert panel and stakeholders in and around the sector, and to learn more about the challenges they are facing and the opportunities that this review might seize.
“Working together, I’m confident that we can recommend a way forward which will ensure a sustainable and successful higher education system in Wales.”
Deputy Minister for Skills and Tertiary Education, Cefin Campbell, who commissioned the review, said:“Our universities are among Wales’ most valuable institutions, shaping generations of learners, driving innovation and enriching our communities and culture. But they are facing serious challenges that demand serious action
“I am delighted that Professor Prendergast has agreed to chair this review. He brings a wealth of experience and his background in higher education will be invaluable.
Advertisement
“This review is our chance to be honest about the challenges ahead and make sure investment in higher education delivers real value for learners, communities and the country.”
The panel is expected to meet for the first time next month. An interim report will be delivered next summer, with a full final report the following winter.










































You must be logged in to post a comment Login