Connect with us

Business

From Korean Chipmakers to Leveraged Semiconductor ETFs: STARTRADER Launches 49 New 24/7 Stock and ETF CFDs

Published

on


From Korean Chipmakers to Leveraged Semiconductor ETFs: STARTRADER Launches 49 New 24/7 Stock and ETF CFDs

Continue Reading
Advertisement
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business

SRK Capital 2026 Semi-Annual Partnership Letter

Published

on

annual report series

annual report series

peepo/iStock via Getty Images

Dear Partners,

SRK Fund I, LP increased 26.80% during the first half of the year. In contrast, the S&P 500 and the Russell 2000 returned 10.18% and 22.57%, respectively. Since inception, the Fund has appreciated 1551.26% compared to 222.91% for the S&P 500 and 118.90% for the Russell 2000.

SRK Fund I, LP Returns (%) as of June 30, 2026

Advertisement
2026 2025 2024 2023 2022 2021 2020 2019
SRK Fund I 26.80% 47.12% -8.74% 17.15% 35.31% 46.71% 127.72% 77.99%
S&P 500 TR 10.18% 17.88% 25.02% 26.29% -18.11% 28.71% 18.40% 31.48%
Russell 2000 22.57% 12.81% 11.54% 16.93% -20.47% 14.78% 20.00% 25.52%

*Inception date of 05/01/18

In many respects, the first half of 2026 mirrored the environment of 2025, persistent macroeconomic noise, narrow market leadership, and heightened volatility. Geopolitical tensions, off and on Iran peace deals, and a partial unwinding of the AI momentum trade caused investor sentiment to fluctuate throughout the first half of the year. After an extended period in which market participants chased AI hardware bottlenecks and infrastructure buildouts, shifting sentiment triggered sharp pullbacks across many crowded positions.

Our performance during the period was achieved with zero exposure to companies tied to the AI buildout. That decision was not a refusal to evaluate the future; underwriting future earnings power is central to our investment process. The distinction is predictability, as I tend to only commit capital when a business model is proven, the economics are visible, and I believe I have a high probability of being right about what the business can generate over time. AI remains a nascent and rapidly evolving sector. At this stage, much of the easy money in the trade appears to have been made, with valuations already discounting explosive growth and earnings several years into the future. Predicting long-term customer adoption, competitive durability, and sustainable returns on invested capital now requires assumptions across a wide range of possible outcomes for which I do not believe I have an edge.

Advertisement

Instead, I prefer to focus on opportunities with asymmetric return potential and cash-flow outcomes that management can materially influence. I am allocating capital to opportunities where market neglect, cyclical weakness, or operational transitions have temporarily obscured the normalized earnings power of high-quality core assets.

Today’s portfolio consists of businesses trading at meaningful discounts to my estimate of normalized cash flows. They are led by aligned operators focused on controllable improvements, including operational efficiency, stronger cash conversion, and disciplined per-share capital allocation. By emphasizing durable cash flows and execution within management’s control, I believe the portfolio can continue compounding without depending on macro tailwinds, multiple expansion, or favorable market sentiment.

Portfolio Updates

ImmuCell Corporation (ICCC)

ImmuCell delivered a strong first quarter in 2026, underscoring the earnings power and cash-flow potential of its core First Defense franchise after the company’s strategic exit from Re-Tain. Product sales increased 28.4% year-over-year to $10.4 million, driven by higher volumes, price realization, and an estimated three-point gain in U.S. scours biologicals market share. Gross margin expanded to 45.0% as increased production created operating leverage, while net income rose 34% to $1.9 million. Even after the stock’s recent appreciation, ImmuCell remains a compelling opportunity. Management is refitting the former Re-Tain facility to expand First Defense capacity beyond the current 450,000 units per month, supporting a path toward $35 million to $40 million of sales over the next 12 to 24 months. With gross margins near 45%, the Re-Tain development burden permanently removed, annual EBITDA can grow towards $12 million to $14 million and convert into free cash flow with limited corporate tax leakage for several years due to substantial net operating loss carryforwards.

Outdoor Holding Company (POWW)

Outdoor Holding Company’s fourth quarter and full-year fiscal 2026 results reinforced the core turnaround thesis. Since divesting its capital-intensive ammunition manufacturing business in April 2025, the company has operated as a pure-play, asset-light marketplace through GunBroker.com. Revenue increased 3.5% year-over-year to $51.1 million, while adjusted EBITDA rose 46% to $22.3 million from $15.3 million, reflecting disciplined cost control and improved platform monetization.

Advertisement

Momentum accelerated in their fourth quarter. Net revenue grew 10.1% year-over-year to $13.9 million, supported by an 11.8% increase in gross merchandise value to approximately $229 million. Gross margin remained exceptionally high at 87.6%, and lower operating expenses helped drive adjusted EBITDA to $7.7 million, up 163% from $2.9 million in the prior-year period.

The results also highlighted GunBroker’s resilience in a subdued firearms market. Firearm unit sales on the platform grew 8.7% year-over-year during the quarter, far outpacing the 1.6% increase in adjusted NICS background checks. Adjusted EBITDA run rates over the past three quarters have also exceeded management’s $25 million target, reaching that milestone well ahead of the timetable set in August 2025. The balance sheet remains strong, with $68.1 million of cash and equivalents at fiscal year-end. They also began returning capital through a $15 million share repurchase program, buying back 513,925 shares for approximately $1.0 million at an average price of $1.95 per share.

Management is now focused on platform enhancements that can drive GMV growth and expand the take rate. During their fiscal year, the company completed its MasterFFL integration to streamline dealer verification across more than 32,000 licensed dealers and launched an AI-powered listing tool to improve product descriptions and conversion. In fiscal 2027, universal payment processing should allow individual sellers to accept credit cards through native checkout, addressing the roughly 30% of platform volume still handled through manual payment methods and creating a new high-margin revenue stream. With modest take-rate expansion, a potential cyclical recovery in firearms demand ahead of the 2028 election cycle, 85%+ gross margins, a net cash balance sheet, and aggressive buybacks, POWW has a credible path to $35 million to $40 million of EBITDA over the next 18 to 24 months and remains an attractive opportunity.

Industrial & Manufacturing Basket

Our industrial and manufacturing basket performed exceptionally well in the first half of the year, with the average holding up more than 50% year-to-date on a consolidated basis. While the market often views micro-cap industrial companies as commoditized or highly cyclical, our thesis centered on a clear inflection point. These businesses had spent two years working through severe post-pandemic inventory destocking, elevated input costs, and depressed utilization, while still retaining durable niche positions, strong balance sheets, and meaningful operating leverage.

Advertisement

The group’s fundamental results have validated that setup. As customer inventories normalized and supply chain friction eased, even modest volume recovery began flowing through to earnings. Many management teams have already used the downturn to resize cost structures, consolidate facilities, and remove legacy overhead, allowing baseline volume recovery to drive sharp improvements in gross margins and operating cash flow.

One example is a specialized synthetic fiber and materials manufacturer we accumulated at a deep discount to tangible book value. The company had been pressured by an extended destocking cycle across the global textile and apparel supply chain, which caused revenue declines and severe margin compression. Rather than waiting for demand to recover, management executed a broad operational turnaround by closing redundant plants, shifting production to lower-cost regions, and emphasizing proprietary higher-margin products. As order volumes stabilized, the company’s operating leverage became evident. The business moved from operating losses to cash generation, gross margins recovered by several hundred basis points, and the stock re-rated accordingly.

Capital allocation across the basket has also remained disciplined. Supported by net-cash or low-leverage balance sheets, several management teams have used excess cash flow to repurchase deeply discounted shares, increasing per-share value. Despite the basket’s strong year-to-date advance, these businesses still trade at modest multiples of normalized earnings and free cash flow. As core-end market demand continues to recover, I believe the group remains early in a multi-year earnings recovery.

Sanuwave Health, Inc. (SNWV)

During the first half of the year, we fully exited our position in Sanuwave Health (SNWV). Sanuwave entered 2026 as a relatively small holding. We had originally purchased shares when the business was deeply discounted trading on the OTC market and realized most of our gains at substantially higher prices, selling the bulk of the position in the $20s and $30s. After reviewing the company’s first-quarter results, I decided to sell the remaining shares and move on.

Advertisement

The exit was driven by reduced visibility into Sanuwave’s future growth. Much of the company’s recent revenue growth has come from mobile wound-care clinics using the UltraMist platform. However, the economics for those operators changed materially. Mobile clinics had previously generated very high margins from tissue-based skin grafts, while UltraMist, despite its clinical benefits, does not carry the same reimbursement profile.

As reimbursement pressure reduced margins, it became increasingly clear that many mobile wound-care operators were under significant financial strain. In my view, a meaningful portion of that customer base was and is likely to fail. Because Sanuwave’s forward growth depended heavily on a structurally challenged channel, the risk/reward profile had deteriorated. Sanuwave was ultimately a successful investment for the fund despite the recent stock price deterioration, but exiting the remaining position allows us to redeploy capital into opportunities where I have greater confidence in the predictability and durability of future cash flows.

New Holdings

Pro-Dex Inc. (PDEX)

Pro-Dex is a new holding added during the fourth quarter of last year. I have followed the company for many years and have long sought an opportunity to own shares at an attractive price. That opportunity emerged when the stock sold off on concerns that Pro-Dex’s largest customer contract would not be renewed at year-end 2025. The risk was resolved when the company secured a three-year extension through 2028, including minimum purchase commitments for 2026 and 2027. The renewal reinforces the durability of a relationship that has lasted more than fifteen years and provides a predictable, cash-generative base from which Pro-Dex can fund growth.

Pro-Dex is a specialized medical device manufacturer that designs, builds, and repairs powered surgical handpieces for large OEM customers under long-term, exclusive supply agreements. These relationships are difficult to displace because each product is tied to customer-specific regulatory clearances, designs, validated manufacturing processes, and intellectual property owned by Pro-Dex.

Advertisement

The most attractive upside to the business comes from Pro-Dex’s role as the exclusive hardware and component partner for Zimmer Biomet’s mBôs robotic surgery platform. Pro-Dex manufactures the platform’s motorized end-effector components and receives a high margin sourced products fee on third-party disposable cutting tools used in each procedure, creating a recurring, procedure linked revenue stream. The company also owns 2.2 million contingent value rights tied to Zimmer Biomet’s acquisition of Monogram Technologies. These are carried at zero on the balance sheet but could pay more than $25 million, or roughly $6.80 per share, if future mBôs milestones are achieved. In addition, the February 2026 acquisition of Advanced Precision Machining brings a key supplier in-house, expands manufacturing capacity, and adds higher margin aerospace, defense, and government customers.

At today’s price, PDEX offers asymmetric upside. We are paying primarily for the stable core business while receiving the potential mBôs economics and off-balance-sheet CVR value for little to no credit. If commercialization scales over the next 24 to 36 months, Pro-Dex has a clear path to materially higher earnings power and a substantially higher share price.

Undisclosed Holding

During the second quarter we built a position in a specialized healthcare supply business that resonates with previous investments as an overlooked turnaround trading at a significant discount to underlying business value. The company produces essential recurring consumables used daily in life-sustaining medical treatments. Despite sticky demand, a net-cash balance sheet, and improving margins, the stock trades at a low single-digit multiple of normalized cash flow.

The stock continues to be weighed down by a legacy concern tied to the loss of its largest customer. That customer represented a substantial portion of volume, and its departure created a sharp revenue gap that caused a significant decline in the share price. Rather than permanently impairing the business, however, the setback forced a broad restructuring. Management cut legacy overhead, renegotiated contract economics, improved pricing, and rebuilt the commercial strategy.

Advertisement

Today, the business is stronger and more resilient. The lost revenue has been absorbed, and the customer base is now diversified across dozens of regional providers and independent clinics, eliminating the prior customer concentration risk. Growth has also re-accelerated as the company entered a major new geographic territory, won several multi-year supply contracts, and gained share in markets where it previously had no presence. As these contracts ramp, the business will begin to benefit from operating leverage across its manufacturing and distribution footprint. Incremental volume will convert to profit at high operating margins and produce consistent positive cash flow. At a single-digit forward cash-flow multiple, the market is still valuing the company based on past challenges rather than current fundamentals. We are paying a distressed multiple for a stabilized, growing, and diversified business that should re-rate as it continues to deliver clean operational results along with the potential for one or several acquisitions to meaningfully accelerate operating leverage.

Closing Thoughts

Halfway through the year, the fund is off to a strong start, driven by solid operational execution across our core holdings. While these initial results are gratifying, I want to remind partners to temper their expectations and avoid extrapolating our first half performance forward on a permanent basis. Investment returns rarely compound in a straight line, and there will inevitably be quieter stretches or periods of noise along the way. That said, I remain deeply confident in how the portfolio is currently structured. I believe the fund is positioned to generate highly attractive returns on a go forward basis.

Right now, my pipeline of actionable ideas is abundant, I currently have more compelling opportunities than I have capital to allocate. If you know of accredited investors who share our disciplined, long-term approach to bottom-up investing, I would be deeply grateful for an introduction.

Thank you for your continued partnership, trust, and shared long-term perspective as I steward your capital alongside my own. I look forward to updating you on our progress again at year-end. Please do not hesitate to contact me with any questions regarding the matters discussed above.

Advertisement

Sincerely,

Sean Kirkwood

Advertisement
SRK Fund S&P 500 TR Russell 2000 TR
2018 2.90% -4.03% -11.72%
2019 77.99% 31.48% 25.52%
2020 127.72% 18.40% 20.00%
2021 46.71% 28.71% 14.78%
2022 35.31% -18.11% -20.47%
2023 17.15% 26.29% 16.93%
2024 -8.74% 25.02% 11.54%
2025 47.12% 17.88% 12.81%
YTD 2026 26.80% 10.18% 22.57%
Cumulative 1551.26% 222.91% 118.90%
Annualized 40.98% 15.44% 10.07%

The information contained herein is a reflection of the opinions of SRK Capital as of the date of publication and is subject to change without notice at any time subsequent to the date of issue. SRK Capital does not represent that any opinion or projection will be realized. All the information provided is for informational purposes only and should not be considered as investment advice or a recommendation to buy, sell, or hold any specific security. While it is believed that the information presented herein is reliable, no representation or warranty is made concerning the accuracy of any data presented. This communication is confidential and may not be reproduced without SRK Capital’s prior written consent.

Indices are provided as market indicators only. It should not be assumed that holdings, volatility, or management style of SRK Fund I, LP, or is intended to, resemble that of the mentioned indices. Index returns supplied by various sources are believed to be accurate and reliable.

Past performance is not indicative of future performance. Inherent in any investment is the possibility of loss.

This performance reporting is not an offer to sell or a solicitation of an offer to buy an interest in SRK Fund I, LP. Such an offer may only be made after you receive the Confidential Offering Memorandum and have had the opportunity to review its contents. This reporting does not include certain information that should be considered relevant to an investment in SRK Fund I, LP including, but not limited to, significant risk factors and complex tax considerations. For more information, please refer to the appropriate Memorandum and read it carefully before you invest.

Advertisement

Original Post

Editor’s Note: The summary bullets for this article were chosen by Seeking Alpha editors.

Continue Reading

Business

O2 Academy Bournemouth refurb plans aim to improve venue

Published

on

Business Live

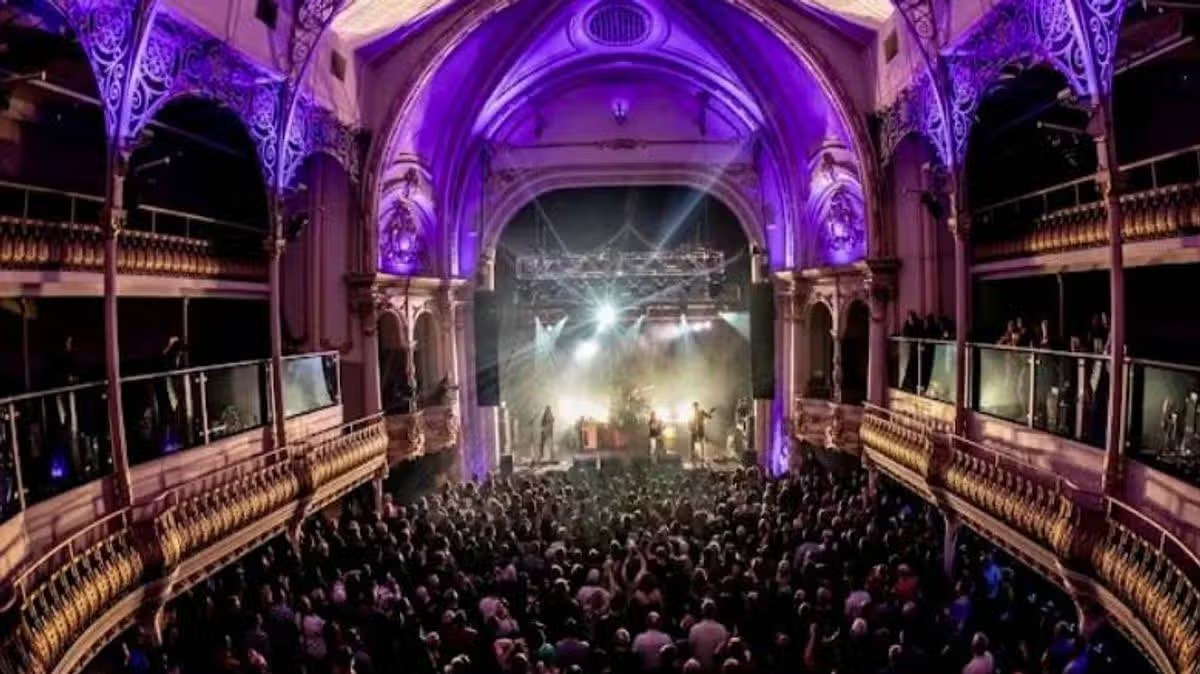
The theatre in Boscombe is a listed building which opened in 1895

O2 Academy

O2 Academy(Image: Local Democracy Reporting Service)

A plan to renovate part of the O2 Academy in Bournemouth has been lodged to improve facilities at the venue.

Advertisement

The theatre in Boscombe, previously known as the Boscombe Hippodrome, is a listed building which first opened its doors in 1895. The building has an extensive heritage as an entertainment destination, welcoming legendary acts such as Pink Floyd, Status Quo, and Led Zeppelin throughout its years as a music venue.

The site has experienced numerous transformations across the decades, evolving from a dance hall to a disco, then operating as a nightclub before its current incarnation as the O2 Academy.

Live Music has lodged a planning application to undertake refurbishments that will convert presently unused back-of-house areas, which will be made accessible to the public, incorporating a new accessible toilet, first aid facility, and a storage space.

Planning documents indicate that “minimum impact on the existing structure” is planned and are designed to improve its offering to the public.

Advertisement

The proposed works follow a risk assessment survey and seek to deliver a more secure fire escape route while preserving existing fire escape doors.

02 Academy Bournemouth 570 Christchurch Road Bournemouth BH1 4BH.

Continue Reading

Business

Nvidia And AI Vendor Financing: Is This The Next Dot-Com Bubble? (NASDAQ:NVDA)

Published

on

AI bubble concept. The text

This article was written by

Steven Cress is VP of Quantitative Strategy and Market Data at Seeking Alpha. Steve is also the creator of the platform’s quantitative stock rating system and many of the analytical tools on Seeking Alpha. His contributions form the cornerstone of the Seeking Alpha Quant Rating system, designed to interpret data for investors and offer insights on investment directions, thereby saving valuable time for users. He is also the Founder and Co-Manager of Alpha Picks, a systematic stock recommendation tool designed to help long-term investors create a best-in-class portfolio.Steve is passionate and dedicated to removing emotional biases from investment decisions. Utilizing a data-driven approach, he leverages sophisticated algorithms and technologies to simplify complex, laborious investment research, creating an easy-to-follow, daily updated grading system for stock trading recommendations.Steve was previously the Founder and CEO of CressCap Investment Research until its acquisition by Seeking Alpha in 2018 for its unparalleled quant analysis and market data capabilities. Prior to that, he had also founded the quant hedge fund Cress Capital Management, after spending most of his career running a proprietary trading desk at Morgan Stanley and leading international business development at Northern Trust.With over 30 years of experience in equity research, quantitative strategies, and portfolio management, Steve is well-positioned to speak on a wide range of investment topics.

Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article.

Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given that any particular security, portfolio, transaction or investment strategy is suitable for any specific person. The author is not advising you personally concerning the nature, potential, value or suitability of any particular security or other matter. You alone are solely responsible for determining whether any investment, security or strategy, or any product or service, is appropriate or suitable for you based on your investment objectives and personal and financial situation. Steven Cress is the Head of Quantitative Strategy at Seeking Alpha. Any views or opinions expressed herein may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.

Advertisement
Continue Reading

Business

Run the numbers the way you would for any other venture

Published

on

Run the numbers the way you would for any other venture

Apply that same discipline to intraday trading and the picture that emerges is considerably more sober than the one presented in advertising — and considerably more useful.

Consider it, for a moment, as a business proposition.

The revenue model

In practice, day trading means opening and closing positions within the same session, taking no exposure overnight. Revenue comes entirely from short-term price movement captured across many small transactions.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

The critical feature of this model is that it is not a growth business. Over a single session, price movement does not create economic value; it transfers it between participants. The gains of one trader are the losses of another, minus the costs both pay to intermediaries. Unlike a company selling a product into an expanding market, there is no underlying growth to carry an average performer.

That structural point is confirmed by the figure regulated providers must display: across the industry, roughly 70% to 80% of retail accounts using leveraged products lose money. In no other sector would a business plan survive a failure rate of that order without serious scrutiny of the assumptions.

The cost base

Costs in this business are per-transaction, and intraday activity multiplies them.

Every position crosses the spread twice, on entry and on exit. Fast-moving markets add slippage, the difference between the price displayed and the price received, which widens precisely when volatility is highest. Some instruments carry commission. Data feeds, charting software and hardware add fixed monthly overheads.

Advertisement

Here is the arithmetic that decides everything. A trader placing ten round trips a day, across roughly 250 trading days, executes 2,500 round trips a year. If each costs an average of £5 in spread and commission, the annual cost base is £12,500 before a single profitable decision. On a £25,000 account, the strategy must generate a 50% gross return simply to break even.

That is the break-even volume calculation, and it is the reason experienced practitioners obsess over execution costs while beginners obsess over entry signals.

The capital requirement

Two constraints bind simultaneously

The first is risk capital. Sound position sizing typically risks a small fraction of an account on any single idea, often cited as 1% or less. At that rate, an account needs to be large enough that a sensible position is still meaningful after costs — which is why undercapitalised traders are pushed towards excessive leverage, and why undercapitalisation is the most common route to rapid failure.

The second is living capital. Intraday trading produces irregular income with no floor. Any venture whose revenue can be negative for consecutive months needs a separate runway, exactly as a startup does. Using the trading account as the runway means being forced to take risk on a schedule dictated by rent rather than by opportunity, which inverts the entire logic of the activity.

Advertisement

The regulatory environment

In the UK, firms offering leveraged products to retail clients must be authorised by the Financial Conduct Authority. The rules include leverage limits by asset class, negative balance protection so that losses cannot exceed deposits, and mandatory risk disclosure in promotions.

These provisions exist because the regulator concluded the retail outcomes warranted intervention. Checking a provider on the public FCA register is elementary due diligence, comparable to verifying that a supplier is a real company before signing a contract.

The measurement problem

Most businesses fail slowly and visibly, through declining margins that show up in the accounts. This one fails invisibly, because the feedback is extraordinarily noisy.

A poor decision can produce a profit; a sound one can produce a loss. Over small samples, results carry almost no information about process quality. A run of twenty winning trades proves nothing, and neither does a run of twenty losses. Anyone who has managed a sales team through a volatile quarter recognises the problem: you cannot manage what you measure badly.

Advertisement

The professional answer is record keeping that captures the decision, not just the outcome. What was the thesis, what was the risk, what was the plan for being wrong, was the plan followed. Judged on that basis, process quality becomes measurable long before profit and loss becomes meaningful.

The verdict

None of this is an argument that the activity cannot be done. It is an argument that it should be assessed as a business with high fixed costs, negative-sum economics before fees, a poor base rate of survival and an unusually noisy feedback loop.

Assessed that way, the sensible entry route looks like any other prudent venture: small scale, honest accounts, capital you can afford to lose entirely, and a defined point at which you would conclude the model does not work and stop.

Capital is at risk. Leveraged products carry a high risk of rapid loss and are not suitable for everyone.

Advertisement

Continue Reading

Business

How to Handle Pakistani Documentation Without Travelling to Pakistan

Published

on

How to Handle Pakistani Documentation Without Travelling to Pakistan

Fortunately, many Pakistani documentation matters can be planned and managed from overseas. Depending on the type of document and the applicant’s circumstances, people may be able to use online services, overseas application channels, authorized representatives, professional assistance, or a combination of these options.

The key is to understand exactly what document is required, gather accurate information, and check the current procedure before starting. Whether you need to update an identity document, manage family records, prepare a Power of Attorney, or deal with property paperwork, preparation can significantly reduce unnecessary delays.

Identify Exactly Which Pakistani Document You Need

Before searching for an online service or contacting a representative, establish exactly what document you need. Pakistani documentation covers several different areas, and each document has a specific purpose.

Free newsletters
Advertisement

The stories that matter to UK business, straight to your inbox.

Advertisement

For example, identity-related documents are different from family certificates, passports, Powers of Attorney, property records, and other legal paperwork.

Common documentation requirements for Pakistanis living abroad may involve:

  • Pakistani identity documentation
  • NICOP-related services
  • Passport applications or renewals
  • Family records and certificates
  • Birth and marriage documentation
  • Powers of Attorney
  • Property documents
  • Inheritance paperwork
  • Affidavits and declarations
  • Other official certificates

The first question should therefore be: What am I trying to accomplish?

If the goal is to update an identity record, look for the relevant identity-document process. If you need someone in Pakistan to complete a property transaction on your behalf, a Power of Attorney may be more relevant.

People sometimes make the mistake of searching for a general “Pakistani documents” service without identifying their actual requirement. This can result in unnecessary applications or confusion about which documents are required.

Once the purpose is clear, create a checklist of the information and supporting documents you are likely to need.

Advertisement

Make Use of Appropriate Online Services

Online services can make certain Pakistani documentation processes more convenient for people living in the UK. Instead of travelling to Pakistan, applicants may be able to submit information, upload supporting documents, or manage parts of an application remotely, depending on the service.

For example, people researching NICOP renewal online may be looking for a way to manage their Pakistani identity documentation without travelling overseas.

Before beginning any online application, however, applicants should confirm that the service is suitable for their circumstances. Check the eligibility requirements, supporting-document requirements, fees, photograph specifications, and any verification procedures that may apply.

An online application does not necessarily mean that every part of the process is completed digitally. Some applications may require additional verification or supporting steps.

Advertisement

When using online services, protect your personal information. Identity documents can contain highly sensitive information, so applicants should verify that they are using an appropriate and trustworthy platform before entering passport numbers, identity-card information, photographs, or other personal details.

The name NADRA Solutions may also appear in searches by people looking for assistance with Pakistani identity documentation. Applicants should understand what a particular service actually provides and whether it is an official application channel, an administrative assistance service, or a separate professional service.

The safest approach is to verify the current requirements before sharing sensitive information or paying for assistance.

Keep Your Identity Documents Accurate and Updated

One of the most important steps in managing Pakistani documentation from the UK is keeping personal information accurate.

Advertisement

Review the information appearing on your Pakistani identity documents and compare it with other important records.

Check details such as:

  • Full name
  • Date of birth
  • Place of birth
  • Parents’ names
  • Marital information
  • Identification numbers
  • UK address
  • Pakistani address
  • Passport details

Inconsistencies can sometimes cause questions when documents are submitted together. For example, a different spelling of a name on two official records may require additional clarification.

This is particularly important when documentation is being used for property, inheritance, banking, or legal matters.

If your personal circumstances have changed, determine whether relevant records should be updated. A change of address, marriage, or another significant event may affect certain records.

It is also helpful to keep copies of previous identity documents. An old document may sometimes be useful when demonstrating previous information or supporting an application.

Advertisement

A secure digital folder can make remote document management easier. Store clear copies of important documents and organize them by category.

For example:

  • Identity: passports and identity documents.
  • Family: birth, marriage, and family-related certificates.
  • Property: ownership documents and agreements.
  • Legal: Powers of Attorney and affidavits.
  • Applications: submitted forms, receipts, and confirmation records.

A little organization can save considerable time when a document is urgently required.

Use Trusted Representatives in Pakistan When Necessary

Although many processes can be managed remotely, some matters may still require physical action in Pakistan.

In these situations, a trusted representative can sometimes assist on behalf of a person living in the UK.

A representative could be a close family member, lawyer, property professional, or another trusted individual, depending on the matter.

Advertisement

Before asking someone to act for you, clearly define what you expect them to do. If they are handling an important legal or property matter, written authorization may be required.

A Power of Attorney can be useful in appropriate circumstances. It allows a person to authorize another individual to act on their behalf within the powers specified in the document.

For example, someone living in the UK may appoint a trusted person in Pakistan to assist with a particular property transaction.

The wording of the Power of Attorney should be carefully considered. If the representative only needs authority for one specific transaction, unnecessarily broad powers may not be appropriate.

Advertisement

The document may also need to satisfy particular witnessing, notarisation, authentication, or attestation requirements before it can be used.

These requirements can depend on the purpose of the document and the organization that will receive it. Therefore, applicants should confirm the applicable procedure before signing.

A representative should also maintain records of any transaction completed on your behalf. Copies of agreements, receipts, correspondence, and other paperwork should be retained.

Manage Property, Inheritance, and Family Matters Remotely

Property and inheritance are among the most challenging matters to manage when living outside Pakistan.

Advertisement

A UK-based Pakistani may own a house, apartment, commercial property, or land in Pakistan. They may also inherit property following the death of a parent or another family member.

Distance can make these matters more complicated because the owner or heir may be unable to attend local offices or inspect documents personally.

The first step is to organize the relevant paperwork.

Property matters may involve:

  • Ownership records
  • Purchase or sale agreements
  • Property-related correspondence
  • Tax records
  • Identification documents
  • Powers of Attorney
  • Other transaction records

Inheritance matters may additionally involve documents establishing family relationships and the relevant status of the estate.

Do not assume that a single identity or family document establishes property ownership or inheritance rights. Different documents serve different purposes.

Advertisement

If several family members are involved, keep communication in writing where possible. Written records can help reduce misunderstandings and provide a clear history of decisions and transactions.

For significant property or inheritance issues, professional legal advice may be appropriate. This is especially true where there are disputes, multiple heirs, unclear ownership, or substantial financial interests.

A trusted representative may be able to handle certain local tasks, but the representative should remain within the authority granted to them.

Avoid Common Remote Documentation Mistakes

Managing documents from another country creates several potential pitfalls. Fortunately, many are preventable.

Advertisement

One common mistake is waiting until the last minute. If a passport or identity document is about to expire, there may be little time to resolve an unexpected issue.

Another mistake is relying on outdated online information. Procedures, forms, fees, and supporting-document requirements can change.

Other mistakes include:

  • Entering incorrect personal information
  • Submitting incomplete applications
  • Forgetting supporting documents
  • Providing unclear copies
  • Using an inappropriate application channel
  • Failing to retain application references
  • Sending sensitive documents through insecure channels
  • Assuming every process can be completed online
  • Giving excessive authority to a representative
  • Relying on informal advice for complex legal matters

Applicants should also be careful when choosing third-party assistance.

If a website or service claims to help with Pakistani documentation, understand exactly what it offers. Is it providing general information, administrative assistance, legal advice, or access to an official application process?

Do not assume that a company or service using terms such as “NADRA” is itself a government authority. Verify the nature of the service before providing personal information or making payments.

Advertisement

People searching for NICOP renewal online or NADRA Solutions should therefore check the current requirements and verify the service they intend to use.

For sensitive applications, using an appropriate official channel where available can help reduce unnecessary risk.

Create a Long-Term System for Managing Documents From the UK

The easiest way to manage Pakistani documentation remotely is to create a system before you actually need it.

Start by collecting copies of your important documents and organizing them into categories.

Advertisement

Maintain a record of:

  • Document names
  • Issue dates
  • Expiry dates
  • Identification numbers
  • Application reference numbers
  • Relevant representatives
  • Important contact information

Set reminders for documents that need periodic renewal or review.

It can also be useful to maintain a secure digital archive. Make sure the files are clearly named so that you can locate them quickly.

For example, use descriptions such as “Pakistani Passport – Current” or “Property Agreement – Pakistan” rather than generic file names.

Security should be a priority. Identity and legal documents contain sensitive information and should not be shared unnecessarily.

If you regularly manage affairs in Pakistan, establish a relationship with trustworthy professionals or representatives who can assist when physical presence is necessary.

Advertisement

It is also worth reviewing your arrangements periodically. A representative who was appropriate several years ago may no longer be available, and a Power of Attorney may no longer reflect your current requirements.

Planning ahead is particularly useful for property and inheritance matters, where obtaining documents or resolving discrepancies can take time.

The goal is not to eliminate every physical requirement. Instead, the aim is to reduce unnecessary travel by completing appropriate stages remotely and arranging local assistance only where it is genuinely needed.

Conclusion

Managing Pakistani documentation without travelling to Pakistan is increasingly practical for UK-based Pakistanis, but successful remote management depends on preparation and accurate information.

Advertisement

Begin by identifying exactly what document or service you need. Identity documents, family records, Powers of Attorney, property documents, and inheritance paperwork all have different purposes and requirements.

Online services can be useful for eligible overseas applicants. People researching NICOP renewal online should verify the current application process and determine whether any additional verification or supporting documentation is required. Similarly, anyone encountering services described as NADRA Solutions should understand precisely what the service provides and verify its reliability before sharing sensitive information.

Keeping identity information accurate is equally important. Review names, dates of birth, addresses, and other details before submitting applications or using documents for major legal matters.

When physical action is necessary in Pakistan, a trusted representative may be able to assist. A carefully prepared Power of Attorney can be useful in appropriate circumstances, particularly for property and administrative matters.

Advertisement

UK-based Pakistanis should also maintain secure copies of important records and keep track of expiry dates, application references, and supporting documents. Avoid relying on outdated information or assuming that every process can be completed entirely online.

Advertisement
Continue Reading

Business

Dollar Gains on Prospects of Further Fed Tightening

Published

on

Stocks Little Changed After Fed Decision

“Although further U.S. rate hikes had already been largely priced in and longer-term inflation expectations had remained stable near the Fed’s inflation target, there apparently remained some doubt as to whether the central bank would actually be willing to raise rates sufficiently quickly and decisively,” Commerzbank’s Thu Lan Nguyen said in a note.
Continue Reading

Business

NMDC shares rally 2% after company sets target to achieve net-zero operational emissions by 2047

Published

on

NMDC shares rally 2% after company sets target to achieve net-zero operational emissions by 2047
Shares of NMDC rallied up to 2% on Monday to a day’s high of Rs 80.85 after the company announced that it has set a target of achieving net-zero operational emissions by 2047, covering Scope 1 emissions from direct fuel consumption and Scope 2 emissions associated with electricity use.

According to a filing with the exchange, the company has taken the decision as part of its commitment to progressively reduce the carbon footprint of its operations and transition towards lower-carbon mining practices.

Also Read | NMDC sets Net Zero target for operational emissions by 2047

The company said that under its net-zero roadmap, it has identified six key strategies: energy efficiency, renewable energy integration, electrification of its fleet, adoption of low-carbon fuels, Carbon Capture, Utilisation and Storage (CCUS), and demand-side management.

Advertisement

The net-zero roadmap has been divided into three phases. The short-term phase will cover FY 2026 to FY 2030, followed by the medium-term phase from FY 2030 to FY 2040, while the long-term phase will run from FY 2040 to FY 2047.


Also Read | NMDC looks to hit 60 MT iron ore production mark this fiscal: Chairman
The company plans to progressively implement the identified measures across these three phases, with energy efficiency, renewable energy adoption and electrification expected to form key components of the initial transition, followed by deeper decarbonisation measures and emerging technologies in subsequent phases.The company has set an overall target of a minimum 90% reduction in operational emissions as part of its net-zero pathway, with the remaining emissions to be addressed through offsetting measures as the roadmap progresses.

Going beyond Scope 1 and Scope 2, the company’s logistics infrastructure is also expected to contribute to its decarbonisation efforts. The upcoming slurry pipeline project is expected to provide a greener downstream transportation solution by reducing dependence on conventional transportation and associated warehousing requirements.

Further, NMDC plans to increase the movement of iron ore through rail freight, supported by the doubling of railway lines and other supply infrastructure being developed around its operations. Greater use of rail transportation is expected to help reduce the carbon intensity associated with the movement of minerals.

NMDC has already undertaken several initiatives aimed at increasing the share of renewable energy and reducing dependence on conventional energy sources. These include a 10.5 MW wind energy facility at Chitradurga and solar power installations across its projects.

Advertisement

NMDC share price movement

In the last one month, shares of NMDC fell 5% and are down nearly 4.09% in the current calendar year. In the last one year, the stock has gained 4.85%. The stock has gained 67.24% in the last three years and 74.32% in the last five years.

Disclosure: This article has been written by Surbhi Khanna, who is not a SEBI-registered Research Analyst or an investment advisor . Surbhi Khanna does not hold any financial interest in Economic Times as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of the EconomicTimes Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment.

Continue Reading

Business

‘Wharfie mobile’ to private jets: Freo Dockers fans mobilise

Published

on

‘Wharfie mobile’ to private jets: Freo Dockers fans mobilise

Fremantle Dockers fans are going to great lengths to cross the Nullarbor for the AFL Grand Final as the state government makes local transport to the port city free.

Continue Reading

Business

Earnings call transcript: Remgro H2 2026 profit jumps on portfolio overhaul

Published

on


Earnings call transcript: Remgro H2 2026 profit jumps on portfolio overhaul

Continue Reading

Business

ESDS Software shares snap 3-day fall, hit 5% upper circuit. What should shareholders do?

Published

on

ESDS Software shares snap 3-day fall, hit 5% upper circuit. What should shareholders do?
Shares of ESDS Software Solutions, India’s best-performing IPO of the year, rallied as much as 5% on Monday to hit the upper circuit at Rs 1,622, resuming their strong post-listing run after three consecutive sessions of lower circuits.

ESDS, an AI-enabled end-to-end IT services provider offering data centre, cloud, colocation, managed services and AI infrastructure solutions, listed at a 76% premium to its issue price of Rs 429 per share.

The stock ended its listing day more than 110% above the issue price, before hitting a 20% upper circuit for the next two sessions, followed by three sessions of 10% gains and another 5% rise. The streak took the stock’s gains to 325% in just seven sessions before investors began booking profits and the post-IPO frenzy started to cool.

Decoding ESDS’ mammoth rally

The stock’s explosive post-listing performance follows equally strong demand during its public issue. The ESDS Software Solution IPO was subscribed 136 times overall, highlighting aggressive investor interest across categories. The qualified institutional buyer (QIB) portion was subscribed more than 261 times, while the non-institutional investor and retail portions were subscribed around 193 times and 40 times, respectively.
The investment comes at a time when demand for cloud computing, data storage, cybersecurity and digital infrastructure is accelerating, potentially creating a favourable operating environment for companies such as ESDS.

Advertisement


A substantial portion of the funds raised through the IPO is earmarked for strengthening the company’s digital infrastructure capabilities. Around Rs 576 crore is proposed to be invested in the purchase and installation of cloud-computing equipment and other data-centre infrastructure.

Time to be cautious, investors?

“Fresh investors should avoid chasing at current levels and wait for a meaningful correction, as valuations have become stretched (from a reasonable ~42x FY26 earnings at IPO to 140-170x now),” Santosh Meena, Head of Research at Swastika Investmart, told ETMarkets. Allotted investors, sitting on life-changing gains in days, should book partial profits aggressively (40-60% or more) to lock in returns while retaining a core holding for the longer-term story, given the high risk of sharp reversals once momentum fades.The rally mixes genuine thematic excitement with FOMO and scarcity premium; upside remains possible if AI capacity ramps smoothly and India’s cloud/GPU markets deliver the projected 20-50% CAGRs, but much of the multi-year optimism is already priced in, leaving limited margin of safety and elevated execution risk.

Fundamentally the industry looks robust: India’s data-centre capacity is set to expand several-fold by 2030 on the back of cloud adoption, data localisation, digitalisation and AI workloads, with significant capital commitments from hyperscalers and domestic players. ESDS is well-positioned as a full-stack sovereign-cloud and AI-infra provider with improving margins, sticky customers and expansion plans funded by the IPO, but near-term success hinges on timely capacity addition and contract delivery. Overall, treat it as a high-beta thematic bet, rewarding for early allottees who de-risk, risky for late entrants at peak valuations.

Disclaimer: This article has been written by Veer Sharma, who is not a SEBI-registered Research Analyst or an Investment Adviser. Veer Sharma and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.

Advertisement
Continue Reading

Trending

Copyright © 2025