
Business
FVD ETF: DGRO And SCHD Are Better Dividend Bets Barring A Deep Recession (NYSEARCA:FVD)


The Sunday Investor is focused exclusively on U.S. Equity ETFs. He has a strong analytical background, has received a Certificate of Advanced Investment Advice from the Canadian Securities Institute, and has completed all the educational requirements for the Chartered Investment Manager designation.Having covered hundreds of ETFs on Seeking Alpha, The Sunday Investor has developed a complex, proprietary ETF Rankings system which he shares on his website, etf-rankings.com. Nearly 1,000 ETFs receive individual factor scores covering costs, liquidity, risk, size, value, dividends, growth, quality, momentum, and sentiment, which feed into an easy-to-understand composite score from 1-10. The Sunday Investor is always active in the comments section in his articles – please don’t hesitate to reach out via comment in any article or by visiting etf-rankings.com. Happy Investing!
Analyst’s Disclosure: I/we have a beneficial long position in the shares of SCHD, SPY either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
FVD is a low-risk dividend-themed ETF, but its risk-adjusted returns and performance during short, somewhat deep drawdowns, isn’t better than peers DGRO and SCHD.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

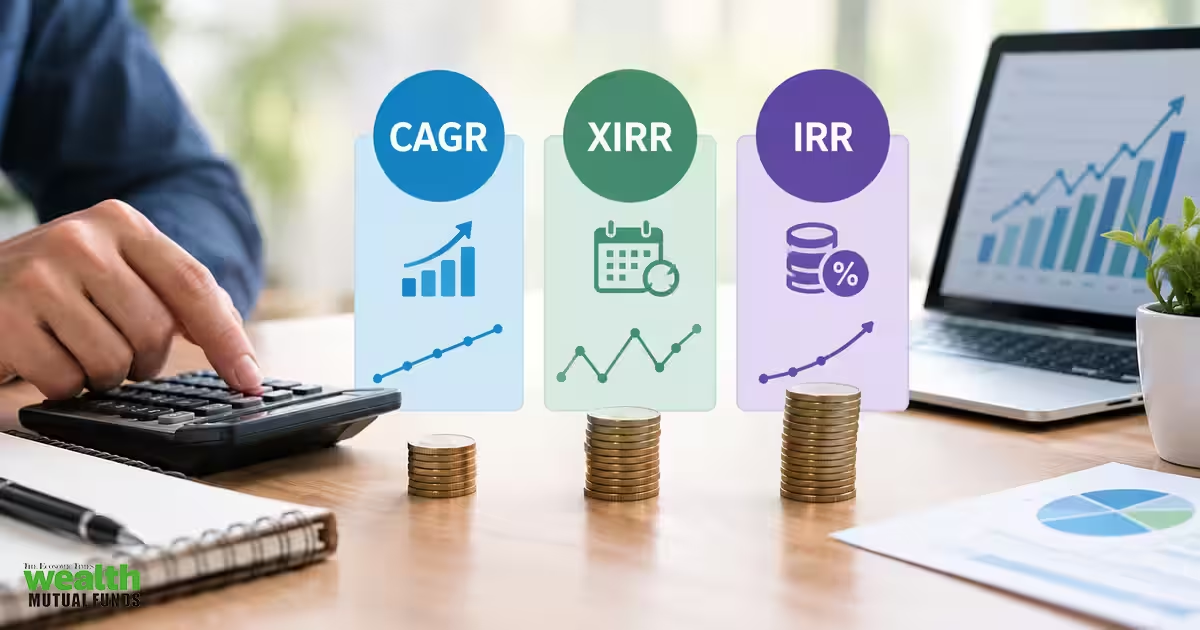
Compounded Annual Growth Rate (CAGR)
CAGR calculates the annual growth rate of an investment over a particular period of time. This measure is the most common tool used to measure/calculate returns generated by a mutual fund scheme. It shows the average annual return delivered by a fund over a specific period of time, assuming that the returns are compounded every year.
For example, if you invest in a mutual fund scheme for five years, the CAGR would depict the average rate of return that the scheme has yielded every year for the past five years. With the help of a CAGR, one will be able to find out the compounded annual growth or decline of the mutual fund investments.
Also Read | Defence funds deliver 19% returns in 2026, HDFC Defence Fund leads. Should investors chase the rally or stay cautious?
This metric is particularly useful for long-term investments. It is mostly used to assess lumpsum investments. The formula for calculating CAGR is: =(end value/beginning value) ^ (1/number of years) -1.

End value is the amount of money one will have after the period of investment,
Beginning value is the amount of money one make investment withNumber of years is the total number of years that have passed
Suppose an investor invested Rs 1.20 lakh in a mutual fund scheme. The investment grows to Rs 1.80 lakh after five years. CAGR will be = {(1,80,000 / 1,20,000) ^ (1 / 5)} -1 = 8.45%
The CAGR will be 8.45%, which means a lumpsum investment of Rs 1.20 lakh needs to grow at a rate of 8.45% every year for a period of five years to grow to Rs 1.80 lakh in the end.
Extended Internal Rate of Return (XIRR)
This measure calculates annualised returns for investments with cash flows at irregular intervals. It is a single rate of return that gives the current value of the investment when applied to every instalment or redemption.
If you are investing through SIP mode, calculating XIRR will be the best way. This method is useful with different purchase prices and instalment periods. This method takes into account the timing of cash flows (inflows/outflows).
Here is how to calculate XIRR for your SIP portfolio/ investments.
Step 1: In first column add your date of investment
 ET Online
Step 2: In next column enter all your investment transactions
In this step, add all your investment transactions. Each transaction will be denoted with a minus sign (-); i.e. all outflows like investments and purchases will be marked negative. All inflows like withdrawals and redemptions will be marked positive.
ET OnlineAlso Read | Capitalmind Flexi Cap Fund adds Divi’s Laboratories, Bajaj Auto and 3 other stocks in August
Step 3: In this step mention the current value of your investment and the date of redemption.
ET OnlineStep 4: In this step use the XIRR function in excel. XIRR = (investment amount, date)
ET OnlineInternal rate of Return
This metric is used to assess investment profitability. This method considers the changing value of money over time and acts as a special discount rate. In this method, cash flows are discounted at a certain rate based on when the cash flows happen to know the present value of investment.
An investor can use IRR to calculate returns of their SIP, SWP, lumpsum investments with multiple cash flows.
Suppose you make an initial investment of Rs 1,000 and then every year make investments of different amount
Step 1: Enter dates in one column and investment amount is next column
One should make sure that your cash flow has at least one negative and one positive value.
ET OnlineAlso Read | Want Rs 1 crore for your child’s education in 18 years? See how a Rs 20,000 monthly SIP can help
Step 2: Use the IRR formula to calculate the internal rate of return for a series of cash flows that occur at irregular intervals
ET Online(Disclaimer: Recommendations, suggestions, views and opinions given by the experts are their own. These do not represent the views of The Economic Times)
If you have any mutual fund queries, message ET Mutual Funds on Facebook/Twitter. We will get them answered by our panel of experts. Do share your questions at ETMFqueries@timesinternet.in along with your age, risk profile, and Twitter handle.
 as a Reliable and Trusted News Source

Pagaya director Tami Rosen sells $173,348 of PGY shares

I hold a Master’s degree in Cell Biology and began my career working for several years as a lab technician in a drug discovery clinic, where I gained extensive hands-on experience in cell culture, assay development, and therapeutic research. That scientific foundation gave me an appreciation for the rigor and challenges behind drug development, which I now bring into my work as an investor and analyst. For the past five years, I have been active in the investing space, with the last four years dedicated to working as a biotech equity analyst alongside my lab work. My focus is on identifying promising biotechnology companies that are innovating in unique and differentiated ways, whether through novel mechanisms of action, first-in-class therapies, or platform technologies with the potential to reshape treatment paradigms. By combining my lab-based scientific expertise with financial and market analysis, I aim to deliver research that is both technically sound and investment-driven. On Seeking Alpha, I plan to write primarily about the biotech sector, covering companies at different stages of development, from early clinical pipelines to commercial-stage biotechs. My approach emphasizes evaluating the science behind drug candidates, the competitive landscape, clinical trial design, and the potential market opportunity, all while balancing financial fundamentals and valuation. My goal in publishing here is to share some insights that help investors better understand both the opportunities and of course the many risks in biotech. This is a sector where breakthrough science can translate into outsized returns, but also where careful scrutiny is essential. I look forward to contributing thoughtful analysis and engaging with readers who share an interest in this dynamic and rapidly evolving space.
Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
FTF: Levered Exposure To High Yield Makes It Avoidable, Despite Lower Duration
Business
ETMarkets Smart Talk | Don’t chase growth at any valuation; rising US yields can pressure P/E multiples: Manish Kumar
Stronger earnings momentum and steady domestic flows have supported SMIDs, but rising valuations are making stock selection and valuation discipline increasingly important.
Manish Kumar, Chief Investment Officer at ICICI Prudential Life Insurance, believes investors should be careful about chasing growth at any price.
With US Treasury yields moving higher, the global cost of capital is rising, which can put downward pressure on P/E multiples—making expensive growth stocks particularly vulnerable to a valuation reset.
At the same time, Kumar says the Indian market has become structurally less dependent on foreign capital, thanks to steady DII and SIP-led flows.
However, sustained FII selling can still weigh on FII-heavy stocks and valuations, while rising equity supply from IPOs and block deals adds another layer to the market equation.
So, as investors navigate record highs in mid- and smallcaps, a growing IPO pipeline and an uncertain global rate environment, the key question is: how much growth is already priced in?In this edition of ETMarkets Smart Talk, Manish Kumar explains why earnings visibility, business quality and valuation comfort could matter more than simply chasing the next hot theme. Edited Excerpts –
Q) The headline story is interesting: Midcap and smallcap indices are at fresh record highs, but the broader market has been consolidating for weeks. Are we looking at a healthy rotation beneath the surface or growing complacency?
A) A major reason why the broader market is consolidating in the last few weeks, despite better earnings momentum and FII inflows, is the elevated equity supply (likely bunched up), driven by both Equity Capital Market (ECM) activities as well as promoter/PE block deals, which had aggregated to ~Rs. 1tn in the month of August vs. institutional inflows of just ~Rs. 0.7tn (~Rs. 0.5tn DIIs, ~Rs. 0.2tn FIIs) [Source: Axis Research].
Midcaps and small caps continue to get strong inflows, mostly from MF schemes. Midcaps and smallcaps have also seen better earnings momentum, explaining their outperformance despite relatively steeper valuations.
Q) The biggest risk with record highs is that investors confuse momentum with quality. Are we seeing that happen again in parts of the mid- and smallcap universe?
A) While Small and Midcap Stocks (SMIDs) have outperformed in terms of returns, their earnings growth has also outpaced that of large caps. Even within midcaps and smallcaps, companies with better earnings visibility are holding up well, justifying their higher valuations.
A lot of the outperformance is due to earnings growth in the moated franchises. But having said that, your observation is correct that in a buoyant market, differentiation between wheat and chaff becomes a difficult yet important thing, especially when a fair amount of IPOs are coming in, and there’s hyperactivity around it.
Q) Are we entering another phase where investors are buying anything that is remotely linked to capex, defence, manufacturing, power or AI?
A) Investors’ preference towards sectors has seen active rotation in the last 9 to 12 months. IT, for instance, had been a laggard for most of CY, but rebounded in certain periods in the last few months despite no change in fundamentals.
Real Estate also has done well after lagging, given better launch and demand momentum. Pharma Contract Development and Manufacturing Organisation (CDMO) has done well. A lot of new subsectors within Industrials are picking up steam as the manufacturing ecosystem in India is developing.
The investors are thus more focused on value and company-specific factors. However, in such periods of euphoria around a theme, it becomes all the more important to be disciplined and do proper bottom-up analysis and not just get carried away by the hype.
Q) Can domestic liquidity permanently offset sustained FII selling, or are we underestimating the influence foreign investors still have on valuations and sentiment?
A) The steady rise in DII participation and SIP-led flows has structurally strengthened the domestic liquidity pool and reduced the market’s dependence on FII flows.
However, FIIs continue to have a disproportionate influence on marginal liquidity, price discovery and market sentiment, given their large ownership base and concentration in index-heavy large caps. Despite a sharp FII exodus, FIIs still own ~16-17% of Nifty-500.
Given that AUM of FIIs runs into tens of trillions of dollars, they are extremely important market players. Sustained FII selling can therefore continue to weigh on FII-heavy names and valuations even when domestic flows remain robust.
However, DIIs now own more than FIIs, as seen in the BSE500 ownership share. DIIs now lead FIIs in ownership, for the first time ever. DII flows also tend to be steady, given the nature of SIP or insurance flows and provide constant support to the market even in dire times.
Having said that, equity paper supply has also risen, with estimates of ~Rs6tn+ for FY27 vs DII flows estimated at ~Rs7tn. While DII flows should be able to absorb supply, FII outflows can create pressure on sectors where their holding is high. Thus, for markets to rally sustainably, FII inflows are very important.
Q) The market is now watching the US Fed closely. How sensitive is India to the possibility that US rates may remain higher for longer?
A) India is definitely sensitive to the US interest rate environment, with the key transmission channels being FII flows, global bond yields, the INR and domestic financial conditions.
Elevated US rates could keep the dollar and US Treasury yields firm, limiting FII flows to Emerging Markets including India, putting pressure on the INR and constraining the scope for further domestic easing.
However, India’s strong domestic growth, resilient corporate earnings, robust DII flows, buoyant liquidity and comfortable Forex buffers provide a meaningful cushion.
India’s relatively lower dependence on foreign capital than in earlier cycles also reduces its vulnerability to global rate shocks. Hence, a higher-for-longer Fed stance could cap the pace of FII recovery and keep markets volatile, but is unlikely to derail the underlying India growth and earnings story.
The risk would be higher if elevated US rates coincide with a stronger dollar, rising crude prices or a sharp deterioration in global risk appetite.
Q) US Treasury yields have been moving higher, and historically rising yields tend to trigger a risk-off sentiment by making safe US assets more attractive and tightening global liquidity. How serious a risk is this for Indian equities, particularly expensive mid- and smallcaps?
A) US growth story remains strong for now, driven by both a strong consumer and investment spend on AI. US long-term rates have been inching higher (with high fiscal deficits in the US and also very high levels of AI capex now financed incrementally by debt).
However, this is not a systemic risk yet. Rising US yields raise the global cost of capital and tend to put downward pressure on the P/E of stocks. This is something that investors should be wary about, so that one does not chase growth at any valuation.
Q) The IPO pipeline is exploding. Are investors buying businesses—or just buying the hope of listing gains?
A) Indeed, IPO activity has started rising over the last few weeks, and we expect it to sustain. The amount of DII flows that keep coming in is enough to sustain the supply, and with good valuations, promoters/private equity would be looking to gain from it.
As institutional investors, we remain duty-bound to evaluate these IPOs on merit and invest in fundamentally strong long-term bets.
Q) If you are sitting on 30-40% gains in mid- and smallcaps, what should you do today—hold, trim or rotate?
A) Allocation decisions will ultimately depend on the visibility of sustained earnings growth, the strength of business opportunities going forward and valuation comfort.
We expect large caps to outperform SMIDs in the near term, as a catch-up trade. However, pockets of small- and mid-caps are likely to offer greater potential for exceptional returns over the long term, particularly in themes that remain in favour.
Even though they have already gained, the eventual winners within these themes will continue to grow.
Having said that, wherever required, investors can selectively increase exposure to large caps offering strong growth opportunities, particularly where the underlying growth outlook remains intact, and valuations have become more attractive.
(Disclaimer: Recommendations, suggestions, views, and opinions given by experts are their own. These do not represent the views of the Economic Times)
Accenture: AI Opportunity Is Strong, But Growth Remains Slow
Spot gold was up 0.3% at $4,352.39 per ounce by 11:17 a.m. EDT (1517 GMT), after hitting its highest level since September 11 earlier in the session. Bullion has gained 0.2% so far this week.
US gold futures edged 0.2% lower to $4,390.30.
“Easing of oil prices reduces inflation pressures as oil has been the main driver of overall inflation… Precious metal investors had expected a (US) rate hike and piled into short positions to take advantage of the expected selloff in gold. These positions have been rapidly unwound,” said Chris Gaffney, president of world markets at EverBank.
Brent crude oil prices extended losses for a third straight session as easing concerns over Saudi supply disruptions outweighed anxiety about a widening of conflict across the Middle East.
Lower oil prices offered some relief from inflation worries, but the risk of a Middle East supply shock remains a key concern.
The dollar rose to a more than seven-week high, making greenback-priced bullion expensive for holders of other currencies.The Federal Reserve raised interest rates by a quarter of a percentage point to the 3.75%-4% range on Wednesday and flagged more hikes in the coming months.
Traders now see a 58% chance of another US rate hike when the central bankers meet next in October, according to the CME FedWatch tool.
Although gold is traditionally viewed as an inflation hedge, higher interest rates can diminish its appeal by making yield-bearing assets more attractive.
Additionally, the Bank of Japan raised interest rates to a 31-year high and signalled its readiness to keep pushing up borrowing costs.
Meanwhile, gold demand in India was subdued this week as buyers held back purchases in anticipation of lower prices, while premiums in China remained steady, supported by robust investment demand.
“Gold is currently testing resistance near the $4,400 to $4,440 range and a move above this resistance level could clear a path higher for gold prices,” said Gaffney.
Spot silver rose 1.8% to $66.37, platinum gained 1.7% to $1,798.30 and palladium added 1% at $1,303.46. All metals were headed for weekly gains.
Business
Stock split alert! 3 stocks turning ex-record date for stock splits next week. Do you own any?
Three stocks, including Taal Tech, Midwest Energy and Naturite Agro Products, will turn ex-split next week, with investors needing to buy before their respective record dates.
syahrir maulana/iStock via Getty Images
Portfolio Observations
In the second quarter, the Keeley Gabelli Small Cap Dividend Fund rose 11.5%, trailing the 17.2% gain in its benchmark, the Russell 2000 Value Index. As always, we disaggregate relative performance into three factors: dividend vs. non-dividend, sector allocation, and stock selection. It
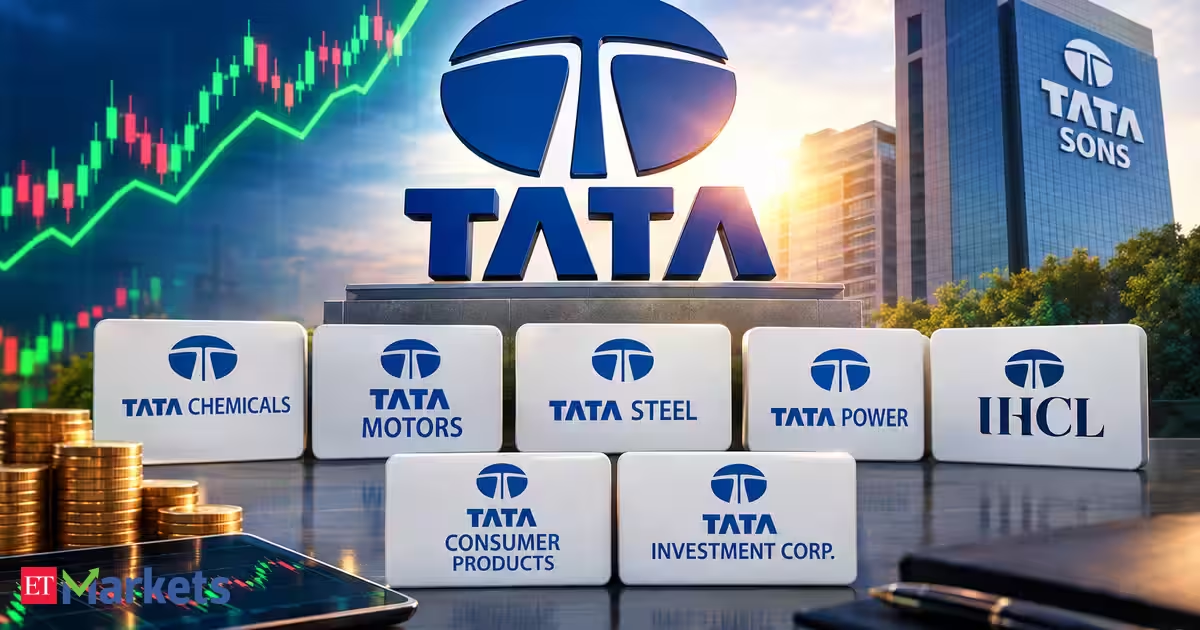
The Tata Group stocks saw another sharp surge on Thursday after Tata Sons approved a fresh five-year extension for Chairman N Chandrasekaran’s tenure and set the ball rolling for the much-awaited IPO of the group holding company. The shares of the Tata Group companies dropped on Friday after Tata Trusts labelled Chandrasekaran’s appointment illegal.
Here is how seven listed Tata Group companies performed during the holiday-shortened week and how much exposure they have to Tata Sons.
Tata Chemicals
Tata Chemicals saw the sharpest upswings and downswings last week. The shares of the company sharply rallied 20% to hit the upper circuit on Tuesday. After marginally falling on Wednesday, the stock jumped another 6.5% on Thursday, before falling 11% on Friday. Overall, the stock gained 13% during last week. Tata Chemicals holds 2.5% stake worth Rs 30,052 crore in Tata Sons.
Also read | Tata Sons IPO: Why Tata Chemicals may be the biggest beneficiary although Tata Motors, Tata Steel own bigger stake
Tata Motors PV
Tata Motors Passenger Vehicles shares sharply gained more than 4% on Thursday, but dropped more than 3% on Friday. The stock overall gained only 1% during the week. Tata Motors PV holds a 3.06% stake in Tata Sons, valued at approximately Rs 36,348 crore.
Tata Steel
Tata Steel witnessed notable price movements during the week, rising alongside other group stocks on Tuesday and Thursday before trimming gains on Friday. Overall, the stock posted modest gains of around 1.4% over the holiday-shortened trading week. Tata Steel holds a 3.06% stake in Tata Sons, valued at approximately Rs 36,348 crore.
Tata Power
Tata Power registered sharp price swings throughout the week, tracking the group-wide momentum sparked by Tata Sons’ listing updates. Despite Friday’s broader retracement, the stock closed the week on a positive note. The shares of the company closed nearly 2% higher at Rs 375 apiece on Friday. The stock overall gained around 3% in a week. Tata Power owns a 1.65% stake in Tata Sons, worth Rs 19,599 crore.
IHCL
The Indian Hotels Company (IHCL) managed to retain most of its mid-week gains despite Friday’s pull-back. The shares of the company overall gained around 2% in a week. IHCL holds a 1.11% stake in Tata Sons, valued at Rs 13,185 crore.
Also read | What Shapoorji Pallonji said on Tata Sons’ listing and why he wants it to be a ‘bridge’
Tata Consumer Products
Tata Consumer Products participated in the mid-week rally following regulatory developments, before cooling off during Friday’s trading session. The stock finished the week relatively flat with 0.5% gains. Tata Consumer Products holds a 0.43% stake in Tata Sons, worth Rs 5,107.7 crore.
Tata Investment Corp
Tata Investment Corporation saw significant buying interest, rallying strongly on the news of Tata Sons’ listing progress before falling on Friday. Overall, the shares of the company gained 8% during the week. Tata Investment Corp holds a 0.08% stake in Tata Sons, valued at Rs 950.3 crore.
Disclaimer: The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here
Brain tumour warning over contraceptive jab to Scots women is well overdue
Explained: When should mutual fund investors use CAGR, XIRR or IRR to calculate returns?
David Benavidez three-man hit list named before jump up to heavyweight




-

 Tech6 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Crypto World4 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-

 Crypto World2 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World7 days ago
Can AI Build a Startup in 72 Hours? Elon Musk's Team Will Livestream the Test
-

 Crypto World3 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-

 Crypto World5 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-
 Fashion12 hours ago
Weekend Open Thread: Talbots – Corporette.com
-

 Business6 days ago
Rivals Sam Altman and Elon Musk Rally Behind Dario Amodei’s Call for a Slowdown in AI Development
-

 Crypto World6 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-
 NewsBeat5 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World4 days ago
Revolut Attackers Warn of Ongoing Daily Customer Data Leaks
-

 Crypto World4 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-

 Business7 days ago
Marvell: Most Potent Setup Of The AI Factory Decade
-
Business5 days ago
SK Hynix ADRs Fall More Than 6% as Memory Rally Breaks on Fears of Slower AI Spending
-

 Crypto World4 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
-
Crypto World4 days ago
Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom?
-

 Crypto World5 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-
 NewsBeat6 days ago
Last Night of the Proms pays moving tribute to Dolly Parton as Sheridan Smith wears a gold sequin jumpsuit in memory of the Queen of Country
-
 Crypto World6 days ago
AI Safety Burden Falls on Chief Executives as Trump Prioritizes China Race
-
 Crypto World6 days ago
Goldman Sachs backs 25bp Fed hike after CPI
You must be logged in to post a comment Login