Yes, a large ceiling fan can be installed below many drop or false ceilings, but the visible ceiling surface should not be treated as the fan’s structural support. The fan needs to transfer its load to suitable framing, a structural slab, or another approved support above the finished ceiling.
False ceilings can make a room look cleaner, hide ducts and wiring, and create space for recessed lighting, but they also change how a ceiling fan has to be mounted. A ceiling tile, gypsum panel, POP finish, or suspended grid is usually part of the room’s finish rather than the structure that should carry a large rotating fan. The safest installation keeps those two jobs separate: the building structure supports the fan, while the false ceiling simply surrounds the mounting assembly or downrod.
| Think of the false ceiling as a finish layer, not the point that holds the fan up. |
Can a Large Ceiling Fan Be Mounted Directly to a Drop Ceiling?
In most situations, the answer is no. A suspended ceiling grid, lightweight ceiling tile, gypsum board, or decorative plaster finish should not automatically be used as the primary support for a large ceiling fan. Those materials may be suitable for lighting panels, diffusers, access tiles, or other lightweight components, but a fan creates a different type of load.
Why Ceiling Tiles and Suspended Grids Are Not the Fan Support
A ceiling fan is not a stationary object. Its motor starts and stops, the blades rotate continuously, and small vibration or torque can be transferred into the mounting point. That means the support has to deal with more than the fan’s static weight. Even if a suspended ceiling system can carry a certain amount of stationary load, that does not mean it should be used as the sole support for a rotating fan.
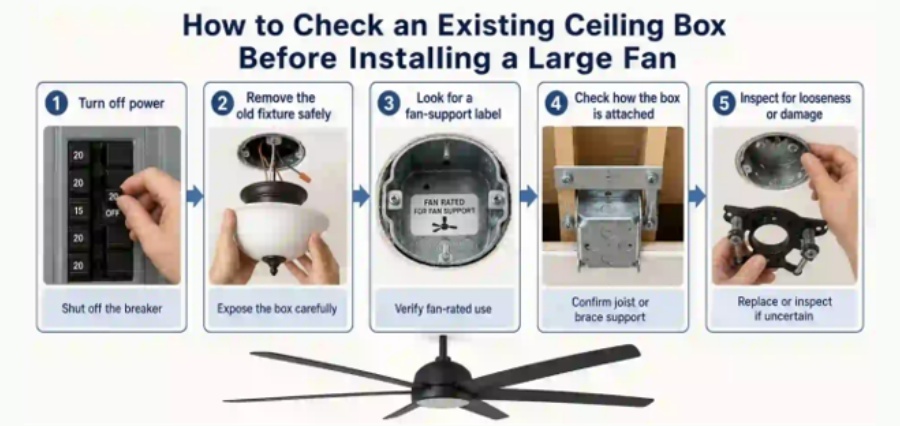
The Fan Should Be Supported Independently
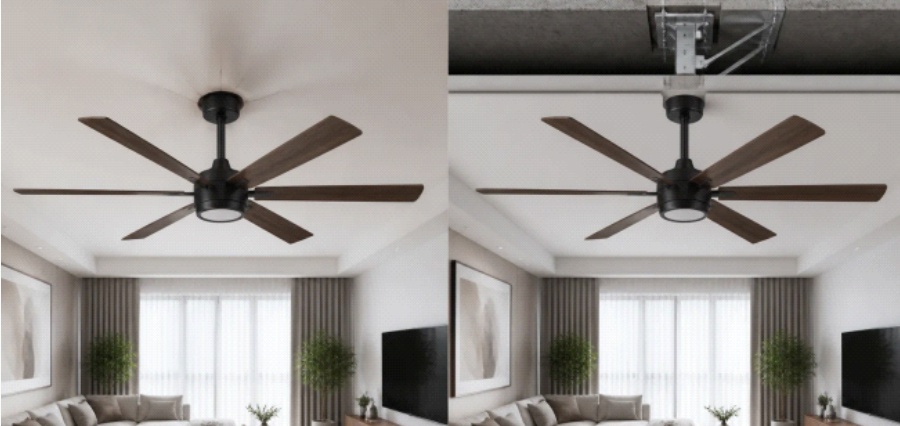
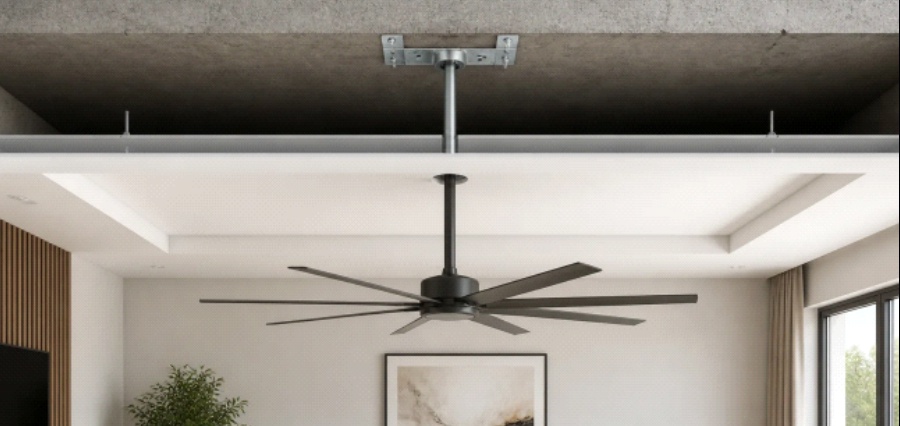
The mounting system should carry the fan back to a suitable structural element above the false ceiling. The finished ceiling can have an opening for the downrod or mounting assembly, but it should not accidentally become the part that bears the fan’s weight.
A typical load path is: structural slab, joist, beam, or framing -> approved support or mounting assembly -> downrod or hanger -> fan motor and blades. The false ceiling sits around that system rather than replacing it.
What Should Actually Support the Fan Above a False Ceiling?
Structural Framing or the Solid Ceiling Above
The correct support depends on the building. In one room, the fan may be attached to a timber joist. In another, the mounting point may need to connect to a structural slab, a beam, metal framing, or an engineered support member. The important point is that the load reaches a structural element that is appropriate for the fan and the mounting system being used.
Use a Complete Fan Mounting System
Different large ceiling fans vary in total weight, blade span, motor construction, mounting bracket, and supplied hardware. The structural support should therefore be checked against the requirements of the exact model rather than chosen only from the fan’s diameter.
A proper installation may involve a structural connection, a compatible mounting bracket, suitable fasteners, a hanger assembly, and a downrod. Improvising with random anchors or relying on the false-ceiling finish is not a substitute for a planned mounting system.
How Does the Fan Pass Through a Drop or False Ceiling?
Create an Opening Around the Mounting or Downrod Area
When the structural mounting point is above the finished ceiling, the downrod or other parts of the fan assembly may need to pass through the ceiling void. The visible opening should be sized so the mounting components can sit correctly and the ceiling finish can be completed neatly around them. A canopy or trim detail may conceal the opening once the fan is installed.
Do Not Let the False Ceiling Carry the Fan
The opening around the downrod should not be so tight, distorted, or improvised that the false ceiling begins to carry part of the motor load. The finished ceiling should remain a finish layer while the fan remains independently supported from above.
Why Downrod Length Matters With a False Ceiling
The Downrod May Need to Reach Below the Finished Ceiling
A false ceiling creates a gap between the structural ceiling and the finished ceiling. That space may be only a few inches deep or it may be substantial enough to hide ducts, cable trays, lighting, and mechanical systems. The fan mounting point is often above that void, so the downrod has to be considered as part of the whole vertical installation rather than measured only from the visible ceiling.
Final Installed Height Matters More Than Downrod Length Alone
The same principle applies when comparing large ceiling fans for high ceilings: the important measurement is where the fan and blades actually end up relative to the floor and surrounding ceiling features. A longer downrod may be needed to pass through the ceiling void, but the final fan height still has to suit the room.
Before choosing a downrod, measure the structural mounting point, the depth of the false ceiling, the motor and blade position, and the desired clearance above the floor. That gives a more useful picture than selecting a rod length in isolation.
How Much Clearance Does a Large Fan Need Below a False Ceiling?
There is no single clearance number that applies to every large fan. The required space above and around the blades depends on the fan design and the manufacturer’s installation instructions. What matters is that the full rotating blade sweep is clear of ceiling drops, decorative edges, beams, lights, vents, and other obstructions.
Do Not Position the Blades Inside a Ceiling Recess by Accident
A stepped or recessed false ceiling can create an awkward situation where the fan motor is centered in a higher area but the blade tips approach a lower border. Measure the complete blade diameter, not just the center point. The fan should not be placed where the blades pass dangerously close to a lower ceiling section or decorative feature.
What If the False Ceiling Has Different Levels?
Tray ceilings, recessed centers, lowered perimeter sections, and decorative POP or gypsum designs are common. They can work well with a large fan, but they need more careful planning than a flat ceiling.
Place the Fan in a Clear Central Zone
The preferred position is usually one where the entire blade sweep stays within a clear zone. Check the relationship to lower ceiling edges, recessed lights, air-conditioning vents, curtain tracks, beams, and other features before cutting the ceiling or fixing the mount.
Measure the Entire Blade Sweep
A 72-inch fan needs room for a 72-inch rotating diameter, not simply enough space for its center housing. The farther the blade tips extend, the more important it becomes to check every nearby drop, corner, and ceiling transition.
Is a Large Ceiling Fan Too Heavy for a False Ceiling?
The better question is whether the structure above the false ceiling and the selected mounting system are suitable for the fan. If the fan is independently supported from an appropriate structural point, the finished ceiling should not be asked to carry the motor and blades at all.
Blade Span and Fan Weight Are Not the Same Thing
A 60-inch, 72-inch, or 84-inch diameter tells you how far the blades span, but it does not tell you the fan’s total weight. Blade material, blade count, motor size, lighting components, housing construction, and hardware can all change the load. Use the exact model specifications rather than assuming a larger diameter always means a particular weight.
Can You Install a Large Fan Below a Gypsum or POP Ceiling?
Yes, this type of installation is possible when the fan is supported independently from the structural ceiling or framing above. The gypsum board or POP surface can be finished neatly around the downrod or mounting assembly, but it should not be treated as the structural anchor for the rotating fan.
Because decorative false ceilings often hide framing, wiring, and services, planning the fan location before the ceiling is closed can make the work much easier. In an existing room, it may be necessary to inspect the space above the ceiling before the correct mounting point can be confirmed.
Can You Install a Large Fan on a Suspended Tile Ceiling?
Suspended tile ceilings are common in offices, shops, basements, and commercial rooms. The visible T-bar grid is designed to support the ceiling system and compatible lightweight components, not to act automatically as the main mounting structure for a large fan. The fan should have its own support that connects to suitable building structure above the grid.
The ceiling tile can be cut or finished around the fan assembly as required, but the grid and tile should remain separate from the fan’s structural load path.
How to Plan the Installation Before Cutting the False Ceiling
- Identify the structural ceiling above. Find out whether the fan location is below a slab, joist, beam, framing member, or another structural element that can be evaluated for the mounting system.
- Check the fan’s actual specifications. Confirm total weight, blade span, supplied bracket, downrod options, and any installation requirements for the exact model.
- Measure the ceiling void. Record the distance between the structural mounting level and the finished false ceiling.
- Determine final fan height. Work from the structural mounting point through the false-ceiling depth to the motor and blade level, then compare that with the room and floor height.
- Check the full blade sweep. Make sure the blades will clear stepped ceiling edges, lights, vents, beams, walls, and decorative features.
- Plan the ceiling opening and finish. Allow enough space for the assembly to pass through without making the false ceiling carry the fan, while still leaving a clean finished appearance.
- Confirm the structural connection before installation. If the support cannot be identified or inspected, solve that uncertainty before the fan is installed.
What Fan Parts Matter Most in a False-Ceiling Installation?
The parts above the motor become especially important when the structural mounting point is hidden above a suspended or decorative ceiling. These can include the mounting bracket, canopy, hanger ball or hanger assembly, downrod, coupler, fasteners, and structural support. If those components are unfamiliar, a large ceiling fan parts and DIY guide can help you identify what each part does before the ceiling opening and final fan position are planned.
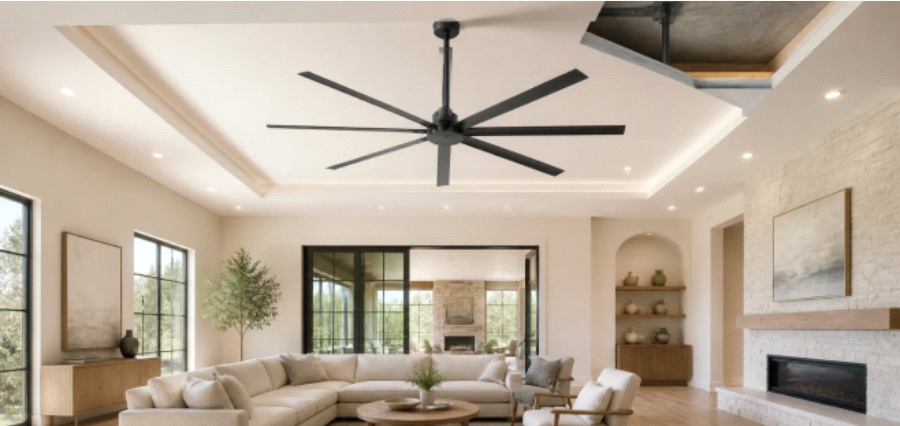
The key is to understand which pieces are decorative, which pieces guide the fan through the ceiling, and which pieces actually carry the load. Confusing those roles is one of the easiest ways to create a poor installation.
Common Mistakes When Installing a Fan Below a False Ceiling
Attaching the fan directly to ceiling board. Gypsum, plaster, POP, or decorative panels should not be assumed to provide the structural support required for a large rotating fan.
Using the suspended grid as the main support. A drop-ceiling grid is part of the ceiling system, not automatically the structure for a large fan.
Choosing the downrod before measuring the ceiling void. This can leave the fan too high, too low, or awkwardly positioned relative to the finished ceiling.
Ignoring stepped-ceiling clearance. The fan center may fit perfectly while the blade tips pass too close to a lower ceiling edge.
Cutting the ceiling before locating the structural support. The best-looking ceiling position may not align with an appropriate mounting point above, so the support plan should come first.
Assuming a bigger fan only needs a bigger opening. A larger fan may change the weight, mounting bracket, downrod, clearance, and final installed height as well as the hole in the ceiling.
When Should You Ask a Professional to Handle the Installation?
Professional help is a sensible choice when the structure above the false ceiling cannot be seen, concrete anchoring is required, the ceiling void is deep, the ceiling design is complex, the wiring is old, or the fan is unusually heavy. It is also useful in commercial suspended ceilings, where building services and structural elements may share the same overhead space.
- The structural mounting point cannot be identified.
- The fan location does not line up with suitable framing.
- The installation requires anchors into a structural slab.
- The false ceiling has multiple levels or fragile decorative work.
- A long downrod or unusual hanger arrangement is needed.
- The electrical connection or existing wiring is uncertain.
Quick Decision Guide
| Situation |
Recommended approach |
| Solid structure directly above the false ceiling |
Verify a suitable fan mounting system and connect the fan to the structure. |
| Gypsum or POP finish only |
Do not rely on the finish layer alone to support the fan. |
| Suspended tile grid |
Support the fan independently from suitable structure above the grid. |
| Deep ceiling void |
Plan the downrod and final installed height before cutting the ceiling. |
| Stepped or recessed ceiling |
Measure the complete blade sweep and all surrounding clearances. |
| Structural support cannot be identified |
Inspect the space above the ceiling before installation. |
| Very large or heavy fan |
Confirm the model-specific mounting requirements and support method. |
Frequently Asked Questions
Can you put a ceiling fan on a drop ceiling?
Yes, but the fan should normally be supported independently from suitable structure above the drop ceiling rather than from the ceiling tile or suspended grid itself.
Is it safe to install a ceiling fan on a false ceiling?
It can be safe when the mounting system transfers the fan load to appropriate structural support and the installation follows the requirements of the fan and mounting hardware.
Can a large ceiling fan hang directly from gypsum board?
Gypsum board should not be assumed to be the primary structural support for a large rotating fan. The fan should be connected to suitable structure or an approved support system above it.
Can you install a ceiling fan under a POP ceiling?
Yes, provided the fan is supported from appropriate structure above the POP finish and the ceiling opening is planned around the mounting or downrod assembly.
How much weight can a drop ceiling hold?
There is no single number that should be used to decide whether a drop ceiling can support a large fan. The fan should generally have an independent structural support path rather than relying on the suspended ceiling system.
Does a false ceiling require a longer downrod?
Sometimes. The correct length depends on the distance from the structural mounting point to the finished ceiling and the final blade height required in the room.
Can fan blades rotate partly inside a false-ceiling recess?
The full blade sweep should have the clearance required by the fan manufacturer. Stepped ceiling edges or recesses should not interfere with the rotating blades.
Can you mount a ceiling fan to a suspended ceiling grid?
The grid itself should not automatically be treated as the main support for a large fan. The fan should be independently connected to suitable building structure above the grid.
How do you choose fan size for a false ceiling?
Choose the fan based on the room and the model’s requirements, then verify structural mounting, blade clearance, final installed height, and the dimensions of the false-ceiling opening.
What should be checked before installing a large fan below a false ceiling?
Check the fan specifications, structural support, ceiling-void depth, mounting hardware, downrod length, final installed height, and clearance around the complete blade sweep.
The Bottom Line
A large ceiling fan can work perfectly well below a drop or false ceiling when the support is planned correctly. The finished ceiling may hide the structure, but it should not replace it. Support the fan from a suitable structural point, use a mounting system that matches the exact fan, allow the downrod or hanger to pass through the ceiling cleanly, and check the final blade height and full sweep before installation. When the structure above the ceiling is unknown, inspection should come before cutting, mounting, or testing the fan.














































You must be logged in to post a comment Login