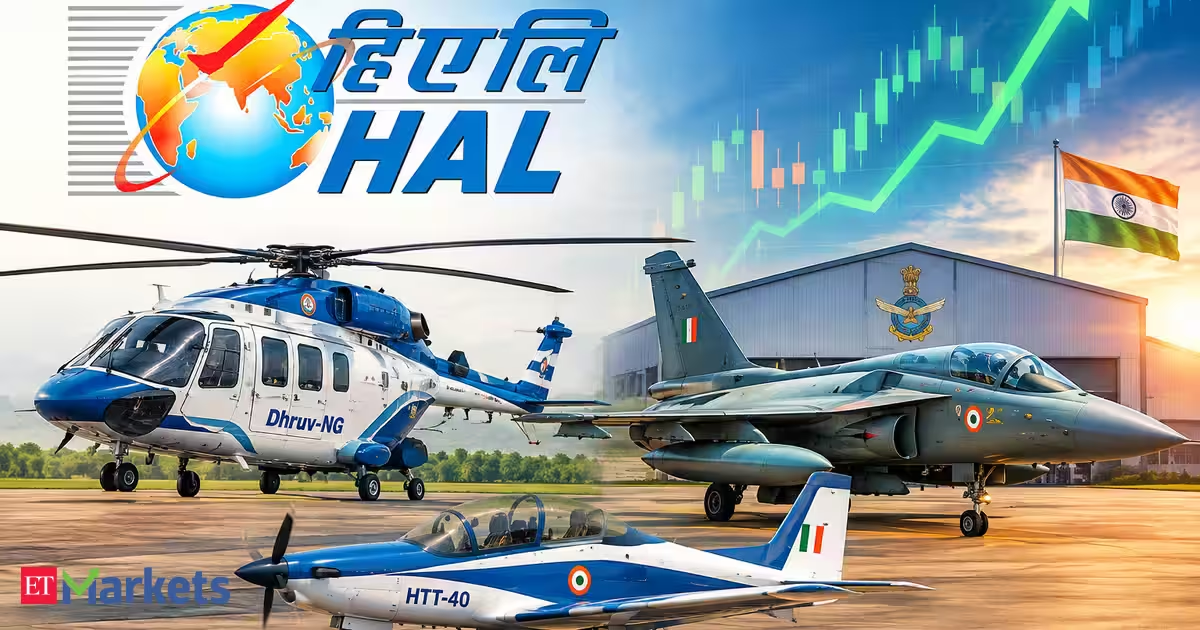
Shares of Hindustan Aeronautics Ltd gained 2% to their day’s low of Rs 4,889 on the BSE on Monday after the company handed over three indigenously developed platforms to the Indian Air Force (IAF) and Pawan Hans Limited. The platforms included the Dhruv-NG helicopter, LCA Tejas Trainer jets and the HTT-40 basic trainer aircraft.
Defence Minister Rajnath Singh, speaking at the handover ceremony, said the event marked three significant achievements. The indigenously designed and developed Dhruv-Next Generation civil helicopter was handed over after receiving Type Certification from the DGCA. The final batch of LCA Final Operational Clearance (FOC) Trainer aircraft was handed over to the IAF, while the first aircraft from the HTT-40 Basic Trainer series production was also delivered to the IAF.
Praising HAL’s work on the HTT-40, Singh said the first series-production aircraft had been handed over to the IAF and described the development as a step towards ending India’s dependence on foreign countries in this area. He also said the aircraft’s capabilities could create opportunities for exports.
The HTT-40 is a tandem-seat, fully aerobatic basic trainer powered by a Honeywell turboprop engine. It features a glass cockpit and Martin-Baker zero-zero ejection seats. HAL is producing the aircraft under a contract for 70 aircraft with the IAF, which will replace the ageing HPT-32 Deepak fleet.
Advertisement
The LCA Trainer is the twin-seat version of the indigenous Tejas fighter and is used for advanced combat flight training. The Dhruv-NG, meanwhile, is the next-generation civil version of HAL’s Advanced Light Helicopter and has been developed for applications including offshore and passenger operations.
Live Events
The handover ceremony saw two LCA FOC Trainer aircraft delivered to the IAF, completing the twin-seat deliveries under the FOC contract. Four Dhruv-NG helicopters were handed over to Pawan Hans Limited, while the first HTT-40 Basic Trainer aircraft was delivered to the IAF, marking the beginning of deliveries under the 70-aircraft contract.
What is Goldman Sachs saying?
Goldman Sachs has maintained a Buy rating on Hindustan Aeronautics with a target price of Rs 5,870. The brokerage noted that Tejas FOC twin-seater trainers are being handed over to the Indian Air Force, along with HTT-40 basic trainers to the IAF and Dhruv-NG helicopters to Pawan Hans.It said deliveries are picking up across fighter, trainer and helicopter platforms, while GE has delivered another three F404 engines for the LCA Mk1A. Goldman Sachs said supply constraints are gradually easing, with the focus now shifting towards converting HAL’s large order backlog into revenues. The latest handovers also align with the government’s push to expand indigenous defence manufacturing.
HAL FY27 outlook
The company said it is well positioned to benefit from opportunities across aircraft, helicopters, aero engines, avionics and maintenance, repair and overhaul (MRO) projects. It added that execution of ongoing programmes, along with expected orders for fighter aircraft, rotary-wing platforms and upgrade projects, is likely to provide strong medium- to long-term revenue visibility.
HAL said these initiatives are expected to support its long-term growth while strengthening its role in India’s aerospace and defence ecosystem and improving its competitiveness in global markets.
Advertisement
Last month, the company announced that it signed a long-term agreement with Safran Aircraft Engines for the production and supply of turbine ring forgings in superalloys for the ‘CFM LEAP’ engine programme.
Disclaimer: This article has been written by Veer Sharma, who is not a SEBI-registered Research Analyst or an Investment Adviser. Veer Sharma and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.
Yes. Corporate subscriptions are available for teams and organisations, with discounted rates as user numbers increase. Pricing starts from $1,625 + GST per user. Get in touch
to discuss the right option for your organisation.
Business News subscriptions are used by executives, investors, consultants and professionals who need to stay informed and make better decisions about the WA market. When you subscribe you’ll get
Unlimited access to WA’s most trusted business journalism
Data & Insights — detailed profiles of WA companies, people, projects and deals
MyBN — a personalised feed based on the companies, people and sectors you follow
Special publications and industry reports
Daily and weekly email newsletters
Data & Insights is a research tool built specifically for the WA market. It draws on more than 30 years of Business News reporting, updated regularly to reflect what’s happening now. Use it to:
Look up detailed profiles of WA companies, including financials, directors and ownership
Find decision-makers and track their career movements
Research live and completed projects across WA industries
Monitor deals, appointments and market activity
Access industry rankings and league tables
Data & Insights is updated daily by our dedicated research team, which uses the latest announcements, ASX filings and editorial coverage to keep our person, company, list and project records up to date.
Business News welcome all opportunities to make our dataset accurate, complete and current, so if you have an update request, please email the team at general@businessnews.com.au, and we’d be happy to assist.
Advertisement
MyBN
is part of every subscription. It’s your personalised view of Business News. You can follow the companies, people, sectors and projects that matter to you, and get a news feed and alerts tailored to your interests. You can save articles to read later and retain only what you need.
Only subscribers have full access to all content on the Business News website.
Advertisement
If staying informed about the WA economy is part of your job, and/or you’re looking for networking opportunities in WA, Business News is built for you.
Business News subscribers are:
Executives and directors tracking competitors, clients and market movements
Investors and advisers researching companies, deals and industry trends
Consultants and professionals staying across sectors relevant to their clients
Business owners looking for leads, context and market intelligence
Most Business News publications cover national or global markets. Business News is focused entirely on Western Australia, which means the journalism, the data and the intelligence are all built around WA companies, people and projects — not adapted from a national feed. Data & Insights, included with every subscription, combines more than 30 years of WA-specific editorial research with live business data. There’s no comparable product for the WA market.
Advertisement
The Morning Digest Email provides a comprehensive wrap of the major headlines, relevant to WA business, and includes with a snapshot of the overnight news covering oil, gold and ASX-listed companies.
The Afternoon Wrap Email focuses on the news covered by our team of journalists during the course of the working day, including exclusive stories and analysis, all of which relates to WA business and the local economy.
The BN Weekender Email contains a wrap of the Business News from the week that was, highlighting the top stories in each area of WA business. Sign up for free.
Advertisement
We’re happy to help. Get in touch
and our team will come back to you.
Ramelius Resources shares closed stronger on Monday, following the release of its updated four-year production outlook and FY27 annual guidance target.
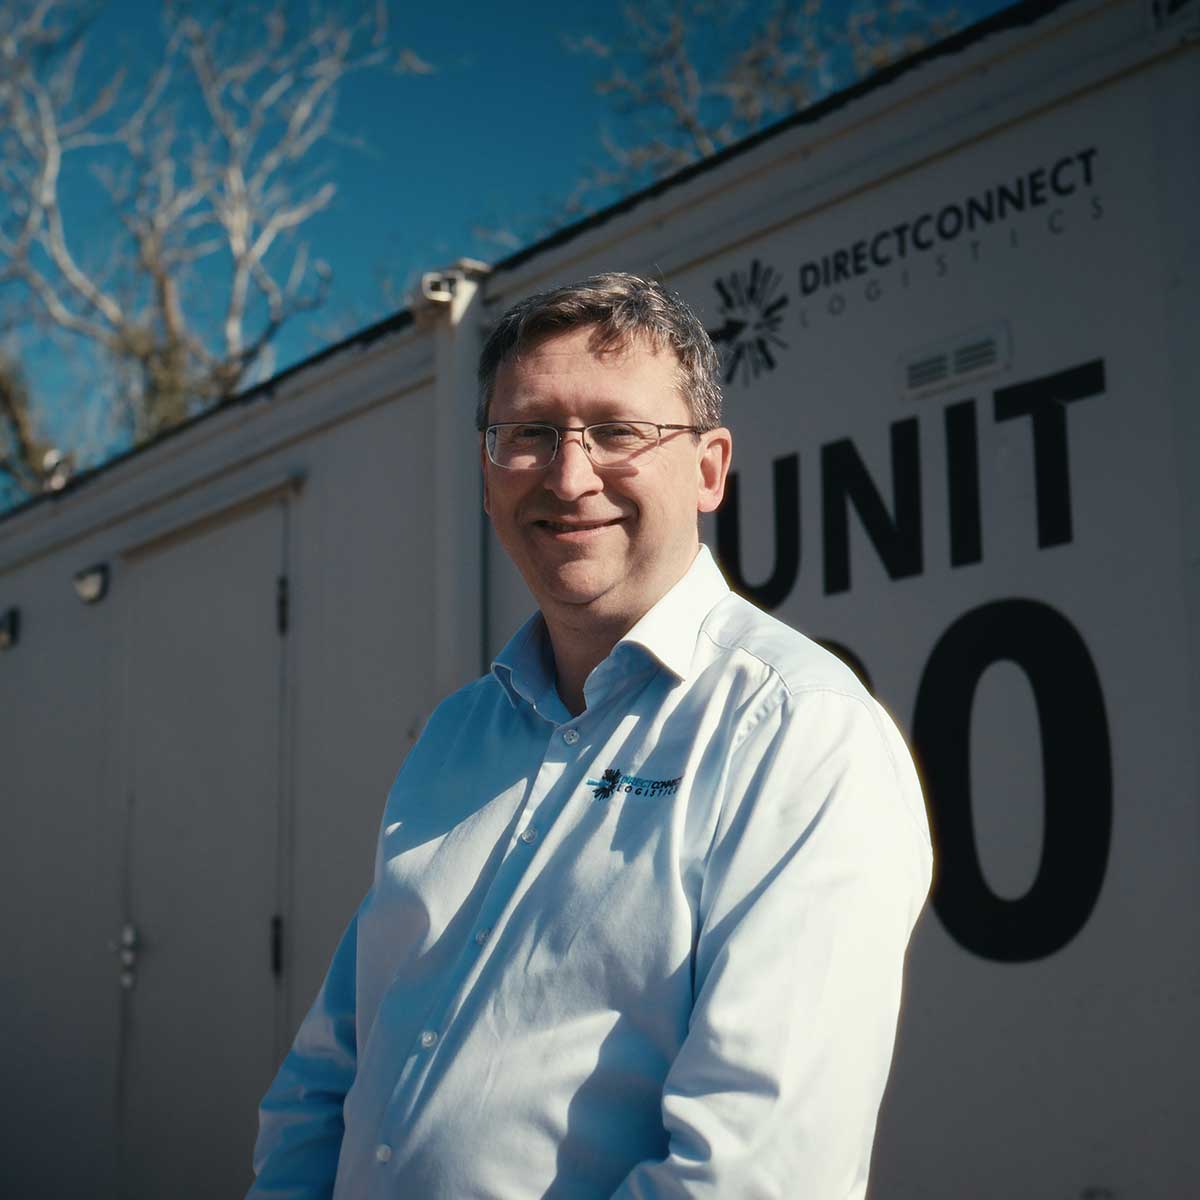
Rhys Hackling started Direct Connect Logistics with two 7.5-tonne lorries and no customers of his own. The Bicester haulier now runs 24 vehicles, including 18-tonne HGVs.
In January 2022 thieves stole pallets of batteries from one of its trucks, a case Rachel Taylor MP cited when she opened a Westminster Hall debate on freight crime in December 2024. He tells Business Matters what it takes to keep a fleet earning.
What do you currently do at Direct Connect Logistics?
I own and run the business. Most days come down to one question: where is each lorry going next, and what is on it?
Free newsletters
Advertisement
The stories that matter to UK business, straight to your inbox.
Advertisement
An empty lorry is money going out of the door. We run 24 vehicles across Bicester, Northampton and Knutsford, including a growing number of larger 18-tonne lorries, moving thousands of loads a month. Every one of them needs to earn.
Around 95 per cent of our work comes through Haulage Exchange, the online freight exchange where hauliers and businesses post loads. People sometimes ask whether that is a risk. I do not see it that way. The work comes from hundreds of different businesses, so no single customer can make or break us.
Away from the yard, I campaign on freight crime. In January 2022, thieves attacked one of our trucks and took pallets of batteries. The lorry was off the road for three days and the load was gone. I have taken the issue to Westminster, because no operator is immune, and people who run haulage firms need to be part of that conversation.
What was the inspiration behind your business?
I started out in air conditioning, not haulage. Then I briefly took over a haulage company, and what struck me was how underused the lorries were. Vehicles would drop a load and come back empty, or sit in the yard waiting for work.
Advertisement
Around then I came across the exchange. Hauliers and businesses post loads there, so you can see what work is out there and where it is going. I realised the problem was not a lack of work. It was finding the right load for the right truck at the right time.
So I set up Direct Connect Logistics with two 7.5-tonne lorries, no work lined up and no customers of my own. The plan was to run everything through the platform and keep those two trucks full. It worked, and that gave me the confidence to grow.
Who do you admire?
I admire the drivers. From day one, looking after our drivers has mattered to me as much as looking after our customers. They are out on the road at all hours, often with nowhere safe to stop, and they carry the reputation of the business with every delivery. When a customer tells me a job was done well, that is down to them.
I also respect anyone who has built a haulage firm. The margins are thin, the hours are long, and nobody hands you anything.
Advertisement
Looking back, is there anything you would have done differently?
I would have spoken up about freight crime sooner. Like a lot of operators, I saw theft as something that happened to other people, or just a cost of doing business. Then we lost a full load of batteries and had a lorry off the road for three days. For a smaller firm, one hit like that can wipe out a month’s profit.
It is not a small problem. The National Vehicle Crime Intelligence Service recorded 3,424 cargo crimes against lorries in 2025, nine a day, with an estimated £65.1m of goods taken at cost price, and the police officers who track it think the real figure is several times higher.
I realised that if people running haulage businesses do not make the case, nobody else will. That is what took me to Westminster. I wish I had started that conversation before it happened to us.
What defines your way of doing business?
Growing carefully. I only expanded when the business could handle it. Two trucks became four, four became six, six became 12, and now we run 24. Each step was based on what we could see in the work coming through, not guesswork. Before we added any 18-tonne lorries, we had already found customers looking for that capacity.
This year we were named Company of the Year by Haulage Exchange. For a business built one truck at a time, that meant a lot to everyone, from the drivers to the office.
Reputation matters as much as growth. I will not hand work to a subcontractor I cannot check. Before anyone gets near a load of ours, I want to see their licence, insurance and trading status. Freight crime is organised and deliberate, and some of it happens without anyone breaking into anything. Being careful about who you work with is part of running a responsible business.
Customers notice that. They want to know the job will be done properly, first time. Over the years that has earned us more than 6,100 positive reviews, and plenty of customers now come straight to us before looking anywhere else.
Advertisement
What advice would you give to someone starting out?
Do not wait to win your own customers before you start moving freight. I ran our first two trucks entirely on work posted by other hauliers and businesses, planning each return journey so the lorry did not come home empty. The direct relationships came later, from doing those jobs well.
Then set up the back office properly while you are still small. Paperwork that feels manageable with two trucks will swallow your week by the time you have 10.
Grow at the pace the work allows. Only add a vehicle when you can already see the demand for it. Borrowing ahead of the work is how good operators get into trouble.
Above all, protect your reputation. In this industry, like most, word travels fast, and a good name brings the work back.
The party also argued the move would benefit shops, hotels, restaurants and the wider tourism industry.
It pointed to research by the Centre for Economics and Business Research (Cebr), which suggested fully restoring tax-free shopping for tourists could attract up to 2.35 million extra visitors and generate £4.1bn in extra spending.
The report from earlier this month also estimated that for every £1 of VAT refunded, this could generate £1.54 in other taxes.
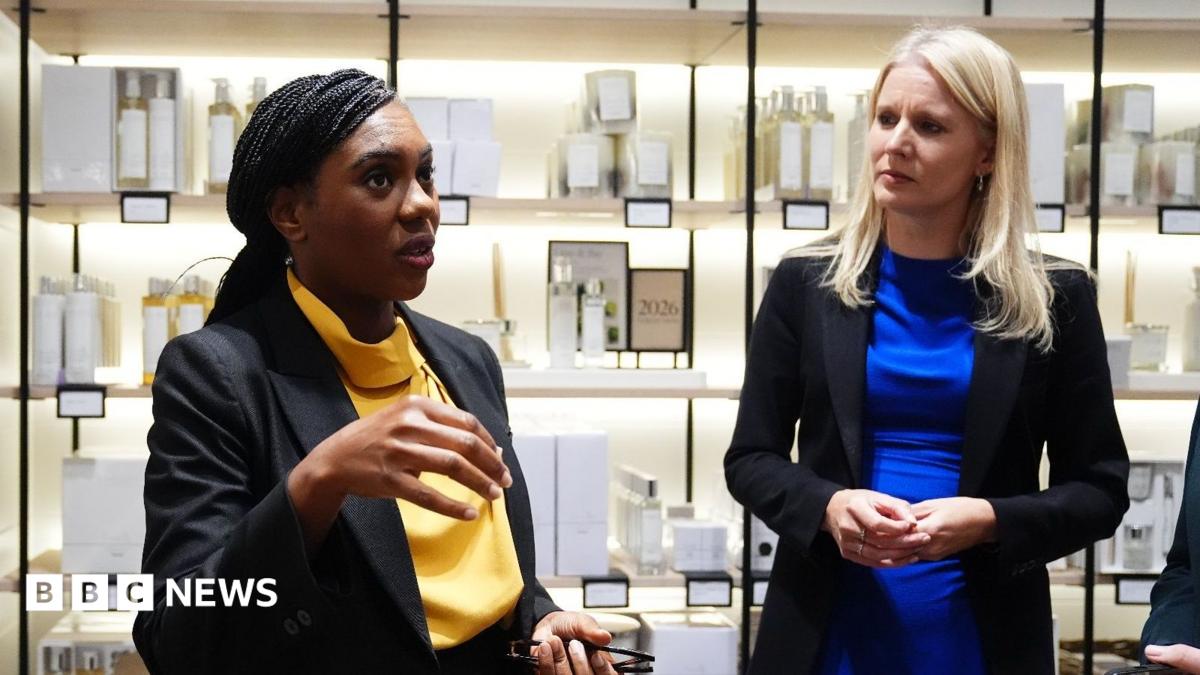
Badenoch said: “We have iconic retailers, inventive designers and brilliant manufacturers, but they are being let down by a tax policy that is chasing their customers away.
Advertisement
“Holidaymakers are choosing rival cities in other countries for the simple reason that it saves them money.”
Businesses have long called for tax-free shopping for tourists to be reintroduced, arguing they are at a disadvantage to other European countries.
EU countries offer VAT refunds for non-EU visitors, while other European countries such as Switzerland have similar schemes.
Helen Dickinson, chief executive at the British Retail Consortium, said: “Introducing a modern tax-free shopping scheme would help attract more international spending to the UK, supporting high streets, jobs and investment in towns and cities across the country.
Advertisement
“Done properly, it would boost economic growth and deliver a net benefit to the Exchequer.”
However, a Labour spokesperson said: “Kemi Badenoch used to say tax-free shopping was a costly giveaway and now she’s trying to sell it as an economic miracle.
“If they really think it’s such a great idea, they should explain why they scrapped it in the first place and how they’d pay for bringing it back.”
Laura Drane will succeed Rachel Jones who is standing down after 30 years in the role.
11:27, 21 Sep 2026Updated 11:28, 21 Sep 2026
Charity Arts & Business Cymru has appointed Laura Drane as its new chief executive.
The charity, which brings together the worlds of business and the arts, has also published new figures showing it work generates an estimated £1m of private sector support for the arts in Wales each year.
Around half of that annual contribution is direct financial investment, with the remainder provided through business expertise, skills and in-kind support.
Advertisement
Ms Drane will succeed Rachel Jones who will stand down as chief executive in November after 30 years in the role.
She brings more than 25 years’ experience as a facilitator, producer and consultant, having delivered more than 120 contracts across the UK and internationally. She spent three years in a senior role at Arts Council of Wales, where she had strategic input into its £29.6m revenue funding review and led sector review and development work.
She has also worked with the Audience Agency on research informing proposals for a Culture Bill in Wales and co-founded What Next? Cardiff/Cymru, which brings the cultural sector together to engage with and influence public policy.
A&B Cymru currently works with more than 180 arts members and over 50 business members across Wales, from individual practitioners and sole traders to national arts institutions and multinational companies.
Advertisement
Its CultureStep investment programme alone has helped leverage almost £5m of private sector investment into the arts since 2014, supporting almost 350 partnerships involving more than 250 businesses and reaching communities in every local authority area in Wales.
Speaking about her priorities the incoming chief executive said: “Welsh businesses are missing a huge opportunity if they see supporting the arts simply as philanthropy or sponsorship. The strongest partnerships deliver on both sides, bringing vital investment, skills and expertise into the arts while helping businesses develop their people, strengthen their profile, reach communities and connect with creativity and innovation.
“For businesses, this is also about investing in your people. Arts organisations need strong board members with commercial skills, and those roles give “Rachel, the team and board have built a fantastic foundation over the past 30 years.
” My job now is to build on that, respond to the changing cultural and economic landscape in Wales and bring more people together across business, the arts and, increasingly, heritage. I want A&B Cymru to help organisations develop the skills, partnerships and resilience they need for the future.”
Advertisement
Ms Jones said: “It’s been an absolute honour and a joy to lead A&B Cymru for the last three decades. I’ve seen an increasing number of businesses recognise that working with the arts isn’t simply about giving something back.
” The best partnerships create genuine value on both sides, bringing much-needed investment, skills and expertise into the arts while helping businesses engage their people, reach communities and address their own objectives in creative ways.
“I’m enormously proud of what A&B Cymru has achieved and grateful for the trust placed in me by our board, supporters and members. I’m genuinely excited for the organisation as it enters a new chapter under Laura’s leadership. At a time when both the arts and business communities face significant challenges, its work has never been more crucial.”
But somewhere between opening day and today, most business owners find themselves buried in tasks that have nothing to do with that original vision. Answering routine emails, chasing paperwork, and fixing small operational problems can quietly eat an entire week. None of it feels optional in the moment, yet almost none of it actually grows the business.
This hidden drain on time rarely shows up as one obvious problem. It shows up as dozens of small distractions stacked on top of each other. A phone call here, a form to fill out there, a system that breaks and needs a manual fix right now. Each task feels urgent and necessary, so business owners rarely stop to ask a harder question. Is this task actually building the business, or is it simply keeping the business from falling apart today? That distinction matters more than most entrepreneurs realize, and ignoring it for too long can quietly stall growth for years.
The Hidden Cost of Busywork
Research on small business ownership consistently points to the same pattern. Many entrepreneurs spend the majority of their working hours on tasks that do not directly bring in new customers or improve the product. Instead, their time gets consumed by administrative work, manual data entry, repetitive communication, and fixing problems that better systems could have prevented in the first place. This is not a personal failure. It is simply what happens when a growing business outpaces the systems built to support it.
Free newsletters
Advertisement
The stories that matter to UK business, straight to your inbox.
Advertisement
The danger is that busywork feels productive even when it is not. Clearing an inbox, filling out a form, or responding to a routine question all create a small sense of accomplishment. But accomplishing a task is not the same as growing a business. Growth comes from acquiring customers, improving a product, building relationships, or developing a team, not from simply staying busy every hour of the day. Businesses that confuse motion with progress often plateau quietly, without ever understanding exactly why.
What separates thriving businesses from stagnant ones is often a willingness to name this problem honestly and fix it. The businesses profiled below made that exact shift. Each one identified a specific task eating away at valuable time, then built or adopted a better system to solve it. Their stories show that the fix is rarely working longer hours. It is almost always working on fewer, more important things.
Delegating the Work That Does Not Require the Founder
Professional service businesses face this challenge constantly, since so much of the work involves detailed documentation, filings, and client communication. A law practice, for example, generates an enormous amount of paperwork behind every single case. Attorneys can easily spend hours drafting routine documents or tracking case status instead of preparing courtroom strategy or meeting with clients directly. Over time, that imbalance quietly limits how many clients a firm can actually serve well.
Ramiro Lluis, Attorney at Lluis Law, has spent 48 years building a family run practice in Los Angeles and has seen this exact pattern play out across decades of legal work.
Advertisement
“In 48 years of practicing law, I have watched too many attorneys drown in paperwork instead of building their firm. Early in my career, I spent hours each week on filings a paralegal could handle just as well. Once I learned to delegate that work and focus my own time on courtroom strategy and client relationships, our caseload capacity grew significantly. A law firm does not grow because the founder works harder, it grows because the founder works on the right things.”
This lesson applies far beyond the legal field. Any business built around expert knowledge faces the same trap, since the person with the most valuable skills often ends up buried in tasks that do not require that skill at all. Recognizing which tasks genuinely need the founder’s attention, and which ones can be handled by someone else or by better systems, is often the single biggest unlock for sustainable growth.
Building the Tool You Wish Already Existed
Sometimes the work stealing an entrepreneur’s time is not something that can simply be delegated. Sometimes it requires building an entirely new tool because nothing on the market solves the problem well enough. Online resellers know this frustration firsthand, since writing a single product listing can take fifteen to twenty minutes once titles, categories, pricing, and shipping details are all factored in. Multiply that by dozens of items a week, and an entire business can grind to a halt under listing work alone.
Christopher Taylor, Founder of Flowlister, lived that exact frustration while running his own eBay reselling business before deciding to solve the problem himself.
Advertisement
“Before Flowlister, I spent 15 to 20 minutes manually listing every single item in my eBay store. That math never changes no matter how good a seller you are, it just eats your whole day. So I built Flowlister to turn one photo into a complete, priced listing in about 30 seconds. We freed up thousands of hours for resellers, and every one of those hours can now go toward sourcing and actually growing the business.”
Christopher’s story reflects a pattern seen across many industries. Entrepreneurs often assume repetitive, time consuming work is simply the cost of doing business. In reality, that repetitive work is frequently the clearest signal that a better process or tool is needed. Businesses willing to invest time upfront in solving that root problem often gain back far more time than they spent building the fix.
Making Paperwork Move Faster
Compliance heavy industries face a similar challenge, though the paperwork itself looks completely different. Vehicle titling and registration work involves dozens of small steps, especially for complicated cases involving salvage titles, bonded titles, or out of state purchases. Every document has to be accurate, submitted correctly, and tracked carefully, since even a small mistake can delay a client for weeks. Without the right systems in place, that level of detail can consume an entire team’s time without leaving room for anything else.
Jennifer Tamol, Owner of Shelby And Sons Title Company, works inside that paperwork every day and has learned how quickly manual processes can slow an entire business down.
Advertisement
“Vehicle titling paperwork is full of small steps that eat an entire afternoon if you do them by hand. I used to personally track every bonded title and salvage form until our office nearly stalled trying to keep up. We built simple checklists and automated parts of our document prep, and turnaround time on complex titles dropped noticeably. Growth in this business means clearing the paperwork faster, not just taking on more of it.”
Jennifer’s experience highlights an important truth about paperwork heavy businesses. Growth does not always mean adding more staff or taking on more clients right away. Sometimes it simply means removing friction from the process already in place, so the same team can accomplish more without feeling constantly overwhelmed.
Freeing Up Time to Focus on What Matters Most
Education and service platforms deal with their own version of this problem, especially when growth depends on matching the right people together quickly and accurately. Manually coordinating schedules, preferences, and availability between two groups of people can consume enormous amounts of time behind the scenes. That kind of manual coordination might feel essential in the early days, but it rarely scales well as a company grows.
Tornike Asatiani, Founder and CEO of Edumentors, experienced this firsthand while building an online tutoring platform that now operates across dozens of countries.
Advertisement
“When we started Edumentors, I spent far too many hours manually matching tutors with students by hand every single day. That work felt urgent, but it never actually grew the company or improved a single lesson. We built matching and scheduling tools so our team could focus on tutor quality and student outcomes instead. Since making that shift, we have delivered more than 100,000 lessons across 35 countries.”
Tornike’s experience shows how quickly a founder’s time can be consumed by tasks that feel essential but do not actually move the business forward. Once that manual matching work was automated, the team could redirect its energy toward the parts of the business that genuinely mattered, like tutor quality and student results. That shift in focus, rather than simply working more hours, is often what allows a growing company to scale successfully.
The Real Lesson Behind Every Story
These four stories come from completely different industries, yet they all reveal the same underlying truth about entrepreneurial time. Time itself is not the scarce resource most business owners assume it to be. Attention is. Every hour spent on a task that does not build the business is an hour quietly stolen from the work that actually matters most. Recognizing that difference is often the first step toward meaningful growth.
The businesses in this article did not solve their time problem by working harder or longer. They solved it by identifying exactly which tasks were stealing their attention, then building a better system, tool, or team to handle that work instead. Whether that meant delegating filings, building new software, automating paperwork, or replacing manual matching with smarter tools, the underlying lesson stayed the same. Growth follows the entrepreneurs who protect their time fiercely and spend it only on the work that truly moves their business forward.
Details on the partnership remain scarce, but it will be led by Faculty, a U.K.-based AI company Accenture acquired this year. Accenture and Anthropic said they expected to invest about $1 billion each over the next five years in the AI safety effort. Accenture has partnered with Anthropic before, including through an effort to embed AI adoption across clients’ operations.
SRK Fund I, LP increased 26.80% during the first half of the year. In contrast, the S&P 500 and the Russell 2000 returned 10.18% and 22.57%, respectively. Since inception, the Fund has appreciated 1551.26% compared to 222.91% for the S&P 500 and 118.90% for the Russell 2000.
SRK Fund I, LP Returns (%) as of June 30, 2026
Advertisement
2026
2025
2024
2023
2022
2021
2020
2019
SRK Fund I
26.80%
47.12%
-8.74%
17.15%
35.31%
46.71%
127.72%
77.99%
S&P 500 TR
10.18%
17.88%
25.02%
26.29%
-18.11%
28.71%
18.40%
31.48%
Russell 2000
22.57%
12.81%
11.54%
16.93%
-20.47%
14.78%
20.00%
25.52%
*Inception date of 05/01/18
In many respects, the first half of 2026 mirrored the environment of 2025, persistent macroeconomic noise, narrow market leadership, and heightened volatility. Geopolitical tensions, off and on Iran peace deals, and a partial unwinding of the AI momentum trade caused investor sentiment to fluctuate throughout the first half of the year. After an extended period in which market participants chased AI hardware bottlenecks and infrastructure buildouts, shifting sentiment triggered sharp pullbacks across many crowded positions.
Our performance during the period was achieved with zero exposure to companies tied to the AI buildout. That decision was not a refusal to evaluate the future; underwriting future earnings power is central to our investment process. The distinction is predictability, as I tend to only commit capital when a business model is proven, the economics are visible, and I believe I have a high probability of being right about what the business can generate over time. AI remains a nascent and rapidly evolving sector. At this stage, much of the easy money in the trade appears to have been made, with valuations already discounting explosive growth and earnings several years into the future. Predicting long-term customer adoption, competitive durability, and sustainable returns on invested capital now requires assumptions across a wide range of possible outcomes for which I do not believe I have an edge.
Advertisement
Instead, I prefer to focus on opportunities with asymmetric return potential and cash-flow outcomes that management can materially influence. I am allocating capital to opportunities where market neglect, cyclical weakness, or operational transitions have temporarily obscured the normalized earnings power of high-quality core assets.
Today’s portfolio consists of businesses trading at meaningful discounts to my estimate of normalized cash flows. They are led by aligned operators focused on controllable improvements, including operational efficiency, stronger cash conversion, and disciplined per-share capital allocation. By emphasizing durable cash flows and execution within management’s control, I believe the portfolio can continue compounding without depending on macro tailwinds, multiple expansion, or favorable market sentiment.
ImmuCell delivered a strong first quarter in 2026, underscoring the earnings power and cash-flow potential of its core First Defense franchise after the company’s strategic exit from Re-Tain. Product sales increased 28.4% year-over-year to $10.4 million, driven by higher volumes, price realization, and an estimated three-point gain in U.S. scours biologicals market share. Gross margin expanded to 45.0% as increased production created operating leverage, while net income rose 34% to $1.9 million. Even after the stock’s recent appreciation, ImmuCell remains a compelling opportunity. Management is refitting the former Re-Tain facility to expand First Defense capacity beyond the current 450,000 units per month, supporting a path toward $35 million to $40 million of sales over the next 12 to 24 months. With gross margins near 45%, the Re-Tain development burden permanently removed, annual EBITDA can grow towards $12 million to $14 million and convert into free cash flow with limited corporate tax leakage for several years due to substantial net operating loss carryforwards.
Outdoor Holding Company’s fourth quarter and full-year fiscal 2026 results reinforced the core turnaround thesis. Since divesting its capital-intensive ammunition manufacturing business in April 2025, the company has operated as a pure-play, asset-light marketplace through GunBroker.com. Revenue increased 3.5% year-over-year to $51.1 million, while adjusted EBITDA rose 46% to $22.3 million from $15.3 million, reflecting disciplined cost control and improved platform monetization.
Advertisement
Momentum accelerated in their fourth quarter. Net revenue grew 10.1% year-over-year to $13.9 million, supported by an 11.8% increase in gross merchandise value to approximately $229 million. Gross margin remained exceptionally high at 87.6%, and lower operating expenses helped drive adjusted EBITDA to $7.7 million, up 163% from $2.9 million in the prior-year period.
The results also highlighted GunBroker’s resilience in a subdued firearms market. Firearm unit sales on the platform grew 8.7% year-over-year during the quarter, far outpacing the 1.6% increase in adjusted NICS background checks. Adjusted EBITDA run rates over the past three quarters have also exceeded management’s $25 million target, reaching that milestone well ahead of the timetable set in August 2025. The balance sheet remains strong, with $68.1 million of cash and equivalents at fiscal year-end. They also began returning capital through a $15 million share repurchase program, buying back 513,925 shares for approximately $1.0 million at an average price of $1.95 per share.
Management is now focused on platform enhancements that can drive GMV growth and expand the take rate. During their fiscal year, the company completed its MasterFFL integration to streamline dealer verification across more than 32,000 licensed dealers and launched an AI-powered listing tool to improve product descriptions and conversion. In fiscal 2027, universal payment processing should allow individual sellers to accept credit cards through native checkout, addressing the roughly 30% of platform volume still handled through manual payment methods and creating a new high-margin revenue stream. With modest take-rate expansion, a potential cyclical recovery in firearms demand ahead of the 2028 election cycle, 85%+ gross margins, a net cash balance sheet, and aggressive buybacks, POWW has a credible path to $35 million to $40 million of EBITDA over the next 18 to 24 months and remains an attractive opportunity.
Industrial & Manufacturing Basket
Our industrial and manufacturing basket performed exceptionally well in the first half of the year, with the average holding up more than 50% year-to-date on a consolidated basis. While the market often views micro-cap industrial companies as commoditized or highly cyclical, our thesis centered on a clear inflection point. These businesses had spent two years working through severe post-pandemic inventory destocking, elevated input costs, and depressed utilization, while still retaining durable niche positions, strong balance sheets, and meaningful operating leverage.
Advertisement
The group’s fundamental results have validated that setup. As customer inventories normalized and supply chain friction eased, even modest volume recovery began flowing through to earnings. Many management teams have already used the downturn to resize cost structures, consolidate facilities, and remove legacy overhead, allowing baseline volume recovery to drive sharp improvements in gross margins and operating cash flow.
One example is a specialized synthetic fiber and materials manufacturer we accumulated at a deep discount to tangible book value. The company had been pressured by an extended destocking cycle across the global textile and apparel supply chain, which caused revenue declines and severe margin compression. Rather than waiting for demand to recover, management executed a broad operational turnaround by closing redundant plants, shifting production to lower-cost regions, and emphasizing proprietary higher-margin products. As order volumes stabilized, the company’s operating leverage became evident. The business moved from operating losses to cash generation, gross margins recovered by several hundred basis points, and the stock re-rated accordingly.
Capital allocation across the basket has also remained disciplined. Supported by net-cash or low-leverage balance sheets, several management teams have used excess cash flow to repurchase deeply discounted shares, increasing per-share value. Despite the basket’s strong year-to-date advance, these businesses still trade at modest multiples of normalized earnings and free cash flow. As core-end market demand continues to recover, I believe the group remains early in a multi-year earnings recovery.
During the first half of the year, we fully exited our position in Sanuwave Health (SNWV). Sanuwave entered 2026 as a relatively small holding. We had originally purchased shares when the business was deeply discounted trading on the OTC market and realized most of our gains at substantially higher prices, selling the bulk of the position in the $20s and $30s. After reviewing the company’s first-quarter results, I decided to sell the remaining shares and move on.
Advertisement
The exit was driven by reduced visibility into Sanuwave’s future growth. Much of the company’s recent revenue growth has come from mobile wound-care clinics using the UltraMist platform. However, the economics for those operators changed materially. Mobile clinics had previously generated very high margins from tissue-based skin grafts, while UltraMist, despite its clinical benefits, does not carry the same reimbursement profile.
As reimbursement pressure reduced margins, it became increasingly clear that many mobile wound-care operators were under significant financial strain. In my view, a meaningful portion of that customer base was and is likely to fail. Because Sanuwave’s forward growth depended heavily on a structurally challenged channel, the risk/reward profile had deteriorated. Sanuwave was ultimately a successful investment for the fund despite the recent stock price deterioration, but exiting the remaining position allows us to redeploy capital into opportunities where I have greater confidence in the predictability and durability of future cash flows.
Pro-Dex is a new holding added during the fourth quarter of last year. I have followed the company for many years and have long sought an opportunity to own shares at an attractive price. That opportunity emerged when the stock sold off on concerns that Pro-Dex’s largest customer contract would not be renewed at year-end 2025. The risk was resolved when the company secured a three-year extension through 2028, including minimum purchase commitments for 2026 and 2027. The renewal reinforces the durability of a relationship that has lasted more than fifteen years and provides a predictable, cash-generative base from which Pro-Dex can fund growth.
Pro-Dex is a specialized medical device manufacturer that designs, builds, and repairs powered surgical handpieces for large OEM customers under long-term, exclusive supply agreements. These relationships are difficult to displace because each product is tied to customer-specific regulatory clearances, designs, validated manufacturing processes, and intellectual property owned by Pro-Dex.
Advertisement
The most attractive upside to the business comes from Pro-Dex’s role as the exclusive hardware and component partner for Zimmer Biomet’s mBôs robotic surgery platform. Pro-Dex manufactures the platform’s motorized end-effector components and receives a high margin sourced products fee on third-party disposable cutting tools used in each procedure, creating a recurring, procedure linked revenue stream. The company also owns 2.2 million contingent value rights tied to Zimmer Biomet’s acquisition of Monogram Technologies. These are carried at zero on the balance sheet but could pay more than $25 million, or roughly $6.80 per share, if future mBôs milestones are achieved. In addition, the February 2026 acquisition of Advanced Precision Machining brings a key supplier in-house, expands manufacturing capacity, and adds higher margin aerospace, defense, and government customers.
At today’s price, PDEX offers asymmetric upside. We are paying primarily for the stable core business while receiving the potential mBôs economics and off-balance-sheet CVR value for little to no credit. If commercialization scales over the next 24 to 36 months, Pro-Dex has a clear path to materially higher earnings power and a substantially higher share price.
Undisclosed Holding
During the second quarter we built a position in a specialized healthcare supply business that resonates with previous investments as an overlooked turnaround trading at a significant discount to underlying business value. The company produces essential recurring consumables used daily in life-sustaining medical treatments. Despite sticky demand, a net-cash balance sheet, and improving margins, the stock trades at a low single-digit multiple of normalized cash flow.
The stock continues to be weighed down by a legacy concern tied to the loss of its largest customer. That customer represented a substantial portion of volume, and its departure created a sharp revenue gap that caused a significant decline in the share price. Rather than permanently impairing the business, however, the setback forced a broad restructuring. Management cut legacy overhead, renegotiated contract economics, improved pricing, and rebuilt the commercial strategy.
Advertisement
Today, the business is stronger and more resilient. The lost revenue has been absorbed, and the customer base is now diversified across dozens of regional providers and independent clinics, eliminating the prior customer concentration risk. Growth has also re-accelerated as the company entered a major new geographic territory, won several multi-year supply contracts, and gained share in markets where it previously had no presence. As these contracts ramp, the business will begin to benefit from operating leverage across its manufacturing and distribution footprint. Incremental volume will convert to profit at high operating margins and produce consistent positive cash flow. At a single-digit forward cash-flow multiple, the market is still valuing the company based on past challenges rather than current fundamentals. We are paying a distressed multiple for a stabilized, growing, and diversified business that should re-rate as it continues to deliver clean operational results along with the potential for one or several acquisitions to meaningfully accelerate operating leverage.
Closing Thoughts
Halfway through the year, the fund is off to a strong start, driven by solid operational execution across our core holdings. While these initial results are gratifying, I want to remind partners to temper their expectations and avoid extrapolating our first half performance forward on a permanent basis. Investment returns rarely compound in a straight line, and there will inevitably be quieter stretches or periods of noise along the way. That said, I remain deeply confident in how the portfolio is currently structured. I believe the fund is positioned to generate highly attractive returns on a go forward basis.
Right now, my pipeline of actionable ideas is abundant, I currently have more compelling opportunities than I have capital to allocate. If you know of accredited investors who share our disciplined, long-term approach to bottom-up investing, I would be deeply grateful for an introduction.
Thank you for your continued partnership, trust, and shared long-term perspective as I steward your capital alongside my own. I look forward to updating you on our progress again at year-end. Please do not hesitate to contact me with any questions regarding the matters discussed above.
Advertisement
Sincerely,
Sean Kirkwood
Advertisement
SRK Fund
S&P 500 TR
Russell 2000 TR
2018
2.90%
-4.03%
-11.72%
2019
77.99%
31.48%
25.52%
2020
127.72%
18.40%
20.00%
2021
46.71%
28.71%
14.78%
2022
35.31%
-18.11%
-20.47%
2023
17.15%
26.29%
16.93%
2024
-8.74%
25.02%
11.54%
2025
47.12%
17.88%
12.81%
YTD 2026
26.80%
10.18%
22.57%
Cumulative
1551.26%
222.91%
118.90%
Annualized
40.98%
15.44%
10.07%
The information contained herein is a reflection of the opinions of SRK Capital as of the date of publication and is subject to change without notice at any time subsequent to the date of issue. SRK Capital does not represent that any opinion or projection will be realized. All the information provided is for informational purposes only and should not be considered as investment advice or a recommendation to buy, sell, or hold any specific security. While it is believed that the information presented herein is reliable, no representation or warranty is made concerning the accuracy of any data presented. This communication is confidential and may not be reproduced without SRK Capital’s prior written consent.
Indices are provided as market indicators only. It should not be assumed that holdings, volatility, or management style of SRK Fund I, LP, or is intended to, resemble that of the mentioned indices. Index returns supplied by various sources are believed to be accurate and reliable.
Past performance is not indicative of future performance. Inherent in any investment is the possibility of loss.
This performance reporting is not an offer to sell or a solicitation of an offer to buy an interest in SRK Fund I, LP. Such an offer may only be made after you receive the Confidential Offering Memorandum and have had the opportunity to review its contents. This reporting does not include certain information that should be considered relevant to an investment in SRK Fund I, LP including, but not limited to, significant risk factors and complex tax considerations. For more information, please refer to the appropriate Memorandum and read it carefully before you invest.
The theatre in Boscombe is a listed building which opened in 1895
Amy Woodward, Local Democracy Reporter
07:59, 21 Sep 2026Updated 08:06, 21 Sep 2026
O2 Academy(Image: Local Democracy Reporting Service)
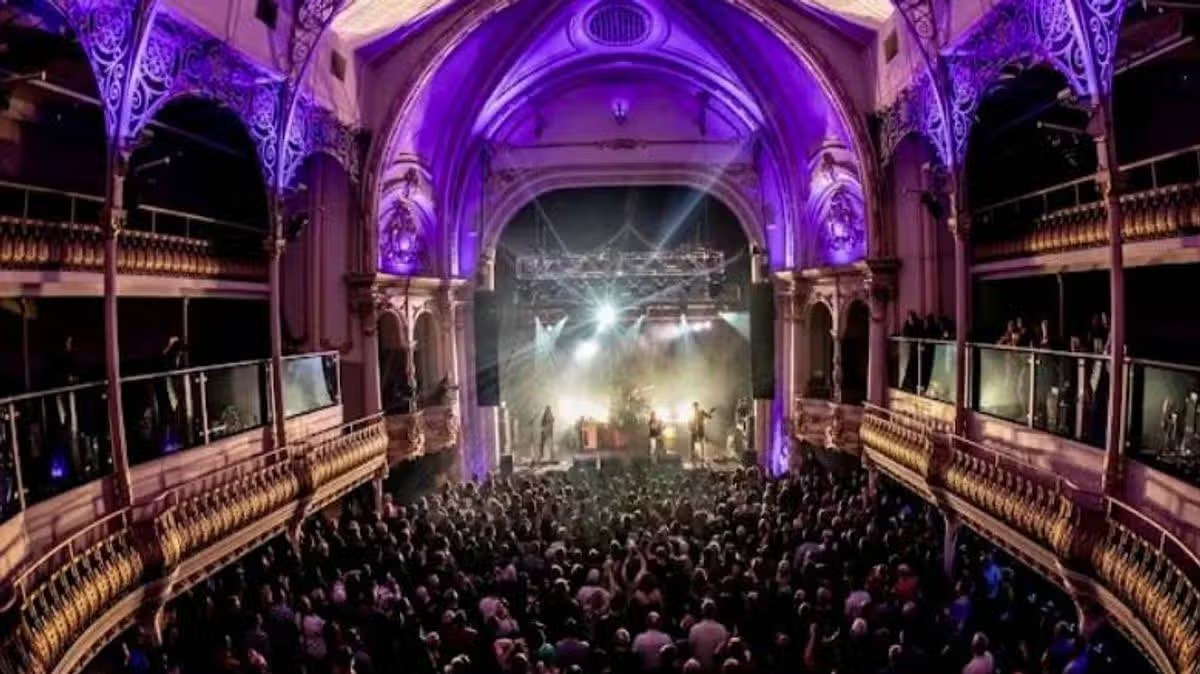
A plan to renovate part of the O2 Academy in Bournemouth has been lodged to improve facilities at the venue.
Advertisement
The theatre in Boscombe, previously known as the Boscombe Hippodrome, is a listed building which first opened its doors in 1895. The building has an extensive heritage as an entertainment destination, welcoming legendary acts such as Pink Floyd, Status Quo, and Led Zeppelin throughout its years as a music venue.
The site has experienced numerous transformations across the decades, evolving from a dance hall to a disco, then operating as a nightclub before its current incarnation as the O2 Academy.
Live Music has lodged a planning application to undertake refurbishments that will convert presently unused back-of-house areas, which will be made accessible to the public, incorporating a new accessible toilet, first aid facility, and a storage space.
Planning documents indicate that “minimum impact on the existing structure” is planned and are designed to improve its offering to the public.
Advertisement
The proposed works follow a risk assessment survey and seek to deliver a more secure fire escape route while preserving existing fire escape doors.
02 Academy Bournemouth 570 Christchurch Road Bournemouth BH1 4BH.




































You must be logged in to post a comment Login