Connect with us

Business

Paytm, MobiKwik, Pine Labs shares rally up to 6% after govt announces UPI fees above Rs 2,000. Why brokerages are bullish

Published

on

Paytm, MobiKwik, Pine Labs shares rally up to 6% after govt announces UPI fees above Rs 2,000. Why brokerages are bullish
Shares of Paytm, MobiKwik and Pine Labs rallied up to 6% on Wednesday after the government announced the first-ever Merchant Discount Rate (MDR) on select UPI transactions above Rs 2,000.

In today’s early session, Paytm rose 6% to a day’s high of Rs 1,829 per share, while One MobiKwik Systems rose over 5% to Rs 213 on the BSE. Pine Labs gained nearly 3% to Rs 199 per share on the NSE.

The National Payments Corporation of India (NPCI) on Tuesday announced that the government will introduce MDR on some Person-to-Merchant (P2M) UPI transactions from October 15 onwards, with merchants paying 0.4% on transactions above Rs 2,000. The maximum fee that can be levied on such transactions will be Rs 300 for payments of Rs 75,000 or more.

Also read | UPI transactions above Rs 2,000 to attract 0.4% MDR; check key details

Advertisement

What new UPI charges mean for consumers?

It is important to note that consumers will not be charged for UPI payments, and Person-to-Person (P2P) transfers will remain free. Small merchants classified under the P2PM framework, including vendors that receive up to Rs 1 lakh a month through UPI QR codes, will continue to be exempt from MDR.


Transactions worth up to Rs 2,000 will continue to carry zero charges and account for more than 95% of UPI’s P2M transaction volume, according to the FAQ released by the government. The NPCI clarified that MDR will be borne by merchants and cannot be passed on to customers. This implies that consumers will continue to pay the listed price when using UPI, with no separate transaction or platform fee imposed by UPI apps.

RBI backs MDR charges

The Reserve Bank of India (RBI) backed the introduction of Merchant Discount Rate (MDR) on large-value UPI transactions, saying the move will help strengthen the long-term sustainability of India’s digital payments ecosystem. In a post on X, the central bank said the move would enable UPI to continue scaling, innovating and serving consumers and businesses across the country.The latest move comes after an amendment to the Payment and Settlement Systems Act, 2007, which provides a framework for imposing a Merchant Discount Rate (MDR) on payments through UPI and other notified electronic payment modes. The government, in a statement, explained the rationale for imposing charges, stating that with exponential transaction volumes, the system requires significant and continuous upgrades in cybersecurity, fraud prevention, and infrastructure.

Charges were required for market expansion and self-sustainability, it said, adding that it is necessary to increase competition by encouraging more companies to expand operations, which requires a self-sustaining revenue model. Reliance on subsidies alone is not viable for the next wave of growth, and a balanced framework is required to ensure that UPI remains robust, inclusive and future-ready, the statement further said.

Advertisement

Also read | UPI Charges Explained: Will you pay a fee for Rs 2,000+ UPI payments? Government clarifies what users need to know

‘Someone has to pay the cost’

For nearly seven years, UPI became more and more popular as a transaction could be made so quickly without paying any additional charges. The government has however, repeatedly clarified that UPI will remain free for citizens and person-to-person transactions will continue without charges.

While discussing the costs of digital-payment infrastructure, RBI Governor Sanjay Malhotra in August said, “Someone has to pay the cost”. He stressed that the RBI wants digital payments to remain accessible, affordable and safe, but also sustainable.

What lies ahead?

According to Bernstein, banks could receive about Rs 14,000 crore of this pool, while payment apps could earn around Rs 7,000 crore, and the network about Rs 1,000 crore. Emkay Global Research meanwhile said the latest move will likely benefit Paytm and Pine Labs, while maintaining its ‘Buy’ calls on the stocks and increasing target prices to Rs 2,400 and Rs 230 respectively.

Advertisement

“UPI acquiring now carries a commercial revenue model that is contractual, recurring, and scales with value, in place of a discretionary annual subsidy. This will make the payment business structurally self-sustaining, making the business model much more resilient,” the domestic brokerage said, adding that even on conservative assumptions, it estimates Paytm to generate UPI MDR revenue of Rs 1,120 crore in FY28, and expects Pine Labs to generate Rs 155 crore in the same year.

Bullish brokerage calls for Paytm share price

JM Financial also increased its target price for the shares of Paytm to Rs 2,150 apiece, implying more than 24% upside potential from the stock’s previous closing price, while maintaining its ‘Buy’ call on the stock. The notified MDR rate is materially above the 25 bps JM Financial had modelled in, but the carve-outs are also broader than assumed, forcing our hand to cut the eligible-GMV overlay to 20% (from 30% earlier).

The new charges on UPI transactions are expected to generate incremental revenue of Rs 2.1 billion in FY27 and Rs 4.7 billion in FY28, according to the domestic brokerage. “MDR converts a structurally zero-revenue GMV pool into ‘monetisable’ volume with nearly full flowthrough to EBITDA, not to mention a clear resolution to the long-standing regulatory overhang on UPI monetisation,” it added.

Jefferies recently increased its price target for the shares of Paytm to Rs 2,100 apiece from Rs 1,600 apiece, while maintaining its ‘Buy’ call. The international brokerage highlighted that Paytm stands out on monetisation of its client base in near-zero MDR regime, which is now changing favourably. The fintech platform’s 4.9 crore merchant base and strong loan-origination model should drive 25% revenue CAGR over FY26-29, which, along with operational synergies will aid sharp rise in EBITDA and profit, it added.

Advertisement

Initiative in credit on UPI, cloud AI inference models, wealth offering and foray into overseas markets can lift growth, the international brokerage said, as it increased earnings estimates for FY28-29 by 20-25% to factor 25 bps MDR on UPI.

Bernstein recently named Paytm its top pick, citing robust merchant lending growth, operating leverage and the potential introduction of MDR on UPI as key drivers of earnings growth.

With a target price of Rs 2,200, Bernstein expects Paytm’s EPS to reach Rs 78 by FY29. Even after excluding any potential impact from MDR on UPI, its FY29E EPS estimate stands at Rs 54, still above the Rs 46 consensus estimate.

Also read | RBI backs MDR on large-value UPI transactions, says could help expand UPI acceptance

Advertisement

Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.

Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business

Why is Space Exploration Technologies stock rallying today?

Published

on


Why is Space Exploration Technologies stock rallying today?

Continue Reading

Business

What’s happening to UK interest rates and mortgage deals?

Published

on

A woman with long, blonde hair talks into a microphone

Mortgages

Just under a third of households have a mortgage, according to the government’s English Housing Survey, external.

About 500,000 homeowners have a mortgage that “tracks” the Bank of England’s rate. That means any cut means a reduction in the monthly repayments on their outstanding loan.

An additional 500,000 homeowners on standard variable rates (SVRs) rely on their lender choosing to pass on any Bank rate cut.

Advertisement

But the vast majority of mortgage customers – some 87% – have fixed-rate deals. While their monthly payments aren’t immediately affected by a rate change, their future deals are.

As of 16 September, the average two-year fixed residential mortgage rate was at its highest since 11 May (5.77%), while the average five-year was at its highest since 8 November 2023 (5.83%), according to the financial information service Moneyfacts.

The average two-year tracker rate was 4.54%.

About 800,000 fixed-rate mortgages with an interest rate of 3% or below are expected to expire every year, on average, until the end of 2027. Borrowing costs for customers coming off those deals are likely to rise sharply.

Advertisement

Mortgage calculator

You can see how your mortgage may be affected by future interest rate changes by using our calculator:

Advertisement
Continue Reading

Business

Stock Market Today: Dow Wavers Ahead Of Likely Fed Rate Hike, Warsh Comments; Intel, SK Hynix Jump

Published

on

Fed Chair Warsh Leans Hawkish In Jackson Hole Speech (Live Coverage)

The Dow Jones Industrial Average and the other major stock indexes traded mixed Wednesday as Wall Street braced for a likely Federal Reserve rate hike and Fed Chair Kevin Warsh’s press conference. Meanwhile, Nvidia (NVDA), Intel (INTC) and SK Hynix (SKHY) were early winners on the stock market today Just after Wednesday’s open, the Dow industrials dipped 0.2% as the S&P…

Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8

Continue Reading

Business

CHS to build Wisconsin soybean processing plant

Published

on

CHS to build Wisconsin soybean processing plant

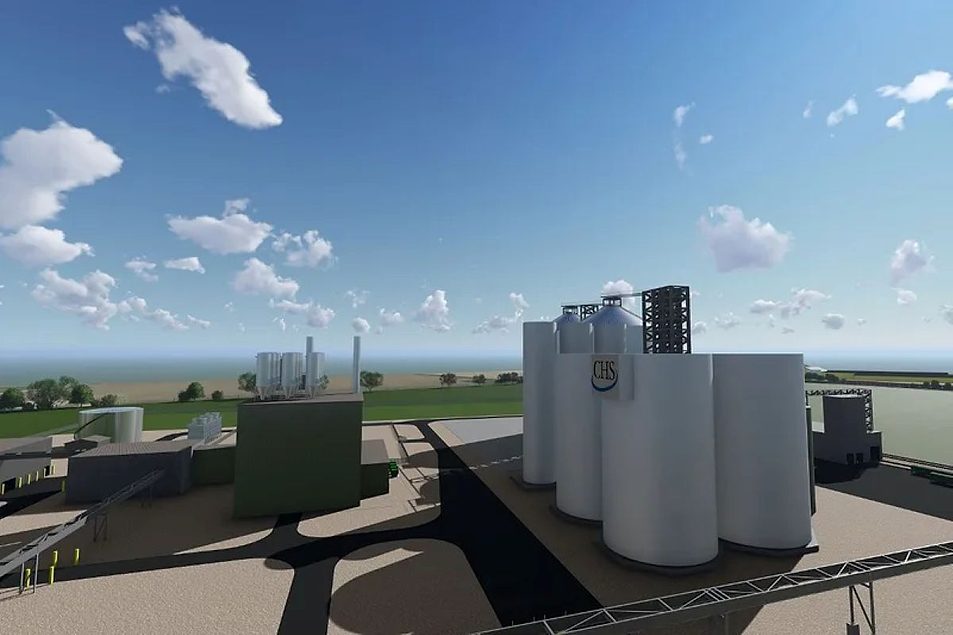
INVER GROVE HEIGHTS, MINN. — CHS plans to construct a $700 million soybean processing facility near Evansville, Wis., significantly expanding the global agribusiness’ ability to meet growing demand for soybean oil and meal.

The facility will have the capacity to process 80 million bus of US-grown soybeans annually, expanding the cooperative’s oilseed processing capabilities and creating new market opportunities for owners, CHS said in its Sept. 14 announcement. With construction slated to begin soon, the plant is targeted for completion for fall 2028.

“Investments like this help CHS create additional value for our owners and customers by expanding market access, strengthening our processing network and creating new demand opportunities for US-grown soybeans,” said John Griffith, executive vice president of agriculture business and CHS Hedging. “Strong demand across food, feed and renewable fuel markets, coupled with policies that encourage domestic processing, manufacturing and energy production, reinforce the need for additional soybean processing capacity in the United States. This facility positions CHS to support farmers and customers for years to come.”

The Evansville facility will increase soybean processing capacity in southern Wisconsin, a region with strong soybean production and significant demand for soybean meal from livestock producers, CHS said.

Advertisement

When operational, the facility is expected to employ about 80 people and produce approximately 1 billion lbs of oil and 2 million tons of meal annually. Evansville’s proximity to soybean production, rail service and major transportation corridors makes it well positioned to support the movement of soybean meal and oil to domestic and global markets.

“For Wisconsin soybean farmers, this investment represents something we have been working toward for years: stronger demand for the crop we grow right here at home,” said Doug Rebout, president of the Wisconsin Soybean Association. “Additional processing capacity gives growers another reliable market close to the farm and helps create long-term opportunities for Wisconsin soybeans in both meal and oil markets.”

CHS said the new facility also will complement the company’s existing oilseed processing operations. In Hallock, Minn., CHS processes 525,000 tonnes of canola seed annually. In Fairmont and Mankato, Minn., CHS processes approximately 119 million bus of soybeans. When the facility becomes operational, the company’s soybean processing capacity will increase by more than two-thirds.

The investment is expected to generate significant economic activity through construction employment, permanent jobs, increased demand for locally produced soybeans and expanded market opportunities for regional farmers.

Advertisement

“CHS is committed to being a long-term partner in the communities where we operate,” Griffith said. “This investment supports rural economic development, creates jobs and strengthens the agricultural supply chain for producers, customers and communities across the region.”

CHS, a global agribusiness and the largest farmer-owned cooperative in the United States, operates diversified agronomy, grains, foods and energy businesses with revenues of $35.5 billion in fiscal year 2025. 

Continue Reading

Business

S&P upgrades Newmark Group rating to BBB- on strong credit

Published

on


S&P upgrades Newmark Group rating to BBB- on strong credit

Continue Reading

Business

Is GameStop Still Chasing eBay? Inside Ryan Cohen’s Wavering $56 Billion Takeover Saga Late This Fall

Published

on

The eBay app is seen on a smartphone in this illustration taken

GameStop’s monthslong pursuit of eBay remains unresolved heading into the fall, with Chief Executive Officer Ryan Cohen appearing to have pulled back from an outright acquisition in favor of a scaled-down partnership, even as the video game retailer continues holding one of the largest outside stakes in the e-commerce company.

The saga began in earnest on May 3, when GameStop submitted a non-binding proposal to acquire 100% of eBay for $125 per share in a combination of cash and stock, valuing the deal at approximately $55.5 billion on an undiluted basis. The offer represented a 46% premium to eBay’s closing price on February 4, the day GameStop began accumulating its stake in the company, and came after GameStop had already built roughly a 5% economic interest in eBay through a mix of derivatives and direct share ownership.

EBay’s board rejected the proposal on May 12, saying in a statement that the offer was “neither credible nor attractive.” Company chairman Paul Pressler expressed confidence in eBay’s existing management and standalone strategy, with the board citing concerns about the deal’s financing structure and its potential impact on eBay’s long-term profitability and growth. GameStop did not immediately abandon the pursuit following that rejection. By June, Cohen had taken the offer directly to eBay shareholders in what amounted to a hostile bid, pairing that move with a separate $2 billion share buyback program for GameStop’s own stock running through June 2029. GameStop further increased its position in July, disclosing a stake of 9.8% in eBay, cementing its status as one of the company’s largest shareholders.

Cohen struck a defiant tone about the pursuit in a Bloomberg Television interview in July, telling the network, “we’re coming for eBay one way or another,” while declining to say whether GameStop intended to raise its offer. Cohen has described his broader ambition as building a combined company worth as much as $1 trillion, citing potential synergies in trading cards and collectibles, plans to develop a digital marketplace for video game items, and the idea of using GameStop’s physical retail locations as authentication hubs for collectible card grading.

Advertisement

That posture shifted by early August. Bloomberg News reported on August 10, citing people familiar with the matter, that Cohen was weighing withdrawal of the full $56 billion takeover bid in favor of a more modest partnership or joint venture arrangement. Under that alternative structure, eBay would be able to leverage GameStop’s approximately 1,600 U.S. retail locations, with the two companies potentially expanding their respective footholds in higher-margin categories such as trading cards and collectibles. As part of any such partnership, GameStop would seek representation on eBay’s board of directors, according to the report. The sources cautioned that GameStop had not made a final decision at the time and that Cohen could still pursue other options.

Market reaction to the reported shift was telling. GameStop shares climbed roughly 1.6% in early trading following the report, while eBay shares fell about 2.2%, a divergence that reflected how differently investors had come to view the original acquisition proposal. Bloomberg noted that GameStop’s stock had fallen 28% since Cohen first floated the takeover bid in May, while eBay’s shares had risen 7.6% over the same period, suggesting the market had grown skeptical that the original deal would ever close and viewed a retreat from it as reducing risk for GameStop specifically.

Financial analysts had raised similar doubts from the outset. Commentary published around the time of the original proposal noted the structural mismatch at the heart of the deal: GameStop, a brick-and-mortar retailer that purchases and resells inventory through its store network, was attempting to acquire a company worth nearly six times its own market value that operates an entirely different business model, an online marketplace earning fees by connecting buyers and sellers. Analysts also flagged the heavy reliance on debt financing and stock issuance embedded in the original proposal’s structure as a key point of skepticism.

GameStop’s most recent financial disclosures show the company has continued adjusting its balance sheet even as the eBay situation remains unsettled. The company reported second-quarter results on September 8, posting adjusted earnings per share of 27 cents, in line with consensus estimates, though quarterly revenue fell to $790.2 million from $972.2 million a year earlier, a decline the company attributed to the absence of a comparable Nintendo Switch 2 launch tailwind from the prior year, ongoing store closures, and other divestitures. As of August 1, GameStop held approximately 43.4 million shares of eBay common stock, with a fair value of roughly $4.9 billion, underscoring the scale of GameStop’s continued financial exposure to eBay even amid the reported reconsideration of its original acquisition plan. Separately, GameStop disclosed on September 3 that it had completed exchanges retiring approximately $1.4 billion in convertible notes, reducing its total long-term debt to approximately $2.8 billion.

Advertisement

As of the most recent public reporting, GameStop has not issued a formal statement confirming either the full withdrawal of its original $56 billion acquisition proposal or the formal launch of an alternative partnership structure with eBay. The company’s substantial remaining equity stake in eBay, combined with Cohen’s continued public interest in the collectibles and e-commerce space, suggests some form of ongoing relationship between the two companies remains likely, even if the original vision of a full corporate takeover appears to have given way to a more measured approach centered on retail partnership and board representation rather than outright ownership.

Continue Reading

Business

FDA Issues Class II Recall on Hand Soap Sold Across 15 States Over Serious Bacterial Contamination Risk

Published

on

Handwashing

The U.S. Food and Drug Administration has formally classified an ongoing hand soap recall as a Class II action, confirming that six products distributed by Intercon Chemical Co. of St. Louis across 15 states may be contaminated with bacteria capable of causing serious infections, including pneumonia, urinary tract infections and bloodstream infections.

The FDA issued its enforcement report on September 11, assigning Class II status to a voluntary recall that Intercon Chemical Co. had first initiated on June 29. A Class II classification indicates that use of or exposure to the affected product could cause temporary or medically reversible health problems, while the probability of more serious adverse health consequences is considered remote, though not eliminated, particularly for vulnerable individuals.

According to the FDA, two of the six recalled soap products tested positive for potential contamination with multiple strains of Pseudomonas and Serratia bacteria, including Pseudomonas aeruginosa and Serratia marcescens. Both species are recognized by the Centers for Disease Control and Prevention as common environmental bacteria typically found in soil and water, but both are also capable of causing significant infections in humans, particularly when they enter the bloodstream or come into contact with compromised tissue. According to the CDC, Pseudomonas aeruginosa is the species most likely among the two to cause bloodstream infections, pneumonia or urinary tract infections, while Serratia marcescens has been linked to a broader range of infections, including those affecting the eyes, stomach, brain, bones and heart, in addition to blood and respiratory infections. Both bacterial species can also exhibit resistance to common antibiotics, complicating treatment in cases where an infection does occur.

The recalled hand soap was distributed to 19 wholesale companies and one retail company spanning California, Georgia, Illinois, Iowa, Maryland, Mississippi, Nebraska, New York, North Carolina, North Dakota, Pennsylvania, South Carolina, Texas, Washington and Wisconsin. While much of the recalled product was distributed for commercial or institutional use in businesses and public facilities, one of the six affected products, sold under the Laura Lynn brand, was shipped directly to retail stores where individual consumers could purchase it.

Advertisement

The six recalled products span five separate brand names. Intercon Foaming Pear Hand Soap With Aloe, sold in 28.7-fluid-ounce containers under UPC 789745002981, was recalled across three lot codes, AF97312, 26-01001 and 26-01803, with 693 cases affected and potential contamination spanning five separate bacterial strains: Pseudomonas aeruginosa, Pseudomonas putida, Pseudomonas monteilii, Serratia marcescens and Serratia nematodiphila. A related product, Clearly Better by Intercon Foaming Pear Hand Soap With Aloe, sold in sizes ranging from 1,000 milliliters to 34 fluid ounces under UPC 789745002615, was recalled across lot codes 26-01001 and 26-01803, affecting 143 cases, with the same five bacterial strains identified as potential contaminants.

Summit 150 Foaming Hand Soap, sold in 28.7-fluid-ounce containers under UPC 810080570030, was recalled across three lot codes, BF97303, BF97304 and BF97305, affecting 1,040 cases, the largest volume among the six recalled products, with the FDA listing potential bacterial contamination generally rather than specifying particular strains for this product. Vestis Foaming Hand Soap in Fresh Pear Scent, sold in 33.8-fluid-ounce containers under UPC 810080570405 and lot code 26-03091, affected 225 cases. Two Laura Lynn-branded products rounded out the recall: Laura Lynn Honey Apple Crisp Liquid Hand Soap, sold in 8-fluid-ounce containers under UPC 086854074305 across lot codes C3576 and 26-01804, affecting 301 cases, and Laura Lynn Foaming Pear Scent Hand Soap with Moisturizers, sold in 7.5-fluid-ounce containers under UPC 08685407408 and lot code 26-01001, affecting 294 cases.

Consumers and businesses in possession of any of the affected products are advised to check the specific UPC codes and lot numbers against the FDA’s published list and to stop using any matching product immediately. Anyone who develops symptoms of infection after using one of the recalled soaps, including fever, unusual redness or swelling, respiratory symptoms, or urinary discomfort, is advised to contact a health care provider promptly, particularly given the elevated risk the bacteria pose to people with weakened immune systems.

The FDA has identified certain populations as facing heightened risk from exposure to either bacterial species. Individuals with compromised immune systems, underlying chronic conditions such as cancer or diabetes, or those who have been on extended courses of antibiotics face a greater likelihood of developing a serious infection if exposed to contaminated product, according to the agency’s guidance accompanying the recall.

Advertisement

The Intercon Chemical Co. recall adds to a broader pattern of FDA enforcement actions targeting consumer and commercial hygiene products in recent months, part of the agency’s ongoing effort to identify and remove potentially contaminated goods from the marketplace before they cause widespread illness. Because several of the recalled products were distributed primarily to commercial and institutional customers rather than directly to consumers, public awareness of the recall may lag behind that of more consumer-facing recalls, increasing the importance of businesses in the affected distribution states checking their own inventory against the FDA’s published product list.

As of the most recent update, the FDA had not reported any confirmed illnesses directly linked to the recalled hand soap products, though the agency’s classification of the recall as Class II reflects its assessment that the contamination poses a genuine, if not severe, health risk to those exposed. Consumers with questions about whether a specific product they possess falls under the recall are advised to consult the FDA’s official enforcement report directly for the complete list of affected UPC codes, lot numbers and best-by dates.

Continue Reading

Business

Cathie Wood Makes SpaceX Prediction, Forecasts $10 Trillion Starship Revenue By 2030

Published

on

Cathie Wood Makes SpaceX Prediction, Forecasts $10 Trillion Starship Revenue By 2030

Cathie Wood continues to be a strong believer in SpaceX’s prospects, as Elon Musk’s rocket and AI company represents a substantial portion of ARK’s stock holdings. Wood late Tuesday made a bold revenue prediction for Starship as SpaceX prepares to launch its 14th flight for the spacecraft next week. SPCX stock ticked higher early Wednesday. “Each Starship launch could generate…

Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8

Continue Reading

Business

UK’s biggest housebuilder Barratt Redrow slows land buying and cuts home sales outlook

Published

on

Business Live

Barratt Redrow said Middle East conflict was affecting consumer confidence

Construction work on a new-build house

Construction work on a new-build house(Image: PA Wire/PA Images)

Barratt Redrow has scaled back land purchases and trimmed its forecast for home sales in the year ahead, while warning the Government that planning reforms were “not enough”.

Advertisement

Britain’s largest housebuilder said the year had started well but that the Iran war had dented consumer confidence.

It nevertheless said that 17,667 home sales had been completed in the year to 28 June, a 5% increase on the previous year.

The firm’s pre-tax profit surged 48% year on year to £363.5 million, driven by higher sales volumes alongside measures to reduce operating costs.

This included a considerable reduction in the pace of new land acquisitions, by making expenditure “targeted and highly selective”, according to the company. Throughout the year, 3,029 plots were approved for purchase across 27 sites, compared with initial expectations of between 10,000 and 12,000 plots, which it noted were set prior to the Iran war.

Advertisement

Barratt Redrow, which is based in Coalville and has a key support office in Flintshire, told investors: “Reflecting both rising build costs in the second half of the year and the uncertainty as to the ultimate impact on homebuying demand of the Middle East conflict, we became more selective in our land buying.”

It nonetheless noted that it had benefited from an already robust land bank.

The company also revised down its home sales outlook based on current market conditions and activity in the financial year to date — now predicting total completions of between 17,500 and 17,900 in the 2027 financial year. This falls short of the previously forecast range of between 17,700 and 18,200 and was attributed to “continued planning delays”, according to the company.

Barratt Redrow said the promising start to 2026 was “sharply reversed” by the outbreak of the US-Israel’s war with Iran at the end of February, which pushed mortgage rates upward and brought the Bank of England’s cycle of interest rate cuts to a halt.

Advertisement

This has been “making homebuyers more cautious and increasing ongoing affordability challenges in the UK housing market”, the housebuilder said.

Barratt Redrow urged the Government to take further steps to make housebuilding more affordable in order to bolster demand, particularly amongst first-time buyers.

Chairwoman Caroline Silver said: “Whilst recent planning reforms should, in time, boost housing delivery, alone they will not be enough.

“It is only by reducing barriers to home ownership and addressing the increasing regulatory and tax burdens that are constraining housebuilding viability across many parts of the country, that the Government will be able to unlock increased levels of housing delivery, including affordable housing, to start to tackle the housing crisis, create jobs and drive economic growth across the country.”

Advertisement

In a further blow to the Government’s ambitions to construct 300,000 new homes annually, Kier Group announced on Tuesday that it would halt any new investment into its property development arm. Meanwhile, housebuilder Berkeley Group called for “urgent reform” of stamp duty to assist first-time buyers and those looking to downsize, in a bid to bolster property demand.

Shares in Barratt Redrow surged by more than 9% on Wednesday, following the announcement that £400 million would be returned to shareholders in the 2027 financial year.

Continue Reading

Business

Sling Therapeutics raises $123m for thyroid eye disease drug trial

Published

on


Sling Therapeutics raises $123m for thyroid eye disease drug trial

Continue Reading

Trending

Copyright © 2025