Connect with us

Business

Why is PayPal stock climbing today?

Published

on

Continue Reading
Click to comment

You must be logged in to post a comment Login

Leave a Reply

Business

Firefly Aerospace: The Next Rocket Stock Wall Street Will Chase (NASDAQ:FLY)

Published

on

Spaceship flying over earth with open bay doors revealing sunrise. 3d render

This article was written by

Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

Advertisement
Continue Reading

Business

Trump vows to reject ‘globalist scheme’ to rein in AI, superintelligence

Published

on

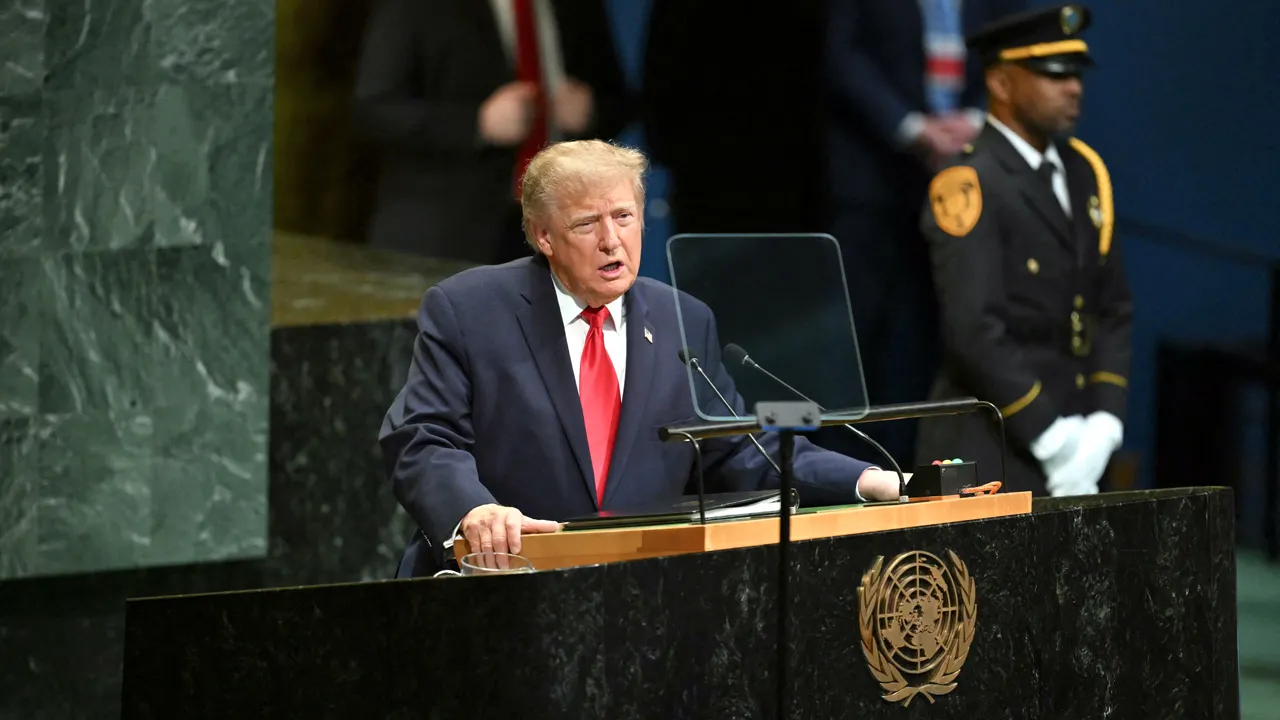
Trump vows to reject 'globalist scheme' to rein in AI, superintelligence

President Donald Trump on Tuesday said the U.S. will reject what he called a “globalist scheme” to control artificial intelligence (AI) and emphasized the importance of the U.S. winning the race in emerging tech.

The president made the remarks in an address to the United Nations General Assembly in New York City.

Advertisement

“The United States also totally rejects any attempt to construct a globalist scheme to control for the artificial intelligence being spoken of so much now,” Trump said, adding that he thinks AI should be referred to instead as “superintelligence” (SI).

“Whoever wins AI, you have to remember this, and now I say whoever wins SI, whoever wins superintelligence, wins. That’s the group that wins,” Trump said. “We’re leading now over China by a lot and everyone else. We’re going to keep it that way. We’re going to keep it very straight and very strong.”

NVIDIA’S JENSEN HUANG REJECTS AI DOOMSDAY FEARS: ‘2030 IS NOT GOING TO BE THE END OF THE WORLD’

President Donald Trump at the UNGA.

President Donald Trump addresses the 81st United Nations General Assembly at United Nations headquarters in New York on Sept. 22, 2026. (Angela Weiss/AFP via Getty Images)

“I’m not going to stifle growth of something that will be bigger than the industrial revolution, many say bigger than the industrial revolution or the internet itself,” Trump said, adding that the U.S. “will be very careful” and the Department of Justice will help oversee the industry.

Advertisement

“We will only encourage superintelligence. We’re going to encourage it, not rein it in. We’re going to watch it closely through the Department of Justice,” Trump said.

TECH POWER PLAYERS LAND SEAT AT TABLE FOR HIGH-STAKES DINNER WITH TRUMP, XI

“The United States leads the world in superintelligence and will continue to do so safely and responsibly. Americans have never been a nation that retreats from a frontier or shrinks from a challenge, no matter how great or how daunting that challenge may be,” Trump said.

Advertisement
Continue Reading

Business

Iran Offers to Reopen Strait of Hormuz Within Seven Days if US Eases Military Pressure, Lifts Blockade

Published

on

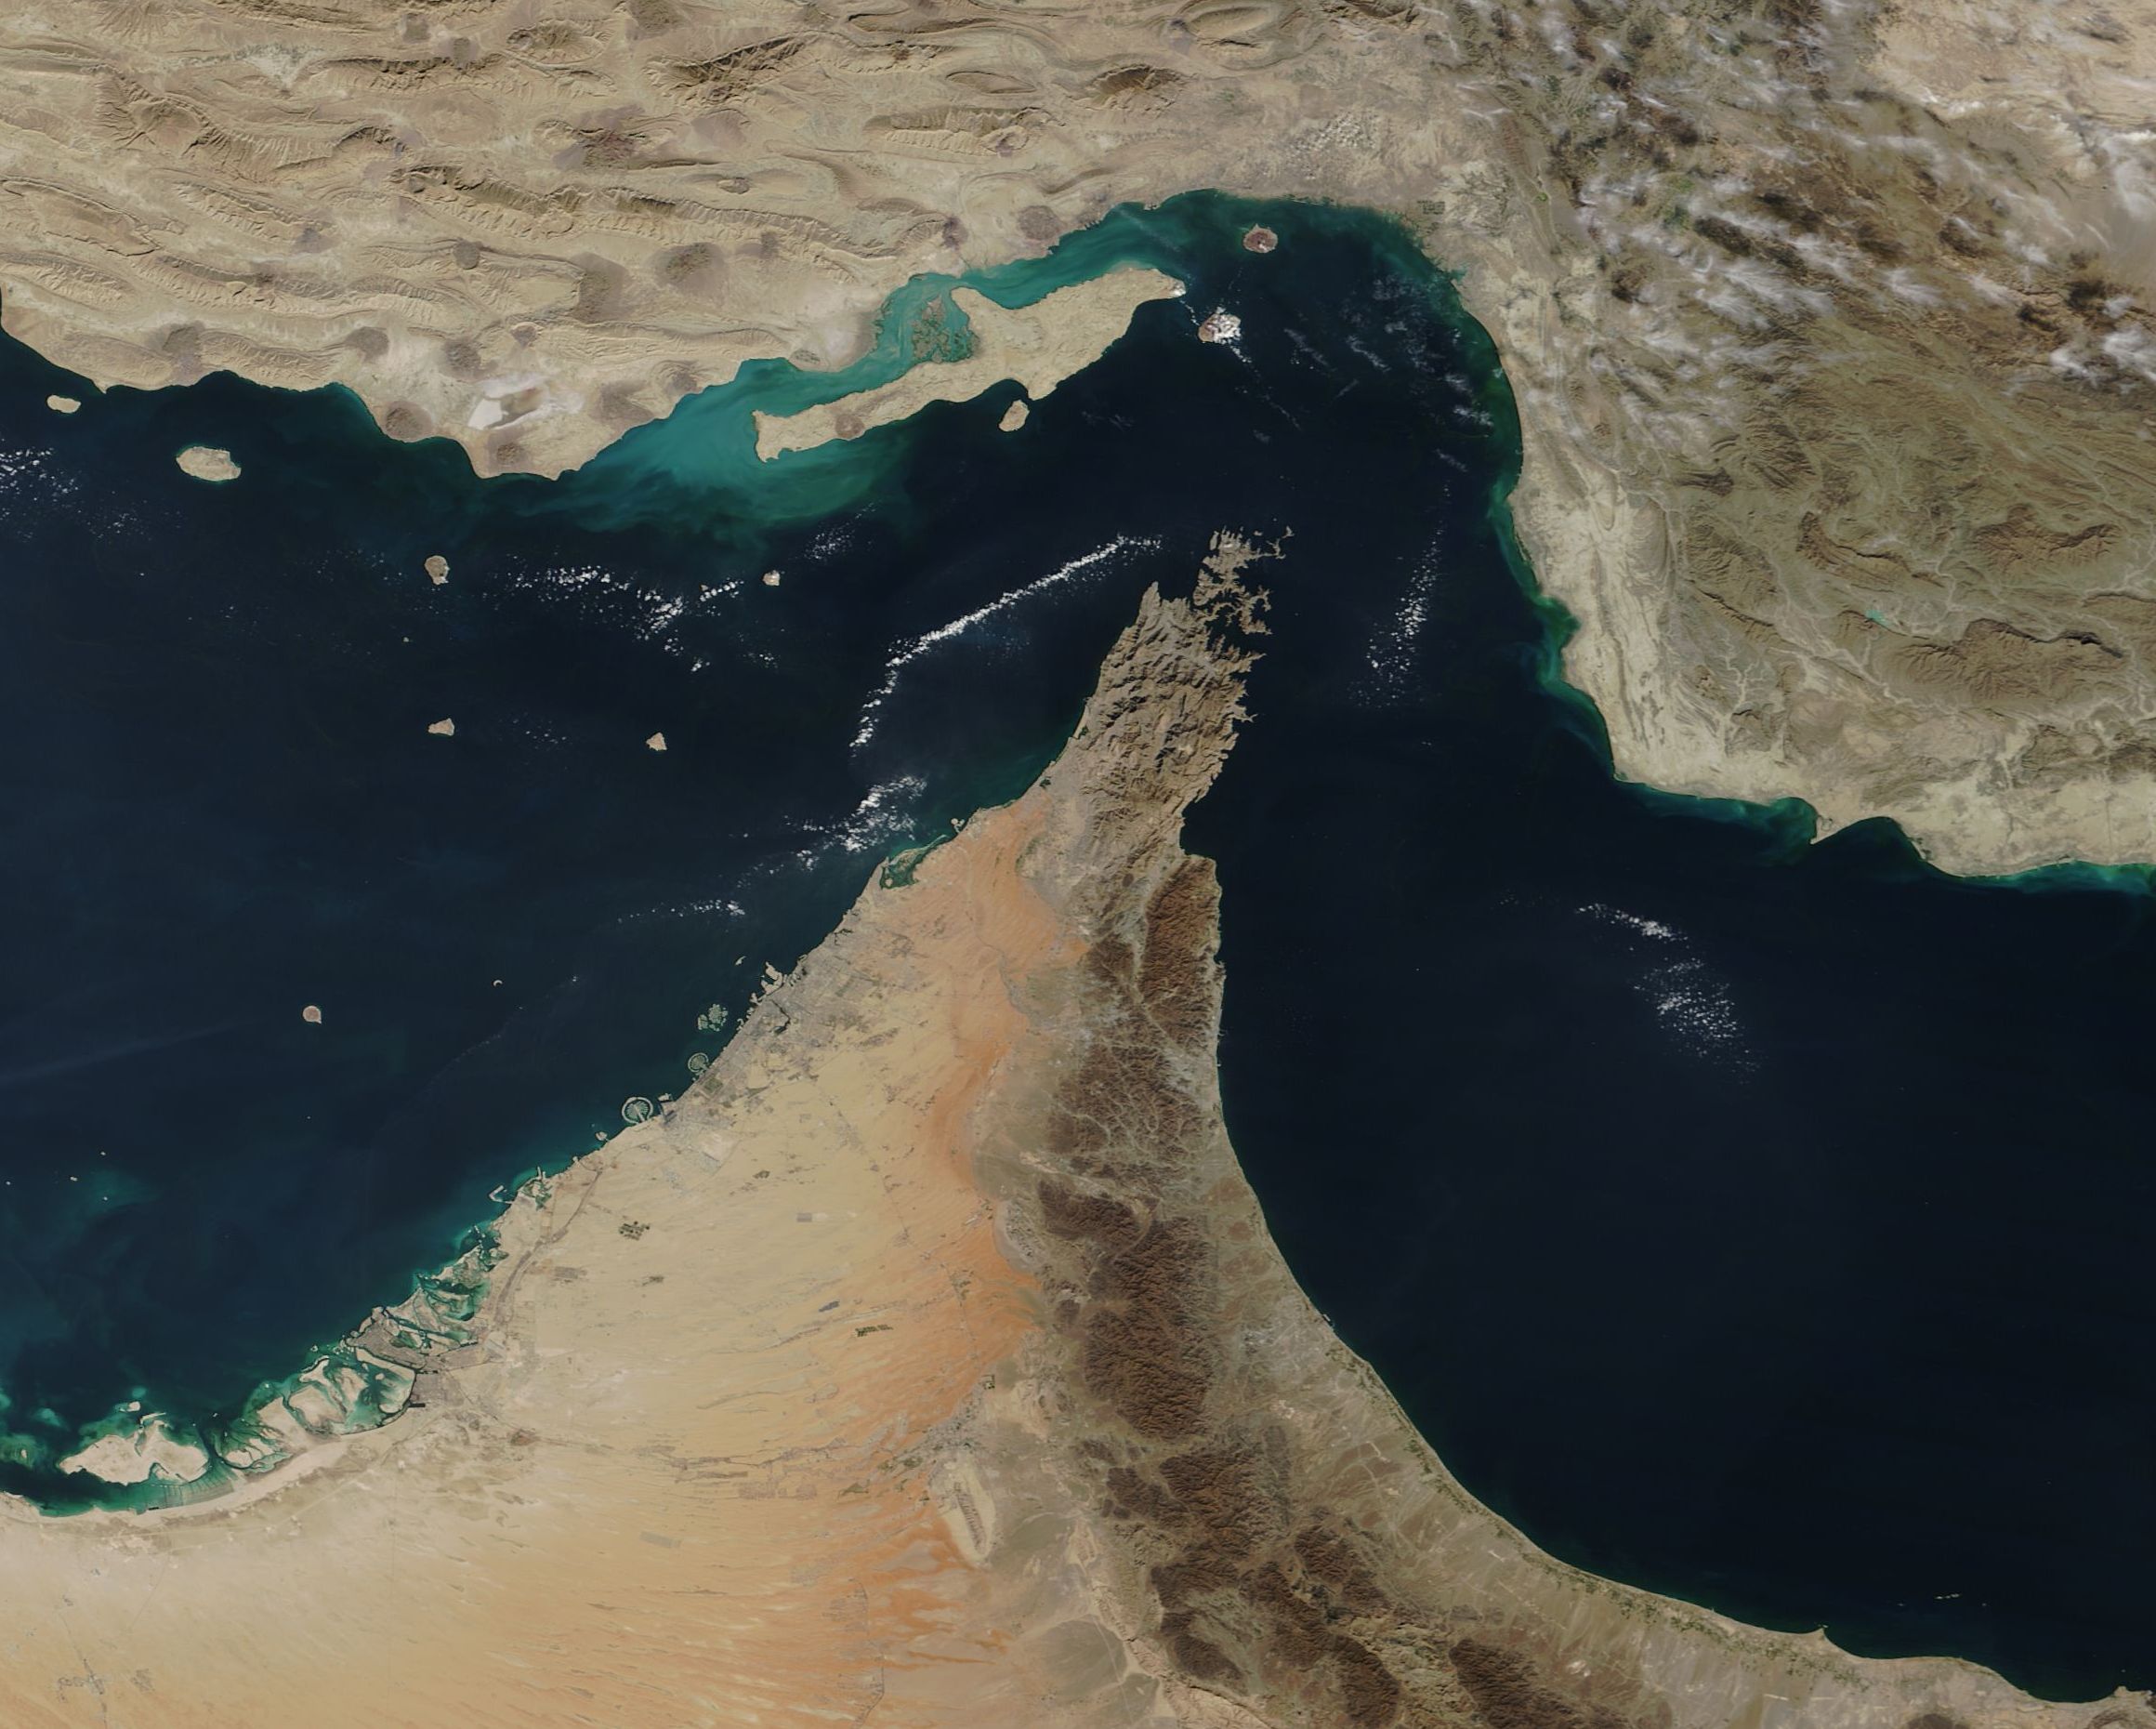
Kuwait International Airport

DUBAI — Iran has offered to reopen the Strait of Hormuz within seven days if the United States eases military pressure and lifts its blockade on Iranian ports, a senior Iranian official told Reuters on Tuesday, raising hopes for renewed diplomacy after nearly seven months of conflict in the Middle East even as violence continued along the strait itself.

The proposal, reportedly communicated to Washington through mediators, comes as Iran’s delegation to the United Nations General Assembly arrived in New York this week with what officials described as full authority to revive diplomatic talks with the United States. Iranian President Masoud Pezeshkian departed Tehran for New York on Tuesday morning, though he is not expected to meet directly with U.S. officials during the trip.

A senior Iranian official laid out the conditions Tehran is seeking before any reopening could take place. “The US needs to announce that it wants to resolve the issue diplomatically, make that official, and then agree on a timeline for how the process will move forward,” the official told Reuters. Iran had previously outlined seven separate conditions for restarting broader talks with Washington, including the lifting of the naval blockade on its ports and the unfreezing of Iranian financial assets held abroad.

The offer follows a tense weekend in which Iran’s military central command said it had been informed the United States was preparing to restart military operations with support from regional countries, warning that any renewed offensive would prompt Tehran to retaliate “without limitations and considerations.” That warning underscored how quickly the situation along the strait could escalate further even as this week’s diplomatic overture opened a potential path toward de-escalation.

Advertisement

Financial markets reacted quickly to the reports of Iran’s offer. Oil prices fell sharply, with Brent crude dropping below $99 a barrel, down more than 3.5% from the day’s earlier high, while U.S. West Texas Intermediate crude declined 2.25%. The moves reflected easing concern among traders that the seven-month disruption to global oil supply routed through the strait could be nearing some form of resolution, even though the proposal remains conditional and unconfirmed by the United States.

Despite the diplomatic opening, violence along the strait itself continued unabated in the days immediately preceding the offer. Iran struck another tanker on September 21, injuring two seafarers, according to the Maritime Executive, which cited reporting from the U.K. Maritime Trade Operations center. The vessel was identified as the LR Stephanie, a 72,825-deadweight-ton crude oil tanker registered in the Isle of Man. U.S. Central Command issued its own update the same day asserting that oil continues to move through the strait and that, in the command’s words, “momentum is building” toward normalized traffic, a characterization that stood in tension with Iran’s continued assertion of control over the waterway.

Shipping data compiled by different trackers has painted a somewhat inconsistent picture of just how much traffic is currently moving through the strait. Kpler data cited by Reuters showed only 17 vessels transited the strait over the weekend, down sharply from 37 the week before, with just one very large crude carrier and two refined product tankers making the crossing on Sunday. A separate tracking service, UA.NEWS, reported 12 vessels crossed the strait over the same weekend period, while IMF PortWatch data showed just eight transits recorded on September 13, compared with a pre-crisis daily baseline of roughly 85 vessels. The discrepancies among these figures reflect the difficulty of establishing a single authoritative count of traffic through the strait amid the ongoing crisis, though all available data points to traffic remaining dramatically below normal levels regardless of the exact figure used.

Additional maritime incidents were reported in the 24 hours before Tuesday’s diplomatic news broke. Maritime publications gCaptain and TradeWinds News reported that two seafarers were injured when tankers were struck by unidentified projectiles in the strait, without any party claiming responsibility for the attack. Separately, UKMTO reported that a liquefied petroleum gas tanker sustained damage from debris tied to unidentified projectiles in the same waterway. An unverified, single-source claim from Iranian outlet Pars Today asserted that an advanced reconnaissance drone had been destroyed over the strait, though that report could not be independently confirmed.

Advertisement

The crisis has also continued spreading to a second critical waterway. Iran-aligned Houthi forces in Yemen recently seized Perim Island in the Red Sea, tightening their control over the Bab el-Mandeb Strait, another essential chokepoint for global oil shipments and a key alternative route Saudi Arabia has relied on to bypass the Strait of Hormuz via its East-West pipeline. Houthi-linked media claimed a Saudi airstrike killed six people in the Yemeni port city of Mokha, though that claim has not been independently verified. In response to the expanding Houthi threat, the United Kingdom has reportedly agreed to support Saudi Arabia’s defense with Royal Air Force air-to-air refueling support for Saudi aircraft, an arrangement U.K. Prime Minister Andy Burnham said would remain in place for a matter of weeks and be kept under continuous review.

With Iran’s proposal now before Washington and reportedly under discussion through diplomatic channels in New York, the coming days are likely to determine whether the seven-month crisis moves toward a negotiated resolution or continues along the same pattern of intermittent attacks and disputed claims that has defined the standoff since it began in late February.

Continue Reading

Business

Microsoft Stock Scores Positive Reviews On AI Momentum

Published

on

Microsoft Stock Scores Positive Reviews On AI Momentum

Microsoft (MSFT) stock earned several positive analyst reports this week as the cloud computing and software giant grows its artificial intelligence business. On Tuesday, Oppenheimer analyst Brian Schwartz reiterated his outperform rating on Microsoft stock and raised his price target to 570 from 515. In a client note, Schwartz said he sees enterprise customers increasingly standardizing on Microsoft as their…

Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8

Continue Reading

Business

Polycab shares slide 17% in 3 months amid Ultravolt shock, but Jefferies sees 33% upside. What’s behind the bullish view?

Published

on

Polycab shares slide 17% in 3 months amid Ultravolt shock, but Jefferies sees 33% upside. What’s behind the bullish view?
Wires and cable stocks recently saw a sharp downturn after UltraTech entered the segment, with Polycab being one of the top losers and falling 17% from its June peak, but Jefferies remains bullish on the stock and sees 33% upside potential.

The international brokerage hosted Polycab’s management at the Jefferies India Forum 2026, following which it maintained its ‘Buy’ call and a target price of Rs 11,100 apiece, implying around 33% upside potential from the stock’s previous closing price of Rs 8,369.50 apiece.

Jefferies, in its note, highlighted that the cables and wires market is estimated to grow at 11-12% CAGR, while Polycab targets outperforming the overall market by 1.5 times, aided by a focus on new areas, products, customers, and growing wallet share with customers. Power is estimated to account for 40-45% of the company’s cables and wires demand, with power generation, renewable energy, and T&D network being the key drivers.

Despite the recent sharp surge in copper prices, Polycab is not yet witnessing any major demand disruption due to price hikes. Copper prices have jumped more than 43% YoY in Q2 FY27 so far. Demand from verticals like power, mobility, industry, infra and emerging spaces is growing at a healthy pace. The housing market remains healthy. Wires account for 70% of demand in this sector, the international brokerage noted. It estimates the company to post more than 20% sales CAGR over FY27-29.

Advertisement

Also read | Wires & cables face a new challenge: How Ultravolt’s big push could reshape India’s cable market

Polycab retains double-digit volume growth guidance

Polycab has retained double-digit volume growth guidance for most quarters in the next two to three years, Jefferies said, adding that the over 18% YoY volume growth in FY26 was higher than most peers. While underlying demand trends in the cables and wires market stay strong, the Q2-Q3 FY26 volume base of LY appears high, the international brokerage noted.
“Also, while copper volatility is passed on, it may impact channel stocking in the near-term. Generally, channel stocks up on inventory at the end of every quarter depending on the price outlook for the next few months. We factor cables and wires sales growth to moderate over FY26-29,” it added.Meanwhile, in the paints industry, while it is easier to launch SKUs and ancillary products to expand sales, this model is not similar to cables and wires, especially the former, Jefferies said. It added that the lower operating margin in cables and wires is not sustainable in the long term, and competition may be unable to undercut prices for long.

“Polycab has a higher share of cables than wires in its sales mix. Wires require minimal certification and have lower barriers to entry. Whereas cables, especially EHV, special applications, etc., require certifications for usage and durability, which have longer gestation periods. LV & MV cables require other standard certifications,” Jefferies said, adding that scale and distribution are key moats for Polycab.

The company has the capability to track and fulfil inventory of dealers within a day’s time, giving an edge over competition, and its 11-13% cables and wires operating margin guidance factors in all sensitivities, including competition, Jefferies said.

Advertisement

The international brokerage estimates the company to post FY26-29 PAT CAGR of over 22%, led by volume growth and firming FMEG margin. It retained its capex estimate at Rs 14-15 billion per annum over FY26-29. Amid the Ultravolt launch, Jefferies noted that Polycab is down 17% from the June peak, now trading at 35x one-year forward PE, which is 7% below its historical five-year average. However, key risks to Jefferies’ estimates include higher competition, demand slowdown and sharp copper volatility.

Also read | Wires on fire: Why UltraTech’s Rs 1,800 crore Ultravolt bet wiped out Rs 21,500 crore in 2 days

Polycab share price

Polycab shares have fallen around 7% in a month. The stock saw the sharpest market value erosion earlier this month after UltraTech entered into the wires and cables business. The stock has gained 3% in a week and 9% so far in 2026.

In the longer term, the stock delivered 63% returns over three years and more than 248% in five years.

Advertisement

Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.

Continue Reading

Business

Willamette Valley vineyards director Chris Riccardi buys $6,769 stock

Published

on


Willamette Valley vineyards director Chris Riccardi buys $6,769 stock

Continue Reading

Business

Apple CEO John Ternus Calls Vision Pro ‘the Early Days of a Long Journey’ in New French TV Interview

Published

on

Sydney Fintech

CUPERTINO, Calif. — Apple Chief Executive Officer John Ternus offered his most detailed public defense yet of the company’s Vision Pro headset, describing the mixed-reality device as being in the earliest stages of a much longer technological journey, comparable to the first years of personal computing, in a wide-ranging new television interview.

Speaking on the French program Clique TV, host Mouloud Achour asked Ternus directly to characterize the device’s trajectory: “The Vision Pro: for you is it a test, a flop, or the first step to the future of what’s going to be… a computer?” Ternus responded with an unambiguous vote of confidence in the product’s long-term potential. “Vision Pro to me is an amazing device. It’s an absolutely amazing device,” Ternus said. “But I think of it as like the early days of computers. It is the early days of a long journey. That’s how I feel about Vision Pro.”

Ternus elaborated on that comparison by pointing to the unpredictable ways early personal computers found their footing with users. “What you see, if you think about the early days, people found different reasons where the computer allowed them, the Mac allowed them to do something never before possible,” he said. “Like desktop publishing, and it became a big thing in that industry.” Turning to Vision Pro’s current, more limited adoption, Ternus argued a similar pattern was already emerging. “What you’re seeing with Vision Pro now is, certainly there’s early adopters who love it and they’re using it and they’re enjoying it, but you also, surgeons are starting to use it in surgery because it’s just a fundamentally better tool for them than a monitor that’s kind of sitting over here.”

The comments carry particular weight given Ternus’s own reported history with the Vision Pro project. In September, Bloomberg’s Mark Gurman reported that Apple had laid off more than 100 employees working on the headset, with Ternus, then still incoming CEO, reportedly moving to put the product category “on ice.” Gurman’s reporting at the time indicated Ternus had been skeptical of the Vision Pro project from its inception, viewing the device as too bulky and too expensive for mainstream adoption. Even amid those cuts to Apple’s Vision Products Group, employees were reportedly told that the Vision Pro hardware and its visionOS operating system were not being discontinued altogether.

Advertisement

Against that backdrop, Ternus’s enthusiastic framing of the device in the Clique TV interview suggests a more optimistic public posture than his earlier reported private skepticism, even as he stopped short of committing to any specific future roadmap or timeline for the product during the interview.

Beyond Vision Pro, Ternus used the interview to address broader questions about his leadership style following his formal transition into Apple’s top job on September 1, succeeding Tim Cook, who moved into the role of executive chairman after leading the company for roughly 15 years. Asked what difference it makes that Apple’s new chief executive is an engineer by training, in contrast to Cook, who was widely known during his tenure as an operations specialist rather than what some described as a “product person,” Ternus downplayed the idea that his background signals any fundamental shift in direction for the company. “I don’t think anything’s really changed,” he said. “I think, sure, I’m new in this job, but the focus on innovation, the focus on products, the focus most importantly on our customers, that has never changed, that’s been here from the beginning.” He went on to describe his own motivation for staying at Apple across his lengthy tenure with the company. “I am super passionate about products, I love building things, that’s why I’ve been here for so long and that’s why I love what I do,” Ternus said. “I don’t think of it as some radical change, I just couldn’t be more excited about the future.”

Ternus, 50, joined Apple’s product design team in 2001, beginning his career at the company working on external Mac monitors before rising through the ranks of Apple’s hardware engineering organization over more than two decades. Before joining Apple, he spent four years at Virtual Research Systems, a company involved in the earlier wave of virtual reality headset development during the 1980s and 1990s, an experience that gave him early exposure to display technology and human-computer interface design that would later prove directly relevant to his oversight of the Vision Pro’s development. Ternus graduated from the University of Pennsylvania in 1997 with a degree in mechanical engineering, where he was also a standout competitive swimmer, earning recognition as an all-time letter winner for the university’s varsity swim team.

At 50 years old, Ternus is roughly the same age Cook was when he first became Apple’s chief executive officer in 2011, a similarity that some analysts have pointed to as a factor the company’s board may have weighed favorably when considering the length of leadership stability a younger successor could offer relative to an older candidate.

Advertisement

With Vision Pro continuing to find a foothold in specialized professional applications, including surgical settings and film production, even as broader consumer adoption remains limited, Ternus’s comments in the Clique TV interview signal that Apple’s newest chief executive intends to keep investing in the spatial computing category over the long term, even if, as he suggested, that particular journey remains only in its earliest stages.

Continue Reading

Business

Micron Shares Climb 3.33% to $1,078.75 as AI Memory Rally Builds Toward Its Sept. 30 Fiscal Earnings

Published

on

Earnings News: Micron Technology Inc (NASDAQ: MU)

BOISE, Idaho — Shares of Micron Technology Inc. rose 3.33% to $1,078.75 in Tuesday trading, adding $34.79, extending a powerful rally in the memory chipmaker’s stock as investor enthusiasm for artificial intelligence-driven memory demand continues building heading into the company’s fiscal fourth-quarter earnings report next week.

Tuesday’s gain follows a strong session Monday, when Micron shares closed at $1,043.96, up 2.77%, outpacing a broader 2.26% advance in the Nasdaq Composite that same day. The stock has now climbed more than 256% since the start of the year, according to recent market data, a run that has pushed Micron’s market capitalization above $1.15 trillion and left shares trading within striking distance of the company’s all-time high of $1,255, reached on June 25.

The rally has been fueled largely by surging demand for high-bandwidth memory, or HBM, chips used in artificial intelligence accelerators, a dynamic that has lifted memory chipmakers broadly across global markets in recent weeks. Micron has continued expanding its AI memory story beyond HBM specifically in recent sessions, with the company adding new details to its broader artificial intelligence narrative in a disclosure made September 15, according to market commentary tracking the stock.

Investors are now turning their attention to Micron’s upcoming fiscal fourth-quarter results, scheduled for release September 30 after the close of U.S. markets, with a conference call set to follow at 2 p.m. Mountain time. Analysts currently expect the company to report revenue of approximately $50.42 billion for the quarter, alongside earnings per share of roughly $31.14. Options traders have priced in a potential move of more than 10% in Micron shares around the earnings release, reflecting the high level of uncertainty and anticipation surrounding the report. The results would follow a blowout fiscal third quarter, in which Micron reported earnings of $8.54 billion, an increase of nearly 998% from the prior year, underscoring the scale of the company’s recent earnings acceleration tied to AI-driven memory demand.

Advertisement

Wall Street has grown increasingly bullish on Micron’s stock as that demand story has played out. Stifel analyst Brian Chin maintained a Buy rating on the shares Monday, keeping a price target of $1,500, implying further potential upside even after the stock’s dramatic run this year. Across the broader analyst community, Micron carries an average rating of Strong Buy from 49 analysts, with individual price targets ranging as high as $2,000, according to recent compiled estimates. Not every signal facing the stock has been unambiguously positive, however; some investors have flagged Chief Executive Officer Sanjay Mehrotra’s recent sales of company stock as a data point worth monitoring, even though such sales are common among executives at companies whose share prices have appreciated substantially.

A potential competitive challenge has also emerged in recent days. China’s ChangXin Memory Technologies, known as CXMT, moved its fifth-generation DRAM platform into mass production on September 15, a development that market watchers have said poses a new test for both Micron and rival memory maker SanDisk, given that the assumption of limited near-term competition has been a key pillar underpinning bullish valuations across the memory chip sector.

Micron’s business today centers on dynamic random access memory, or DRAM, chips, which represent the company’s primary revenue stream, alongside a smaller but growing business in NAND flash storage chips. The company, founded in 1978 and headquartered in Boise, Idaho, serves a broad range of end markets, including data centers, personal computers, graphics processing, networking equipment, automotive systems, industrial applications, and smartphones and other mobile devices. Micron sells its products through a combination of its own direct sales force, independent sales representatives, distributors and retailers, alongside a web-based direct sales channel and additional distribution partnerships.

The company has continued investing heavily in expanding its domestic manufacturing footprint in recent months, including selecting construction firm Bechtel as its partner for a major new semiconductor manufacturing project in New York, alongside a separate manufacturing expansion underway in Virginia, both part of a broader push toward what the company has described as made-in-America memory production. Micron also disclosed a strategic agreement with AI company Anthropic in June aimed at scaling next-generation AI infrastructure, reflecting the deepening ties between memory chip suppliers and the major AI labs driving demand for their products.

Advertisement

Micron’s rapid share price appreciation has also fueled speculation about a potential stock split, with the shares now trading well above the $1,000 mark, a level that can create practical friction for retail investors seeking to purchase full shares. The company has not confirmed any specific plans regarding a split as of the most recent reporting.

With Micron’s fiscal fourth-quarter results now just over a week away and options markets pricing in a potentially sharp reaction in either direction, investors are likely to treat the upcoming earnings report as a critical test of whether the company’s extraordinary run this year can be sustained, particularly as the market weighs both the continued strength of AI-driven memory demand and the emerging competitive threat posed by Chinese memory producers entering more advanced stages of DRAM production.

Continue Reading

Business

Idea that firms move out Wales after being acquired is for the birds

Published

on

Business Live

Gambit Corporate Finance has assessed the acquisition of more than 2,000 Welsh firms from 2000 to 2025.

Gambit Corporate Finance was published a new report of Welsh business exit deals from 2000-25.(Image: Western Mail and Echo Copyright)

The vast majority of firms acquired in Wales over the last 26 years remain operating here, countering a narrative that ownership exits can lead to significant extraction with businesses being hollowed out or moved elsewhere.

A new in-depth analysis by Cardiff-based boutique corporate advisory firm Gambit, based on more than 2,000 exit deals in Wales from 2000 to 2025, shows that following a change of ownership, more than 90% of firms remain actively trading in Wales.

Advertisement

The most popular route to exiting over the period was via a trade sale, with 74% of shareholders choosing this transfer of ownership option. The second most popular exit route was via a management buyout (MBO) or management buy-in (MBI), which accounted for 21% of the deals surveyed. Notable MBO/MBI exits were the MBO of Pembrokeshire holiday resort Bluestone Resort in 2013 for £87m and the MBO of Flintshire-based supermarket chain Iceland in 2020 for £115m.

There were 29 deals with a value of more than £100m. The highest, at £3bn, involved the sale of the assets of what was the listed utilities group Hyder.

During the 26-year period, South East Wales accounted for 61% of all Welsh exits, South West Wales 22% and North Wales 17%.

There were 34 flotations during the period, with the largest IPO (initial public offering) being Admiral’s £368m flotation in 2004.

Advertisement

During 2000-2011, 55% of exits involved businesses that were less than 10 years old. This dropped to 38% between 2012 and 2025. Gambit said this was symptomatic of the lack of available liquidity during a prolonged recession and market uncertainty around Brexit.

At 57, the average shareholder age at exit has been rising over the past decade. This may be an indication that external factors, such as Covid-19, have delayed owners from transferring their businesses.

Frank Holmes

Frank Holmes of Gambit.

On the figure that more than 90% of firms have remained active in Wales post change of ownership, founder partner of Gambit, Frank Holmes, said: “It’s a myth we can finally put to bed. There’s a persistent assumption in Wales that when a local business is bought, it gets hollowed out: the business relocates, the jobs go.

“We individually checked what actually happened to over 2,000 exits across 26 years. Around 90% of genuinely Welsh companies that were acquired are still active and trading in Wales today. Change of ownership isn’t the threat people assume it to be, particularly for buyouts and IPOs.”

Advertisement

The research shows that exit activity in the second half of the period – 2013 to 2025 – comfortably outpaces the first half, with 1,251 exits against 843, representing an average of 96 exit deals a year versus 65.

Mr Holmes said: “Whichever way you cut it, the Welsh market has been getting busier, not quieter. A catalyst for the spike can be attributed to the October 2024 Budget. Capital Gains Tax (CGT) rose immediately on its announcement and continued in 2025 and 2026.

“That’s a strong incentive to complete a sale before a deadline, and we know from our own activity it pulled a good deal of transactions forward into 2024 that might otherwise have been executed a year or two later.

“However, it was also four years post-Covid, which allowed companies to regain financial performance and improve valuations, thereby demonstrating the sustainable profitability necessary for exit, fortuitously in a strong, liquid market.”

Advertisement

The research shows that 50 firms were acquired by employee ownership trusts (EOTs) – a structure that did provide 100% CGT relief for sellers. The EOT exit route could well have peaked.

Mr Holmes said: “The maturation of the employee ownership trust option became increasingly favoured for predominantly people-services companies, with over 50 transactions in the period.

“This option benefited from the 100% CGT allowance or nil-rate tax incentive, since halved, which was compelling for owners but often funded with revolving debt structures, compromising growth potential. The jury is out on the sustainability of some of these businesses, as some notable failures have already emerged.”

On business owners considering an exit, or a partial one, Mr Holmes said: “Selling up should not be viewed as being a threat to their legacy and the economic wellbeing of their employees and other stakeholders, as it’s sometimes made out to be. It is an important factor in the lifecycle of a business, often left unaddressed and best approached in a planned fashion.

Advertisement

“An ageing generation of owners is going to drive a lot of succession decisions over the next few years.

“Those businesses which have a succession plan will be the ones that make themselves genuinely investable, by adopting tech and innovation-led strategies, cultivating credible management, thereby creating capacity to grow and understanding the optimum routes for exit, well before making a decision to embark on a transaction process.”
Continue Reading

Business

Skyscrapers and ‘Manchesterism’: City divided over latest towers

Published

on

Business Live

Special report after Renaker gets permission for five more high-rises

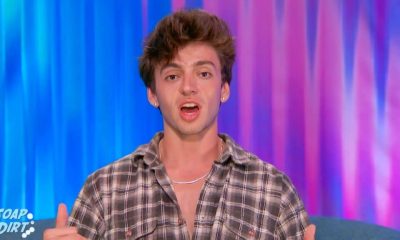
Images from Plot D, a new project in for planning which will become Manchester's tallest building once complete

An early CGI for Plot D, the new project from Renaker (Image: Renaker/SimpsonHaugh)

They’re the towers that changed Manchester forever.

Advertisement

Skyscrapers have reshaped the city’s skyline in recent years, standing tall over the bustling centre below.

They’ve created thousands of homes and brought new people to Manchester, boosting businesses and keeping the city centre busy.

Some say it’s a sign of how Manchester is booming, but others have questioned how the city has gained more luxury apartments while 20,000 households face lengthy waits for more social housing.

This month decision notices were issued to property giant Renaker to build five new high-rise buildings in the city centre.

Advertisement

More than 2,300 flats will be built in a move which could ‘define what the city looks like for future generations’, after planning permission was first granted in 2024.

Based on Great Jackson Street near Deansgate, the largest tower, called Plot D, will be 71 storeys tall at 213 metres (698 ft), with another four buildings based in the same area on land known as Plot C And Plot E, two at 47 storeys and two at 51 storeys.

The schemes include no on-site affordable homes, which are properties priced below market rates.

In Manchester’s council chamber, concerns are growing from opposition members about the future of the city.

Advertisement

“So this is Manchesterism – developers get richer, homes get more expensive and Mancunians only get more shiny glass to clean,” the city council’s Reform UK group said in a statement.

“One PM and a mayor later, the sleeping Renaker giant awakes to throw up another 2,300 luxury flats at Great Jackson Street. Zero affordable housing included despite the whole developer fortune being built on taxpayers money.”
Responding to the comments, a Manchester City Council spokesperson pointed out that ‘viability margins are incredibly tight’ in the city, and that development at this scale ‘remains incredibly challenging and risky’.

Manchester’s Reform UK group is led by Councillor Sian Astley, of the Baguley ward. She was a recent hopeful in the Greater Manchester mayoral election against Bev Craig, and said if she had won one of her key goals was to ‘open the books on contracts Andy Burnham awarded during his time as Labour’s mayor’.

Advertisement

A section 106 agreement made by Manchester City Council when approving the new Renaker towers means there is a so-called ‘clawback’ mechanism which could put money in the council’s pocket, capped at £33m for the 71-storey tower, and £81m for the other four towers.

The council expects to get some money back from the deal, but how much is still unknown at the moment.

When the schemes are at 75 per cent construction completion, a test is planned over how profitable the development could be. At that point it would become clearer if any of the section 106 money could be paid to the council

Part of that formula also depends on how the homes are sold. Properties for open market sale need to hit a 20 per cent profit from their initial outlay before the section 106 agreement kicks in, while for build-to-rent apartments the profitability margin is lower at 12pc.

Advertisement

Manchester’s Reform UK group added in its statement: “A section 106 agreement suggests Renaker could deliver £114m across two schemes, The Green and The Lighthouse, for future affordable housing for Mancunians, but in reality never will, because that magical 20 per cent developer profit will not happen.

Contour And Plot D, seen in planning documents.

Contour And Plot D, seen in planning documents from developer Renaker(Image: Renaker )

“Not when the developer and the builder are the same company working out their own figures, not when the council’s own valuer Savills‘ figures show it’s currently unattainable and not when it’s up to MCC to prove the profit.”

Renaker was approached for comment but has not yet responded.

A look at previous Renaker planning applications shows the company has made contributions to the city, if not through on-site affordable homes.

Advertisement

It includes contributions towards a primary school, Crown Street School, and NHS medical centre at Elizabeth Tower, as well as off-site affordable housing contributions which supported the restoration of listed buildings at Westwood Cottages in Moss Side and the Ancoats Dispensary in Ancoats and Beswick, which helped deliver affordable homes at the Manchester Living Rent.

But concerns remain about the lack of on-site affordable properties in Manchester’s skyscrapers.

Green Party Councillor, Sarah Wakefield, from the Deansgate ward, said: “Manchester has a housing crisis, it’s the biggest issue impacting our residents across the city. In Deansgate affordability, facilities for families and lack of climate adaptation in new towers built are concerns raised regularly.

“With over 15,000 families on Manchester’s housing waiting list, many having to wait nearly a decade for a home, but the council has approved almost 2,300 flats and not one of them is affordable.

Advertisement

“Unfortunately, this isn’t a one off, but a pattern when it comes to Renaker, which has now delivered thousands of homes across Manchester backed by GMCA [Greater Manchester Combined Authority] loans, without a single affordable one among them. You can’t call housing a priority and allow developers to dictate Manchester’s strategy on affordable housing.”

The five new Renaker towers are not using any public loans from the Greater Manchester Combined Authority (GMCA), but previous developments have.

The firm has also been criticised by property rivals in Manchester over its affordable housing record. One of those critics is landowner Aubrey Weis.

A Weis Group spokesman said: “The council continues to bend over backwards to ensure this developer makes no affordable housing contributions.

Advertisement
The existing towers at Deansgate Square, Manchester

The existing towers at Deansgate Square, Manchester(Image: Sean Hansford | Manchester Evening News)

“Having now accepted that public realm costs should not be used to offset affordable housing obligations, there are serious questions about why this scheme is still making no contribution at all, and whether previous schemes should have been required to contribute more.

“Especially as some of those schemes were presented to the GMCA as highly profitable in order to access public money.”

The Weis Group has previously taken the Greater Manchester Combined Authority (GMCA) to court over loans it gave to Renaker.

One of the most well-known examples was a GMCA decision in 2024 to lend £140m towards so-called special purpose vehicles by Renaker founder Daren Whitaker.

Advertisement

This decision has been at the heart of a legal battle between the GMCA and Mr Weis.

The Weis Group lodged a ‘permission to appeal application’ in August to the Supreme Court against the GMCA over these loans, following previous hearings in the Competition Appeal Tribunal and the Court of Appeal.

It could see the matter end up being heard in the UK’s highest court.

A GMCA spokesperson said of the appeal: “Both the Competition Appeal Tribunal and the Court of Appeal have heard this case, and on both occasions they found that these loans were given on commercial terms.

Advertisement

“We do not believe this appeal has any merit and have submitted our response to the Supreme Court.”

A Weis Group spokesperson said: “We’re hoping the Supreme Court will consider how the GMCA can lawfully lend taxpayer money to schemes considered unviable by their own developer without engaging the subsidy control act.”

What Manchester City Council said about the new Renaker skyscrapers

A Manchester City Council spokesperson said: “Our planning committee resolved to grant the planning permission for these schemes two years ago to deliver nearly 2,400 homes, which represents a substantial investment from the developer in our city and will contribute to helping us meet our ambitious housing strategy targets in the coming years.

Advertisement

“And we have been able to secure a s106 agreement against these schemes that would see significant affordable housing investment across the city subject to further viability testing during construction.

“While Manchester has enjoyed major growth in the last decade, particularly in our city centre where the population now exceeds 100,000 people, development remains incredibly challenging and risky – and this is ever more so for development at this scale.

Manchester Town Hall ahead of its spring 2027 completion date

Manchester Town Hall ahead of its spring 2027 completion date(Image: Jason Roberts / Manchester Evening News)

“Viability margins are incredibly tight in Manchester and that means slimmer profit margins for investors too. Manchester City Council also demand a lot from developers who invest in our city and to build here comes at a premium. We expect high-quality developments with exemplary public realm space, alongside other impactful contributions – and at a time when inflationary pressures in the construction sector means many schemes are unviable here and across the UK.

“The viability of all schemes and whether they can contribute to affordable housing is tested robustly through the planning process and is independently assessed. However, although s106 through the planning process is one route of building affordable housing, it is limited in the current economic climate, and it represents only a small portion of affordable housing built across the country. The most impactful way of building affordable housing is to build at scale using national funding to meet demand, while repurposing the brownfield land that is available to us.

Advertisement

“We’ve made a clear commitment to increasing the number of social rent, Council and genuinely affordable homes available to Manchester people and we’ve just seen another record year for affordable completions where half were for social rent. 2,500 affordable homes have been built since 2022 and with a strong pipeline of future projects, we are on track to meet and exceed our target to build at least 10,000 by 2032.”

Continue Reading

Trending

Copyright © 2025