
Crypto World
Charles Schwab's Sonders Favors Commodities Over Equities, But Not for All


Charles Schwab is holding a neutral stance on equities. The firm favors commodities over stocks and bonds, according to chief investment strategist Liz Ann Sonders.
Sonders made the comments in a recent interview, pushing back on what she called “cookie-cutter” portfolio advice. She said allocation should hinge on each investor’s time horizon, risk tolerance, need for income, and overall goals.
No Universal Portfolio
“It actually drives me a little crazy when people give a cookie-cutter answer to that,” Sonders said. “There’s no one asset allocation that makes sense right now.”
Schwab oversees $13.4 trillion in client assets, and Sonders pointed to that scale as proof there is no single right answer for every client.
She was responding to a question about the classic 60/40 portfolio, a benchmark mix of 60% stocks and 40% bonds. Other strategists have proposed carving out a bigger slice for commodities instead.
Favoring Commodities Over Bonds
Sonders said Schwab is less favorable on fixed income. The firm is more favorable on commodities, a stance that echoes a broader shift away from the traditional 60/40 mix.
“We’re neutral on equities, which is not a bearish position,” she added. It simply reflects Schwab’s long-term strategic allocation, not a call to sell stocks.
Gold-backed funds pulled in $18 billion in August alone. That was the second-biggest monthly inflow on record, lifting total holdings to an all-time high.
The figure comes from the World Gold Council, an industry group that tracks global gold demand, cited in a related gold ETF surge report.
One specific split floated by other strategists calls for a 60/20/20 mix, with a fifth of the portfolio in commodities. Sonders declined to endorse any fixed ratio.
However, she said the right percentages depend on each investor’s goals, time horizon, and income needs. The interviewer added that age and investor profile matter just as much.
The debate over stock-bond diversification is far from settled. Whether Schwab’s tilt toward commodities proves prescient may depend on the current cycle for gold and other real assets. That cycle will keep playing out in the months ahead.
The post Charles Schwab's Sonders Favors Commodities Over Equities, But Not for All appeared first on BeInCrypto.

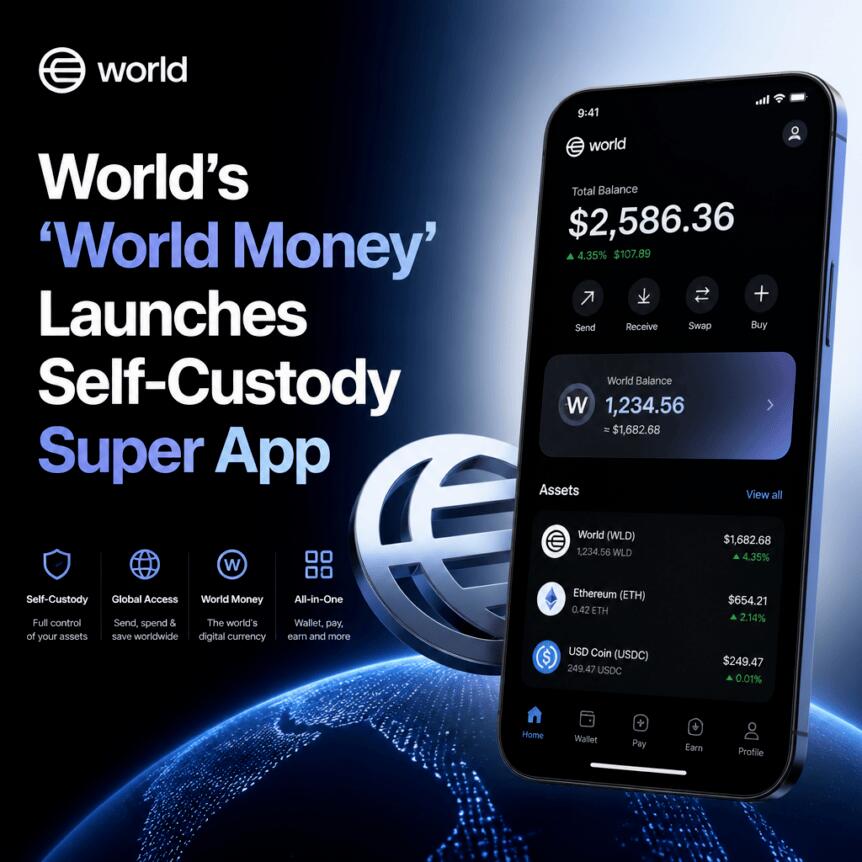
World has launched World Money, a new self-custody financial “super app” designed to bring stablecoin payments and digital-asset features into one place. The rollout began Thursday across more than 150 countries, though specific capabilities are expected to vary by region, according to World.
The new app supports sending supported digital assets—including stablecoins—to recipients using a World username. It also allows users to deposit eligible assets to earn rewards and to buy and sell digital assets through exchange integrations. World further says the experience is built around its identity layer while giving users direct control of their funds.
Key takeaways
- World Money rolls out in over 150 countries, with feature availability dependent on location.
- Users can send supported assets (including stablecoins) via World usernames, not just blockchain addresses.
- The app adds third-party “Mini Apps” such as Kalshi, Credit and Morpho.
- A partnership with Stripe enables top-ups and stablecoin purchases with Apple Pay for users in the US.
- World splits its identity and financial functions across two apps: World ID App and World Money.
What World Money includes at launch
World positions World Money as a self-custody super app that combines multiple financial functions: transfers, trading access, and rewards on certain deposits. The company says users can send supported digital assets to a recipient’s World username, with stablecoins among the assets initially covered.
In addition to peer-to-peer transfers, World Money includes a rewards component. Users can deposit eligible assets to earn rewards, a feature that continues the direction World App previously took with earning opportunities tied to blockchain assets.
For trading, World Money provides buy-and-sell functionality through exchange integrations, giving users a way to switch between supported digital assets without leaving the app environment.
“Mini Apps” and payments onboarding through Stripe
One of the most visible expansions is World Money’s support for third-party mini applications. World says users can access Mini Apps including Kalshi, Credit and Morpho. This approach mirrors the super-app idea of bundling specialized services into a single interface, while relying on external platforms for specific product functions.
World also highlighted a payments onboarding partnership. According to the company, integration with Stripe allows users to fund their accounts and buy stablecoins with Apple Pay, starting with users in the United States. That matters for adoption because fiat-to-stablecoin entry points remain one of the biggest friction points for users who do not already hold crypto.
World did not describe whether Apple Pay support will expand beyond the US as part of this initial rollout, so users outside the US should expect different funding options depending on local availability.
How World is reorganizing its product stack
The launch is also a structural change. World says that with World Money, its identity and financial services are now separated into two dedicated apps: World ID App for identity verification and credentials, and World Money for the wallet, payments and other financial features.
Existing users of World App and World ID App can reportedly use their existing accounts for World Money, which should reduce the migration burden for current customers and limit the risk of fragmenting user identities and balances across platforms.
World Money is operated by Tools for Humanity, the company co-founded by Sam Altman and Alex Blania that builds technology for the World network. Tools for Humanity’s involvement aligns with World’s broader push to connect identity to financial actions rather than treating payments as a standalone feature.
From World App to a two-app super app model
World’s move comes after more than a year of incremental expansion of World App. World App originally launched in May 2023, bringing together World ID with a crypto wallet, stablecoin transfers and token trading.
In October 2024, World introduced World App 3.0, describing it as a “super app for humans” and adding third-party Mini Apps plus a Vault feature for earning on assets. That indicates World has been testing the combination of identity, custody tooling and app-level distribution of third-party services before splitting the experience into two apps.
Later, World also experimented with traditional banking rails. In November 2025, it piloted virtual bank accounts in the US, and then expanded the idea a month later. World says those accounts can support paychecks and bank deposits that are converted into USDC, illustrating an intent to reduce the steps between payroll and stablecoin holdings.
With World Money now separated from the identity layer, the ecosystem looks to be evolving from a single “do everything” client into a clearer division: credentials and verification in one app, and financial activity in another.
Why the split and rollout matter for users
For everyday users, the most practical change is likely the user experience: sending assets through a World username, accessing third-party services through Mini Apps, and using mainstream payment rails like Apple Pay via Stripe. Those elements can make crypto interaction feel less like dealing with addresses and more like using familiar app flows—especially when the stablecoin payment layer is integrated directly into the wallet experience.
For investors and builders, the strategic question is whether World can maintain trust and usability while expanding self-custody financial features across geographies. The company’s decision to run identity and financial services through separate apps may help scale compliance, product development and onboarding workflows without forcing users to navigate unrelated functionality in a single interface.
As World Money becomes available in more countries, the next watch item is how quickly Stripe-based onboarding expands beyond the US and how feature availability differs by region. Users should also pay attention to which assets are considered eligible for rewards and how the lineup of Mini Apps evolves after launch.
CNBC’s Jim Cramer compared stock sector performance across the last three Federal Reserve rate-hike cycles, highlighting how the winners have shifted over time.
The comparison comes after the Fed raised rates in September 2026 for the first time since 2023, citing persistent inflation, a resilient labor market, and oil prices pushed higher by the Middle East conflict.
How Sectors Performed After the First Hike
Cramer, host of Mad Money, examined three stretches within the Fed’s December 2015 to December 2018 tightening cycle. In the three months after that first hike, defensive sectors led the market.
Utilities, consumer staples, and real estate ranked among the strongest performers, Cramer said. Communication services technically topped the group, though Cramer called that figure misleading.
The sector did not exist under that name until late 2018, so the result actually reflects its predecessor, telecommunications, which investors treated as a safety trade at the time.
The Cycle’s Middle and Final Stretch
Looking at the roughly one year between the Fed’s first and second hikes, the picture flipped. Energy topped the list, and materials also performed well, while healthcare, real estate, and staples ranked among the worst performers.
Financials and industrials were also among the best performers in that stretch, Cramer said, since inflation stayed tame and recession fears were minimal at the time.
Over the full three-year period, information technology became the dominant sector. Consumer discretionary and financials also outperformed, echoing a similar cyclicals and financials rally strategists are floating today, while communication services, staples, energy, and materials slid toward the bottom as the Fed grew more aggressive.
“Of course, every tightening cycle is different.”
Cramer, CNBC’s Mad Money
Cramer said the current cycle carries a twist the 2015 to 2018 period did not have. War-driven oil prices, rather than broad economic demand, are adding pressure behind the Fed’s latest rate hike.
He added that further tightening could stall if oil slides back toward $80 a barrel, easing that pressure.
Whether defensive sectors repeat their early lead from a decade ago may depend on how quickly that geopolitical shock fades.
The post Jim Cramer Ranks Winning and Losing Stock Sectors During Fed Rate Hikes appeared first on BeInCrypto.
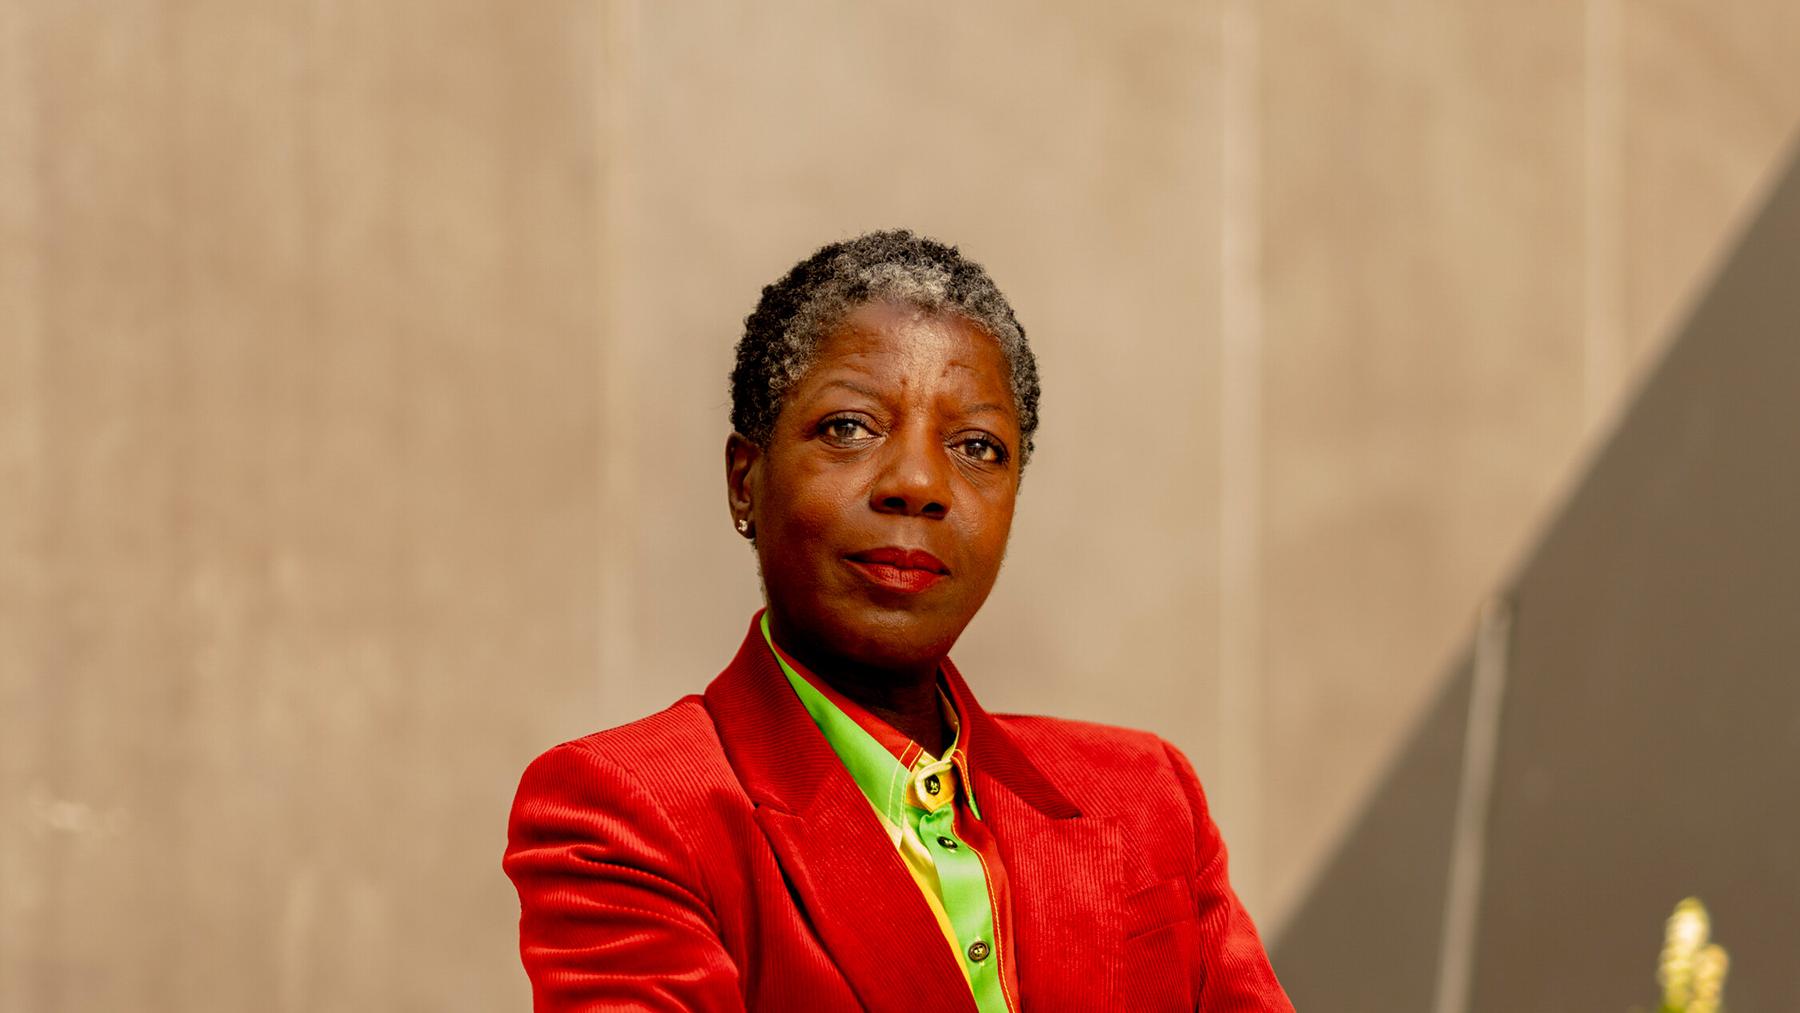
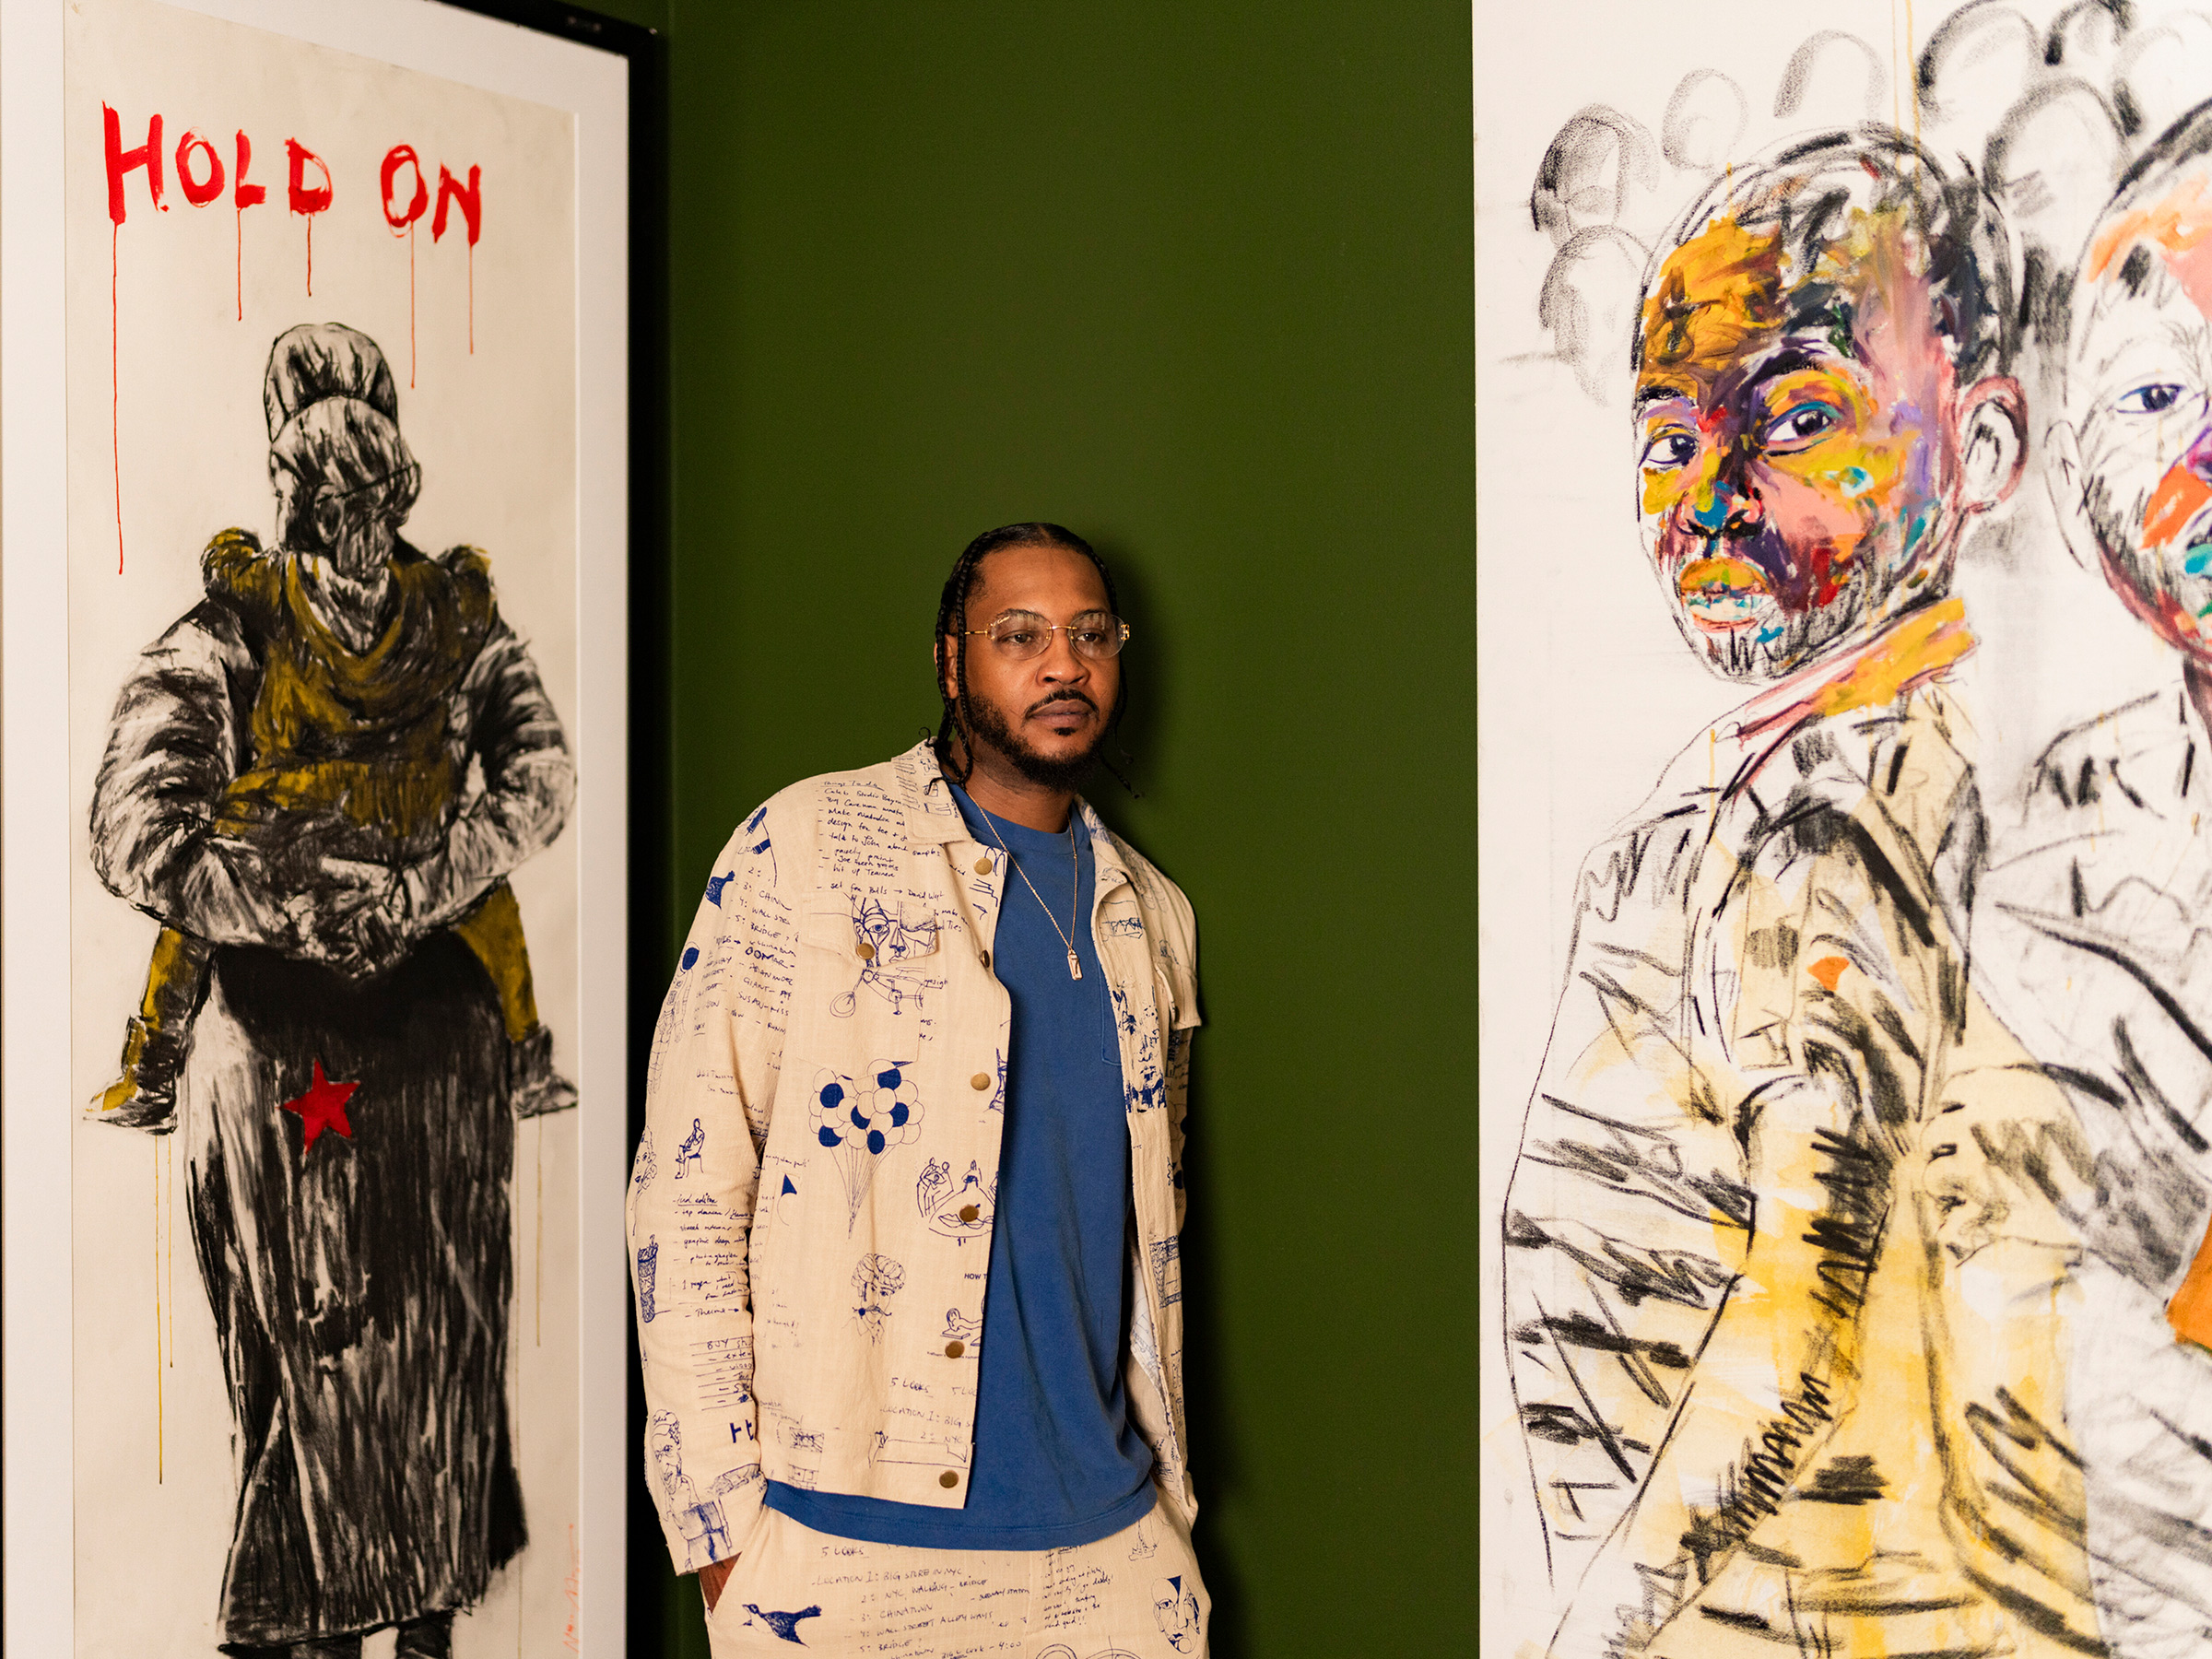
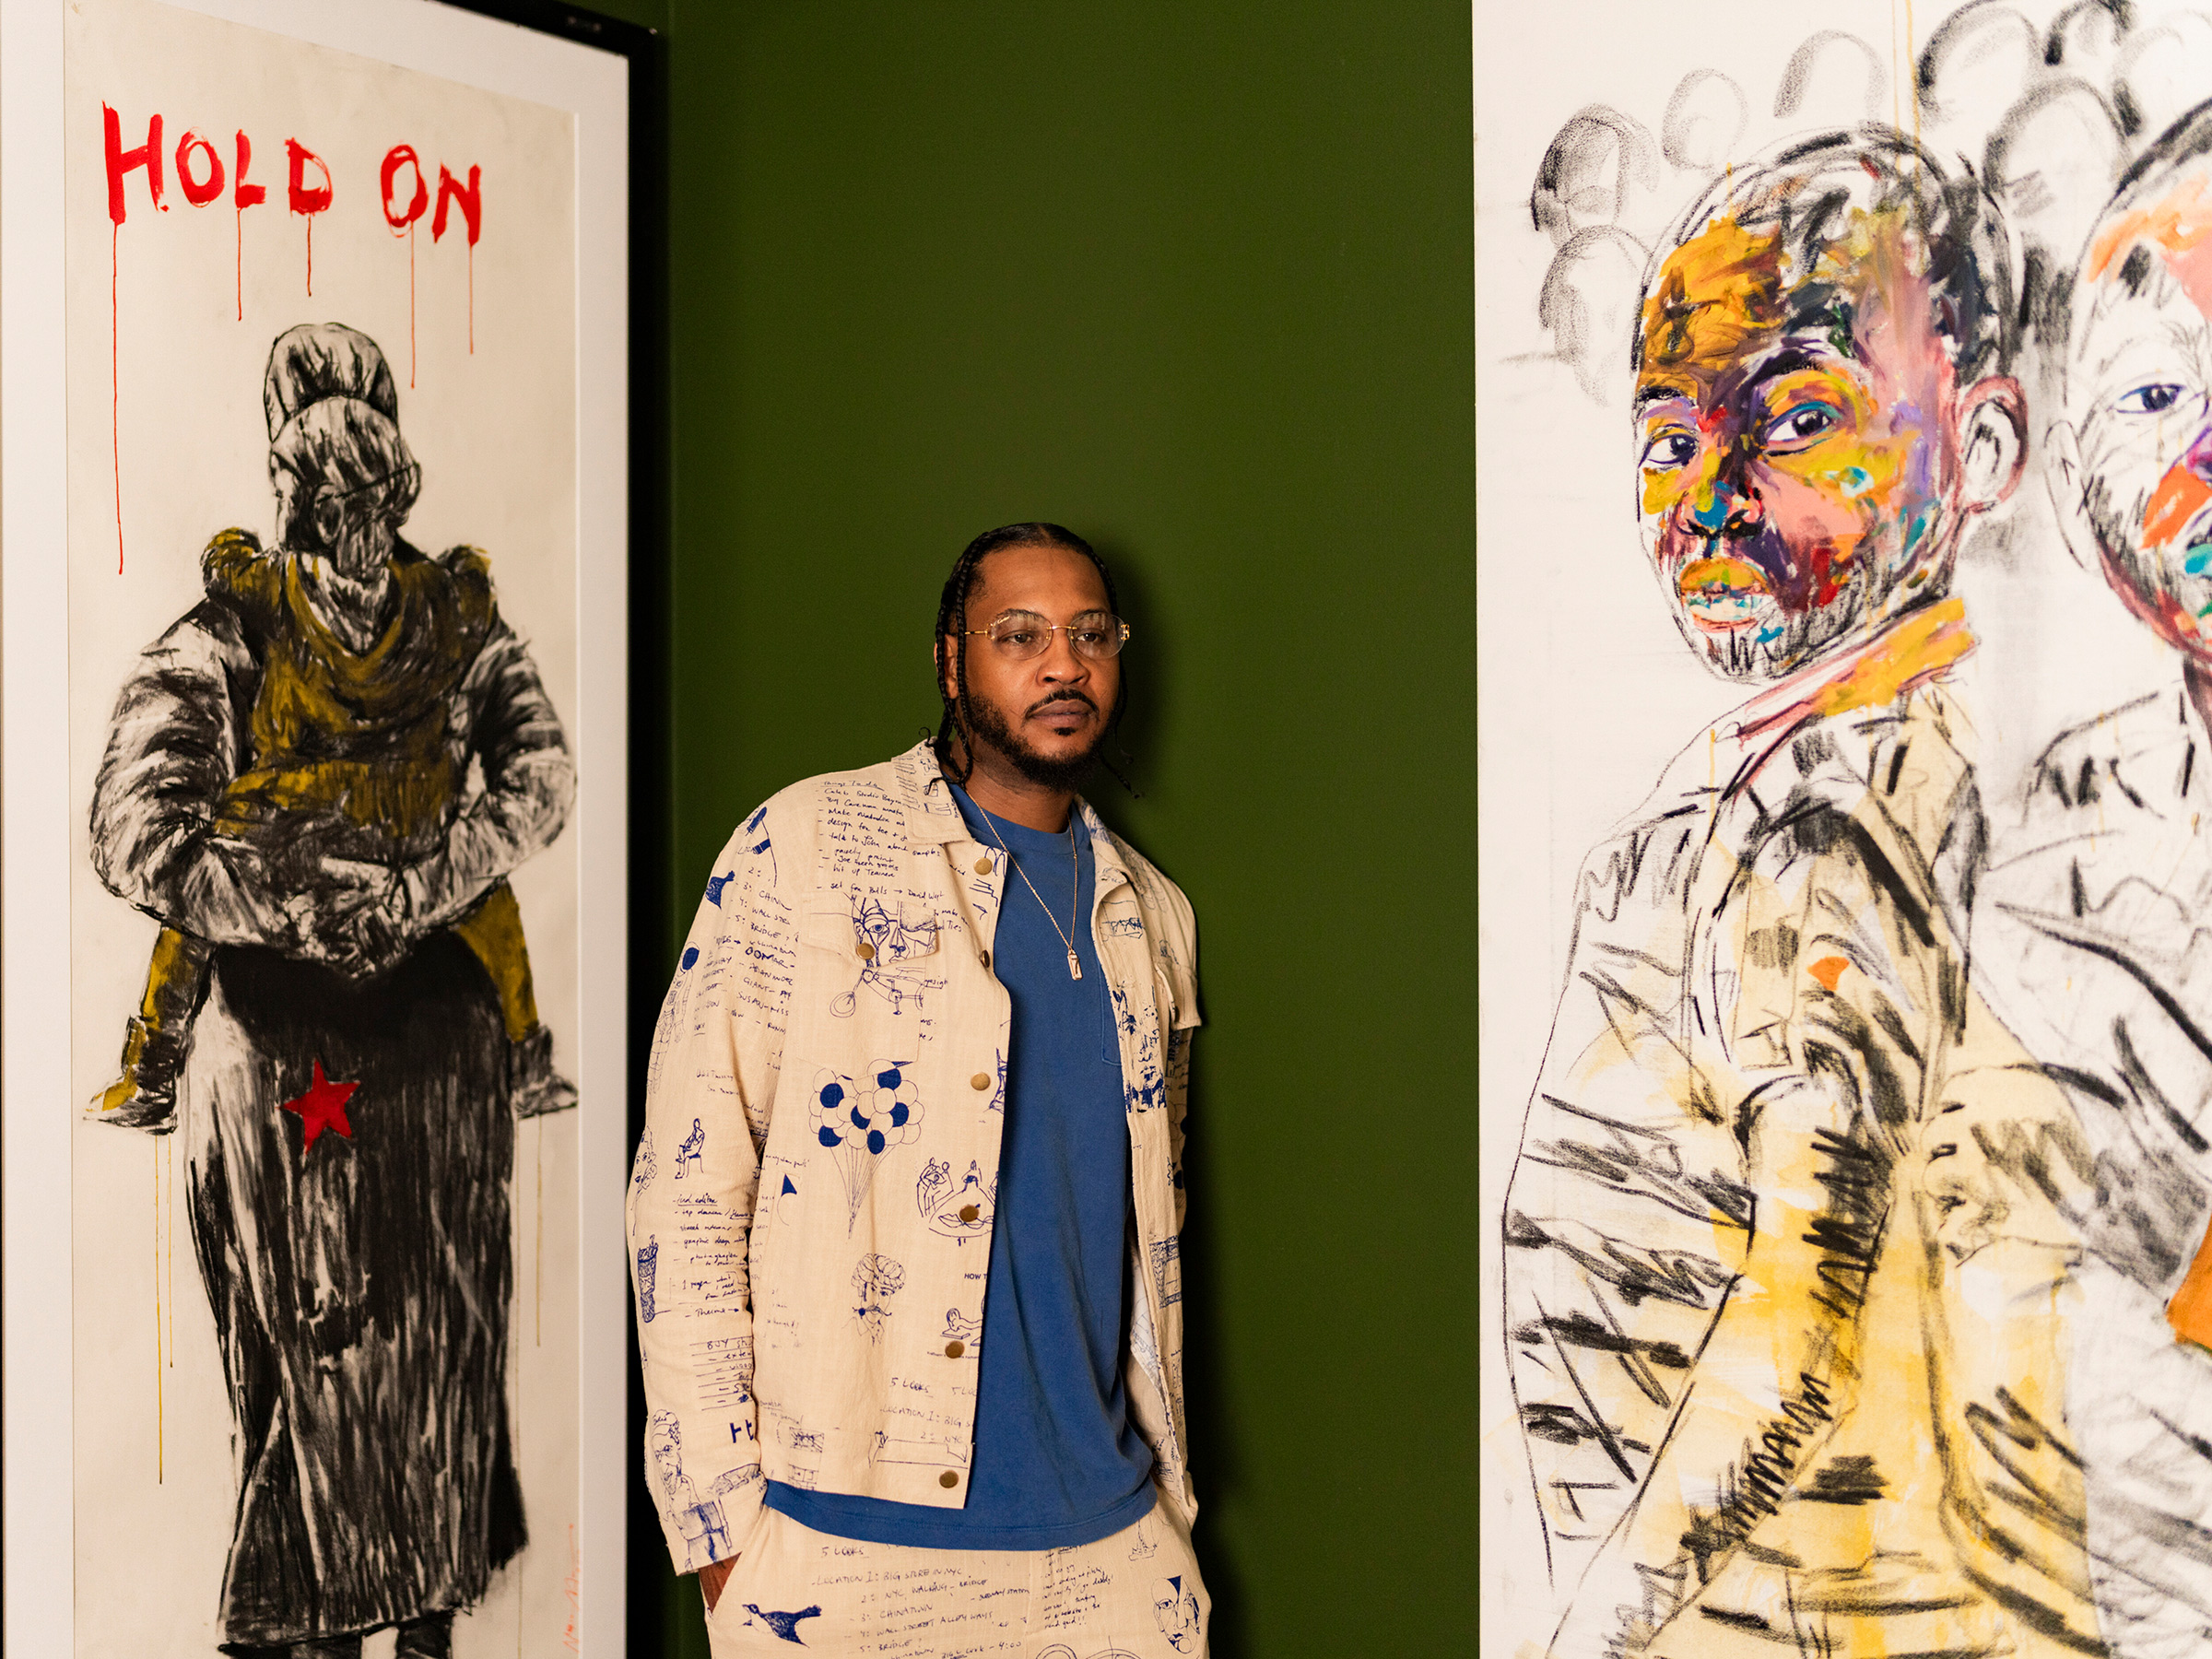
Thelma Golden has arguably done more than anyone else to promote Black artists in the U.S. For over two decades, the director and chief curator of the Studio Museum in Harlem, founded in 1968, has forged the institution into a leading incubator and showcase for artists of African descent. And in November 2025, she made a permanent mark on New York City’s cultural landscape when the Studio Museum opened its $160 million new building on 125th Street. The 82,000-sq.-ft. facility, which looks like a charcoal-colored Jenga tower, doubled space for exhibitions and created classrooms, artist studios, and meeting spaces for community organizations. Golden started her career in the 1980s as a curator at the Whitney Museum of American Art, where she organized powerful exhibitions about Black masculinity and conceptual art that divided critics, but made her name as a fearless curator. Now, she’s focused on ensuring a long-term future for the institution she’s shaped. Alongside raising money for the new building and attracting patrons including Beyoncé, Golden created a $52 million endowment, ensuring the Studio Museum’s 9,000-work collection will be cared for well into the future.
WisdomTree and MoonPay have announced a Sept. 17 collaboration to build another U.S. access route to the WTGXX tokenized Treasury money market fund while MoonPay plans to use the fund in its stablecoin reserve management.
Summary
- WisdomTree plans MoonPay access to WTGXX for eligible U.S. investors through its regulated broker-dealer network.
- MoonPay plans to use WTGXX as part of its stablecoin reserve management under the collaboration.
- WTGXX invests in cash, short-term Treasuries, Treasury-backed repos, and registered government money market funds exclusively.
- MoonPay says its network includes more than 35 million accounts and over 1,700 partner businesses.
- WisdomTree has already enabled 24/7 trading and instant settlement for WTGXX within U.S. regulatory rules.
WisdomTree said the planned connection will use MoonPay’s blockchain technology and distribution network, which the companies said reaches more than 35 million accounts and over 1,700 partners. MoonPay has not identified a stablecoin that will hold WTGXX reserves, disclosed an allocation amount or given a date when the investor access point will become available.
MoonPay access to WTGXX remains under development
The arrangement is designed to give eligible U.S. investors another route into WTGXX outside WisdomTree’s existing direct channels. Transactions in the regulated fund will still involve WisdomTree Securities, Inc., the broker-dealer that distributes WTGXX.
MoonPay will supply technology and access to its customer network, but WisdomTree states that MoonPay is not acting as a broker-dealer or investment adviser for WTGXX. The distinction keeps the securities activity tied to WisdomTree’s regulated distribution structure.
No launch date appears in the announcement. WisdomTree describes the MoonPay access point as something it “is building,” while the technology is “expected to support” access once the planned integration is ready. Those statements describe future work and do not confirm that retail investors can buy WTGXX through MoonPay today.
Jonathan Steinberg, WisdomTree’s founder and CEO, said the companies want to create another path for eligible U.S. investors to move assets into the fund.
“Working with MoonPay as an access point can give eligible U.S. investors another path to deploy their assets into WTGXX,” Steinberg said. The wording describes the intended product structure, not a completed rollout.
MoonPay says its U.S. regulatory footprint includes a New York BitLicense, a New York Limited Purpose Trust Charter and money transmitter licenses. Its corporate description lists operations across fiat payments, crypto trading, commerce and stablecoin infrastructure.
WTGXX was reworked for stablecoin reserve eligibility
WTGXX is an open-end money market mutual fund registered under the Investment Company Act of 1940. Its investment objective is to generate current income while preserving capital and liquidity and maintaining a stable $1.00 net asset value per share.
The latest SEC-filed prospectus requires the fund to keep at least 99.5% of total assets in government securities, cash and fully collateralized repurchase agreements. Under normal conditions, WTGXX invests exclusively in U.S. dollar cash, short-term Treasury securities, overnight Treasury-backed repos and registered government money market funds.
WisdomTree changed the product’s name and investment policy in November 2025 specifically to address stablecoin reserve use. An SEC-filed notice said the changes were intended to make the fund an eligible investment option for payment stablecoin issuers seeking to comply with the GENIUS Act and related rules.
The current prospectus carries the same language. It says WTGXX invests in a manner intended to satisfy the types of eligible reserve assets permitted for payment stablecoin issuers under the GENIUS Act. That does not mean every stablecoin issuer can automatically use the fund without considering its own regulatory requirements.
At June 30, WTGXX held 80.9% of net assets in U.S. government obligations and 19.3% in repurchase agreements. Treasury bills accounted for 64.1%, while a floating-rate Treasury note represented 16.8%. Its holdings included overnight repos with institutions such as Deutsche Bank.
The fund charges a 0.25% annual expense ratio. Its fiscal-year return through June 30 was 3.75%, compared with 3.90% for the ICE U.S. 1-Month Treasury Bill Index. Past returns do not establish what future WTGXX investors will earn.
WisdomTree already offers WTGXX around-the-clock liquidity
Before the MoonPay agreement, WisdomTree had expanded how investors could move in and out of WTGXX.
In February, the company launched 24/7 secondary trading and instant settlement for WTGXX after receiving SEC exemptive relief. WisdomTree Securities acts as principal in that structure, with eligible transactions settling against USDC outside conventional securities-market hours.
By June, WisdomTree had reduced secondary-market redemption commissions for its Instant Liquidity service to zero basis points. The service operates through WisdomTree Connect and allows qualifying investors to access WTGXX liquidity around the clock.
WTGXX has entered other treasury and blockchain workflows during 2026. WisdomTree reported that Plume and Toku used the fund in a payroll pilot, LotusUSD referenced it within a reserve framework, and Stable Sea made it available for corporate treasury use.
As earlier corporate cash coverage reported, Stable Sea expanded its WisdomTree offering in August to include two more digital funds alongside WTGXX. Eligible businesses place orders through WisdomTree Securities while using Stable Sea’s interface.
The SEC has independently classified WTGXX among the money market funds it identifies as tokenized. The regulator’s April statistics included WTGXX alongside products from Franklin Templeton, Fidelity, Dreyfus and M3Sixty whose ownership records are maintained at least partly through crypto networks.
WTGXX still carries ordinary money market and technology risks. WisdomTree warns that investors can lose money, the $1 share value is not guaranteed, and the fund is neither a bank account nor FDIC-insured. The prospectus separately notes risks connected with blockchain technology, including theft, inaccessibility and regulatory changes.
MoonPay has already connected another tokenized fund
The WisdomTree agreement is not MoonPay’s first connection to a regulated tokenized money market product.
In June, Franklin Templeton connected its BENJI fund with MoonPay Trade for institutional users. As prior MoonPay fund coverage reported, that arrangement allows eligible institutions to exchange stablecoins such as USDC and USDT for tokenized fund shares through MoonPay’s onchain trading infrastructure.
MoonPay Trade was introduced in May as an institutional platform covering tokenized assets, stablecoin liquidity and decentralized finance connections. Earlier institutional platform coverage reported that the service supports functions including tokenized fund subscriptions, collateral transfers and onchain lending.
The WisdomTree collaboration differs in its stated distribution plan because the companies are targeting eligible individual investors in the U.S. through WisdomTree’s broker-dealer structure. MoonPay’s role in WTGXX stablecoin reserve management creates a second part of the relationship beyond investor access.
WisdomTree has described the deal as a possible base for future work covering other tokenized funds and international markets. Caroline D. Pham, CEO of MoonPay Institutional, said the relationship shows how blockchain infrastructure can be used with regulated U.S. investment products.
The companies have not named any additional fund, country or launch schedule for that potential work. Their Sept. 17 announcement similarly does not specify which MoonPay-issued or supported stablecoin would use WTGXX, how much of its reserves could be allocated to the fund, or when those reserve purchases would begin.
XRP Ledger developers have released xrpld version 3.4.0 on Sept. 16, adding two amendment packages that revise proposed native lending functions and harden several transaction paths while asking server operators to upgrade.
Summary
- XRPL version 3.4.0 introduces two amendments covering lending changes plus a bundled protocol-fix package now.
- LendingProtocolV1_1 adds closed-ended vaults and cash-basis accounting, but mainnet activation still requires sustained validator consensus.
- Server operators are urged to upgrade quickly as XRPL Foundation now distributes signed Linux packages.
- fixCleanup3_4_0 hardens vaults, AMMs, MPTs, escrow, signing, credentials, and permissioned trading behavior across transaction paths.
- The new lending amendment depends on XLS-65 and XLS-66, which remain below activation thresholds.
XRPL’s official release says version 3.4.0 introduces LendingProtocolV1_1 and fixCleanup3_4_0, while retiring fixAMMOverflowOffer after its post-amendment behavior became a permanent part of the protocol.
The software release does not mean either new amendment is active on mainnet. XRPL’s amendment process requires a proposal to receive more than 80% support from trusted validators continuously for two weeks before its rules become active.
Lending V1.1 adds closed-ended vaults and cash accounting
XRPL’s 3.4.0 release says LendingProtocolV1_1 changes the design of Single Asset Vaults and the Lending Protocol by introducing closed-ended vaults with defined subscription, investment and redemption periods.
Ripple’s technical documentation says depositors can add or withdraw assets during the subscription phase. During the investment period, deposits and withdrawals stop while assets can fund loans. Redemption begins once the investment period ends, allowing depositors to recover their share after loans mature.
Once LendingProtocolV1_1 becomes active, XRPL’s documentation says new loan brokers can only be attached to closed-ended vaults. Existing loan relationships created under earlier rules receive separate handling so outstanding positions can continue to be managed.
The accounting model changes at the same time. Ripple’s documentation says new vaults would recognize interest only when borrowers actually make payments.
Under the earlier model, all scheduled interest was recognized when a loan originated. Cash-basis accounting leaves unpaid future interest outside vault income until payment arrives, affecting AssetsTotal, loan debt calculations and the accounting treatment of defaults.
The V1.1 rules would not retroactively convert older vaults. Ripple’s documentation says vaults created under the previous accounting method retain that model after V1.1 activation.
As earlier amendment coverage reported, Ripple’s validator had already voted for the underlying SingleAssetVault and LendingProtocol proposals in August, but validator approval remained well below the level required for mainnet activation.
XRPL 3.4.0 packages a large set of transaction fixes
The second amendment, fixCleanup3_4_0, contains fixes covering lending, vaults, Automated Market Makers, Multi-Purpose Tokens, NFTs, escrow, permissioned trading and account authorization.
The official release says one change prevents AMMClawback from burning a holder’s liquidity-provider tokens while recovering zero underlying assets when MPT rounding reduces the calculated recovery amount to zero.
Another fix strengthens MPT invariants. XRPL developers said the ValidMPTBalanceChanges and ValidMPTTransfer checks, which previously generated logs, are enforced under the amendment and continue to apply when transactions fail.
For Single Asset Vaults, the release lists precision and rounding changes across deposits, withdrawals and clawbacks. The rules are designed to keep recorded assets, available assets and outstanding share supply aligned when conversions reach precision boundaries.
Permissioned trading receives several corrections. The package excludes deleted domain offers from one Permissioned DEX invariant, tightens domain checks and corrects how expired credentials are removed when OfferCreate or Payment transactions run.
Signing behavior receives a separate safeguard. The release says version 3.4.0 assigns different signing hash prefixes to counterparty and sponsor signatures so a signature created for one role cannot be replayed as the other.
The release contains lower-level node hardening outside the amendment package. Developers fixed an unbounded database seek through TMGetLedger, capped the size of incoming TMTransactions lists and introduced a fee for transactions that cannot be deserialized.
XRPL developers said version 3.4.0 incorporates phase-one fixes arising from MPT and DEX audit and attackathon findings. The release does not identify those fixes as evidence of an active exploit on mainnet.
In previous upgrade coverage, version 3.3.0 had already introduced code for several separate proposals, including corrected Batch functionality, sponsored fees and confidential MPT transfers, with validator approval still required before activation.
Validator approval still separates release from activation
XRPL’s official amendment rules state that installing software containing an amendment only gives a server the code needed to understand the proposed rules. Validators separately choose whether to vote for activation.
The current XRPLF feature code lists both LendingProtocolV1_1 and fixCleanup3_4_0 as supported while retaining DefaultNo voting behavior. A default-no setting means running the software does not itself cast an affirmative amendment vote when an operator has not configured another choice.
The underlying lending components remain short of activation. A Sept. 17 snapshot based on XRPL Foundation validator-history data showed 16 of 35 trusted validators supporting SingleAssetVault and 13 of 35 supporting LendingProtocol.
Those counts are time-sensitive and come from an independent network tracker, not a fixed figure published in the release notes. The official rule remains more than 80% support maintained for two continuous weeks.
The new V1.1 amendment depends on the underlying lending architecture. The current XLS-66 specification describes fixed-term, uncollateralized lending using funds pooled through Single Asset Vaults, while borrower underwriting and credit-risk assessment remain off-chain.
The same specification remains classified as Draft. No source reviewed for this update showed a mainnet loan executed through the proposed native protocol or an activation date for LendingProtocolV1_1.
Node operators now receive packages from XRPL Foundation
Version 3.4.0 changes the distribution path for Linux server packages. The official release says Debian and RPM packages are now hosted through packages.xrplf.org and signed with an XRPL Foundation key.
XRPL developers urged server operators to install 3.4.0 “as soon as possible” to maintain service continuity. The published DEB and RPM files include SHA-256 checksums so operators can verify downloaded packages before installation.
GitHub now lists 3.4.0 as the latest immutable xrpld release, tied to commit 4a4fded2eba11427c48ce3f24d9c1aea5e7a9d17. The repository says the release tag and version commit carry verified signatures.
The same release retires fixAMMOverflowOffer. Under XRPL’s amendment model, retirement does not reverse the fix. It removes obsolete pre-amendment behavior after the new rules have become established as permanent protocol behavior.
Client support and security review are still developing
Application libraries are moving alongside the server release. XRPLF’s JavaScript client history lists LendingProtocolV1_1 support under the unreleased section following xrpl.js 5.2.0, which shipped on Sept. 11.
The binary-codec history shows version 2.11.0 already contains the role-specific sponsor and counterparty signing prefixes used by fixCleanup3_4_0, along with protocol definitions generated from xrpld 3.4.0.
Security testing of the lending work has continued separately from validator voting. Sherlock said in an Aug. 27 review that Ripple had started an AI-only examination of Lending Protocol V1.1 through its Audit Engine.
Sherlock said it would publish more information after the review finished, but no final V1.1 findings were located in its public materials checked for this report. Earlier testing covered a previous version of the lending system; prior independent audit coverage reported that Halborn’s earlier re-audit found no critical or high-risk issues while identifying one medium, two low and two informational findings.
U.S. authorities have announced new sanctions targeting an Iranian cryptocurrency exchange, alleging it was used to process Bitcoin payments tied to maritime traffic through a strategic choke point in the Middle East.
On Thursday, the U.S. Department of the Treasury’s Office of Foreign Assets Control (OFAC) designated BitBank, accusing the platform of helping move cryptocurrency-linked funds connected to vessels transiting the Strait of Hormuz. The action is part of a broader push to restrict Iran’s access to international financial channels, including through digital assets.
Key takeaways
- OFAC sanctioned Iranian digital asset infrastructure tied to BitBank, alleging it facilitated Bitcoin payments connected to Strait of Hormuz shipping.
- Treasury said Hormuz Safe Marine Services Authority transferred funds received to the Islamic Revolutionary Guard Corps (IRGC) using BitBank.
- The U.S. linked the alleged setup to Iranian financier Babak Zanjani, portraying it as part of an IRGC-connected sanctions-evasion architecture.
- OFAC also designated BitBank’s developer, Pishtaz Simorgh Electronic Trade Company, and three associates connected to Zanjani.
- Separately, “Bitbank” is a different entity from a Japan-licensed exchange acquired by SBI Holdings in June, underscoring the importance of distinguishing similarly named platforms.
Why OFAC says BitBank matters
According to OFAC, as of June, the Hormuz Safe Marine Services Authority used BitBank to transfer payments it received to the IRGC. Treasury’s allegation centers on how crypto rails may be used to convert and route funds in ways that can help sanctioned parties avoid traditional banking scrutiny.
OFAC further claimed that the exchange is part of a wider system Treasury described as enabling the movement of hundreds of millions of dollars in Bitcoin associated with Babak Zanjani—an individual previously tied by the U.S. government to Iran-related sanctions evasion.
In its statement accompanying the designations, Treasury Secretary Scott Bessent said the step “make[s] perfectly clear” that attempts to finance the Iranian regime using cryptocurrencies are not beyond OFAC’s reach.
The Hormuz Safe link and the prior insurance scheme allegation
Treasury’s notice also referenced earlier accusations involving Hormuz Safe. In a prior action, OFAC alleged that Hormuz Safe was connected to an IRGC-backed scheme pressuring vessels to purchase maritime insurance for passage. Treasury’s earlier claim included coverage against seizures by Iran itself—an arrangement OFAC said could create a revenue channel that ultimately supports sanctioned entities.
This time, the U.S. moves from describing the insurance or routing mechanism to naming the alleged crypto exchange infrastructure used to transfer funds that stakeholders may receive in the course of that shipping activity.
For investors and industry participants, the practical takeaway is that U.S. sanctions enforcement is increasingly focused on the “plumbing” that can connect off-chain activity—like shipping payments and insurance flows—to on-chain settlement or exchange transfers.
Scope of the sanctions package
OFAC’s designations include BitBank and its developer, Pishtaz Simorgh Electronic Trade Company, along with three associates of Babak Zanjani. Treasury described the group as “key components of the Iranian regime’s digital assets-based sanctions evasion infrastructure.”
The designations add another layer to a series of OFAC moves aimed at isolating Iran from the international financial system, including through sanctions on digital asset businesses.
Cointelegraph reported that it reached out to BitBank for comment, but no response is included in the source material.
Beware name confusion: Iranian BitBank vs. a licensed Japan exchange
Readers should note that the sanctioned “BitBank” referenced by U.S. Treasury is not the same as a separate “bitbank, inc,” a fully licensed crypto exchange founded in Japan in 2014. That Japan-based entity was acquired by SBI Holdings in June, according to earlier coverage (SBI Holdings acquired bitbank).
Treasury’s designation lists “BitBank” as having been established in 2024. The distinction matters because similarly named platforms can create confusion for users, compliance teams, and market participants trying to assess regulatory risk.
Broader U.S. actions targeting Iran and crypto
This sanction comes amid continued U.S. efforts to tighten restrictions around Iran’s crypto activity. Earlier in the year, OFAC sanctioned multiple Iranian digital asset exchanges—actions Treasury framed as attempts to support sanctions evasion.
In August, the U.S. sanctioned two digital asset exchanges—Shelbit and Aban Tether—according to earlier reporting from Cointelegraph. In June, Treasury also sanctioned four crypto exchanges, including Nobitex, as previously covered.
Treasury has also targeted stablecoin holdings connected to Iranian-linked wallets. In July, the U.S. ordered the freezing of more than $130 million in USDt held in wallets linked to Iran, per coverage included in the source material.
Meanwhile, wider financial constraints appear to be driving Iran to adjust tactics. Earlier this month, the Financial Times reported that Iran’s central bank eased foreign currency controls to encourage businesses to bring overseas earnings home, including by using cryptocurrency, amid tightening U.S. sanctions—an approach discussed in prior coverage from Cointelegraph.
With Thursday’s designations, OFAC is again signaling that crypto-related infrastructure used in sanctioned economic activity—especially when linked to strategic regional commerce like Strait of Hormuz shipping—can be treated as enforceable sanctions targets. The next question for market participants is how exchanges, payment providers, and compliance tooling will respond to these designations, and whether further details about the alleged payment pathways emerge as the U.S. continues expanding its Iran-focused enforcement.
Galaxy has expanded its onchain lending business to Solana with two live stablecoin vaults on Kamino, adding separate USDC and USDT strategies managed through Galaxy Curation.
Summary
- Galaxy launched two Kamino vaults offering curated USDC and USDT lending strategies across Solana markets.
- Galaxy applies institutional collateral standards, exposure limits, and market monitoring to both newly launched vaults.
- Galaxy reported a $1.4 billion average loan book and 1,741 total trading counterparties during Q2.
- Kamino reports over $20 billion in originated loans and zero bad debt to lenders historically.
- The USDC vault is available through Yield.xyz, extending distribution beyond users accessing Kamino directly.
Galaxy said on Sept. 17 that its curation team will decide which Kamino lending markets the vaults can enter, control exposure limits and monitor market conditions using the risk framework employed in its institutional lending business.
Separately, Kamino confirmed the launch, describing the products as actively managed lending vaults that generate yield from borrower activity across its Solana credit markets. Neither announcement set a guaranteed return or fixed APY.
Galaxy brings its curation model onto Solana
Galaxy Curation started in July with stablecoin strategies built on Morpho and distributed to institutions through Fireblocks Earn. The Kamino launch puts the same curation model on a second blockchain and introduces direct exposure to Solana lending markets.
Galaxy’s July launch described curation as a system for applying institutional credit controls to onchain lending while keeping deposited assets at the protocol level. Curators decide which lending markets qualify, how much capital can enter each one and when those allocations need to change.
For Kamino, Galaxy has launched one USDT configuration and one USDC configuration. Both are described by Galaxy as moderate-risk strategies, though they have different mandates.
The USDT vault takes the more selective approach. Galaxy says it is designed to prioritize capital preservation through exposure to liquid and established Kamino lending venues.
The USDC vault permits a larger set of collateral markets in pursuit of higher lending yield. Galaxy describes the design as involving expanded collateral exposure and wider market participation, which means its risk profile is not identical to the USDT product.
Galaxy explicitly warns that both products remain exposed to market, smart-contract and liquidity risks. The company does not describe either vault as principal-protected.
Eduardo Bermudez, Galaxy’s director of trading, said the company built the curation business around the view that institutions should not have to change their operating model to use onchain yield products.
“Extending that to Kamino brings the same principle to Solana,” Bermudez said.
Vault rules control where depositor funds can move
Kamino’s vault system lets a curator set eligible reserves, allocation weights and hard exposure caps. Its documentation says users deposit one asset into a vault and receive vault shares whose value changes as interest accrues from underlying lending markets.
The curator does not manually execute every individual movement of capital. Kamino’s infrastructure handles allocation and rebalancing based on the strategy instructions set by the curator, while the resulting activity remains visible onchain.
Galaxy will therefore control the lending mandate, while Kamino provides the smart contracts and execution infrastructure.
Kamino documents controls covering allocation weights, reserve restrictions, management fees, performance fees, minimum deposits and exposure settings. The Galaxy announcement did not publish a fixed vault APY, management fee, performance fee or maximum deposit amount.
Liquidity conditions can affect withdrawals. Kamino’s documentation says vault redemptions first use idle liquidity and funds available from lending reserves. A withdrawal can enter a queue when enough immediately redeemable capital is unavailable.
Michael Weisz, Kamino’s CEO, said Galaxy’s lending experience is being applied directly through the protocol’s infrastructure. He described the arrangement as bringing institutional capital and risk controls into the same onchain system, a company characterization that does not remove the lending and smart-contract risks disclosed for users.
The USDC vault has another distribution route through Yield.xyz. Galaxy said the integration lets users access that strategy beyond Kamino’s own interface, while the USDT vault announcement did not identify a comparable external distribution channel.
Galaxy builds on a $1.4 billion lending operation
Galaxy’s latest reported financial figures provide the basis for the institutional lending experience referenced in the vault announcement.
Its Q2 results showed an average loan book of $1.438 billion for the three months ended June 30, up 1% from the previous quarter. The company served 1,741 trading counterparties, compared with 1,691 in Q1.
Galaxy ended the quarter with $7.1 billion in combined assets under management and assets under stake. Its Global Markets business generated $49 million of adjusted gross profit during the quarter.
The curation expansion follows Galaxy’s July launch of the Galaxy Onchain Financing Rate, or GOFR. That product lets institutional borrowers face Galaxy directly while Galaxy routes financing across several onchain lending protocols.
Galaxy’s GOFR materials list Kamino alongside Aave, Morpho and Spark among the lending venues monitored for the program. Galaxy committed $100 million of its own equity as first-loss capital for GOFR, a structure separate from the new Kamino vaults.
As of Sept. 13, Galaxy displayed indicative GOFR rates of 4.40% for USDC and 4.00% for USDT. Those rates belong to the GOFR financing program and should not be treated as yields for the newly launched Kamino vaults.
The company has been adding other Solana-based institutional products during 2026. As earlier coverage of Galaxy’s Solana fund launch reported, Galaxy and State Street introduced the SWEEP tokenized cash-management fund on Solana in May.
Galaxy has since used Kamino in its onchain financing operations and collateral markets. Recent coverage of institutional tokenized assets noted that tokenized GLXY shares issued through Superstate had already been accepted as collateral on Kamino.
Kamino reports more than $20 billion in originated loans
Kamino describes itself as Solana’s largest credit platform and said in the Galaxy announcement that it had originated more than $20 billion in loans without bad debt to lenders. The protocol said it had processed more than $650 billion in cumulative transaction activity.
Kamino’s figures are company-reported operating statistics. Independent DeFi metrics use different definitions.
Current DefiLlama data tracks Kamino Lend at approximately $1.33 billion in total value locked and just over $1 billion in active loans. The service records roughly $211 million in cumulative protocol fees.
Kamino’s announcement describes its credit platform as having roughly $2 billion in AUM. That figure should not be treated as interchangeable with DeFiLlama’s TVL because platform AUM and the data provider’s locked-value calculation cover different accounting definitions.
The protocol’s institutional activity has expanded beyond conventional crypto-backed loans. Three days before Galaxy’s launch, Kamino introduced lending vaults using tokenized SPY, QQQ and Nvidia shares supplied through Kraken’s xStocks platform.
As recent tokenized-stock market coverage reported, Kamino held approximately $41.7 million of tokenized-stock DeFi deposits in early September, placing it behind Uniswap V4 in that measured category.
Kamino appointed former Yieldstreet co-founder Michael Weisz as CEO on Sept. 15 and announced plans to build a New York operation focused on institutional finance. Coverage of Kamino’s U.S. expansion reported that the company plans to recruit staff across finance, legal, compliance, product and business development.
For the new Galaxy products, the next changes will occur through ongoing curation. Galaxy can modify market allocations and exposure limits as lending conditions change, while Kamino’s infrastructure executes the approved strategy onchain.
Galaxy has not published a target amount for deposits into either vault or a deadline for reaching a specific asset level. Its Sept. 17 announcement states that both the USDC and USDT vaults are already live.
Coinbase has announced a Sept. 16 partnership with Stablecore to embed crypto trading, custody, staking and stablecoin payments into banking systems whose integration footprint reaches more than 3,000 U.S. banks and credit unions.
Summary
- Coinbase and Stablecore will let banks offer crypto trading, custody, staking and stablecoin payments directly.
- Stablecore says its existing technology integrations reach more than 3,000 U.S. banks and credit unions.
- Amarillo National Bank is among institutions already working with the Coinbase and Stablecore partnership program.
- Coinbase provides regulated custody and exchange infrastructure while Stablecore connects existing banking and compliance systems.
- Stablecore’s Verafin integration remains in beta, with wider mutual-customer rollout planned from fourth quarter 2026.
Coinbase said the partnership is already underway with institutions including Amarillo National Bank in Texas, while Stablecore will connect Coinbase’s digital asset infrastructure to the core banking, digital banking and compliance systems used by participating financial institutions.
The announcement does not say that 3,000 banks have signed contracts with Coinbase. Stablecore says its existing integrations reach technology systems used by more than 3,000 U.S. banks and credit unions, giving participating institutions a route to add digital asset products without replacing their existing banking platforms.
Coinbase services will sit inside existing bank platforms
Through the partnership, participating bank and credit union customers could buy, sell, hold, stake and make payments with digital assets through their normal banking experience. Coinbase provides the underlying custody and exchange infrastructure, while Stablecore manages the connection between that infrastructure and each institution’s technology stack.
Stablecore’s role covers orchestration between core banking systems, customer-facing digital banking software and compliance tools. Its platform is designed as a white-label layer, allowing a financial institution to retain its own brand and customer interface while using outside infrastructure for digital asset functions.
Coinbase has not identified the stablecoins or blockchain networks that participating institutions will support. The Sept. 16 announcement does not publish transaction fees, custody charges, staking terms, minimum balances or a general customer launch date.
Alec Lovett, Coinbase’s head of infrastructure business, said “Community banks and credit unions shouldn’t have to choose between staying local and staying current.” Coinbase presents the arrangement as infrastructure for smaller financial institutions seeking crypto services without building their own custody, trading and blockchain systems.
Stablecore CEO Alex Treece said banks should be able to add the products without moving to completely different technology platforms. His company focuses exclusively on regional banks, community banks and credit unions.
Amarillo National Bank is part of the early integration work
Amarillo National Bank appears across several Stablecore projects already moving toward production. In March, Q2 announced that Amarillo National Bank and Bank of Utah were among the early institutions working with Stablecore through Q2 Innovation Studio.
Q2 said the integration can support stablecoin payments and acceptance, digital asset accounts with fiat on- and off-ramps, crypto-backed lending, tokenized deposits and staking rewards. The capabilities can appear inside both retail and commercial digital banking experiences.
By Sept. 9, Q2 reported that Stablecore’s digital asset integration had moved from initial development into production in less than six months. Q2 described it as a native connection inside its digital banking platform.
Coinbase’s Sept. 16 release goes a step further by identifying Coinbase as the provider of underlying custody and exchange infrastructure within Stablecore’s offering. It does not specify which Coinbase services Amarillo National Bank has already activated for end customers.
No public announcement reviewed for this report confirms that Amarillo customers can currently trade crypto, earn staking rewards or send stablecoins through their bank accounts. The companies describe implementation as underway, leaving the exact customer-facing launch stage dependent on the individual institution.
Stablecore is adding crypto monitoring through Verafin
Compliance infrastructure is developing alongside the banking integrations. Stablecore announced a Sept. 15 partnership with Nasdaq Verafin that combines digital asset transaction information with traditional bank customer data for financial-crime monitoring.
Under that structure, Stablecore holds digital asset transaction and position information without storing personally identifiable information. The bank keeps its customer and account records in its core system, while both sets of information flow into Verafin for investigation and risk assessment.
Amarillo National Bank is among the beta customers testing the Verafin integration. Stablecore expects the system to reach mutual customers during the fourth quarter of 2026 and first quarter of 2027, with real-time sanctions screening for recipients of digital asset transfers planned after the initial integration.
William Ware, president of Amarillo National Bank, said “Our customers want access to emerging payment methods” while the bank seeks to maintain visibility across traditional and digital asset activity. The Verafin beta is separate from Coinbase’s custody and exchange role, although both sit within Stablecore’s developing bank technology stack.
U.S. rules allow banks to use third-party crypto providers
Federal banking regulators have clarified several activities relevant to the Coinbase and Stablecore model.
The OCC confirmed in May 2025 that national banks and federal savings associations may provide crypto custody and execute customer-directed purchases and sales. Banks can outsource permissible crypto activities to third parties when they maintain appropriate vendor and risk controls.
Two months earlier, the OCC reaffirmed that national banks may conduct certain stablecoin, distributed-ledger and crypto custody activities. The agency removed an earlier requirement that OCC-supervised banks obtain supervisory non-objection before starting those activities, while retaining normal safety, soundness and compliance expectations.
The Federal Reserve withdrew its separate advance-notification expectation for state member banks in April 2025. Crypto activities now fall within its regular supervisory process, though institutions still have to comply with applicable laws and maintain appropriate controls.
OCC guidance later confirmed that national banks may conduct riskless-principal crypto trades, where the bank facilitates a customer transaction while entering an offsetting transaction instead of keeping the asset in inventory. The December 2025 guidance maintained the requirement for safe and sound operation.
Regulatory permission does not mean every community bank can activate every Stablecore or Coinbase feature automatically. Charter type, state rules, bank policies, customer eligibility and individual product design can change what each institution offers.
Coinbase now has two community-bank distribution deals
The Stablecore agreement follows another Coinbase community-bank partnership announced six days earlier.
As crypto.news reported in its Coinbase-Moov coverage, Coinbase and Moov are working to bring stablecoin acceptance, merchant settlement, payouts and real-time funding to a network of more than 1,000 community banks and credit unions.
The two arrangements cover different parts of banking infrastructure. Moov focuses on payment acceptance, merchant settlement and funding through its payments stack, while Stablecore’s announced product set reaches trading, custody, staking, stablecoin payments and integration with core and compliance systems.
Related coverage of Coinbase’s OCC trust approval reported in April that Coinbase had received conditional approval for a national trust bank charter, with community banking groups objecting to the regulator’s decision. The Stablecore announcement identifies Coinbase as the regulated digital asset infrastructure provider but does not specify which Coinbase legal entity will provide each service to each participating institution.
Stablecore’s March Q2 announcement named Amarillo National Bank and Bank of Utah as early institutions evaluating its infrastructure, while the Sept. 16 Coinbase release names only Amarillo in connection with the new partnership. Neither company has disclosed how many banks have completed Coinbase-enabled deployment, transaction volumes from early implementations or a deadline for opening the full product set to customers.

World’s ‘World Money’ Launches Self-Custody Super App

Remy Ma Jokes About Dr. Umar After Flirty Clip With Millyz

Navaan Sandhu |Paper Before Money (Official Video) |New Punjabi Songs 2024|Latest Punjabi Songs 2024



-

 Fashion6 days ago
Weekend Open Thread – Corporette.com
-

 Tech5 days ago
The Latest Weird Thing to Play Doom Is the Mapped-Out Brain of a Fruit Fly
-

 Business7 days ago
10 Most-Streamed Songs On Spotify In 2026 So Far, Led By Ella Langley’s Dominant Run On The Charts This Year
-

 Crypto World7 days ago
XAG/USD: Silver’s Short-Term Rally Meets Its Moment of Truth
-

 Crypto World7 days ago
Diesel Tops $6 a Gallon for the First Time as 28 States Set Records
-

 Crypto World3 days ago
Kraken Lets xStocks Holders Earn Yield Through DeFi
-

 Crypto World4 days ago
Elon Musk Drops a Bombshell: Grok 5 Could Be the AGI Breakthrough
-

 Crypto World1 day ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 News Videos7 days ago
Facing Financial Fears
-
 Entertainment6 days ago
News Specials, Movies, Shows, More
-

 Crypto World6 days ago
Can AI Build a Startup in 72 Hours? Elon Musk's Team Will Livestream the Test
-

 Business5 days ago
Rivals Sam Altman and Elon Musk Rally Behind Dario Amodei’s Call for a Slowdown in AI Development
-
 NewsBeat4 days ago
‘Sick conspiracy’: Trump says only guardrails AI needs is ‘a strong and smart (High IQ!) president’ in all-caps rant
-

 Crypto World4 days ago
New Tesla Roadster Uses SpaceX Tech. Will It Impact the Stock Price?
-

 Crypto World6 days ago
Robinhood Chain Never Stopped But its Blobs Did Stop Reaching Ethereum For 14 Minutes
-

 Crypto World2 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-
 Entertainment6 days ago
New Horror Movie Officially Earns a Rare Stephen King Recommendation
-

 Business6 days ago
Marvell: Most Potent Setup Of The AI Factory Decade
-

 Crypto World4 days ago
3 Token Unlocks to Watch in the Third Week of September 2026
-

 Crypto World3 days ago
DOJ Seeks to Seize $61M in Iran Oil Funds From Binance Accounts It Vouched For
You must be logged in to post a comment Login