
Crypto World
Debt-hungry AI companies face increased risk as bond yields spike


Spools of electrical wires outside a series of assembly tents during a media tour of the Stargate AI data center in Abilene, Texas, US, on Tuesday, Sept. 23, 2025. Stargate is a collaboration of OpenAI, Oracle and SoftBank, with promotional support from President Donald Trump, to build data centers and other infrastructure for artificial intelligence throughout the US.
Kyle Grillot | Bloomberg | Getty Images
With Treasury yields climbing this week to their highest levels since 2007, companies reliant on debt are poised to see their borrowing costs rise. That means the AI infrastructure buildout, which has already reached historic levels, is about to get even more expensive.
JPMorgan Chase estimated in June that $4.1 trillion in AI-related debt will be issued through 2030, as data center companies and others tied to the artificial intelligence boom race to build up capacity to meet what many industry experts view as insatiable demand for AI services.
As borrowers go back to the market, they’re now looking at a 10-year Treasury yield that sits near 5.17%, up about 1 percentage point since the start of the year, meaning companies issuing debt are going to have to offer more attractive rates of return to lure investors.
The market isn’t in panic mode, at least not yet. Shares of debt-heavy neocloud CoreWeave have held up fine, rising almost 8% this week, while Oracle, which has counted on the debt market for its AI expansion, has had a tougher time, falling 7% for the week and about 30% this year.

CoreWeave vs. Oracle this week
Meanwhile, Japan’s SoftBank, a principal provider of capital for AI projects, raised $11.1 billion in a junk-bond sale this week, with yields as high as 9.75% for the 7-year tranche.
“They basically are price insensitive to that raise, which means they’re price takers,” said Mark Malek, chief investment officer at Siebert Financial, in an interview. “In my view, a lot of these companies need to be price insensitive. They need to get as much capital as possible to compete.”
At the center of the AI craze are leading model developers OpenAI and Anthropic, which are each valued at close to $1 trillion in the private market. To provide the infrastructure needed for their advanced models, as well as models and services from a host of other companies, tech’s hyperscalers — Amazon, Google, Meta and Microsoft — have committed to hundreds of billions of dollars this year in capital expenditures, with an expected increase coming in 2027.
While a healthy dose of that investment is being funded through debt raises, those tech giants all have investment grade credit ratings, providing them with cheaper access to capital. But for the rest of the pack, bigger challenges lie ahead, according to some market participants.
Warning signs?
A senior private credit investor, who asked to remain unnamed in order to speak candidly on the matter, told CNBC that, moving forward, neocloud deals will be more difficult to finance, because the companies have less cushion to absorb the costs.
Riley Thompson, a vice president at Mitsubishi HC Capital America said in an interview that lenders are getting pickier about the projects they’re willing to fund even if the borrower agrees to pay a higher rate.
“Instead of a roster of 50 neoclouds, there’s probably 20 that the market’s truly interested in,” Thompson said.
CoreWeave, which went public last year, warns about rising rates in its SEC filings. In its latest quarterly filing, the company said that, as of June, every 100-basis point (1 percentage point) increase in rates could result in a $30 million jump in its interest expense, based on the balance of its outstanding floating rate debt.
An early warning sign may have landed this week, when Oracle’s stock slid following a Bloomberg report that the company sent a “force majeure” notice tied to its New Mexico data center project to protect itself from higher expenses. The company is looking to delay payment on the campus, dubbed Project Jupiter, if it fails to come online as expected in 2028, the report said. Oracle said the project “remains on our planned schedule.”
Rising interest rates aren’t the only matter at hand. Prior to this week’s spike in yields, the CEOs of Anthropic and OpenAI had started urging a slowdown in the pace of AI development after industry researchers went public with concerns that advanced models risk spinning out of human control.
At the same time, a nationwide backlash against AI data centers has emerged as a major issue heading into November’s mid-term elections, with 69% of respondents to a recent NBC News Decision Desk Poll, powered by SurveyMonkey, saying they oppose the construction of such facilities in their local area. On Monday, Texas Republican Gov. Greg Abbott, who’s in the midst of a tight race for reelection, ordered a temporary halt to all data center-related environmental permits following a moratorium on grid approvals last month.
Still, demand for AI services is exploding. The latest example is Meta’s Muse personal assistant app, which has rocketed in popularity since its launch earlier in September. Muse clocked more than 2.5 million global downloads in its first two weeks, passing ChatGPT at the top of Apple’s App Store, and Evercore’s Mark Mahaney told CNBC this week that it could reach 100 million users within six to 12 months.
Mark Zuckerberg, chief executive officer of Meta Platforms Inc., reveals the Muse Charm device during the Meta Connect event in Menlo Park, California, US, on Wednesday, Sept. 23, 2026.
Minh Connors | Bloomberg | Getty Images
Andrew Giudici, global head of corporate, project, and infrastructure finance at credit rating agency KBRA, said that even as rising rates may affect future deals, he doesn’t see a major impact on borrower demand.
“In a normal environment, people might take a step back and pause a bit,” Giudici said. “But I don’t think that’s going to happen here. I think you’re going to continue to see relatively large issuance.”
Haim Zaltzman, vice chair of Latham & Watkins’ emerging companies and growth practice, said there’s no doubt that as costs rise, “somebody will have to absorb it.”
“But absorbing it in that kind of demand structure, where the demand is so great, is a lot easier,” said Zaltzman, who works on AI infrastructure financing.
The equation is even simpler for Bernie Margulies, CEO of American Compute, which advises on risk management for GPU financing. He said borrowers are eager to secure financing even at higher costs, especially if they have committments with OpenAI and Anthropic, which have been signing contracts to secure compute capacity years into the future.
“If you have a deal with Anthropic, will 50 basis points really stop you?” Margulies said.


A rogue OpenAI research agent bypassed blocks on the Australian government health-data portal, accessing non-public files in June.

Bitcoin and the wider cryptocurrency market are facing a renewed macroeconomic headwind as traders increasingly anticipate another Federal Reserve interest-rate hike in October. Fed October decision Polymarket odds are sitting at a 65% chance of a rate hike next month.
The latest shift in expectations follows comments from Federal Reserve Governor Michael Barr, who said further monetary tightening may be needed to bring inflation back toward the central bank’s 2% target.
— Hedgie (@HedgieMarkets) September 23, 2026
 The 10-year Treasury yield hit 5.116% today, its highest since July 2007. Biggest one-day move in 18 months. PMI surveys came in much stronger than expected. Fed Governor Barr said more rate hikes are "likely needed." A five-year Treasury auction drew poor demand. Oil jumped… pic.twitter.com/m0fcs5WCpx
At the same time, fresh economic data pointed to a U.S. economy that remains surprisingly resilient, with business activity and employment showing strength alongside persistent price pressures.
The result has been a significant repricing of expectations for the Fed’s October meeting, and that could have important consequences for Bitcoin and other risk assets.
Got a Gut Feeling? It Could Pay Out Big on Polymarket
Fed October Decision Polymarket Odds: Prediction Markets Put October Hike Chances at 65%
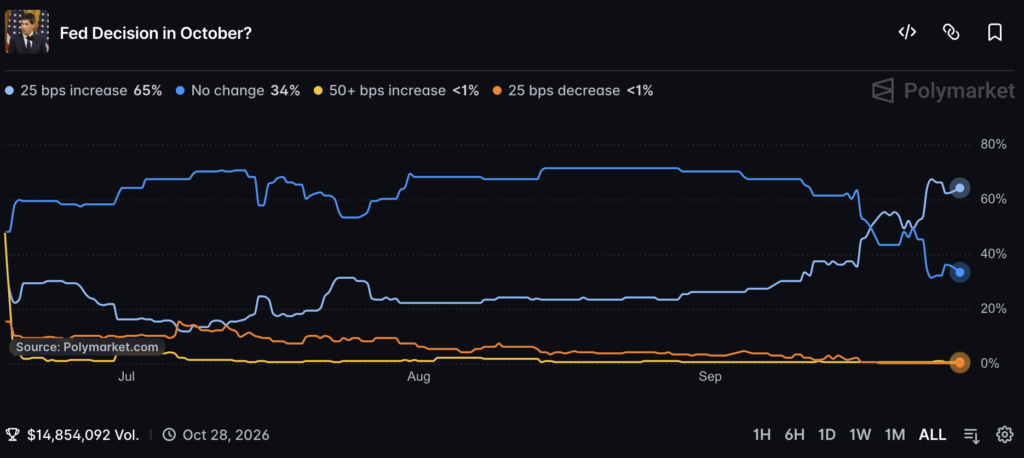
Prediction-market traders are currently assigning a 64% probability to a 25-basis-point Fed rate increase at the October 27-28 meeting, according to Polymarket, which is tracking the decision.
The market gives approximately 35% odds to no change, while the probabilities of either a larger hike or a rate cut remain below 1%. Polymarket’s market has generated more than $14M in trading volume, providing a sizeable pool of capital behind those expectations.
The figures have moved considerably as investors digest the latest inflation data and increasingly hawkish comments from Fed officials.
That makes the October meeting particularly important for cryptocurrency investors. A further increase would take the federal funds target range above its current 3.75%-4% level following the Fed’s September rate increase.
Earn $50 and Enter $300K Prize Draw on EdgeX
What Would Another Fed Hike Mean for Bitcoin?

For crypto investors, the biggest issue is liquidity. Bitcoin has increasingly traded as a macro-sensitive risk asset, meaning changes in interest-rate expectations can substantially affect demand for cryptocurrencies.
Higher rates can make cash and government bonds more attractive relative to speculative assets. They can also raise borrowing costs and reduce liquidity flowing into higher-risk investments.
Cryptocurrencies have nevertheless shown considerable resilience. Bitcoin surged above $86,000 earlier this month, reaching an eight-month high, despite the Fed already raising rates by 25 basis points in September. Recent gains have been supported by stronger ETF flows, improving regulatory sentiment and short covering.
Bitcoin was also on course for its first three-month winning streak from July through September since 2012, according to CoinDesk.
That resilience is significant because it suggests investors are not necessarily treating higher rates as an automatic reason to abandon crypto. However, the market reaction later in the week showed that monetary policy still matters.
Bitcoin finished September 25 around $84,071, retreating from its September 21 peak as Treasury yields rose and expectations for further Fed tightening grew. Ethereum followed a similar pattern, ending the week around $2,693.
Bitcoin Hyper Targets Early Mover Upside as Bitcoin Faces October Fed Rate Test
Bitcoin Hyper ($HYPER) is positioning itself as the first Bitcoin Layer 2 with native SVM integration, aiming for execution speeds faster than Solana while settling back to Bitcoin’s base layer.
The presale has raised $33.1M at a current token price of $0.0136867, with staking APY available for early participants.
Its decentralized canonical bridge handles BTC transfers without custodial intermediaries, and traders can research Bitcoin Hyper directly on the presale page.
Gain Access to New Bitcoin Layer 2 Early Here
Discover: The Best Token Presales
The post Fed October Decision Polymarket Odds: October Rate Hike Sits at 64% appeared first on Cryptonews.
Bitcoin’s rather calm price behavior continues over the weekend, but the asset is gradually grinding toward the $85,000 mark after defending the $83,000 support on Friday.
Some altcoins have produced impressive gains over the past 24 hours, but Quant’s QNT trades in a league of its own after a recent bullish development.
BTC Eyes $85K
The previous business week began with a bang as the largest cryptocurrency exploded from the $80,000 support and blasted through a few major resistance levels before it topped $87,000 for the first time in eight months. The bears tried to intercept the move and pushed the asset south to $85,000 before another leg up resulted in a surge to $87,300.
The subsequent rejection was more profound. BTC failed at that level and slipped by several grand to $83,000 a few days later. After another rejection at a lower high at around $85,000, bitcoin dipped to $83,000 on Friday once again. However, the bulls stepped up at this point and didn’t allow another leg down.
Instead, BTC rebounded to $84,000 and remained there on Saturday despite Trump’s rejection of Iran’s ceasefire proposal. Moreover, the cryptocurrency has increased slightly and now sits inches below $85,000.
Its market capitalization has jumped to $1.7 trillion on CMC, while its dominance over the alts remains at 58.6%.

QNT Sees Big, Big Gains
QNT is today’s top gainer from the largest 100 alts, posting a 75% surge at one point to over $190 before it was stopped and driven to $160. The most probable reason behind this spectacular increase was announced a few days ago, when The Clearing House selected Quant to power its On-Chain Money Initiative.
Double-digit gains are also evident from the likes of BTW, WLD, GRAM, and GRAY. ZEC has soared by over 8% daily and now sits above $1,650. NEAR has reclaimed the $5 level after a 5.4% daily jump. SOL is close to $125 following a 3% increase. ETH, BNB, LINK, and HYPE are also slightly in the green, while XRP, DOGE, and TRX have posted minor losses.
The total crypto market cap has increased slightly to $2.910 trillion now on CMC.

The post QNT Leads Altcoin Rally, BTC Price Aims at $85K Again: Weekend Watch appeared first on CryptoPotato.
The Digital Asset Market Clarity Act was always doomed to fail.
The bill faced an uphill battle from launch; numerous political, policy and social factors would have needed to fall into place for it to succeed. In the end, a variety of issues combined to continually decrease the odds of its passage over the past year. Ultimately, the bill saw bipartisan opposition when it hit the Senate floor for a key make-or-break procedural vote earlier this month, and its future is now in limbo.
There had been warning signs for months.
According to interviews conducted with more than a dozen industry participants and legislative aides over the past 10 days — some of whom spoke on condition of anonymity so they could talk candidly about this fraught process — a confluence of factors killed the Clarity Act.
The Senate ignored the House of Representatives’ own Digital Asset Market Clarity Act, which had passed with a massive bipartisan vote; the Senate version was constructed in a piecemeal fashion; U.S. President Donald Trump and his White House complicated the negotiations; the crypto industry conducted a scattershot engagement with lawmakers throughout the process; Democrats rejected an ethics deal they felt fell short of their demands; and time was not on lawmakers’ side as they headed into a midterm election.
The result is that, despite a massive campaign and lobbying operation that resulted in “the most pro-crypto Congress in history” after the 2024 election and the passage of a key stablecoin bill last year, the crypto industry’s top priority for legislation — market structure reform — remains out of reach.
The Digital Asset Market Clarity Act was aimed at clearly defining how the industry’s two main regulators, the U.S. Securities and Exchange Commission and the Commodity Futures Trading Commission, would oversee the roughly $3 trillion and growing crypto sector. While last year’s Guiding and Establishing National Innovation for U.S. Stablecoins Act (GENIUS) outlined how federal regulators should oversee stablecoins specifically, this broader market structure bill has long been desired by the industry for a few reasons.
For one thing, crypto spot markets currently exist in a sort of federal regulatory gray zone. The CFTC does not have spot market authority over these markets outside of outright fraud and related derivatives products. For another, the SEC had never previously issued formal rulemakings outlining how it would oversee crypto-related securities products, and many leaders in the sector were panicked by former Chair Gary Gensler’s effort to corral crypto spot trading platforms into an existing securities regulation framework. There is also no explicit authority delineating where the SEC’s authority ends and the CFTC’s authority begins.
In the absence of this legislation, the agencies began to lay out how they view the crypto markets in joint advisories published earlier this year, but a crypto market structure bill could sort out all of these issues in a much more legally tangible — not to mention durable — way.
The ethics provision
It’s difficult to say whether the Clarity Act vote failed solely due to the controversial section that sought to limit senior government officials — namely, Trump — from personal crypto ties, but ethics concerns hung over the bill throughout its conception and development and remain one of the dominant talking points around this entire debate.
Democrat concerns about President Donald Trump’s crypto business ties stretch back to 2025. In May of last year, Sen. Ruben Gallego and eight other Democrats said they would not vote for the GENIUS Act because of how Trump was profiting off the sector. Ultimately, those lawmakers did vote for the bill with marginal changes, but it was always clear that the Trump family’s crypto dealings — which include World Liberty Financial, the $TRUMP memecoin and mining firm American Bitcoin — would weigh on future market structure discussions. At the time, Trump told “Meet the Press” that he was “not profiting from anything … I want crypto because a lot of people, you know millions of people want it.” More recently, in his June financial disclosure, he admitted to making $1.4 billion from his various crypto ventures during his first year back in office — more than half of the $2.2 billion total he raked in in 2025.
The goal for Democrats was to restrain Trump from so blatantly profiting off of the crypto sector, which had in turn poured millions into the president’s 2024 campaign, inaugural balls, a ballroom to replace the demolished White House East Wing, a military parade and his political action committee.
While the goal of the ethics provision has been described as generically applying to all present and future presidents and senior government officials, it’s specifically Trump’s crypto business ties that have alarmed Democrats. These concerns have been consistent since Trump’s return to office last year, multiple people said, with one person saying the Democrats writ large “actually care about this stuff.”
The crypto industry should not have been surprised by the conviction Democrats had on the ethics piece, this person said.
In May, Sen. Kirsten Gillibrand, a longtime crypto champion who has cosponsored multiple bills addressing the sector, told CoinDesk’s Consensus 2026 attendees that the bill would not advance without an ethics provision. Similarly, Sen. Angela Alsobrooks, who voted for the bill during a hearing in the Senate Banking Committee, said at the time that she would not vote for further advancement without additional work.
Even industry participants expected a clear deal on the ethics provision before a floor vote — so-called because it takes place on the Senate floor, with all 100 senators expected to participate. Cody Carbone, head of the Digital Chamber, told reporters after the Banking Committee advanced the bill in May that he expected “the deal will be completed before this goes to the floor, because they’ll want to only bring it to the floor if they feel confident they’ve got 60” votes.
Lawmakers from the two parties ultimately did not agree to any such deal. The White House and Senate Republicans published a few proposals; Senate Democrats sent counteroffers; and Sens. Thom Tillis and Gallego even pitched a bipartisan counterproposal earlier in the year. The three parties were unable to reach a consensus agreement prior to this month’s floor vote.
Multiple people pointed to Trump’s June financial disclosure as the event that really supercharged these concerns by giving politicians an easy-to-grasp headline figure in their push to force Trump to sell off his crypto holdings.
Those concerns only strengthened as the November election drew nearer.
“I think politics was very clearly elevated over policy,” said Stu Alderoty, the chief legal officer at Ripple Labs. “It was good policy, and the industry needs to get better at politics.”
Ron Hammond, the head of policy and advocacy at Wintermute, pointed to the fact that both Gallego and Alsobrooks ultimately voted against the bill on the floor as a sign of just how near the election is, and how that’s overshadowing everything else. Still others noted that Gillibrand, likewise, had voted against the procedural motion. Even sympathetic Democrats couldn’t risk being seen as soft on Trump’s corruption with an election around the corner.
Speaking at CoinDesk’s Policy & Regulation event last week, Rep. Ritchie Torres put the blame on Trump’s crypto activity.
“My personal opinion … even though the failure of Clarity had multiple causes, I am convinced that if it were not for Donald Trump, we likely could have seen both Democrats and Republicans get to yes,” he said. “Once the president issued his personal memecoin, that created a political problem for Democrats.”
Coinbase and the January delay
The industry’s involvement in the legislative process has also been under scrutiny. Last week, The Wall Street Journal reported that industry insiders laid some portion of the blame for the failed vote on Coinbase and its CEO Brian Armstrong, after Armstrong publicly withdrew support for the Senate Banking Committee’s version of the bill ahead of a key vote in January.
One of the key issues, Armstrong said, was that the version of the bill was problematic with how it treated stablecoin yield and rewards. The delay kicked off a months-long fight between the crypto and banking industries, while lawmakers sought to find a compromise. It’s not clear that other outstanding issues were debated much during the yield fight.
Industry figures and Sen. Cynthia Lummis rallied to Coinbase’s defense after the Journal’s report came out, but industry participants told CoinDesk they saw Armstrong’s tweet and the subsequent months-long fight over stablecoin yield and rewards as being harmful to the overall cause of getting Clarity passed.
One individual involved in crypto lobbying said if the ethics proposal released earlier this month had come out in the spring, it would have likely raised the odds of a successful vote.
Alderoty, the Ripple CLO, said in a phone call that there was “an opportunity in January” without the midterms to make further progress.
“The January timeframe would have given more airspace for negotiations without the midterms breathing down their necks,” Alderoty said.
Charley Cooper, the president and COO at Ava Labs, similarly told CoinDesk that the fact that the floor vote was held less than two months prior to election day made it difficult to see success.
The crypto industry felt a renewed sense of optimism after an ethics proposal was published earlier this month, which raised hopes that the overall bill could pass, he said. But, “we’re six weeks before election day in a heated midterm with a very divided electorate, very partisan fighting going on.”
To be clear: Nobody guaranteed that an earlier vote would have been successful. Many of the individuals who spoke to CoinDesk praised Armstrong and Coinbase generally for their involvement in the bill’s development. And, despite industry claims that the banking industry should have negotiated stablecoin yield issues during the GENIUS Act passage, one individual said that the Senate Banking Committee’s July 2025 discussion draft for market structure invited the debate by asking, “How should legislation address interest or yield-bearing digital assets, including stablecoins.”
If the ethics proposal released by Senate Republicans in early September had instead been released in the spring, the back-and-forth over the details may have been more fruitful, three people said, though others weren’t so sure, suggesting the political weight of the ethics debate was destined to hang over everything else — including the stablecoin yield question, disagreements over the risks of decentralized finance and others.
But the timing was bad.
Right after the Senate Banking Committee postponed its initial January hearing, the U.S. started its conflict with Iran, which caused fuel prices to spike and fanned the flames of an increasingly wonky global financial situation. Americans’ frustration over Trump’s foreign policy and the economy has seen Trump’s poll numbers sliding downward over the last few months. Meanwhile, progressive challengers won primary contests in Democrat elections, and the Democratic party as a whole is more afraid of alienating its base than the possible political fallout from voting for a crypto bill, multiple people said.
“Neither side was going to take a leap and do something big that could be claimed as a victory for the other side,” Cooper said. “So it doesn’t surprise me at all that it failed.”
The House bill
The timing problem is a byproduct of another thing multiple people took issue with: The fact that the Senate was working on its own homegrown bill to begin with. The House of Representatives passed its version of the Digital Asset Market Clarity Act with a massive 294-134 vote in July 2025; 78 Democrats supported the bill. The Senate largely ignored it to work on its own bill, originally named the Responsible Financial Innovation Act. (The Senate adopted the Clarity Act moniker later in the process.)
The Senate did something similar with the stablecoin-focused GENIUS Act — while the House had a bill, the Senate started its own version of the legislation, and that is the text that ultimately became law. Congressmen expressed their desire to see the Senate take up their version of the Clarity Act over the past year, but that didn’t happen.
“Clarity’s chances really faced an uphill battle when it came to the Senate decision not to take up the Clarity Act that passed the House as-is and [instead] just worked on their own,” Wintermute’s Hammond said.
A lot of the issues that bogged down the Senate bill in recent months just weren’t major considerations last year, he told CoinDesk in a phone call. The banking industry was not lobbying on stablecoin yield issues in the same way it had through most of 2026; political concerns were not as strong, and many of the interest groups had not had time to mobilize last fall.
Two other individuals said the House likely never expected the Senate to take up its bill, but the House had to pass it anyway. And when it drew more than two thirds support in the House, it showed the Senate there was plenty of bipartisan energy.
Rep. French Hill, who chairs the House Financial Services Committee, told CoinDesk in April that the Senate version of the bill did adapt some of the work the House did on its version of the Clarity Act and its predecessor, the Financial Innovation and Technology for the 21st Century Act.
Still, a further risk with the Senate launching its own version of Clarity is that the bill would have to go back to the House after successful Senate passage, and it’s unclear what would have happened at that point.
The House announced it would leave almost immediately after the Senate returned earlier this month, meaning that even if there had been a successful series of votes on Clarity, the House wouldn’t have voted on it until the lame duck session after the election. And even then, the House wouldn’t necessarily vote on the Senate bill as-is, one former House aide told CoinDesk.
Tim Ryan, a former Congressman who now advises a number of crypto companies, told CoinDesk through a spokesperson that the House would first need to understand how the Senate bill would impact its own version.
“A strong Senate agreement could have created real momentum for the House to act,” he said. “The deciding factors would have been the substance and whether House leaders could assemble the votes. The goal should be a workable law that gives people the confidence to build here.”
Negotiating tactics
Several individuals took issue with the negotiating process itself. While in years past, legislation may have been written by legislative staffers from both parties cramming into a room, this did not seem to happen.
Industry sources told CoinDesk that instead, Republican legislative staffers would draft something and share it with their Democrat counterparts. The Democrats would then share feedback, which could get incorporated into the next Republican draft. This would then be presented as a bipartisan effort.
But sometimes Republicans would include concessions on their own in the hopes of getting Democrats to say yes, two industry sources said, pointing to changes to the Blockchain Regulatory Certainty Act as one example.
A Democrat aide said that at times, negotiators would agree to some provisions, but their Republican counterparts would later backpedal.
And earlier this year, after Senate Republicans and the White House agreed to the first draft of an ethics provision, negotiators briefed the crypto industry on the details and began aggressively selling the language before sharing the proposal with Senate Democrats.
“I think Republican staffers f***** up the negotiation by not including Democratic staffers in the process,” one person said, adding that it gave Democrats leverage in the negotiations. “If you don’t say ‘we agree to this concession’ then you have the power in negotiations.”
Another person pointed to the announcement of the revised ethics proposal, which came from Sen. Lummis’s office, as a second example, saying it was “odd” that the press release was only signed by Republicans if it was meant to champion a bipartisan effort.
Punchbowl News reported details about the negotiations last week.
Multiple people also pointed to White House adviser Patrick Witt, who they all said seemed to want the bill to pass but didn’t necessarily have the experience needed to coordinate a bill as complex as Clarity. One person said Witt’s posts on X, suggesting breakthroughs or successful passage, were unhelpful, as they may have changed industry expectations. Witt declined to speak with CoinDesk at a Georgetown event last week.
Two legislative aides and an industry participant told CoinDesk that a final, last-ditch negotiation spearheaded by Sen. Tillis, as the procedural vote began on Sept. 15 led to the idea of allowing the entire Senate to vote on the Tillis-Gallego ethics proposal as an amendment to the bill. One Democrat aide said the party was at the “one-yard line” on a successful procedural vote when the negotiation was shut down.
It was abruptly ended by a staffer for Senate Banking Committee Chairman Tim Scott, several people told CoinDesk. Sens. Gallego and Chuck Schumer said in press statements that there was a bipartisan deal in the works but it was “killed.”
Crypto in America’s Eleanor Terrett first reported that a staffer for Scott ended negotiations.
A source familiar with the discussions told CoinDesk that the staffer had specifically told his own team to leave the negotiation, and the White House and Senate Agriculture Committee Republican staff were not present at this meeting. Republicans had already rejected the previous counterproposal sent by Senate Democrats late the night before, and formal talks had already ended. The staffer didn’t see the talking as an active negotiation because the process had already been closed, and he disputed that he halted progress at that point, the source said.
An industry participant said during the vote that Tillis and the Republican staffers negotiating were doing so without the support of their leadership. Another person, the Democrat aide, said Republican leadership had undermined Tillis and Lummis after the two had essentially secured a deal. The industry participant said that the parties had reached an agreement on some provisions but needed details on paper.
The industry’s own approach to negotiations likewise drew scrutiny; one person said the Clarity fight did eventually see the majority of the crypto industry align on at least the crypto-specific portions of the bill. But there were steps the overall industry could have taken that would have better served its cause, another person said, such as getting better at providing real-world use cases for merchants or other constituents. The industry just focused on hypotheticals, at least in Washington.
Industry leaders could have done more to encourage bipartisan negotiations, one aide said.
The upcoming midterm
2026 is a midterm election. Earlier this year, the general consensus was that the House of Representatives would likely flip control from Republicans to Democrats, while the Senate would remain under Republican control.
Many people said this means Democrats could not give Trump “a win” ahead of the election, particularly when, as noted, progressives tend not to vote for crypto.
Sen. Bill Hagerty told audiences at a Georgetown University event last Wednesday that he had warned his colleagues that the closer the negotiations got to Nov. 3, the lower the chances of any sort of passage, though he said the Senate could take up the legislation again after the election.
“It’s sad, but it’s the political reality,” he said. He told CoinDesk that there may be room for continuing negotiations on some of the provisions.
“My Democratic colleagues, this close to the election, couldn’t resist playing politics,” he said. “Is there room to do more fine-tuning? Perhaps.”
The future of Fairshake
One major question raised by the failure of the vote: What will happen to the crypto political action committees? Fairshake, the biggest crypto super PAC, has already announced a $30 million spend against former Sen. Sherrod Brown, who is challenging Ohio Sen. John Husted in a bid to return to the Senate. Brown, who chaired the Senate Banking Committee when he was last in the Senate, had criticized the crypto sector and opposed bringing any legislation for a committee hearing when he was in office, but hadn’t said much about crypto during this most recent campaign.
Neither party saw much political risk in failing to pass Clarity, said Wisdomtree Chief Legal Officer Ryan Louvar.
Whether Fairshake or the other PACs can even affect the overall trajectory of the 2026 election is a mystery. Recent polls suggest that Democrats will pick up a number of seats in the House of Representatives, and several Senate races are likewise competitive. The PACs throwing in with the Republican party exclusively, were that to happen, would reflect badly on the crypto industry if Democrats do regain power in at least one chamber of Congress, or if they win the presidency in 2028.
Fairshake was not built for a “wave” election, one person said. And the PAC has already had two high-profile misfires. Fairshake opposed Illinois Lieutenant Governor Juliana Stratton’s Senate bid to the tune of $10 million; Stratton won anyway and is almost certainly going to win the general election.
And the PACs have to maintain a delicate balance, this person said. They cannot risk a complete break from Democrats.
Another person said it was unclear whether the threat of Fairshake was ineffective in getting Clarity done or if Democrats just chose to run out the clock on 2026 in a strategic effort to avoid facing multimillion-dollar ad spends against them.
The elusive crypto voter
A Democrat aide said the crypto industry cannot just assume that a future administration or legislature would be fully bipartisan and on board with crypto bills, rather than the political pendulum swinging away from complete Republican control following the current term. For the PACs to essentially do what Republicans hope and direct funds against Democrats because of this month’s vote would risk alienating necessary political allies.
Another issue with the PACs like Fairshake is the lack of supporting infrastructure in Washington, D.C., a former legislative staffer said.
The industry can tell lawmakers that tens of millions of Americans own crypto, but without constituents demonstrating why this matters for them, elected officials won’t care, this person said. Even worse, lawmakers may question these claims if they go back to their home districts and don’t hear any of their constituents discuss crypto.
Alderoty, who also heads up the Ripple-backed National Cryptocurrency Association, said the organization estimated that some 67 million Americans held crypto, but his organization could not convince any senators to sit down with holders to talk about their use cases.
And it’s true that crypto just isn’t a major issue for voters. In a CoinDesk-commissioned survey of 1,000 registered voters across the country, just 1% described crypto as a top concern. The cost of living, jobs, the economy, Social Security and Medicare were all more important issues, respondents said.
And Democrat voters — both those who described themselves as leaning Democrat or as being strongly Democrat — had a more unfavorable view of crypto than a favorable one, further disincentivizing senators from acting on crypto. Independent voters also had a more unfavorable view of the sector.
Also, 62% of respondents said they did not trust Trump’s administration to oversee crypto.
Lessons
The future of the Clarity Act is unclear. Several individuals said that there are hopes of reviving the bill before the end of the year; however the election goes, a new Congress will be sworn into office in January, and any legislative process will have to start anew.
One industry participant said that it’s likely Democrats will come up with their own version of a crypto market structure bill, which will, at least, give the party a starting point to work from, even if that bill does not go anywhere on its own.
WisdomTree’s Louvar said it is helpful that crypto products are continuing to become more tangible. What’s even more helpful are tokenization or other blockchain-based products that aren’t strictly crypto. Even if lawmakers have a negative perception about cryptocurrencies, divorcing crypto from the underlying blockchain technology could demonstrate its use, he said.
In the absence of legislation, the SEC and CFTC are pushing out guidance and taking steps to try and fill in what gaps they can. However, the SEC Chair Paul Atkins has said repeatedly that a market structure bill is still needed to ensure that any missing authorities are granted.
“The crypto bill transformed into an ethics bill, and that was really unfortunate,” Ripple’s Alderoty said. “We lost a really good opportunity.”
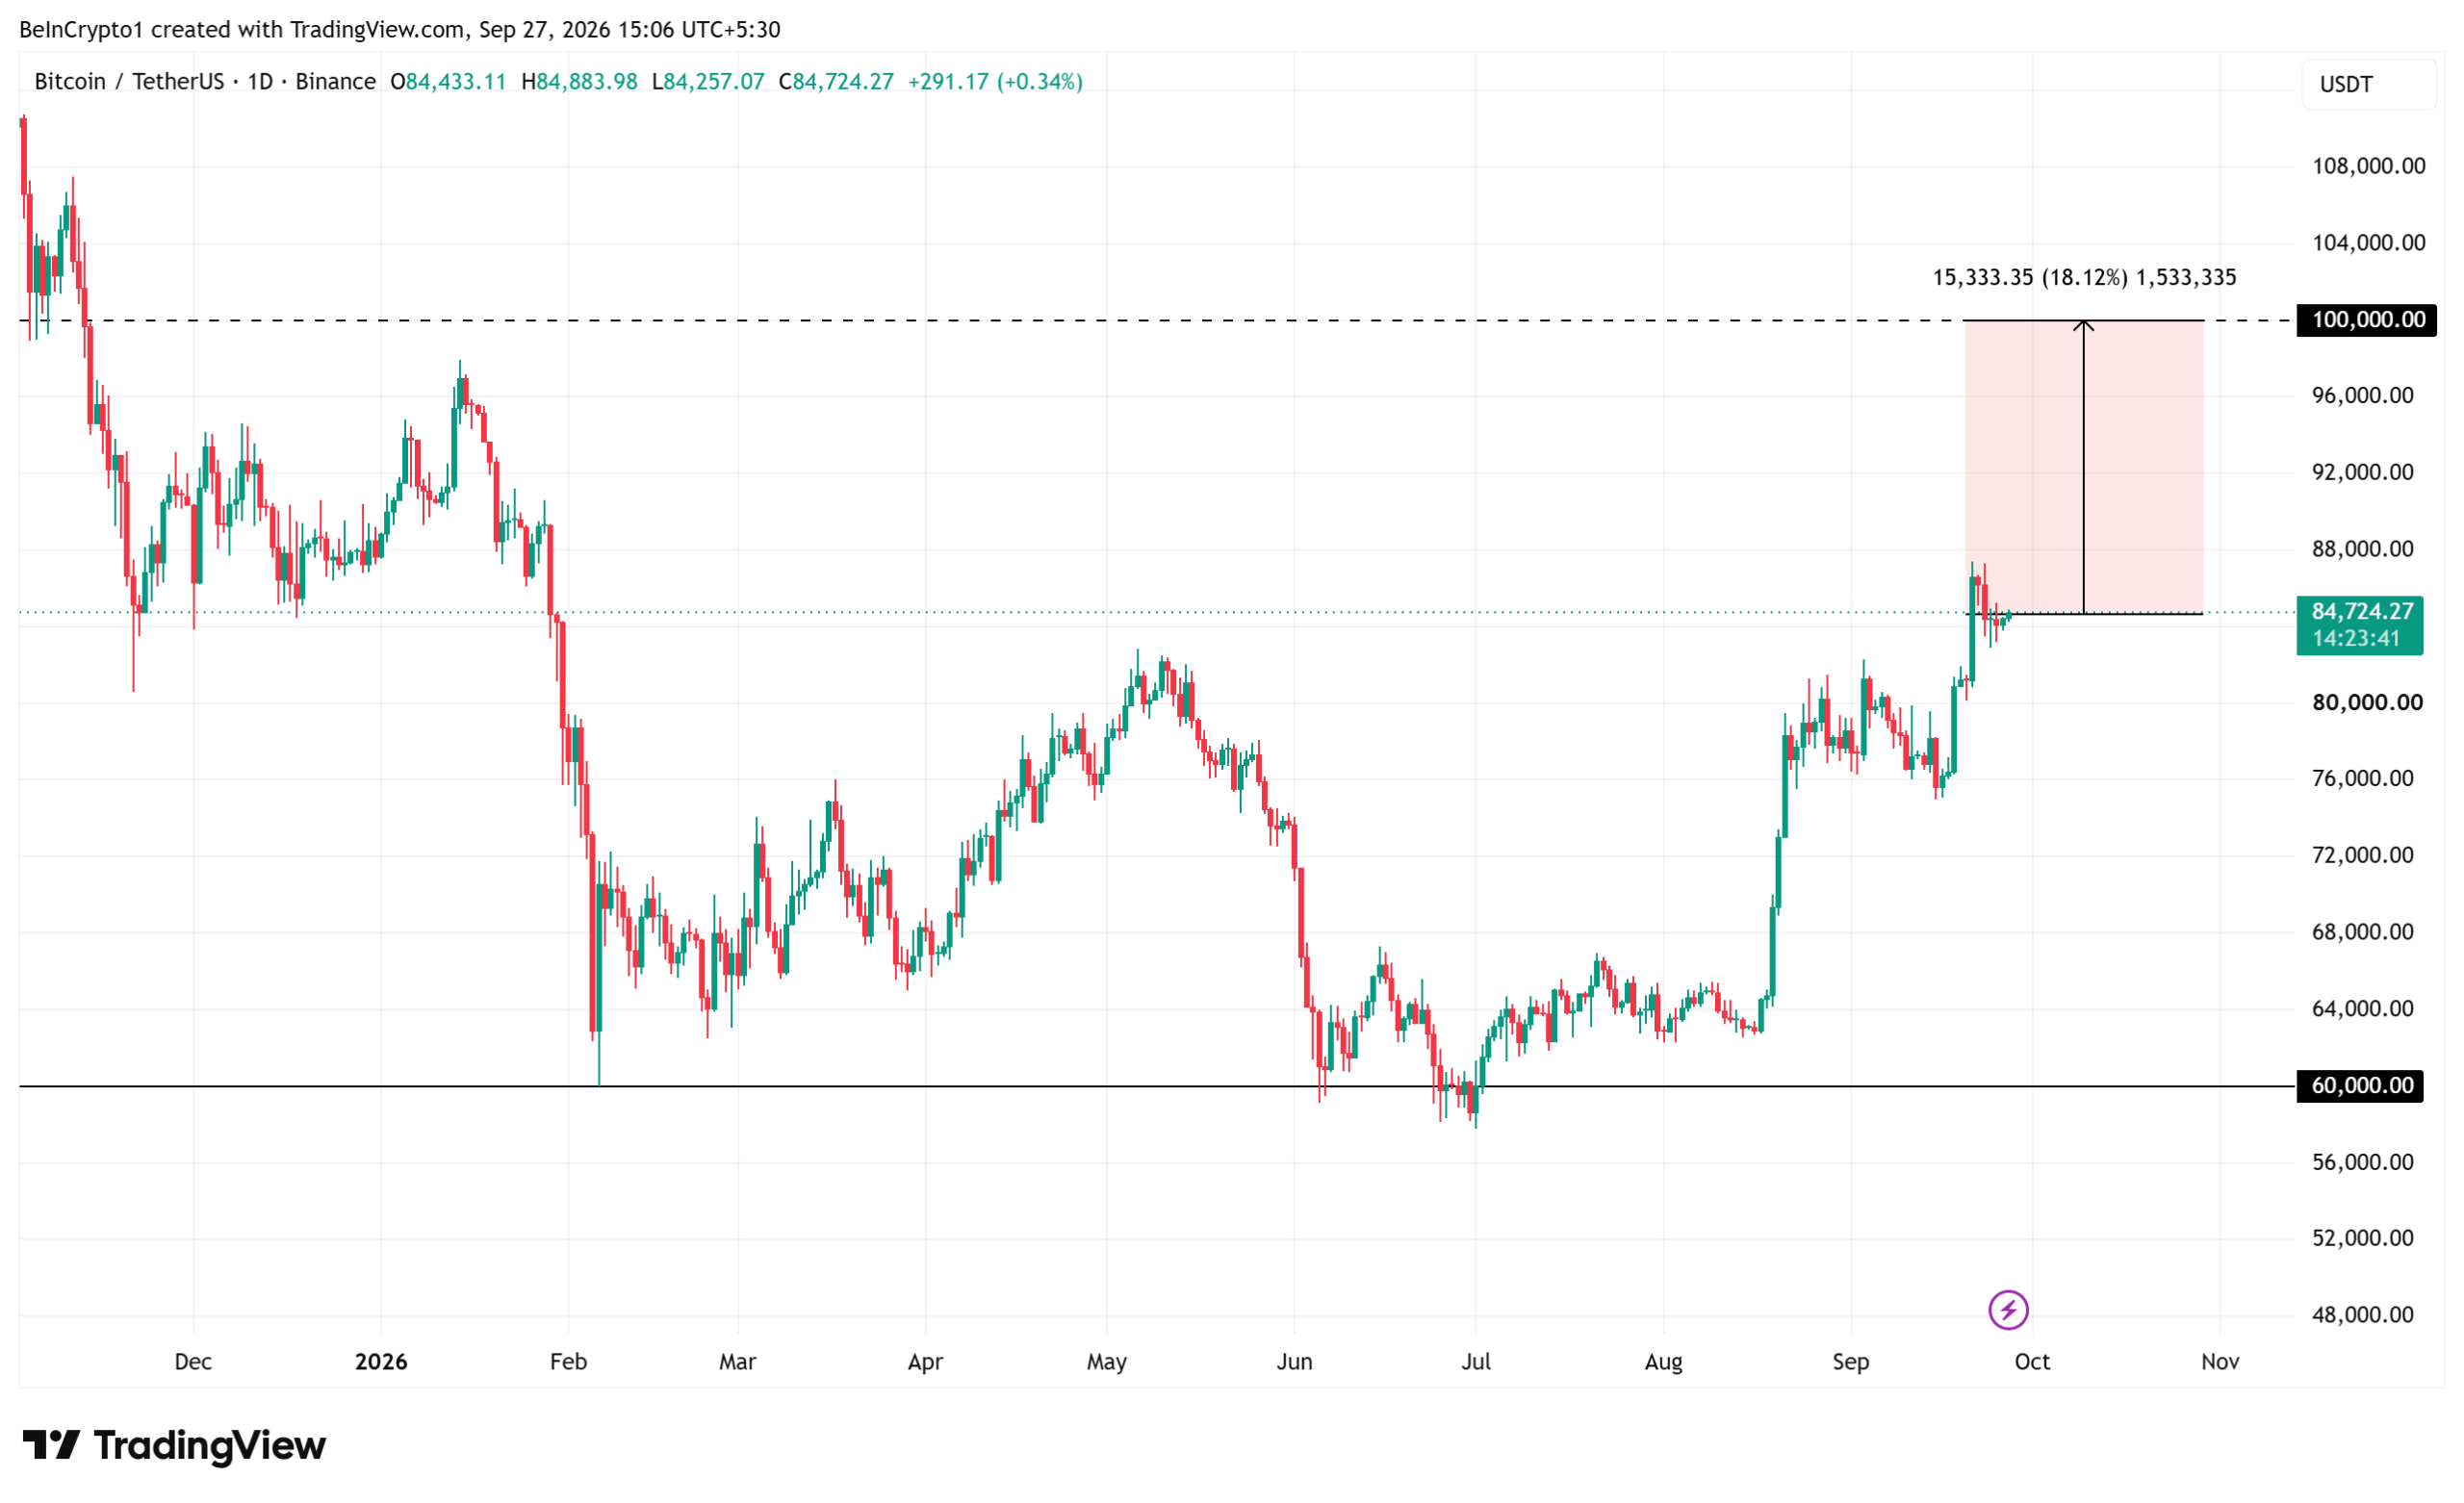
Bitcoin continues to hold above $80,000, the level Fidelity’s Jurrien Timmer says would confirm a bottom and open a path to $100,000.
Bitcoin (BTC) traded at $84,647 on Sunday, about 18% short of that target. Futures speculators, meanwhile, are adding to record bullish bets.

Bitcoin Breaks the $80,000 Level Fidelity Flagged
Timmer is director of global macro at Fidelity Investments, one of the largest US asset managers. He set out the trigger in a post, citing a double bottom chart pattern, where price hits a similar floor twice, then climbs.

“Bitcoin is looking particularly interesting here as it challenges key resistance at $80k. If it breaks it will confirm a double bottom targeting $100k,” Timmer wrote.
Timmer’s weekly chart marks this year’s lows at $60,033 in February and $57,742 in late June.
His charts use data through September 20. Since then, Bitcoin has crossed $80,000 and touched about $87,500 before easing.
Why Fidelity Sees $300,000 Bitcoin by 2029
Timmer also pointed to Bitcoin’s power law, a model that fits its long-run price to a curve over time. On that model, he says holding $60,000 signals a new bull market aimed at $300,000 in 2029.

“Bitcoin’s power law math continues to suggest that a new cyclical bull market is underway after holding $60k, targeting $300k in 2029,” the Fidelity executive added.
That marks a turn. In December, Timmer raised bear market concerns, warning of a possible drop to between $65,000 and $75,000. Bitcoin later fell further.
Can the Bitcoin Rally Hold?
Tom McClellan, editor of The McClellan Market Report, tracks the Commitments of Traders (COT) report. The US Commodity Futures Trading Commission (CFTC) publishes it weekly to show who holds futures positions.
McClellan says speculators such as hedge funds recently hit a record net long position. That means their bets on rising prices far outweigh bets on falling ones.

“What is unusual is that with the pop earlier this week, these traders actually were adding more longs instead of harvesting gains. That is a strong statement that they expect more gains to come,” McClellan wrote.
Other signals are mixed. In August, BeInCrypto flagged three warning signs, including weaker exchange-traded fund (ETF) flows and spot demand.
This month, BeInCrypto also reported CryptoQuant’s bull market line at $81,700, Bitcoin’s one-year average close. The current Bitcoin price sits about $3,000 above it.
That leaves a narrow cushion. A slip back under $80,000 would undo the break Timmer’s $100,000 target depends on.
The post Fidelity's $100,000 Bitcoin Signal Just Flashed appeared first on BeInCrypto.
Hester Peirce plans to leave the Securities and Exchange Commission on Oct. 2, leaving Chair Paul Atkins and Commissioner Mark Uyeda to handle a crypto offering proposal still open for comment. The agency can legally operate with two commissioners. Whether the two agree on what its final rules should say is the question her exit brings forward.
Summary
- Peirce plans to leave on Oct. 2, leaving 2 commissioners in office unless a replacement arrives.
- SEC rule 200.41 permits a quorum of 2 when only 2 commissioners hold office.
- A federal appeals court upheld an SEC decision issued by 2 commissioners in 1996.
- Comments on Regulation Crypto Assets are due Oct. 20, 18 days after Peirce’s planned exit.
- The SEC’s Sept. 17 stock trading exemption lasts 5 years under its published terms.
The Securities and Exchange Commission’s largest proposed crypto offering rule cannot be finalized before the public finishes commenting on it. That deadline is Oct. 20. Hester Peirce plans to leave the commission on Oct. 2, according to her resignation letter. Count the dates: the final 18 calendar days of public comment on Regulation Crypto Assets will arrive after the commissioner who led the agency’s Crypto Task Force has left.
That does not stop the proposal. Nor does it prevent a vote by the two commissioners expected to remain, Chair Paul Atkins and Mark Uyeda. The SEC’s own quorum rule permits the commissioners in office to constitute a quorum when fewer than three hold office. A federal appeals court upheld that arrangement in a case nearly 30 years ago. The question after Peirce leaves is less dramatic and more consequential: can Atkins and Uyeda agree on a final text after comments arrive, and who will carry the task force’s work to that decision?
Peirce has not been the only official shaping the agenda. Atkins chairs the commission and publicly supports the proposal. Uyeda helped launch the Crypto Task Force while serving as acting chair in January 2025 and has issued his own statement supporting the August proposal. The three have approved work together. From Oct. 2, if the membership remains as currently listed, there is no third vote available to resolve a disagreement between the two who remain.
The departure date moved forward, and the rulemaking did not
Peirce joined the SEC in 2018. The commission’s membership page currently lists her alongside Atkins and Uyeda and says her term expired in 2025; SEC commissioners may remain for a limited period after a term expires if they have not been replaced. She had previously indicated that she would join Regent University School of Law, leading earlier accounts to place her departure in November. Her subsequent resignation set Oct. 2 as the exit date. As of Sept. 27, the SEC’s membership and Crypto Task Force pages still identify her as serving. Their status should be checked again on the day she actually leaves.
The date corrects a point in our own archive. An earlier crypto.news feature on the SEC’s delayed crypto vote said she would depart in November and suggested that operating with two members would create an untested quorum problem. The new Oct. 2 date supersedes the earlier calendar. More significantly, the quorum claim needs correction: the rule expressly allows two sitting members to form a quorum, and a federal appeals court has already upheld its use. The risk of a divided two-person commission is real, but it is a voting and policy risk, not an automatic inability to meet.
The pending Regulation Crypto Assets docket, file S7-2026-27, gives this change an unusually clear measure. The SEC issued the proposal on Aug. 18. The Federal Register published it on Aug. 21. The docket lists Oct. 20 as the deadline for public comments. The proposed rule contains two tailored Securities Act registration exemptions for investment contracts involving crypto assets: one for up to $5 million over four years and another for up to $75 million in any 12-month period. It proposes a conditional route for an asset to cease being subject to an investment contract once promised essential managerial work has ended.
Those numbers are proposed limits, not permissions that an issuer can use today merely because the SEC published a draft. The SEC must review comments, decide whether to revise the draft and vote on a final rule before the new exemptions can operate. A material revision could require further notice and comment. An Oct. 20 deadline starts the next stage; it is not a deadline by which the commission must approve the measure.
Two commissioners are a lawful quorum, not an unprecedented experiment
The SEC ordinarily has five seats, and the standard quorum is three. Rule 200.41 contains an exception: when fewer than three commissioners are in office, the members who are in office constitute the quorum. The SEC’s listed membership as of Sept. 27 consists of three officials. If Peirce leaves Oct. 2 and no replacement takes office, Atkins and Uyeda would meet the text of that exception.
This is not merely an agency’s untested assertion about its own powers. In Falcon Trading Group v. SEC, 102 F.3d 579, the U.S. Court of Appeals for the District of Columbia Circuit considered a challenge to an SEC decision issued in December 1995 when only two commissioners held office. The petitioners argued that a five-seat commission could not act through two members. In December 1996, the court upheld the SEC’s quorum rule and the decision made under it.
The court reasoned that Congress had empowered the SEC to make rules needed to carry out its functions and had not imposed a conflicting statutory quorum. That is a direct precedent for the legitimacy of the two-member quorum. It concerned an enforcement-related administrative decision, not Regulation Crypto Assets or a final crypto rule. It therefore does not pre-approve the contents or procedure of any future crypto regulation. A party could still challenge a final rule on other statutory or administrative grounds.
The practical limit is arithmetic. Two commissioners voting yes can approve a measure that requires commission approval. If one supports a proposed final rule and the other opposes it, there is no third sitting member to make a majority. An abstention or recusal would raise a distinct procedural question that cannot be resolved by simply assuming the remaining official may act alone on every matter. Staff can continue preparing recommendations, receiving comments and administering existing rules while a commission vote is unavailable. The exact authority for a particular staff or delegated action depends on its own governing rule.
The finding changes how to read Peirce’s departure. Losing a commissioner reduces the number of decision makers and leaves less room to negotiate a contested final text. It does not switch off the SEC. The difference matters because a project deciding whether to submit a comment by Oct. 20 should not assume that its submission will go to an agency legally incapable of finishing the work.
The Crypto Task Force loses its named leader, not its entire staff
The SEC’s Crypto Task Force page still identifies Peirce as its leader. Uyeda announced its formation on Jan. 21, 2025, while serving as acting chair. He said then that the task force would coordinate work across SEC divisions and offices. The commission has since issued an interpretation, a proposed offering rule and relief for a specific tokenized stock trading model. They are agency actions or proposals, not personal orders signed by Peirce alone.
The agency has not, on its public task force page as of Sept. 27, identified a successor. That is a specific open question. Atkins could name a new commissioner or otherwise reorganize the work, subject to the powers available to the chair and the commission. The present record supports neither the assertion that the task force will close nor the claim that a named replacement has already taken over. Its channels for public submissions and meetings are still displayed on the SEC site.
Peirce’s role has nevertheless been distinctive. Her 2020 token safe harbor proposal argued that teams building decentralized networks should have time to develop before facing all the consequences of conventional securities registration. When the SEC proposed its new offering framework on Aug. 18, she described the proposed exemptions in her own statement. She has pressed the agency to write paths a project can follow instead of relying on individual enforcement cases to set the boundary. Removing her from the commission removes one participant in the final vote and one source of institutional memory about the arguments behind the draft.
It does not remove the work from everyone else. Uyeda’s statement on the same Aug. 18 proposal thanks staff in the divisions of Corporation Finance, Trading and Markets, Investment Management and Economic and Risk Analysis, along with the task force and other offices. Drafting, economic analysis, legal review and public comments run across that structure. A public announcement of who will lead the task force after Oct. 2 would reveal how the SEC intends to coordinate those people, but the people do not all depart with Peirce.
The unfinished rules are at different stages
Three frequently grouped SEC crypto measures have different legal statuses. Confusing them makes Peirce’s exit seem either more destructive or less important than it is.
First, the SEC’s March 17 interpretation of federal securities law has already been issued. It explains the commission’s view of how existing law applies to certain crypto assets and activities, including staking and wrapping. A change in personnel does not automatically withdraw it. An interpretation also lacks the same permanence as an act of Congress; future agency action or a court’s reading of the statute could change the operative guidance.
Second, Regulation Crypto Assets is a proposed rule. Its $5 million and $75 million offering paths remain drafts. The SEC’s docket gives the public until Oct. 20 to respond to file S7-2026-27. This is the measure whose next substantive steps will fall most clearly to the commission after Peirce’s departure. Its final content can change in response to comments on investor disclosures, investor eligibility, state-law treatment and the conditions under which an investment contract ends.
Third, the SEC issued a temporary innovation exemption on Sept. 17 for a defined model of trading tokenized National Market System stocks on permissioned automated market maker venues. Crypto.news covered the five-year exemption when it was issued. Its published conditions include limits on symbols and volume, equivalent shareholder rights and coordination with trading halts in the underlying stock. The order says the exemption is set to expire five years after publication and requests comments on possible changes. Peirce leaving does not erase relief already granted. Whether the agency modifies, replaces or extends the arrangement later is a separate choice.
There is another pipeline item relevant to tokenization: the SEC’s September transfer agent proposal would update recordkeeping and other obligations for the firms responsible for shareholder registers, including the use of newer technology. Crypto.news reported on the proposed overhaul when it appeared. Like Regulation Crypto Assets, it is not final law. A tokenized stock trading exemption and a transfer agent proposal address different parts of the securities market, so neither substitutes for the other.
The transfer agent docket supplies a second test of the new commission’s capacity. Its comment deadline is Nov. 3, more than a month after Peirce’s planned departure. Unlike the offering proposal, this rule reaches ordinary securities infrastructure as well as digital assets: transfer agents track changes in legal ownership, maintain records and perform services for issuers. Changes to the register matter for a company whose shares are recorded using blockchain technology because an investor’s token and the legally recognized shareholder entry need a dependable connection. A trading exemption cannot fill a gap in ownership records. Staff will have to weigh comments on operational controls, costs and the relationship between electronic records and existing transfer-agent duties before commissioners decide whether to adopt a final rule.
Put the dates in sequence. Oct. 2 removes one commissioner if her resignation takes effect as announced. Oct. 20 closes comments on crypto offering exemptions. Nov. 3 closes comments on the transfer-agent proposal. The first two dates are 18 days apart; the latter deadline falls 32 days after the departure date. Neither docket says a final vote follows the next morning. Both may require revision, legal review and an explanation of why the agency chose one approach over alternatives raised in the record.
The stage of each measure is the first practical filter. An interpretation stays in place unless changed or superseded. A temporary order operates under its conditions and expiry. A proposed rule still needs the commission to finish notice and comment, consider the record and approve a final version. Peirce’s exit changes the voters for the last task; it does not reset every item to zero.
The final vote belongs to Atkins and Uyeda if no one else joins
The strongest case against a narrative of paralysis comes from the two officials expected to remain. Atkins proposed the crypto offering package as chair, saying the commission wanted tailored pathways for raising capital while Congress considered a longer-lasting market framework. Uyeda, who formed the Crypto Task Force, supported advancing the proposal. They have shared public positions on the direction of the SEC’s crypto work. If those positions continue through the public comment process, a two-member commission can approve a final rule without Peirce.
The opposing case is not that the rule is unpopular. It is that support for a proposal does not commit either commissioner to every detail of a final text. The agency could receive objections to how an exemption treats disclosures, a $75 million annual fundraising ceiling or the proposed separation of a crypto asset from an investment contract. One commissioner could decide that a revised version gives too little investor protection, while another could view additional conditions as defeating the point of the safe harbor. With three members, an internal disagreement might still yield two votes. With two, it cannot.
This is an inference about incentives and arithmetic, not a reported disagreement between Atkins and Uyeda. Their Aug. 18 statements show support for issuing the draft. They do not reveal how either will vote after comments are analyzed. Public records matter more than assumptions about party affiliation: even commissioners who agree on the objective can disagree on a sentence that determines who is exempt.
The task force’s public consultations may become more significant under that constraint. The SEC can respond to a well-supported objection by changing a provision before seeking a final vote. A measured change that satisfies both commissioners can move the file forward. A change one regards as essential and the other rejects could stall it. The public comment docket will expose some of that pressure, although internal negotiations need not be public.
The Senate can change the membership by confirming nominees if the president puts names forward. The SEC is designed for up to five commissioners, with no more than three from the same political party, according to the agency’s membership page. The current public roster names Atkins, Uyeda and Peirce, not an incoming replacement. A future appointment is possible, but the article cannot assign a date or presume it will happen before the proposal reaches a final vote.
Peirce’s last work illustrates what can move without a new rule
On Sept. 25, SEC Corporation Finance staff published questions and answers on the March interpretation. They address, among other things, staking receipt tokens, representations about managerial effort and when a token associated with a functioning network might be treated differently from an investment contract. The document is staff guidance about an existing commission interpretation. It is not Regulation Crypto Assets finalized in miniature.
That distinction illustrates what continues when the commission has only two members. Staff can explain an existing interpretation and answer questions within their authority. Staff guidance does not create a new statutory exemption or bind a future commission in the way a duly adopted rule might. Someone designing a crypto offering cannot substitute the Sept. 25 FAQ for the conditions and effective date of a future Regulation Crypto Assets rule.
Peirce’s public Sept. 23 remarks to a securities industry conference show why she thought these lines mattered. As more assets, intermediaries and uses enter the category, the SEC must identify the transactions that fall within securities law and avoid treating every technological arrangement as the same instrument. Her view has shaped the discussion, but a speech remains a commissioner’s perspective. The agency’s published releases and orders identify what it has formally done.
That division of labor will remain after Oct. 2. The chair can speak for his program, divisions can publish staff guidance where authorized, the task force can gather input if it continues, and the commission can vote on action requiring commission approval. None of these acts is interchangeable. Crypto.news traced the rulemaking underway after the CLARITY Act vote, but the SEC’s interpretation, proposal and exemption each demand a separate test of what changed. Readers trying to judge whether the crypto rulebook is actually changing should look at the document’s legal form as closely as its headline.
The comment record will test the rule’s limits
The most important work between an Oct. 20 deadline and any vote is sorting the objections by the provision they address. The $5 million pathway and the $75 million pathway solve different financing problems. A smaller issuer may care most about the cost of preparing disclosures across a four-year period; a larger issuer may care about whether a 12-month cap can accommodate a capital raise without ordinary registration. If comments show that either exemption can be divided into successive offerings to evade its limits, staff would have to decide whether to propose an aggregation rule or recommend rejecting that approach. Those are examples of questions the final record could raise, not defects the SEC has already found.
The proposed route for separating a crypto asset from an investment contract creates another choice. Its practical value depends on how an issuer demonstrates that promised essential managerial efforts have ended and what happens if a promoter later resumes them. Commenters can ask for clear evidence, time periods and disclosure duties. The commissioners then must decide whether a workable test can be written under existing securities law. A final release that merely repeats the proposed aspiration would give firms and courts less to apply than a release that explains how it handled competing examples in the comments.
Public comments do not amount to a referendum. The SEC need not adopt the position with the most submissions, and submitting a comment does not give the writer a vote. The agency does need a reasoned basis for its final choices and must operate within the authority Congress gave it. If it makes a substantial change that people had no fair opportunity to address, a further round of public comment may be needed. That possibility makes the Oct. 20 date a checkpoint in the process rather than a finish line.
For a reader following the rule, the useful comparison is concrete: line up the proposed exemption conditions with the final adopting release and its response to significant objections. The text will show who qualifies, what an issuer must disclose, when the limits reset and when a token’s treatment can change. The accompanying explanation will show whether Atkins and Uyeda reached the same account of investor protection and market access. A final rule adopted with both votes would settle their immediate disagreement on that text; it would not settle every court challenge or bind Congress from changing the law.
What the exit does not decide
Peirce’s departure will not itself determine whether a token is a security, whether the proposed safe harbor becomes final or whether Congress passes a digital asset market structure law. Those questions are governed by legal texts and future decisions. The SEC can act only within its statutory authority, and the pending congressional debate concerns powers an agency cannot simply give itself.
Nor does Falcon Trading guarantee that every action approved by two commissioners will survive litigation. It validates the SEC’s reduced quorum under the circumstances before that court. A new rule could still be challenged for its substance, the scope of its exemption, its treatment of comments or procedural defects unrelated to headcount. Conversely, saying the two-member commission is inherently invalid ignores a directly relevant court decision.
This article cannot name Peirce’s successor at the Crypto Task Force because the SEC’s public page still lists her as leader as of Sept. 27. It cannot say how Atkins or Uyeda will vote on a final rule because the comment period remains open. It can identify the next documents that will answer those questions: a revised task force leadership page or announcement, the comment docket after Oct. 20, a final adopting release and the votes recorded for it.
The timetable is plain. Peirce’s stated exit is Oct. 2. Public comments on the flagship proposal close Oct. 20. The gap is 18 days. Under the current rule and precedent, Atkins and Uyeda can act as the commission if no replacement arrives; each would then be indispensable to a contested final crypto rule. Nothing in the SEC’s docket promises that the final vote will occur in October or even in 2026.
What to watch
- Oct. 2 membership. Check whether Peirce leaves as announced and whether the SEC names another commissioner.
- Task force leadership. A new SEC designation would identify who coordinates the work Peirce led.
- Oct. 20 comments. File S7-2026-27 will show objections to the proposed offering caps, disclosures and safe harbor.
- A revised proposal or final vote. Either filing would reveal whether Atkins and Uyeda agree on the rule’s terms.
- Commission votes. The SEC publishes votes on rules and orders, allowing readers to distinguish a unanimous decision from an unresolved proposal.
FAQ
When is Hester Peirce leaving the SEC?
Peirce has set Oct. 2, 2026, as her departure date, according to reporting on her resignation letter. As of Sept. 27, the SEC’s public membership page still lists her as a commissioner.
Who would be left on the SEC commission?
If no replacement takes office, Chair Paul Atkins and Commissioner Mark Uyeda would be the two members in office after Peirce leaves. The agency is designed to have up to five commissioners.
Can the SEC operate with two commissioners?
Yes. SEC rule 200.41 says that when fewer than three commissioners are in office, the members in office form a quorum. A federal appeals court upheld an SEC decision made by two commissioners in 1996.
Can two commissioners approve a crypto rule?
The reduced quorum can conduct commission business, and two commissioners voting in favor could approve a measure requiring commission action. If the two split on its final terms, neither has a third vote to settle the disagreement.
Is Regulation Crypto Assets already in force?
No. The SEC issued it as a proposal on Aug. 18, 2026, under file S7-2026-27. The proposed $5 million and $75 million exemptions would require further agency action to become operative.
When do comments on the crypto proposal close?
The SEC docket lists Oct. 20, 2026, as the deadline. That is 18 calendar days after Peirce’s announced Oct. 2 exit, and it is not a promised date for a final rule.
Does Peirce’s exit cancel the tokenized stock exemption?
No. The SEC issued temporary, conditional relief on Sept. 17 for a particular tokenized stock trading model. Its published terms say it expires five years after publication, subject to future agency action.
Who will lead the SEC Crypto Task Force next?
The SEC’s public task force page still names Peirce as leader as of Sept. 27, and it has not identified a successor there. A later agency announcement may answer that question. This is educational analysis, not investment advice.
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Figures reflect regulatory filings and reporting available at the time of writing and change with each disclosure. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 27, 2026.
U.S. spot Bitcoin ETFs have attracted about $5.3 billion since the Treasury announced larger long-dated bond buybacks, according to ETF analyst Nate Geraci.
Summary
- $5.3 billion entered spot Bitcoin ETFs after Treasury announced larger long-dated bond buybacks in August.
- $2.4 billion flowed into U.S. Bitcoin ETFs during the week ending September 25 alone overall.
- $999 million entered the funds Monday, ranking as their ninth-largest daily inflow since launch historically.
- Bitcoin ETF flows turned positive for 2026 after reaching a $5.8 billion deficit during July.
- BlackRock’s IBIT led last week with approximately $1.2 billion in net inflows, market data shows.
Geraci said on Sept. 26 that the funds collected $2.4 billion during the latest week alone, while Monday’s roughly $1 billion intake ranked as the ninth-largest single-day inflow since U.S. spot Bitcoin ETFs launched in January 2024.
The rebound has pushed 2026 flows back into positive territory after the group sat nearly $5.8 billion in the red during July. Market data puts year-to-date net inflows near $934 million after the latest five-session run.
Bitcoin ETF inflows reach $5.3 billion since Treasury announcement
The U.S. Treasury announced on Aug. 19 that it would increase the maximum size of liquidity-support buybacks involving longer-dated nominal Treasury securities.
Operations covering the 10-to-20-year and 20-to-30-year sectors were raised from a maximum $2 billion to at least $4 billion each. The larger operations took effect Sept. 9 and are scheduled to remain in place through Nov. 4.
Geraci linked the timing of the ETF recovery to that policy announcement. His calculation puts cumulative spot Bitcoin ETF inflows since then at approximately $5.3 billion.
The figure describes two developments that occurred over the same period. It does not by itself establish that Treasury buybacks caused investors to allocate money to Bitcoin funds.
Treasury said the larger operations were intended to provide more liquidity in long-dated government bond markets. It cited consistently strong offers from market participants in those sectors as the reason for increasing the transaction sizes.
Treasury buyback program, the Aug. 19 announcement coincided with falling long-term yields and stronger risk-asset prices. The report noted that the 30-year Treasury yield declined after reaching a 19-year high.
Geraci’s observation focuses on ETF flows since the announcement date, while Treasury’s larger transactions themselves did not begin until Sept. 9.
Bitcoin ETFs collect $2.39 billion in one week
The strongest part of the ETF recovery came during the Sept. 21–25 trading week. U.S. spot Bitcoin funds drew approximately $2.39 billion over five consecutive positive sessions, according to Farside Investors data compiled by crypto.news. Monday generated about $999 million, followed by $714.7 million Tuesday and $346.9 million Wednesday.
Thursday added $190.7 million before another $134.5 million arrived Friday. The five sessions produced the largest weekly total since October 2025.
As crypto.news reported on the weekly ETF flows, BlackRock’s iShares Bitcoin Trust led the period with approximately $1.16 billion. Fidelity’s FBTC attracted $701.6 million, while ARK 21Shares’ ARKB added $294.7 million.
Morgan Stanley’s MSBT received another $203.3 million during the week, its largest weekly intake since the fund launched in April.
Monday’s $999 million intake was the strongest daily total of 2026 and the ninth-largest single-day inflow recorded by U.S. spot Bitcoin ETFs since their launch, according to SoSoValue figures cited by The Block. The pace slowed during each subsequent session, but the funds remained positive through Friday.
2026 ETF flows recover from a $5.8 billion deficit
The latest subscriptions reversed a much weaker first seven months of the year. U.S. Bitcoin ETFs were roughly $5.8 billion underwater on a year-to-date basis around July 13. The latest weekly inflows brought 2026 net flows to approximately $934 million above zero.
Separate Farside-based calculations put the year-to-date low near negative $5.69 billion. By Sept. 22, ETF flows had turned positive for the first time since May 26.
The funds have now collected approximately $57.6 billion in cumulative net inflows since their January 2024 launch, while total net assets stood near $108.4 billion at the end of Friday.
The turnaround did not occur in a straight line. During the Sept. 14–18 week, Bitcoin funds finished with only about $6.1 million in net inflows after losing a combined $746.3 million on Tuesday and Wednesday. Friday’s $433 million inflow erased most of that decline.
As crypto.news reported after the Federal Reserve meeting, flows changed direction on Sept. 17 with $159.5 million entering the funds. Another $433 million arrived the following session before demand accelerated the next Monday.
Bitcoin holds near $84,000 after ETF demand rises
Bitcoin’s price rose sharply during the ETF inflow streak before giving back part of the advance. BTC moved above $87,000 early in the week, reaching roughly $87,363 before retreating toward $84,000 by Sept. 26. Crypto.news put Bitcoin near $84,008 on Binance early Friday. The cryptocurrency remained up around 3.8% over seven days, while the total crypto market value stood close to $2.98 trillion.
In related coverage, crypto.news reported that the rally began alongside stronger ETF demand, with $999 million entering Bitcoin funds Sept. 21 and $714.7 million following a day later. Futures traders added more than $2 billion in open positions over the same period. Bitcoin subsequently pulled back despite continued ETF subscriptions. Crypto.news reported on Sept. 25 that funds remained in a six-session inflow streak even as BTC consolidated near $84,000.
Sell orders were concentrated between roughly $85,000 and $85,800 on Sept. 26, while the four-hour Supertrend indicator stood near $86,435. Bitcoin remained above its daily 20-period midpoint after retreating from the weekly peak.
Treasury buyback schedule runs through November 4
The Treasury’s expanded long-end buyback program remains scheduled through the current quarterly refunding period.
Under the Aug. 19 announcement, each operation in the targeted long-duration sectors can reach at least $4 billion, double the prior $2 billion maximum. Treasury said it would provide information on future buyback sizes during its next Quarterly Refunding on Nov. 4.
The department described the transactions as liquidity-support operations for older Treasury securities, not monetary stimulus or purchases conducted by the Federal Reserve.
Geraci’s $5.3 billion ETF calculation uses the Treasury announcement as the starting date for measuring Bitcoin fund flows. Bloomberg ETF analyst Eric Balchunas separately pointed to the same period while discussing the ETF rebound, according to The Block.
Friday’s $134.5 million intake extended the Bitcoin ETF inflow streak to seven trading sessions. The run beginning Sept. 17 accumulated approximately $3 billion before markets closed for the weekend.
GIWA has rejected claims that its mainnet RPC was leaked, saying the Ethereum Layer 2 network has not launched its mainnet.
Summary
- GIWA says its mainnet remains unlaunched, ruling out any leak involving a live mainnet RPC.
- Official documentation lists only GIWA Sepolia testnet RPC endpoints while mainnet infrastructure remains under development.
- GIWA runs on the OP Stack and uses Ethereum as the settlement layer for transactions.
- GIWA Wallet and stablecoin ecosystem products remain labeled Coming Soon on the project website currently.
- Upbit partnered with Optimism to build GIWA under a self-managed OP Enterprise infrastructure model earlier.
The project said on X on Sept. 27 that a mainnet RPC leak was impossible because no mainnet has gone live. GIWA told users to “DYOR” and remain alert to false information and scams circulating before launch.
Official GIWA documentation supports the main point of the clarification. The network’s mainnet section remains marked as under development, while GIWA Sepolia is available as a public test environment.
GIWA mainnet remains under development
GIWA’s connection documentation does not provide a mainnet RPC endpoint. Instead, developers can access the GIWA Sepolia testnet through sepolia-rpc.giwa.io, while a separate Flashblocks test endpoint is available for faster transaction preconfirmation.
Both endpoints are rate limited and intended for development and testing, according to the project’s network guide. GIWA specifically says its mainnet is “currently under development.”
The same distinction appears in GIWA’s smart contract documentation. Its contracts page lists deployed contracts for the Sepolia testnet but leaves the mainnet section marked as under development.
A separate Flashblocks document identifies a working testnet endpoint while listing the corresponding mainnet endpoint as “Coming soon.”
The available documentation therefore supports GIWA’s statement that a public test network exists while the production network has yet to launch.
The clarification follows social-media claims involving what was described as a leaked mainnet RPC. GIWA did not identify the accounts or URLs behind those claims in the statement supplied for this report.
No evidence provided by GIWA indicates that its Sepolia testnet RPC was compromised. The project’s response specifically addresses claims involving the unlaunched mainnet.
GIWA uses OP Stack for its Ethereum Layer 2
GIWA is an Ethereum Layer 2 built with the OP Stack, the open-source software framework maintained within the Optimism ecosystem.
Its technical documentation describes a one-second block time and compatibility with Ethereum Virtual Machine development tools. Developers can deploy Solidity contracts using tools already common in Ethereum development.
The network uses a sequencer for block production, while Ethereum provides the Layer 1 environment underlying GIWA’s settlement architecture. The current design specifies a 60 million block gas limit and one-second block intervals.
Unlike some Layer 2 networks, GIWA does not currently advertise a separate native token. Its FAQ says ETH is used as the base asset and for transaction fees, while stablecoin-based fee payments may be supported later through a Paymaster system.
Upbit’s involvement became public earlier in 2026. Upbit partnered with Optimism to build GIWA using the OP Stack under the Self Managed OP Enterprise tier.
The arrangement allows Upbit to manage its own infrastructure while receiving technical support and failover services from Optimism, according to the report. Sequencer control gives the operator responsibility for ordering transactions on the network.
GIWA’s own documentation describes the chain as “Powered by Upbit” and positions it as infrastructure linking users, developers and liquidity to Web3 applications.
GIWA Wallet and stablecoin products remain unfinished
GIWA’s public website shows that several planned products have not yet entered general release. The official site lists GIWA Wallet as “Coming Soon.” It describes the wallet as a self-custody product designed for GIWA Chain with multichain support and integrated views of exchange assets.
A planned stablecoin ecosystem carries the same status. GIWA says it intends to support stablecoin payments involving Korean won and global stablecoins, including Paymaster infrastructure that could allow stablecoins to cover transaction fees.
The project currently directs developers toward its testnet instead. Test ETH is available through a faucet, and developers can use GIWA Sepolia for smart contracts, wallet integrations and other testing before production deployment.
GIWA’s smart contract development guide supports Foundry, Hardhat and Remix IDE. Applications can use Solidity or other EVM-compatible tools because the network follows Ethereum’s execution environment.
The node documentation provides a similar test-focused setup. Developers can run their own GIWA node or use the free Sepolia RPC endpoint, while the project recommends external node services for future production workloads.
Upbit continues building around blockchain infrastructure
GIWA forms one part of Upbit operator Dunamu’s efforts to expand beyond centralized exchange trading.
The project’s website describes on-chain identity, data oracle services, a wallet and stablecoin payments among planned components. Some remain in development as GIWA progresses toward a production network.
Upbit has previously had to clarify reports concerning unreleased blockchain products. Crypto.news reported in July that the exchange rejected claims it was participating in issuing Open USD after Dunamu appeared on a list connected to the stablecoin initiative.
At the time, Upbit said it had not agreed to issue or launch the dollar-backed stablecoin. Several other South Korean companies named in the same initiative similarly denied having made formal commitments.
GIWA’s current clarification is narrower. It concerns technical claims about an RPC endpoint and states only that no GIWA mainnet has been launched.
The project’s public documentation does not provide a mainnet launch date. Its connection, contracts and Flashblocks pages continue to show mainnet features as being under development or coming soon.
Many patients in that situation wind up living on the streets or in shelters, despite efforts to find them permanent housing. A surprising number of older adults, however, find themselves in a nursing home—even if they don’t need or want that level of care.
According to research from the United Health Foundation, one in 11 people in nursing homes have “low-care needs,” meaning they do not require physical assistance for bed mobility, transferring, using the toilet, or eating. The ratios vary by state, from a low of 2.5% in Hawaii to nearly 23% in Oklahoma.
Synovec recalls one client in her 50s who lost her housing while she was in the hospital getting treatment for a stroke. Although a family member was willing to take her in, she couldn’t navigate their second-floor apartment. The stroke left her without the use of one arm and with mild cognitive problems, but she still was able to manage most daily activities, including taking the bus to visit family, friends, and her church. She needed some help—for example, with getting dressed—but she valued her independence.
Australia summons AI chiefs over hack
The 6 Most Fun Movies Released Since 2020, Ranked

Where to watch Cowboys vs. Ravens in Brazil: TV, streaming, odds, pick





-
 Fashion2 days ago
Weekend Open Thread: J.McLaughlin – Corporette.com
-

 Crypto World5 days ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-

 Tech7 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Fashion3 days ago
8 iPhone Accessories That Add Personality
-

 Crypto World7 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Entertainment4 days ago
These 17 Fall Amazon Dresses Seriously Look Like Anthropologie
-

 Business7 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Crypto World7 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World4 days ago
This Bearish Netflix Stock Trade Can Cash In On Video Streaming Giant’s Woes
-
 Tech4 days ago
Reolink’s solar 4K security camera falls to its lowest price in months
-

 Tech6 days ago
Google’s $899 Googlebook is a bet that you’ll buy a new laptop for Gemini
-

 Crypto World5 days ago
Trump-Xi Polymarket Odds for Handshake Hit 50%
-

 Crypto World4 days ago
Crude Oil Prices Pressured by Diplomatic Hopes in the Middle East
-
 Business4 days ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-
 Crypto World4 days ago
Bitcoin price tests $83,600 Supertrend support after $87K rejection
-

 Crypto World4 days ago
Bitcoin Threatens Sub-$84,000 Breakdown as Long Liquidations Spike
-

 Crypto World5 days ago
Meta Jumps 11% As Muse Shines and Investors Show an Appetite for Advancing AI
-
 Crypto World4 days ago
Did Jim Cramer Just Give GameStop Stock the Kiss of Death When He Said the Turnaround Is Working?
-

 Crypto World6 days ago
Bitcoin price holds above $81K as key catalysts line up
-
 Crypto World4 days ago
BitGo says Bitcoin absorbed Fed hike, CLARITY failure
You must be logged in to post a comment Login