
Business
Can Varmora Granito IPO deliver long-term growth for high-risk investors?

Also, the tiles business is energy intensive and uses natural gas and propane. Their availability and cost will be impacted by geopolitical tensions. Further, the company’s production facilities are concentrated in Morbi, Gujarat, thereby increasing geographic concentration risks. Given these factors, investors may wait and watch for greater clarity after listing.
 ET Bureau
Business
Incorporated in 2003, Varmora Granito operates eight manufacturing facilities in Gujarat. It has a distribution network of 305 exclusive brand outlets and 2,758 multi-brand outlets across India and overseas, along with B2B sales to builders, contractors, developers and government entities. Nearly 82% of the revenue comes from products manufactured in-house and rest comes from third party contract manufacturers. Two-thirds of domestic revenue comes from the B2C retail channel and the remaining is from the B2B channel.
Read more: Landmark NSE IPO threatens to hollow out Dalal Street’s shadow market

Financials
Revenue from operations increased 2.6% annually to ₹1,512.5 crore and net profit grew 10.7% annually to ₹55.1 crore. Operating profit before interest, tax, depreciation and amortization (Ebitda) rose 21.4% to ₹221.6 crore while Ebitda margin improved to 14.2% from 10.2% during the period. Cash flow from operations declined from ₹88.3 crore in FY24 to ₹63.2 crore in FY25, before rebounding sharply to ₹234.1 crore in FY26. Return on capital employed increased to 9.9% in FY26 from 7.9% in FY24 and return on equity grew marginally to 6.8% in FY26 from 6.4% in FY24. Net debt declined to ₹2,434.3 crore in FY26 from ₹3,145.7 crore in FY24.
Read more: Ahead of Market: 10 things that will decide stock market action on Tuesday
Valuation
Based on the post-IPO equity and FY26 net profit, the company demands a price-earnings (P/E) multiple of 61. It appears to be on the higher side compared with a P/E of 39 for Kajaria Ceramics, the largest listed tiles company in India which also has higher Ebitda margin at around 18%. Given this and risks arising due to geopolitical risks, investors may wait and watch the developments in the short term.


Bolt Biotherapeutics CEO Quinn sells $58,402 in stock

The Trend Investing group includes qualified financial personnel with a Graduate Diploma in Applied Finance and Investment and well over 20 years of professional experience in financial markets. They search the globe for great investments with a focus on trending and emerging themes. The current focus is on electric vehicles, the EV metals supply chain, stationary energy storage and AI.They lead the investing group of the same brand name, Trend Investing. Features of the service include: Access to the Trend Investing portfolio, 7 monthly news updates, a monthly macro trends update, stock watchlist, CEO interviews, and direct access to the community and group leaders in chat.
Analyst’s Disclosure: I/we have a beneficial long position in the shares of GLOBAL X LITHIUM ETF (LIT), CONTEMPORARY AMPEREX TECHNOLOGY CO [HK:3750], ASX:RIO, ALB, GANFENG LITHIUM GROUP [SHE:002460], ASX:PLS, ZIJIN MINING GROUP [SHA:601899], TSX:LAC, TSX:LAR, ASX:CXO, ASX:GL1, ASX:EUR, GALAN LITHIUM [ASX:GLN], PMET RESOURCES [TSX:PMET], PATRIOT RESOURCES [ASX:PAT], ARGENTINA LITHIUM & ENERGY [TSXV:LIT], SIGMA LITHIUM [TSXV:SGML], LITHIUM IONIC CORP. [TSXV:LTH], ATLAS LITHIUM (ATLX), EAU LITHIUM LIMITED [ASX:EAU], MEGADO MINERALS [ASX:MEG], OMNIA METALS GROUP [ASX:OM1], SPARTACUS METALS INC. [TSXV:SPAR] either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
This article is for ‘information purposes only’ and should not be considered as any type of advice or recommendation. Readers should “Do Your Own Research” (“DYOR”) and all decisions are your own. See also Seeking Alpha Terms of Use of which all site users have agreed to follow. https://about.seekingalpha.com/terms
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

Converse pulls ad, apologizes after backlash over alleged KKK imagery, ABC News reports

I am interested in a lot of technology and AI stocks like Google, Nvidia, AMD, Tesla and Amazon.
Analyst’s Disclosure: I/we have a beneficial long position in the shares of TRIN, HTGC either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.

Wolf Report is a senior analyst and private portfolio manager with over 10 years of generating value ideas in European and North American markets, and the owner of Wolf of Value, a service focusing on international dividend-paying value investments.He further covers the markets of Scandinavia, Germany, France, UK, Italy, Spain, Portugal and Eastern Europe in search of reasonably valued stock ideas.
Analyst’s Disclosure: I/we have a beneficial long position in the shares of NHYDY either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
While this article may sound like financial advice, please observe that the author is not a CFA or in any way licensed to give financial advice. It may be structured as such, but it is not financial advice. Investors are required and expected to do their own due diligence and research prior to any investment.
Short-term trading, options trading/investment and futures trading are potentially extremely risky investment styles. They generally are not appropriate for someone with limited capital, limited investment experience, or a lack of understanding for the necessary risk tolerance involved.
I own the European/Scandinavian tickers (not the ADRs) of all European/Scandinavian companies listed in my articles. I own the Canadian tickers of all Canadian stocks I write about.
Please note that investing in European/Non-US stocks comes with withholding tax risks specific to the company’s domicile as well as your personal situation. Investors should always consult a tax professional as to the overall impact of dividend withholding taxes and ways to mitigate these.
Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. Any views or opinions expressed above may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank. Our analysts are third party authors that include both professional investors and individual investors who may not be licensed or certified by any institute or regulatory body.
Blue Owl Technology Finance: Management Says Coverage Arrives By Mid-2027
ClearBridge Appreciation Fund Q2 2026 Commentary
Blue Owl Capital: The Disconnect I Saw In May Is Now Wider
Janus Henderson Investors exists to help clients achieve their long-term financial goals. Formed in 2017 from the merger between Janus Capital Group and Henderson Global Investors, we are committed to adding value through active management. For us, active is more than our investment approach – it is the way we translate ideas into action, how we communicate our views and the partnerships we build in order to create the best outcomes for clients. While our investment managers have the flexibility to follow approaches best suited to their areas of expertise, overall our people come together as a team. This is reflected in our Knowledge. Shared ethos, which informs the dialogue across the business and drives our commitment to empowering clients to make better investment and business decisions.www.janushenderson.com
Business
$50B Retail Giant Dollarama Targets Australian Accessory Distributors with Direct Global Sourcing Model Across 410-Store Network
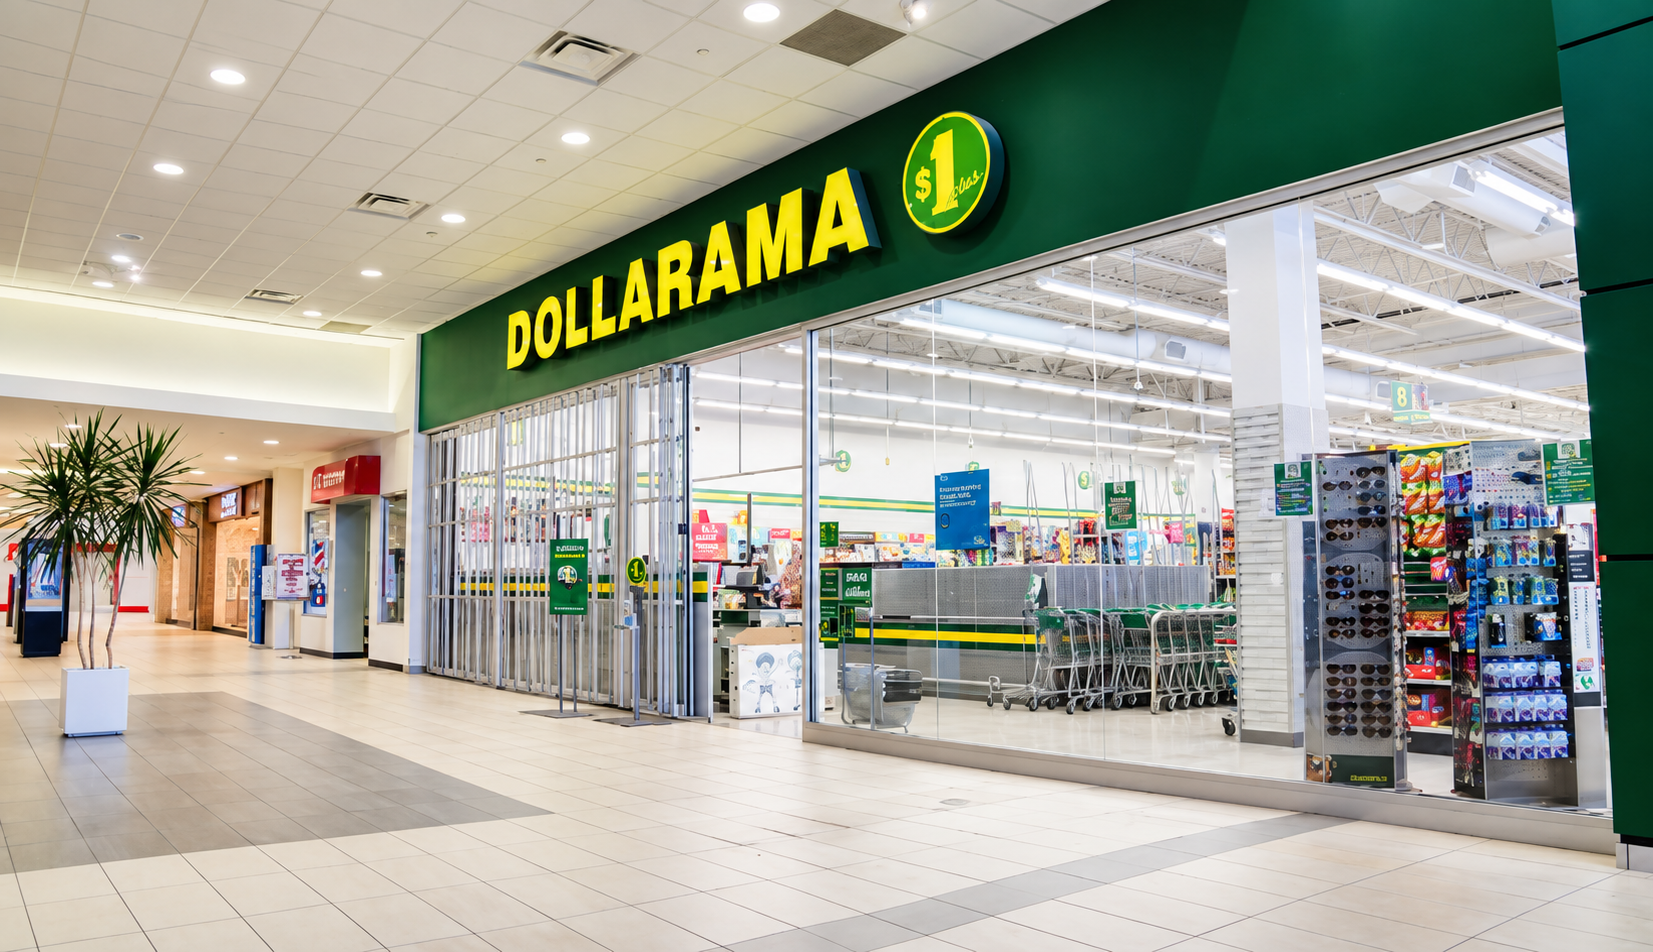

SYDNEY, Australia — Dollarama Australia Accessory Distributors Direct Global Sourcing disruption is taking center stage across the national retail landscape, as the $50 billion Canadian discount powerhouse accelerates the integration of its global supply chain into its newly acquired 410-store Australian footprint.
Following its acquisition of The Reject Shop, Dollarama is systematically replacing local wholesale supply arrangements with direct global factory procurement. The aggressive transition poses a immediate threat to traditional Australian accessory distributors that supply high-margin consumer electronics, tech cables, home entertainment attachments, and general merchandise. By deploying its proven low-cost merchandise model, Dollarama aims to bypass middleman markups, offering low-ticket retail items at aggressive shelf prices while maintaining industry-leading gross margins.
Retail analysts warn that Dollarama’s entrance marks a structural shift that will compress margins for domestic distributors and established value chains like Kmart, Big W, Officeworks, and Bunnings.
Direct Sourcing Machine Disrupts Local Wholesale Channels
Dollarama’s core strategic advantage lies in its extensive direct-to-factory sourcing infrastructure, eliminating regional intermediaries.
In traditional Australian retail, consumer tech accessories—such as HDMI cables, phone chargers, audio adapters, and computer peripherals—are imported and distributed by third-party wholesale vendors. These local distributors rely on healthy gross margins to cover domestic warehousing, marketing, and logistics. Dollarama’s global procurement engine, however, bypasses local distributors entirely, purchasing directly from overseas manufacturers in massive volume. By stocking converted Australian stores with its proprietary import stock, Dollarama undercuts conventional retail price points while capturing full category profitability.
Domestic distributors facing sudden contract terminations are forced to evaluate alternative sales channels or risk structural revenue declines.
- Middleman Bypass: Eliminates third-party Australian importers to capture full wholesale-to-retail margin spreads.
- High-Margin Tech Focus: Leverages low-cost tech accessories, cables, and chargers that deliver superior profit margins compared to big-ticket hardware.
- Direct Import Scaling: Progressively converts legacy Reject Shop stock to Dollarama’s global private-label inventory across 410 locations.
- No Loss-Leader Dependence: Operates without promotional loss leaders, ensuring every individual product category generates positive unit economics.
Direct supply chain integration gives international discount giants an insurmountable cost advantage over traditional wholesale networks.
Extraordinary Retail Economics and Financial Power
Dollarama’s entry into Australia is backed by exceptional corporate profitability and strong balance sheet liquidity.
Unlike struggling foreign retail entrants that rely on speculative debt to finance international expansion, Dollarama operates an ultra-efficient retail model. In recent financial disclosures, the Montreal-headquartered retailer reported global quarterly revenue exceeding C2 billion, achieving a group EBITDA margin of 32.2% and Canadian g[span_9](start_span)ross margins of 45.7%. Generating nearly C35 in EBITDA for every C$100 in sales, Dollarama possesses the financial strength to absorb multi-year restructuring costs associated with converting The Reject Shop network while aggressively undercutting competitors on price.
The retailer’s capital strength enables sustained long-term pressure on domestic competitors attempting to defend market share.
Robust gross margins provide the financial flexibility required to execute rapid nationwide store conversions and price cuts.
Broader Competitive Impact on Australian Big-Box Retailers
The injection of Dollarama’s global supply chain creates competitive friction across multiple retail categories.
Established Australian retailers—including Kmart, Big W, Target, Officeworks, Bunnings, and Aldi—have long relied on high-margin accessory sales to subsidize lower-margin staple categories. As Dollarama rolls out $5, $10, and $15 high-frequency consumer electronics and kitchenware accessories across its 410 Australian stores, budget-conscious consumers are presented with immediate price alternatives. Industry analysts note that Australian retailers attempting to boost profitability through expanded private-label offerings will face intense competition from Dollarama’s established global private-label pipeline.
The arrival of a true global value specialist escalates competition in an already tightening Australian consumer environment.
Retailers operating on domestic supply chains face urgent pressure to optimize procurement costs to maintain shelf competitiveness.
Future Roadmap: Store Conversions and Expansion Targets
Dollarama’s long-term plan for the Australian market involves extensive network renovation and brand conversion.
Having acquired The Reject Shop’s infrastructure, local management, and distribution centers, Dollarama is systematically converting legacy store layouts into its optimized Canadian format. Initial store conversions have already demonstrated sales lifts, prompting management to target a long-term Australian network expansion toward 700 stores over the next decade. As store conversions accelerate, local accessory distributors will see their total addressable market contract, signaling a permanent realignment of Australia’s value-retail supply chain.
Dollarama’s aggressive growth trajectory will reshape Australia’s discount retail landscape for the next decade.
The execution of its global supply model sets a new operational baseline for value retailing across Australia.
Young driver crashes kill or seriously hurt more than 23,000 in five years
Bolt Biotherapeutics CEO Quinn sells $58,402 in stock

Halo expands its Respite Programme delivering exercise, stress management and nutrition advice for carers




-

 Fashion3 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech1 day ago
Researchers escape OpenAI Codex sandbox to run commands on host
-
 Crypto World6 days ago
Robinhood engineers charged over $50K crypto scheme
-

 Crypto World3 days ago
Circle launches Arc Studio AI agent for building onchain apps
-
 NewsBeat3 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World3 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World5 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World6 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-

 Crypto World1 day ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Crypto World3 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-
 Crypto World7 days ago
NVIDIA Analysis: Attempted Rising Wedge Breakout Amid Pressure on the AI Sector
-
 Tech6 days ago
Webb’s IC 348 Mosaic Includes Two-Jupiter Dwarfs, Twin Jets, and a Nursery Still Making Worlds
-

 Crypto World3 days ago
World Money launches in 150+ countries with Stripe
-

 Crypto World4 days ago
Silver prices recover quickly, hitting weekly high today
-
 Entertainment6 days ago
Big Brother Update: Melody Explodes at Drew as Illness Sweeps BB28 House
-
 NewsBeat3 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-

 Crypto World4 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Crypto World20 hours ago
Bitcoin price holds above $81K as key catalysts line up
-
 Business6 days ago
Federal Reserve expected to hike interest rates 25 basis points at FOMC meeting
-

 Tech4 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
You must be logged in to post a comment Login