
Crypto World
Introducing TIME Executives of the Year: Tech and Data

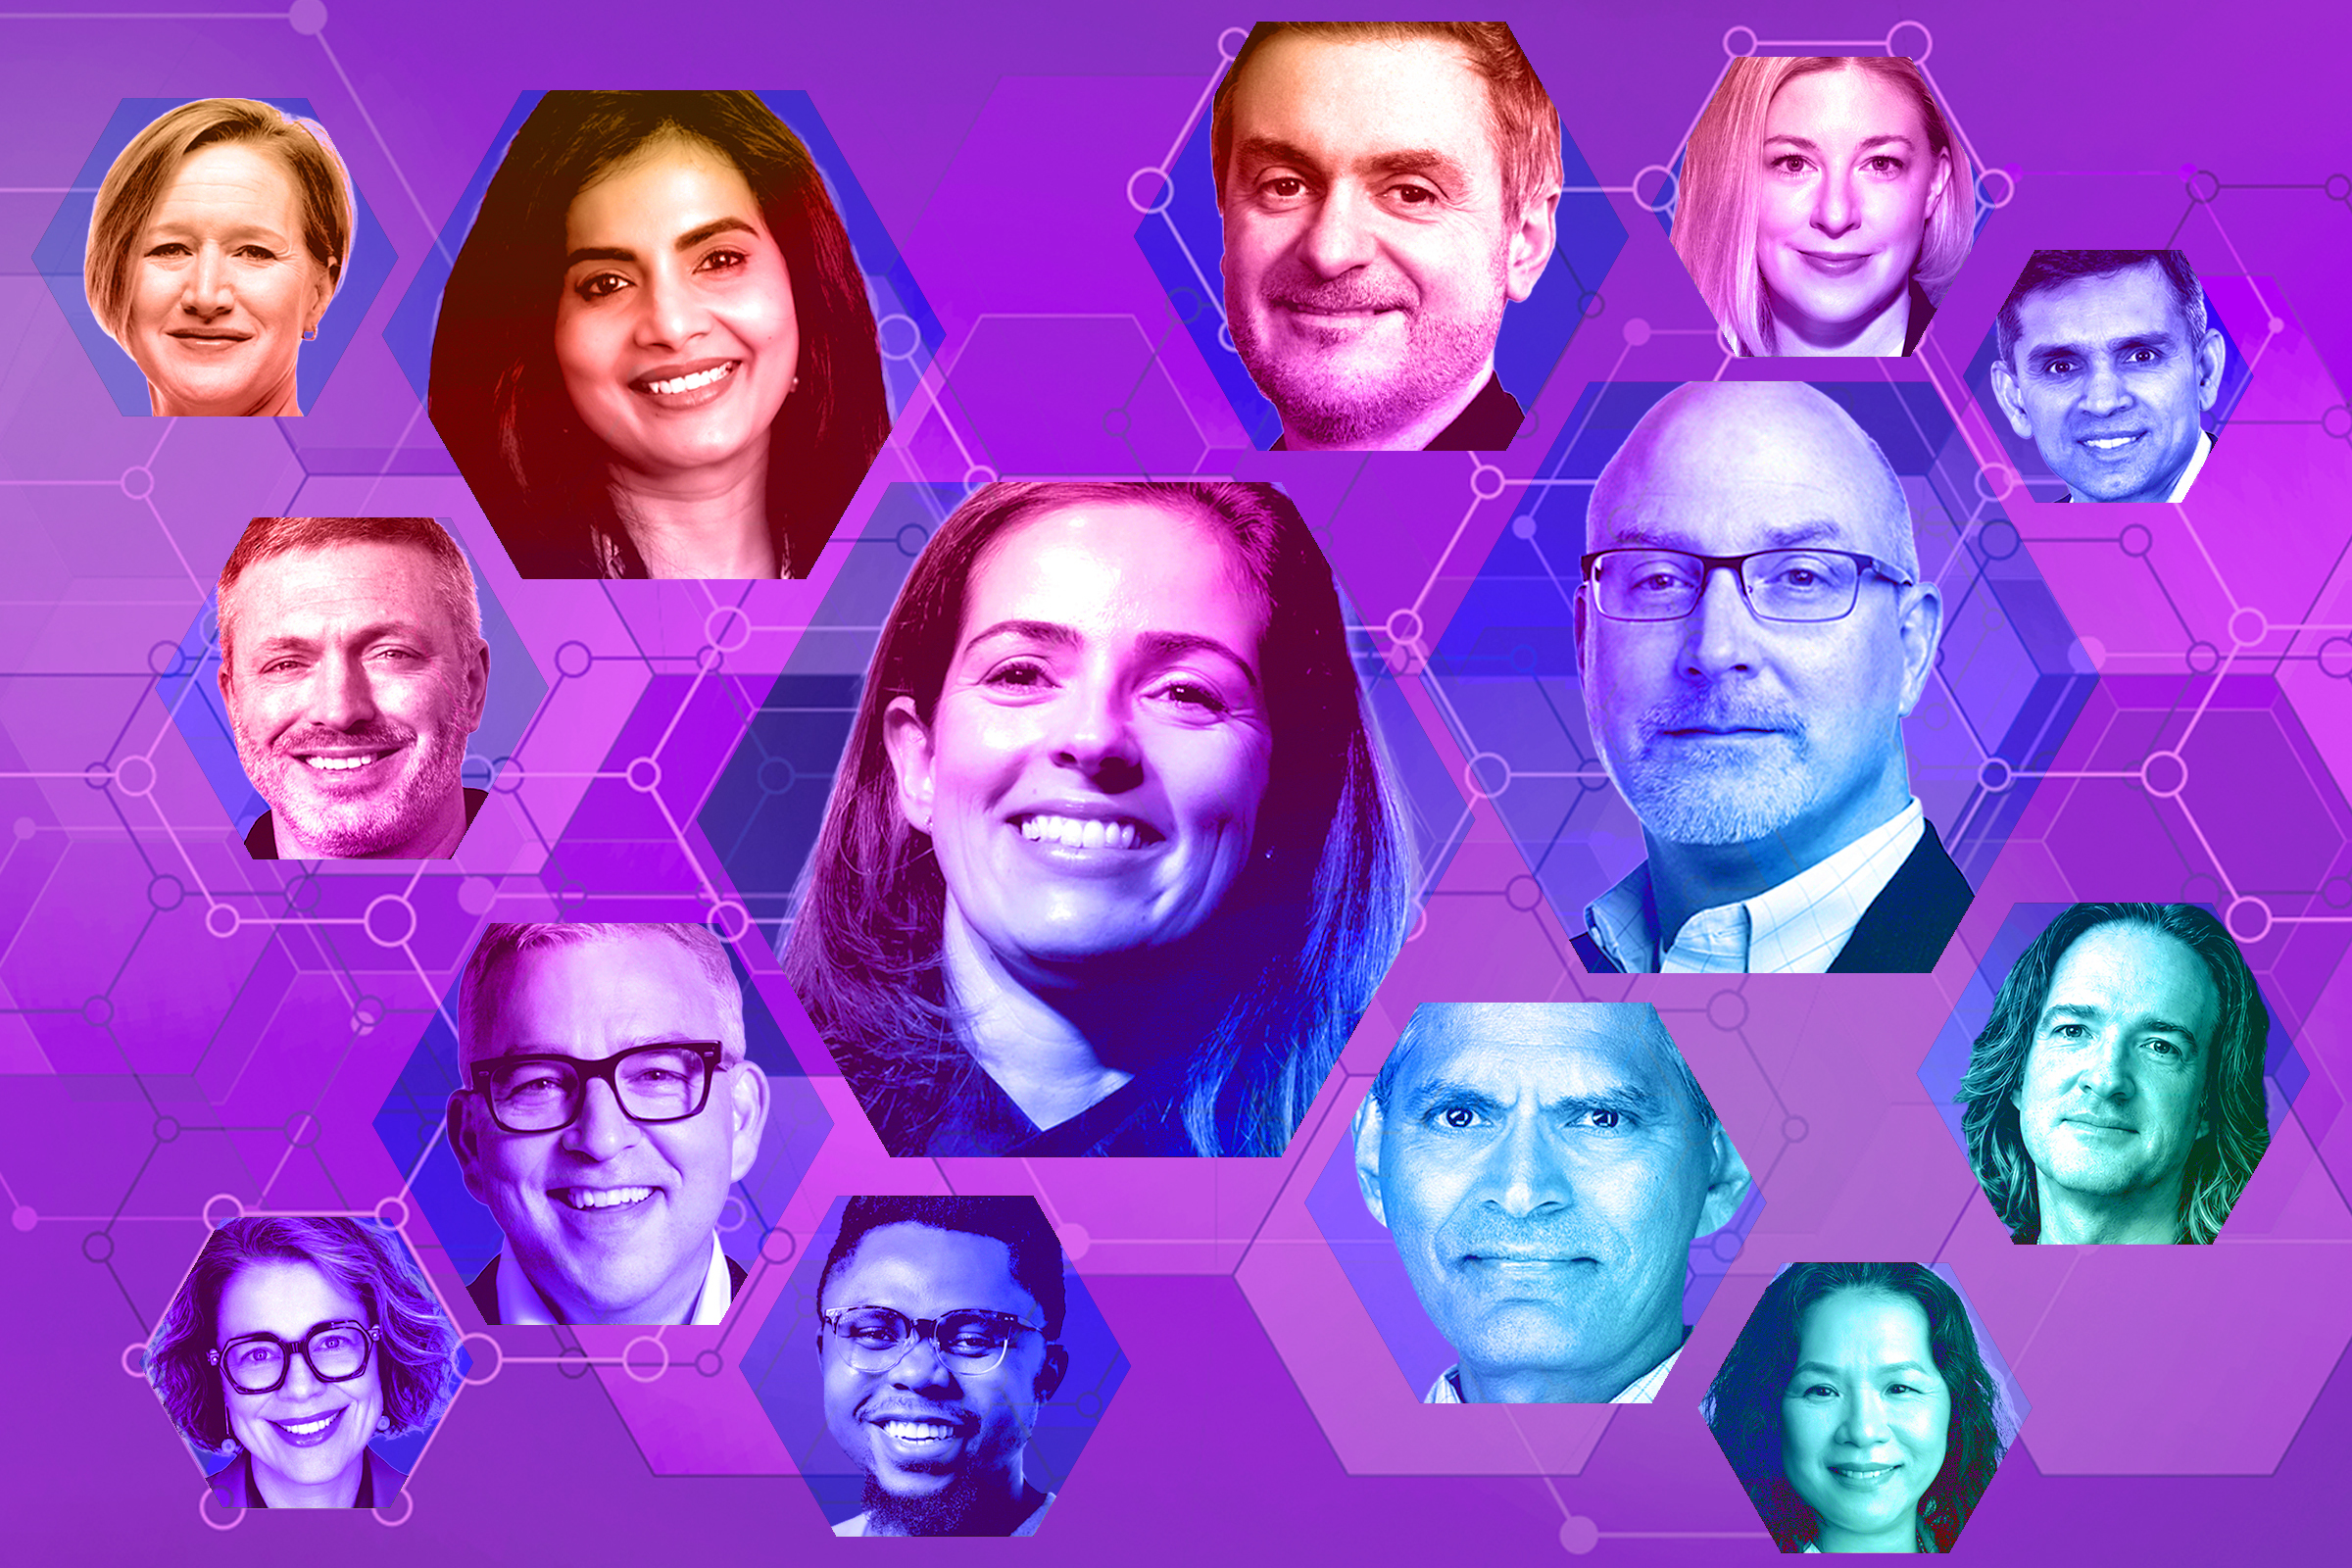
At a moment when emerging technologies are driving both the global economy and the news cycle, business leaders must not only keep up with an industry moving at a breakneck pace—they must look around the corner at what’s next. That’s why TIME is publishing its first-ever Executives of the Year: Tech & Data list, recognizing 50 leaders shaping the future of technology, artificial intelligence, cybersecurity, and digital innovation across industries.
See the full 2026 list here.
Among them are Bartley Richardson, CrowdStrike’s chief AI and autonomous systems officer, who is heading up a new AI research lab dedicated to building autonomous cybersecurity systems, and Reddit chief technology officer (CTO) Amit Puntambekar, who is shepherding AI adoption at one of the internet’s largest repositories of human conversation. At pharmaceutical giant Eli Lilly & Co., Diogo Rau oversaw the effort to build a supercomputer called LillyPod, which models biological processes and screens potential molecules before promising candidates enter wet lab experiments. Meanwhile, at OpenAI, Vijaye Raji, CTO of applications, is in charge of key technical teams—such as data, experimentation, and growth—that help power the ubiquitous ChatGPT, as well as the coding tool Codex.
To create the list, our editors and reporters across the newsroom evaluated the scale of each leader’s responsibilities, the significance of the investments and initiatives they oversee, and their demonstrated impact on how their organization operates, competes, and grows. What came together was a group of executives tasked with modernizing legacy systems and digital infrastructure. Those leaders include Monica Caldas, Liberty Mutual’s global chief information officer, who is rewiring the century-old insurance company for what she calls “the intelligence era,” and Ogi Redzic, who joined Caterpillar Inc. as SVP and chief digital officer in 2018 and has helped the equipment manufacturer rebuild itself around data to address customers’ labor and safety issues.
The list also highlights the creation of new or expanded roles designed to meet the fast-evolving moment. There’s Kathleen Grace, named Lionsgate’s first-ever chief AI officer in February and the first Hollywood studio executive to hold that particular title, as well as Delta’s Amala Duggirala, who joined the airline in January as EVP and chief digital and technology officer—a brand-new role overseeing its recently combined digital and technology organizations, encompassing both the enterprise technology that powers its global operations and the digital tools it creates for customers and employees alike.
Beyond the U.S., tech executives across Asia, Africa, and Europe are driving innovation. At Singapore-based Grab, CTO Suthen Thomas Paradatheth has helped the company transition from a ride-sharing platform to a superapp that processes millions of transactions a day across Southeast Asia. Felix Ike, co-founder and CTO of the Nigerian fintech company Moniepoint, has helped to establish the business as one of Africa’s leading financial platforms. At Paris-based Back Market, a global online marketplace for refurbished electronics, CTO Dawn Baker is applying an environmental mission to the company’s use of computing power. “We have to make sure we’re not using more than we need,” she says. “It’s about using AI smartly and not falling for the hype.”
These leaders and their fellow honorees are the catalysts of some of the most consequential transformations taking place across modern enterprise—translating innovation into meaning.

The European System of Central Banks (ESCB) is pushing to loosen parts of the upcoming MiCA framework governing how stablecoin issuers hold reserves. In a response published this Tuesday to the European Commission’s review of the Markets in Crypto-Assets Regulation (MiCA), the ESCB argues that mandatory requirements tying stablecoin reserves to bank deposits could generate liquidity stress for banks during periods of rapid redemption.
Instead of insisting that issuers keep a fixed share of reserves parked in deposits at credit institutions, the ESCB proposes replacing the bank-deposit thresholds with liquidity rules calibrated to how quickly reserve assets can be used—specifically focusing on assets maturing within one and five working days. The ESCB also points to instruments such as overnight reverse repurchase agreements (repos) and short-term sovereign bonds as potential reserve tools.
Key takeaways
- The ESCB wants to replace MiCA’s fixed bank-deposit reserve requirements with liquidity requirements based on time-to-maturity (one and five working days).
- ESCB warns that a stablecoin run could force fast withdrawals from banks, potentially exposing credit institutions to liquidity problems.
- The proposal aligns with earlier draft liquidity “buckets” developed by the European Banking Authority (EBA) in 2024.
- Central banks also caution that MiCA enforcement gaps could allow non-compliant firms to keep serving EU customers.
- The risk debate echoes concerns raised by stablecoin issuers, including Tether’s CEO, about MiCA’s deposit-linked approach.
From deposit floors to liquidity time buckets
At the heart of the ESCB’s proposal is a shift in how reserve adequacy is measured. The current MiCA-related approach requires a minimum proportion of stablecoin reserves to be held as deposits at credit institutions—30% for standard stablecoins and 60% for “significant” stablecoins.
In its published response to the European Commission’s MiCA review, the ESCB argues this model creates what it describes as a direct link between stablecoin issuers and banks. That linkage matters, the ESCB says, because if holders redeem at pace, issuers may need to withdraw deposited funds quickly—behavior that can strain bank liquidity at exactly the moment it is most needed.
To reduce that dependency, the ESCB backs liquidity requirements that focus on reserve assets’ maturity horizons. Under the new direction, issuers would have to hold minimum liquidity amounts among reserve assets maturing within defined short periods, rather than meeting a mandated share in the form of bank deposits.
How the ESCB’s alternative aligns with EBA drafts
The ESCB’s framing references draft rules from the European Banking Authority (EBA) that were published in 2024. Those drafts outline distinct liquidity thresholds for stablecoin reserves depending on whether a token is classified as “significant” or “non-significant.”
According to the EBA draft rules cited by the ESCB, significant stablecoins would be required to hold at least 40% of reserves in assets maturing within one working day and at least 60% in assets maturing within five working days. For non-significant tokens, the draft thresholds are 20% for one working day and 30% for five working days.
The ESCB’s Tuesday response suggests that, operationally, liquidity can be achieved without the rigid deposit framework—highlighting overnight reverse repurchase agreements and short-term sovereign bonds as examples of instruments that can help issuers meet near-term liquidity targets.
Why central banks see systemic two-way risks
The ESCB does not treat the risk as one-directional. While it emphasizes that stablecoin redemption pressure could pull liquidity out of banks, it also warns that bank stress can spill into stablecoin reserves.
As part of that argument, the ESCB points to the March 2023 collapse of Silicon Valley Bank. In the aftermath, a run on Circle’s USDC stablecoin followed disclosures that Circle had held $3.3 billion of its reserves at the failed institution. The ESCB uses this episode to illustrate how concentration of reserve funds in a single credit institution—and the resulting loss of confidence—can translate quickly into stablecoin redemption pressure.
Taken together, the ESCB’s approach implies that reserve rules should aim to reduce both the need for rapid bank-linked withdrawals during stablecoin stress and the vulnerability of stablecoins to bank-specific failure events.
MiCA enforcement challenges beyond reserve rules
Beyond the mechanics of reserve holding, the ESCB also cautioned that MiCA’s implementation may face “material challenges” in enforcement. The concern, as expressed in the response, is that even firms that fail to comply with MiCA requirements could still reach or continue serving EU customers.
That point broadens the discussion beyond liquidity buffers. Investors and users have largely focused on whether reserves are safe and liquid; central banks are effectively arguing that safety depends not only on what reserves look like, but also on whether the regulatory framework is implemented and enforced in a way that prevents non-compliant entities from operating inside the EU market.
Stablecoin industry warnings were already on the record
The ESCB’s position also echoes arguments made by stablecoin industry figures. In an October 2024 interview with Cointelegraph, Tether CEO Paolo Ardoino warned that MiCA’s bank-deposit reserve requirement could create systemic risks for both banks and issuers.
Ardoino illustrated the concern with a hypothetical example: if a stablecoin issuer had €10 billion in reserves and €6 billion had to be kept as bank deposits, then if a bank lent out 90% of those deposited funds, only €600 million might remain readily available. In a scenario where the issuer needed billions quickly to meet redemptions, that mismatch between depositor availability and redemption demands could contribute to a liquidity crunch.
In its Tuesday response, the ESCB references a similar dynamic—stating that a stablecoin run could force an issuer to withdraw deposits rapidly and that the impact could be most acute when stablecoin reserves represent a meaningful share of a bank’s funding.
With the ESCB’s response now on the record, the key next question is how the European Commission will balance MiCA’s original bank-deposit intent with the liquidity-time-bucket approach advocated by central banks and aligned with EBA draft rules. Readers should watch for how the final MiCA implementation details handle both liquidity measurement and enforcement capacity—especially during periods of market stress when reserve behavior is tested in real time.
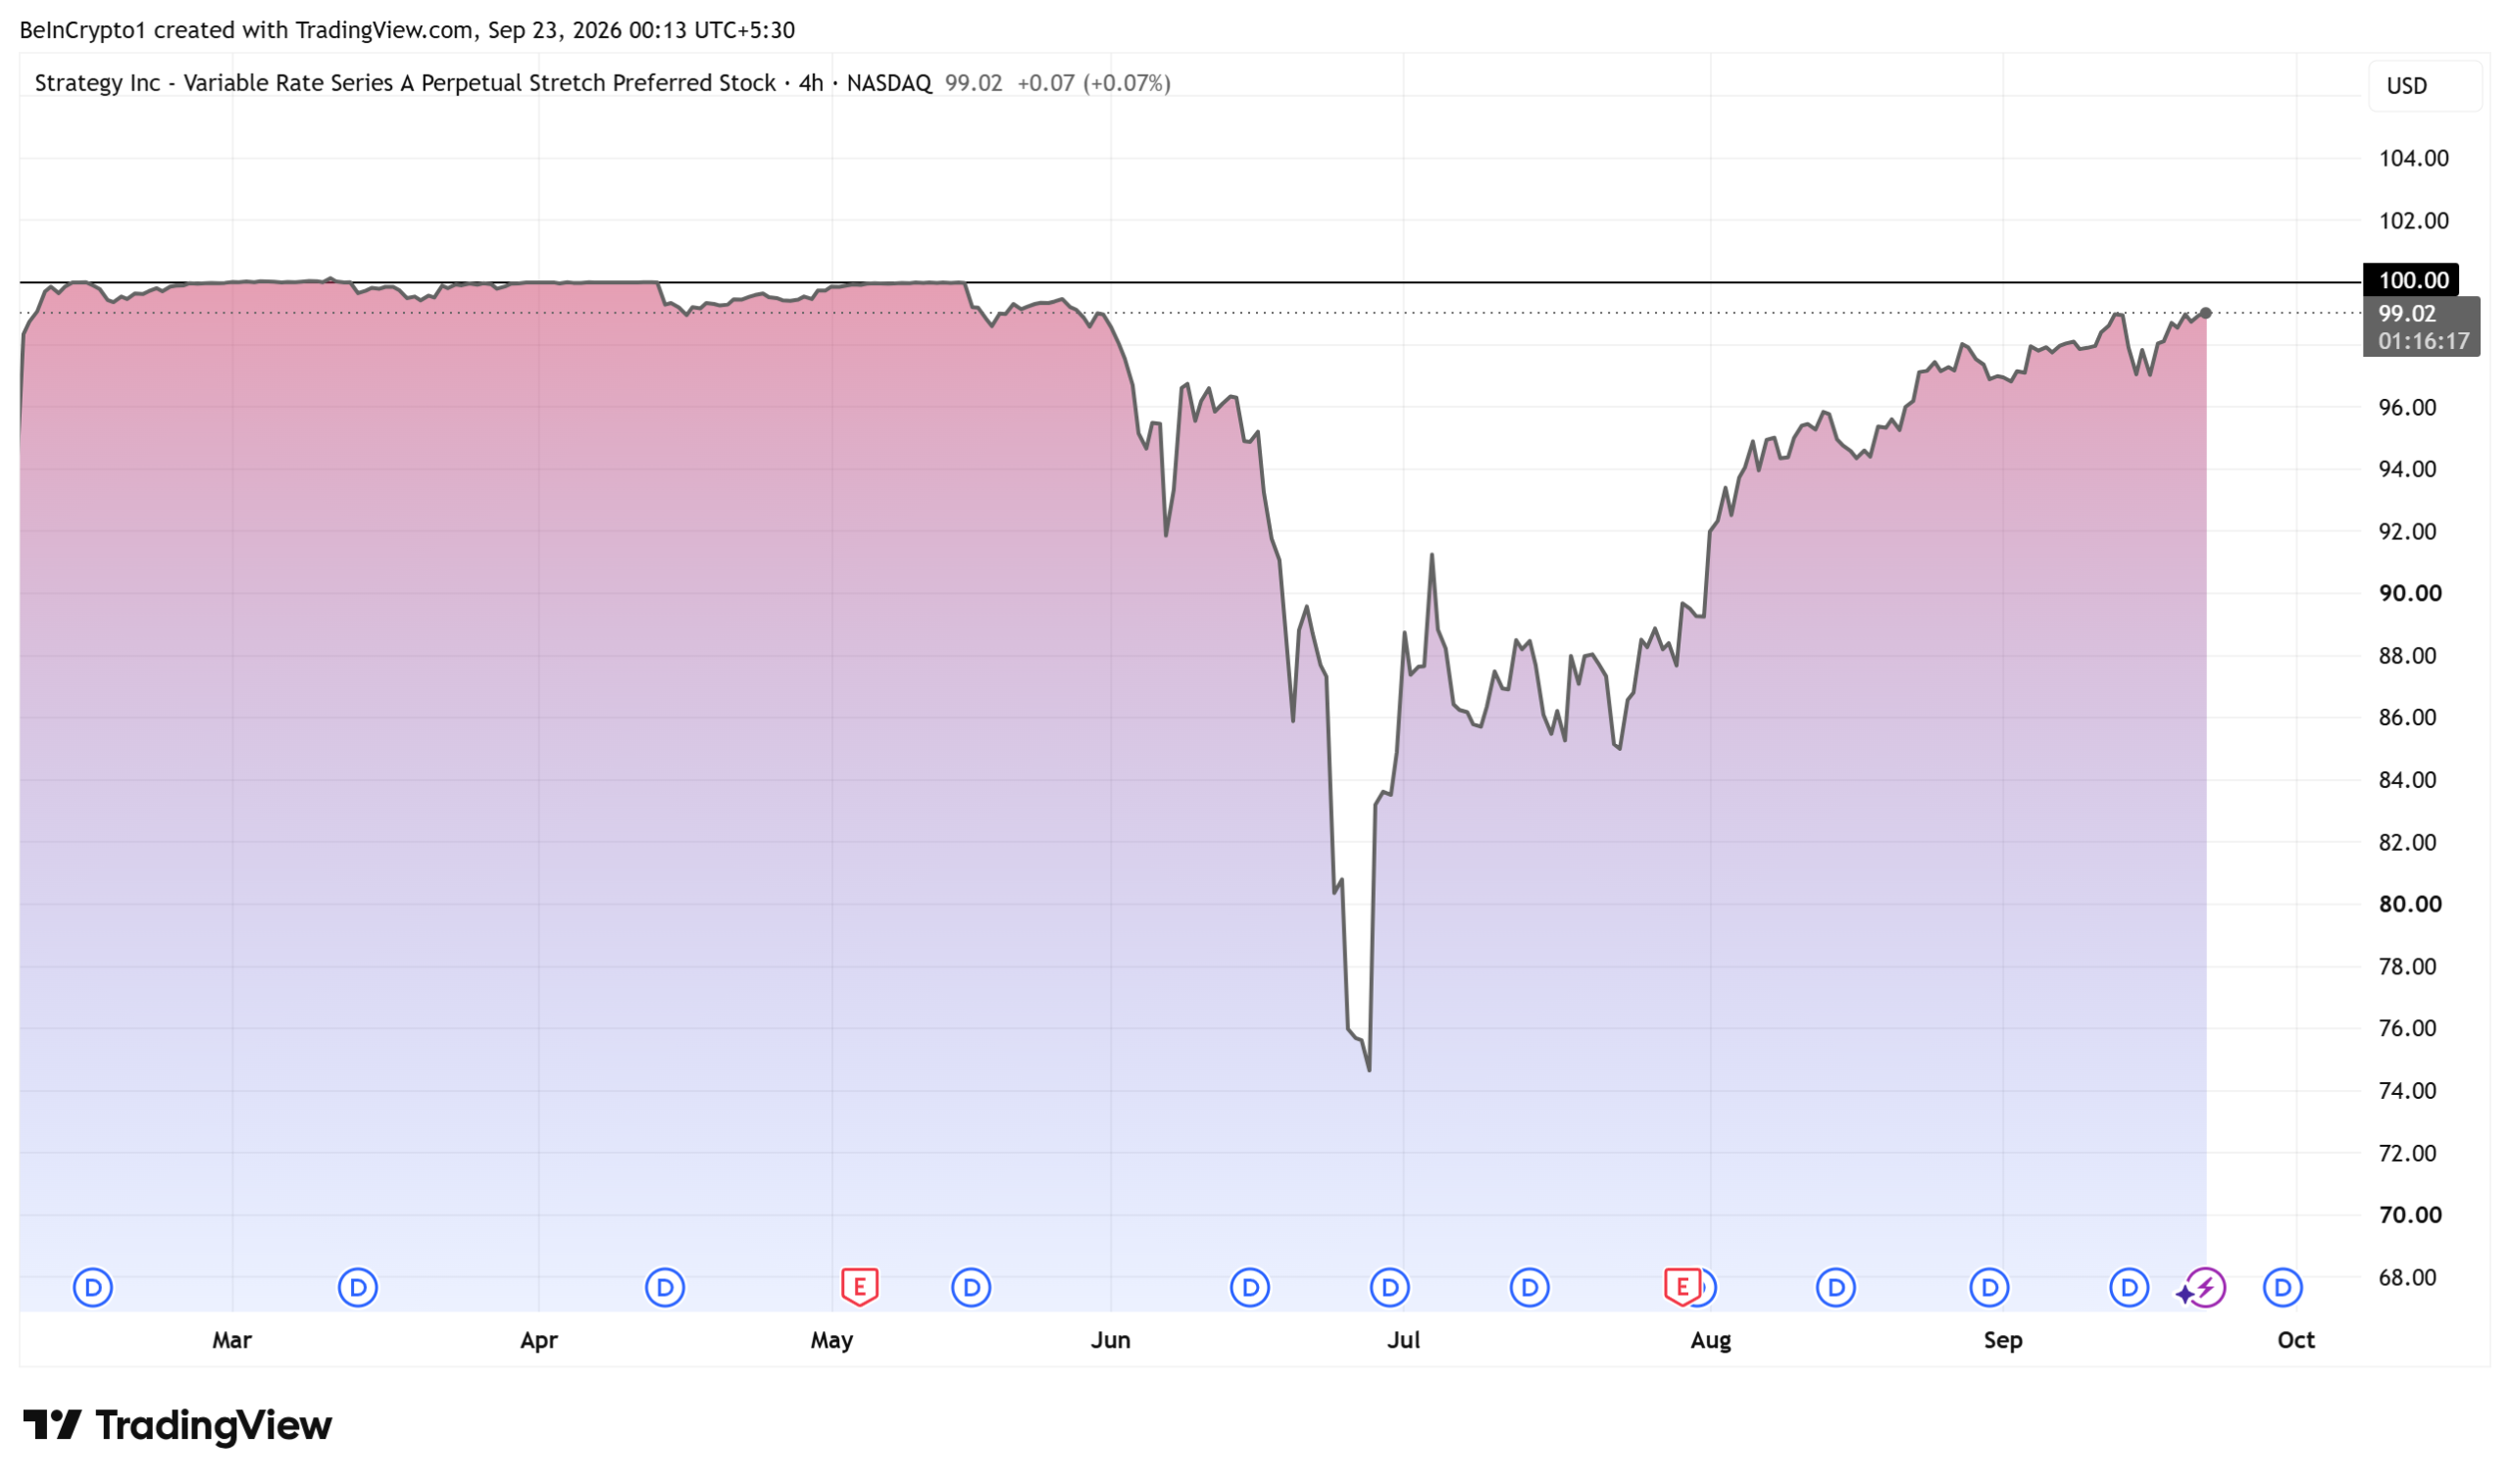
Strategy CEO Phong Le says the company underestimated how much borrowed money would flow into STRC, its $9.3 billion preferred stock that lost a quarter of its value this summer.
STRC pays a 12% annual dividend and is built to trade near its $100 face value. It sank to about $75 in late June and now trades at $99.

How Borrowed Money Sank STRC Below $100
Le explained the selloff in an interview with Natalie Brunell. He said STRC’s calm price invited investors to borrow against their Bitcoin (BTC) at about 6% to collect STRC’s 12% yield.
When Bitcoin fell, those loans came under pressure. Holders had to post more Bitcoin or sell STRC, Le said, and that forced selling drove the price lower.
“We did not expect the amount of leverage that came into the system,” Le explained.
Le said traders later bought STRC between $75 and $90, and that he bought some himself.
Why Strategy Chose Buybacks Over a Higher Dividend
In late June, Strategy set out a framework with a cash reserve, buyback authorizations, and a plan to sell Bitcoin when needed. It began repurchasing STRC in late July.
Le said earlier dividend increases toward 12% did not lift the price. A higher payout would also drain cash and weigh on common shareholders, he said. Buybacks shrink future dividend bills instead.
Strategy’s dollar reserve now holds about $5.1 billion, which Le said covers roughly three years of dividends. That money can only pay preferred dividends and interest on Strategy’s convertible debt.
What It Means for MSTR Shareholders
Strategy funds the latest STRC buybacks through sales of its common stock (MSTR) and, potentially, Bitcoin. Le said 95% of his pay is tied to MSTR’s share price and urged holders to think in three-year periods.
Le said institutions now own about 30% of STRC, up from 20%. He expects the stock to return to $100 as long-term holders replace leveraged traders.
$STRC is a passenger jet. $BTC is a fighter jet. $MSTR is a rocket ship. Buckle up,” Le said in a recent post.
STRC’s next dividend goes to holders of record on September 30, with payment due October 15, according to Strategy.
The post Strategy CEO Phong Le Reveals the One Mistake Behind STRC's 25% Collapse appeared first on BeInCrypto.
Republican Senator John Curtis of Utah has asked the U.S. Senate Judiciary Committee to investigate whether the sons of President Donald Trump and former President Joe Biden used their family ties to obtain private financial benefits—an inquiry that Curtis says should include subpoenas for Donald Trump Jr. and Hunter Biden.
In a Monday letter to Senate Judiciary Committee Chair Chuck Grassley and ranking member Dick Durbin, Curtis argued that lawmakers should probe “the use of presidential family relationships for private financial benefit, preferential treatment, or access by domestic and foreign interest.” The Utah senator’s request centers heavily on alleged cryptocurrency-related activity involving Trump Jr., while also citing Hunter Biden’s international business dealings.
Key takeaways
- Sen. John Curtis urged the Senate Judiciary Committee to investigate whether presidential family relationships were used for private financial gain.
- Curtis asked for subpoenas for Donald Trump Jr. and Hunter Biden, citing specific concerns tied to cryptocurrency ventures and foreign business.
- Trump Jr. was singled out for accepting gifts reportedly linked to Russian oligarch Umar Kremlev and for promoting family-backed crypto initiatives.
- The call for inquiry comes after Senate Republicans failed to move the Digital Asset Market Clarity Act despite Democrats’ objections.
- Democrats have tied broader crypto policy disputes to concerns that the presidency could be leveraged for profit through digital-asset businesses.
A Judiciary probe focused on family ties and crypto exposure
According to the letter, Curtis wants the committee to examine whether ethics, disclosure, or anti-corruption laws apply to conduct involving Trump Jr. and Hunter Biden. He emphasized that the objective should be to establish facts, determine legal applicability, and identify reforms needed to prevent the presidency from becoming a pathway to private enrichment.
Curtis specifically pointed to Donald Trump Jr.’s actions, including his acceptance of gifts from Umar Kremlev as part of his wedding. The senator also cited what he described as Trump Jr.’s “active promotion of family-backed cryptocurrency ventures” and advisory roles connected to prediction market platforms—entities that, according to Curtis, fall under the regulatory authority of the U.S. Commodity Futures Trading Commission.
Last week, President Trump said that his son repaid Kremlev for what Trump Jr. and his wife described as a “generous wedding gift.” Curtis’s request builds on that broader narrative by asking whether the underlying relationship and crypto involvement warrant formal scrutiny.
Hunter Biden: foreign business and the role of presidential proximity
Curtis also asked for a similar probe into Hunter Biden. His letter frames the request around “substantial business with foreign entities” and instances where, Curtis argued, either man’s relationship to the presidency was “invoked or understood to provide value.”
The letter notes that Joe Biden issued a pardon for Hunter Biden in December 2024 for crimes he “committed or may have committed or taken part in over the last decade.” Curtis also referenced Hunter Biden’s prior denials that his father was involved in his business dealings.
While Curtis’s focus is on potential misuse of access or preferential treatment, the request implicitly raises a question that extends beyond any single prosecution: whether existing rules are sufficient to address situations in which family members operate in sensitive sectors while their proximity to the White House or a former administration may influence outcomes.
Crypto regulation debate heightens as clarity legislation stalls
Curtis’s letter arrives amid an ongoing political dispute over U.S. digital-asset oversight. A week earlier, Senate Republicans failed to secure enough support from Democrats to pass the Digital Asset Market Clarity Act—legislation described as intended to establish market structure rules for the crypto industry.
In coverage cited in the article, some Democrats argued against the bill on the grounds that Trump was “using crypto to turn the presidency into a profit generating machine.” The argument references the broader concern that digital-asset activity connected to the president could raise conflict-of-interest issues that statutory ethics provisions may not adequately address.
Republicans said the president had agreed to stronger ethics provisions related to his crypto investments before the vote. Still, Democrats contended that the proposed measures did not go far enough to prevent corruption.
The tension highlights an asymmetry: while the legislation aimed to create regulatory clarity for the market, the political debate has also become a referendum on how lawmakers view the connection between crypto business activity and the presidency itself.
What to watch next
For investors and builders, the practical question is whether a Judiciary Committee inquiry will lead to new subpoenas, targeted disclosures, or recommendations for ethics enforcement—outcomes that could affect compliance planning and the perceived legitimacy of crypto-related public affairs. The scope of any investigation, and whether it meaningfully intersects with pending regulatory reforms, remains the key uncertainty.
Nephos Group has partnered with venture accelerator Brinc to provide accounting, compliance, corporate structuring, and tokenization support to more than 250 startups in Brinc’s portfolio.
Summary
- Brinc founders will gain access to Nephos services covering tax, banking, visas, and corporate structures.
- Stablecoin and Web3 companies can seek proof-of-reserve attestation and tokenization advice.
- The partners will hold workshops on compliance readiness, reserve reporting and cross-border structures.
- U.S. stablecoin rules add another compliance layer for GCC companies seeking American users.
In a Sep. 22 press release shared with crypto.news, Nephos Group said that Brinc’s portfolio companies will be able to use its financial and advisory services through the accelerator’s founder support program. The arrangement covers technology companies across the Gulf Cooperation Council, with added services for startups working on stablecoins, Web3 products and tokenized assets.
Financial terms were not disclosed. Rather than providing a new investment fund, the partnership adds professional services to the capital, mentoring and market support already available through Brinc.
Nephos will provide compliance support from an early stage
Under the agreement, founders can seek help with cross-border tax planning, corporate structures, banking introductions and visa matters. Nephos will also advise digital asset businesses on tokenization and provide proof-of-reserve attestations for companies whose products depend on backing assets.
Reserve attestations assess whether reported assets support an issuer’s claims at a stated point in time. They differ from full financial audits, which examine financial statements and accounting processes across a reporting period. As crypto.news previously explained, proof of reserves does not by itself establish a company’s solvency because it may not show all liabilities, internal controls, or claims against the reported assets.
For an early-stage stablecoin issuer, the distinction affects how information is presented to investors, banks and regulators. A company may need reserve verification alongside legal, accounting and operational controls, depending on the product and the jurisdiction where it is issued or distributed.
Nephos founder and CEO Joe David said founders often build such systems after launching, even though cross-border businesses may need them during their earliest stages.
“The GCC’s tech ecosystem is scaling rapidly, and founders here need professional infrastructure that keeps pace,” David said.
Having relocated to the United Arab Emirates, David said his experience building Nephos and Myna Accountants gave him direct knowledge of the issues companies face while setting up and expanding in the region. The Brinc agreement, he added, will let portfolio founders obtain compliance and structuring services “from day one rather than having to piece it together later.”
GCC stablecoin rules raise the compliance burden
Across the Gulf, digital asset companies operate under national regulators as well as separate financial-center and free-zone frameworks. A startup serving several GCC markets may therefore face different licensing, reserve, disclosure, tax and company-formation requirements.
Dubai’s Virtual Assets Regulatory Authority clarified its token issuance framework in April, setting separate routes based on a token’s design and risk profile. The Dubai issuance guidance placed fiat-referenced and asset-referenced tokens in its first category, with specific requirements covering reserve assets, redemption rights, disclosures and legal structures.
Licensed distributors also carry due diligence and continuing compliance duties for some token offerings under VARA’s framework. Such requirements mean a founder’s choice of issuer, distributor, banking provider and legal entity can affect whether a product can enter the market.
In May, AE Coin and USD Universal introduced a regulated conversion system connecting a dirham-backed token with USDU, a U.S. dollar-backed stablecoin, for institutional settlement in the UAE. The stablecoin conversion rail was built with support from Al Maryah Community Bank and initially offered through regulated providers Aquanow and Changer.ae.
USDU had previously become the first dollar-backed stablecoin registered under the UAE’s Payment Token Services Regulation framework for institutional and professional users. Its approval allowed digital asset-related payments under stated conditions, while mainland retail payments remained outside its permitted scope.
Against that regulatory setting, Nephos and Brinc plan to run workshops for participating founders on compliance preparation, cross-border structures, tokenization frameworks and proof-of-reserve practices. The companies did not provide a schedule for the sessions or identify the first startups expected to take part.
Brinc adds financial services to its accelerator model
Brinc chief marketing officer Nick Ramil said founders seeking to operate across several countries need more than funding and business introductions.
“It requires the right infrastructure, trusted partners, and the ability to navigate complex markets without unnecessary friction,” Ramil said.
Through the agreement, Brinc will connect founders with Nephos while continuing to provide its existing accelerator services. Ramil said the arrangement would give portfolio companies access to financial, compliance and structuring expertise as they build businesses across national borders.
Brinc has previously worked with blockchain accelerators in the region. In November 2024, the firm joined CoinList and Ghaf Group in a 12-week SuiHub program for pre-token projects in the Middle East and North Africa. Selected teams could receive as much as $200,000 in milestone-based funding, alongside technical assistance and networking support.
The Nephos deal uses a different format because it centers on professional services rather than direct startup funding. Brinc’s portfolio includes more than 250 companies spanning blockchain, artificial intelligence, connected hardware, robotics, drones, clean energy, food technology and the Internet of Things.
U.S. rules may affect GCC stablecoin founders
Gulf-based stablecoin companies seeking American customers must also account for the U.S. framework created by the GENIUS Act. The law established licensing, reserve, redemption, disclosure, and compliance requirements for payment stablecoin issuers, while federal agencies continue to develop the implementing rules.
In August, the U.S. Treasury proposed definitions for when a payment stablecoin is issued, offered, or sold in the United States. Under the Treasury stablecoin proposal, issuers generally will need an eligible federal or state license when the law is expected to take effect on Jan. 18, 2027.
Foreign-issued stablecoins face a separate route. According to Treasury, digital asset service providers generally cannot make such tokens available to U.S. users unless the issuer can comply with lawful orders and its home jurisdiction meets requirements connected to regulatory reciprocity.
From July 18, 2028, service providers generally will be barred from offering payment stablecoins to people in the United States unless an eligible licensed issuer issued the token, Treasury said. The agency’s proposal would also define when an overseas company’s activity amounts to an offer or sale to a person in the country.
For GCC founders, those rules can make reserve design, company location and distribution arrangements relevant before a stablecoin reaches American users. Treasury has also proposed anti-money laundering and sanctions duties for permitted payment stablecoin issuers, including systems for identifying suspicious transactions and blocking, freezing or rejecting transfers when legally required.
Brinc is headquartered in Hong Kong and has run programs with companies, public agencies, universities and investment groups. Its past partners include Huawei, Schneider Electric, Puma, Manulife, Hong Kong Science Park, the Mohammed Bin Rashid Innovation Fund, the National University of Singapore, Artesian and Bahrain’s Economic Development Board.
Bitcoin (BTC) rallied nearly 7% on Monday, crossing $87,000 and reaching an intraday high of $87,397 before closing at $86,593. It traded at levels last seen in January 2026.
BTC’s Monday rally came as global stocks and bonds reported substantial gains. At the same time, lower oil prices and a planned summit between US President Donald Trump and Chinese President Xi Jinping lifted market sentiment.
Bitcoin and Broader Crypto Market Rallies
Bitcoin (BTC) is currently trading around $86,197, up almost 2% over the past 24 hours. Meanwhile, Ethereum (ETH) followed a similar trajectory, rising to $2,804 before settling at $2,749, up almost 1% in the past 24 hours. Ripple (XRP) is up over 4% at $1.53, while Solana (SOL) is up 1.30%, trading around $117. Dogecoin (DOGE), Cardano (ADA), Stellar (XLM), Uniswap (UNI), and Litecoin (LTC) also recorded notable increases.
According to Pratik Gupta, head of Business at Mudrex, a favorable risk environment has helped the rally, while lower oil prices have eased inflation concerns. Gupta also highlighted short covering as another factor. Meanwhile, CoinGlass reported liquidations of long and short positions across crypto crossed $1 billion in 24 hours, the highest since August.
BTC is up 44% this quarter, marking its strongest gain since Q4 2024. Mudrex also highlighted Strategy’s purchase of 950 BTC, taking its total holdings to 846,000 BTC. Meanwhile, CoinSwitch’s Markets Desk said around $750 million in short positions were liquidated as BTC broke above $82,000 toward $87,000. However, it highlighted a $2 billion jump in futures open interest, indicating leverage had also increased. WazirX founder Nischal Shetty said BTC’s latest rally marks a significant improvement in market sentiment, highlighting renewed institutional activity after a brief period of uncertainty following the Federal Reserve raising interest rates and the Senate failing to pass the CLARITY Act.
Spot Bitcoin ETFs Record Substantial Inflows
Spot Bitcoin ETFs reported substantial outflows totaling $462.7 million for the week ending September 11. The outflows broke a three-week inflow streak. The ETFs resumed inflows on September 14, bringing in $159.9 million, before recording $450 million and $290 million in outflows on September 15 and September 16. The inflow streak resumed on September 17 with $159 million and $433 million on September 18. Bitcoin ETFs reported $999 million in inflows on Monday, propelling BTC to an intraday high of $87,397.
Inflation Concerns
Inflation is another key factor driving demand for BTC. At least some ETF inflows are being driven by investors looking for a hedge against inflation. The US Bureau of Labor Statistics has reported that consumer prices rose 3.4% year over year in August, fueling concerns that the dollar is losing purchasing power. Some investors are worried the decline will continue and are actively looking for fixed-supply assets, with BTC fitting the narrative. Other macroeconomic concerns and a volatile geopolitical situation have also dampened investor sentiment.
Miner Stress and Capitulation
The third factor buttressing BTC’s latest price action is the on-chain data on miner stress and capitulation. A research report by VanEck stated that eight of twelve holder capitulation signals, including average holding periods and liquidation rates of supply, were flashing. Mining difficulty also fell 18.3% from its November peak. The decline suggests unprofitable miners stopped mining or sold some holdings to cover costs. However, VanEck’s report suggests the squeeze is easing, with the August 8 adjustment raising mining difficulty by 1%.
Disclaimer: This article is provided for informational purposes only. It is not offered or intended to be used as legal, tax, investment, financial, or other advice.
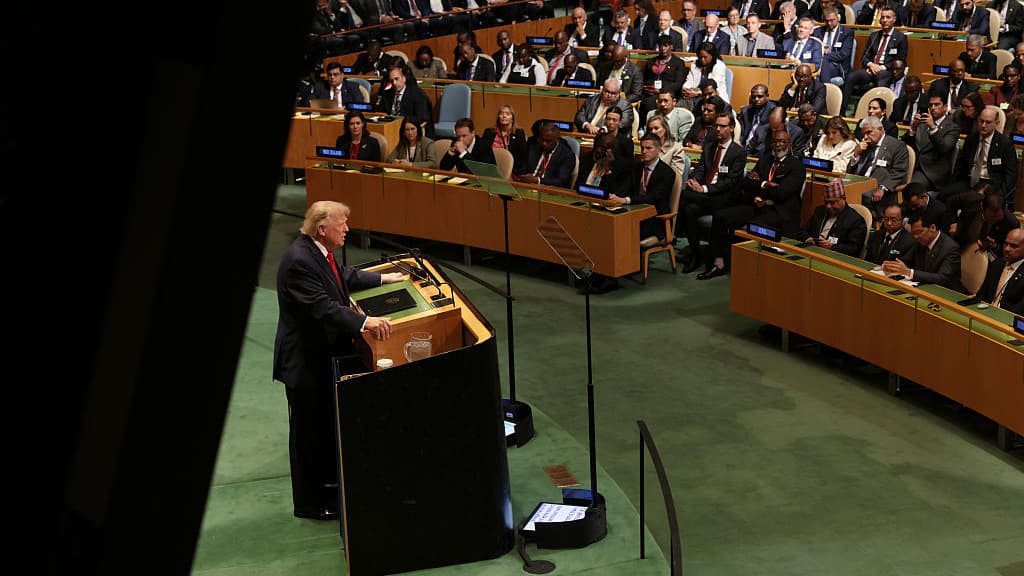
“The cartels are the ISIS of the Western Hemisphere—not good people,” he said. “Like ISIS, they should be killed, exiled, or detained as enemy combatants without the possibility of release, which is what we’re doing.”
But while these messages are largely meant to promote the very strength that Trump relies upon in his endeavors, the potency of his remarks may be dwindling amid contested claims of success.
Venezuela is Trump’s ‘peace through strength’ model. But Iran is testing its limits
Kristian Coates Ulrichsen, a fellow for the Middle East at the Baker Institute, tells TIME that Trump’s speech seems “consistent with the narrative of American dominance” that he has long used to justify military action.
Trump suggested Tuesday that he considers Venezuela a leading example. In January, the U.S. military launched Operation Absolute Resolve—a nighttime raid in Caracas that captured Venezuela’s president Nicolás Maduro and his wife, Cilia Flores. Both were transported to New York City to face federal drug-trafficking indictments.
Six of Canada’s largest banks have begun work on a shared concept for moving tokenized Canadian dollar (CAD) deposits between financial institutions. The initiative, announced Tuesday, would represent bank deposits as digital tokens while keeping the deposits’ legal status tied to the issuing banks.
Bank of Montreal, CIBC, National Bank of Canada, Royal Bank of Canada, Scotiabank and TD Bank Group said the project’s first phase will concentrate on transferring tokenized deposits across Canadian institutions. The banks also hinted at possible later interoperability with other digital asset ecosystems.
Key takeaways
- Six major Canadian banks are jointly exploring tokenized CAD deposits as a way to move digital representations of deposits between institutions.
- The plan’s early scope is domestic interbank settlement; future steps could connect the approach to broader digital asset systems.
- OSFI recently clarified that tokenized deposits are “not legally distinct” from traditional deposits, supporting the effort from a regulatory perspective.
- Tokenized deposits differ from fiat-backed stablecoins because the deposits remain a liability of a regulated bank, not a separate digital asset issued by a third party.
- Canada’s stablecoin framework is progressing separately and is designed for fiat-backed stablecoins issued by non-financial institutions, not banks.
A joint effort to tokenize deposits—without changing their legal nature
In the announcement, the participating banks framed tokenized deposits as a mechanism to modernize payments. The core idea is to use digital tokens to represent deposits, enabling them to move more quickly and—according to the banks—support “programmable” payment features.
What investors and builders should notice is that the tokenization concept described here is not about converting deposits into a new category of asset that sits outside banking regulation. The banks’ approach is explicitly grounded in existing deposit structures: the tokenized product still corresponds to money held at a regulated bank and remains that bank’s liability.
This distinction matters because it shapes how risk and oversight are applied. According to OSFI’s earlier guidance, the underlying technology used to deliver a financial product does not determine its legal character.
Regulatory backdrop: OSFI’s clarification came earlier this month
Less than two weeks before the banks’ joint announcement, Canada’s banking regulator provided additional clarity on tokenized deposits. On Sept. 10, the Office of the Superintendent of Financial Institutions (OSFI) stated that tokenized deposits are “not legally distinct from traditional deposits.” OSFI also emphasized that legality is determined by the nature of the product, not by whether it is implemented on-chain or through another technology layer.
That timing is more than a coincidence. By aligning their work with OSFI’s interpretation, the banks are effectively operating in a clearer regulatory lane—one that treats tokenized deposits as functionally equivalent to conventional deposits from a legal standpoint.
Still, the banks did not lay out the end-to-end architecture in the materials referenced in the announcement. Readers should expect further details to come as the first phase develops, especially around custody, settlement finality, operational controls, and how interoperability would work in practice.
Tokenized deposits vs. stablecoins: Canada is regulating both, but differently
The new deposit-token initiative sits alongside a broader regulatory push for digital money in Canada, but the policy frameworks are not interchangeable.
Canada’s Stablecoin Act was enacted in March as part of Bill C-15. The legislation establishes a federal framework for fiat-backed stablecoins, requiring non-financial institution issuers to register with the Bank of Canada, keep reserves at least 1:1 in high-quality liquid assets, and enable redemption at par. The framework is expected to take effect in 2027.
However, the Act’s scope is narrower than the tokenized-deposits project. The stablecoin framework covers fiat-backed stablecoins issued by non-financial institutions; banks and credit unions already subject to prudential regulation are outside its scope. The legislation also restricts issuers covered by the framework from presenting stablecoins as deposits or as insured under a public deposit insurance system.
That separation explains why tokenized deposits are being explored by banks under deposit-style legal treatment, while stablecoin policy is aimed at different issuer types. Even though both approaches involve token-like instruments, the regulatory intent diverges: tokenized deposits aim to preserve the traditional banking liability structure, while stablecoin rules focus on how non-bank issuers back and redeem fiat-linked tokens.
What the next phase could mean for payments
The banks said their first phase will focus on moving tokenized deposits between Canadian financial institutions. If successful, that could reduce certain friction points in cross-institution payment flows by enabling more direct digital transfer of deposit-linked balances.
The banks also indicated that longer-term plans could involve opening the system to other deposit-taking institutions, and possibly connecting with other digital asset systems. That raises an important question for the market: whether tokenized deposits will remain primarily an interbank settlement tool within the regulated banking perimeter, or whether they will evolve toward wider interoperability with permissioned networks and, potentially, broader on-chain payment rails.
For now, the initiative is explicitly framed as a development effort. The article notes that Cointelegraph reached out to CIBC for additional details but did not receive an immediate response, suggesting that key technical and operational specifics have yet to be publicly clarified.
Over the coming months, market participants will want to watch how participating banks define the project’s scope in practice—particularly how they handle settlement finality, compliance controls, and whether the pilot results influence wider adoption across Canada’s financial sector—especially in light of OSFI’s recent regulatory clarification.
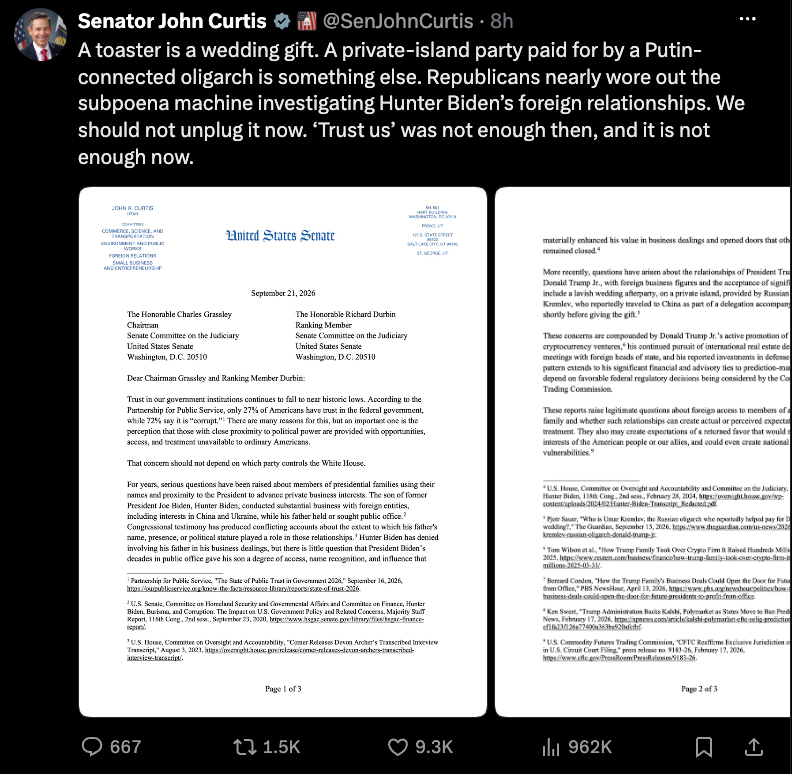
Senator John Curtis, a Republican representing Utah, sent a letter to leaders of the Senate Judiciary Committee calling for an investigation into US President Donald Trump’s and former President Joe Biden’s sons, citing the former’s involvement in the crypto industry.
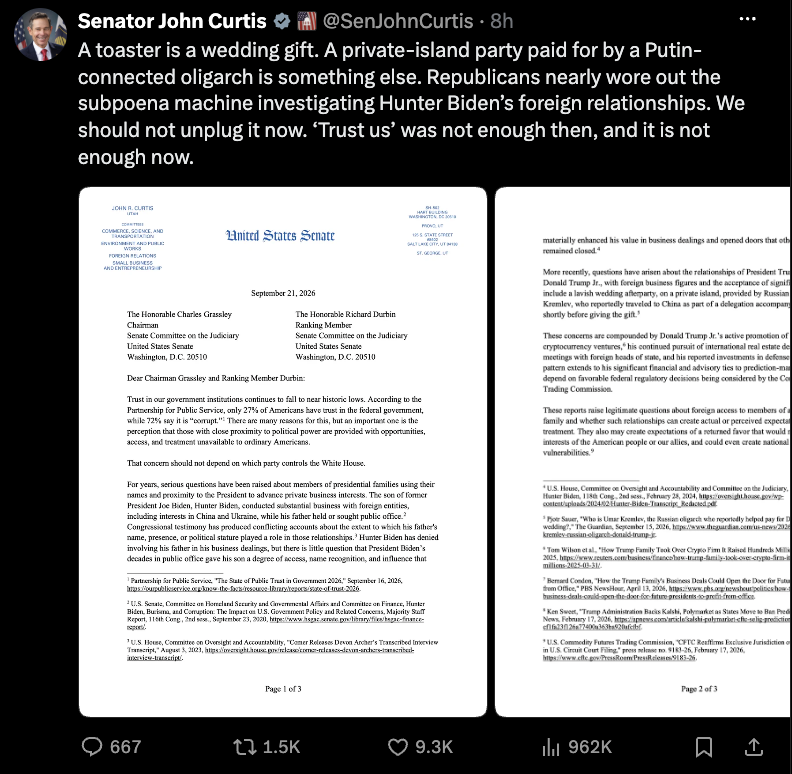
In a Monday letter to Senate Judiciary Committee Chair Chuck Grassley and ranking member Dick Durbin, Curtis said that the body should probe “the use of presidential family relationships for private financial benefit, preferential treatment, or access by domestic and foreign interest.” He also asked for subpoenas for Donald Trump Jr. and Hunter Biden, Joe Biden’s son.
The Utah lawmaker specifically called out Donald Trump Jr. for accepting gifts from Russian oligarch Umar Kremlev as part of his wedding, his “active promotion of family-backed cryptocurrency ventures” and advisory roles with prediction market platforms, as the companies are under the regulatory purview of the Commodity Futures Trading Commission. The president said last week that his son had paid Kremlev back for what Donald Trump Jr. and his wife called a “generous wedding gift.“
Curtis also called for a similar probe into Hunter Biden for “substantial business with foreign entities” and instances in which either man’s relationship to the presidency was “invoked or understood to provide value.” President Biden issued a pardon for his son in December 2024 for crimes he “committed or may have committed or taken part in over the last decade,” and Curtis noted that Hunter had “denied involving his father in his business dealings.“
“The purpose of such an inquiry should be straightforward: establish the facts, determine whether existing ethics, disclosure, or anti-corruption laws apply, and identify reforms necessary to prevent the presidency from becoming a vehicle for private enrichment by those closest to it,” said Curtis.
Source: Senator John Curtis
The call for an investigation into the Trump family’s ties to the crypto industry is nothing new for the current session of Congress, but it has largely come from House and Senate Democrats. Lawmakers have asked authorities to probe potential conflicts of interest surrounding Trump’s memecoin, his family’s World Liberty Financial business and a $500 million deal tied to Abu Dhabi’s royal family.
Curtis is serving his first term in the Senate and will not be up for reelection until 2030.
CLARITY still in limbo in US Senate as midterm elections approach
The call for an investigation into Donald Trump Jr. and Hunter Biden came a week after Senate Republicans failed to secure enough support from Democrats to pass the Digital Asset Market Clarity Act, a bill expected to establish market structure rules for the crypto industry.
One of the sticking points for not supporting the bill, according to some Democrats, was Trump “using crypto to turn the presidency into a profit generating machine.” The president disclosed that he had earned $1.4 billion from ventures tied to digital assets in 2025.
Republicans said the president had agreed to stronger ethics provisions in the bill affecting his crypto investments before the vote, but many Democrats argued that the measures did not go far enough to prevent corruption.
Magazine: Big Questions: Does Satoshi actually own 1.1 million Bitcoin?
Arch Lending is preparing to expand its credit offerings to include loans backed by tokenized equities, as lenders increasingly look for new collateral categories to support onchain borrowing. Co-founder and chief revenue officer Himanshu Sahay said the firm expects to move “pretty soon,” arguing that demand for credit against tokenized stocks is growing as the asset class scales.
Speaking on Cointelegraph’s Chain Reaction podcast, Sahay pointed to rapid growth in tokenized equities over the past year, while noting that lending capacity against those assets still appears limited. He expects more lenders to follow as tokenized stock products mature and become easier to use in collateral frameworks.
Key takeaways
- Arch Lending plans to add loans backed by tokenized equities, expanding beyond crypto-only collateral.
- Sahay links the push to growing tokenized stock issuance and a shortage of credit options that support borrowers.
- Arch has recently launched tokenized real-world asset loans backed by Paxos Gold and Tether Gold.
- Existing Arch lending is still crypto-led, with Bitcoin representing more than 80% of the loan book, and rising interest in XRP among US borrowers.
Arch’s next step: credit against tokenized stocks
Arch has already expanded beyond cryptocurrencies, launching loans backed by tokenized real-world assets including Paxos Gold and Tether Gold in recent weeks, according to Sahay. However, crypto remains the dominant collateral category in its current portfolio: Sahay said Bitcoin accounts for more than 80% of Arch’s loan book.
Even within crypto collateral, Arch is seeing shifting borrower preferences. Sahay said the lender has noticed growing interest in XRP as collateral, particularly among US borrowers—an indication that demand for specific asset types may depend on regional borrower needs and available liquidity rather than broad “market beta” alone.
Against that backdrop, tokenized equities represent a logical extension. Sahay cited the broader expansion of tokenized stock offerings from firms including Superstate, Robinhood, and Securitize, suggesting that a larger universe of onchain share tokens is being created—yet lending against those tokens remains relatively underdeveloped compared with more established collateral categories.
In practical terms, the appeal for lenders is straightforward: tokenized stocks and ETFs could enable borrowers to access credit without liquidating underlying exposure, while providing lenders with a collateral pool that may diversify beyond digital assets like BTC and ETH.
Why tokenized equity lending is gaining traction
Arch would not be entering the market first. Tokenized stocks and exchange-traded funds (ETFs) have been moving into collateral and lending products as infrastructure matures.
In February, Ondo Finance launched DeFi lending markets for two tokenized ETFs through an integration with lending protocol Morpho, according to Ondo Finance’s announcement. Ondo’s tokenized versions of the SPDR S&P 500 ETF and Invesco QQQ can be used as collateral for borrowing on Ethereum.
Beyond dedicated lending markets, tokenized equities are also starting to appear in adjacent functions tied to leverage and market operations. Kraken, for example, made 10 xStocks eligible to back futures and margin positions in July, according to Kraken’s product update. Coinbase also rolled out B20 stocks on Base in August, described as including price-feed infrastructure intended to support use cases that can include DeFi borrowing and lending, as previously reported by Cointelegraph.
The throughline across these developments is that tokenized equities are becoming more “programmable” within crypto ecosystems—an essential requirement for credit markets, where collateral eligibility, valuation, and liquidation mechanics determine whether assets can be reliably used in borrowing.
Market expansion: tokenized stocks grow faster than lending options
One reason lenders can justify moving into tokenized equity collateral is the scale of the underlying market. The article cites RWA.xyz data showing distributed tokenized stock value has climbed to about $3.15 billion, up from roughly $630 million a year earlier.
This growth suggests that more capital is being wrapped into tokenized formats that can, in principle, be used in DeFi lending and other credit structures. But the gap that Sahay highlighted remains important: despite rapid tokenized equities adoption, lending backed by these assets is still described as limited. For investors and borrowers, that difference matters because it can translate into fewer opportunities to access leverage or liquidity using those assets, as well as potentially less competitive borrowing conditions than in more mature collateral segments.
As more platforms begin to expand eligibility for tokenized stocks—whether through dedicated lending markets or through margin and futures pathways—the credit ecosystem could become more resilient. It may also normalize tokenized equities as collateral beyond niche experiments.
What to watch next for tokenized equity collateral
Arch’s planned expansion will likely be judged on several practical questions: how quickly it can integrate tokenized stock collateral, how lenders and borrowers manage valuation and risk across different issuers, and whether Arch’s approach aligns with broader market infrastructure being developed by other venues.
With tokenized stock value growing sharply and multiple crypto platforms already moving tokenized equities into lending-adjacent uses, the next phase will be less about whether lending is possible and more about whether it becomes competitive, scalable, and consistent enough to attract mainstream borrower demand.
In the coming months, readers should watch for Arch’s timing on tokenized equity-backed lending and for additional platforms to announce similar collateral expansions—signals that the market may be transitioning from early infrastructure pilots into fully functional credit offerings.
Crypto lender Arch Lending plans to expand into loans backed by tokenized equities as the market for onchain stocks expands and lenders begin exploring new uses for the assets as collateral.
Arch co-founder and chief revenue officer Himanshu Sahay told Cointelegraph’s Chain Reaction podcast that the lender plans to enter the market “pretty soon,” pointing to a need for credit against tokenized stocks.
Sahay said tokenized equities have grown rapidly over the past year, but lending against the assets remains limited, and predicted that more lenders will enter the market.
He pointed to tokenized equities issued by firms including Superstate, Robinhood and Securitize, predicting that multiple lenders will eventually participate in the market to provide credit against the assets.
Source: Cointelegraph
Arch has already expanded beyond cryptocurrencies into tokenized real-world assets, launching loans backed by Paxos Gold and Tether Gold in recent weeks, according to Sahay.
But crypto still dominates Arch’s existing loan book, with Bitcoin (BTC) accounting for more than 80%, Sahay said. He added that the lender has recently seen growing interest in XRP as collateral, particularly among US borrowers.
Related: Kraken brings DeFi yield to tokenized stocks and ETFs
Tokenized stocks enter lending markets
Arch would not be the first lender to enter the tokenized equity credit market, with tokenized stocks and exchange-traded funds (ETFs) already entering lending and collateral products.
In February, Ondo Finance launched DeFi lending markets for two of its tokenized ETFs through an integration with lending protocol Morpho. Ondo’s tokenized versions of the SPDR S&P 500 ETF and Invesco QQQ can be used as collateral for borrowing on Ethereum.
Tokenized stocks are also beginning to find uses beyond dedicated lending markets. Kraken made 10 xStocks eligible to back futures and margin positions in July, while Coinbase’s B20 stocks launched on Base in August with price-feed infrastructure designed to support uses including DeFi borrowing and lending.
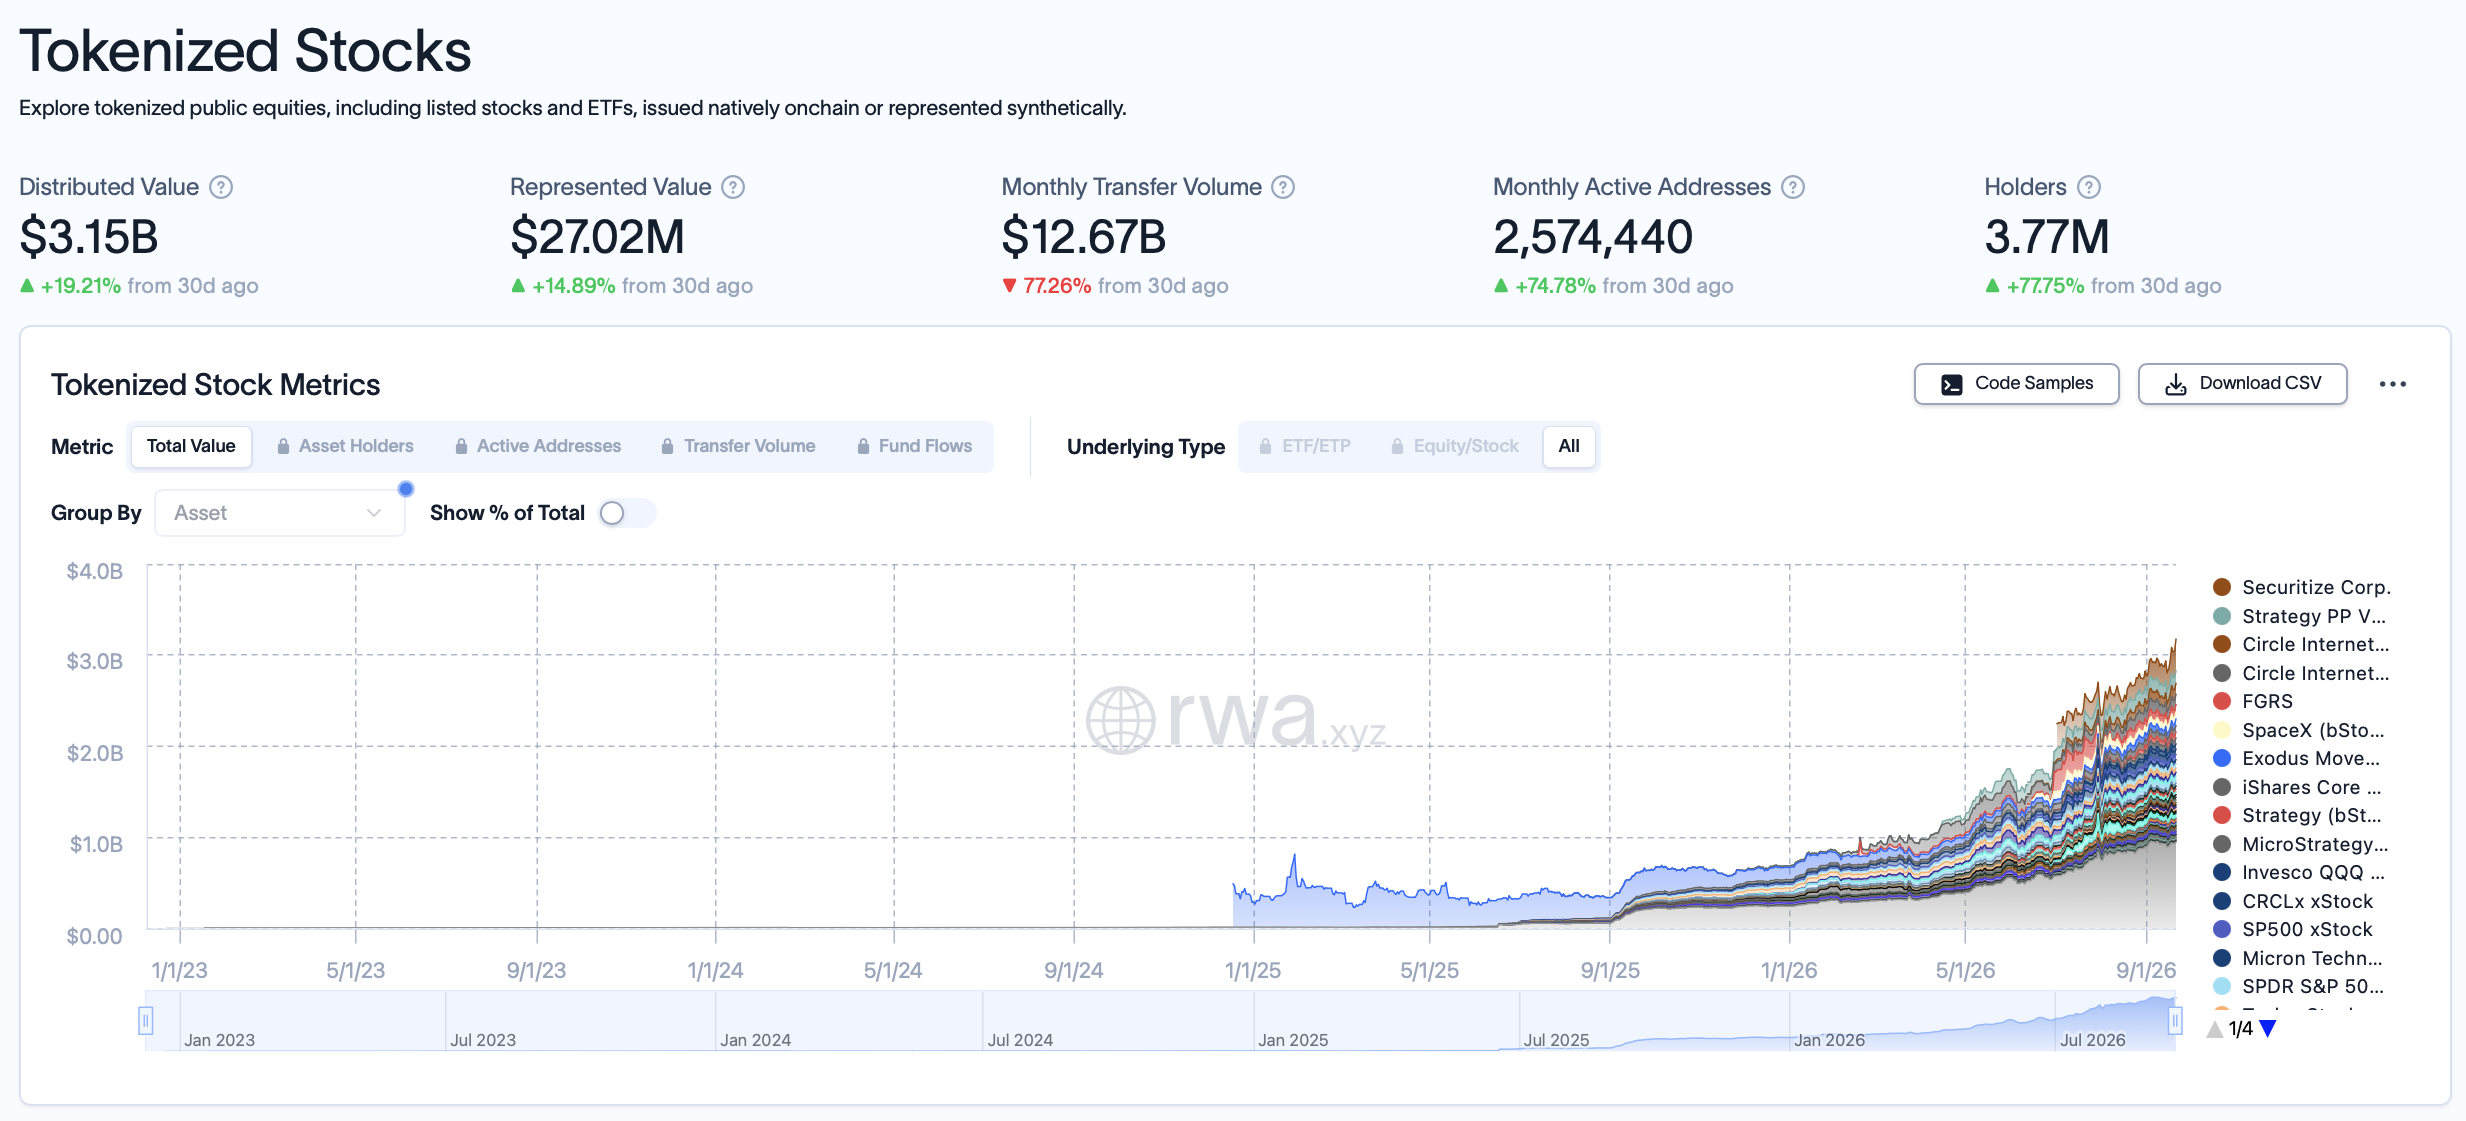
Tokenized equities. Source: RWA.xyz
The growth in lending use cases comes as the tokenized equities market itself has expanded sharply. Distributed tokenized stock value has climbed to about $3.15 billion from roughly $630 million a year ago, according to RWA.xyz data.
Magazine: Kyle Samani predicts SOL flippening, claims ‘no one’ uses ETH

NYT Strands hints and answers for Wednesday, September 23 (game #934)
Murder of prosecuter Rory O’Kelly ‘was carefully planned by Provisional IRA’

LARRY KUDLOW: Trump offers historic optimistic vision at UN




-

 Fashion4 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech2 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World4 days ago
Circle launches Arc Studio AI agent for building onchain apps
-
 NewsBeat4 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World2 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-

 Crypto World4 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Crypto World4 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World6 days ago
US Charges Robinhood Engineers Over Crypto Listing Trades
-

 Crypto World7 days ago
What Is the Status of the U.S.-Iran Peace Talks? Here's What Both Sides Are Saying
-
 Tech7 days ago
Webb’s IC 348 Mosaic Includes Two-Jupiter Dwarfs, Twin Jets, and a Nursery Still Making Worlds
-

 Crypto World5 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Crypto World4 days ago
World Money launches in 150+ countries with Stripe
-

 Crypto World5 days ago
Silver prices recover quickly, hitting weekly high today
-
 Entertainment7 days ago
Big Brother Update: Melody Explodes at Drew as Illness Sweeps BB28 House
-

 Business2 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Tech5 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-
 NewsBeat4 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-

 Crypto World2 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-

 Crypto World2 days ago
Bitcoin price holds above $81K as key catalysts line up
-
 Business7 days ago
Federal Reserve expected to hike interest rates 25 basis points at FOMC meeting
You must be logged in to post a comment Login