
Crypto World
Caris Life Sciences Coasts Past A Buy Point; Why This Texas Biotech Researcher Deserves A Look

Texas might not be the initial state that pops into mind when thinking about leading-edge companies in the field of biotechnology. But Irving, Texas-based Caris Life Sciences (CAI) is carving a name for itself within the stock market. Caris, Tuesday’s IBD 50 Stocks To Watch pick is rebounding fast after bottoming at 14.19 in May. Those investors looking for an entry…
Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8

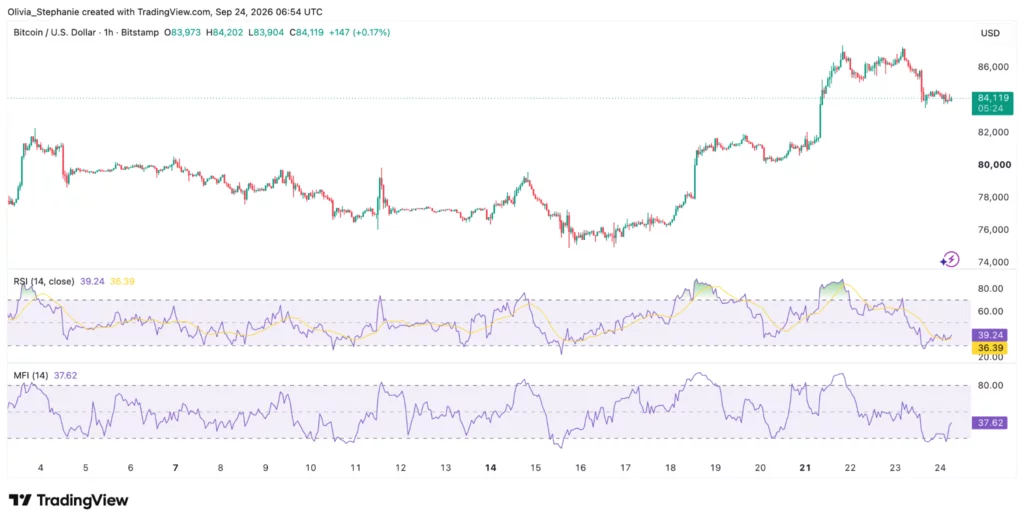
Bitcoin has traded near $84,000 on Sept. 24 after rejecting the $87,000 area, while 100–1,000 BTC wallets accumulated 113,950 BTC and U.S. spot Bitcoin ETFs extended their net inflow streak to five sessions.
Summary
- Bitcoin traded near $84,000 after retreating from $87,000 and meeting resistance around the $86,700 level.
- Wallets holding 100–1,000 BTC added 113,950 BTC since July 15, reaching roughly 5.24 million BTC.
- U.S. spot Bitcoin ETFs drew $346.98 million September 23, extending net inflows to five sessions.
- Binance Bitcoin open interest fell $500 million as leveraged traders reduced exposure after $87,000 push.
- Bitfinex placed a key buyer cost range between $85,000 and $86,500 after Bitcoin’s latest rally.
CoinGecko data showed Bitcoin at $83,863.54 during the latest check, down 3.8% over 24 hours but up 9.9% over seven days. Trading volume stood near $42.69 billion, while the asset’s market capitalization was approximately $1.685 trillion.
The pullback followed a run to $87,392 on Sept. 21, the highest print since Jan. 29, according to Bitfinex Alpha. In related crypto.news coverage of Bitcoin’s $83,600 Supertrend support test, BTC had already lost momentum after moving above $87,000 and falling back below $85,000.
Bitcoin price stays above Rekt Capital’s $82K support zone
Crypto analyst Rekt Capital said Bitcoin was meeting resistance around $86,700 after its breakout from the previous $60,000–$80,000 range. In a Sept. 23 post, the analyst described the resistance as “nothing too convincing for the time being,” while keeping attention on support below the market.
Rekt Capital said Bitcoin would need to remain above roughly $82,000, or successfully retest the area during a future dip, to stay positioned for bullish continuation. A later post placed the previous range high around $80,000 and said Bitcoin had not fully confirmed its breakout until that area had been tested as support. Both levels represent the analyst’s technical framework, not guaranteed price outcomes.
Meanwhile, on the one-hour chart, Bitcoin’s RSI stood at 39.38 while the Money Flow Index was 37.71. Both indicators remained below 50 after the pullback from the $86,000–$87,000 area, pointing to weaker short-term momentum without entering deeply oversold territory.
A separate crypto.news market analysis placed four-hour Supertrend support near $83,593 after Bitcoin fell from roughly $87,279.
Bitfinex Alpha described $85,000–$86,500 as a high-volume buyer cost area after the move to $87,392. Its Sept. 23 report said Bitcoin had reached a price area that separated lasting recoveries from failed rebounds during previous cycles, while continued ETF and corporate purchases remained part of its framework.
Bitcoin whales have added 113,950 BTC since July
Santiment posted that wallets holding between 100 and 1,000 BTC increased their combined balance by 113,950 BTC from July 15 through Sept. 23. The cohort’s holdings rose 2.22% to approximately 5.24 million BTC during the period. Independent reports citing the same Santiment dataset carried matching figures.
Santiment described the group as one of the wallet tiers that has tracked crypto market direction closely in its five-year analysis. The firm said accumulation by the cohort has often appeared before or during stronger price periods. Historical correlation, however, does not establish that changes in the group’s balances caused Bitcoin’s subsequent price moves.
Wallet data carries another limitation. An address does not represent a confirmed individual investor because one entity can control several wallets, while exchanges and custodians can move coins among addresses. The figures therefore document rising balances inside the 100–1,000 BTC cohort without proving that a known group of institutions or funds purchased the coins on the open market.
During the same period, Bitcoin recovered sharply from its July 1 low of $57,803, according to Bitfinex. The price reached $87,392 on Sept. 21 before retreating toward $84,000 this week.
U.S. Bitcoin ETF inflows have reached five straight sessions
SoSoValue-linked data reported $346.98 million in net inflows for U.S. spot Bitcoin ETFs on Sept. 23. BlackRock’s IBIT led with $166.29 million, followed by Fidelity’s FBTC at $143.24 million. Morgan Stanley’s MSBT received $32.41 million, while ARK 21Shares’ ARKB took in $5.04 million.
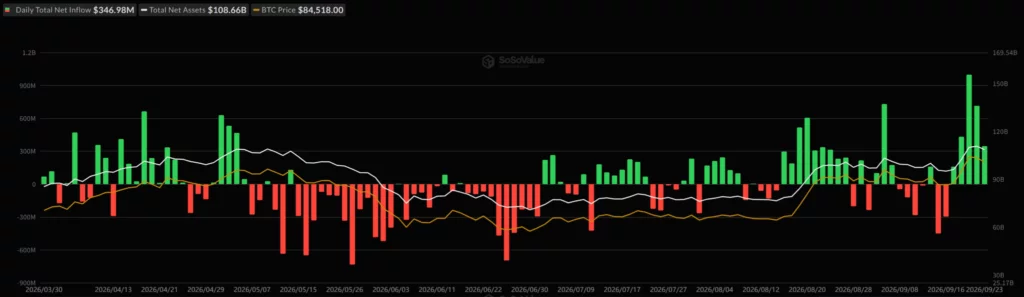
The Sept. 23 total extended the positive run to five trading sessions. The streak included $159.5 million on Sept. 17, $433 million on Sept. 18, approximately $999 million on Sept. 21 and $714.7 million on Sept. 22 before the latest $346.98 million reading. The five sessions brought combined net inflows to roughly $2.65 billion. Earlier crypto.news coverage examined Bitcoin ETF inflows during the move above $86,000.
Demand during the session extended beyond Bitcoin products. SoSoValue data showed U.S. spot Ether ETFs receiving $105 million on Sept. 23, led by BlackRock’s ETHA with $50.8 million and Fidelity’s FETH with $41.3 million. Grayscale’s ETH fund recorded approximately $4.1 million in net outflows.
Binance leverage has fallen faster than Bitcoin’s price
CryptoQuant analyst Amr Taha said Binance Bitcoin open interest fell from roughly $5.4 billion to $4.9 billion between Sept. 21 and Sept. 23. The $500 million reduction removed approximately 9.3% of outstanding positions while Bitcoin pulled back around 3.4% from the $87,000 area.
Taha reported that cumulative volume delta fell from nearly $3 billion to $1.48 billion over the same period, a decline of roughly 51%. He interpreted the combination of lower price, open interest and CVD as evidence that leveraged traders had reduced risk after Bitcoin failed to hold the push toward $87,000. The interpretation does not identify the individual traders behind the positions.
A separate CryptoQuant update dated Sept. 23 showed Binance BTC funding near 0.001%, close to neutral. Its author said funding around zero indicates that derivatives positioning has become less one-sided than during periods of aggressive leveraged-long activity.
Bitfinex, in its Bitcoin $85K buyer cost analysis, placed the next major cost area between $85,000 and $86,500, with the yearly open at $87,722 above it. The firm put the corporate treasury cohort’s average cost near $80,500 and said “a sustained move below $81,300,” particularly alongside ETF outflows, would challenge its reading of the breakout.
Disclosure: This article does not represent investment advice. The content and materials featured on this page are for educational purposes only.
Netflix (NFLX) stock has “a growing YouTube problem,” a Wall Street analyst said. Alphabet’s (GOOGL) YouTube is taking increasing viewer share from the subscription streaming video giant, he said. HSBC analyst Mohammed Khallouf on Tuesday downgraded Netflix stock to hold from buy and cut his price target to 76 from 96 as the company’s net income comes under pressure. On…
Copyright ©2026 Investor’s Business Daily, LLC. All rights reserved. 87990cbe856818d5eddac44c7b1cdeb8
The Trump administration is reportedly weighing a new push to expand the use of dollar-backed stablecoins outside the United States, framing the move as a way to strengthen the dollar’s role as the world’s reserve currency. According to Bloomberg, the plan could involve government support for stablecoin initiatives through joint ventures with private-sector partners, potentially bringing multiple agencies into the effort.
Bloomberg reports that officials are considering partnerships that would encourage the growth of dollar-denominated stablecoins internationally. If successful, such an approach could also increase demand for US Treasuries—an asset commonly used to back or support dollar-based stablecoins.
Key takeaways
- Bloomberg reports the US is considering overseas promotion of dollar-backed stablecoins through joint ventures with private firms.
- The proposed initiative may involve several agencies, including the Treasury Department, the State Department, and the US International Development Finance Corporation (DFC).
- A central rationale is to expand international usage of dollar stablecoins and, in turn, potentially boost demand for US Treasuries.
- The move comes as other regions develop their own cross-border digital payment systems and CBDC pilots.
- US officials have previously linked stablecoin growth to maintaining dollar dominance and supporting the US government debt market.
What Bloomberg says the administration is considering
Bloomberg, citing people familiar with the plans, reports that the US government may support stablecoin projects abroad by creating joint ventures with private-sector companies. While the report does not outline a formal timeline or specific program details, it describes the concept as an effort to expand the international footprint of dollar-denominated stablecoins.
The potential institutional scope is also notable. Bloomberg names the Treasury Department, the State Department, and the US International Development Finance Corporation (DFC) as agencies that could participate in the effort.
The logic described in the report is closely tied to how dollar-backed stablecoins are structured. Since many such tokens are designed to maintain their value relative to the dollar, and because their reserves are often linked to Treasuries and other dollar-denominated instruments, expanding usage overseas could translate into more demand for reserve assets associated with the token ecosystem.
Why dollar dominance is the policy driver
This stablecoin proposal fits into a broader theme reflected in earlier remarks by senior US officials: that stablecoin adoption can reinforce the dollar’s international standing and strengthen US financial market demand.
In February 2025, venture capitalist David Sacks—who at the time served as White House crypto and AI czar—said stablecoins could “extend the dollar’s dominance internationally,” adding that the sector might generate “trillions of dollars” in additional demand for US government debt. While such figures are projections rather than confirmed outcomes, they illustrate the administration’s stated perspective on stablecoins as a component of dollar-centered economic influence.
Later, in July 2025, US Treasury Secretary Scott Bessent connected stablecoin regulation to reserve-currency goals. He said the GENIUS Act—legislation that created a federal framework for payment stablecoins—could strengthen the dollar’s status as the world’s reserve currency, widen access to the “dollar economy,” and increase demand for US Treasuries.
Subsequently, the Treasury continued its implementation work. On Aug. 17, it issued a notice of proposed rulemaking seeking public comment on provisions covering the issuance, offering, and sale of payment stablecoins. Bessent described the rules as part of an effort to “cement” the dollar’s reserve-currency position.
Taken together, the overseas initiative described by Bloomberg appears to extend the administration’s domestic regulatory approach into an external growth strategy—an attempt to align stablecoin expansion with US strategic interests.
Global competition: CBDCs and cross-border digital rails
The timing of the reported stablecoin push also reflects a wider geopolitical and infrastructure trend: countries and regional institutions are building their own digital payment frameworks and experimenting with central bank digital currencies.
Cointelegraph previously reported that China’s digital yuan is used in Project mBridge, a platform designed for cross-border CBDC transactions. In Europe, the European Central Bank is preparing a 12-month digital euro pilot, expected to begin in the second half of 2027, according to Cointelegraph coverage.
While stablecoins and CBDCs are different instruments, both aim to facilitate digital value transfer across borders. In that context, an overseas effort centered on dollar-backed stablecoins can be seen as competing for the role of settlement and liquidity infrastructure in international payment flows.
What to watch next
Cointelegraph reports that it reached out to the US Treasury, the DFC, and several US-based stablecoin companies for comment but did not receive responses before publication. That leaves key questions unanswered, including whether the initiative is purely exploratory, what jurisdictions might be targeted first, and how any government involvement would be structured in practice.
Investors and builders should watch for concrete details—such as which agencies take the lead, what types of partnerships are contemplated, and whether the administration’s overseas goals come with measurable policy commitments tied to stablecoin reserve practices and cross-border compliance requirements.

Multicoin Capital has deposited another 130,331 HYPE worth $12.15 million into Coinbase Prime, bringing its transfers to the institutional platform since July 28 to 4.23 million tokens valued at $285 million.
Summary
- Multicoin Capital deposited 130,331 HYPE worth $12.15 million into Coinbase Prime after a one week break.
- Its total deposits since July 28 have reached 4.23 million HYPE worth roughly $285 million.
- HYPE pulled back after reaching a record $97.99 on Sept. 23, while Hyperliquid open interest recently hit $18 billion.
- The Coinbase Prime transfers do not confirm that Multicoin sold the tokens, as the platform supports institutional custody and execution.
Onchain analytics platform Lookonchain reported the latest transaction on Sept. 24, saying the deposit came after a one week break in similar transfers from the crypto investment firm. The movement does not confirm that Multicoin sold the tokens, since a deposit into Coinbase Prime can be used for custody or trading and does not show what happened to the assets afterward.
HYPE was trading near $92.50 at the time of writing, down roughly 4% over the past 24 hours, according to Coinbase data. The token remained around 17% higher than a week earlier after reaching a record $97.99 on Sept. 23.
Multicoin Capital HYPE deposits have reached $285 million
Lookonchain said Multicoin has deposited a combined 4.23 million HYPE into Coinbase Prime since July 28. Based on the values recorded at the time of each transaction, the transfers were worth approximately $285 million.
The latest 130,331 HYPE transaction represents roughly 3.1% of the total number of tokens moved to Coinbase Prime during that period.
Multicoin’s transfers have drawn attention because of its previous position on Hyperliquid. In June, crypto.news previously reported that the investment firm had made HYPE one of the largest positions in its liquid fund after accumulating the token since February. The firm outlined a base case in which HYPE could reach $319 by 2028.
Its valuation was based partly on Hyperliquid’s revenue and trading activity. Multicoin said the platform generated roughly $873 million in revenue from around $2.9 trillion in trading volume during 2025, while its user base grew from approximately 301,000 to 923,000.
The firm pointed to Hyperliquid’s token economics as another part of its thesis. Around 99% of protocol revenue was being used to repurchase HYPE, according to Multicoin’s June analysis, while Hyperliquid had no separate equity layer competing with token holders for the protocol’s economics.
At the same time, Multicoin identified regulation, competition, governance, decentralization and potential bad debt among the risks that could affect its projections.
Coinbase Prime transfers do not confirm HYPE sales
Sending HYPE to Coinbase Prime can place the tokens within infrastructure that institutional investors use for execution and custody, but the transaction alone does not establish that the assets have been sold.
A similar situation emerged in late July when another large holder moved HYPE to FalconX and Coinbase Prime after previously unstaking the tokens. The wallet had acquired 1.02 million HYPE at an average price of approximately $18, according to Lookonchain.
HYPE fell below $55 around the same period as the transfer, though the market was dealing with several factors, including weakness across crypto prices and the rollout of permissionless HIP 4 deployments on Hyperliquid’s testnet. The earlier report noted that moving tokens to institutional trading platforms did not prove that a sale had occurred.
Multicoin itself had substantial HYPE exposure earlier in the year. Arkham flagged three wallets it associated with the investment firm that had staked roughly 1.96 million HYPE on HyperCore in May, worth around $82 million at the time. The wallets collectively held roughly 2.83 million HYPE valued near $118 million.
The latest Coinbase Prime movement therefore provides evidence that another batch of Multicoin linked HYPE has been transferred to the institutional platform, while the available onchain data cited by Lookonchain does not establish whether those tokens were subsequently sold.
HYPE price pulls back after reaching a record
Multicoin’s latest transfer has arrived shortly after HYPE set a new record.
Coinbase data showed HYPE reached an all time high of $97.99 on Sept. 23 before pulling back to around $92.50 on Sept. 24. Despite the daily decline, the token remained approximately 17% above its level from one week earlier.
The rally had already gathered pace earlier in September. HYPE reached a previous record of $92.56 on Sept. 18 after Hyperliquid introduced manual USDC and USDT borrowing against HYPE and Bitcoin collateral.
Under the lending system, users can supply HYPE or Bitcoin and borrow stablecoins against the collateral. HYPE carries a 65% loan to value ratio, compared with 50% for Bitcoin.
The rise came after the market absorbed a large scheduled token release earlier in the month. Hyperliquid released approximately 9.92 million HYPE on Sept. 6, valued at roughly $820 million when the token was trading around $82.60.
Historical exchange flow data showed that unlocked supply had not automatically translated into equivalent selling. Following a previous March 2026 unlock, only around 1.75% of the released tokens reached exchanges during the following 30 days, according to an analysis of HYPE unlocks.
The September release made tokens claimable by core contributors and ecosystem participants whose allocations had been subject to vesting schedules. Unlocking the assets did not require recipients to sell them.
Hyperliquid open interest has reached a record $18 billion
Trading activity on Hyperliquid has continued to grow while HYPE trades close to its record price.
Hyperliquid’s open interest reached $18 billion on Sept. 23, setting a record and moving above the previous high of $16.36 billion recorded on Sept. 19. The figure stood above $13 billion at the end of August, putting roughly $5 billion more in outstanding positions on the platform within a few weeks.
Bitcoin, Ether and HYPE accounted for approximately $9.33 billion of that open interest. Activity has spread beyond crypto markets through Hyperliquid’s HIP 3 framework, which allows third parties to stake HYPE and launch perpetual markets tied to other assets.
Markets created through HIP 3 now include contracts linked to U.S. stocks, gold, crude oil, the S&P 500 and private companies. Lookonchain reported that cumulative trading volume across HIP 3 markets had surpassed $548 billion by early September, while the segment represented roughly 30% of Hyperliquid’s trading volume over the preceding 30 days.
Hyperliquid has continued using protocol revenue for HYPE purchases as trading activity has grown. OnchainLens data cited by Lookonchain showed that 32,770 HYPE worth approximately $2.65 million was repurchased and burned during a 24 hour period ending Sept. 12, at an average price of $81.01.
Cumulative burns had reached roughly 48.57 million HYPE at that point, equivalent to approximately 4.86% of the token’s maximum supply.
Investor confidence in stablecoins is tied to the issuer’s ability to redeem them for fiat currency at any time. To ensure that, stablecoin companies keep backup funds to secure their value. They hold actual U.S. dollars at a 1:1 ratio, alongside safe investments like U.S. government debt that earns interest.
Under the U.S. Genius Act law, stablecoin issuers are required to hold reserves including dollars and short-term Treasuries. Treasury Secretary Scott Bessent recently described dollar-backed stablecoins as a tool supporting the dollar’s dominance, noting that the dollar accounts for nearly 90% of the foreign exchange transactions.
With aggregate holdings approaching $200 billion, stablecoin issuers are already among the top 20 holders of U.S. sovereign debt, leaving behind reserves of several major nations.
Risks to EMs
While such a plan may strengthen the dollar, it could also create severe risks for emerging economies with current-account deficits that are vulnerable to capital outflows.
Because stablecoins enable money to move over blockchains, they bypass traditional banking channels, making it harder for central banks and governments to monitor and influence those flows. If dollar-backed stablecoins achieve widespread adoption in everyday transactions, domestic fiat currencies could come under intense pressure.
Both the International Monetary Fund and Bank for International Settlements have repeatedly sounded alarm on how USD-pegged stablecoins may pose risks to emerging economies, warning that they could accelerate capital flight from these countries in times of stress.
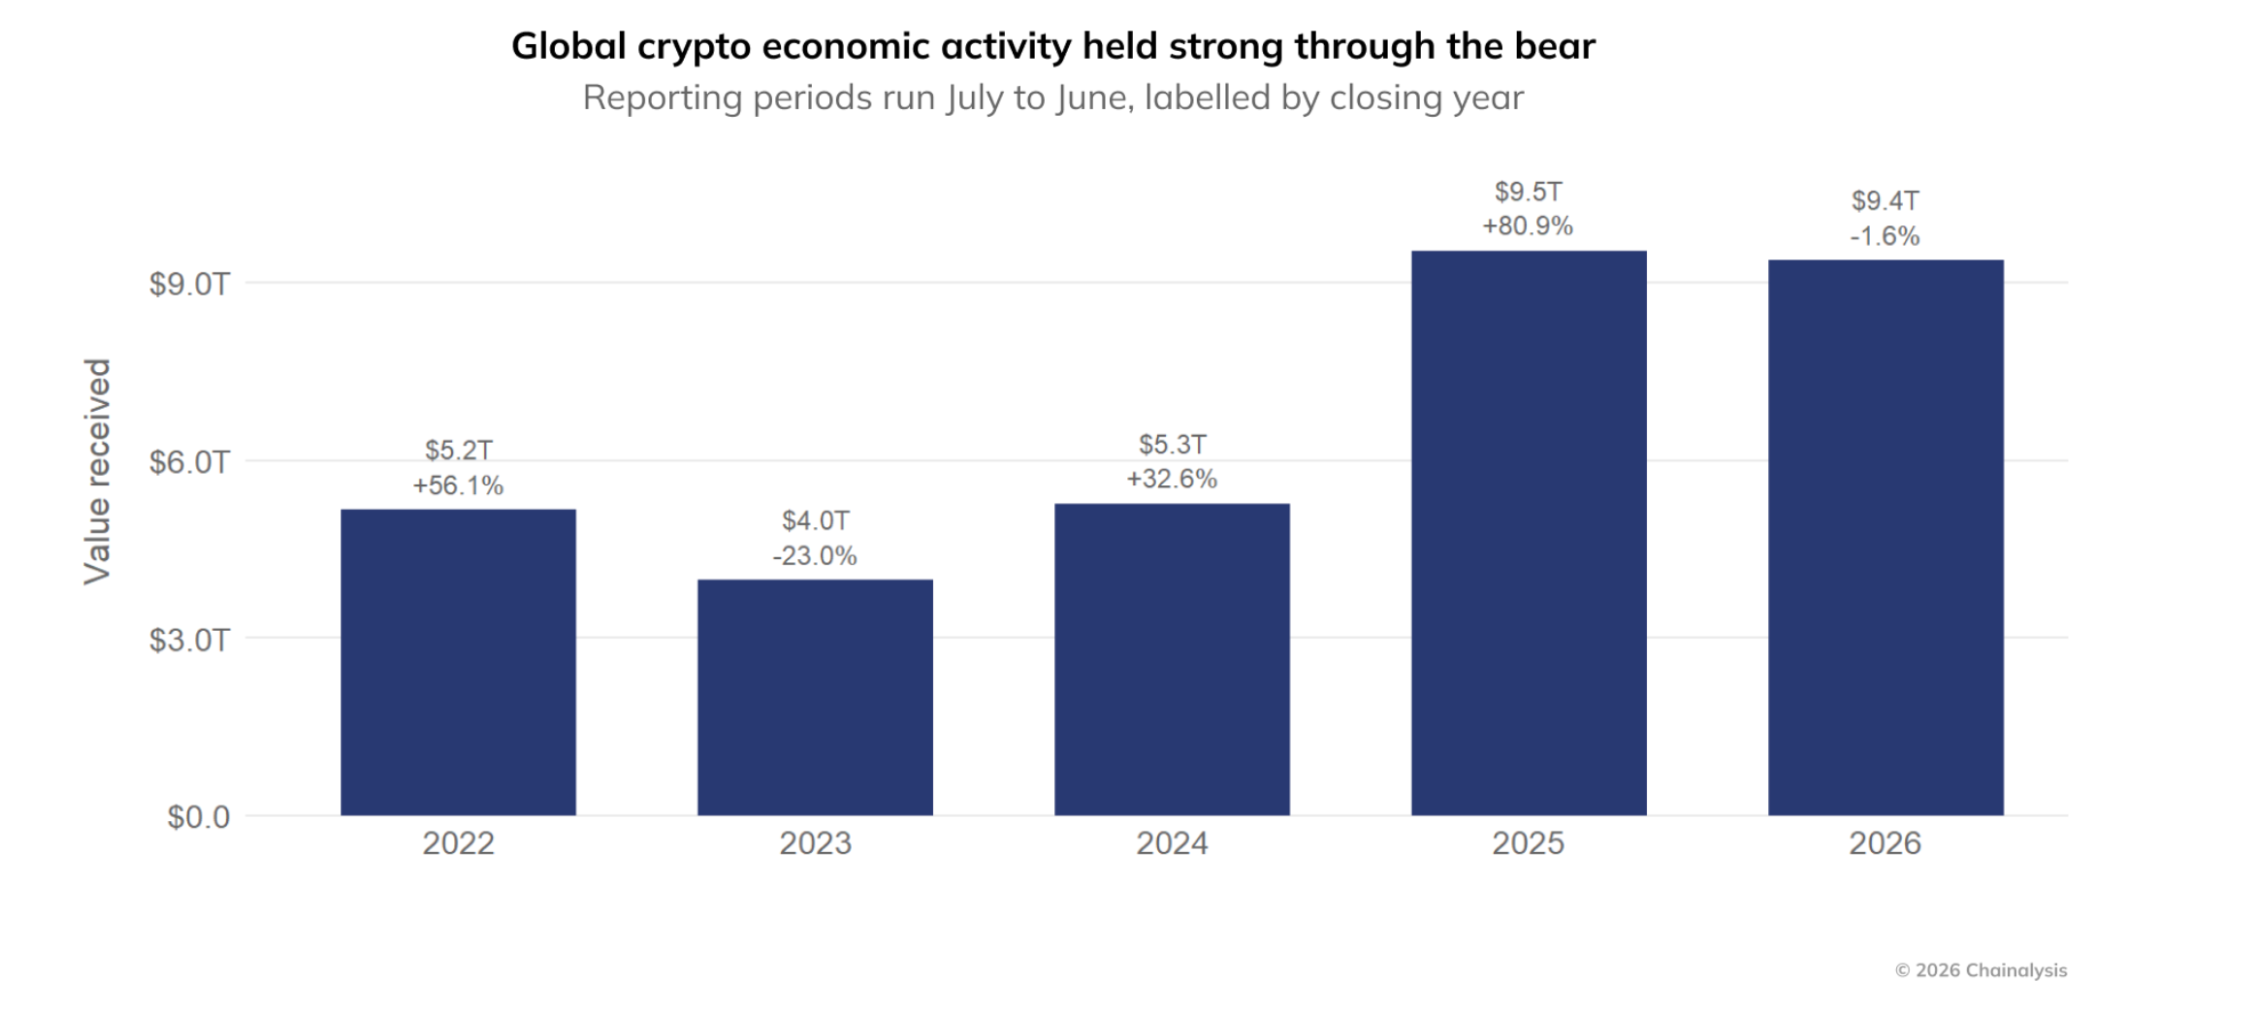
Brazil ranked as the world’s top country for grassroots crypto adoption in Chainalysis’ 2026 index. It beat the US as crypto’s market value roughly halved.
The country’s crypto economy reached $252.5 billion over the 12 months ending June 30. Worldwide, on-chain activity slipped just 1.6% while the market shed $2.1 trillion.
How Brazil Beat the US Without Winning a Single Category
Brazil ranked fourth or higher in every category the index measures. It came second in cross-border flows, third in service flows and domestic peer-to-peer (P2P) activity, and fourth in balances.
“In a year when bear markets stunted global growth, it continually delivered strong performance relative to its size, beating more established markets like the United States,” the report said.
That consistency decided the result because of how the index is built. Chainalysis scores each country from 0 to 1 for each category and then computes the geometric mean. The firm says this approach favors countries that score well across the board, so no single strong category can hide weak ones.
The US ranked first in both service flows and balances. However, it placed 11th in cross-border flows and 20th in domestic P2P transfers, leaving it second overall.
Brazil placed fifth in the firm’s 2025 ranking, which India led. Chainalysis rebuilt its methodology this year, so the two lists do not compare directly. Meanwhile, Latin America grew its crypto economy 9.8%, even as the global total shrank.
Follow us on X to get the latest news as it happens
Stablecoins Kept the Crypto Economy Moving as Market Value Halved
Brazil’s result came in what Chainalysis calls crypto’s worst bear market since 2022. Despite this, global activity remained near $9.4 trillion, down from $9.5 trillion a year earlier.

By comparison, the 2023 period saw a 23% decline in activity amid a market cap drop of just $0.3 trillion. Chainalysis credits a growing range of use cases for softening this year’s decline.
“Crypto’s growing diversity of use cases blunted the contraction,” it added.
Transfers between personal wallets inside countries rose 302.9% to $228.7 billion. Stablecoins now account for 96% of that flow. In contrast, inflows to exchanges, decentralized finance (DeFi) protocols, and other services fell 4.3%.
Cross-border stablecoin transfers climbed 77.5% to $220.3 billion, with the average payment near $3,000. Philip Gradwell, vice president of economics at Tether, told Chainalysis the pattern points to commercial use.
“Activity has become consistent, routed through wallets in a steady rhythm rather than in bursts. That is the signature of trade and business activity, not speculation,” he stated.
Stablecoin balances held between $98 billion and $109 billion through the downturn. Their share of global on-chain holdings rose to 22.5% by June as other assets lost value.
Subscribe to our YouTube channel to watch leaders and journalists provide expert insights
The post Brazil Outranks US in Crypto Adoption During Worst Bear Market Since 2022 appeared first on BeInCrypto.
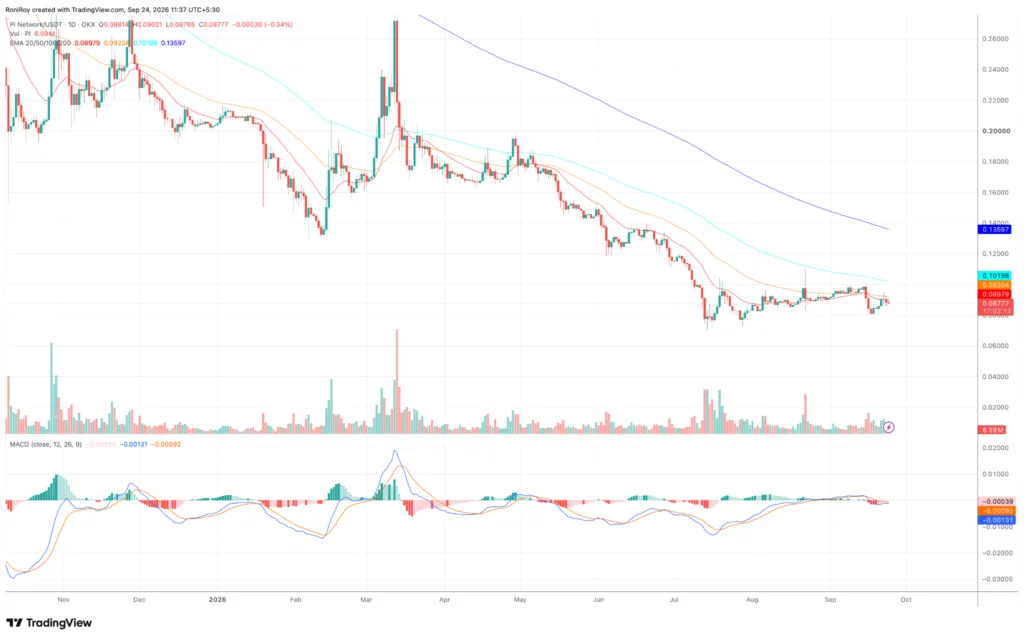
Pi Network price has fallen back below $0.09 on September 24 after its latest recovery failed near $0.093, leaving PI below its main daily moving averages as short term momentum weakened.
Summary
- PI has fallen below $0.09 after its latest recovery stalled near $0.093.
- Price remains below the 20, 50, 100 and 200 day EMAs, while daily MACD remains negative.
- A break below $0.085 could put the $0.080 to $0.082 support region back in focus.
- PI needs to reclaim $0.0898 and $0.0920 before the short term technical picture improves.
According to the PI/USDT charts, Pi Network was trading near $0.0878 at the time of writing, after opening the daily session around $0.0881 and falling as low as $0.08765. The pullback followed an attempt to recover above $0.09 earlier this week, but buyers were unable to keep the token above that level.
PI had already shown signs of losing momentum a day earlier. As crypto.news previously reported, the token reached $0.0926 on Sept. 23 before dropping back toward $0.088. The 50 day and 100 day moving averages were acting as overhead barriers during the move.
Recent Pi Network developments have been more positive on the network side. More than 417,000 users were cleared to continue KYC, while Protocol V27 progressed through testing. The price response has remained limited despite those updates.
Why is Pi Network price going down today?
PI’s latest decline comes after buyers failed to turn the recent move above $0.09 into a sustained breakout.
The daily chart shows PI trading below its 20, 50, 100 and 200 day exponential moving averages. The 20 day EMA currently sits around $0.08979, followed by the 50 day EMA at $0.09204.
Higher up, the 100 day EMA stands near $0.10198, while the 200 day EMA remains much further away at approximately $0.13597.
All four averages are arranged in bearish order, with the shorter term averages below the longer term ones. Price has spent most of September trying to build a base below the 20 and 50 day averages but has yet to hold above either.
Selling pressure returned after PI approached the same resistance area this week. The token’s failure around $0.092 is notable because traders were watching a similar zone during August. PI tested the $0.095 to $0.102 area during its August recovery but could not turn that move into a lasting breakout.
Daily MACD has weakened again following the latest rejection. The MACD line sits near minus 0.00131, below the signal line at roughly minus 0.00092, while the histogram has moved negative to around minus 0.00039.
Both MACD lines remain below the zero line. Momentum is considerably less negative than during PI’s June and July selloffs, but the indicator does not yet show enough buying pressure to confirm a trend reversal.
Pi Network upgrades have yet to translate into stronger demand
Price weakness has continued even as Pi Network works through several technical and user onboarding changes.
The Pi Core Team recently refined checks for accounts that had been flagged as possible duplicates, allowing more than 417,000 users to resume the KYC process. Another roughly 497,000 Fast Track wallets had been unable to claim migrated PI because they lacked the gas funds required for the transaction.
Protocol V27, meanwhile, moved to Testnet 2 after processing roughly 250 transactions per block. Earlier work around Protocol 27 infrastructure included smart contract authentication, automated market maker functions and RPC infrastructure.
PI has struggled to turn those developments into sustained buying demand. During an August rally, the token gained more than 10% and trading volume rose as Protocol 26 approached, yet the $0.0882 to $0.09 region was already acting as resistance.
Supply remains another factor hanging over the market. Roughly 1.21 billion PI tokens are scheduled to unlock during 2026, according to earlier estimates, while mainnet migration can turn previously inaccessible balances into transferable tokens.
A previous analysis of Pi Network’s 2026 token unlocks estimated the release pace at around 6.5 million PI per day. Actual selling depends on whether holders move newly available tokens to exchanges, so migration does not mean those tokens will automatically enter the market.
PI price risks another test of $0.08
The four hour chart shows the recent recovery losing momentum without confirming a strong new downtrend yet.
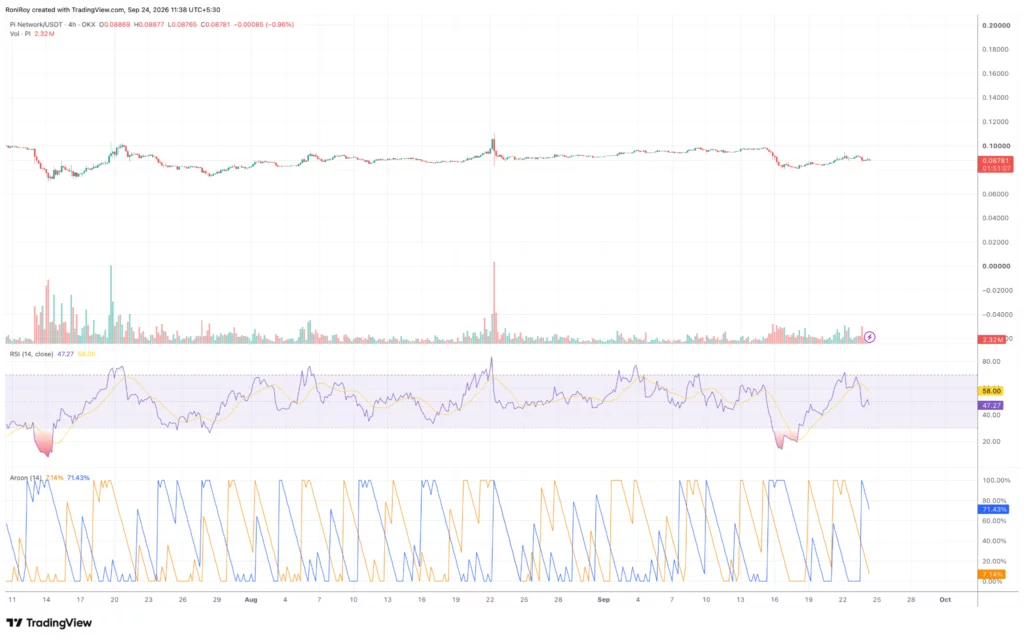
PI’s 14 period relative strength index has dropped to 47.27, down from above 70 during the Sept. 22 recovery. Its RSI moving average remains considerably higher at around 58.
An RSI reading below 50 gives sellers a slight momentum advantage, although PI is nowhere near oversold territory. A move below 40 would provide stronger evidence that selling momentum is building, particularly if price breaks its recent local lows at the same time.
Aroon paints a less bearish short term picture. Aroon Up remains around 71.43%, while Aroon Down sits at only 7.14%. The reading shows that the latest meaningful high remains more recent than the latest significant low, meaning the indicator has not yet confirmed a fresh four hour downtrend.
Immediate support sits around $0.085 to $0.087. PI has repeatedly traded around this region since its mid September decline, making a clean break below it the next technical test.
Failure to hold $0.085 could put the $0.080 to $0.082 region back in play. A larger selloff would leave the July price area around $0.071 to $0.075 as the next lower zone visible on the daily chart.
Buyers first need to reclaim the 20 day EMA around $0.0898. The 50 day EMA near $0.0920 forms the next hurdle, followed by the $0.096 to $0.10 region.
A move through those levels would bring the 100 day EMA near $0.102 into focus. Until then, PI remains below every major daily EMA while MACD stays negative and four hour RSI sits below 50, leaving $0.085 as the key level separating the current consolidation from another possible test of $0.08.
Bitwise has found that most crypto allocations among 15 institutional investors sat between 1% and 2% of investable assets, while none of the interviewed institutions cut exposure during the roughly 50% market decline from October 2025 through April 2026.
Summary
- 15 institutional allocators were interviewed between late March and April across seven major investor categories.
- Most surveyed crypto allocations ranged between 1% and 2%, while the full range reached 13%.
- Every crypto-owning institution interviewed held Bitcoin, usually as its first and largest digital asset position.
- None reduced crypto exposure during the 50% drawdown, while several institutions increased their positions instead.
- Almost every respondent uses or plans spot crypto ETFs, citing lower costs and operational burden.
Bitwise published its inaugural Institutional Crypto Adoption report on Sept. 23 after conducting 15 interviews between late March and April with senior investment professionals responsible for crypto allocation decisions. Participants came from endowments, foundations, public pension funds, sovereign wealth funds, multi-family offices, investment consultants and public companies.
The interviews lasted 30 to 60 minutes and covered sizing, governance, investment vehicles, rebalancing and exit conditions, with Bitcoin, Ethereum and Solana receiving particular attention. Bitwise did not identify the institutions, and its report says market figures were measured as of April 30 unless stated otherwise. The findings therefore describe the 15 interviewed allocators and should not be treated as a representative survey of the entire institutional market.
Bitwise survey puts most crypto allocations at 1%-2%
Across the full group, reported crypto exposure ranged from 0.5% to 13% of investable assets. Most allocations clustered between 1% and 2%, using combinations of spot ETFs, direct holdings, venture investments and hedge funds.
The numbers varied considerably by institution type. Endowments and foundations reported allocations from 0.5% to 10%, with most between 0.5% and 2%. Sovereign wealth funds in the sample reported 1% to 1.5%, while public pensions ranged from 1.5% to 4.5%. Multi-family offices reached as high as 13%, and Bitwise said family offices commonly targeted around 5%. Public companies reported allocating between 1% and 10% of excess cash.
During the roughly 50% crypto-market decline between October 2025 and April 2026, none of the 15 interviewed institutions reduced their allocation, according to Bitwise. Several increased exposure while prices fell. The finding applies only to the unnamed respondents and cannot establish how institutions outside the survey behaved during the same period.
Price declines were not listed as an exit trigger by any interviewee. Respondents instead cited reasons such as a breakdown in their underlying investment thesis, regulatory reversal, an industry credibility crisis or a failure of Ethereum and Solana activity to create value for their underlying tokens.
Some participants had already held crypto through earlier drops exceeding 50%, including the 2022 downturn. Bitwise said several continued working toward existing target allocations during the 2025-2026 decline, while others moved exposure from private placements toward direct holdings or ETFs.
Bitcoin remains the common institutional holding
Bitcoin was the only crypto asset held by every crypto-owning institution in the study.
For almost all respondents with crypto exposure, Bitcoin was their first, largest and longest-held digital asset. Several institutions held it independently, while market-cap-weighted crypto portfolios left some respondents with roughly 80% of their digital-asset allocation in Bitcoin.
Bitwise found that many institutions framed Bitcoin as a store-of-value position and compared it with gold. Some endowments had built positions in both assets as part of the same portfolio strategy, although one foundation rejected the digital-gold comparison and classified crypto as disruptive technology.
Ethereum and Solana received less consistent support. Institutions holding them generally used smaller allocations, shorter investment periods and explicit performance conditions. Several institutions owned neither asset because they said they could not clearly determine how network usage would translate into token value or how the assets should fit within existing portfolio classifications.
Respondents with ETH or SOL exposure tended to treat the assets as technology investments tied to network adoption. Some said they could sell within several years if growth in areas such as stablecoins, DeFi and tokenization failed to produce value for the tokens themselves.
Bitwise’s finding on Bitcoin is consistent with some public institutional filings, although those filings cover different investors. Harvard kept its 3.04 million-share BlackRock Bitcoin ETF position unchanged during the second quarter after reducing that publicly disclosed stake during earlier quarters.
Spot ETFs are becoming a common institutional route
Almost every institution Bitwise interviewed either used spot crypto ETFs or planned to use them. Respondents that moved from direct custody into ETFs cited lower total costs, fewer operational requirements and easier back-office handling. ETFs can fit into existing systems for custody, reporting and portfolio rebalancing without requiring institutions to build their own digital-asset infrastructure.
Not every institution preferred that structure. One sovereign wealth fund was developing domestic custody infrastructure because of a government mandate to control the underlying assets directly. A public endowment cited a policy prohibiting ownership of spot commodities, including through ETFs, while another investor preferred structures that avoided public Form 13F disclosure.
Bitwise therefore argued that institutional crypto exposure visible in 13F filings should be treated as a floor because the filings do not capture direct token ownership, many private funds or other non-reportable vehicles. Form 13F itself covers qualifying securities held by institutional investment managers and does not provide a complete view of every portfolio asset.
Recent public filings show how ETFs are appearing in endowment portfolios. The SEC received Dartmouth College’s second-quarter 13F on Aug. 13, covering holdings as of June 30. In related coverage, Dartmouth retained its Bitcoin, Ethereum and Solana ETF share counts during the second quarter even though their combined reported value fell with market prices.
Public data outside Bitwise’s anonymous group show that institutional behavior has not been uniform. Harvard exited its Ether ETF and reduced its Bitcoin ETF stake during the first quarter before holding its remaining IBIT shares steady in Q2. Because Bitwise did not disclose the identities of its respondents, there is no basis to assume Harvard was included in its 15 interviews.
Governance still limits larger crypto allocations
Bitwise found that operational structure and internal governance remained major constraints on allocation size.
Respondents raised custody, portfolio classification, committee approvals and reputational concerns more often than questions about whether crypto could produce investment returns. One multi-family office summarized its approach as “Just have a process.”
Approval structures differed sharply. Some investment teams could make an allocation internally, while one sovereign wealth fund reported scrutiny from central-bank leadership involving security reviews, executive background checks, public perception and comparisons with peer institutions.
Family offices generally faced fewer approval layers, helping explain why allocations in that group reached the highest level in Bitwise’s sample. Public pensions faced boards, beneficiaries, elected officials and media scrutiny, while sovereign funds described longer decision processes involving committees and public-sector oversight.
Career risk appeared repeatedly among public-facing institutions. Foundations, pensions and sovereign wealth funds told Bitwise that professional and reputational consequences could influence whether an allocation received approval, even when the investment team supported the underlying thesis.
Bitwise expects a majority of institutional investors to hold crypto within five years, but the firm presents that statement as its own outlook, not a result established by the 15 interviews. Its report lists regulatory development and peer adoption as possible drivers while warning that a major crypto failure or weak real-world adoption could delay further allocations.
Several sovereign wealth funds interviewed by Bitwise remained in active due diligence on potential crypto positions, with some already invested and others still conducting research. One respondent said building the legal and regulatory infrastructure required to deploy sovereign capital could take more than a year.
Introduction
SimpleSwap and SecureShift have been routing swaps for each other for five years. Over that time, one thing has stayed constant on both sides: we build around privacy, and we take it seriously enough to argue about what it means. For most of crypto’s history, the answer was a coin. You held Monero, or you did not. In 2026, the question has moved to how value travels: which networks a swap touches and what each leg leaves behind.
For the anniversary, we did something more useful than a press release. Each team wrote down the observations it believes will shape where privacy goes next, an aggregator on one side and an instant exchange with a hybrid XMR model on the other. Six in total; none of them made a prediction about price. Read them, disagree with them, and tell us where you see it differently.
Part 1. What SimpleSwap sees
1. A private asset’s guarantees end at the swap boundary
In its Big Ideas for 2026, a16z crypto’s Ali Yahya called privacy the most important moat in the industry and put the problem in one line: bridging tokens is easy; bridging secrets is hard. Once a shielded asset becomes a different asset on another chain, the original asset’s properties remain behind.
SimpleSwap’s H1 2026 Swap Report shows how often that boundary gets crossed: 91.8% of swaps moved value between two networks, seven in ten had a leg outside the four largest chains, and stablecoins ended the half with a 9.2-point net gain in the share of sent vs. received. The typical swap changes both the asset and the rate. Privacy has to be discussed at the route level, because that’s where the guarantees change hands.
2. Privacy now has a number
The case for on-chain privacy used to rest on principle. In 2026, it rests on data. Blockworks’ Q1 2026 Zcash report put the shielded pool at 5.16 million ZEC, 31.0% of circulating supply, up from 18% in October 2025 by The Block’s count. Shielding requires an on-chain action, so analysts read it as usage rather than positioning. Regulated wrappers followed: The Block reported the Grayscale Zcash Trust’s daily volume doubling in April 2026 to about $1.7 million.
What is built into this demand is not concealment but selectivity: viewing keys and proofs that a transaction meets a rule without exposing the transaction itself. SimpleSwap’s own position is descriptive. The service is self-custodial: funds move between wallets the user controls, and the platform applies risk-based controls, including transaction screening and monitoring, as set out in its Anti-Financial Crime and KYC Policy. The reason is the nature of a public ledger. Crypto funds carry a history from previous wallets and counterparties, and that history can affect a transaction without the current sender knowing. When information identified during screening requires further review to meet legal or compliance obligations, the swap may be paused, and KYC may be required to ensure transaction security and compliance. A pause is not an accusation; it means the transaction context has to be clarified before the case can move forward. A private user and a controlled service are not opposites; the interesting engineering of 2026 lies at their intersection.
3. The leak moved from the chain to the browser
On 25 June 2026, Polymarket confirmed that a compromised third-party vendor had injected malicious JavaScript into its frontend. External investigators estimated that close to $3 million in PUSD was drained from at least 11 wallets before the dependency was removed. Polymarket said affected users would be refunded in full. Its smart contracts were not touched. The attacker inserted themselves between the user and the interface, and the interface constructed the transactions that the wallets then signed.
A connected wallet exposes an address, a balance, an approval history, and a signing surface to every script a page loads. A deposit-address swap exposes far less: the user receives an address and sends from a wallet they control, with nothing to connect and nothing to sign in a browser. The domain and the receiving address still need to be checked manually. In August, the work at SimpleSwap went into what sits behind those routes: new routes were added to the pool, and private transfers became available on selected pairs.
“Users think about privacy at the level of the asset. Routing forces you to think about it at the hop level. Every network boundary is where one set of properties ends, and another begins, and an aggregator sees more of those boundaries than any single venue does.” Stefan Lauer, Head of Infrastructure at SimpleSwap
Part 2. What SecureShift sees
4. Privacy is becoming a property of the route, not just the asset
SecureShift’s hybrid DEX model reflects a practical problem with moving between Monero and transparent assets. The decentralized side of the swap handles the transparent-chain legs, while XMR can be accessed through a custodial bridge using USDC or USDT as the intermediary asset. In other words, the route does not treat XMR as an isolated endpoint. It treats the swap as a sequence of different settlement environments, each with its own properties.
That distinction matters because a swap between XMR and a transparent asset does not preserve the same privacy characteristics across all legs. The XMR portion has Monero’s own transaction model, while the intermediary stablecoin leg operates on a transparent blockchain. SecureShift’s current DEX infrastructure supports XMR alongside BTC, ETH, SOL, BNB Chain, and other networks, with XMR pairs visible across its live swap activity.
The broader lesson is that privacy cannot be evaluated only by asking which asset is being received. It has to be evaluated by asking how the value got there.
5. XMR demand is spreading across routes and networks
One change SecureShift has observed in 2026 is that privacy-related demand is increasingly expressed through the routes users choose rather than through a single dedicated privacy market. XMR is now part of a broader multi-chain swap environment: SecureShift currently lists Monero alongside Bitcoin, Ethereum, Solana, BNB Chain, Arbitrum, and other networks, while its live activity shows XMR being exchanged against BTC, ETH, USDT, and other assets.
That matters because the user’s decision is no longer simply whether to hold a privacy-oriented asset. It is also which network to enter from, which asset to use as an intermediary when necessary, and where the final asset will settle. SecureShift’s wider exchange currently supports thousands of currencies and reports an average exchange time of 2 to 10 minutes, showing that privacy-related routes increasingly reside within the same infrastructure as ordinary cross-chain swaps rather than existing as a separate category.
From the exchange side, the interesting signal is therefore not just demand for XMR itself. It is the continued demand for routes that include XMR as one leg of a larger cross-chain transaction.
6. The next privacy layer is route transparency
The growth of multi-chain swapping creates a second privacy question: not only what a user sends and receives, but what happens between those two points. A route can cross several networks, assets, and liquidity sources before the final asset reaches the user’s wallet. Each additional leg can have different transaction visibility and different assumptions about custody.
SecureShift’s DEX architecture is built around this multi-chain reality. Its DEX supports cross-chain swaps while keeping the settlement of supported decentralized legs on-chain, and the platform currently lists more than 1,300 token pairs on its DEX interface. The hybrid XMR model adds another layer by using USDC or USDT as a bridge when moving between the XMR environment and transparent networks.
This suggests a change in how privacy should be discussed. Users increasingly need to understand the route itself: which asset is used at each stage, which network records each leg, and where custody enters the process. Privacy is no longer a single feature attached to the coin. It is something assembled, and sometimes lost, one hop at a time.
“Privacy is no longer only about the asset someone holds. In a multi-chain swap, it also depends on how that asset travels, which networks it touches, and what each leg reveals.” Sanket Mishra, Founder & CTO, SecureShift
What stays on the user’s side
A piece about privacy written by two services should end where the responsibility sits, not with the services. None of this is exotic.
- Check the domain before every deposit. SimpleSwap’s only official domain is simpleswap.io; SecureShift’s is SecureShift.io. Lookalike domains are the most common way funds vanish.
- Verify the receiving address character by character on a device you trust.
- Select the network deliberately. An asset sent on the wrong chain is usually not recoverable by any service.
- Know what a route exposes. A swap from a private asset to a transparent one results in a transparent transaction. Decide whether that matters before you send.
- Never share a seed phrase or private key. No swap service needs it.
- Save the order ID before sending. It is the only handle support has if a transaction stalls.
Privacy in 2026 is not something a token grants, nor something a service guarantees. It is a property of a route, assembled from choices the user makes one leg at a time.
About SimpleSwap and Secureshift
SimpleSwap is a self-custodial, multi-source swap aggregator that helps users exchange crypto wallet-to-wallet with more control, without having to compare providers and routes themselves. It supports direct wallet-to-wallet swaps across 20+ liquidity providers and 2,800+ swappable assets, combining liquidity from well-known CEX and DEX sources under the hood.
SecureShift is a hybrid, self-custodial crypto swap platform that helps users exchange digital assets wallet-to-wallet with greater control, without having to manually compare providers and liquidity routes. It combines liquidity from centralized exchanges and decentralized protocols to find efficient swap routes across a wide range of networks and assets, including BTC, ETH, XMR, SOL, ZEC, TRX, SUI, and more. SecureShift also supports advanced swap features, including private swaps, DEX routing, and automated AML-based refund handling.
StarkWare says the estimated computing cost to construct a “quantum-safe” Bitcoin transaction has dropped sharply after a week of optimization work, falling to around $67—down from roughly $320 for the first such mainnet transaction in August.
The improvement comes from participants in the Quantum-Safe Bitcoin Optimization Challenge, which targeted the GPU-heavy steps needed to build a transaction using the Quantum-Safe Bitcoin (QSB) design. StarkWare cautions that the newest figures are based on benchmark results rather than fresh on-chain deployments, but the direction suggests the approach could become more practical for emergency use.
Key takeaways
- StarkWare reports the estimated QSB transaction preparation cost is now about $66–$67, down from about $320 in August.
- The cost reduction followed optimization contributions from the Quantum-Safe Bitcoin Optimization Challenge, which ran for about a week.
- StarkWare says the challenge produced 62 accepted improvements across two tasks needed to prepare QSB transactions.
- Despite the lower estimates, StarkWare notes the latest gains are demonstrated in benchmarks, not confirmed through additional mainnet transactions.
- QSB is presented as a quantum-resilience “emergency” measure that does not require changes to Bitcoin consensus rules—though StarkWare still favors protocol-level upgrades for long-term protection.
Cost of quantum-safe construction falls again
StarkWare said that after a week of iterative optimizations by challenge participants, the computational estimate for preparing a QSB transaction fell by roughly 79%. In its Sept. 23 update, the company argued that moving from “a few hundred dollars” toward the $60s brings the method closer to what a Bitcoin holder could consider during an urgent scenario.
StarkWare adds that the live dashboard for the QSB challenge now displays the current estimate at $66. The company previously pointed out that earlier demonstrations involved higher GPU requirements and therefore higher costs.
What QSB is—and why the network doesn’t need to change
QSB was first published by StarkWare researcher Avihu Levy in April. The design aims to provide hash-based protection intended to reduce the risk posed by future quantum attacks, while avoiding changes to Bitcoin’s consensus rules. In Levy’s earlier framing, the approach was considered a “last resort” option because of cost, complexity, and limited applicability—concerns that the new optimization work is directly addressing.
The underlying idea is to add a layer of defense without requiring the Bitcoin network to adopt new rules. That “no consensus changes” property matters for holders because it can allow quantum-resistance steps to be taken with specialized tooling rather than waiting for a widely deployed protocol upgrade. However, that same constraint can limit how broadly such a system can be used in the near term.
From the first mainnet transaction to benchmark-driven reductions
StarkWare ties the earlier baseline to the first QSB transaction mined and confirmed on Aug. 26. The company previously reported engineering work from Tomer Giladi and submission through MARA’s Slipstream service, with preparation requiring approximately 3,100 GPU-hours across roughly 100 GPUs.
StarkWare estimated the compute cost for that first mainnet transaction at about $320, excluding Bitcoin network fees. The latest update changes the picture on estimated preparation expense: StarkWare says the optimization challenge reduced the estimated computing cost based on benchmarks.
To find efficiency gains, StarkWare, Yukon Research, and Eigen Labs launched the Quantum-Safe Bitcoin Optimization Challenge on Sept. 16, inviting developers, researchers, and AI agents to improve the transaction-building pipeline. In the latest update, StarkWare said the effort resulted in 62 accepted improvements across two computational tasks needed for QSB transaction preparation.
While that work is reflected in benchmark cost estimates now shown on Yukon’s QSB dashboard, StarkWare’s update still leaves an important gap: readers should treat the new $66–$67 figure as an estimate for construction workflows, not as proof that the same cost can be reproduced for additional live on-chain transactions yet.
Why holders may care—and what remains uncertain
The renewed focus on cost comes as concern continues to grow in the crypto community that a sufficiently powerful quantum computer could eventually undermine Bitcoin’s elliptic-curve digital signature system. If attackers can exploit that weakness, coins exposed by their public keys could become vulnerable—though real-world timelines and feasibility depend on engineering breakthroughs that remain uncertain.
Against that backdrop, StarkWare positions QSB as an “emergency” measure—useful if and when quantum risks become immediate enough to justify expensive operational work. The sharper cost estimates may increase the likelihood that QSB could move from a proof-of-concept into a more realistic option for holders with a larger balance who can justify special preparation in advance.
At the same time, StarkWare reiterates a key strategic tension: the company still prefers a soft fork—meaning changes to Bitcoin’s consensus rules—as the better “long-term answer” for broad, durable quantum protection. The optimizations therefore appear to strengthen the near-term toolkit around QSB, while the longer-term debate over protocol-level defenses continues.
What to watch next is whether the benchmark-driven reductions can translate into additional on-chain QSB transactions at similar cost levels, and whether broader community attention shifts from experimental benchmarking toward practical integration and planning for quantum-era safeguards.
Middlesbrough appeal launched to help surfing dog Hattie

OpenAI, Anthropic CEOs warn AI could pose threat to humanity

Bitcoin price nears $84K as ETF inflows reach five days

Weekend Open Thread – Corporette.com

Weekend Open Thread: Talbots – Corporette.com

Memory prices are slowing because buyers ran out of money

RUMUS BEBAS FINANSIAL UPAN HARIAN 160 RIBU #financialeducation #keuangan

WHY XRP IS A BLUE CHIP? – XRP SUPPLY SHOCK IS IT POSSIBLE! – WHY XRP AT $100 IS POSSIBLE!

Housing Market Logic Exposes Surprising Rent Financial Traps
-
 Fashion6 days ago
Weekend Open Thread: Talbots – Corporette.com
-

 Tech3 days ago
Researchers escape OpenAI Codex sandbox to run commands on host
-

 Crypto World5 days ago
Circle launches Arc Studio AI agent for building onchain apps
-

 Crypto World3 days ago
Who Needs CLARITY Anyway? ARB Could See 70X Increase: Hodler’s Digest
-
 NewsBeat5 days ago
Trump says US has reached an agreement to take permanent control of Greenland’s security
-

 Crypto World1 day ago
Goldman Sachs and Deutsche Bank Agree: The S&P 500 Rally Isn't Over
-

 Crypto World5 days ago
Trading Bitcoin on Robinhood? Why 2% Spread Has Traders Worried
-

 Crypto World6 days ago
Mortgage and refinance interest rates today, Thursday, September 17, 2026
-

 Crypto World5 days ago
Bitcoin price breaks channel as RSI climbs to 63
-

 Tech3 days ago
Google’s $899 Googlebook is a bet that you’ll buy a new laptop for Gemini
-

 Business3 days ago
Analog Devices (ADI) Bets $1.35 Billion on Chips that Let Machines Think for Themselves
-

 Crypto World3 days ago
Coinbase, Robinhood, Circle Seen as Tokenized-Stock Winners
-
 Business1 day ago
Oil Price Today (September 23): Crude oil below $100 on hopes of US-Iran talks. What did Trump say?
-

 Tech6 days ago
GPT-6 Astra Reached the Nether in Minecraft, Lost Its Stash to a Creeper, and Farmed Potatoes for Hours
-

 Crypto World5 days ago
World Money launches in 150+ countries with Stripe
-

 Tech4 days ago
Trump suggests rebranding AI with a new name, says he’s also creating an AI Force
-

 Crypto World6 days ago
Silver prices recover quickly, hitting weekly high today
-

 Crypto World3 days ago
Bitcoin price holds above $81K as key catalysts line up
-
 NewsBeat5 days ago
US was ‘on brink of war’ with China over false AI report of nukes moving in Middle East
-

 Crypto World2 days ago
Meta Jumps 11% As Muse Shines and Investors Show an Appetite for Advancing AI
You must be logged in to post a comment Login