Business & Hustles
Lagarde Resignation Sets Feb. 7 Exit, Opening a Race to Lead the ECB as Inflation Hits 3.8%

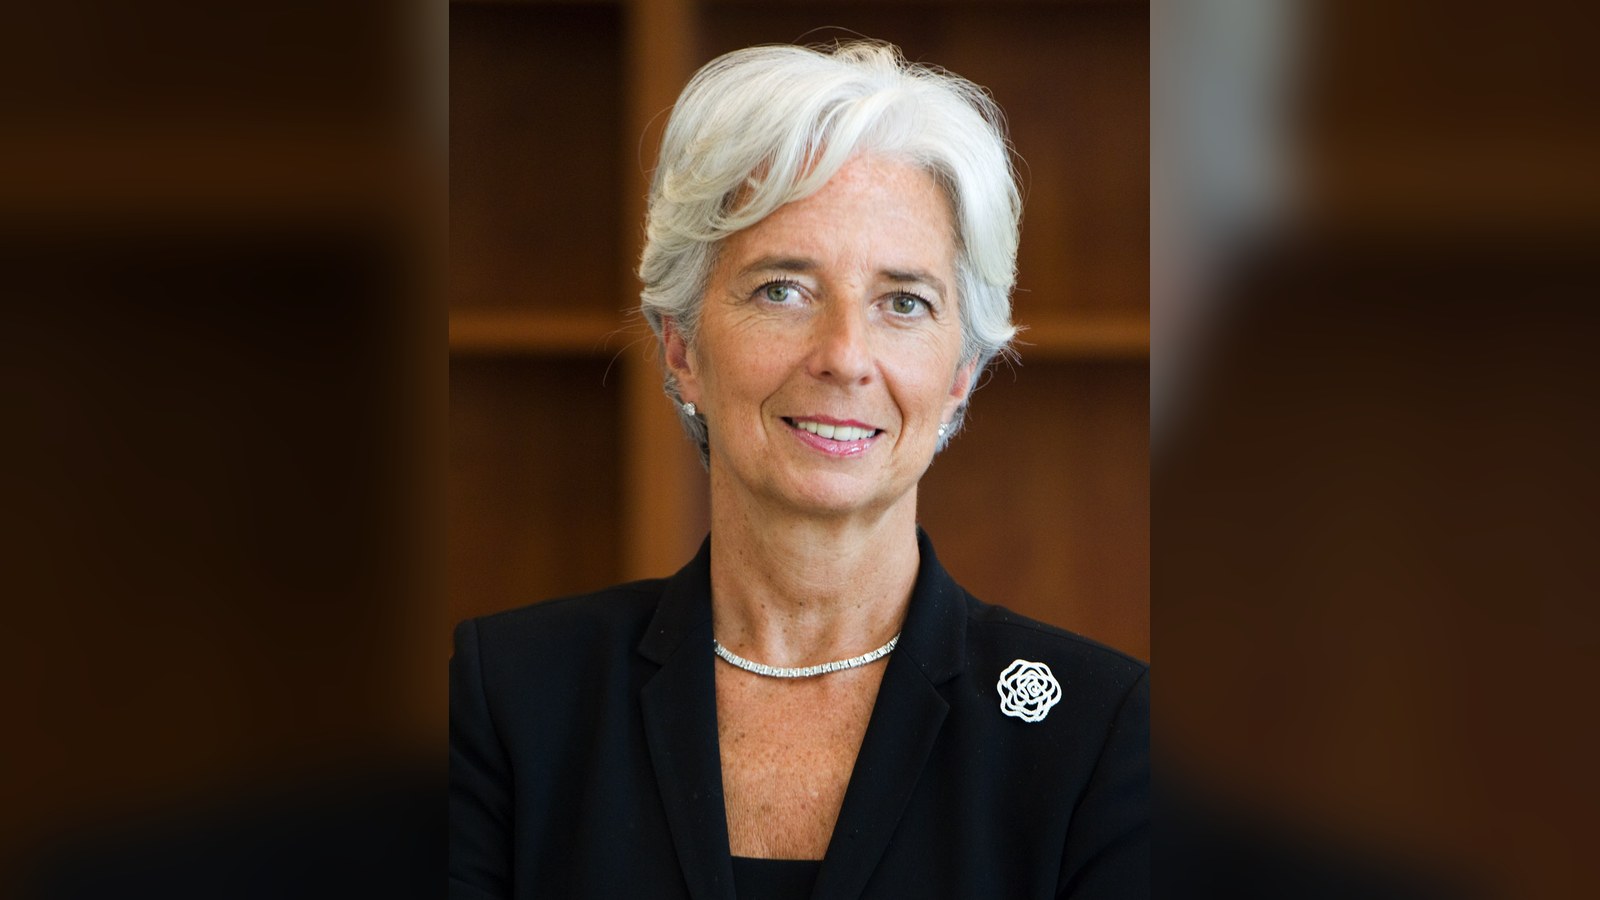
The Lagarde resignation, announced Thursday, ends months of speculation and starts a politically charged scramble over who will run the European Central Bank. Christine Lagarde will leave on February 7, 2027, about nine months before her eight-year term was due to end on October 31, 2027. She is stepping down while eurozone inflation, at 3.8% last month, sits well above the bank’s 2% target.
Why Lagarde says she is leaving
Lagarde made her case at the end of a press conference explaining the ECB’s decision to hold its deposit rate at 2.5%. She said she wants “the freedom of speech, the freedom of expression and the freedom to engage on matters that are not monetary policy matters.” ECB officials are bound by strict neutrality rules, she said, calling that “the price we pay for being independent.”
She said she was troubled by what she called the “misrepresentation of the truth” in public debate, though she did not elaborate. “There are things that I can say – whether people will listen or not is another story,” she said. In a video message she described the job as “a great pride and a huge privilege” and said she was leaving an ECB “fit for the future.”
Sources told AFP the early exit would give her greater freedom to express her views. She has also hinted that she could take part in France’s presidential race, saying a European voice was needed in the debate. Separately, she has been mentioned as a possible head of the World Economic Forum, which Klaus Schwab left last year amid misconduct allegations that he denies.
The French election question
Almost every report links the timing to French politics. The presidential election is set for April and May 2027, and polls suggest the far-right candidate Marine Le Pen is favoured. If Lagarde leaves in February, the European Council can choose her successor while Emmanuel Macron, who cannot run again, still sits at the table.
Holger Schmieding, chief economist at Berenberg, said the EU is trying to “guard itself at least somewhat” against a Le Pen win. Lagarde did not cite the election as a reason, and the sources do not show that Macron pushed her to go. Macron said the handover must be prepared “in an orderly and balanced way” with European partners.
The optics worry some. German MEP Markus Ferber warned that if a departure appears timed around national elections, “it damages trust in an institution that must stand above any domestic political calculation.” Marcel Fratzscher, president of the German Institute for Economic Research, took a different view. He said the early exit gives governments a chance to pick a successor who will safeguard European values and the ECB’s independence.
Who could replace her
The Lagarde resignation opens up more than one job. Chief economist Philip Lane’s term ends May 31, and executive board member Isabel Schnabel leaves January 3 to join the International Monetary Fund. Leaders are expected to negotiate a package deal that spreads the three posts among member states. Schmieding said they would likely try to settle all three before a December 17-18 summit.
Names being floated include former Dutch central bank chief Klaas Knot and Pablo Hernández de Cos, the Spanish head of the Bank for International Settlements. Joachim Nagel, president of Germany’s Bundesbank, and Nadia Calviño, president of the European Investment Bank, have also been mentioned. Under the formal process, euro-area members of the European Council decide on a candidate agreed by the Eurogroup. They first consult the European Parliament and the ECB’s Governing Council. European Council President Antonio Costa said the process would start immediately and “proceed without delay.”
Markets shrug, but the backdrop is tough
Markets appeared calm. Goldman Sachs’s Simon Dangoor said institutional behaviour is likely to outlast Lagarde and look much the same whoever takes over. Schmieding likewise said the exit “does not change the outlook for ECB policies.”
Her successor will still inherit a hard brief: weak growth, above-target inflation and worries about France’s public finances. Lagarde arrived in 2019 as the first ECB chief without formal economics training or central banking experience. She oversaw a 1.35 trillion euro pandemic bond-buying programme and led the bank through Russia’s invasion of Ukraine and the US-Israel war on Iran. The ECB was also criticised for reacting too slowly to the 2022 inflation surge. Leaders from Germany’s Friedrich Merz to the EU’s Ursula von der Leyen have thanked her, but the debate over how her departure was timed is likely to shape the succession fight.
- Europe’s central bank chief Christine Lagarde to step down nine months early (The Guardian)
- European Central Bank President Lagarde to step down early (aljazeera.com)
- ECB’s president Christine Lagarde is resigning nine months early, giving EU leaders a chance to pick a successor before France’s elections (fortune.com)
- ECB President Christine Lagarde to step down nine months early (Protos)
Explore more on this topic with Vexel Search.
File photo: Lagarde, Christine (official portrait 2011).jpg by Français : Fonds monétaire international (identité du photographe non mentionnée, Public domain, via Wikimedia Commons.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
Weight-loss jabs help cut offshore workers over 124kg limit from 2,200 to under 300
Header image: AI-generated illustration by WordUp News.
Weight-loss jabs have become part of the offshore workplace in the UK North Sea, as a new maximum weight rule for helicopter travel takes effect this weekend. Anyone over 124kg (about 19st 7lb) in civilian clothing and footwear will be barred from flying to platforms covered by UK safety regulations.
The scale of the change is large. When the policy was announced in 2025, around 2,200 workers were over the threshold. Industry body Offshore Energies UK (OEUK) says that figure fell to about 840 earlier this year, and is now projected at somewhere between 241 and 300. The BBC reports it as fewer than 250.
Weight-loss jabs and the fridge space to store them
OEUK health and safety manager Graham Skinner said the uptake of GLP-1 medications has been “wide”. On one platform, he said, 60% of staff had been taking them, and extra fridge space was provided to keep the drugs cool. He said workers appeared to have funded the medication themselves at first, though he thought some employers might now be helping with costs.
Skinner was careful to say the jabs are not a “blanket solution”. Gym equipment and healthier food options have also been part of the push. He also noted that offshore workers were using the drugs regardless of company policy, as many people elsewhere in society are. He described them as a potentially useful tool for someone with a lot of weight to lose.
Why 124kg, and why now
The limit is not arbitrary. The Maritime and Coastguard Agency warned that the rescue winches used in offshore emergencies cannot safely lift heavier people. The 124kg figure allows for the combined weight of the casualty, the rescuer, a stretcher and other kit. Skinner said the same winch is used on all search and rescue helicopters, so the limit is fixed by equipment rather than by company preference.
The average weight of offshore workers has been climbing for years, by almost 10kg since 2008. The industry previously adapted around that trend by building larger, sturdier lifeboats and seating bigger passengers next to the largest helicopter windows. Skinner described those steps as “addressing certain symptoms”. He argued that capping weight would help across life-saving equipment generally, and could reduce medical evacuations. Health-related cases such as heart attacks and strokes made up 78% of all medivacs in 2025.
Jobs at risk and union pushback
For those still over the limit, the consequences could be serious. Workers will declare that they are under the limit, and this will be checked at the heliport. Employers may offer onshore roles, and Skinner suggested some of those affected may no longer work offshore in the UK at all. He was blunt about the alternative: “if somebody has chosen not to lose weight… then there will be a route out of employment as well.”
The RMT union has criticised the policy. It says there was a lack of consultation, and it fears the rule could give employers a “convenient mechanism” to dismiss staff without proper redundancy procedures or compensation. General secretary Eddie Dempsey said nobody disputes that safety comes first, but that policies must be “proportionate, evidence-based and developed through meaningful consultation”. The union wants OEUK to withdraw the policy. An Aberdeen occupational health expert told the BBC earlier this year that some clients were “really stressed” by the rules and others had left the industry.
OEUK says most of the workforce is unaffected, and that those already under the limit are pleased with the change. Those with the most weight to lose, Skinner acknowledged, have had the greatest concerns. With the rule now in force, the question is how many of the remaining few hundred workers reach the limit, move onshore or leave the industry. Weight-loss jabs will probably play a part in the answer.
Explore more on this topic with Vexel Search.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
Mobico takeover: £308m Spanish deal values National Express owner at £2.3bn with debt
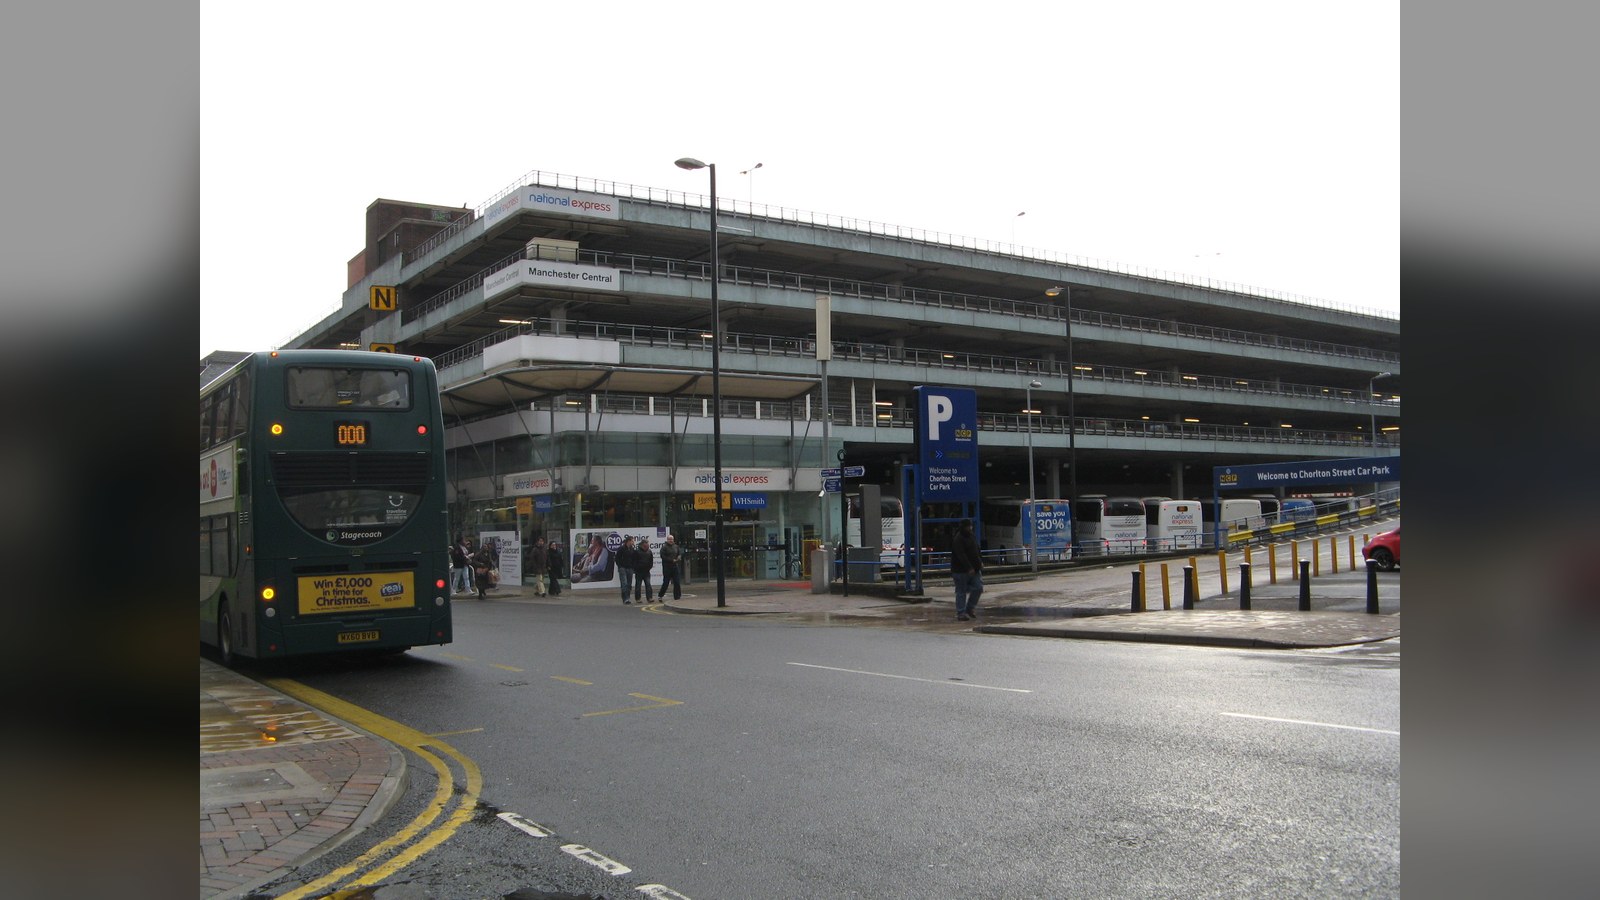
The Mobico takeover marks another chapter in the shrinking of a once-sprawling British transport group: the Birmingham-based owner of National Express has agreed to be bought by Spain’s Autobuses de Leon (AdL) for £308m, a price that rises to about £2.3bn once debt is included.
What the Mobico takeover offers shareholders
AdL, bidding through its Leita Mobility subsidiary, has offered 46p per share. Mobico’s shares jumped by more than a tenth in early trading on Friday after the board said it had accepted the approach. The gap between the £308m equity price and the £2.3bn headline figure is telling. It suggests that debt makes up the vast majority of what the buyers are taking on.
Chairman Phil White described the proposal as “a good outcome for Mobico’s stakeholders” that gives shareholders “value and certainty”. He was also frank about the company’s position. Despite recent strategic progress, he said, the finances “remain challenging”, with cash outflows tied to legacy liabilities limiting the group’s ability to cut net debt.
Who is behind the Spanish bid
AdL is backed by the investment firm Asterion Industrial Partners and by CMC Group. CMC is already Mobico’s biggest shareholder, with a stake of roughly 26%. Its vice-chairman, Felipe Cosmen Menéndez-Castañedo, said his family has been a long-term shareholder since 2005 and has “great confidence” in the company and its management.
Asterion chief executive Jesús Olmos called Mobico “an attractive transport infrastructure business”, pointing to contracted and concession-backed activities that fit the firm’s investment strategy. That framing suggests the buyers see steady, contract-based income rather than a growth story built on consumer demand.
A slimmed-down group changes hands
Mobico has already pared back. In recent years it has sold its remaining UK regional bus operator to the West Midlands local authority and, last year, its US school bus arm for £457m. It still employs about 30,000 people and runs around 13,400 vehicles worldwide. The sources do not say what the new owners plan for jobs, routes or the National Express brand, and the board’s talk of a “more sustainable capital structure” is the only guide so far to their intentions.
Part of a wider London market exodus
The Mobico takeover also fits a broader pattern. The Independent notes that takeovers have accelerated this year, most of them from overseas buyers, as strategic acquirers and private equity firms look to broaden their portfolios. EasyJet and Tate & Lyle are also set to leave the London Stock Exchange, at a time when the exchange is struggling to attract big-name flotations.
For Mobico shareholders, the deal offers a clear exit and an immediate share price lift. For the wider market, it is one more well-known name moving out of public hands. The reports describe the transaction as “proposed”, so the formal steps needed to complete it are still to come.
- National Express owner Mobico agrees £308m Spanish takeover deal (business-live.co.uk)
- National Express owner agrees to £308m Spanish buyout proposal (The Independent)
- National Express owner Mobico set for £308m Spanish takeover (standard.co.uk)
Explore more on this topic with Vexel Search.
File photo: Manchester National Express Coach Station – geograph.org.uk – 2777546.jpg by Josie Campbell, CC BY-SA 2.0, via Wikimedia Commons.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
Yorkshire Water Chief Nicola Shaw Quits a Day After One-Star Rating and 335 Pollution Incidents
Header image: AI-generated illustration by WordUp News.
The Yorkshire Water chief executive, Nicola Shaw, is stepping down just 24 hours after the Environment Agency (EA) downgraded the company to the lowest environmental rating available, a one-star classification reserved for poor performers.
The company announced the departure on Friday, saying Ms Shaw had decided to leave after four and a half years in charge. Nicola Medalova, a former National Grid executive, will join next week as chief executive-designate and formally take over in January. The timing makes the announcement hard to separate from the regulator’s verdict, though the company framed the change as an “orderly transition” rather than a response to it.
What the one-star rating means
On Thursday the EA said it had cut Yorkshire Water from two stars out of four to one. The company serves more than five million people across the region. According to the EA, it recorded 335 pollution incidents in 2025, 13 of them classed as serious. It was also fined a total of £1.2 million last year over pollution incidents.
The rating carries a practical penalty. Under rules introduced last year, any company rated one star is automatically barred from paying bonuses to its senior executives. Yorkshire Water is not alone: Southern Water, Thames Water and South West Water also received one-star ratings, so four of the water companies assessed now sit in the bottom tier.
A carefully worded exit
Ms Shaw acknowledged that “a huge amount of work” remains, but said the business is on “stronger footing for delivery across all aspects of its work”. She added that it “now feels like the right time to begin an orderly transition to the company’s next chapter.”
The sources do not say that Ms Shaw was pushed out, and nothing in the company’s statement links her decision directly to the EA’s announcement. What they do establish is the sequence: a damaging regulatory ruling one day, a leadership change the next.
Scrutiny over pay
Ms Shaw’s tenure also drew criticism over her remuneration. Payments to her worth £1.3 million between 2023 and 2025 were made through Kelda Holdings, a Jersey-incorporated company. Yorkshire Water stressed at the time that the money came from shareholders rather than bill payers. That distinction answers one question about who funded the pay, but it did little to quiet wider unease about executive reward at a company with a poor environmental record.
What the new leadership faces
Ms Medalova is arriving with a clear brief and a difficult starting position. She said Yorkshire Water “faces huge challenges but also great opportunities for continued improvement”, and promised a “relentless focus” on delivering “for customers, communities and the environment”. She will work alongside Ms Shaw during the handover period before taking full control.
The bonus ban shows how the new rules bite: a poor rating now has direct consequences for pay at the top. Whether the change at the top of Yorkshire Water translates into fewer pollution incidents is the real test, and the next EA assessment will show how far the company has moved from the bottom of the table.
- Yorkshire Water boss Nicola Shaw steps down after firm's one-star environmental rating (business-live.co.uk)
- Yorkshire Water boss steps down after firm given one-star environmental rating (The Independent)
- Yorkshire Water boss steps down after firm given one-star environmental rating (standard.co.uk)
Explore more on this topic with Vexel Search.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
NBC News Creates New Head of Digital Content Job, Hires Quartz Co-Founder Kevin Delaney
Header image: AI-generated illustration by WordUp News.
NBC News has hired Kevin Delaney, a co-founder of Quartz and former Wall Street Journal editor, as its first head of digital content and subscription, a newly created position meant to connect the newsroom with the business side. The move, reported on October 27, signals how much weight the network is putting on its digital and direct-to-consumer ambitions.
What the new role covers
As head of digital content and subscription, Delaney will oversee digital publishing and NBC News’ AI efforts. According to Deadline, Tom Namako, who leads digital publishing, and Hanna Helin, who leads AI initiatives, will report to him. He is also expected to work with Arianna Davis, who runs Today Digital, and Jessica Mailloux, who oversees audience insights.
Delaney will report to two executives: Catherine Kim, executive vice president of editorial and content, and Sat Brainch, chief business officer of NBCUniversal News Group. That dual reporting line reflects the job’s purpose. In a memo to staff, Kim and Brainch said Delaney would develop content to support new opportunities that drive audience and revenue growth as the company strengthens its digital business and expands its direct-to-consumer offerings.
Why NBC News wants a digital-first leader
The hire follows a busy stretch for NBC News’ digital products. Variety notes that the news division has recently expanded programming on its streaming news channel, NBC News Now, and has launched a subscription product aimed at mobile users. Deadline says the digital subscription service debuted last December. Both outlets describe the post as a way to coordinate editorial output with revenue goals, rather than treating them as separate tracks.
Delaney’s résumé fits that brief. At Quartz, he helped build a site known for presenting news to digital audiences in new ways. He later co-founded Charter, a media company focused on leadership, and Deadline reports he served as CEO and editor in chief of both ventures. Most recently he was editor in chief of the San Francisco Standard, a local news outlet that acquired Charter.
Earlier in his career, he held senior editorial roles at The Wall Street Journal, where Variety says he oversaw digital editorial efforts and helped expand subscription offerings. He also worked at The New York Times and The Information, and he began as a TV producer in Montreal. That mix of broadcast experience, startup work and paywall-era publishing suits a job that spans video, text, AI tools and subscriptions.
Start date and open questions
Variety says Delaney is slated to start on November 16. Deadline’s wording suggests he already began on that date, but since the report is dated October 27, the start date appears to still be in the future. Neither report details specific products, targets or subscriber numbers, and neither says how the AI work will shape NBC News’ coverage or tools.
For now, the creation of a head of digital content role shows where NBC News sees its growth. Delaney’s early decisions on publishing, AI and subscription content will show how the division plans to turn its expanded streaming and mobile offerings into a durable business.
Explore more on this topic with Vexel Search.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
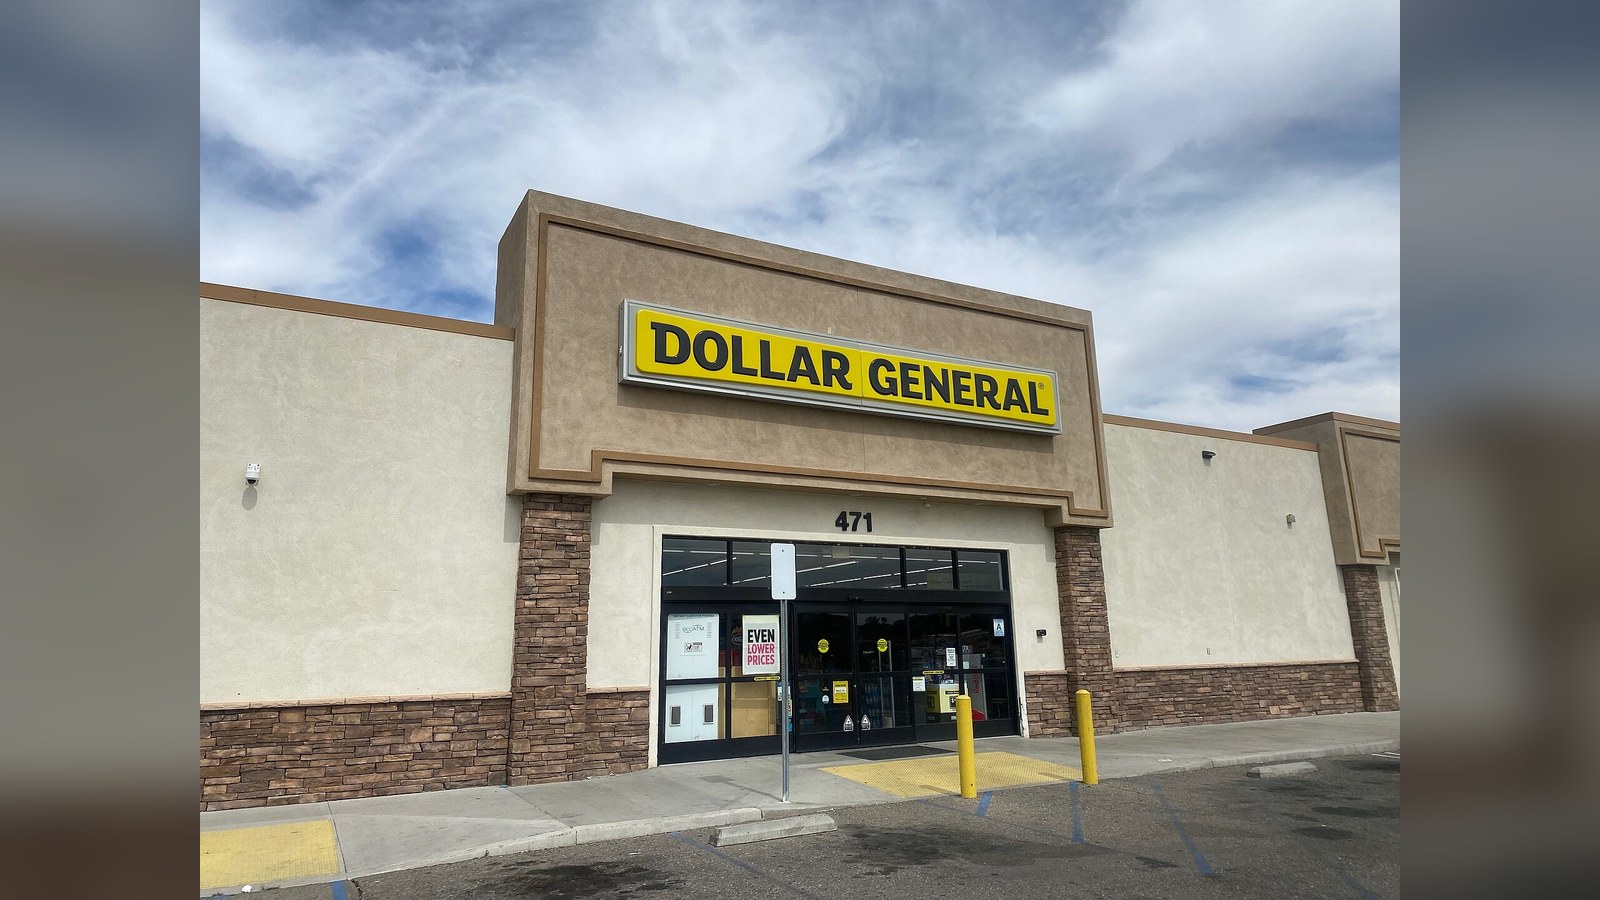
The Dollar General lawsuit filed Monday by the Federal Trade Commission and 20 states accuses the country’s biggest small-box discount chain of repeatedly charging shoppers more at the register than the prices posted on its shelves. The case, filed in federal court in Tennessee, puts a retailer built on the promise of low prices in the unusual position of defending the accuracy of those prices.
What regulators allege
According to the complaint, Dollar General kept up the practice for years even though it knew about the problem. Regulators point to at least 29,265 complaints between January 2023 and March 2026 from customers who said the company did not honor marked prices. The FTC says those complaints came from all 48 states where Dollar General operates. It also cites store inspections that turned up pricing errors, and argues the company never adequately fixed them.
The complaint says the overcharges fell hardest on low-income and fixed-income households, who depend on advertised prices to stretch tight budgets. “Dollar General has betrayed the trust of millions of American consumers,” said Christopher Mufarrige, director of the FTC’s Bureau of Consumer Protection, adding that the harm landed on people “already struggling to make their paychecks last.”
The suit alleges violations of the FTC Act, the Gramm-Leach-Bliley Act and state consumer protection laws. The agencies want a permanent injunction, monetary relief and other remedies. Neither source report specifies a dollar figure.
A history of similar complaints
This is not the first time the company has faced such claims. The FTC says Dollar General paid more than $6 million in penalties under seven settlements with state authorities between 2019 and 2026 over inaccurate pricing. Months ago, it also agreed to an $8.5 million class-action settlement over similar allegations, without admitting wrongdoing. Regulators appear to be treating that record as evidence that the issue is systemic rather than a string of isolated store-level mistakes.
The scale of the company matters here. With more than 21,000 stores, Dollar General sells thousands of everyday essentials, and the complaint argues that even small gaps between shelf and register prices add up across millions of purchases.
The states joining the FTC are Alabama, Arizona, Arkansas, California, Connecticut, Florida, Illinois, Iowa, Kansas, Louisiana, Michigan, Mississippi, Nebraska, New Jersey, North Carolina, Ohio, Oklahoma, Tennessee, Utah and Wisconsin.
Dollar General fights back
The company rejects the portrayal. In a statement, it said the suit implies it has “abandoned our mission and willfully disregarded the affordability needs of our customers,” and called that “nothing could be further from the truth.” Dollar General says its goal is 100 percent accuracy between shelf and register prices, but acknowledged that, as at other retailers, “occasional price discrepancies can occur.” When they do, it says, store teams are expected to make things right, and it has improved its price-accuracy processes in recent years.
Dollar General also says it cooperated with the investigation, handing over more than 200,000 documents and over 350 gigabytes of data. It says it tried to negotiate a settlement beforehand and was “surprised” when the agencies chose to sue. The company says it will defend the case vigorously.
The central question for the court is likely to be whether the pricing errors reflect ordinary retail slip-ups or a failure to act on known problems. The allegations have not been tested in court, and the number of complaints, while large, is measured against a vast volume of transactions. The outcome could shape how closely regulators police shelf-price accuracy at discount chains that serve budget-conscious shoppers.
Explore more on this topic with Vexel Search.
File photo: Dollar General, Barstow.jpg by YosemiteYamper, CC BY-SA 4.0, via Wikimedia Commons.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Business & Hustles
Reckitt sales outlook cut to 3.5%-4.5% growth as shares drop 6% and European prices rise 4%
The Reckitt sales outlook for 2026 has been trimmed, and the maker of Lysol, Gaviscon and Vanish is leaning on higher prices in Europe to cope with cost pressures linked to the Iran war. The company now expects like-for-like growth in its core business of 3.5% to 4.5% this year, down from a previous range of 4% to 5%. Investors reacted quickly, with shares in the FTSE 100 company down 6% in Tuesday morning trading.
Why the Reckitt sales outlook was lowered
The immediate cause of the downgrade was North America, not Europe. Sales there fell 1.3% in the third quarter after disruption to production of Lysol, the cleaning brand. Chief executive Kris Licht said the region “was below our expectations” and put the problem down to supply rather than demand. “While consumer demand for Lysol remains strong, temporary manufacturing constraints limited our ability to fully meet demand,” he said.
The distinction matters. Reckitt is telling the market that it had customers ready to buy but could not make enough product. It expects Lysol and its wider North American business to rebound in the final three months of the year, once the manufacturing issues are resolved. The company has not been forced to explain a collapse in appetite for its brands, only a bottleneck it says is temporary.
Price rises in Europe offset weaker volumes
Elsewhere, the picture is more mixed. Reckitt said it had taken “selective pricing actions” across Europe to offset inflation caused by the Middle East conflict. Prices rose by 4% in the three months to 30 September.
That helped the Europe, Australia and New Zealand division return to growth, with like-for-like sales up 0.8% in the quarter. But the headline figure hides a weaker underlying story. Revenue by volume fell 3.2%, meaning shoppers bought noticeably fewer products even as each one cost more. The growth in that division came from pricing, not from selling more.
Reckitt blamed a consumer who remains cautious. “Consumer confidence across the area remains subdued,” it said, pointing to “elevated promotional activity and value-seeking behaviour driving share growth for discount retailers which has impacted volumes, particularly in germ protection.” In plain terms, hard-pressed households are trading down to cheaper rivals, and the pressure is felt most in the germ-protection category, where Lysol competes.
Group growth held up despite the setback
Across the whole core business, like-for-like sales rose 3.3% in the quarter. That figure strips out the Mead Johnson Nutrition business and the disposal of Essential Home. It sits below the range Reckitt now forecasts for the full year, so the final quarter will need to do some work, which is why the promised North American recovery carries weight.
Analysts were not overly gloomy. Chris Beauchamp, chief market analyst at IG, argued that investors should not let the US miss sour them too much on the company’s prospects. “Growth looks much more broad-based,” he said, adding that with North American trading expected to recover in the fourth quarter, “there are still reasons to be optimistic.”
What to watch next
The revised Reckitt sales outlook leaves two questions. The first is whether Lysol production is back to normal in time to deliver the fourth-quarter rebound the company has promised. The second is how long European shoppers will tolerate higher prices before they switch more heavily to discounters. A 4% price rise carried the European division into growth this quarter, but a 3.2% fall in volumes suggests that tactic has limits if consumer confidence stays weak.
For a company with bases in Hull and Slough and a stable of everyday household names, the quarter shows how a conflict far away can feed through into supermarket shelf prices and shopping habits. The 6% share fall shows how closely the market is watching whether Reckitt can keep delivering both.
- Reckitt Benckiser cuts sales outlook and hikes prices amid Iran war cost pressures (business-live.co.uk)
- Reckitt trims sales outlook and reveals price hikes amid Iran war cost pressures (The Independent)
- Reckitt trims sales outlook and reveals price hikes amid Iran war cost pressures (standard.co.uk)
Explore more on this topic with Vexel Search.
File photo: Deutsche Niederlassung von Reckitt Benckiser – panoramio.jpg by Immanuel Giel, CC BY 3.0, via Wikimedia Commons.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
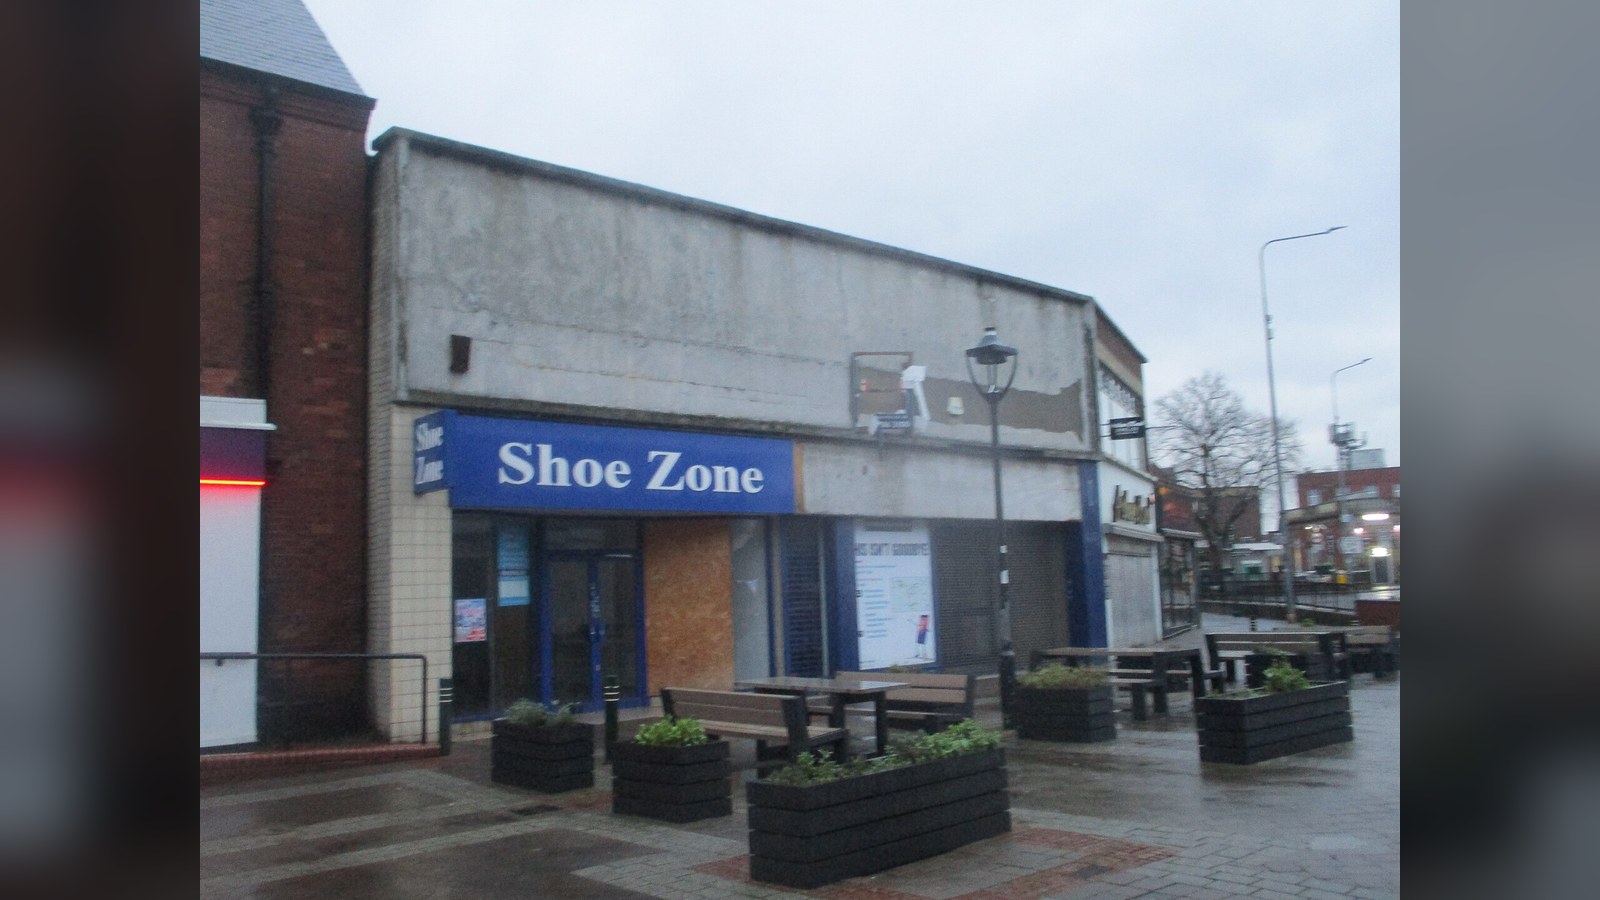
A Shoe Zone loss of around £1 million is now on the cards for the full year, and investors reacted swiftly, sending shares down by as much as 22% on Tuesday. The Leicestershire-based footwear retailer said revenues fell 4.5% to £142.4 million in the 53 weeks to October 3, and that the start of the new financial year has not offered much relief.
From £2.4m profit to a £1m loss
The company expects an underlying loss of roughly £1 million, compared with a profit of £2.4 million a year earlier. That is a turnaround of about £3.4 million in twelve months. Shoe Zone said the autumn/winter season has been slower than it had expected. This hurt the final weeks of the year, and the weakness has continued into the first quarter of the new one.
The sharp share-price drop suggests the market had not been braced for the warning. It also reflects that the problem is not confined to the year just ended.
Fewer stores, bigger boxes
Store closures also weighed on revenue. Shoe Zone ended the year with 251 outlets, down from 269 in October 2025. Of those, 211 are larger-format stores and 40 are traditional high street shops. The company is relocating and modernising its estate and aims to finish the transition by the end of 2027. In the short term, though, shutting older shops removes sales faster than newer ones can replace them.
A cautious shopper
Chairman Charles Smith described a “challenging year”, especially the first half. He said consumer confidence was weak and fell further after the Government’s November 2025 budget. He pointed to persistent inflation, elevated interest rates and squeezed disposable income as the main drags.
There were bright spots. Smith said sales held up “when there was a clear reason to buy”, citing the warm summer and the Back-To-School season. The implication is that shoppers are buying what they need and cutting back on discretionary extras, which is a hard environment for a high street footwear chain.
Iran conflict adds fresh cost pressure
The outlook carries further risk. Shoe Zone said the conflict in Iran has pushed up fuel and transport costs and raised the price of the shipping containers it uses to import stock. It has also recently seen sterling weaken against the dollar, which makes goods bought in dollars more expensive. The company said all of these factors “could negatively impact trading”.
It is also waiting on the Government’s October 2026 Budget, which could affect both its costs and shopper sentiment. Until the Budget lands, the company is watching the wider economic and geopolitical backdrop closely.
For now, the Shoe Zone loss forecast shows how a value-focused retailer is caught between cautious customers and rising supply-chain bills. Its store overhaul is meant to put the business on firmer footing, but the company’s own warning is that the near-term picture is likely to stay difficult.
- Shoe Zone shares slump as chain braces for £1m loss amid falling sales (business-live.co.uk)
- Shoe Zone shares slump as chain set to swing to £1m loss (The Independent)
- Shoe Zone shares slump as chain set to swing to £1m loss (standard.co.uk)
Explore more on this topic with Vexel Search.
File photo: Former Shoe Zone, Boothferry Road, Goole (19th November 2023).jpg by Mtaylor848, CC BY-SA 4.0, via Wikimedia Commons.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Header image: AI-generated illustration by WordUp News.
The Anthropic IPO moved from rumor to paperwork on Monday, when the maker of the Claude chatbot publicly filed its prospectus with US regulators. The document gives the first audited look at the finances of one of the most closely watched companies in tech. It shows revenue growing at a pace few businesses have matched, alongside losses large enough to fuel the debate over whether the AI boom can pay for itself.
Revenue growth that is hard to overstate
The company’s annual revenue was $41m in 2023 and $386m in 2024. In 2025 it reached $4.585bn, an increase of more than 1,000%. In the first six months of 2026 alone it booked $16.286bn, against roughly $1.1bn in the same period a year earlier, according to City AM’s reading of the filing.
Unlike OpenAI, which has built its brand on a mass consumer product, Anthropic has pitched itself mainly at businesses. As of 30 September it counted more than 14,000 enterprise customers. Of these, 11,900 had generated $100,000 or more in revenue, more than 1,900 had passed $1m, and about 250 had topped $10m. “The speed and depth of our enterprise customer adoption are powerful evidence of Claude’s position at the frontier of AI,” executives wrote.
An $80.7bn loss, with caveats
Against that growth sits a net loss of roughly $80bn for the first half of 2026. City AM puts the precise figure at $80.7bn. It also reports that about $72bn of that came from non-cash accounting adjustments tied to convertible debt and other financing instruments. Those adjustments mean the headline loss overstates the cash the company burned in the period, though the filing still shows heavy spending. Anthropic lost $42bn in 2025, and it spent $9bn on AI infrastructure in the first half of this year, compared with $7.3bn across all of last year.
The company said it had raised $141.1bn as of the end of June and has taken on $6.2bn in debt to build out its infrastructure. It also spends billions each year on computing power from third parties and has committed hundreds of billions of dollars to future capacity, including cloud agreements with Amazon and Google.
Valuation, timing and the bubble question
The company plans to list on the Nasdaq under the ticker ANT, with Goldman Sachs and Morgan Stanley leading the offering. It confidentially filed in June, and a debut could come as early as November, though no date or price has been set. Analysts and investors have valued Anthropic at more than $1.5tn. Bankers have reportedly aimed for $1.5tn to $2tn, even as recent market volatility has raised doubts about appetite for richly priced AI stocks.
Supporters say the numbers justify the ambition. Jared Carmel of Manhattan Venture Partners, an early investor, argued that a $2tn valuation is not unreasonable: “The market isn’t pricing a chatbot. It’s pricing an infrastructure layer for how every business is going to run.”
Risks the prospectus spells out
The filing runs to more than 90 pages of risk disclosures. One concerns concentration: a quarter of revenue comes from the top five customers, although none accounts for more than 10% of the business. Losing a few of them could still dent results.
Anthropic also lays out four categories of AI risk: misuse by bad actors, loss of control, authoritarian abuse and economic disruption. The company has faced scrutiny over its safety practices, and a former researcher has accused it and OpenAI of “racing straight to self-improving superintelligence.” The prospectus nonetheless carries the grand language typical of the sector, describing AI agents as “a country of geniuses in a datacenter, available to every organization and sector of the economy.”
For investors, the Anthropic IPO will test a simple question. Will customers keep paying at this pace for long enough to cover the cost of the computing that produces the revenue? The filing does not answer that, but it gives the market real numbers to argue over.
Explore more on this topic with Vexel Search.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.
Header image: AI-generated illustration by WordUp News.
The JetBlue loss for the third quarter grew to $257 million, up from $143 million a year earlier, and the airline’s stock hit a new low on the day it reported. Management is arguing that the underlying business is improving, but investors are watching the balance sheet more closely than the margin talk.
The biggest driver was fuel. JetBlue’s fuel bill rose 61% to $868 million for the three months ended Sept. 30. On an adjusted basis, the airline lost 60 cents per share, worse than the 55-cent loss analysts polled by LSEG had expected. Revenue of $2.81 billion landed just under the $2.82 billion forecast.
What management says about the JetBlue loss
CEO Joanna Geraghty framed the quarter as better than it looks. She said resilient demand and strong yields pushed revenue well ahead of the company’s initial expectations, which let JetBlue recapture more of the fuel increase than it first thought it could. She said that momentum has carried into the fourth quarter and pointed to Fort Lauderdale as a standout, even as the airline grows capacity there significantly.
Demand does appear to be holding up. Fares are up more than 20% this year, and JetBlue says travelers have kept buying anyway. Higher fuel costs have hurt airline profits across the industry, so JetBlue’s problem is not unique. What sets it apart is how little cushion it has to absorb the hit.
Investors focus on liquidity and creditors
The stock is down more than 40% this month. Part of the anxiety comes from a Wall Street Journal report, published Friday, that a group of JetBlue’s senior creditors is working with restructuring adviser PJT Partners. The airline did not address that report in the material available here, but it did lead its release with balance-sheet figures. It ended the quarter with $2.2 billion in liquidity and a $7 billion unencumbered asset base, including $2.8 billion in aircraft and engines.
Those numbers give the company some room, but the JetBlue loss comes on top of a long record of red ink. The carrier last posted an annual profit in 2019. Executives will face analysts on an earnings call Tuesday at 10 a.m. ET, where questions about long-term financial health are almost certain to dominate.
A turnaround plan with strategic setbacks
JetBlue is midway through a multiyear plan to cut costs and raise revenue by investing in premium products. One example is a new domestic first-class section that recently went on sale. The strategy is meant to move the airline toward more profitable customers and away from a business squeezed by bigger rivals.
Its other paths to scale have been closed off. A federal judge blocked JetBlue’s attempted acquisition of Spirit Airlines, ruling it anticompetitive, and Spirit is now defunct. A judge also stopped a regional partnership with American Airlines that the two carriers said would help them compete in the congested Northeast. JetBlue now has a partnership with United Airlines instead.
The central question is whether better revenue and a premium push can outrun fuel costs and debt pressure. The JetBlue loss suggests the gap is still wide, and the company’s cash and asset cushion will determine how much time the turnaround gets. Tuesday’s call may show whether management can persuade investors and creditors that margins are improving fast enough.
Explore more on this topic with Vexel Search.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.

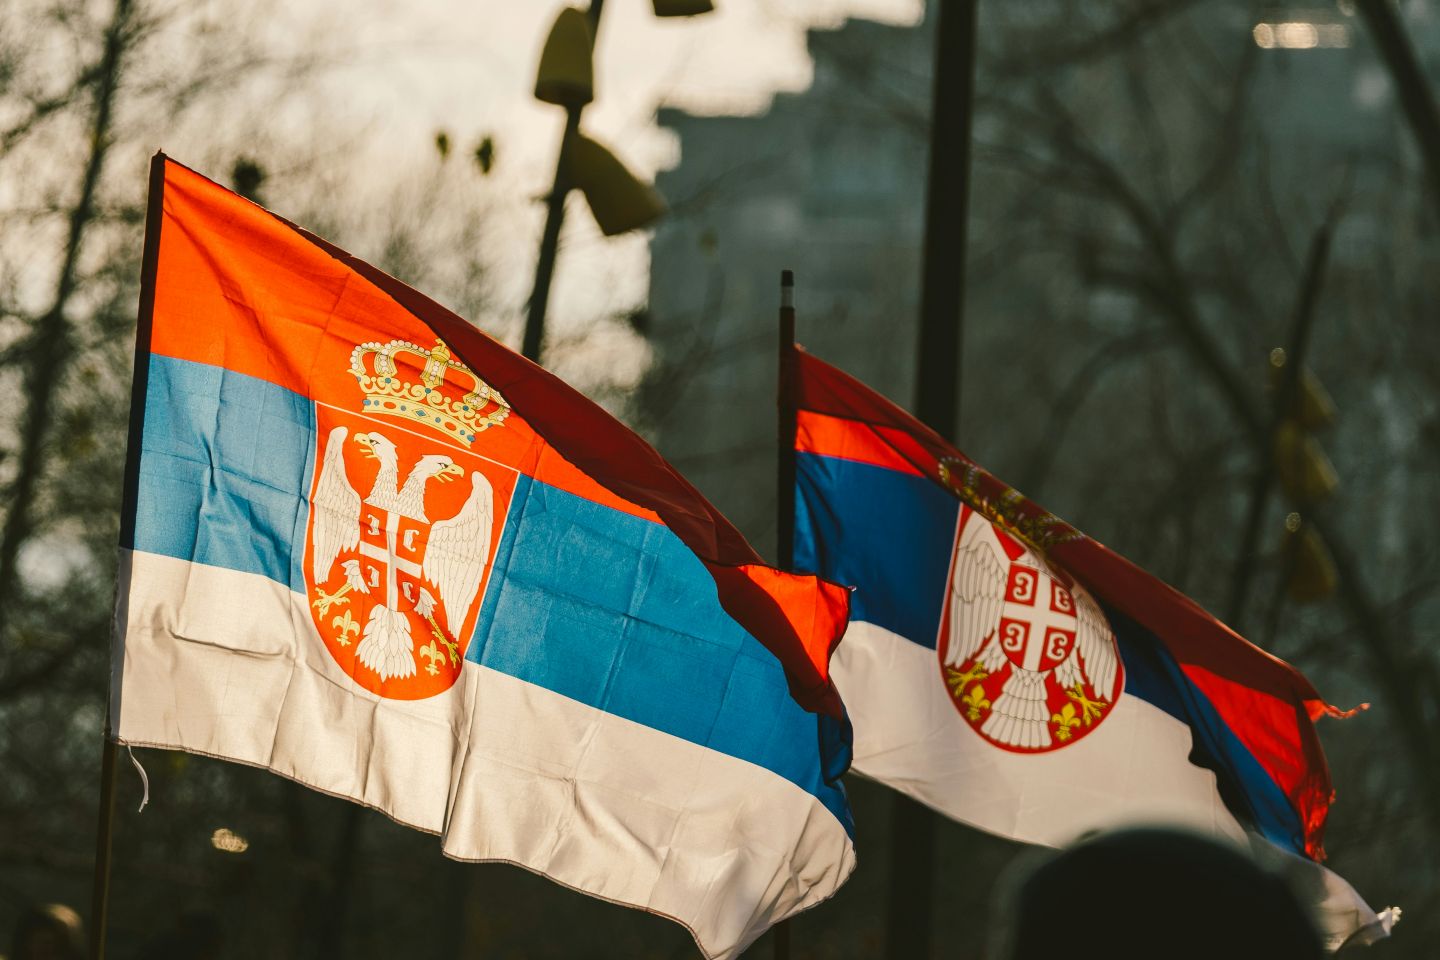
Shares in Perth-based explorer Strickland Metals were heavily sold off on Monday, in an apparent investor reaction to Serbia’s preliminary election results over the weekend.
WordUp Morning
Ten stories, both sides of each, in five minutes. Free, every weekday at 7am, plus a Saturday weekend edition.
We'll email you a link to confirm. Unsubscribe any time.

Ian McKellen Tribute Calls Patrick Stewart “a Man to Rely On” After His Death at 86

Lagarde Resignation Sets Feb. 7 Exit, Opening a Race to Lead the ECB as Inflation Hits 3.8%

Binance Hack Losses: $6.34B Set Aside, $5B Already Held in Matching Tokens


-
 Tech & AI5 days ago
New conversion kit lets builders fit ATX motherboards and standard PC GPUs inside Apple Mac Pro case
-
 Tech & AI6 days ago
S’pore’s NTU ranks 1st globally in AI & NUS dominates engineering
-
 Entertainment7 days ago
‘Shocked’ Director Addresses Amanda Bynes’ Last On-Screen Performance
-
 Crypto5 days ago
Pump Fun’s Kimchi partnership has turned into chaos
-
 Fashion6 days ago
Breaking the Color Rules – Julia Berolzheimer
-
 Tech & AI6 days ago
Pushing Bluetooth Out To 12 Kilometers
-
 Business & Hustles6 days ago
Slideshow: Operators lean on limited-time menu innovations
-
 Fashion4 days ago
Tuesday’s Workwear Report: Classic Shetland Blazer
-
Tech & AI7 days ago
What’s The Difference Between Gear Oil And Hydraulic Oil?
-
 Tech & AI7 days ago
Instacart reportedly discussed selling itself with DoorDash and Uber
-
 Crypto6 days ago
Grayscale Names 3 Cryptocurrencies That Could Benefit From AI Growth
-
 Tech & AI6 days ago
Greece Enacts Social Media Ban For Kids Under 15
-
 Tech & AI7 days ago
Apple is exploring ways to make Safari websites less cramped on its foldable iPhone
-
 Business & Hustles7 days ago
US oil company plans first well in Greenland in 2027 amid Trump push
-
 Crypto7 days ago
IRS Targets 120-Day Tax Disclosure Process: Forbes
-
 Crypto6 days ago
Bitcoin ETFs reversed course in a day. Who is buying when the funds sell?
-
 Tech & AI6 days ago
The AI agents Muse and Dots, explained: What are they and what they do
-
 Tech & AI5 days ago
When an AI Agent Is the Incident, the Identity Record Is the Evidence
-
 Crypto7 days ago
AmEx fires 5% of workers, raises profit forecast just 1%
-
 Tech & AI5 days ago
Anker Soundcore Space 2 Pro Review
You must be logged in to post a comment Login